The Week Ahead – Apple, Midterms and Jobs Test a Market on Edge
The rotation out of Tech continued last week. Now a packed week headlined by Apple on Monday, Tuesday’s midterm elections, and Friday’s jobs report test a market with thin gamma and CTAs near their sell triggers.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
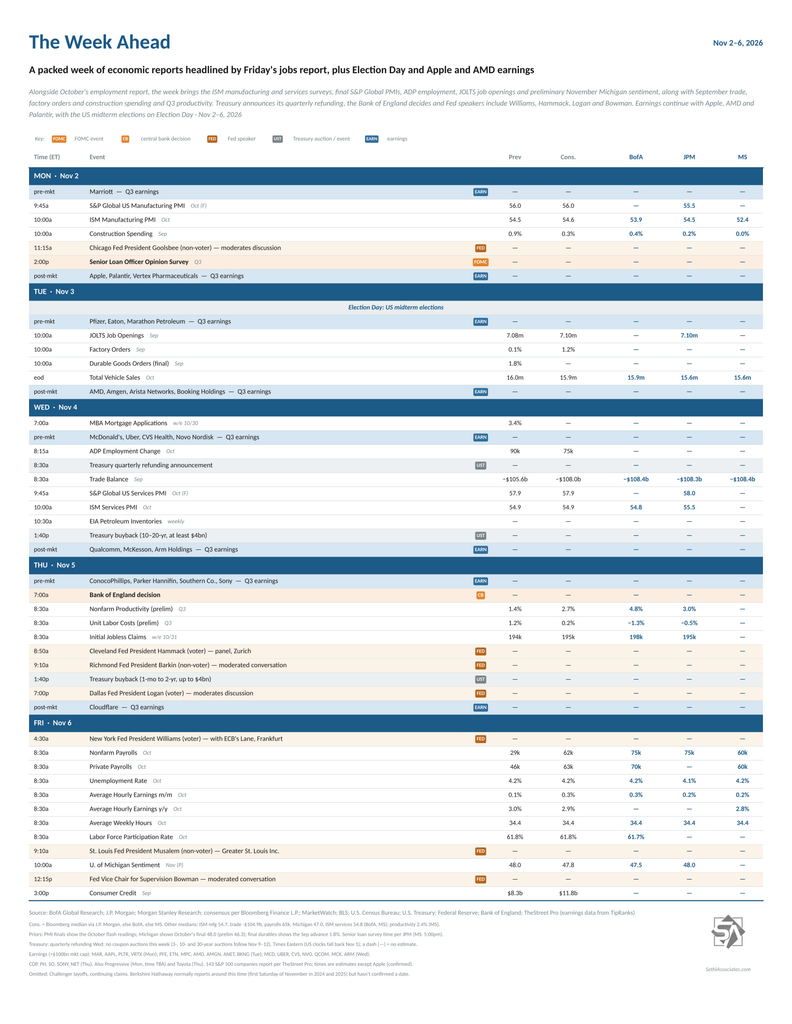
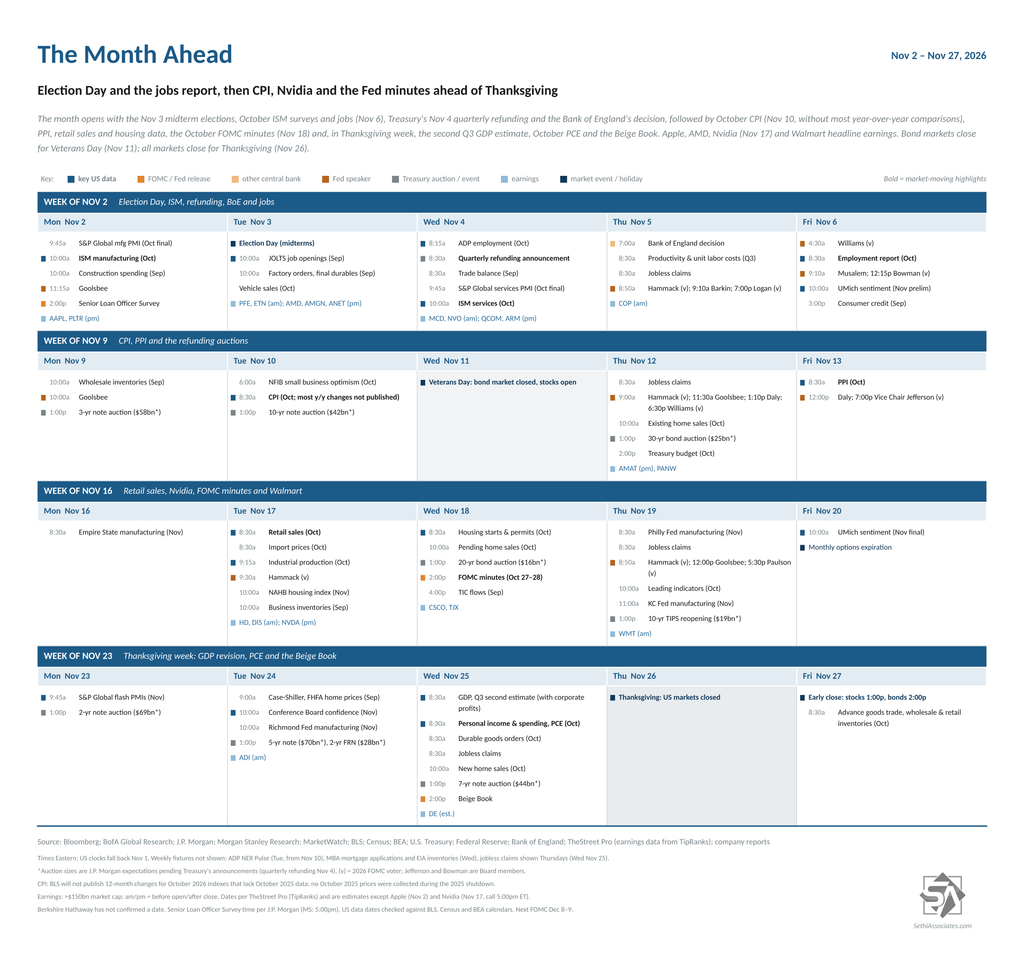
It’s a packed week. We get notable economic reports every session, more earnings including Apple and AMD, Fed speakers return, the Treasury makes its much-anticipated quarterly refunding announcement, and, of course, the US midterm elections are Tuesday. Hopefully by now you know US clocks fell back this morning, so all times are EST.
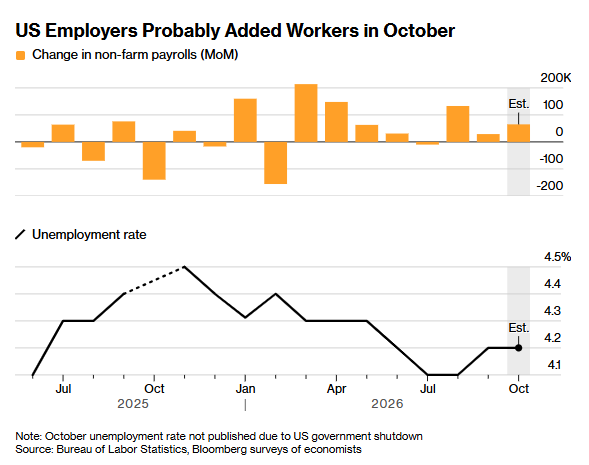
US economic reports are headlined by Friday’s employment situation report. Bloomberg consensus is for a gain of 65,000 nonfarm payrolls with the unemployment rate holding at 4.2%.
Other October reports are the ISM manufacturing and services surveys, final S&P Global PMIs, ADP employment and vehicle sales. September reports include JOLTS job openings, the trade balance, factory orders and construction spending. We’ll also get Q3 productivity and unit labor costs, preliminary November University of Michigan consumer sentiment and the usual weekly reports (mortgage applications, unemployment claims, etc. – no weekly ADP report this week with the monthly report out).
Fed speakers return in force after last week’s meeting. Chicago Fed President Goolsbee (non-voter) speaks Monday. Cleveland Fed President Hammack (voter), Richmond Fed President Barkin (non-voter) and Dallas Fed President Logan (voter) speak Thursday. New York Fed President Williams (permanent voter who is a key voice), St. Louis Fed President Musalem (non-voter) and Fed Vice Chair for Supervision Bowman speak Friday. The Fed also releases its Senior Loan Officer Opinion Survey Monday.
There are no non-Bill (>1yr in maturity) US Treasury auctions, but, perhaps more importantly, Treasury announces its quarterly refunding Wednesday, with Monday’s borrowing estimates previewing the total needed. Speculation is high that there may be reductions to longer maturities, although the questionnaire sent to the Treasury advisory committee did not indicate that was coming.
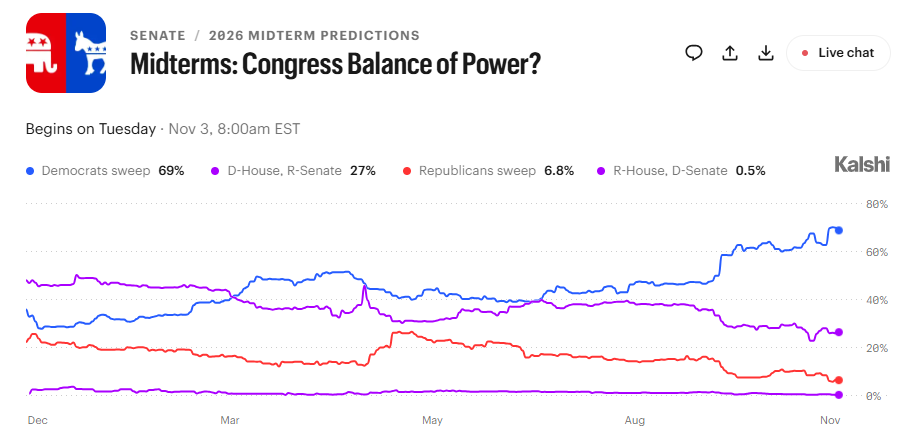
And then there are the midterms Tuesday. Goldman’s desk notes Kalshi is pricing 69% odds of a Democratic sweep (although Kalshi also priced 80% odds of a Bolsonaro victory in the just completed Brazilian Presidential elections). BofA doesn’t expect the result to “meaningfully alter our economic outlook through 2028 due to limited scope for legislation.” Its baseline is Democrats flipping the House and Republicans holding the Senate, which means gridlock, and it notes stocks have generally thrived when Congress is split. They say a Republican sweep is the clearest upside risk for growth, a Democratic sweep mainly brings control over nominations (including to the Fed), and the biggest downside risk is data-center regulation, mostly at the state and local level. Deficits stay around 6% of GDP either way. The House also passed a continuing resolution funding the government through December 11th, so there’s no shutdown risk this month, and there is speculation that the debt limit may be pushed off during the lame duck session.
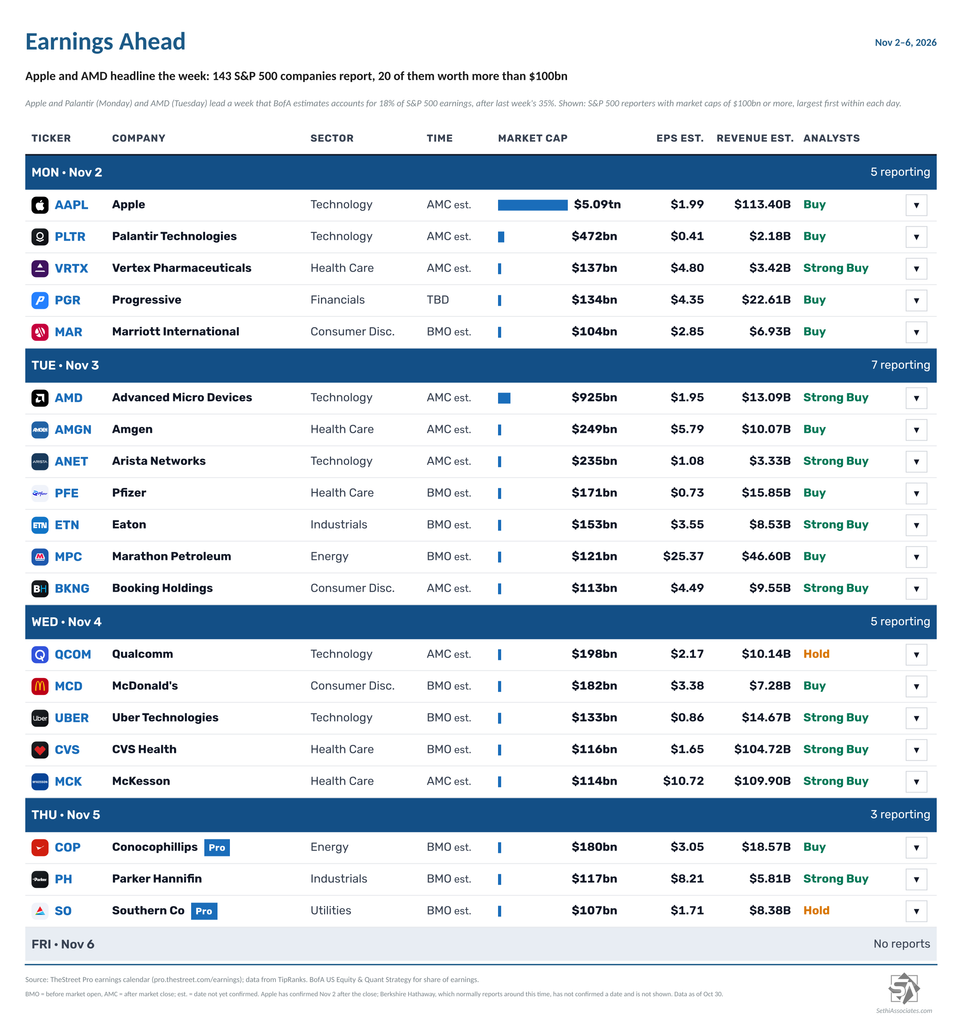
Meanwhile, Q3 earnings season continues with 143 S&P 500 components reporting (18% of index earnings, according to BofA), 20 of them with market caps over $100bn:
- Monday: Apple (AAPL), Palantir (PLTR), Vertex Pharmaceuticals (VRTX), Progressive (PGR) and Marriott (MAR)
- Tuesday: AMD (AMD), Amgen (AMGN), Arista Networks (ANET), Pfizer (PFE), Eaton (ETN), Marathon Petroleum (MPC) and Booking Holdings (BKNG)
- Wednesday: Qualcomm (QCOM), McDonald’s (MCD), Uber (UBER), CVS Health (CVS) and McKesson (MCK)
- Thursday: ConocoPhillips (COP), Parker Hannifin (PH) and Southern Co. (SO)
Berkshire Hathaway (BRK.B) normally reports around this time as well but hasn’t confirmed a date.
Outside the S&P 500, Novo Nordisk (NVO), Arm Holdings (ARM), Sony (SONY), Toyota (TM) and Cloudflare (NET) also report.
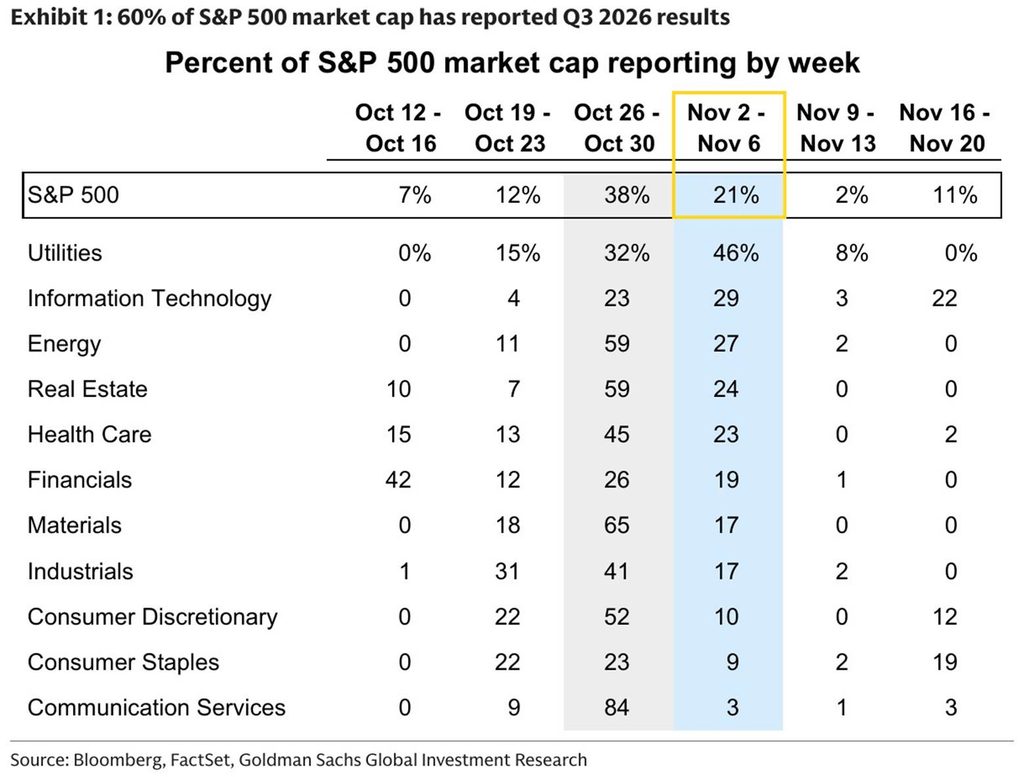
Goldman notes this week brings 143 companies accounting for 21% of S&P 500 market cap, including nearly half of Utilities (46%) and 29% of Info Tech.
Ex-US highlights from Deutsche Bank:
“In Europe, central bank decisions are due in the UK, Norway and Sweden, and a number of economic activity indicators are out in Germany. Highlights in Asia include PMIs in China and wages in Japan… Our UK economists… expect the MPC to raise Bank Rate to 4%, delivering the first rate hike since 2023.
“A number of September economic indicators are due in Germany, including retail sales (Monday), factory orders (Thursday) and industrial production (Friday). October CPI prints are due for Switzerland (Tuesday), Eurozone (Wednesday) and Sweden (Thursday). Over in Asia, economic data in focus includes October official PMIs [Saturday] and private gauges on Monday (manufacturing) and Wednesday (services) in China as well as September wages in Japan on Thursday. In Australia, the RBA will decide on rates on Tuesday and our economists expect a hold… Rounding out notable events, there will be a meeting on production policy amongst OPEC+ countries on Sunday.”
And here is a link to TipRanks’ Economic Calendar.
And a link to Bloomberg’s Week Ahead (gift link).
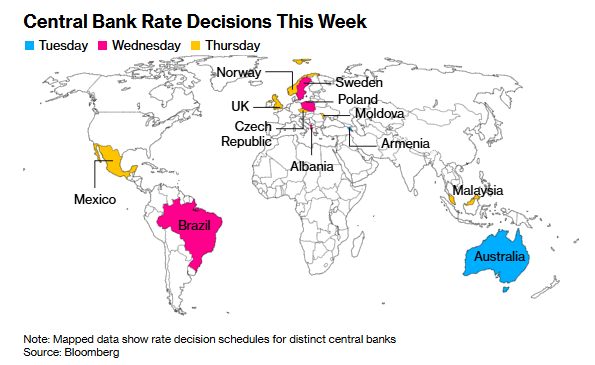
And a link to Christophe Barraud’s international Week Ahead rundown.
This post will go through in order (in case you want to skip around): the economy, the Fed and interest rates, earnings, valuations, breadth, positioning, sentiment, seasonality, and then my wrap-up.
The Economy Keeps Beating Expectations
Looking first at the economy, my intro has remained the same since the start of the Iran conflict (and longer term, more or less all of the past five years – I’ve not had a recession probability above 40% since the pandemic): “we continue to see it weathering the various storms remarkably well due in large part to resilient consumption (boosted by huge increases in wealth over the past few years despite slowing incomes) and AI-spending… with data of late showing a stable (and perhaps accelerating) economy, but one that is also boosting inflation.”
Last week was heavy on data, and for the most part it remained consistent with the foregoing:
- Q3 GDP grew 3.37% annualized, the fastest since Q3 2025 and above the 3.2% consensus, on strong consumer and equipment spending (Q3 GDP Beats on Strong Consumers and Equipment Spending).
- September core PCE prices rose 0.3% (0.317% unrounded), the most since February, lifting the annual rate to 3.12%, in line with expectations. That dragged on real consumer spending which came in flat inflation-adjusted and incomes which fell the most since April (Inflation Remains Elevated as Real Spending Stalls).
- Q3 employment costs rose 0.8% q/q, in line with expectations, with year-over-year compensation growth slowing to 3.37%, the least since Q2 2021, and real compensation falling further negative (Fed’s Favorite Wage Metric Shows Slowest Annual Gain Since 2021 as Real Pay Remains Negative).
- Initial jobless claims edged down to 194,000, with the four-week average the lowest since 1969 (Jobless Claims Refuse to Budge as Four-Week Average Hits Lowest Since 1969).
- ADP’s preliminary weekly estimate showed private employers adding 67,000 jobs in the four weeks ending October 10th, a second week of slowing and the fewest since the period ending August 29th, with the four-week moving average down for a second week to 85,500 from a September 26th peak of 93,750 (ADP Hiring Growth Slows for Second Week).
- September durable goods orders rose 1.8%, boosted by aircraft, while core equipment shipments grew at their fastest quarterly pace since 2020 (Business Investment Gauge Sees Fastest Quarterly Growth Since 2020).
- The September goods trade gap widened to an 18-month high on record capital goods imports (the category that contains AI-related equipment), even as exports rose more than expected (AI Imports Push Goods Trade Gap to 18-Month High).
- Conference Board consumer confidence jumped to the highest since June, even as consumers planned less spending on services and durable goods (Consumer Confidence Rebounds to Highest Since June).
- September new home sales came in better than expected even as prices rebounded from the lowest since 2021 (New Home Sales Hold Near Year’s High Even as Prices Rebound).
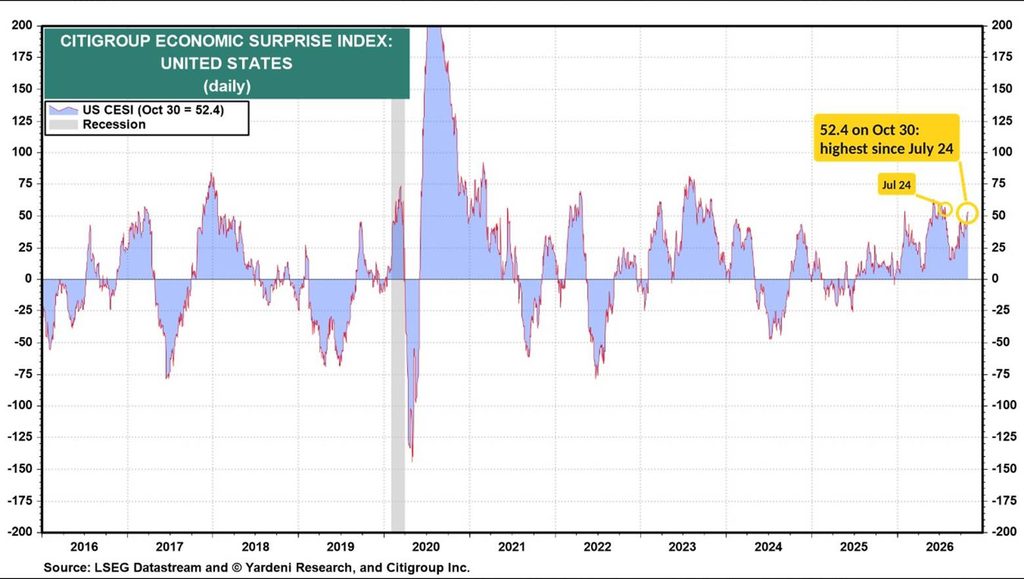
With the data continuing to come in better than expected, the Citi US Economic Surprise Index rose to 52.4 on Friday, its highest since July 24th, up from 44.4 a week earlier.
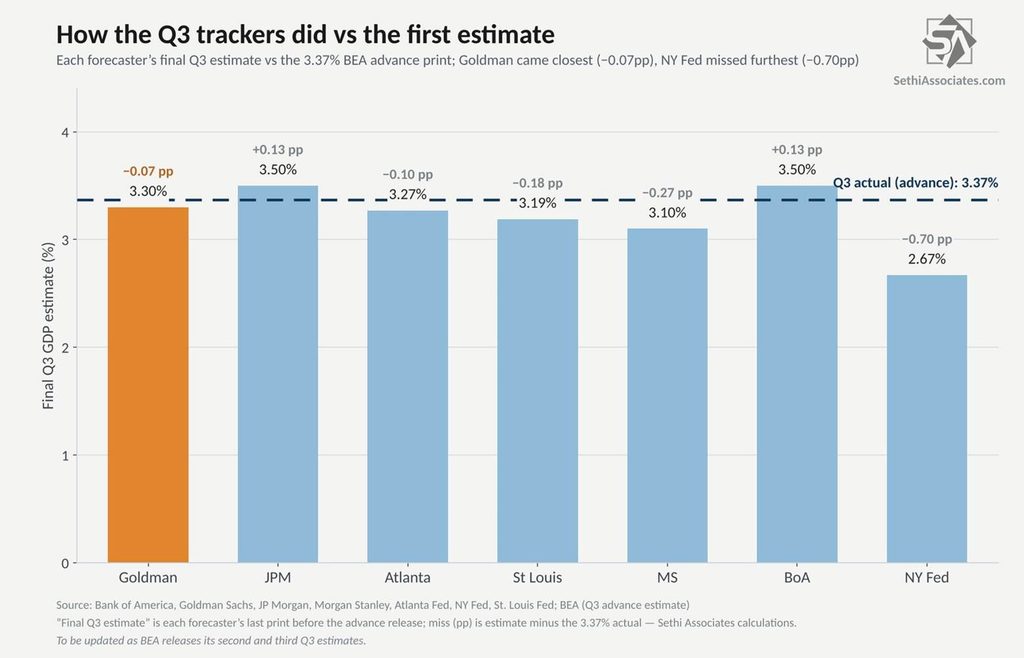
As noted above Q3 GDP came in at 3.37%, and Goldman’s tracker came closest as of last Friday’s readings, but only one tracker was off by more than 0.3% which was the NY Fed at 2.67%. In terms of the Atlanta Fed’s GDPNow, if you missed it I dove into its tendency in third quarters to come in close to but above its last read (Q3 GDP Trackers Cluster Near 3.3%, but GDPNow’s History Says Watch for an Upside Miss).
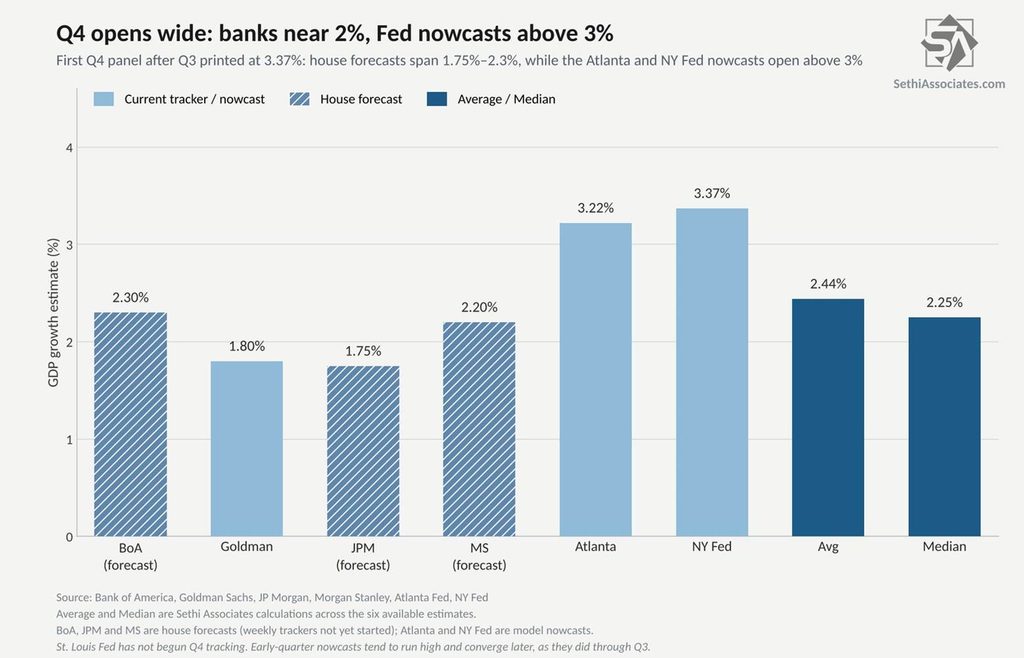
For Q4, the early readings are spread out which is not unusual at the start of a quarter (in that regard, the very close clustering for Q3 was though unusual). Goldman started tracking at 1.8% and the NY Fed at 3.37%, while the Atlanta Fed’s GDPNow opened at 3.22%. BofA, JPM and Morgan Stanley haven’t started tracking yet, but their forecasts are 2.3%, 1.75% and 2.2%, and the St. Louis Fed hasn’t begun. Across the six, the average is 2.44% and the median 2.25%.
Remember though that GDPNow’s early nowcasts have historically run high. It has started above the advance print in 34 of 57 quarters (ex-2020), by 0.40pt on average, and all three 2026 openings ended well lower (Q1 3.13% → 1.99%, Q2 3.70% → 1.50%, Q3 4.95% → 3.37%). For more on the GDPNow see GDPNow Tracking Slowdown in Q4.
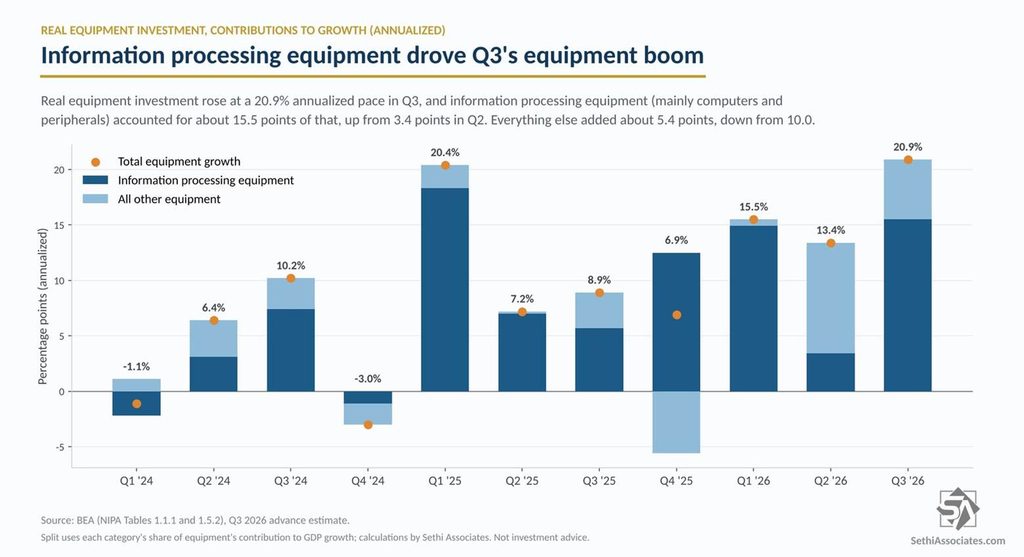
Under the hood, both JPM and Morgan Stanley highlighted how much of Q3’s strength came from AI along with surprisingly resilient consumer spending. Real business investment rose at a 12.7% annualized rate, which JPM says is the fastest in 20 years outside of post-recession recoveries, led by a 20.9% jump in equipment (information processing equipment +37.3%, per MS), while MS notes spending on data centers rose 127%. But the gains were narrower than in Q2. JPM estimates non-tech investment contributed just 1.6 points of the 21% rise in equipment spending, versus 8.2 points the prior quarter. JPM (Feroli) also brings up a fact frequently cited by economists which is a good amount of that spending is imported reducing its GDP impact:
“Much of the related equipment is manufactured abroad, and some of it is produced in a very capital-intensive manner, so the immediate employment impact is probably more limited than the dollar figures might suggest. It also means investment is that much more dependent on the trajectory of a single industry.”
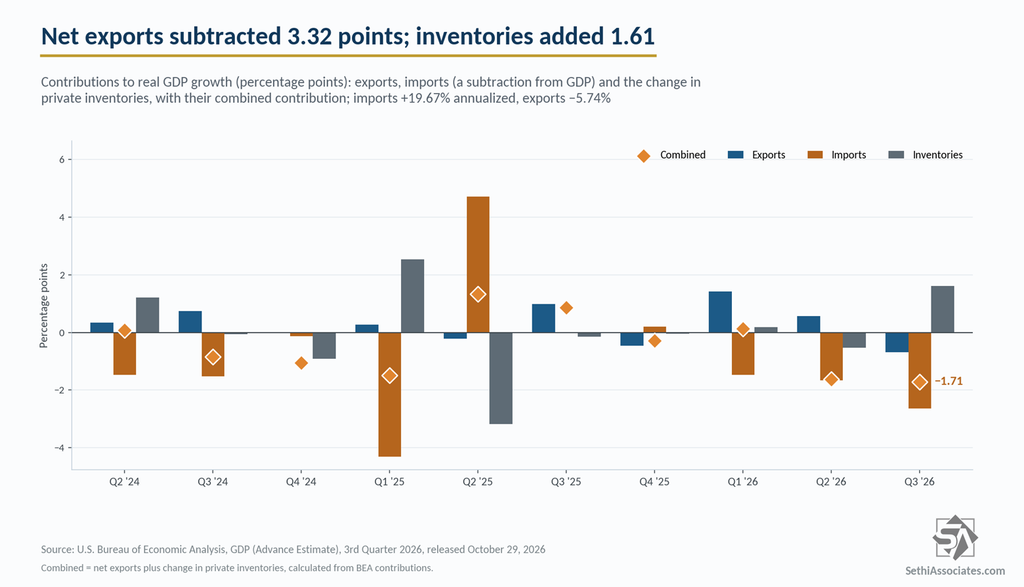
BEA’s own breakdown tells the same story. Per Claude, information processing equipment (mainly computers and peripherals) accounted for about 15.5 points of Q3’s 20.9% equipment gain, up from 3.4 points in Q2, while everything else added about 5.4 points, down from 10.0. (JPM’s 1.6 points uses a broader definition of tech.) But trade subtracted 3.32 points, the most since Q1 2025.
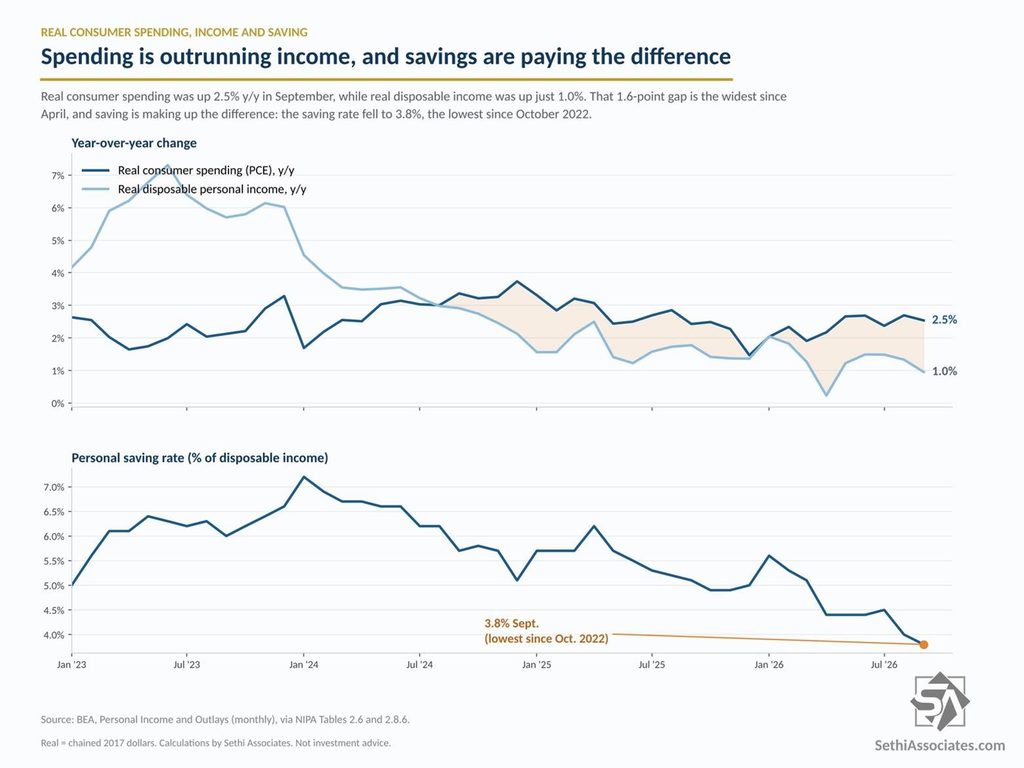
Real consumption grew at a 3.8% pace for a second straight quarter, but with real income growth tepid, the saving rate fell to 3.8% in September. Morgan Stanley (Gapen):
“Household spending is running faster than income, which suggests that the consumer cannot indefinitely sustain the recent two-quarter pace of growth by drawing further down on saving. The four-quarter change in consumer spending through the third quarter at 2.5% is probably closer to the truth.”
Real disposable income was up just 1.0% y/y in September versus 2.5% for real spending, the widest gap since April, and the saving rate is the lowest since October 2022.
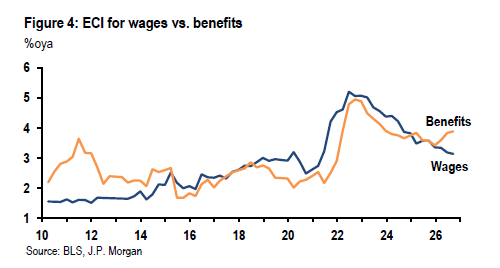
Like MS, for Q4, JPM looks for growth to slow in their case to 1.75%, noting real consumption was flat in September and Chase card data suggest subdued October retail spending. That contrasts with GDPNow’s starting point and the firmer BofA card data below. On wages, JPM notes ECI compensation has held at 3.4% y/y for four straight quarters, with wage growth slowing to a new cycle low of 3.1% while benefit costs (health care +6.4% y/y) accelerated.
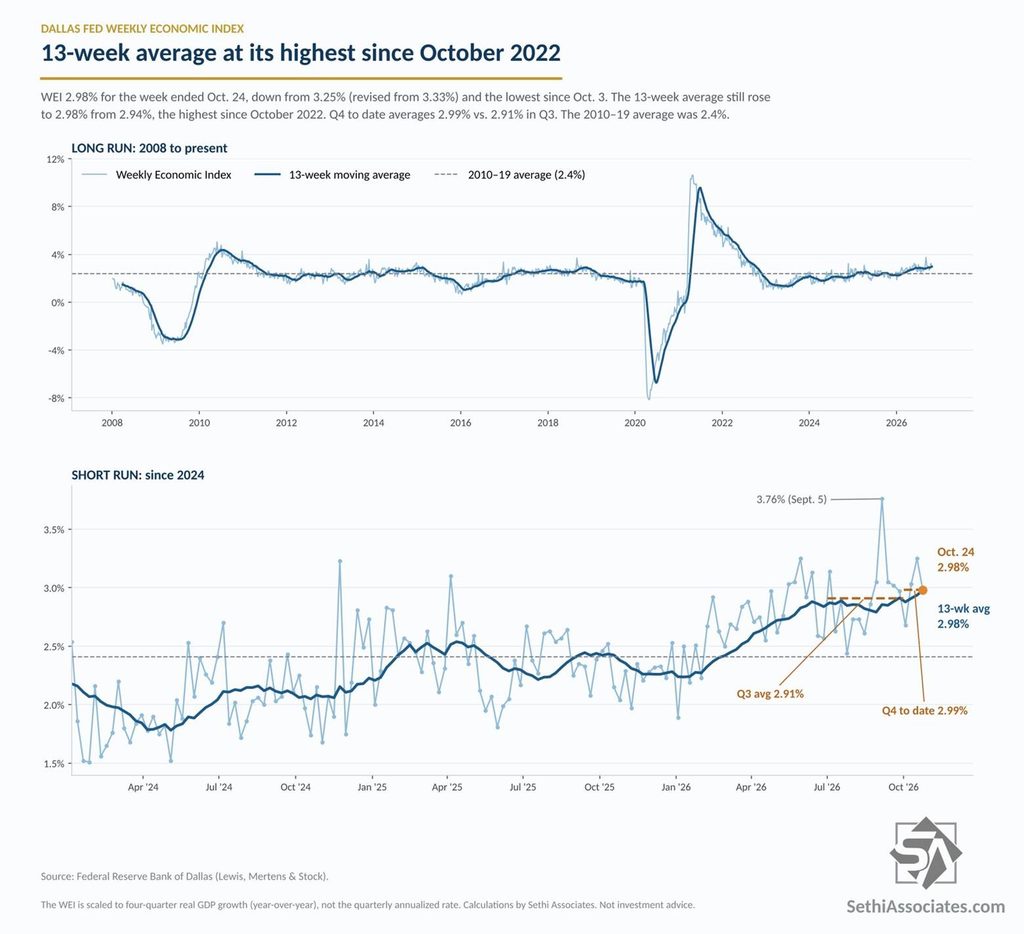
The Dallas Fed Weekly Economic Index (WEI)* slipped to 2.98% in the week through October 24th (so it doesn’t include last week’s data) from 3.25% the prior week (revised down from 3.33%), the lowest since the week of October 3rd.
More importantly, the 13-week average still rose to 2.98%, the best since October 2022, continuing to show economic momentum above trend (the 2010–19 average was 2.4%). Q4 to date it’s averaging 2.99%, a touch above Q3’s 2.91%.
But note it has run high the past two quarters. For Q3 it averaged 2.91% against actual y/y growth of 2.07%, its biggest overestimate since Q3 2022, after 2.84% vs. 2.19% in Q2. Part of that gap reflects the weak Q4 2025 quarter still in the y/y comparison, as the last two quarters averaged about 2.8% annualized.
*The WEI is scaled as a y/y rise for real GDP (so different from most GDP trackers, which are Q/Q SAAR), uses 10 daily and weekly economic series and runs a week behind other GDP trackers. It has tracked actual GDP closely over time (a 0.92 correlation since 2008).
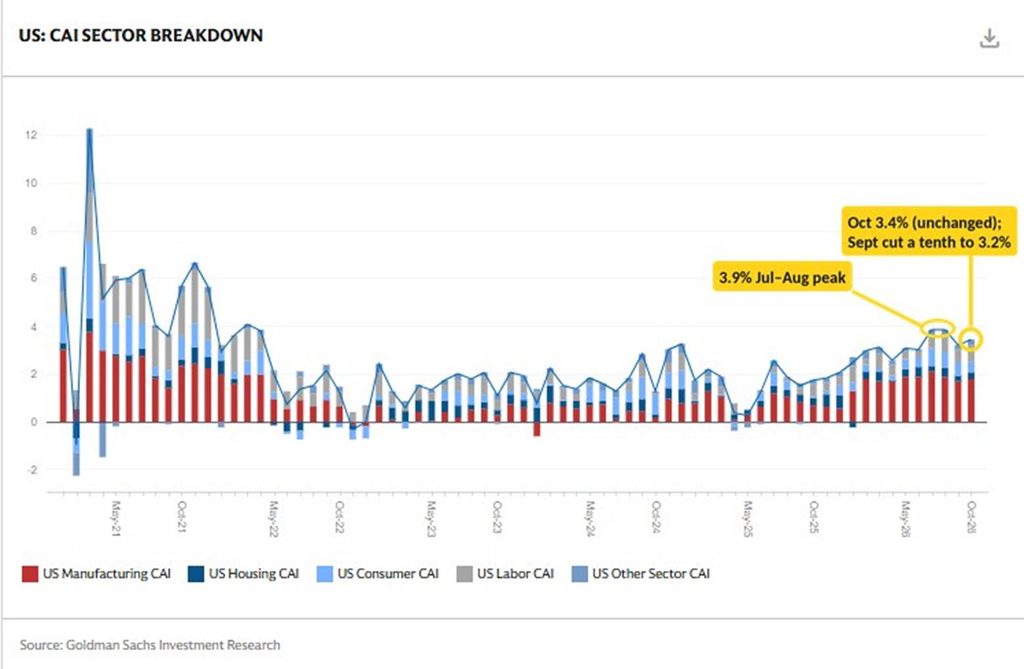
Goldman’s Current Activity Indicator* held at 3.4% in October, though September was revised down a tenth to 3.2%. Still, other than the post-2022 peak of 3.9% in July and August, it’s the best since then.
*The CAI is their “real-time measure of inflation-adjusted economic momentum using 37 inputs.”
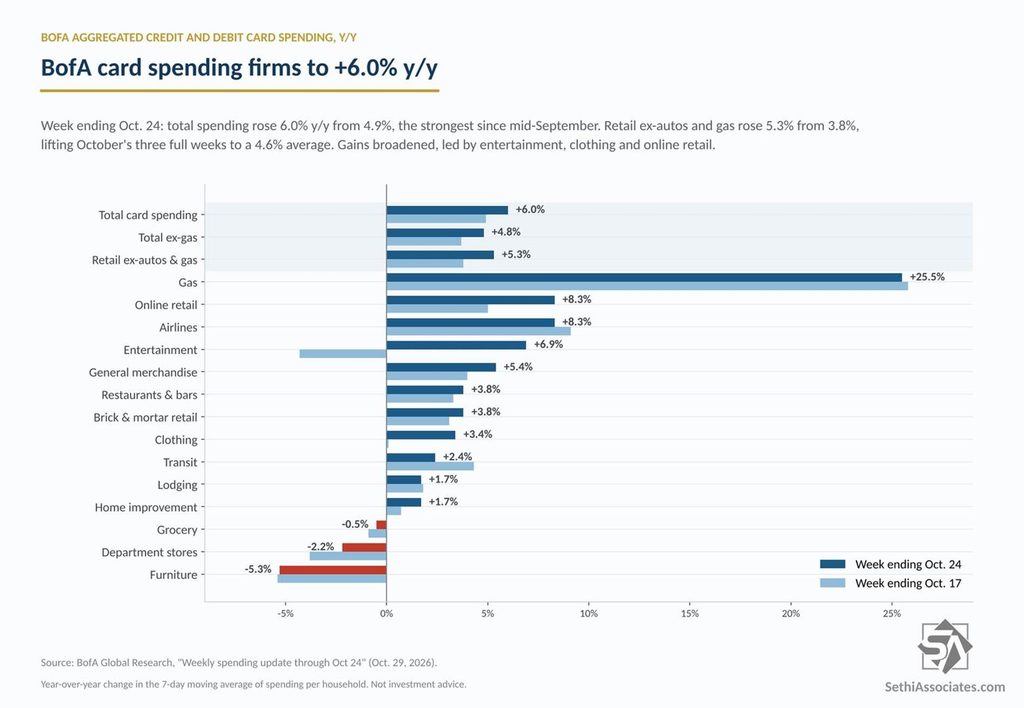
BofA card spending (credit+debit) firmed to a robust +6.0% versus the year-ago period (y/y) in the week ending October 24th, up from +4.9% the prior week and the strongest reading since mid-September. In particular, ex-gasoline and autos spending growth rose to +5.3% y/y from +3.8%, back to its late-September pace, lifting October’s three full weeks to an average of +4.6%.
- Total +6.0% y/y (+4.8% four-week moving average)
- Ex-gasoline +4.8% y/y (+3.6% four-week moving average)
- Ex-autos and gasoline +5.3% y/y (+3.9% four-week moving average)
BofA said spending growth strengthened broadly relative to the prior week, led by entertainment, clothing and online retail. On the income split, BofA again noted that lower-income spending growth has consistently outpaced higher-income over the past several weeks.
Gasoline held at +25.5% y/y (from +25.8%), still elevated versus a year earlier.
Among categories, entertainment swung to +6.9% from −4.3%, clothing rose to +3.4% from +0.1%, and online retail jumped to +8.3% from +5.0%. General merchandise (+5.4%, from +4.0%), restaurants & bars (+3.8%, from +3.3%) and home improvement (+1.7%, from +0.7%) also firmed. Airlines eased to +8.3% from +9.1% and transit to +2.4% from +4.3%, the only meaningful decliners.
Three categories were negative y/y, down from four the prior week: furniture (−5.3%), department stores (−2.2%, improved from −3.8%), and grocery (−0.5%).
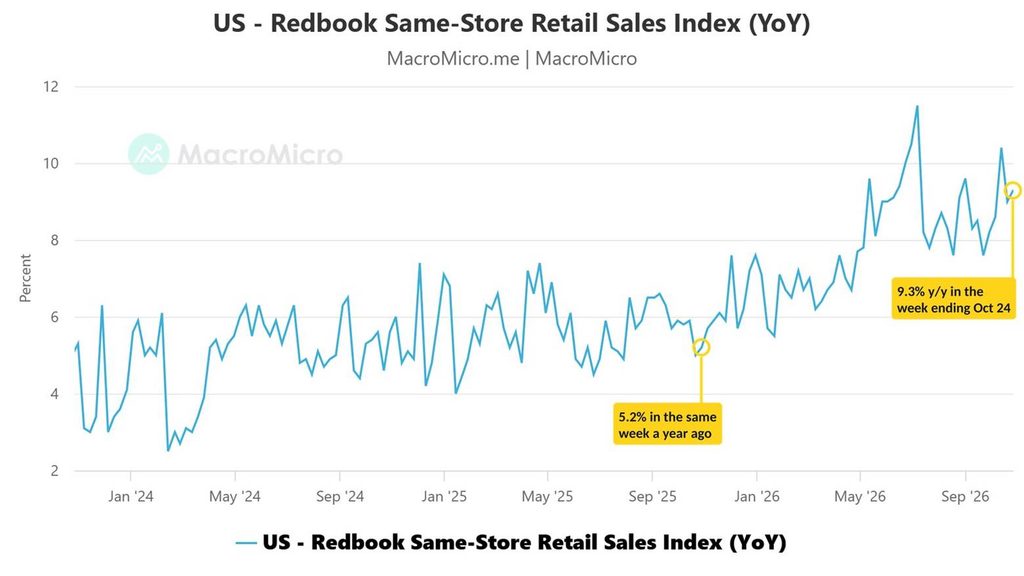
Redbook sales* rose 9.3% y/y in the week ending October 24th, up from 9.0% the prior week and well above the 5.2% in the same week a year ago.
*Redbook sales are same-store sales across a panel of large general-merchandise retailers, such as department stores, discount chains, apparel retailers, drugstores, and warehouse clubs.
A Not-So-Hawkish Hold
The FOMC held at 3.75% to 4% in a 10-2 vote, with Governor Lisa Cook and Cleveland Fed President Beth Hammack dissenting in favor of a hike, while offering no clear signal on December (FOMC Holds Rates Steady; Governor Cook Dissents). The statement said the “accumulation of more information will help the committee determine the policy stance appropriate to ensure a timely return of inflation to the committee’s 2% goal.”
Friday’s speakers leaned hawkish, but they were also some of the more hawkish coming into the decision showing the balance of power remains in the core of the Fed which though lost a member with Cook’s dissent. Still it seems that Governors Warsh, Jefferson, Powell, Waller, and Bowman along with NY Fed President Williams (who is the Vice-Chair of the FOMC) are roughly aligned, and while Governor Barr has like Cook been more hawkish in his appearances, he also fell in line suggesting he remains loosely part of the core. That is seven votes which is all that is needed for a decision whatever the other members want.
In terms of those speakers, Dallas Fed President Logan said the FOMC needs at least two more 25-basis-point hikes, St. Louis Fed President Musalem said “additional firming of monetary policy will be necessary, and soon,” and Richmond Fed President Barkin said a “gradual approach” makes sense because the Fed is “not much behind the curve,” per the WSJ.
Barkin (not a voter this year but will be in 2027), who has been less hawkish than the other two, in a SiriusXM interview Friday, agreed with Logan and Musalem that “the direction of travel is pretty straightforward — the question, though, is pace,” adding “[a] gradual approach is a good way to go.” What’s driving his view is demand: consumer spending has been surprisingly resilient given relatively flat incomes, businesses tell him cost pressures are broad-based, and the AI investment surge is straining supply chains, “that kind of demand-side inflation,” adding “if we do see a continued surge in demand, that would be the kind of thing you might want to lean against.”
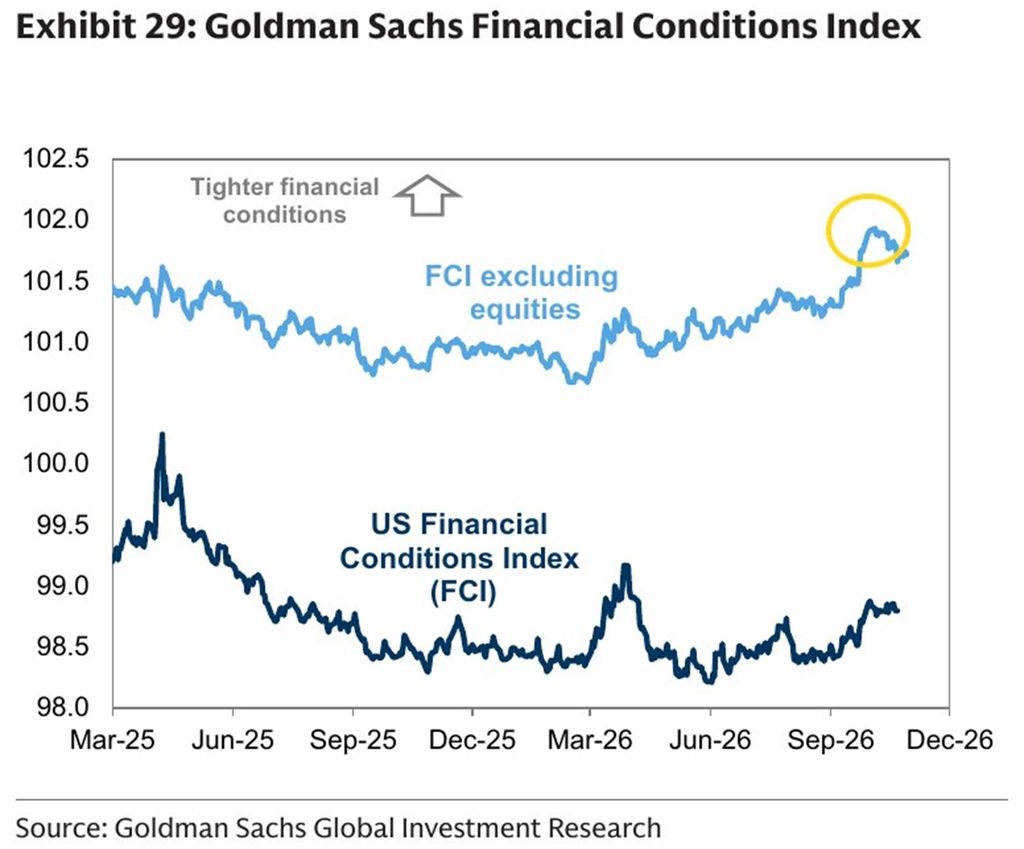
Goldman’s Financial Conditions Index backs up Warsh’s point about tighter conditions. Excluding equities, it rose in October to its tightest since at least March 2025 (the start of Goldman’s chart), though it has eased a bit since as bonds yields tapered off, while the overall index is also well above year-ago levels. The gap between the two indices is consistent with my note last week that much of whatever looseness there is in financial conditions is a function of equities, meaning the Fed has to be sensitive to creating a large equity selloff.
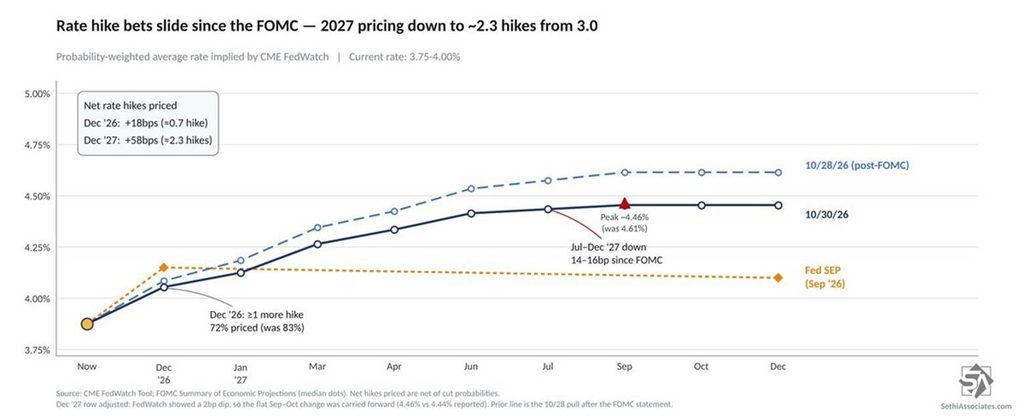
And consistent with that, and given AI’s importance to the economy (both the investment mentioned earlier and the wealth effect from huge gains in AI-related stocks, which has supported consumer spending despite falling incomes), Fed rate hike expectations fell along with the AI names last week.. December ended the week at a 72% chance of a hike (from 78% a week earlier and 83% right after the FOMC), with 58 basis points of hikes priced through December 2027 (about 2.3 hikes), down from 68bp a week earlier (and 74bp, about three hikes, right after the FOMC), per CME FedWatch (18bp priced by December 2026, from 21bp after the FOMC).
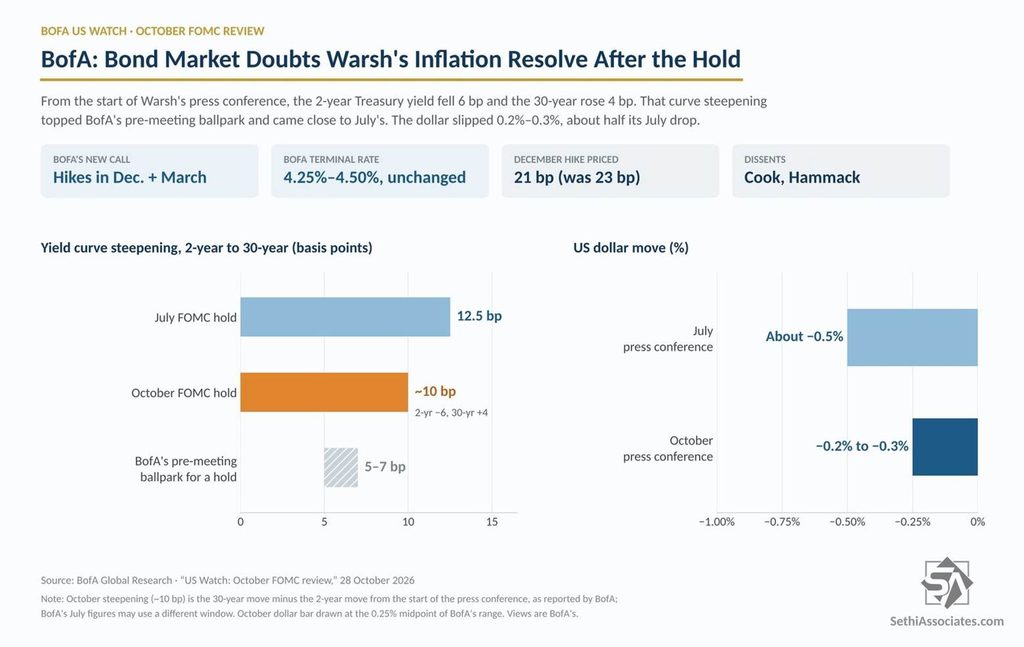
I mentioned the October rate hike call from BofA was curious particularly given they said they had low conviction. So where did they pivot to? BofA senior US economist Aditya Bhave called it “a not-so-hawkish hold.” Warsh pointed to tighter financial conditions as a sign the September hike is working and wouldn’t lean into a December move, which BofA calls dovish since markets are pricing one. BofA’s rates strategist Mark Cabana says the bond market didn’t see Warsh as credible on inflation:
- From the start of the press conference, the 2-year yield fell 6 bp and the 30-year rose 4 bp. That steepening was bigger than BofA’s 5–7 bp ballpark and not far from July’s 12.5 bp
- The dollar fell 0.2%–0.3%, about half its July drop
- December hike pricing slipped to 21 bp from 23 bp
BofA now expects hikes in December and March, with its 4.25%–4.50% terminal rate unchanged and held through the end of 2027. It warns the long end will “continue to haunt” the Fed until it gets more serious on inflation, and says the move raises the odds Treasury trims long-end auction sizes at Wednesday’s refunding.
JPM and Morgan Stanley also still expect a December hike, with MS also looking for one in March (to 4.25%–4.5%). JPM (Feroli) on Warsh’s press conference:
“The post-meeting press conference left many Fed observers, including ourselves, scratching their heads. The first question… was to ask about the rationale for pausing when there had been no progress on inflation since the last meeting. Warsh gave a reply that lasted over three minutes, but that didn’t directly answer the question.”
MS says it would take a large correction in asset markets to derail December, adding that “an equity market decline would need to be larger than people think (e.g., more than 10%).” And Ed Yardeni goes further, saying “Fed officials are likely to signal a bigger rate hike in December than expected, say 50bps rather than 25bps,” now that the blackout period is over (I think that is unlikely and while Ed has been an astute player of equity markets his Fed calls have been much less accurate).
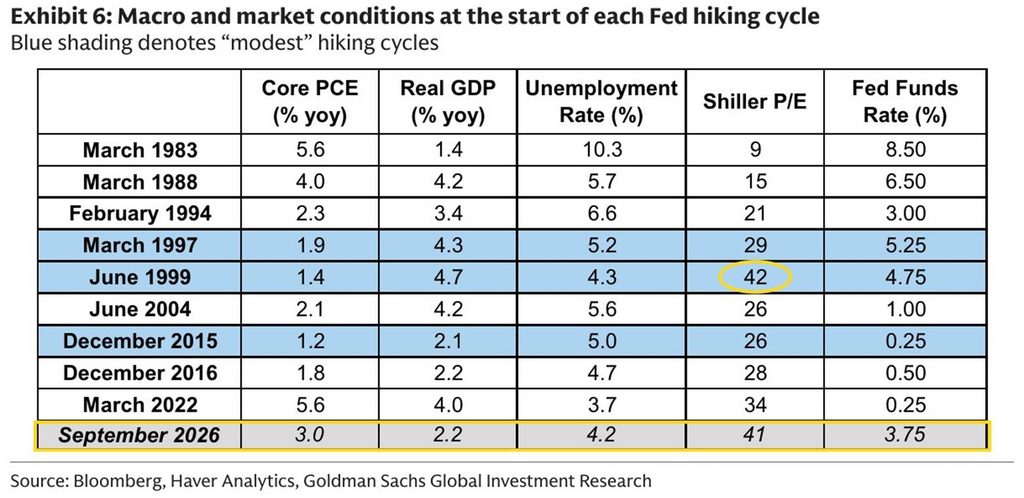
So what does a “modest” hiking cycle mean for markets? Goldman:
Tightening cycles have historically been longer and larger than this one is expected to be, and there are a limited number of historical examples of modest hiking cycles. 1997 and 2015 were cycles where the Fed hiked only once, and 1999 was the next smallest hiking cycle at 175bps of tightening. We bucket those three smallest and shortest hiking cycles (1997, 1999, and 2015) as ‘modest’ tightening cycles and the larger and longer cycles as ‘other cycles’ (1983, 1988, 1994, 2004, 2016, 2022)…
-Equities tend to struggle after the first hike but recover quickly.
-Both front- and long-end yields tend to rise in anticipation of the first hike. In the median, yields tend to peak locally shortly after the first hike in modest hiking cycles but continue to rise for some time in other cycles.
-The curve tends to flatten into the first hike, and this flattening tends to continue after the first hike…Our rates strategists similarly noted that front-end forward yields usually peak around the end of rate hikes and after the peak in inflation is confirmed in the data and that, after the peak in forward yields, flattening tends to stop as the curve rallies in parallel.
-The real trade-weighted US Dollar tends to strengthen into the first hike, but its performance afterwards has been mixed across cycles.
Goldman’s Vickie Chang adds some detail. In the median of both modest and larger cycles, equities troughed within two months of the first hike and recovered within four. Six-month returns were flat to positive in every cycle except 1994 and 2022, and 12-month returns were positive in all but 2022.
So far, so good: the S&P 500 is up 0.4% from its close on the day of the September 16th hike, even after Friday’s drop.
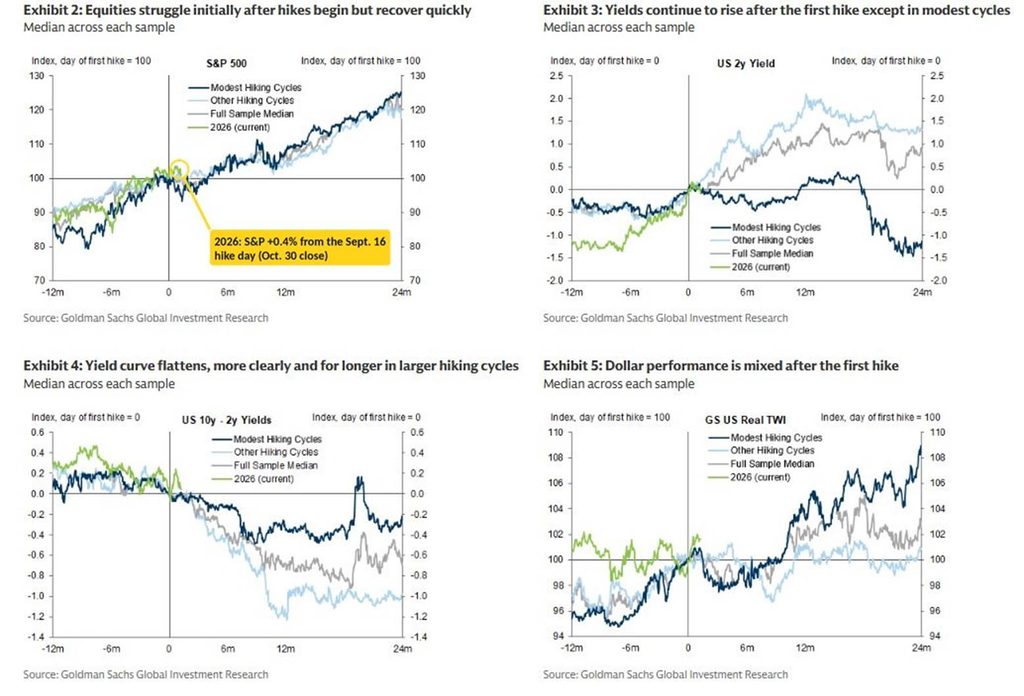
But the medians hide big differences among the three modest cycles, and this one doesn’t fit neatly into any of them. Goldman says 2026 has a strong labor market and a starting fed funds rate well above zero (closer to 1997 and 1999), growth more like 2015, equity valuations like 1999 (a Shiller P/E of 41 vs. 42 then), and core inflation (3.0%) well above the sub-2% readings at the start of all three.
The two one-hike cycles, 1997 and 2015, are closest to Goldman’s own call in terms of how much tightening we get (its economists expect just one more hike, while markets were pricing about three when Goldman wrote this on October 27th, and about two-and-a-third after Friday). In both, yields peaked around the hike and then fell. But in 1997, with strong growth and benign inflation, equities troughed quickly and rallied strongly, while in 2015 growth worries kept the S&P 500 rangebound for longer. In 1999, the Fed hiked into an investment boom with strong growth and high valuations similar to today. Yields kept rising, the S&P 500 stayed rangebound, and the tech bubble eventually burst, contributing to the 2001 recession.
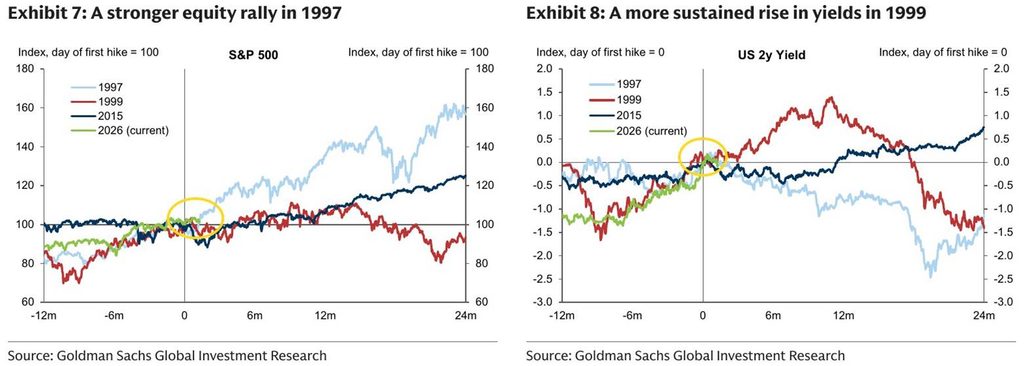
Goldman’s baseline (a modest number of hikes, growth around potential and gradual inflation relief) “should imply a modestly positive path for equities from here.” But it sees three risk scenarios:
- An earlier end to hikes on better inflation news, which “likely requires oil price relief,” would be “the most positive market scenario—a mild version of the 1997 experience.”
- An interruption on growth worries, most likely “if the pockets of financial stress that have emerged broaden into a wider issue,” would “likely be less friendly for risk assets initially but could then imply some relief, as in 2015.”
- And if growth holds up, “the risk… is that this is the start of a more extended tightening process driven by an investment boom, as in 1999, and that the longer that process continues the greater the risk of a more meaningful growth downgrade further down the road.”
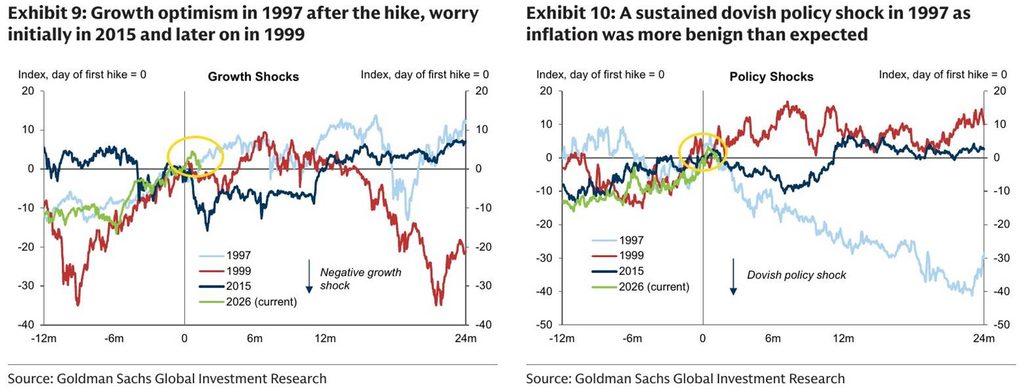
Goldman’s framework, which splits market moves into “growth” and “policy” shocks, shows how different those stories were: 1997 saw positive growth shocks and a sustained dovish policy shock after the hike, while growth worries hit early in 2015 and later on in 1999.
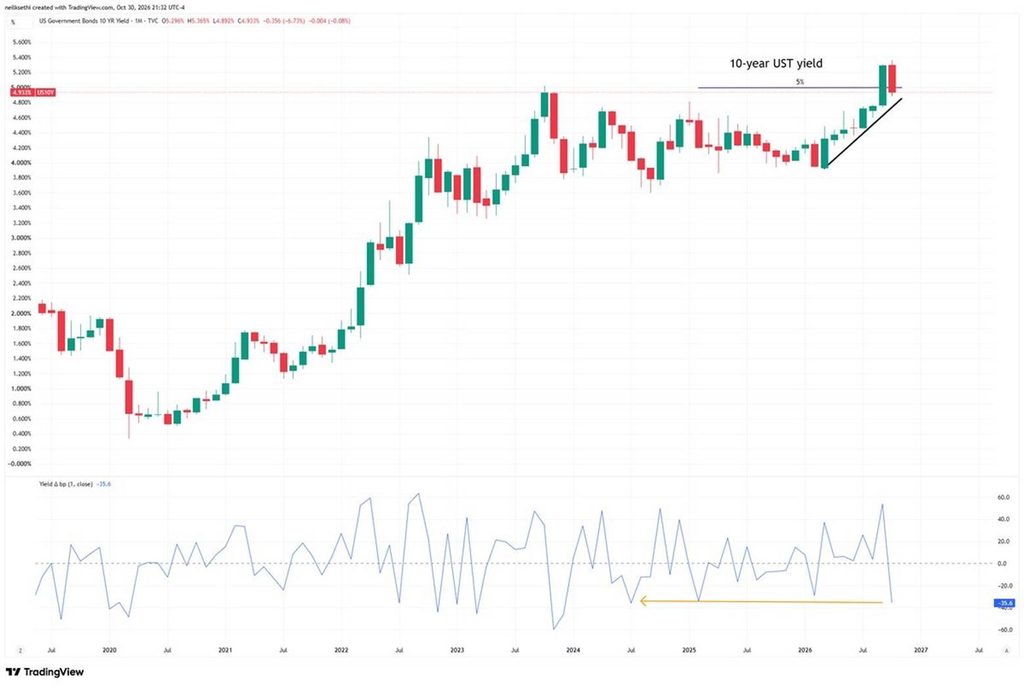
Turning to rates, Treasuries were the anti-AI trade in October, with the 10-year yield falling over 35 basis points in the month, the first monthly decline since the start of the Iran conflict and the largest since July 2024. The 2-year closed the week at 4.59% (−9bp w/w), the 10-year at 4.93% (−6bp) and the 30-year at 5.31%, so all three are now inside the ranges I set in early August (tops of 4.75%, 5% and 5.75%). Last week the 2- and 10-year were only barely back in.
Goldman’s asset allocation team thinks there’s more to come. It’s overweight US 10-year Treasuries on both 3- and 12-month views, looking for the 10-year yield to fall to 4.72% in three months, 4.62% in six and 4.44% in 12, from 5.03% on October 28th. Christian Mueller-Glissmann’s team says “markets are pricing a more restrictive monetary policy backdrop” and “more hawkish rates pricing has started to weigh on growth sentiment,” and the title of their October 12th report sums up the shift: bonds are “gradually moving from headwind to hedge.”
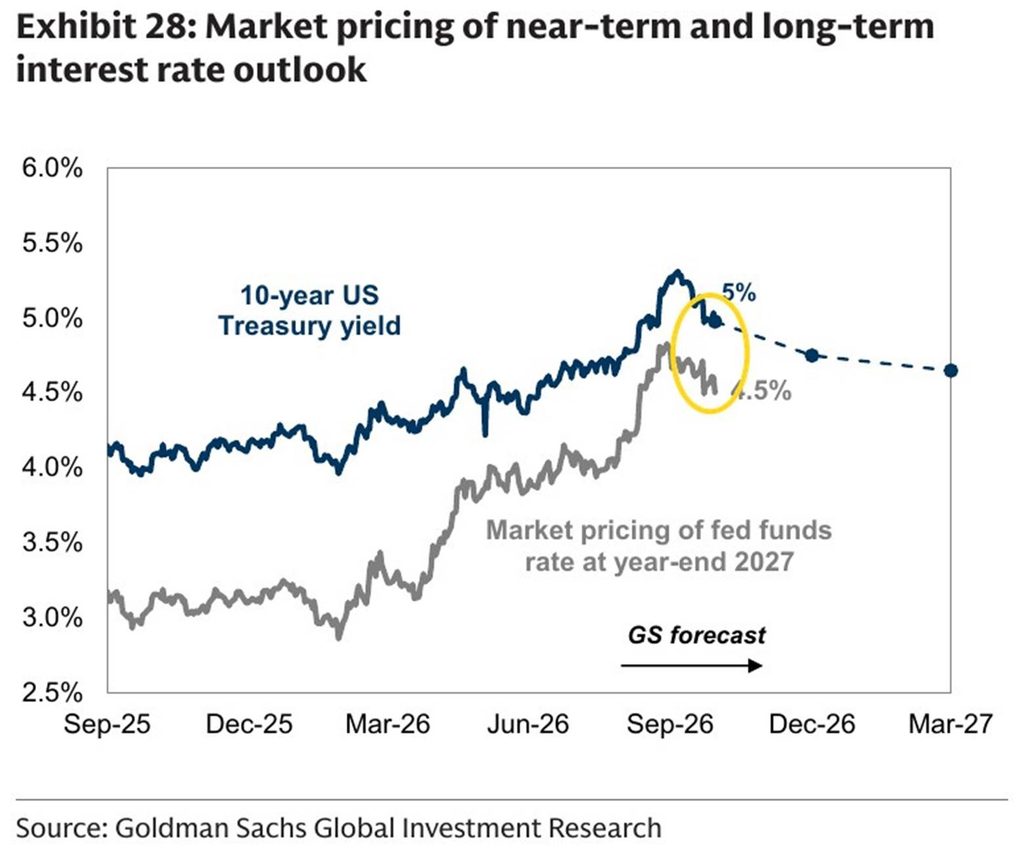
Goldman’s forecast path for the 10-year (dashed line) heads toward the mid-4s by March, while markets are pricing fed funds at about 4.5% at year-end 2027.
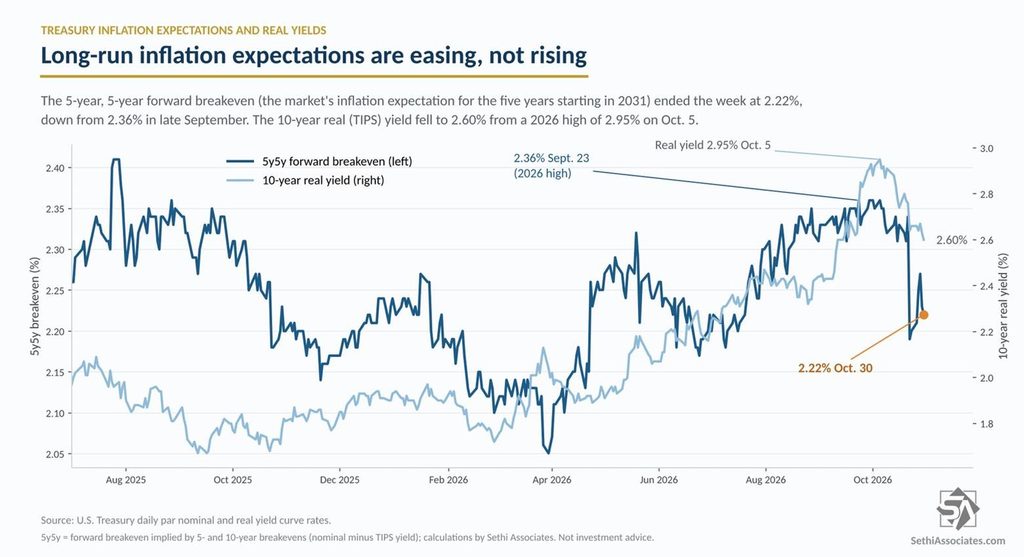
Underneath the drop in yields, long-run inflation expectations eased. The 5-year, 5-year forward breakeven (the market’s expectation for average inflation over the five years starting in 2031, a measure the Fed watches closely) ended the week at 2.22%, little changed from 2.20% a week earlier but down from its 2026 high of 2.36% on September 23rd. Shorter-run expectations are higher, with the 5-year breakeven at 2.46%, so the market sees the current inflation bump fading. The 10-year real (TIPS) yield fell to 2.60% from 2.66% a week earlier, its lowest since September 14th and down from its 2026 high of 2.95% on October 5th.
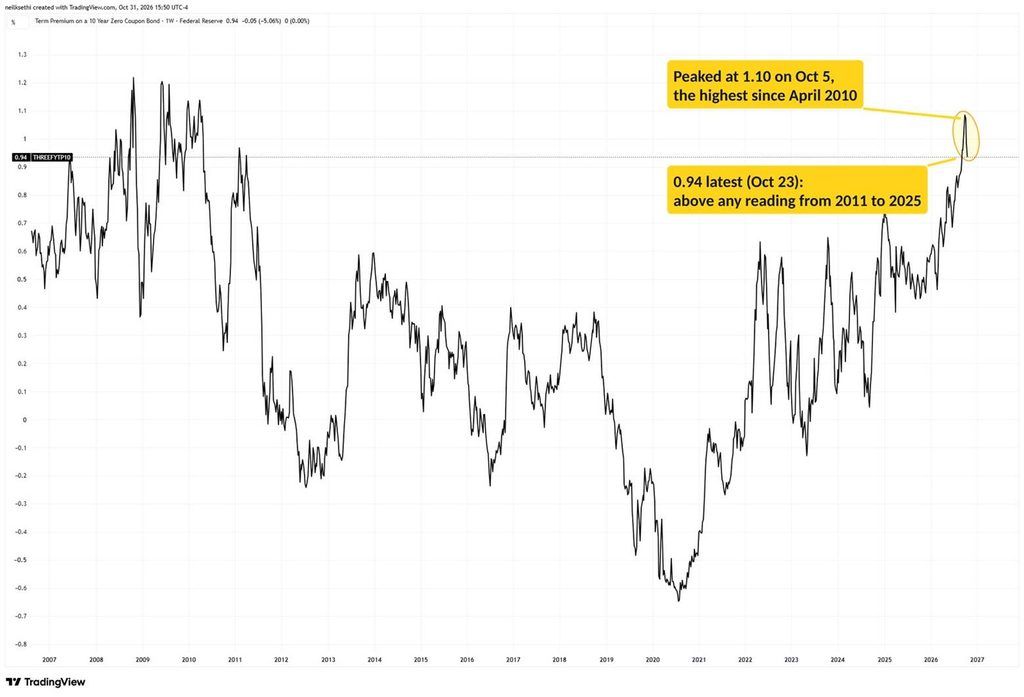
The term premium (the extra yield investors demand to hold longer-term bonds) is also coming off its highs. The Fed’s 10-year term premium (the Kim-Wright model) peaked at 1.10 on October 5th, the highest since April 2010, and was 0.94 in the latest reading (October 23rd), still above any reading from 2011 through 2025. The NY Fed’s ACM measure shows the same pattern, at 0.66 on October 29th from a 0.99 peak on October 7th, its highest since June 2014.
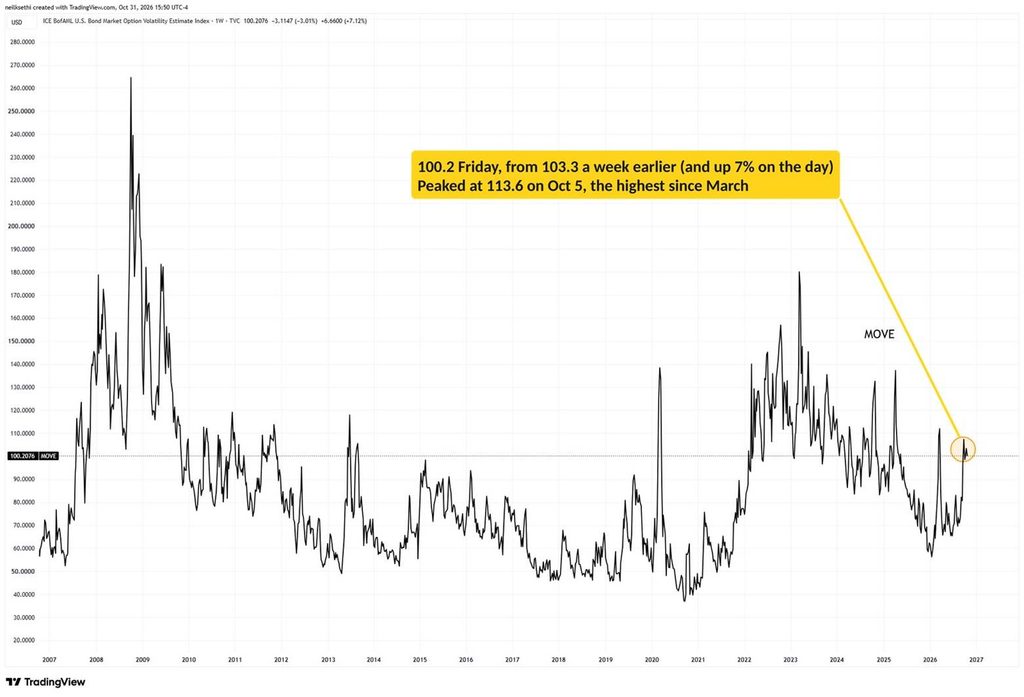
And bond volatility has calmed some. The MOVE index ended the week at 100.2, down from 103.3 a week earlier and from 113.6 on October 5th, its highest since March, although it jumped 7% Friday remaining elevated as sharp moves down are just as “volatile” as sharp moves higher.
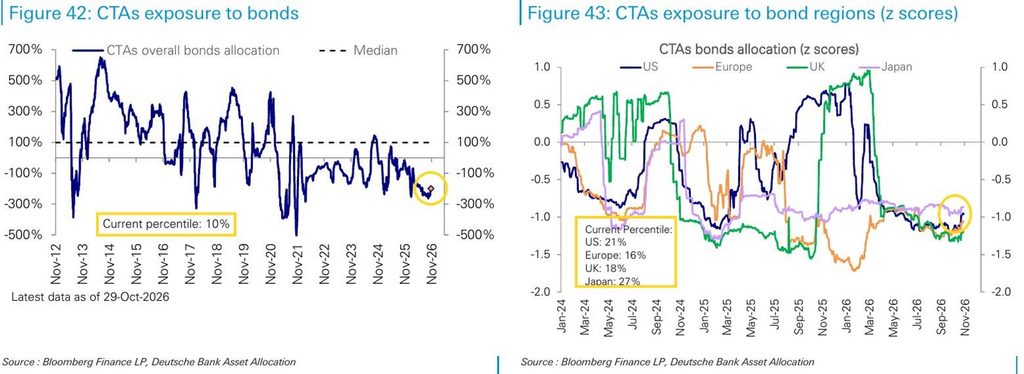
CTAs could help that along. DB continues to see only modest CTA covering in bonds, with US positioning at the 21st percentile (from the 17th) and global at the 10th (from the 7th).
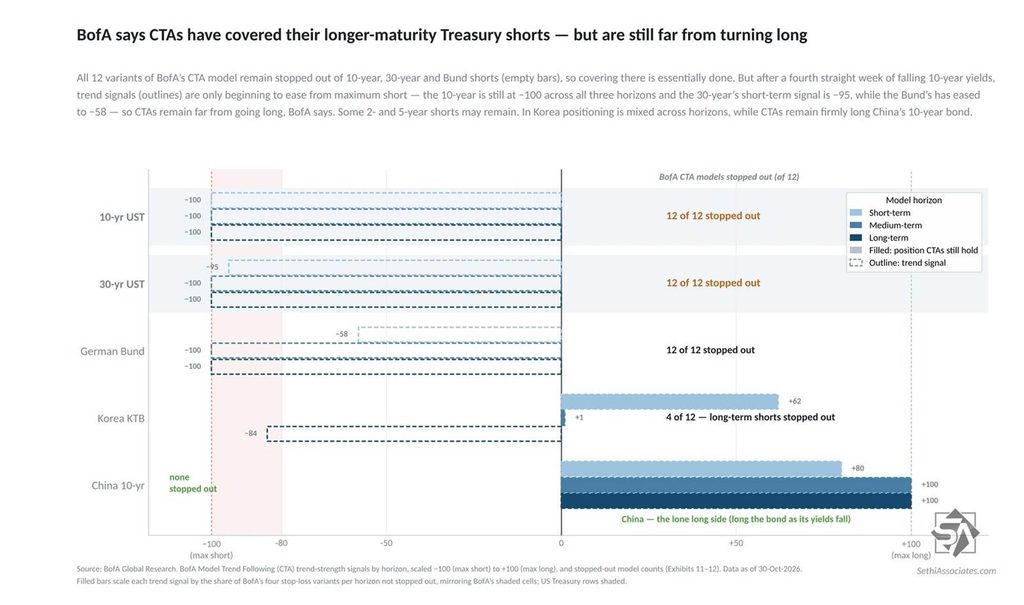
BofA sees CTAs with more short covering though with all 12 variants of its CTA model stopped out of 10-year, 30-year and Bund futures shorts. But after a fourth straight week of falling 10-year yields, trend signals are only beginning to ease from maximum short. The 10-year is still at −100 across all three horizons, so BofA says CTAs remain “far from establishing long positions.” On the short end they say some 2- and 5-year shorts may remain.
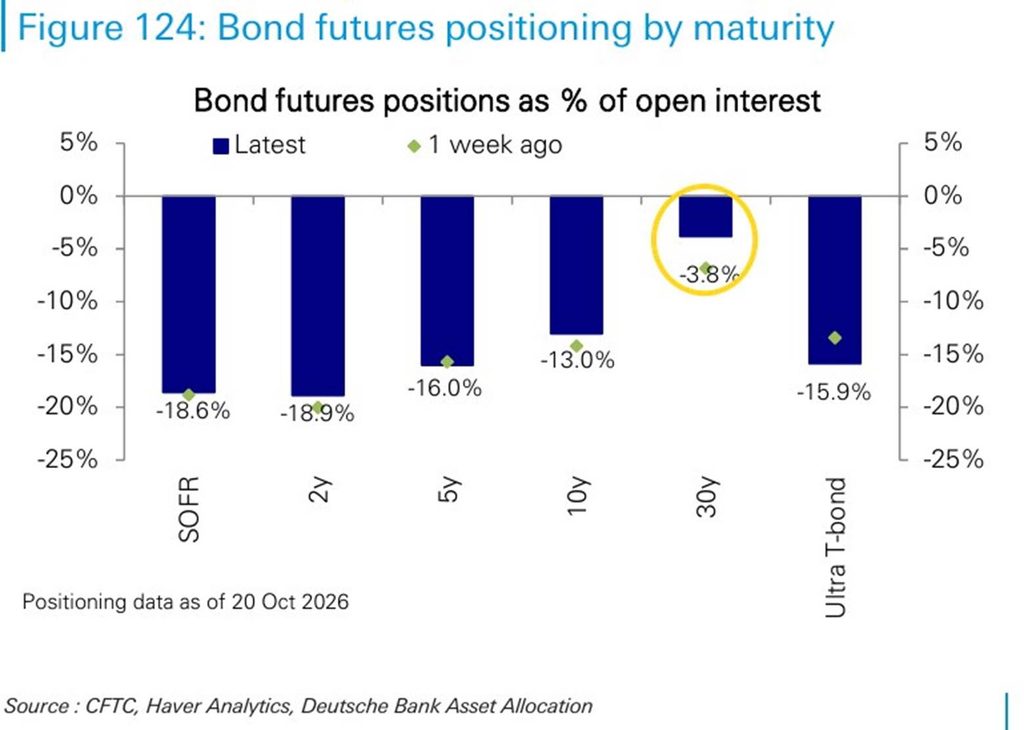
Looking more broadly, DB’s read of the CFTC data (as of October 20th) shows speculators still net short across the curve: net shorts are 18.9% of open interest in 2-year futures, 16.0% in 5-year, 13.0% in 10-year and 15.9% in the Ultra bond, but only 3.8% in the 30-year.
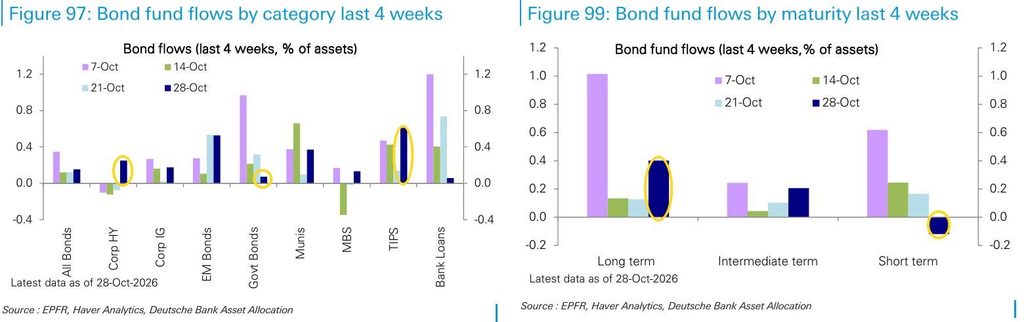
And bond fund flows continue to show investors buying the bond dip for a sixth week and last week extending duration. Per DB, long-term bond funds took in about 0.4% of assets in the week through October 28th, roughly triple the prior two weeks, while short-term funds saw outflows (about −0.1%), the first in the past four weeks. TIPS (about 0.6%), EM bonds (about 0.5%) and high yield (about 0.25%, its first inflow in four weeks) led, while government bond funds took in the least of the four weeks (about 0.07%).
Earnings Have Been a Mixed Picture
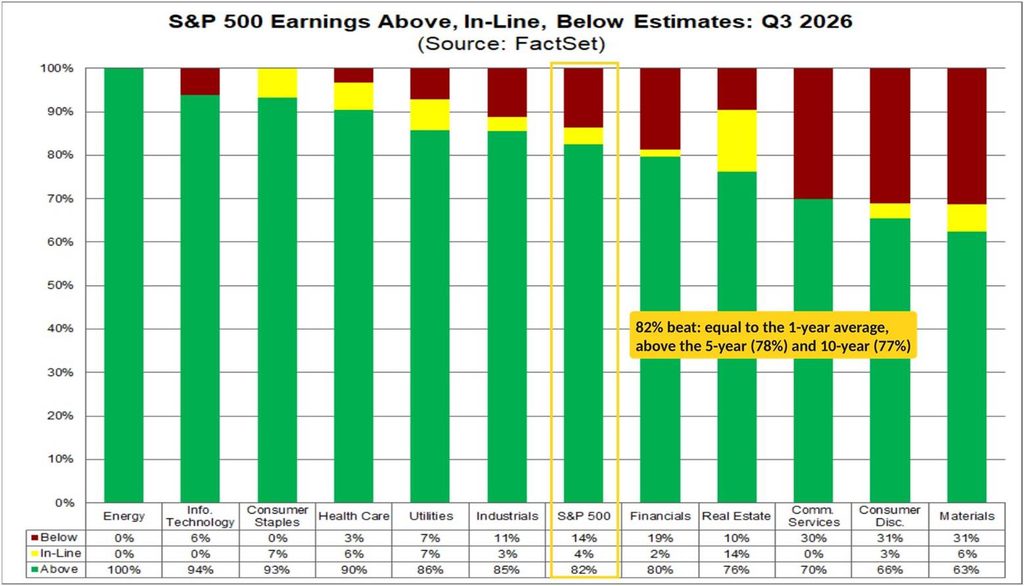
Looking at Q3 earnings, we’re now past the halfway point with 60% of the S&P 500 reporting through Thursday according to FactSet, and beats remain high with 82% beating, equal to the 1-year average and above the 5-year average of 78% and the 10-year average of 77%.
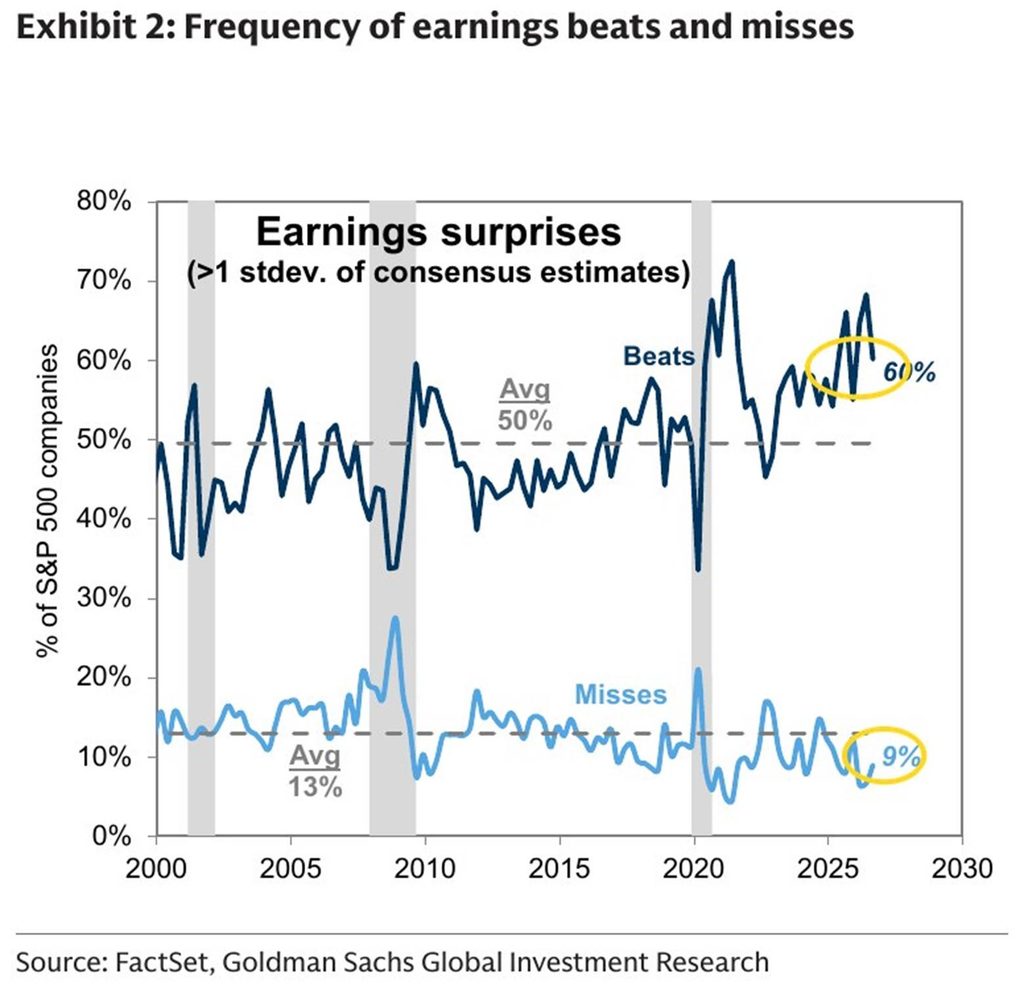
Goldman looks at it a bit differently: 60% of S&P 500 companies have beaten consensus EPS by more than a standard deviation of analyst estimates, above the 50% historical average but down from 64% over the past four quarters, while just 9% have missed by that much (13% on average).
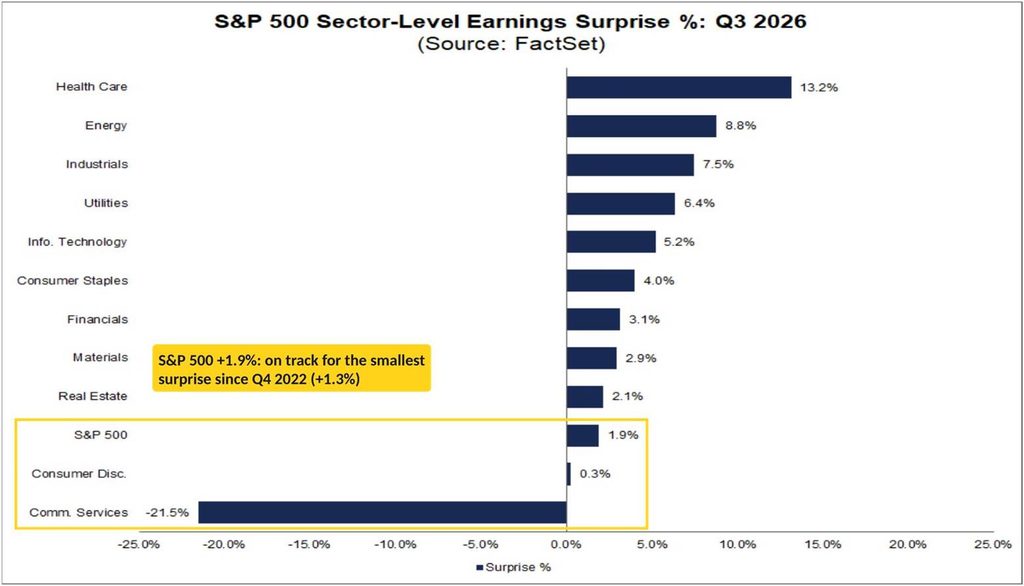
The magnitude of the beats though remains historically weak at just +1.9% (from +2.1% the prior week), well below the 1-year average of 13.8%, the 5-year average of 7.5% and the 10-year average of 8.0%. If that holds, it would be the smallest surprise since Q4 2022 (+1.3%). The Communication Services sector remains the big drag at −21.5%, on the GAAP charges at Alphabet (GOOGL) and Meta (META).
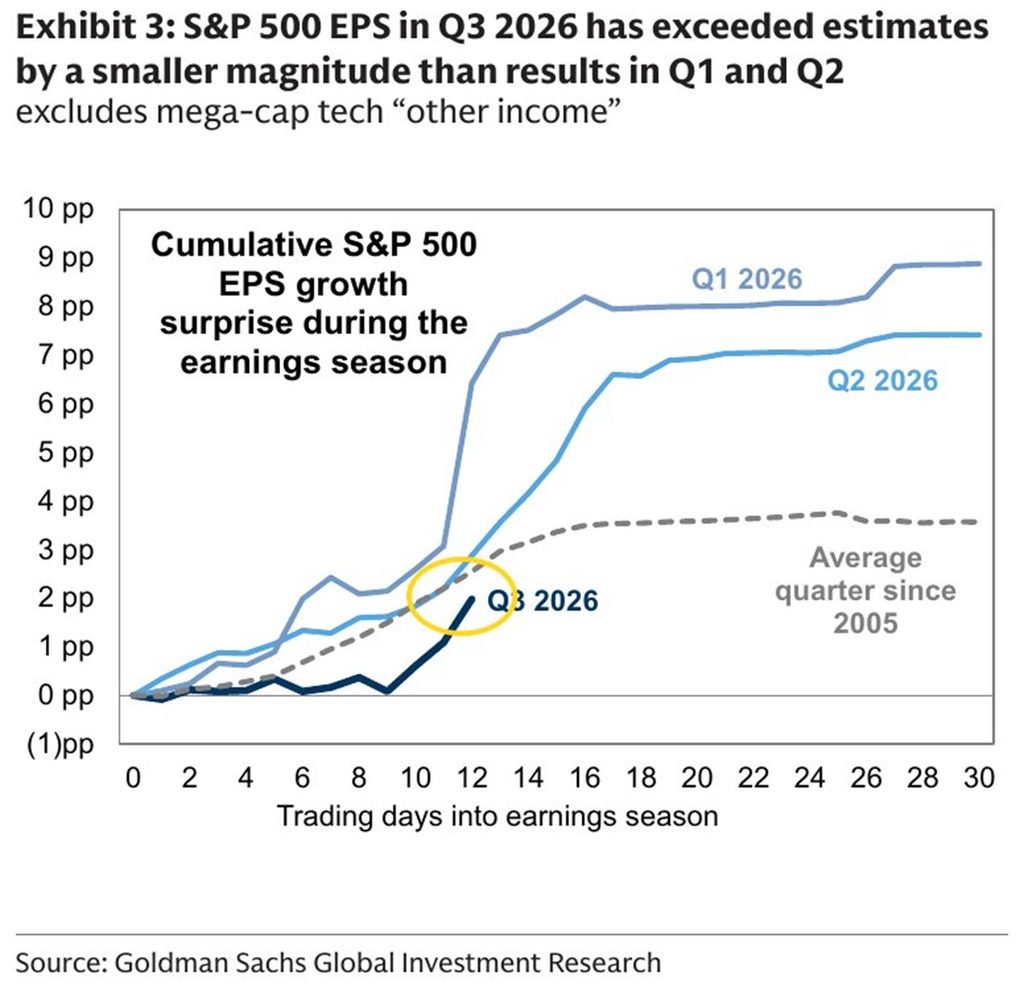
Goldman’s tally (which excludes mega-cap tech “other income”) shows the same thing. Twelve trading days in, the aggregate surprise has added about 2 points to Q3 growth, slightly behind the average quarter since 2005 and well short of the pace in Q1 and Q2 (which ended at roughly 9 and 7.5 points).
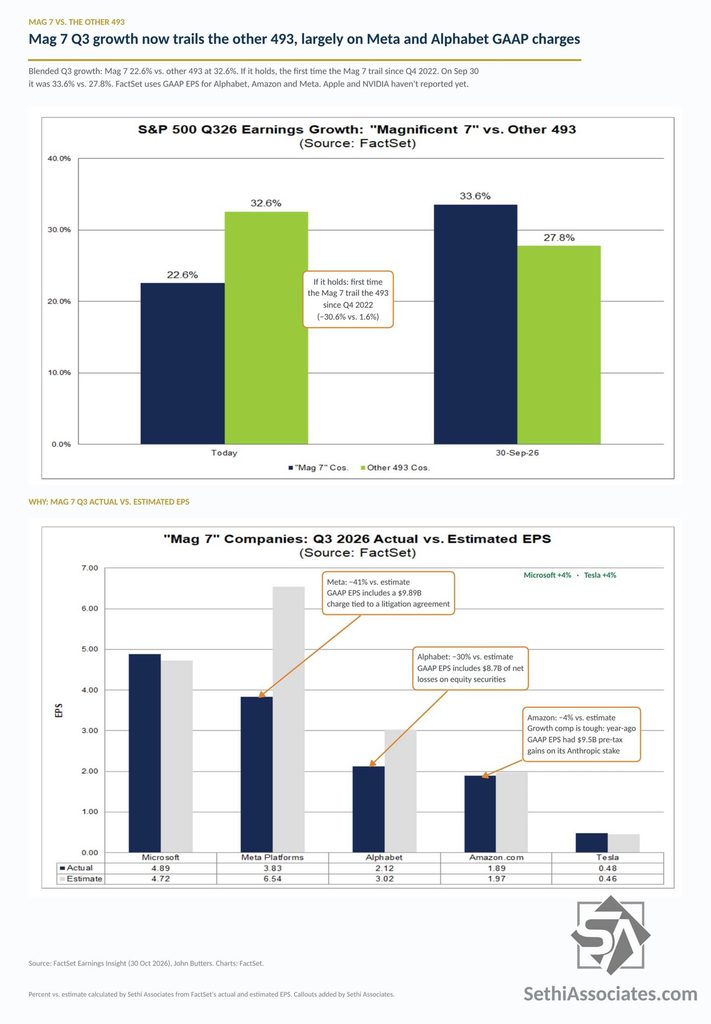
That has left the “Magnificent 7” reporting lower earnings growth than the other 493. Per FactSet’s John Butters, the Mag 7 are now reporting lower Q3 earnings growth than the other 493: 22.6% vs. 32.6%. If that holds through the end of earnings season, it’s the first time since Q4 2022. On September 30th the expectation was the reverse, at 33.6% vs. 27.8%.
But note it’s largely a function of big GAAP charges at two companies (FactSet uses GAAP EPS for Alphabet, Amazon and Meta):
- Meta: −41% vs. estimate, with a $9.89B litigation charge in the quarter
- Alphabet: −30% vs. estimate, with $8.7B of net losses on equity securities
- Amazon (AMZN): a tough comparison, since year-ago EPS included $9.5B in pre-tax gains on its Anthropic stake
- Microsoft and Tesla both beat, and Apple reports Monday while Nvidia doesn’t report until November 17th.
The part that isn’t accounting: analysts also expect the Mag 7 to trail in Q4 (22.6% vs. 30.8%), and that gap has widened since September 30th (23.6% vs. 28.3%). The 493 are being lifted by Energy, where Q4 estimates rose 20.3% in October.
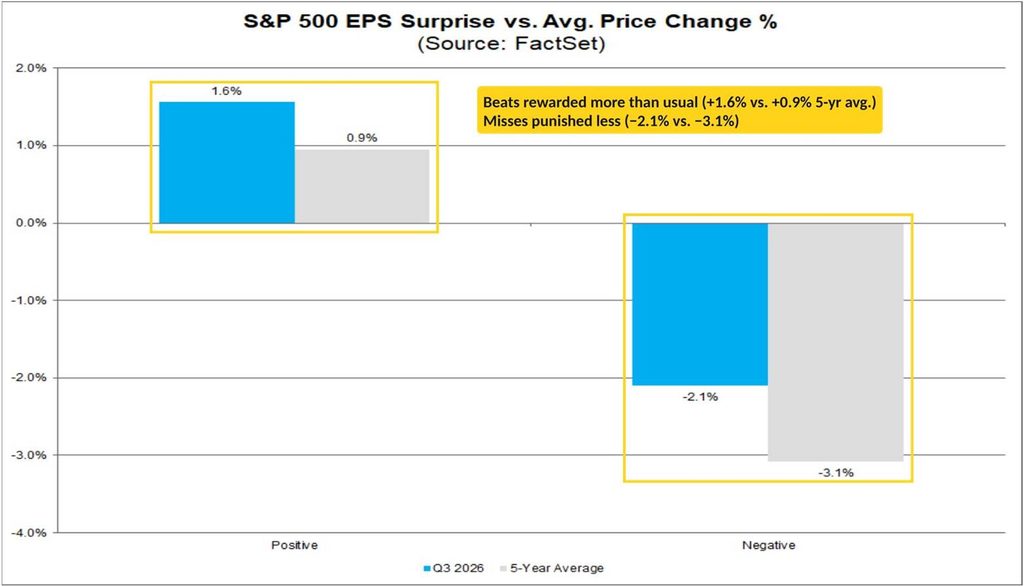
Despite the headlines market reactions have been more favorable than history. Overall, beats are being rewarded more than usual and misses punished less. FactSet says companies beating estimates have averaged a +1.6% move from two days before their report to two days after, versus a 5-year average of +0.9%, while those missing have averaged −2.1%, versus a 5-year average of −3.1%. The size of the beat has mattered too: the four companies beating by more than 40% averaged +4.7%, the 23 beating by 20% to 40% averaged +2.6%, and the 226 beating by less than 20% averaged +1.1% to +1.5%.
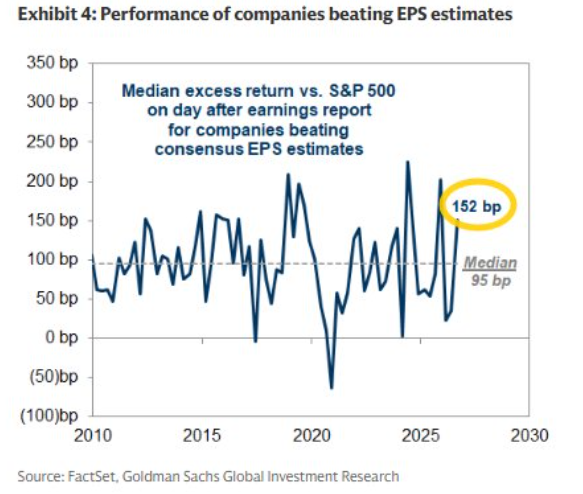
Goldman’s measure tells the same story: the median stock beating EPS estimates has outperformed the S&P 500 by 152bp the day after reporting, well above the 95bp historical median, a reversal after several quarters of below-average rewards for beats.
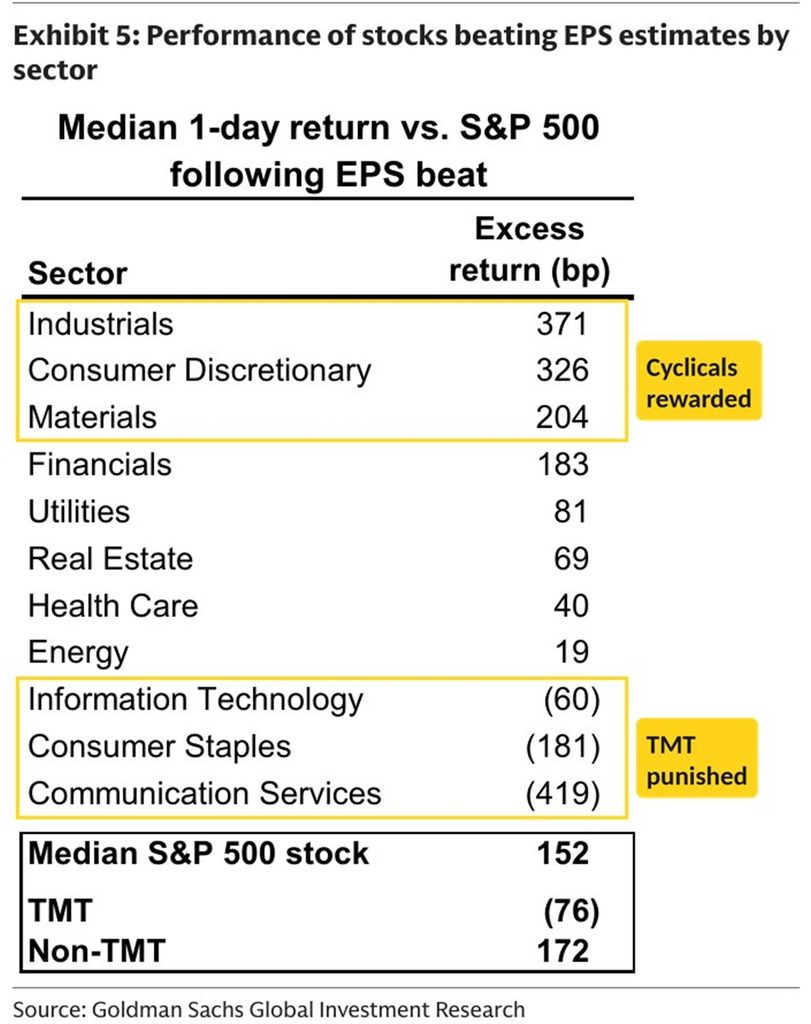
But the averages hide a sharp split between the megacap growth sectors and everything else. Outside TMT (Technology, Media, and Telecommunications), beats have been rewarded with a median 172bp of outperformance, led by Industrials (+371bp), Consumer Discretionary (+326bp) and Materials (+204bp), cyclical sectors where, Goldman notes, hedge fund positioning had recently fallen sharply. TMT beats have instead underperformed by a median 76bp, and Communication Services (−419bp), Consumer Staples (−181bp) and Info Tech (−60bp) are the only sectors where beating has been punished.
Some notables last week: Alphabet (GOOGL) had its worst day on record (−12.6%) after its miss, Intel (INTC) had its worst day ever (−28.6%) on its outlook, and Goldman’s list of the S&P 500’s worst performers for the week is all Tech: ServiceNow (NOW, −34%), F5 (FFIV, −26%), Fortinet (FTNT, −24%), Intel (−24%) and Twilio (TWLO, −22%). That’s what’s behind the “catch up” and “catch down” in breadth Goldman highlights in the breadth section: 70% of S&P 500 stocks are up since the season started, but they’re only half the index’s market cap.
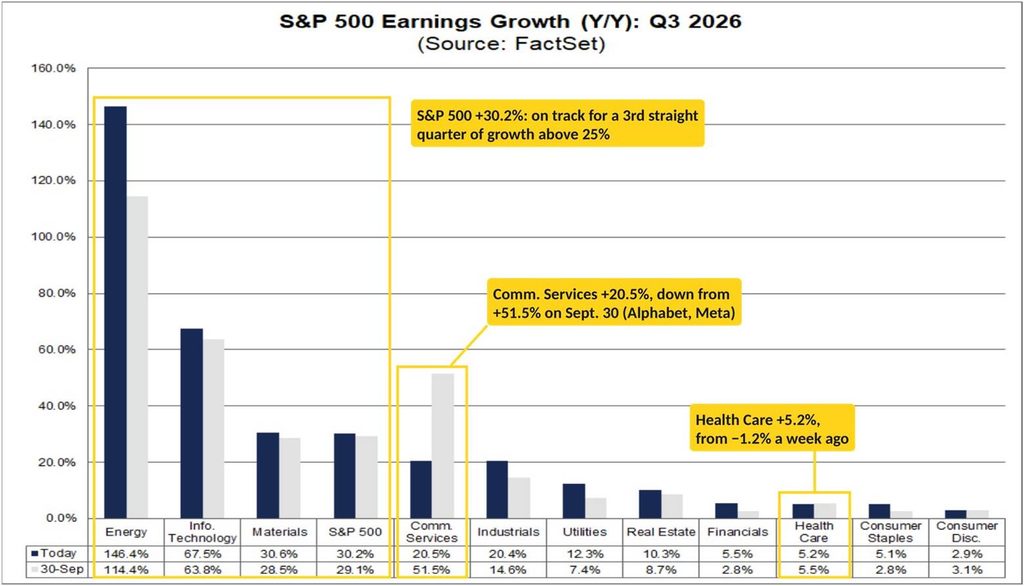
But despite all that overall Q3 expected earnings growth climbed another seven tenths to +30.2%, which would be a third straight quarter above 25%. Energy extended to +146.4% y/y (up from +79.3% on June 30th), followed by Tech +67.5% and Materials +30.6%, while Comm Services fell to +20.5% from +39.8% the prior week (and +53.1% on June 30th).
All eleven sectors are now expected to report y/y growth, with Health Care swinging to +5.2% from −1.2% the prior week on beats from Eli Lilly, Merck, Bristol Myers Squibb, Gilead and Regeneron (though still below the +8.7% on June 30th).
And just a reminder on the typical “earnings inflation” we see each earnings season (numbers are from the end of the quarter, which is where the “inflation” metrics are measured from):
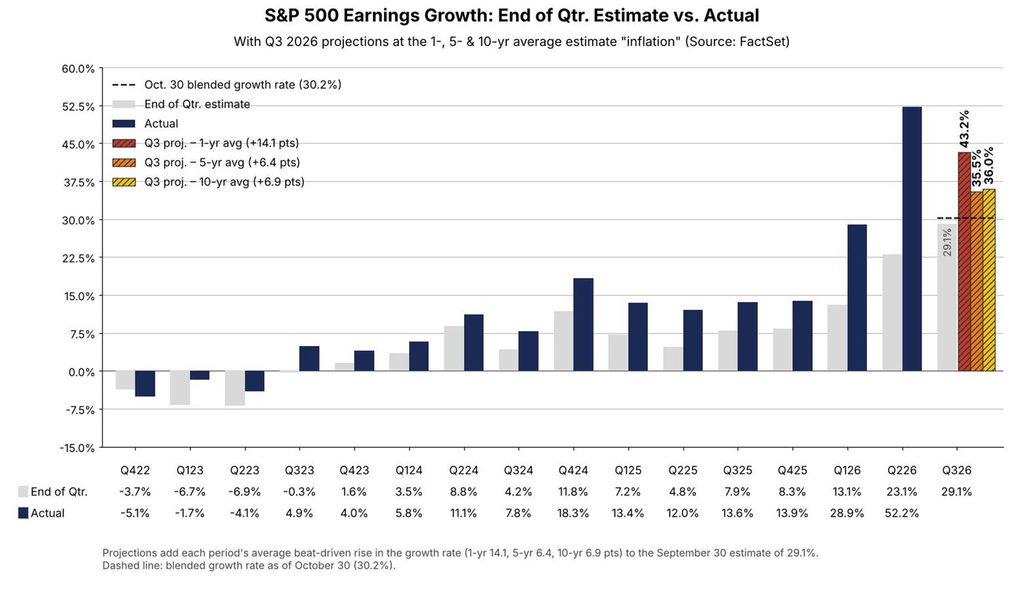
With the blended growth rate already at 30.2%, the 5- and 10-year averages imply roughly another five to six points from here.
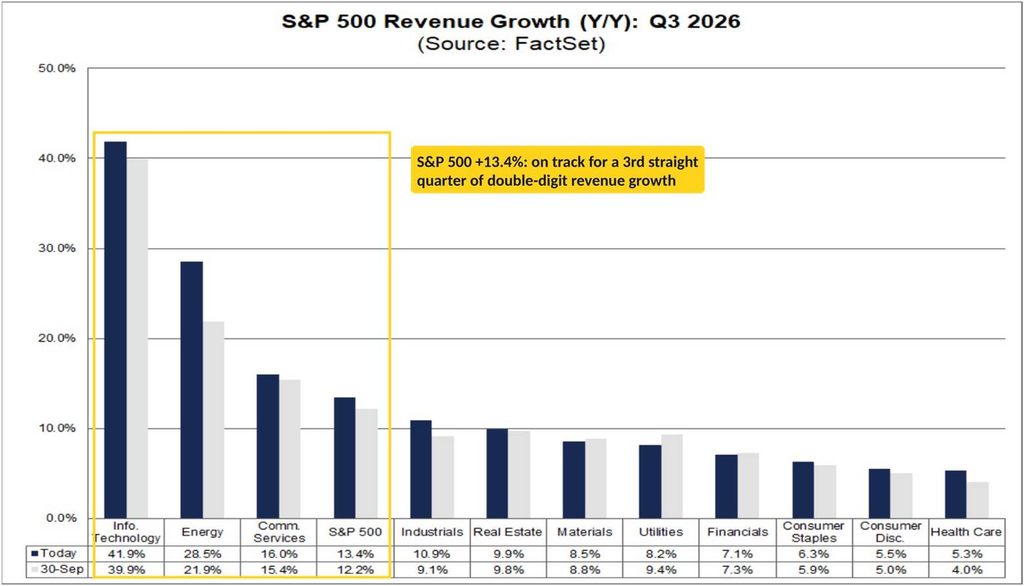
Q3 revenue growth expectations also jumped to +13.4% (from +12.7%), on track for a third straight quarter of double-digit growth after +15.5% in Q2. Expectations are led by Tech (+41.9%), Energy (+28.5%) and Communications (+16.0%).
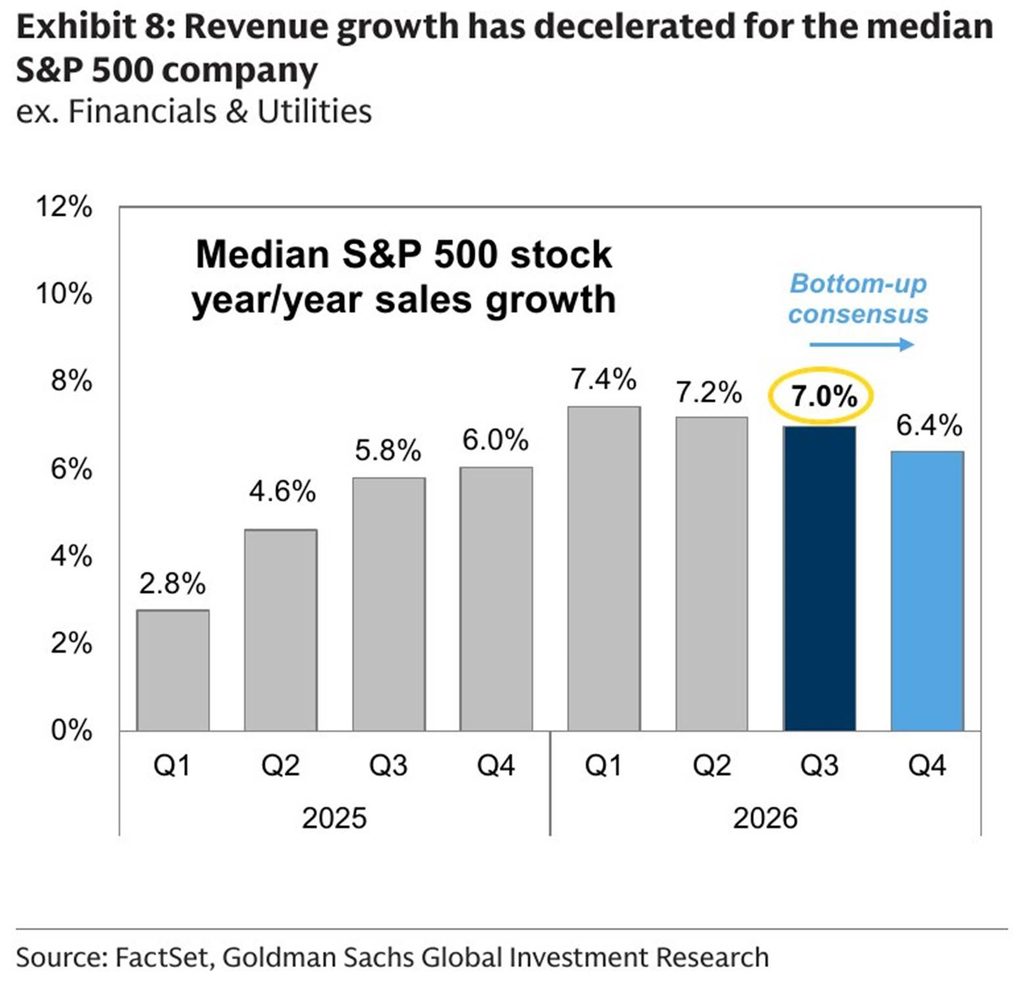
For the median company (excluding Financials and Utilities), Goldman has revenue growth at 7.0% down slightly from 7.2% in Q2 and 7.4% in Q1, but easing further to 6.4% for Q4.
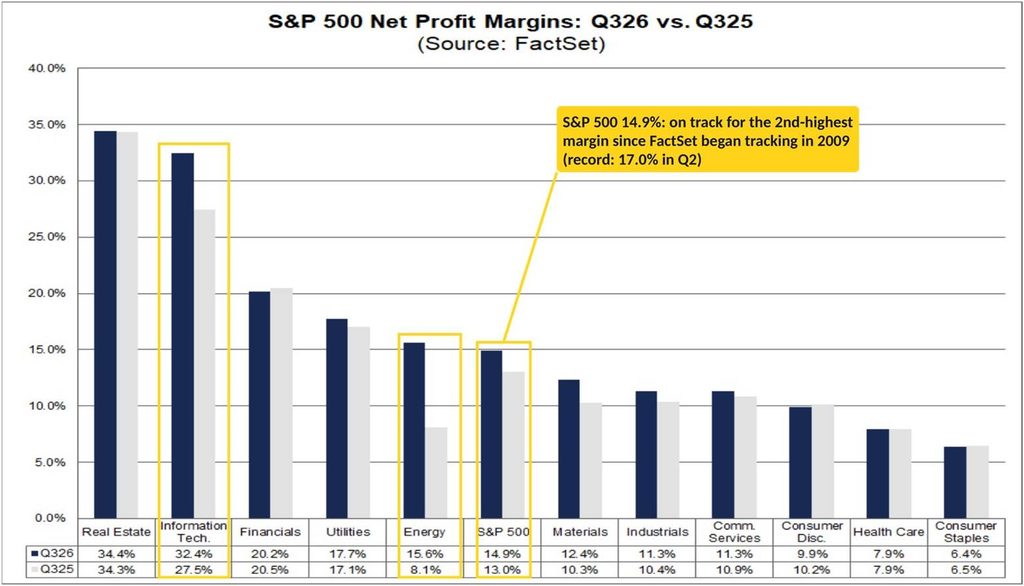
Net profit margins held at an elevated 14.9%, the second highest on record (since 2009) after 17.0% in Q2 and up from 13.0% a year ago, led by Tech’s 32.4% (vs 27.5% a year ago and a 25.9% five-year average) and Energy’s 15.6% (vs 8.1%).
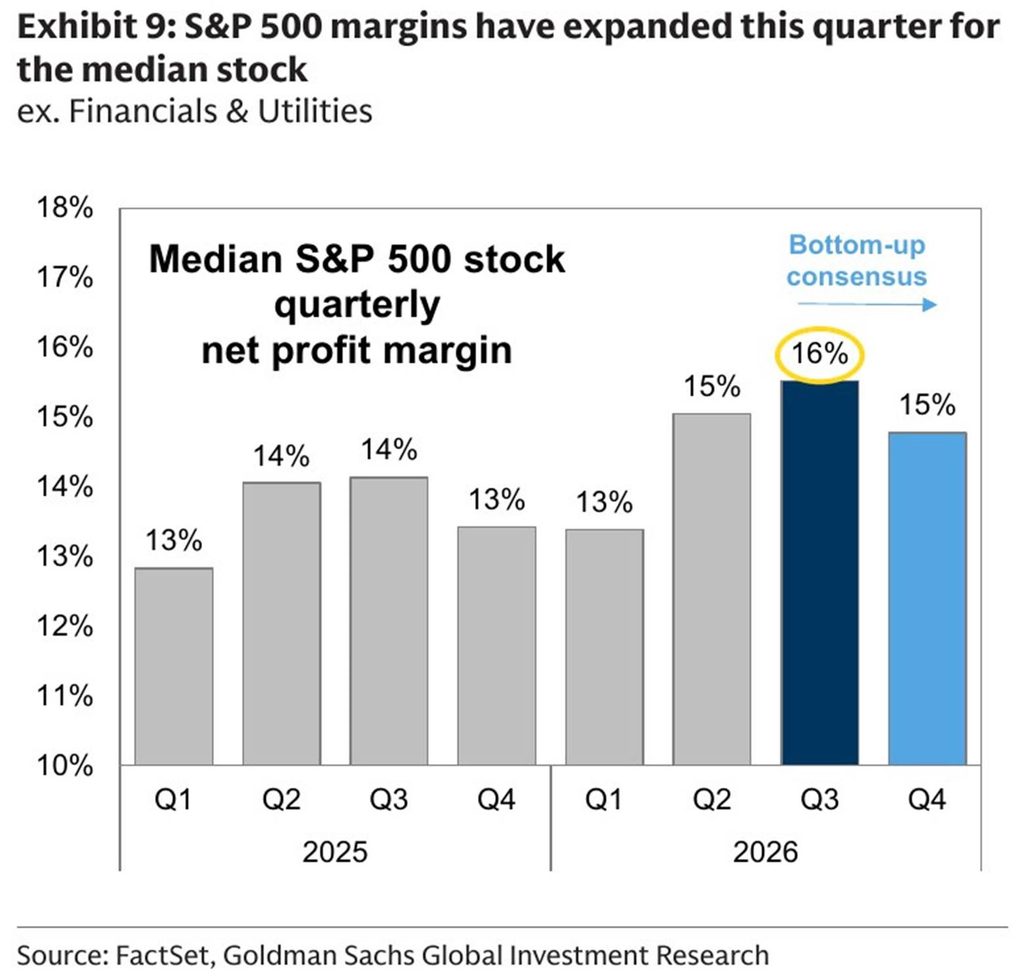
And it’s not just a semiconductor story as I may have over-emphasized in previous weeks. Goldman says the median company’s net margin (ex-financials and utilities) rose to a record of about 16% in Q3, with Industrials margins expanding substantially over the past several quarters while Consumer Staples margins have struggled.
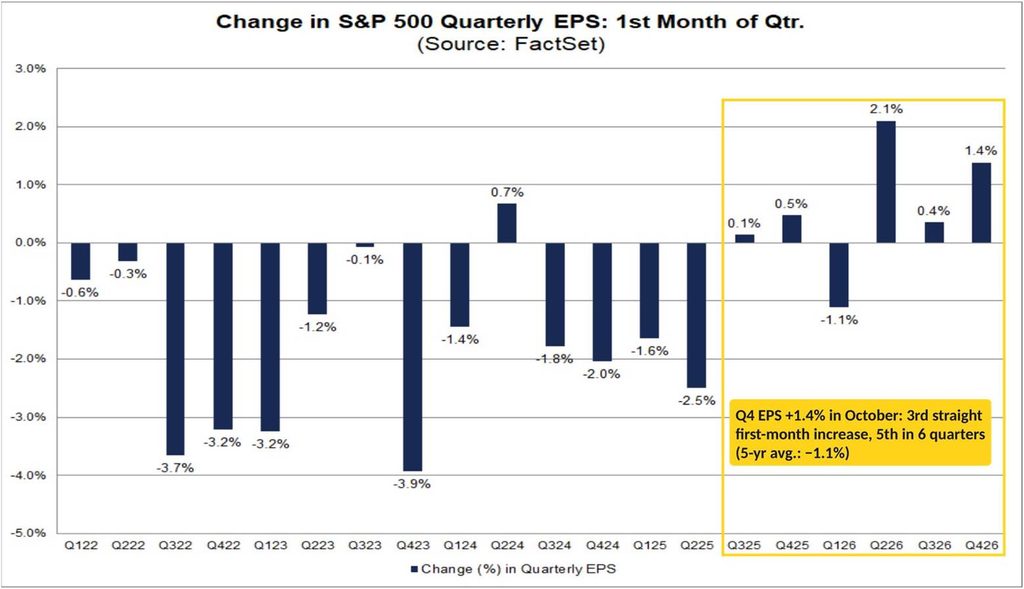
And for a third straight quarter, analysts raised estimates in the first month of the quarter. FactSet says the Q4 bottom-up EPS estimate rose 1.4% in October (to $94.79 from $93.49), versus an average first-month decline of 1.1% over the past five years, 1.3% over the past ten and 1.9% over the past 20. It’s the fifth time in six quarters. Q4 growth is now expected at +28.4%, and guidance has also been better than usual: 40% of the 47 companies that have guided Q4 have been negative, versus a 5-year average of 60%.
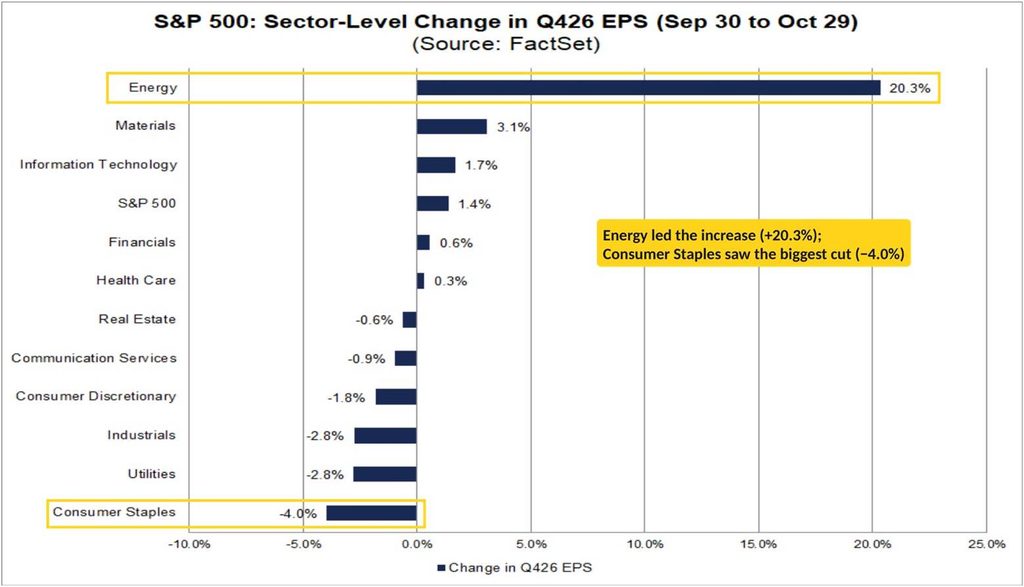
But only five of the eleven sectors saw increases, and only three rose more than the index: Energy (+20.3%), Materials (+3.1%) and Tech (+1.7%), while Consumer Staples (−4.0%) saw the largest cut. Tech’s gain is modest, but as the largest slice of S&P 500 earnings it carries more weight than the number suggests. And while FactSet framed the question around “concerns in the market about higher oil prices,” so far higher oil is driving the upgrades, not cutting them.
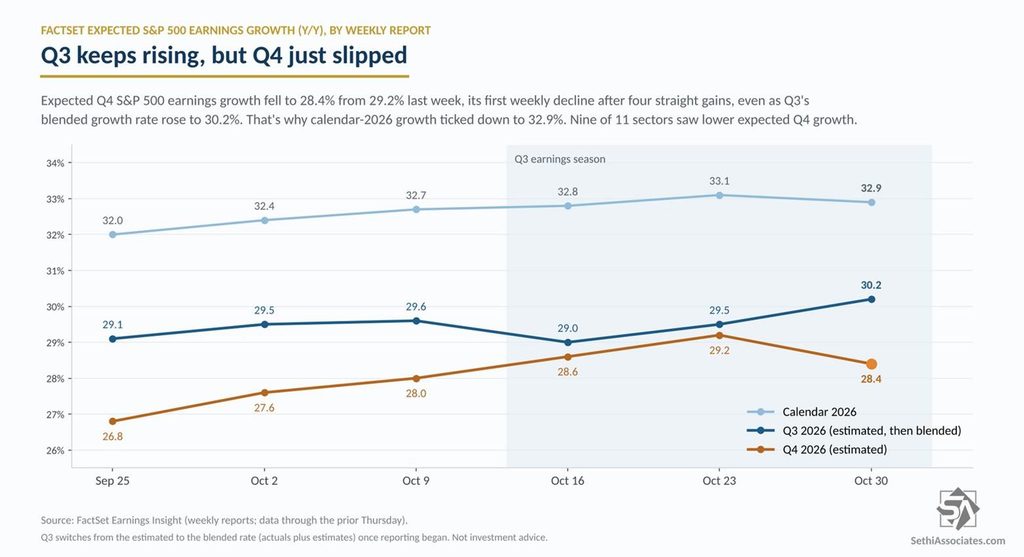
But last week Q4 earnings expectations went the other way. Even as Q3 growth rose another seven tenths, expected Q4 growth fell to 28.4% from 29.2%, its first weekly decline after four straight gains (it’s still up from 27.0% on September 30th).
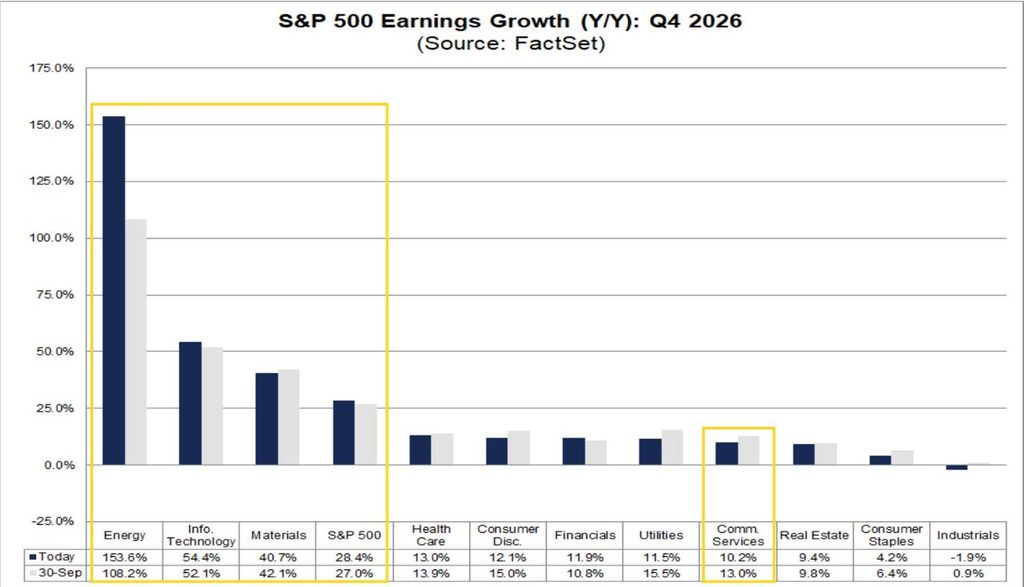
The cuts were broad, with nine of the eleven sectors seeing lower expected Q4 growth on the week, led by Comm Services (10.2% from 12.7%), Materials (40.7% from 43.1%), Utilities (11.5% from 13.0%), Industrials (−1.9% from −0.5%) and Consumer Discretionary (12.1% from 13.5%). Only Tech edged up (54.4% from 54.2%), while Real Estate was unchanged.
So analysts are trimming next quarter as companies report this one, which fits with Goldman’s point (below) that revision breadth has moderated and margin estimates are being cut. It’s also why 2026 growth slipped even as Q3 rose.
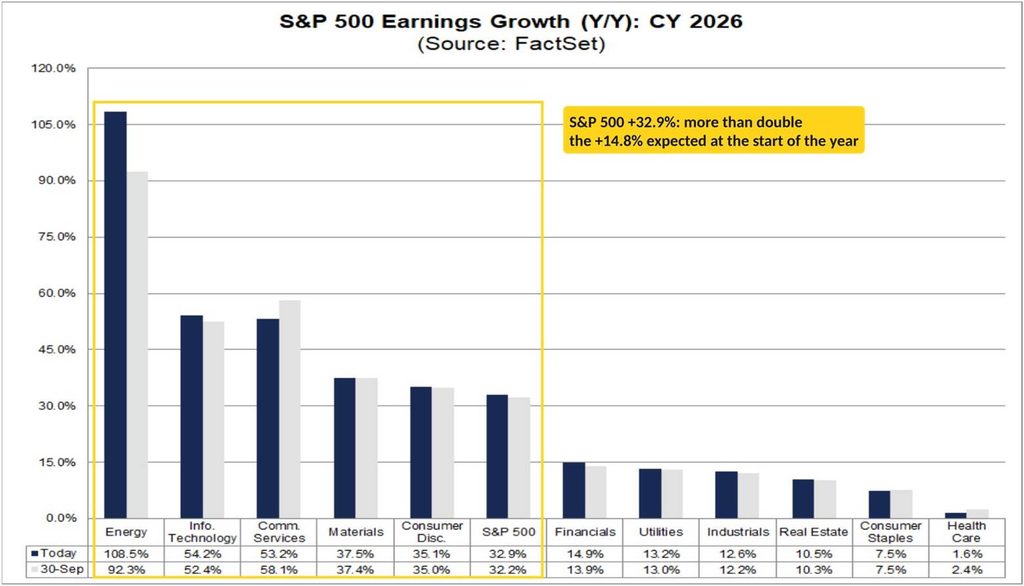
In that regard, 2026 SPX earnings growth expectations edged down to +32.9% (from +33.1%), though still up from +24.0% on June 30th, +17.1% on March 31st, and over double the +14.8% at the start of the year. Energy leads at +108.5% (up from +6.4% at the start of the year), followed by Tech at +54.2% (up from +28.6%), which moved back ahead of Communications (+53.2%, down from +56.8% the prior week after Alphabet). Those sectors along with Materials (+37.5%) and Consumer Discretionary (+35.1%) remain the five expected to come in above the SPX average.
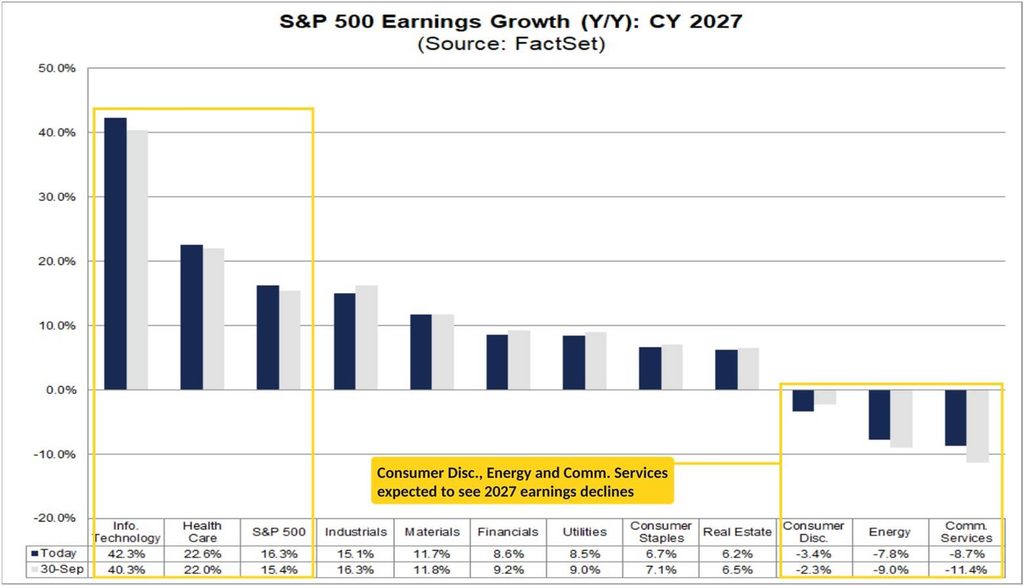
And 2027 earnings are expected to be up another +16.3% (from +16.0%), still below the +17.5% as of June 30th as the large investment gains in Alphabet, Amazon, etc., are not expected to repeat. Tech again leads (+42.3%), followed by Health Care (+22.6%), with no other sector above the SPX average (Industrials just under at +15.1%). Communications (−8.7%), Energy (−7.8%) and Consumer Discretionary (−3.4%) are expected to see declines.
Yardeni, whose data comes from LSEG rather than FactSet, has 2027 at a similar +16.1% ($425) and 2028 up another 16.2% ($494), and he’s skeptical:
“Industry analysts’ consensus earnings expectations for the S&P 500 show nothing to fear but fear itself. The real concern is that they are not only fearless but also too optimistic.”
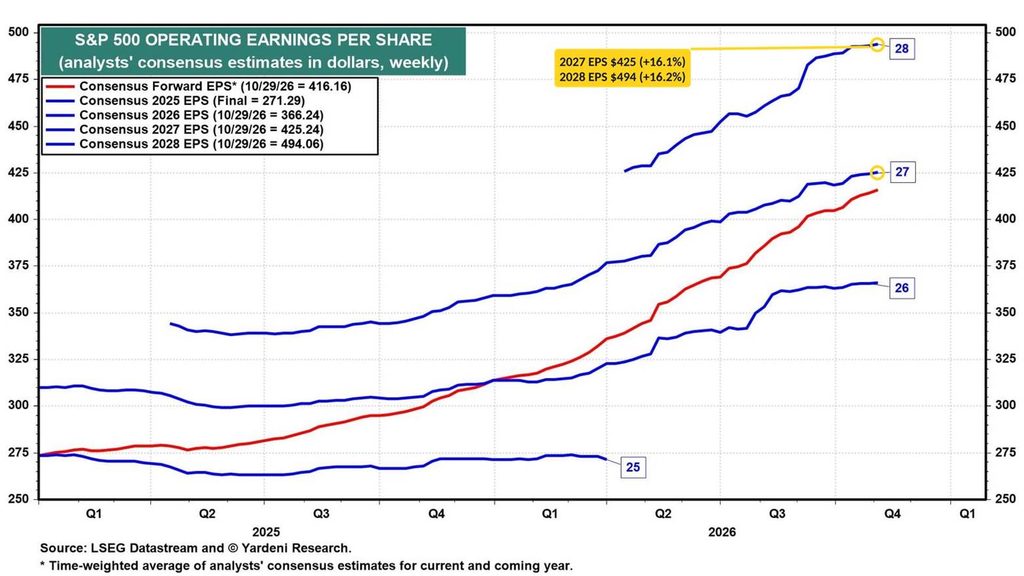
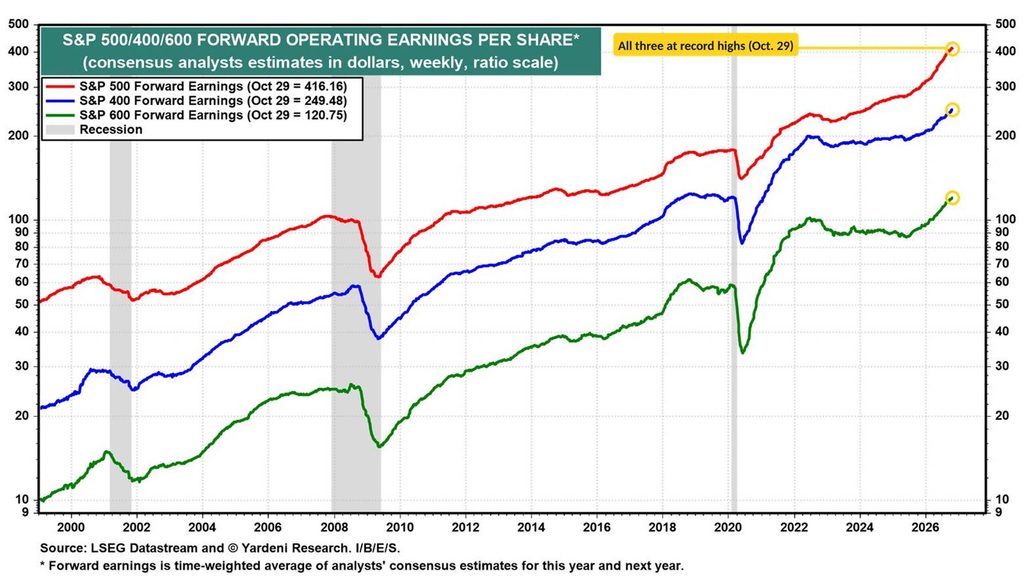
Still, he notes “forward earnings for the S&P 500, S&P 400, and S&P 600 all rose to record highs again last week.”
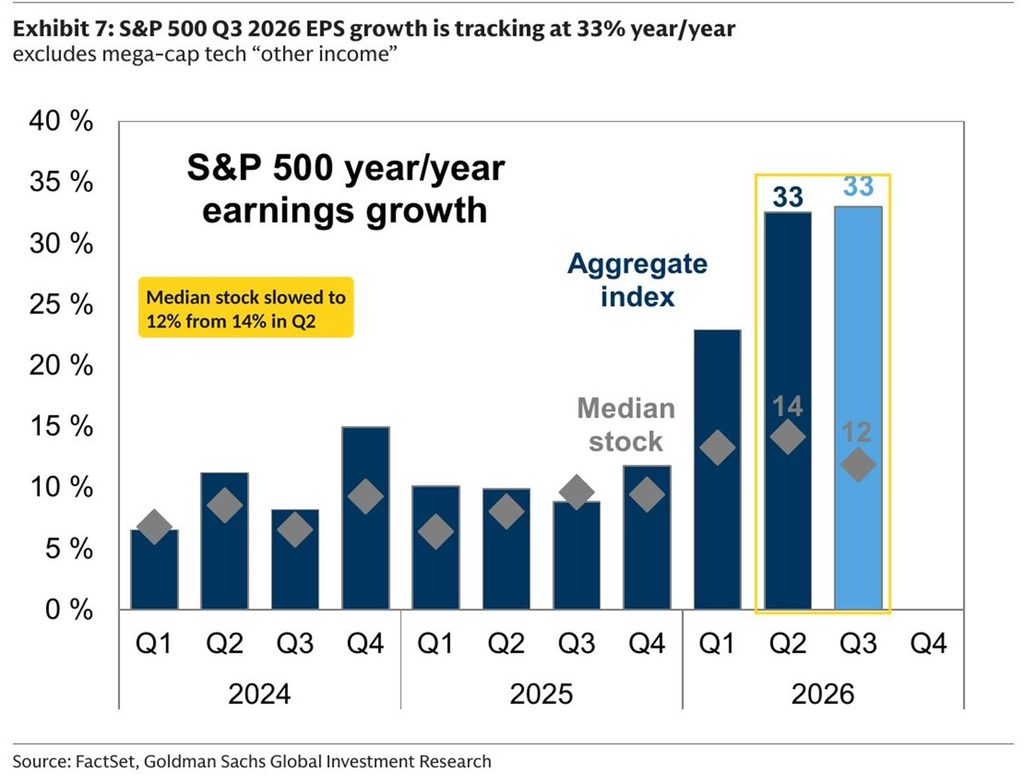
Goldman’s midseason update sums up a challenge for equities: earnings growth is strong, but it’s no longer accelerating. Excluding mega-cap tech “other income,” Goldman has Q3 S&P 500 EPS growth tracking at 33% y/y (above FactSet’s 30.2%, which uses GAAP results for Alphabet, Amazon and Meta), matching Q2 as the strongest quarter in recent decades outside of post-recession recoveries. But that ends the acceleration of the past few quarters, and growth for the median stock has slowed to 12% from 14% in Q2 (versus a 10-year median of 8%).
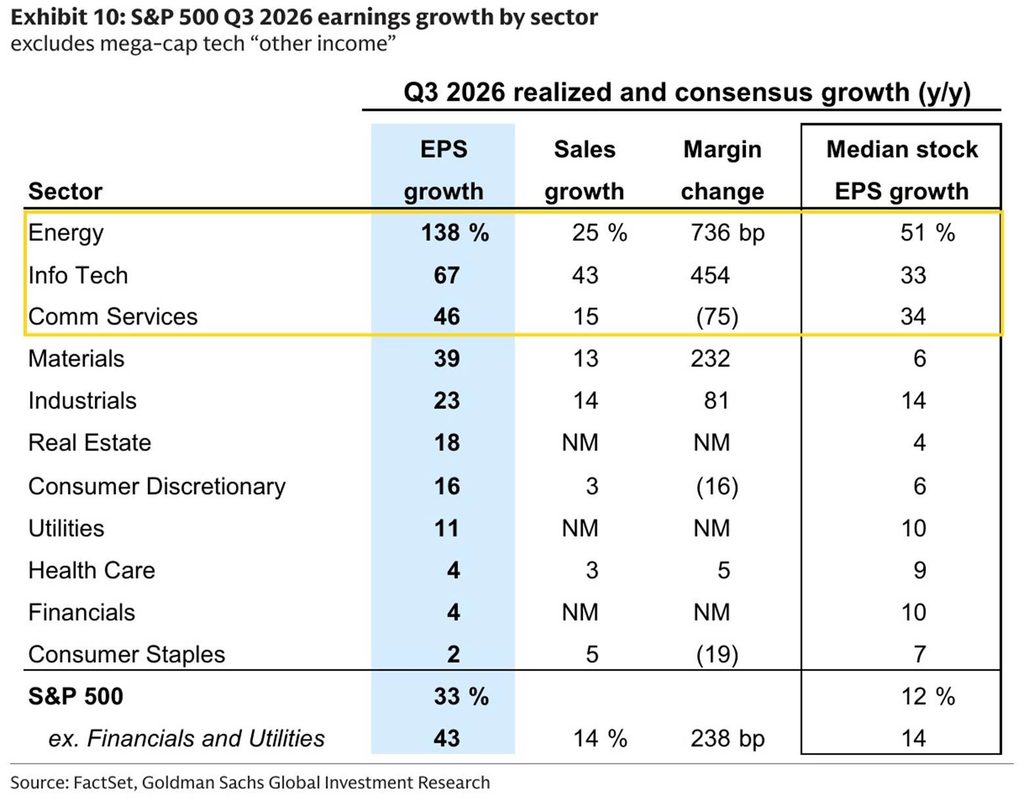
By sector, Goldman has Energy (+138%), Info Tech (+67%) and Comm Services (+46%) leading, with Info Tech and Comm Services together accounting for more than 60% of S&P 500 EPS growth in Q3 and Energy another 20%. Excluding Financials and Utilities, aggregate growth is 43%, though only 14% for the median stock.
Goldman:
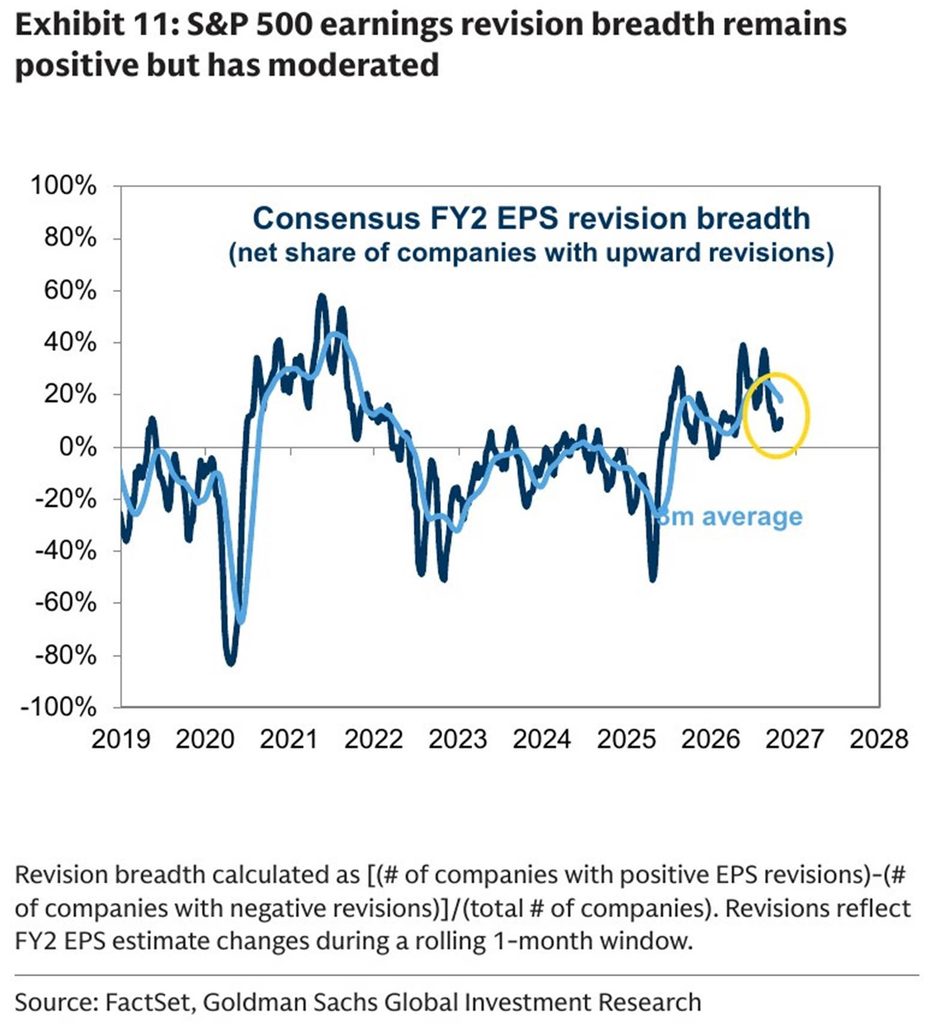
“Alongside strong earnings results, analysts have continued to lift forward earnings estimates this season, but the rate of upward revisions has slowed. Consensus estimates for 2027 S&P 500 EPS have risen by 2% since the start of the earnings season. While companies with estimate upgrades continue to outnumber those with downgrades, earnings revision breadth has moderated relative to the last several months. In particular, analysts have trimmed profit margin estimates for many companies alongside rising energy prices.”
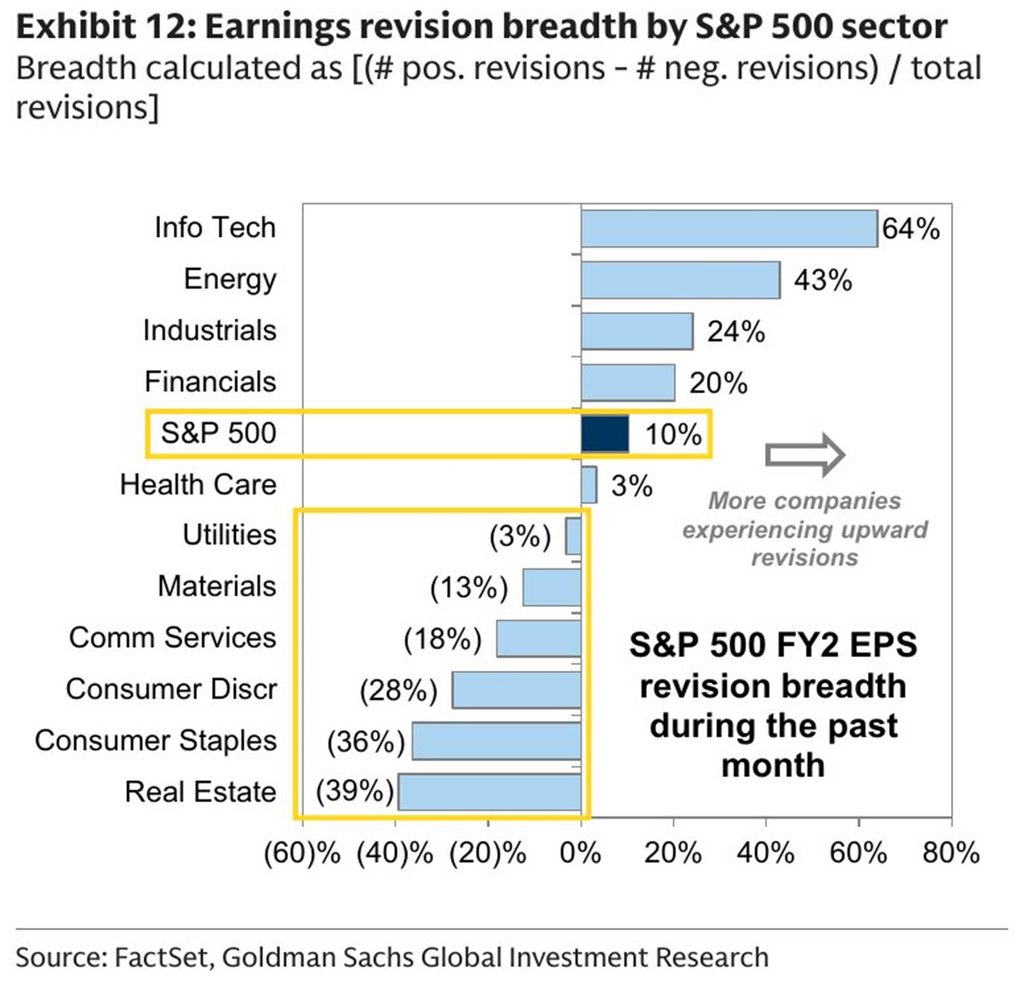
S&P 500 revision breadth is +10% over the past month and now positive in only about half of sectors, led by Info Tech (+64%) and Energy (+43%), while Real Estate (−39%), Consumer Staples (−36%) and Consumer Discretionary (−28%) are the weakest.
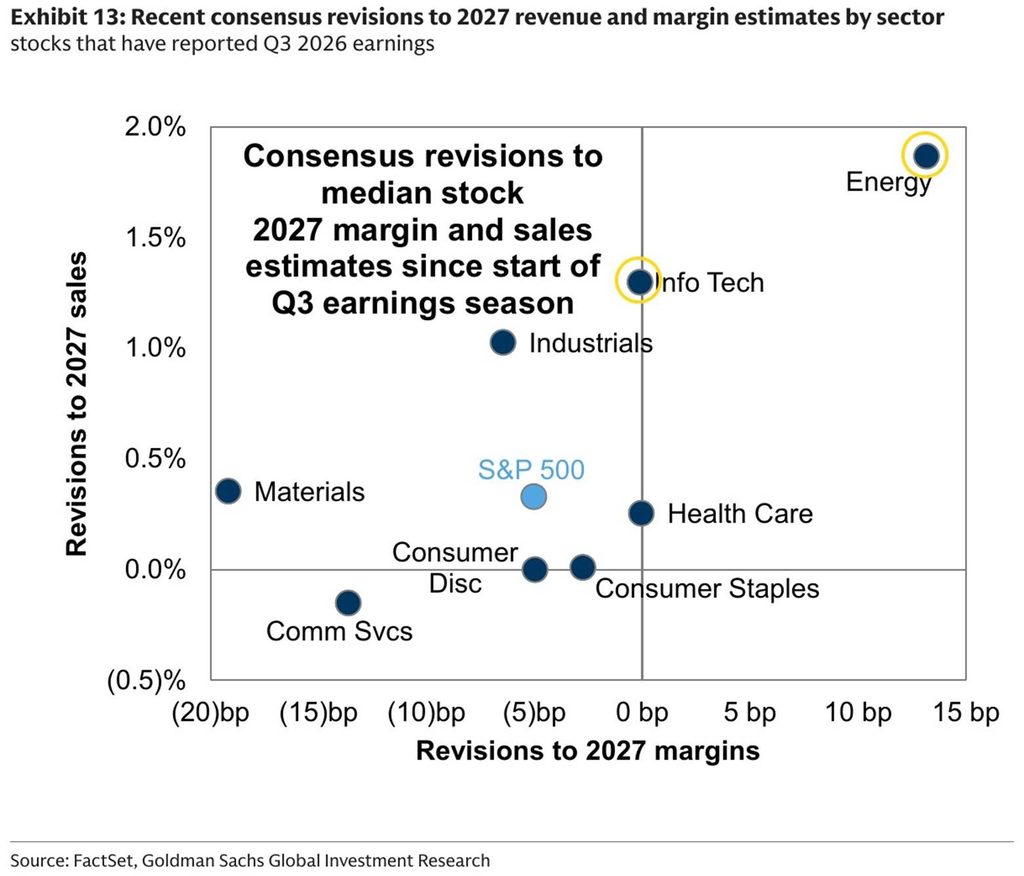
For companies that have reported, the median stock’s 2027 sales estimate is up about 0.3% since the season began, while its margin estimate is down about 5bp, as “the pressure from rising input cost prices has been reflected both in management commentary and in analyst margin estimate revisions.” Energy (sales +1.9%, margins +13bp) is the clear standout, with Info Tech seeing the next-biggest sales upgrade (+1.3%) on flat margins.
And on AI spending:
“Similarly, Q3 results support our view that AI investment spending will continue to grow but that the growth rate of AI capex is peaking. The hyperscalers are on track to spend roughly $800 billion in capex this year (+96% year/year) and analyst estimates suggest that spending will grow to $1.2 trillion in 2027 (+44%). Those estimates remained fairly stable this reporting season, in contrast with the pattern of upward revisions in recent quarters. Reflecting the likely deceleration in AI capex growth, analyst estimates show earnings growth for S&P 500 AI infrastructure stocks peaking at 80% this quarter and slowing to roughly 40% in 2027.”
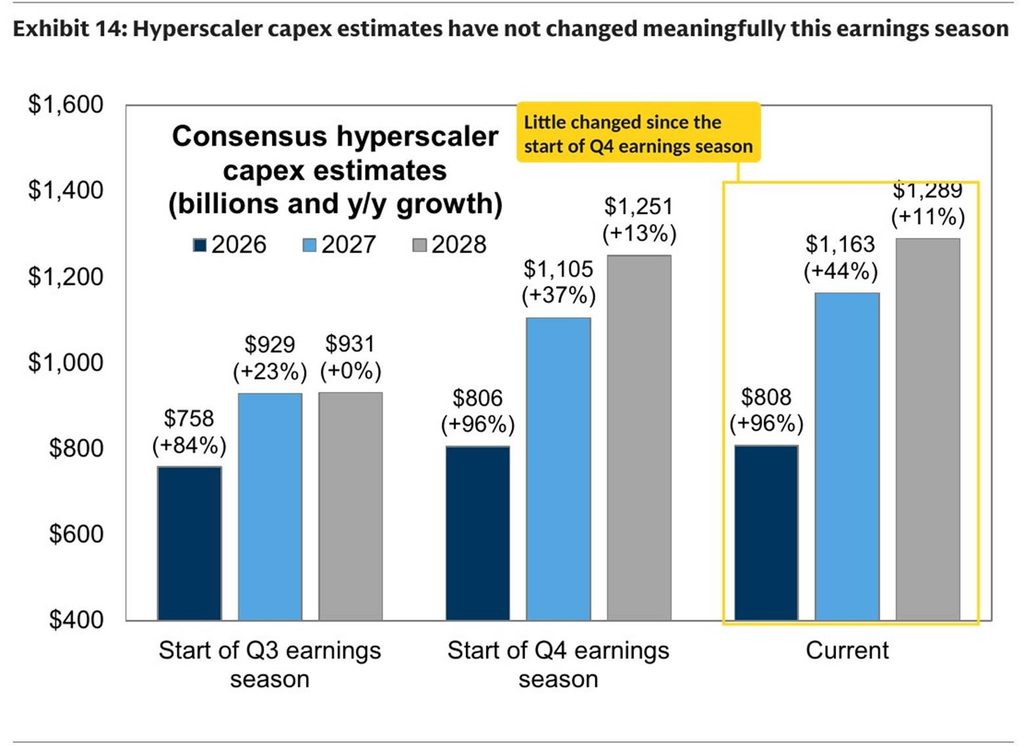
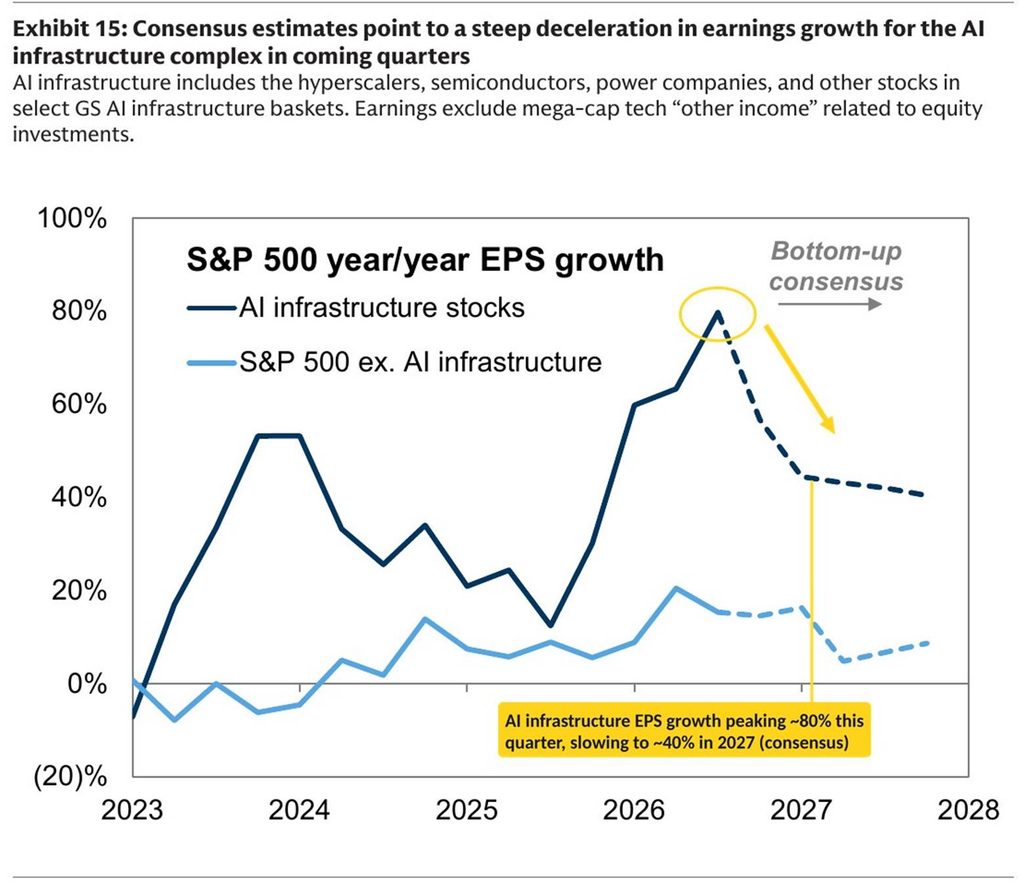
Goldman puts that 80% AI infrastructure growth at more than five times the 15% for the rest of the S&P 500.
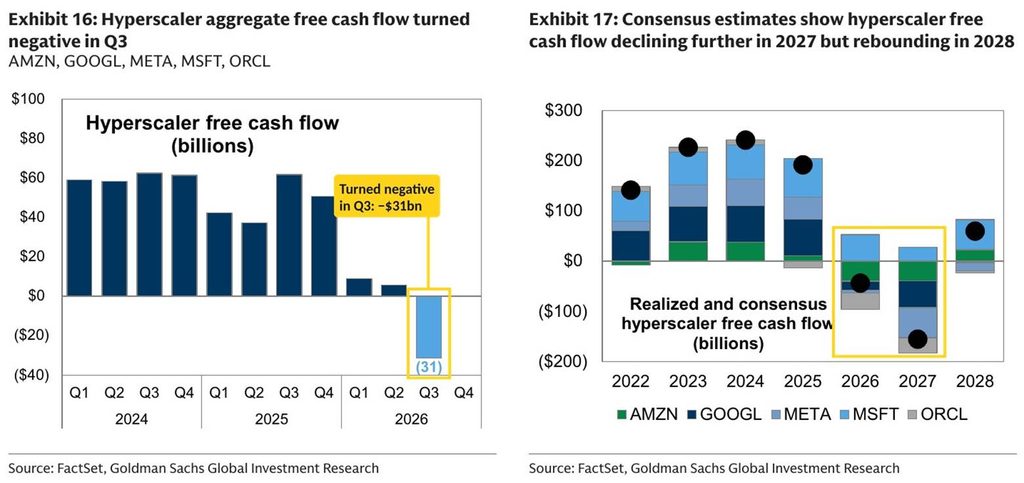
That spending now exceeds the hyperscalers’ cash flow from operations. Goldman notes that Amazon, Alphabet, Meta, Microsoft and Oracle collectively reported negative free cash flow in Q3 (about −$31 billion), with consensus showing it falling further in 2027 before turning positive in 2028.
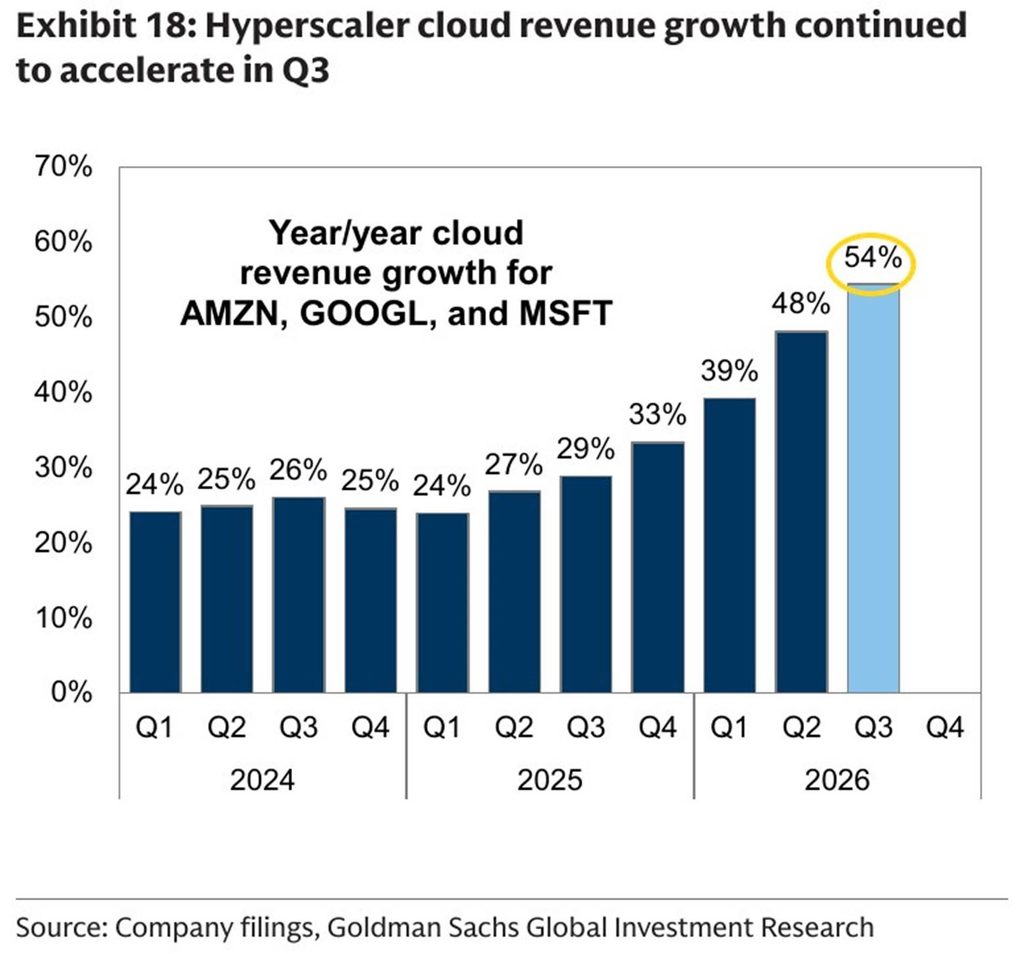
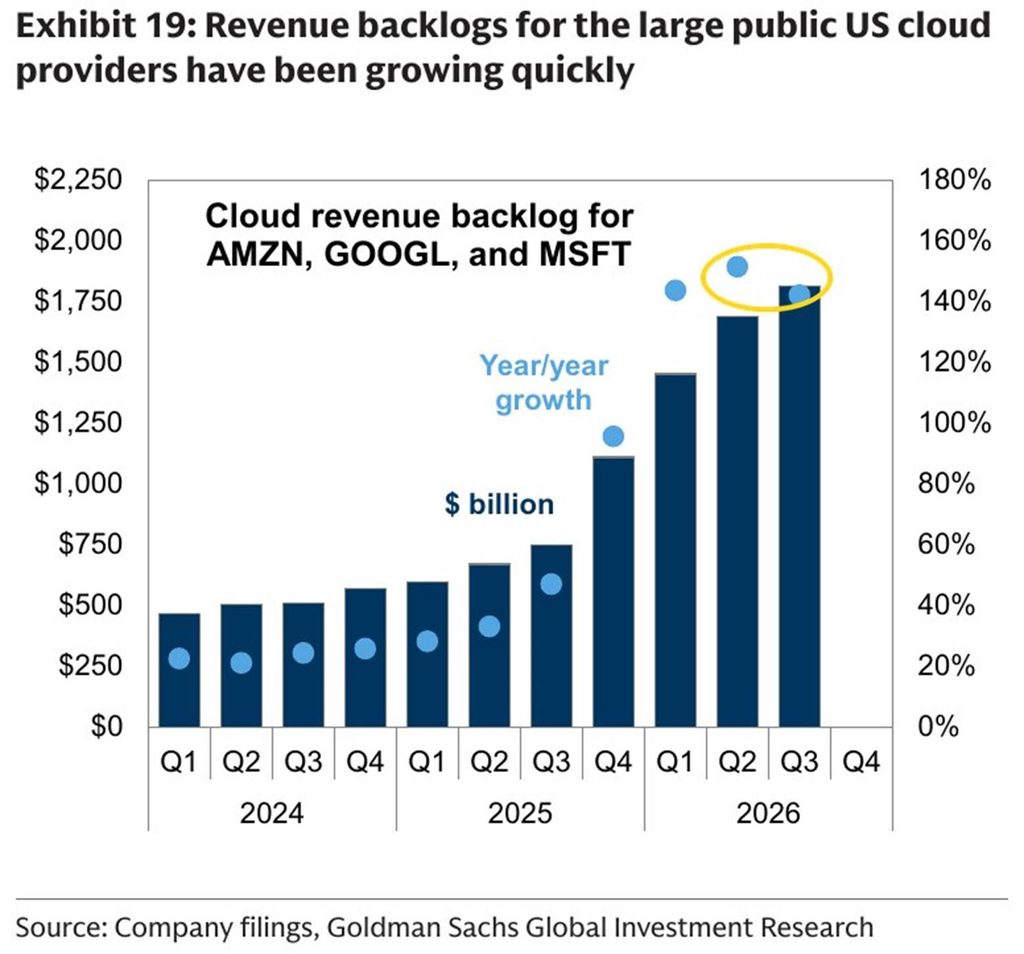
Payoff is showing up in the cloud businesses though. Cloud revenue growth for Amazon, Alphabet, and Microsoft (MSFT) accelerated to 54% y/y in Q3 from 48% in Q2 and 39% in Q1, and their combined cloud backlog reached roughly $1.8 trillion, about 2.4 times a year earlier, though backlog growth slowed slightly from Q2.
But Goldman notes Q3 renewed focus on AI disruption risk. Its analysts highlighted Alphabet’s disappointing search revenues and reduced search referral traffic to Reddit (RDDT), and its economists “have also noted several early signs of AI-related labor market disruption.”
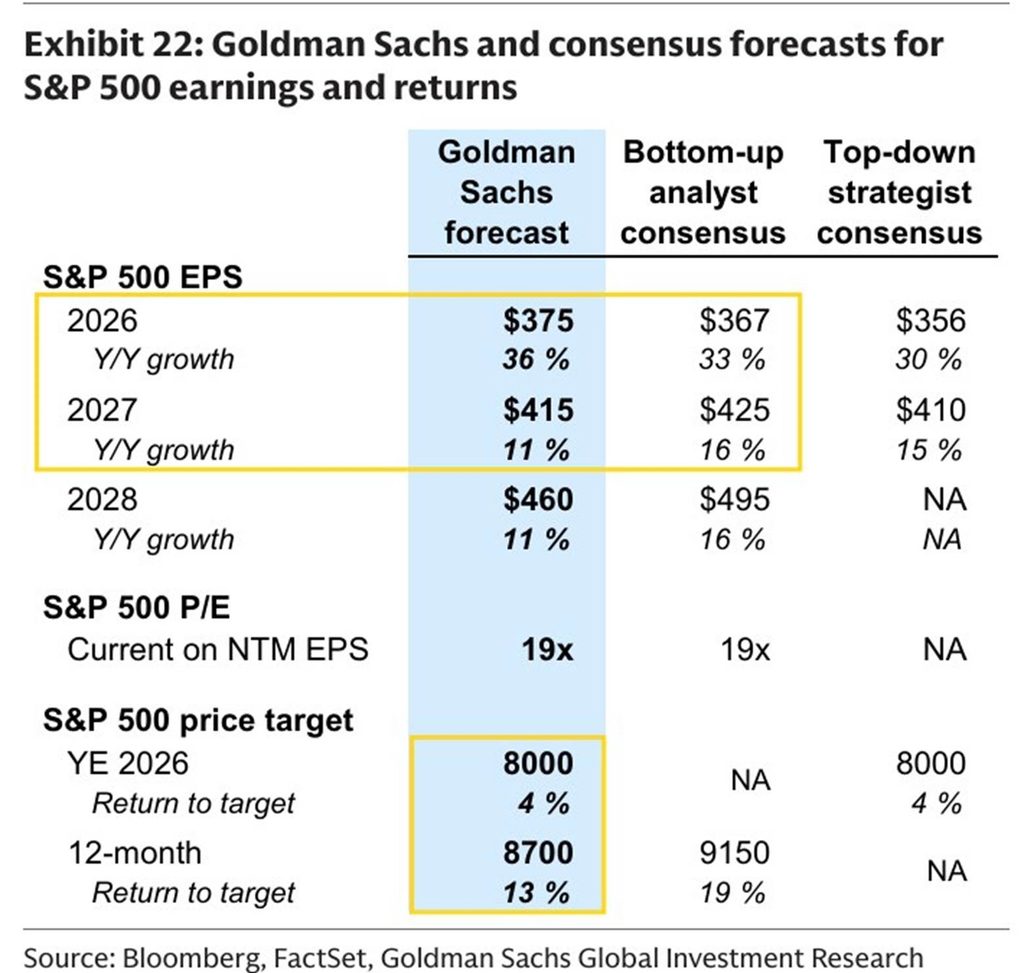
Goldman’s own forecasts are for 2026 EPS of $375 and 2027 of $415 (vs bottom-up consensus of $367 and $425), with a year-end S&P 500 target of 8,000 and a 12-month target of 8,700.
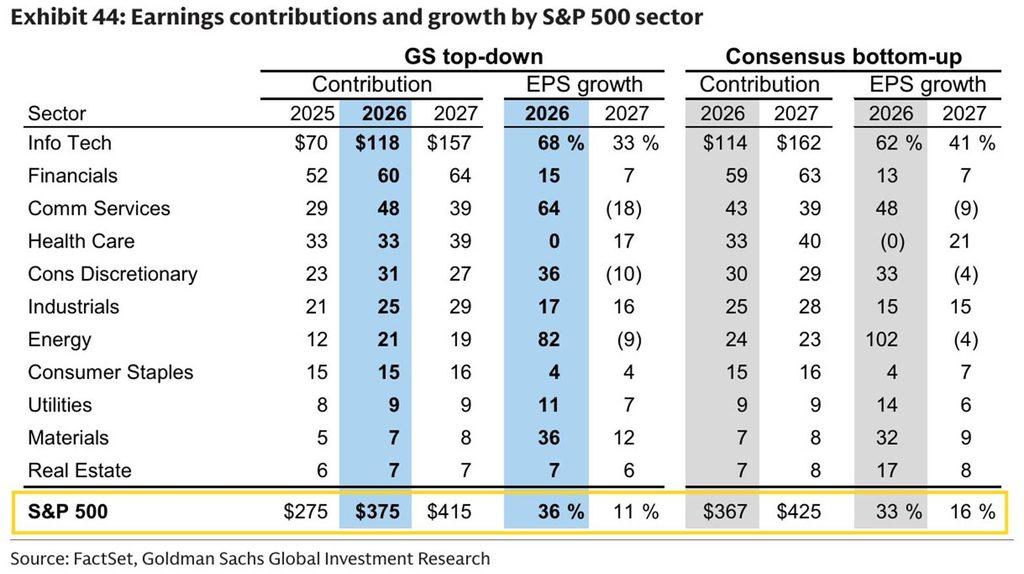
Goldman’s 2027 forecast ($415, +11%) sits below consensus ($425, +16%) in most sectors, with the biggest gaps in Info Tech (+33% vs. +41%), Comm Services (−18% vs. −9%) and Consumer Discretionary (−10% vs. −4%). Excluding non-recurring items, Goldman sees S&P 500 EPS growth slowing to 18% in 2027 from nearly 30% this year.
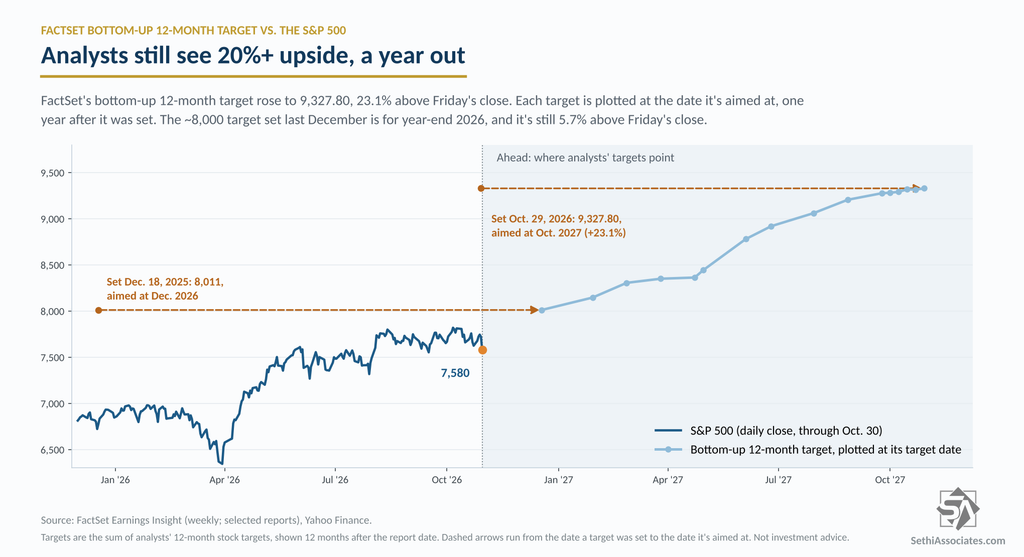
Analysts meanwhile still see plenty of upside, with FactSet’s compilation of analyst bottom-up SPX 12-month price targets edging up to 9,327.80 (+14pts w/w, ~+1,000 pts since March 31st, ~+1,400 pts since Thanksgiving, and ~+2,635 pts since July 1, 2025). That would be +20.8% from Thursday’s close (7,720.39), down from +21.5% the prior week as the index rose about 0.7% through Thursday (and +23.1% from Friday’s close).
As a reminder, we started the year with a 12-month bottom-up price target of 8,000. Friday’s close leaves the S&P 500 about 5.7% below that.
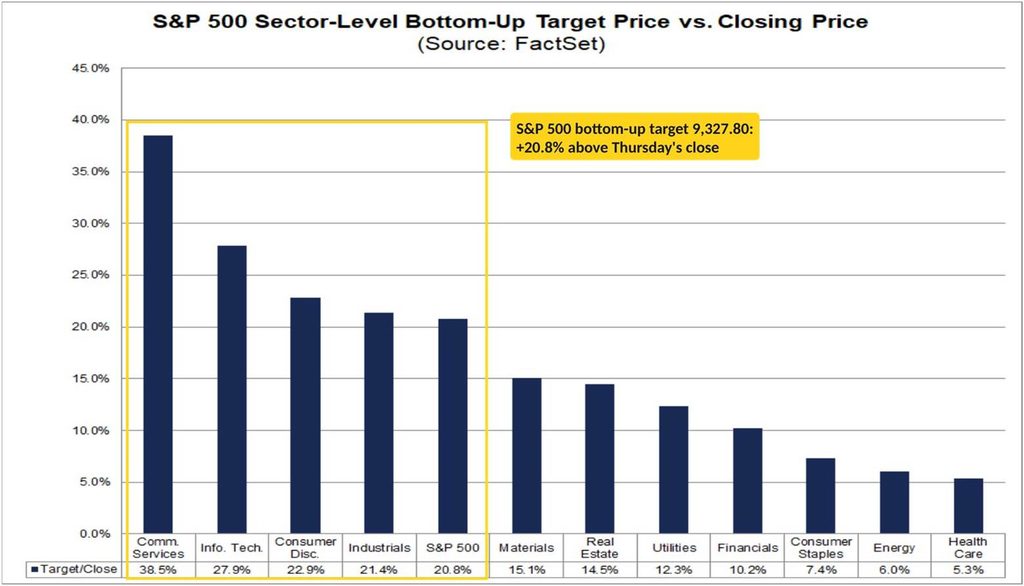
Communications (+38.5%, from +30.6%) now has the most expected upside, followed by Tech (+27.9%, from +30.6%) and Consumer Discretionary (+22.9%). Health Care (+5.3%), Energy (+6.0%) and Consumer Staples (+7.4%) remain the only sectors with single-digit expected upside, with Financials (+10.2%) just above.
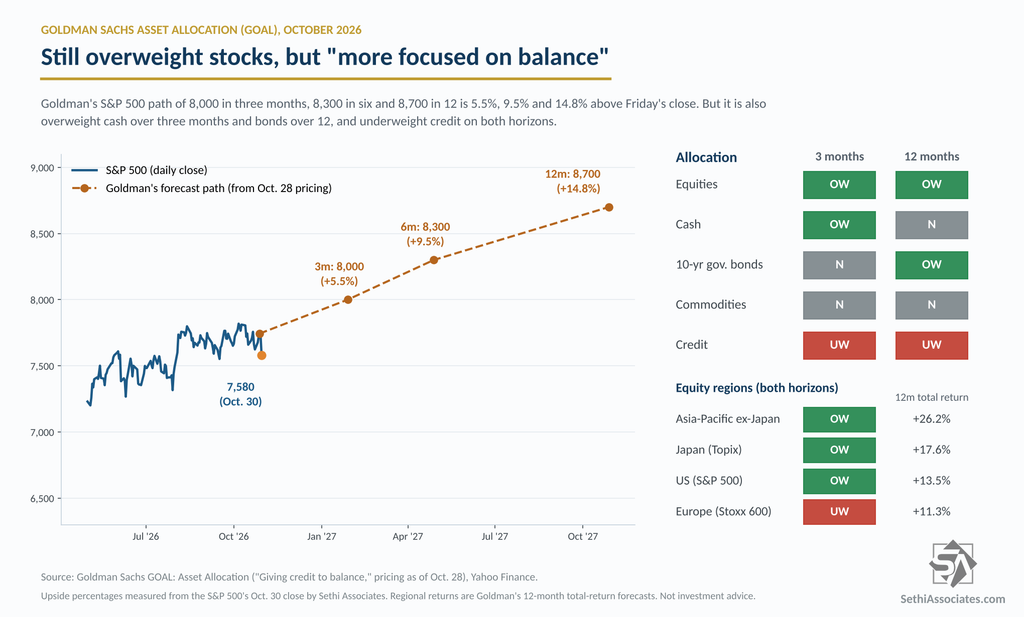
Goldman’s asset allocation team is less optimistic but still overweight equities over both three and 12 months, with the S&P 500 at 8,000 in three months, 8,300 in six and 8,700 in 12, and the US among its preferred regions along with Asia ex-Japan and Japan (Europe is least preferred). But they’re now “more focused on balance”: overweight cash over three months, overweight bonds over 12, and underweight credit on both.
The case rests on earnings, which “are still materially outstripping nominal GDP,” and AI-related stocks “have been more driven by earnings than valuations” since June. The caveat is the same one as above: “AI hyperscaler capex creates headwinds to ROE,” and mega-cap Tech ROEs “are expected to decline.”
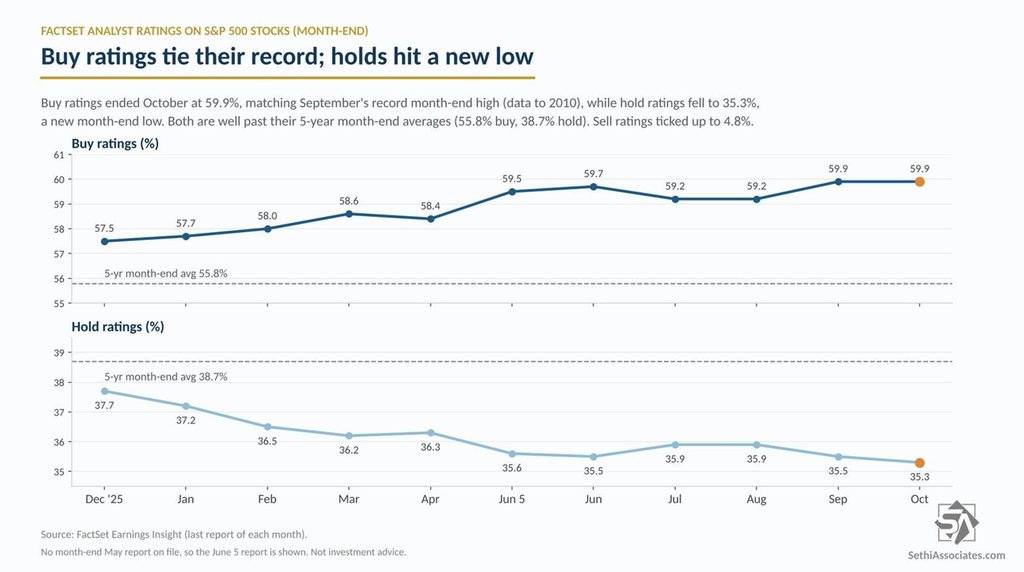
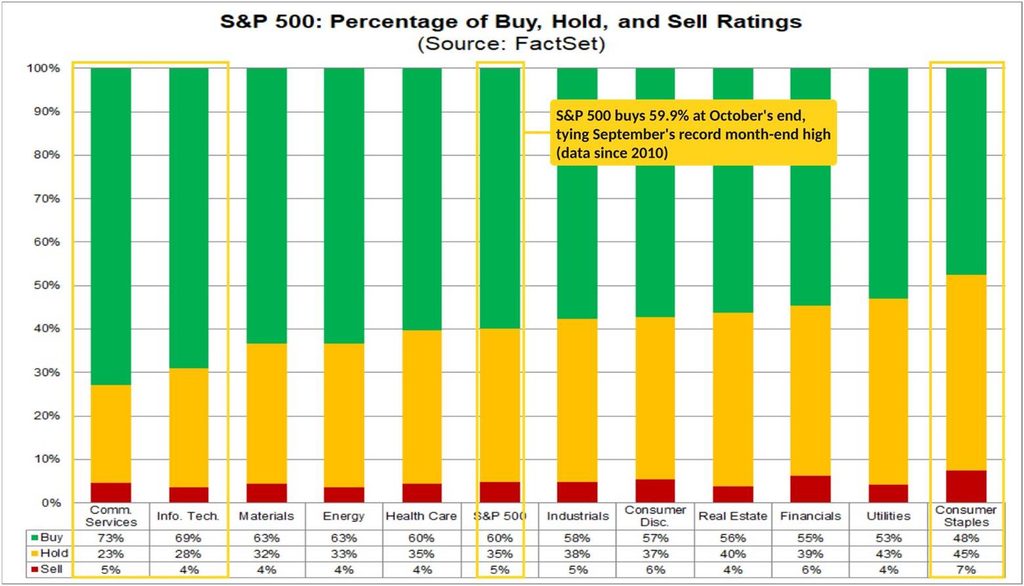
In terms of analyst ratings, buy ratings ended October at 59.9% (from 60.0% the prior week), matching September’s record month-end high (to 2010), while hold ratings fell to 35.3%, a new month-end record low (from 35.5% in June and September). The 5-year month-end averages are 55.8% and 38.7%. Sell ratings ticked up to 4.8%, still in their narrow range since 2009 and below the 5-year month-end average of 5.6%.
Communications (73%) and Tech (69%) have the highest share of buys, while Consumer Staples has the lowest (48%) and the most sells (7%).
Valuations Remain Well Off Highs
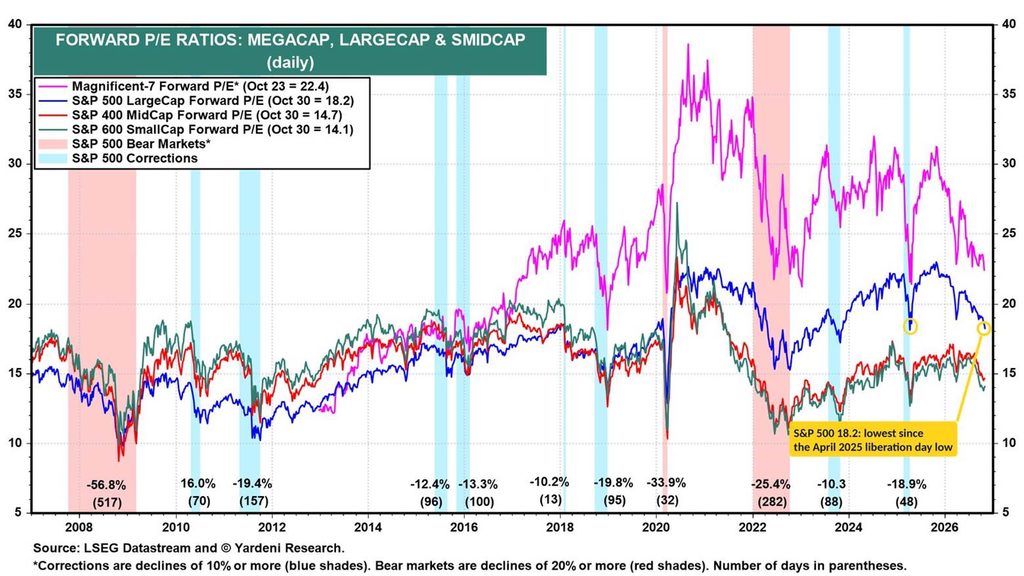
With the index falling and earnings estimates rising, the S&P 500’s forward P/E is down to 18.2 on Yardeni’s numbers, “its lowest reading since the April 2025 liberation day low.” As he notes, “forward earnings is up 49.1% since then! (The stock market rally since then is all attributable to fabulous earnings momentum, or FEMO, because FOMO, or the fear of losing out that drives up the ‘P’ of ‘P/E,’ isn’t a factor.)” Mid caps (14.7) and small caps (14.1) are cheaper still, and the Mag 7 is at 22.4 (as of October 23rd).
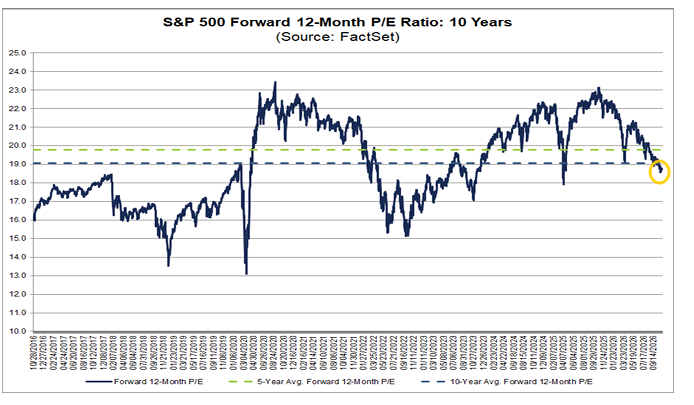
FactSet’s forward P/E is 18.7, below the 5-year (19.8) and 10-year (19.1) averages and down from 19.0 on September 30th, as the index rose 0.9% since then while forward EPS rose 2.5% (through Thursday). The trailing P/E is 25.9.
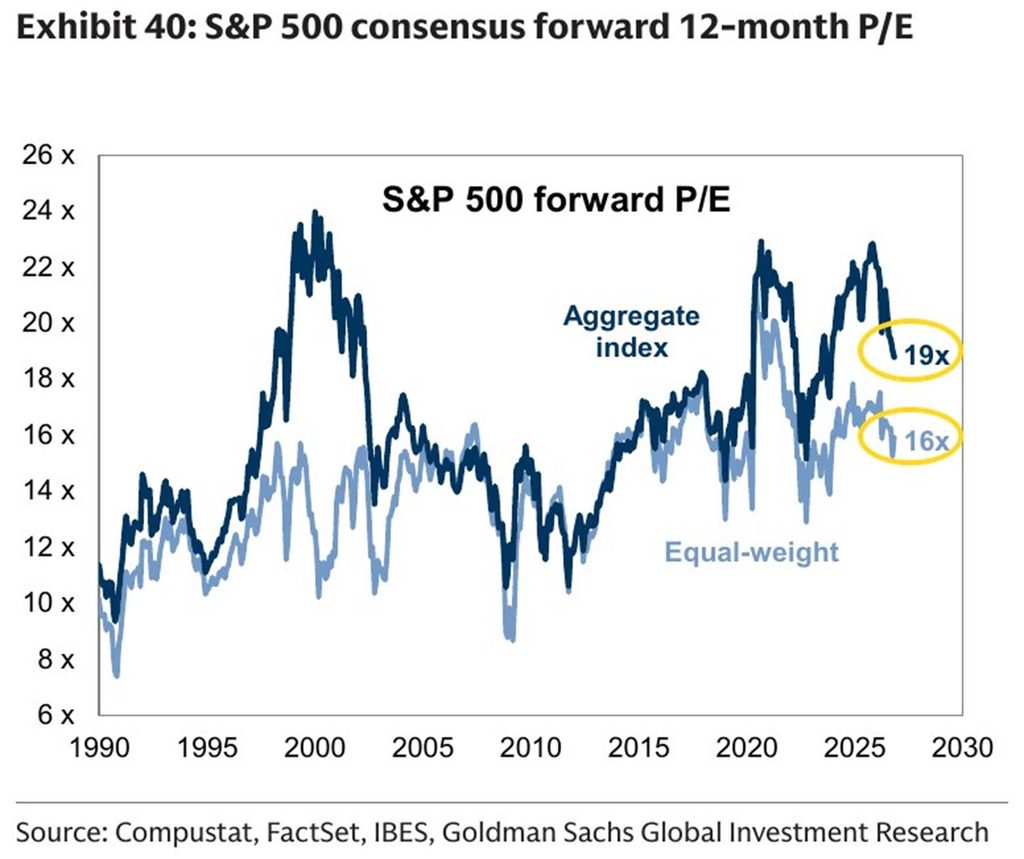
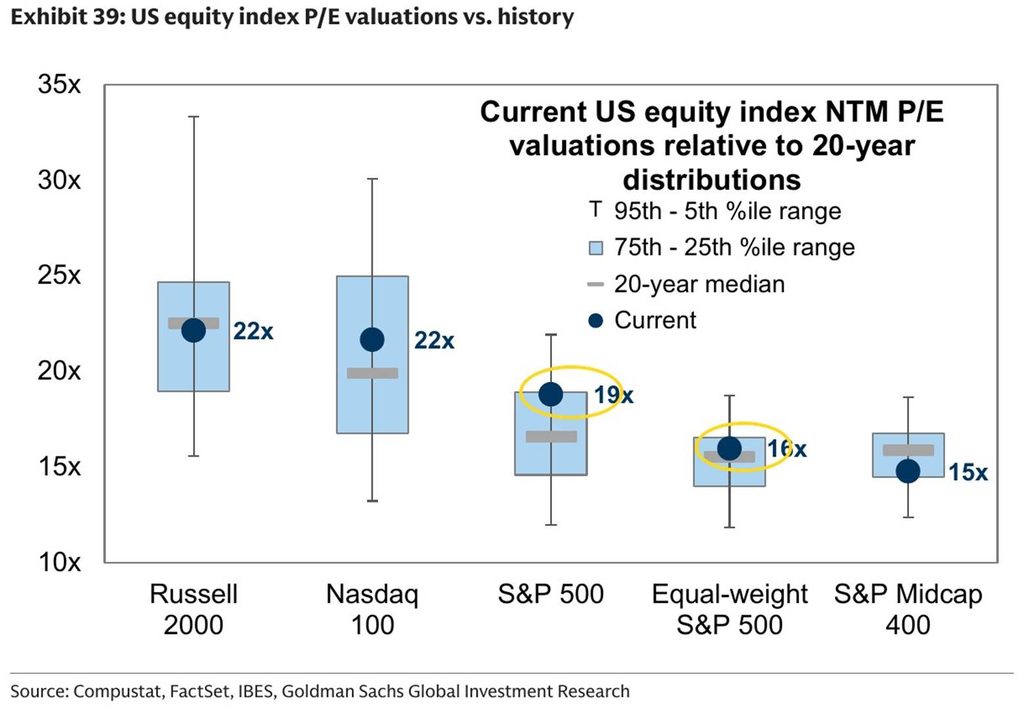
Goldman has the S&P 500 at 19x forward earnings and the equal-weight index at 16x. Against their 20-year histories, the S&P 500 sits near the top of its middle range, while the equal-weight index is near its median and the S&P 400 (15x) is below it.
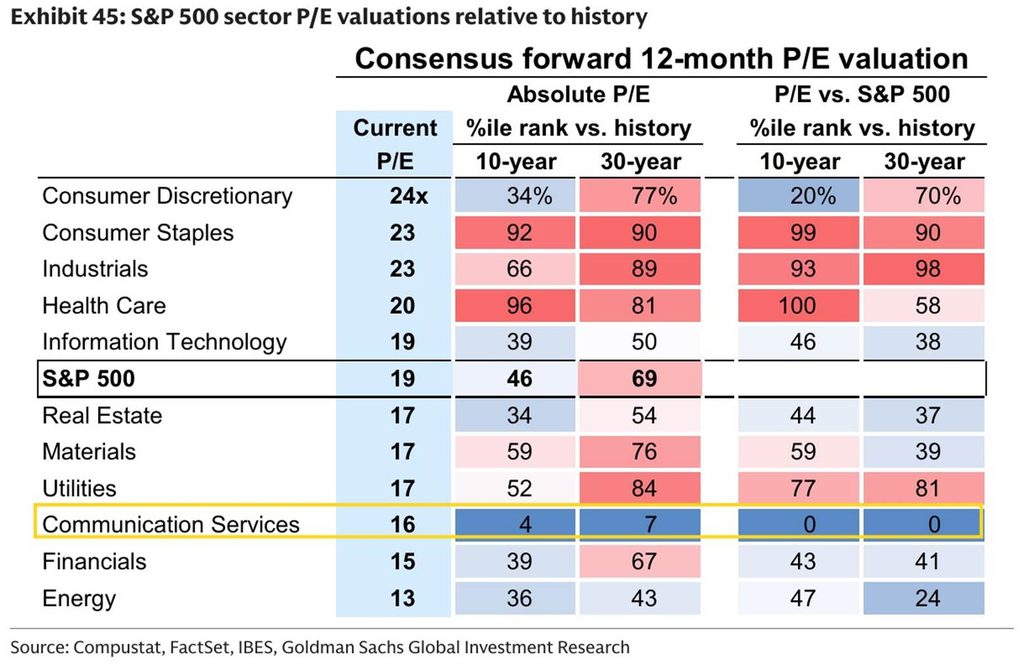
By sector, Comm Services (16x) is the cheapest it’s been relative to the S&P 500 on both 10- and 30-year lookbacks (0th percentile), while Consumer Staples, Industrials and Health Care sit at or near the top of their 10-year relative ranges (99th, 93rd and 100th percentiles).
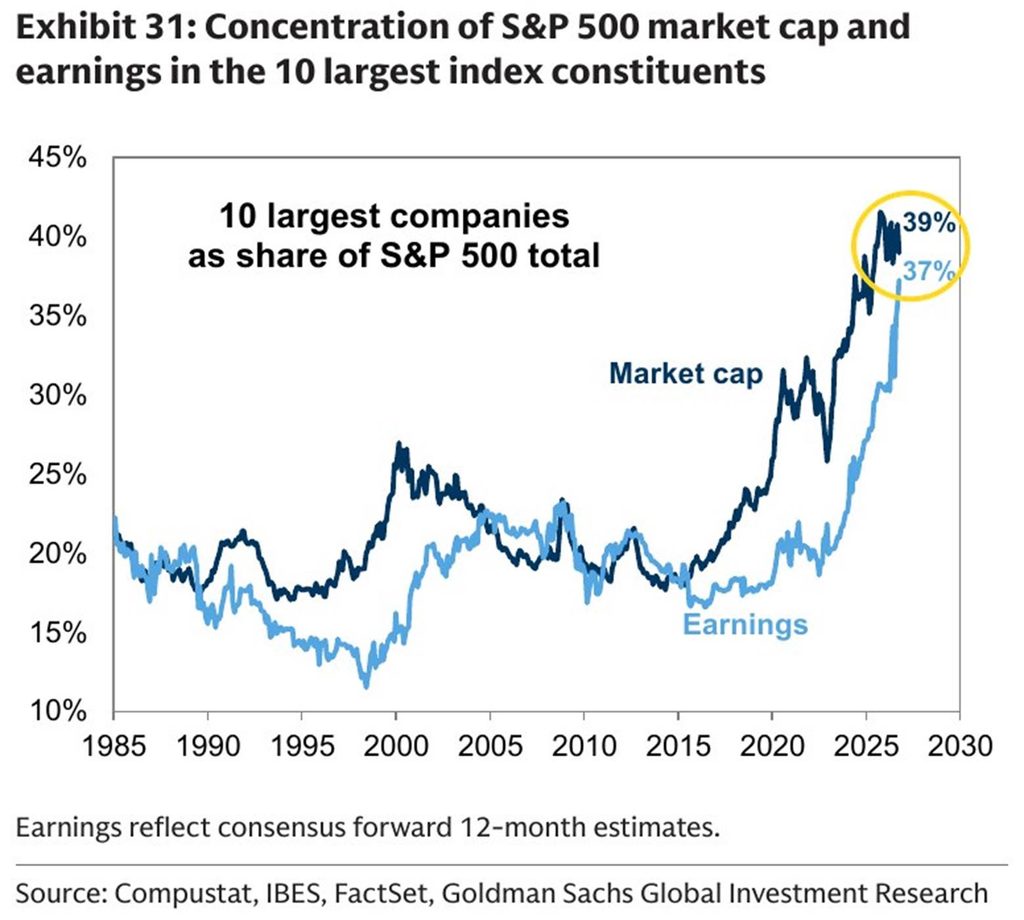
And concentration remains extreme, with the 10 largest companies accounting for 39% of S&P 500 market cap (just off the record) and a record 37% of forward earnings (data since 1985).
Breadth Continues to Improve
Breadth improved again almost across the board last week, even with sharp drops Friday, though the Nasdaq continues to lag.
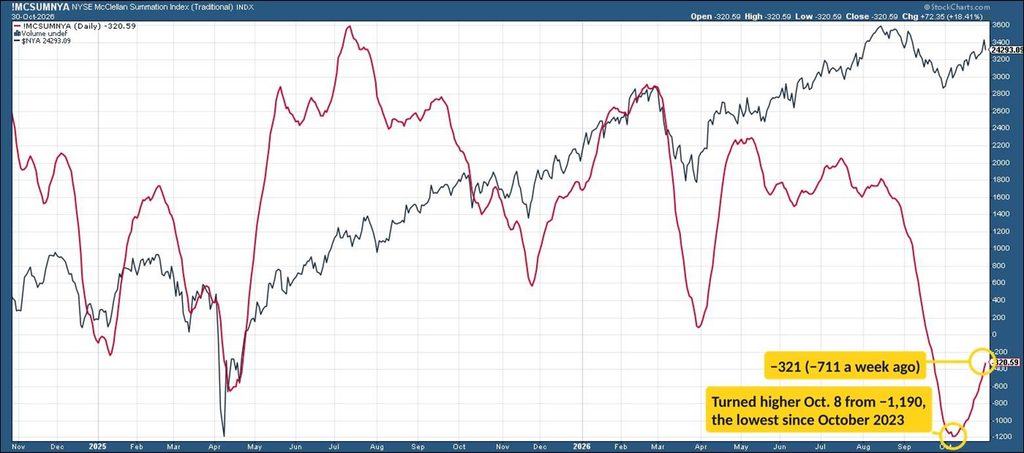
The McClellan Summation Index (red line, broadly whether the typical stock is doing relatively better or worse than the index) continued its turn higher, to −321 from −711 a week earlier. Here’s Claude’s update on the rebound from the October 8th sub-zero turn:
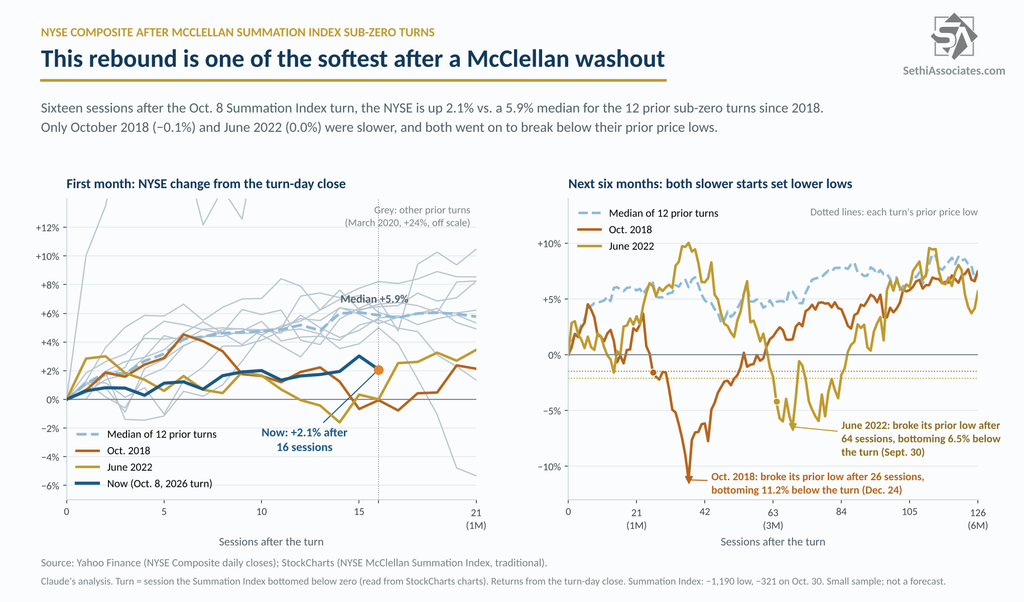
Sixteen sessions in, the rebound remains one of the softest. The NYSE is up 2.1% since the October 8th turn, against a median of 5.9% at the same point after the 12 prior turns. Only October 2018 (−0.1%) and June 2022 (0.0%) were slower, and both were followed by lower price lows. The Summation Index has climbed about 870 points from its −1,190 low, the lowest since October 2023. The one-month mark (21 sessions) comes Friday, when the prior turns’ median gain was 5.8%, with 11 of 12 higher.
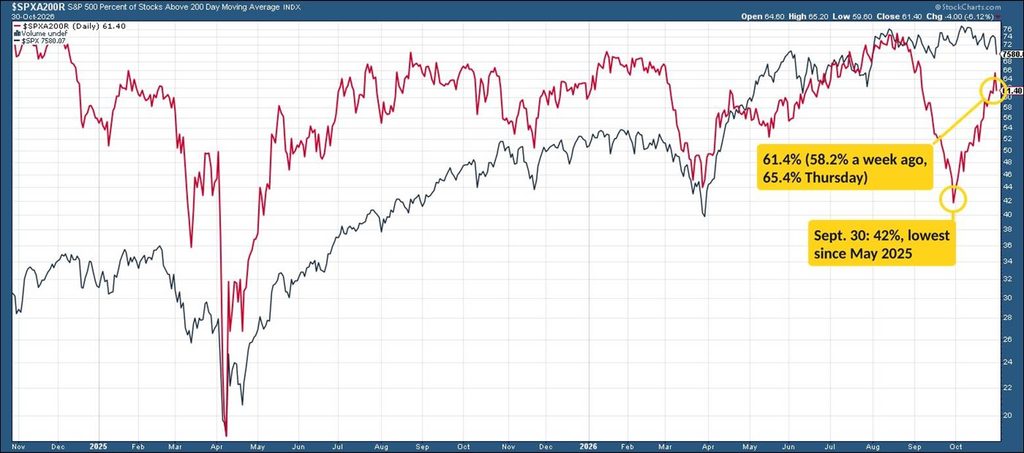
The percentage of stocks over their 200-DMAs (red lines) improved again for the S&P 500, up to 61.4% from 58.2% a week earlier (and 65.4% Thursday), and up from 42% at the September 30th low, the lowest since May 2025.
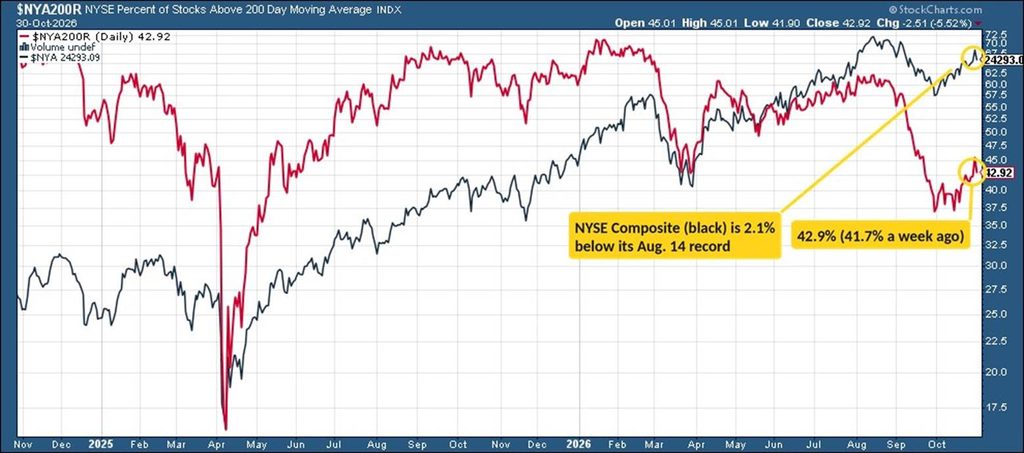
The NYSE edged up to 42.9% from 41.7%, even though the NYSE Composite (black line) is just 2.1% below its August 14th record.
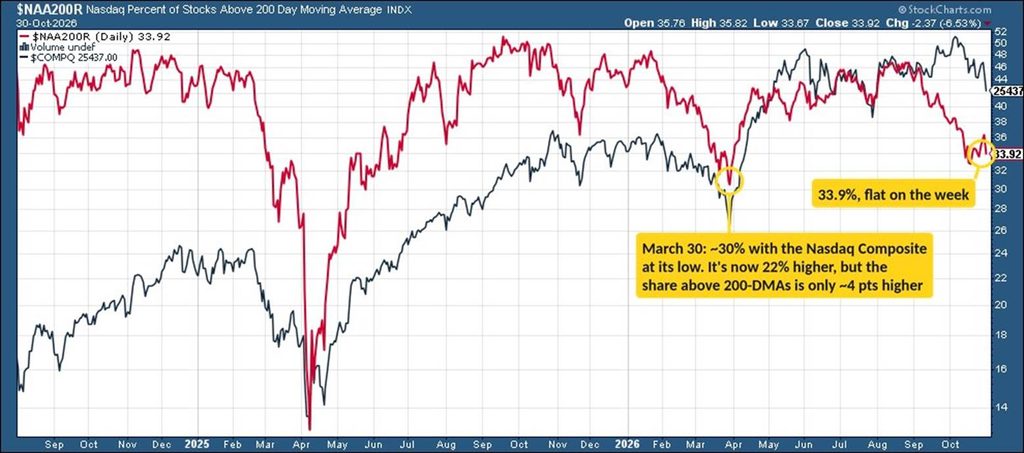
While the Nasdaq was flat at 33.9%. On March 30th, the Nasdaq Composite’s 2026 low, about 30% of its stocks were above their 200-DMAs. The Composite is 22% higher now, but the share above their 200-DMAs is only about 4 points higher.
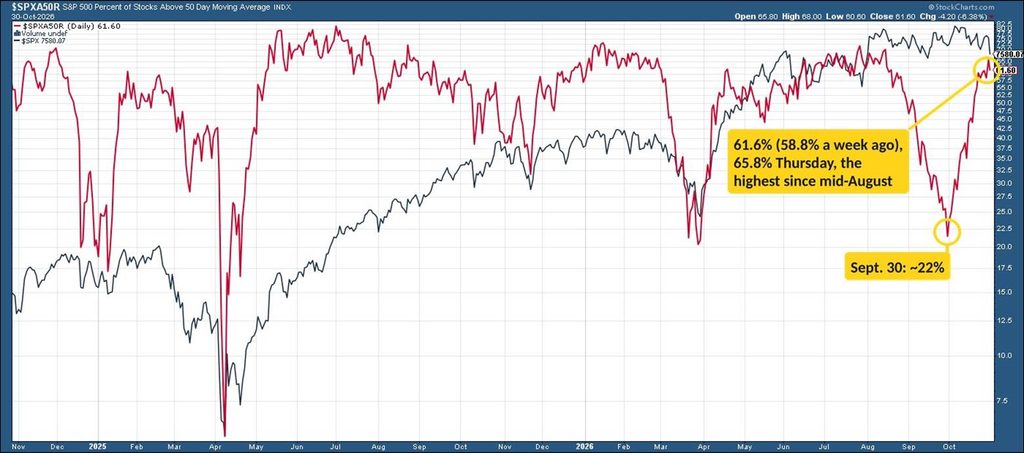
It was a similar story for the shorter-term 50- and 20-DMAs, with all three exchanges higher on the week despite Friday’s drops. The S&P 500’s 65.8% above its 50-DMA Thursday was the highest since mid-August.
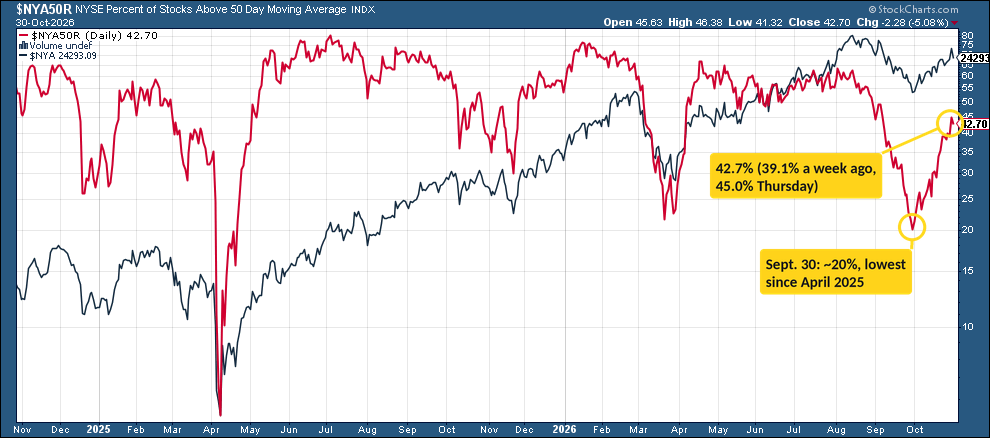
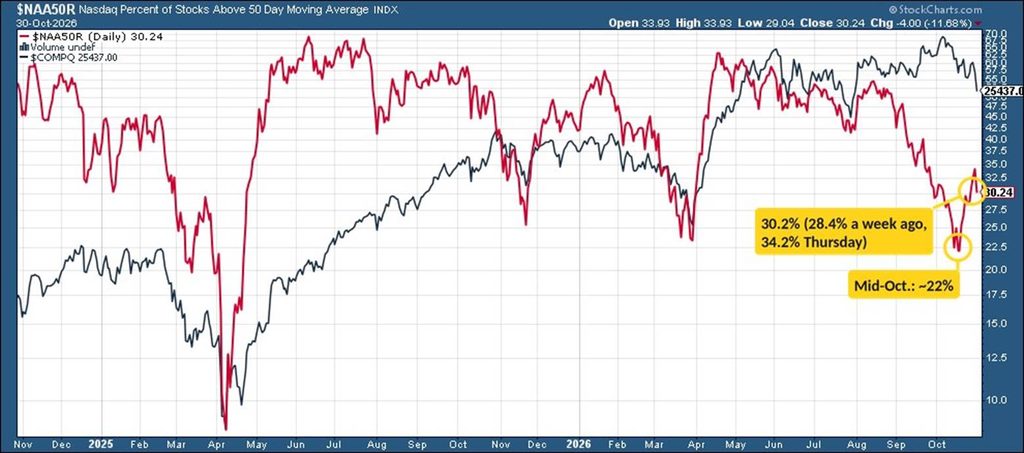
50-DMAs: S&P 500 61.6% (from 58.8%), NYSE 42.7% (from 39.1%), Nasdaq 30.2% (from 28.4%)
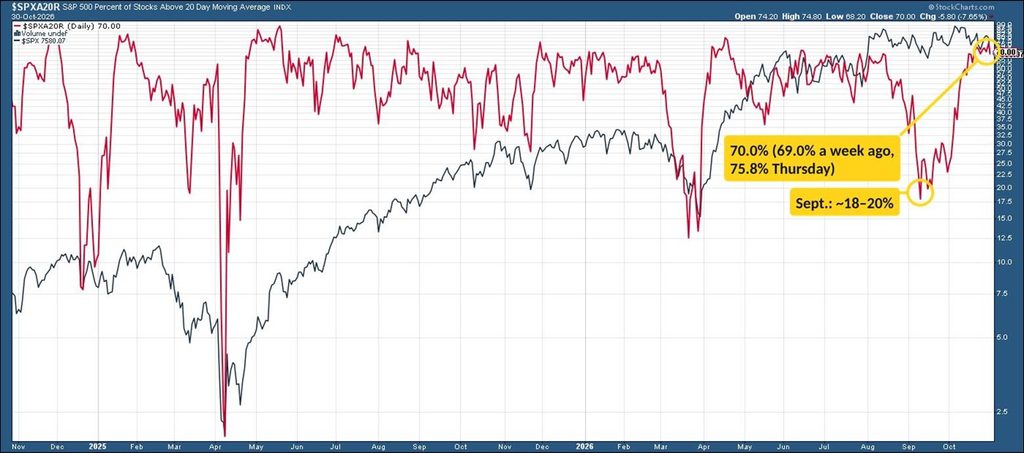
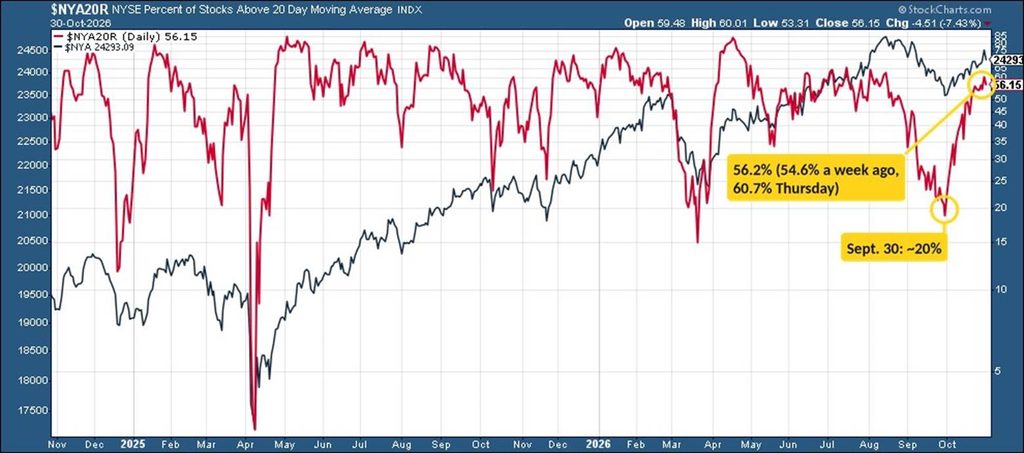
20-DMAs: S&P 500 70.0% (from 69.0%), NYSE 56.2% (from 54.6%), Nasdaq 38.2% (from 34.1%)
50-DMAs
20-DMAs
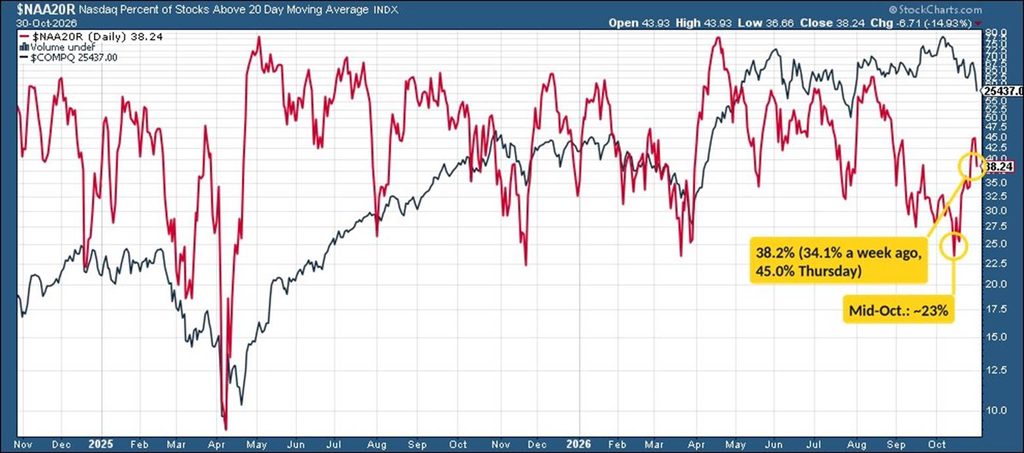
S&P 500 new 52-week highs jumped to 43 Friday from 22 Thursday, the second highest since late July after the 47 on October 22nd, and the 10-DMA (blue line) rose to 23.6 from 22.1 a week earlier, the highest since early August.
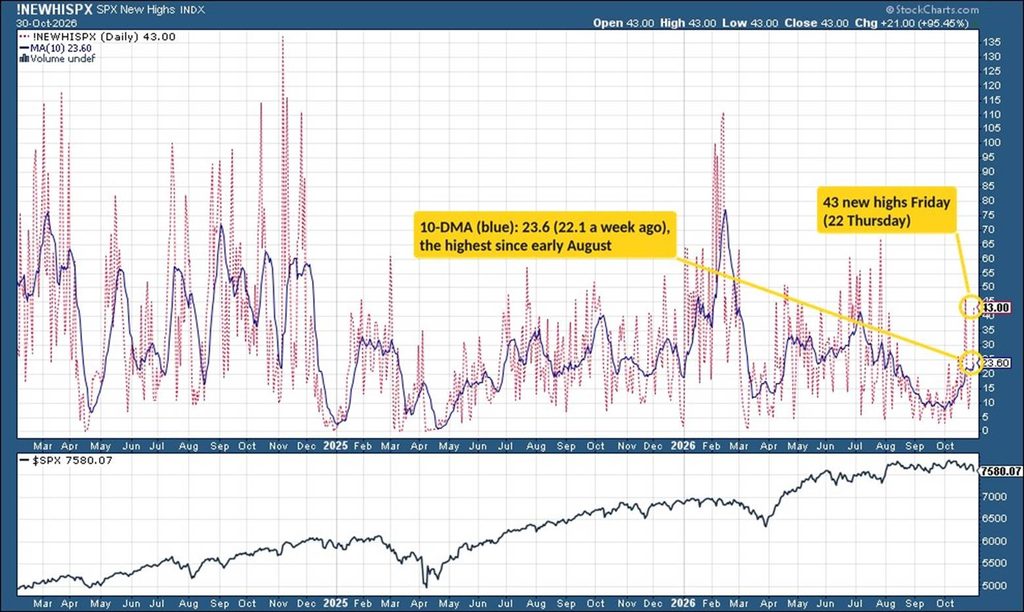
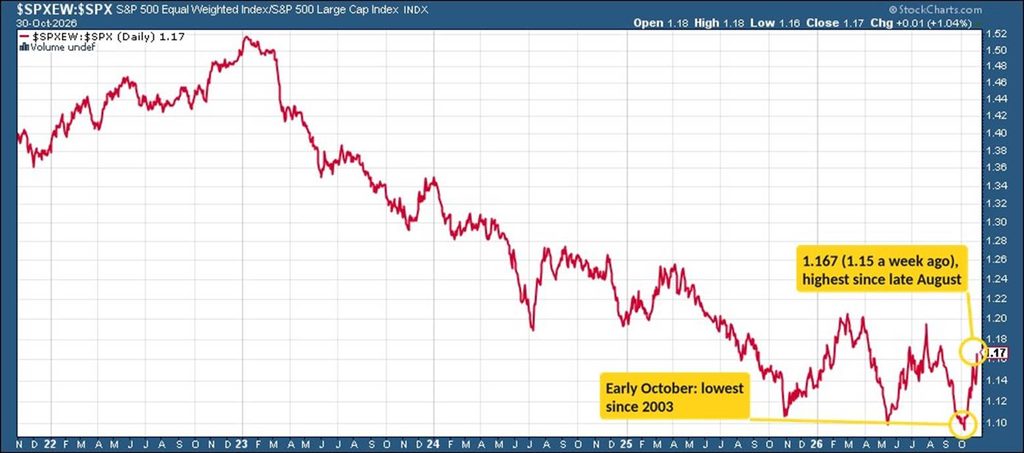
The ratio of the equal-weight S&P 500 to the cap-weighted index extended its bounce from the lowest since 2003 in early October, up to 1.167 from 1.15, the highest since late August. The equal-weight index beat the cap-weighted one by 1.5 points Thursday and by about a point Friday.
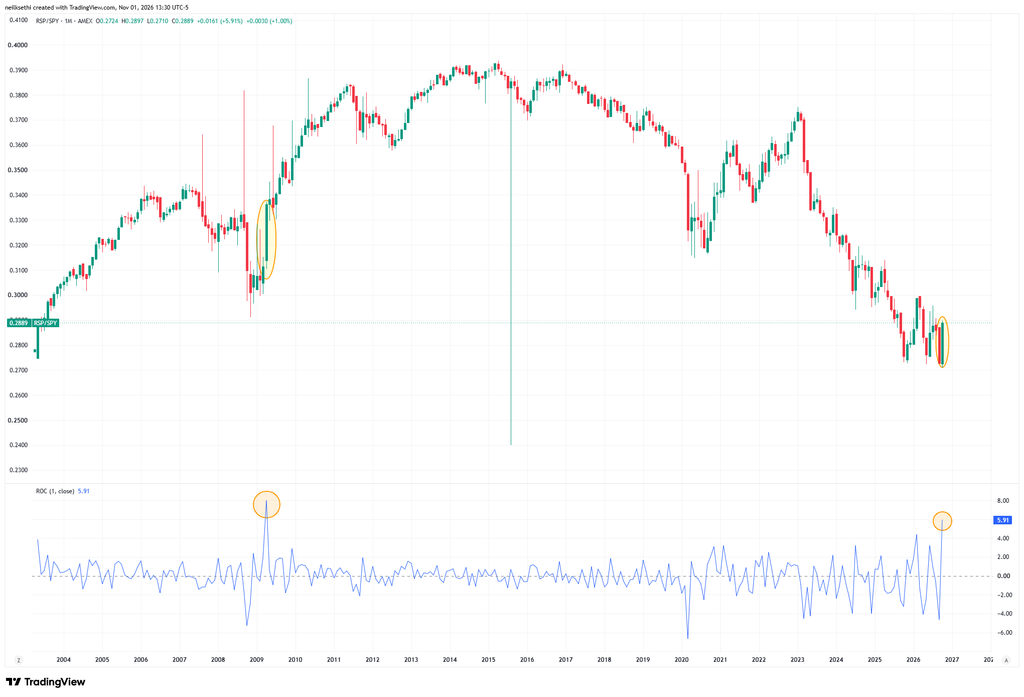
And October’s rotation was historic for the equal-weight index, with RSP returning 5.0% versus −0.9% for SPY, a 5.9-point gap that was its second-largest monthly outperformance after only April 2009 (data since 2003).
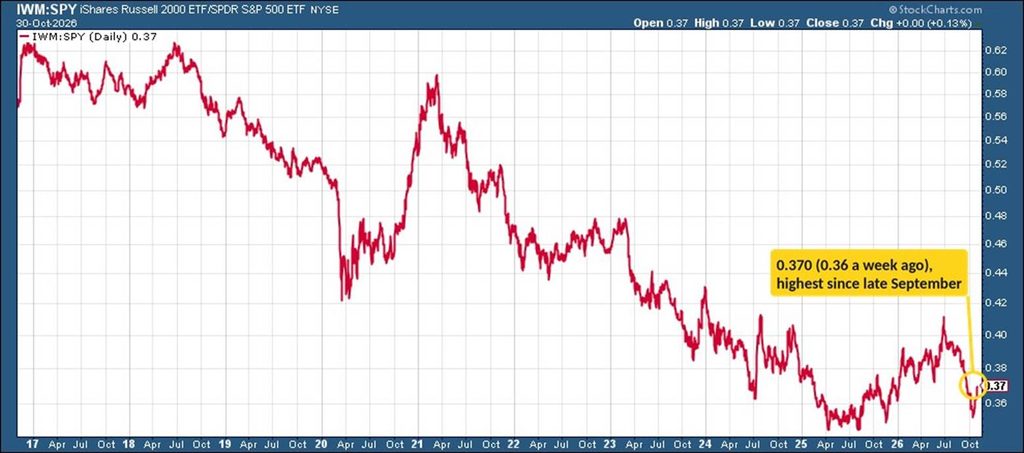
The ratio of small caps to large caps (IWM:SPY) finally made some (incremental) progress, up to 0.370 from 0.36, the highest since late September.
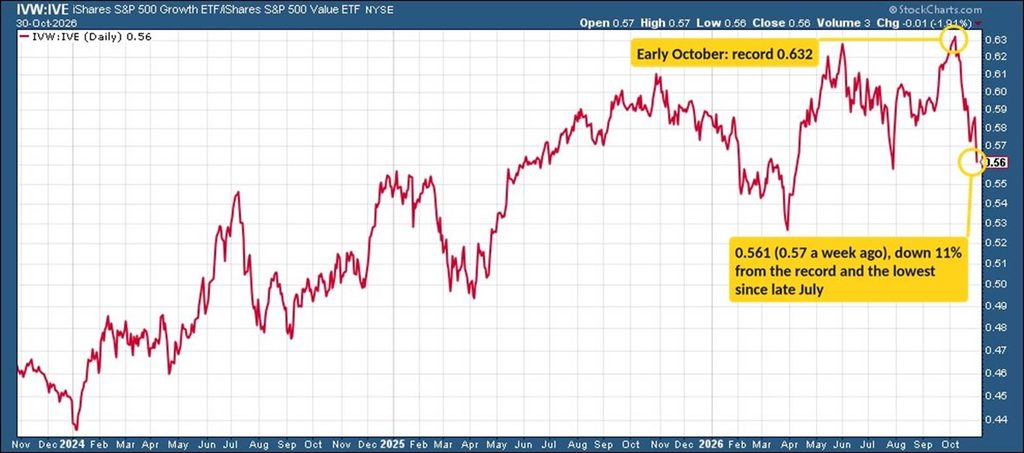
While S&P 500 growth/value (IVW:IVE) continued to fall, down to 0.561 from 0.57, the lowest since late July and 11% below its early-October record.
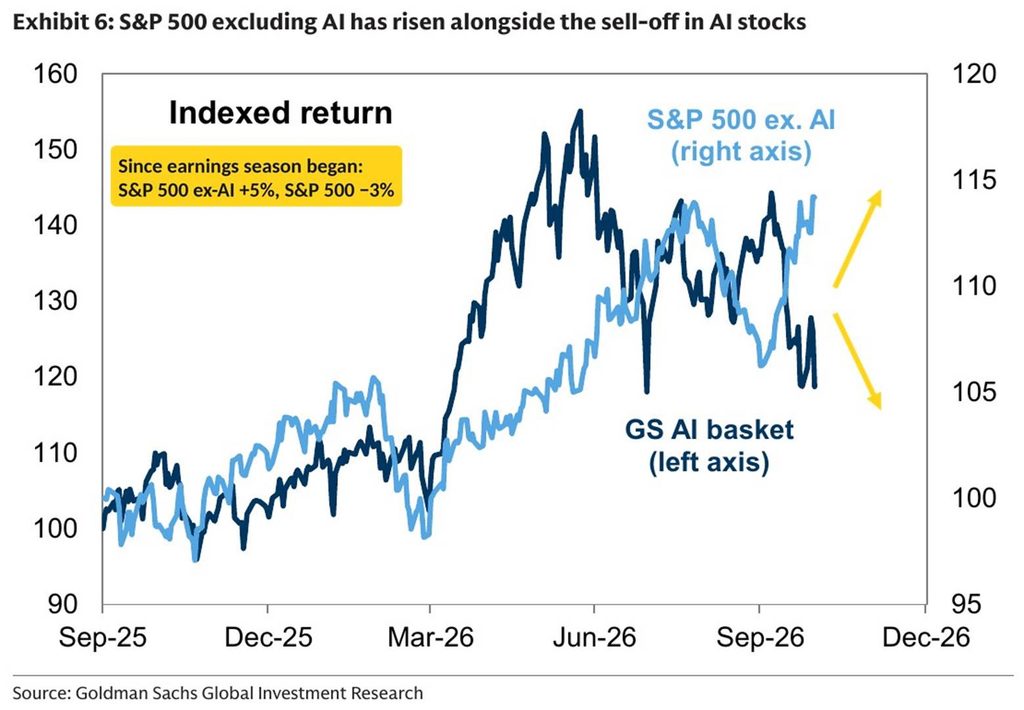
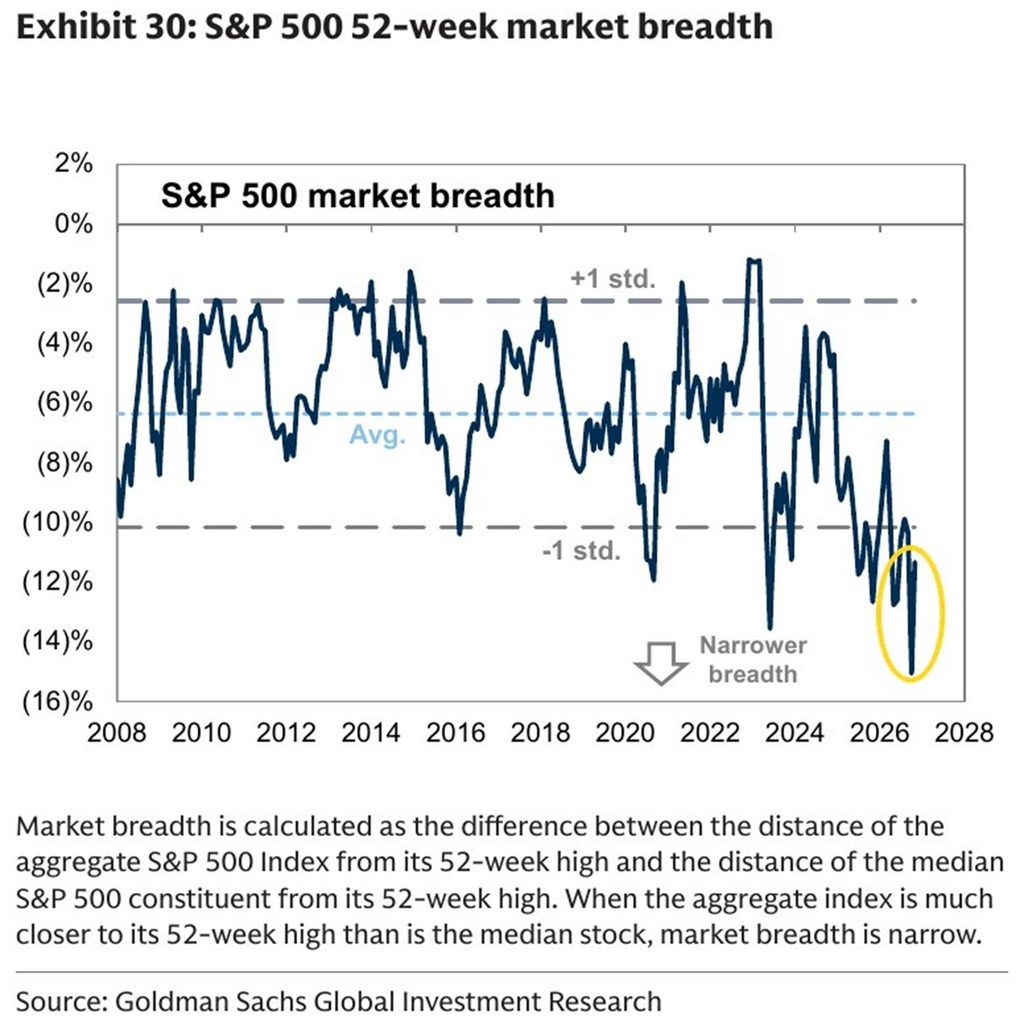
Goldman says narrow breadth “has begun to broaden via a simultaneous ‘catch up’ and ‘catch down'”: since the start of Q3 earnings season, 70% of S&P 500 companies have posted positive returns, but they account for just 50% of the index’s market cap, so the S&P 500 has fallen 3% while the S&P 500 ex-AI has risen 5%.
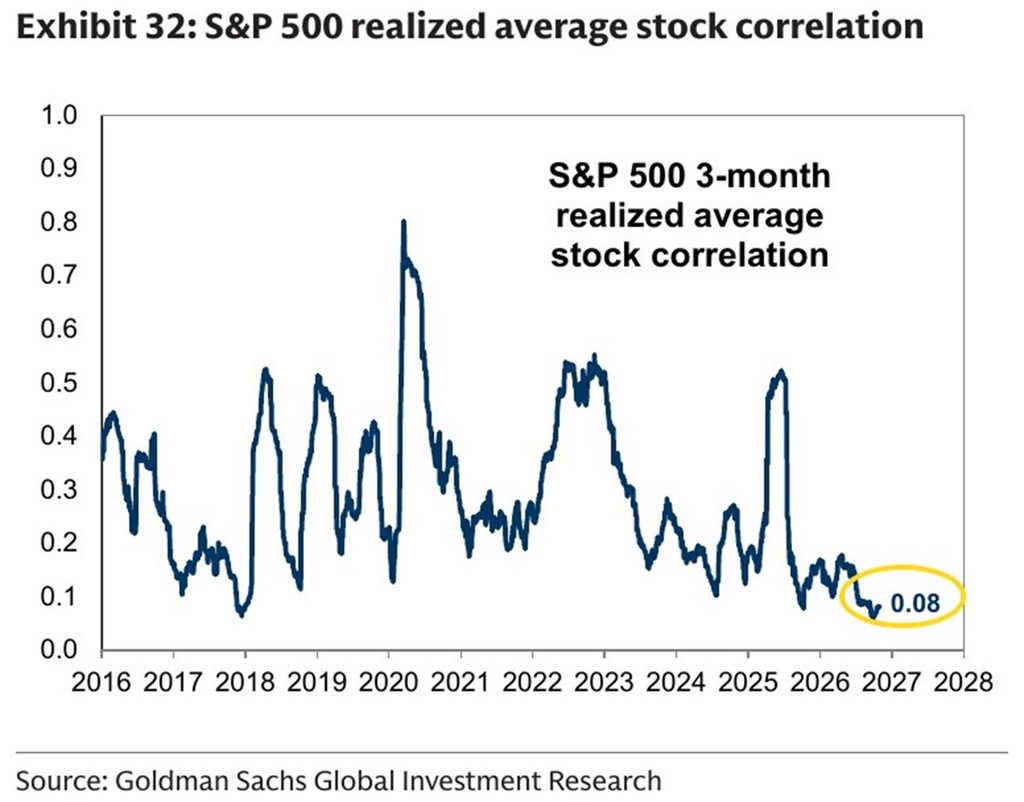
Goldman’s asset allocation team adds that “realised dispersion is at the highest level since the early 2000s” (stocks moving very differently from the index) while implied correlations “are close to all-time lows,” and that “the Tech sector equity weight is now above Tech Bubble levels.” Even the share of S&P 500 stocks with a negative beta has risen, “similar to during the Tech Bubble.”
Some Buying Ahead of Friday’s Selloff; Selling into It
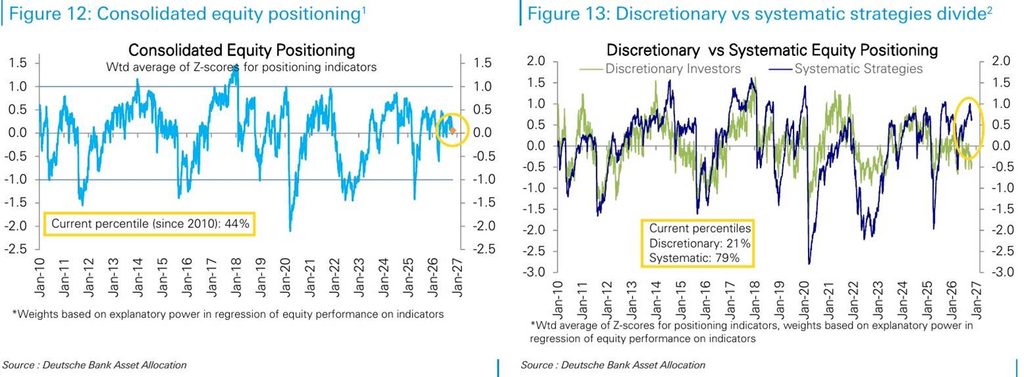
Starting with Deutsche Bank, overall equity positioning ticked up to the 44th percentile (from the 41st), with discretionary investors at the 21st percentile (from the 18th) and systematic strategies unchanged at the 79th.
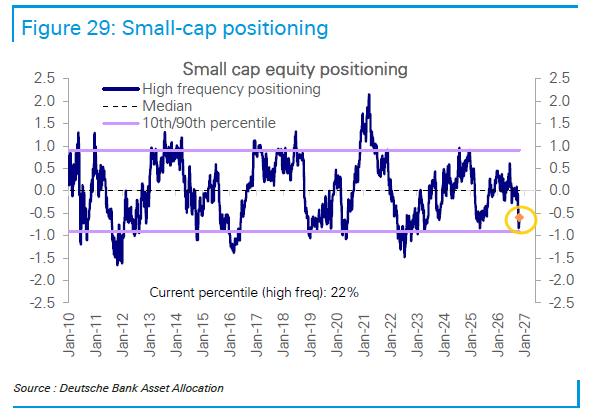
Large-cap positioning rose to modestly overweight (66th percentile, from the 59th), and small caps to the 22nd (from the 12th). Within large caps, discretionary investors are neutral (48th percentile in their text), a level DB says is in line with mid-single-digit earnings growth, against Q3 growth tracking around 30%.
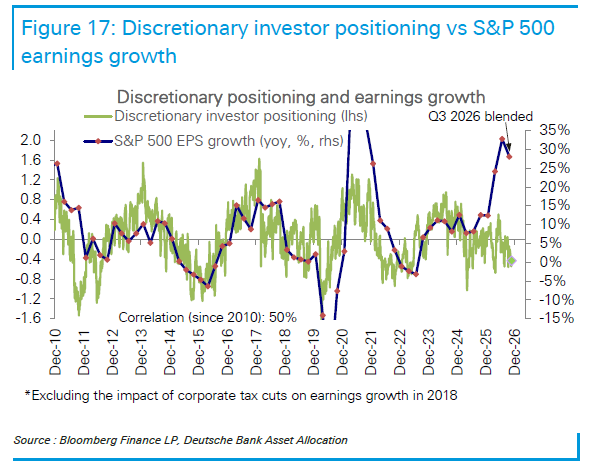
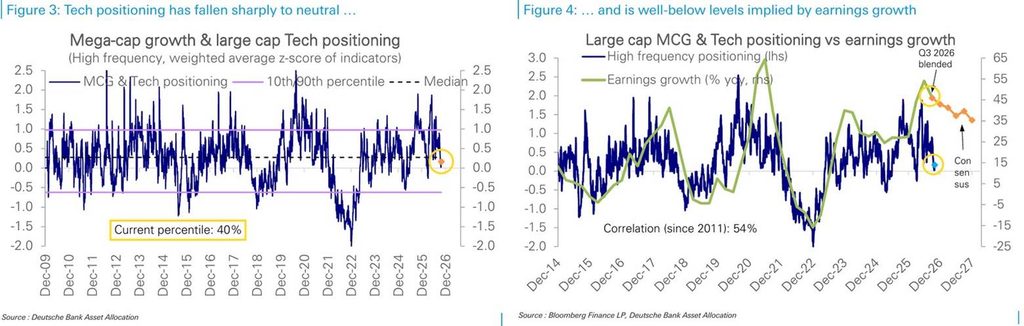
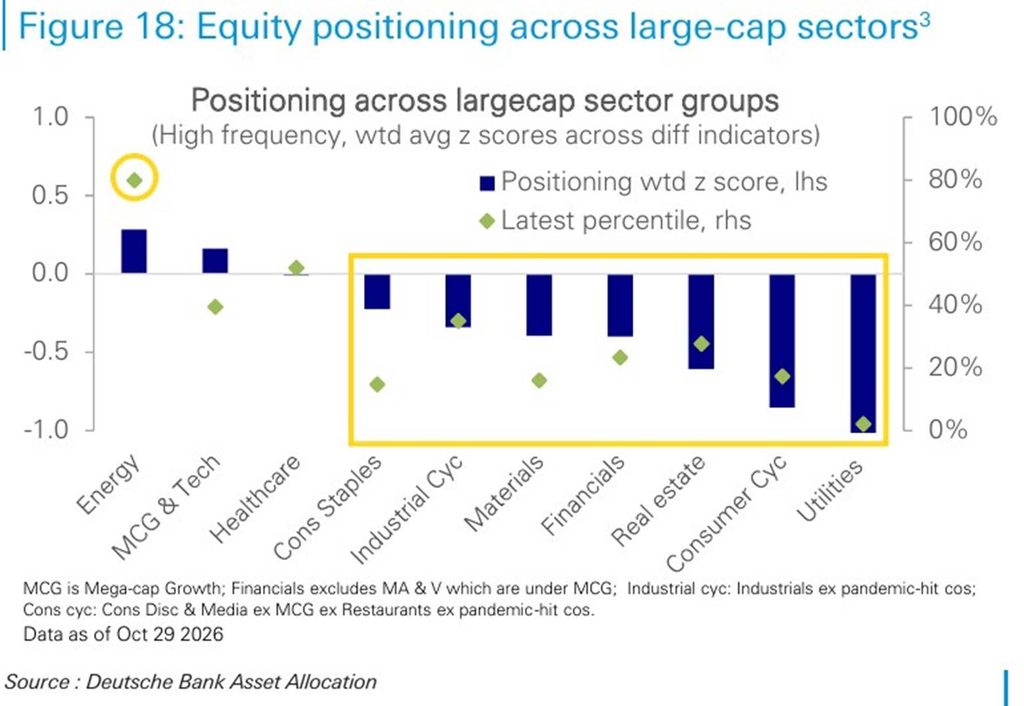
Tech positioning edged up to the 40th percentile (from the 33rd). DB says that’s in line with earnings growth of around 10%, versus ~47% in Q3 and the 36% consensus expects by the end of next year. Outside of Tech, sector positioning is very low (6th percentile), with Utilities (2nd), Consumer Staples (15th), Materials (16th) and Consumer Cyclicals (17th) the lowest and Energy (80th) the only sector clearly overweight.
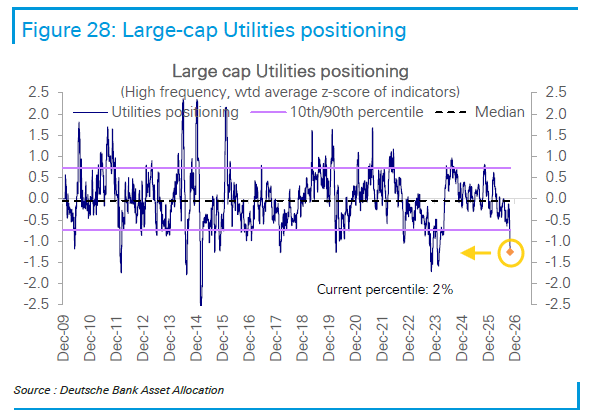
Despite the recent rally, Utilities positioning is in just the 2nd percentile, the least since 2021.
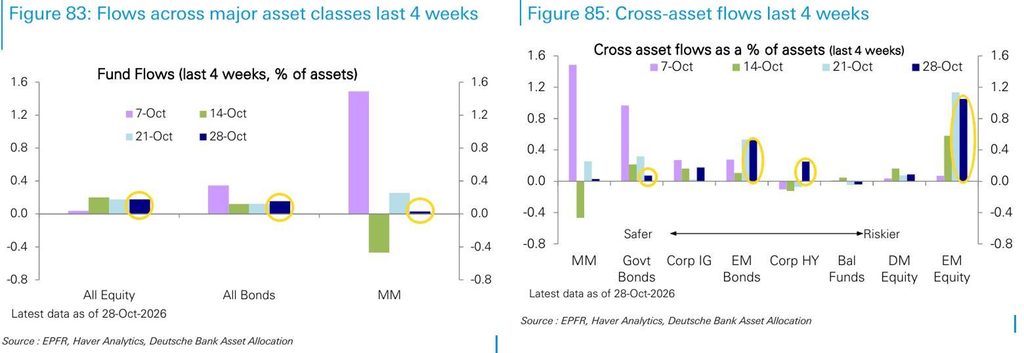
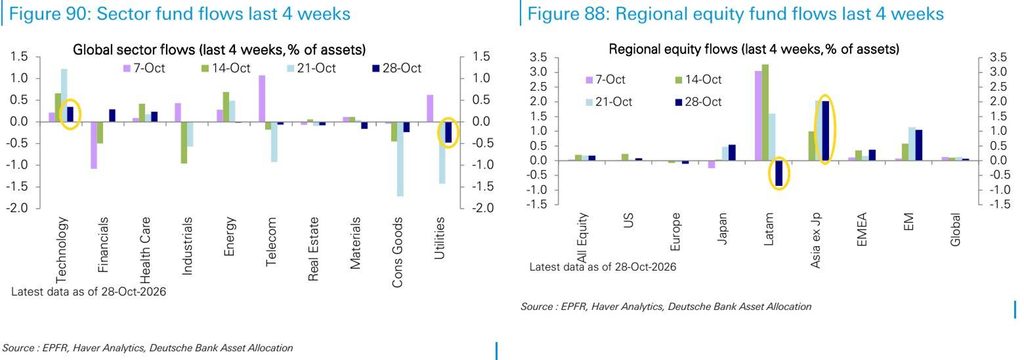
Fund flows were steady into the selloff. Per DB’s read of EPFR data (week through Wednesday, October 28th), equity funds took in about 0.2% of assets for a third straight week, bond fund inflows ticked up by about 0.15%, and money market inflows slowed to near zero (from about +0.25% the prior week).
The risk appetite showed up abroad. EM equity funds took in more than 1% of assets for a second week, led by Asia ex-Japan (about 2%), while Latin America saw outflows (about −0.85%) after big inflows earlier in the month, and US equity funds took in less than 0.1%. By sector, Tech funds still saw inflows (about 0.35%), but well below the prior week’s ~1.2%, while Utilities saw outflows for a second week (about −0.5%).
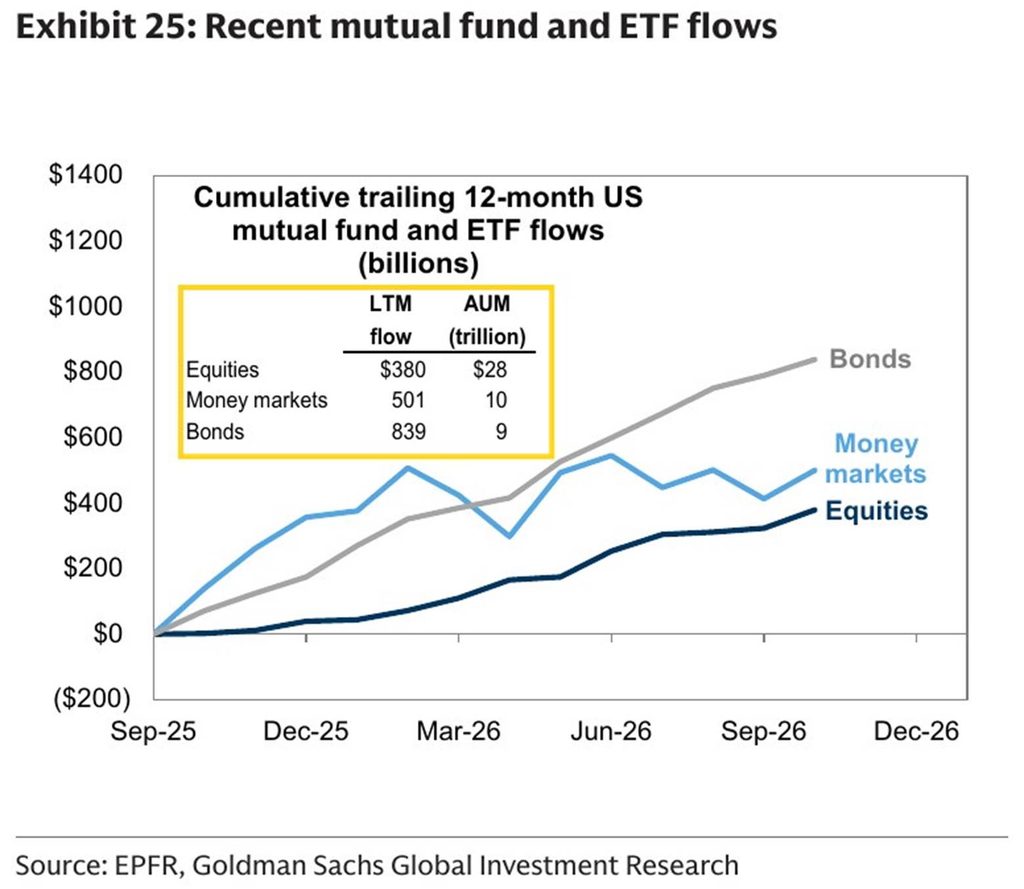
And for perspective on the longer-run trend, Goldman tallies $839B of inflows to US bond mutual funds and ETFs over the past 12 months, versus $501B for money markets and $380B for equities.
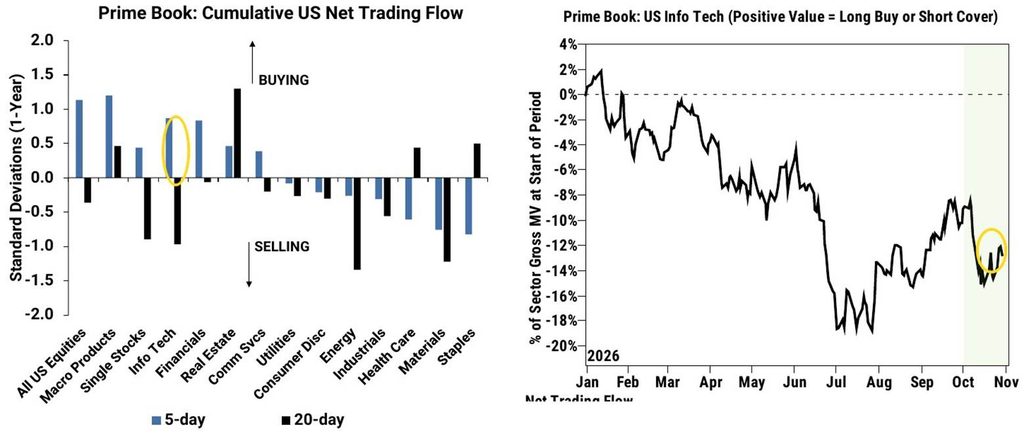
Goldman’s look at hedge funds finds they finally bought, but mostly by covering shorts. Goldman’s Prime Book saw hedge funds net buy US equities for the first time in four weeks (October 23–29, +1.1 SDs vs. the past year), with index and ETF products making up 73% of the buying as US-listed ETF shorts fell 4.8%, the largest percentage covering in more than six months.
Single stocks were modestly net bought after five weeks of selling, almost entirely on short covers. Info Tech was the most net bought sector, but that buying was only ~40% of what hedge funds sold the prior three weeks, and the Mag 7 were net sold in four of the last five sessions, which Goldman says suggests “little recovery in risk appetite.” Hedge funds also unwound Financials risk at the fastest pace in more than six months.
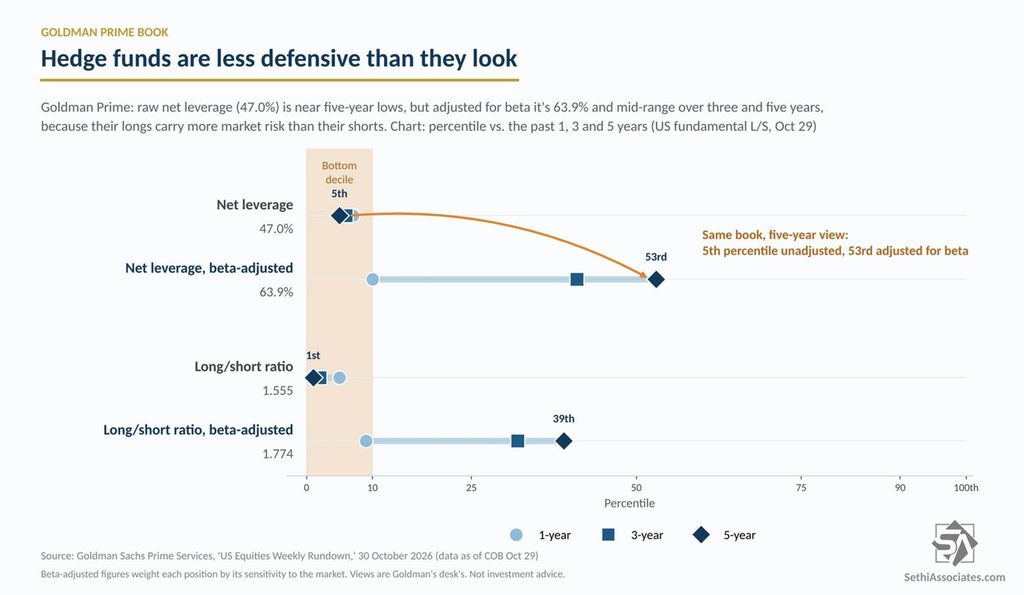
That lifted net leverage 3.6 points to 47.0% from the prior week’s five-year low, though it’s still only at the 5th percentile over five years, while gross leverage (216.3%) is at the 91st. The long/short ratio (1.555) sits at the 1st percentile over five years.
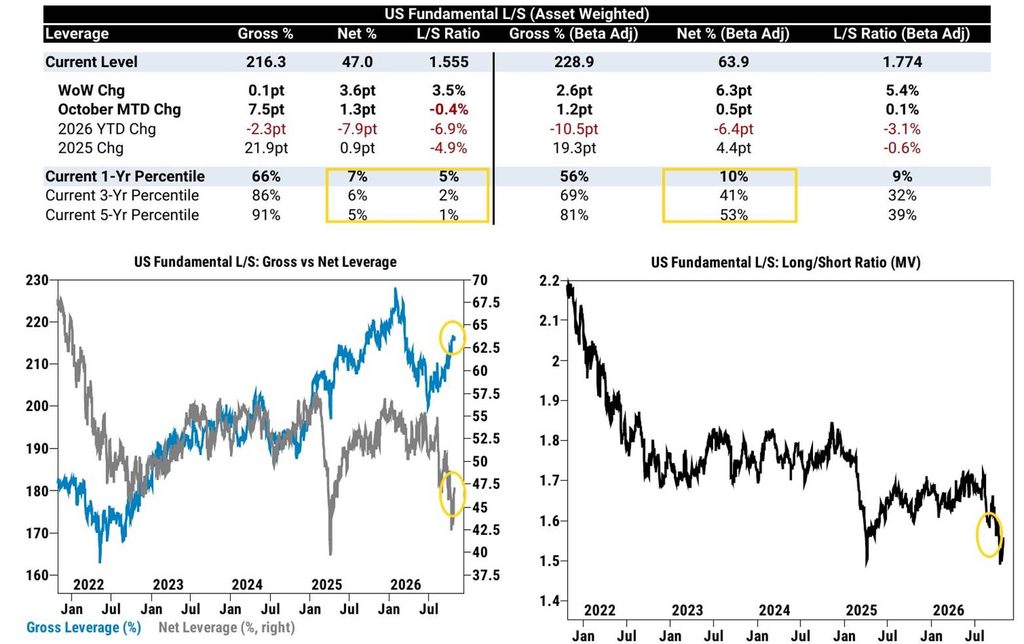
On a beta-adjusted basis (a risk-adjusted measure of positioning), though, net leverage is 63.9%, which is only at the 41st percentile over three years and the 53rd over five. In addition to what stocks/sectors they are in, hedge funds’ longs carry more market sensitivity than their shorts (per Claude, an average beta of about 1.1 on the longs vs. about 1.0 on the shorts), consistent with what Bloomberg’s Simon White has described: hedge funds holding on to their core AI longs and hedging by shorting the index. So in terms of actual market risk, they’re not nearly as defensively positioned as the headline net number suggests.
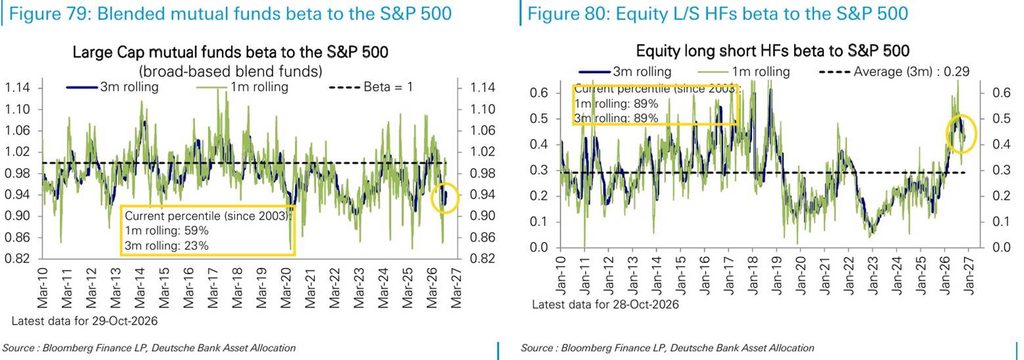
DB’s beta measures point the same way: equity long/short hedge funds’ rolling beta to the S&P 500 is at the 89th percentile (since 2003) on both a 1- and a 3-month basis, while large-cap mutual funds are at the 59th percentile on a 1-month basis and the 23rd on a 3-month basis.
But Goldman’s Shares desk says the picture changed Friday: a week that started with demand for semis, “predominately from the Long Only community,” ended in an aggressive selloff with very little defense according to a weekend update. Asset managers finished the week net sellers, “reversing early week tech demand + some,” with most of the supply “at the epicenter of tech.” ETFs were ~31% of the tape Friday, the highest full session since June, and the moves “felt systematic / top-down driven” (month-end also played a part). And pensions were modeled to buy only ~$4.5bn of stocks for month-end, the 31st percentile of estimates over the past three years.
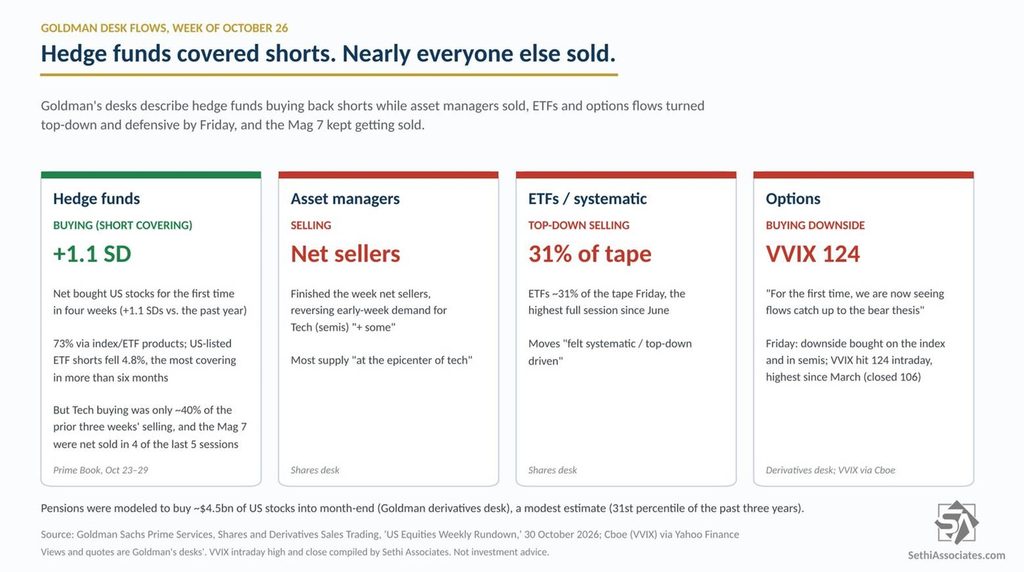
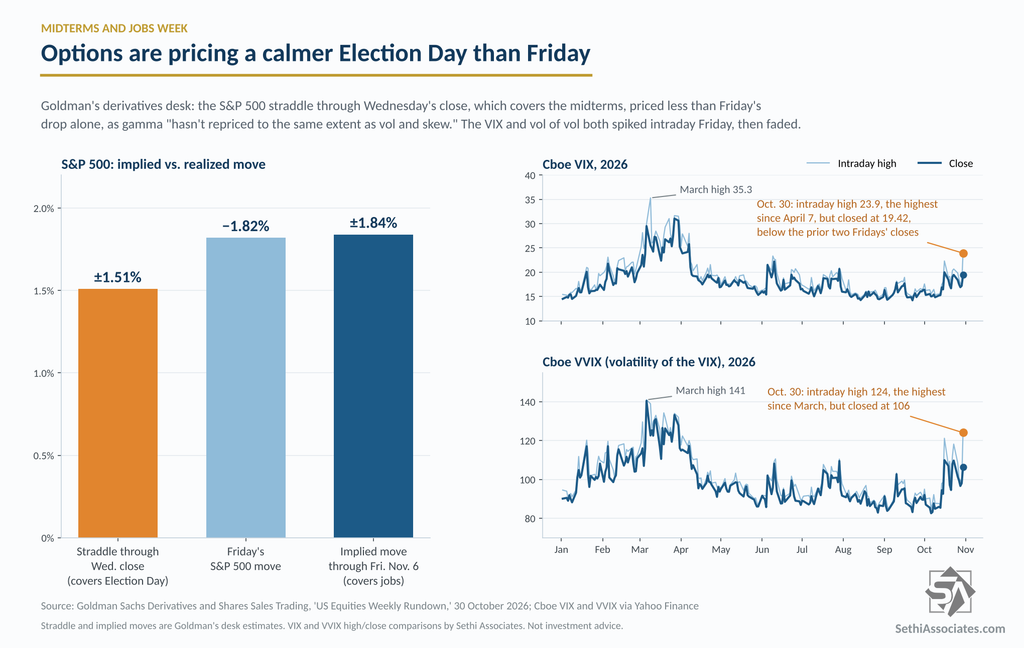
Goldman’s derivatives desk says that “for the first time, we are now seeing flows catch up to the bear thesis,” with Friday’s activity concentrated in buying downside on the index and semis. Vol of vol (VVIX) hit 124 intraday Friday, its highest since March.
But they note markets are strangely sanguine ahead of the election. Gamma “hasn’t repriced to the same extent as vol and skew”: the straddle through Wednesday’s close, covering the midterms, they find is just priced at a 1.51% move, less than Friday’s 1.82% drop alone. The S&P 500’s implied move through Friday is 1.84%. The VIX itself closed Friday at 19.42, after hitting 23.93 intraday, below its close the prior two Fridays.
Levels Goldman is watching are the S&P 500’s 100-DMA (7,614) and the CTA medium-term threshold (7,544–7,554). The index closed below its 100-DMA Friday for the first time since April 8th, trading as low as 7,527.56 before closing at 7,580.07, back above the threshold.
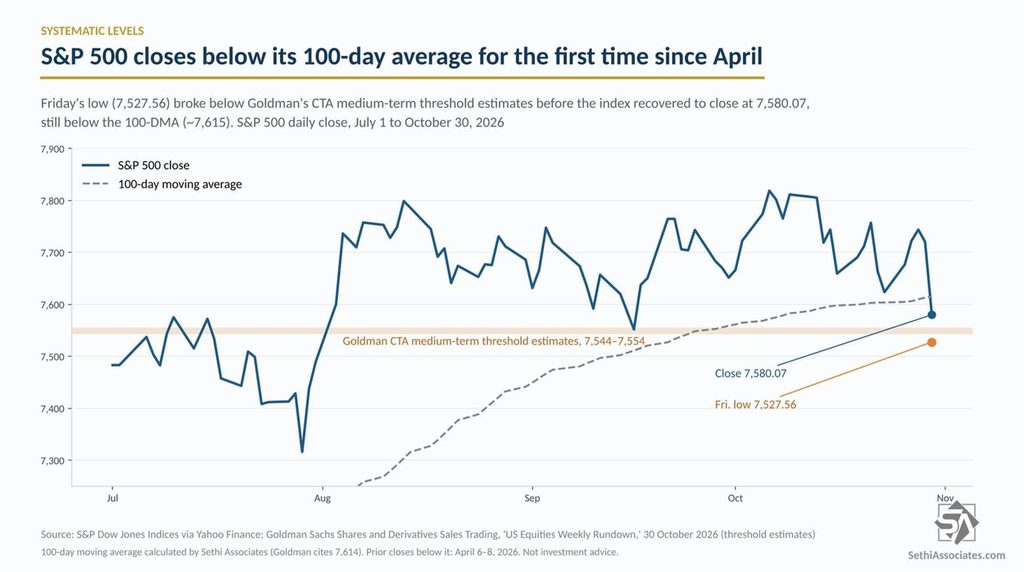
BofA similarly sees CTA selling thresholds right around current levels. The sell trigger for the S&P 500 now sits around −0.1% (from ~−0.5% the prior week), measured on December S&P 500 futures: 7,606 vs. Friday’s 7,617, and BofA says a further ~2% decline would fully unwind CTAs’ remaining longs. No sell triggers were listed for the Nasdaq-100 (from ~−0.2%), where 11 of BofA’s 12 CTA models have now stopped out, or the Russell 2000 (from ~−3.0%), but they see a buy trigger for the latter at +1.8% (from +2.4%).
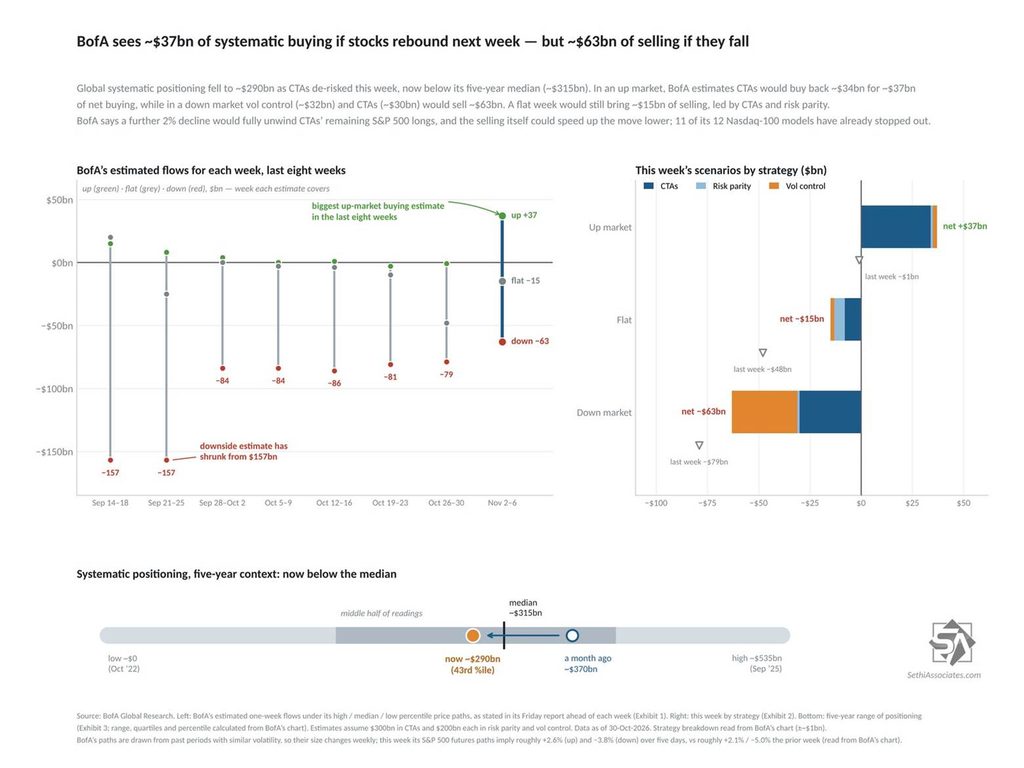
For the upcoming week in global CTA equity flows they see:
- −$15B of selling in a flat market (from −$48B the prior week), with selling from CTAs (~$8B), risk parity (~$5B) and vol control (~$2B)
- +$37B of buying in an “up” market (BofA’s high-percentile path, which scales with volatility and this week implies roughly +2.6% for S&P 500 futures over five days; from −$1B of selling), almost all from CTAs reloading (~$34B), the biggest up-market buying estimate in the last eight weeks
- −$63B of selling in a “down” market (BofA’s low-percentile path, roughly −3.8% for S&P futures this week vs about −5% the prior two weeks; from −$79B), split between vol control (~$32B) and CTAs (~$30B)
Global systematic positioning fell to ~$290B as CTAs de-risked this week, below its five-year median (~$315B) and down from ~$370B a month ago.
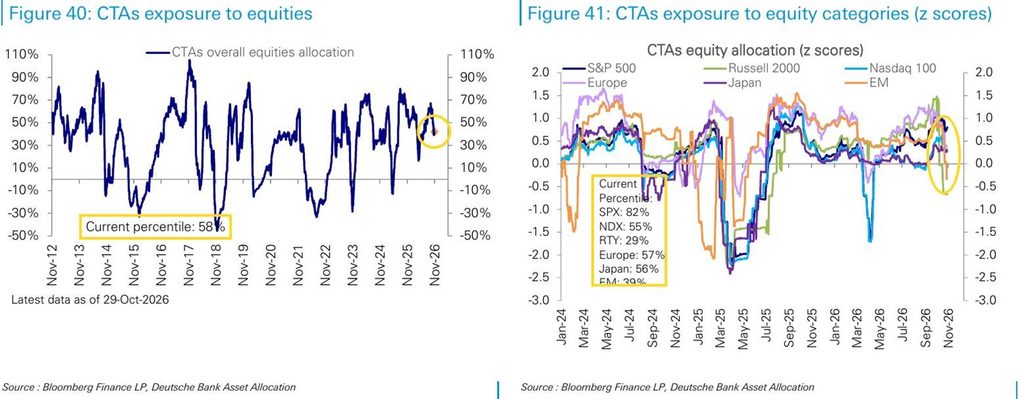
At DB, global CTA equity positioning slipped to the 58th percentile (from the 62nd), with the S&P 500 at the 82nd (from 87th), the Nasdaq-100 at the 55th (from 66th) and the Russell 2000 at the 29th (from 30th).
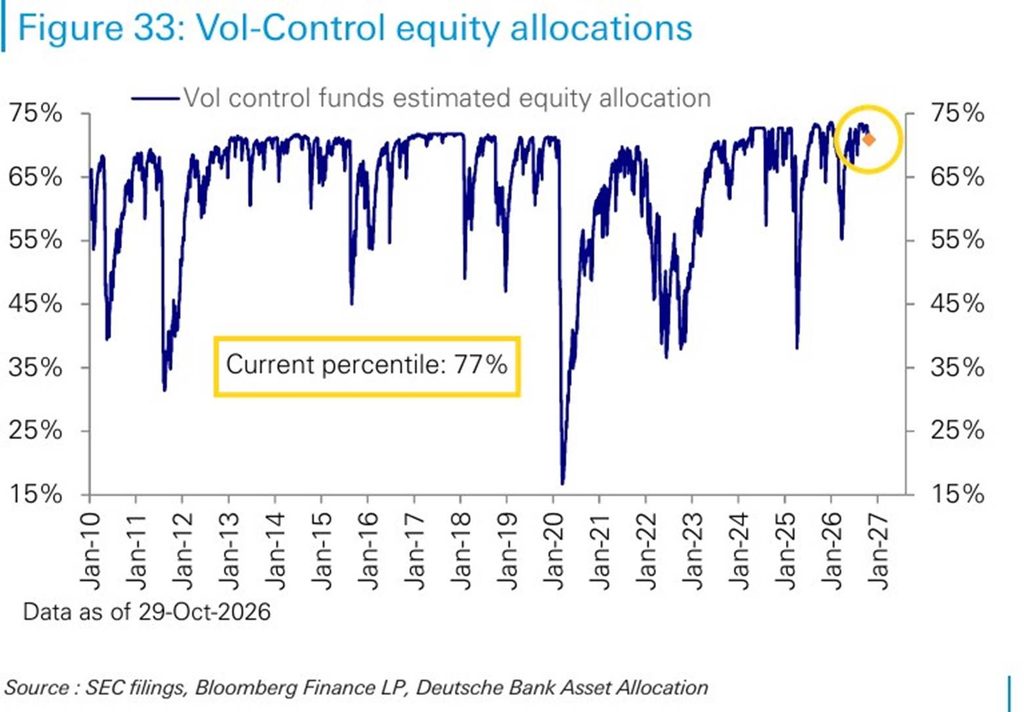
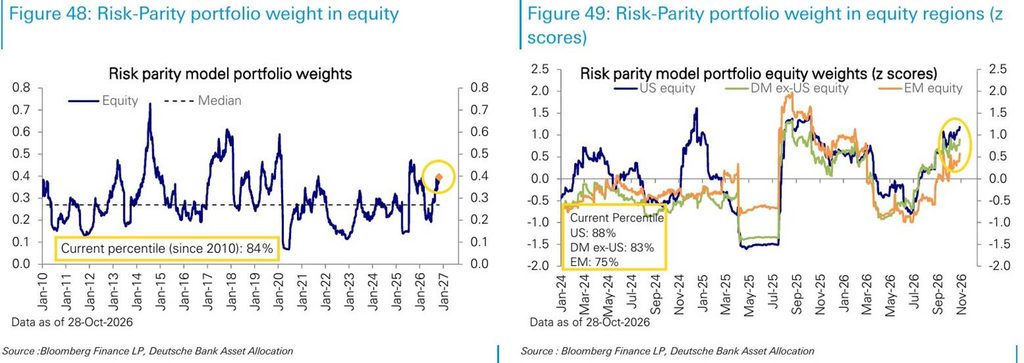
Vol control* eased to the 77th percentile (from the 81st), and risk parity** equity allocations were little changed at the 84th (from 85th).
*Vol control strategies enter and exit based on changes in volatility over past windows (mostly 1-month and 3-month).
**Risk parity funds balance risk across asset classes based on relative volatility, often using leverage, to reach a target portfolio risk level.
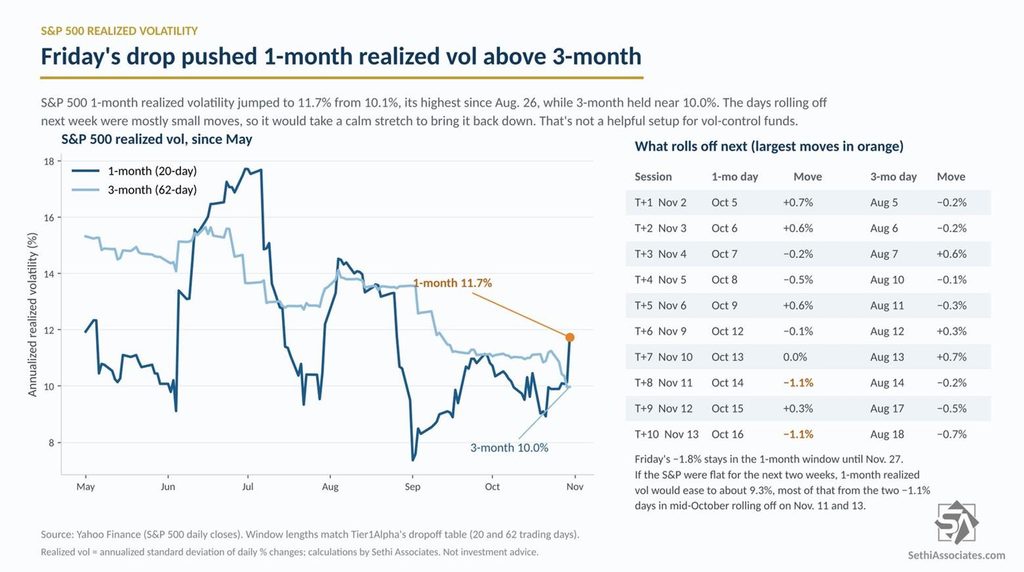
Vol control though has a tough setup for next week. Tier1Alpha’s data show 1-month S&P 500 realized volatility edging above 3-month on Thursday for the first time since late September, and Friday’s 1.8% drop widened the gap. Per Claude, using the same windows, 1-month realized vol jumped to 11.7% from 10.1%, its highest since August 26th, while 3-month held near 10.0%.
That makes the 1-month volatility lookback the main driver of flows according to Tier1Alpha and the days rolling out of the 1-month window this week are mostly small moves. Even if the S&P were flat for the next two weeks, 1-month realized vol would only ease to about 9.3%, and most of that would come from two −1.1% days in mid-October rolling off on November 11th and 13th, no help this week.
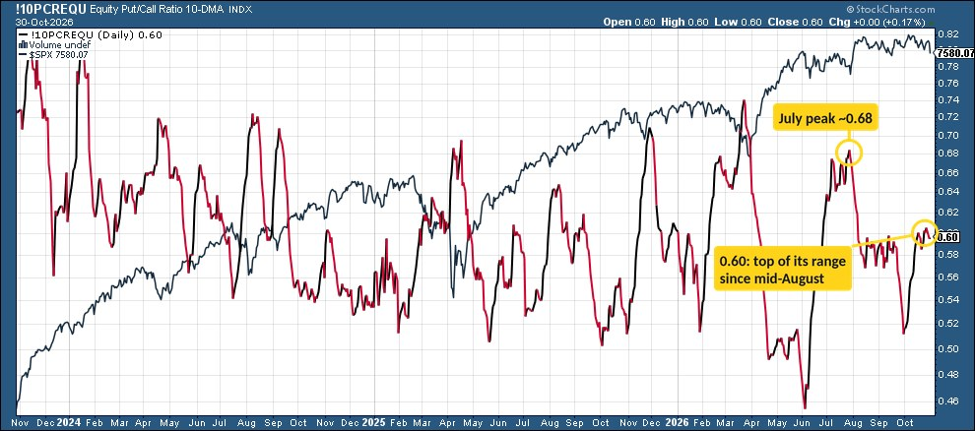
The CBOE equity put/call ratio jumped to 0.66 Friday (from 0.58), the highest in over a week, but its 10-DMA (0.60) is only near the top of its range since mid-August and below July’s ~0.68 peak, so traders aren’t hedging aggressively. To the extent this is moving higher it acts as headwind as dealers have to sell to hedge the puts they are selling.
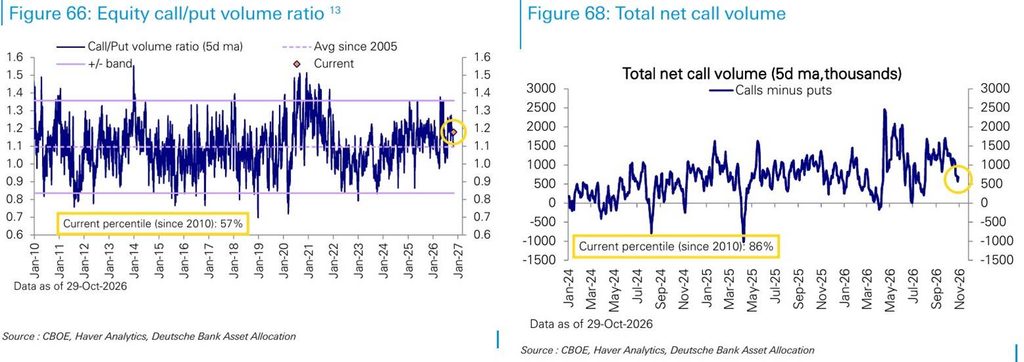
Similarly, DB’s call/put 5-DMA held at the 57th percentile, though net call volume (calls minus puts) is at the 86th, so call buying remains heavy.
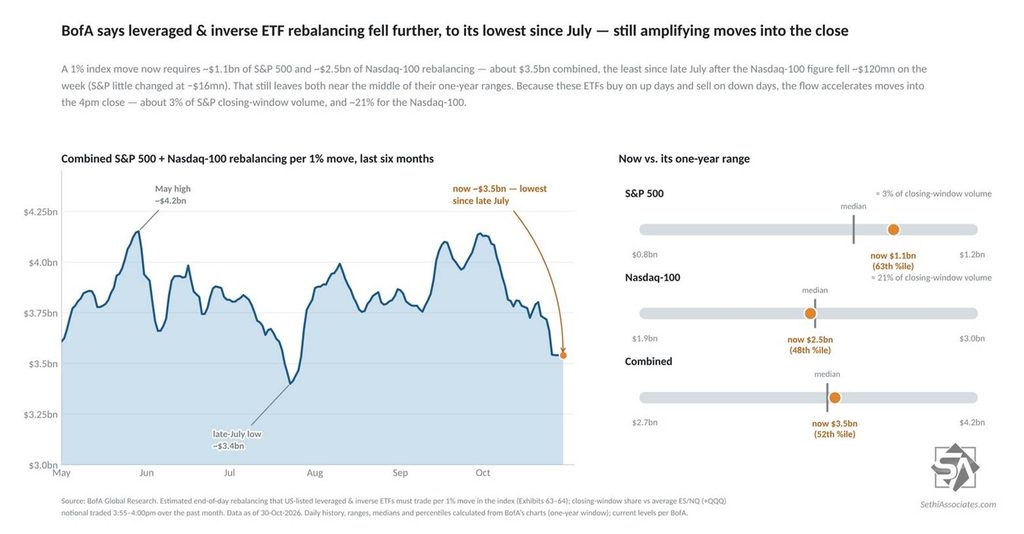
Turning to leveraged ETFs which act as “negative gamma” per Charlie McElligott (funds have to buy or sell in the direction of market moves each day) BofA saw another week of sharply reduced AUM for the Nasdaq-100 group pulling down forced selling/buying from a 1% index move to ~$1.1B for the S&P 500 and ~$2.5B for the Nasdaq-100. That’s roughly $3.5B combined, the least since late July, after the Nasdaq-100 figure fell ~$120M on the week (the S&P was little changed at −$16M). That still leaves both near the middle of their one-year ranges.
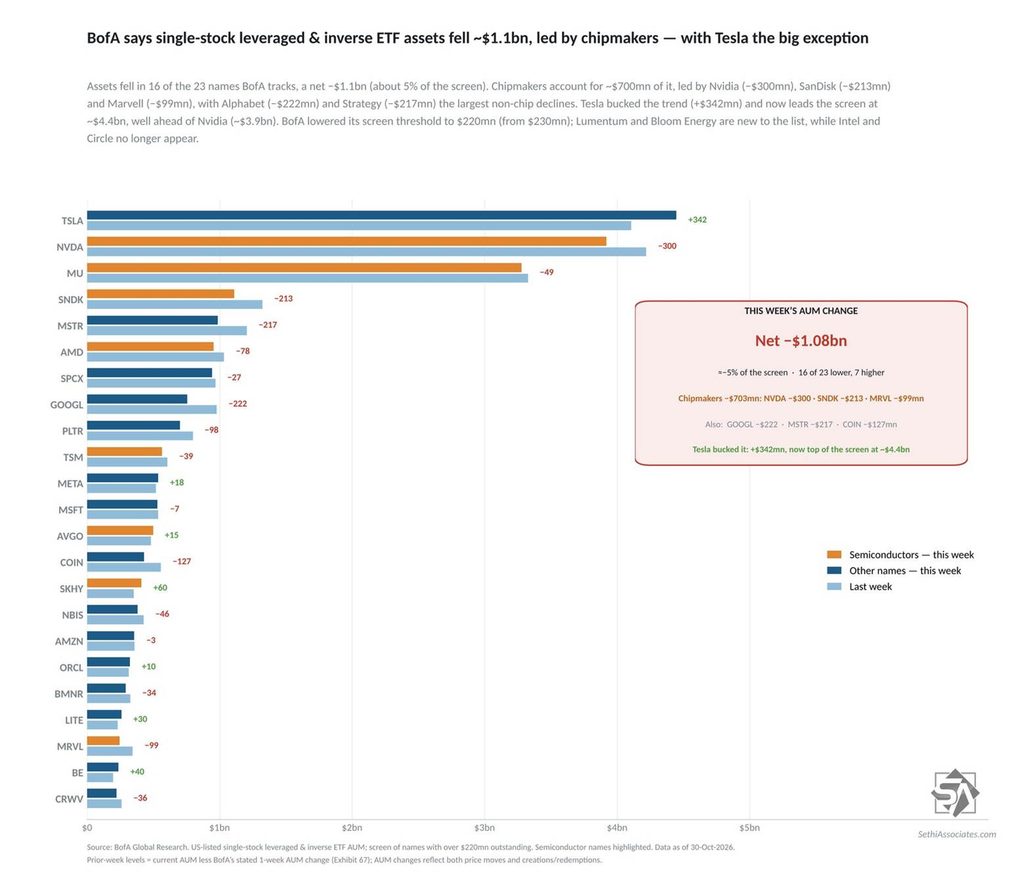
Similarly, BofA says single-stock leveraged and inverse ETF assets fell a net ~$1.1B last week (reflecting both price moves and flows), with 16 of the 23 names it tracks lower. Chipmakers accounted for ~$700M of the decline, led by Nvidia (NVDA, −$300M), SanDisk (SNDK, −$213M) and Marvell (MRVL, −$99M). Alphabet (GOOGL, −$222M) and Strategy (MSTR, −$217M) were the largest non-chip declines. Tesla (TSLA) bucked the trend (+$342M) and now leads the screen at ~$4.4B, well ahead of Nvidia (~$3.9B).
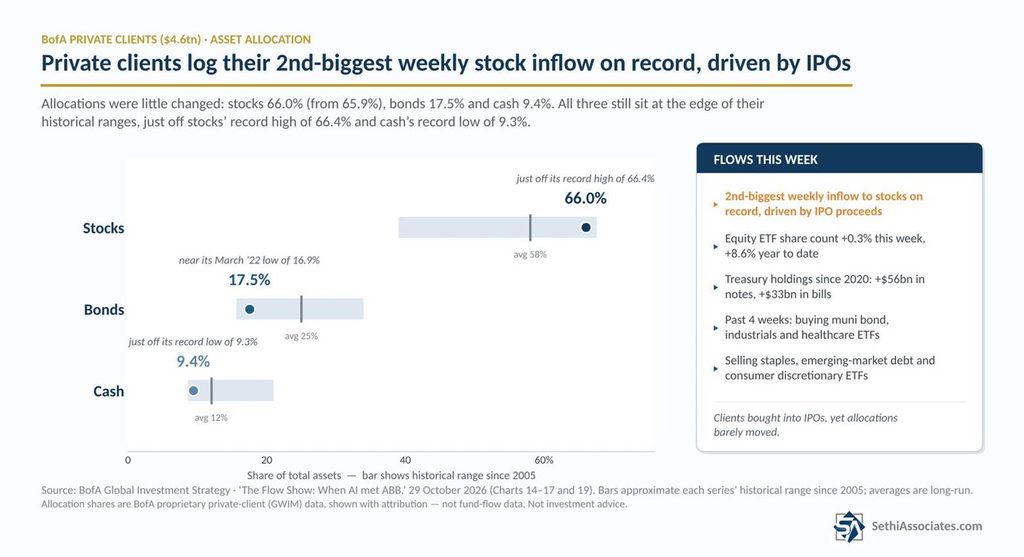
Turning to retail, BofA says private clients ($4.6 trillion AUM) were buyers again, logging their 2nd-biggest weekly equity inflow on record. Curiously, they said it was “driven by IPO proceeds,” and I’m not sure what that refers to, as there haven’t been any major IPOs the last couple of weeks.
With the equity drawdown though allocations barely moved: stocks 66.0% (from 65.9%), bonds 17.5% and cash 9.4%. That’s just off stocks’ record high of 66.4% and cash’s record low of 9.3%.
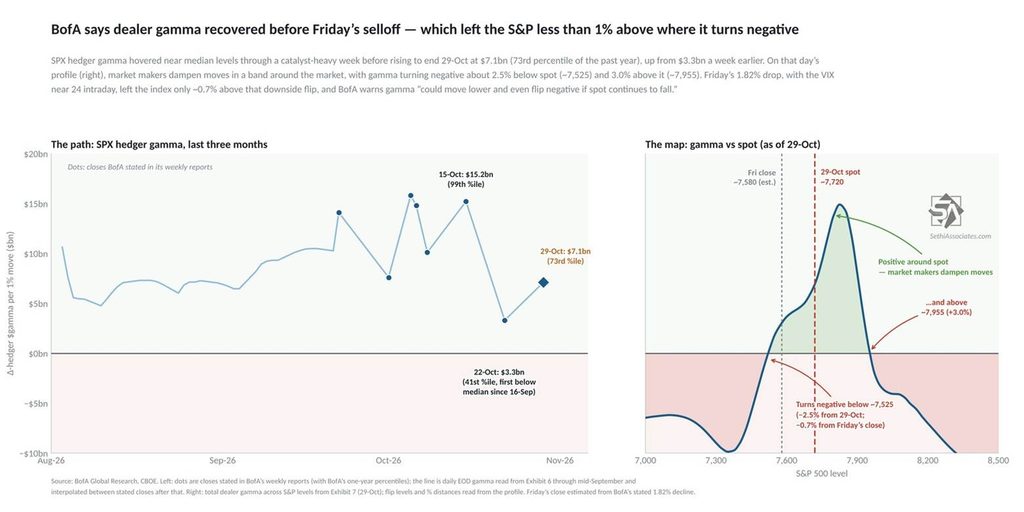
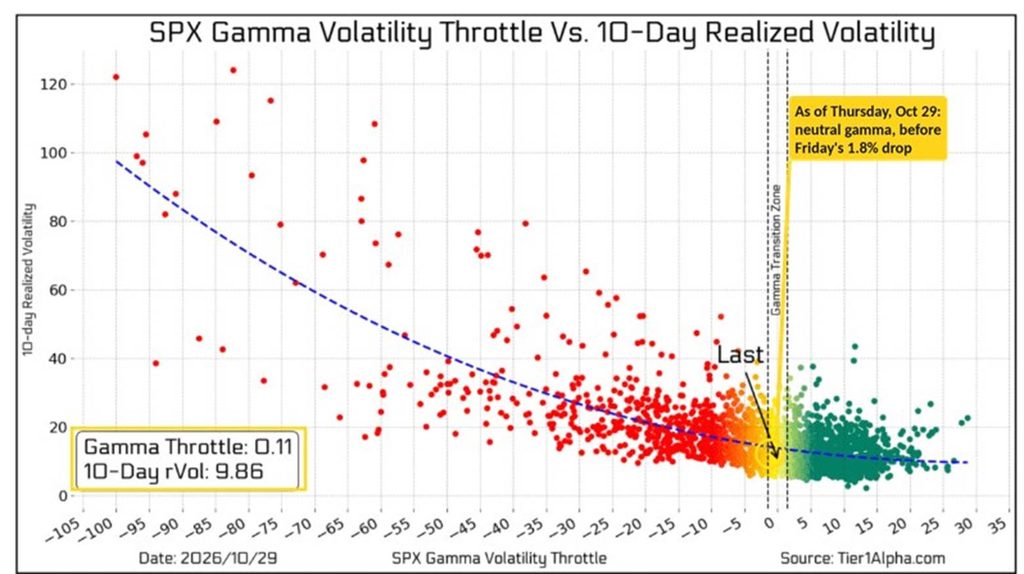
On gamma*, BofA says SPX hedger gamma hovered near median levels through a catalyst-heavy week before rising to end Thursday at a healthy $7.1B (73rd percentile of the past year), up from $3.3B a week earlier. But Friday’s 1.82% drop according to their model left the index with very thin positive gamma, less than 1% from flipping negative. Friday’s intraday low of 7,527.56 came within a few points of it. In that regard BofA warned gamma “could move lower and even flip negative if spot continues to fall.”
So there looks to be very little protection from market moves and any notable declines will likely be accelerated by market makers. A bounce though would bring gamma back to more positive levels.
*Gamma plays an important, if nebulous, role in market volatility. Positive gamma means options market makers buy and sell against price moves, which dampens volatility. Negative gamma means the reverse: market makers trade with the move, accelerating rallies and selloffs and adding to volatility.
Tier1Alpha (as of Thursday) already saw gamma as neutral, so they will likely find it have moved negative when they update Monday morning.
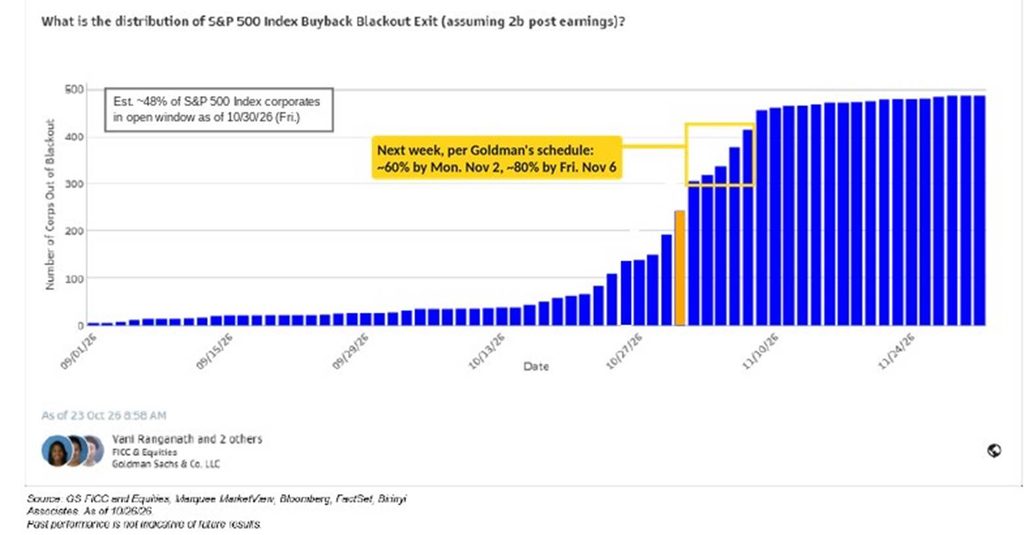
Turning to corporate buybacks (an important source of underlying demand), the blackout period is ending. Goldman’s buyback desk estimated ~27% of the S&P 500 was in an open buyback window as of October 26th, “almost doubling to ~50% by the end of the week.” Its schedule has that rising to about 60% by Monday and about 80% by Friday, and the desk expects “an uptick in volumes into November, which seasonally ranks as our second most active execution month on the desk.” Clients are also “slowly moving back into opportunistic open market flow,” with discretionary orders at 16% versus 84% in 10b5-1 plans (from 15% and 85% the prior week).
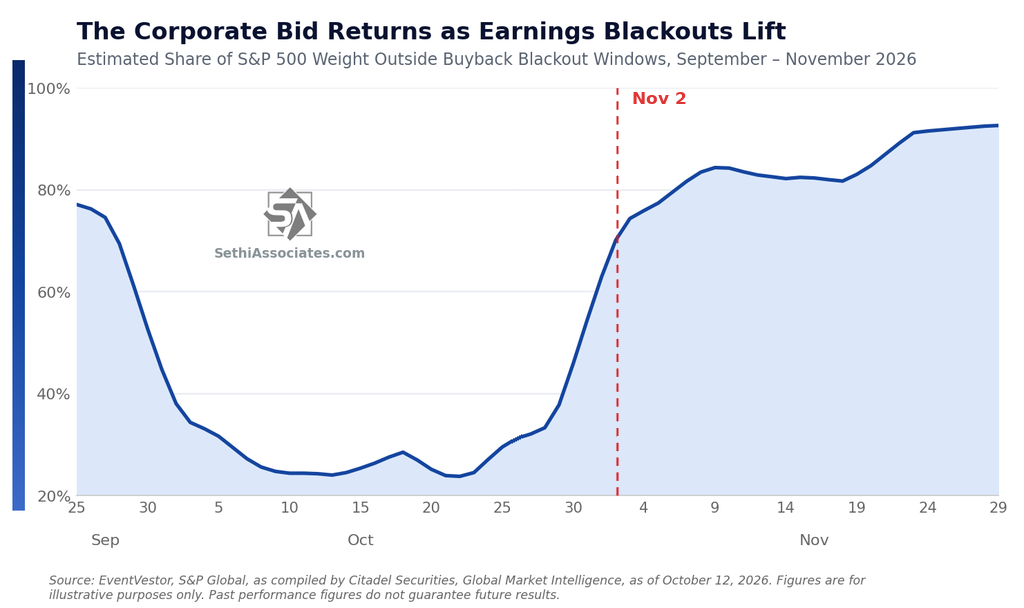
Citadel models buybacks a little further along with 70% of discretionary buybacks by index weight for S&P 500 companies active as of Monday (discretionary buybacks represent ~30% of all buybacks), up from around 30% last Monday, rising to around 80% by Friday and about 85% early the following week.
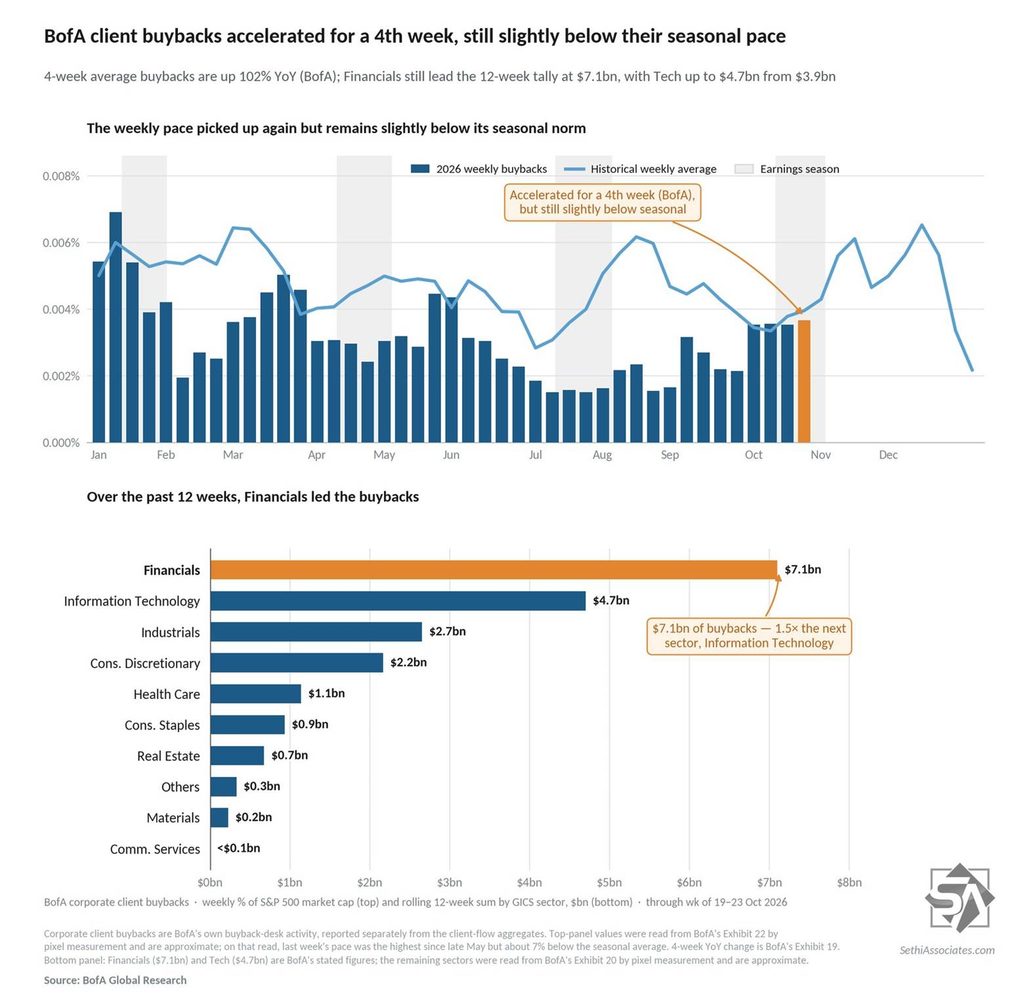
BofA meanwhile saw corporate client buybacks accelerate for a 4th week in the week ending October 23rd, though they remain slightly below their seasonal average. On a 4-week average basis they jumped to +102% vs the year earlier, from +44% the prior week. Financials still lead the past 12 weeks at $7.1B, about 1.5x the next sector, Tech ($4.7B, up from $3.9B).
In late September, BofA said annualized cumulative buybacks YTD were tracking ~25% below 2025 levels and more than 40% below 2024 levels, though above 2010-23 annual levels. They note that “rolling 52-wk buybacks as a % of S&P 500 market cap are currently the lowest since Aug. 2021.”
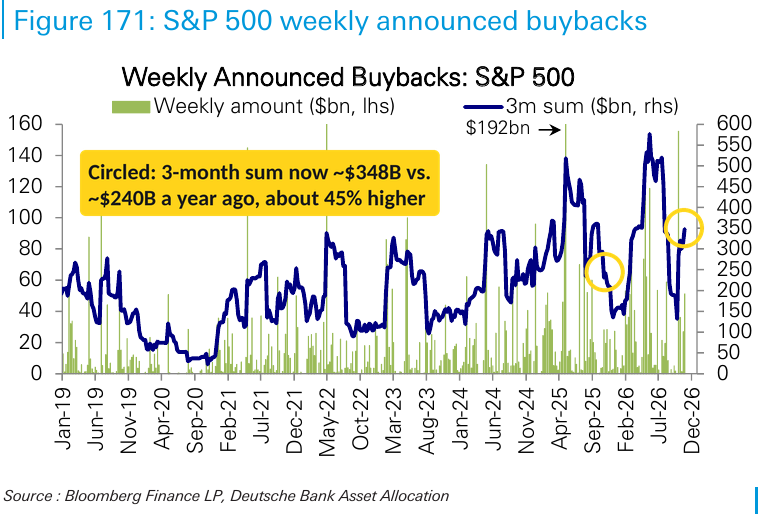
Despite the reduced buybacks from the hyperscalers, DB’s tally of announced S&P 500 buybacks over the past three months has rebounded to about $350B, roughly 45% above the ~$240B of a year ago, after dipping to about $130B in mid-September. A single ~$155B week in late September accounts for much of the rebound.
Sentiment Bounces Off Extreme Fear, But Isn’t Washed Out
Sentiment (which I treat separately from positioning) is one of those things that is generally positive for equities when it’s above average but not extreme (“it takes bulls to have a bull market”, etc.), although it can stay at extreme levels for longer than people think, so really it’s most helpful when it’s at extreme lows (“washed out”).
Most sentiment indicators bounced last week ahead of Friday’s selloff, and none of them are at the kind of extreme lows that typically mark a bottom.
American Association of Individual Investors (AAII), a retail focused weekly investor survey, moved a little less bearish although note the survey closed Wednesday night ahead of the end of week selloff:
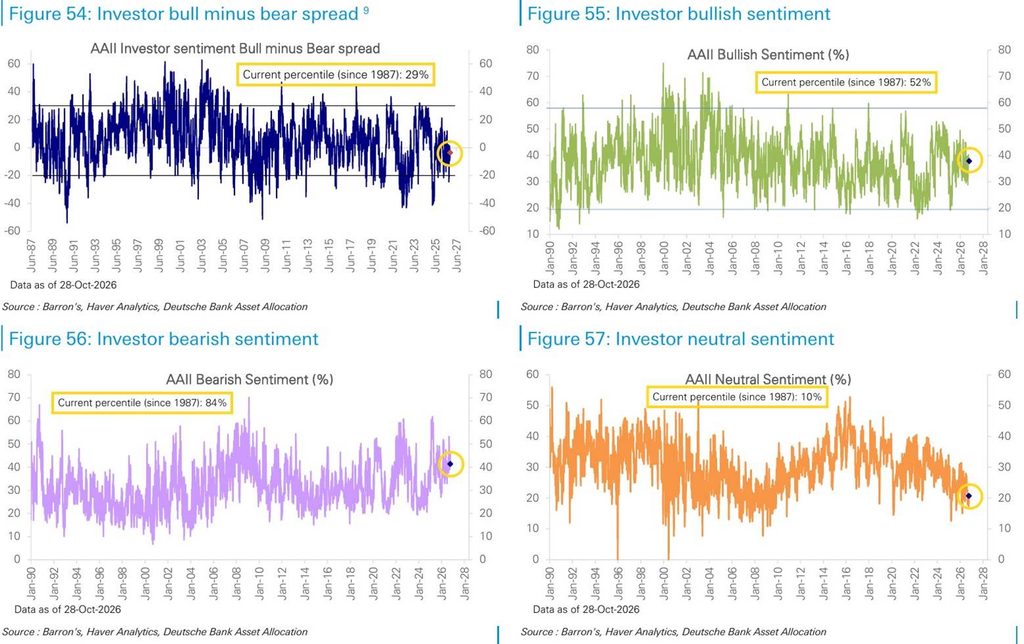
- AAII Bulls (those who see higher stock prices in 6 mths, blue line) edged up to 37.8% from 36.9% the prior week, moving back above the long-term historic average of 37.5% after a week below.
- Bulls though remained below the level of the Bears (who see lower stock prices in 6 mths, red line), even as the Bears fell to 41.4%, the least in three weeks, from 45.8% the prior week (and further below the 53.3% six weeks ago, the highest since May 2025). That leaves Bulls above Bears just twice in the last 15 weeks. Bears also remain above the long-term average of 31.0% for a 37th straight week (and they’ve only been below it 9 weeks since Dec 12, 2024).
- The Neutral camp (yellow line) rose to 20.7%, the most in three weeks, from 17.3% (which was the least since early April). It remains under the long-run average of 31.5% and has been over that only twice since July 2024.

DB notes the bull-bear spread rose to the 29th percentile (since 1987) from the 21st, with bearish sentiment at the 84th percentile (from the 91st), bullish at the 52nd (from the 48th) and neutral at just the 10th (from the 4th).
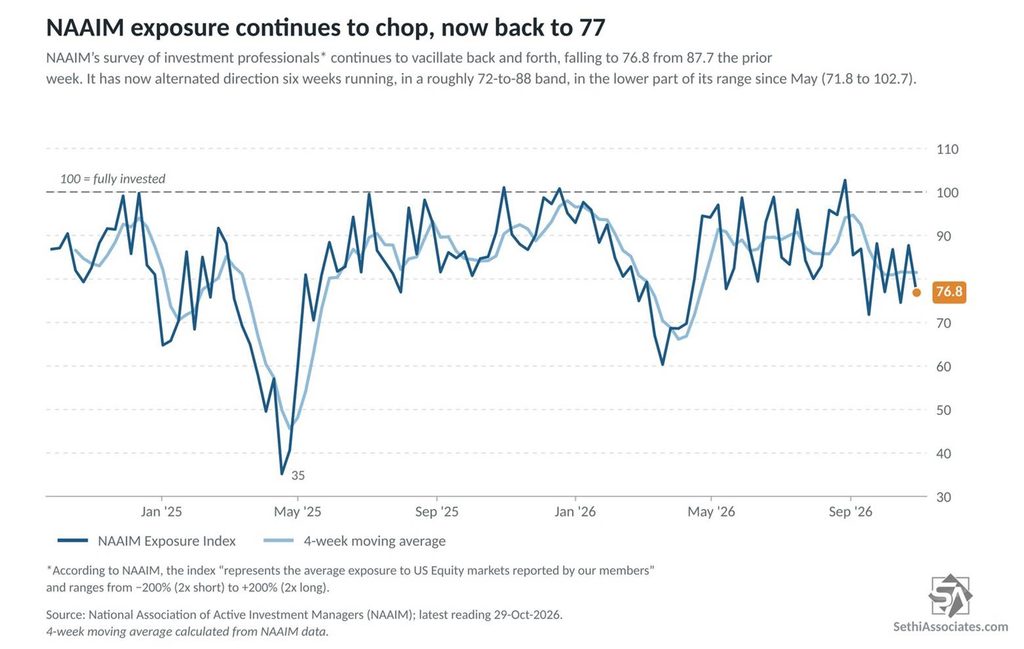
NAAIM’s survey of investment professionals* continues to vacillate back and forth, falling to 76.8 from 87.7 the prior week. It also closed Wednesday night. It has now alternated direction six weeks running, in a roughly 72-to-88 band, in the lower part of its range since May (71.8 to 102.7).
*The index according to NAAIM “represents the average exposure to US Equity markets reported by our members” and ranges from −200% (2x short) to +200% (2x long).
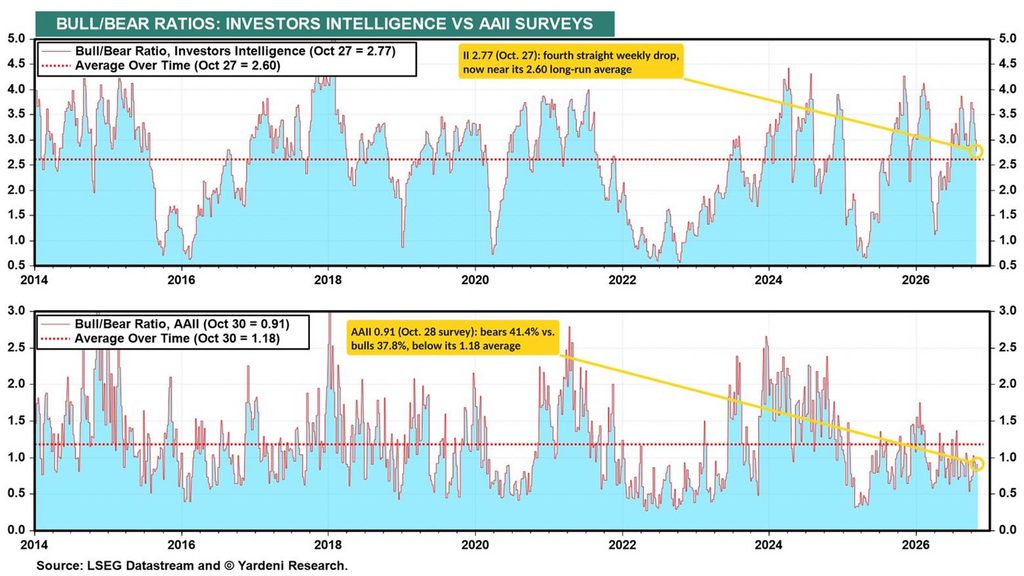
The Investors Intelligence (independent investment-newsletter writers) bull/bear ratio fell for a fourth week to 2.77 from 2.99, though it’s still above its 2.60 long-run average. Combined with AAII’s 0.91 bull/bear ratio (below its 1.18 average), Ed Yardeni says “odds are that Friday’s drop in the S&P 500 weighed on the bull/bear ratios (BBR) we track. We hope so. From a contrarian perspective, bearish BBR readings are bullish.”
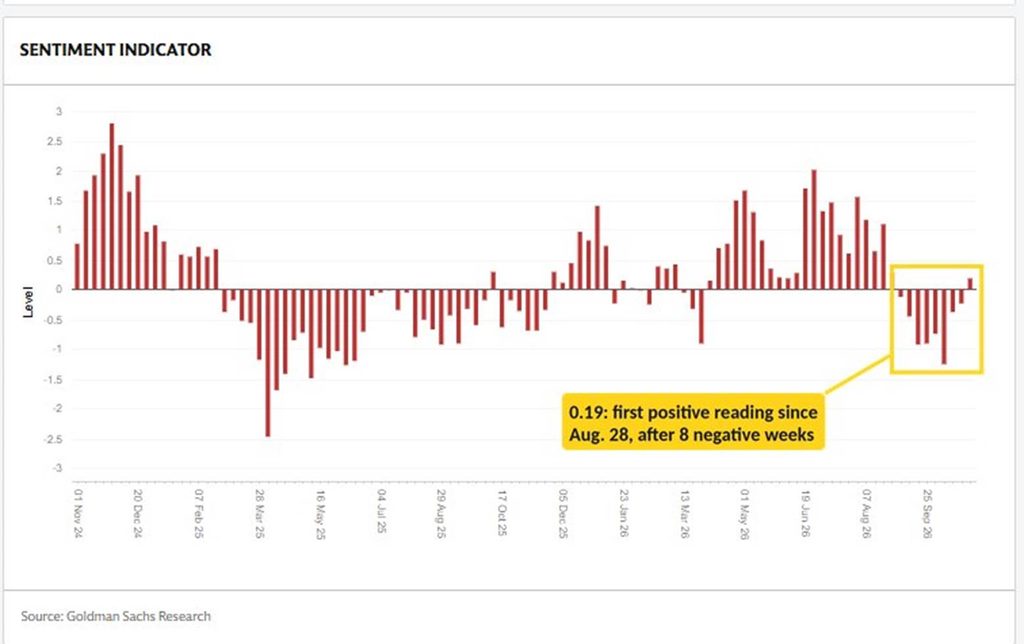
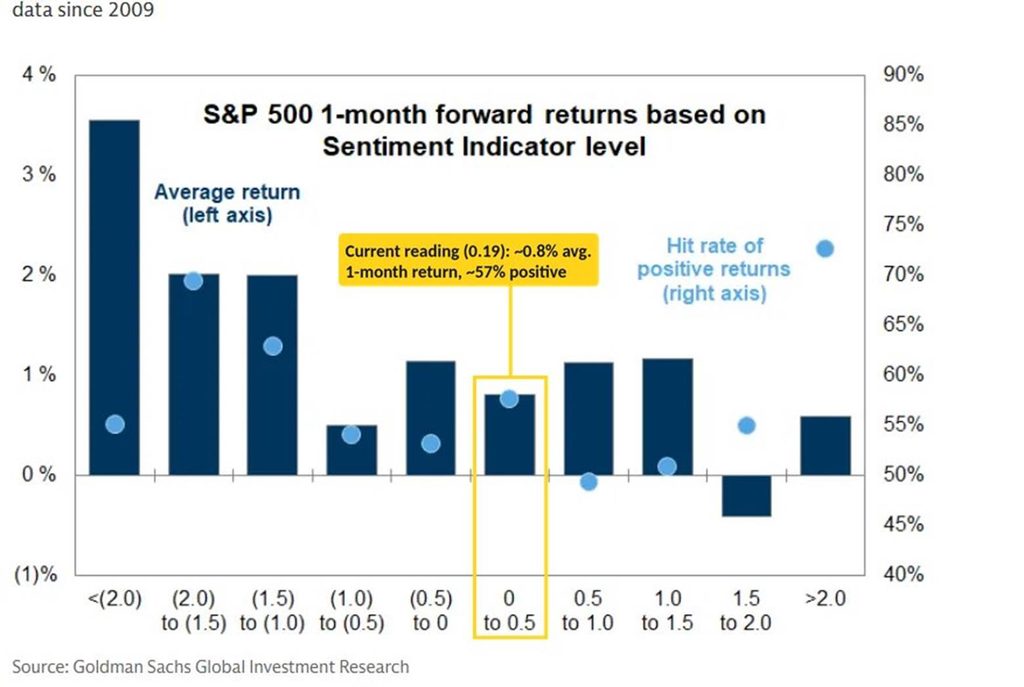
And Goldman’s US Equity Sentiment Indicator* turned positive at 0.19 (from −0.23 the prior week), its first positive reading since August 28th, ending a run of eight negative weeks. The current reading is associated with a 1-month average return of around 0.8% since 2009, with a positive rate around 57%.
*The indicator combines “six weekly and three monthly indicators that span [across the more than 80% of the US equity market that is owned by institutional, retail and foreign investors]. Readings of +1.0 or higher have historically signaled stretched equity positioning. Readings of -1.0 or lower have signaled very light positioning and have historically been a statistically significant signal for subsequent S&P 500 performance”.
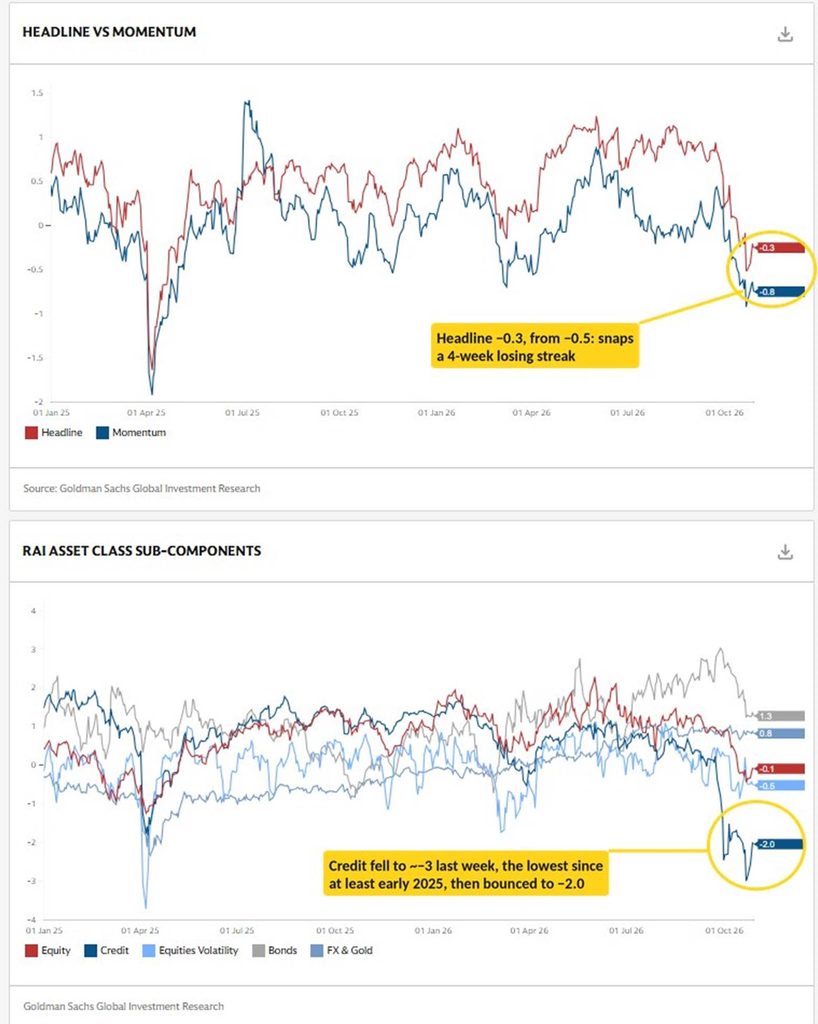
While Goldman’s Risk Appetite Indicator* rebounded to −0.3 from −0.5 the prior week, snapping a four-week losing streak, and the momentum index edged up to −0.8 from −0.9.
Under the hood, credit remains the weak spot. Its sub-component bounced to −2.0, but the prior week it fell to about −3, well below its April 2025 low (around −1.8) and the lowest since at least the start of 2025 (where the chart begins). Equities recovered to around flat (−0.1). Goldman’s asset allocation team adds that cross-asset sentiment and positioning “are back to more neutral levels,” and its equity tail-risk model “still points to a less negative asymmetry… but with worsening signal from the business cycle and sentiment.”
*”Goldman Sachs Risk Appetite Indicator (RAI) aims to track the level of global market risk appetite and risk aversion based on various market variables. A sharp rise in the index can send a warning signal that investors have more risk appetite and are potentially exposed to a correction if consensus views are tested. Similarly, a sharp decline indicates a reduction in risk appetite, and at extreme levels it can indicate that markets may have overshot. RAI signals are most powerful when the level of risk appetite is very low below -1.5, with levels closer to -2.0 giving the clearest signal over longer time horizons, as at such levels the asymmetry of subsequent medium term equity return becomes very positively skewed. RAI momentum is designed to track short term shifts of market risk appetite, and subcomponents of the RAI.”
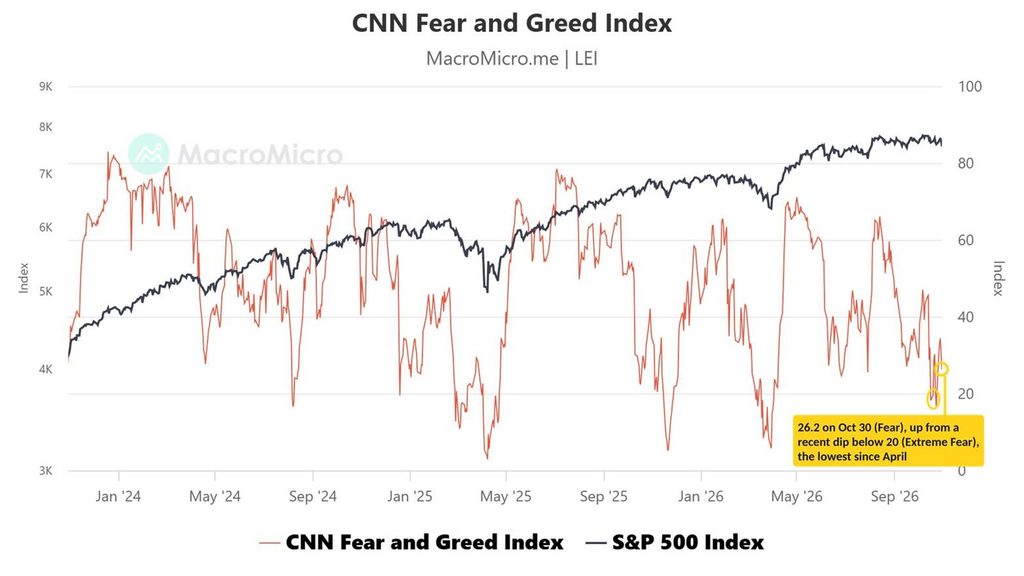
The CNN Fear & Greed Index ended the week at 26.2 (Fear), up from 16.7 (Extreme Fear) a week earlier, which was the least since April. It had climbed to 34 on Thursday before Friday’s selloff.
Five of the seven indicators are now in Fear, with two still in Extreme Fear.
Extreme Greed = None
Greed = None
Neutral = None
Fear = stock price strength (net new 52-week highs) (from Extreme Fear); stock price breadth (McClellan Volume Summation Index) (from Extreme Fear); put/call options (5-day put/call ratio) (from Extreme Fear); market volatility (VIX & its 50-DMA) (from Extreme Fear); junk bond demand (vs investment grade)
Extreme Fear = market momentum (SPX vs 125-DMA); safe haven demand (20-day difference in stock/bond returns)
And I noted in previous weeks if you have any questions on the indicator, TheStreet Pro’s own Jason Meshnick is your guy, as he helped create it.
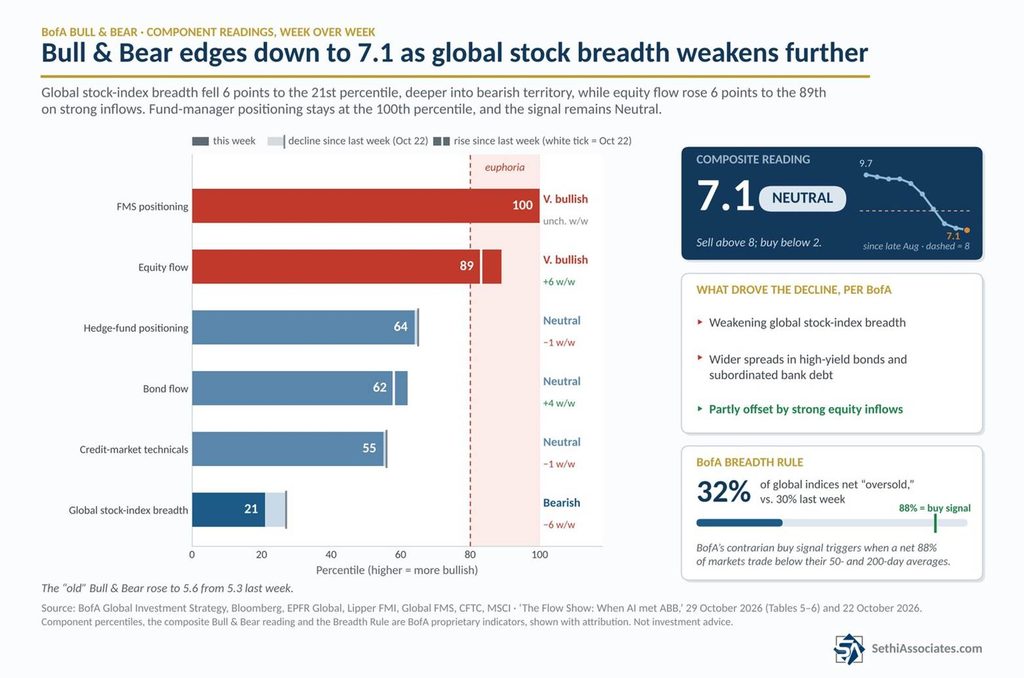
BofA’s Hartnett (Flow Show) says the Bull & Bear Indicator is “down to 7.1 from 7.2,” its third straight weekly decline (from 8.1 three weeks ago, when it ended the sell signal that began May 26th), driven by weakening global stock breadth and wider spreads in high-yield and subordinated bank debt, offset by strong equity inflows.
Under the hood, global stock breadth fell deeper into bearish territory (21st percentile, from 27th), while equity flow rose to the 89th. Fund-manager positioning is still at the 100th percentile, and the signal remains Neutral.
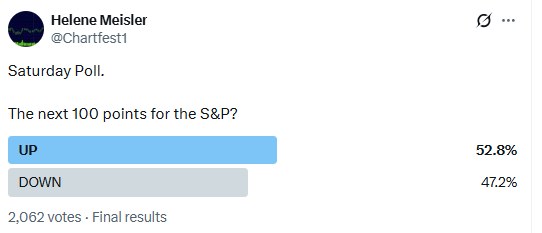
Helene Meisler’s Saturday poll on the direction for the next 100 points for the S&P 500 was again mildly bullish, at 52.8% up versus 47.2% down (2,062 votes), up from 50.7% last week and the fourth bullish result in five weeks.
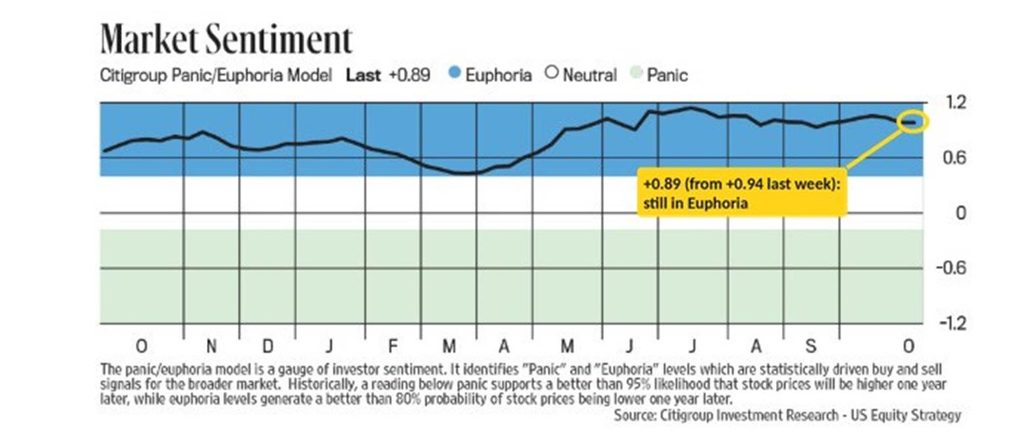
And Citi’s Panic/Euphoria Model which Helene has each week in her Chart Fest eased to +0.89 from +0.94 but remains in Euphoria, a level Citi says has historically come with “a better than 80% probability of stock prices being lower one year later,” although as I have indicated in the past the recent track record has been weak.
Seasonality Turns Strongly Supportive
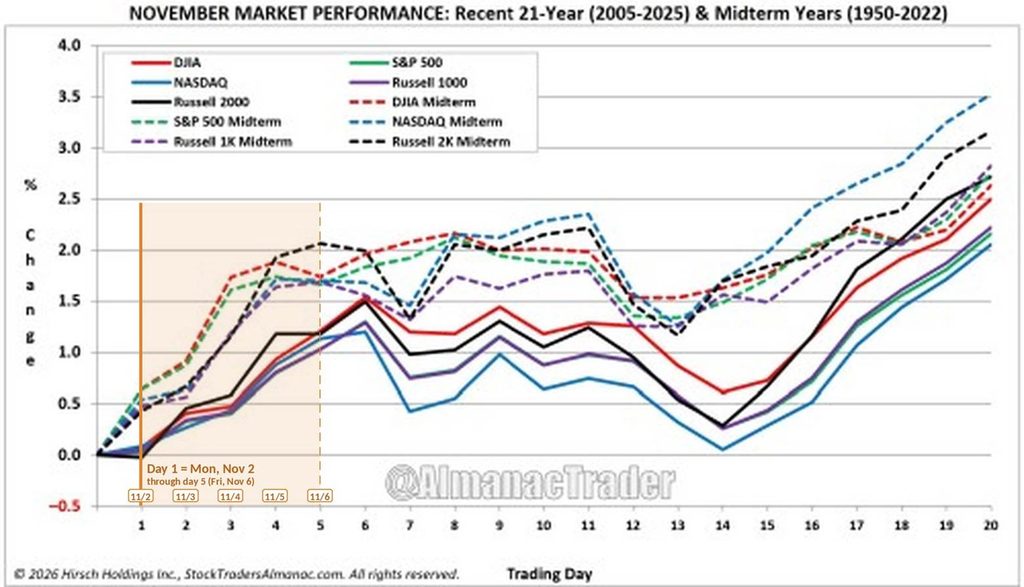
Looking at the seasonality breakdown from Jeff Hirsch, editor of the Stock Trader’s Almanac & Almanac Investor Newsletter, November opens with one of its strongest stretches. Hirsch counts eleven bullish days for the S&P 500 in November, including six in a row starting on the first trading day.
Monday is trading day 1. Over the past 21 years, the major indices have gained about 1–1.2% by Friday (day 5), roughly half of their full-month gain. Monday has been about flat on average, and the gains have built from Tuesday through Friday. The Russell 2000 has jumped about 0.6% on Thursday alone. The run has topped out the following Monday (day 6, Nov. 9), with the indices up about 1.2–1.5% for the month before a mid-month pullback.
And midterm years have started faster. The midterm lines are up about 0.4–0.65% after day 1. By Friday, the DJIA, S&P, Nasdaq and Russell 1000 are up about 1.7% and the Russell 2000 about 2.1%. That’s roughly half to two-thirds of their full-month gain in the first five sessions. The DJIA and S&P have done nearly all of that climbing by Wednesday, while the Nasdaq and Russells catch up on Thursday, and the run has lasted longer, to about 2% by the eighth trading day (Nov. 11). Election Day falls on Tuesday (day 2) this year. Historically, though, it has landed anywhere from the 2nd to the 6th trading day of November, so the midterm averages don’t map neatly onto a post-election reaction.
From there, Hirsch’s “strong start, mid-month dip, strong finish” pattern takes over (November Strong Start, Mid-Month Dip, Strong Finish). The indices have pulled back into trading days 13–14 (Nov. 18–19), when the 21-year averages give back most of their early gains. They then rally into month-end, finishing up about 2–2.7% across all years and 2.6–3.5% in midterm years, led by the Nasdaq.
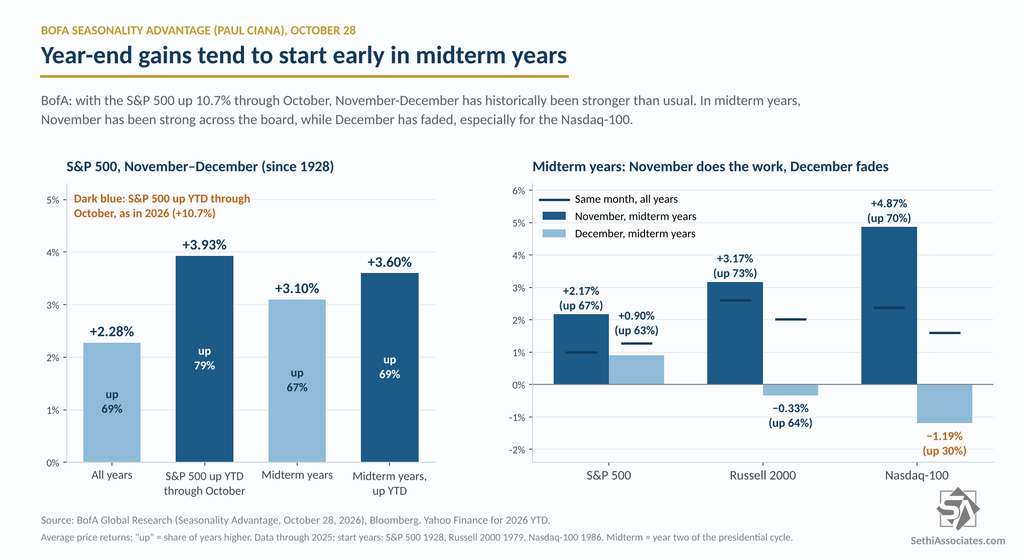
BofA’s Paul Ciana (Seasonality Advantage) agrees that “year-end gains tend to start early in year two of the US Presidential Cycle“:
When the S&P 500 is up year-to-date through October (it’s up 10.7% this year), November-December has risen 79% of the time since 1928, by +3.93% on average, versus 69% and +2.28% for all years. In midterm years with a positive YTD, it’s 69% and +3.6%.
In midterm years, Halloween to Christmas Eve has been up 75% of the time (18 of 24) by +2.27%.
November has averaged +2.17% for the S&P 500 in midterm years (up 67%), +3.17% for the Russell 2000 (up 73%), and +4.87% for the Nasdaq-100 (up 70%).
In midterm-year Novembers, Materials (up 89% of the time, +3.98%) and Real Estate (up 83%, +4.08%) join the usual leaders, Discretionary, Industrials and Tech (though BofA’s sector data only start in 1990, or 2001 for Real Estate).
Elsewhere in midterm-year Novembers, oil has been weak (WTI down 80% of the time, −8.0% on average), and the 2s10s curve has flattened in 11 of 12 (−15bp).
The caveats: December is less generous in midterm years (the Nasdaq-100 has fallen 70% of the time, −1.19%), and BofA flags November-December 2018, year two of Trump’s first term, as “a risk” (the S&P fell 9.2% that December).
Wrap-Up – One Down, Two to Go?
Last week’s Week Ahead was titled “Can Big Tech Earnings Save the Day?”. The answer, at least as far as Tech, and therefore the overall indices, was concerned was an emphatic No. Alphabet had its worst day on record Thursday and Intel its worst on Friday leading the entire Tech sector to its second-worst day since April 2025. For the month it was the worst for the Nasdaq since March 2025 and the Philadelphia Semiconductor ETF (SOX) ended the month down 15.4%.
But it was a much better week for the average stock. The Russell 2000 rose 1.3% and the equal-weighted S&P 500 0.8%. Goldman notes 70% of S&P 500 stocks are up since earnings season started, with the S&P 500 ex-AI up 5% even as the index is down 3%. So there’s plenty that’s working, which is where money has rightly been rotating.
In that regard I mentioned on October 13th (Bank Earnings Get a Cool Reception as Chip Jitters Linger) that I had sold out of Micron Technology (MU) when it broke support and would continue to do that with other stocks that did the same, perhaps putting on some shorts if things continued to deteriorate. That’s just what I did, with my AI and Tech positioning dramatically reduced, although definitely not eliminated, and I’m ready to step back in when the price action dictates. I’ve already started to cut the oversized bond positions I noted a month ago as well as several names that ran a good bit in October, to have more cash available.
I said on Friday (Chip Rout Sends Nasdaq to Worst Month Since March 2025) that the week’s selloff “did confirm my inclination to sell bounces in Tech for now, at least until we see some better evidence of stability than we got last week (and preferably until some of the commentators I’ve mentioned who have called the twists and turns of the past couple of years astutely turn more bullish).”
And in that regard one of the commentators I was referring to has now turned. Deutsche Bank, which downgraded Tech to neutral on October 9th, just two sessions after its relative peak, moved it back to overweight Friday:
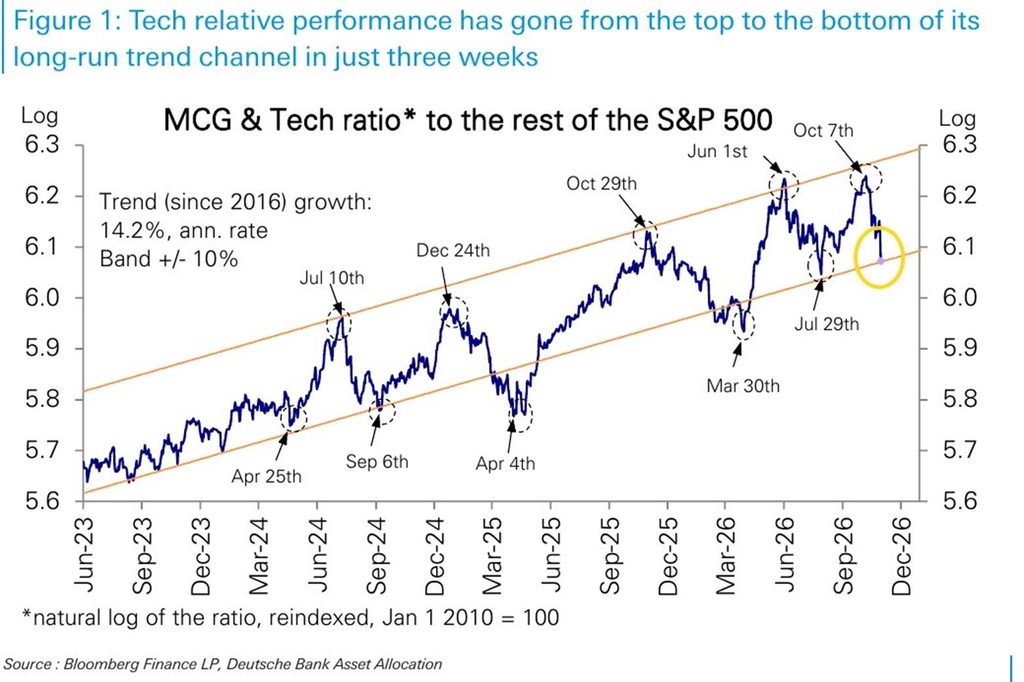
“Three weeks ago, we downgraded Tech tactically from overweight to neutral as the risk-reward seemed unfavorable with performance, positioning and the perception of growth all asymmetric… Tech has underperformed sharply since then, taking it to the bottom of its decade-long relative trend channel, and investor positioning in Tech has also dropped sharply and is in line with a significant deceleration in earnings growth. The risk-reward is now in favor of Tech again and we upgrade it back to overweight. We note that previous rotations into Tech have also seen the S&P 500 rally hard.
“With the sharp selloff late this week, MCG & Tech has now underperformed by over 16pp in the last three [weeks], selling off 11% even as the rest of the S&P 500 rose almost 6%. MCG & Tech relative performance is now at the bottom of its long-run trend channel, a level from which it has V-turned up 5 times in the last 2 1/2 years… On average, these rotations into Tech have seen it rise 32%, outperforming the rest of the S&P 500 by 30pp. We note that S&P 500 performance in previous rotations into Tech has been very strong (up 16% over 3 months on average).”
Those “averages” in the commentary are medians in DB’s table which shows just how unusual this rotation has been compared to the past few. MCG & Tech’s 16.3-point underperformance took only 18 trading days, versus 43 to 109 for the prior four rotations away from Tech (a 17.9-point median), and the S&P 500 fell just 2.8% over the stretch, versus a 6.0% median decline, while the equal-weighted index rose 3.6% (versus a 1.4% median).
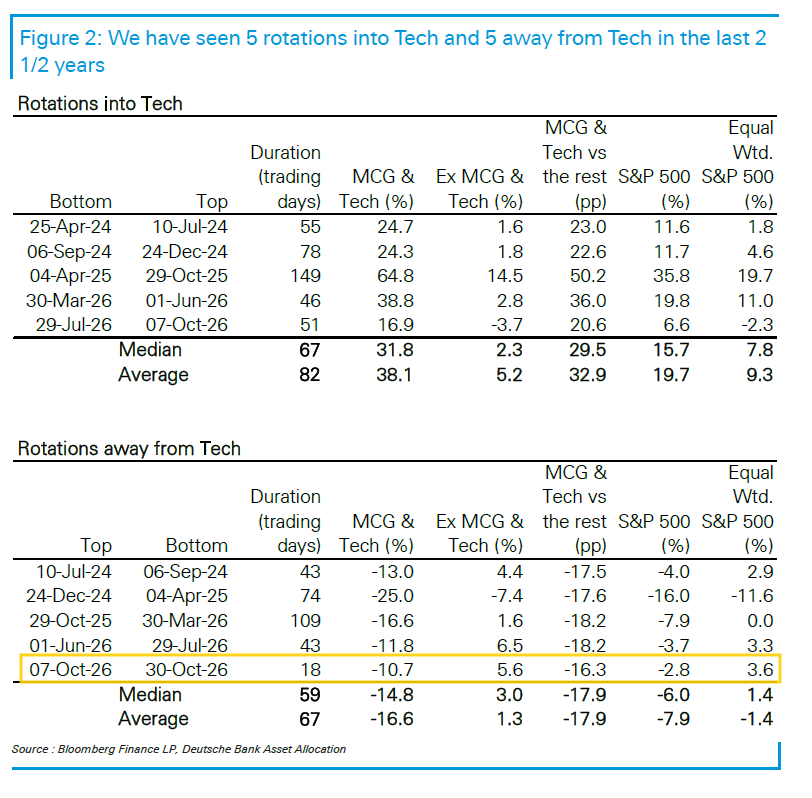
So while they are becoming more constructive, there is some caution as this selloff hasn’t quite reached the median (or average) price declines and is not even close on duration. That doesn’t mean the rebound can’t start now, but it would be the shortest and shallowest seen the past couple of years.
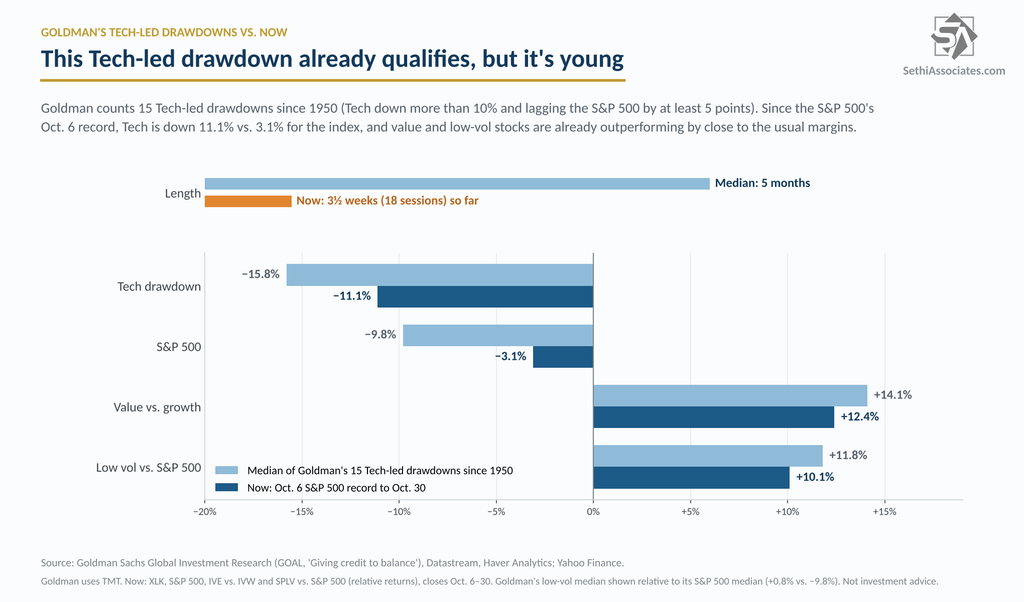
Similarly, Goldman’s asset allocation team counts 15 Tech-led drawdowns since 1950 (a fall of more than 10% with at least 5 points of underperformance vs. the S&P 500). The median lasted five months, with Tech down 15.8% and the S&P 500 down 9.8%. Per Claude, the Tech sector ETF (XLK) is down 11.1% from the S&P 500’s October 6th record versus 3.1% for the index, so this one qualifies on that metric, but it’s less than four weeks old. One thing that has gone according to the playbook: value has outperformed growth by 12.4% since October 6th and low-vol stocks have outperformed the S&P 500 by 10.1%, close to what’s typical in these episodes.
And we still haven’t gotten the all clear from any of the others who turned more cautious (Rubner, Yardeni, Kettner, etc.). Yardeni on Saturday still counseled investors “to proceed with caution in the coming days” until the midterms and the Middle East play out, though he’s sticking with his 7,900 year-end target (“Santa is coming”).
And you can add some caution from Helene to the list. Last weekend, she said the Nasdaq looked a lot like the Sentiment Cycle chart from market technician Justin Mamis’s 1991 book The Nature of Risk, a stylized market path labeled with how the crowd feels at each stage (first two charts). In Are You Paying Attention to the Market’s Subtle Warnings?, she wrote, “I submit to you that Nasdaq is currently in ‘Disbelief’, likely at Subtle warning… if it does break, I expect we will see sentiment follow the pattern on the Sentiment Cycle chart.” On Friday it did just that, closing below the support line she drew off the August lows. In her Saturday Substack update (last chart), she added that the Nasdaq had “an outside month which is generally considered bearish,” that the head-and-shoulders top she’d drawn in the QQQ “came to fruition,” and that Friday’s QQQ volume was the “highest since early June.”
And then there’s the midterms. Bloomberg had a piece earlier this month running through various scenarios. Wall Street unsurprisingly is generally looking for gridlock (the call from BofA, Citi, etc.) with Citi’s Stuart Kaiser calling a stymied Congress the ideal outcome with profits booming and GDP growing at a steady clip.
History is consistent with that view. Under a Republican president with a split Congress, the S&P 500 has averaged 13.7% a year since 1950, per Carson Investment Research, versus 8.3% when Republicans controlled Congress and 4.9% when Democrats did. A Democratic sweep, the outcome Kalshi favors, is the scenario most likely to spark a selloff analysts believe, mainly on the risk of AI regulation, from restrictions on data centers to rules on how models are developed. Trump’s veto would make it hard to pass anything, but Democrats could still keep the pressure on the industry through investigations and hearings.
Healthcare could benefit if they push to reverse Medicaid cuts, while defense contractors have already slumped on expectations of tighter scrutiny of military spending. In bonds, a blue sweep could weigh on prices if Trump, as a lame duck, leans more heavily on executive action such as new tariffs or raising geopolitical tensions, which is close to the post-midterm risk I discuss in the wrap-up.
A Republican hold, which polls suggest is unlikely, would keep the favorable backdrop for AI stocks intact and could spark a rally in financials and industrials. As Manulife John Hancock’s Matt Miskin put it, “Status quo would not be a bad thing per se.”
But whatever the outcome, history is on the bulls’ side. Wells Fargo found the S&P 500 has risen in the 12 months after every midterm election since World War II. Per Truist, stocks tend to fall in the months before a midterm and start rallying shortly before the vote (we’re not seeing that second part yet).
But some caution is appropriate. According to Claude’s read of Truist’s chart, the S&P 500 is normally up only about 1% at the end of October in a midterm year and finishes up about 5%, with roughly 3 points of that coming after Election Day (which always falls between November 2nd and 8th). This year, though, the S&P 500 is already up 10.7% through October, so perhaps we’ve front-run the gains?
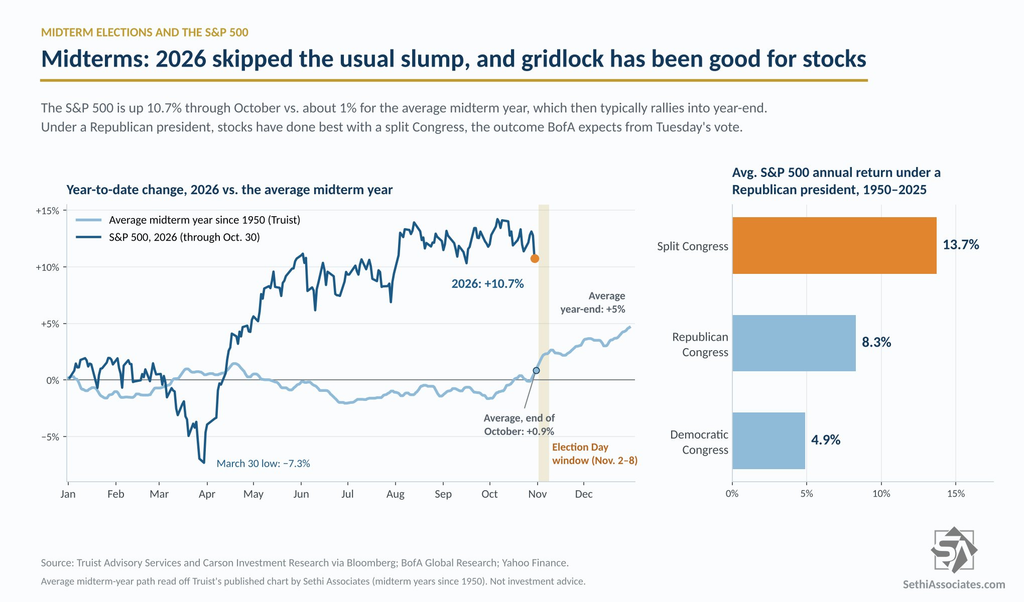
And as I’ve mentioned previously, in this particular mid-term there is the “Trump risk”:
“it looks increasingly likely that we get an escalation in Iran after the midterms, which I’d expect to be risk-off until it’s resolved. So I wouldn’t put in a buy order for November 4th just yet. But I think this will be a ‘one last push’ by the administration to salvage what they can from the Iran situation (many think the regime is in very bad shape and that this is what’s needed to get it to capitulate or risk collapse).
In addition, there are several experts in the field, such as Bloomberg’s Nathan Dean, who see renewed action on tariffs and other Trump priorities as likely to regain momentum post-elections.
Again though DB is less concerned:
“What about risks of post-midterm policy shifts? In our reading, a lot is already priced in… On the geopolitical front, the oil market is already pricing in significant supply disruptions with oil prices 65% above our estimate of medium-term fair value based on global growth and the US dollar, close to the premium seen at the peak during the first month of the Iran war.”
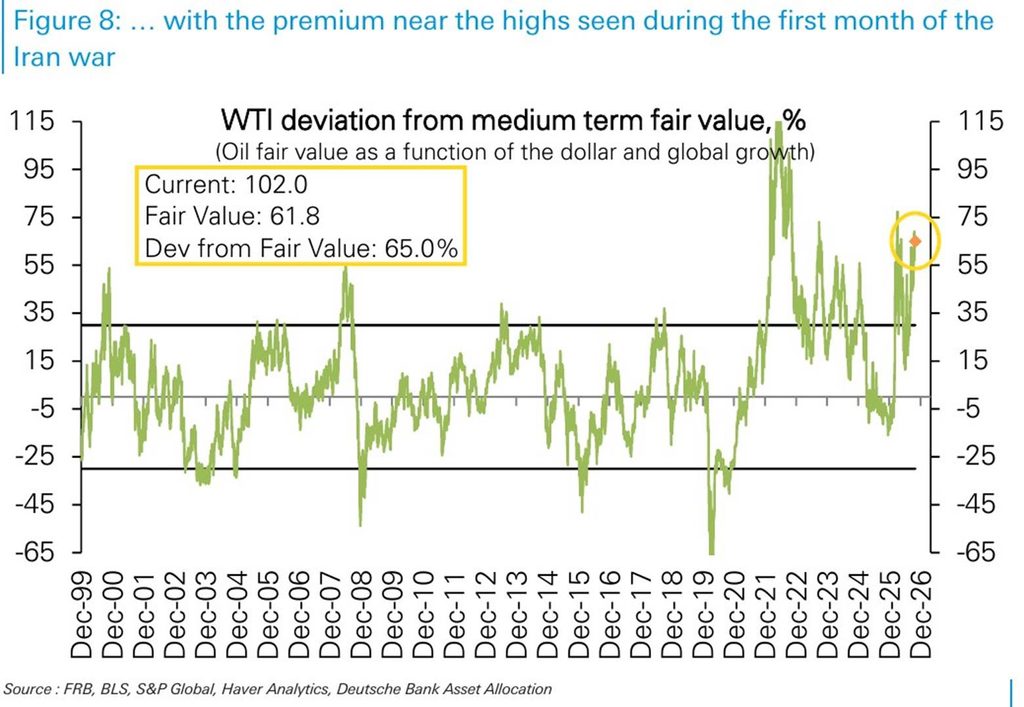
Otherwise, the rest of the indicators are mixed. Sentiment is no longer panicky, with Goldman’s Sentiment Indicator positive for the first time since August, Citi’s Panic/Euphoria Model still in Euphoria and AAII bulls back above average. Flows were starting to turn up with hedge funds covering shorts, but Friday likely will at least slow that if not reverse it while systematic strategies are on the cusp of more selling. Gamma is no longer a cushion and is close to (if not already) an accelerant to downside volatility.
More positively, the buyback blackout is ending fast, and one way or the other we will get through some heavy catalysts in the election and jobs report this week. That’s not to mention more key earnings, Treasury’s refunding Wednesday, etc.
So that leaves me watching and waiting. I’ve had my fingers burned one too many time trying to guess if the stove was ready to be touched (or if the knife was done falling, etc.) so I’ll wait until things firm up better, either through the fundamentals or the price action, preferably both, before adding back the risk I’ve taken off the past few weeks.
I remain optimistic on things improving at some point. Seasonality is very supportive, positioning is much, much cleaner (BofA’s “up week” CTA buying is the most in two months), a lot of headline risk will be behind us in the not too distant future, retail still seems to be buying the dips, valuations are relatively favorable, etc.
As always, let’s see what we get and go from there.
At the time of publication, in terms of securities mentioned, Sethi was long AAPL, AMZN, BKNG, BRK.B, CIBR, ETN, GOOGL, MSFT, NVDA, PLTR, UBER, SPY, IWM, RSP and numerous Treasury ETFs and short AMD.