New Home Sales Hold Near Year’s High Even as Prices Rebound
September new home sales beat even as prices rebounded from low since 2021.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
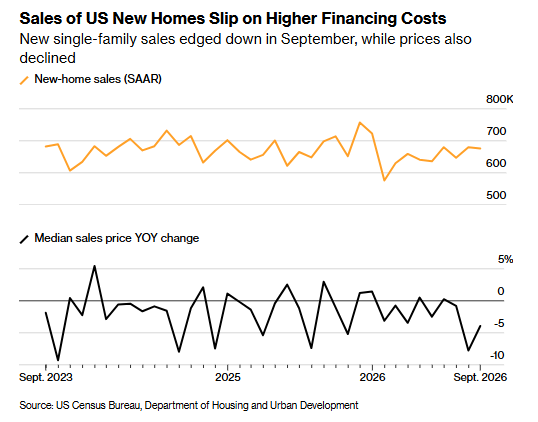
U.S. New Home Sales, September: 676,000 (estimate 651,000; previous 684,000; previous revised 680,000)
- New home sales, month over month: minus 0.6% (estimate minus 4.5%; previous 6.4%; previous revised 5.1%)
- Median sales price: $400,400, or minus 3.9% from September 2025 (previous $393,700, or minus 5.8% from August 2025; previous revised $385,400, or minus 7.8%)
Executive Summary
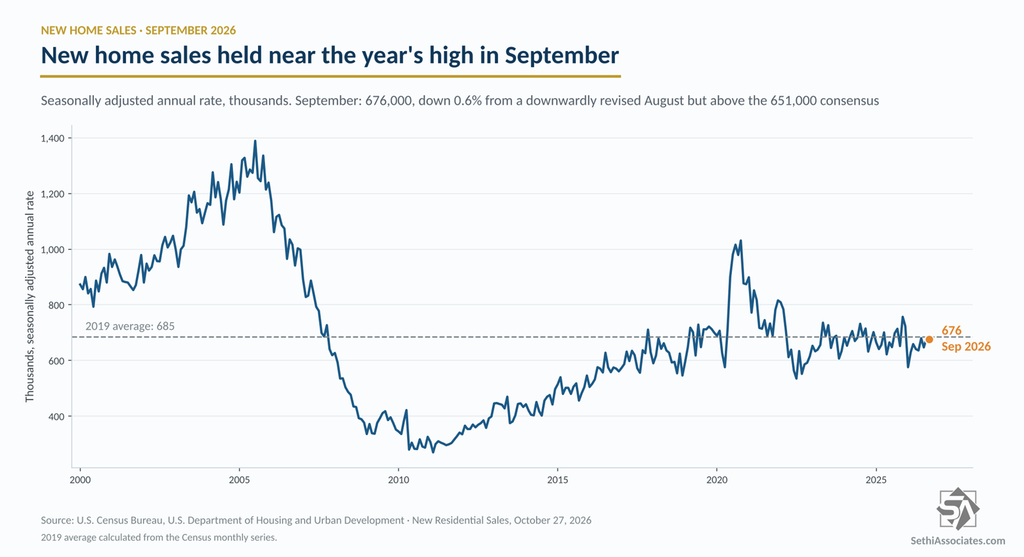
- September new home sales edged down just 4,000 (0.6%) to a 676,000 seasonally adjusted annual rate, well above the 651,000 consensus and within 4,000 of the year’s high of 680,000 set in both June and August after August was revised down to 680,000 from 684,000. July was revised up to 647,000. Sales are down 5.3% year-over-year and 2.9% year-to-date.
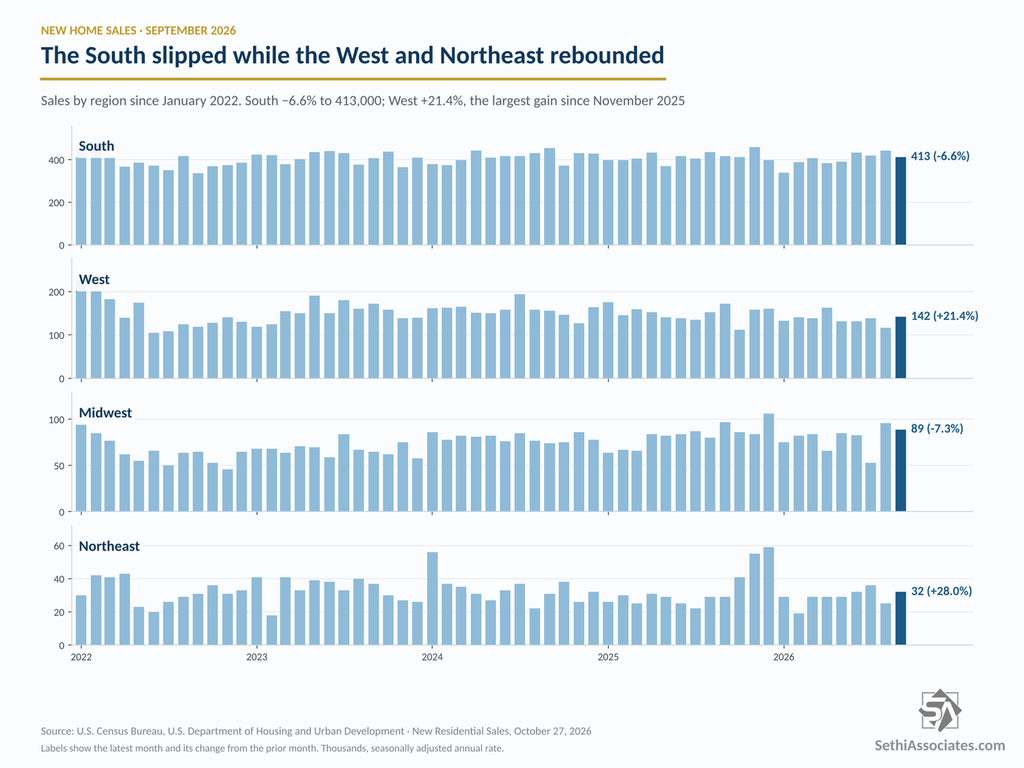
- The South fell 6.6% to the lowest since May, while the West jumped 21.4%, the largest gain since November 2025.
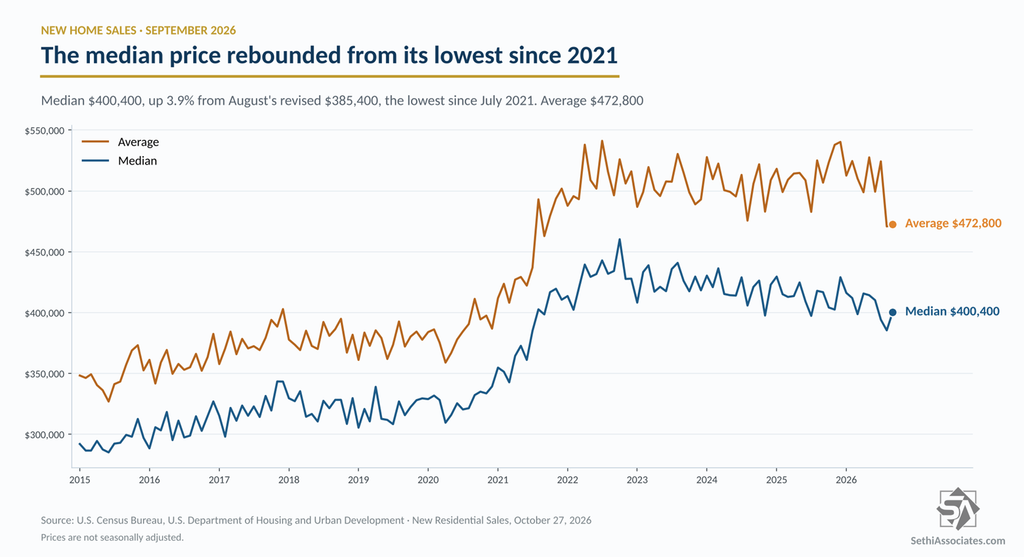
- The median price rebounded 3.9% to $400,400 after August was revised down to $385,400, the lowest since July 2021, leaving it down 3.9% year-over-year. The average edged up 0.4% to $472,800 after August was revised down to $470,800, the lowest since September 2021, making August’s $53,500 drop an even larger record one-month dollar decline.
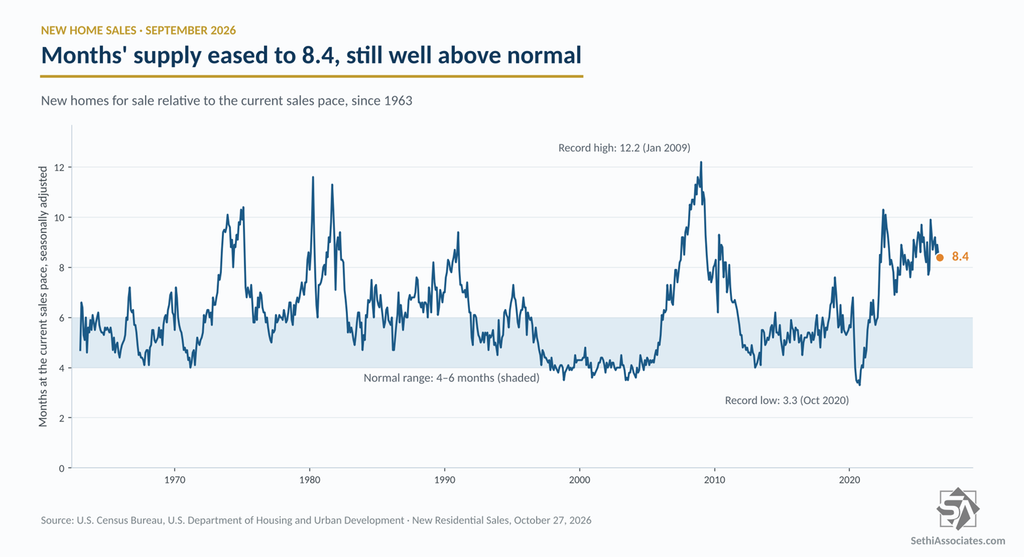
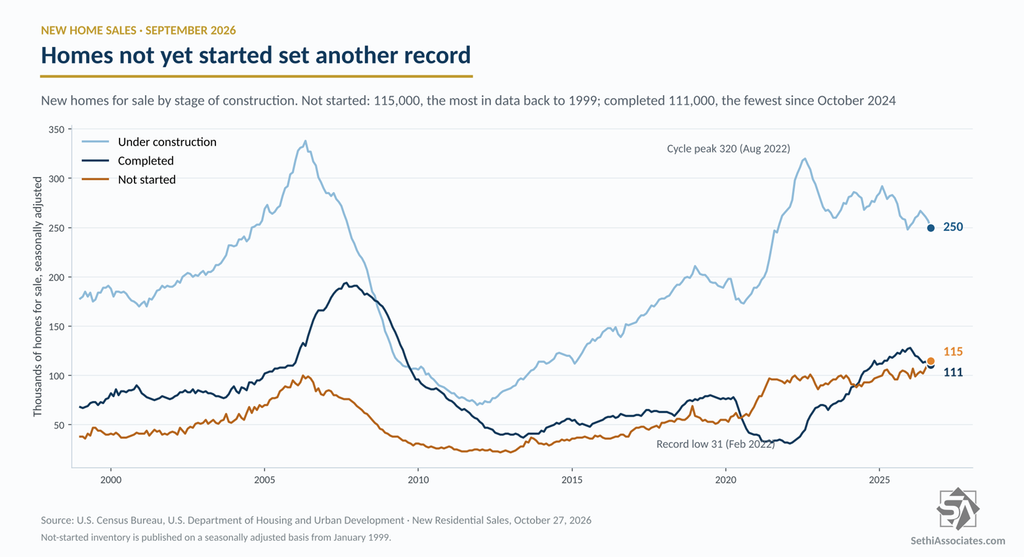
- Homes for sale eased to 476,000, the fewest since September 2024, and months of supply edged down to 8.4, the least since December 2025 but still well above the normal four-to-six-month range. Completed inventory fell to 111,000, the fewest since October 2024, while homes not started rose to another record at 115,000.
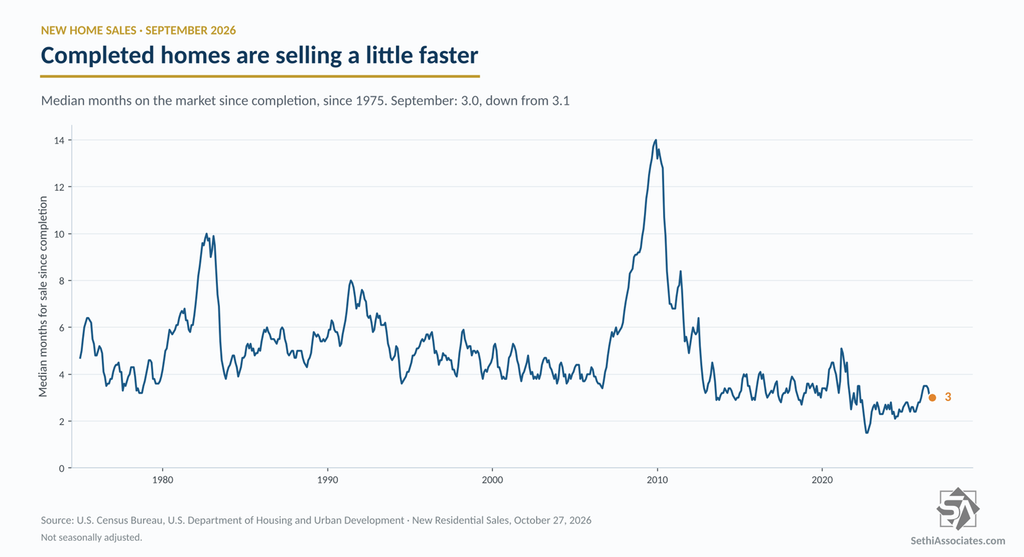
- The median months to sell a completed home edged down to 3.0 from 3.1, matching January for the shortest since December 2025.
Note: New-home purchases normally account for about 10% of total sales and are calculated when contracts are signed, so they do not account for cancellations (so can overstate sales when cancellations are high). Most of what is reported in the media is seasonally adjusted, so I report on that basis as well. Finally, note that this report is subject to significant revisions — the 90% confidence interval for the month-over-month figure in this report is a huge ±13.8%.
The seasonally adjusted annual rate for new home sales edged down 4,000 (0.6%) in September from August (m/m) to a 676,000 seasonally adjusted annual sales rate (SAAR), well above the 651,000 consensus and within 4,000 of the year’s high of 680,000 set in both June and August. was even as homebuilder confidence fell to the lowest level in 14 years.
August was revised down to 680,000 from 684,000, trimming that month’s gain to 5.1% from 6.4%, while July was revised up to 647,000 from 643,000, and June to 680,000 from 672,000. Sales are down 5.3% year-over-year, and down 2.9% year-to-date.
By region, though, the South, the largest market representing over 60% of all new home sales, fell 6.6% to 413,000, the lowest since May 2026, and is down 0.7% year-over-year. The Midwest fell 7.3% to 89,000, giving back part of August’s record jump (revised to 81.1%, still the largest monthly gain in data back to January 1973), and is down 8.2% year-over-year.
That was offset by the West jumping 21.4% to 142,000, the largest monthly gain since November 2025 and the highest rate since April 2026, though it is still down 17.4% year-over-year. And the Northeast rose 28.0% to 32,000, the highest since July 2026, up 10.3% year-over-year.
The median sales price rebounded 3.9% from August to $400,400, after August was revised down to $385,400, the lowest since July 2021. The median is down 3.9% year-over-year, which Bloomberg notes is “the seventh of nine months so far in 2026 to show a year-over-year price decline.”
The average sales price edged up 0.4% to $472,800 after August was revised down to $470,800, the least since September 2021. That revision made August’s $53,500 (10.2%) drop in the average price an even larger record one-month dollar decline; in percentage terms it was the largest since September 2014. In September average prices were down 6.7% year-over-year.
McBride puts the median 13.0% below its October 2022 peak and the average 12.6% below its July 2022 peak, adding, “This just means builders are selling more lower priced units!”
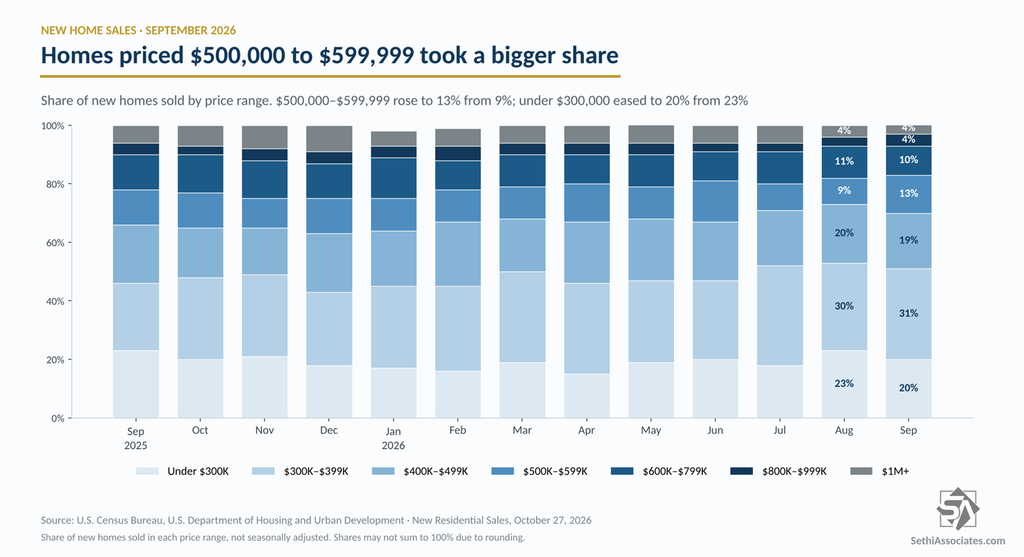
By price range, the rebound came as homes priced $500,000 to $599,999 rose to 13% of sales from 9%, while sales under $300,000 eased to 20% from 23%. The $1 million-and-over bracket held at 4%. About 70% of sales were under $500,000 and 30% over, with McBride noting the over-$500,000 share is down from 42% at the 2022 peak, while the under-$300,000 share is up from a low of 9.3% in July 2022. “Homebuilders have been building less expensive homes to keep up volumes,” he says. Bloomberg adds that builders are “offering smaller homes and subsidized mortgage rates to offset poor affordability.”
New home supply eased to 476,000 from 481,000, the fewest since September 2024, and is down 2.3% year-over-year.
And the months of supply at the current sales rate edged down to 8.4 from 8.5, the least since December 2025, though still well above the “normal” range of four to six months.
In terms of the mix of that supply, the inventory of completed homes for sale fell to 111,000, the fewest since October 2024, and down from January’s 128,000, which was the highest since June 2009. It remains more than triple the record low of 31,000 in February 2022.
The inventory of homes under construction fell for a fourth straight month to 250,000, the fewest since December 2025 and 22% below the cycle peak of 320,000 in August 2022, but still above the 198,000 of February 2020.
Meanwhile, the inventory of homes not started rose to 115,000, another record high, and more than double the 55,000 of January 2020.
At the current sales pace, that comes out to 2.0 months of completed supply, 4.4 months under construction (down from 7.1 months in July 2022, per McBride) and another 2.0 months not yet started. McBride says homebuilders “are probably waiting to start some homes until they clear more inventory, and have a firmer grasp on prices, mortgage rates and demand.”
The median months to sell a completed home edged down to 3.0 from 3.1, matching January for the shortest since December 2025, and down from the 3.5 that prevailed from March through May, which was the highest since August 2021.
All charts are built from the Census Bureau release here.