Business Investment Gauge Sees Fastest Quarterly Growth Since 2020
Aircraft orders drove a 1.8% headline jump, but core equipment shipments grew at their fastest quarterly pace since 2020, a boost for Q3 GDP.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
- U.S. Durable Goods Orders (M/M) Sep P: 1.84% (est 1.9%; prev -0.1%; prev R 0.12%)
- Durables Ex-Transportation (M/M): 0.46% (est 0.6%; prev 0.2%; prev R 0.32%)
- Cap Goods Orders Nondef Ex Air (M/M): 0.46% (est 0.7%; prev 1.6%; prev R 1.55%)
- Cap Goods Ship Nondef Ex Air (M/M): 1.22% (est 0.8%; prev 0.5%; prev R 0.60%)
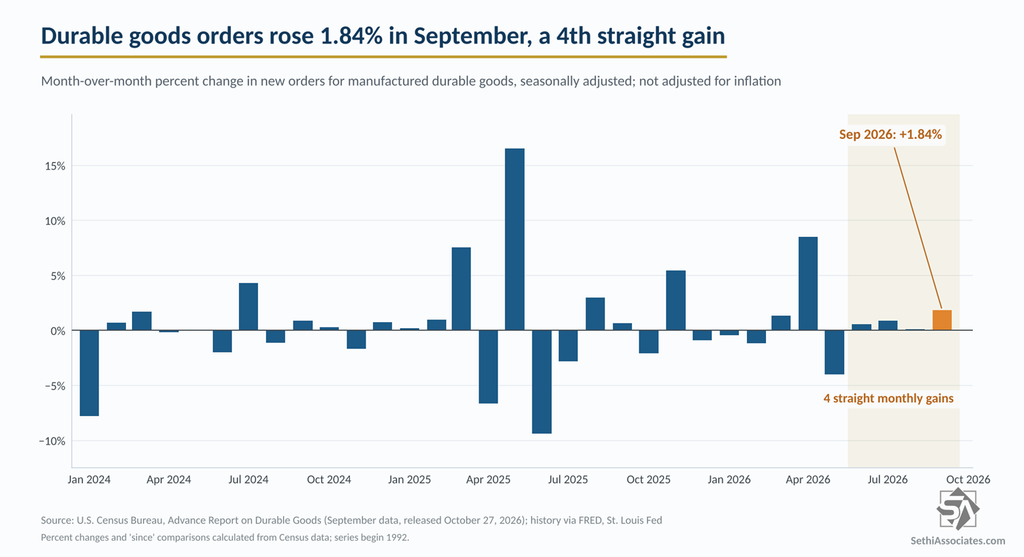
Durable goods orders (goods meant to last at least three years) jumped 1.84% in September, just under the 1.9% expected, with the headline driven by lumpy nondefense aircraft orders — mostly Boeing (BA) — up 28.44% and accounting for about $5.6 billion of the $6.3 billion gain. August was revised up slightly to a 0.12% gain (initially reported as a 0.07% decline). Orders have been “up six of the last seven months,” according to the Census Bureau’s advance report, and are up 9.94% year-over-year. Figures are seasonally adjusted but not adjusted for inflation.
Transportation equipment, which also includes automobiles (+0.32% m/m), in turn rose 4.6%. But beneath that, orders were also very solid, and shipments even better.
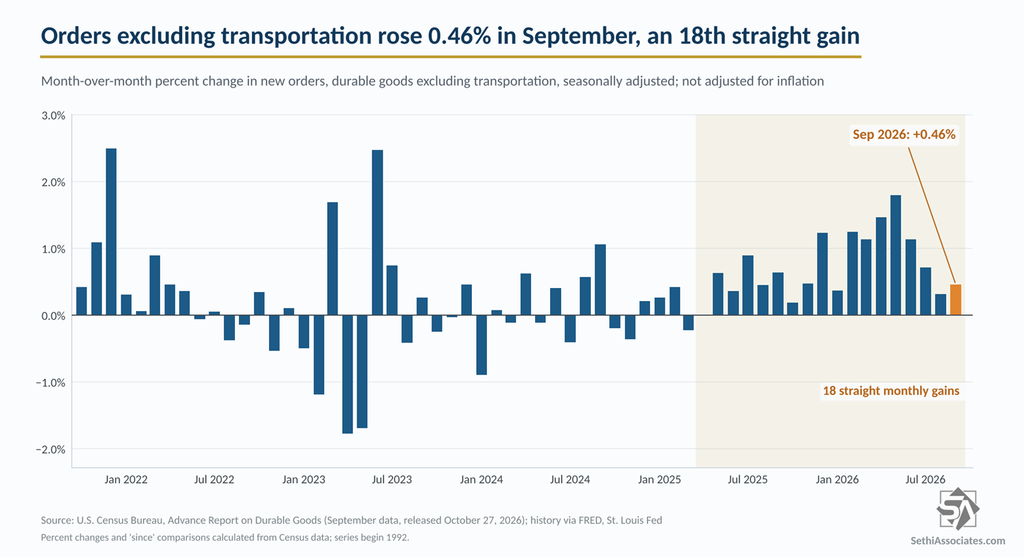
Excluding transportation, orders rose a very healthy 0.46%, but below the 0.6% expected, after an upwardly revised 0.32% in August. That is the 18th straight monthly gain, leaving them at an all-time high and up 11.06% year-over-year. Aside from the prior month that is the strongest year-over-year pace since August 2021.
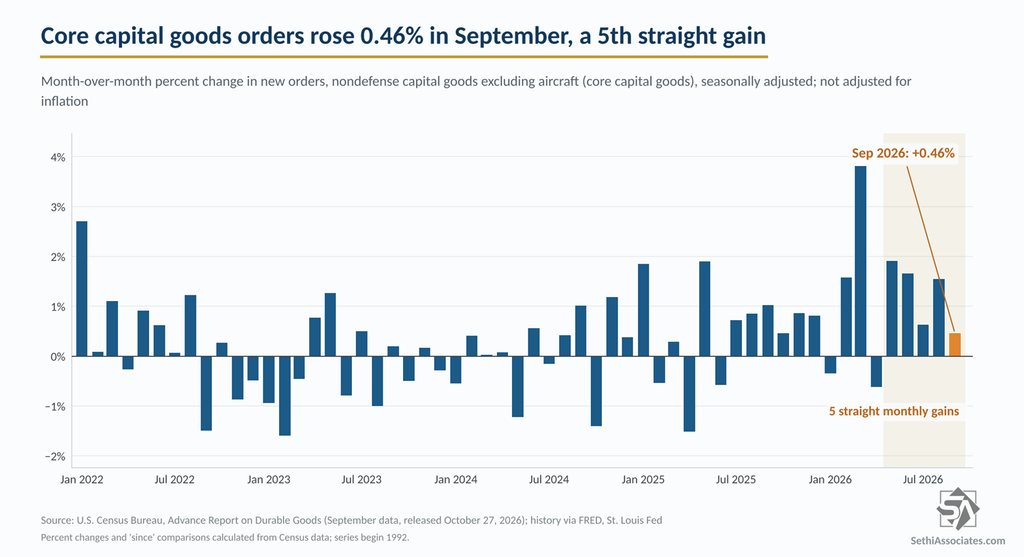
Core capital goods orders (nondefense excluding aircraft, a proxy for business capital spending plans) also (weirdly) rose 0.46%, also short of the 0.7% expected, but after a very strong 1.55% in August. Even with the slowing it was a fifth straight gain taking them to an all-time high, and they are up 13.47% year-over-year.
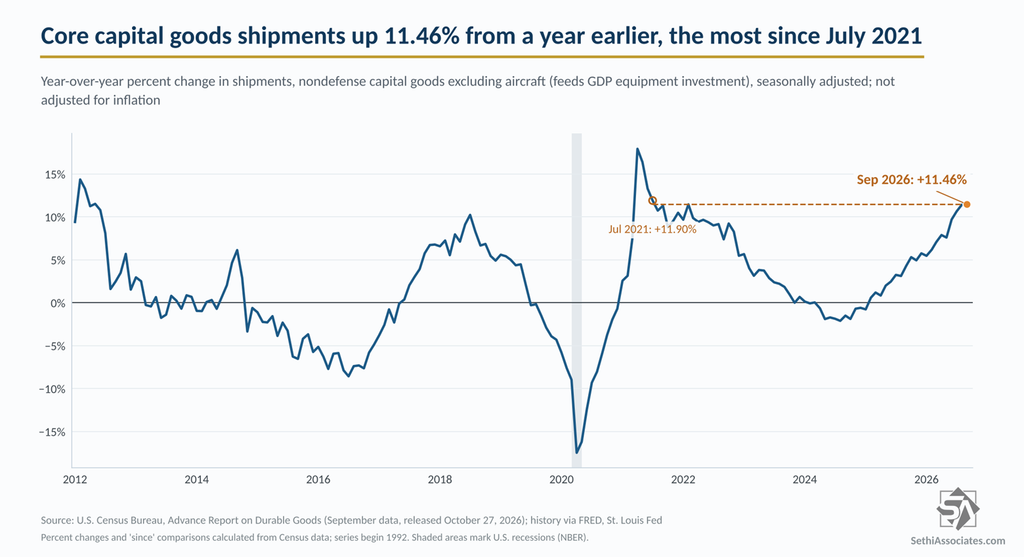
Core capital goods shipments, which feed into the equipment investment line of gross domestic product, rose 1.22%, beating the 0.8% expected, after an upwardly revised 0.60% in August. That is an eighth straight gain, to an all-time high, and they are up 11.46% year-over-year, the most since July 2021. Economists tend to prefer shipments to orders as a read on business investment because orders can be canceled, while shipments reflect equipment that has actually been delivered, which is why the government uses shipments, not orders, for GDP.
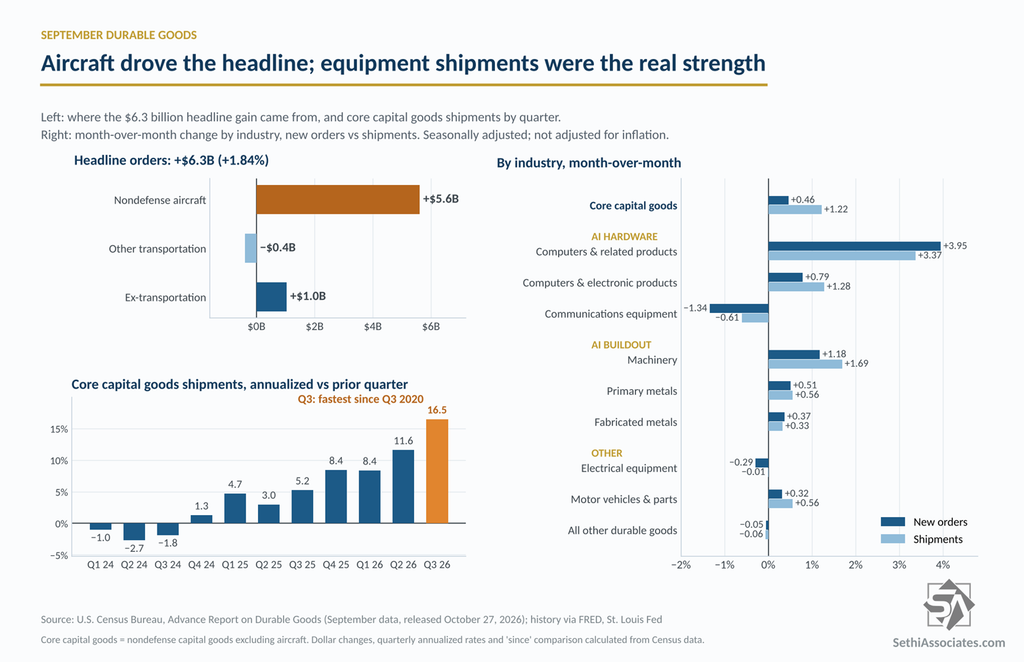
Between the beat for September and upward revision to August, that should boost Q3 GDP estimates. For the third quarter as a whole, core shipments grew at a 16.5% annualized pace over the second quarter, the fastest since the third quarter of 2020, while broader nondefense capital goods shipments including aircraft grew at an 11.0% pace.
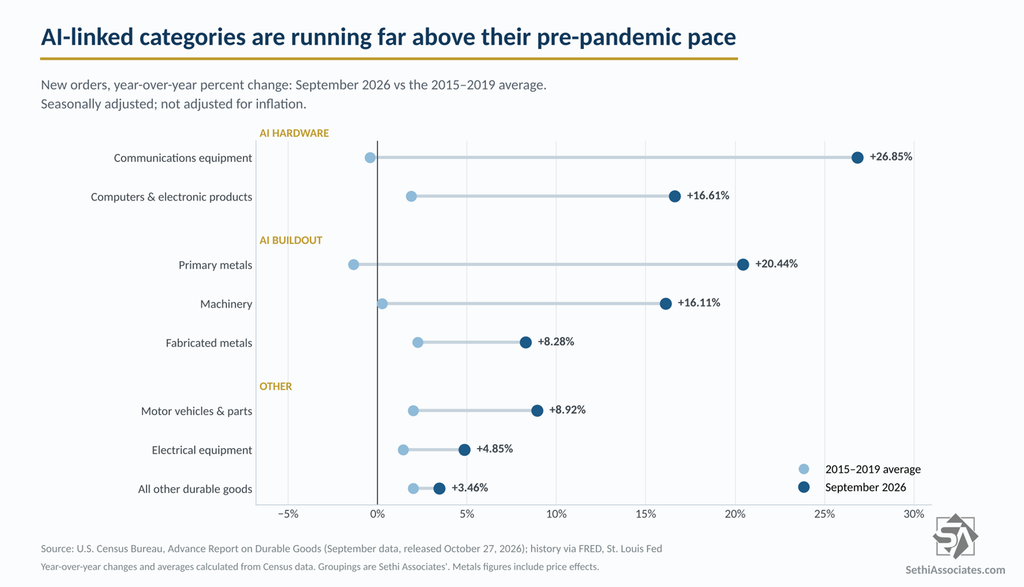
Looking at the AI impact, as you might expect the categories tied to artificial intelligence spending are running far above their pre-pandemic pace. Communications equipment orders are up 26.85% year-over-year against a 0.44% average decline from 2015 to 2019, computers and electronic products are up 16.61% (versus 1.88%), machinery 16.11% (versus 0.25%) and primary metals 20.44% (versus a 1.35% decline), although the metals figures include price changes. Since 2023, each has moved closely with computer orders. Electrical equipment, which the Census Bureau groups with appliances and lighting, is though up just 4.85%, not far from its old pace.
In September, the buildout side stayed strong while the hardware side was mixed. Machinery orders rose 1.18%, a 19th straight gain to an all-time high, and machinery shipments rose 1.69%. Computers and related products orders jumped 3.95%, but communications equipment, the AI spending proxy ZeroHedge flags (“a proxy for AI spend”), fell 1.34% for a second straight month.
The advance report doesn’t break machinery down further, but through August, the full report showed strong year-to-date gains in the pieces most tied to data centers: ventilation, heating and air-conditioning equipment (the largest piece, at about one-sixth of machinery orders) up 18.4%, turbines, generators and power transmission equipment up 15.9% and industrial machinery up 39.3%. Not all of it is AI, though: oil and gas field machinery was up 37.6% and construction machinery 14.7% (all not seasonally adjusted, January through August versus a year earlier). We’ll get more detail next week with the full factory orders report as noted at the end.
Backlogs (unfilled orders) rose 0.84%, a 17th straight monthly gain, to an all-time high of $1.62 trillion, up 8.96% year-over-year.
The full report, with revisions and nondurable goods, comes with factory orders on November 3.