Stock Market Today

Market updates and conversation from TheStreet Pro team. Follow the latest and join the conversation below.

Stock Market Today: October 29, 2026

Newest first · All times Eastern · 3 updates

DATE:
By Neil Sethi

Lagarde to Leave ECB Early, Adding to Leadership Turnover

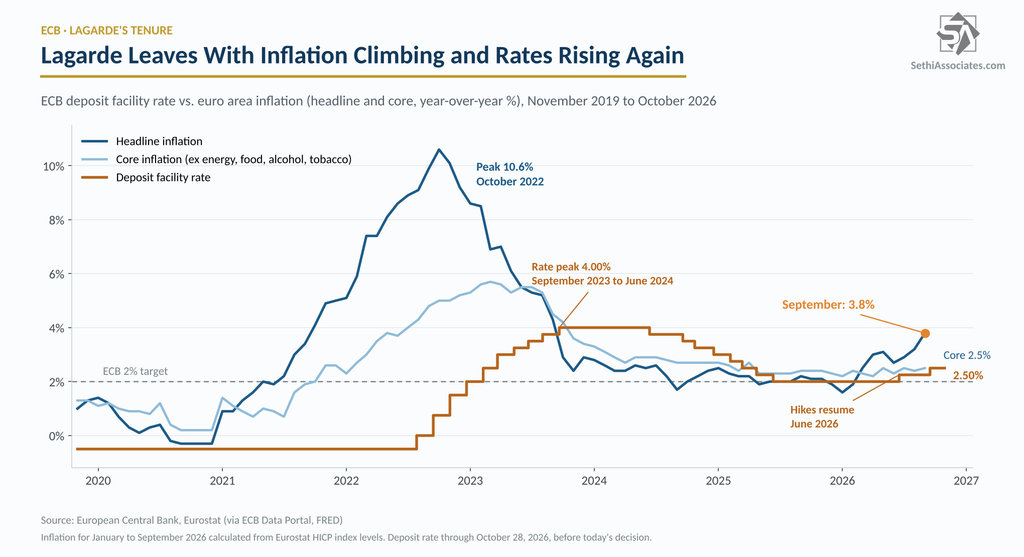
After months of speculation that she would leave before her eight-year term ends in October 2027, European Central Bank President Christine Lagarde announced today that she will step down on February 7, 2027, just hours ahead of the Governing Council’s latest rate decision, according to Bloomberg. Hers is the third of the six Executive Board seats set to turn over by May.

Lagarde becomes only the second president in the ECB’s 28-year history to leave early, after Wim Duisenberg, whose shortened stint had been agreed in advance to break a France-Germany deadlock before the bank’s launch.

Lagarde, 70, told fellow policymakers she wanted “greater freedom to express her views” because she could not stay neutral on developments in France ahead of its April presidential election, the Financial Times reported. She has ruled out running herself and has been in talks to chair the World Economic Forum. In a video message, she said she leaves with “a sense of good work done, and an ECB that is fit for the future,” per Bloomberg.

The Decision

Markets and economists widely expect the ECB to hold its deposit rate at 2.50% later this morning as officials weigh higher energy prices and recent bond-market turmoil. That would follow hikes in June and September to counter elevated inflation tied to the Iran war, but markets expect further tightening, Bloomberg noted. Bloomberg Economics expects Lagarde to wrap up the hiking cycle in December, which could give her successor some room before any further rate changes are needed. Euro area inflation rose to 3.8% in September from 3.2% in August, with core at 2.5%, according to Eurostat.

The decision is due at 9:15 a.m. ET, followed by Lagarde’s press conference at 9:45 a.m. ET.
The Succession Race

Three of the six Executive Board seats — the presidency, the chief economist and the markets portfolio — turn over by May. Isabel Schnabel is leaving a year early to join the International Monetary Fund and Philip Lane’s term expires in May, so governments will likely try to settle all three in one deal, with EU summits in November and December, per Bloomberg.

For the presidency, Spain is backing Pablo Hernández de Cos, general manager of the Bank for International Settlements and former Bank of Spain governor, while the Dutch government is backing former Dutch central bank chief Klaas Knot, the FT reported. Economists surveyed by Bloomberg in October see De Cos as the favorite. Knot built a reputation as a hawk during the eurozone debt crisis but has since softened into a pragmatist seen as responsive to bond-market stress, according to The Wall Street Journal, which also noted that an outsider can’t be ruled out given Lagarde herself was a last-minute pick in a 2019 package deal.

The timing also lets President Emmanuel Macron help pick Lagarde’s successor before his final term ends, with far-right candidate Marine Le Pen leading French polls, which risks accusations of political encroachment on the ECB’s independence, Bloomberg added. Banque de France’s governor also left early, with Macron naming his chief of staff, Emmanuel Moulin, to the post.

Market Reaction

The news barely moved markets following the announcement. The euro was down 0.1% against the dollar at $1.114, per the FT, while the 10-year German Bund yield was 1 basis point lower at 3.36% and the French-German 10-year spread held at 154 basis points, according to Bloomberg. That spread recently hit its widest since 2011, and French long-term borrowing costs topped 5% last week for the first time since 2002 per the FT. Berenberg chief economist Holger Schmieding told the FT the departure doesn’t change the outlook for ECB policy or for how the bank handles French risks.
By Neil Sethi

Q3 GDP Trackers Cluster Near 3.3%, but GDPNow’s History Says Watch for an Upside Miss

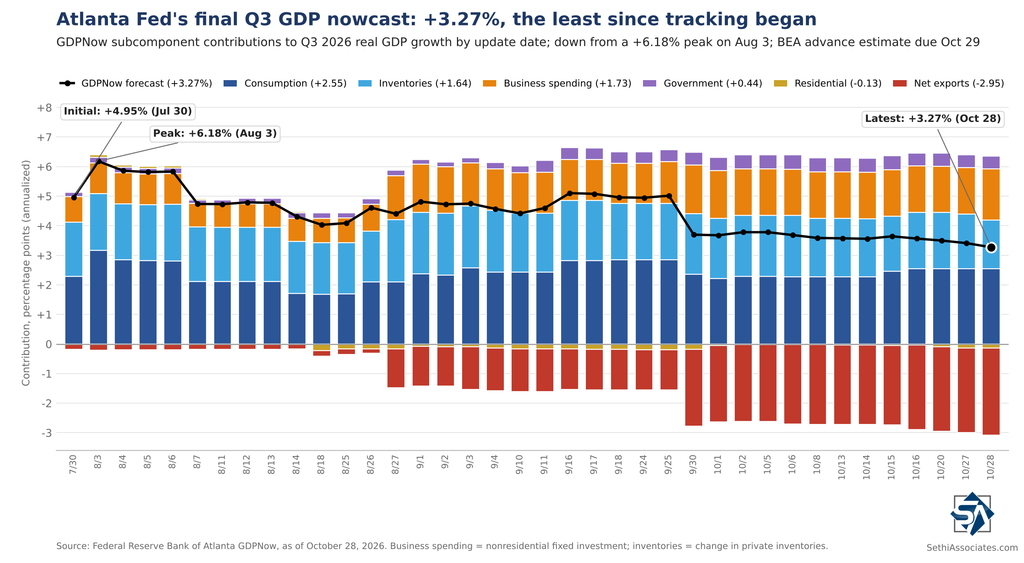
Ahead of Q3 GDP later this morning the Atlanta Fed’s GDPNow final Q3 nowcast came in at 3.27% Wednesday, the least since it initiated tracking for the quarter, down from its 6.18% peak on August 3.

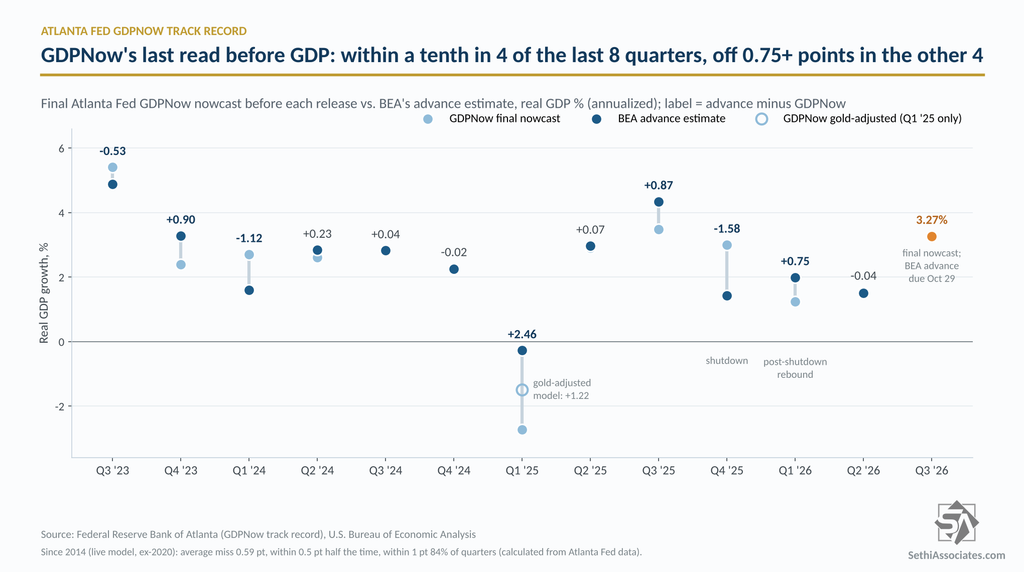
Over the past two years, GDPNow’s last reading before the advance GDP report has been either very close or well off, with little in between. It was within a tenth in four of the last eight quarters (Q3 and Q4 2024, Q2 2025 and Q2 2026) and off by 0.75 percentage point or more in the other four.

Over its history since 2014 (excluding 2020), GDPNow’s average miss has been 0.59 point. It has been within half a point half the time and within a point 84% of the time.

But a couple of unique historical tendencies are worth keeping in mind:

▪ GDPNow’s final reading usually falls from where it stood a month before the release (34 of 56 quarters excluding 2020). That’s what we saw in Q1 and Q2, and now Q3, down 1.75 points from 5.02% on September 25. But when it has fallen more than half a point in that final month, the actual print has come in above its final reading in 16 of 22 quarters.

▪ In third quarters specifically, the advance print has come in above GDPNow’s final reading in 10 of 14 quarters (excluding 2020), by an average of 0.31 point.

Here’s GDPNow’s final breakdown of the components as of October 28 and changes from my last update October 20:

Consumption = +2.55% (0.00%)

Business spending (nonresidential fixed investment) = +1.73% (+0.16%)

Inventories = +1.64% (−0.21%)

Government = +0.44% (0.00%)

Residential investment = −0.13% (−0.03%)

Net exports = −2.95% (−0.09%)

GDPNow Forecast: +3.27% (−0.23%)

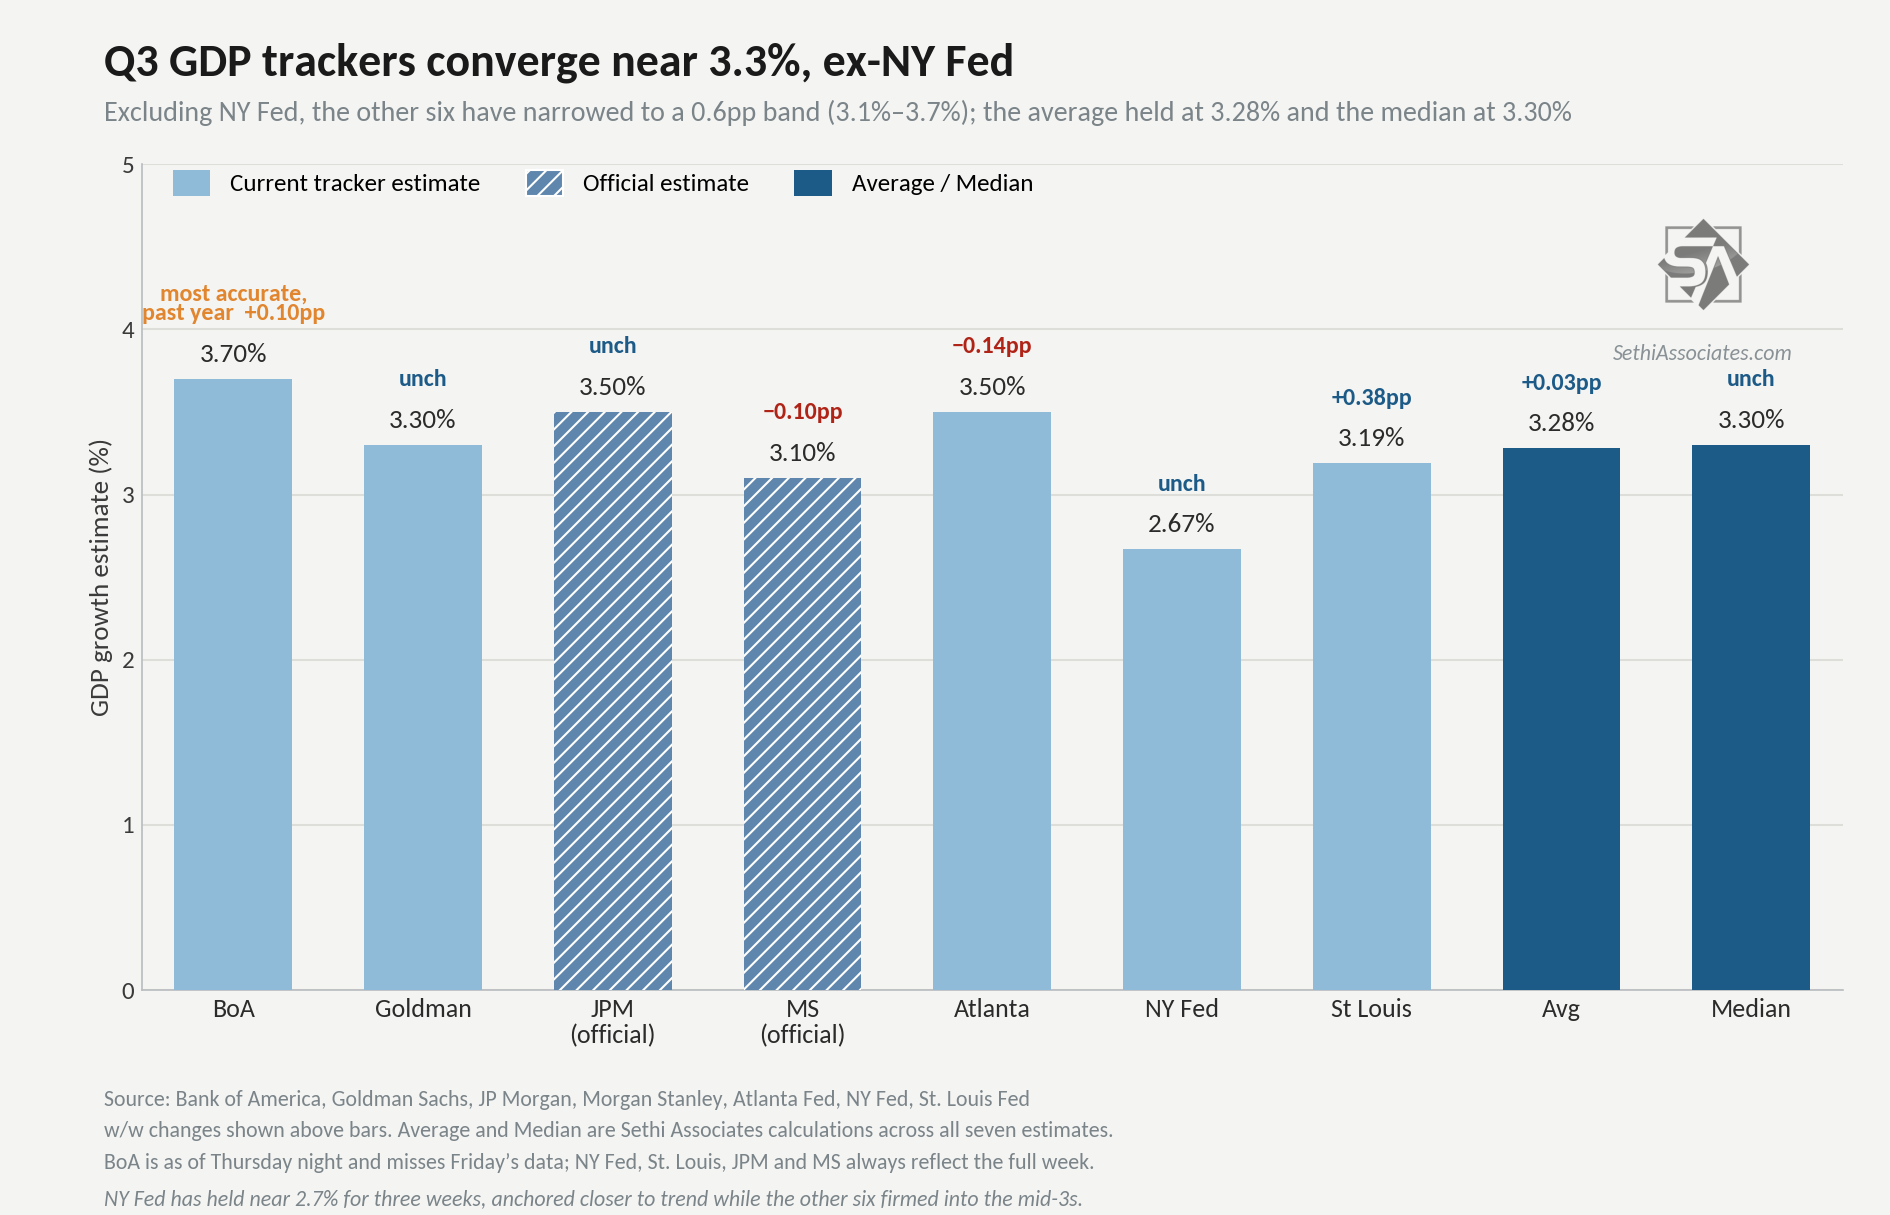
GDPNow, though, has plenty of company this quarter. As of Friday, six of the seven major trackers I follow were between 3.1% and 3.7%. The outlier is the New York Fed’s Staff Nowcast at 2.67%, where it has held for three weeks. The average as of Friday was 3.28% and the median 3.30%.

Bank of America’s tracker has been the most accurate of the group over the past year and is the highest this quarter at 3.70%.

By Neil Sethi

Thursday’s Schedule: GDP and Amazon Headline Another Busy Day

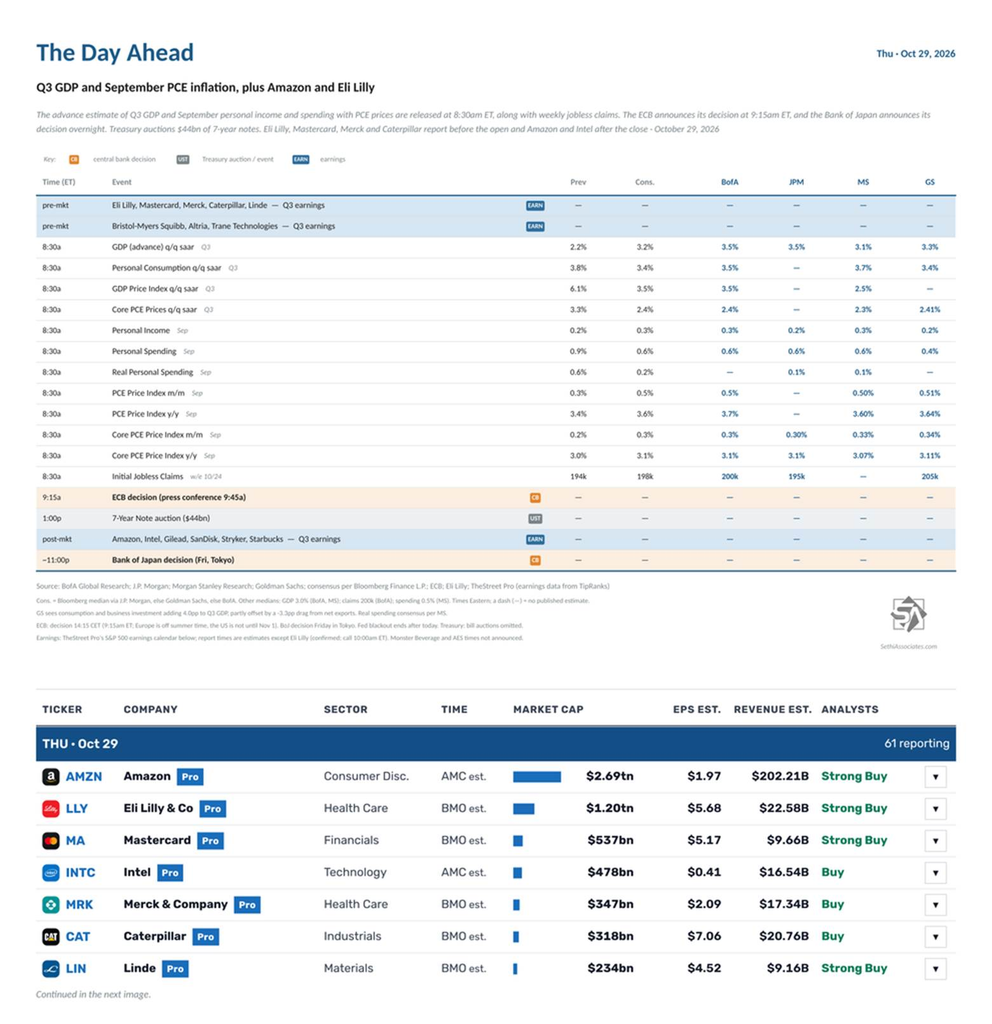
US economic data includes the advance estimate of Q3 GDP, which will incorporate September personal income and spending with PCE prices that will also be separately reported. We’ll also get weekly unemployment claims.

The Fed’s blackout period extends until midnight, with Fed speakers resuming Friday.

The non-Bill (>1yr in maturity) US Treasury auction is $44bn of 7-year notes.

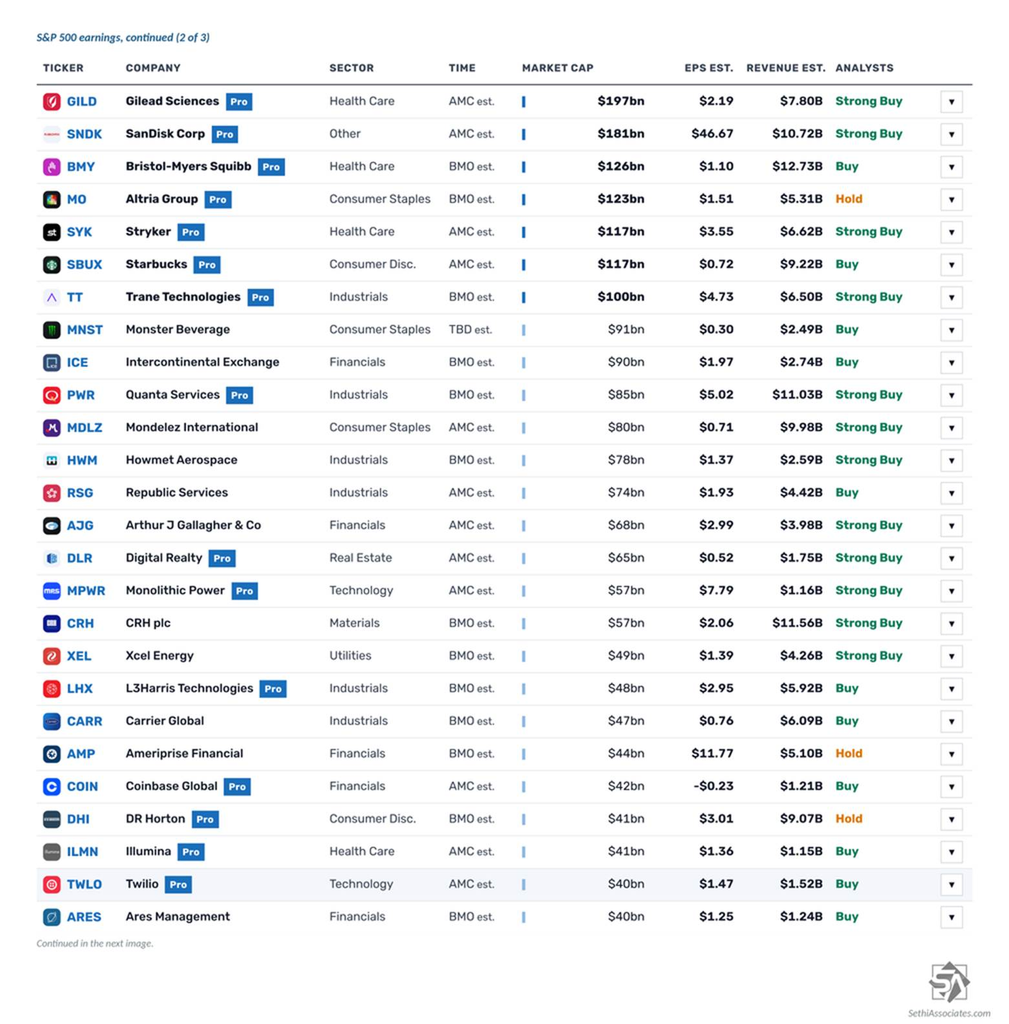
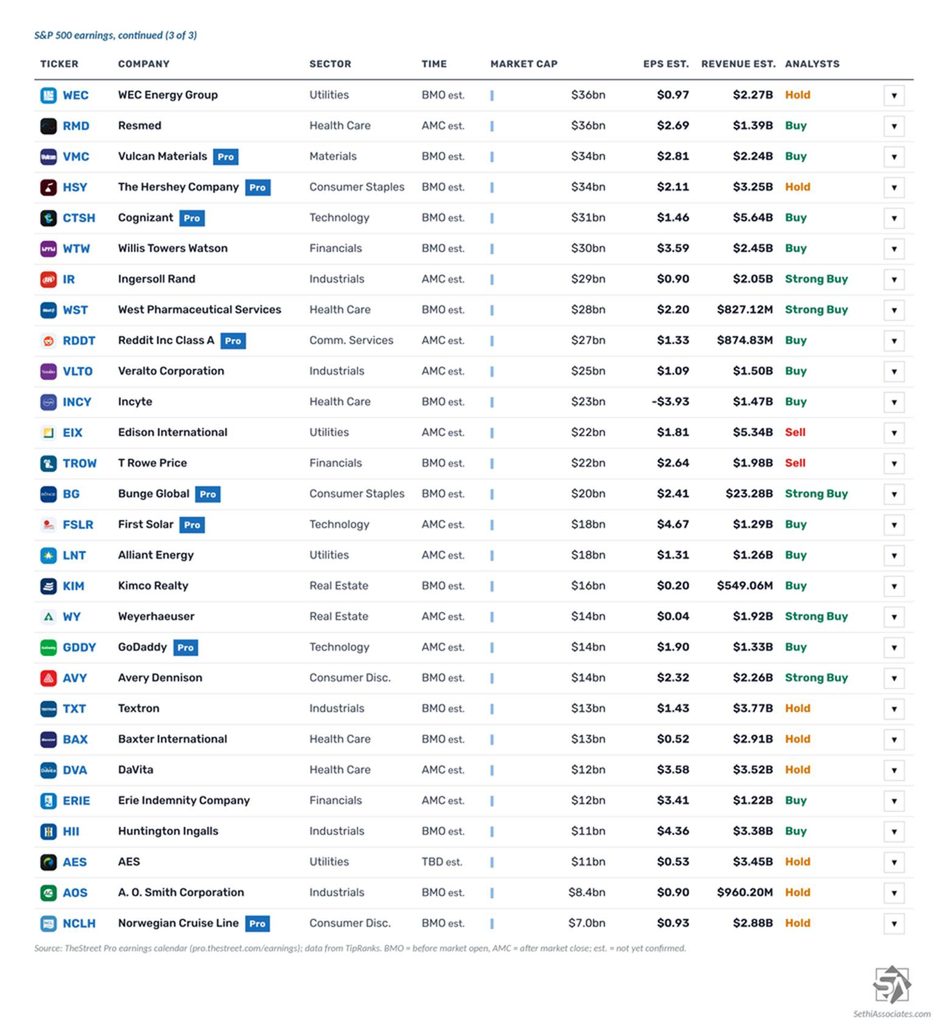
61 S&P 500 components report, 14 of them with market caps over $100bn:61 S&P 500 components report, 14 of them with market caps over $100bn:

Before the open: Eli Lilly (LLY), Mastercard (MA), Merck (MRK), Caterpillar (CAT), Linde (LIN), Bristol Myers Squibb (BMY), Altria (MO), Trane Technologies (TT), Intercontinental Exchange (ICE), Quanta Services (PWR), Howmet Aerospace (HWM), CRH (CRH), Xcel Energy (XEL), L3Harris (LHX), Carrier (CARR), Ameriprise (AMP), D.R. Horton (DHI), Ares Management (ARES), WEC Energy (WEC), Vulcan Materials (VMC), Hershey (HSY), Cognizant (CTSH), WTW (WTW), West Pharmaceutical (WST), Incyte (INCY), T. Rowe Price (TROW), Bunge (BG), Kimco Realty (KIM), Avery Dennison (AVY), Textron (TXT), Baxter (BAX), Huntington Ingalls (HII), A.O. Smith (AOS) and Norwegian Cruise Line (NCLH)

After the close: Amazon (AMZN), Intel (INTC), Gilead (GILD), SanDisk (SNDK), Stryker (SYK), Starbucks (SBUX), Mondelez (MDLZ), Republic Services (RSG), Arthur J. Gallagher (AJG), Digital Realty (DLR), Monolithic Power (MPWR), Coinbase (COIN), Illumina (ILMN), Twilio (TWLO), ResMed (RMD), Ingersoll Rand (IR), Reddit (RDDT), Veralto (VLTO), Edison International (EIX), First Solar (FSLR), Alliant Energy (LNT), Weyerhaeuser (WY), GoDaddy (GDDY), DaVita (DVA) and Erie Indemnity (ERIE)

Time not announced: Monster Beverage (MNST) and AES (AES)

Outside the US, Shell (SHEL), TotalEnergies (TTE) and Volkswagen (VWAGY) report.

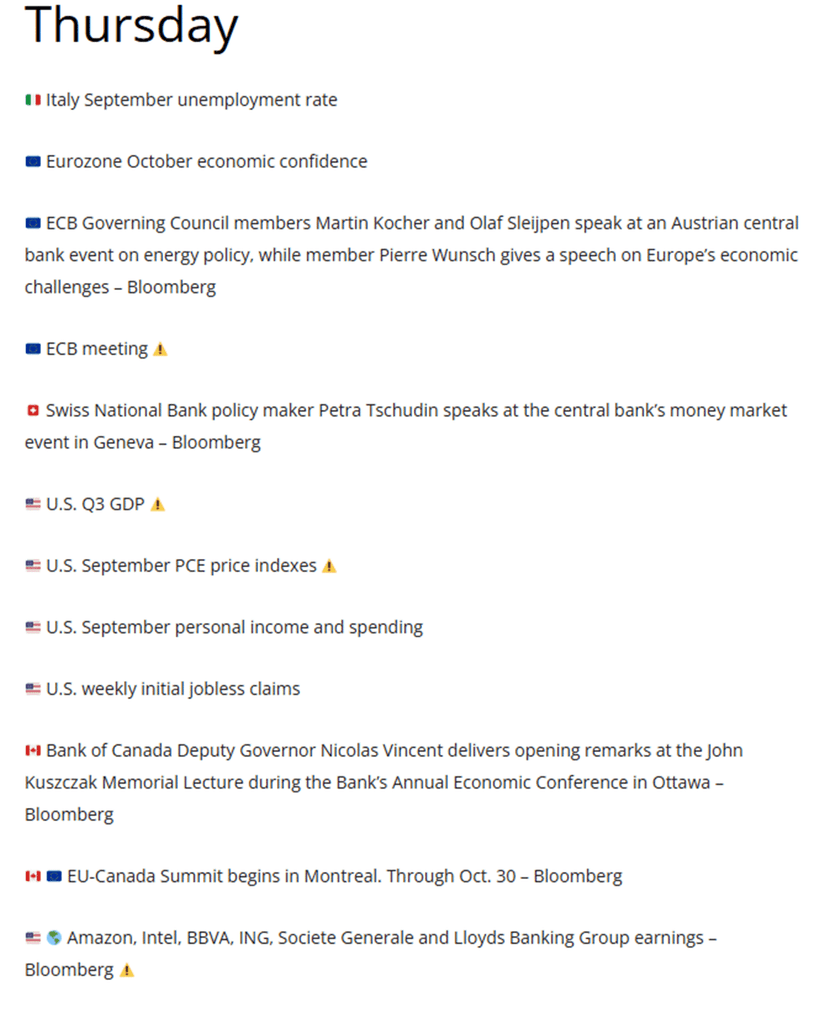
Ex-US highlights include a policy decision from the ECB, UK September net consumer credit and M4, Japan October consumer confidence index, Italy September unemployment rate, October consumer confidence index, economic sentiment and manufacturing confidence, Eurozone October economic confidence and Sweden Q3 GDP indicator.

From Christophe Barraud’s international Week Ahead rundown:

Conversation 0 Comments

One ongoing discussion across all days. Everyone can read; sign in to take part.

Your voice matters. Discussions are moderated for civility. Read our guidelines .

Log in to join the conversation

Loading comments...