Market updates and conversation from TheStreet Pro team. Follow the latest and join the conversation below.
Stock Market Today: October 30, 2026
Newest first · All times Eastern · 2 updates
DATE:
By Neil Sethi
GDPNow Tracking Slowdown in Q4
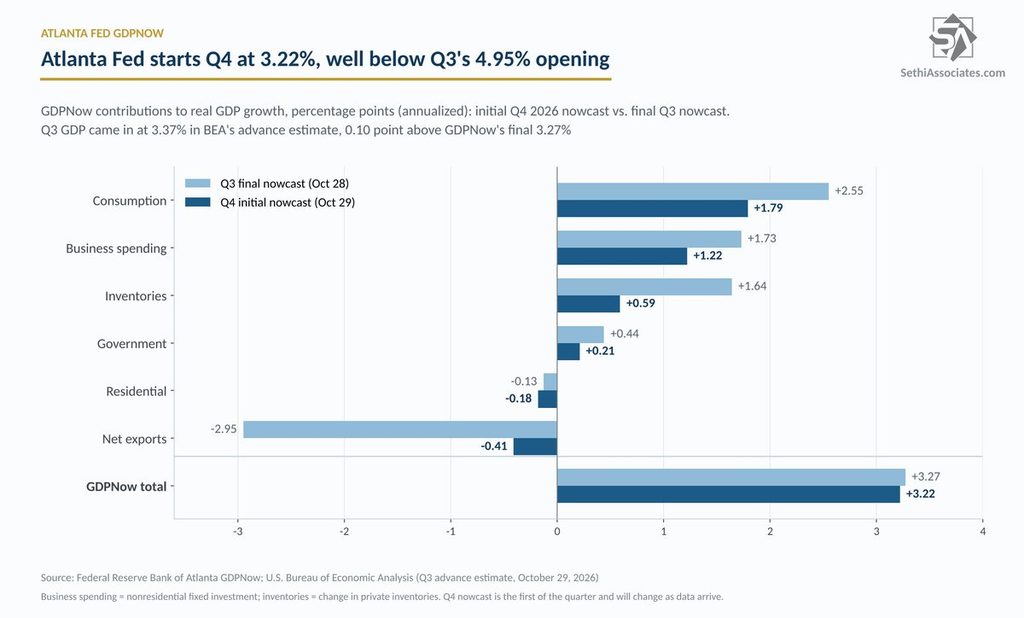
Consistent with my note yesterday morning, Q3 GDP came in at 3.37%, just 0.10 pt above the Atlanta Fed GDPNow’s final 3.27% nowcast, fitting both of the tendencies I (or I guess I should say Claude) flagged:
1 – after a big drop in the final month, and 2 – in third quarters,
the actual print has usually come in close to but above GDPNow’s last read.
GDPNow has now landed within about a tenth of the actual print in five of the last nine quarters.
Turning to Q4, the Atlanta Fed has now started tracking at 3.22%:
Consumption +1.79 pts (vs +2.55 in the final Q3 nowcast)
Business spending +1.22 (vs +1.73)
Inventories +0.59 (vs +1.64)
Government +0.21 (vs +0.44)
Residential −0.18 (vs −0.13)
Net exports −0.41 (vs −2.95)
Note though GDPNow’s early nowcasts of a quarter have historically run high. It has started above the advance print in 34 of 57 quarters (ex-2020), by 0.40 pt on average. All three 2026 openings ended well lower:
The Day Ahead: US Calendar is Light, but Tech Continues Selloff
Futures are pointing to another rough session for large cap indices with the S&P 500 indicated lower by over 1% and the Nasdaq-100 (QQQ) 2.5%. Again non-Tech is faring better with the Russell 2000 (RUT) indicated lower by just under a hafl percent.
Otherwise though catalysts are light today:
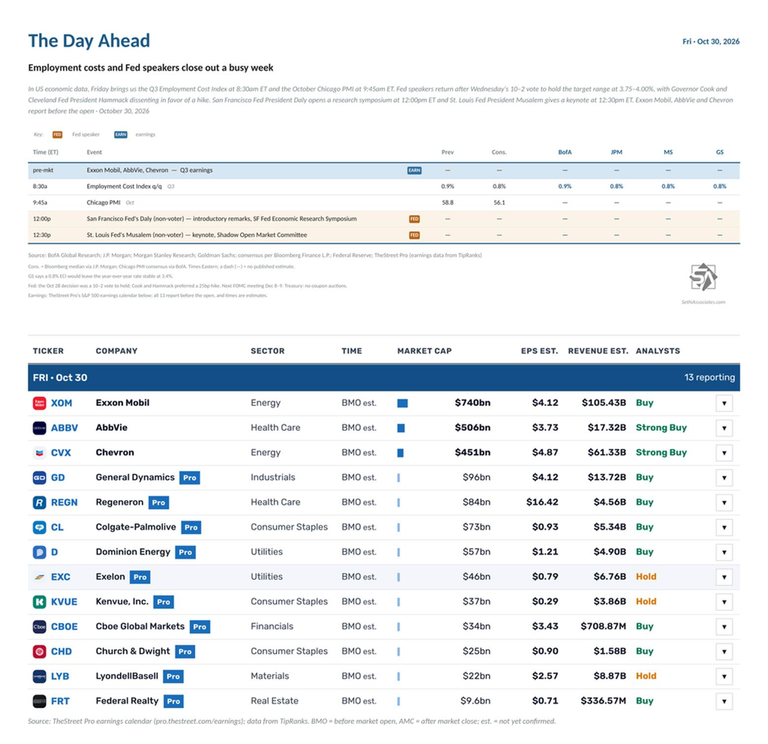
In US economic data, Friday brings us the Q3 Employment Cost Index (the Fed’s preferred wage inflation metric) and the October Chicago PMI.
Fed speakers return after Wednesday’s 10-2 decision to hold the fed funds target range at 3.75%-4%, with Governor Cook and Cleveland Fed President Hammack dissenting in favor of a 25bp hike. San Francisco Fed President Daly gives introductory remarks at the San Francisco Fed’s Economic Research Symposium at 12pm ET, and St. Louis Fed President Musalem delivers a keynote address at the Shadow Open Market Committee meeting at 12:30pm ET.
There are no non-Bill (>1yr in maturity) US Treasury auctions.
13 S&P 500 components report, all before the open, three of them with market caps over $100bn:
Before the open: Exxon Mobil (XOM), AbbVie (ABBV), Chevron (CVX), General Dynamics (GD), Regeneron (REGN), Colgate-Palmolive (CL), Dominion Energy (D), Exelon (EXC), Kenvue (KVUE), Cboe Global Markets (CBOE), Church & Dwight (CHD), LyondellBasell (LYB) and Federal Realty (FRT)
Outside the US, AstraZeneca (AZN), Sanofi (SNY) and BP (BP) report.
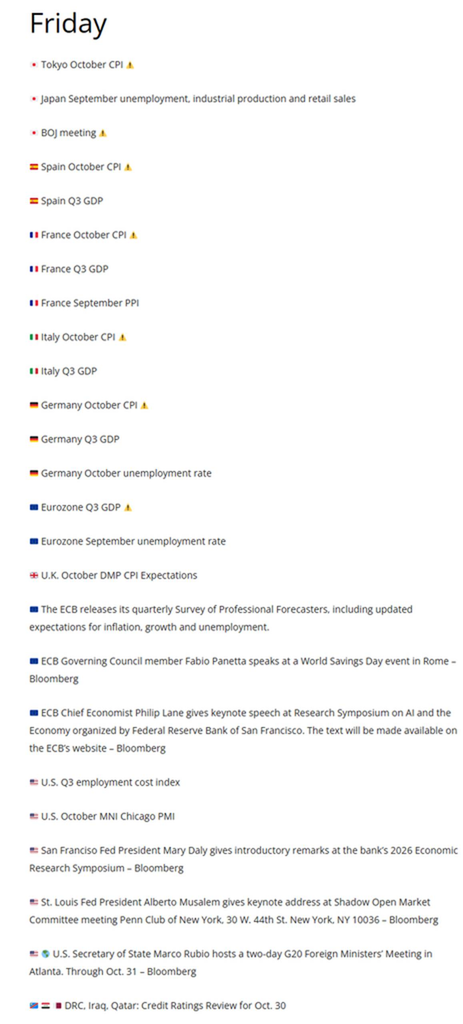
Ex-US is a busier day, with highlights including a decision from the Bank of Japan, Japan October Tokyo CPI, September jobless rate, job-to-applicant ratio, retail sales, industrial production and housing starts, UK October Lloyds Business Barometer, the ECB Survey of Professional Forecasters, Germany October CPI, unemployment claims rate, Q3 GDP and September import price index, France October CPI, Q3 GDP, private sector payrolls, September consumer spending and PPI, Italy Q3 GDP and October CPI, Eurozone Q3 GDP and September unemployment rate, Spain October CPI and Canada August GDP. The G20 foreign ministers also meet in Atlanta (through October 31).
Conversation 0 Comments
One ongoing discussion across all days. Everyone can read; sign in to take part.
Your voice matters. Discussions are moderated for civility. Read our guidelines .
Log in to join the conversation