The Week Ahead – Time For a Bounce?
After the S&P 500’s worst week since April 2025 left it in a correction, equities will look to rebound in a holiday-shortened week headlined by October personal income and spending and the Fed’s Beige Book.
You've reached your free article limit
You've read 0 of 1 free Pro articles.

PCE Prices and the Beige Book Headline a Holiday-Shortened Week
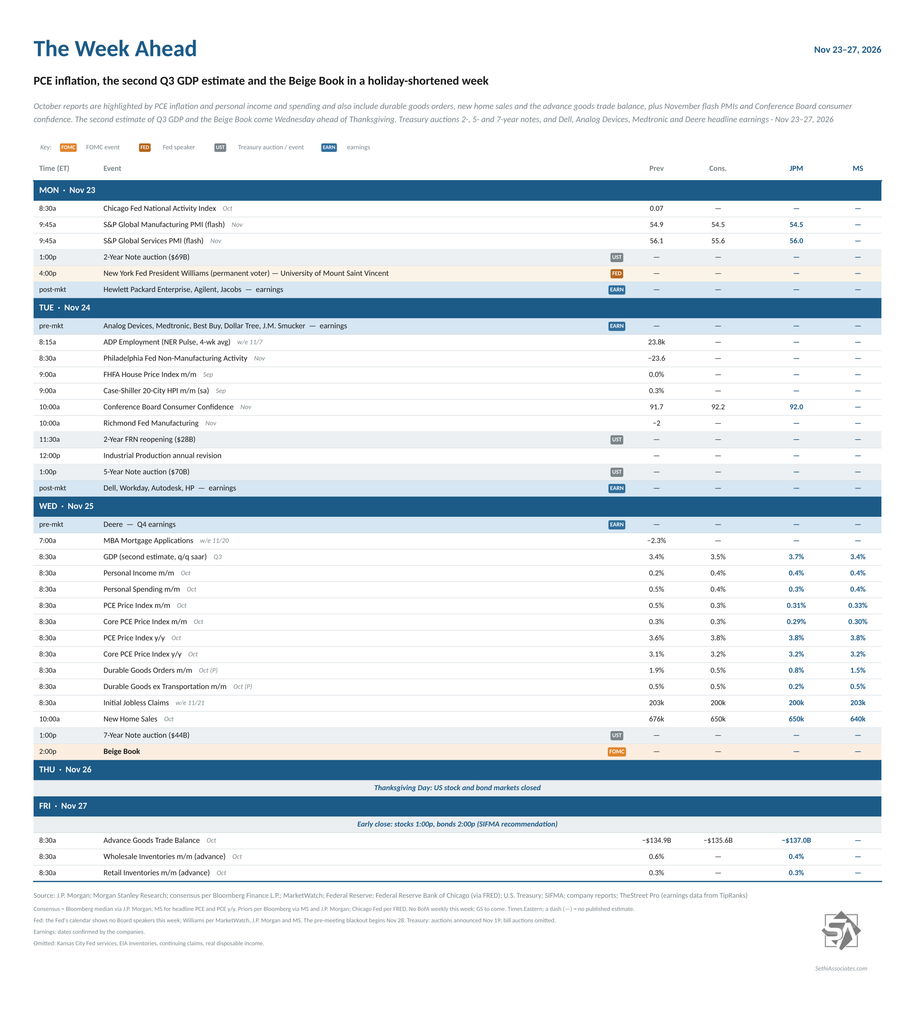
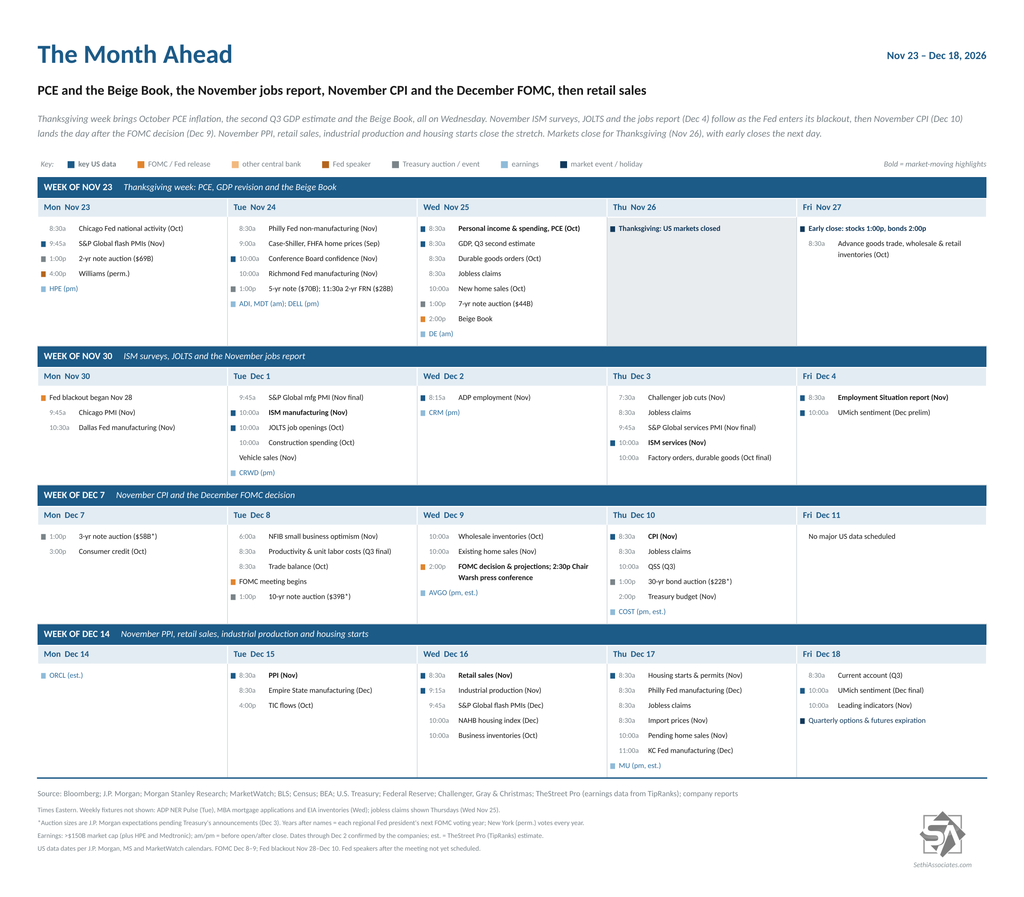
US economic reports are front-loaded ahead of Thursday’s Thanksgiving holiday, with the most notable all Wednesday, headlined by October’s personal income and spending report which includes core PCE inflation, the Fed’s preferred inflation metric. Bloomberg consensus is for core PCE to rise 0.3% m/m (3.2% y/y, from 3.1%) and headline 0.3% (3.8% y/y, from 3.6%). Personal income and spending are both expected to rise 0.4%. The second estimate of Q3 GDP is also Wednesday, with consensus at 3.5% (the advance estimate was 3.4%).
Other October reports include durable goods orders (consensus +0.5%), new home sales (650,000), the Chicago Fed National Activity Index, the advance goods trade balance, and advance retail and wholesale inventories. November reports include the S&P Global flash PMIs (consensus 54.5 for manufacturing and 55.6 for services), Conference Board consumer confidence (92.2, from 91.7), and the Richmond Fed and Philadelphia Fed non-manufacturing surveys. September reports include the FHFA and Case-Shiller home price indexes. We’ll also get the usual weekly reports, with jobless claims moving up to Wednesday (consensus 200,000), plus the Fed’s annual revision to industrial production Tuesday.
The Fed releases its Beige Book Wednesday afternoon, while New York Fed President Williams (permanent voter) speaks Monday at 4pm ET, the only scheduled Fed speaker. The blackout period begins at midnight Saturday ahead of the December 8–9 FOMC meeting.
Non-Bill (>1yr in maturity) US Treasury auctions include $69B of 2-year notes Monday, a $28B 2-year FRN reopening and $70B of 5-year notes Tuesday, and $44B of 7-year notes Wednesday, each a day ahead of the normal schedule due to the Thursday holiday.
US markets are closed Thursday for Thanksgiving, and Friday is a half day (stocks close at 1pm ET, bonds at 2pm ET).
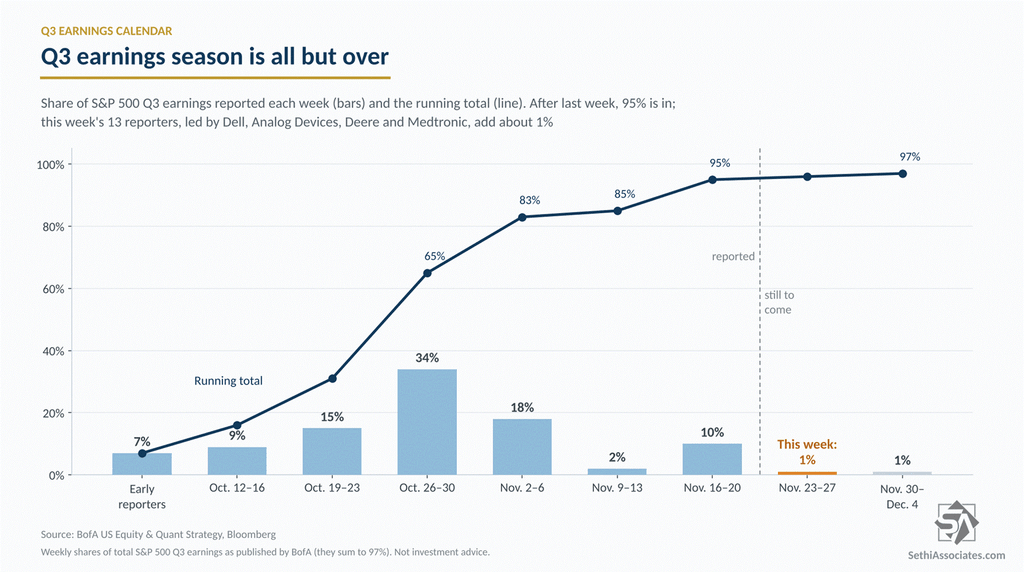
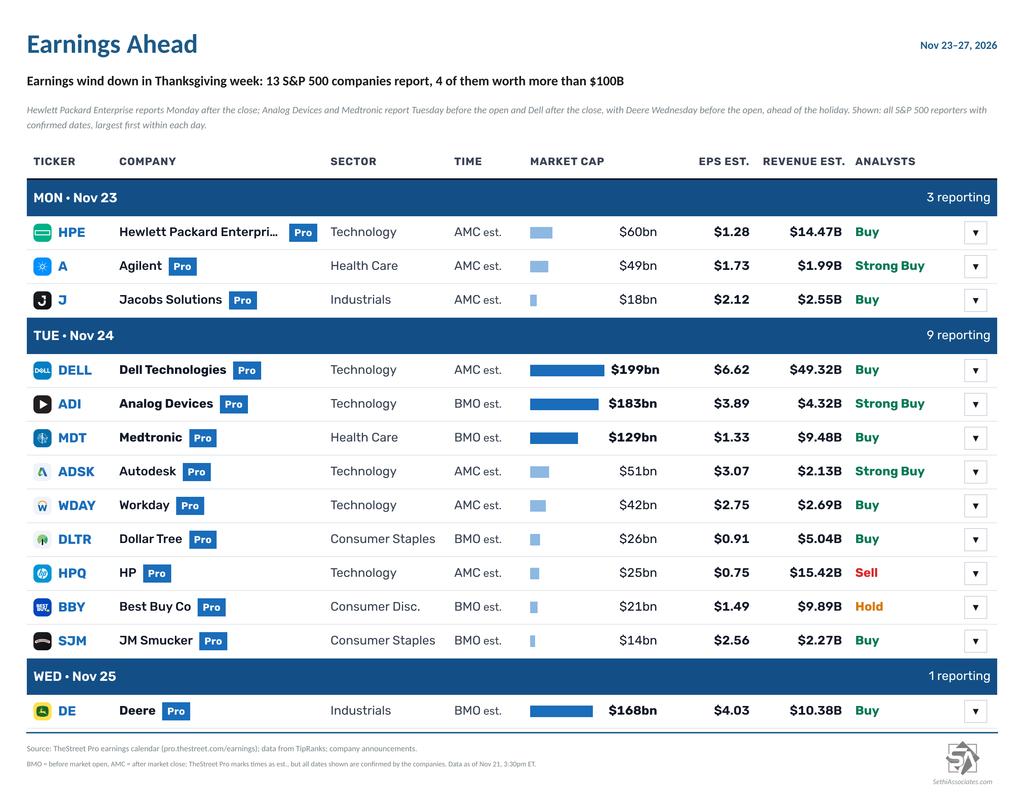
We’re now in the formal wind-down of Q3 earnings, with 13 S&P 500 components expected to report (1% of index earnings, according to BofA), four of them with market caps over $100B:
- Monday: Hewlett Packard Enterprise (HPE), Agilent (A) and Jacobs Solutions (J), all after the close.
- Tuesday: Medtronic (MDT), Analog Devices (ADI), Best Buy (BBY), Dollar Tree (DLTR) and J.M. Smucker (SJM) before the open; Dell (DELL), HP (HPQ), Autodesk (ADSK) and Workday (WDAY) after the close.
- Wednesday: Deere (DE) before the open.
- Outside the S&P 500, we’ll hear from Zoom (ZM) and Symbotic (SYM) Monday, and Dick’s (DKS), Burlington (BURL) and Abercrombie & Fitch (ANF) Tuesday.
Ex-US highlights from Deutsche Bank:
“In Europe, the focus will also be on preliminary November CPIs from France and Spain on Friday, with prints for Germany and the Eurozone due the week after next. Our European economists… forecast a 3.53% YoY HICP reading for France and 4.57% for Spain. From the ECB, there will be the account of the October meeting (Thursday) and the October consumer expectations survey (Friday). Rounding out the European calendar, in Germany, sentiment indicators due include the November Ifo survey (Tuesday) and December GfK consumer confidence (Thursday)…
“Inflation releases are also due in Asia, including Japan’s November Tokyo CPI (Friday) and Australia’s October CPI (Wednesday…). For the former, our Chief Japan economist sees an acceleration in both the core index to 2.9% YoY (2.6% in October) and the core-core index to 2.7% YoY (2.6%)… Elsewhere in the region, China’s October industrial profits will be out Friday.”
Also, global flash PMIs come Monday.
- And here is a link to Bloomberg’s Week Ahead (gift link).
- And a link to Christophe Barraud’s international Week Ahead rundown.
- And a link to TipRanks’ Economic Calendar.
This post will go through in order (in case you want to skip around): the economy, the Fed and interest rates, earnings, valuations, positioning, breadth, sentiment, seasonality, and then my wrap-up.
Housing Is Weak, but the Consumer Keeps Spending
Looking first at the economy, my intro has remained the same since the start of the Iran conflict (and longer term, more or less all of the past five years – I’ve not had a recession probability above 40% since the pandemic): “we continue to see it weathering the various storms remarkably well due in large part to resilient consumption (boosted by huge increases in wealth over the past few years despite slowing incomes) and AI-spending… with data of late showing a stable (and perhaps accelerating) economy, but one that is also boosting inflation.”
Last week’s data was consistent with that. The consumer, the labor market and manufacturing held up (outside of a couple of regional Fed PMIs, which I don’t find particularly useful except in aggregate) and import prices kept running hot, but housing sales buckled under 7%+ mortgage rates::
- ADP’s weekly NER Pulse showed private employers adding 95,000 jobs in the four weeks ending October 31st, the most since the four weeks ending September 26th, and the four-week moving average rose for the first time in five weeks. That pace works out to roughly 103,000 a month, above the top of the St. Louis Fed’s 15,000–87,000 breakeven range, so the early-October soft patch now looks like a pause (ADP Weekly Hiring Jumps to Most Since September).
- October retail sales rose 0.21%, double the 0.1% estimate, despite a 1.60% drop at auto dealers. The control group, which feeds into GDP, rose 0.58%, the most since August, and September was revised higher across the board (October Retail Sales Beat Across the Board Despite Falling Auto Sales).
- October industrial production fell 0.4% as utilities and energy output dropped sharply, but manufacturing rose for a second month, driven by autos, to its highest level since March 2022 (What to Watch as Utilities and Energy Mask Solid Factory Output).
- Continuing jobless claims jumped 70,000 to 1.763 million, the biggest increase since January 2024, while initial claims remained subdued, rising just 1,000 to 203,000 and leaving the four-week average near the least since 1969. The caveat: Goldman attributes most of the jump in continuing claims to Michigan (Continuing Jobless Claims Jump by the Most Since January 2024, But Note the Caveat).
- Import prices rose 1.1% in October, well above the 0.7% expected, to an estimated 9.1% from a year ago, the most since June 2022. Computers and chips boosted nonfuel import prices, which rose the most from a year earlier since April 2022, and capital goods import prices rose 1.46%, “the largest advance since the index was first published on a monthly basis in December 1988,” led by a record 3.56% jump for computers, peripherals and semiconductors (Fuel and AI Hardware Boost Import Prices to 4-Year High).
- NAHB’s Housing Market Index fell to 25 in November, the lowest since April 2012, with all three components and all four regions also falling, while 46% of builders cut prices, the most since Covid (3 Things to Watch as Homebuilder Sentiment Sinks to Lowest Since April 2012).
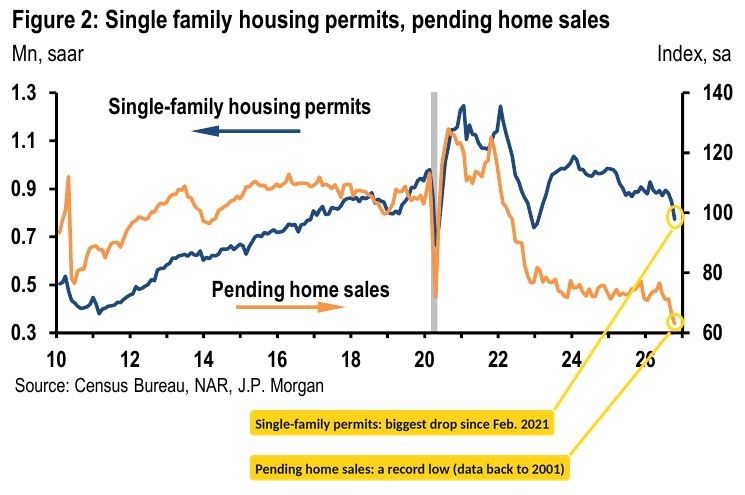
- Housing starts jumped 9.9% in October to 1.309 million, well above estimates, on a 25.5% rise in multifamily, but total building permits, a leading indicator, fell to the lowest since May 2020, with single-family permits dropping the most since February 2021 (What to Watch as Housing Starts Jump, but Total Permits Sink).
- Pending home sales (contract signings for existing homes) fell 4.7% in October, more than expected, to a new record low in data back to 2001, down 16.7% from a year earlier (Pending Home Sales Sink to Second Straight Record Low).
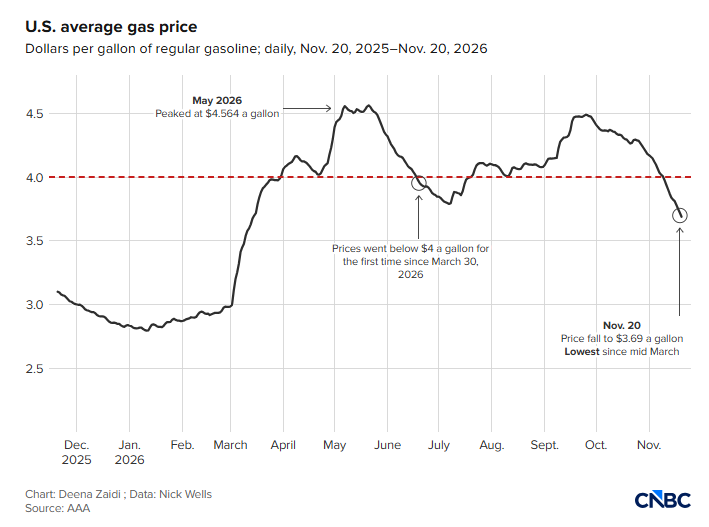
- Final November University of Michigan consumer sentiment was revised up to 51.5 from 51.0, the highest since August, as the midterms lifted expectations. Expectations swung by political party more than in any midterm in data back to 2006, surging for independents and Democrats and falling for Republicans to the lowest since October 2024 (Consumer Sentiment Gets a Post-Election Lift as Inflation Expectations Plunge). Meanwhile inflation expectations eased across the board. Gas prices should help further: AAA’s national average fell to $3.69 a gallon Friday, though that’s still about 59 cents above a year ago.
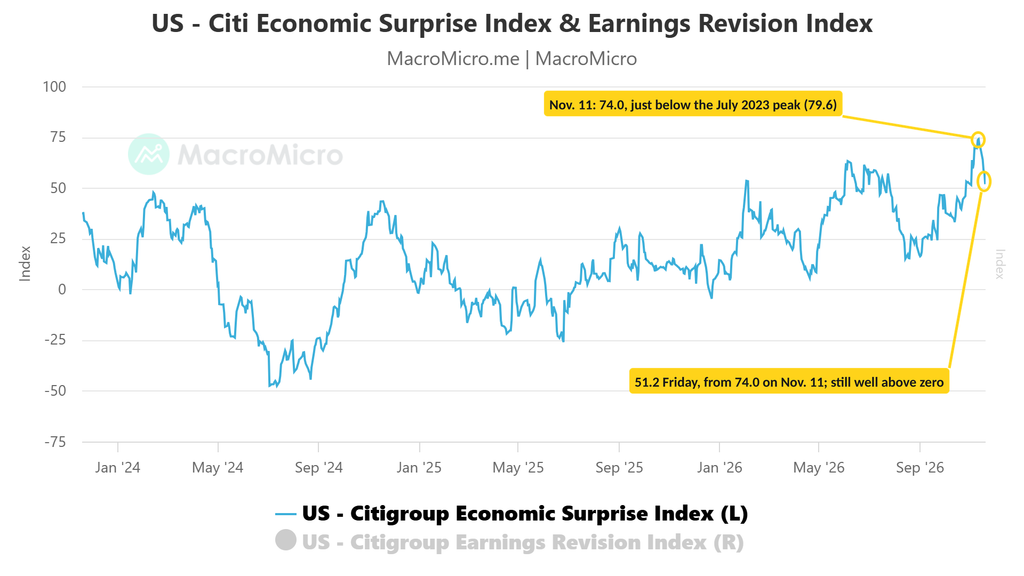
With housing and the Fed PMIs missing, the Citi US Economic Surprise Index fell to 51.2 Friday from 74.0 on November 11th (which was just below the July 2023 peak of 79.6), though it remains around the highest since 2023 prior to this most recent spike.
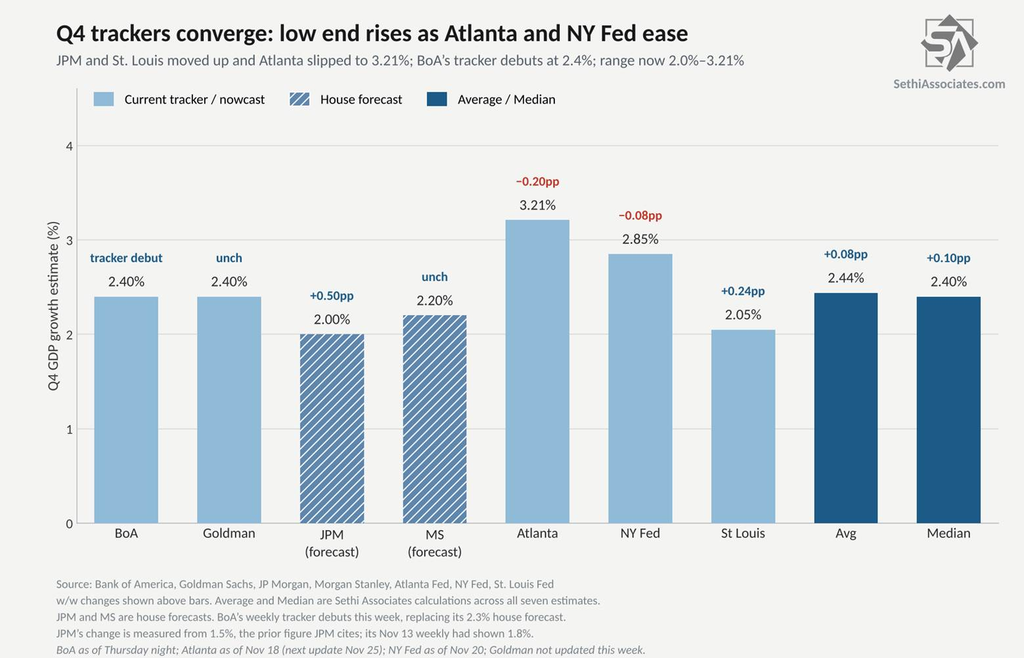
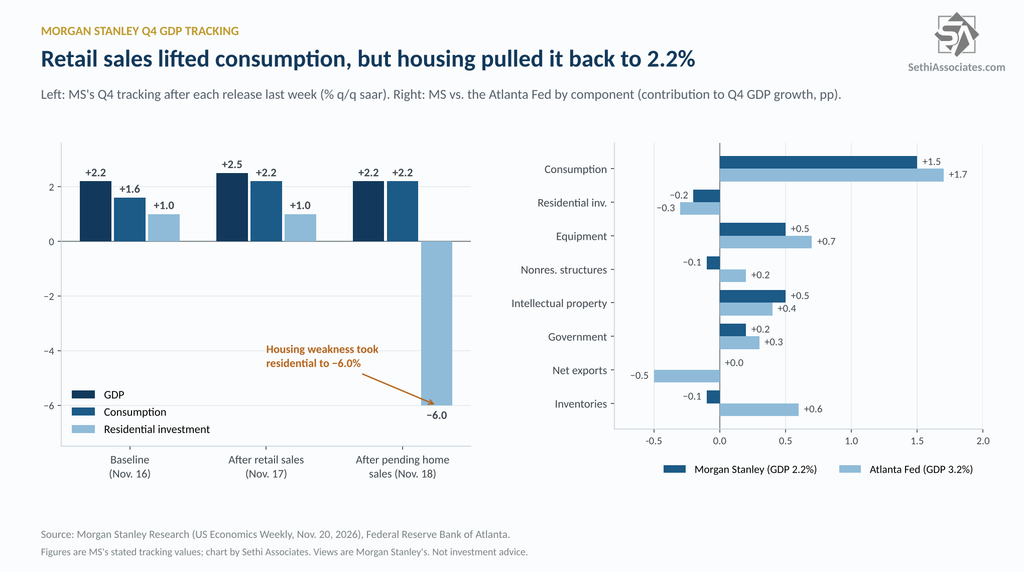
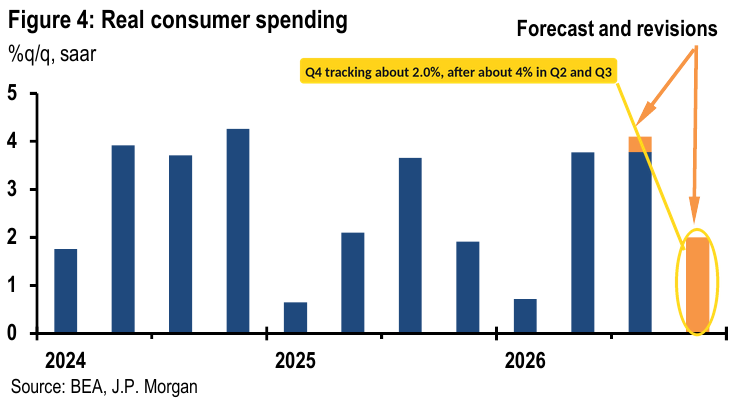
Looking at the Q4 GDP trackers, the Atlanta Fed’s GDPNow eased to 3.21% as of November 18th, from 3.41% on November 13th, with retail sales and industrial production trimming it Tuesday and housing starts Wednesday (its next update is Wednesday, November 25th). The NY Fed’s Nowcast edged down to 2.85% from 2.93%. JPM raised its forecast to 2.0% “on the back of better-than-expected consumer spending,” while Morgan Stanley’s tracking is unchanged at 2.2%, as the boost from retail sales was offset by weaker housing. BofA’s new weekly tracker debuted at 2.4% (replacing its 2.3% house forecast), Goldman’s was unchanged at 2.4% (after raising it from 1.8% on retail sales Tuesday), and the St. Louis Fed’s rose to 2.05% from 1.81%. Across the seven, the average rose to 2.44% from a revised 2.36% last week (we published 2.34%), and the median to 2.40% from 2.30%.
Morgan Stanley: “Strong retail sales (and upward revision) bumped up our consumption tracking, while new weakness in housing pulled residential investment sharply lower. For consumption, holiday spending — the November and December retail spending — will be the more important driver of 4Q growth. For residential investment, tighter monetary policy appears to be further slowing the housing sector.”
JPM: October retail sales “bucked expectations for a pause,” leaving “our early tracking of 4Q real annualized consumer spending growth at 2.0%, a good outcome, albeit slower than the boomy 3.75-4.0% pace seen in the middle two quarters of the year. The housing market is doing less well, with mortgage rates exerting a drag both on new homebuilding and sales of existing homes.”
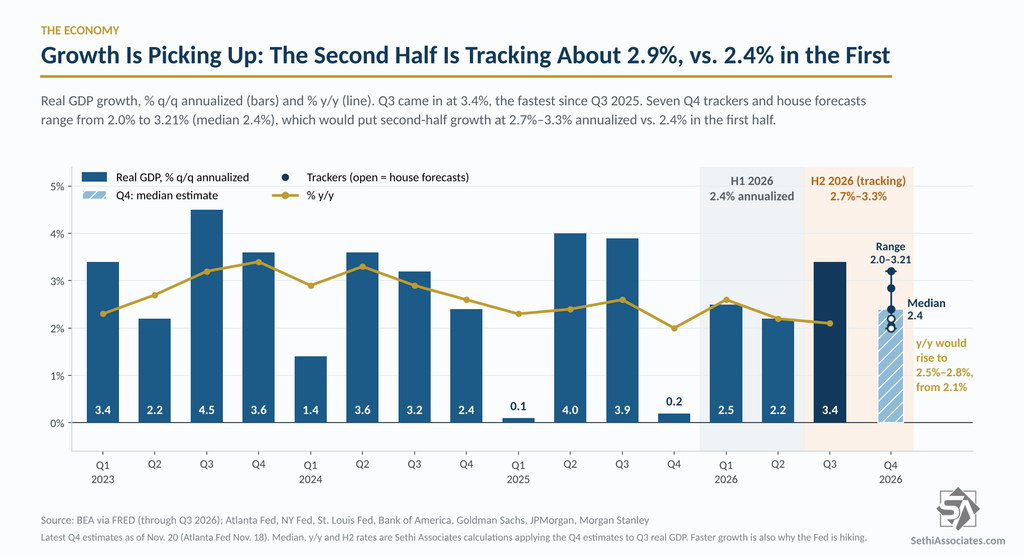
Still, growth seems to be picking up from the first half. Q3 grew 3.4%, and the seven trackers I follow have Q4 at a median of 2.4% (average 2.44%), in a range of 2.0% to 3.21%. That would put second-half growth at a 2.7%–3.3% annualized rate (about 2.9% at the median), vs. 2.4% in the first half, lifting y/y growth to 2.5%–2.8% from 2.1%. The flip side is that it’s also why the Fed is hiking.
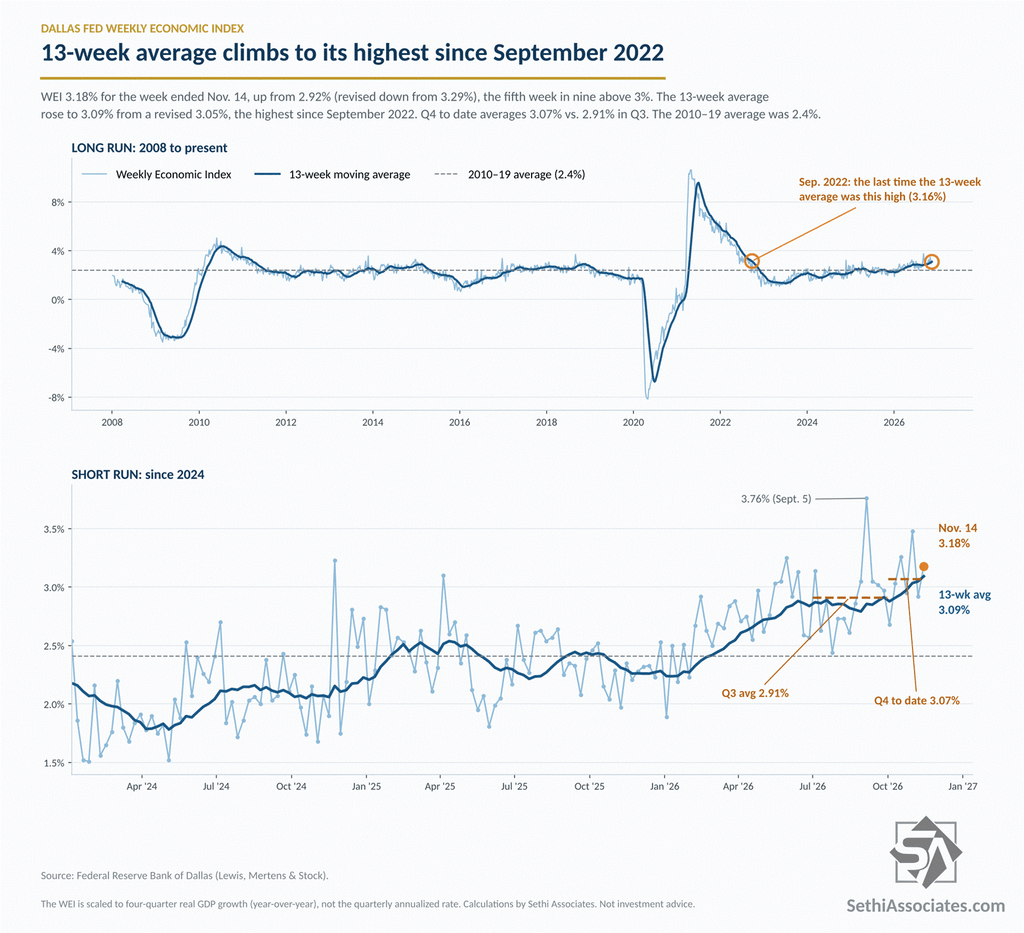
Meanwhile, the Dallas Fed Weekly Economic Index (WEI)* rose to 3.18% in the week through November 14th (so it doesn’t include last week’s data), from 2.92% the prior week (revised down from 3.29%), the fifth week in nine over 3%.
The 13-week average rose further to 3.09% (from a revised 3.05%), its highest since September 2022, continuing to evidence economic momentum that is well above trend (the 2010–19 average was 2.4%). For Q4 to date it’s averaging +3.07% y/y, which would be the strongest y/y GDP growth since Q2 2024 (3.3%), although with only seven weeks in, that would imply an aggressive ~4.2% Q/Q SAAR, so treat it with caution.
*The WEI is scaled as a y/y rise for real GDP (so different from most GDP trackers, which are Q/Q SAAR), uses 10 daily and weekly economic series and runs a week behind other GDP trackers.
It has over time tracked actual GDP closely (a 0.92 correlation since 2008, see chart), although the last two quarters it has come in high, predicting +2.91% y/y GDP growth in Q3 vs the actual first estimate of +2.07% and for Q2 +2.84% vs +2.19%. More importantly, though, it has consistently indicated no recession and relatively healthy growth since the pandemic (which is what we’ve experienced), never dipping below +1% since 2021.
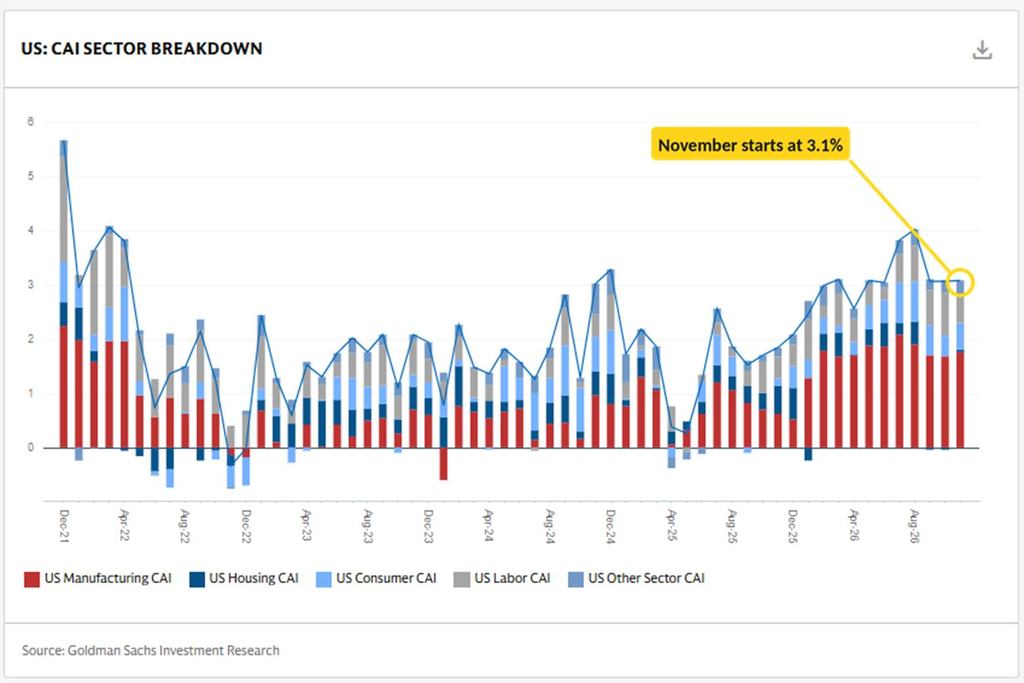
Goldman’s Current Activity Indicator* started November at 3.1%, while October was revised down to 3.1% as well (from 3.2%), matching September. That’s a step down from late summer, when July (3.8%) and August (4.0%) were the strongest since 2022. Manufacturing remains the biggest contributor, at 1.8 points.
*The CAI is their “real-time measure of inflation-adjusted economic momentum using 37 inputs.”
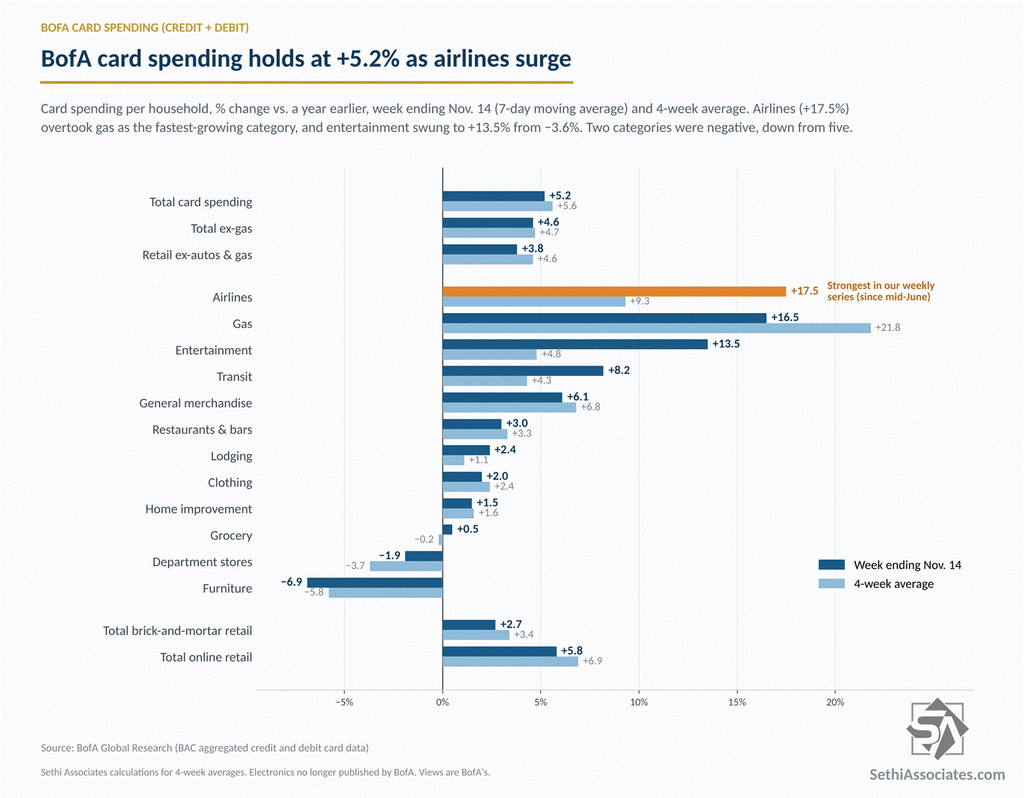
BofA card spending (credit+debit) edged up to +5.2% versus the year-ago period (y/y) in the week ending November 14th, versus +5.1% the prior week, as BofA pointed to acceleration in entertainment and airline spending. Goods spending softened, though: ex-gasoline and autos spending growth eased to +3.8% y/y from +4.1%.
- Total +5.2% y/y (+5.6% four-week moving average).
- Ex-gasoline +4.6% y/y (+4.7% four-week moving average).
- Ex-autos and gasoline +3.8% y/y (+4.6% four-week moving average).
Gasoline saw the largest slowdown, cooling to +16.5% y/y from +20.2%, its lowest reading since mid-July. On the income split, BofA again noted that lower-income spending growth has consistently outpaced higher-income over the past several weeks.
Among categories, airlines jumped to +17.5% from +4.1%, their strongest reading since at least mid-June, and overtook gas as the fastest-growing category. Entertainment saw the largest week-over-week increase, swinging to +13.5% from −3.6%, and transit rose to +8.2% from +4.2%. Lodging (+2.4%), home improvement (+1.5%) and grocery (+0.5%) all improved, the latter two moving back into positive territory. General merchandise eased to +6.1% from +8.4% and clothing to +2.0% from +2.9%, while online retail was little changed at +5.8%.
Two categories were negative y/y, down from five the prior week: furniture (−6.9%, unchanged) and department stores (−1.9%, improved from −2.5%).
Redbook sales* were more robust, up 9.5% y/y in the week ending November 14th, down from 10.1% the prior week and the lowest in three weeks, but a sixth straight week at 9% or more and well above the 6.1% of a year earlier.
*Redbook sales are same-store sales across a panel of large general-merchandise retailers, such as department stores, discount chains, apparel retailers, drugstores, and warehouse clubs.

Fed Speakers Stay Hawkish, but Hike Bets Ease Anyway
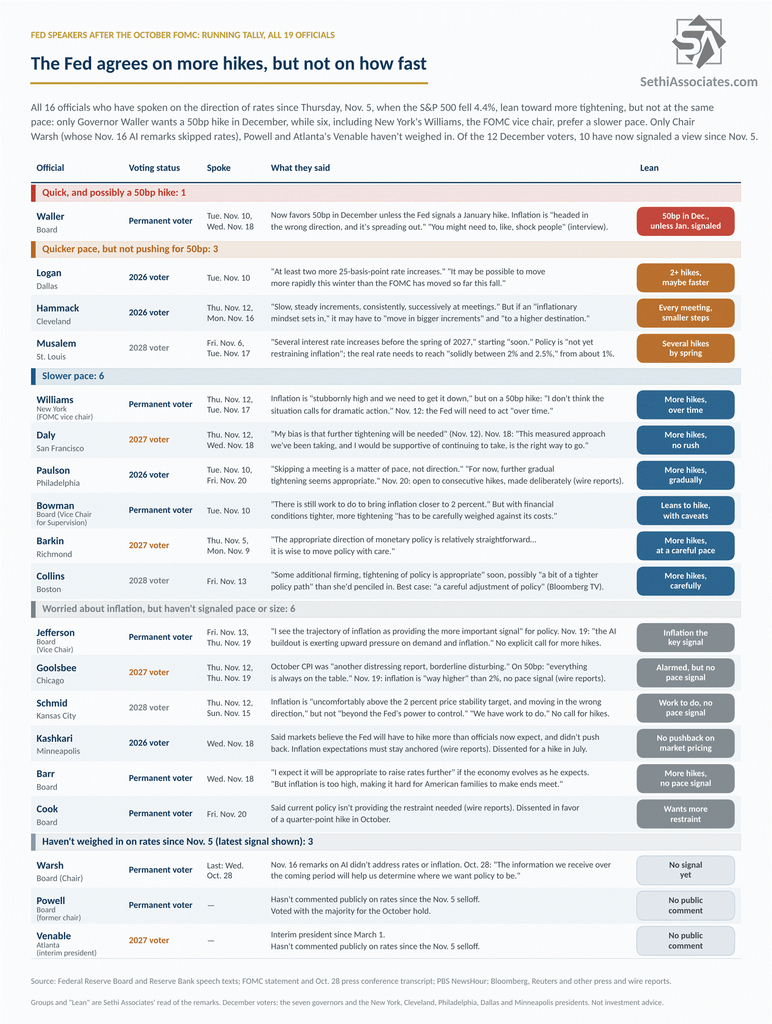
Fedspeak stayed hawkish last week even as stocks slid. Governor Waller expanded on his thinking about a 50 basis point hike from the week before, saying that unless the Fed hikes 25 basis points in December and clearly signals a January hike, it should go 50bp in December: “You might need to, like, shock people,” he said in an interview (see Fed’s Waller: ‘You Might Need to, Like, Shock People’). St. Louis’ Musalem (a 2028 voter) gave the most aggressive guidance yet: “several interest rate increases before the spring of 2027,” starting “soon.” He also said he was “not overly concerned” by the tightening in financial conditions (see Fed’s Musalem Wants ‘Several’ Hikes Before Spring, but Note His Record). But the leadership pushed back on a bigger move. New York’s Williams, the FOMC vice chair, said “I don’t think the situation calls for dramatic action,” although if AI-driven spending continues, “we may need to raise rates more.” San Francisco’s Daly backed “this measured approach.”
Governor Barr said “I expect it will be appropriate to raise rates further.” Governor Cook, who dissented for a hike in October, said current policy isn’t providing the restraint needed. Minneapolis’ Kashkari noted markets expect more hikes than officials do and didn’t push back. All will vote in December. Chair Warsh’s Monday remarks on AI and productivity skipped rates, while Vice Chair Jefferson said “the AI buildout is exerting upward pressure on demand and inflation.”
By my count, 16 of the 19 FOMC participants have now signaled more tightening ahead. Waller alone is calling for 50bp in December, although the minutes show at least one other participant saying it should be under consideration (perhaps Musalem). And since Waller seems fine with 25bp in both December and January, that puts him in line with Logan, Hammack and Musalem, who all want a quicker pace. On the other side, Williams, Daly, Paulson, Bowman, Barkin and Collins have said they prefer a slower one. Jefferson, Goolsbee, Schmid, Kashkari, Barr and Cook are worried about inflation without signaling pace. Only Warsh, Powell and Atlanta’s Venable (acting president until a successor to the now-retired Bostic is selected) haven’t weighed in, and 10 of the 12 December voters have now signaled a view. BofA counts more Fedspeak in the past two weeks than in any two-week stretch since the start of last year.

The minutes from the October 27–28 meeting further confirmed the hold was a pause, not a pivot. “Almost all participants” saw further hikes as likely appropriate (up from “most” in September), “some” favored a 25bp hike at the meeting (so more than the two dissenters, Governor Cook and Cleveland’s Hammack), and “a couple” said more than 25bp “could warrant consideration” in December “if incoming inflation data were unfavorable,” which October’s core CPI was. “Most” said inflation pressures were “broad based,” “almost all” discussed the risk of disappointing returns on AI investment, and no participant discussed a rate cut (see Fed Minutes: ‘Almost All’ See More Hikes, and ‘a Couple’ Floated a Bigger Move).
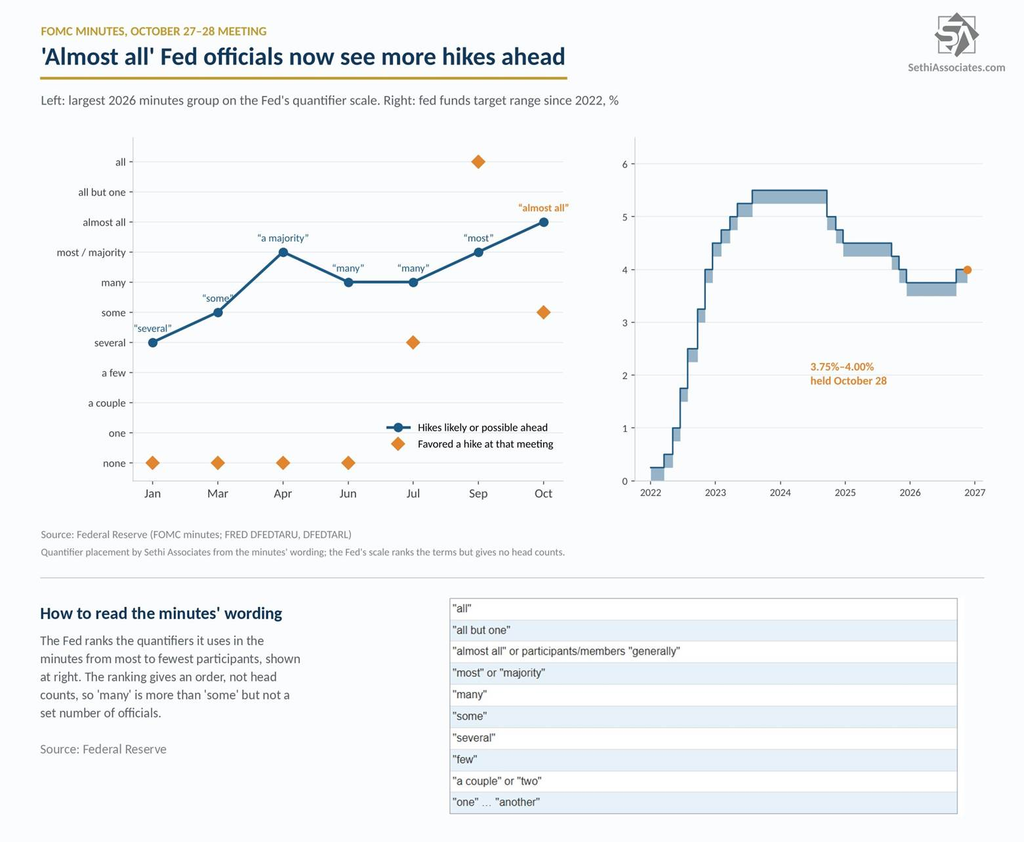
JPM says two strong messages came across: “First, the Committee is very strongly inclined to hike at the December FOMC meeting. The messaging was so strong it left one to wonder why they didn’t just go ahead and hike last month. Second, the caucus for hiking 50bp next month is small, only a ‘couple,’ presumably Waller and some other unnamed and unknown hawk.” Morgan Stanley notes the minutes cited tighter financial conditions as one reason for October’s hold.
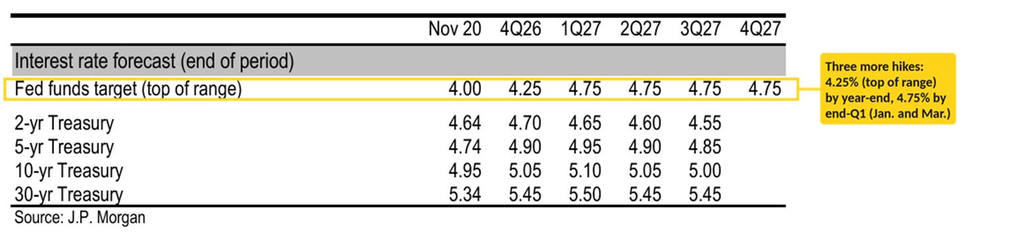
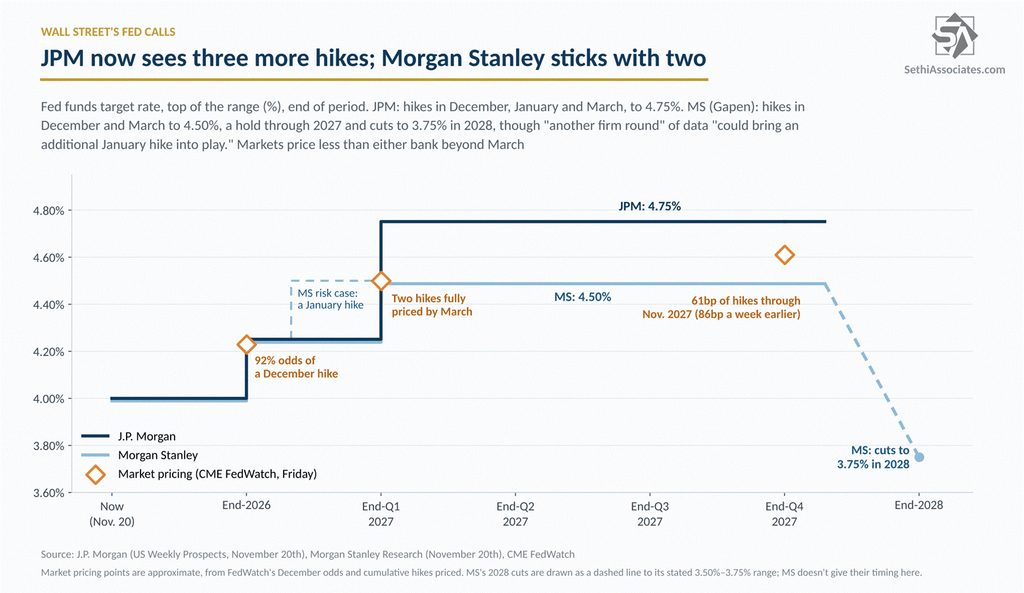
JPM, which released its 2027 outlook last week, now expects three more rate hikes, in December, January and March. “Our forecast now incorporates consecutive moves at the three upcoming meetings,” taking the top of the fed funds range to 4.25% by year-end and 4.75% by the end of Q1, where it stays through 2027. “While the Fed doesn’t see overheating in the economy, they will be sensitive to concerns about their inflation-fighting credibility.” Its global team adds that “at the December FOMC meeting, we expect the median voter to project rates to move beyond 4.5%.”
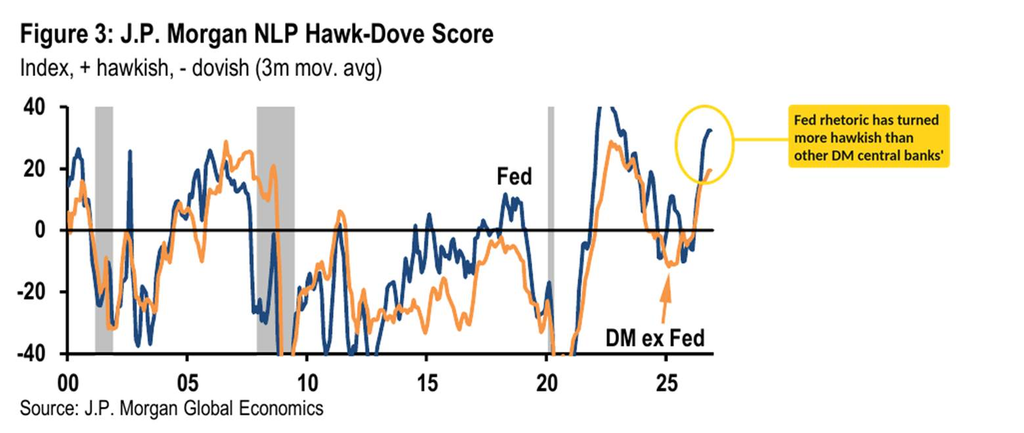
JPM’s language-based Hawk-Dove score shows how fast the tone has changed: “The hawkish shift in Fed rhetoric in recent weeks is dramatic and has recently moved beyond the signal sent by other DM central banks.”
Morgan Stanley’s Michael Gapen is sticking with 25bp hikes in December and March, then a hold through 2027 before easing in 2028, “although another firm round of employment and inflation data could bring an additional January hike into play.” A 50bp December move “faces a high bar, requiring renewed oil price pressures and clear evidence of broader labor market overheating.” It sees core PCE inflation ending this year at 3.2%, 2.6% in 2027 and 2.2% in 2028. MS notes most officials favor a gradual pace, with Williams rejecting the need for “dramatic action,” and says “tighter financial conditions appear to be an important reason for this caution.”
That leaves JPM a hike above Morgan Stanley, at 4.75% vs. 4.50% for the top of the range, and both above market pricing after March.
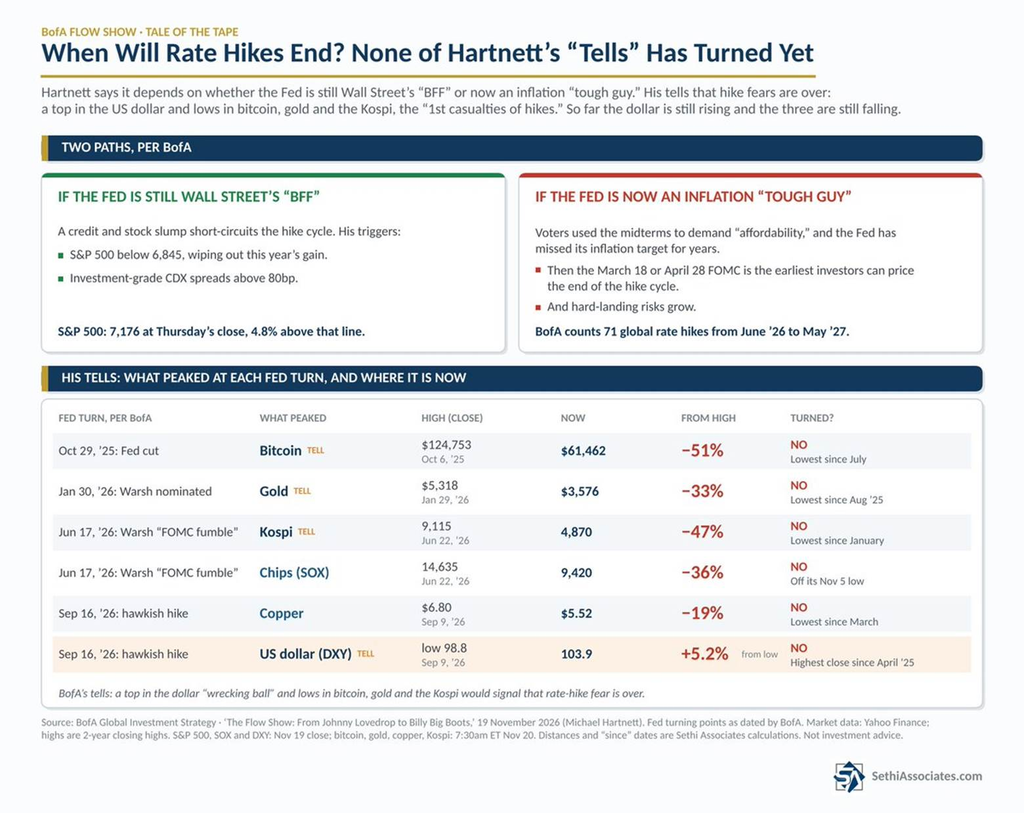
BofA’s Hartnett asks “when will rate hikes end?” If the Fed is still Wall Street’s “BFF,” a credit and stock slump will short-circuit the hike cycle, with his triggers an S&P 500 below 6,845 (wiping out this year’s gain, but now just 1% below Friday’s close) or investment-grade CDX spreads above 80bp. If the Fed is now an inflation “tough guy,” the March 18th or April 28th FOMC is the earliest markets can position for “peak rates,” and hard-landing risks grow. His tells that hike fears are over are a top in the US dollar “wrecking ball” and lows in bitcoin, gold and the Kospi, the “1st casualties of hikes.” None had turned as of Thursday.
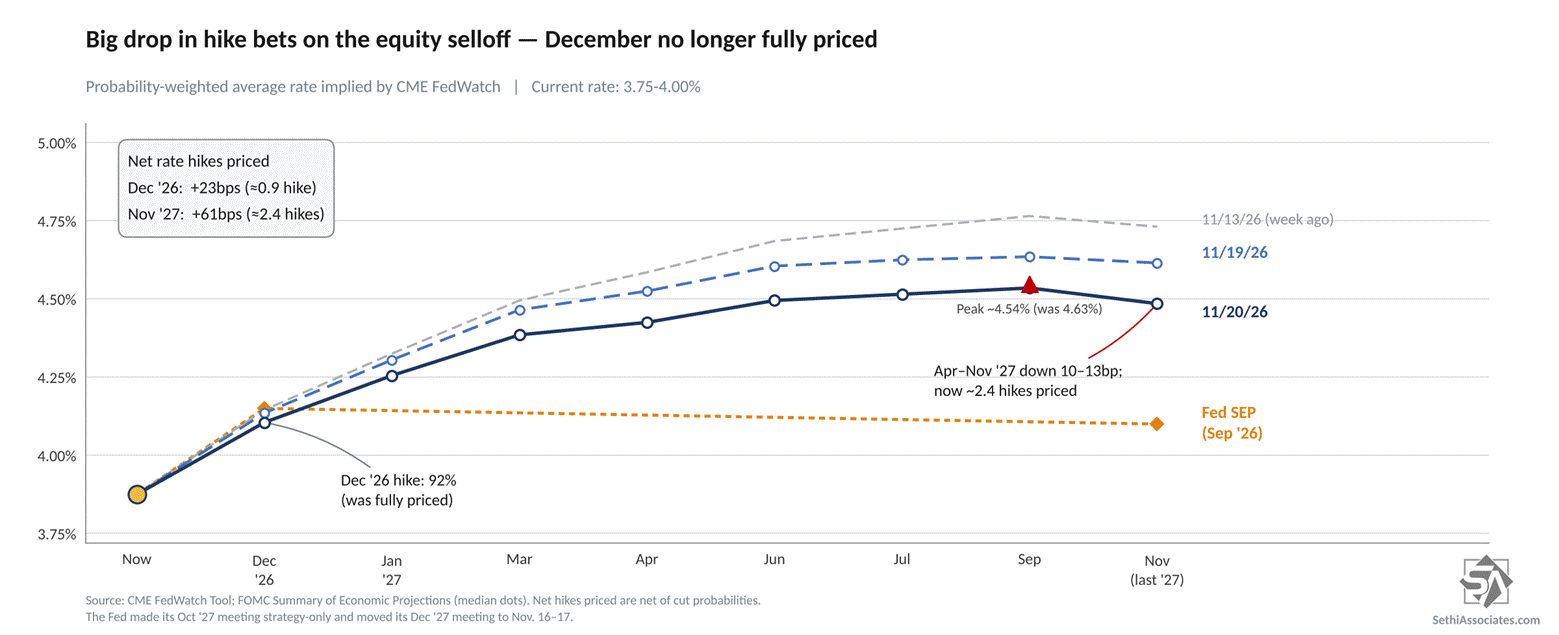
Despite the continued hawkish rhetoric, rate-hike bets fell sharply last week with the equity selloff. A December hike is no longer fully priced, at 92% on CME FedWatch (with a 0% chance of a 50bp hike and an 8% chance of a hold), although two hikes are still fully priced by March. Markets now price 61 basis points of hikes through the Fed’s final 2027 meeting in November, nearly two and a half hikes, down from 74bp Thursday and 86bp a week earlier.
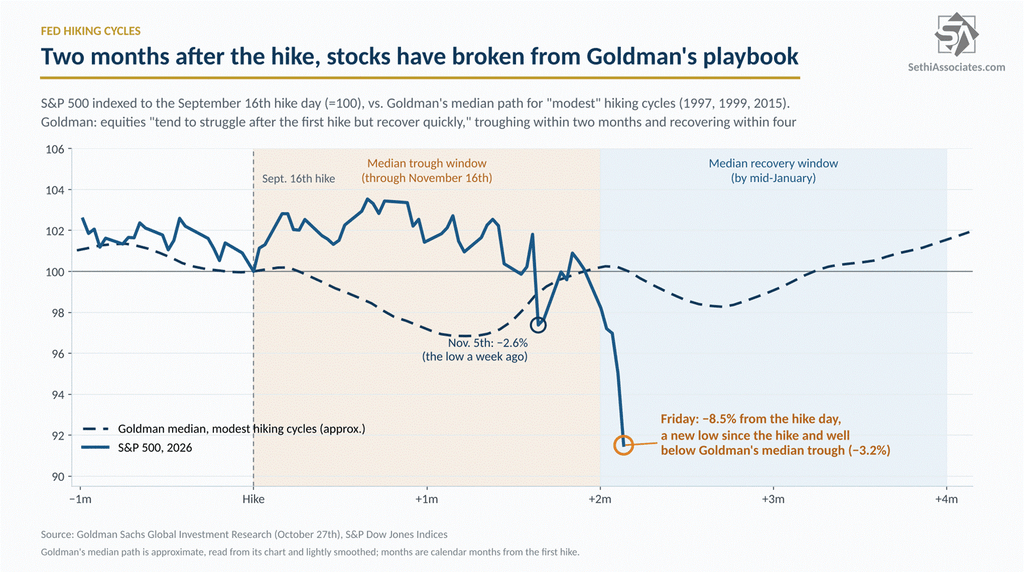
As a reminder, Goldman said that after a first rate hike in a “modest” hiking cycle, equities “tend to struggle after the first hike but recover quickly,” with the median trough within two months. That pattern has now broken. Monday marked two months since the September 16th hike, and by Friday the S&P 500 had closed 8.5% below its hike-day close, a new low since the hike and well below the roughly 3% median trough in Goldman’s study. The risk Goldman flagged was a 1999-style cycle, with the Fed hiking into an investment boom with strong growth and high valuations. With markets only expecting two to three more hikes, it seems hard to say the Fed is responsible for the selloff given the historical pattern.
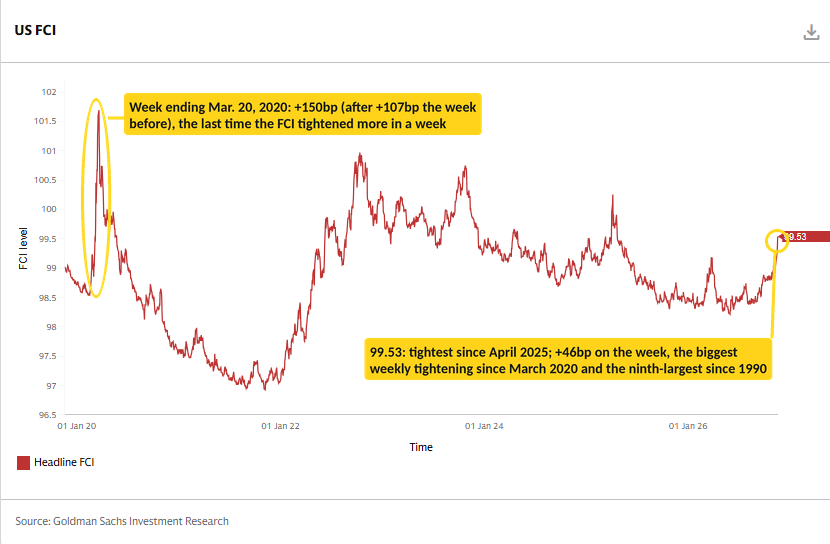
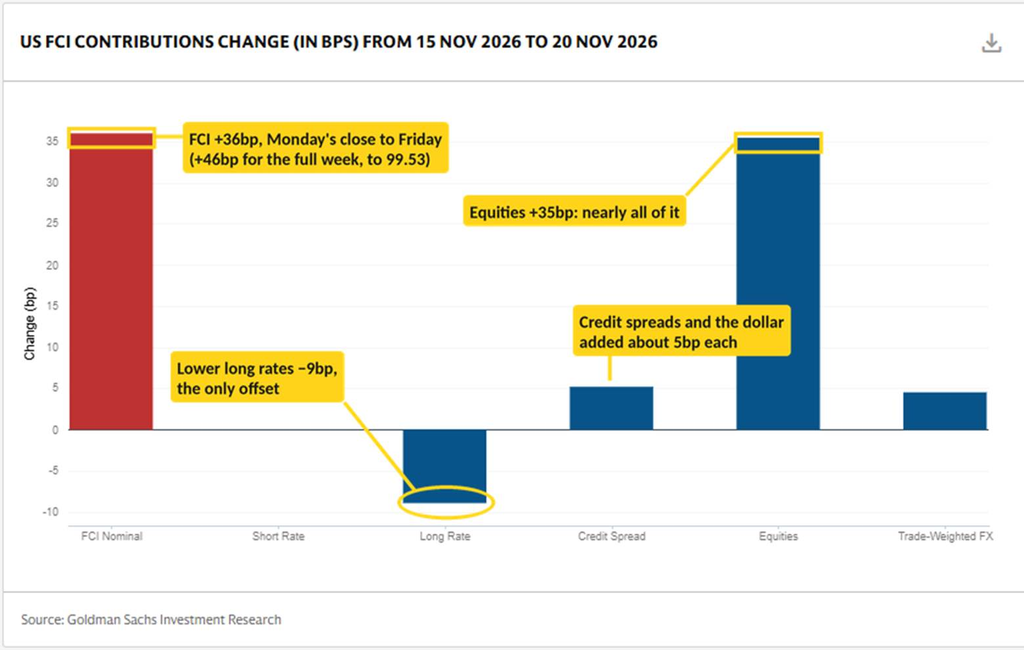
And with the equity selloff financial conditions are tightening sharply. Goldman’s US Financial Conditions Index tightened 46bp on the week to 99.53, the biggest weekly tightening since March 2020 and the ninth-largest since 1990, leaving it the tightest since April 2025. It has now tightened 78bp since the S&P 500’s October 6th record. From Monday’s close through Friday, equities added about 35bp of tightening, credit spreads and the dollar about 5bp each, and lower long-term yields offset about 9bp.
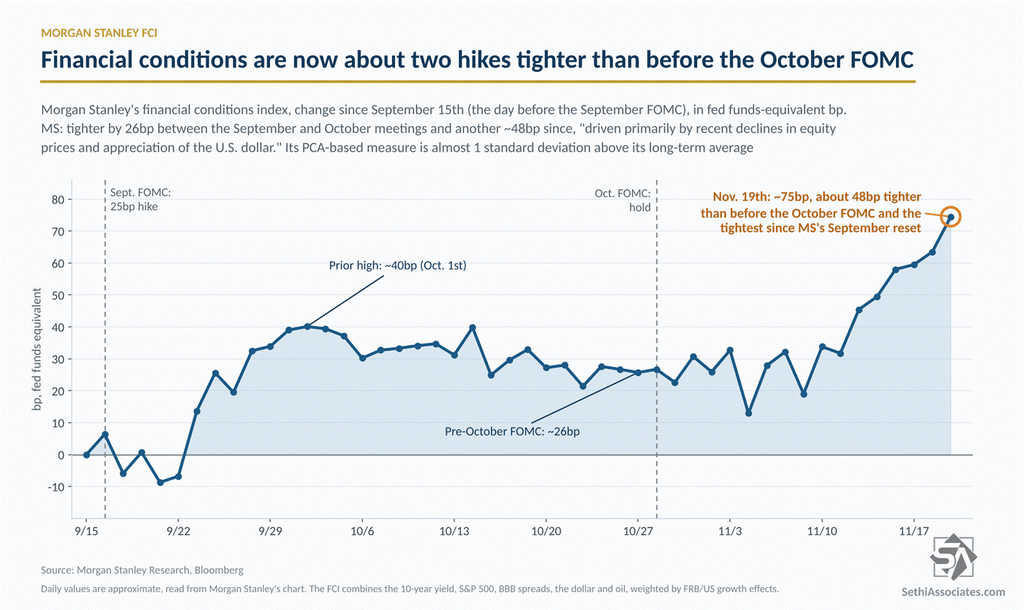
And MS says that as of Thursday’s close its financial conditions index showed conditions “about two hikes tighter” than before the October meeting (about 48bp), “driven primarily by recent declines in equity prices and appreciation of the U.S. dollar.”
Its second gauge, a statistical composite of financial variables (its “PCA-based measure”) scored against history, is “almost 1 standard deviation” above its long-term average (0.86 a week earlier), meaning conditions are notably tighter than normal. As MS puts it, “financial conditions have tightened but remain moderately restrictive.”
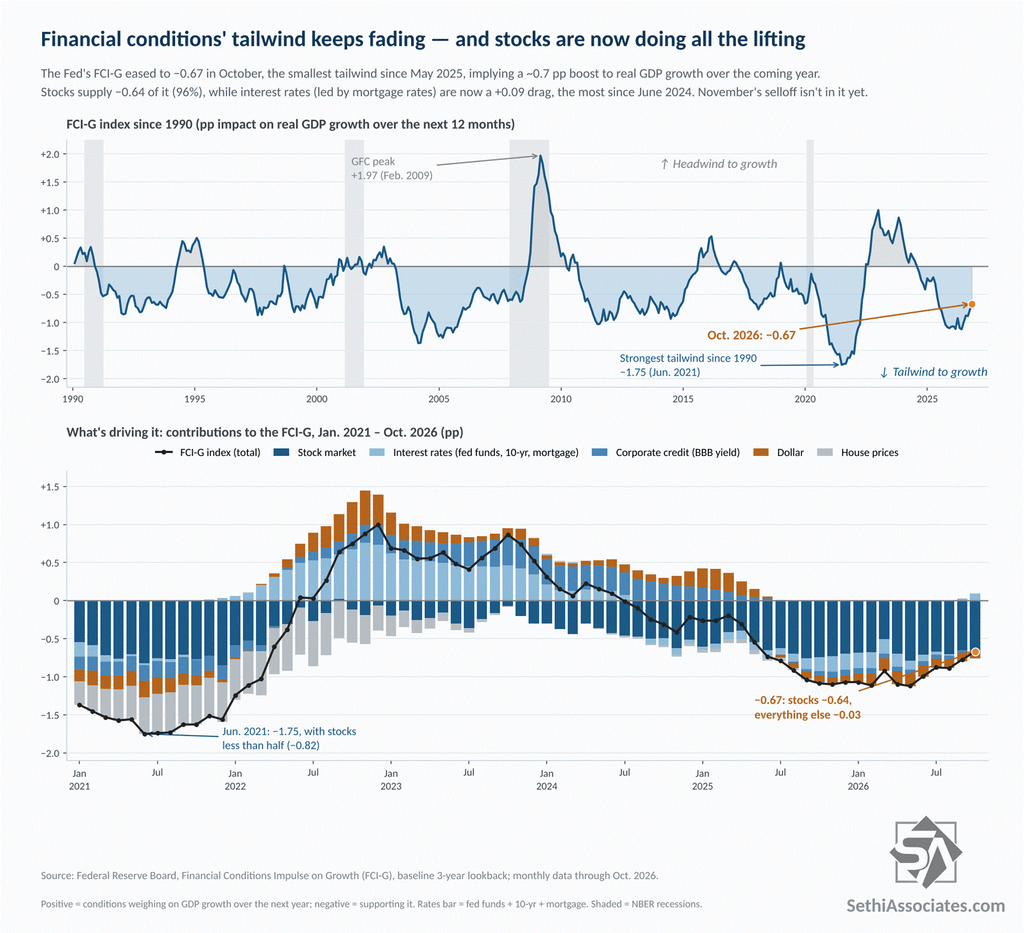
This brings me back to an analysis I did previously on the Fed’s own financial conditions index which, if you recall, shows how much of the remaining support depends on stocks. In October the Fed’s Financial Conditions Impulse on Growth (FCI-G) eased to −0.67 (from −0.78), the smallest tailwind since May 2025, and stocks now supply −0.64 of it, or 96%. But everything outside equities nets to just −0.03, and interest rates have turned into a +0.09 drag, the most since June 2024, led by mortgage rates (+0.12).
At the June 2021 extreme, by contrast, the index pointed to a 1.75-point boost to growth, with stocks supplying less than half (−0.82) and house prices (−0.48), the dollar (−0.22) and corporate borrowing costs (−0.20) doing much of the rest. With the S&P 500 down 8.8% in November, the equity component is tightening significantly, and as I noted when the September data came out, with stocks carrying nearly all of what’s left, this measure can move quickly from accommodative to tight.
And while Fed speakers haven’t mentioned the equity selloff, the minutes and some speakers (Bowman in particular) have mentioned tighter financial conditions as a reason for October’s hold.
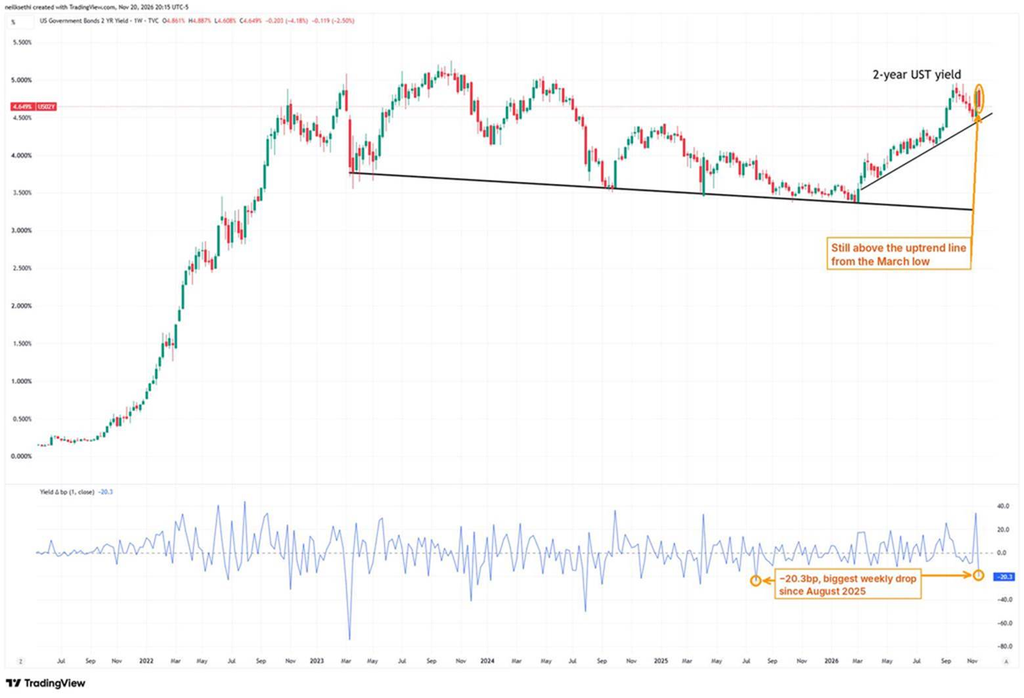
Turning to rates, Treasuries rallied as stocks fell. The 2-year yield fell 20.3bp on the week to 4.65%, its biggest weekly drop since August 2025, though it remains above the uptrend line from the March low and about 77bp above the midpoint of the fed funds range.
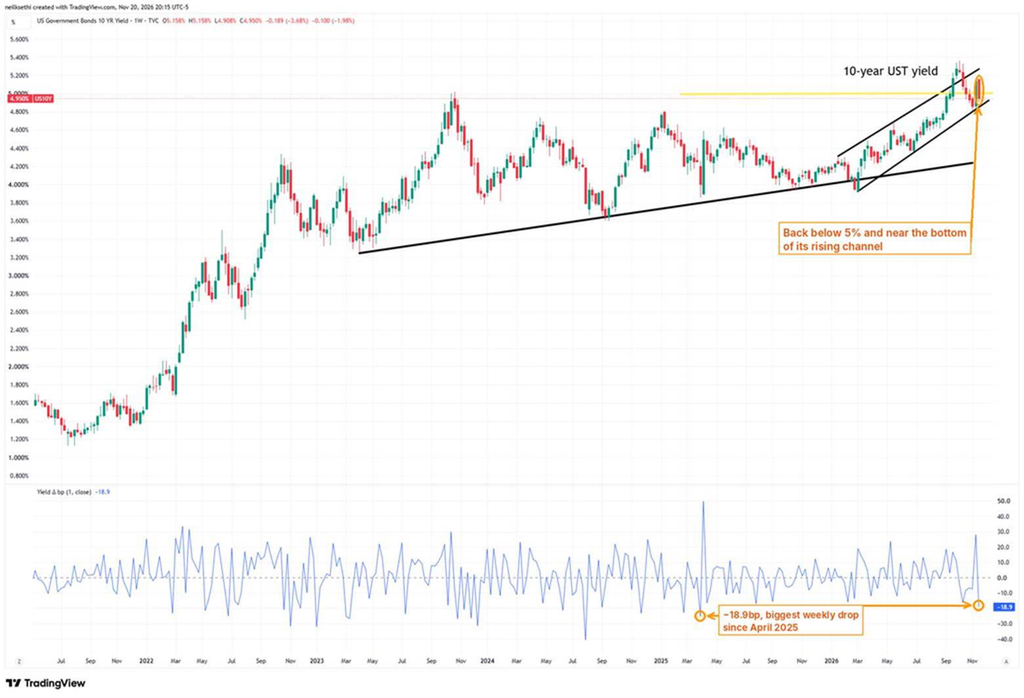
The 10-year fell 18.9bp to 4.95%, its biggest weekly drop since April 2025, back below 5% and near the bottom of its rising channel. BMO’s Ian Lyngen called the break below 5% “not an especially meaningful technical event” and sees resistance near 4.90%, the bottom of the channel. The 30-year fell to 5.34%, and the curve steepened slightly, with 2s10s at 29bp from 27bp (Treasury closing yields).
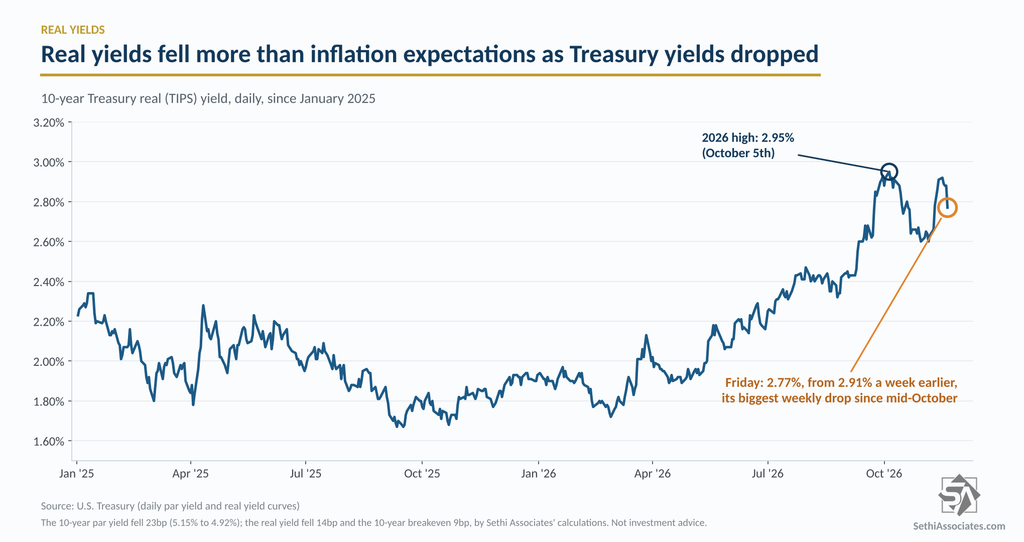
Underneath the drop in yields, both real yields and inflation expectations fell. The 5-year, 5-year forward breakeven (the market’s expectation for average inflation over the five years starting in 2031, a measure the Fed watches closely) ended the week at 2.12%, down from 2.18% a week earlier, after touching 2.10% Thursday, its lowest since early April, and well below its 2026 high of 2.36% on September 23rd. Shorter-run expectations fell more, with the 5-year breakeven down 12bp to 2.18%, its lowest since August 5th, and the 10-year breakeven down 9bp to 2.15%, its lowest since September 2024. The 5-year is still above the 5y5y, so the market still sees the current inflation bump fading, but the gap narrowed to 6bp from 12bp.
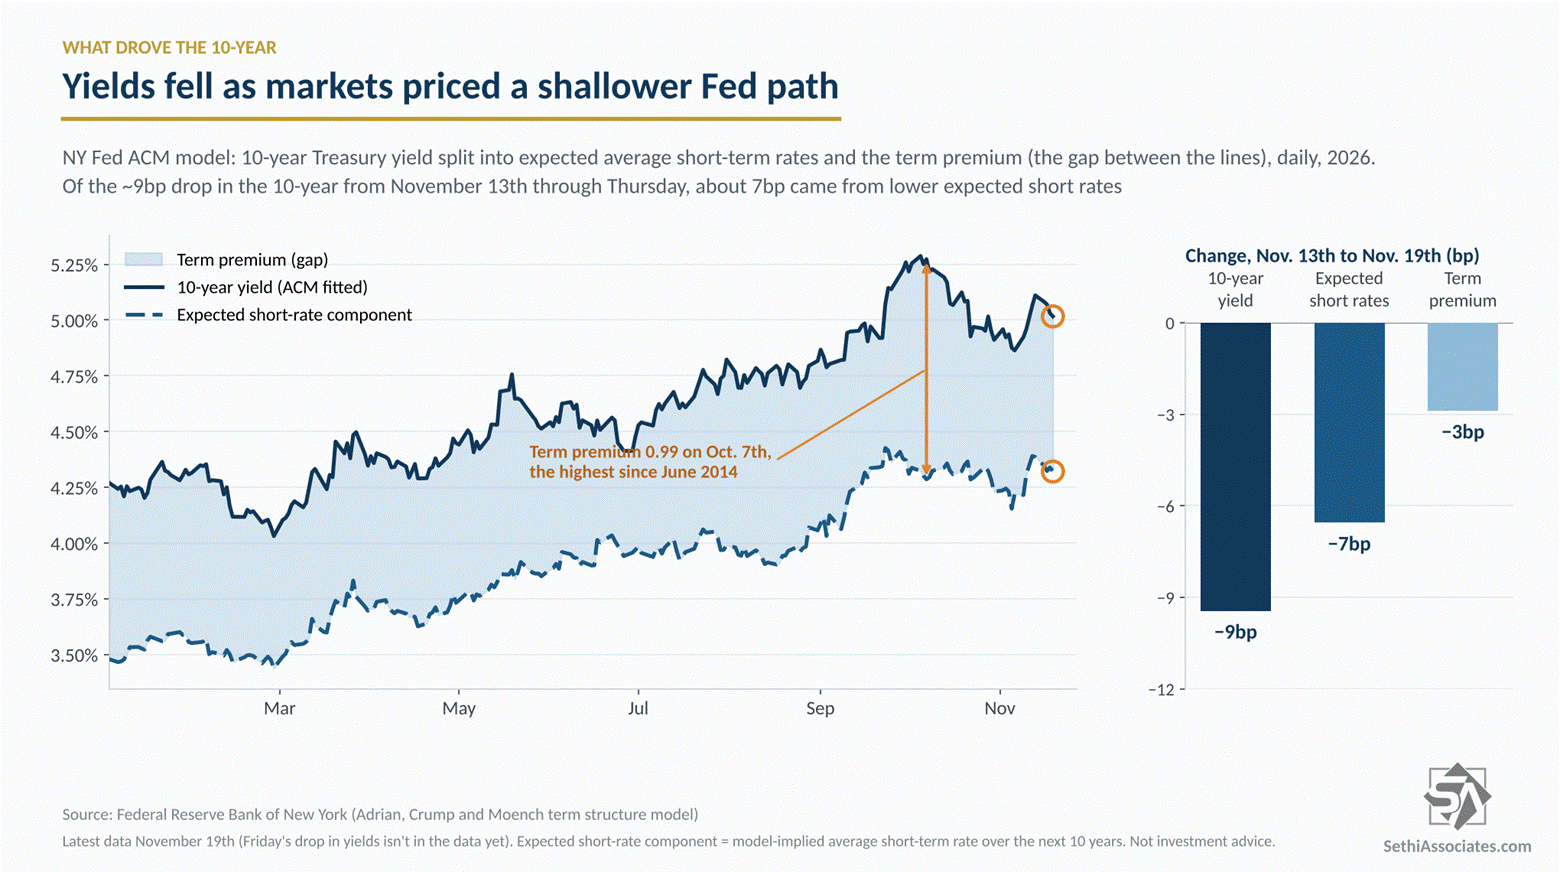
But a bigger factor according to the NY Fed’s ACM model is the drop in the expected Fed rate path. Of the roughly 9bp drop in the 10-year from November 13th through Thursday (the latest data), about 7bp came from lower expected short-term rates, with the ACM term premium (the extra premium demanded by investors to hold longer maturities) easing to 0.70 from 0.72, well below its October 7th peak of 0.99, which was the highest since June 2014. Note though the ACM data don’t include Friday yet, when the 10-year fell another 12bp on Treasury’s par curve, almost all of it in real yields.
In that respect, the 10-year real (TIPS) yield fell to 2.77% from 2.91%, its biggest weekly drop since mid-October, though still not far below its 2026 high of 2.95% on October 5th. On Treasury’s par curve, about 14bp of the 10-year’s drop came from lower real yields and about 9bp from lower inflation expectations.
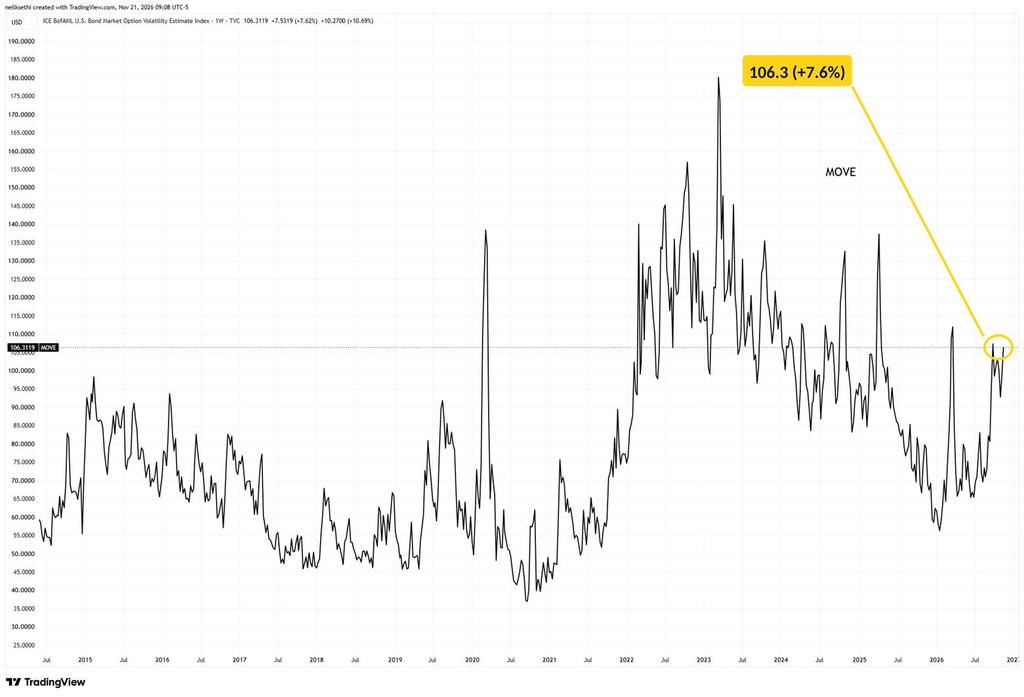
The big drop in yields kept bond volatility elevated, but it hasn’t spiked above its highs of the year. The MOVE index ended the week at 106.3, up 7.6% from 98.8 a week earlier.
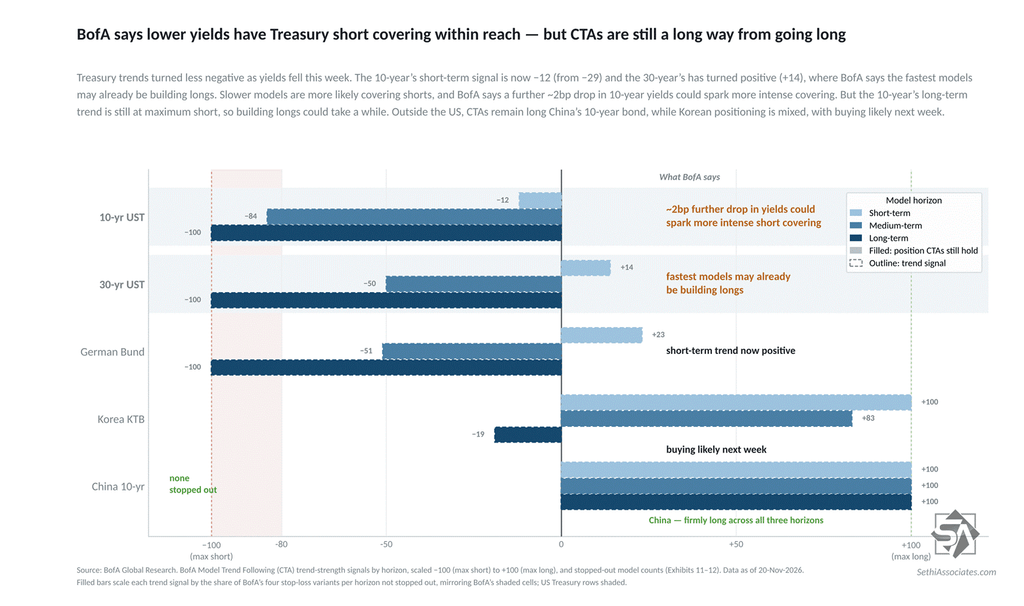
And bond demand from trend followers is turning. BofA says Treasury trends turned less negative as yields fell last week, and the fastest models may already be building longs in 30-year and Ultra bond futures. Slower models, and all models in other maturities, are more likely covering shorts, and a further ~2bp drop in 10-year yields could spark more intense short covering. But the 10-year’s long-term trend is still at maximum short, so it could take a while before CTAs build longs.
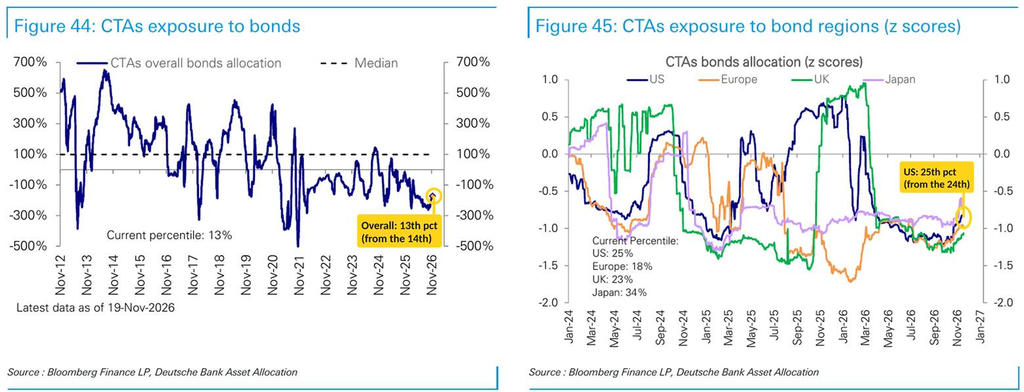
DB sees CTAs paring US bond shorts (25th percentile, from the 24th) but adding to them in Europe (18th) and Japan (34th), leaving their overall bond allocation at the 13th percentile since 2012 (from the 14th).
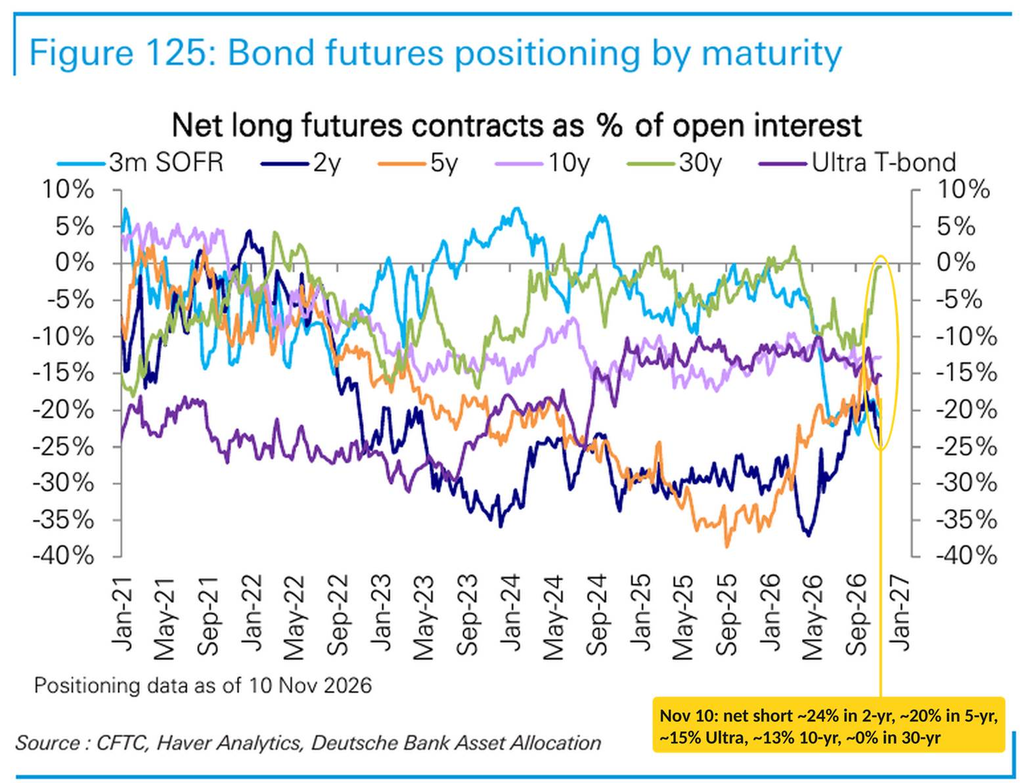
Looking at broader positioning, DB’s read of the CFTC data (as of November 10th, so a bit delayed) shows speculators still net short across most of the curve: about 24% of open interest in 2-year futures (from 22.5%), about 20% in 5-year (from 19.0%), about 15% in the Ultra bond and about 13% in 10-year futures, while the 30-year is roughly flat.
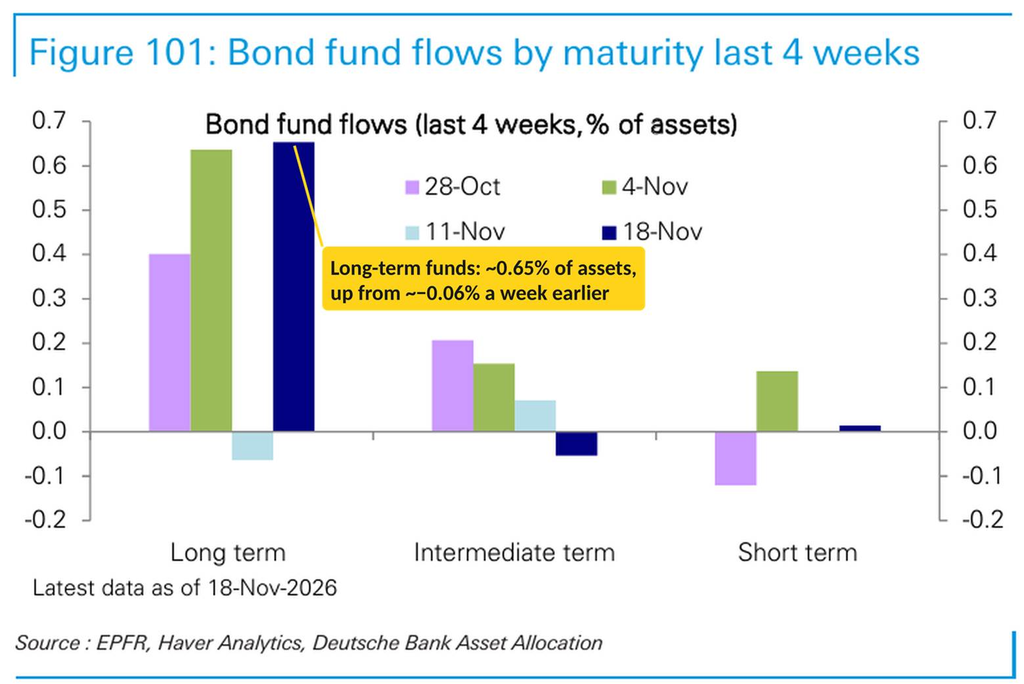
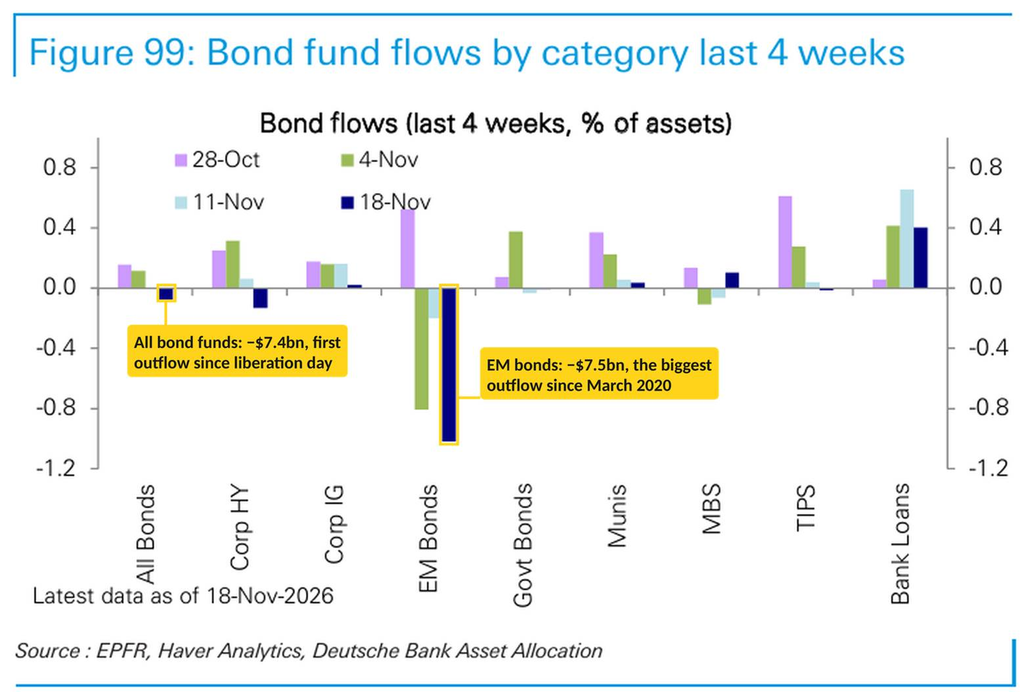
While bond fund flows were mixed. Per DB, long-term bond funds took in about 0.65% of assets in the week through November 18th (from about −0.06%), even as bond funds overall saw their first outflows since liberation day (−$7.4 billion, covered in the flows below).
Credit was mixed. Spreads on CCC-rated (and lower) junk bonds widened 45bp on the week to 13.61%, their highest weekly close since 2020 (and before that 2016), while the investment-grade spread was more contained, up 5bp to 0.94%, though still around its highest since May 2025.
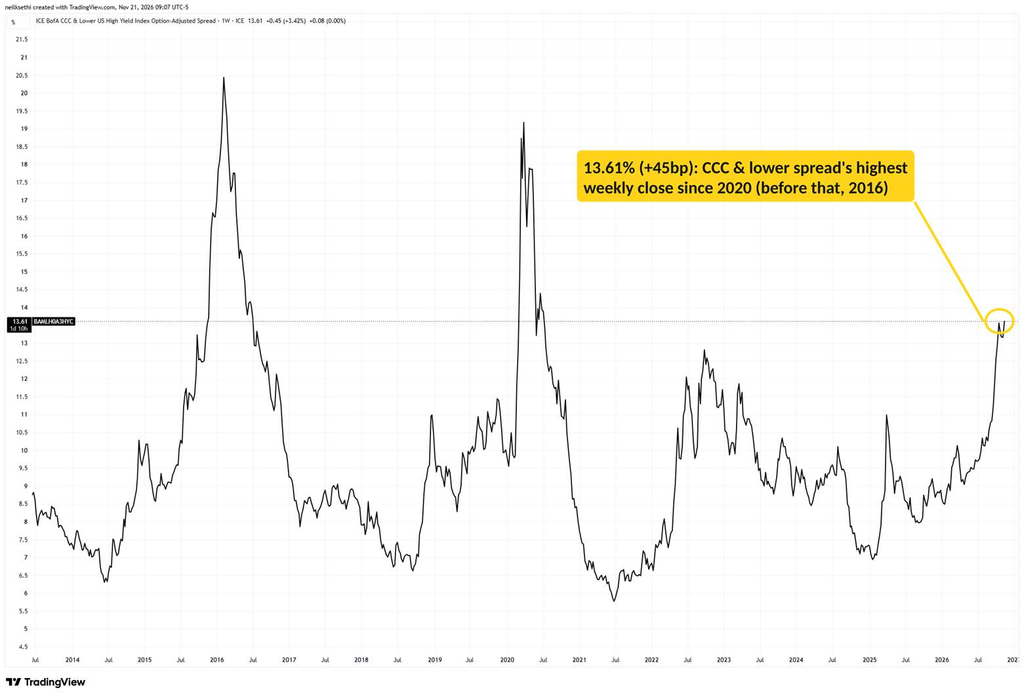
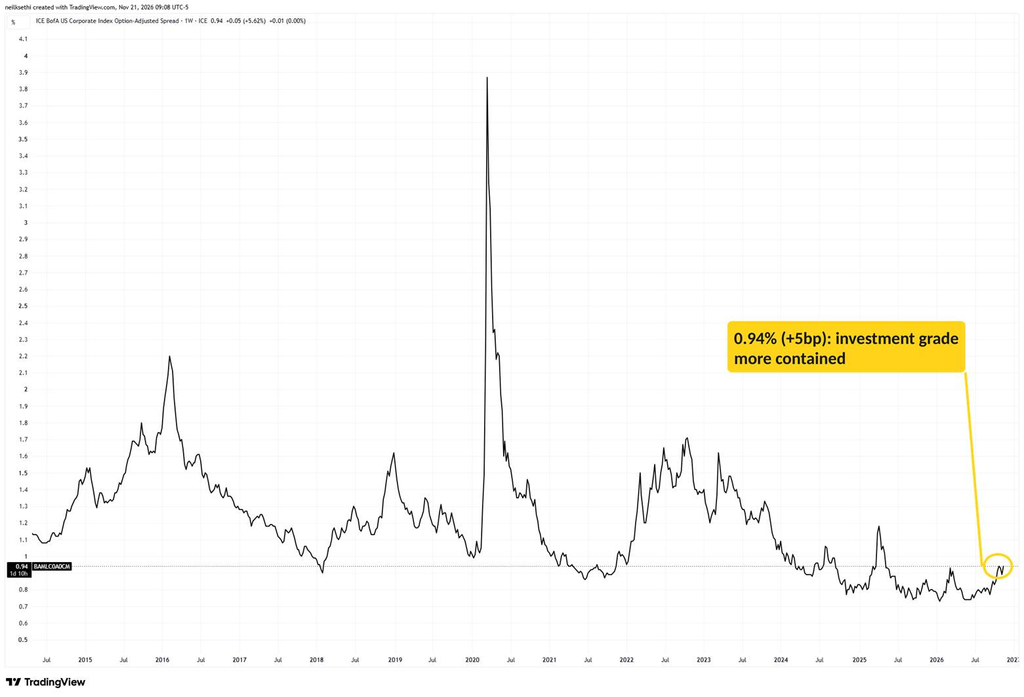
Fedspeak is light this week, with New York Fed President Williams (permanent voter) Monday at 4pm ET the only scheduled speaker, and the Beige Book Wednesday. The Beige Book is important, though, as the Fed pays a lot of attention to anecdotal “on the ground” reports like that one. The blackout begins at midnight Saturday ahead of the December 8–9 meeting.
Q3 Earnings Season Wraps Up With Growth Over 30%
Looking at Q3 earnings, we’re basically done, with 93% of the S&P 500 reporting through Thursday according to FactSet – we have just a few megacaps left to go, particularly Broadcom (AVGO) December 9th, Costco (COST) December 10th and Micron (MU) December 17th – and beats remain high with 84% coming in above expectations, above the 1-year average of 82%, the 5-year average of 78% and the 10-year average of 77%.
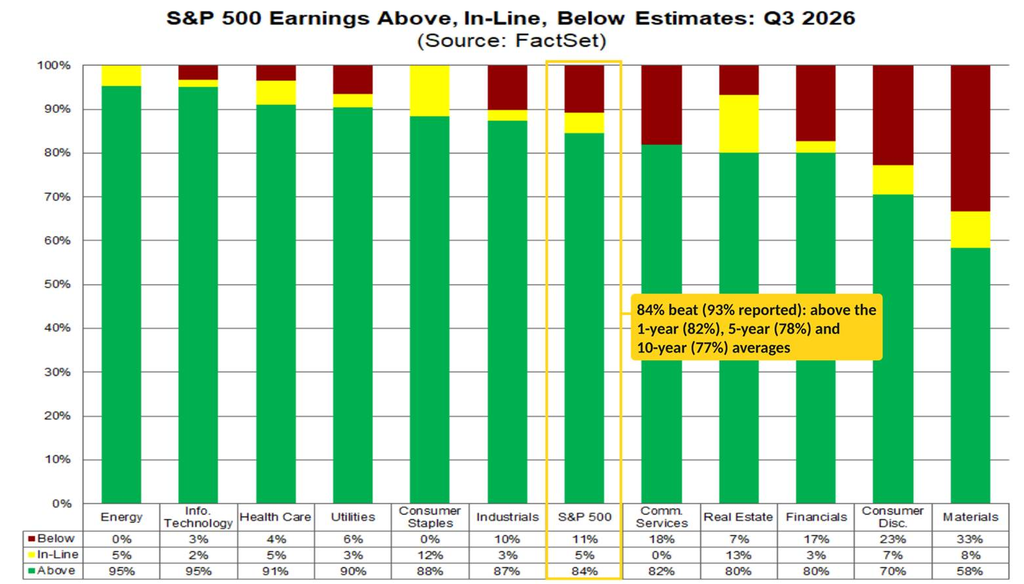
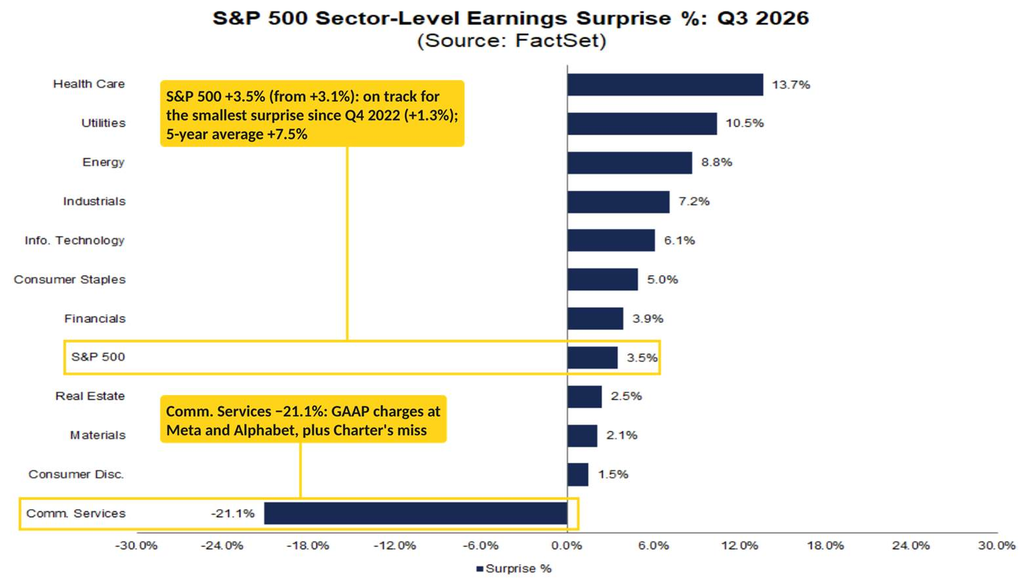
The magnitude of the beats though remains historically weak at +3.5% (from +3.1% the prior week), well below the 1-year average of 13.8%, the 5-year average of 7.5% and the 10-year average of 8.0%. If that holds, it would be the smallest surprise since Q4 2022 (+1.3%). As noted in prior weeks, though, it’s in large part a function of the Communication Services sector at -21.1% (from -22.1%), on the GAAP charges at Alphabet (GOOGL) and Meta (META), along with a big miss at Charter Communications (CHTR). Excluding Alphabet and Meta altogether, it would be about +6.1% by my calculations, still below the 5- and 10-year averages.
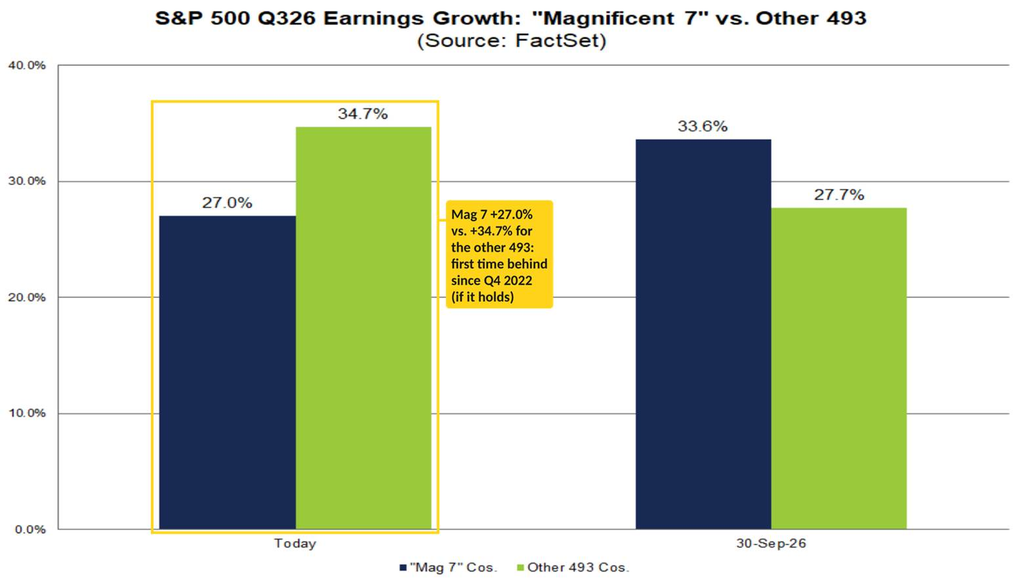
FactSet’s topic of the week puts a finer point on the Magnificent 7. With Nvidia (NVDA) reporting Tuesday, all seven have now reported, and just four of them (57%) beat, versus 84% for the S&P 500, with the group missing estimates by 4.9% in aggregate against a 3.5% beat for the index. That leaves the Mag 7’s Q3 earnings growth at 27.0%, down from the 33.6% expected on September 30th, while the other 493 have climbed to 34.7% from 27.7%. If it holds, it would be the first quarter since Q4 2022 that the Mag 7 grew earnings more slowly than the rest of the index, and analysts expect the same in Q4 (22.6% vs. 30.8%). As a reminder, FactSet uses GAAP EPS for Alphabet, Amazon (AMZN) and Meta.
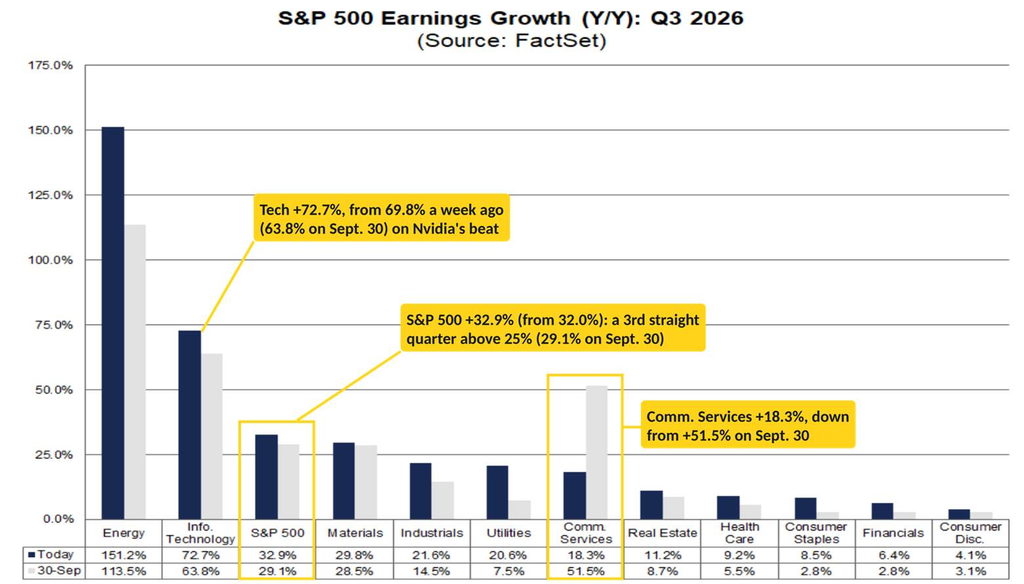
With Nvidia’s beat the biggest contributor, Q3 expected earnings growth climbed another 0.9 points to +32.9% (from a revised 32.0%), which would be a third straight quarter above 25% and an eighth straight of double-digit growth. Energy held at +151.2% y/y (up from +113.5% on September 30th), followed by Tech, which jumped to +72.7% from a revised +69.8%, and Materials at +29.8%. Comm Services was little changed at +18.3% (from +18.2%), still well below +51.5% on September 30th.
Within Tech, semiconductors are now growing 141% (from 133%).
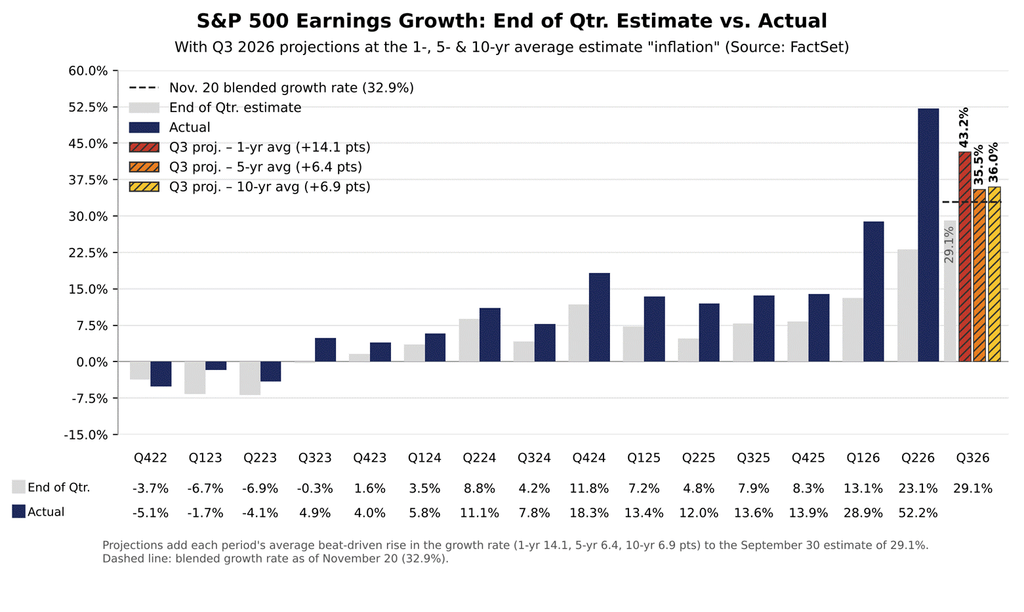
The changes have been directionally consistent with the typical “earnings inflation” we see each earnings season as I mentioned at the start of the reporting period (numbers are from the end of the quarter, which is where the “inflation” metrics are measured from). So far the growth rate has risen 3.8 points since September 30th, against 5- and 10-year average gains of 6.4 and 6.9 points over a full season. That said, with 93% of companies reported, there’s little room left, so it looks like we’ll come in below that this quarter.
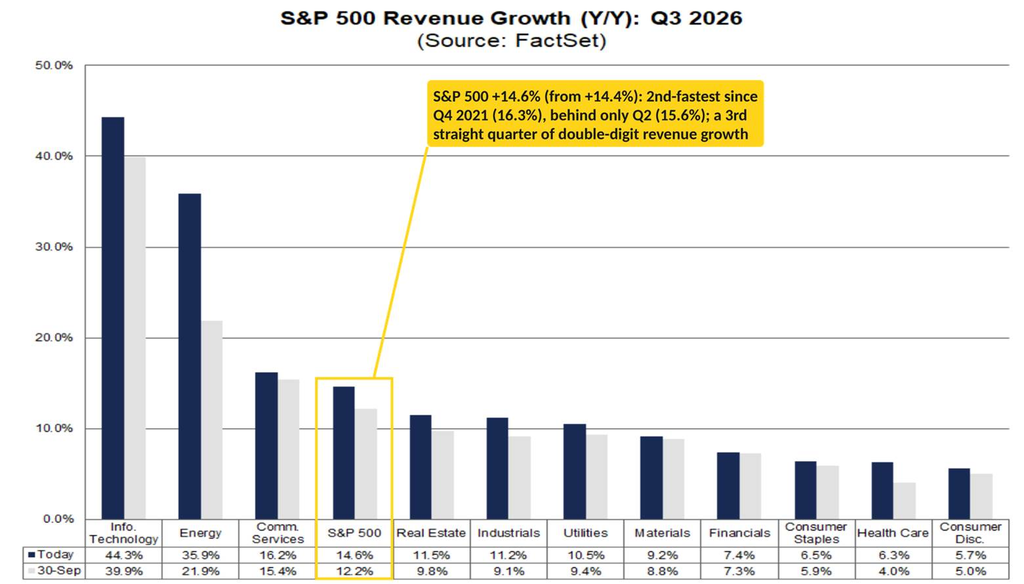
Q3 revenue growth expectations also rose to +14.6% (from +14.4%), which would be the second fastest since Q4 2021 (16.3%), behind only Q2 (15.6%), and a third straight quarter of double-digit growth. Expectations are led by Tech (+44.3%), Energy (+35.9%) and Communications (+16.2%). And 74% of companies have beaten revenue estimates (5-year average 70%), by an aggregate +2.2% (5-year average +1.8%).
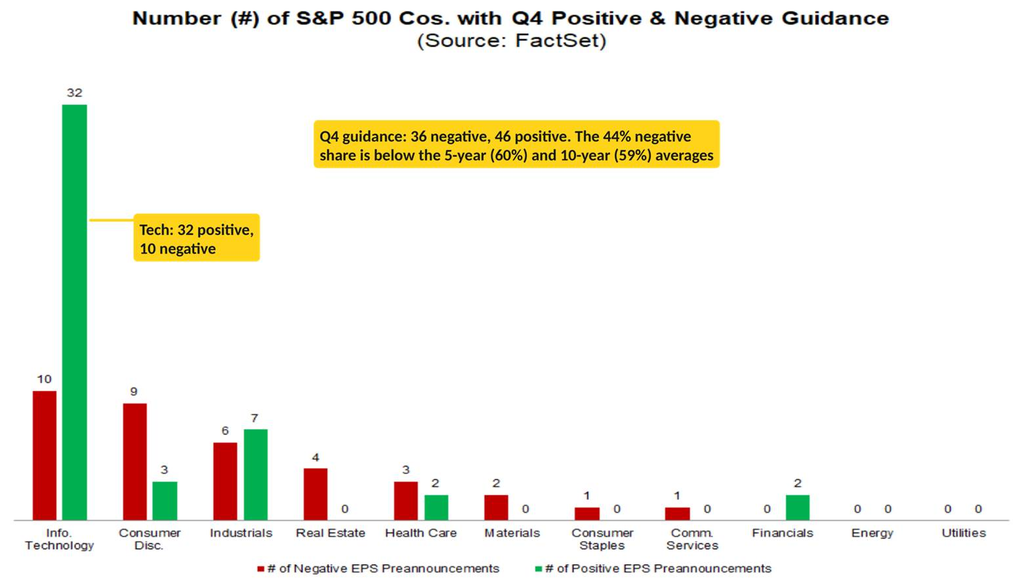
Expected Q4 growth rose to 28.9% (from 28.3%, and up from 26.8% on September 30th), and guidance remains better than usual: 44% of the 82 companies that have guided Q4 have been negative, versus a 5-year average of 60%. Energy (162.0% from 160.2%) and Tech (57.0% from 55.1%) led the increase, with Materials (36.8% from 36.6%) edging up, while Utilities (7.1% from 7.6%), Consumer Discretionary (10.5% from 10.7%) and Industrials (-2.4% from -2.3%) were trimmed again and Comm Services held at 8.6%.
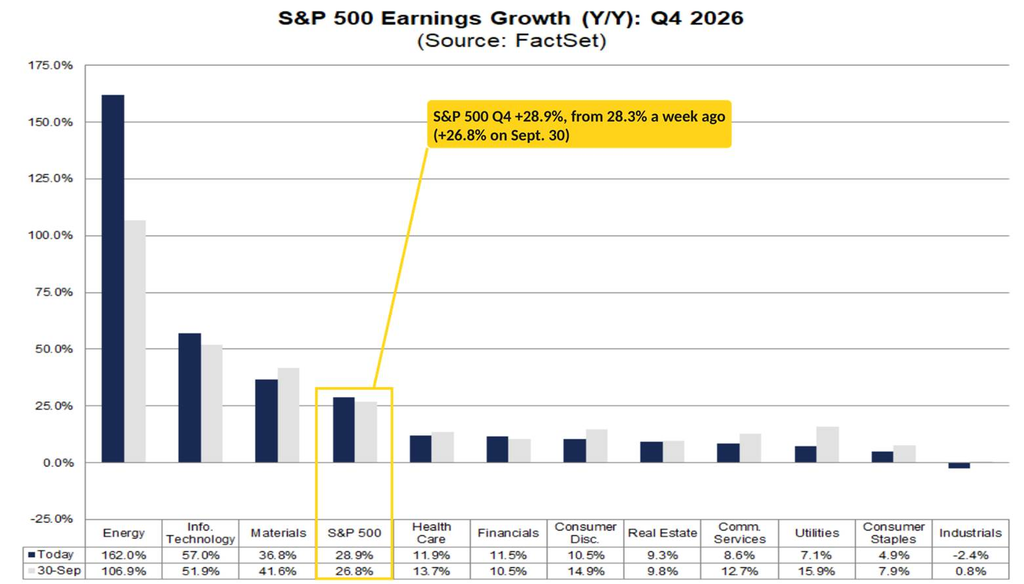
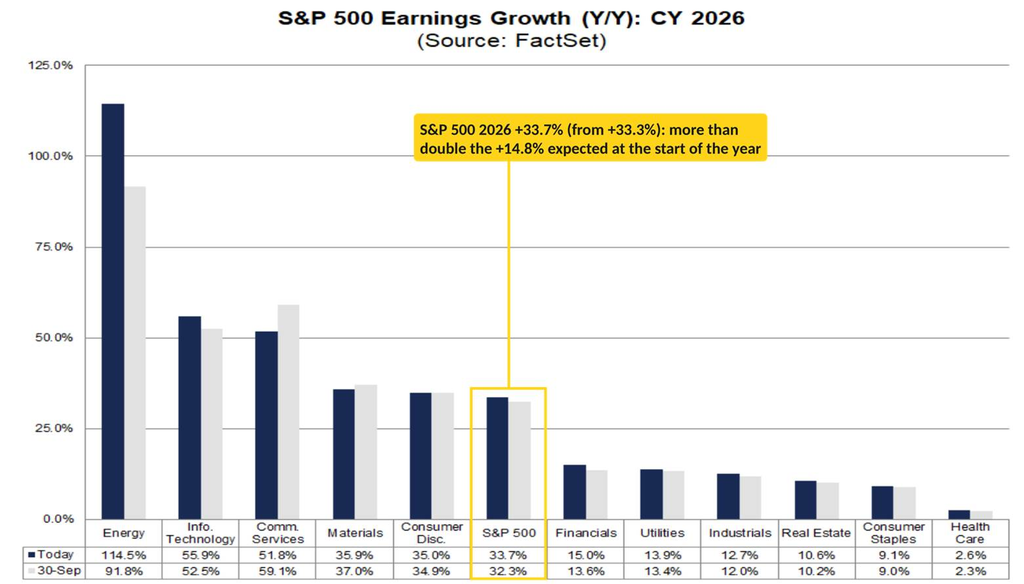
With Q3 and Q4 estimates both moving higher, 2026 SPX earnings growth expectations rose to +33.7% (from +33.3%), up from +24.0% on June 30th, +17.1% on March 31st, and well over double the +14.8% at the start of the year. Energy leads at +114.5% (from +113.6%; up from +6.4% at the start of the year), followed by Tech at +55.9% (from +54.6%; up from +28.6%) and Communications (+51.8%, unchanged). Those sectors along with Materials (+35.9%) and Consumer Discretionary (+35.0%) remain the five expected to come in above the SPX average.
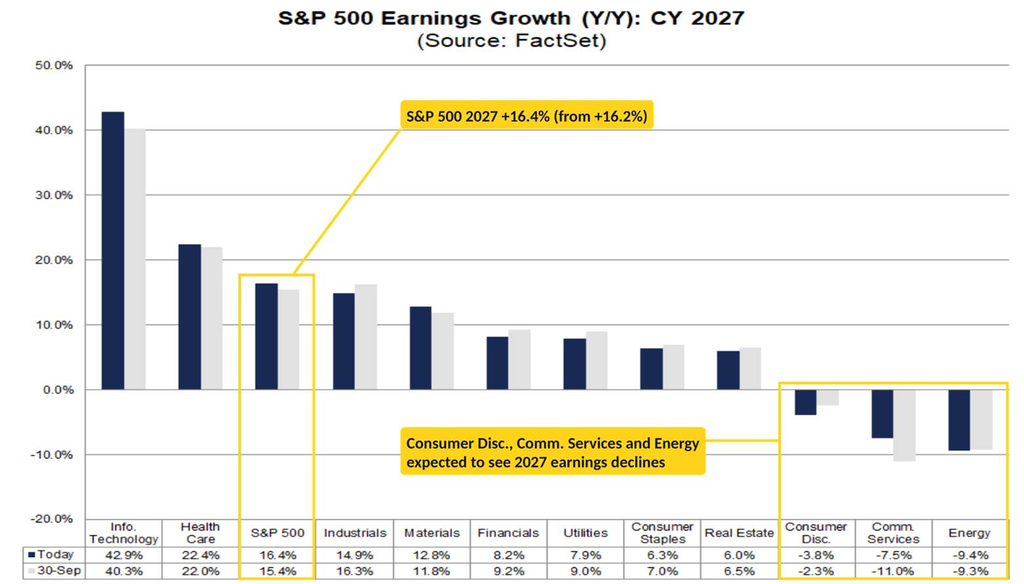
And 2027 earnings are expected to be up another +16.4% (from +16.2%), slightly lower than the +17.5% as of June 30th, but that’s even as the 2026 comp has risen 9.7 points over that time. Tech again leads (+42.9%), followed by Health Care (+22.4%), with no other sector above the SPX average (Industrials just under at +14.9%). Energy (-9.4%), Communications (-7.5%) and Consumer Discretionary (-3.8%) are expected to see declines, the latter two after seeing big boosts in 2026 on “other income” tied to AI investments (notably Anthropic and OpenAI).
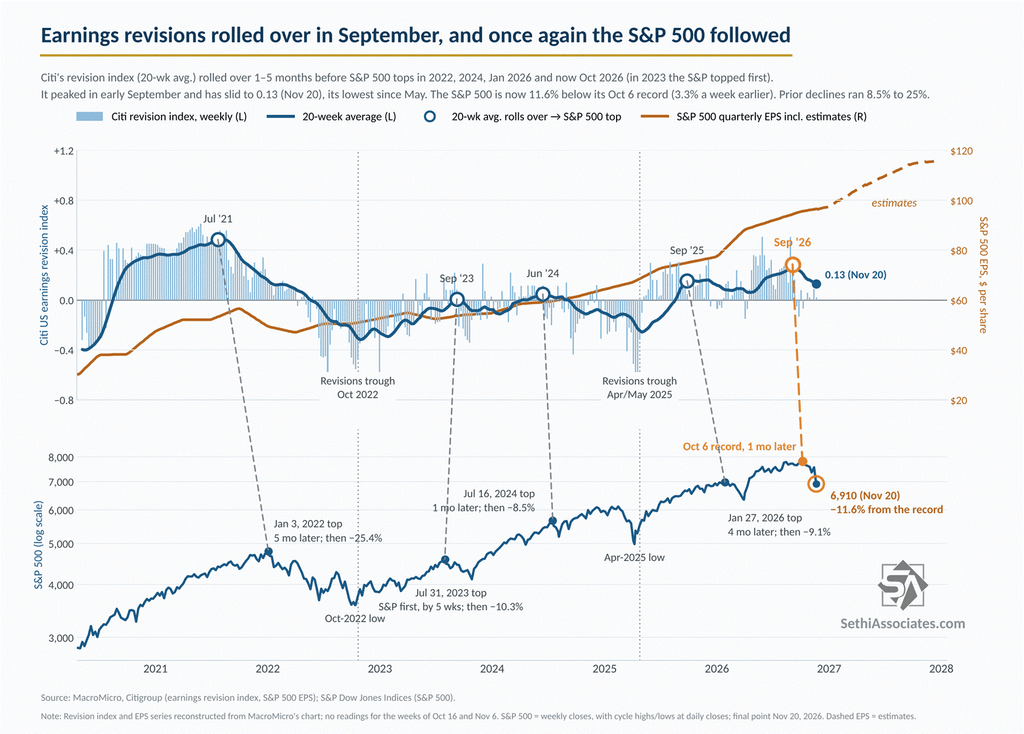
Turning to earnings revisions, Citi’s earnings revision index slipped to +0.02 from +0.09 the prior week, and its 20-week average eased to 0.13 from 0.14, its lowest since May (it was 0.29 in early September). As I noted on October 25th, in three of the four prior rollovers since 2021, the 20-week average turned one to five months before an S&P 500 top (January 2022, July 2024 and January 2026), followed by declines of 8.5% to 25% (in 2023, the S&P 500 topped first). This time it rolled over in September, about a month before the S&P 500’s October 6th record, and the index is now 11.6% below that record (from 3.3% a week earlier).
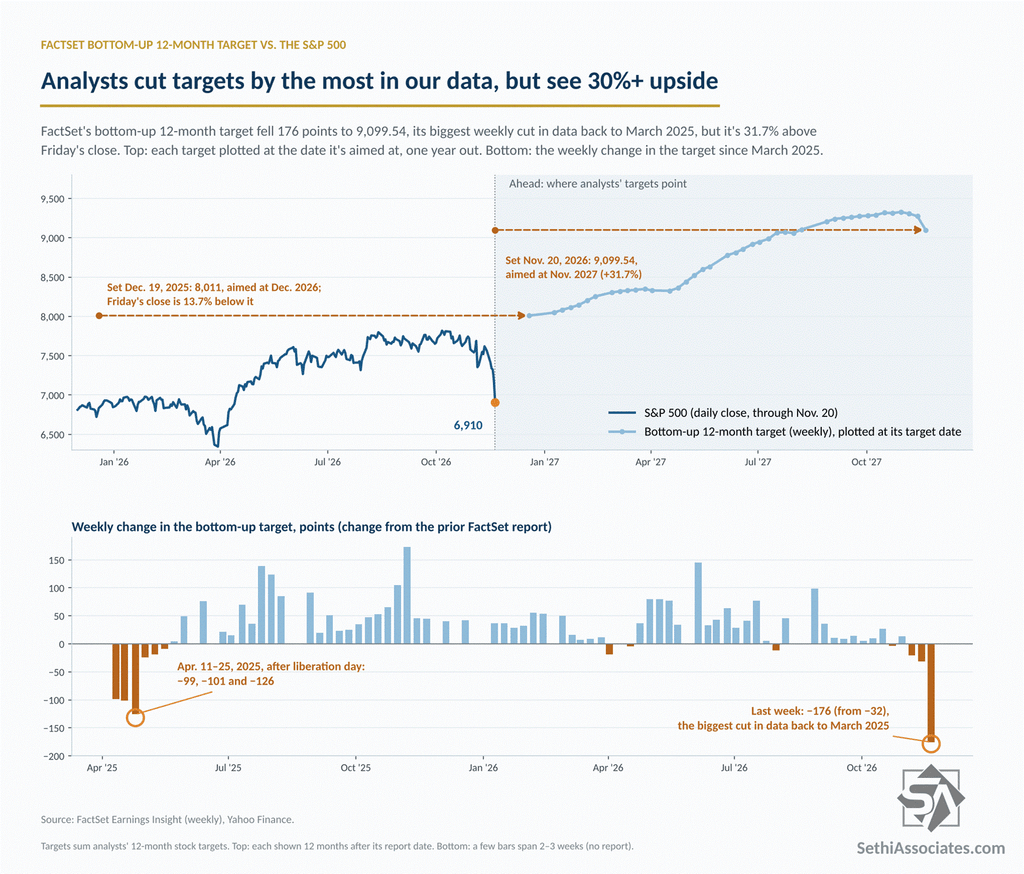
Analysts meanwhile continue to see plenty of upside, although FactSet’s compilation of analyst bottom-up SPX 12-month price targets fell for a third week, and by far the most of the three, to 9,099.54 (-176pts w/w, about +775 pts since March 31st, about +1,175 pts since Thanksgiving, and about +2,410 pts since July 1, 2025). That’s the biggest weekly cut in FactSet’s bottom-up target in our data back to March 2025, larger than any of the three post-liberation-day cuts (−99, −101 and −126 points).
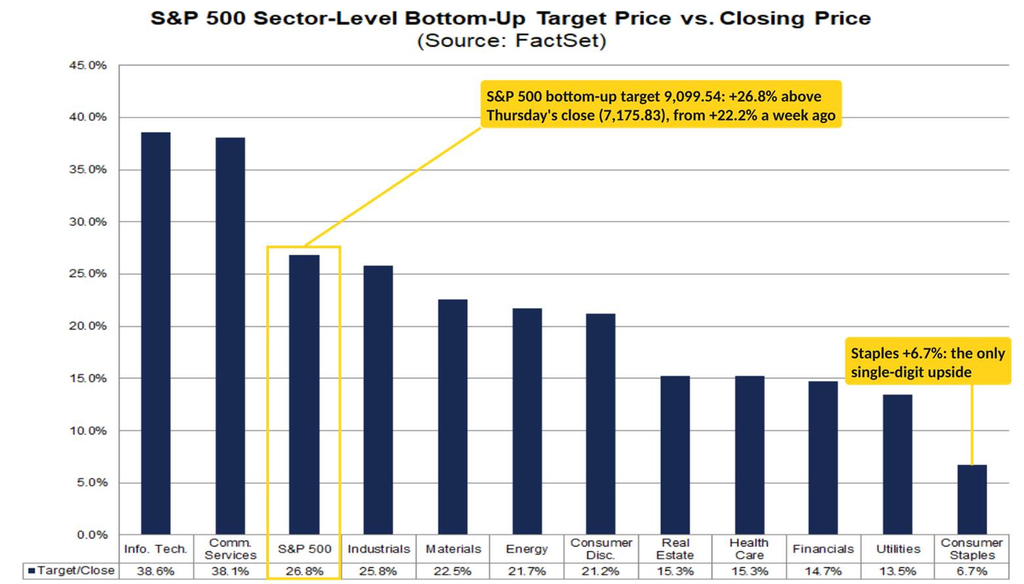
Still, the target represents a gain of +26.8% from Thursday’s close (7,175.83), up from +22.2% the prior week as the index fell 5.5% through Thursday (and +31.7% from Friday’s close). As a reminder, we started the year with a 12-month bottom-up price target of about 8,000 (8,010.64). Friday’s close leaves the S&P 500 about 13.7% below that.
Tech (+38.6%, from +35.8%) remains on top for expected upside, followed closely by Communications (+38.1%, from +29.2%) and Industrials (+25.8%, from +19.7%). Energy’s expected upside jumped to +21.7% from +14.6%. Consumer Staples (+6.7%, from +4.6%) is now the only sector with single-digit expected upside, as Health Care (+15.3%, from +8.3%) and Financials (+14.7%, from +8.9%) moved into double digits.
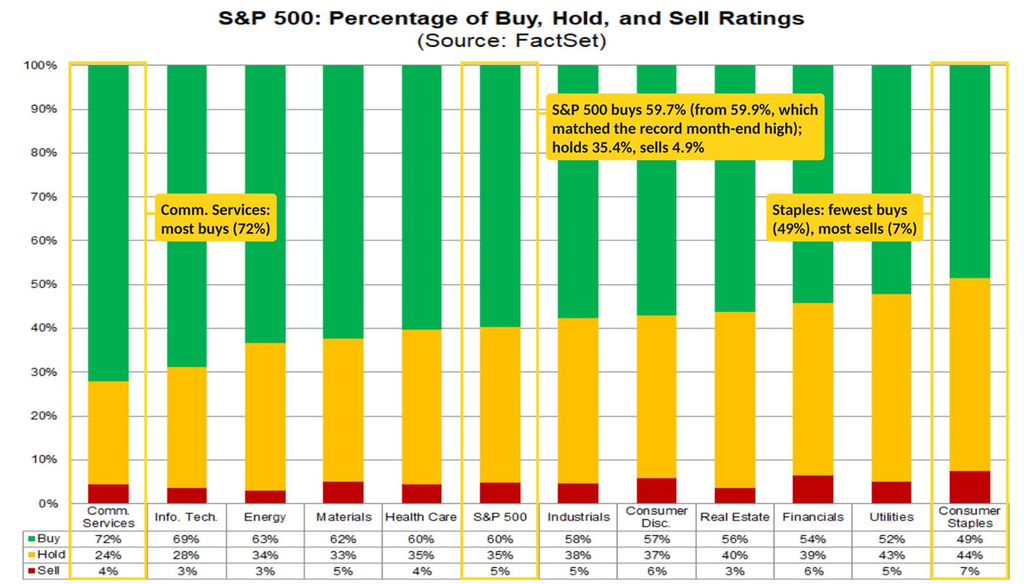
In terms of analyst ratings, buy ratings edged down to 59.7% from 59.9% (which had matched the record month-end high, to 2010, set at the end of October), while hold ratings rose to 35.4% from a record-low 35.3% and sells rose to 4.9% (from 4.7%). The 5-year month-end averages are 55.8%, 38.7% and 5.6%. Communications (72%) and Tech (69%) have the highest share of buys, while Consumer Staples has the lowest (49%) and the most sells (7%).
Valuations Fall Below Their Long-Term Averages
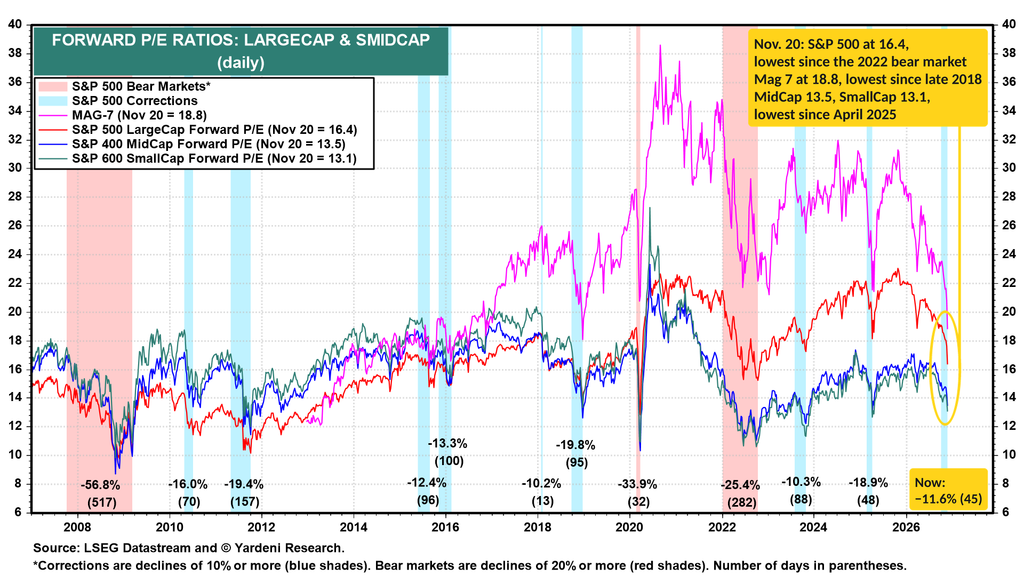
Yardeni says the S&P 500’s correction “has been led by a sharp drop in its forward P/E,” which “plunged to 16.4 on Friday,” the lowest since the 2022 bear market, even as forward earnings rose to a record $421.84. The Magnificent 7’s fell to 18.8, the lowest since late 2018, leaving its premium to the S&P 500 at 2.4 points, the narrowest since early 2017, and the S&P 400 MidCap (13.5) and S&P 600 SmallCap (13.1) are at their lowest since April 2025.
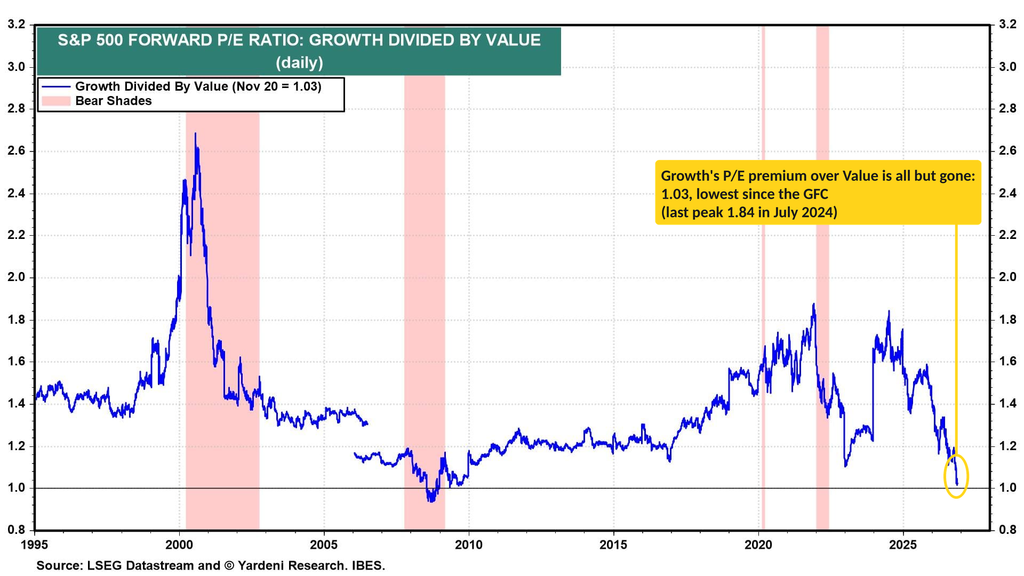
Growth’s forward P/E has fallen to 17.8 from 29.7 late last year, barely above Value’s 17.3, taking the ratio of the two to 1.03, the lowest since the Great Financial Crisis. Yardeni says “the unwinding of the AI trade this year has eliminated Growth’s valuation premium over Value,” a premium he expects to rebuild “once the AI selling panic subsides.”
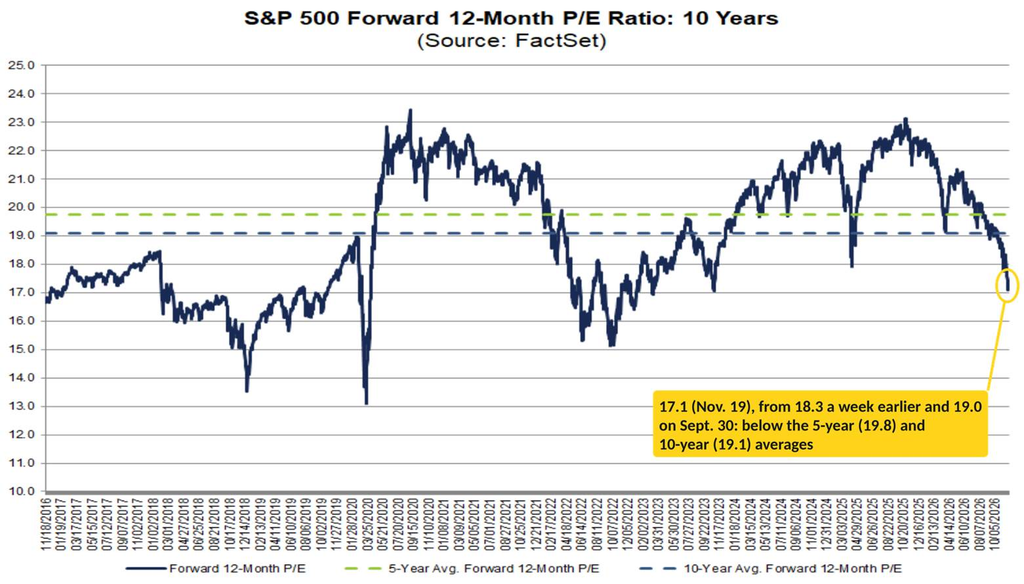
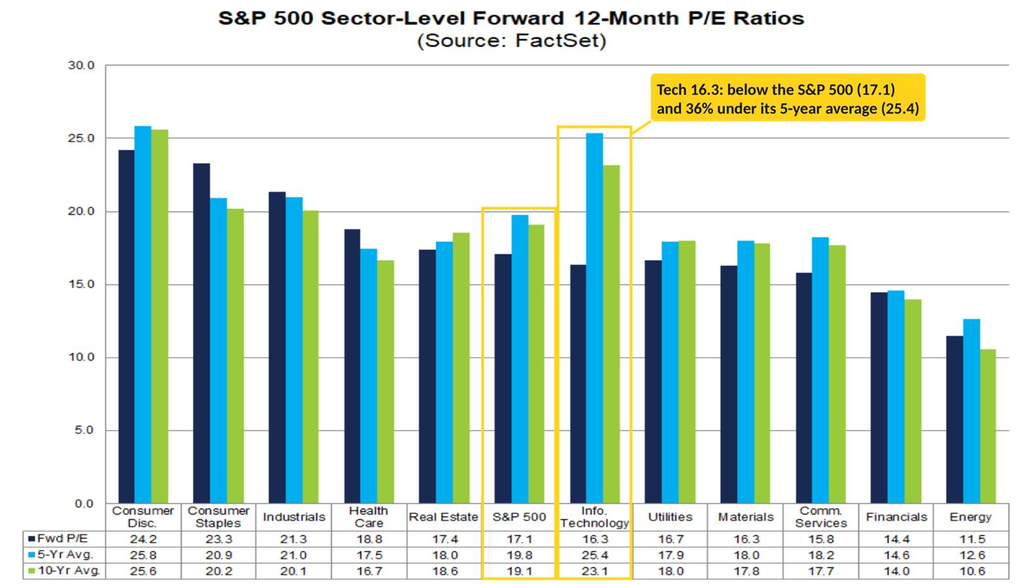
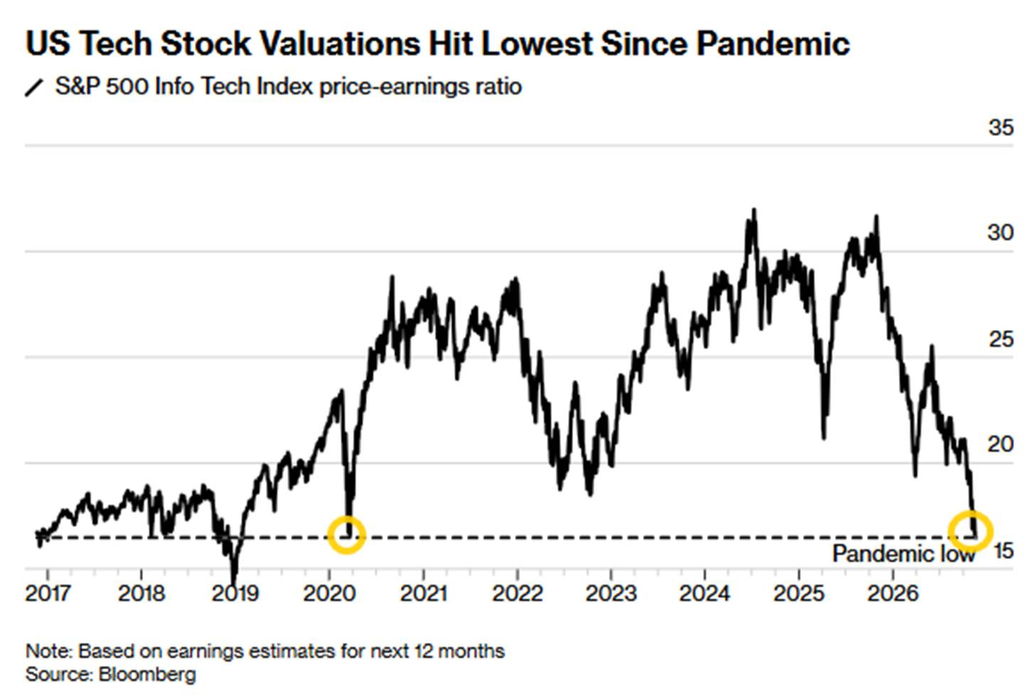
FactSet’s forward P/E* for the S&P 500 fell to 17.1 (as of Thursday) from 18.3, below the 17.7 of two weeks ago (which was the lowest since November 1st, 2023), and further below the 5-year (19.8) and 10-year (19.1) averages. That’s down from 19.0 on September 30th, as the index fell 6.2% since then while forward EPS rose 4.4%. Tech’s forward P/E fell to 16.3 from 18.0, its lowest since the Covid crash, now below the S&P 500’s and 36% under its 5-year average (25.4). The trailing P/E fell to 22.9 (from 25.4), now below both its 5-year (24.4) and 10-year (23.7) averages.
*Note P/Es can differ based on the particular metrics used for forward earnings.
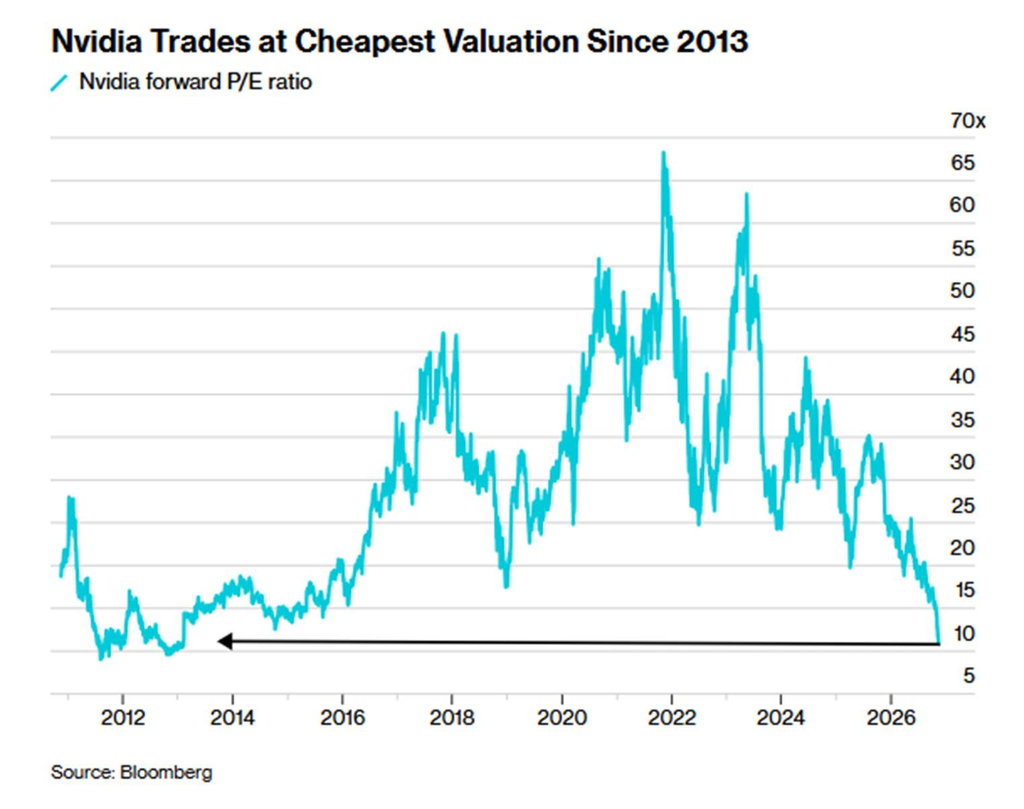
Bloomberg’s data tell the same story for Tech, with US Tech valuations back at their pandemic low as of Wednesday (so likely below now), and Nvidia (NVDA) trading at its cheapest forward P/E since 2013 (Yardeni has it at just 8.1 times forward earnings as of Friday).
Positioning Gets Further Washed Out
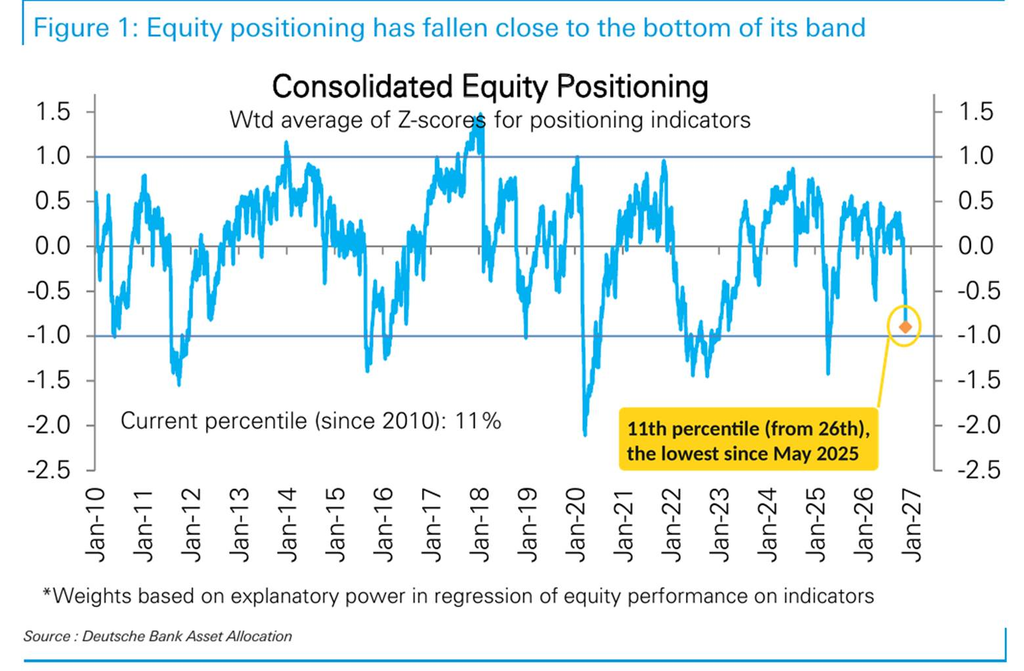
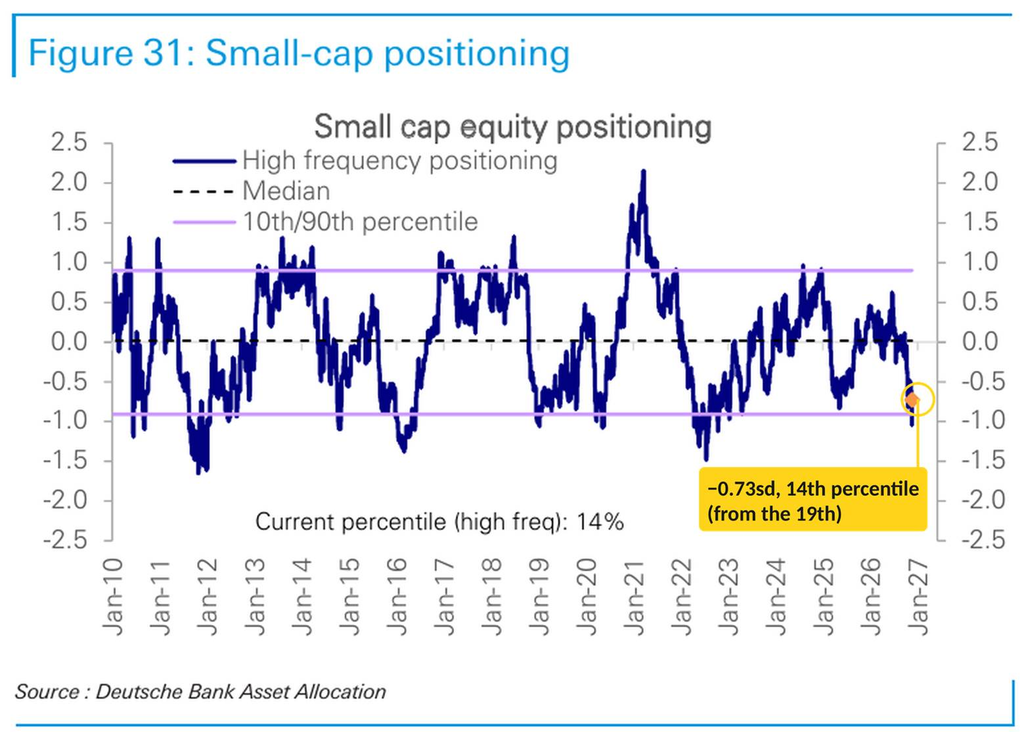
Starting with Deutsche Bank, which says equity positioning “is now very low, not just low relative to earnings growth.” Its consolidated measure fell to -0.90sd, the 11th percentile (from the 26th), the lowest since May 2025 and “close to the bottom of its typical band,” which is “approaching levels from which it has typically bounced.”
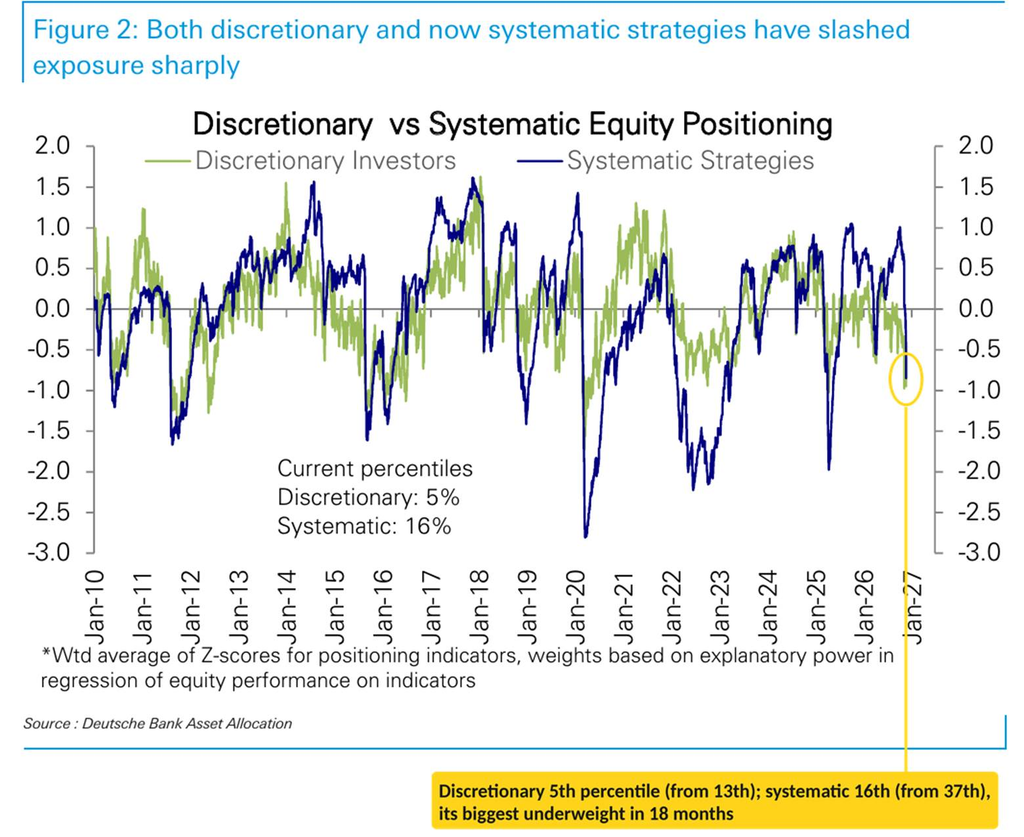
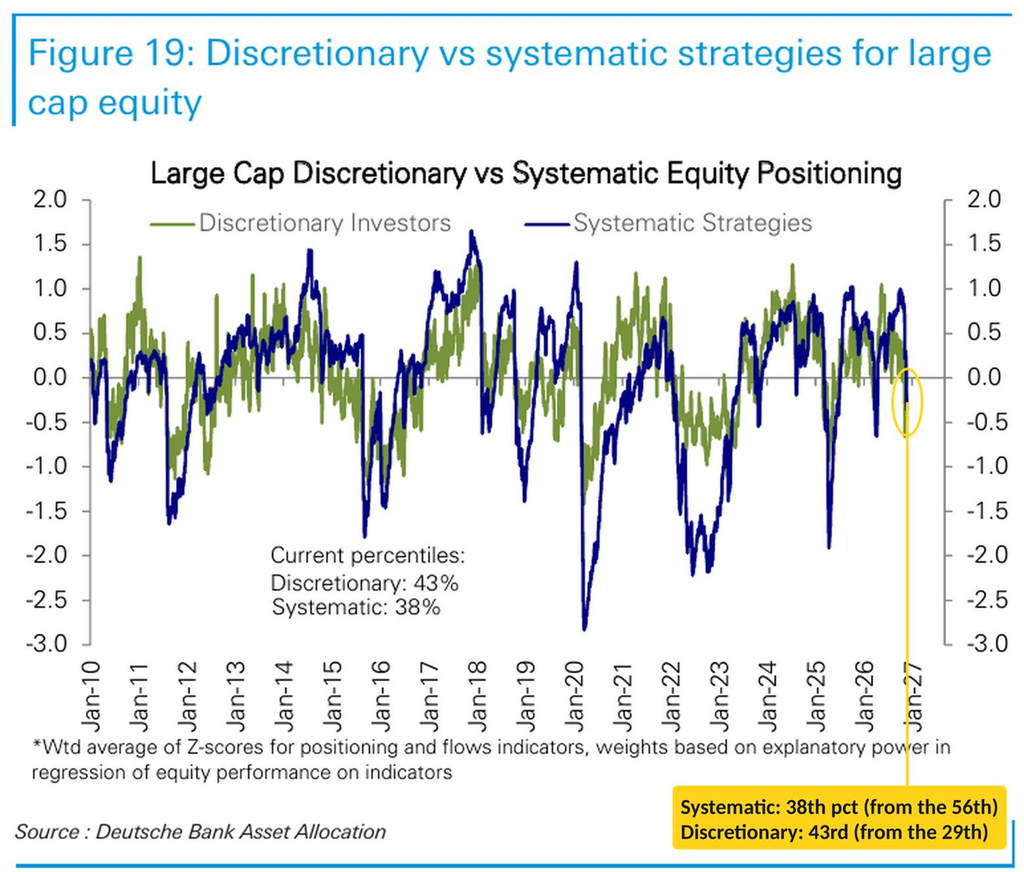
Discretionary investor positioning slipped further underweight, to the 5th percentile (from the 13th), while systematic strategies’ positioning “crashed from neutral last week to its biggest underweight in 18 months” (16th percentile, from the 37th).
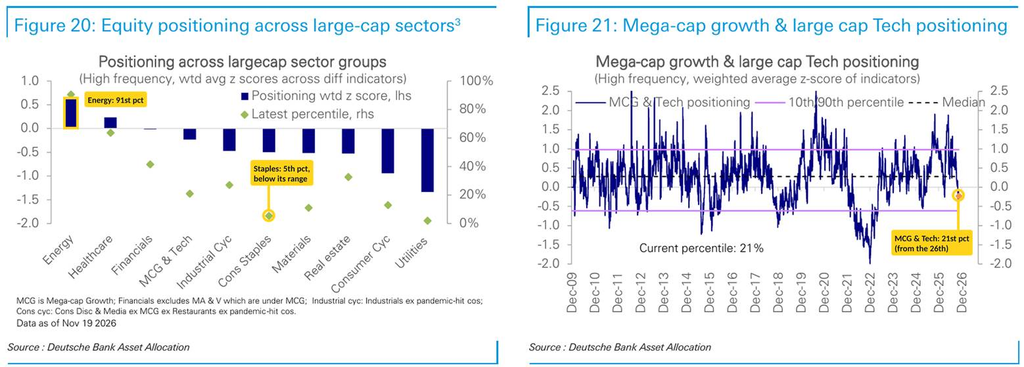
Large-cap positioning fell to modestly underweight (27th percentile, from the 37th), as did MCG & Tech (21st, from the 26th), while small caps slipped “closer to the bottom of its usual range” (14th, from the 19th).
Within large caps, DB’s chart shows systematic strategies falling to the 38th percentile (from the 56th), while discretionary investors rose to the 43rd (from the 29th).
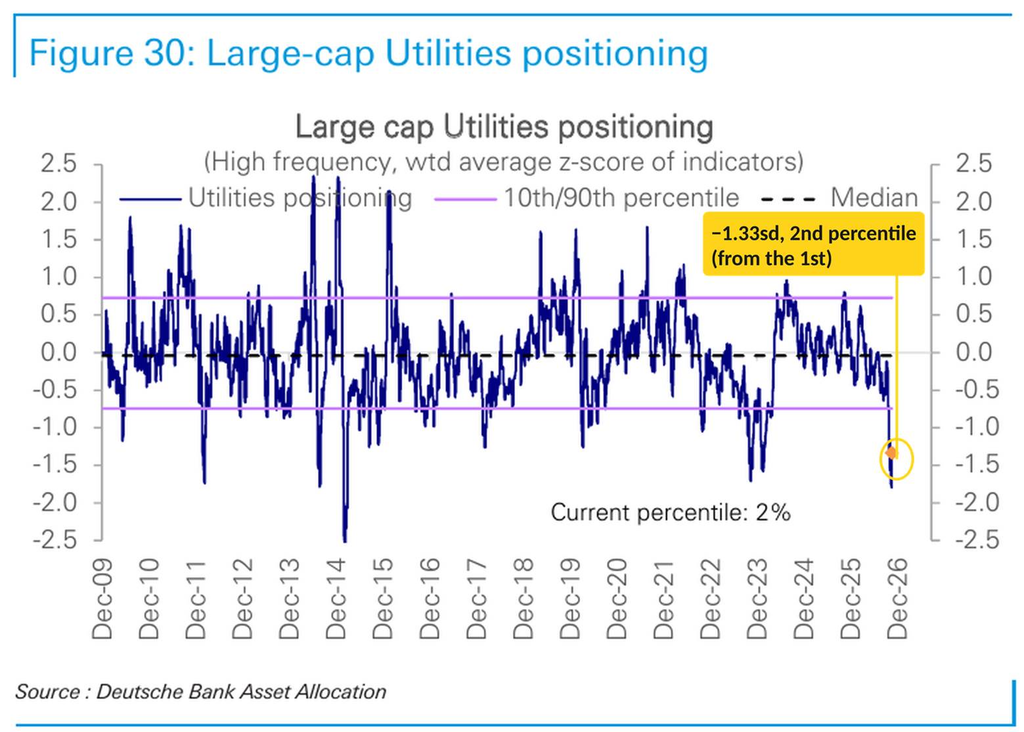
Across sectors, Energy “jumped to notably overweight” (91st percentile, from the 83rd) and Healthcare stayed overweight (64th), while Financials slipped to neutral (42nd, from the 51st). Materials (11th, from the 24th) and Consumer Cyclicals (13th, from the 25th) “fell to significantly underweight,” Real Estate dropped to underweight (33rd), and Industrial Cyclicals stayed underweight (27th). Among defensives, Consumer Staples “fell below the bottom of its range” (5th), while Utilities “rose slightly from extremes” (2nd, from the 1st).
DB frames the pullback in a few ways:
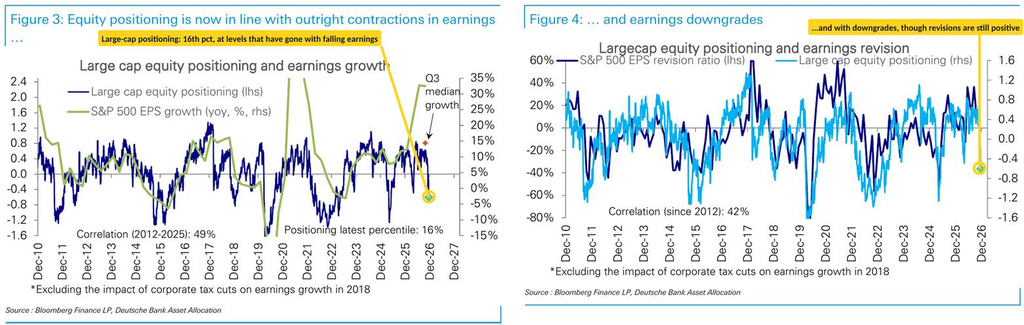
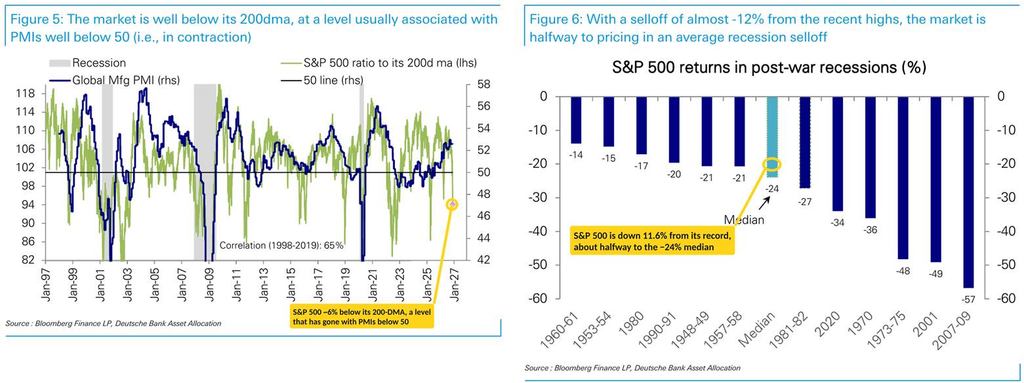
“Halfway to a typical recession selloff. Pricing and positioning is now in line with an outright contraction in S&P 500 earnings and a drop in the ISM and global manufacturing PMIs to well below 50. We note that the median S&P 500 decline in post-war recessions is -24%, putting the current selloff almost half-way there.”
DB’s charts show large-cap positioning (16th percentile on this measure) at levels that have historically gone with outright earnings contractions and downgrades, even though S&P 500 earnings are growing about 30% and revisions are still positive. And the S&P 500’s roughly 6% discount to its 200-DMA is a level usually associated with global manufacturing PMIs well below 50; the global PMI is still about 52, by my read of DB’s chart.
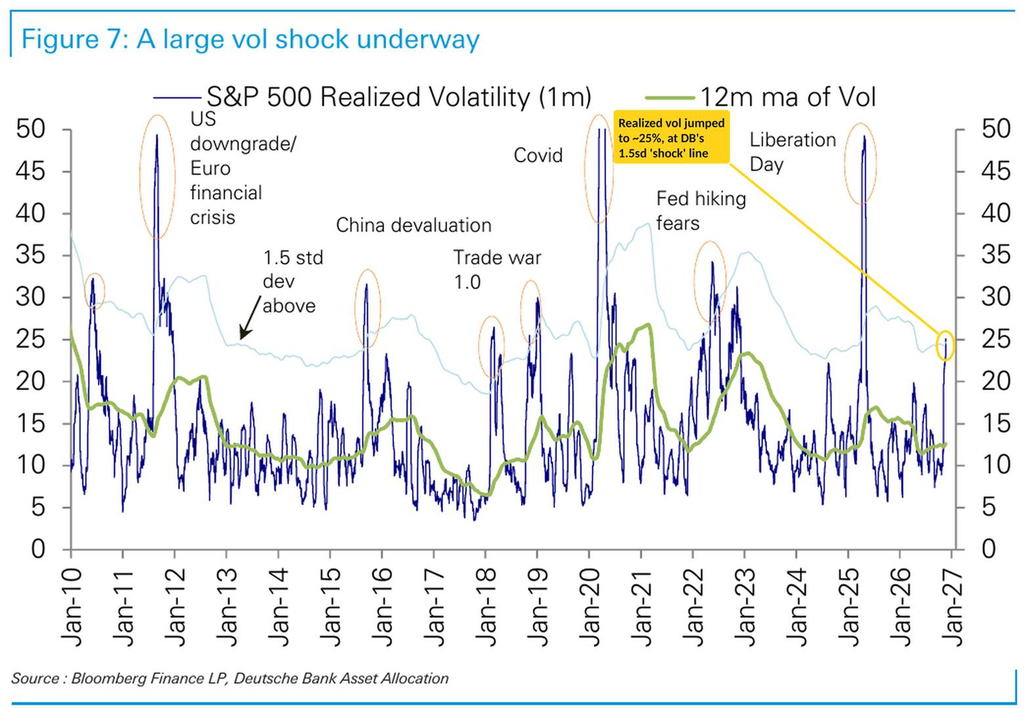
“Now into a vol shock.” Implied and realized volatility, intraday ranges, the inversion in the VIX futures curve and implied correlations have all spiked into the top decile. “In past vol shocks, it took an average of 6 to 8 weeks for vol to subside and equities to bottom. The S&P 500 declined on average -14% to -16% in these episodes outside recessions and took 4 to 6 months to fully recoup the declines.” Measured from last week, that would point to a bottom in early to mid-January, and the S&P 500 is already down 11.6%.
And Tech “is now at the bottom of a decade-long channel on an absolute basis and well below its channel relative to the rest of the S&P 500.” The last time it was at the bottom of its absolute channel was the end of March, and the Nasdaq-100 “is now more than -10% below its 200dma, only the 5th such occurrence in the last decade” (the end-2018 selloff, the start of the pandemic, 2022 and liberation day).
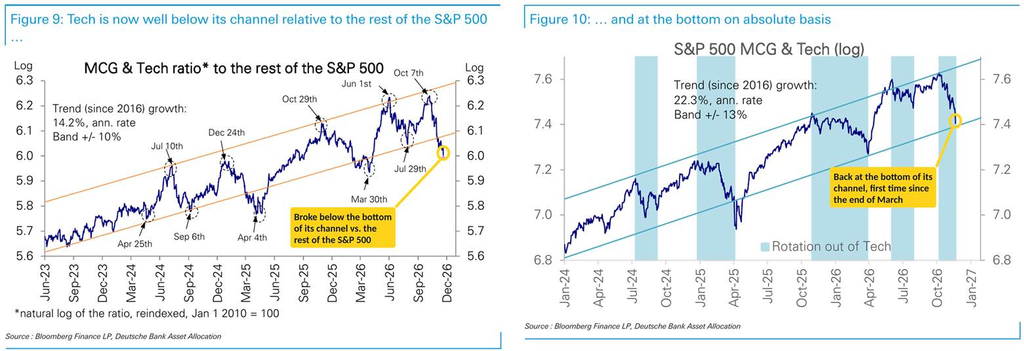
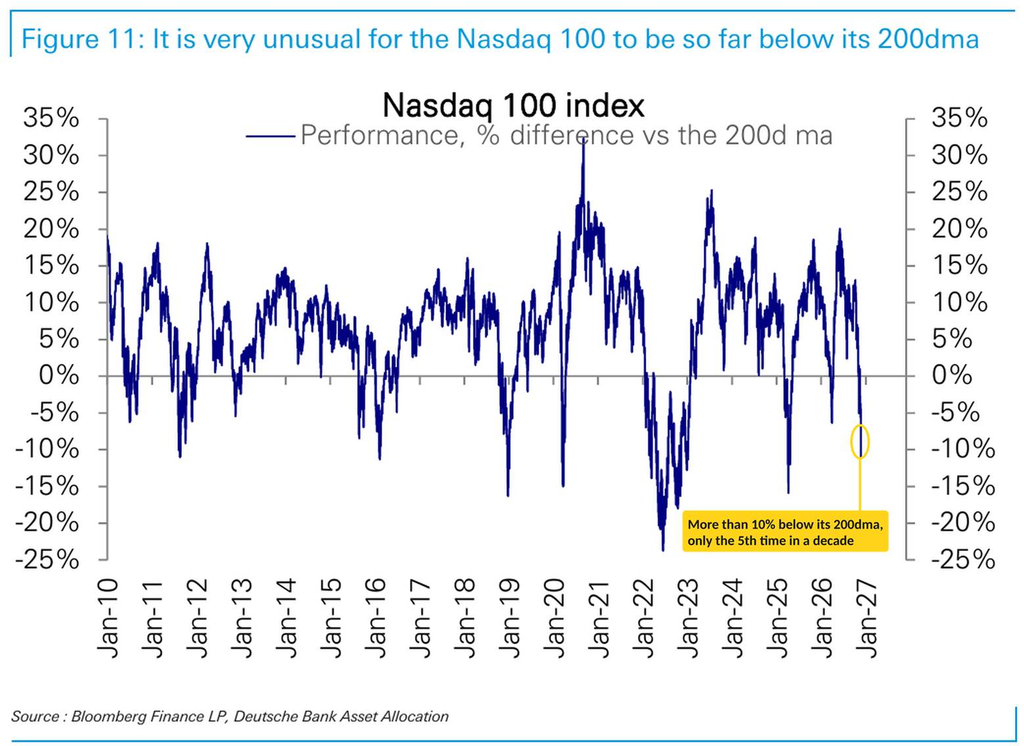
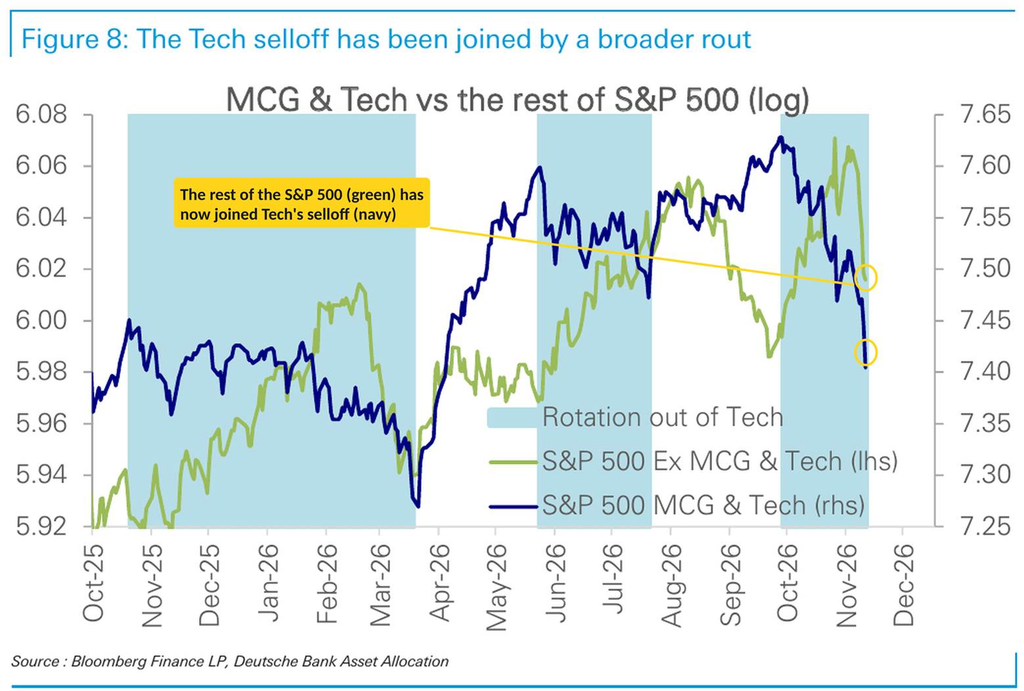
DB adds that the Tech selloff “has been joined by a broader rout,” with the rest of the S&P 500 (ex-Mega-Cap Growth and Tech) now falling sharply too.
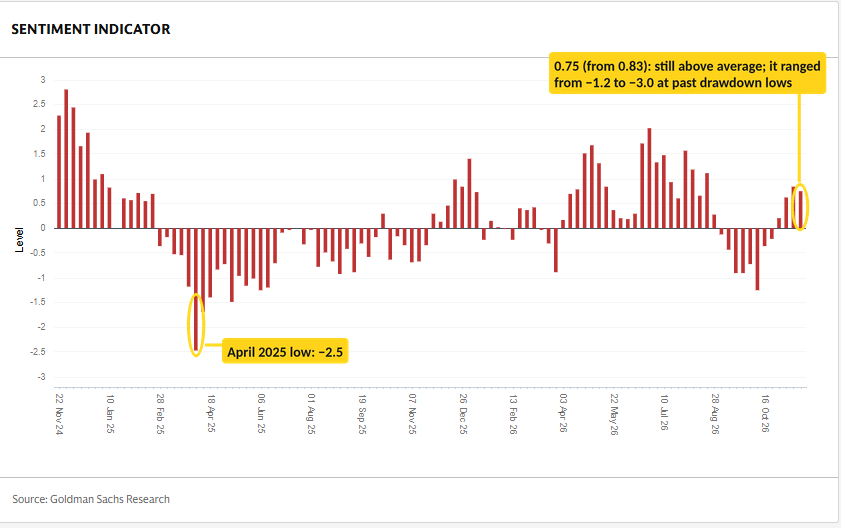
Goldman, though, says positioning hasn’t come down enough yet. It’s watching for one of three conditions to support a bottom: “news that increases investor confidence in the trajectory of future earnings associated with AI investment and monetization,” “an improvement in the macro backdrop, such as a dovish signal for Fed policy,” or “a major decline in investor positioning, such as has often marked the bottoms of past drawdowns.”
On that last one, “despite the hedge fund unwind, our indicator of broad equity investor positioning remains elevated.” Goldman’s Sentiment Indicator eased to 0.75 from 0.83, still above average, while at past drawdown lows it ranged from -1.2 (October 2022) to -3.0 (October 2011), including -2.5 in April 2025.
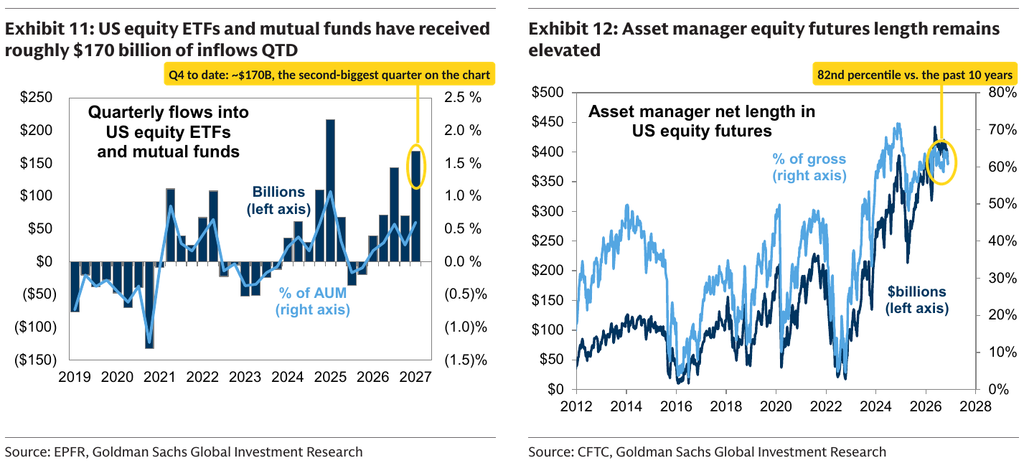
Hedge fund net leverage is the lowest since April 2025, but US equity mutual funds and ETFs have taken in about $150 billion over the past month (nearly $170 billion this quarter), and asset managers’ equity futures length is in the 82nd percentile of the past 10 years.
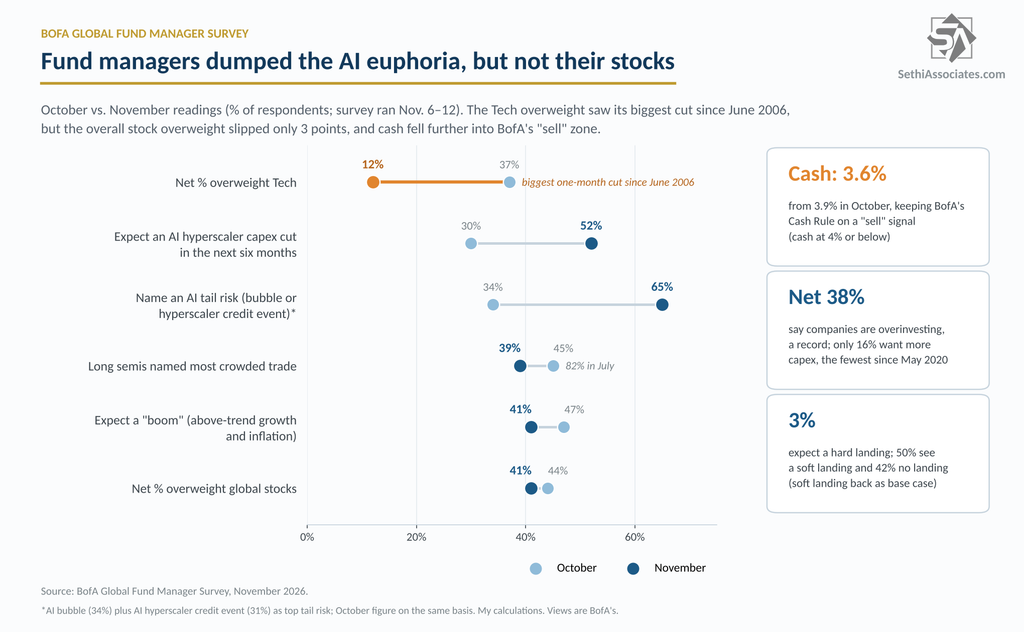
BofA’s November Global Fund Manager Survey makes the same point. Fund managers cut their Tech overweight to a net 12% from 37%, the biggest one-month cut since June 2006 (more here), as “euphoria on boom & AI” ended: 52% now expect an AI hyperscaler to cut capex in the next six months (from 30%), and a record net 38% say companies are overinvesting. But they’re not bearish on stocks overall. The equity overweight slipped only to a net 41% from 44%, and cash fell to 3.6% from 3.9%, still in BofA’s “sell” signal zone. Hartnett notes the best entry points for Tech have historically come when investors cut it to an underweight, and at a net 12% overweight they’re not there yet. On the economy, 50% now expect a soft landing, ahead of 42% for no landing, the first time since June it’s been the base case, and just 3% expect a hard landing (Fund Managers Cool on the Economy, but Don’t See a Recession).
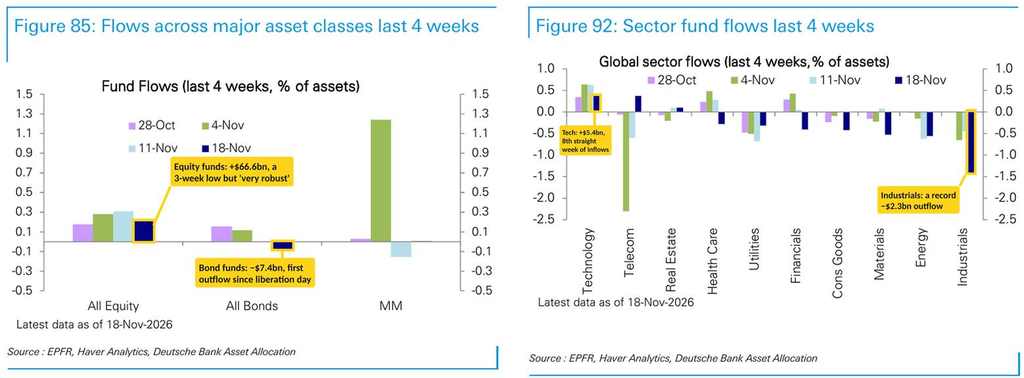
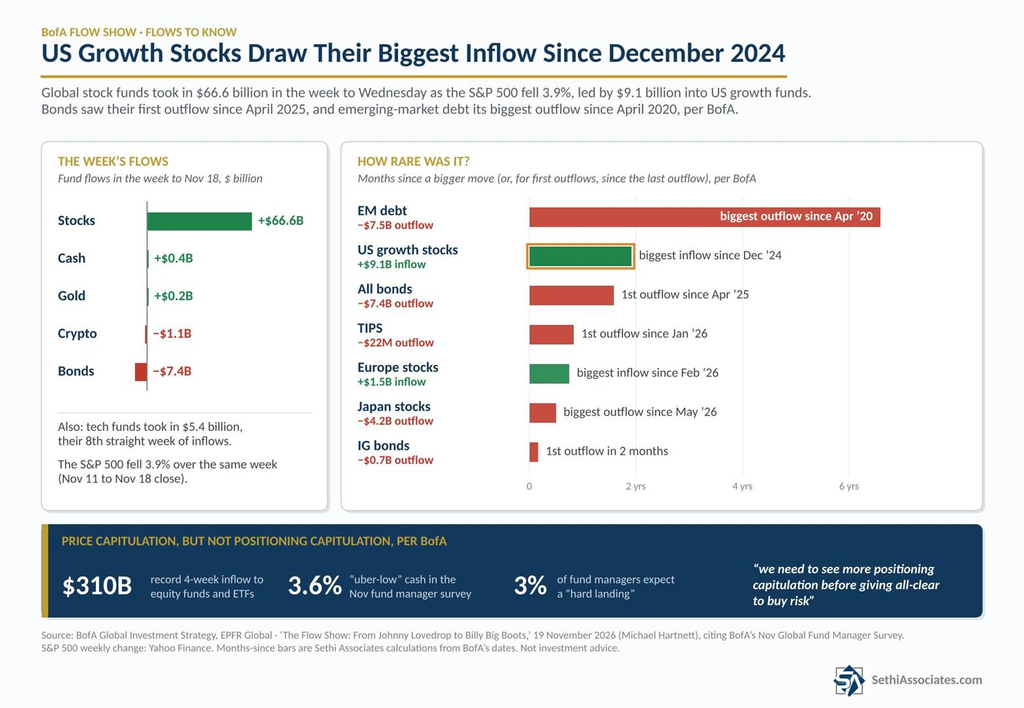
The fund flows also bear that out. Per DB’s read of EPFR data (week through Wednesday, November 18th), equity funds took in $66.6 billion, a three-week low but still “very robust,” down from $98.3 billion the prior week. US funds again led ($45.6 billion), and Tech funds took in $5.4 billion, their eighth straight week of inflows, while Industrials saw a record $2.3 billion outflow. Bond funds in contrast saw outflows (-$7.4 billion) for the first time since liberation day, including $7.5 billion out of EM bond funds, the most since March 2020. And money market funds took in just $0.4 billion, with US inflows ($21.9 billion) offset by outflows from Europe (-$25.4 billion).
Japan, though, saw its first outflows in six weeks (−$4.2 billion). Europe ($1.5 billion) took in money for a second week, and EM inflows ($8.3 billion) slowed to a six-week low.
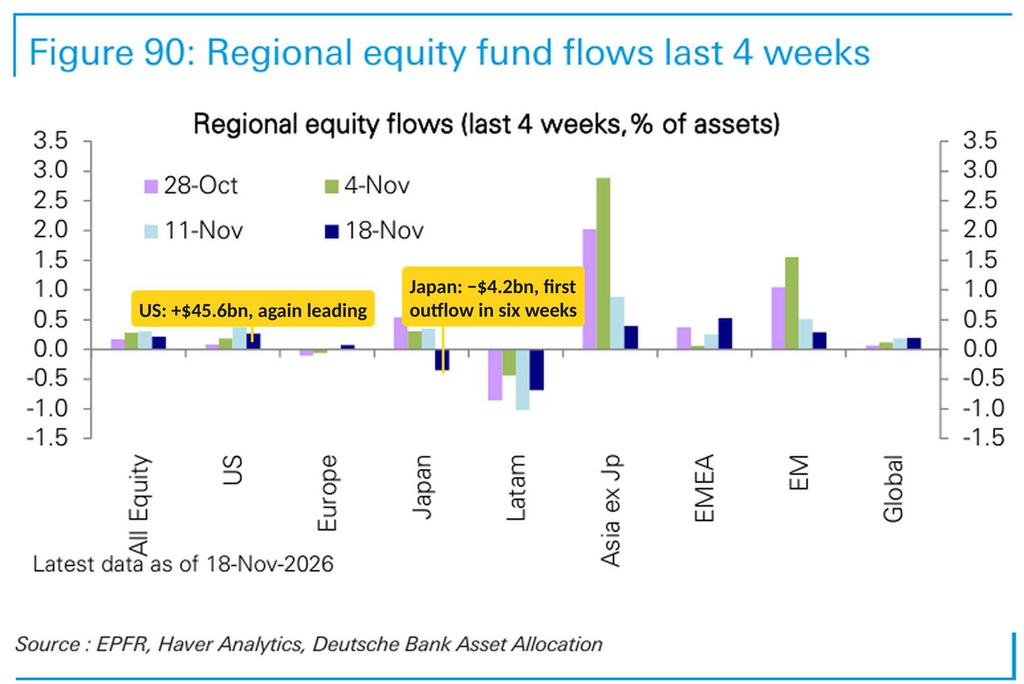
BofA’s read of the same EPFR data (Flow Show) shows US growth funds taking in $9.1 billion, the biggest inflow since December 2024, even as the S&P 500 fell 3.9% over the week through Wednesday. Japan stocks saw a $4.2 billion outflow, the biggest since May, while Europe took in $1.5 billion, the most since February. Hartnett’s take is similar to Goldman’s: “we need to see more positioning capitulation before giving all-clear to buy risk.”
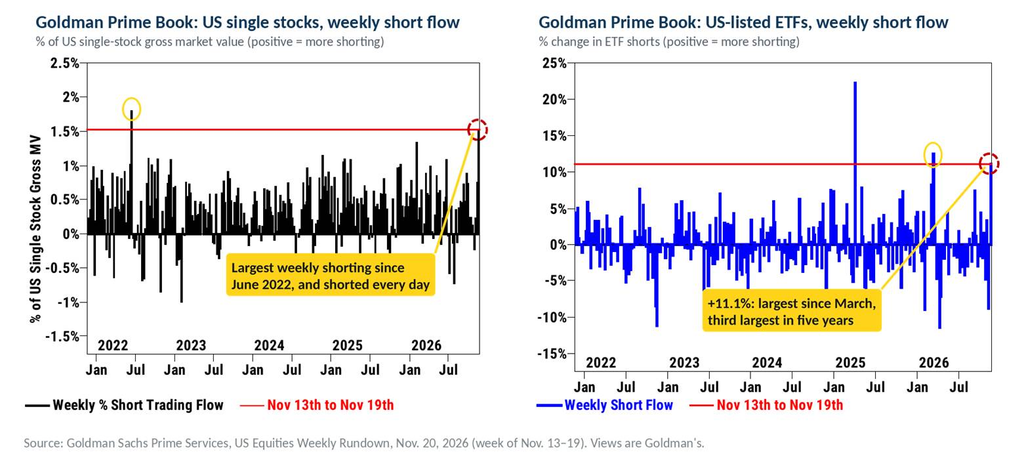
Hedge funds, in contrast, kept selling. Goldman’s Prime Book saw them net sell US equities for a third straight week (November 13–19, 6 of the last 7), with short sales outpacing long buys 1.4 to 1 in single stocks. They shorted single stocks every day, the largest weekly shorting since June 2022 and the third largest in a decade. They net bought macro products (index and ETFs) for a fourth week, but US-listed ETF shorts rose 11.1%, the largest percentage increase since March and the third largest in five years, led by large-cap, Financials, small-cap and credit ETFs.
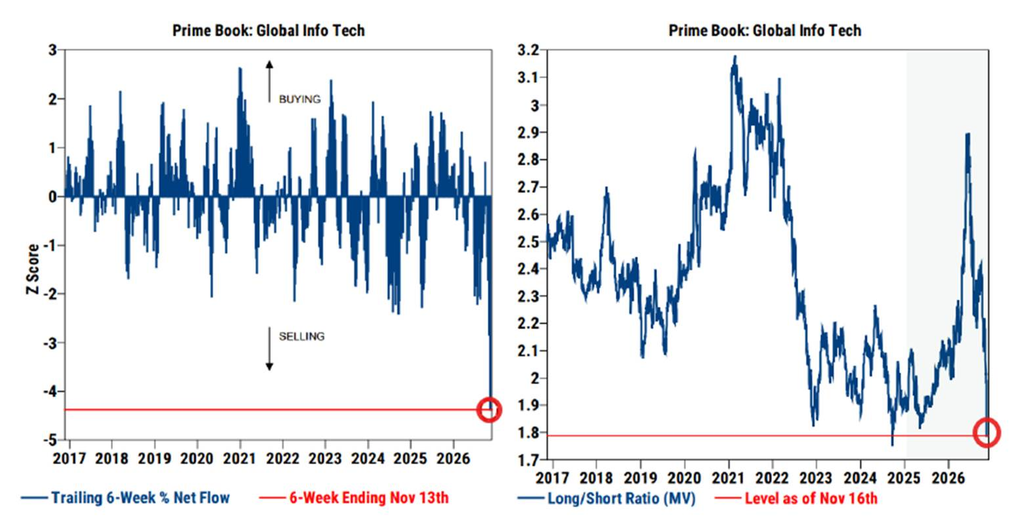
Financials were the most net sold sector (-2.2 SDs), at the fastest pace in more than five years, while Energy was the most net bought (+1.4 SDs), the largest percentage buying in more than seven months. Info Tech was one of only two sectors that were net bought on the week (with Energy), but Goldman’s derivatives desk says hedge funds sold tech “at the fast[est] pace on record over the last 6-weeks.”
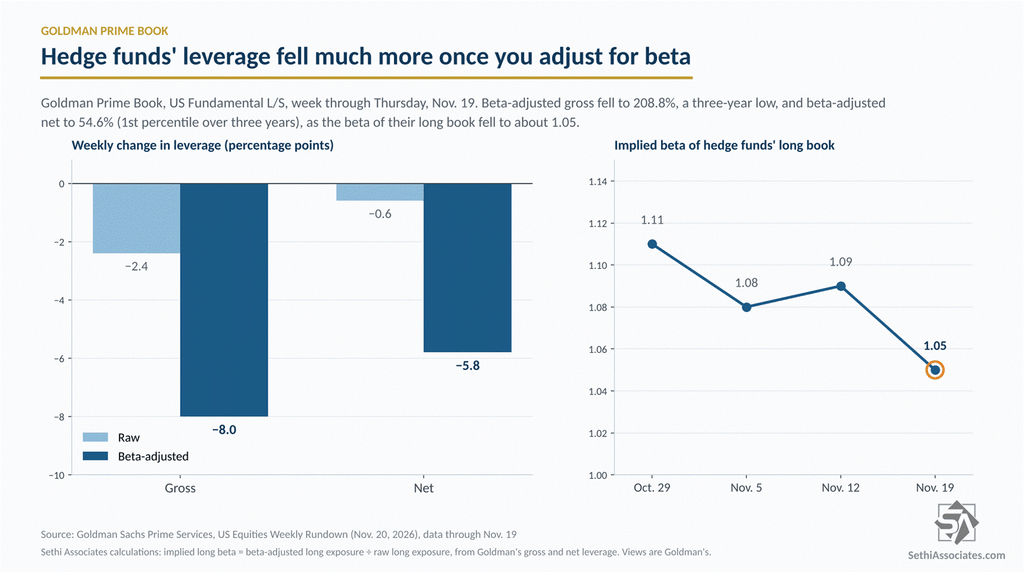
And the hedge fund selling continued to be in the higher-risk part of the book. Through Thursday, US Fundamental Long/Short gross leverage fell 2.4 points to 206.7% (21st percentile one-year), and net leverage fell 0.6 points to 44.8% (5th percentile). But beta-adjusted, gross fell 8.0 points to 208.8%, a three-year low (0th percentile on one- and three-year lookbacks), and net fell 5.8 points to 54.6% (0th percentile one-year, 1st three-year). For the month, beta-adjusted gross is down 16 points and net 9 points. The bigger drop in the beta-adjusted figures implies their longs’ average beta slipped to about 1.05 from 1.09, as the high-beta longs fell hardest.
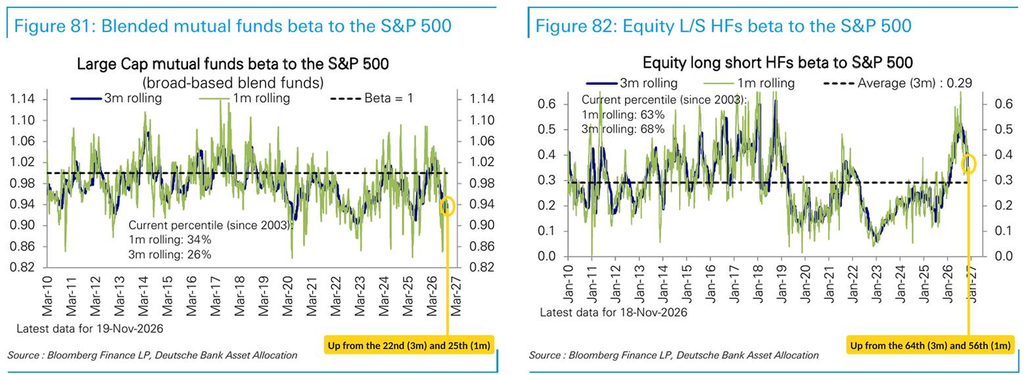
DB’s beta measures, which lag, actually rose though: equity long/short hedge funds’ rolling beta to the S&P 500 is at the 63rd percentile (since 2003) on a 1-month basis, from the 56th, and the 68th on a 3-month basis, from the 64th. So on this measure there remains a lot of higher-beta risk (likely Tech) on hedge fund books. Large-cap mutual funds are at the 34th on a 1-month basis (from the 25th) and the 26th on a 3-month basis (from the 22nd).
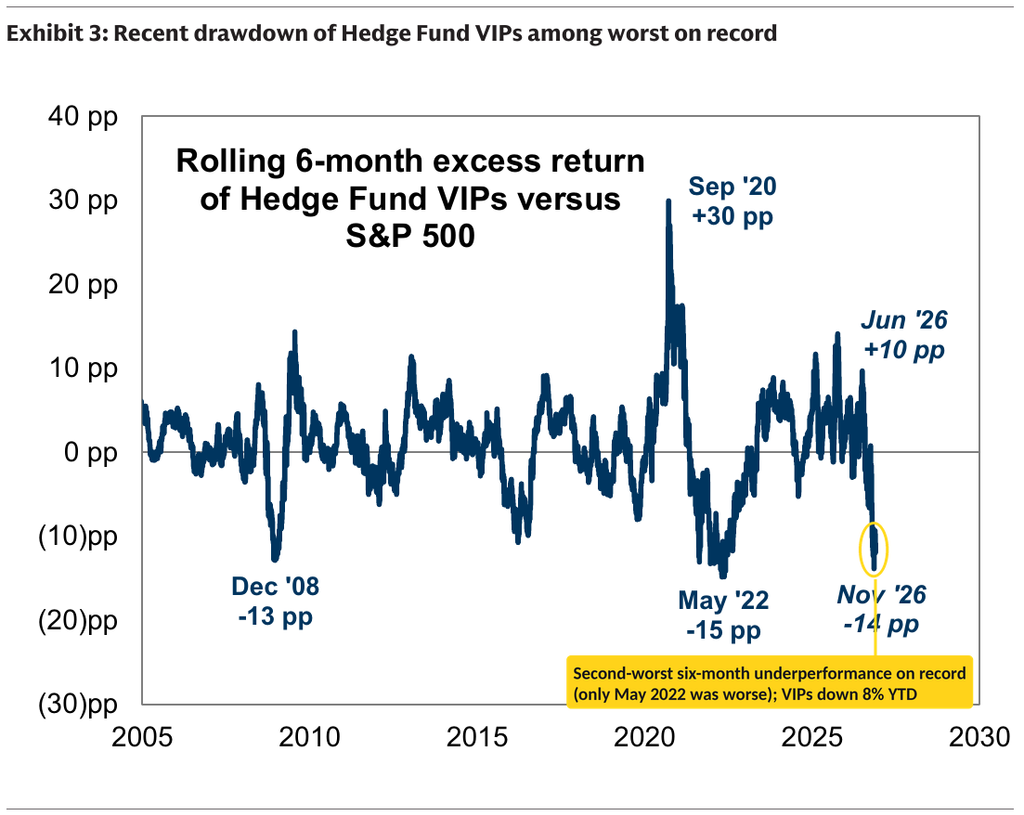
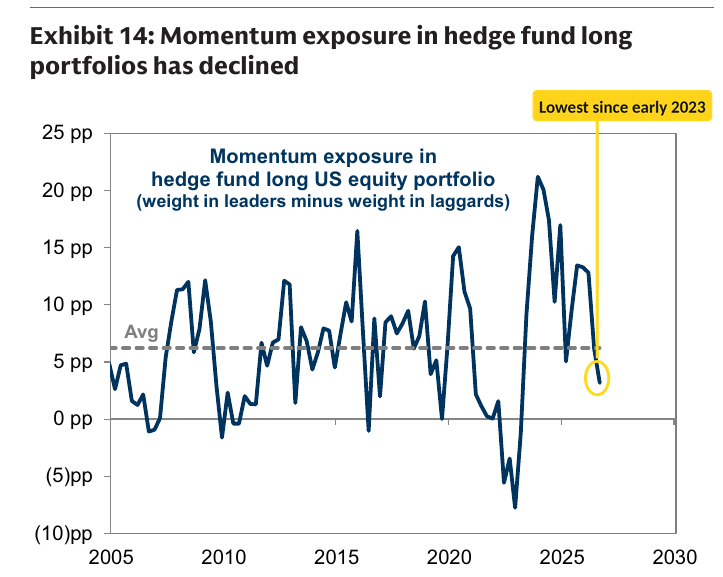
Goldman’s quarterly Hedge Fund Trend Monitor (13F holdings at the start of Q4) shows the damage from the AI unwind. Its basket of hedge funds’ most popular longs (VIP) is down 8% YTD, and its 14-point underperformance over the past six months ranks among the worst in its 20-year history (only May 2022 was worse, at 15 points). Long/short net exposures rival April 2025 as the lowest since before Covid. Funds cut TMT and added to cyclicals (Financials, Discretionary, Industrials) and defensives (Staples, Utilities), and momentum exposure is the lowest since early 2023. Goldman’s “rising stars” (stocks hedge funds have been adding) include Intel (INTC), Meta (META), Allstate (ALL), Home Depot (HD), IQVIA (IQV) and Merck (MRK), while Alphabet (GOOGL) and Qualcomm (QCOM) are falling out of favor.
Goldman’s derivatives desk sums it up: “Positioning is washed out, vol indicators are screaming oversold, sentiment is on the lows, and the panic we saw this week was palpable.” Its US vol panic index ended the week at a record (per ZeroHedge) at 9.8 out of 10 (6.5 a week earlier), and “historically, readings north of 9.5 have signaled near term relief.” The one-week jump in the VIX was the fifth largest on record, behind only October 10th, 2008, April 4th, 2025, February 28th, 2020 and May 7th, 2010. After those four, the S&P 500 was higher a year later every time (median +26.4%, vs. +11.9% for all days) and six months later in three (median +13.9%), but two weeks later only once (median −2.3%), per Goldman’s data.

But the desk’s bottom line is more cautious: “Technical indicators point to a potential near-term bounce, but further out the market is going to continue to face challenges until we get further clarity on the Fed’s path and the future of the AI trade.”
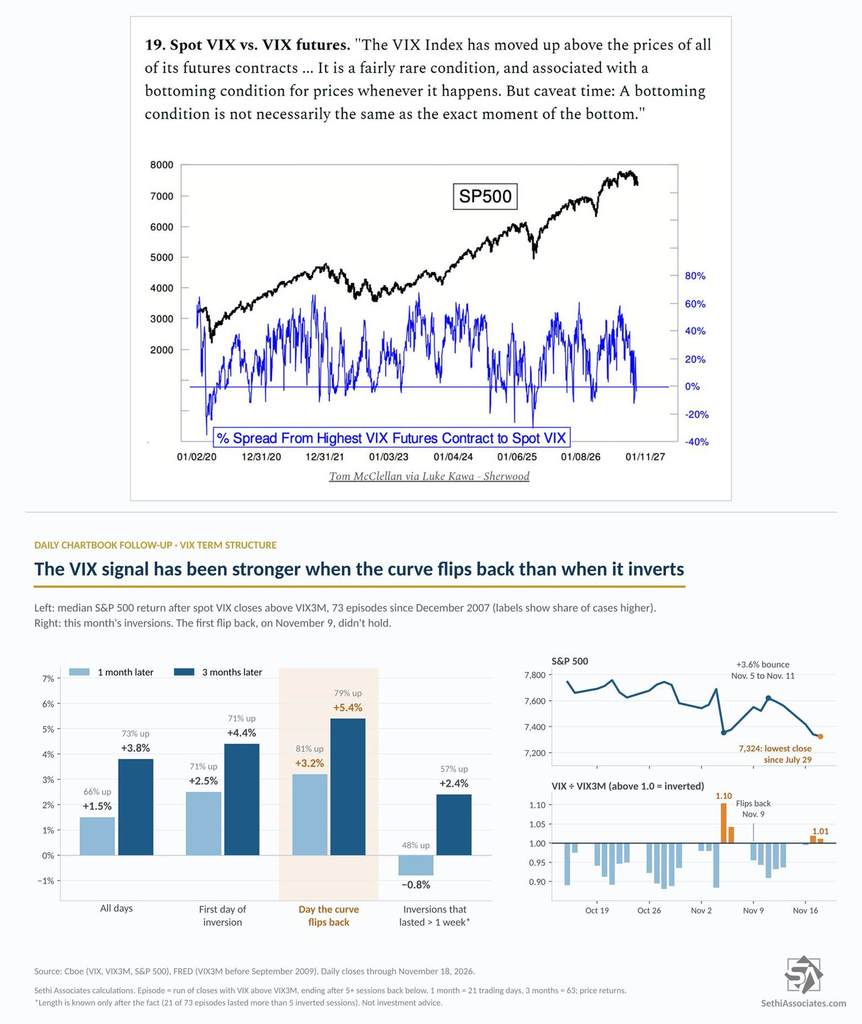
The VIX curve also inverted. Spot VIX closed above three-month VIX (VIX3M), which has happened on only about 10% of trading days since late 2007 (75 episodes), and Tuesday it also closed above six-month VIX, a “fairly rare condition” that Tom McClellan ties to “a bottoming condition for prices,” though “not necessarily the exact moment of the bottom.” By my calculations, the S&P 500 has done better than average a month after the first day of an inversion (median +2.5%, 71% higher) and better still on the day the curve flips back (+3.2%, 81%), vs. +1.5% and 66% for all days. The problem is the inversions that drag on: the 21 that lasted more than a week (2008, 2011, late 2018 and 2020 among them) saw a median -0.8% the next month. So the more useful tell is a flip back that sticks.
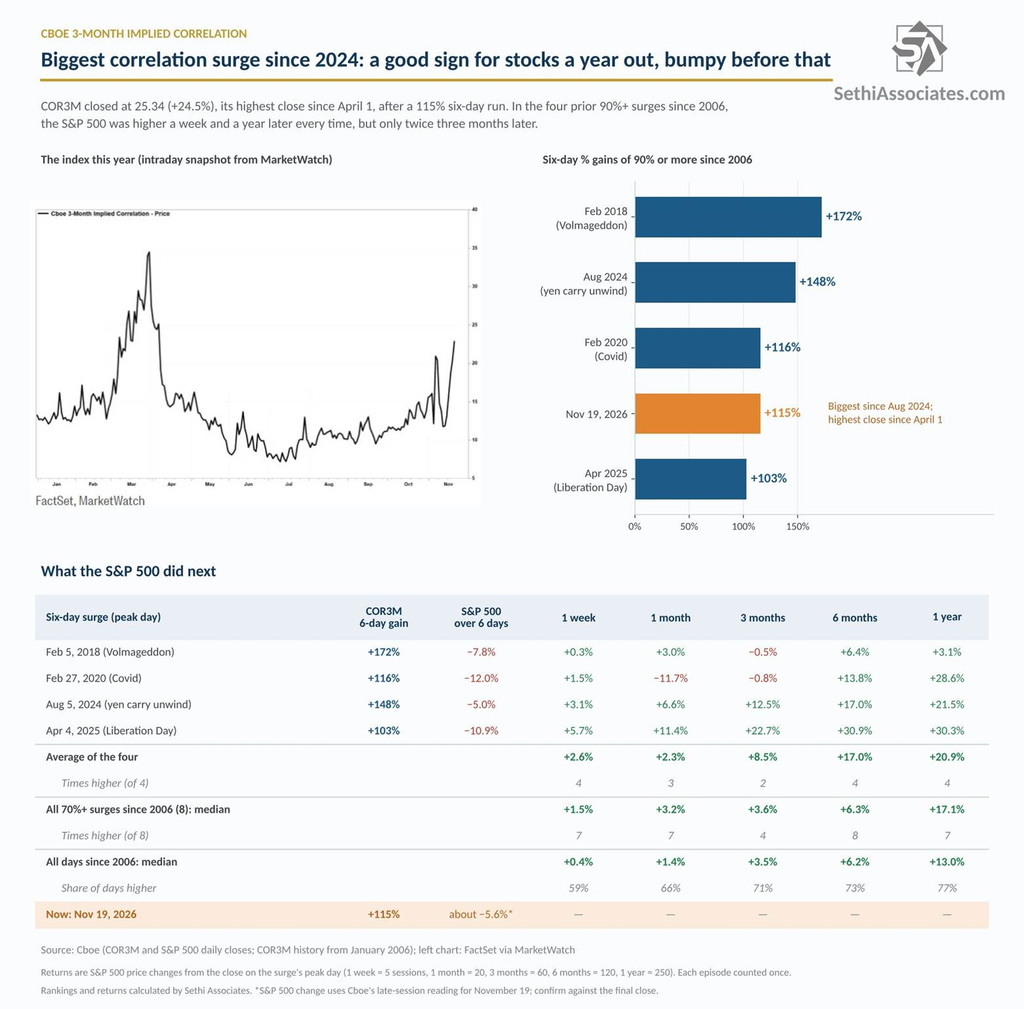
Stocks are also increasingly moving together, often a sign of market stress. Cboe’s 3-month implied correlation index (COR3M) jumped to 25.34 Thursday, its highest since April 1st, after rising 115% over six days, the biggest six-day rise since the August 2024 yen carry unwind and bigger than during liberation day. Since stocks have mostly fallen, that means investors are cutting equity risk across the board, not just selling AI to buy something else.
The good news is after the four prior surges of 90% or more since 2006, the S&P 500 was higher a week, six months and a year later every time (average one-year gain 20.9%), though only twice three months later. Surges like this tend to come in the “sell everything” phase of a pullback, which has usually been nearer the end than the start (Stocks Are Suddenly Moving in Lockstep. That’s Been Bullish in the Past).
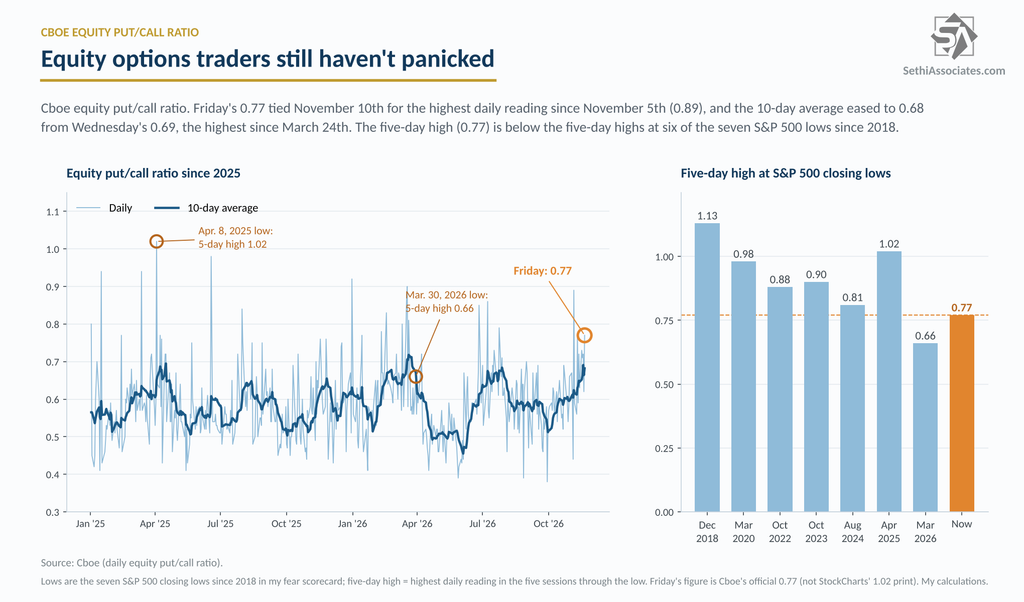
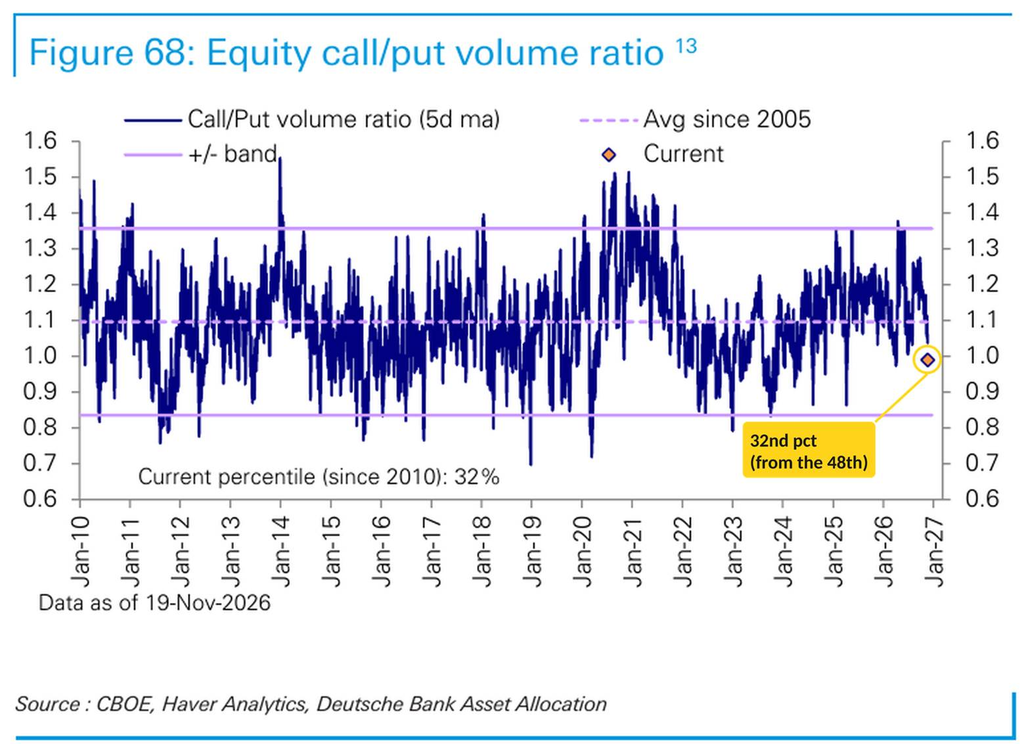
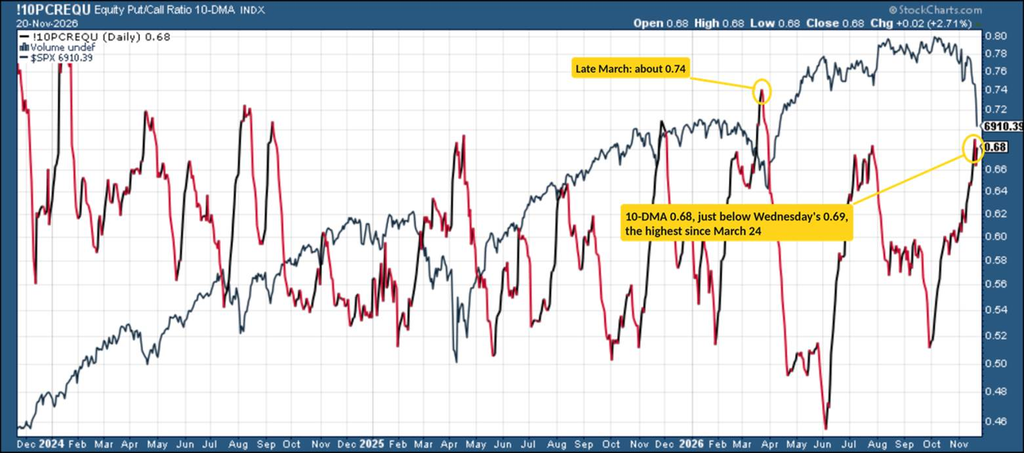
Options volumes show more hedging, but more in index and ETF products than in single stocks. Cboe’s equity put/call ratio ended the week at 0.77 (its 10-DMA at 0.68, just below Wednesday’s 0.69, the highest since March 24th), while the total put/call ratio was 1.13, index options 1.27 and ETF options 1.35. DB’s call/put ratio (5-DMA) fell to the 32nd percentile (from the 48th), and S&P 500 skew rose.
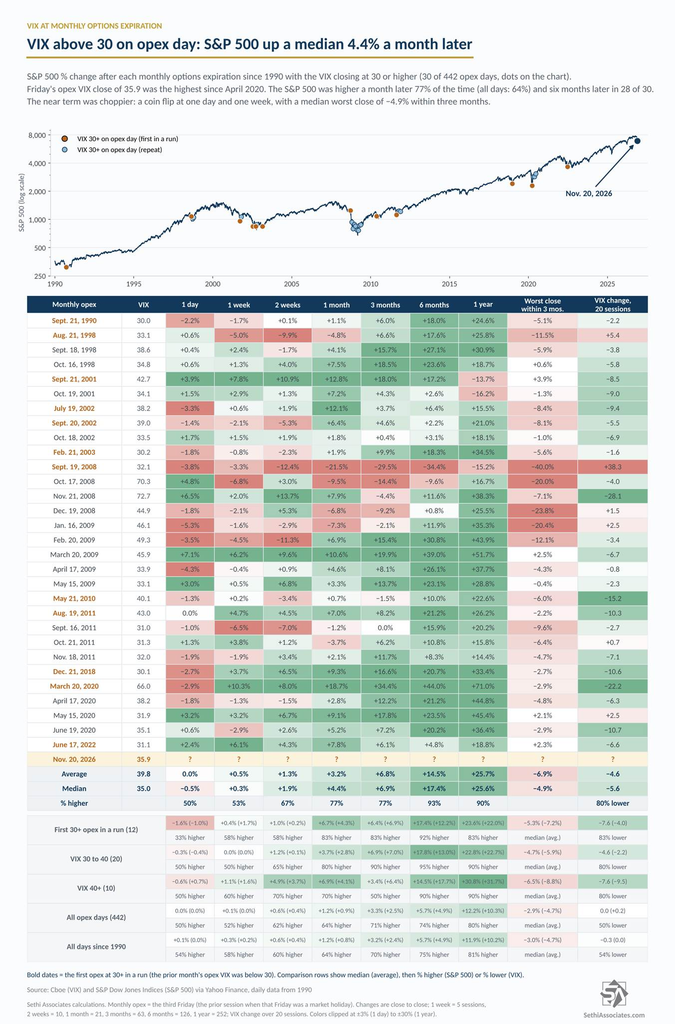
Friday was also monthly options expiration, and the VIX closed at 35.9, its highest on an expiration day since April 2020. Since 1990, there have been 30 monthly expirations with the VIX at 30 or higher. Here’s what they show, vs. all days since 1990:
The first week was basically a coin flip, with the S&P 500 higher about half the time. One month later, the median gain was 4.4%, and the S&P 500 was higher 77% of the time (all days +1.2%, 64%). Six months later, the median gain was 17.4%, and the S&P 500 was higher in 28 of 30 cases (all days +5.7%, 75%). The downside often came first: the median worst close within three months was 4.9% below the expiration-day close (all days 3.0%). The worst case was September 2008, with the S&P 500 down 21.5% a month later and as much as 40% within three months.
Many of those readings came in clusters (nine in 2008–09), but counting only the first expiration in each run (12 cases), the S&P 500 was higher a month later 83% of the time (median +6.7%) and six months later 92% of the time (median +17.4%).
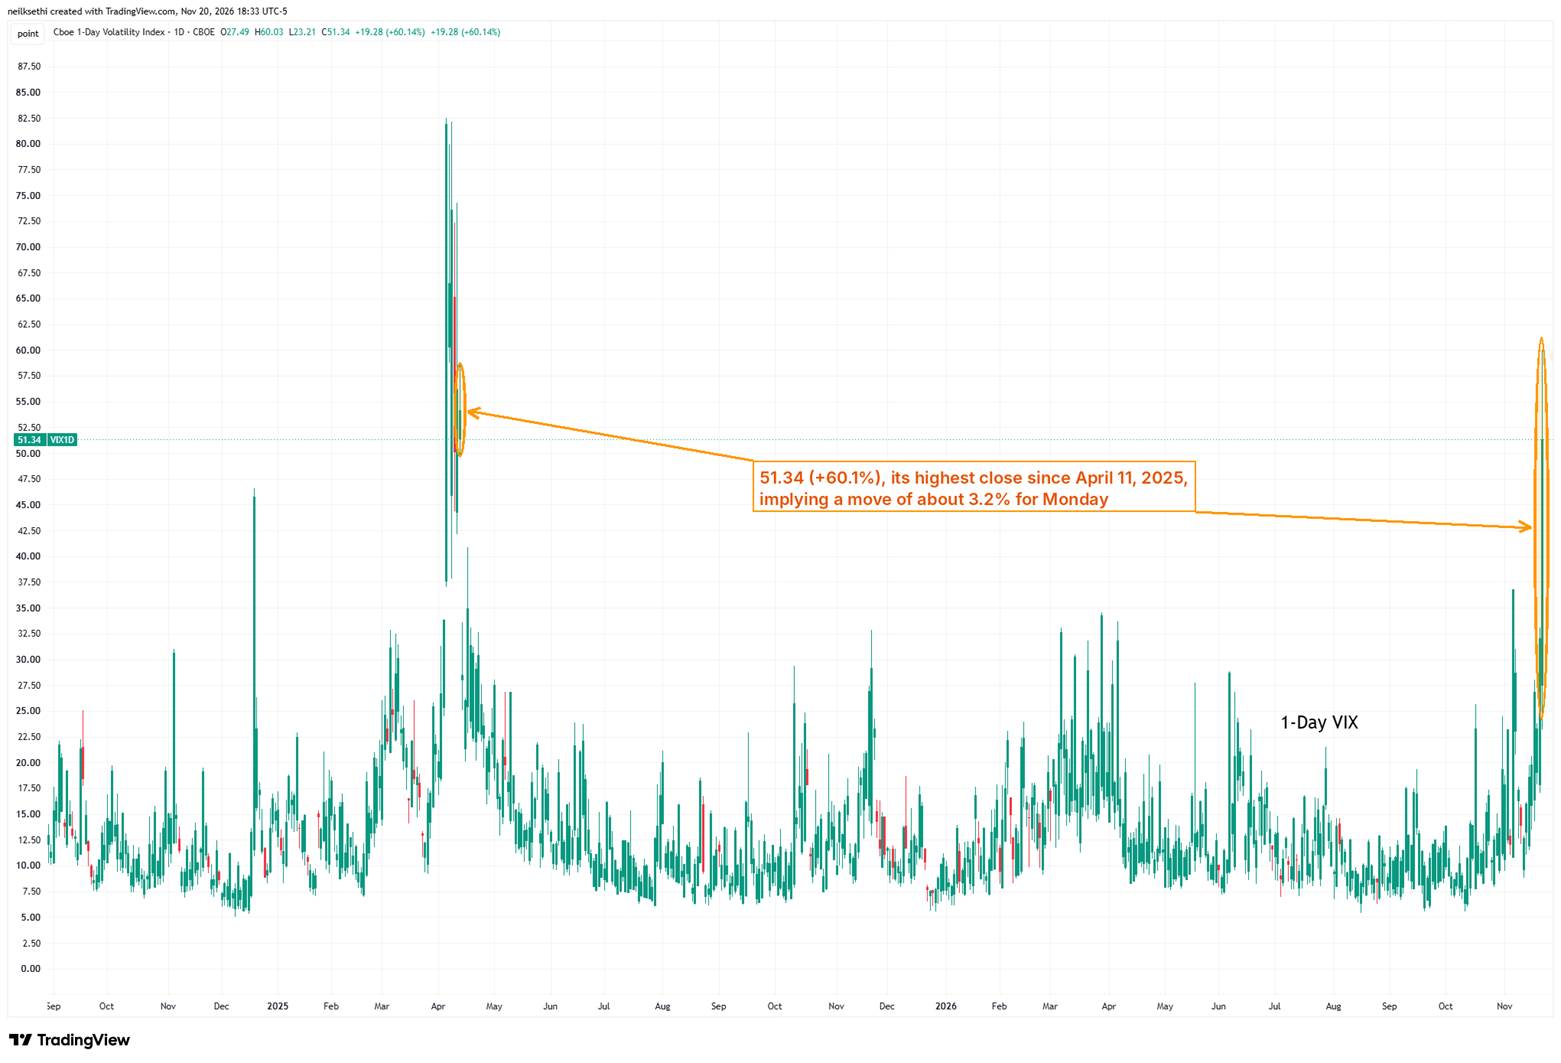
For perspective, options are pricing a 3.27% move for the S&P 500 through Friday, November 27th (per Goldman). It fell 8.6% last week, though, and the 1-Day VIX is pricing a 3.23% move for Monday alone.
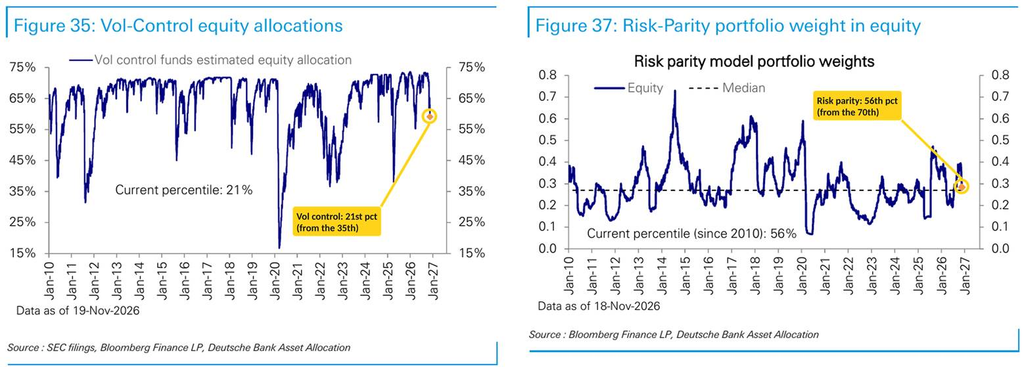
Turning to the systematic community, DB says vol control funds cut their equity allocation again (21st percentile, from the 35th), “while their sensitivity to further market selloffs rose modestly.” Risk parity funds also have finally started to more notably trim their equity allocation (56th percentile, from the 70th).
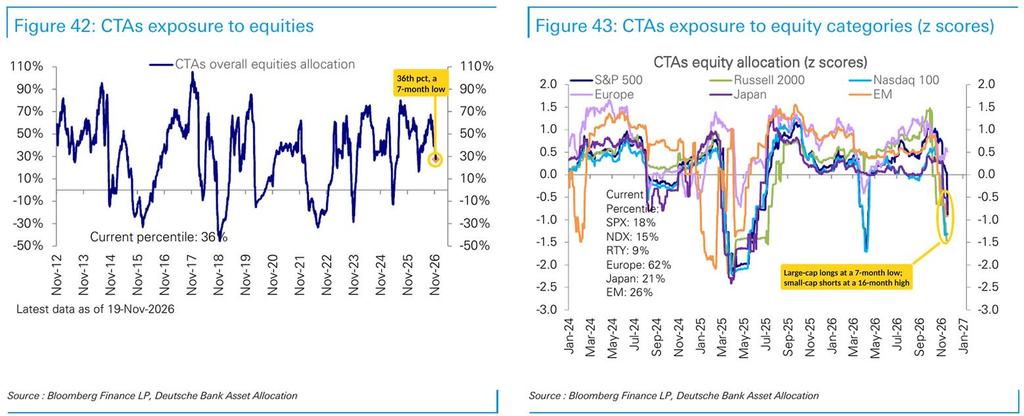
CTAs’ equity allocation fell to its lowest in seven months (36th percentile), with their positioning in US large caps also at a seven-month low (18th percentile), shorts in small caps at a 16-month high (9th) and the Nasdaq-100 still slightly short (15th).
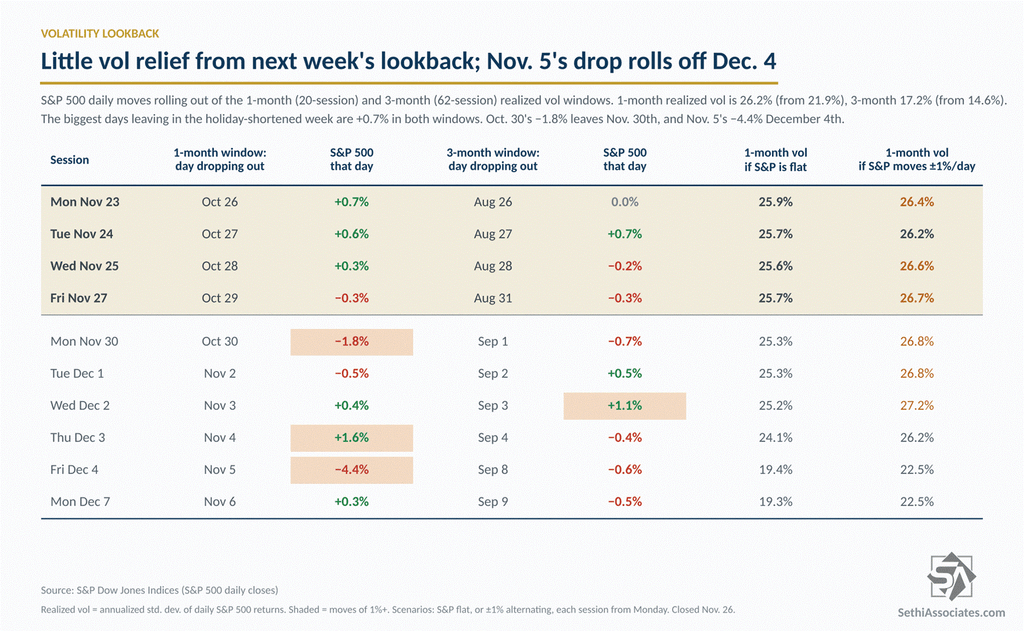
Looking at the potential for vol-control funds to rebuild exposure,, one-month realized volatility jumped to 26.2% last week (from 21.9%), the highest since early May 2025, and three-month to 17.2% (from 14.6%), the highest since early July 2025, by my calculations. The lookback window won’t help much in the holiday-shortened week. The biggest days dropping out are +0.7% in both windows, so even a flat S&P 500 would only ease one-month vol to about 25.7% by Friday. The relief comes the following week, when October 30th’s -1.8% rolls off Monday, November 30th, and November 5th’s -4.4% on December 4th (jobs report day), which would take it to about 19.4% if the S&P 500 stayed flat. That matters for vol-control funds, which size their equity exposure off realized volatility.
Goldman estimates CTAs are now net short $19 billion of US equities after selling $57 billion over the past month, and its forecasts show them “selling in every scenario over the next week,” with the S&P 500 below all three of its trigger levels (7,596 short-term, 7,540 medium-term and 7,119 long-term).
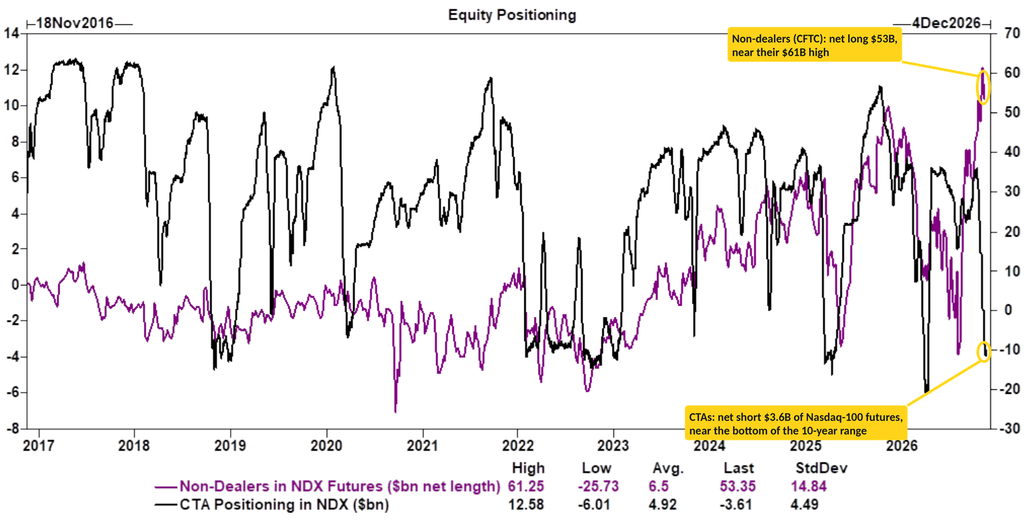
Its derivatives desk says CTA positioning in Nasdaq-100 futures “is near the bottom end of the 10-year range,” and “this seems closer to the end than the beginning to us.” “On the flip side, CFTC data still has non-dealer positioning near the highs.”
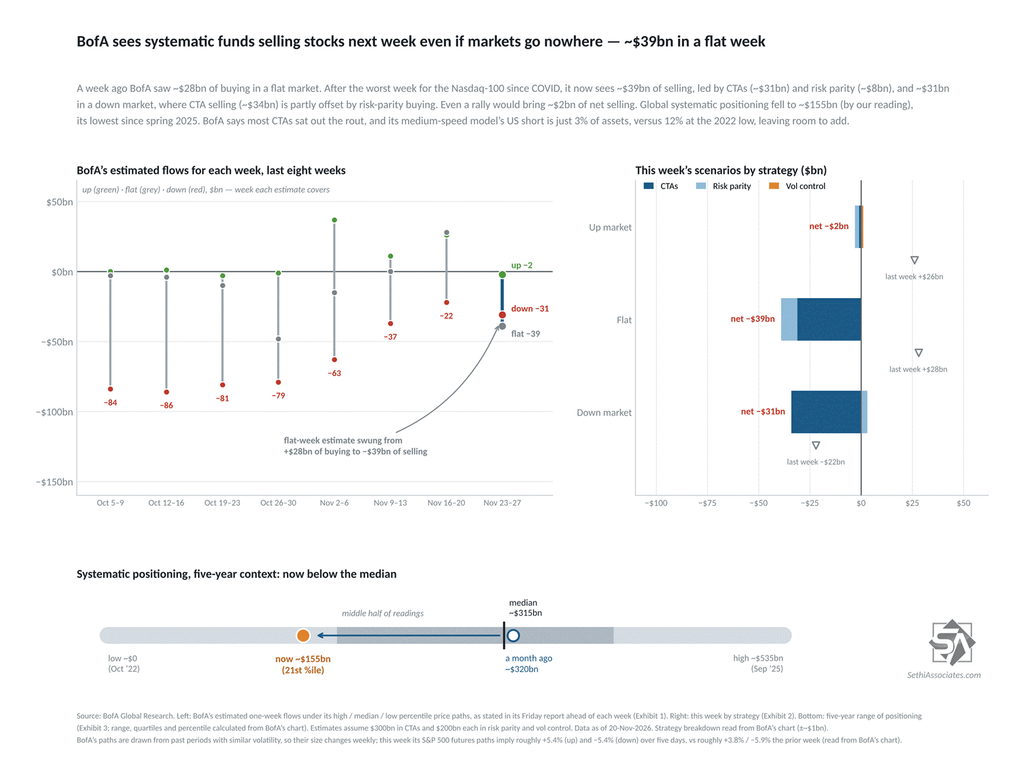
BofA also sees systematic funds selling stocks next week even if markets go nowhere. It again lists no sell triggers for the S&P 500, Nasdaq-100 or Russell 2000, and says most CTAs sat out last week’s tech rout, the worst week for the Nasdaq-100 since Covid: the fastest models were already short, while slower ones were still positioned for the prior uptrend. Its medium-speed model’s US short is just 3% of assets, versus 12% at the 2022 low, leaving room to add.
Specifically they see:
- −$39B of selling in a flat market (from +$28B of buying last week), led by CTAs (~$31B) and risk parity (~$8B).
- −$2B of selling in an “up” market (BofA’s high-percentile path, roughly +5.4% for S&P 500 futures over five days this week; from +$26B of buying last week), as small selling from CTAs and risk parity outweighs vol-control buying.
- −$31B of selling in a “down” market (BofA’s low-percentile path, roughly −5.4% for S&P futures this week; from −$22B last week), as CTA selling (~$34B) is partly offset by risk-parity buying (~$3B).
Global systematic positioning fell to ~$155B (by our reading of BofA’s chart), its lowest since spring 2025 and down from ~$320B a month ago.
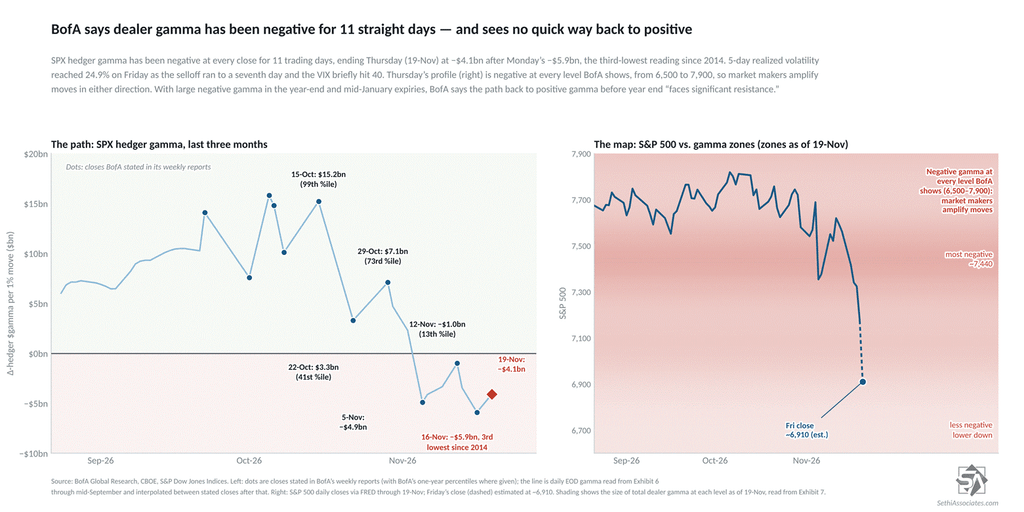
Consistent with last week’s note which said BofA saw no reasonable path to positive gamma for the week, BofA says SPX hedger gamma has remained negative at every close for 11 trading days, ending Thursday at −$4.1B after Monday’s −$5.9B, the third-lowest reading since 2014. Five-day realized volatility reached 24.9% on Friday.
Thursday’s profile is again negative at every level BofA shows, from 6,500 to 7,900, so market makers would continue to notably amplify moves in either direction according to BofA’s modeling. With large negative gamma in the year-end and mid-January expiries, BofA says the path back to positive gamma before year end “faces significant resistance.”
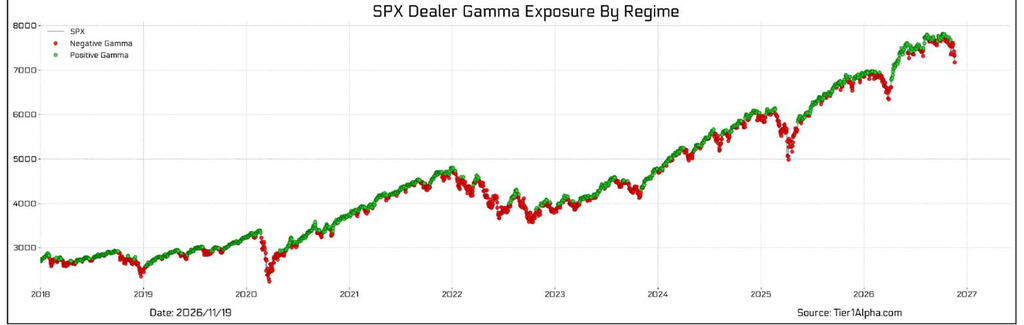
Tier1Alpha though sees Friday’s monthly expiration as a potential turning point. While it also has dealers very short gamma, it says the expiration, with an estimated $2.3 trillion in notional open interest, “should help clear out much of the negative gamma exposure dealers have had to manage over the past several weeks, which has mechanically amplified volatility and contributed to forced deleveraging from systematic funds.”
It points to three factors. Aggregate monthly gamma falls to its cyclical lows after expiration, positions established at higher strikes get rolled lower, and “more organic price action can exert greater influence as mechanical hedging pressures ease.” It calls that last one “the largest unknown risk factor in the current setup, since discretionary selling can continue even as dealer hedging pressures subside.”
Since 2012, it counts 37 other times the S&P 500 was in negative gamma heading into monthly expiration with the VIX above 20. In 81% of them, the VIX was lower a week later and stayed below its pre-expiration level over the following month, and in 68% it closed back below 20 at least once along the way. It views this expiration as “a strong potential inflection point rather than a guaranteed reversal,” but “if volatility does begin to subside next week, there is a high probability that a subsequent wave of mechanical releveraging would follow.”
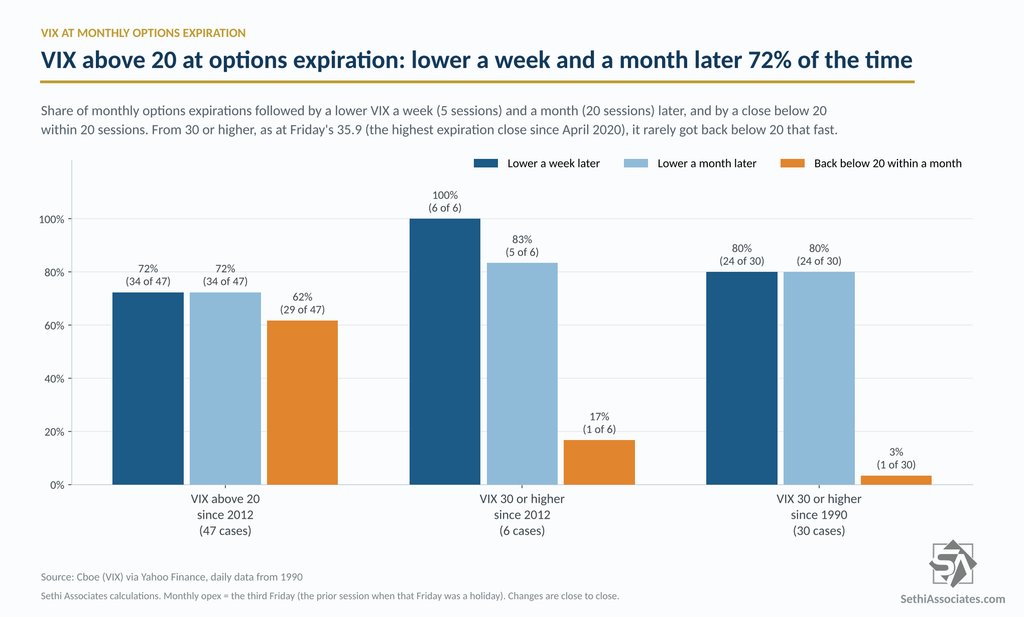
My own numbers point the same way, with a caveat on timing. Without Tier1Alpha’s gamma filter, the VIX was lower a week later after 72% of the 47 monthly expirations since 2012 with the VIX above 20, and lower a month later after 72%, while it closed back below 20 within a month 62% of the time. From 30 or higher, though, as on Friday, it has taken longer to get back below 20. In the six such cases since 2012, the VIX was lower a week later every time and a month later in five, but only one got back below 20 within a month. Going back to 1990, the VIX was lower 20 sessions after a 30+ expiration 80% of the time (24 of 30), by a median 5.6 points.
Turning to leveraged ETFs, which also add to the volatility of moves, BofA says leveraged and inverse ETFs now need to trade ~$855M of S&P 500 and ~$1.9B of Nasdaq-100 per 1% move, about $2.7B combined, after falling $184M and $531M with prices last week. By our calculations all three figures are at their lowest since late March. Because these ETFs buy on up days and sell on down days, the flow accelerates moves into the 4pm close, equal to about 2% of S&P closing-window volume and ~14% for the Nasdaq-100.
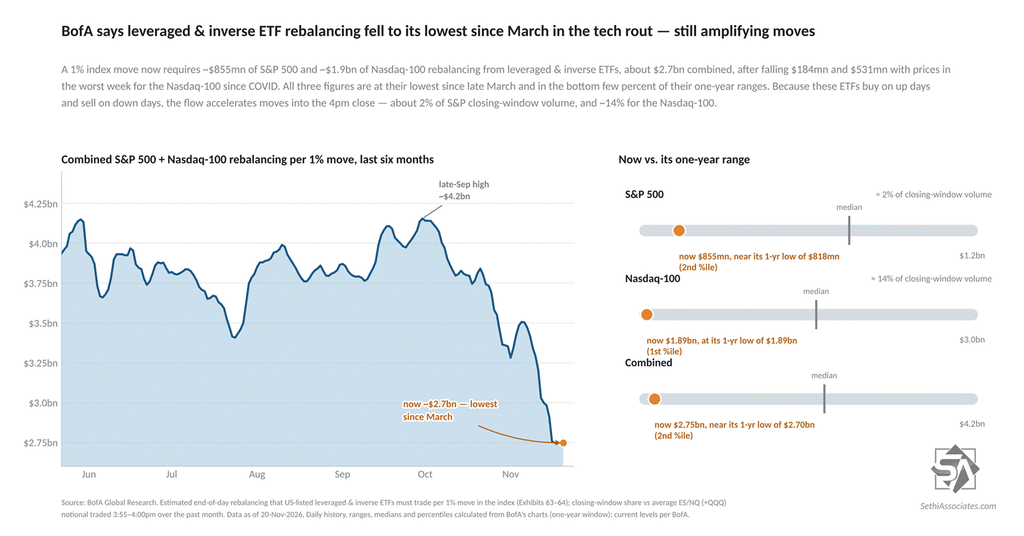
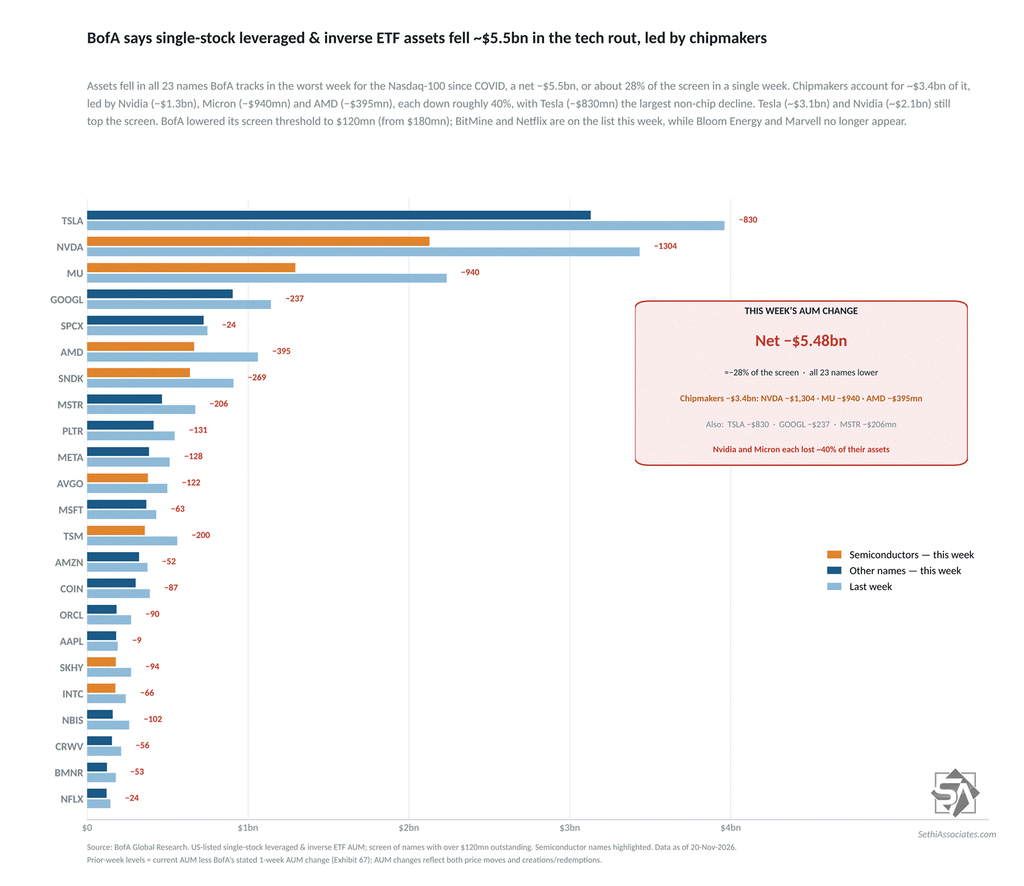
BofA says single-stock leveraged and inverse ETF assets fell a net ~$5.5B last week, with all 23 names it tracks lower, about 28% of the screen in a single week. Chipmakers accounted for ~$3.4B of it, led by Nvidia (NVDA) (−$1.3B), Micron (MU) (−$940M) and Advanced Micro Devices (AMD) (−$395M), each down roughly 40%. Tesla (TSLA) (−$830M) was the largest non-chip decline. Tesla (~$3.1B) and Nvidia (~$2.1B) still top the list in terms of AUM.
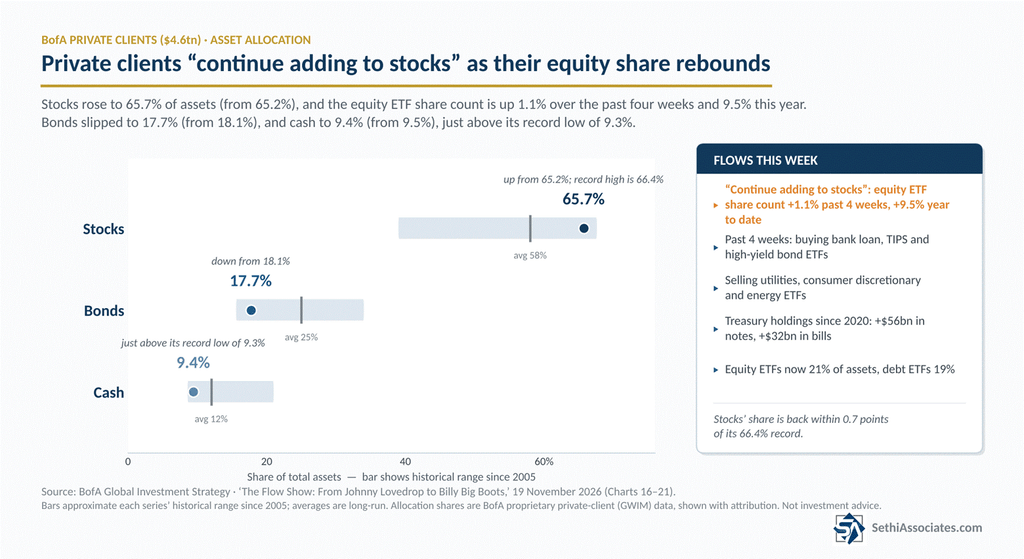
BofA’s Hartnett (Flow Show) says BofA’s private clients ($4.6 trillion in assets) “continue adding to stocks,” with their equity ETF share count up 1.1% over the past four weeks and 9.5% this year. Despite the drawdown, stocks rose to 65.7% of assets from 65.2%, within 0.7 points of their 66.4% record, while bonds slipped to 17.7% from 18.1% and cash to 9.4% from 9.5%, just above its record low of 9.3%.
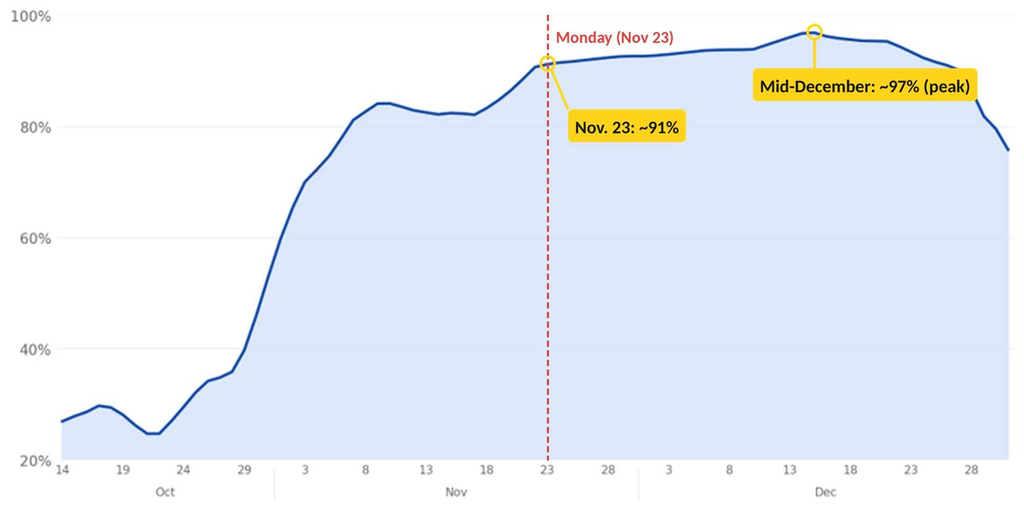
Turning to corporate buybacks (an important source of underlying demand), the blackout period is now largely behind us. Citadel estimated last week that about 91% of S&P 500 index weight would be eligible to repurchase shares by Monday (November 23rd), peaking near 97% in mid-December, before falling back late in the month as the next blackout begins.
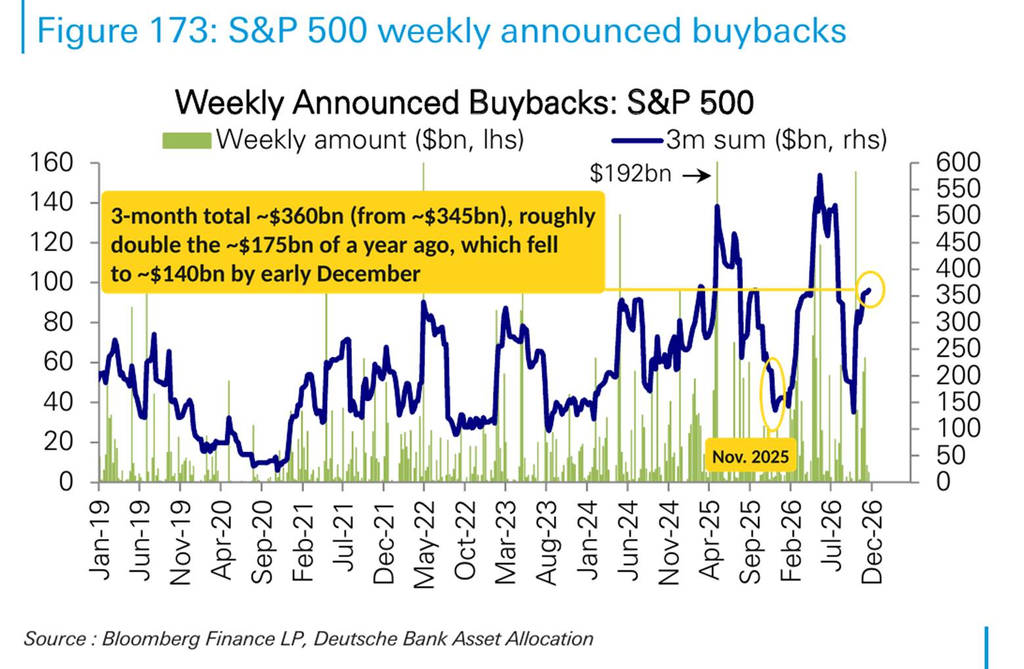
DB’s tally of announced S&P 500 buybacks over the past three months rose to about $360B (from ~$345B), roughly double the ~$175B of a year ago, although last year it fell to about $140B by early December.
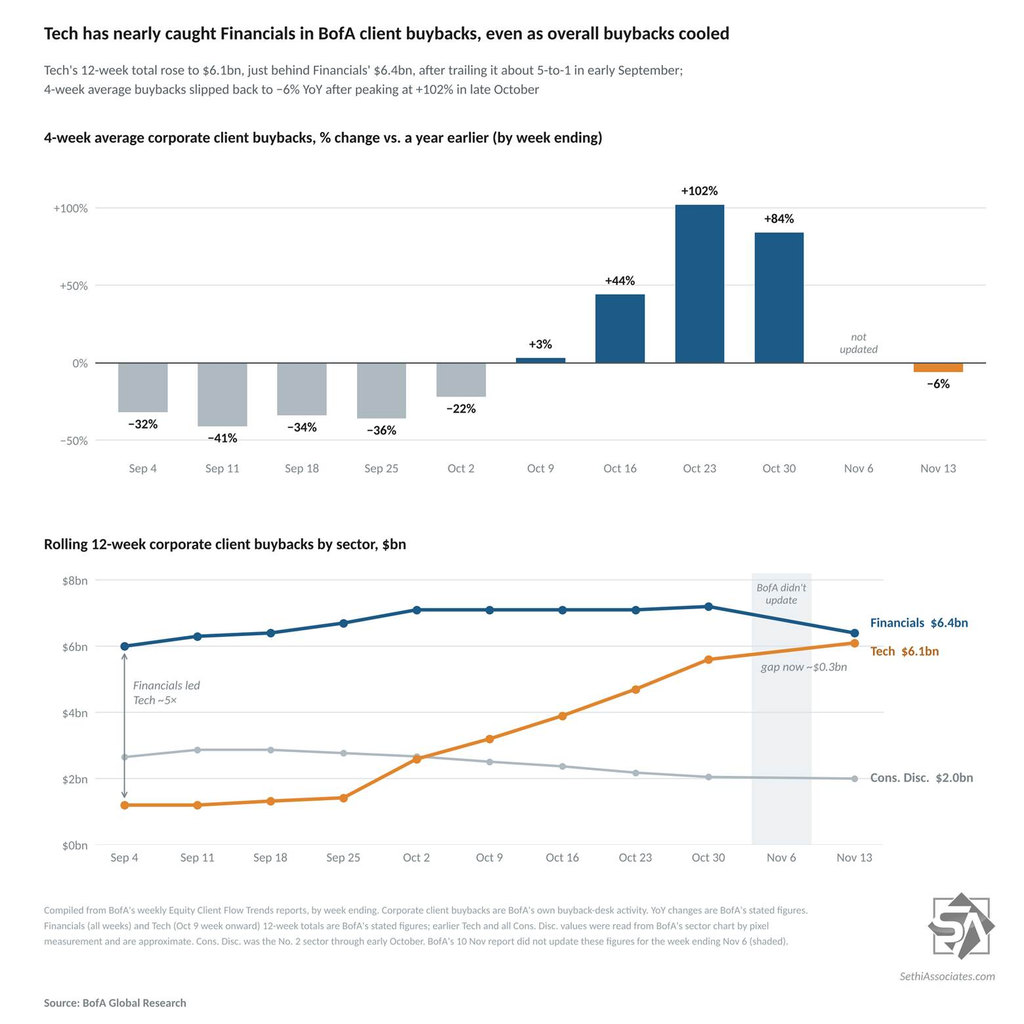
BofA saw corporate client buybacks slow for a second week in the week ending November 13th, remaining below their seasonal average. On a 4-week average basis they fell to -6% vs. the year earlier, from +84% in late October. Financials still lead the past 12 weeks at $6.4 billion, but Tech ($6.1 billion) has nearly caught up after trailing by roughly 5x in early September, by our calculations. BofA said annualized cumulative buybacks YTD are tracking below 2024-25 levels, though above 2010-23 annual levels. “Rolling 52-wk buybacks as a % of S&P 500 market cap are the lowest since Aug. 2021.”
Breadth Breaks Down, but the Typical Stock Fell Less Than the Index
Breadth deteriorated sharply last week on all three exchanges I track. The share of NYSE and Nasdaq stocks above their 200-DMAs fell to the lowest since the spring of 2025, and the McClellan Summation Index’s rollover was confirmed as the NYSE broke its pre-turn low. But the selling was concentrated in the biggest names, and the equal-weight S&P 500 held up better than the cap-weighted index.
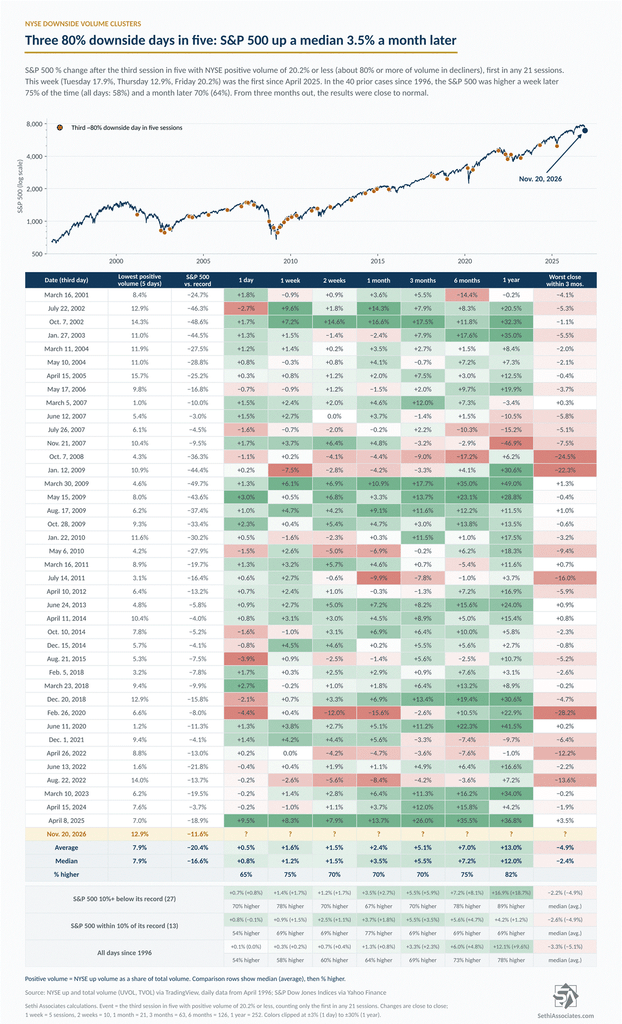
Downside volume was heavy all week. NYSE downside volume was 82.1% of the total Tuesday, 87.1% Thursday and 79.8% Friday, with Thursday’s 12.9% upside volume the lowest since May 21st, 2025 (9.3%). And new 12-month lows jumped to nearly 1,100 Friday from 725 Thursday, per Rev Shark.
As mentioned in the Saturday’s chart update, that’s the first time since April 2025 that we’ve had three days of about 80% downside volume within five sessions, and history says that has tended to be good for stocks, at least in the near term. In the 40 prior cases in data back to 1996, the S&P 500 was higher a week later 75% of the time (median +1.2%, vs. 58% and +0.3% for all days) and a month later 70% of the time (median +3.5%, vs. 64% and +1.3%).
From three months out, though, the results were close to normal. When the S&P 500 was already at least 10% below its record, as it is now (27 cases), it was higher a year later 89% of the time (median +16.9%).
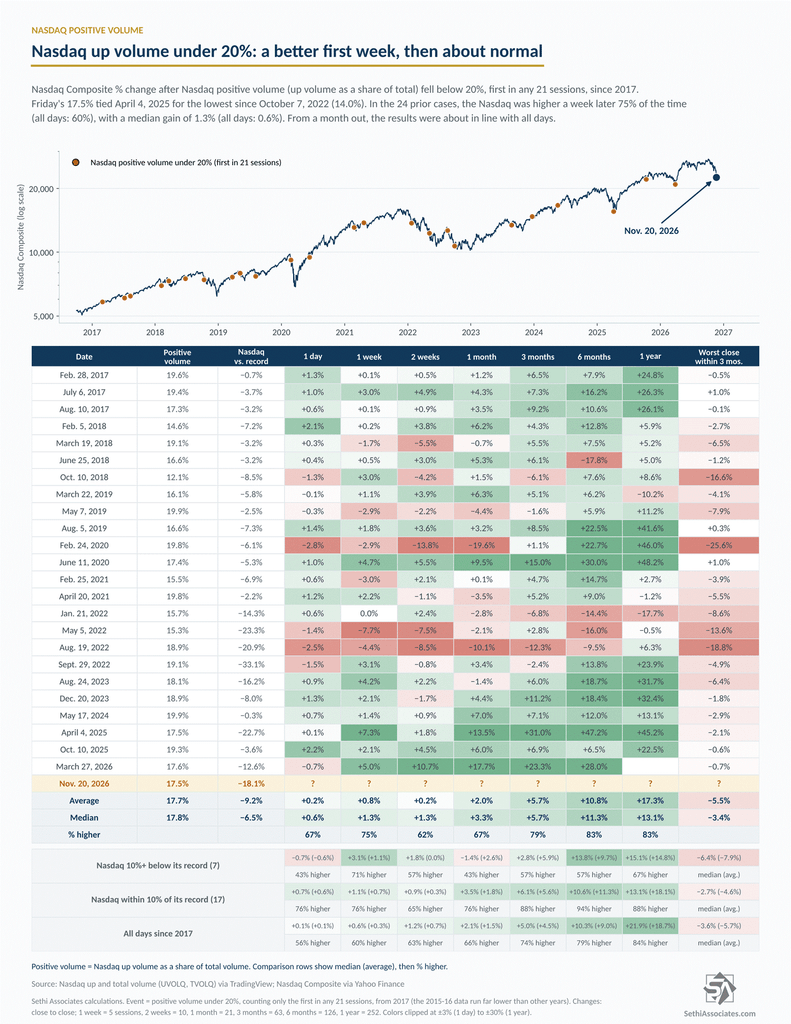
On the Nasdaq, positive volume was 17.5% Friday on a 5.28% loss in the Nasdaq Composite, tying April 4th, 2025 for the lowest since October 7th, 2022 (14.0%). Since 2017, after readings below 20% (24 cases), the Nasdaq was higher a week later 75% of the time (median +1.3%, vs. 60% and +0.6% for all days), though from a month out the results were about in line with all days.
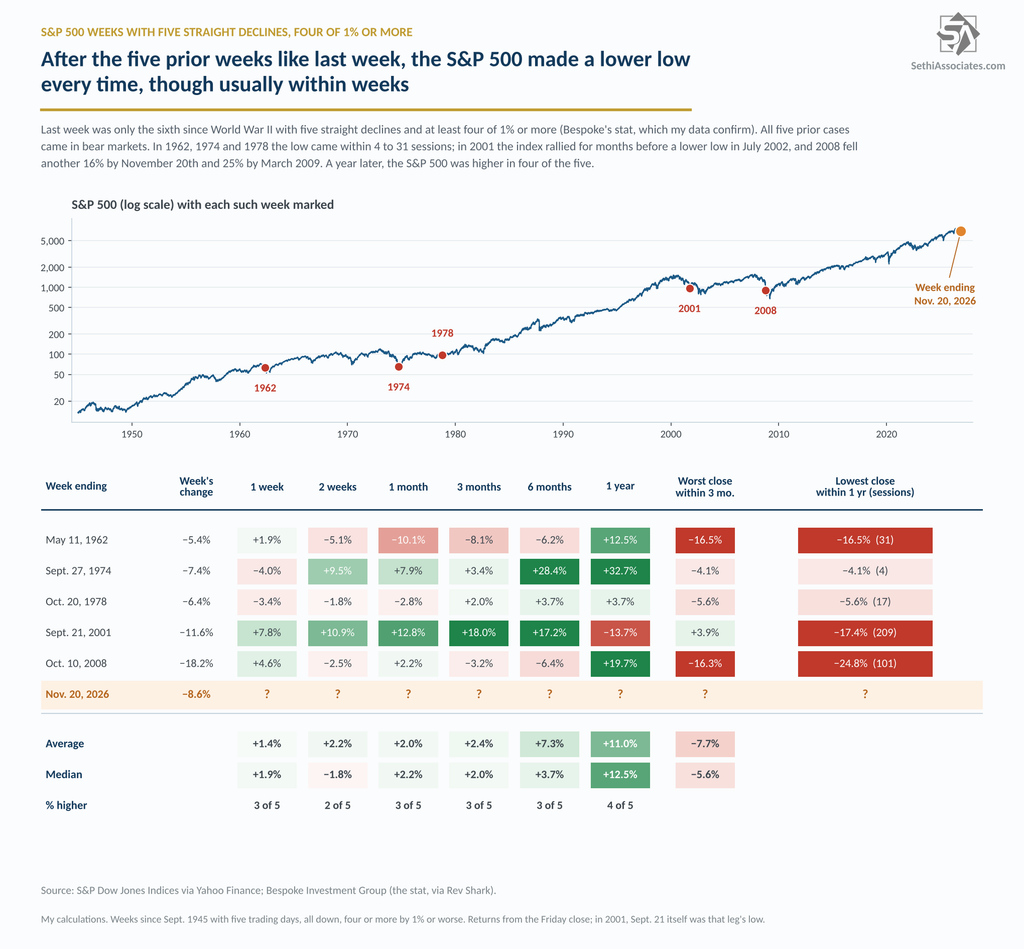
Rev Shark also passed along a Bespoke stat: it was only the sixth time since World War II that the S&P 500 fell all five days of a week with at least four 1%+ declines (1962, 1974, 1978, 2001 and 2008). All came during bear markets, and each made a lower low before the selling ended, though in 1962, 1974 and 1978 the bottom was only weeks away.
Net new highs were also the weakest since April 2025 on both exchanges Friday (NYSE -551, Nasdaq -1,251), and the Nasdaq’s has now been negative for 60 straight sessions, the longest run since November 2022 (see Friday’s Charts – A Correction for the S&P 500 and the Worst Week for Chips Since 2001).
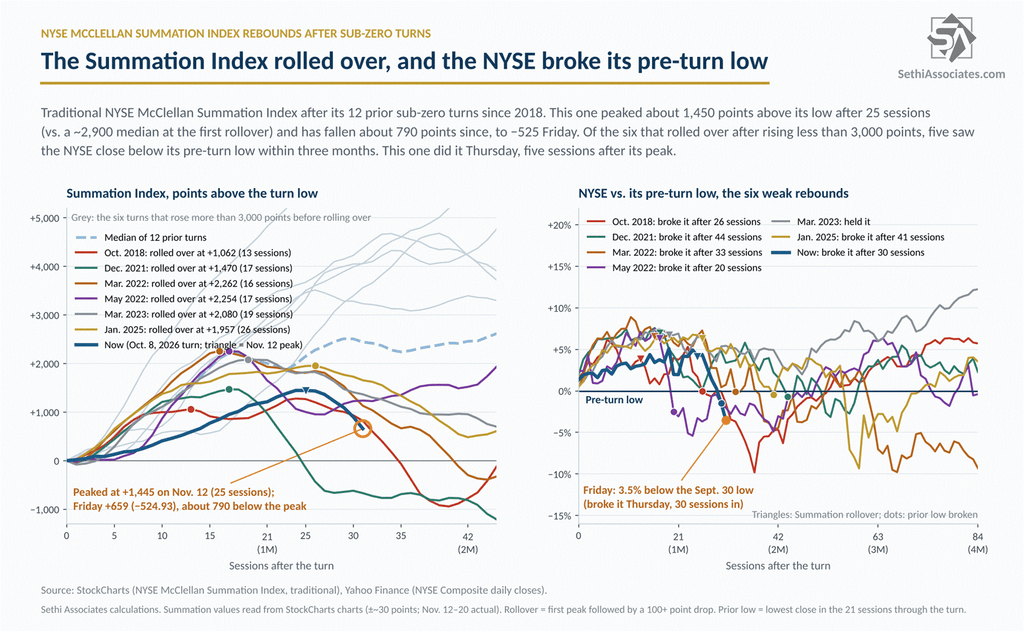
The McClellan Summation Index (red line, broadly whether the typical stock is doing relatively better or worse than the index) plunged to -525 from +251 a week earlier, its biggest weekly drop since March and its lowest level since late October.
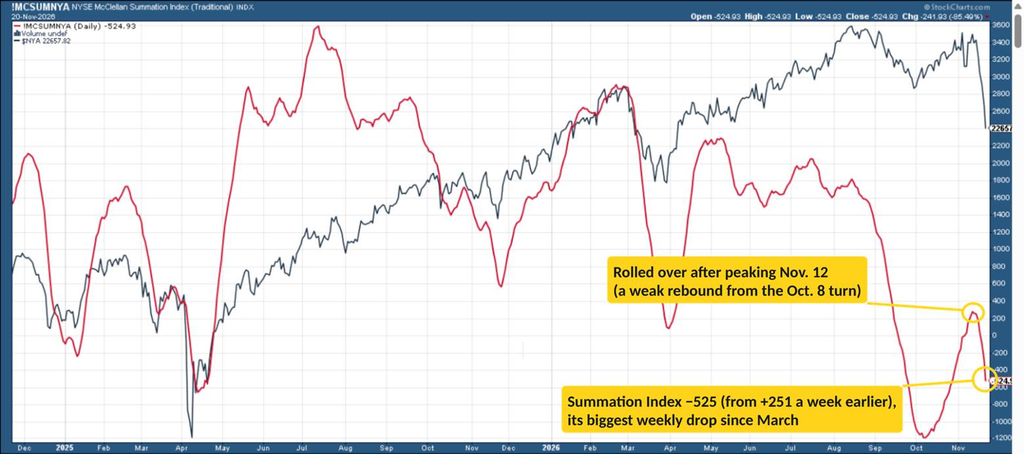
That confirms the rollover I flagged as a risk last week. The index peaked on November 12th, 25 sessions after its October 8th sub-zero turn and about 1,450 points above its low, roughly half the 2,900-point median at the first rollover for the 12 prior turns since 2018. In five of the six prior turns that rolled over after rising less than 3,000 points, the NYSE closed below its pre-turn low within three months.
This time it took five sessions. The NYSE Composite closed below its September 30th low (23,490.80) on Thursday, 30 sessions after the turn, and ended the week at 22,657.82, 3.5% below it. Only May 2022 broke its low faster after the peak (three sessions). In the five prior cases, the NYSE fell a median of another 8.9% (range 3.0% to 9.8%) to its low over the next three months, which came four to 54 sessions after the break (median 18).
Applied to Thursday’s close, that median would put the NYSE near 21,080, about 7% below Friday’s close. But the NYSE was also higher three months after the break in three of the five (median +2.0%), so the breaks tended to come late in the selling rather than at its start. With five cases, though, that’s a small sample.
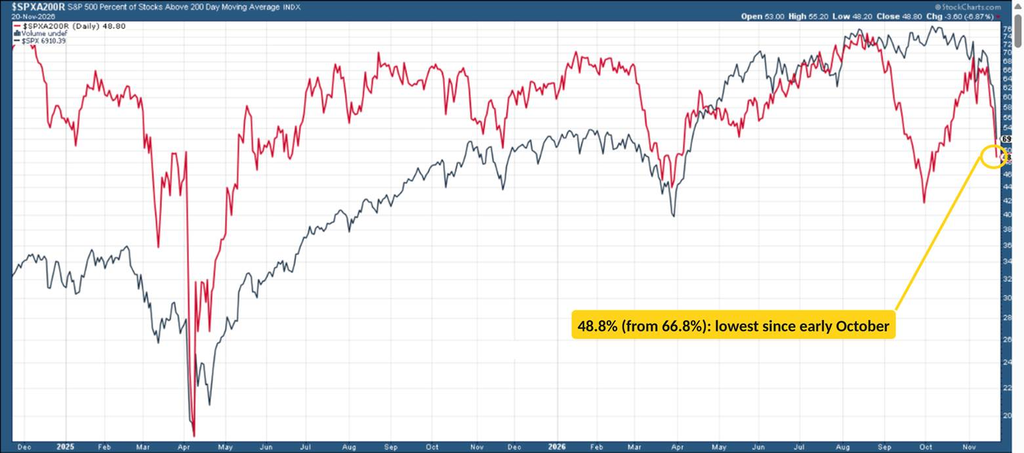
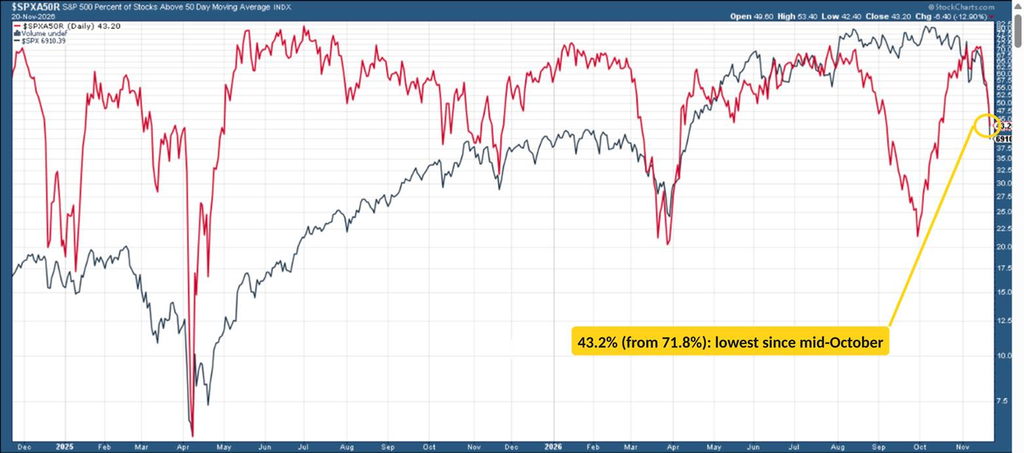
The percentage of stocks over their 200-DMAs (red lines) plunged for the S&P 500, to 48.8% from 66.8% a week earlier, its lowest since early October, though still above the roughly 42% at the September 30th low.
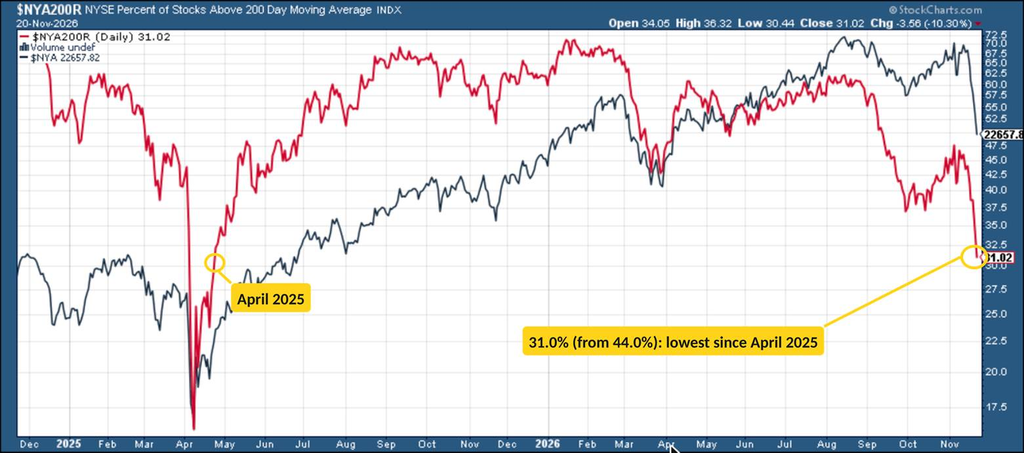
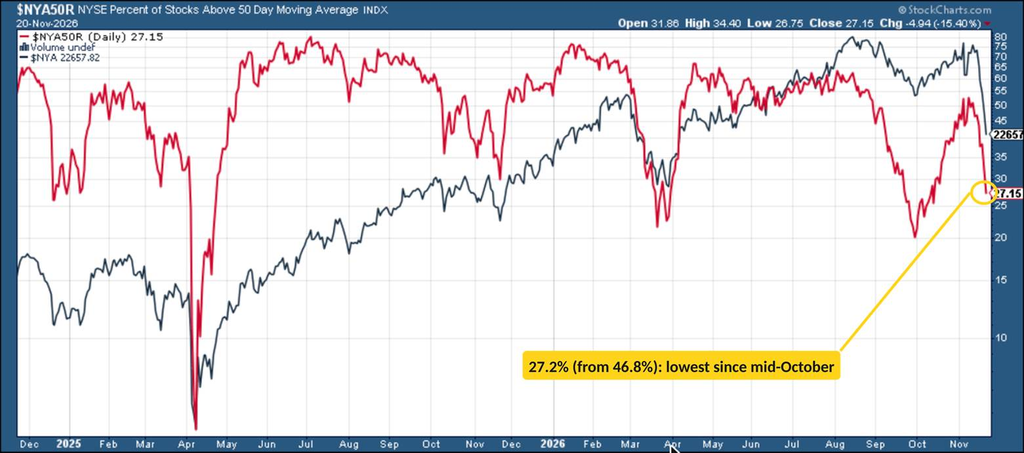
The NYSE fell to 31.0% from 44.0%, its lowest since April 2025.
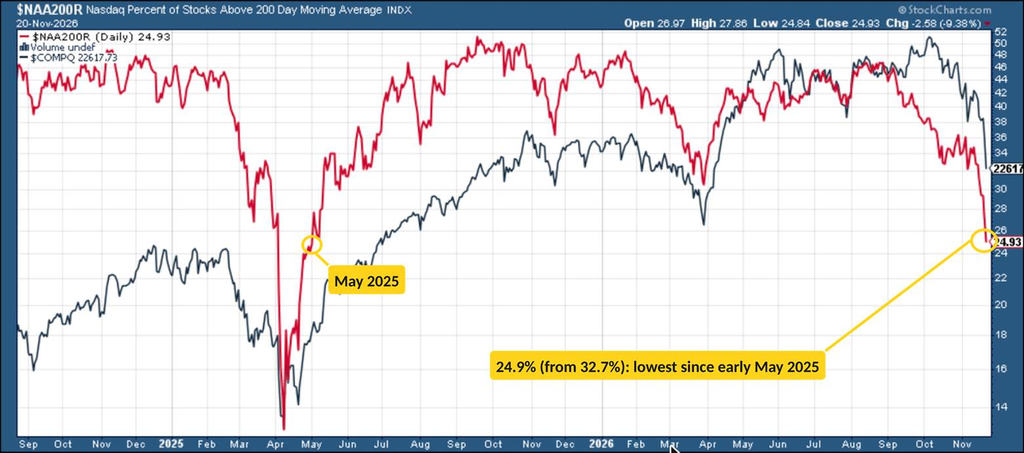
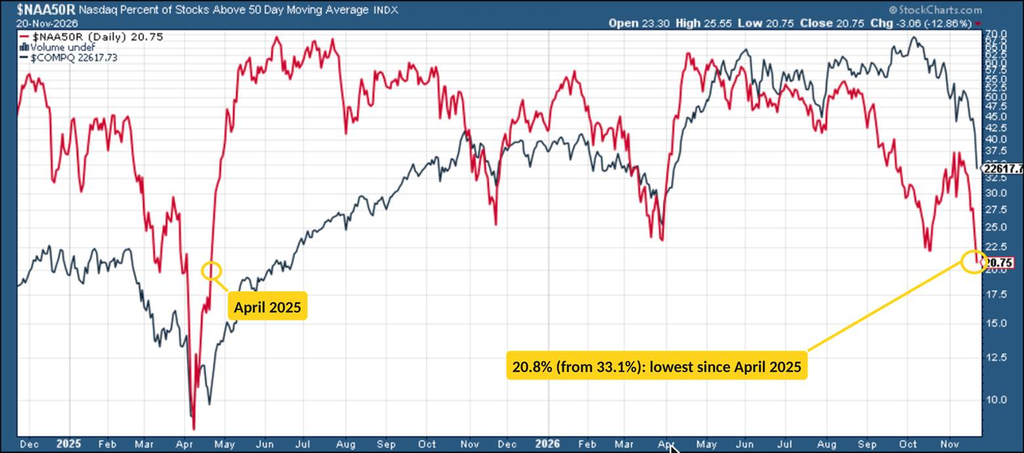
The Nasdaq dropped to 24.9% from 32.7%, its lowest since early May 2025, as the Nasdaq Composite (black line) fell 10.0% on the week.
The 50-DMAs also dropped sharply on all three exchanges: S&P 500 43.2% (from 71.8%), NYSE 27.2% (from 46.8%) and Nasdaq 20.8% (from 33.1%). That’s the Nasdaq’s lowest since April 2025; the S&P 500 and NYSE are at their lowest since mid-October.
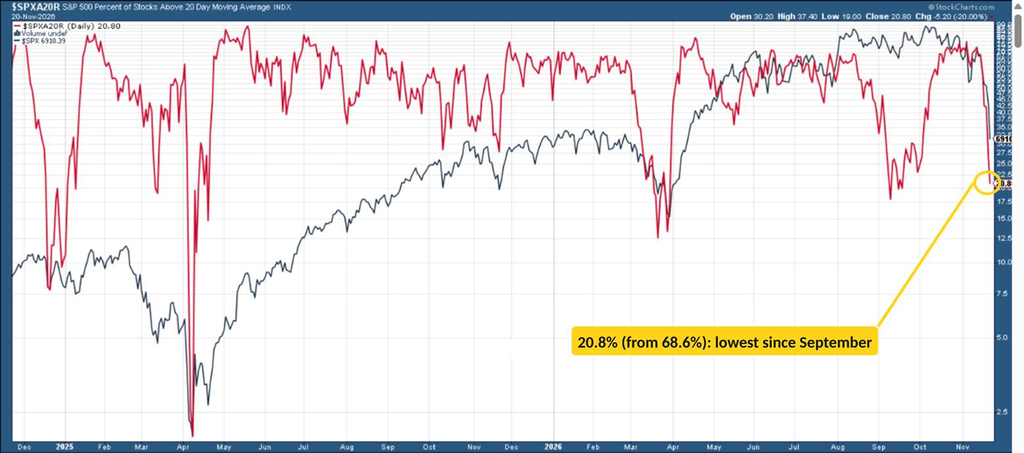
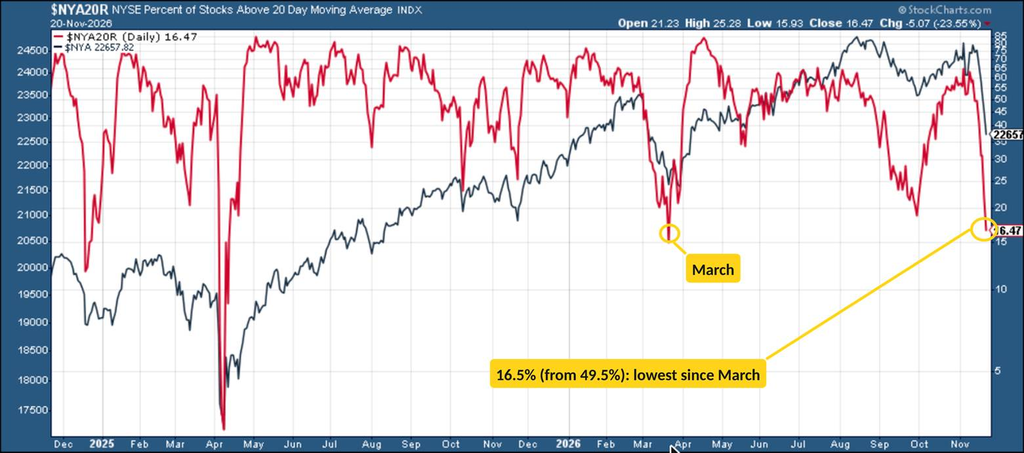
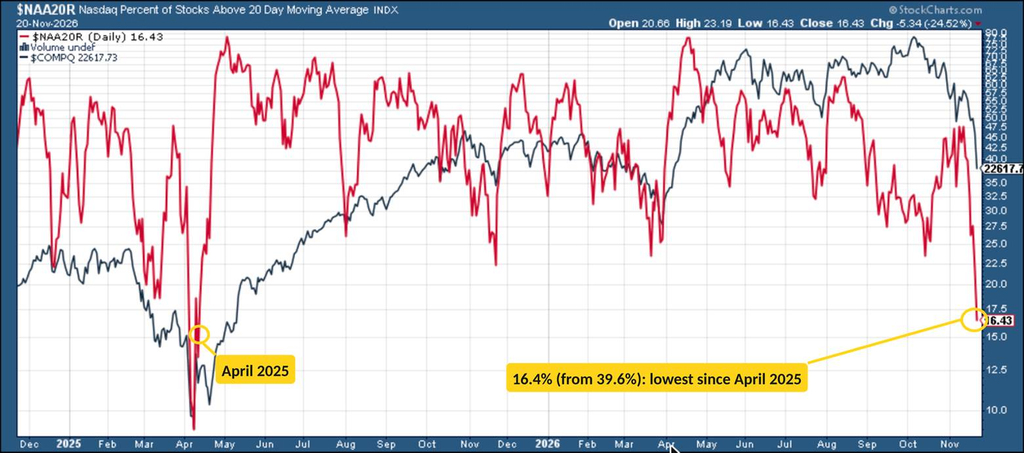
The 20-DMAs, which react fastest, collapsed: S&P 500 20.8% (from 68.6%, the lowest since September), NYSE 16.5% (from 49.5%, the lowest since March) and Nasdaq 16.4% (from 39.6%, the lowest since April 2025).
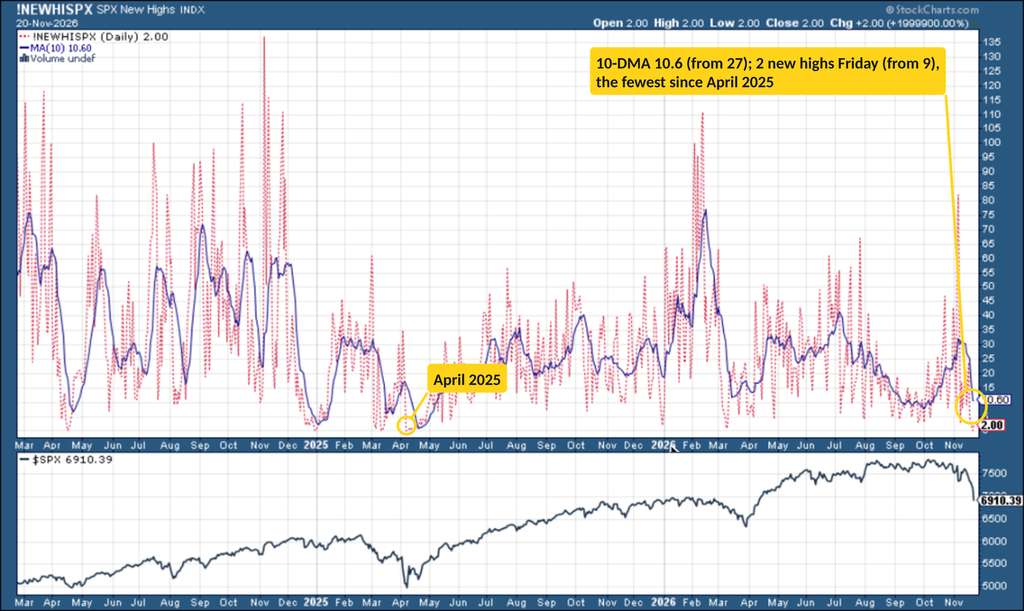
S&P 500 new 52-week highs were 2 Friday, the fewest since April 2025, down from 9 a week earlier. As expected, with the roughly 80 new highs on November 5th rolling out of the window, the 10-DMA fell sharply, to 10.6 from 27, nearly back to the roughly 8 at the start of October.
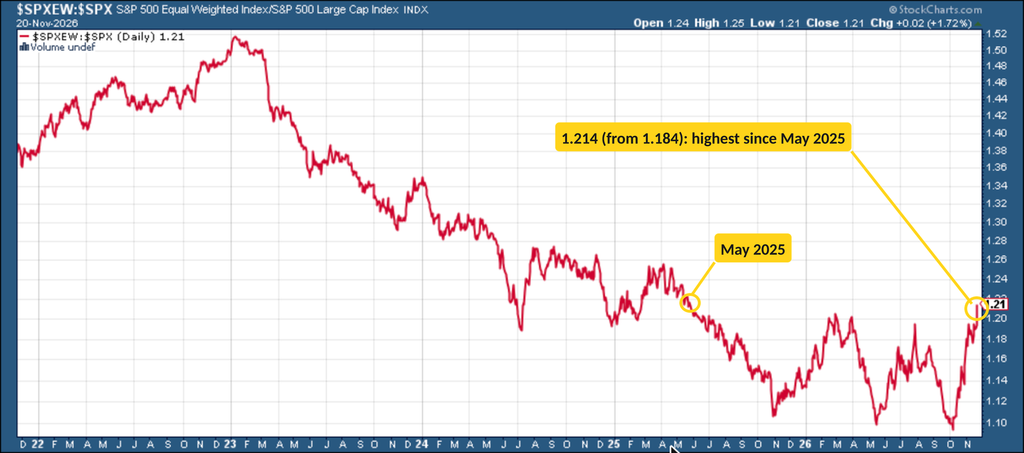
The ratio of the equal-weight S&P 500 to the cap-weighted index jumped to 1.214 from 1.184, its highest since May 2025, as the equal-weight index (RSP -6.2%) fell less than the cap-weighted one (SPY -8.6%).
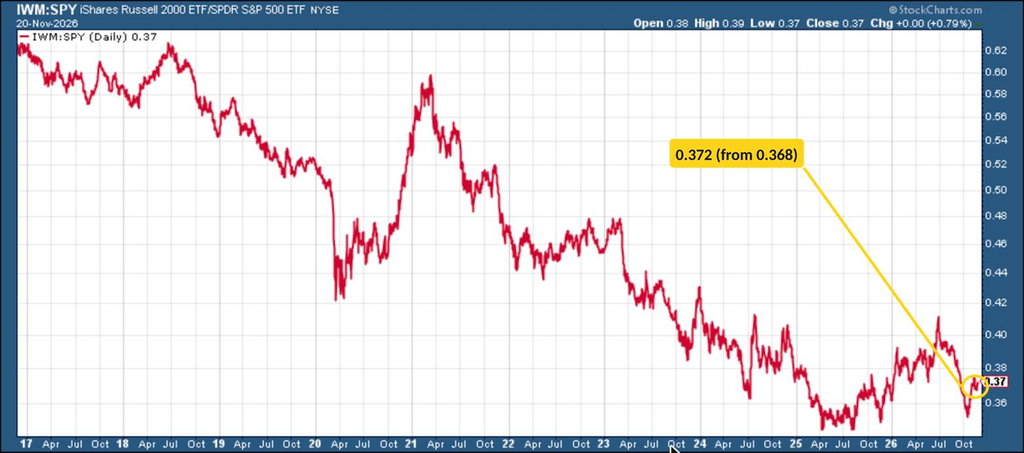
The ratio of small caps to large caps (IWM:SPY) edged up to 0.372 from 0.368, as small caps (IWM -7.5%) also fell less than the S&P 500.
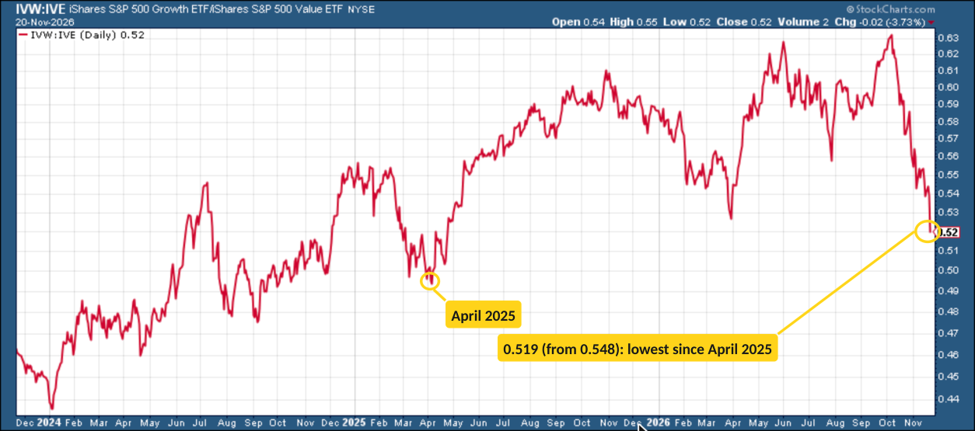
S&P 500 growth/value (IVW:IVE) slid to 0.519 from 0.548, its lowest since April 2025, as growth (IVW -10.8%) fell nearly twice as much as value (IVE -6.0%).
Sentiment Mostly Hasn’t Caught Up to the Selloff
The sentiment surveys mostly closed before Thursday’s and Friday’s selloff, and outside of a couple of surveys, it shows.
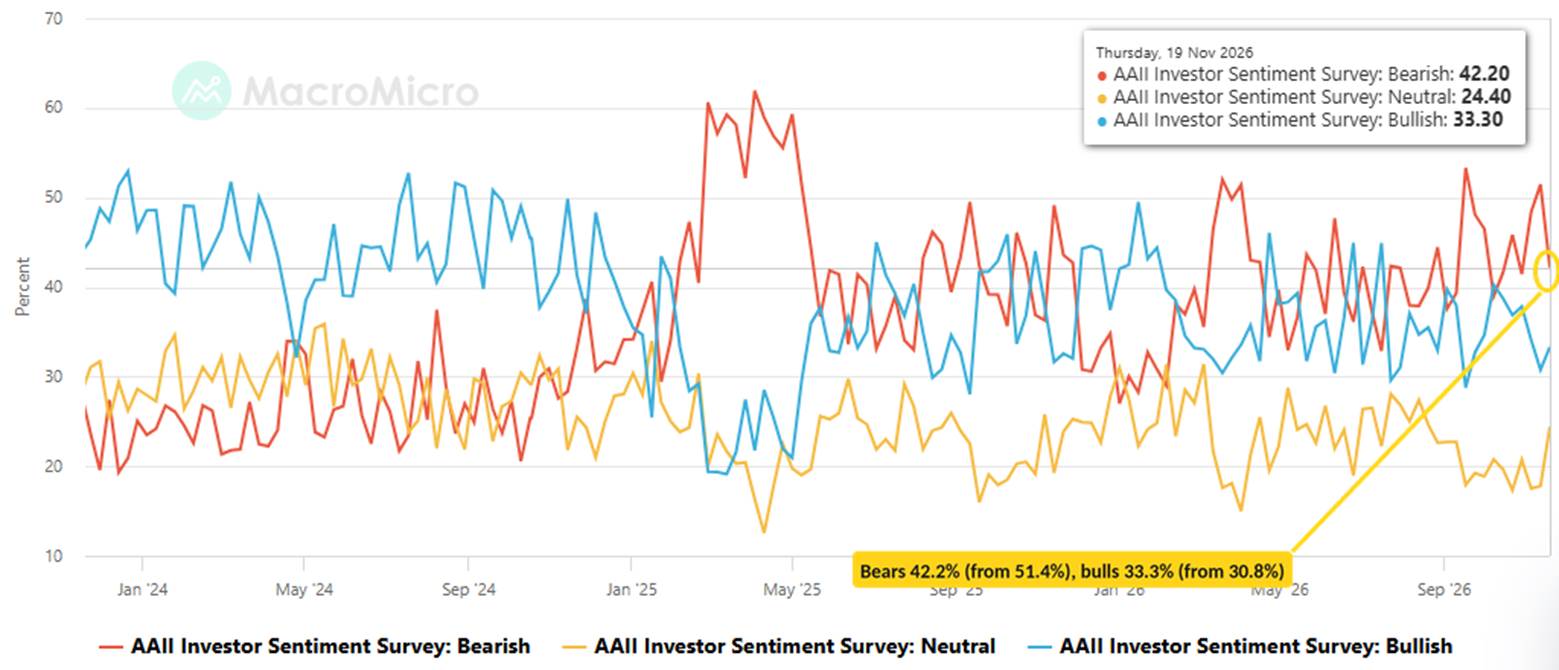
AAII bears actually fell to 42.2% from 51.4%, with bulls up to 33.3% from 30.8% and neutral up to 24.4% from 17.8% (survey through Wednesday). That took the bull-bear spread to -8.9 from -20.6 and the bull/bear ratio to 0.79 from 0.60, still below its 1.18 average.
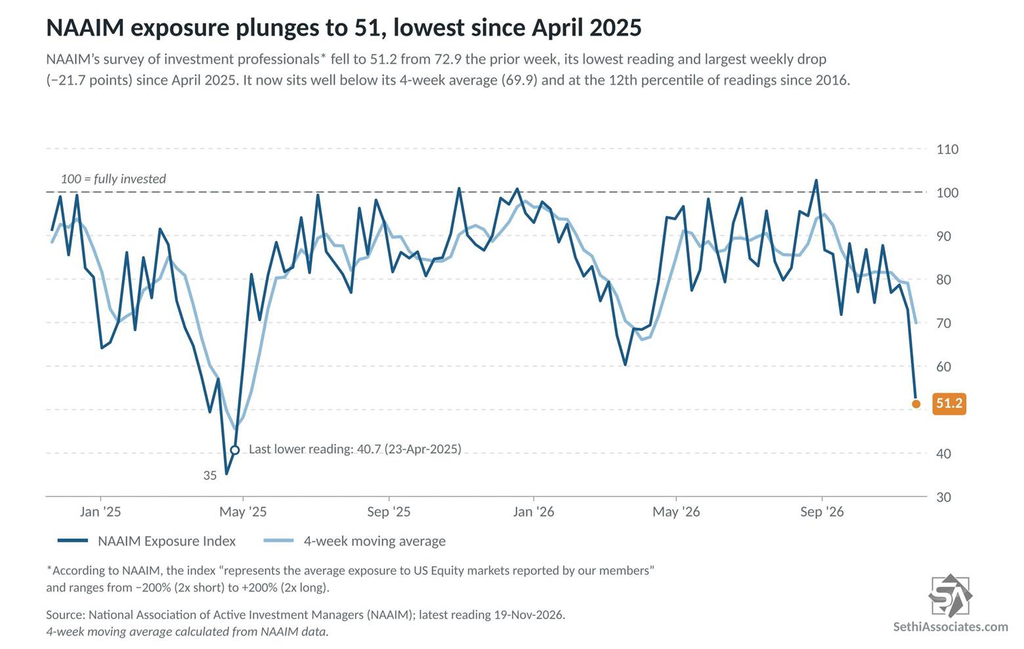
NAAIM’s exposure index fell to 51.2 from 72.9, its lowest and its biggest weekly drop since April 2025 (Active Managers Slashed Stock Exposure but Retail Investor Bearishness Eased).
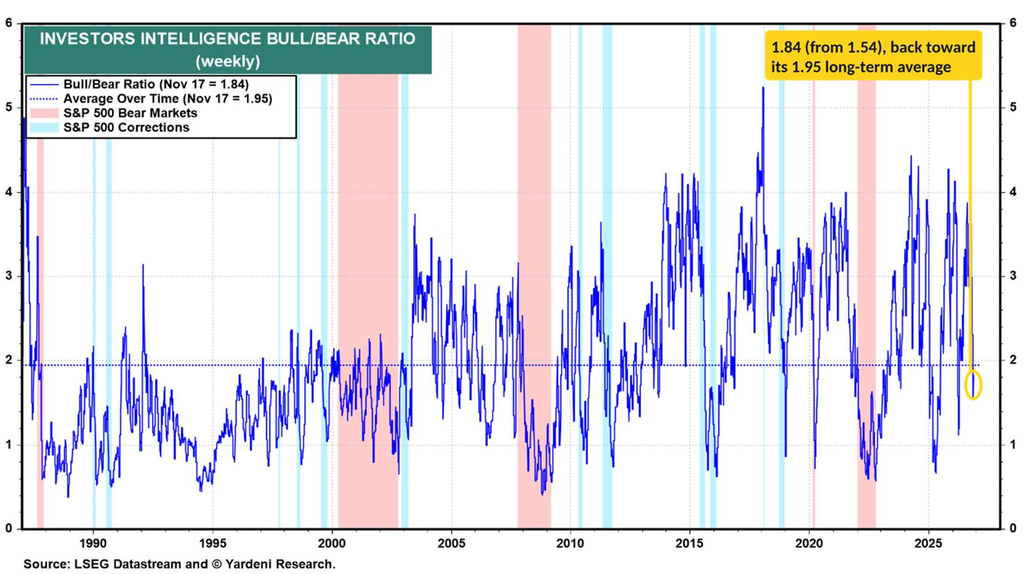
Investors Intelligence’s bull/bear ratio rose to 1.84 from 1.54 (survey through Tuesday), back toward its long-term average of 1.95, after Yardeni called last week’s reading “a strong buy signal.” This week he says both the II and AAII bull/bear ratios are below their long-term averages and expects them to be “even lower over the coming week.” And with “no recession in sight,” he doubts the VIX (35.9) and the Nasdaq VIX (45.3) “will rise much from here.”
Helene Meisler‘s Saturday poll (“The next 100 points for the S&P?”) swung to 61.9% Up from 46.1% a week earlier (on 2,623 votes), her most bullish result since at least late August (she had 61.1% Up on October 3rd). Last week’s majority Down voters were right.
In her Saturday Chart Fest, she notes that the Daily Sentiment Index (the share of futures traders who are bullish) is at 9 for both the S&P 500 and the Nasdaq, while the 10-DMA of the equity put/call ratio is “finally getting up there.” It ended the week at 0.68, just below Wednesday’s 0.69, the highest since March 24th.
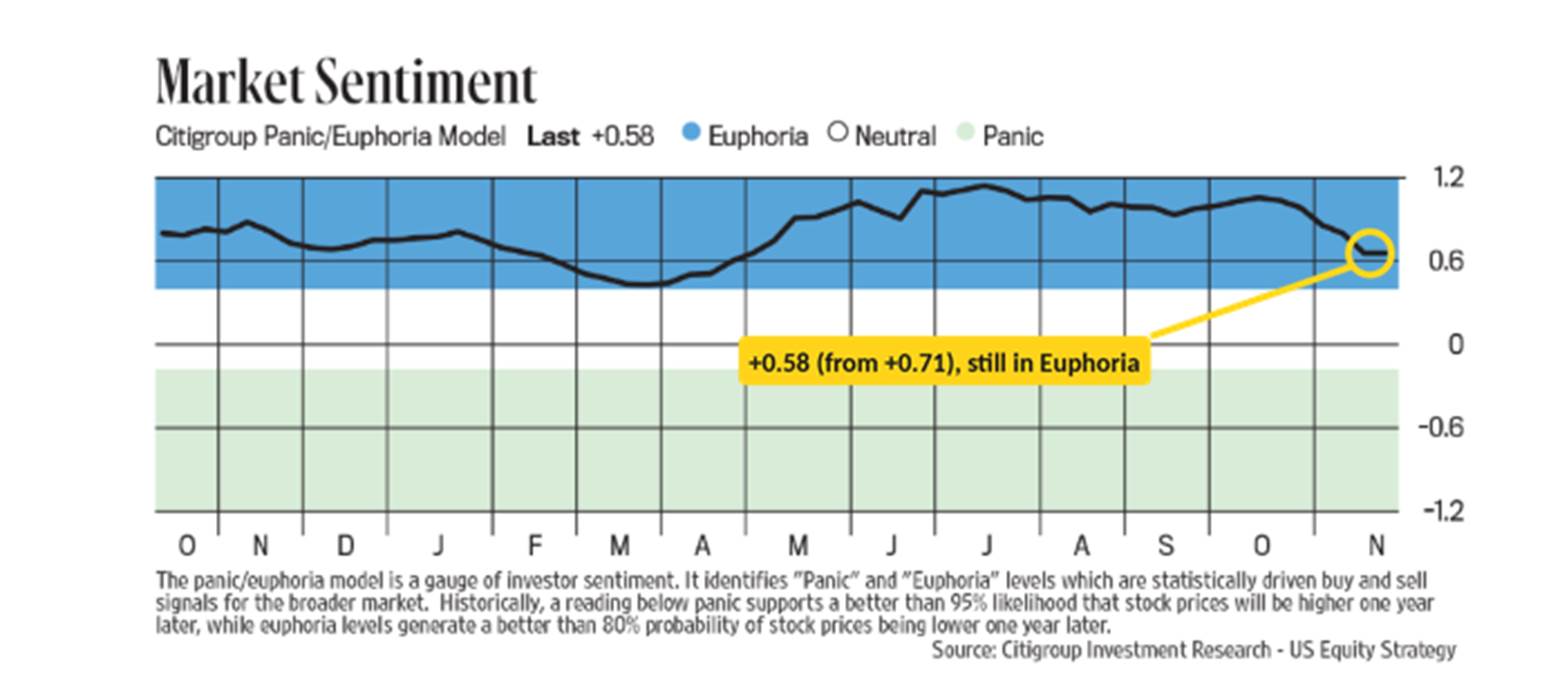
And Citi’s Panic/Euphoria Model, which Helene has each week in her Chart Fest, eased to +0.58 from +0.71 but remains in Euphoria. Helene suspects it’s a week old by the time Barron’s shows it, and “no matter what occurs next week this will be lower.”
As noted earlier, Goldman’s US Equity Sentiment Indicator eased to 0.75 from 0.83, still above average and well above the −1.2 to −3.0 range at past drawdown lows.
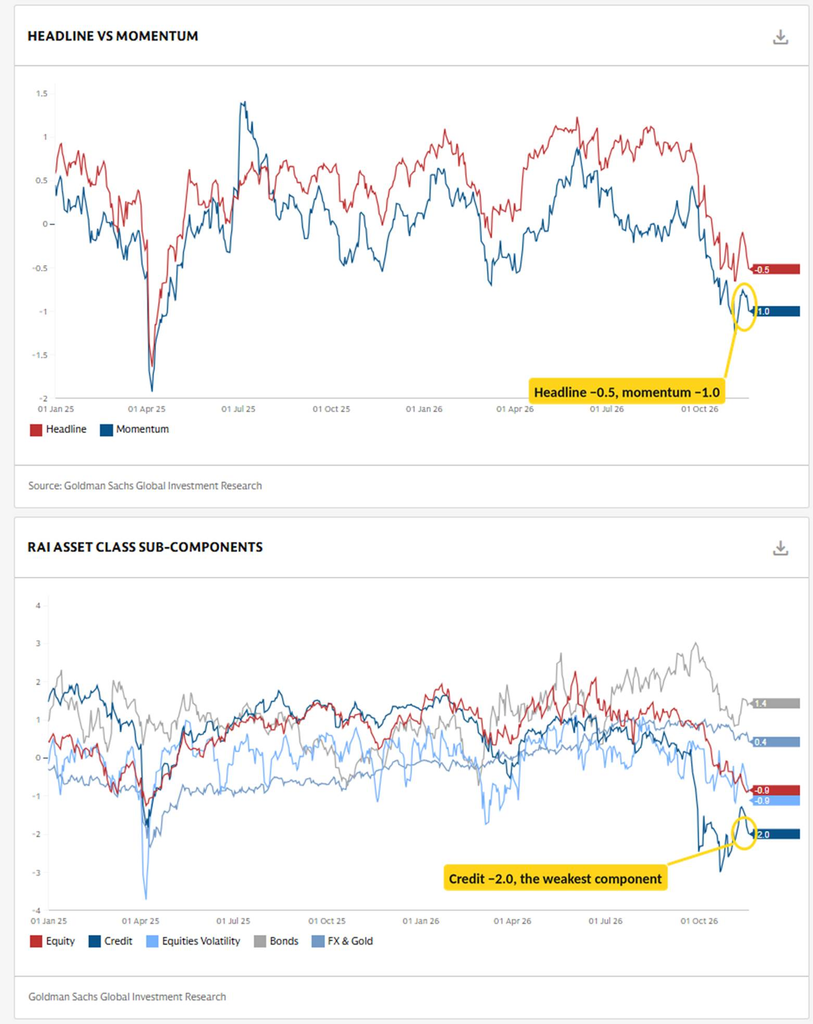
Goldman’s Risk Appetite Indicator* saw a more significant softening to −0.5 from −0.1 the prior week, but it’s still above the −0.7 of two weeks ago, which was its lowest since April 2025. The momentum index slipped to −1.0 from −0.8, also above its −1.2 two weeks ago (also its lowest since April 2025). By component, credit remains the weakest (−2.0, from −1.3), followed by equities (−0.9, from −0.6) and equity volatility (−0.9, from −0.3), while bonds (1.4, unchanged) and FX & gold (0.4, from 0.6) are still positive.
*”Goldman Sachs Risk Appetite Indicator (RAI) aims to track the level of global market risk appetite and risk aversion based on various market variables. A sharp rise in the index can send a warning signal that investors have more risk appetite and are potentially exposed to a correction if consensus views are tested. Similarly, a sharp decline indicates a reduction in risk appetite, and at extreme levels it can indicate that markets may have overshot. RAI signals are most powerful when the level of risk appetite is very low below -1.5, with levels closer to -2.0 giving the clearest signal over longer time horizons, as at such levels the asymmetry of subsequent medium term equity return becomes very positively skewed. RAI momentum is designed to track short term shifts of market risk appetite, and subcomponents of the RAI.”
The CNN Fear & Greed Index fell to 9.7 (Extreme Fear) Friday, its lowest since March 30th (5.8), from 37.4 (Fear) a week earlier. It ended every day of the week in Fear or Extreme Fear: Monday 31.1, Tuesday 26.0, Wednesday 29.9, Thursday 15.9.
Six of the seven indicators are now in Extreme Fear, up from two, with one in Fear.
- Extreme Greed = None
- Greed = None (junk bond demand fell to Extreme Fear)
- Neutral = None (stock price breadth and market volatility fell to Extreme Fear)
- Fear = stock price strength (net new 52-week highs)
- Extreme Fear = market momentum (SPX vs 125-DMA); safe haven demand (20-day difference in stock/bond returns); put/call options (5-day put/call ratio) (from Fear); market volatility (VIX & its 50-DMA) (from Neutral); stock price breadth (McClellan Volume Summation Index) (from Neutral); junk bond demand (vs investment grade) (from Greed)
And I noted in previous weeks if you have any questions on the indicator, TheStreet Pro’s own Jason Meshnick is your guy, as he helped create it.
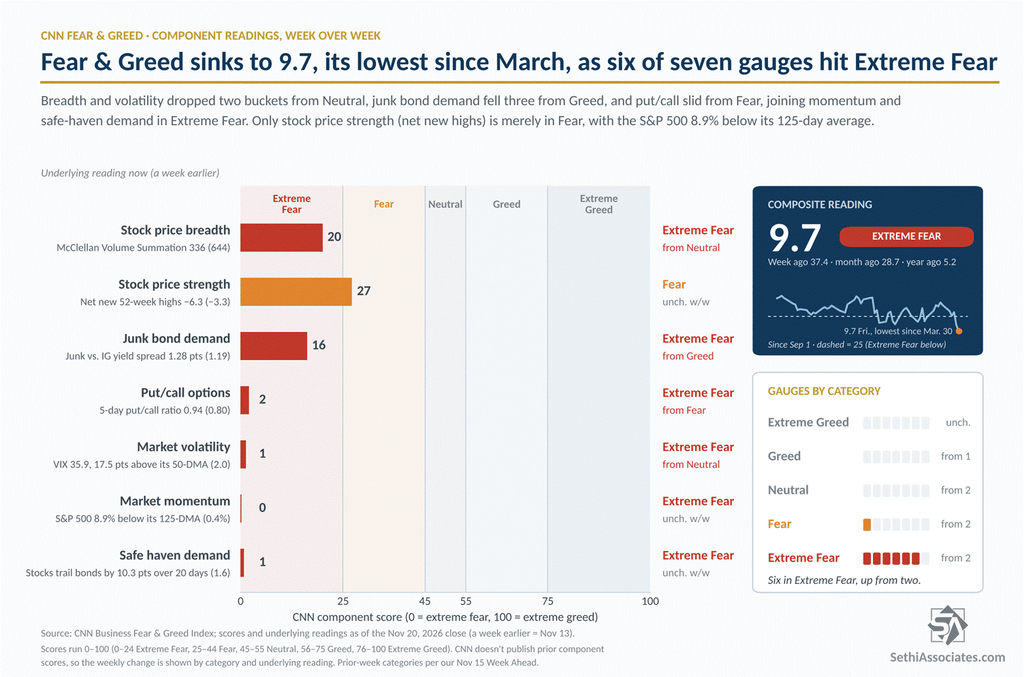
In CNN’s data back to 2021, after the six prior first readings of 10 or below in a month, the S&P 500 was higher one and three months later every time (medians of +5.7% and +8.0%, vs. +1.5% and +4.3% for all days), though it’s a short history, and a year later it was higher only three of five times.

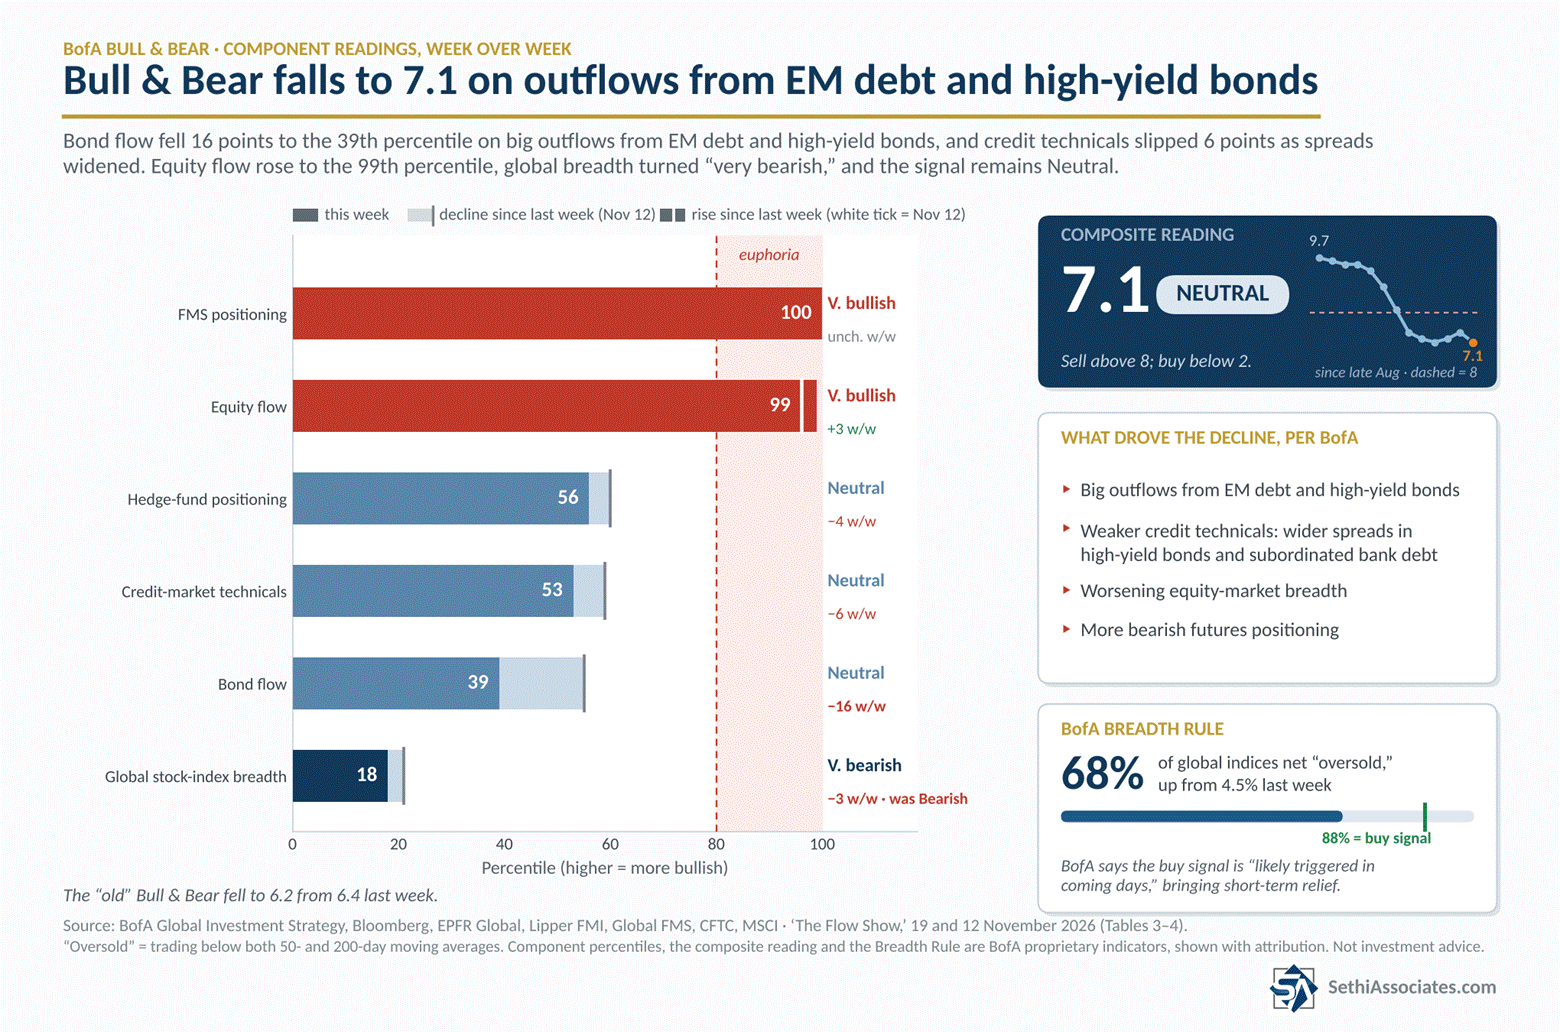
BofA’s Hartnett (Flow Show) says his Bull & Bear Indicator fell to 7.1 from 7.4 on big outflows from EM debt and high-yield bonds and weaker credit technicals (wider spreads in high-yield bonds and subordinated bank debt). Worsening equity breadth and more bearish futures positioning also weighed. Still it is far, far away from the 2.0 buy signal.
- Bond flow: down 16 points to the 39th percentile.
- Credit technicals: down 6 to 53.
- Hedge-fund positioning: down 4 to 56.
- Global breadth: down 3 to 18, now “very bearish.”
- Equity flow: up 3 to 99.
- Fund-manager positioning: unchanged at 100.
The signal stays Neutral (sell above 8). The “old” Bull & Bear fell to 6.2 from 6.4.
His Global Breadth Rule jumped to a net 68% of global indices “oversold” from 4.5% last week. He says the 88% buy signal is “likely triggered in coming days,” bringing short-term relief after Thanksgiving. A big rally still needs the 10-year Treasury yield below 4.5%, WTI below $70 and a top in the dollar on weak payrolls and CPI.
Thanksgiving Week Has Been Strong, but November Is Way Off Script
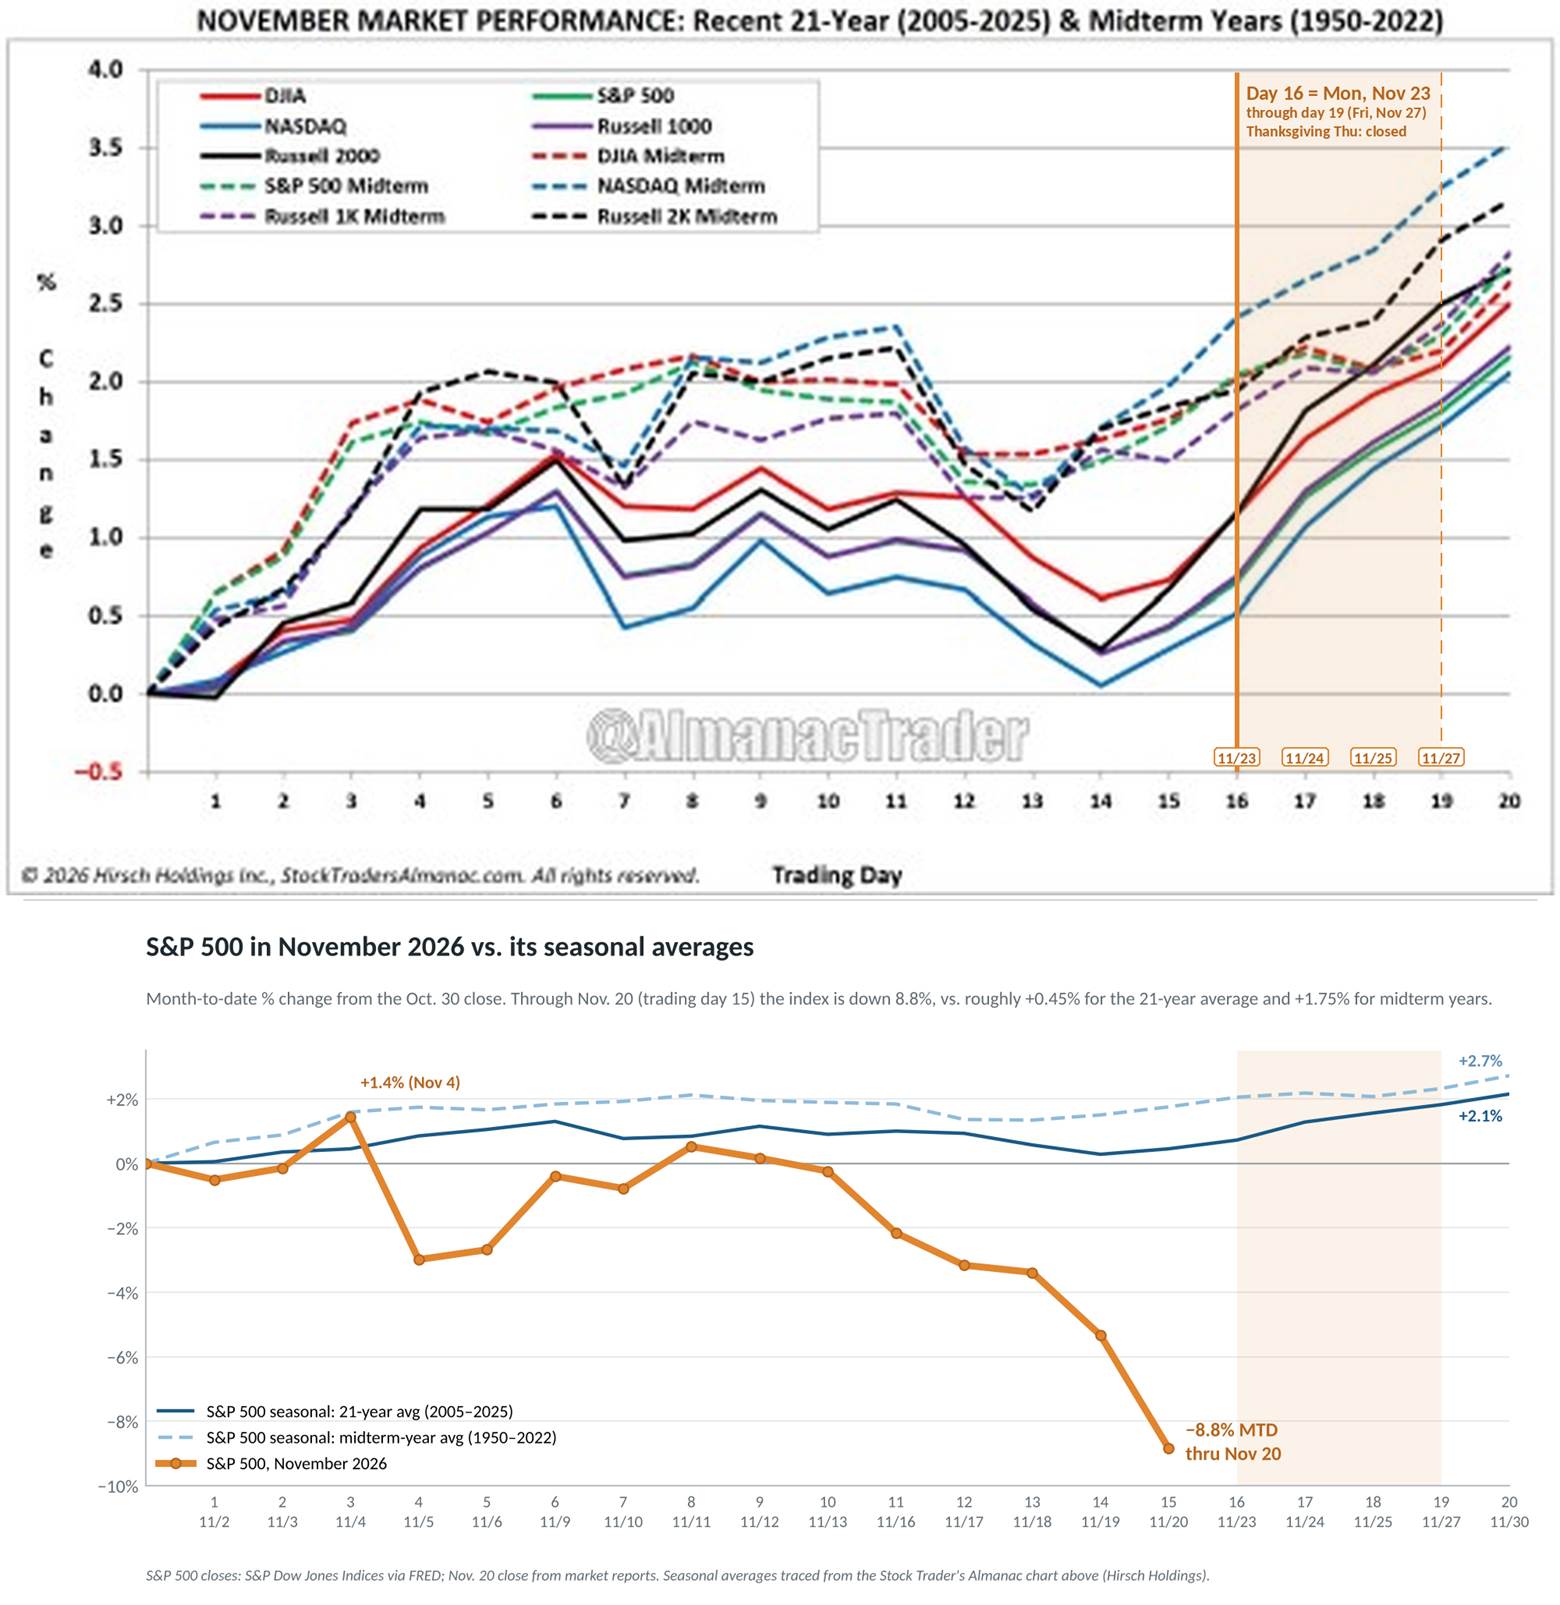
Looking at the seasonality breakdown from Jeff Hirsch, editor of the Stock Trader’s Almanac & Almanac Investor Newsletter, Thanksgiving week has historically been one of November’s strongest.
Monday is trading day 16. Over the past 21 years, the major indices have averaged gains on every trading day of the holiday-shortened week. That adds up to about 1.35–1.4% for the DJIA, S&P 500, Nasdaq and Russell 1000, and about 1.8% for the Russell 2000. Tuesday has been the best day, adding about 0.5–0.65%. Wednesday and the half-session Friday after Thanksgiving have each added about 0.2–0.4%.
Midterm years though have been more mixed. The Nasdaq has gained about 1.25% and the Russell 2000 about 1.1%, while the Russell 1000 has added about 0.85% and the DJIA and S&P only 0.4–0.55%. The DJIA, S&P and Russell 1000 have dipped slightly on Wednesday, but every midterm line has risen on Friday. Hirsch notes that recent weakness around Thanksgiving has shifted DJIA and S&P strength to look more like the Nasdaq and Russell 2000. His advice is to go long into any weakness before the holiday and exit into strength just before or after.
The month then wraps up Monday, Nov. 30 (day 20), which has added another 0.2–0.4% across all years. One caution: this year day 20 is also the Monday after Thanksgiving, and that Monday has been higher in just 5 of the past 21 years (an average −0.6%), and 29 of 76 since 1950, by our calculations.
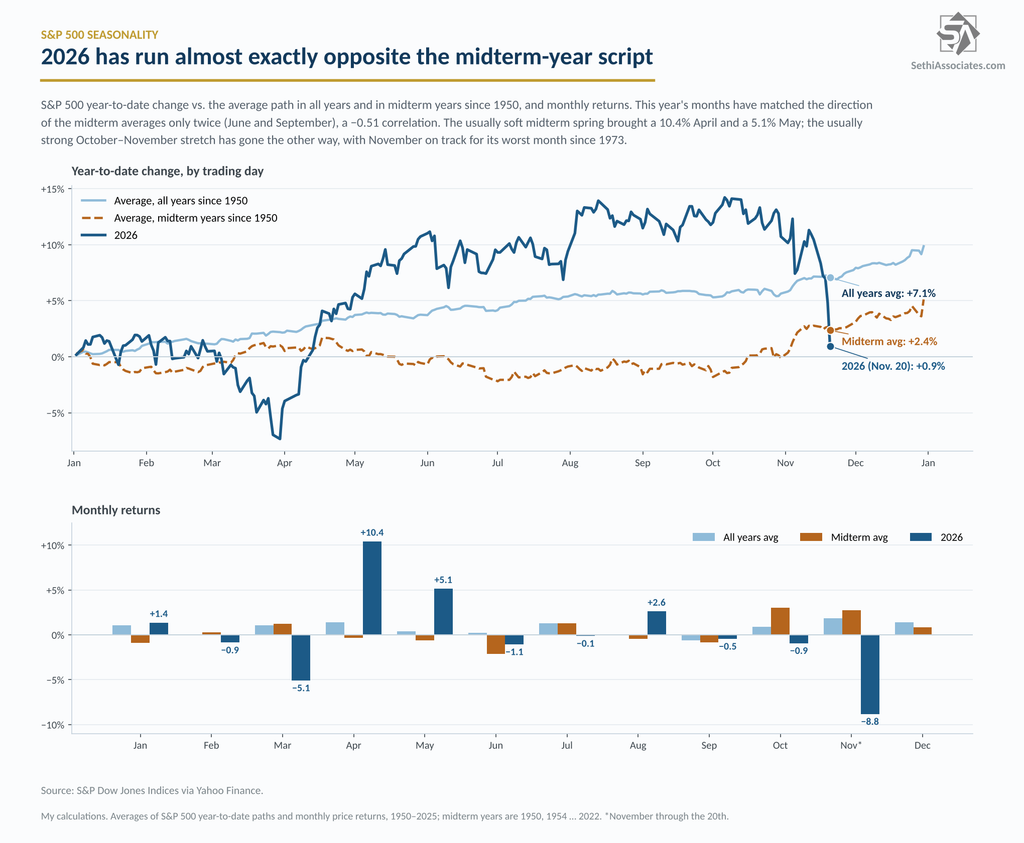
This year, though, the seasonal script has gone badly off course. Through Friday, the S&P 500 is down 8.8% for November, compared with about +0.45% for its 21-year average and +1.75% for midterm years at the same point. If November ended here, it would be the S&P 500’s worst November since 1973 (−11.4%), worse than 1987 (−8.5%), 2000 (−8.0%) and 2008 (−7.5%). Even a full seasonal rally from here, about 1.7% across all years, would leave the index down roughly 7% for the month, by our calculations.
That’s been the story all year. By my calculations, 2026’s monthly returns have mostly run opposite the midterm-year averages since 1950 (a −0.51 correlation), matching their direction in just two of 11 months (June and September). The usually soft midterm spring brought a 10.4% gain in April and 5.1% in May, the 99th and 93rd percentile of all months since 1950, while October, which has risen 74% of the time in midterm years by an average 3.0%, fell 0.9%. So November’s miss is par for the course, which is a good reminder that seasonality is a guide, not a forecast.
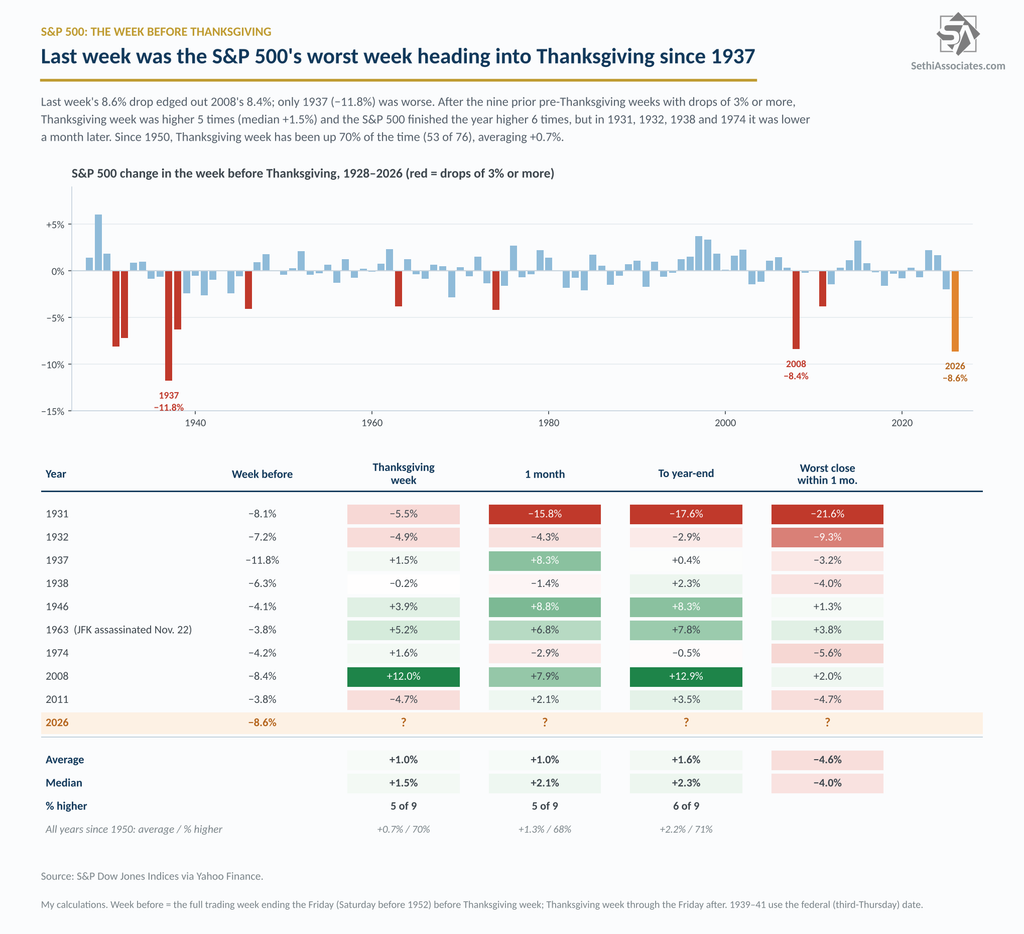
Looking at last week, the 8.6% drop was the S&P 500’s worst week heading into Thanksgiving since 1937, edging out 2008’s 8.4% (my calculations). Since 1950, Thanksgiving week has been up 70% of the time (53 of 76), with an average gain of 0.71%. In the four years since 1950 when the S&P 500 fell at least 3% the week before (1963, 1974, 2008 and 2011), Thanksgiving week was higher three times, including a 12.0% rally in 2008, but fell 4.7% in 2011. Going back to 1928, after the nine prior pre-Thanksgiving weeks with drops of 3% or more, Thanksgiving week was higher five times (median +1.5%), and the S&P 500 finished the year higher six times.
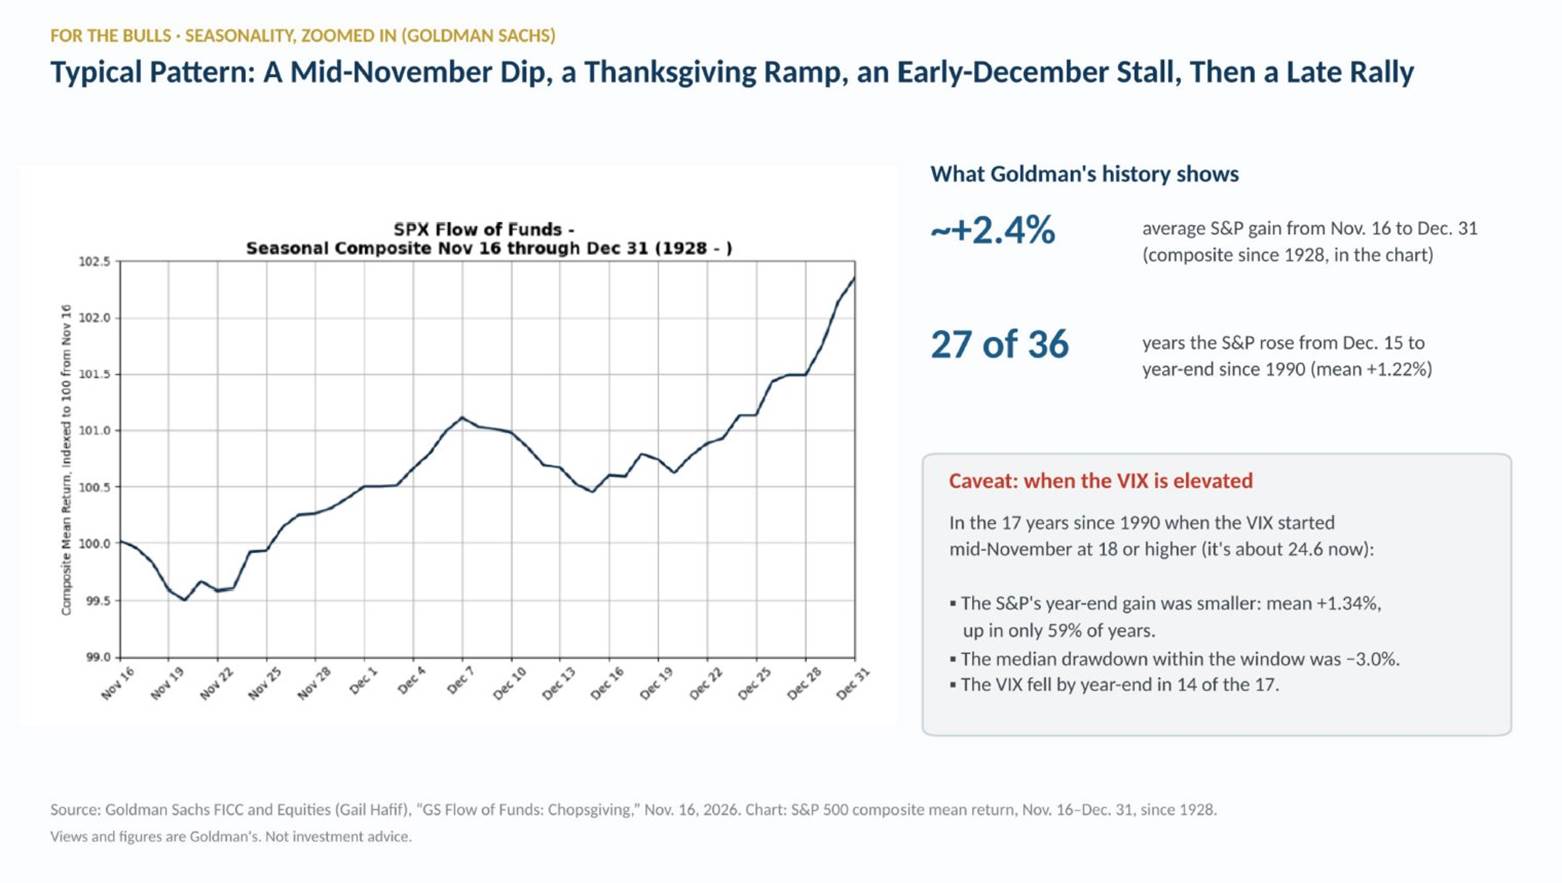
Goldman says everyone has probably heard how positive seasonality is in November and December, but “if this tape has taught us anything, it is that we need to zoom in far more closely than a 2-month period.” Performance has historically gotten a boost in the immediate Thanksgiving period, stalled in early December and picked up again into the holidays. The caveat: in the 17 years since 1990 when the VIX started mid-November at 18 or higher, as it did this year, the S&P 500’s year-end gain was smaller (a mean +1.34%, up in 59% of years). The period usually sees a dip first (a median drawdown of 3.0% within the window), and most of the gains come late, with a mean +1.22% from December 15th to year-end and the S&P 500 up in 27 of 36 years.
We’ve now more than covered the dip part. The S&P 500 fell 8.6% last week from the November 13th close, nearly three times Goldman’s median drawdown, and the VIX ended the week at 35.90, about double its 18 threshold.
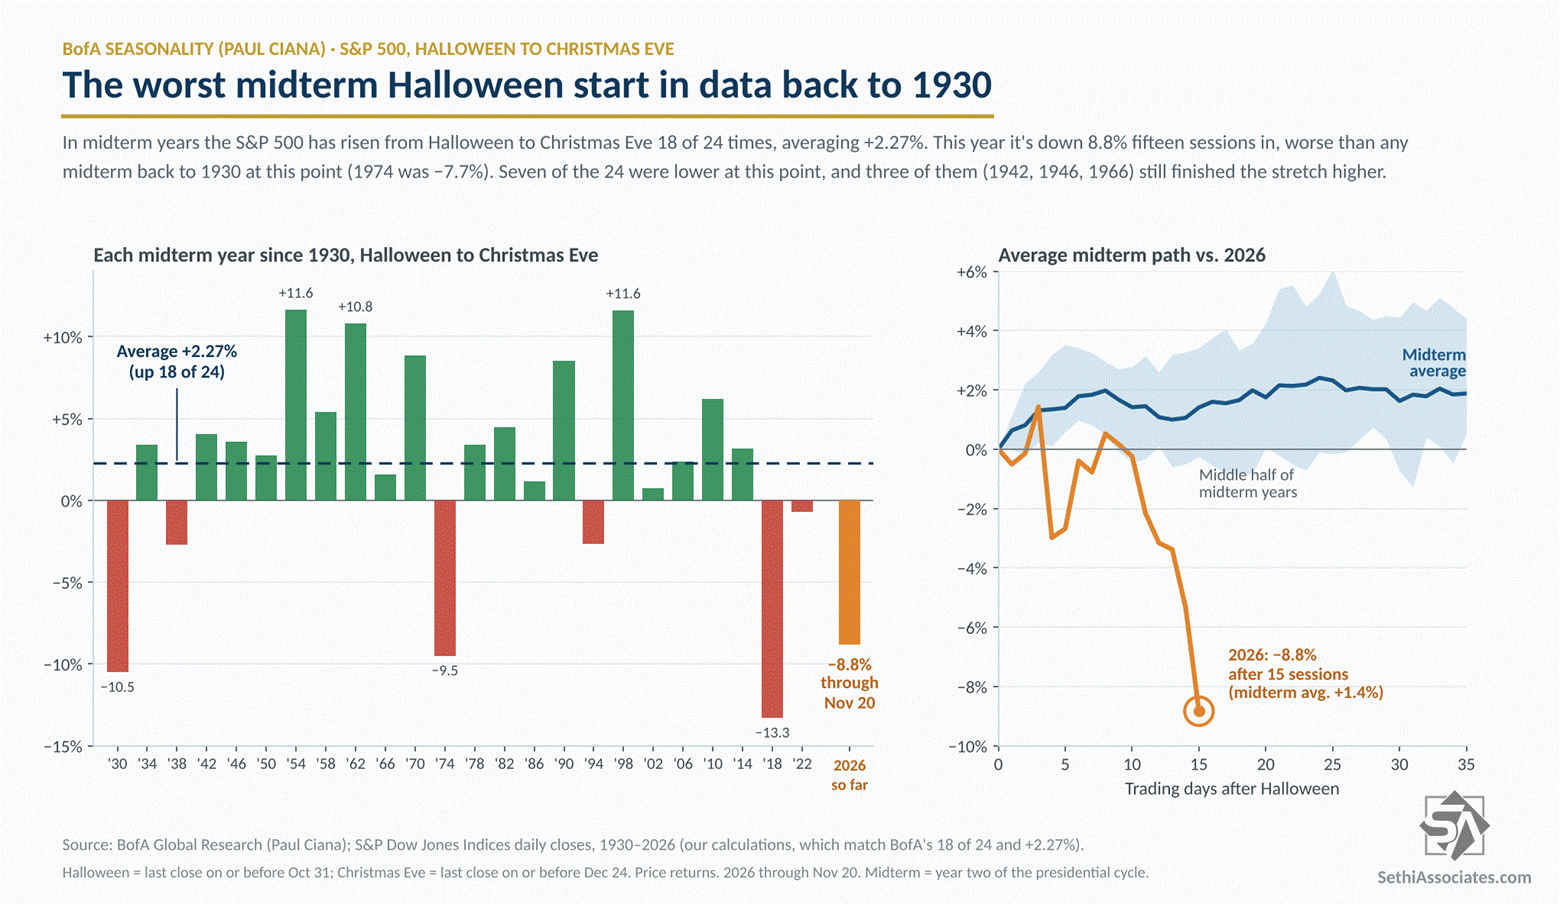
BofA’s Ciana noted that in midterm years, Halloween to Christmas Eve has been up 75% of the time (18 of 24) by +2.27%. With the S&P 500 now down 8.8% since Halloween (the October 30th close), matching that average would take a 12.2% rally in the 23 sessions through Christmas Eve.
Fifteen sessions in, the S&P 500 is down 8.8% from its Halloween close, the worst start for any midterm year in data back to 1930 (1974 was −7.7% at the same point). Seven of the 24 midterms were lower at this point, and three of them (1942, 1946 and 1966) still finished the stretch higher, by my calculations.
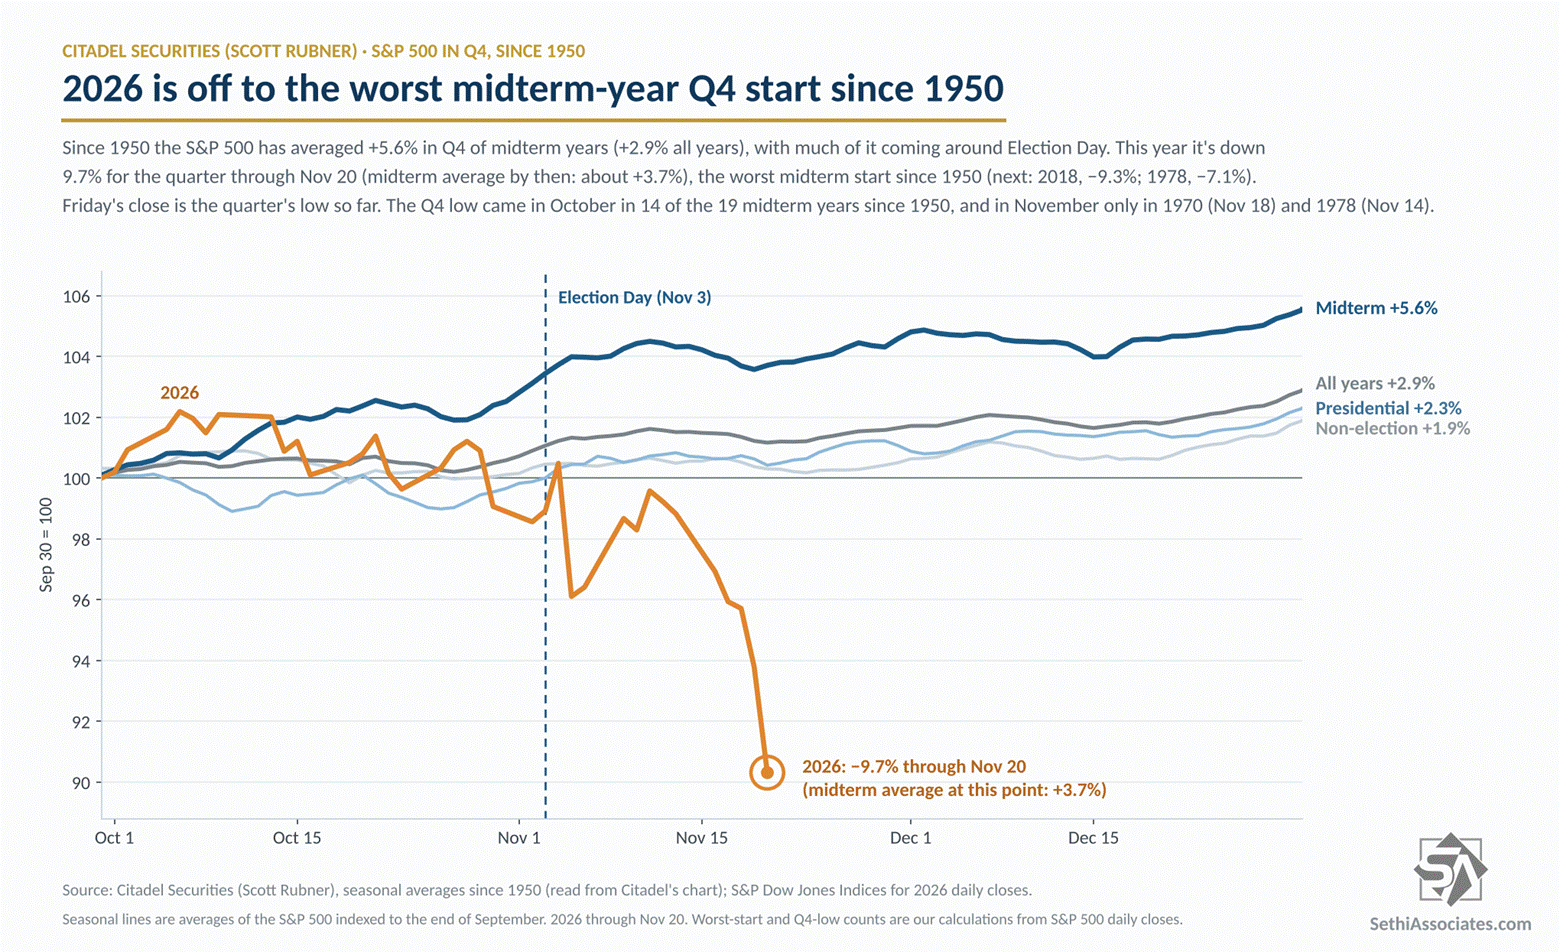
And with the S&P 500 down 9.7% for Q4, matching Citadel’s Rubner’s +5.6% midterm Q4 average would now take a nearly 17% rally into year-end. Friday’s close (6,910.39) is the new Q4 low, 6.0% below the November 5th close (7,353.73) that had held it until Tuesday.
That’s the worst start to Q4 for any midterm year since 1950, worse than 2018 (-9.3%) and 1978 (-7.1%) at the same point, by my calculations. In those two years, the S&P 500 finished Q4 down 14.0% and 6.3%.
Wrap-Up — Did We Get the Panic?
Last week’s Week Ahead asked “Have We Seen the Q4 Bottom?” The answer was an emphatic no. The S&P 500 fell 8.6%, its worst week since April 2025, taking out the November 5th close it had bounced from and ending the week in a correction. In last week’s Wrap-Up I said I was “definitely more bullish than I was a week ago, even as I acknowledge a retest of the November 5th lows remains a distinct possibility.” This is why I shouldn’t trade with my gut. The retest came, and then some.
On Friday I noted that Baird’s Ted Mortonson said the “fundamentals are out the window” and called this “a positioning story,” one that will “require real panic, not fear,” and I said I’d spend the weekend looking for signs of it. So did we get the panic?
Among the professionals, it does look like it, and as I wrote Thursday, “That Felt Panicky.” Goldman’s vol panic index ende the week at a record 9.8 out of 10, the VIX closed at its highest level on an options expiration day since April 2020, and the CNN Fear & Greed Index fell to 9.7, its lowest since March. Hedge funds shorted single stocks every day last week and cut their beta-adjusted gross leverage to a three-year low.
And systematics are getting there. DB says systematic positioning is the lowest in 18 months and Goldman estimates CTAs are now net short $19 billion of US stocks.
That has sent Deutsche Bank’s consolidated positioning measure down to the 11th percentile, “approaching levels from which it has typically bounced.” We also saw NYSE downside volume around 80% in three of five sessions, something that hadn’t happened since the liberation day selloff, and Nasdaq positive volume tie its lowest since October 2022.
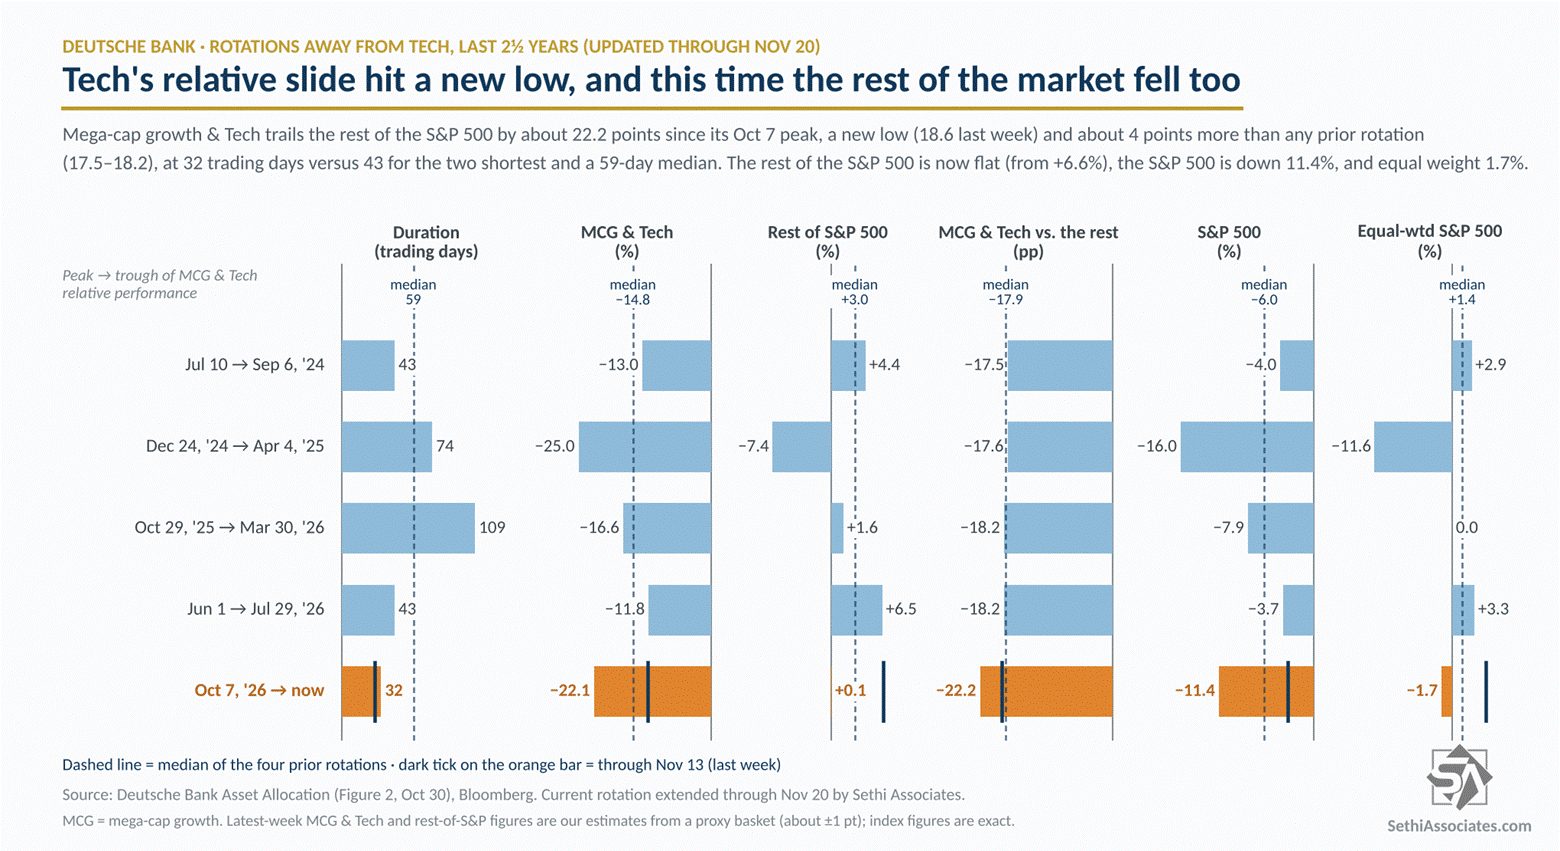
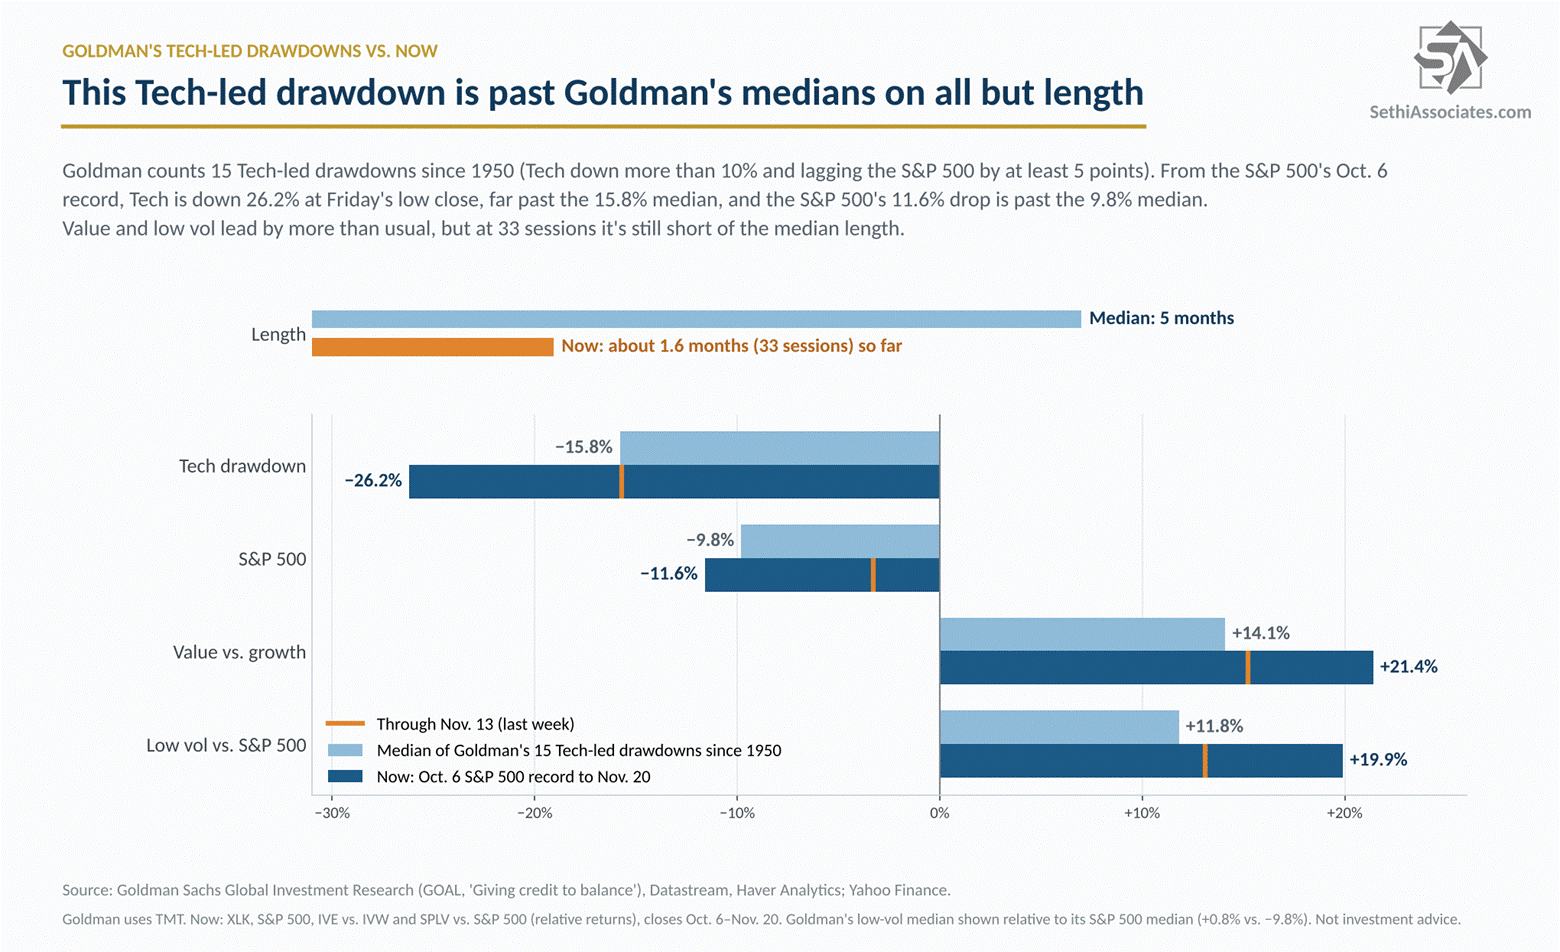
And we saw the selling spread. The Tech unwind itself is already more extreme than past episodes. On DB’s framework, the drop in Mega-Cap Growth and Tech relative to the rest of the S&P 500 is about 4 points bigger than in any of the four prior rotations, and what changed last week is that the rest of the market fell too. On Goldman’s, Tech’s 26% drop from the October 6th record is well past the 16% median for Tech-led drawdowns, and the S&P 500’s 11.6% is past its 9.8% median, though at 33 sessions it’s well short of the typical five months.
But we also saw the equal-weighted S&P 500 and Russell 2000 with their worst weeks since April 2025, gold its worst since August 2025, copper since July 2025, and bitcoin fall to the lowest since September 2024.
Many of these have historically led to a bounce the following week (and Thanksgiving week has been up 70% of the time since 1950):
- After the 19 prior times since 1990 that the VIX first closed at 35 or higher, the S&P 500 was higher a week later 79% of the time (median +2.2%, vs. +0.3% for all days).
- After the six prior first CNN Fear & Greed readings of 10 or below in a month (data back to 2021), the S&P 500 was higher a week later in five.
- After the 40 prior clusters of three roughly 80% NYSE downside-volume days since 1996, the S&P 500 was higher a week later 75% of the time (median +1.2%, vs. +0.3% for all days).
- After the four prior 90%+ surges in Cboe’s implied correlation index since 2006, the S&P 500 was higher a week later every time.
- After the 24 readings of Nasdaq positive volume below 20% since 2017, the Nasdaq was higher a week later 75% of the time (median +1.3%, vs. +0.6% for all days).
- Goldman says panic readings over 9.5 have signaled near-term relief.
- Tier1Alpha says the VIX was lower a week after 81% of similar expirations.
- Hartnett says his Global Breadth Rule buy signal is “likely triggered in coming days,” bringing short-term relief after Thanksgiving.
But there are plenty of signs that not everyone has panicked. Cboe’s equity put/call ratio ended at 0.77 (the 1.02 in Friday’s update was later corrected by StockCharts), lower than at six of the seven S&P 500 lows since 2018. AAII bears fell, Investors Intelligence’s bull/bear ratio rose, and Helene’s poll swung to its most bullish since at least late August (taken Saturday). Goldman’s Sentiment Indicator is still above average, investors put about $150 billion into US equity funds over the past month, and BofA’s private clients are within a point of their record allocation to stocks, with cash just above its record low.
The strategists have pointed this out. BofA’s Hartnett says “we need to see more positioning capitulation before giving all-clear to buy risk,” and Goldman, as noted above, says “despite the hedge fund unwind, our indicator of broad equity investor positioning remains elevated.”
That split shows up in a fear scorecard I’ve started to build out (only using data I have easy access to, and I only had so much time this weekend to work on it, so bear with me). My composite of seven fear gauges is at 93, matching the April 2025 low and above four of the seven lows since 2018. Two of the three signals I tested are flashing buy (the composite at 85 or higher and the VIX at 35 or higher), and the one that isn’t is the equity put/call ratio. Meanwhile, the fundamentals are stronger than at any of those lows, with analysts expecting S&P 500 earnings growth of 33.7% this year and 16.4% next, and a forward P/E of about 16.5, below the last four lows.
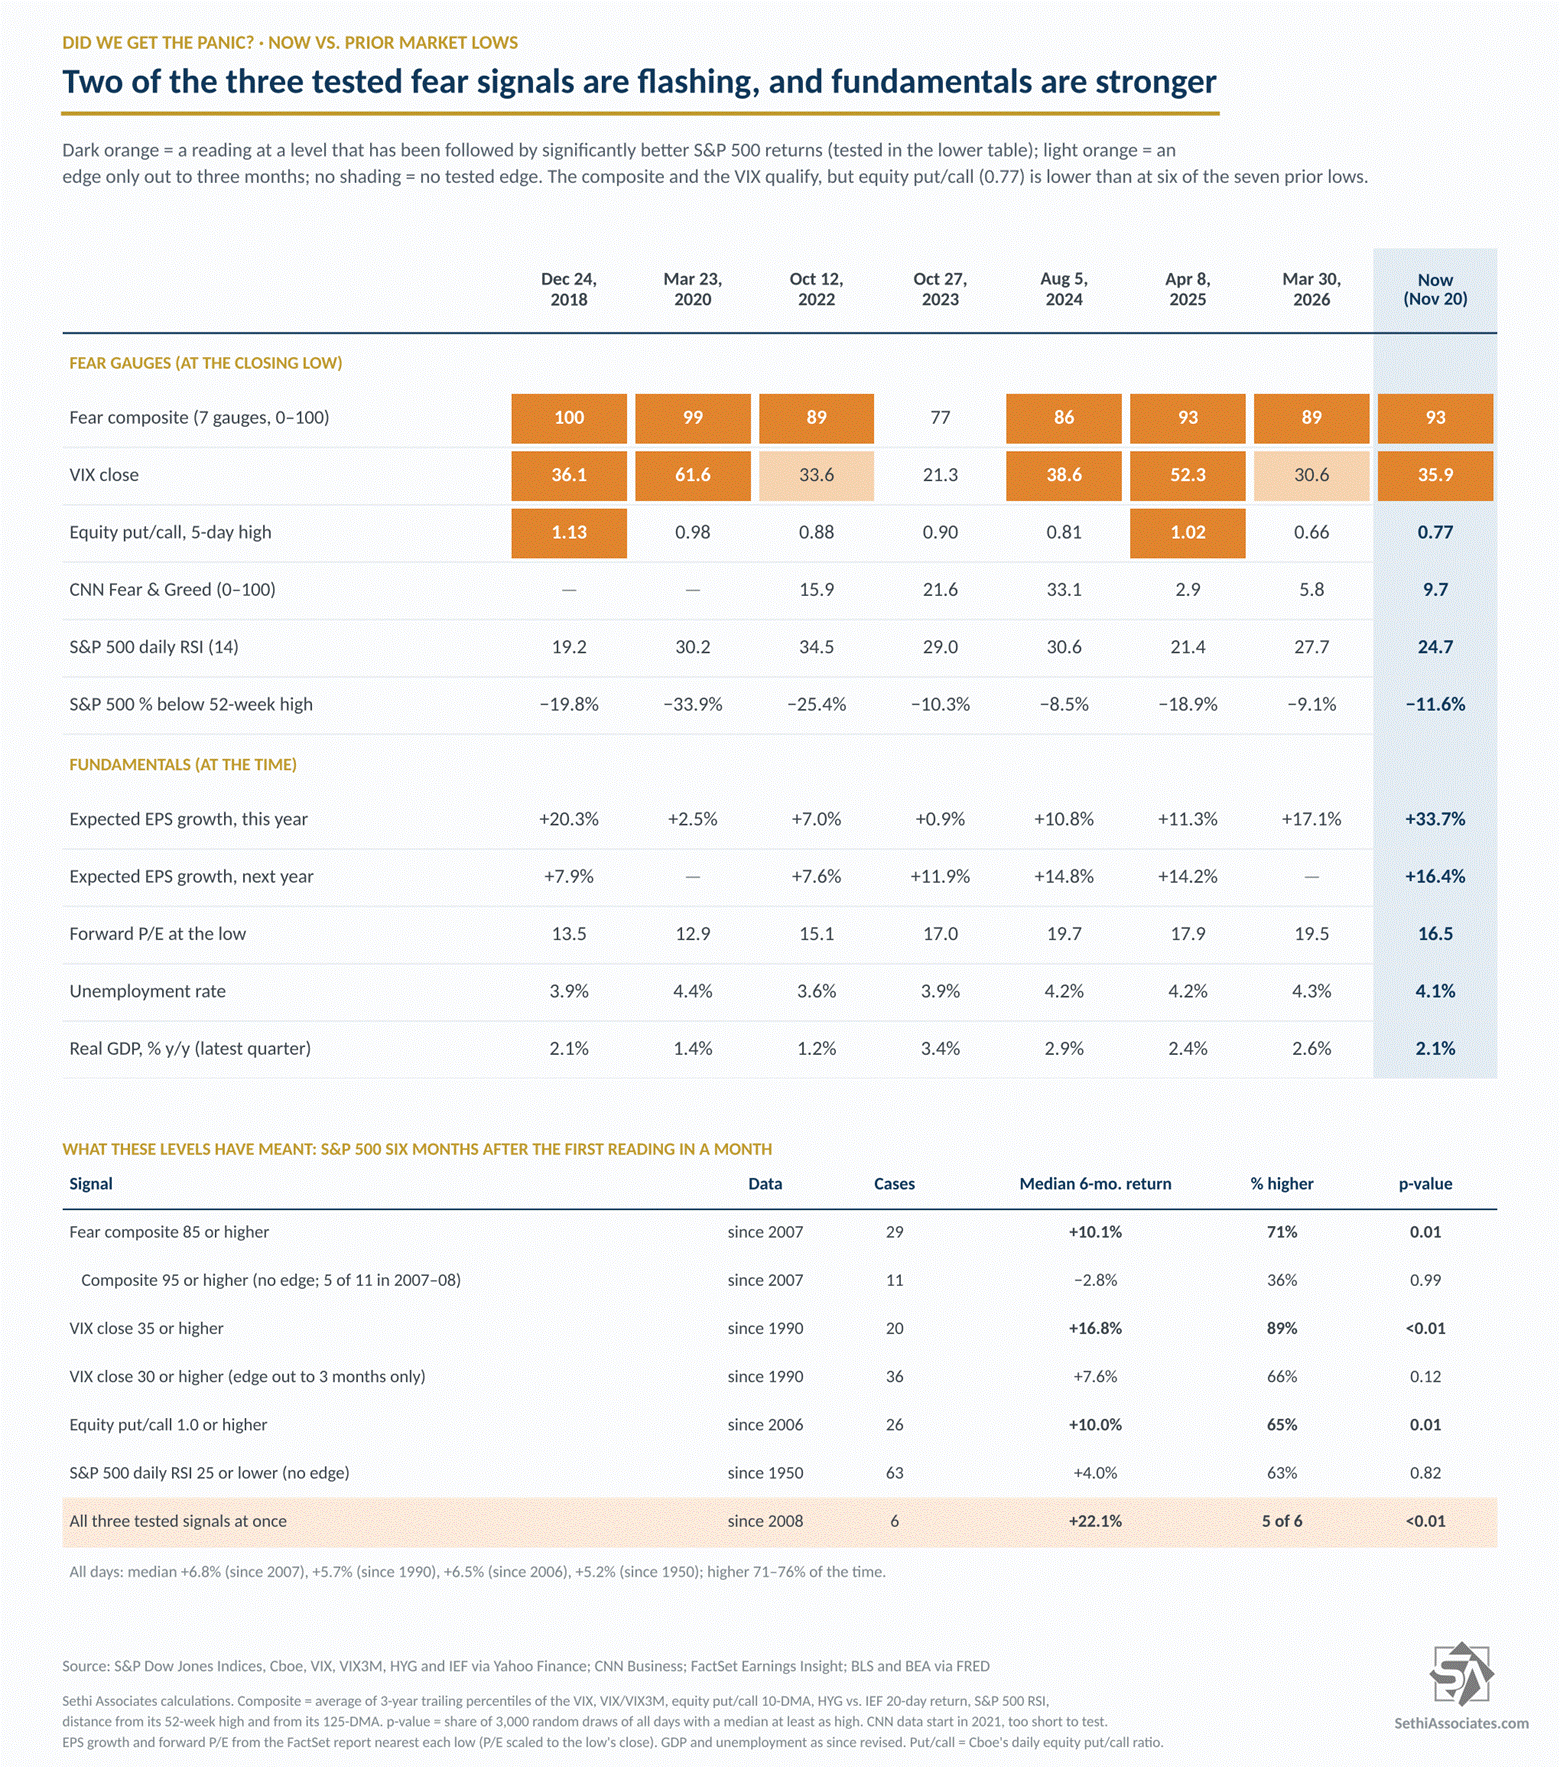
So the answer to whether we’ve seen panic is, I guess, “partly.”” We got the forced selling from the fast money, and as Goldman’s derivatives desk put it, “positioning is washed out, vol indicators are screaming oversold.” What we haven’t seen is capitulation from the retail and long-only investors who have been buying every dip.
Helene’s Sentiment Cycle Chart frames it the same way. She says the Nasdaq is “following that Sentiment Cycle Chart” she showed a few weeks ago, and last week’s 10% drop took the Composite to its lowest close since April 7th (22,618), through the cycle’s “Overt warning” line and onto the leg that ends in “Panic,” which in her cycle is followed by a sharp rebound and then a retest.
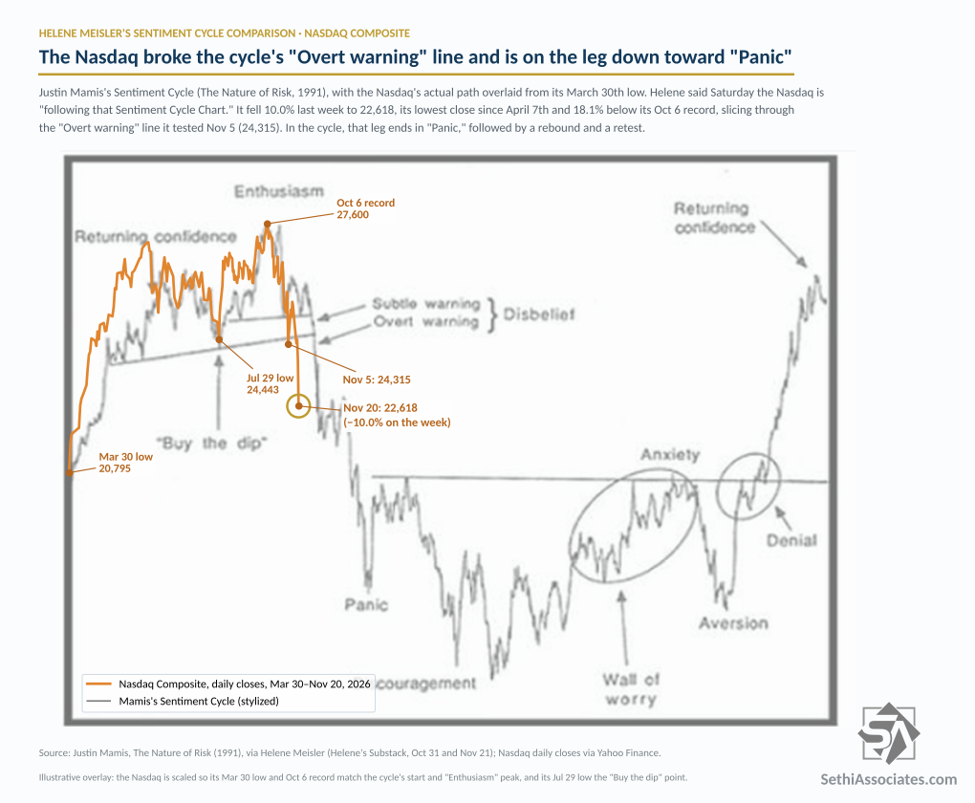
And while most of the backtests warn of a bumpy period coming, a lot of what we saw last week has historically been good for stocks down the road (my calculations unless noted):
- When the VIX first closed at 35 or more (19 times since 1990), the S&P 500 was higher six months later 89% of the time, with a median gain of 16.8% (vs. 5.7% for all days).
- After the 30 monthly options expirations since 1990 with the VIX at 30 or higher, it was higher six months later in 28.
- After the 12 prior weeks since 1990 when Goldman’s Financial Conditions Index tightened at least 41bp (it tightened 46bp last week, the most since March 2020), it was higher three months later 11 times, with a median gain of 6.5%, about double the norm.
- After the four prior 90%+ surges in Cboe’s implied correlation index since 2006, it was higher a year later every time.
- After clusters of three roughly 80% NYSE downside-volume days with the S&P 500 already 10% or more below its record (27 cases since 1996), it was higher a year later 89% of the time.
- The S&P 500, Nasdaq Composite and Nasdaq-100 are the most oversold since April 2025. An S&P 500 RSI of 25 or lower hasn’t been a reliable buy signal on its own, but in the 32 cases since 1950 when it came with the index already 10% or more below its 52-week high, the S&P 500 was up a median 6.9% six months later and 18.0% a year later, vs. 5.2% and 10.6% for all days.
- The seven-day losing streak, the first since February 2020, shows the same split. After the 46 prior streaks since 1950, the S&P 500 was higher a month later only 48% of the time, but six months later it was up a median 7.0% (74% higher), and 12 of the 13 since 1980 were higher. Half of the 20 streaks with drops of 5% or more, like this one (9.3%), saw another 5% decline within three months, though.
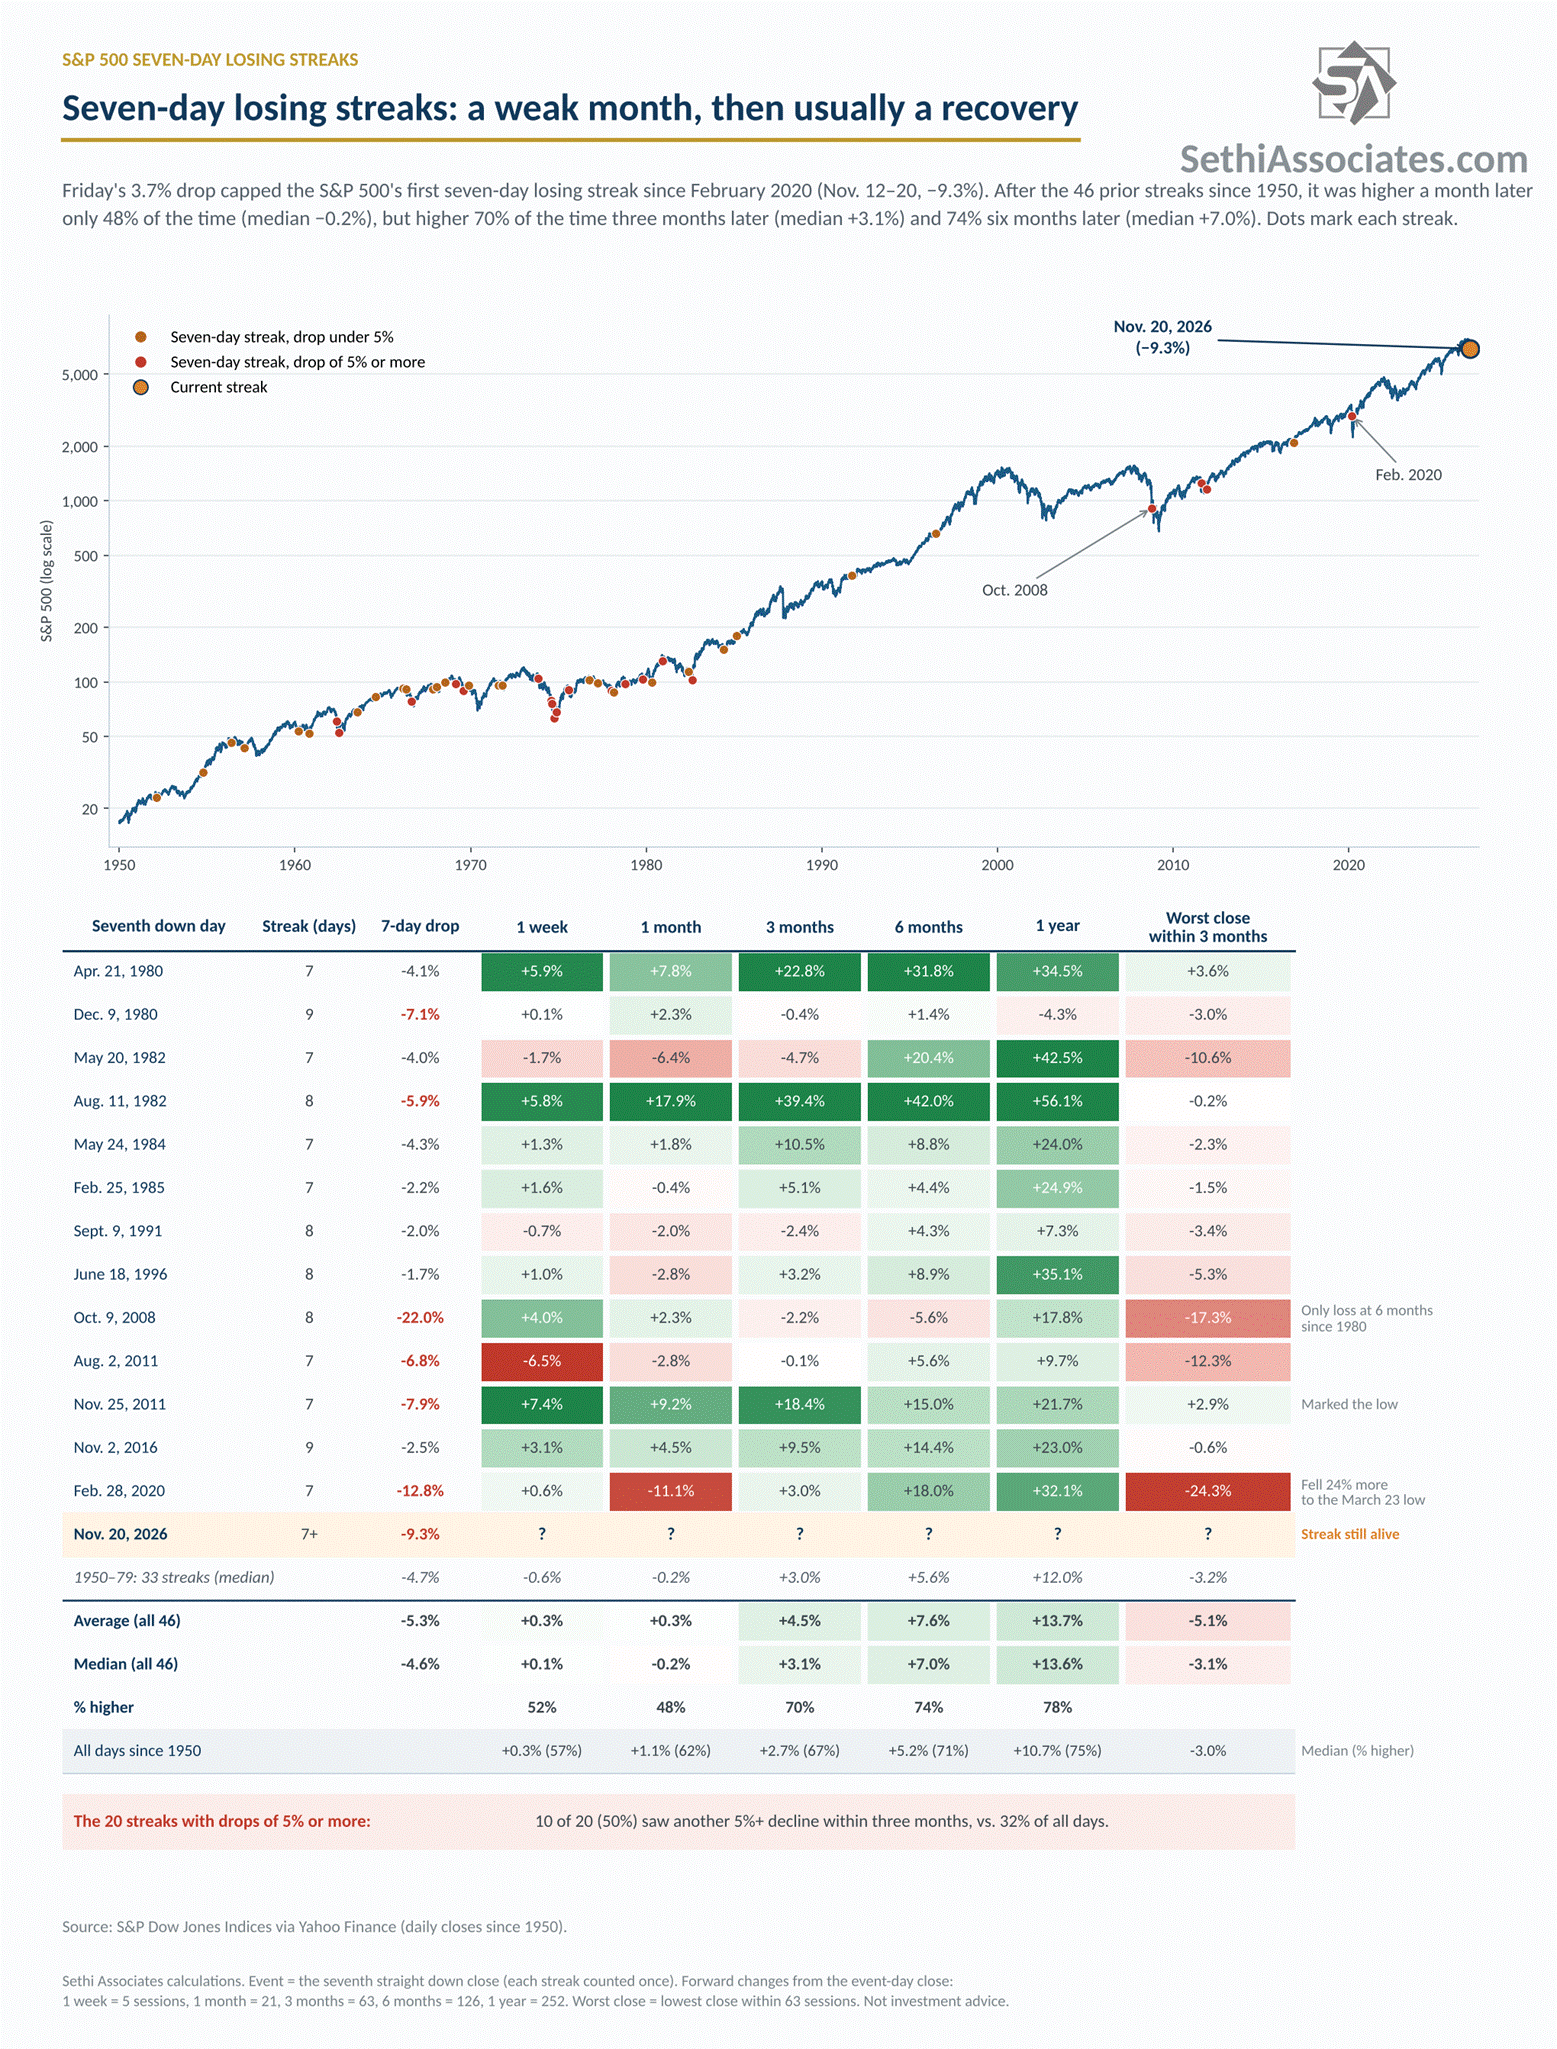
But between the next week and “down the road,” things have often been more mixed and volatile:
- After the 30 monthly expirations since 1990 with the VIX at 30 or higher, the first week was a coin flip, and the median worst close within three months was 4.9% below the expiration-day close (vs. 3.0% for all days).
- After the 12 prior big weekly FCI tightenings, the first week was also a coin flip, and the median worst close over the next three months was 3.7% below the event week’s close. In October 2008 the S&P 500 fell another 18.2% the next week.
- After the four bigger weekly VIX jumps, the S&P 500 was higher two weeks later only once (median −2.3%), per Goldman’s data.
- In the 32 cases since 1950 when the S&P 500’s RSI hit 25 or lower with the index already 10% off its high, it was higher a month later only 53% of the time (median +0.3%), and the median worst close over the next three months was 5.5% below.
- After the 46 prior seven-day losing streaks, the S&P 500 was higher a month later only 48% of the time, and half of the 20 with drops of 5% or more saw another 5% decline within three months.
- All five prior weeks with five straight declines and at least four 1%+ drops came in bear markets and made a lower low before the selling ended, with a median worst close over the next three months 5.6% below that Friday’s close.
- When the NYSE broke its pre-turn low after the five prior weak McClellan rebounds, it fell a median of another 8.9% to its low over the next three months, which came a median 18 sessions after the break.
- DB says that in past vol shocks it took an average of 6 to 8 weeks for vol to subside and equities to bottom, with the S&P 500 down 14% to 16% on average outside recessions, which would point to a low in early to mid-January.
- Goldman and BofA both see systematic funds selling again next week, even in a flat market, and the Monday after Thanksgiving has been higher in only 5 of the past 21 years.
The selloff also puts a bit of a dent in the “guru watch” metric I had noted in prior weeks. I’ve only seen updates from DB and Yardeni since Friday, and while DB continues to call for a rebound, Yardeni has become more cautious, lowering his year-end target to 7,500 from 7,900 (which was down from 8,400 on September 15th), but thinks a bear market is unlikely as “we don’t see an impending recession.”
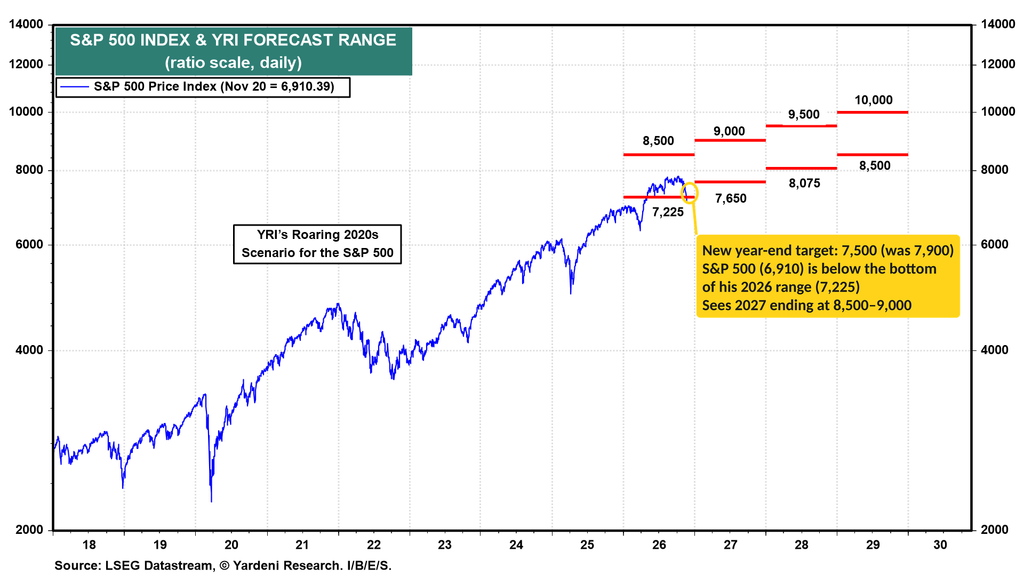
As for me, I think I learned my lesson about trying to predict upside. As I mentioned, a bounce would certainly be historically normal, but we’re now also in a historically sharp and volatile drawdown (one of the quickest corrections on record, according to Ryan Detrick of Carson Group), which means the “tails” of the distribution are fatter (i.e., big moves in either direction are more likely). That’s only exacerbated by negative gamma and the still-large amounts in leveraged products (even if they’re down significantly from the highs).
That argues even more for just taking things as they come. As I said Friday, I’ve been rigorous about sticking to my stops, so I’ve dramatically cut back my equity exposure and am sitting on quite a bit of cash. I’ll be looking to deploy that tactically in the upcoming weeks until we have better stabilization, at which point I may make some longer-term bets.
One other thing to watch, and I’ll have a more detailed post on it Monday, is the depth of this drawdown. The nine corrections that stopped short of 15% (6,646 on the S&P 500, 3.8% below Friday’s close) all bottomed by 14.4% and were higher a year later every time, while all 15 that went past it fell at least 18.9%, and 11 of them became bear markets. Speed mattered too: the six that got there within three months mostly stopped short of 20% (which as noted is consistent with this drawdown).
As always, let’s see what we get and go from there.
At the time of publication, in terms of securities mentioned, Sethi was long AMZN, GOOGL, NVDA, SOXL and numerous Treasury ETFs, and short IBIT, IWF, IWM and VOO.