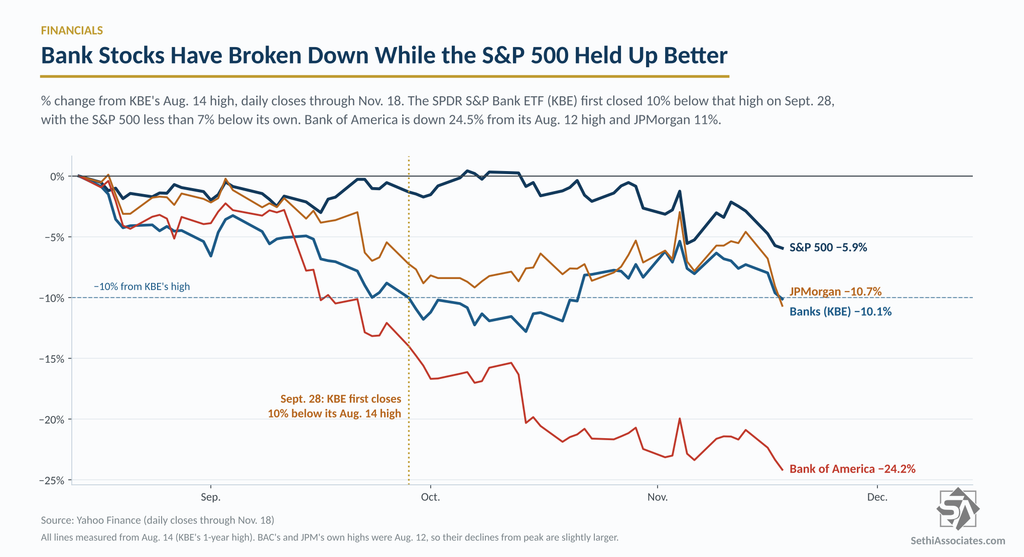
The SPDR S&P Bank ETF (KBE) first closed 10% below its 1-year high (set Aug. 14) on Sept. 28, with the S&P 500 less than 7% below its own high, and as of Wednesday’s close it was still more than 10% below.
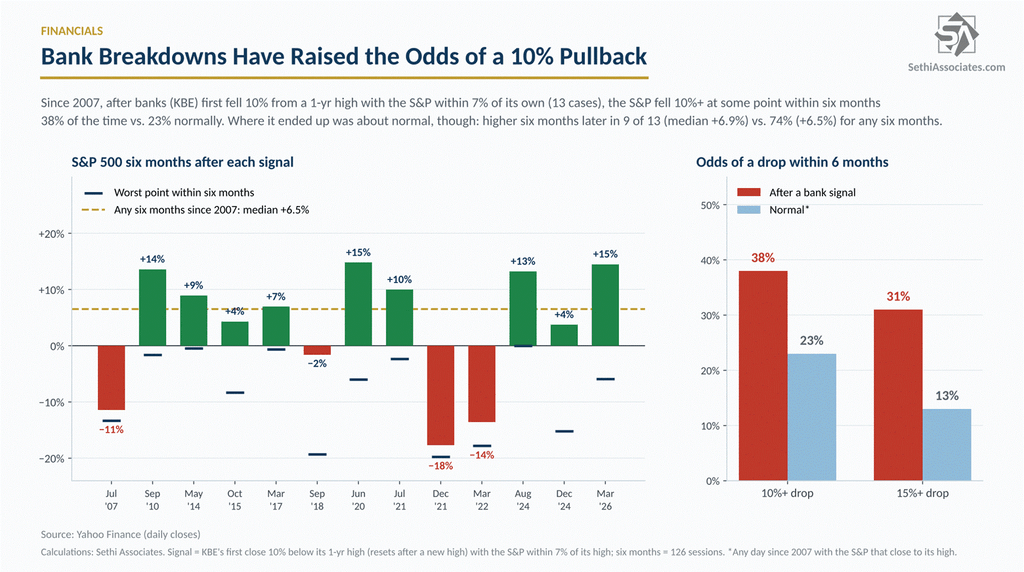
Since 2007, there have been 13 prior signals like that. “I used KBE’s first close 10% below a 1-year high, with the S&P within 7% of its own high, and reset the signal after banks make a new high.
The S&P’s path was noticeably rougher than normal afterward. It fell 10% or more at some point within six months in 5 of the 13 (38%). That compares with 23% for any day since 2007 with the index that close to its high. The odds of a 15%+ drop were 31% vs. 13%. The 10%+ drops came after the 2007, 2018, December 2021, March 2022 and December 2024 signals.
Where the S&P ended up was about normal, though. It was higher six months later in 9 of the 13, with a median gain of 6.9%. That’s roughly in line with any six-month period since 2007, which was up 74% of the time with a median of 6.5%. So it’s not a reliable sell signal, but definitely a caution sign.
Within the group, the big banks have been hit harder. As of Wednesday’s close, Bank of America (BAC) was down 24.5% from its Aug. 12 high and JPMorgan (JPM) was off 11%.
High-Profile IPOs Have Usually Lagged in Their First Year, but Note the Exceptions
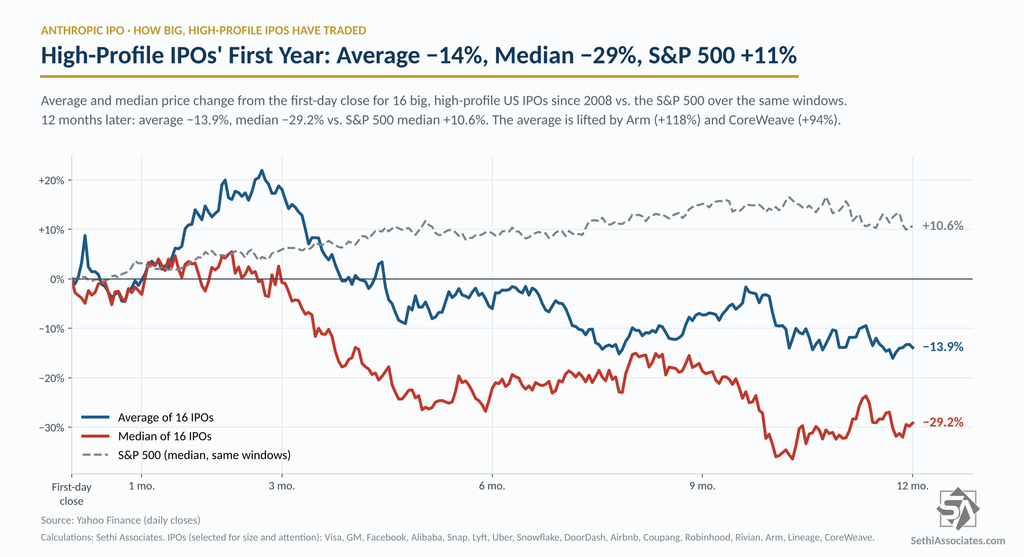
With Anthropic (ANT) set to begin trading today, I looked at how 16 big, high-profile U.S. IPOs since 2008 performed over their first year. These are deals that drew a lot of attention, from Facebook and Alibaba to Rivian and Arm. The usual pattern has been to track the S&P 500 closely at first, then lag notably starting a little over two months in.
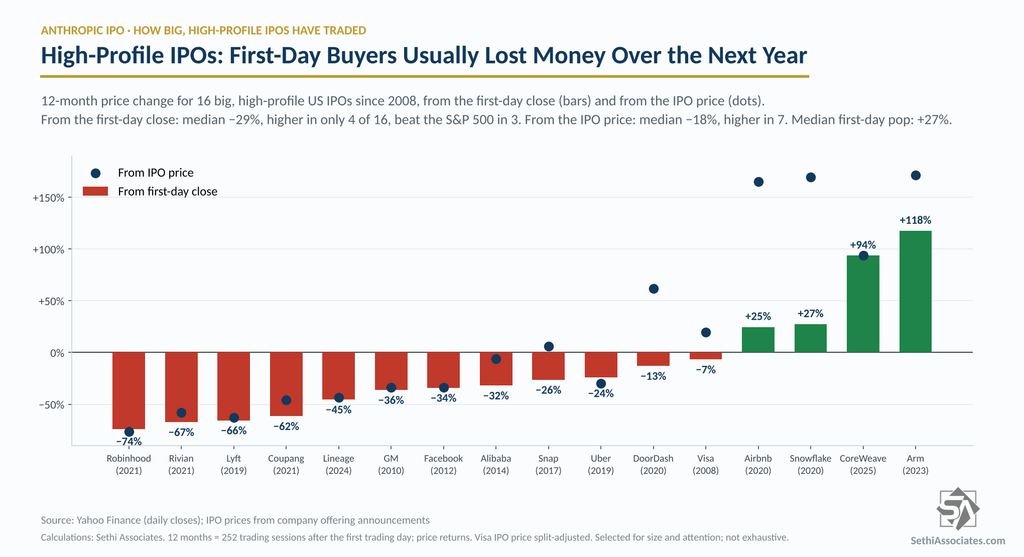
Measured from the first-day close, the median stock was down 29% after 12 months. Only four of the 16 were higher, and just three beat the S&P 500, which gained a median 11% over the same windows. The average was −14%, better than the median only because of two big winners. Even buyers who got shares at the IPO price were down a median 18% after a year, despite a median first-day pop of 27%.
The worst included Robinhood (HOOD) (−74%), Rivian (RIVN) (−67%), Lyft (LYFT) (−66%) and Coupang (CPNG) (−62%). Facebook, now Meta Platforms (META), fell 34%. The winners were Arm Holdings (ARM) (+118%), CoreWeave (CRWV) (+94%), Snowflake (SNOW) (+27%) and Airbnb (ABNB) (+25%). Notably, the two biggest gainers were among the most recent deals, and both are tied to AI, CoreWeave most directly.
You’ll notice a new video player on the home page today. It’ll be there through tomorrow, when we’ll be showing the live stream of TipRanks’ coverage of the ANT IPO and the AI trade.
TipRanks may have some additional coverage today, which I’ll be posting here, in Stock Market Today.
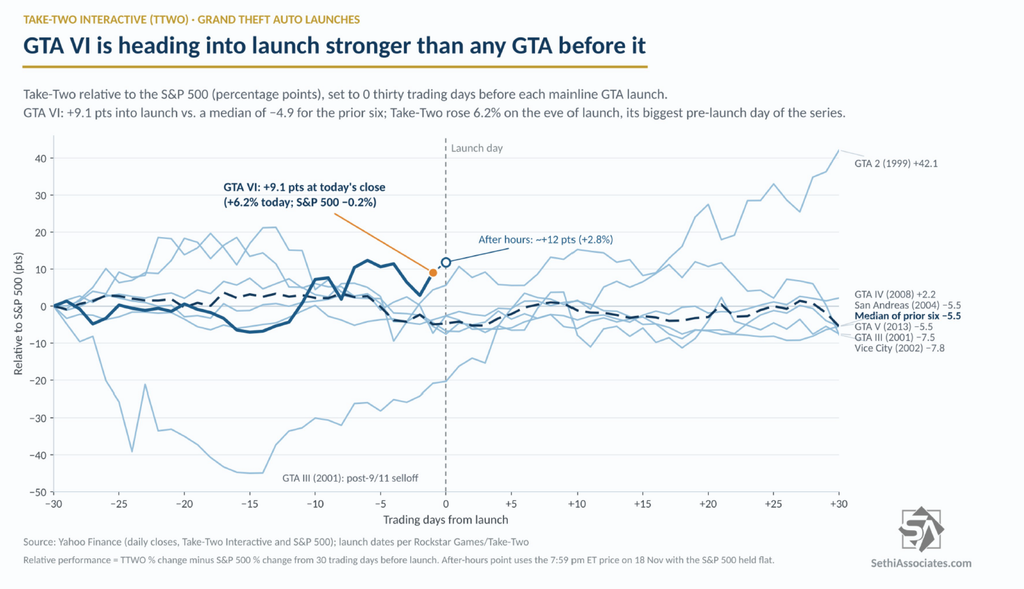
Take-Two is indicated about 2.8% lower premarket (as of 8 a.m. ET). That comes though after the stock ran well ahead of its typical pre-launch path, which may set the context for what comes next.
Going into this release, Take-Two beat the S&P 500 by about 9 points over the 30 trading days before launch. Across the six prior GTA launches, the median was nearly 5 points of underperformance over the same stretch, and only GTA 2 (1999) also outperformed. Wednesday’s 6.2% gain was also the biggest day-before-launch move of the series; the prior six ranged from −8.1% to +5.3%. That came after GTA VI hit a 99 Metacritic score based on 150 critic reviews, tying The Legend of Zelda: Ocarina of Time for the highest ever.
Historically, the stock gained well before release and faded into launch, then outperformed modestly after. It has beaten the S&P on launch day in 4 of 6 releases, but only by a median of about 1 point. Thirty days out, the median has been about 3 points ahead of the S&P measured from launch day.
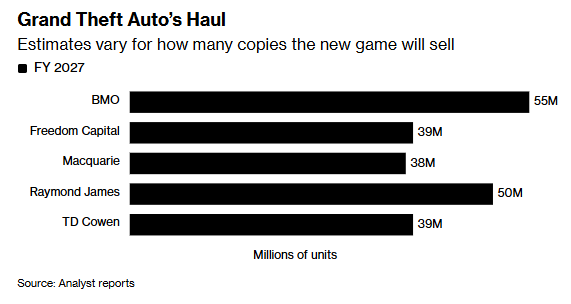
Demand doesn’t look to be an issue. Sensor Tower estimated preorder revenue reached $1.45 billion from 14.94 million copies sold as of Nov. 16 (gaming.net). Bloomberg reports the game is expected to generate over $3 billion in sales in its first few months. Analyst estimates for fiscal 2027 unit sales range from 38 million (Macquarie) to 55 million (BMO).
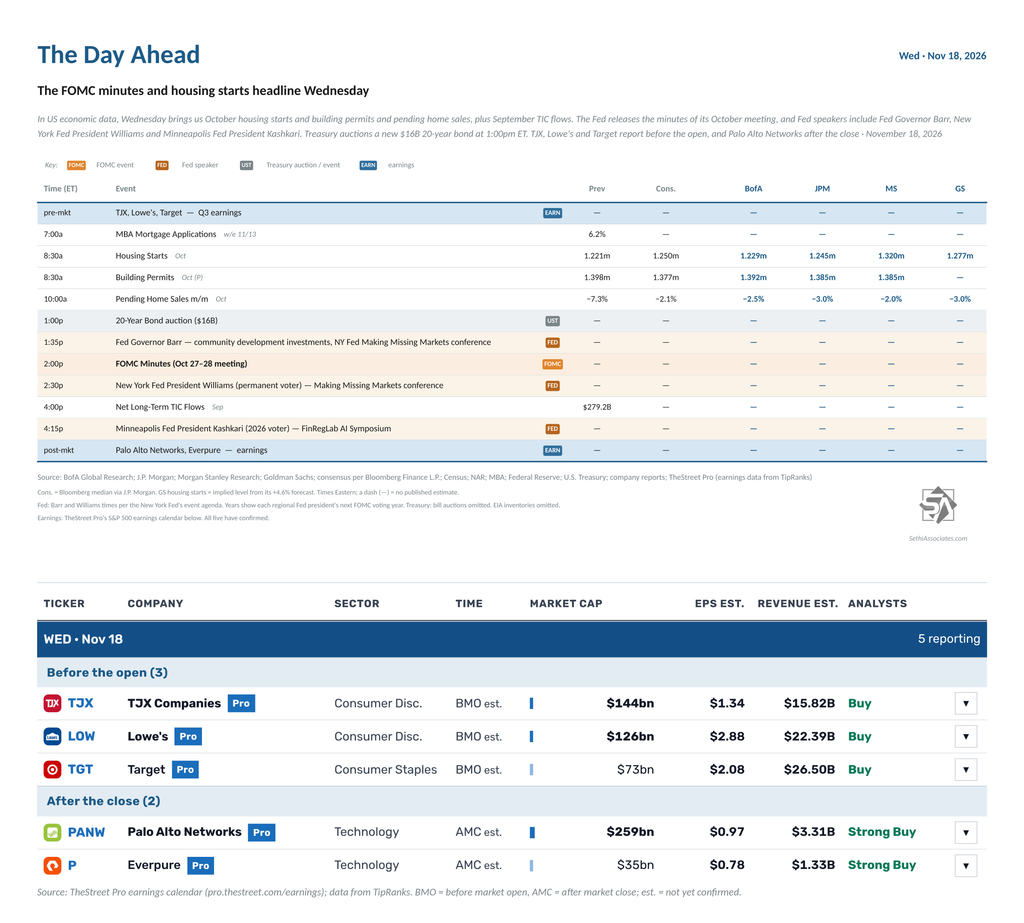
The Day Ahead — Anthropic Debuts and Walmart Reports
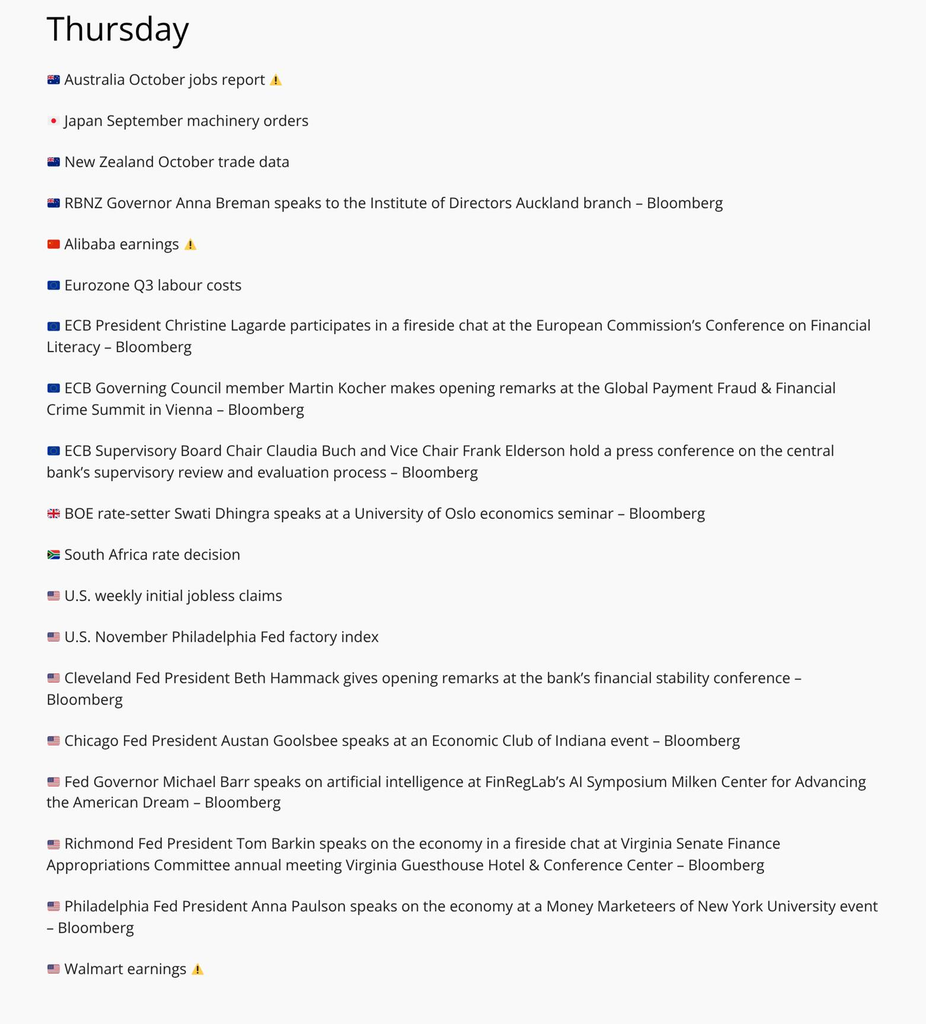
In US economic data, Thursday brings us the November Philadelphia Fed and Kansas City Fed manufacturing surveys and the October leading index, plus the usual weekly jobless claims.
Fed speakers include Cleveland Fed President Hammack (2026 voter), Chicago Fed President Goolsbee (2027 voter), Fed Governor Barr, Richmond Fed President Barkin (2027 voter) and Philadelphia Fed President Paulson (2026 voter).
Non-Bill (>1yr in maturity) US Treasury auctions bring us a $19B 10-year TIPS reopening at 1:00pm ET.
Four S&P 500 components report, one of them with a market cap over $100B:
Before the open: Walmart (WMT) and Williams-Sonoma (WSM).
After the close: Intuit (INTU) and Ross Stores (ROST).
Outside the S&P 500 we’ll hear from Chinese heavyweights Alibaba (BABA), PDD Holdings (PDD) and NetEase (NTES).
Anthropic (ANT) is also set to begin trading on the Nasdaq after pricing its IPO tonight.
Ex-US highlights include New Zealand’s October trade data (4:45pm ET Wednesday) and Australia’s October jobs report (7:30pm ET Wednesday), Japan’s September core machinery orders, the UK’s November CBI industrial trends, eurozone Q3 labor costs, South Africa’s rate decision (8am ET) and Banxico’s minutes (10am ET), plus the ECB’s supervisory press conference with Buch and Elderson and remarks from ECB President Lagarde and the BoE’s Dhingra. APEC’s leaders’ meeting in Shenzhen wraps up, with President Trump, Xi Jinping and Vladimir Putin expected to meet Thursday.
Conversation 0 Comments
One ongoing discussion across all days. Everyone can read; sign in to take part.
Your voice matters. Discussions are moderated for civility. Read our guidelines .
Log in to join the conversation