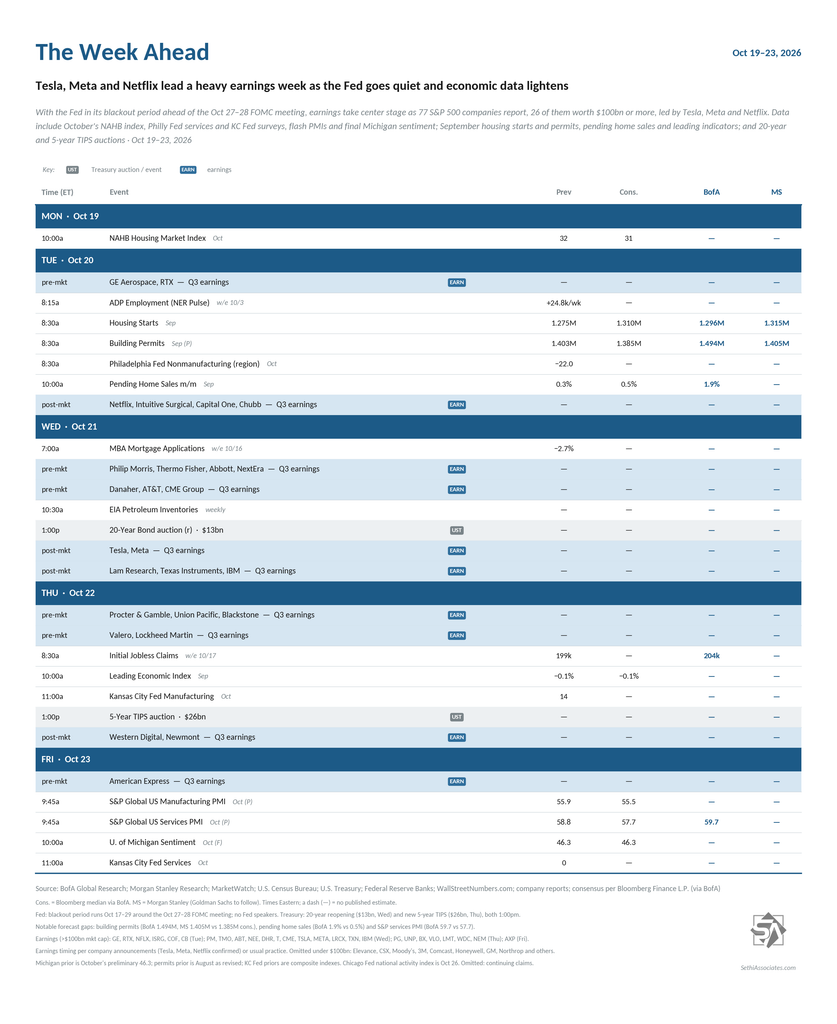
After a busy week, US economic data lightens next week. October reports are highlighted by S&P Global flash PMIs and final University of Michigan consumer sentiment and also include the NAHB housing market index, the Philly Fed services survey, and the Kansas City Fed manufacturing and services surveys. September reports include housing starts and building permits, pending home sales and the Conference Board’s leading and coincident indicators. We’ll also get the usual weekly reports (ADP, mortgage applications, unemployment claims, etc.).
The Fed enters its blackout period Saturday ahead of the October 27–28 FOMC meeting, so there are no Fed speakers next week.
Non-Bill (>1yr in maturity) US Treasury auctions resume with a $13bn 20-year bond reopening Wednesday and a $26bn new 5-year TIPS auction Thursday.
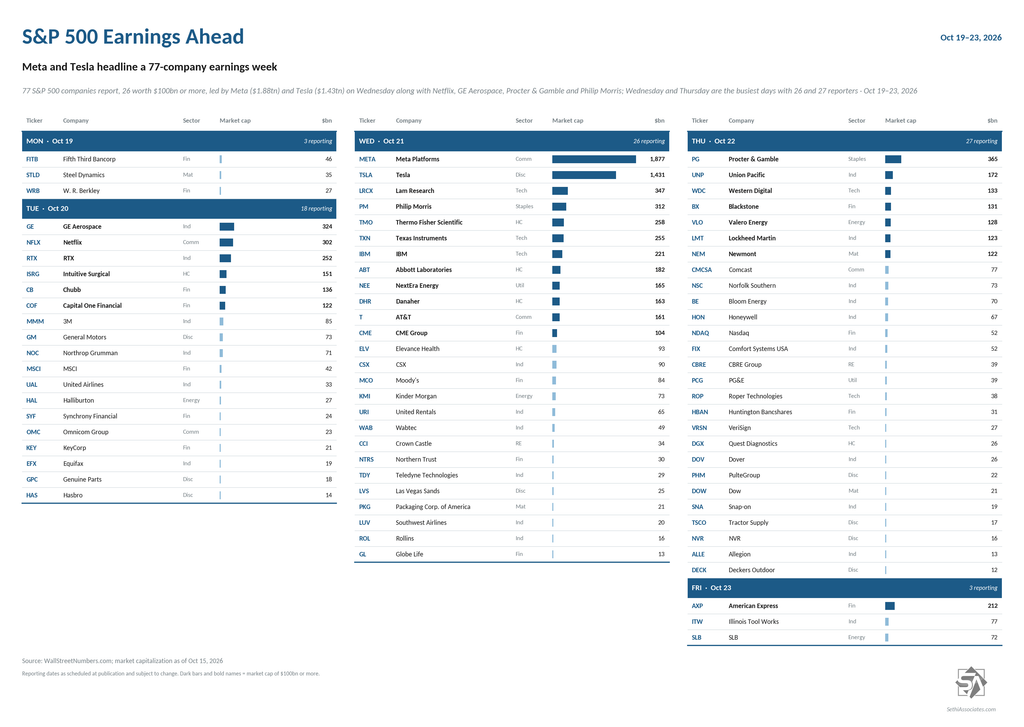
Q3 earnings season kicks up a gear with 77 S&P 500 components reporting, 26 of them with market caps over $100bn:
Tuesday: GE Aerospace (GE), Netflix (NFLX), RTX (RTX), Intuitive Surgical (ISRG), Chubb (CB) and Capital One (COF)
Wednesday: Meta Platforms (META), Tesla (TSLA), Lam Research (LRCX), Philip Morris (PM), Thermo Fisher (TMO), Texas Instruments (TXN), IBM (IBM), Abbott (ABT), NextEra Energy (NEE), Danaher (DHR), AT&T (T) and CME Group (CME)
Thursday: Procter & Gamble (PG), Union Pacific (UNP), Western Digital (WDC), Blackstone (BX), Valero (VLO), Lockheed Martin (LMT) and Newmont (NEM)
Ex-US highlights from Deutsche Bank:
Global growth will be in focus next week with the flash October PMIs due Friday for economies including the US, UK, Japan, Germany and France. In Europe, there will also be the ZEW survey for Germany (Tuesday) and October business confidence in France (Thursday).
A busy week is ahead for UK data, with labour market indicators due Tuesday and September inflation out Wednesday. Our UK economists expect inflation to push to its highest rate all year, with headline CPI rising to 3.49% YoY and core pushing to 2.74% YoY. They see headline RPI jumping to 3.93% YoY. Friday brings October GfK consumer confidence and September retail sales.
A quieter week is ahead for central bank events, with highlights including the Bank of Korea’s policy decision on Thursday (our economists expect a pause) and the ECB’s consumer expectations survey on Friday. ECB’s quiet period starts Wednesday.
Over in Asia, the week begins with China’s Q3 GDP report on Monday, alongside September retail sales and industrial production indicators. Our economists forecast industrial production growth to accelerate to 6.0% YoY from 5.2% in August and retail sales growth to edge up to 0.6% YoY but remain weak. Against this backdrop, they see Q3 GDP growth at 4.4% YoY, below the lower end of the growth target.
In Japan, highlights include September national CPI (Friday) and trade balance (Wednesday). Our Chief Japan economist forecasts the core CPI (all items less fresh food) to rise by 2.1% YoY (vs. 1.7% in August) and the core-core CPI (all items less fresh food and energy) to increase by 2.3% YoY (vs. 1.9% in August). Inflation prints are also due in Canada (September CPI on Monday) and New Zealand’s (Q3 CPI on Wednesday
This post will go through in order (in case you want to skip around): the economy, the Fed and interest rates, earnings, valuations, breadth, positioning, sentiment, seasonality, and then my wrap-up.
The Economy Continues To Grow Above Trend
Looking first at the economy, my intro has remained the same since the start of the Iran conflict (and longer term, more or less all of the past five years – I’ve not had a recession probability above 40% since the pandemic): “we continue to see it weathering the various storms remarkably well due in large part to resilient consumption (boosted by huge increases in wealth over the past few years despite slowing incomes) and AI-spending… with data of late showing a stable (and perhaps accelerating) economy, but one that is also boosting inflation.”
As noted previously, while things tailed off in July into the start of August, since then we have seen economic momentum rebound outside of the housing sector with the caveat as mentioned two weeks ago we did see nonfarm payroll growth stall out (which though may simply be a function of a harsh seasonal adjustment) and we got a relatively weak personal income figure.
Last week was heavy on data and for the most part it remained consistent with the foregoing, but with perhaps another chink in the armor in the retail sales report (which, though, like payrolls two weeks ago comes after a very strong August report):
Retail sales rose 0.8% versus a 0.3% estimate, but gas stations were over 70% of that while control group sales, which feed into GDP, rose only 0.14%, the least since July, versus the 0.3% estimate.
Industrial production beat estimates, rising from a year earlier the most since September 2022, as manufacturing rebounds from August’s dip and utility output jumps to a record high led by electricity.
September existing-home sales rose 1.5% from August, but NAR’s chief economist cautioned Q4 closings could be ‘measurably down’ as affordability slips year-over-year for the first time this year.
Initial employment claims came in at 199,000, only the 11th week below 200,000 since 1969, while the four-week average of continuing claims fell to its lowest level since April 2023.
Preliminary weekly hiring report from ADP for the four weeks ending September 26th fell for the first time since early August, but very slightly and only after an upward revision to the prior week. At +99k (+24.75k/wk), it was otherwise the best since June 6th, and the 4-week moving average rose for a sixth week to +74.3k, the best since July 11th.
Mortgage Bankers Association purchase index, which measures loan applications, dropped 4%, marking the sixth straight weekly decline — the longest such stretch since July-August 2023. The gauge stands at the lowest level since early 2025. Meanwhile, MBA’s refinance gauge fell for an eighth straight week, to the lowest level since early 2025. That was as the contract rate on a 30-year fixed mortgage ticked up 1 basis point to 7.50% in the week ended Oct. 9, the highest level since November 2023.
I had said two weeks ago, “the most concerning item to me at this point is wage growth, but so far that hasn’t dented consumer spending with the large gains in wealth from stock and home prices.” I can’t say that after the September retail sales number, but that’s just around one-third of consumer spending, so we’ll see what the full numbers bring at the end of the month. While many credit the AI-boom with carrying the economy, consumption was 68% of GDP in the first half of the year.
But JPM’s Feroli notes:
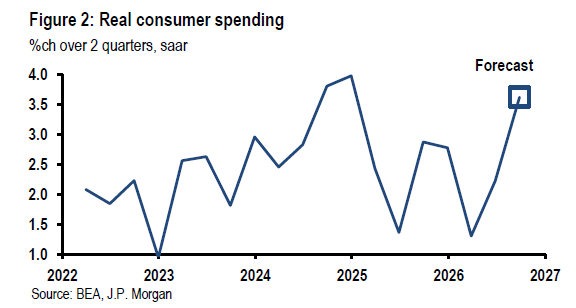
Alongside the inflation data, September’s key activity reports were reasonably solid. Retail sales were not particularly strong, but real consumer spending still likely rose 0.1% in September, capping a brisk two-quarter gain (Figure 2) and suggesting some upside risk to our fourth-quarter spending growth forecast of 1.5%.
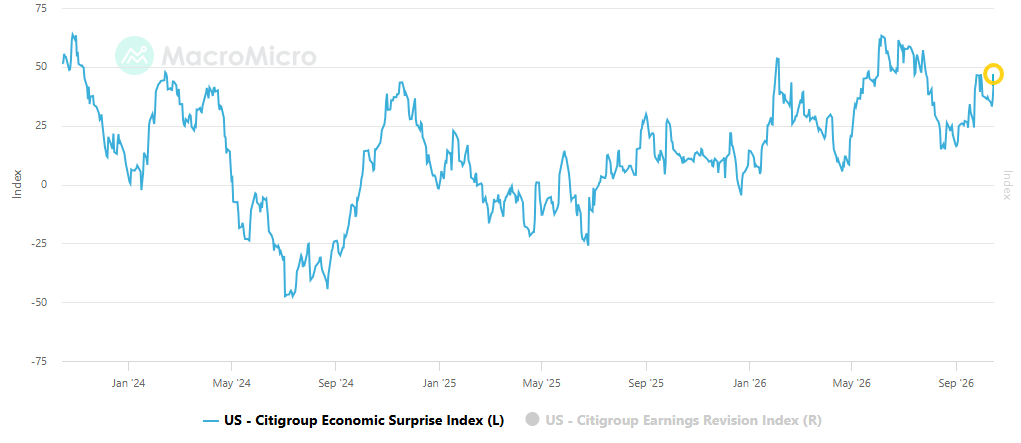
Remembering that a hot inflation print (which we had three of this week) counts as a positive surprise (as it is associated with a stronger economy), the Citi economic surprise index jumped to 46.1, just below the 46.5 September peak (the best since July), from 36.1 the prior week.
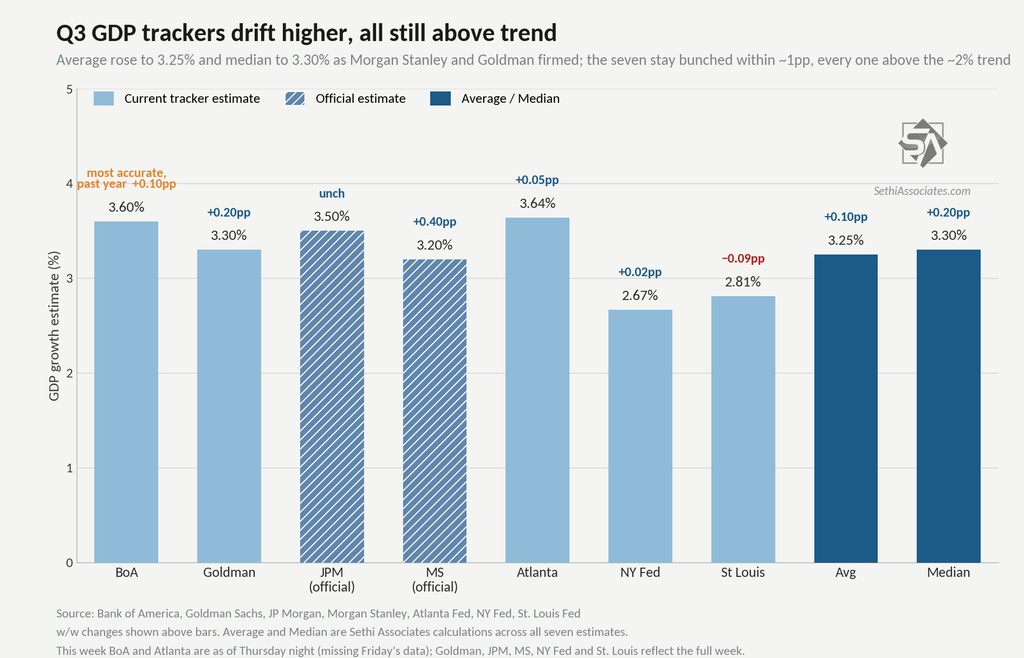
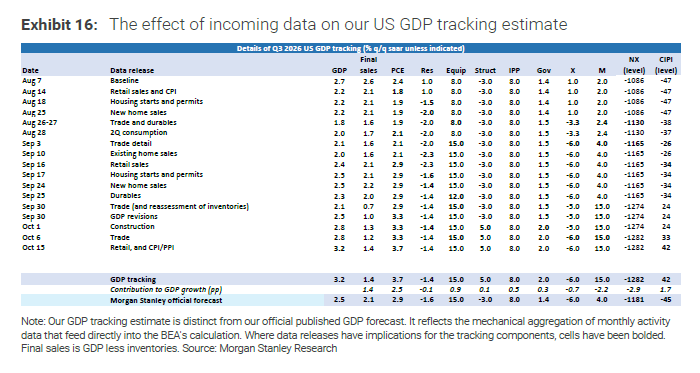
And Q3 GDP estimates were alsoboostedoverall with the average improved to +3.25% from +3.15% the prior week, and the median slipped to +3.30% from +3.10%, very strong growth.
BofA (who has been the most accurate over the past year) +3.6% (from +3.5% the prior week). Goldman +3.3% (from +3.1%) JPM +3.5% (+3.5%) Morgan Stanley +3.2% (+2.8%) Atlanta Fed +3.64% (from +3.59%) NY Fed +2.67% (+2.65%) St Louis Fed +2.81% (+2.90%) Avg = +3.25% (from +3.15%) Median = +3.30% (from +3.10%)
Here’s MS on their GDP boost:
Our third-quarter GDP tracking estimate rose 0.4 percentage point to 3.2% this week. Although September retail sales were soft, annual revisions to the retail sales data lifted our estimate of third-quarter real consumer spending growth by 0.4 percentage point to a 3.7% quarterly annualized rate. We also raised our estimate of third-quarter inventory investment slightly.
This marks the second consecutive quarter of roughly 4.5% growth in private domestic final purchases—a measure of private demand—and 3.75% consumption growth. Both have accelerated by more than a percentage point from their pace over the preceding four quarters.
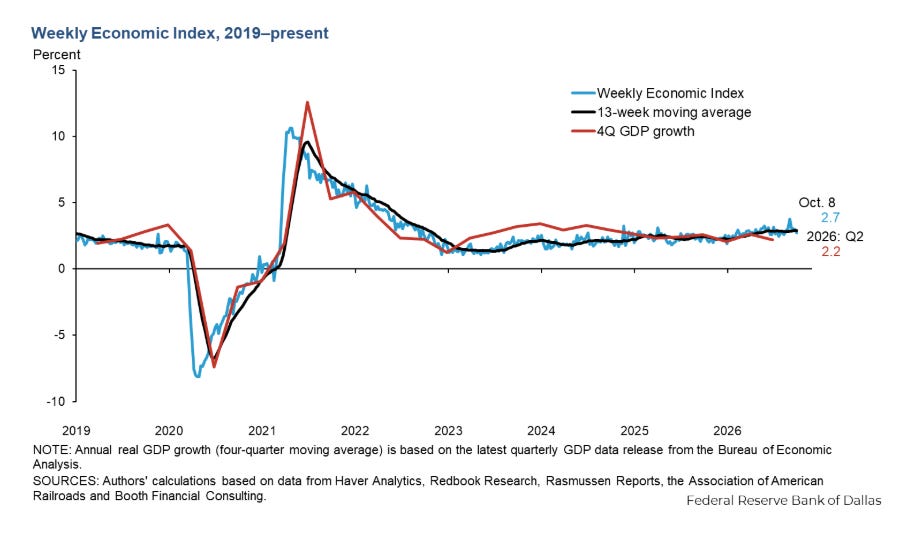
And as you know if you’re a regular reader, one of my favorite GDP trackers is the Weekly Economic Index from the Dallas Fed.*
In the week through October 10th (so doesn’t have last week’s data) it got back over 3% for the fifth week in six at +3.05%, from +2.91% the prior week (as revised).
The 13-week average also reaccelerated to 2.91%, tying two weeks ago with the best since 2022, still continuing to evidence economic momentum that is above trend.
*The WEI is scaled as a y/y rise for real GDP(so different than most GDP trackers which are Q/Q SAAR) and uses 10 daily and weekly economic series but runs a week behind other GDP trackers.
It has over time had one of the highest correlations with actual GDP of any tracker(see chart)although for Q2 it came in highpredicting +2.80% y/y GDP growth vs the actual first estimate of +2.10%, while for Q1 it predicted +2.48% vs 2.66%. More importantly, it has consistently indicated no recession and relatively healthy growth since the pandemic (which is what we’ve experienced).
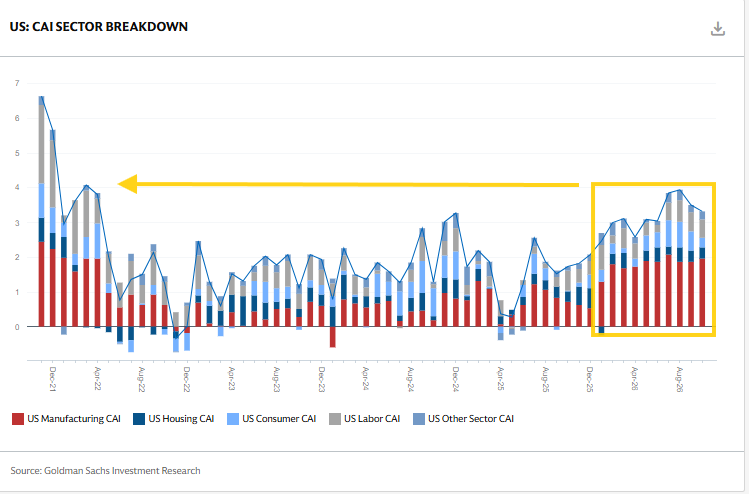
Goldman initiated their October US Current Activity Indicator* at 3.3%. While very solid, it is now a second consecutive month of deceleration from a peak in August at +3.9% which was the best since March 2022. Still it’s the strongest ten-month period since then.
*The CAI is their “real-time measure of inflation-adjusted economic momentum using 37 inputs.”
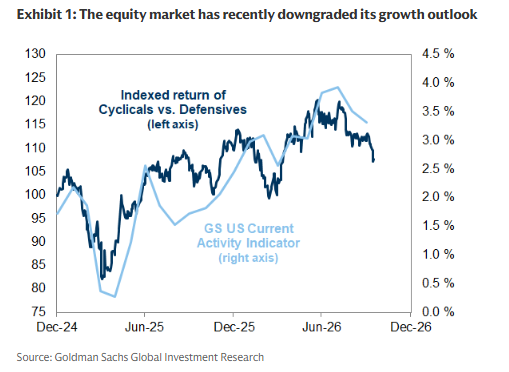
Goldman tied this to the concerns about AI:
Intensifying concerns about the cost and availability of funding have caused investors to reduce their equity market exposures and price a deceleration in the growth outlook. Rising energy prices and interest rates have weighed on the performance of many cyclical equities since early August. During the last two weeks, however, the potential implications of a sharply rising cost of capital on the AI build-out have weighed further on the market outlook for economic and earnings growth.
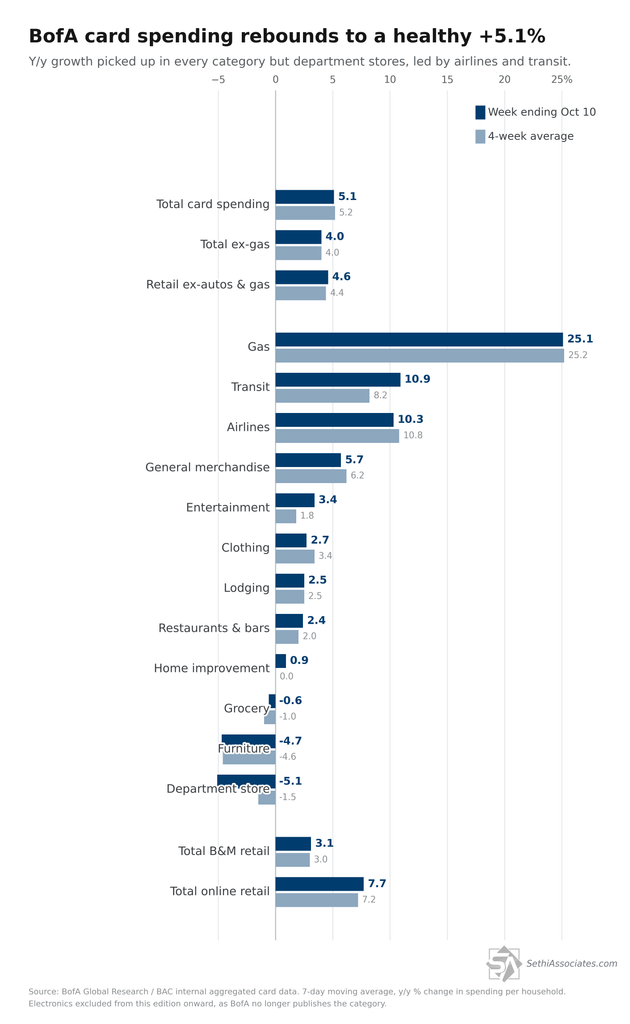
BofA card spending (credit+debit) rebounded to +5.1% versus the year-ago period (y/y) in the week ending October 10th, up from +3.0% the prior week which BofA said was likely depressed by the Nor’easter. In particular, ex-gasoline and autos spending growth rose to +4.6% y/y from +1.8% — which gives hope for a rebound in October retail sales. BofA called spending healthy and said Hurricane Isaias’s impact was limited to some sectors, such as restaurants in the South.
Ex-autos and gasoline +4.6% y/y (+4.4% four-week moving average)
The rebound was nearly as broad as last week’s slowdown: y/y growth picked up week over week in every category except department stores. On the income split, BofA noted that lower-income spending growth has consistently outpaced higher-income over the past several weeks.
Gasoline rose to +25.1% y/y (from +22.5%), still elevated versus a year earlier.
Ex-gasoline, airlines (+10.3%, from +4.2%) and transit (+10.9%, from +5.8%) led the rebound, and online retail rose to +7.7% from +4.5%. General merchandise (+5.7%) and entertainment (+3.4%) firmed. Lodging (+2.5%) and restaurants & bars (+2.4%) returned to positive territory after both slipped to −0.1% the prior week.
Three categories were negative y/y, down from six the prior week: department stores (−5.1%, the only category to slow), furniture (−4.7%, from −7.4%), and grocery (−0.6%, from −3.4%).
And Redbook sales*in the week of October 9th accelerated jumped to +10.4% y/y growth, the best since 2022 and nearly double the 2025 average of +5.8% y/y.
*Redbook sales are same-store sales across a panel of large general-merchandise retailers, such as department stores, discount chains, apparel retailers, drugstores, and warehouse clubs.
October Skip, December Hike Expectations Crystalize
Turning to interest rates and the Fed, I had noted two weeks ago that “the center had spoken”:
we saw two key Fed members come out Tuesday (NY Fed President Williams) and Thursday (Vice-Chair Jefferson) making it clear that the core of the Fed (which is comprised of typically the Chair, Vice-Chair and NY Fed President and also almost certainly includes Powell, so a third of the FOMC) sees “no need for urgency” for a rate hike.
It would be highly unusual for two such high profile Fed members to give such a speech without having cleared it with the Chair. In fact, I think it is not unlikely that they did it in close coordination to try to bring down the market probabilities on an October hike which had exceeded 70%.
Which I noted last week was further confirmed by leading voice Governor Waller
As I mentioned in the Thursday update Waller said “I anticipate additional hikes to support a timelier return of inflation to our 2 percent goal. But there is some flexibility about when those hikes will occur. The hikes do not need to come at consecutive meetings, but they should be in place in an acceptable period of time.” This further confirmed October is off the table, but December is highly likely. See the Thursday report link above for more on Waller’s comments.
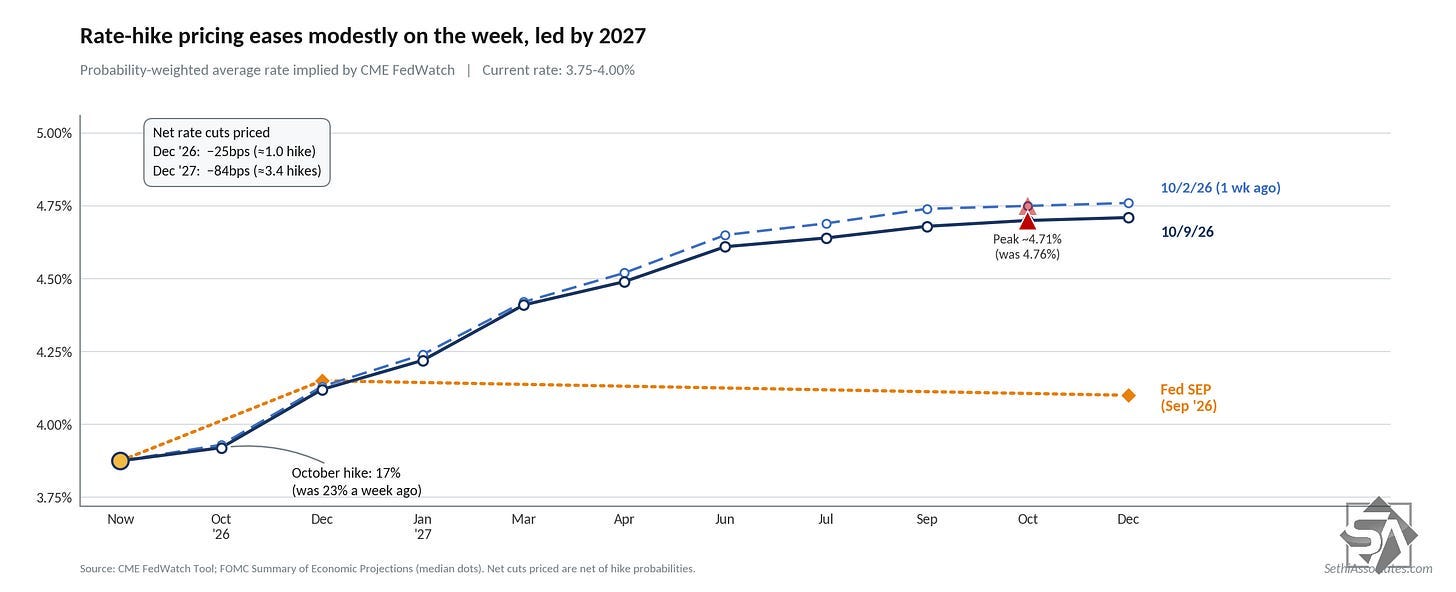
That had seen the chance of an October hike fall to 17%, while leaving an 85% chance of a December hike. For now markets still price in two more hikes in 2027, but that is a lot less certain than I think is pause-and-hike this year.
And then Monday Williams was back, as I wrote, “taking some heat out of 2027 Fed rate hike expectations in an interview with Bloomberg News.”
Williams said if the outlook plays out as he expects, “it may be appropriate to have one more rate hike” this year, and he doesn’t see “any reason to believe that we would need to do more,” though he caveats that saying “we’ll have to see.” Note also though the “may” is still attached to the “one more rate hike”.
On the drivers of inflation: -Tariffs: the effects “mostly are in the rearview mirror.” -Energy: “the bigger story” for the near-term inflation outlook, and now passing through into core, with airfares “the most obvious example.” -AI: “the one that I’m watching the closest right now,” with “abrupt and large” price increases in AI-driven subsectors and “signs of some spillovers into labor costs in construction.”
But he noted underlying inflation measures “have clearly come down,” with the NY Fed’s multivariate trend inflation around 2.3% and the Dallas Fed trimmed mean around the same level over the last six months, and he expects overall inflation to be “near our 2% target for the year as a whole next year.”
On rates: -He thinks the neutral rate has moved up “a quarter to half a percentage point” from 2019, but the longer-run real neutral rate is still “around one percent or a little bit above” so “we’re not that far from neutral.” -On 10-year yields near 5%, he said he doesn’t like the phrase “the market’s doing our work for us,” adding “I also don’t like the word pause.” -Ahead of … CPI, he said he has no specific core print in mind: “I’d prefer low to high.”
“This is not an economy that is overheating overall.”
That saw rate hike expectations for 2027 fall to 50 basis points (two regular-sized hikes) from 61 prior to him speaking.
But I also noted “while I thought 70% was a bit high for pricing an October hike, I similarly think 23% [now 18%] may be a bit low with September CPI and PPI still ahead. Hot prints on those may very well swing the committee,” which was also the view of MS’ Gapen and JPM’s Feroli.
And sure enough we got not one, but three hot inflation prints this week:
Headline consumer prices (CPI) rose 0.649% in September, just rounding down to the 0.6% expected, but still the most since March and core (excluding food and energy) rose 0.33%, the most since April, against the 0.2% expected. Only 11 of 73 economists in Bloomberg’s survey had forecast 0.3%.
And after PPI, import prices rose 1.13% in September, the most since May, above the 1.0% expected and were up 8.10% from a year earlier, the most since July 2022 as fuel prices rebounded and nonfuel import prices hit their highest annual rate since April 2022, with semiconductor prices posting an eighth straight record year-over-year gain.
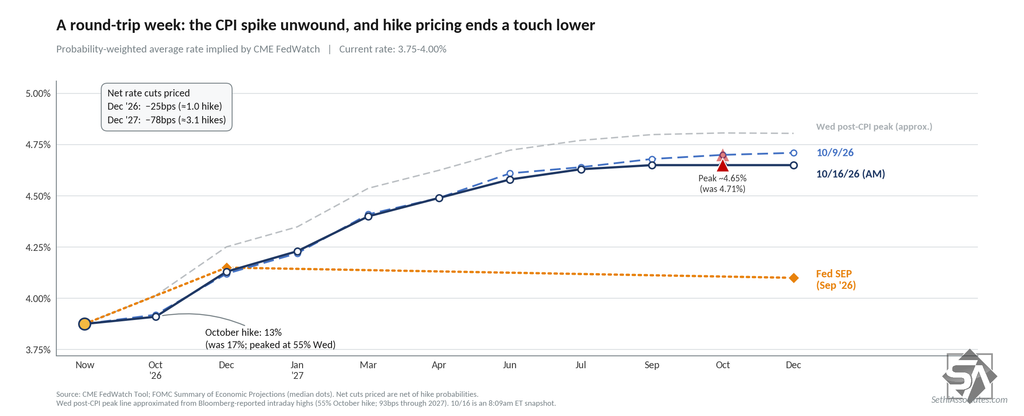
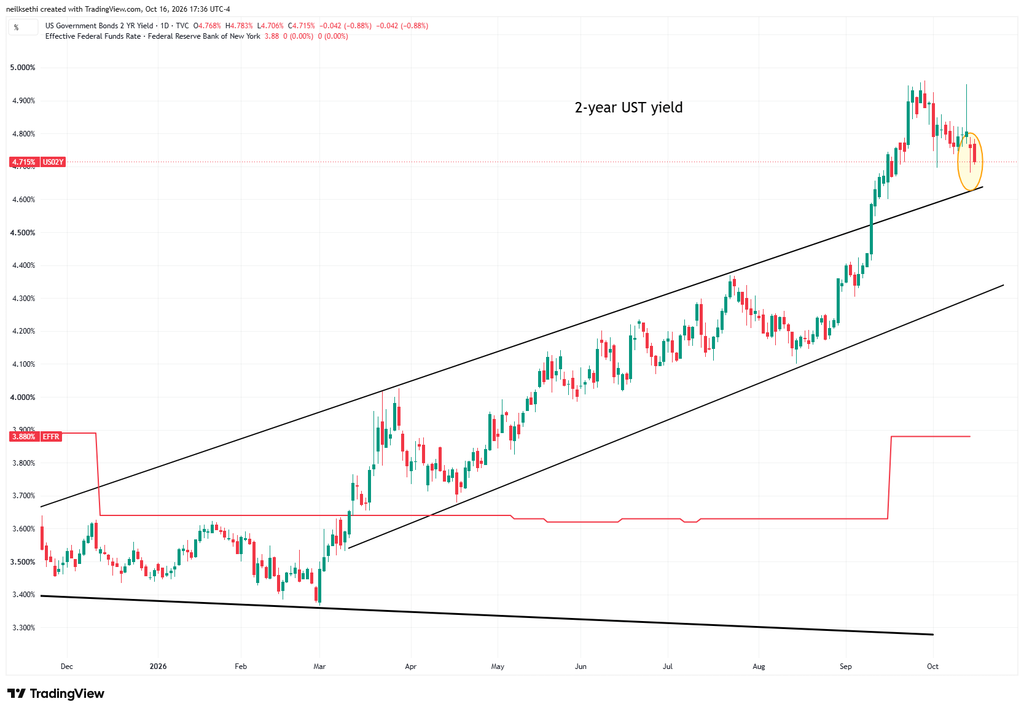
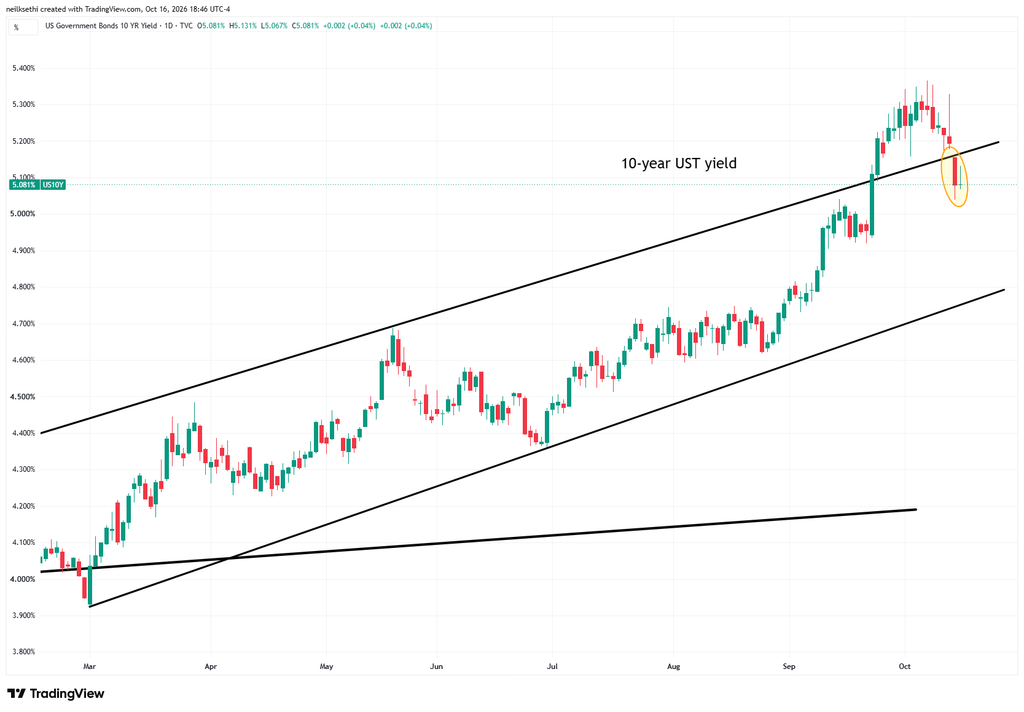
And following CPI we did see the reaction that I thought we’d see with October rate hike pricing jumping over 50% per Bloomberg and 2027 expectations moving back towards 100 basis points of hikes through the end of next year. And along with that Treasury yields surged up double digits across the curve.
But then something nobody (outside of perhaps BofA’s derivatives team as noted below) saw coming happened. It all reversed. I’ve yet to find a conclusive answer, but the best one I’ve heard — and at this point the one that has been accepted by the zeitgeist — is that at the same time, the AI trade was cracking due to fears of the sustainability of the AI buildout. A material slowing in that would have ripple effects both through the wealth channel (equity gains have been fuel for spending given the slowing income gains as I’ve mentioned numerous times) and through the direct impact on AI-related purchases.
[BofA] looked at the action on October 8th (the day of the OpenAI revenue headline from the FT) and said “that event provides one of the cleanest case studies of how the equity market might react in a more prolonged and consequential AI slowdown event.”
Specifically they noted that “despite the broader equity lower, yields higher regime that the market has experienced for many months, risks of an AI slowdown elicited lower yields along with lower equities on 8-Oct nearly immediately, with the move holding until the end of the day (Exhibit 16). Such a reaction to AI-specific worries is similar to the DeepSeek event in Jan-25, which also saw a sharp Nasdaq decline with rates falling.”
We also saw this in the unwinding of the dot-com bubble in 2000 they note, as “an AI slowdown would hit both growth and inflation (less capex, less power and resource consumption), which pushes yields lower still. In other words, the bond market would finally start behaving like a hedge again, right when it’s needed.” (ZeroHedge quote)
And of course that reversal also came at a time when it seemed we were seeing the start of an unwind in the short bonds trade, so once it got started, it would make sense that traders might look to lock in some profits which likely added to the quick drop.
But whatever the reason as noted that brought October hike expectations back to under 30%, which left just Chair Warsh on Thursday night to change those expectations before entering the Fed’s blackout window. As I mentioned in my preview was likely, Warsh declined to do so which firmed expectations for an October hold:
Consistent with last night’s update, Chair Warsh provided little direction on monetary policy during his fireside chat with IMF Managing Director Kristalina Georgieva this morning (Bangkok time) which crystalized expectations for a hold at the FOMC meeting at the end of the month.
“We made very clear that we would deliver price stability, and we removed a dose of accommodation about a month ago,” Warsh said. “I don’t prejudge meetings. I don’t believe in saying now what I might do at the meetings that we have in the balance of this year.”
The chance of an October hike fell in half to ~13% [ending Friday at 17%] from ~30% before he spoke with a hike by December though holding at near 90%. 2027 expectations were little changed with another 53 basis points of hikes expected in 2027 assuming one more hike this year.
I don’t believe the Fed has ever hiked when probabilities for a hike were that low (13% [or 17%]).
So, as mentioned, if nothing changes we’re either getting a hold at the October meeting or what will be one of the biggest (if not the biggest) hawkish surprises we’ve seen from the Fed.
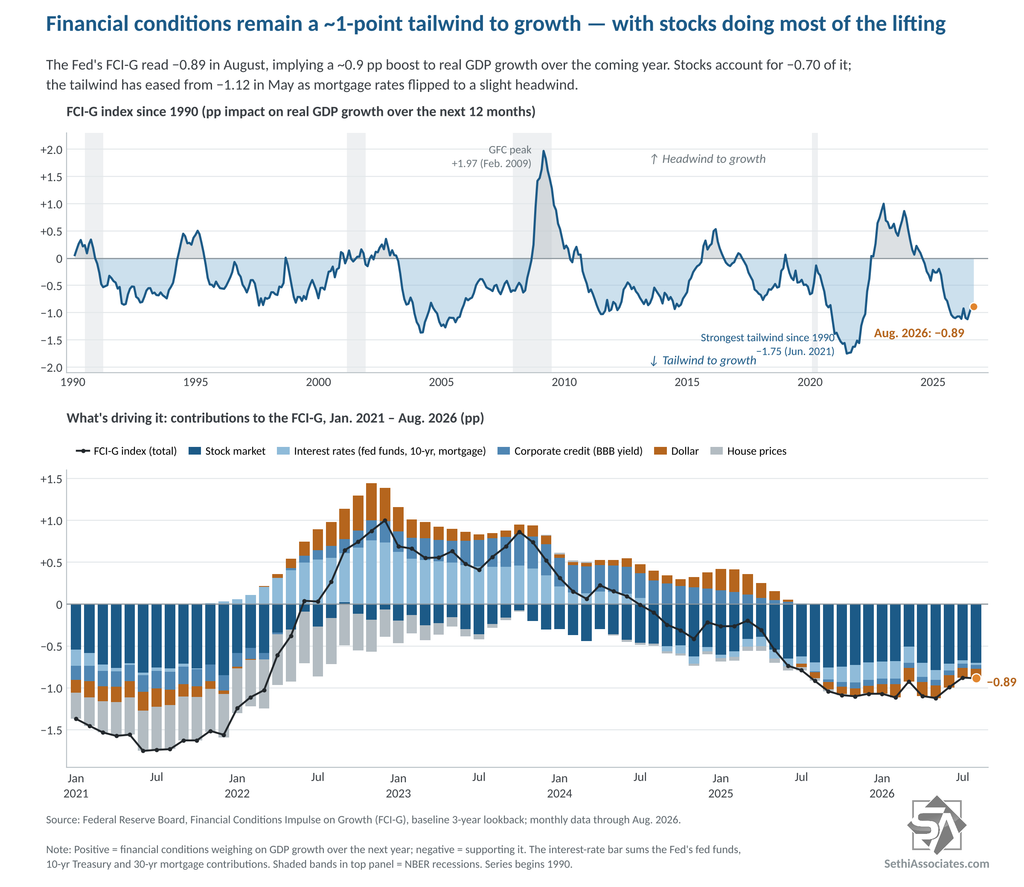
But looking further out, there has been much discussion about how restrictive the current levels of rates are. Fed Chair Warsh described the September rate hike as “removing a dose of accommodation”. Judging from the Fed’s own financial conditions index quite a bit more may be needed, although as BMO noted this weekend most of the current accommodation is being supplied by equity prices making this a “more fragile” situation than 2021 when the accommodation was more broad-based.
At its June 2021 extreme, the index pointed to a 1.75-point boost to growth, but stocks supplied less than half of it (−0.82). Rising house prices (−0.48), the dollar (−0.22) and low corporate borrowing costs (−0.20) did much of the rest. Today, stocks account for −0.70 of the −0.89 total, or nearly 80%. Everything outside equities adds up to less than two-tenths of a point. Interest rates have already stopped helping. Their combined contribution has shrunk from −0.12 in May to roughly zero, and mortgage rates are now a slight drag. The August reading also predates the September hike.
This is why BMO believes many Fed members want to go slow on tightening. Aggressive tightening which results in a sustained equity market downturn would turn financial conditions from accommodative to restrictive quickly.
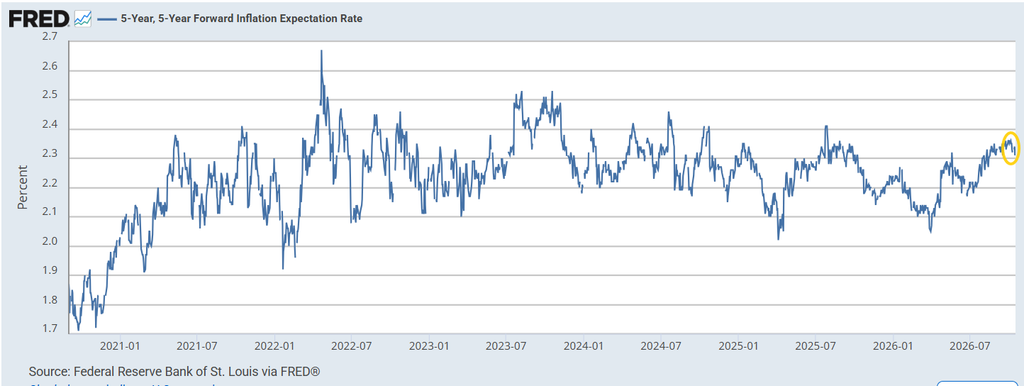
Taking a quick look at inflation expectations, those continue to remain well below their post-pandemic highs with the Fed favorite 5-year, 5-year forward rate (expected inflation starting in 5 years over the following 5 years) Friday at 2.33%. While it is near the highest in a year it’s well below the peaks in 2022 and 2023.
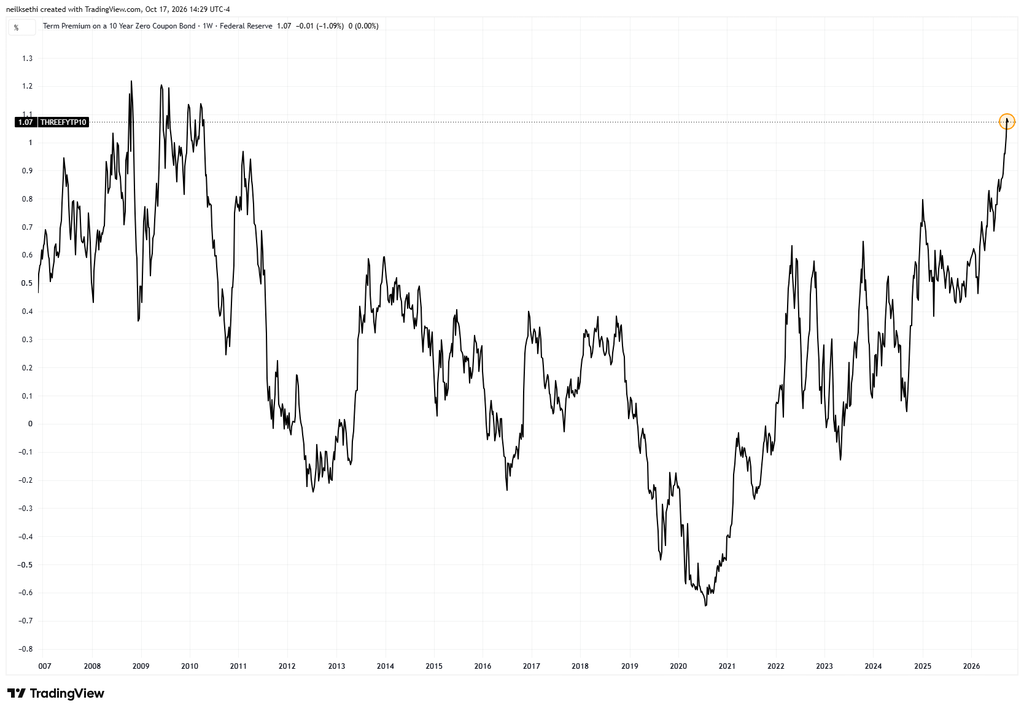
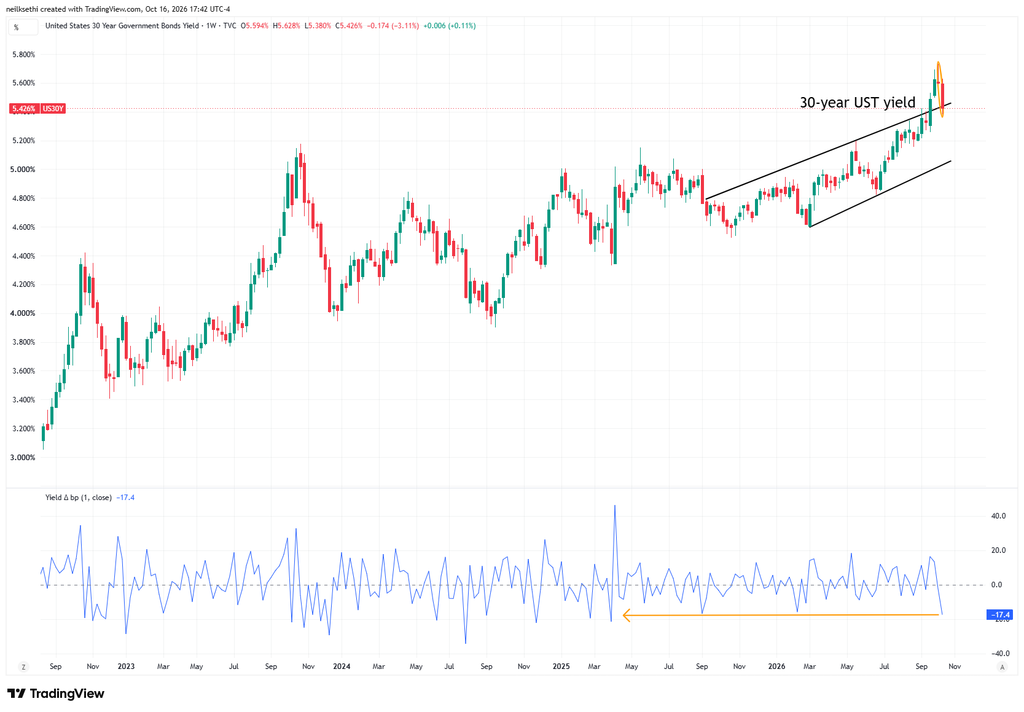
And with the drop in nominal yields last week as discussed in the Friday update, we saw term premium (extra yield investors demand to hold a longer-term bond instead of continually rolling over short-term bonds for the same period) — which has been the main source of pressure on the long-end — fall back week-over-week for the first time since July according to the Kim-Wright model, though only modestly from the highest since March 2010. That fits the AI-driven growth explanation for the rise in yields earlier.
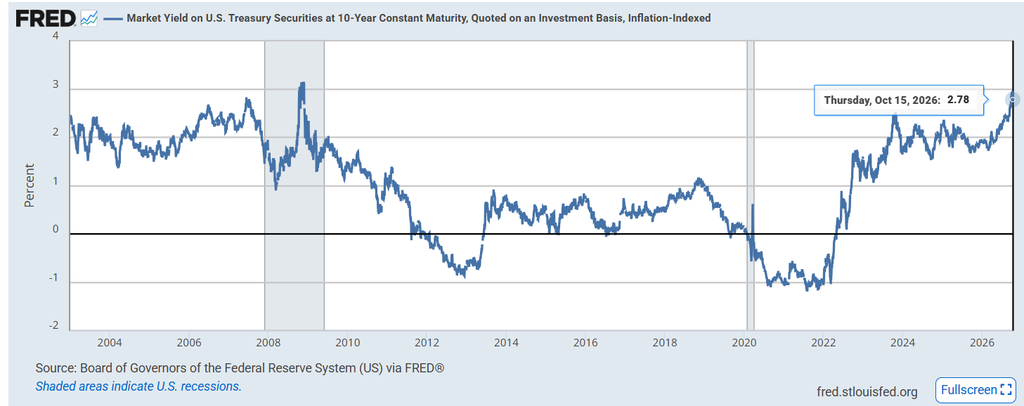
Which in turn saw the 10-year real rate (via the hypothetical constant-maturity, 10-year Treasury Inflation-Protected Security) ease back to 2.78% from just off its post-2008 high of 2.88% the prior week.
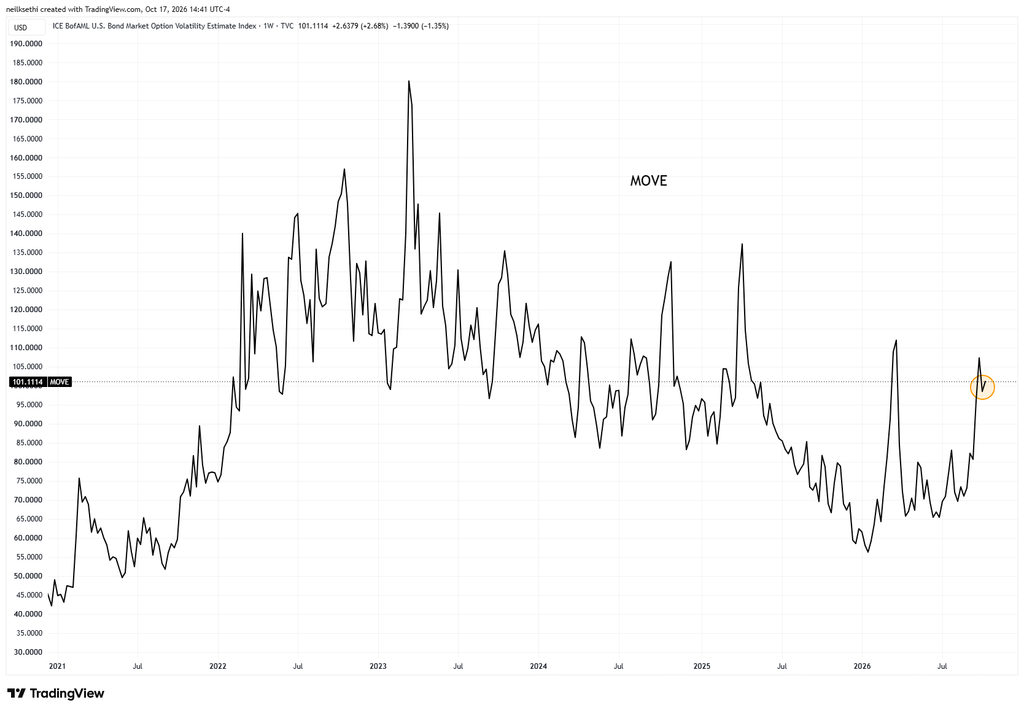
But bond volatility as measured by the MOVE index (expected 30-day volatility for Treasuries) edged higher after falling back the prior week from the highest since March.
Overall, on yields, as I said three weeks ago, we remain above my new ranges established at the start of August for the 2-year and 10-year: “I still think that 5% on the 10-year and 5.75% on the 30-year represent areas where we will see very strong buying. On the 2-year I think a lot depends on whether the Fed hikes. If they do, there’s potentially another ~30 basis points to the upside (~4.75%). If they don’t, I think we’re going lower from here.”
I said last week “I still for now think we’ll end the year back in those ranges,” and the 2-year and 10-year are getting closer while the 30-year remains under.
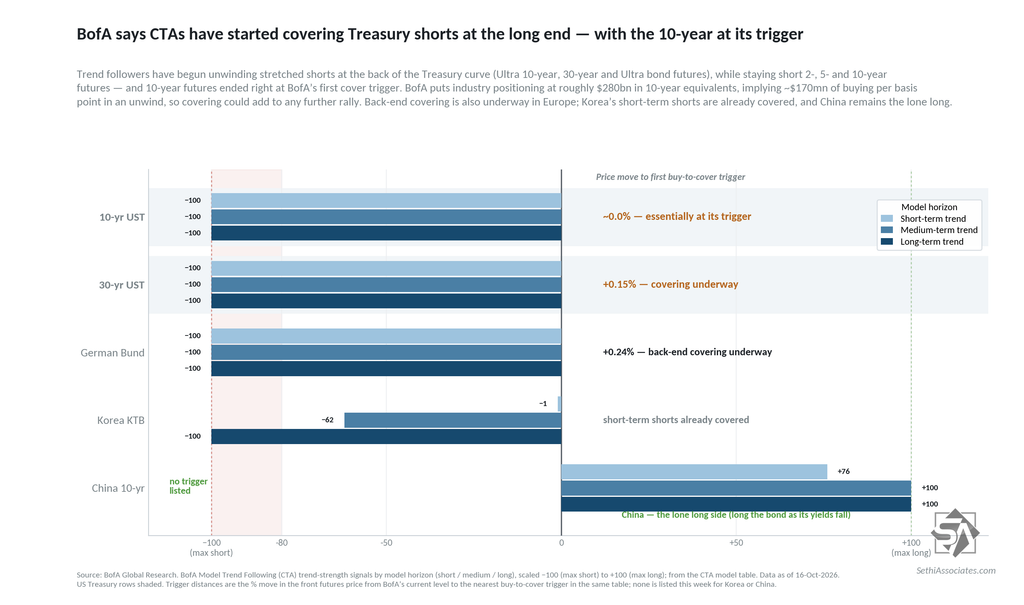
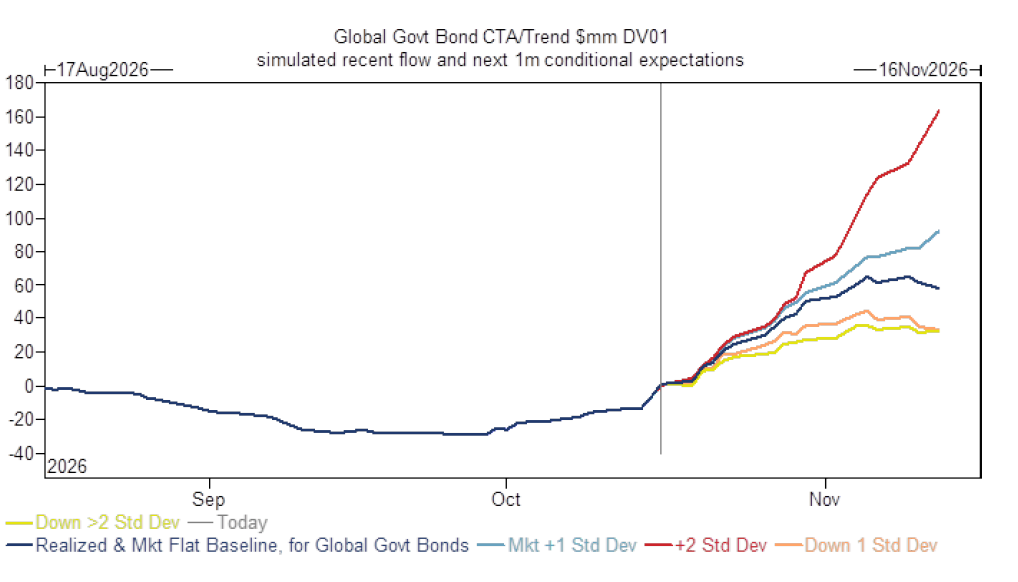
And I mentioned earlier that we had seen some bond shorts covering this week, and BofA says CTAs did begin covering at the very long end with shorter maturities “just off our first trigger levels”:
CTAs have begun covering stretched US Treasury futures shorts at the back end, with unwinds underway in UXY, US and WN contracts. However, trend followers remain short TU, FV and TY, leaving substantial covering risk if the rally extends. In fact, TU and TY futures ended Friday near just off our first trigger levels. Industry positioning may have reached about $280bn in 10yr equivalents, implying approximately $170mn of buying per basis point during an unwind. Equity market weakness and the initial reduction in sCTA shorts likely reinforced the rally.
FV: 5-Year US Treasury Note Futures TU: 2-Year US Treasury Note Futures TY: 10-Year US Treasury Note Futures US: US Long Bond Futures UXY: Ultra 10-Year US Treasury Note Futures WN: CME Ultra Long Term U.S. Treasury Bond Future
Goldman also sees some CTA covering at the long end and expects more with shorts at a “meaningful amount” (this is repeated in the positioning section):
We expect CTA/trend followers to be buyers of some govt bond futures in the baseline scenario.
Coming into Friday, while signals remain more negative overall across the suite of global products, we have seen some flips in short trend, in Eurex, Japan and US longer duration futures. We expect the community is short a meaningful $164mm/bp DV01 globally, and has covered or profit taken on $12mm/bp in the last 1 week.
For the next one week, in the baseline scenario we expect a further $20mm of short covering, and $64m in the next 1 month cumulatively. This would leave the position still short, though not as sizably as before.
The short and medium-term trend price level in the TY 10-Yr future is 105.62 and 107.73 currently, corresponding to roughly 5% and 4.7% in OTR 10-Yr rate terms.
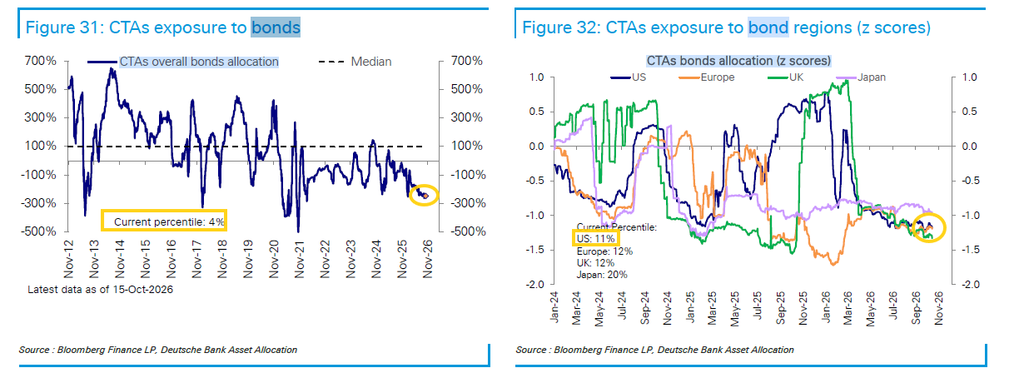
DB continues to say CTA “bond shorts remain extreme”with US net positioning falling to the 11th percentile to 2012 from the 14th the prior week. Globally they’re at the 4th percentile.
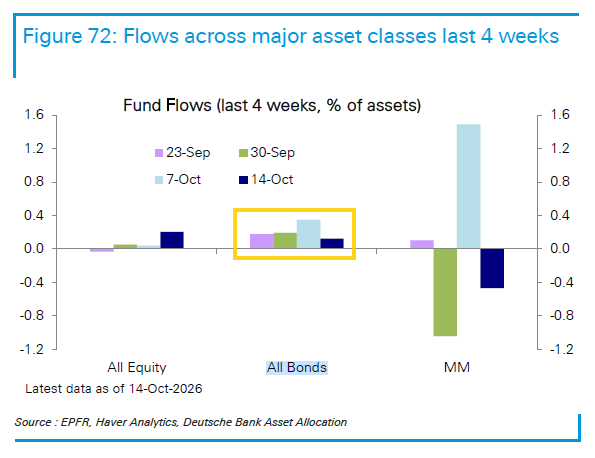
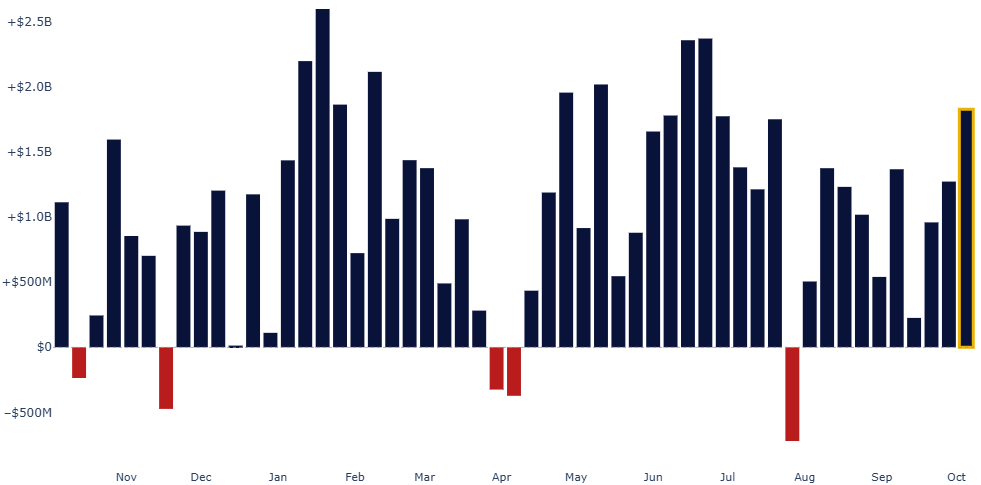
And we continue to see evidence of buying although DB notes bond inflows decelerated to $11.8B from $33.8B the prior week (and money markets gave back $53.1B of last week’s “massive” $166.4B inflow). Still it was a 4th straight week of inflows:
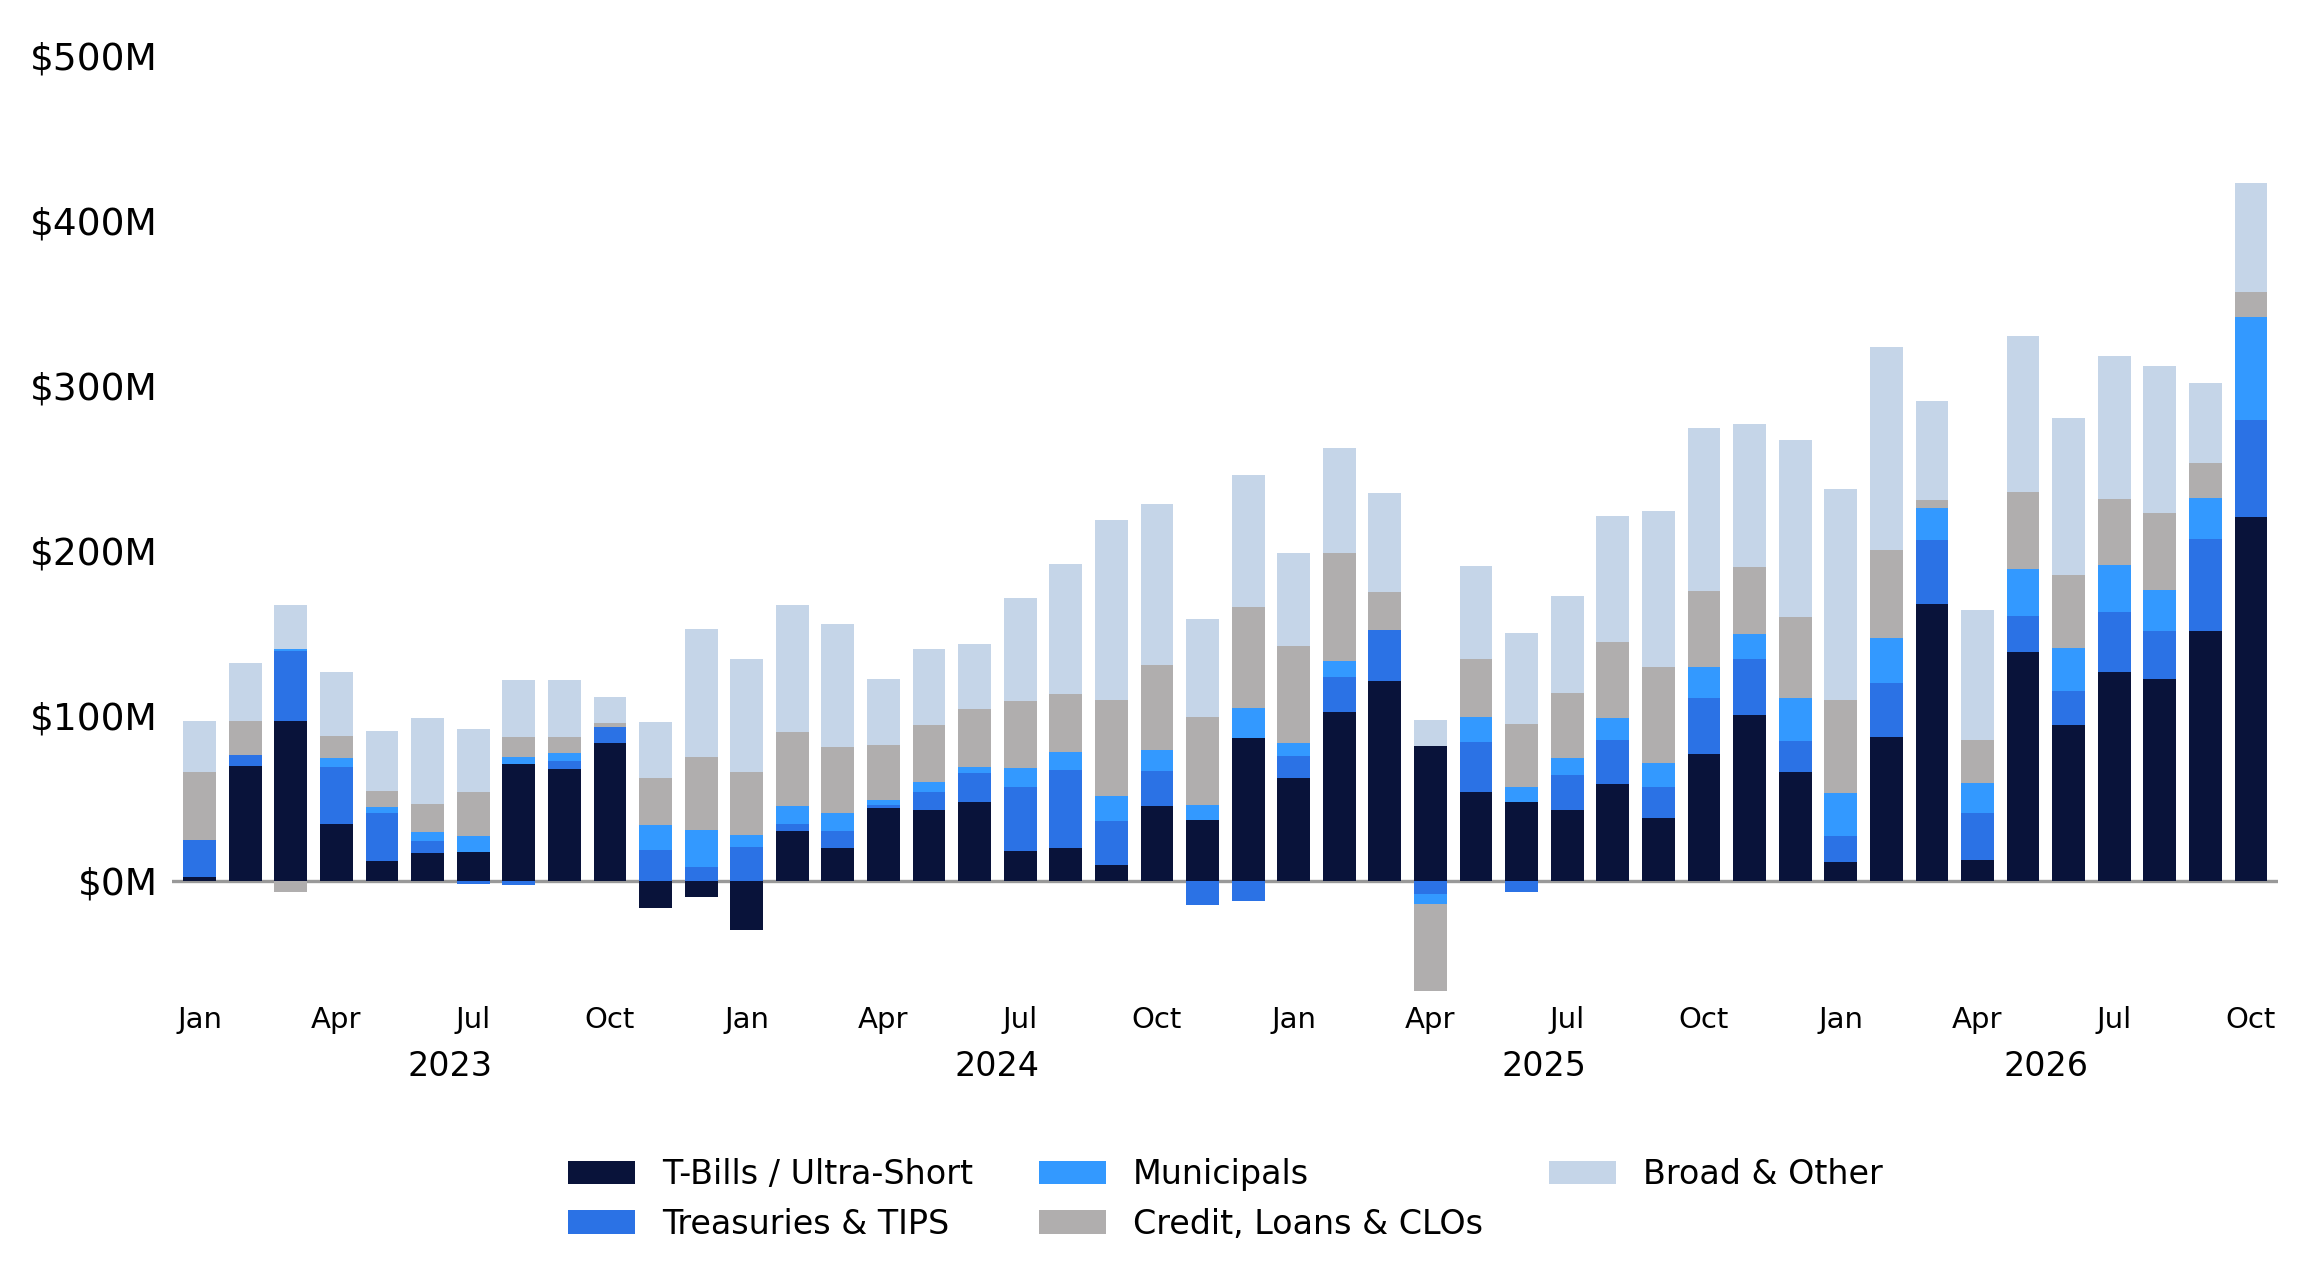
And Citadel’s Scott Rubner says “We are also seeing record-paced demand for fixed-income ETFs. Retail has net bought nearly $3 billion across bond ETFs through the first seven sessions of October, averaging $422 million per day, 28% above the previous monthly record pace. The buying has been concentrated in T-bills and ultra-short duration (2.3x the trailing 1Y average), municipal bonds (2.6x) and Treasuries (1.9x), while credit, loan and CLO ETFs are seeing just 0.4x their usual demand. If the current pace holds, October would be the largest month of retail fixed-income ETF buying in our dataset since 2017.”
So as I’ve said for the past month “we remain in a precarious place for bond shorts. There will be that huge short covering rally that will see yields plummet, at least briefly.” It seems with the declines last week that moment is closer but hasn’t quite triggered yet.
Earnings Growth Robust But Past the Peak
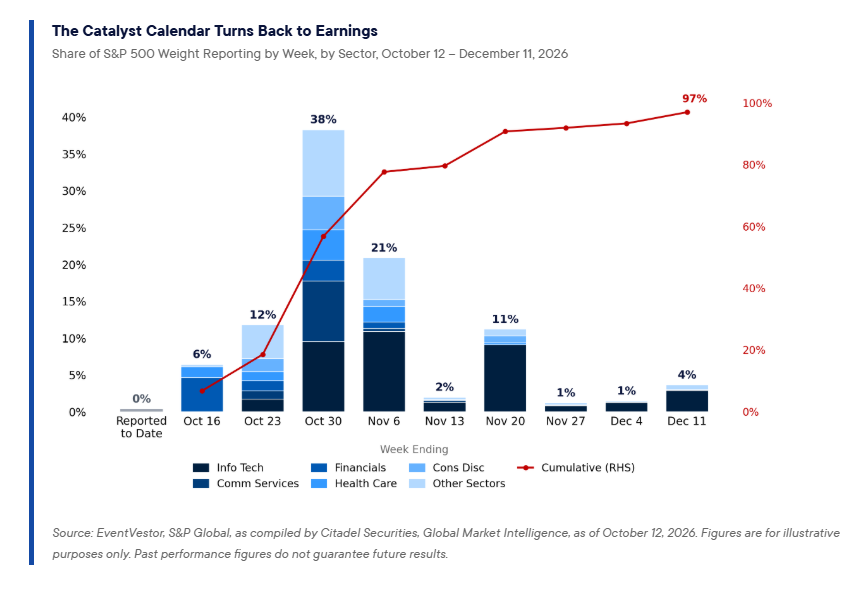
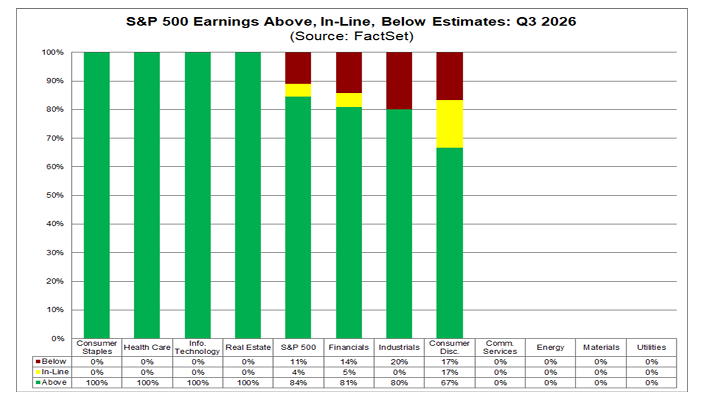
Looking at Q3 earnings, we remain very early in the season with just 9% of the S&P 500 reporting by earnings weight, but beats have been high with 84% beating, slightly below the 86% beat rate in Q2 (which was the best since Q2 ‘21) and vs the 5yr average of 78% and the 10yr average of 76%.
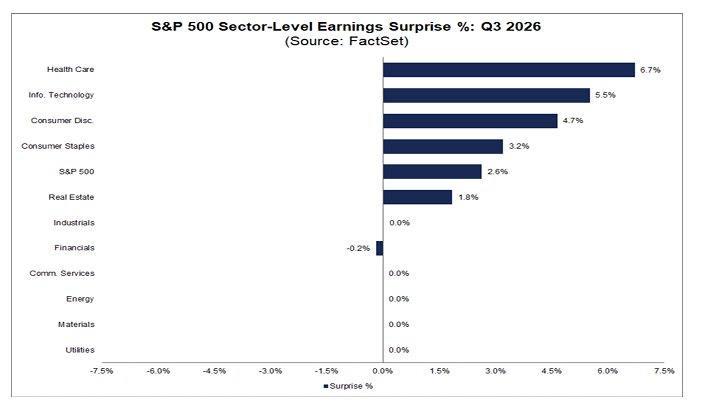
The magnitude of the beats though has been just +2.6%, a tenth of the +26.5% in Q2, which though was the best since FactSet began tracking the metric in 2008. But remember Q2 started out modest before jumping higher when the Tech earnings rolled in. That compares with the 10-year average of 7.4% and the five-year average of 7.0%.
In that regard, Goldman notes
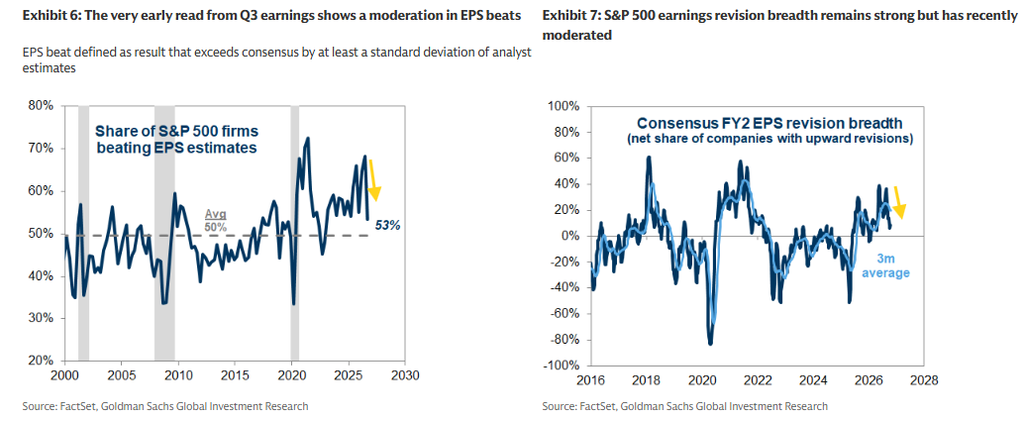
The very early read from the Q3 earnings reporting season supports the view that the rates of earnings growth and estimate upgrades have peaked. With 10% of S&P 500 companies having reported results, 53% of firms have beaten consensus EPS by more than a standard deviation of analyst estimates.
This remains above the 25-year average of 50% but a substantial step down from the average rate of 64% during the past four quarters. Similarly, while upgrades to analyst earnings estimates continue to outnumber downgrades, revision breadth has declined during the last several weeks alongside the underperformance of cyclical stocks.
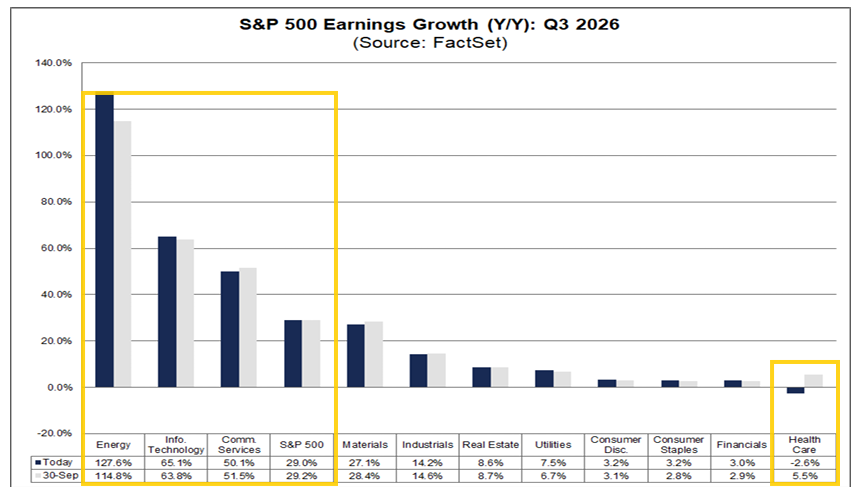
And that has seen Q3 expected earnings ease back six tenths to +29.0%. Energy though extended to +127.6% y/y growth (up from +79.3% at the start of the quarter — July 1st), followed by Tech +65.1% and Comm Services +50.1%.
And now we have one sector expected to have negative y/y growth in Health Care -2.6% (from +5.5% from the start of the quarter).
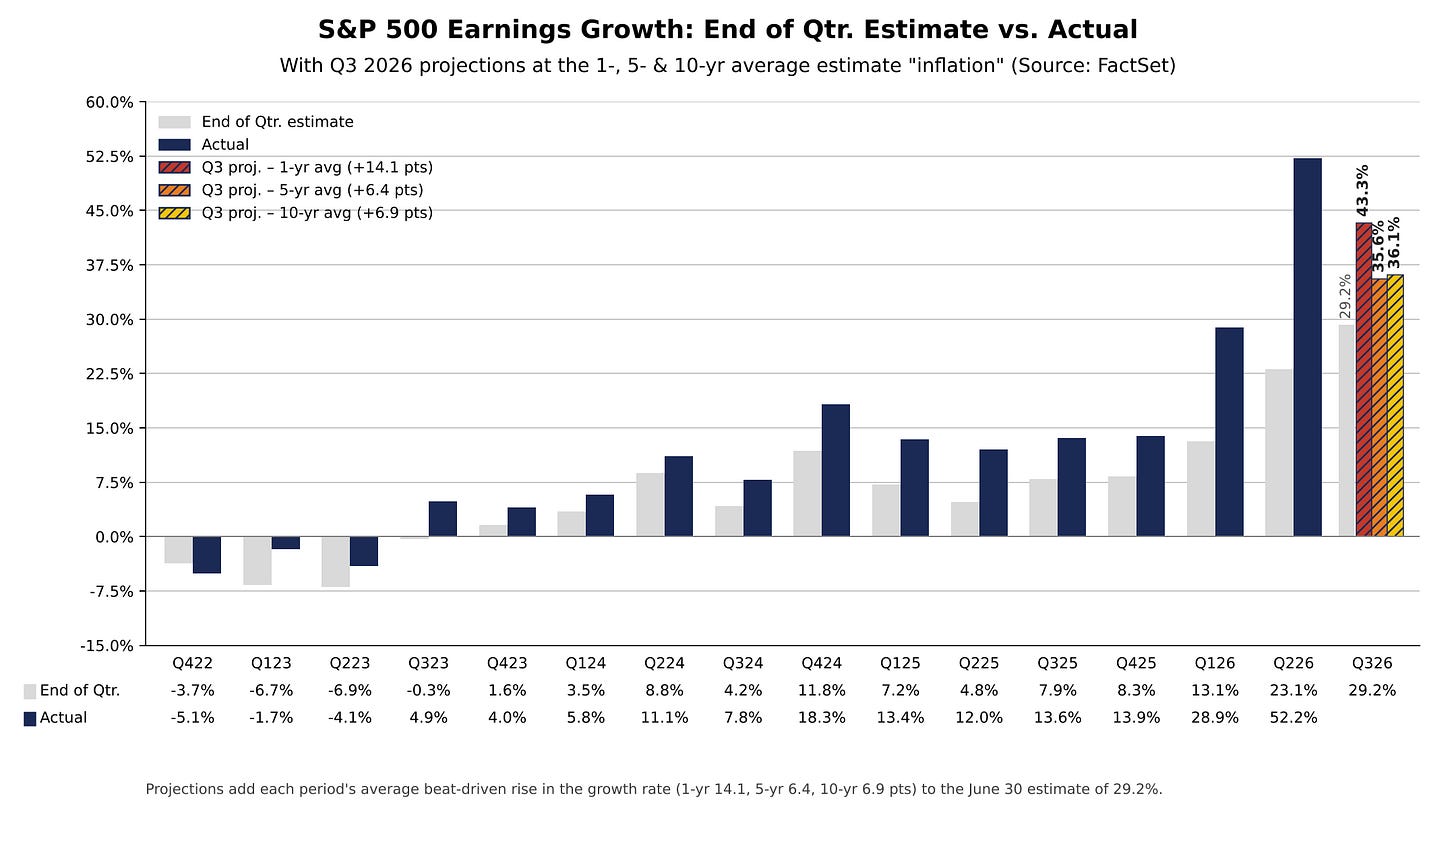
And just a reminder on the typical “earnings inflation” we see each earnings season (numbers are from the start of earnings season which is where the “inflation” metrics are measured to):
As those who followed me over from Neil’s Newsletter know ahead of each earnings season I discuss how if past is any guide the earnings growth for the coming earnings season can be expected to come in well above expectations at the start of the season.
According to Factset data, over the past 1, 5 & 10 yrs S&P 500 companies have beaten earnings expectations by 13.8%(!), 7.5% & 8.0% respectively, resulting in “inflation” to the earnings estimates on average over the quarter by 14.1%(!), 6.4% & 6.9% respectively over where they stood as of the start of the quarter (in this case June 30 which was 29.2%).
Using those averages would mean Q3 earnings could come in at +43.3%(!), 35.6%, or 36.1% respectively.
Actual earnings by the end of the quarter have failed to surpass expectations at the start of the quarter in only 3 of the past 43 quarters (Q1 ‘20, Q3 ‘22, and Q4 ‘22 are the only exceptions according to Factset).
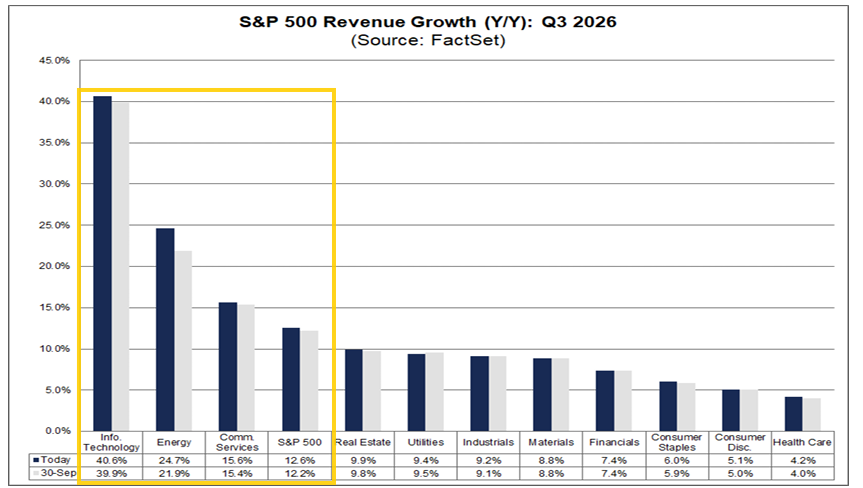
Q3 revenue growth expectations though rose to +12.6%, on track for a third consecutive quarter of double-digit revenue growth after +15.5% in Q2 which was the best since Q4 2021 (16.1%).
Expectations are led by Tech (+40.6%), Energy (+24.7%), and Communications (+15.6%).
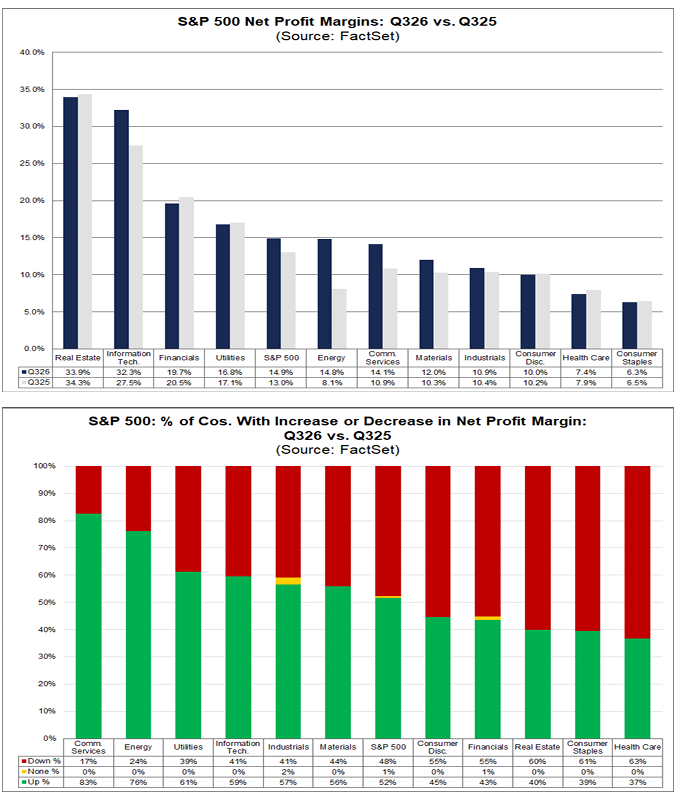
Which continues to boost profit margins now estimated by Factset to come in at a record 14.9%, up from 13.0% a year ago, in large part due to Tech’s 32.3% margin (much of it due to semiconductors) up from 27.5% a year ago.
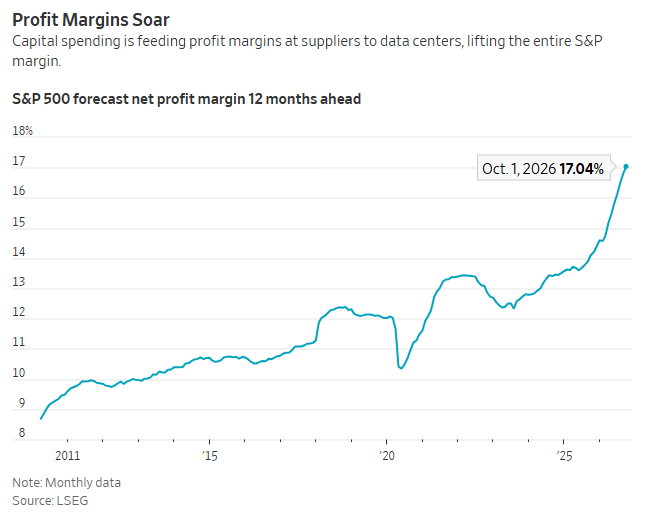
And margins are expected to keep climbing from here, with the 12-month forward profit margin forecast from LSEG for the S&P 500 now at 17%. It was 12% January 2020.
Wall Street Journal
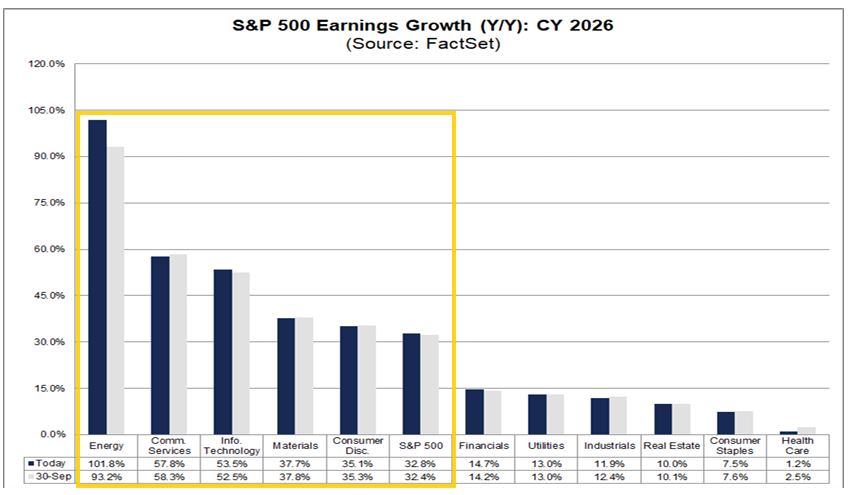
Boosted by those record margins, 2026 SPX earnings growth expectations also edged higher to +32.8%, up from +24.0% on June 30th, +17.1% on March 31st, and over double the +14.8% at the start of the year.
As in 2025, Tech is a leader with y/y earnings growth of +53.5% (up from +28.6% at the start of the year) but Energy is expected to exceed that (on a percentage basis) at +101.8% (up from +6.4% at the start of the year) along with Communications +57.8%. Those sectors along with Materials (+37.7%) and Consumer Discretionary (+35.1%) represent the five sectors expected to come in above the SPX average.
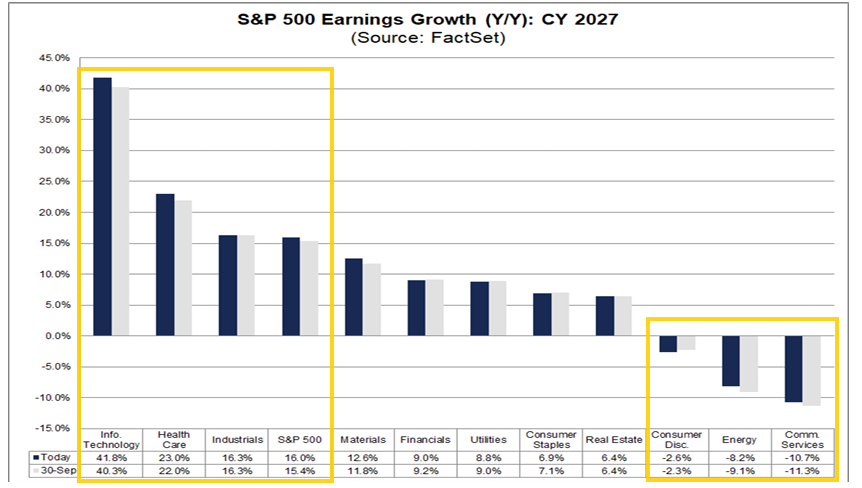
And 2027 earnings are expected to be up another +16.0% on top of the elevated 2026 results, which is down though from +17.5% as of June 30th as analysts are not carrying over all (but still most of) the boosts in 2026 earnings to next year. Still it’s a double digit advance on top of what is expected to be a 30%+ gain in 2026. That would also represent a fourth straight year of double-digit earnings growth for the S&P 500, something we’ve rarely seen.
2027 is expected to be led again by Tech (+41.6%, up from 24.6% at the start of the second quarter on April 1st, despite the huge increase in 2026 estimates since then) followed by Health Care (+23.0%) which is expected to see a big turnaround after lagging in 2026. Industrials (+16.3%) is also above the SPX average.
With hyperscaler investment gains (in Anthropic, OpenAI, etc.) expected to slow, the sectors that have seen the biggest boosts from that are now expected to see negative y/y growth (Comm Services, -10.7% from +8.2% at the start of the third quarter, and Consumer Discretionary, -2.6% from +13.9%) along with Energy (-8.2%) as petroleum prices are expected to soften.
Here’s Goldman’s thoughts from this weekend:
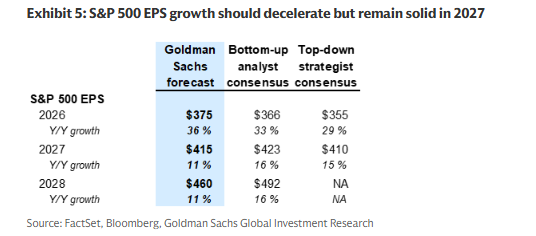
Our baseline forecasts point to decelerating – but still solid – growth into 2027. We expect S&P 500 EPS growth of 36% in 2026 will slow to 11% in 2027. Adjusting for non-recurring accounting distortions to 2026 earnings, our forecast for earnings growth in 2027 would register 18%.
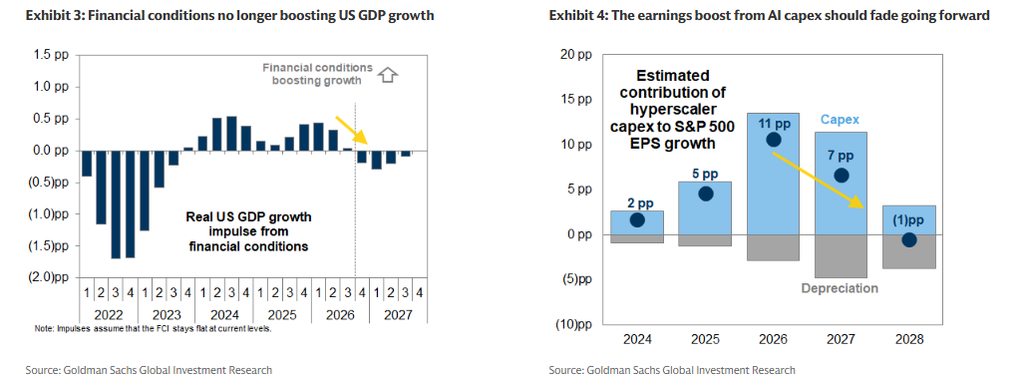
Our forecasts assume a modest deceleration in real US economic growth in coming quarters, in part reflecting the drag from higher oil prices and interest rates. In addition, we estimate that AI capex is currently contributing about half of S&P 500 EPS growth, and that impulse should diminish into 2027 as capex growth slows and depreciation expenses build.
Our 2027 S&P 500 EPS forecast is similar to the current bottom-up consensus estimate, implying that the recent trend of large upward revisions to analyst estimates is likely behind us. The distribution of potential earnings outcomes is wider in 2028, by which time we think the boost to growth from AI investment spending will have completely faded. Our base case is for another year of healthy earnings growth in 2028, although our estimates are 7% below the bottom-up consensus forecast.
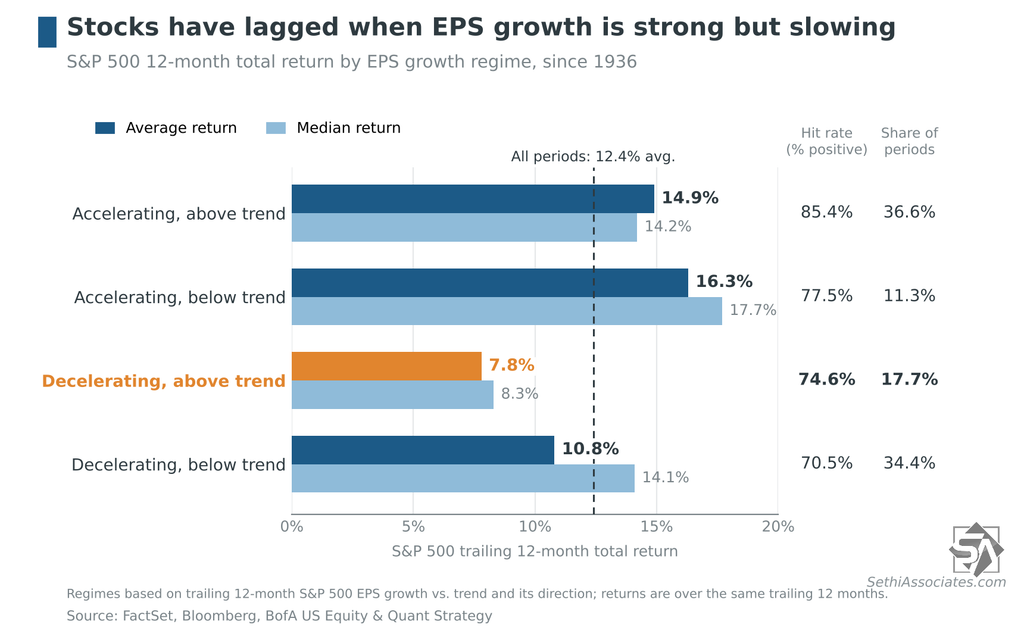
In terms of S&P 500 readthrough, note that BofA’s Subramanian has found that S&P 500 returns have been weakest when earnings growth is above trend but slowing. Trailing 12-month returns in that regime averaged 7.8%, versus 12.4% across all periods since 1936. Consensus sees S&P 500 EPS growth slowing to 16% in 2027 from over 30% this year.
But Goldman has a different take:
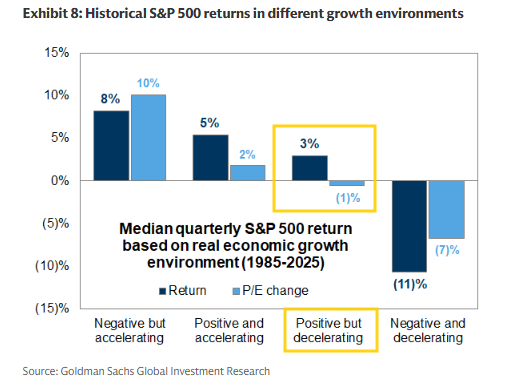
Even with growth slowing, equities should continue to rise as long as earnings continue to grow. For the S&P 500, positive but decelerating growth has historically been associated with positive but moderating returns. These patterns are similar whether looking at economic or earnings growth. In addition, returns in decelerating growth environments have historically been driven by earnings growth rather than valuation expansion.
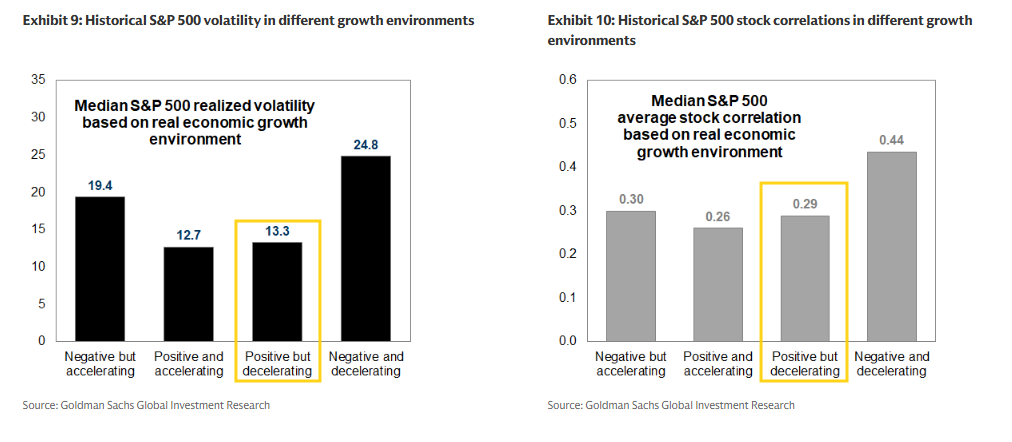
Equity market volatility is usually more dependent on the direction of economic and earnings growth than on changes in the growth rate. Despite the recent rise in intra-market volatility, correlations across S&P 500 stocks and index volatility have remained near record lows (Exhibit 33). Historically, equity market volatility and average stock correlations have risen only slightly as growth decelerated, with large increases typically occurring when growth turned negative.
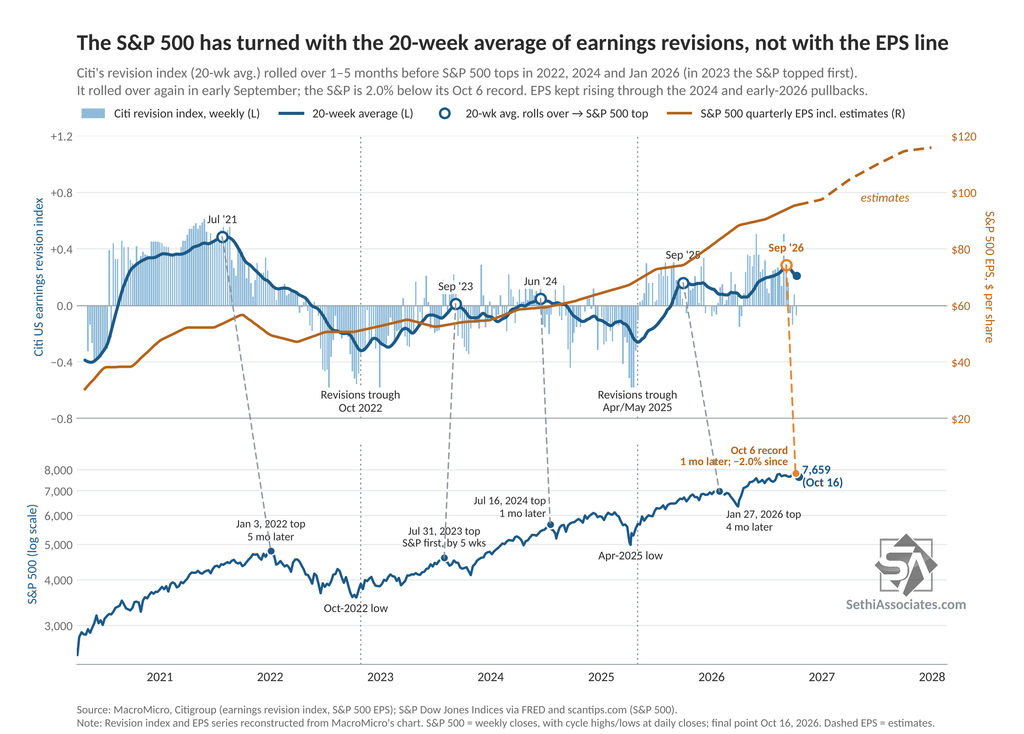
And we again this week (third week in four) saw negative earnings revisions according to Citigroup. I said last week “I’m not too concerned about a few weeks of that,” but “what I’m watching more closely is the 20-week moving averagewhich does lead the S&P 500 if we see a prolonged softening.” So that might be another factor in the weakness in the SPX of late. Still too early to tell how much further the softening has to go.
FWIW Citadel’s Scott Rubner said this week: “Over the past four quarters, S&P 500 companies have raised guidance nearly three times for every cut. Outside the 2009-2010 and 2020-2021 recoveries, this is the most supportive stretch of corporate guidance in 20 years of data.“
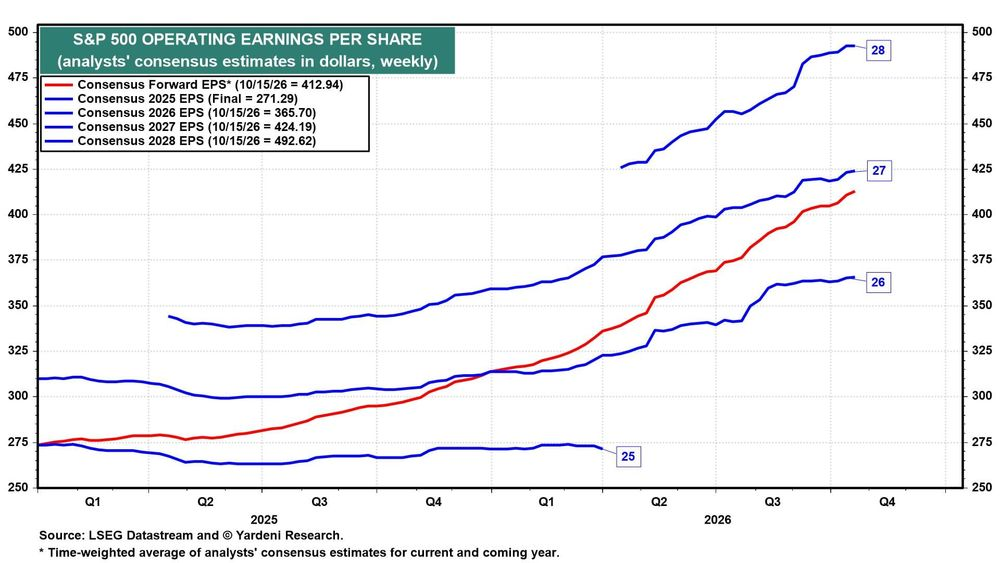
The big banks reported mixed but solid overall Q3 earnings last week. On average, they met banking industry analysts’ expectations. Last week, the consensus EPS for all analysts covering S&P 500 companies edged up to $365.70 this year, $424.19 next year, and $492.62 in 2028 (chart).
Those are extremely bullish expectations considering that we are still forecasting $500 in 2030! If the analysts are right, the S&P 500 could rise to 10,000 by the end of next year, assuming a forward P/E of 20.0-21.0. For now, we are sticking with 10,000 by the end of the Roaring 2020s, i.e., at the end of 2029.
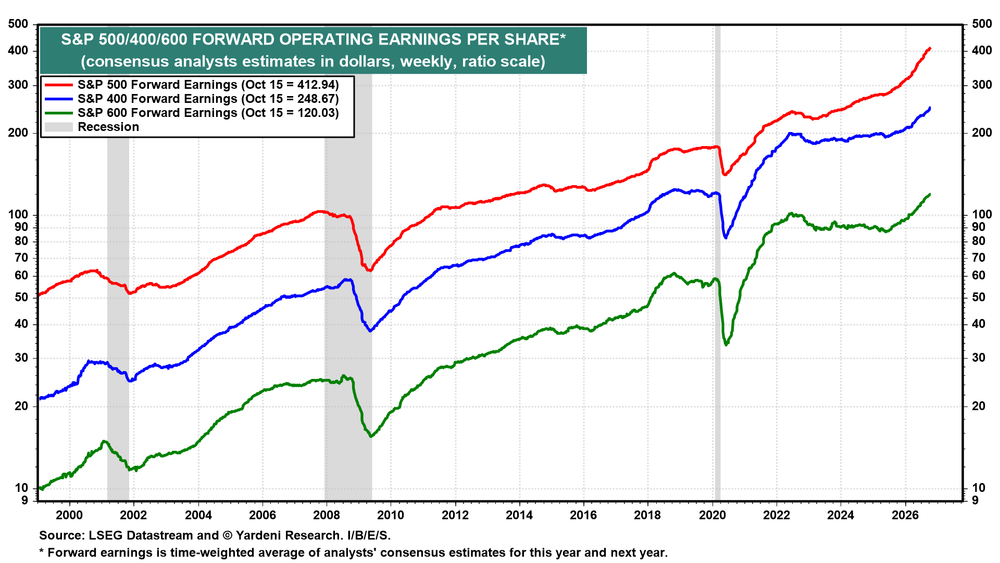
And he again notes the strong earnings extend beyond the largest stocks: “The S&P 500, S&P 400, and S&P 600 continued to rise to record highs last week (chart).”
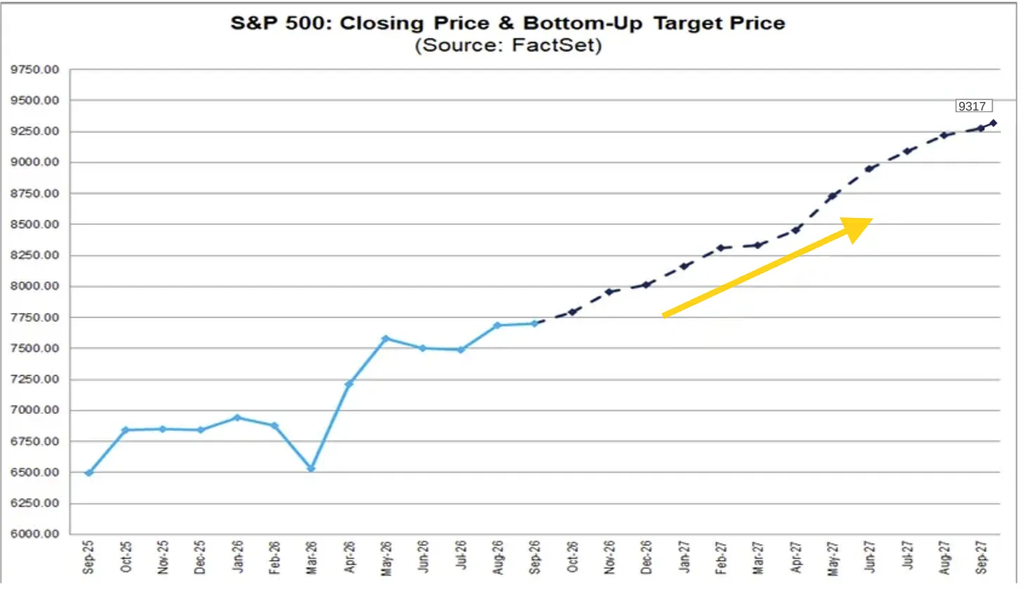
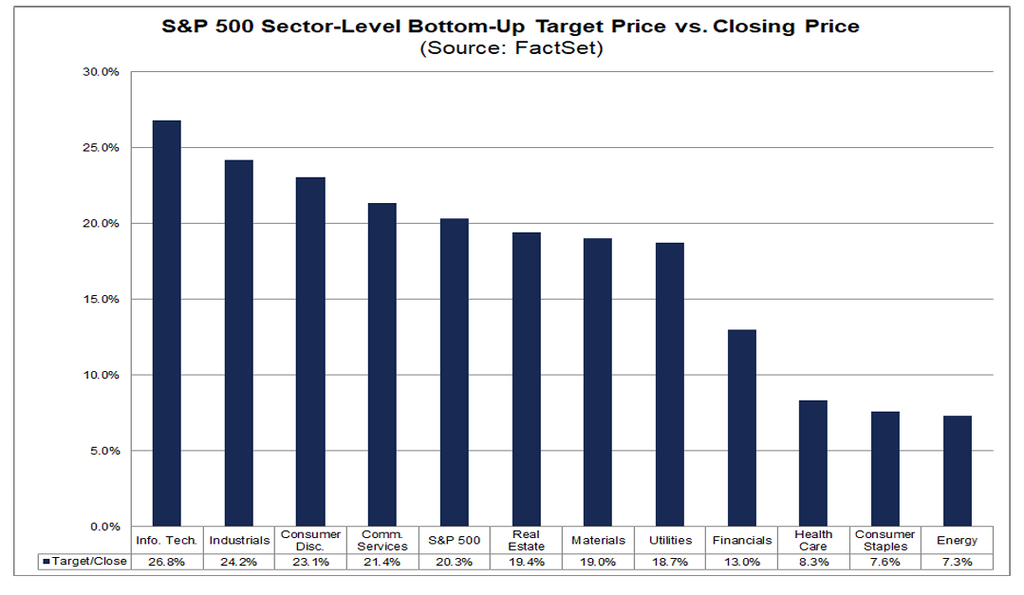
Analysts meanwhile collectively continue to think that the S&P 500 has a lot of upside with FactSet’s compilation of analyst bottom-up SPX 12-month price targets up to 9,317 (+26pts w/w, ~1,020 pts since March 31st, ~+2,195 pts since Thanksgiving, and ~+3,145 pts since July 1, 2025). That would be +20.3% from Thursday’s close.
Info. Tech. (+26.8%, up from +21.4% the prior week) has jumped past Industrials (+24.2%) as the sector expected to see the largest 12-month price increase, followed by Consumer Discretionary (+23.1%). On the other side, Energy (+7.3%), Consumer Staples (+7.6%) and Health Care (+8.3%, down from +13.9%) now all have single-digit expected upside.
As a reminder we started the year with a 12-month bottom-up price target of 8,000 and according to FactSet the last 20 yrs (through 2024) analysts have been on avg +5.9% too high from where they start the year, but they have underestimated it five of the past six years (including 2025 when they saw 6,755 at the start of the year and we ended at 6,845). Currently we’re about 3.3% away.
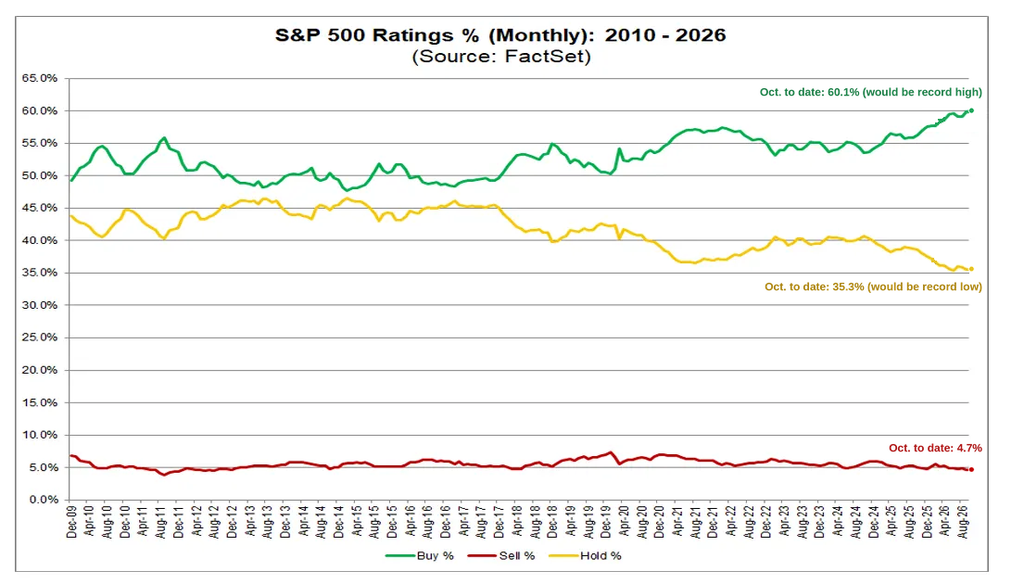
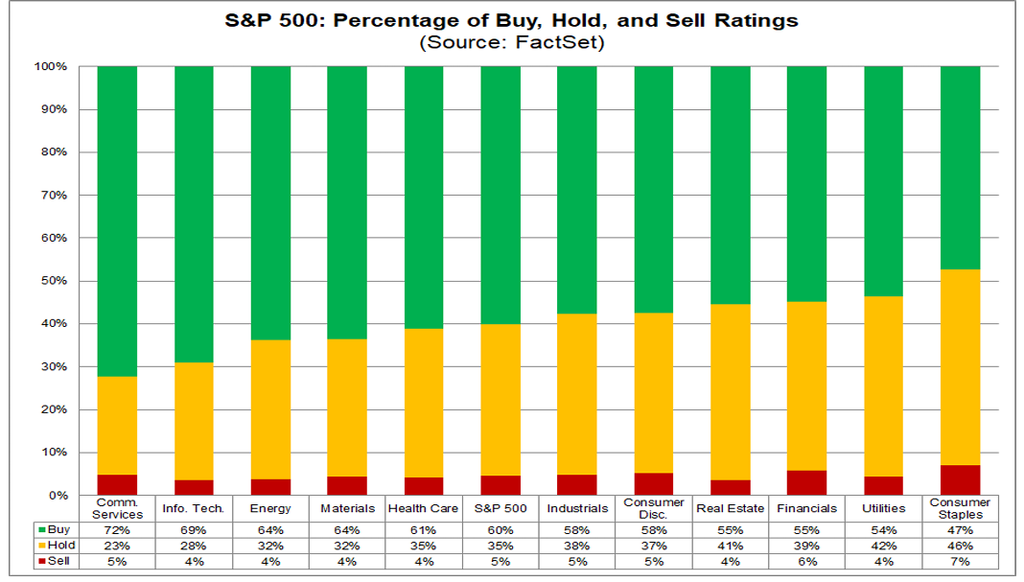
In terms of analyst ratings, buy and hold ratings continue to dominate with buy ratings unchanged w/w at 60.1%. That would be a new month-end record high (to 2010) if it holds through the end of October. The 5-year month-end average is 55.8%. At the sector level, Communication Services (72%) and Info. Tech. (69%) have the highest share of buy ratings, while Consumer Staples has the lowest (47%) and the highest share of sell ratings (7%).
Hold ratings are also unchanged at 35.3%. That would be a new month-end record low (to 2010) if it holds, vs the 5-year month-end average of 38.7%. Sell ratings are at 4.7%, remaining in their narrow range since 2009 but below the 5-year month-end average of 5.6%.
Valuations Still Under Pressure
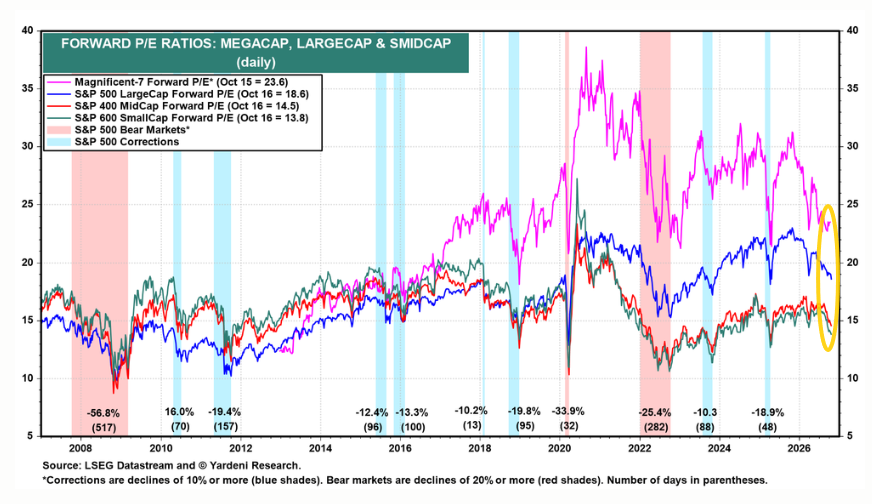
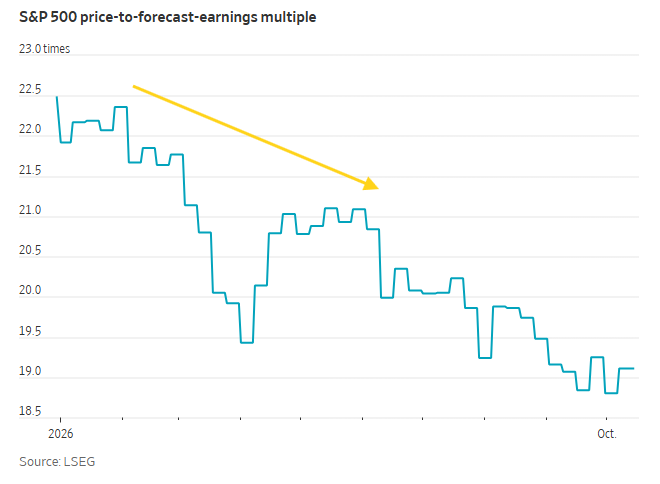
Valuations outside the Mag-7 continue to push lower, all though around the least since liberation day.
The fall this year has been dramatic (note forward P/Es are often inconsistent even for the same index reflecting what is used in the earnings calculation).
Wall Street Journal
While Citadel’s Rubner notes
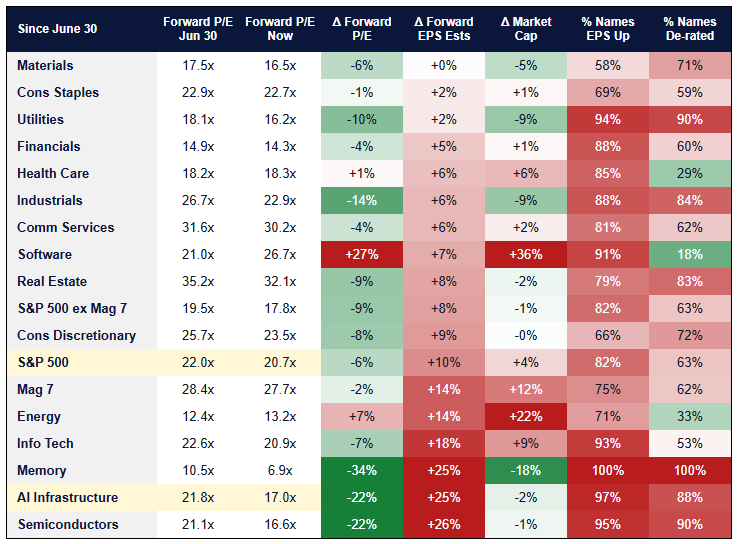
The divergence between forward earnings expectations and valuations has been particularly pronounced across Semiconductors, Memory, and AI infrastructure. Since the end of June, forward earnings expectations have risen sharply even as valuation multiples have compressed:
And another reminder if we do see yields softening we’ll also likely see a rerating in stocks:
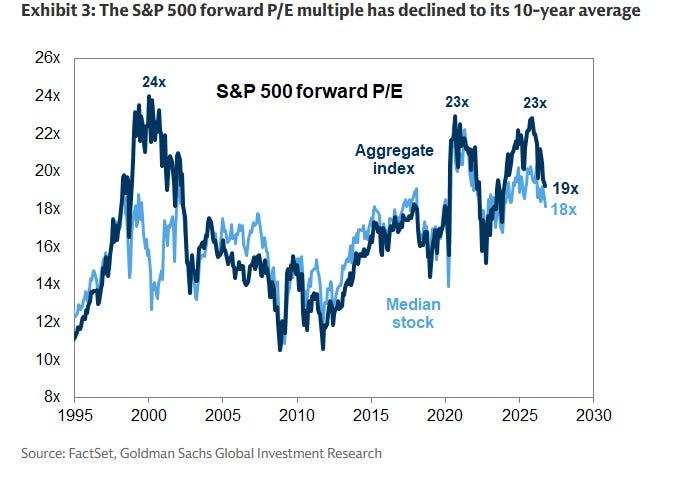
Goldman: As investor positioning has declined, the S&P 500 P/E multiple has contracted to 19x, and now matches its 10-year average.Year to date, the S&P 500 has risen by 13% but the consensus forward 12-month EPS estimate has risen by 29%. The result is a 13% decline in the forward P/E multiple, which has declined from 23x a year ago to 19x today.
Breadth – Are We Past the Bottom (Part II)?
As I said last week, “breadth metrics more universally improved this week outside of the Nasdaq.”
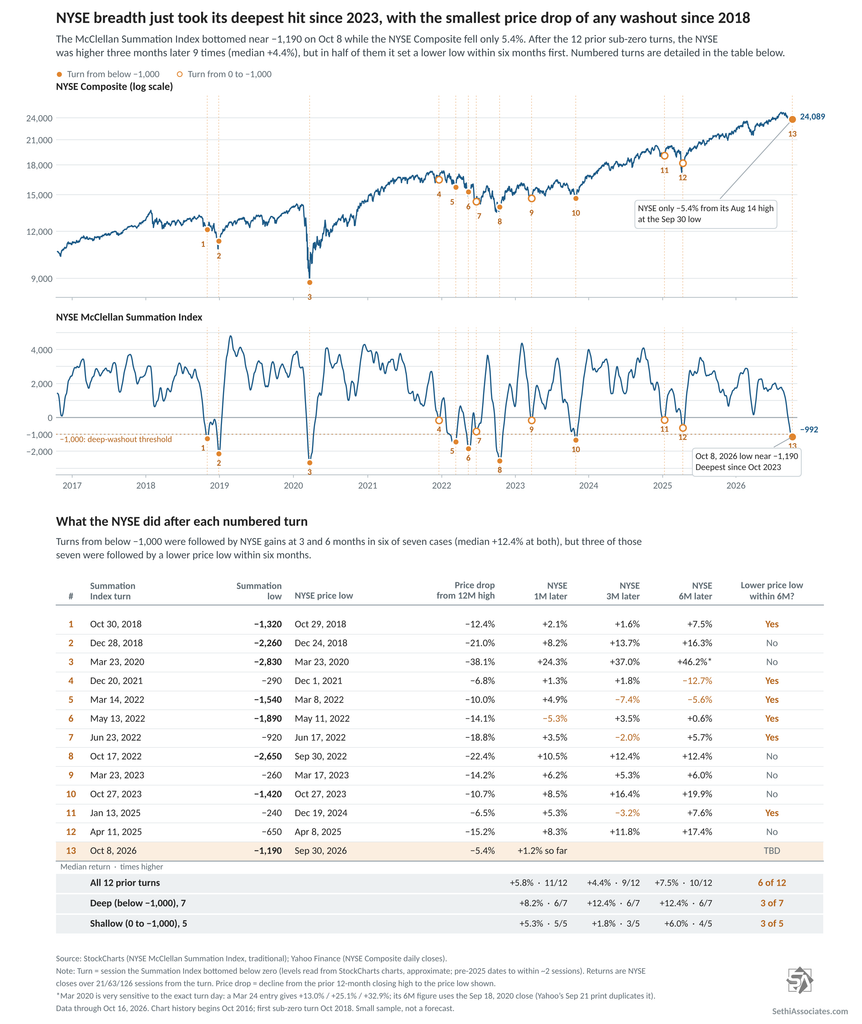
The McClellan Summation Index (red line, broadly whether the typical stock is doing relatively better or worse than the index) has continued its turn higher from the lowest since October 2023. As I mentioned three weeks ago “you can see, though, when it does rebound, rallies in the NYSE Composite are generally fairly powerful.”
Here’s Claude’s analysis on that:
The Index bottomed near −1,190 on Oct 8, its deepest reading since October 2023, though well short of the 2018, 2020 and 2022 washouts. What stands out is how little price damage came with it. The NYSE Composite fell just 5.4% from its Aug 14 high, the smallest drop of the 13 sub-zero breadth washouts since 2018.
History is supportive, with caveats. After the seven prior turns from below −1,000, the NYSE was higher three and six months later in six of seven cases, with a median gain of 12.4% at both points. But three of those seven, in October 2018 and twice in 2022, were followed by a lower price low within six months.
A turn in breadth hasn’t always marked the bottom in price. Across all 12 prior sub-zero turns, the NYSE was higher a month later 11 times, and it’s up 1.2% since this one.
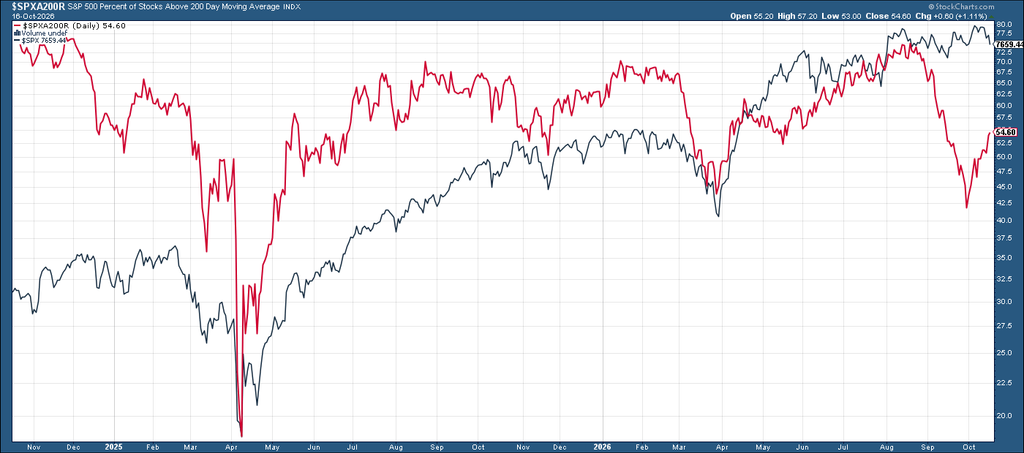
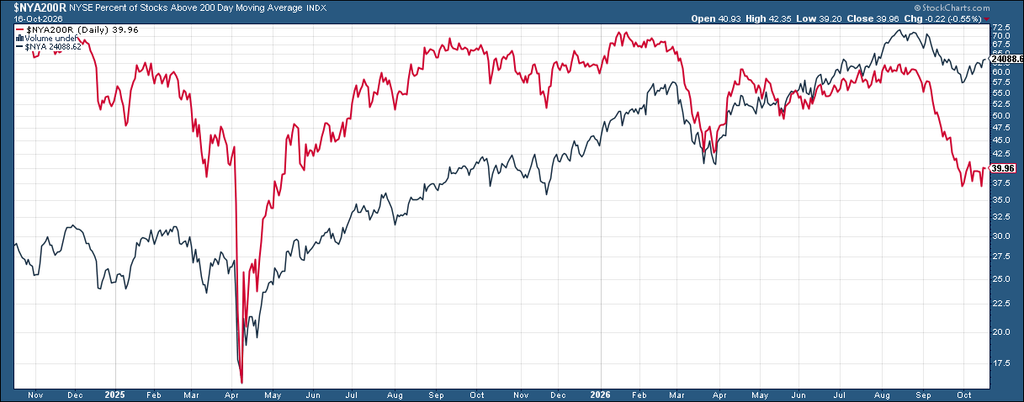
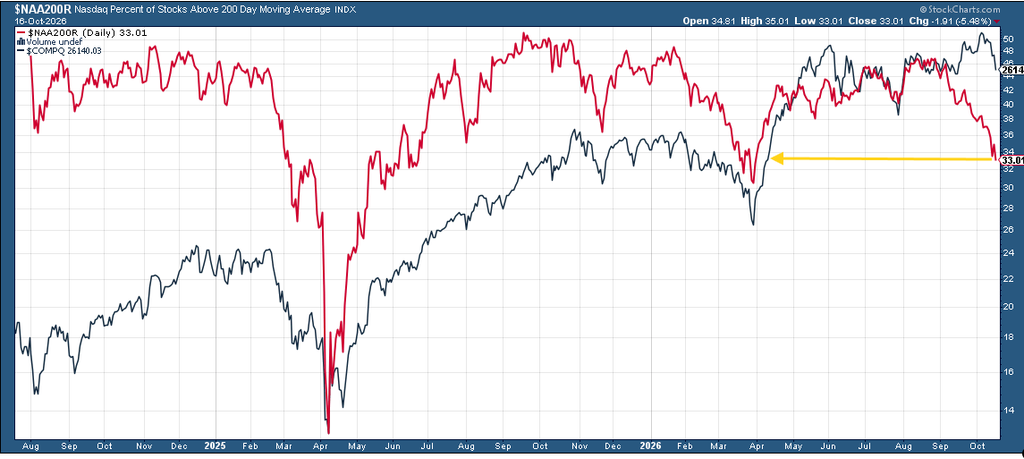
Percentage of stocks over 200-DMAs (red lines) are mixed. The S&P 500 has seen the most progress now up to 55%.
They NYSE though is off the lows but hasn’t made much progress.
While the Nasdaq hit a new “since March” low on Friday.
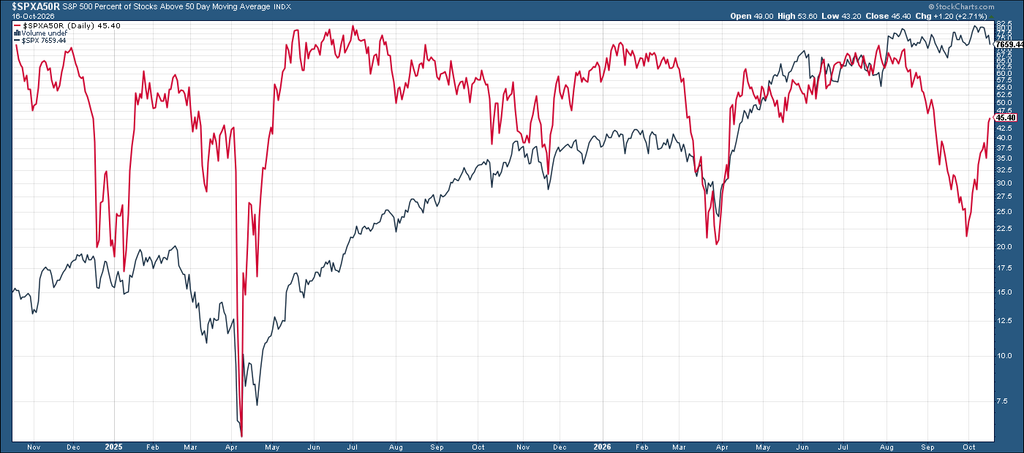
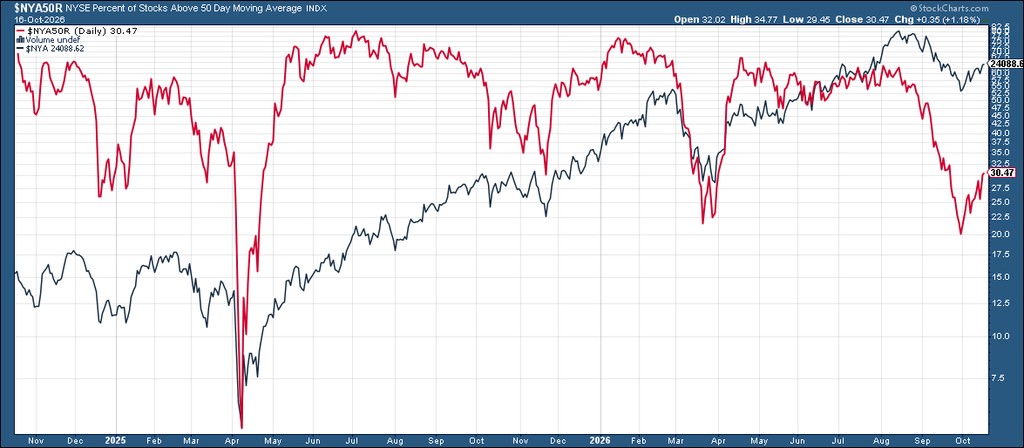
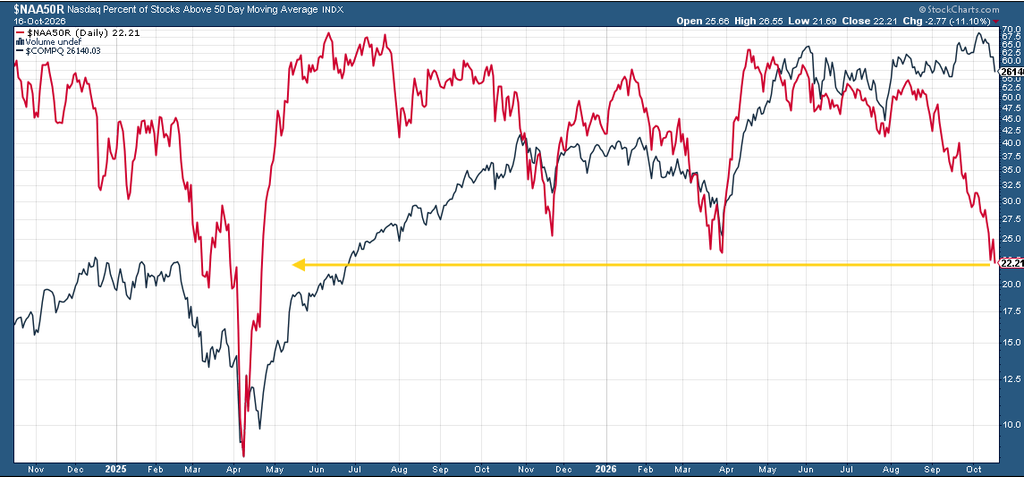
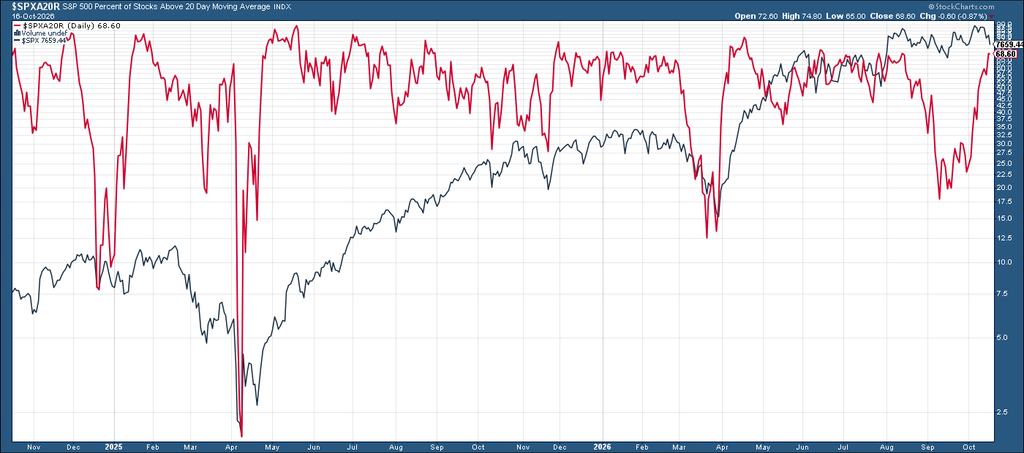
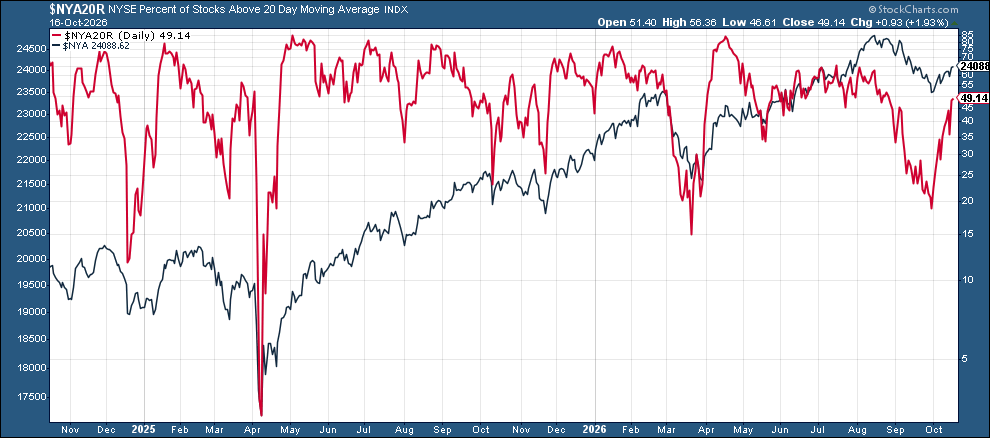
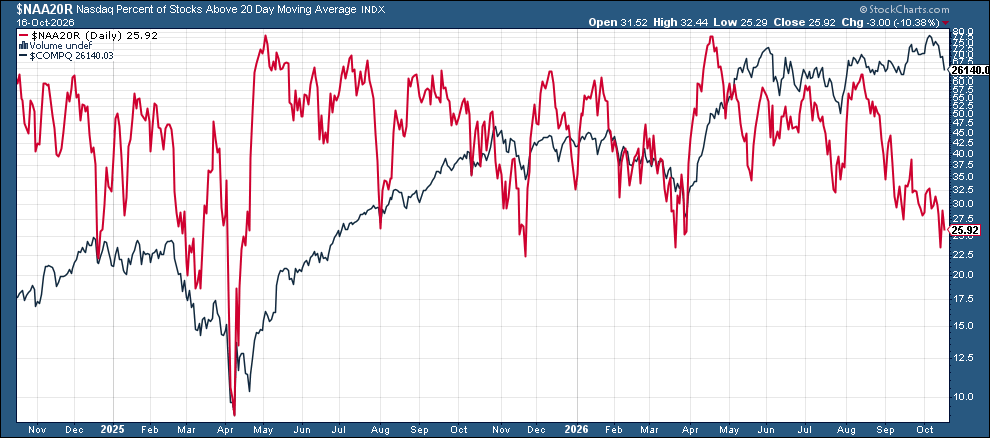
And a similar story for shorter-term 50 & 20-DMAs although on these the NYSE has made more progress, the SPX is back to around the highest since April on 20-DMAs while the Nasdaq is now the least since April 2025 on the 50-DMAs.
50-DMAs
20-DMAs
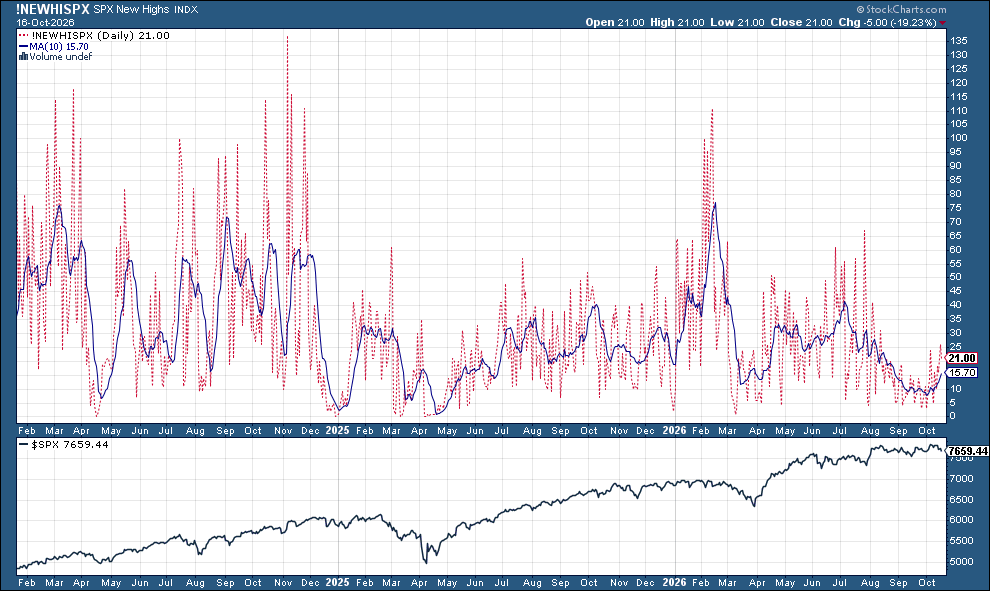
SPX new 52-week highs remain very subdued but the 10-DMA (blue line) is drifting higher.
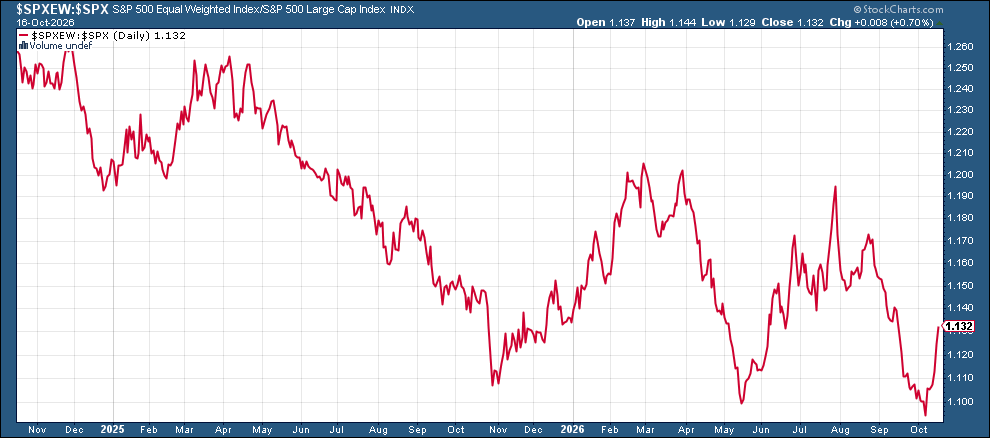
And the ratio of the equal-weight SPX to the cap-weighted has continued its bounce after hitting the lowest level since 2003.
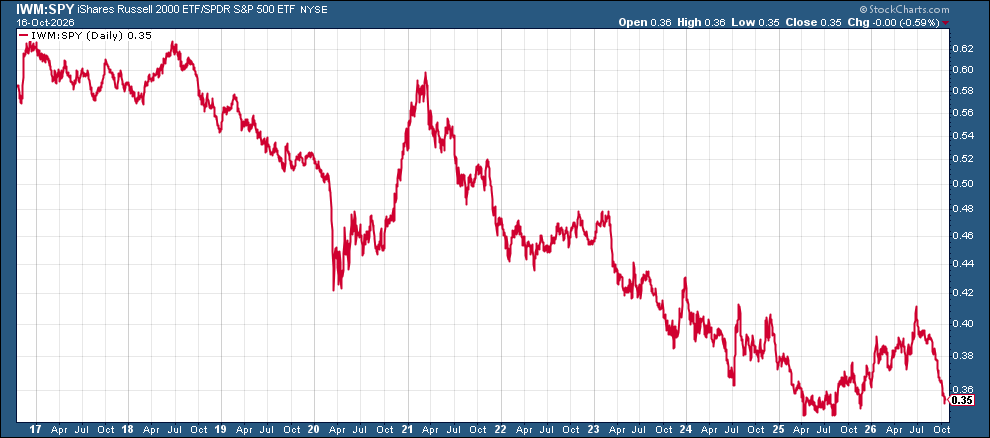
But the ratio of small caps to large caps (Russell 2000 to SPX) continues to drop now at the lows of the year.
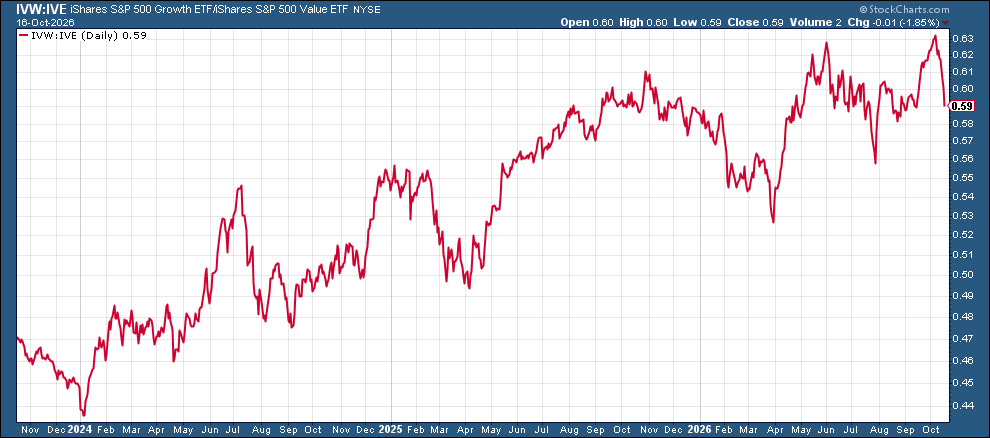
While S&P 500 growth/value continued to fall sharply after making an all-time high two weeks ago.
Positioning Continues to Bifurcate
Deutsche Bank:
Our measure of aggregate equity positioning edged lower this week but remained modestly overweight, at 0.17 standard deviations, or the 51st percentile.
The decline was driven by modest reductions in discretionary investor positioning, which moved further underweight to −0.36 standard deviations, or the 24th percentile.
Meanwhile, systematic strategies’ positioning remained largely unchanged at an elevated 0.81 standard deviations, or the 86th percentile.
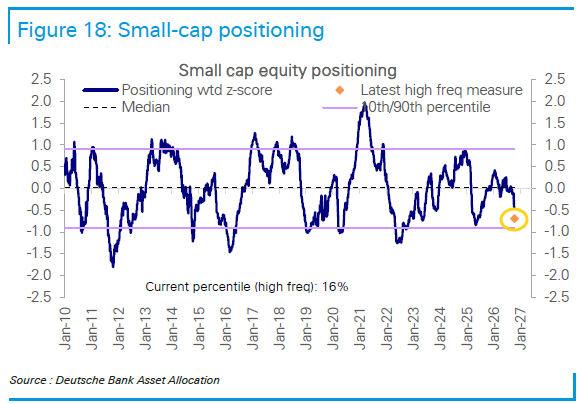
“Positioning in large caps (0.39sd, 69th percentile) declined this week but remained overweight, while that in small caps (-0.69sd, 16th percentile) moved deeper underweight.” That 16th percentile is the lowest since the liberation day pullback.
In terms of sector positioning they find:
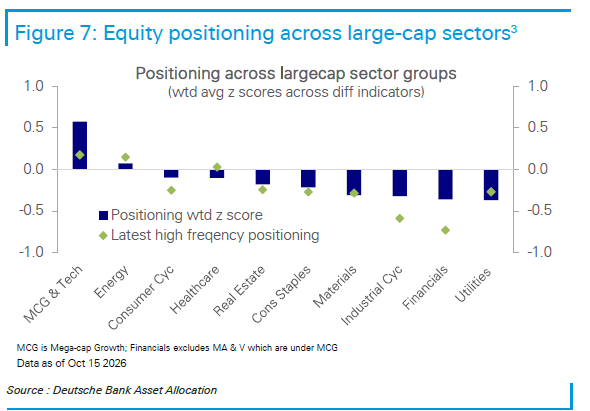
Across sectors, positioning remains modestly overweight in MCG & Tech, Energy, and Health Care, and underweight elsewhere.
MCG & Tech positioning declined notably but remained modestly overweight at 0.18 standard deviations, or the 40th percentile. Energy positioning shifted from modestly underweight to modestly overweight at 0.15 standard deviations, or the 74th percentile.
Consumer Cyclicals positioning fell sharply, moving from modestly overweight to notably underweight at −0.25 standard deviations, or the 57th percentile. Materials remained underweight at −0.29 standard deviations, or the 21st percentile. Positioning in Financials and Industrial Cyclicals also declined sharply, leaving both near the bottom of their historical ranges: Financials stood at −0.73 standard deviations, or the 11th percentile, and Industrial Cyclicals at −0.59 standard deviations, or the 21st percentile.
Among defensives, Health Care positioning edged higher to just above neutral at 0.03 standard deviations, or the 54th percentile. Real Estate positioning rose modestly but remained underweight at −0.24 standard deviations, or the 51st percentile. Utilities and Consumer Staples positioning both declined and remained underweight, each at −0.27 standard deviations, corresponding to the 34th and 13th percentiles, respectively.
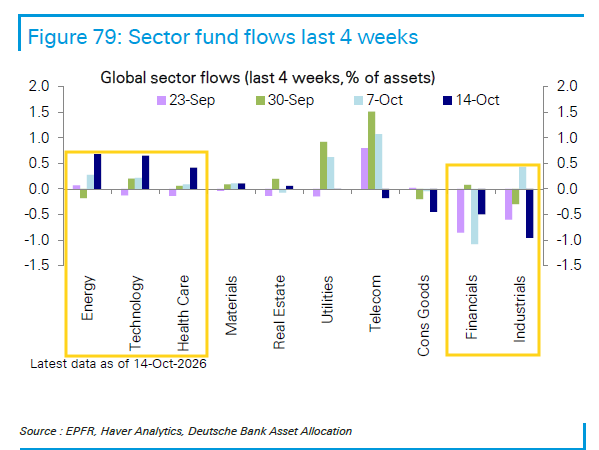
In terms of flows last week, DB saw a “sharp acceleration” in US inflows at +$39.1B from +$3.3B the prior week (and two weeks of outflows before that), led for a second week by Tech (+$10.7B after +$3.5B), “At the other end, Industrials (-$1.6bn) suffered their biggest weekly outflows in over 12 years. Financials (-$1.4bn) witnessed outflows for a second straight week.”
Goldman though says hedge funds were selling Tech:
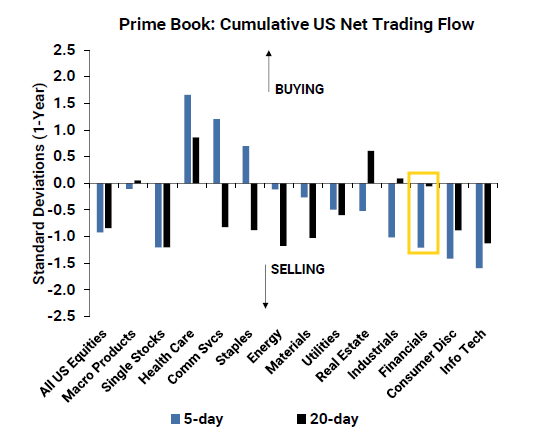
Info Tech, by far the worst performing US (and global) sector this week, was also the most net sold in both $ and SD terms (-1.6 SDs 1-year), driven by long sales and to a much lesser extent short sales (6 to 1).
All subsectors were net sold on the week, led by Semis & Semi Equip, which made up 57% of the $ net selling within Info Tech, and to a lesser extent Software and Electronic Equip, Instruments & Components.
Semis & Semi Equip stocks now make up 9.5% of total US net MV on the Prime book, in the 39th/88th percentiles vs. the past 1-year/5-years.
“All of the cumulative net buying from hedge funds in Global AI since the start of 2025 has been reversed.”
And they saw selling in Financials as well:
As large cap banks kicked off the Q3 reporting season, HFs net sold US Financials for the first time in 5 weeks (-1.2 SDs 1-year), driven by short sales far outpacing long buys (4.4 to 1). Capital Markets (especially Asset Managers & Data Services), Insurance, and Transaction & Payment Processing were the most net sold subsectors, while Consumer Finance and Banks were modestly net bought.
Financials now make up 10.8% of total US net MV on the PB book, in the 55th/32nd percentiles vs. the past 1-year/5-years.
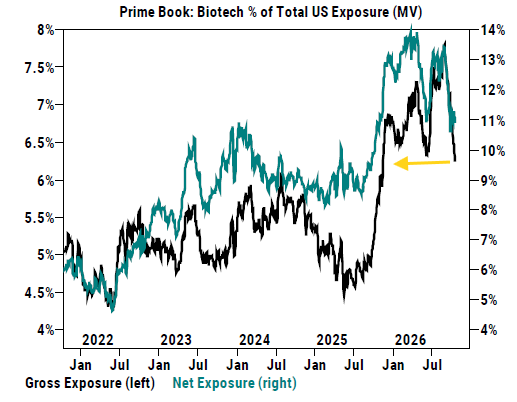
But buying in Health Care:
In contrast, Health Care was by far the best performing as well as the most net bought US sector on the PB book this week (+1.7SDs), driven by short covers and to a lesser extent long buys (2.2 to 1), which points to continued risk unwind as the sector’s gross trading activity decreased for a 5th straight week.
Nearly all subsectors (sans Pharmaceuticals) were net bought this week, led by HC Equip & Supplies (long buys), HC Providers & Svcs (long buys + short covers), and Life Sciences Tools & Svcs (short covers), while Biotech saw the largest de-grossing activity within the sector, driven by short covers modestly outpacing long sales.
US Biotech long/short ratio now stands at 3.12, in the 5th/28th percentiles vs. the past 1-year/5-years.
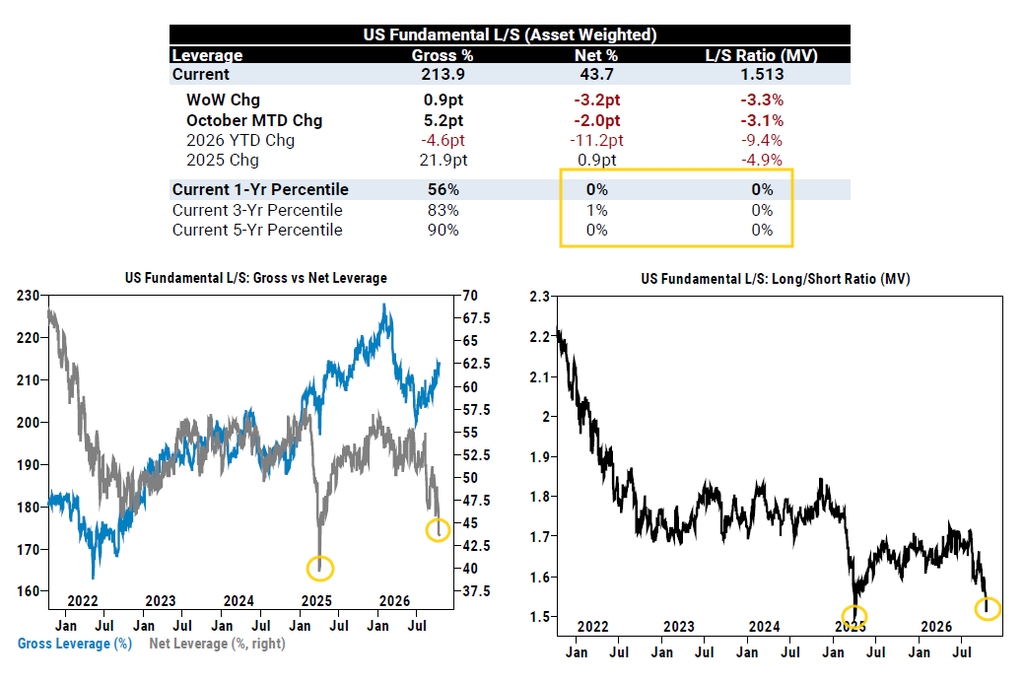
And overall hedge fund net positioning according to Goldman has dropped to levels we haven’t seen outside of liberation day in the past five years as they look to protect gains. While US Long/Short Fund gross leverage is at the 56th percentile one-year (and the 90th five-year percentile), US net leverage saw “the largest weekly decline since Apr ’25 (week of Liberation Day) and the 4th largest weekly decline in the past five years to 43.7%” which is the 0 percentile for both the one and five-year lookbacks.
The US Fundamental long/short ratio (MV) remained at the 0 percentile one-year (and now also five-year). So hedge funds decreased longs and increased shorts last week, likely in a move to preserve what has been a good year, but leaving a huge amount of room for them to eventually reengage with the market.
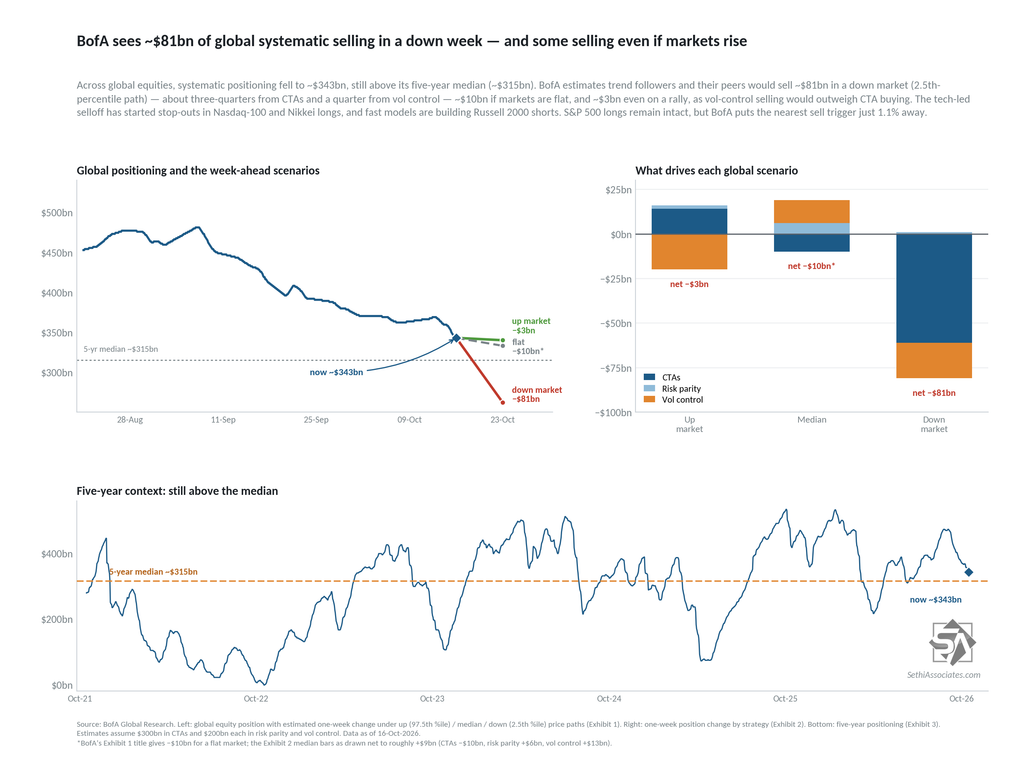
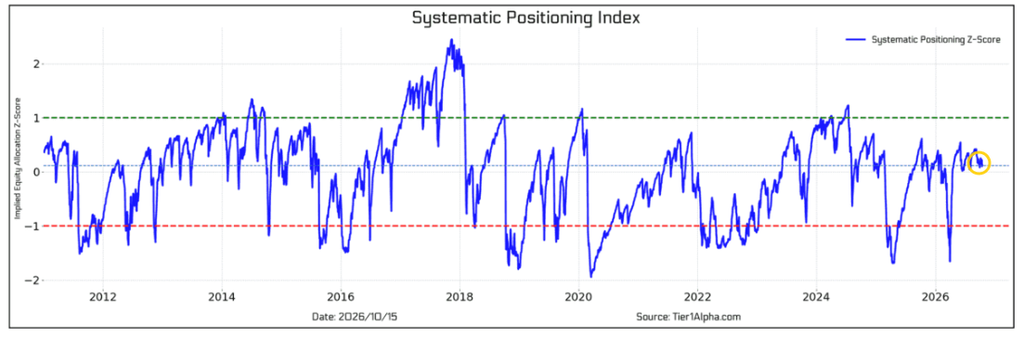
Turning to systematic positioning, BofA unlike DB saw more selling from the systematic community bringing levels down near the 5-year median. They say while “CTA equity exposure remains long overall, the breadth of that positioning is deteriorating,” with selling under all scenarios this week:
Nasdaq-100 and Nikkei longs have begun to stop out following the technology-led selloff, with further selling possible next week. Faster-moving models are also building Russell 2000 shorts, while weakening Euro Stoxx 50 trends leave positioning vulnerable to additional unwinds.
S&P 500 longs remain intact for now, with the nearest sell trigger now only 1.1% away. The rise in realized volatility should also reduce position sizes across equity markets where trend followers remain long.
As they noted, the sell trigger for the S&P 500 now sits just ~1.1% away (from ~3.0% last week), with longs fully unwound ~3.7% lower. Nasdaq-100 longs have already begun to stop out, with the next trigger ~0.9% below (from ~1.5% last week). The Russell 2000 is sitting right on its first sell trigger, with the next ~2.0% lower, and no buy trigger is listed (from +2.7% last week).
In terms of the upcoming week they see:
−$10B of selling in global equities in a flat market (from −$4B last week). Note though that’s BofA’s stated figure, but its strategy breakdown shows ~$10B of CTA selling more than offset by risk-parity and vol-control buying, so it may be closer to moderate buying;
−$3B of selling even in an “up” market (from +$1B last week), as ~$20B of vol-control selling outweighs ~$14B of CTA buying (“up market” defined as the 97.5th percentile price path or ~+3.5%, similar to Goldman); and
−$81B of selling in a “down” market (from −$86B last week and −$84B the prior week), led by ~$61B from CTAs and ~$20B from vol control, with risk parity roughly flat (“down market” defined as the 2.5th percentile price path or ~−2.9%, different than Goldman who uses −4.5%).
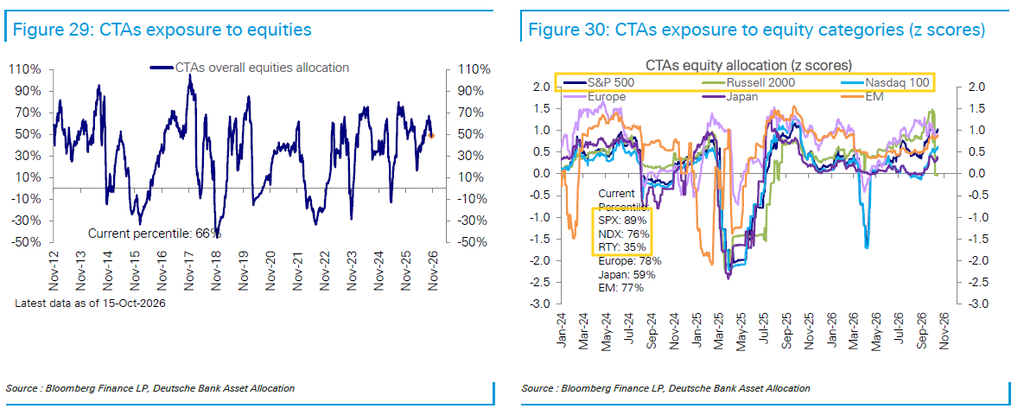
DB says they saw global CTA positioning as having “declined this week but remains elevated” at the 66th percentile to 2010 (but down from the 89th five weeks ago), and unlike BofA they see US positioning as having risen to the 77th percentile from the 67th the prior week (but still down from the 91st two weeks ago).
The Russell 2000 remained at just the 35th percentile, while the Nasdaq-100 curiously (given the large drop in the index) rose to the 76th from the 69th, while the S&P 500 edged to the 89th from the 87th.
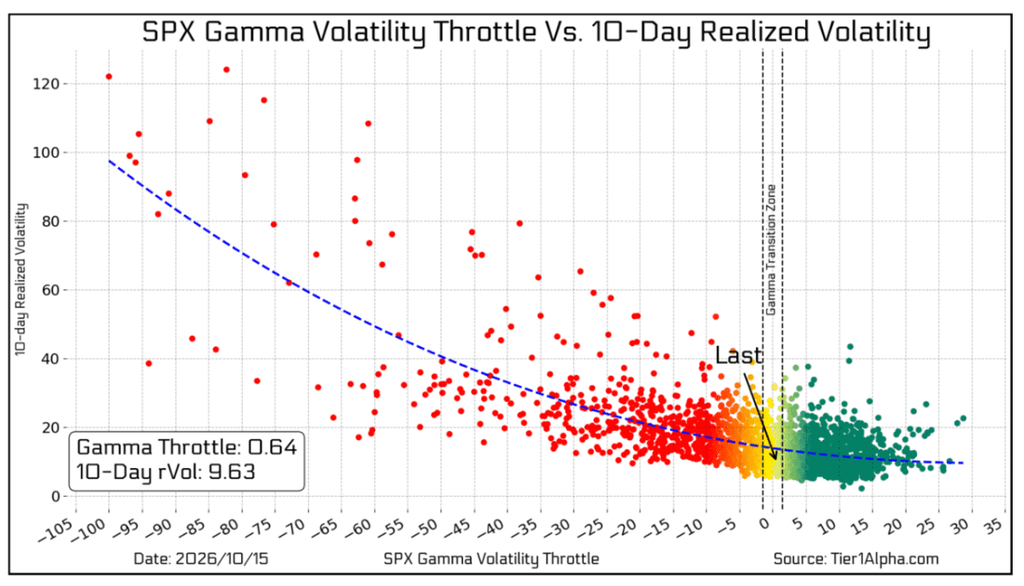
Here was Tier1Alpha’s take from Friday morning (like BofA they see systematic positioning as close to the 5-year median):
the directional outlook remains less clear, particularly as CTAs remain in a highly dynamic state, with considerable path dependency embedded in the setup. These strategies are forced to buy into strength and sell into weakness, creating a self-reinforcing feedback loop similar to negative gamma that can amplify price swings in both directions. Last week, these flows were broadly negative, although it is notable that even with the first 1% decline since July, the volatility response remained relatively muted.
The bullish scenario for next week involves strengthening momentum, forcing CTAs to mechanically increase equity exposure and providing a supportive tailwind for the index. On the other hand, the bearish scenario, which remains our primary concern, involves rising volatility alongside the weak CTA positioning, potentially triggering additional selling from other systematic participants, volatility control funds, and levered fund rebalancing.
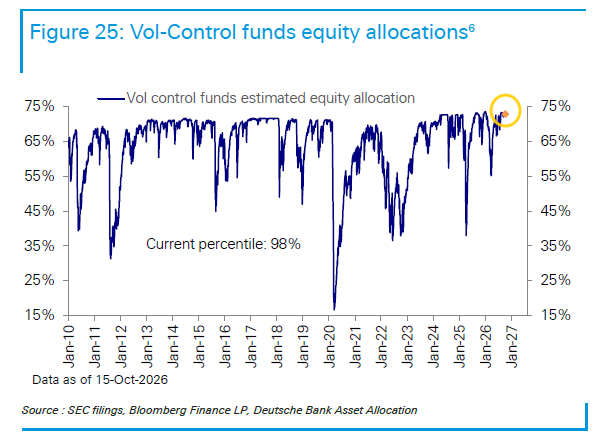
Looking at vol control* positioning, DB finds that it “declined this week but remains elevated” at the 98th percentile, remaining a risk if volatility were to spike. In that regard, they said:
Their sensitivity to selloffs increased sharply, making funds more responsive to downside moves than last week. With positioning still stretched, capacity to add further equity exposure remains limited, while the higher sensitivity to selloffs means a less supportive flow backdrop if volatility rises.
*vol control strategies enter and exit based on changes in volatility over past windows (mostly 1-month and 3-month).
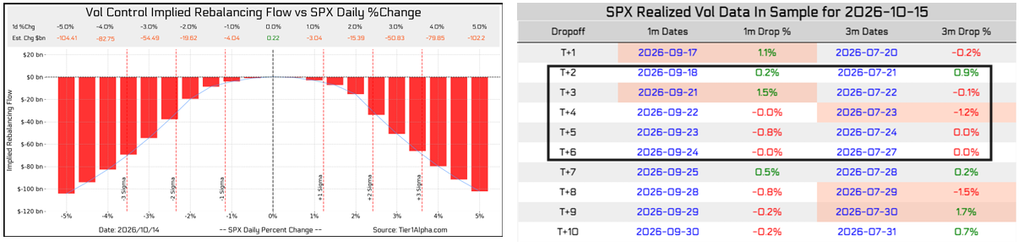
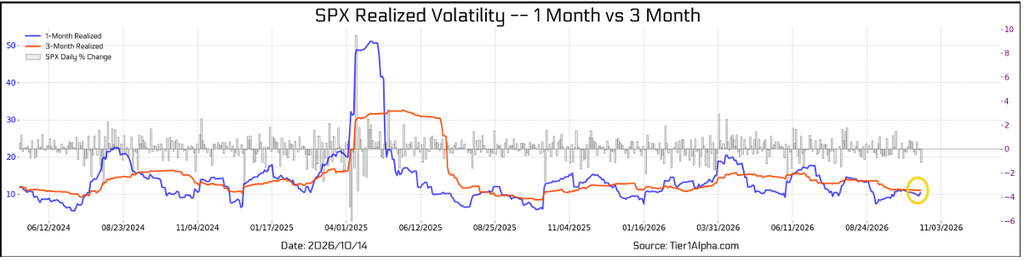
Looking at the upcoming week, it’s not constructive for further vol control releveraging and a risk for deleveraging. One 1%+ day drops off each of the 1-month and 3-month lookbacks, and there are four 0.0% days dropping off in addition to 0.1% and 0.2% days.
1-month volatility remains just below 3-month leaving the latter as the predominant volatility trigger according to Tier1Alpha.
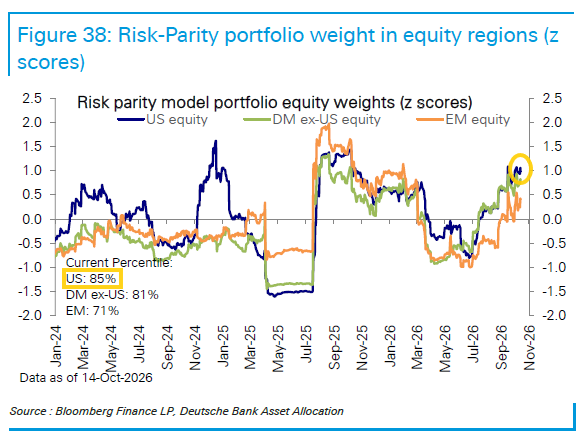
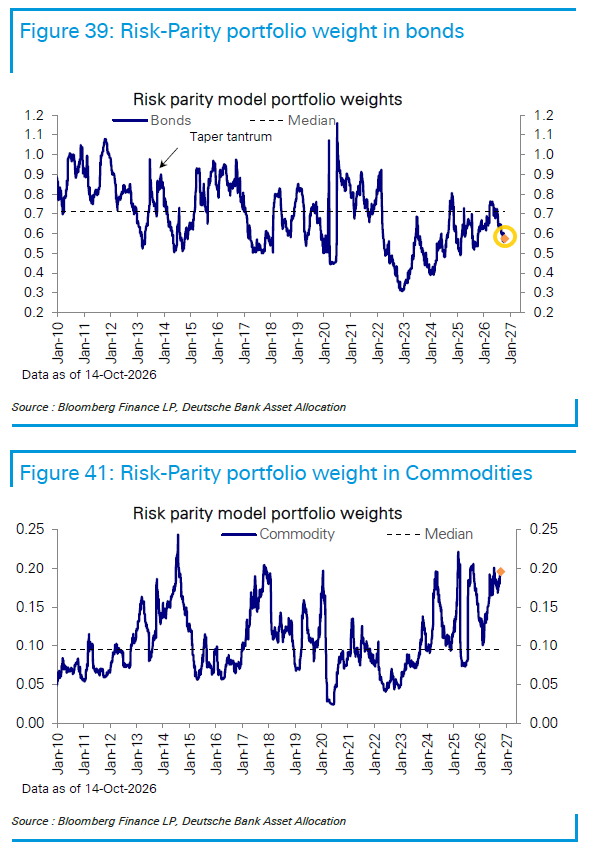
While for risk parity* DB says for a second week “equity allocations increased this week,” with the US edging up to the 85th percentile (from the 84th the prior week). Bond exposure though “remained below historical norms” at the 30th percentile while commodities remain elevated at the 97th percentile.
*Risk parity funds balance risk across asset classes based on relative volatility, often using leverage, to reach a target portfolio risk level.”
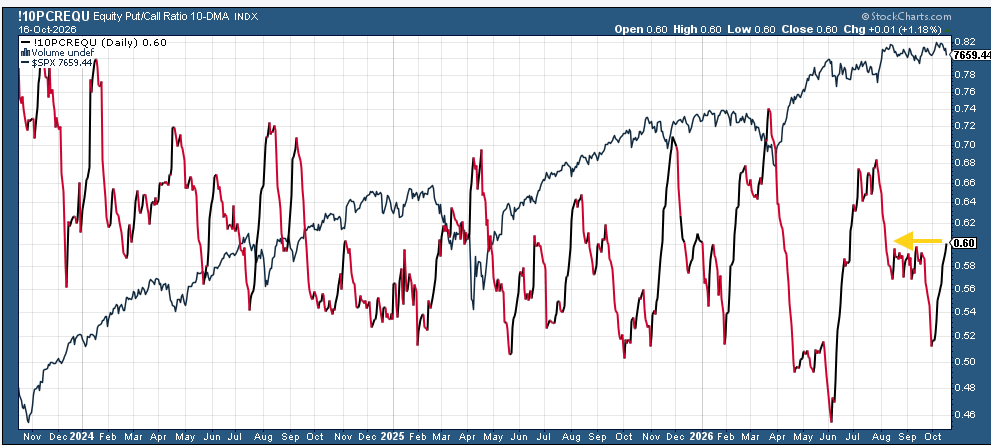
While put/call buying (which adds incremental downside/upside pressure) rose to the highest since early August.
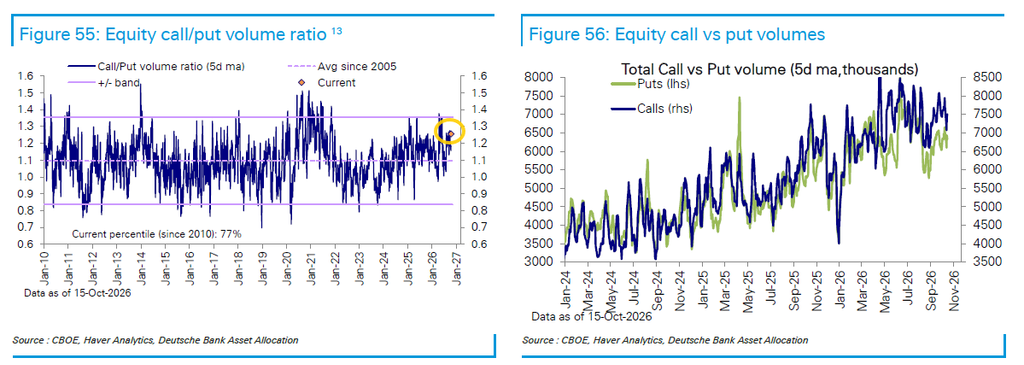
And DB said the 5-DMA of call/put volume decreased for a third week to the 77th percentile from the 90th three weeks ago, “as a decline in index option volumes more than-offset increases in ETF and single-stock option volumes. Within single-stock options, the decline was most pronounced in MCG & Tech, with a more modest decline in Financials.”
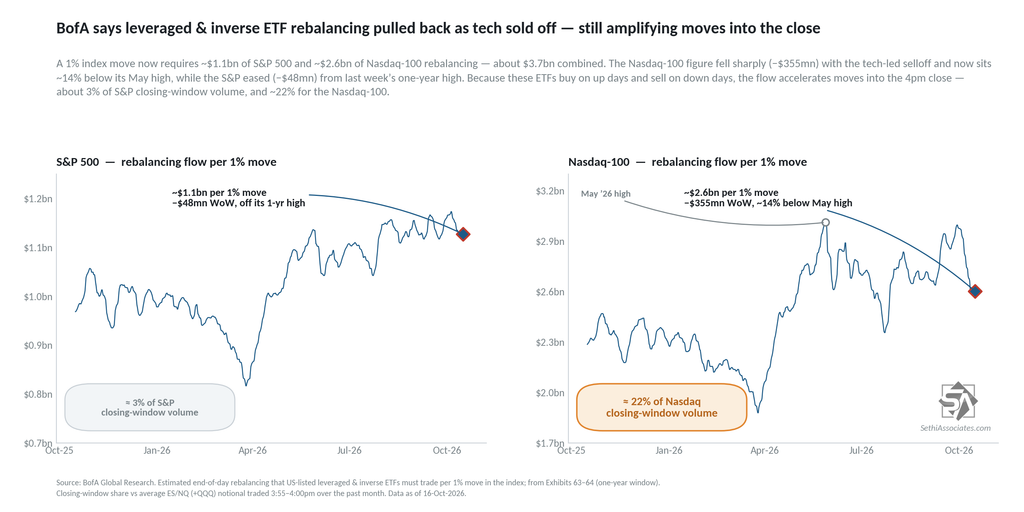
Like call buying, leveraged positioning acts as a “negative gamma source” as Charlie McElligott has put it (meaning that there is added buying/selling pressure from them in the direction of daily flows as they rebalance each day).
BofA estimates that rebalancing flows for SPX and Nasdaq-100 leveraged ETFs fell back along with the equity declines last week.
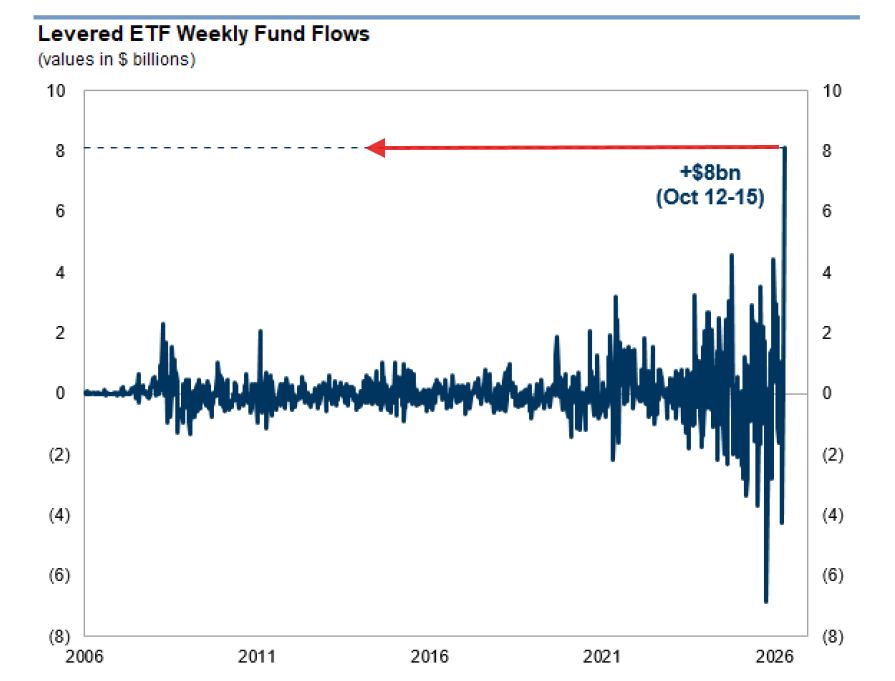
But Goldman says it was due to a drop in price not outflows as “over $8 billion has poured into levered ETFs over the past four days, which is the largest weekly inflow in our dataset… This demand coincides with the NDX finishing lower for five consecutive sessions.”
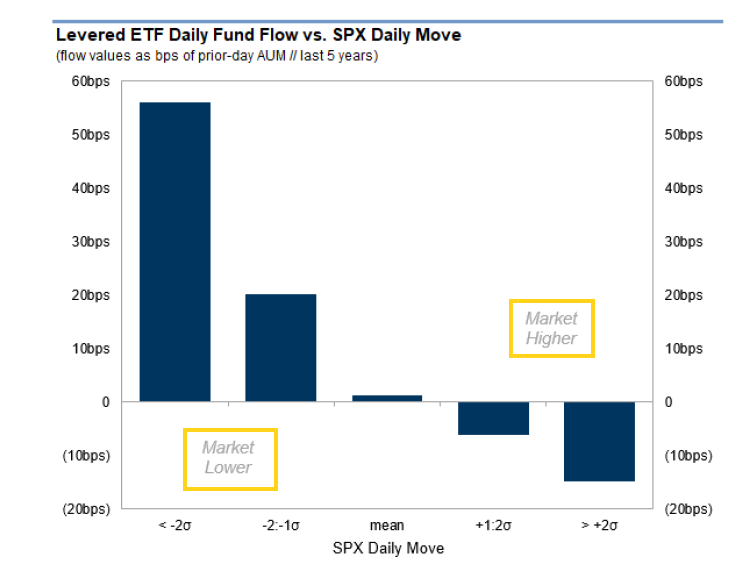
Which is consistent with past patterns:
Flows within the levered ETF complex have historically been strongest on days where the broader market has faced challenging price action (-2σ events), and weakest during the market’s best days of performance (+2σ). In addition to the inverting flow behavior, it’s worth noting that flows are larger on an absolute basis when the market experiences challenging price action.
On the fund level, this dynamic is particularly apparent within SOXL (+3x semis), which has garnered +$6 billion this week (tracking for its largest weekly & rolling 5-day haul ever), despite its target index (ICESEMI) languishing -11% (a -2σ event).
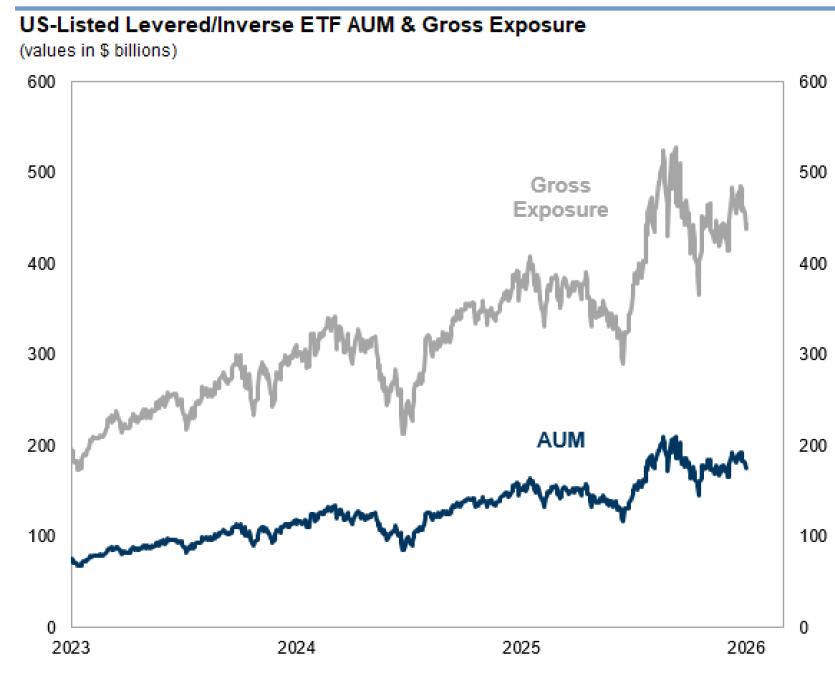
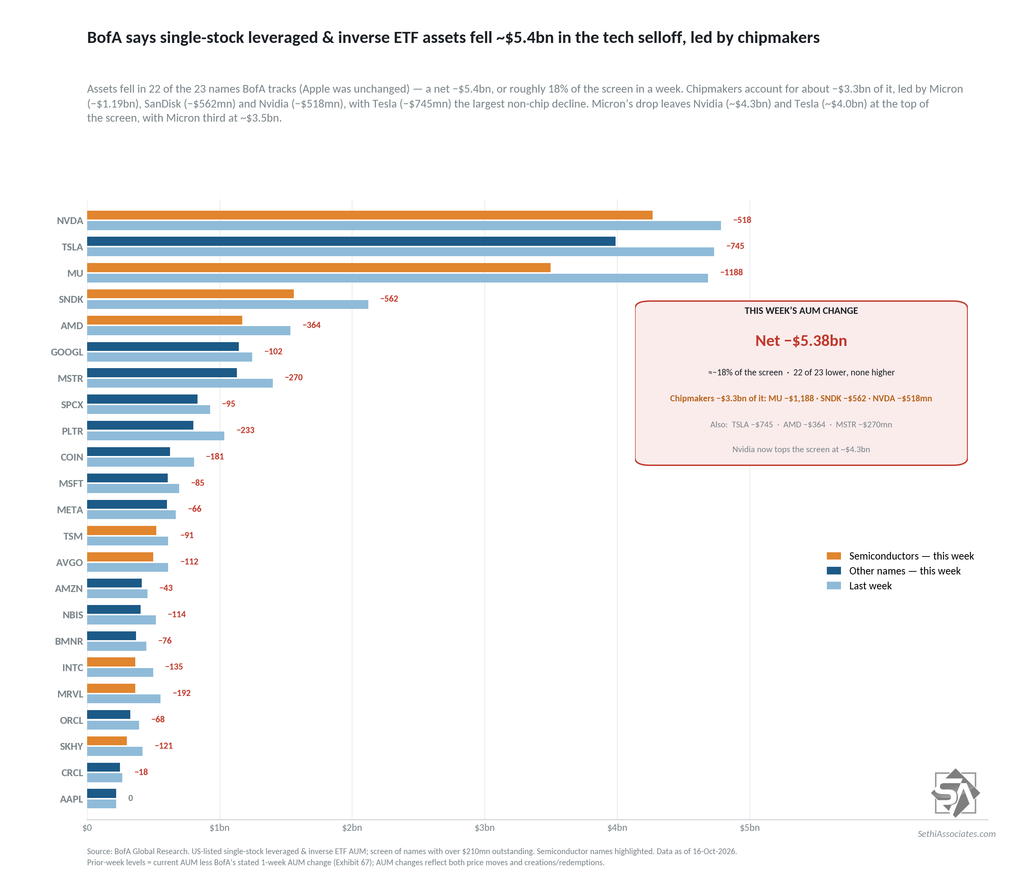
In aggregate, levered & inverse ETFs represent $176 billion in AUM and $444 billion in gross exposure, with growth at the top line primarily dictated by market appreciation. This flow dynamic is important given the number of “invested units” (i.e., flows) has net increased. Therefore, if the market environment does improve, this recent demand could act as a growth catalyst to the complex.
Single-stock leveraged ETF AUM also fell with all of the top 22 largest seeing AUM drop a huge -$5.2B driven by semiconductors shedding $3.3B of AUM.
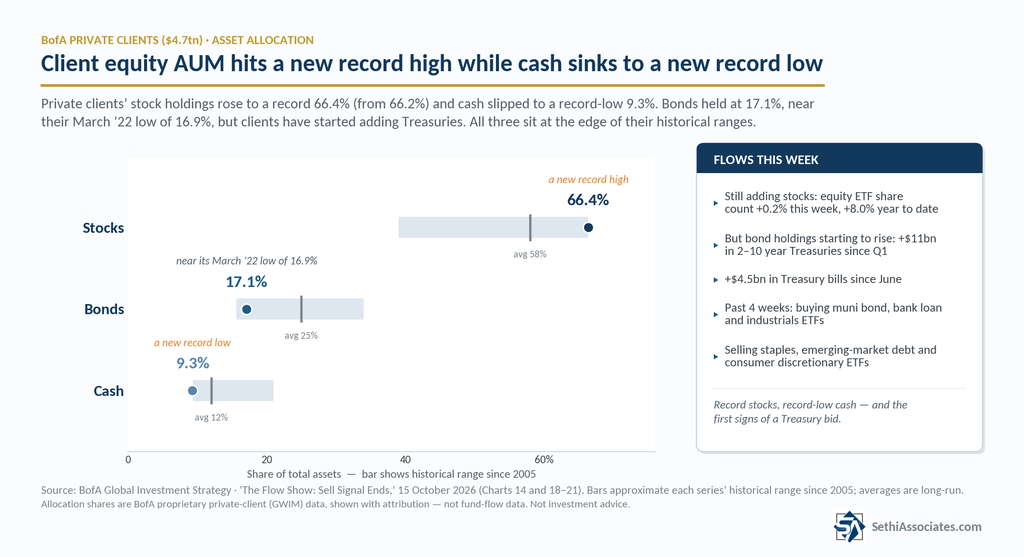
Turning to retail positioning, BofA client retail equity positioning rose back to its joint record high of 66.4% of client AUM, while bonds remained at 17.1% (two tenths above the 16.9% September 4th that was the lowest since March 2022), while cash fell to 9.3%, a new record low.
And Citadel’s Scott Rubner dove into retail flows on Citadel:
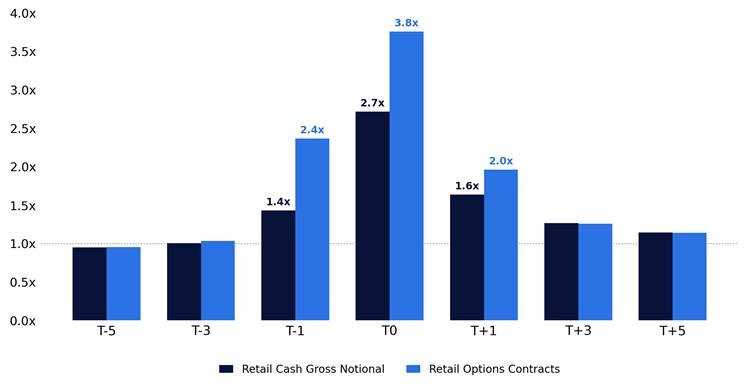
Retail buying is picking up again, even as overall trading activity remains below average. Last week, retail net bought $9.1 billion of US equities on our platform, the largest weekly net buying in 15 weeks (since late June) and the ninth-largest week over the past year.
The increase has been driven by stronger directional conviction rather than elevated volumes. Retail was 2.7% better to buy last week, a 90th-percentile reading for weekly directional skew, while gross trading activity remained in just the 42nd percentile of the past year. Weekly net buying has now increased for three consecutive weeks, from $4.8 billion to $6.4 billion and $9.1 billion.
Buying has been heavily concentrated in ETFs and the AI complex. Across themes:
Semiconductors: $2.6 billion net bought, the third-largest week of the past year (96th percentile). At the current pace, October is on track to be the largest month of net buying on our platform, running at 3x the 1Y average.
AI Infrastructure: $2.4 billion net bought, the fourth-largest week of the past year (94th percentile).
Neoclouds: $700 million net bought, the largest weekly accumulation we have observed in the group.
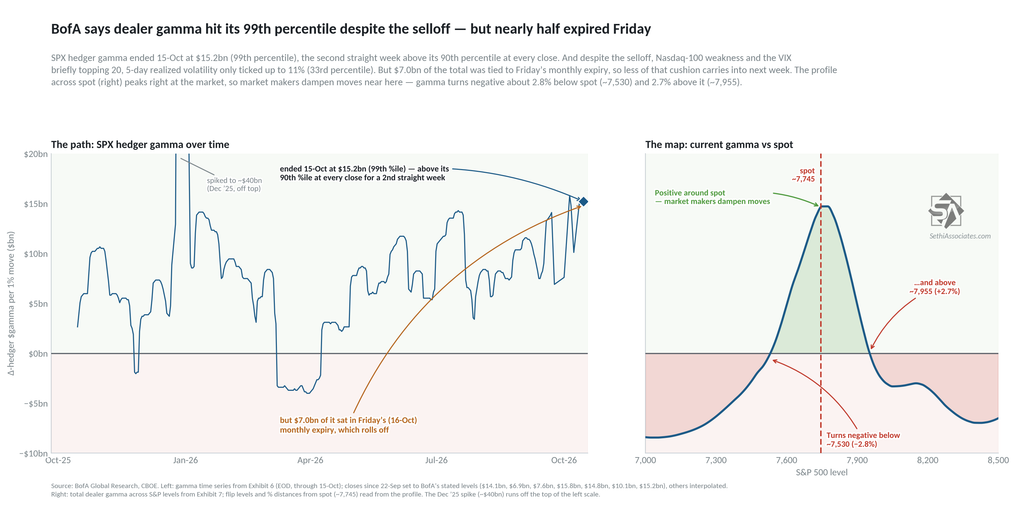
And turning to gamma* BofA saw SPX gamma last week at the 99th one-year percentile on Thursday, “the second straight week where gamma finished above 90th %ile at every single close,” which almost certainly dampened volatility. However, nearly half of that gamma was in options tied to Friday’s options expiration so gamma can be expected to at least start the week positive but off the extreme levels hit last week.
Again the curve looks more like a mountain than a hill, very elevated around 2% in either direction but falling sharply if we move outside of that range, turning negative before we even get to 3% (noting though that these are not fixed and will move daily as does spot).
*gamma plays an important if nebulous role in market volatility —positive gamma means options market makers will buy/sell in the opposite direction of moves in price dampening volatility, while negative gamma means the inverse and market makers accelerate rallies/sell-offs adding to volatility.
While we generally do not expect much from the expiration itself, it creates an interesting setup for next week as gamma levels fall back toward their cyclical lows. With dealer hedging activity playing a smaller role, organic supply and demand, alongside other systematic players, should become more dominant, creating conditions for a modest expansion in volatility.
We’ll see what they say Monday morning.
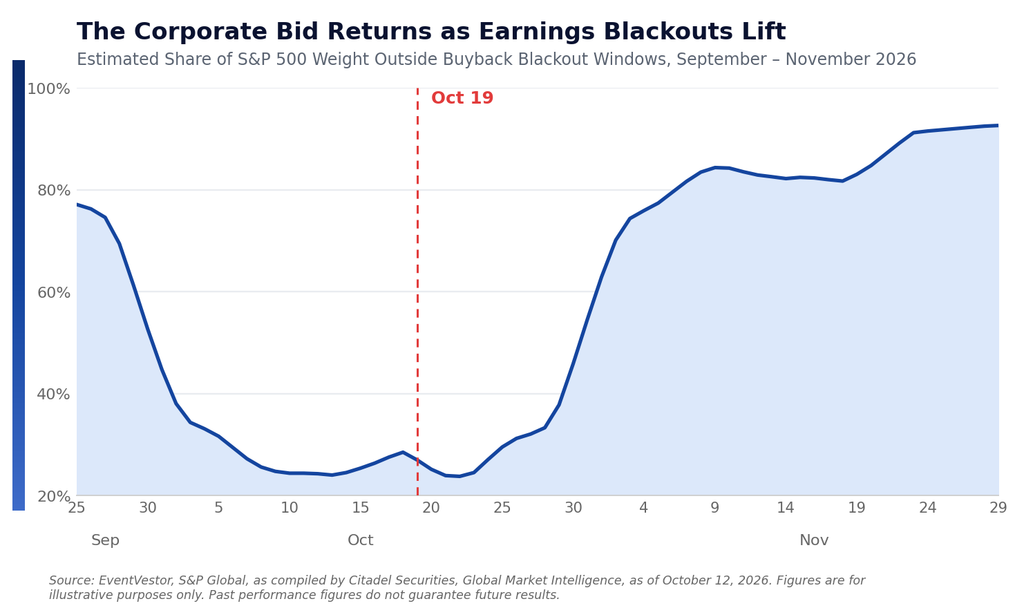
Turning to corporate buybacks (an important source of underlying demand), we remain deeply into the buyback blackout period with just around 25% of discretionary buybacks by index weight for S&P 500 companies active this week on average (discretionary buybacks represent ~30% of all buybacks), and as noted last week “it won’t get back above 40% until we get into November.”
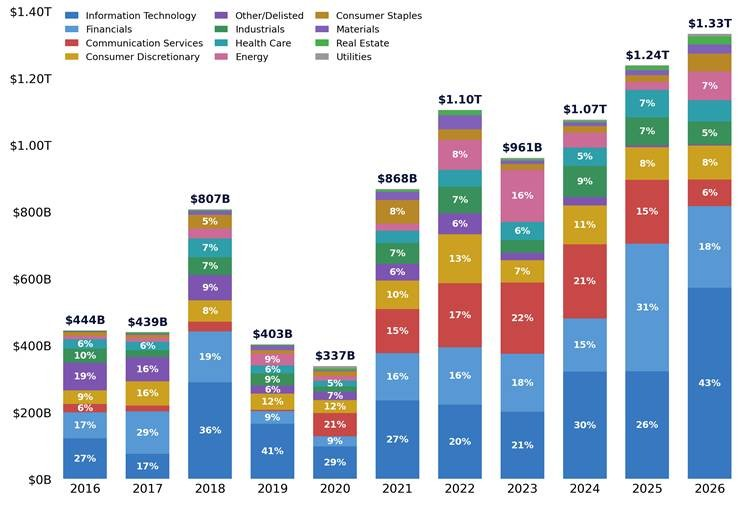
And Rubner notes “US corporates have already announced a record $1.3 trillion of share repurchase authorizations YTD, 8% ahead of last year’s record pace. Technology alone accounts for $573 billion, or 43% of the total.”
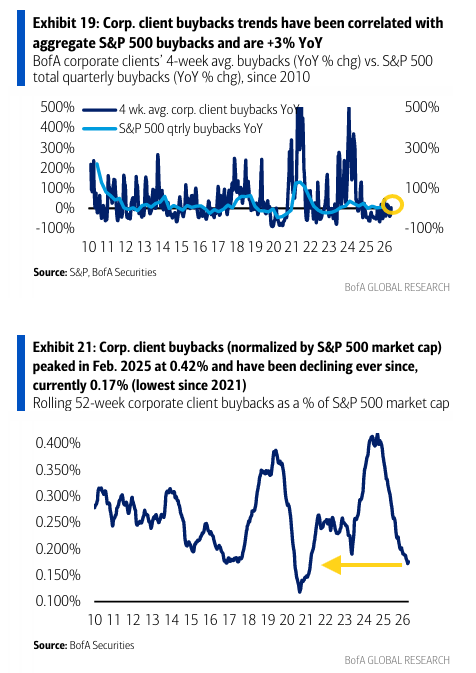
While BofA saw corporate client buybacks accelerate for a 2nd week last week, edging just above their seasonal average, a rarity this year. On a 4-week average basis they also moved to +3% vs the year earlier, the first positive read in a month, from -22% the prior week. Financials still lead the past 12 weeks at $7.1B, more than twice the next sector, Tech ($3.2B).
They said a month ago annualized cumulative buybacks YTD were tracking ~25% below 2025 levels and more than 40% below 2024 levels, though above 2010-23 annual levels. “Rolling 52-wk buybacks as a % of S&P 500 market cap are currently the lowest since Aug. 2021.”
Sentiment Turned Lower But Overall Far From Washed Out
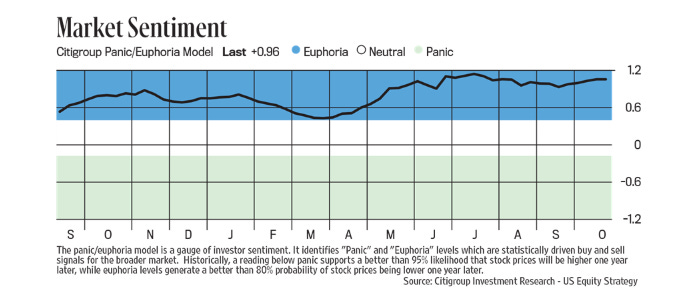
Sentiment (which I treat separately from positioning) is one of those things that is generally positive for equities when it’s above average but not extreme (“it takes bulls to have a bull market”, etc.), although it can stay at extreme levels for longer than people think, so really it’s most helpful when it’s at extreme lows (“washed out”).
Sentiment indices were more broadly week this week, but none hit extreme levels.
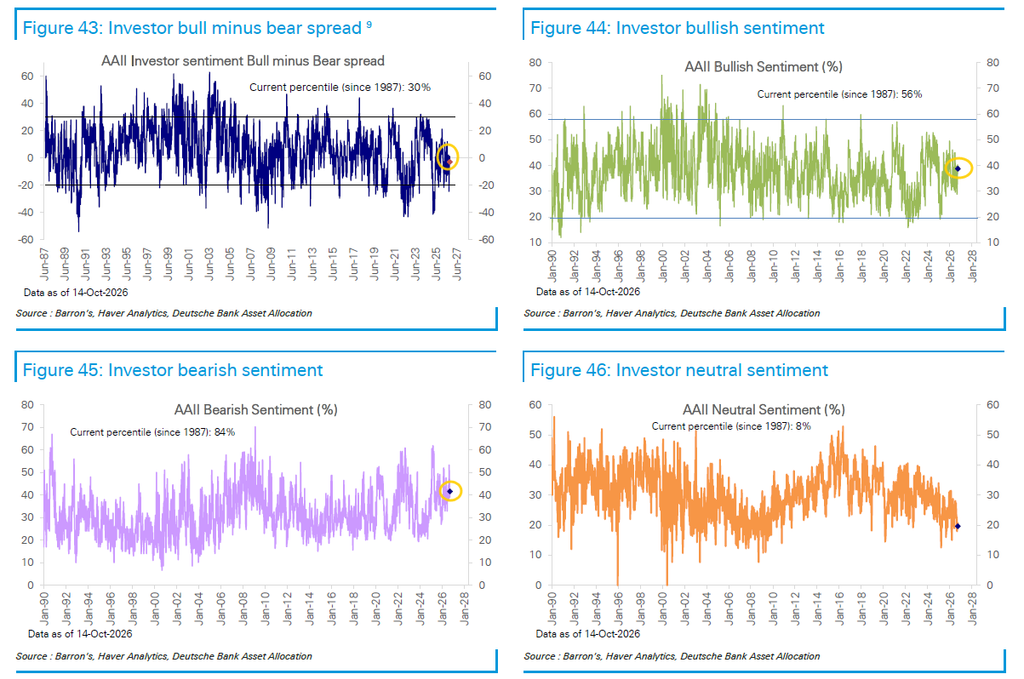
American Association of Individual Investors (AAII) sees Bulls slip back under Bears after just one week above:
AAII Bulls (those who see higher stock prices in 6 mths, blue line) eased to 38.7% from 40.3% (although still above the 28.8% four weeks ago, which was the least since September 2025), remaining above the long-term historic average of 37.5% for a second week.
Bulls though fell back below the level of the Bears (who see lower stock prices in 6 mths, red line) as the Bears rose to 41.6% from 39.1% the prior week (still well below the 53.3% four weeks ago, the highest since May 2025). That leaves Bulls above Bears just twice in the last 13 weeks. Bears still remain above the long-term average of 31.0% for a 35th straight week (and they’ve only been below it 9 weeks since Dec 12, 2024).
The Neutral camp (yellow line) dropped to 19.7% from 20.8%. It remains under the long-run average of 31.5% and has been over that only twice since July 2024.T
DB notes the bull-bear spread fell back to the 30th percentile to 1987 although still well above the 4th a month ago. Bearish sentiment remains high (84th percentile) although well off where we were at the end of September while bullish sentiment is at the 56th percentile.
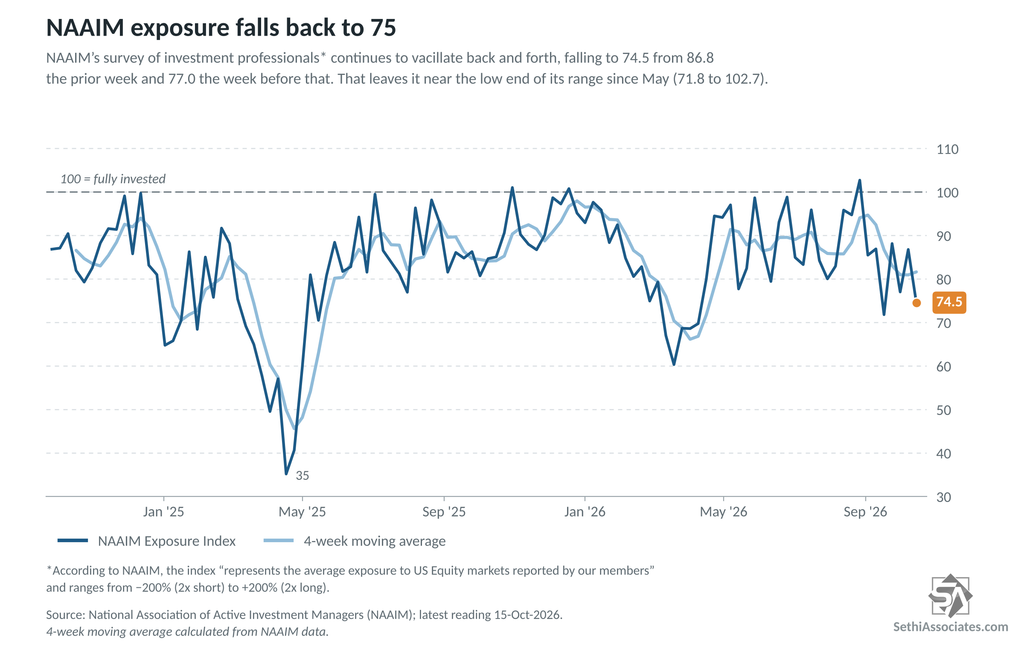
NAAIM’s survey of investment professionals* continues to vacillate back and forth, falling to 74.5 from 86.8 the prior week and 77.0 the week before that. That leaves it near the low end of its range since May (71.8 to 102.7).
*The index according to NAAIM “represents the average exposure to US Equity markets reported by our members” and which ranges from -200% (2x short) to +200% (2x long).
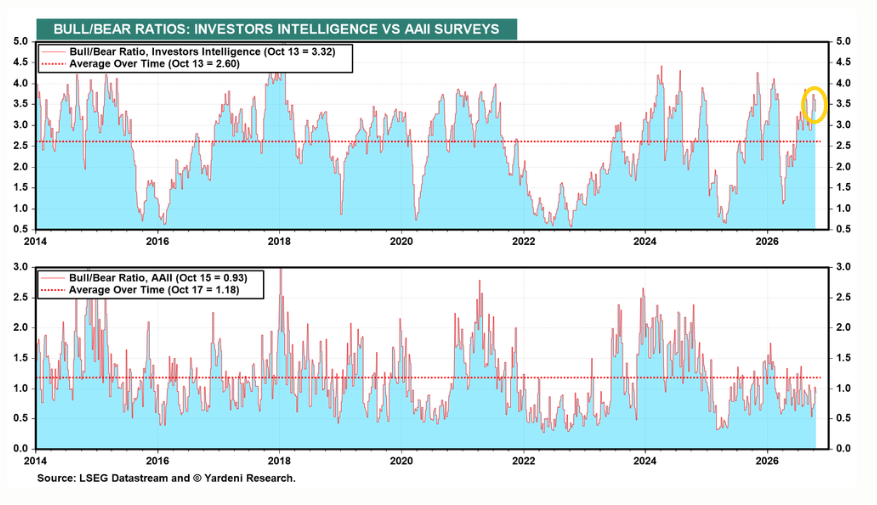
While the Investors Intelligence (independent investment-newsletter writers) survey saw the bull/bear ratio edge back for a second week to 3.32 from 3.75 two weeks ago, but still up from 2.88 four weeks ago and remaining above its average since 2008. Ed Yardeni says “The market letter writers have been more bullish than retail investors lately (chart). Odds are they will both be a bit more pessimistic this week.”
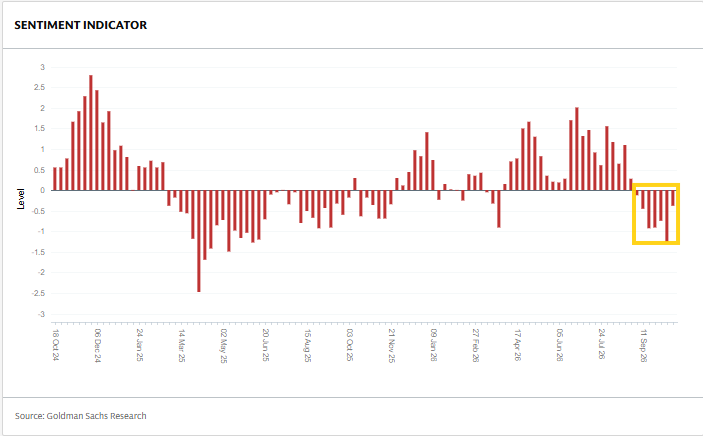
And Goldman’s US Equity Sentiment Indicator*, remained negative for a sixth week but at -0.37, the least negative since the first of those weeks.
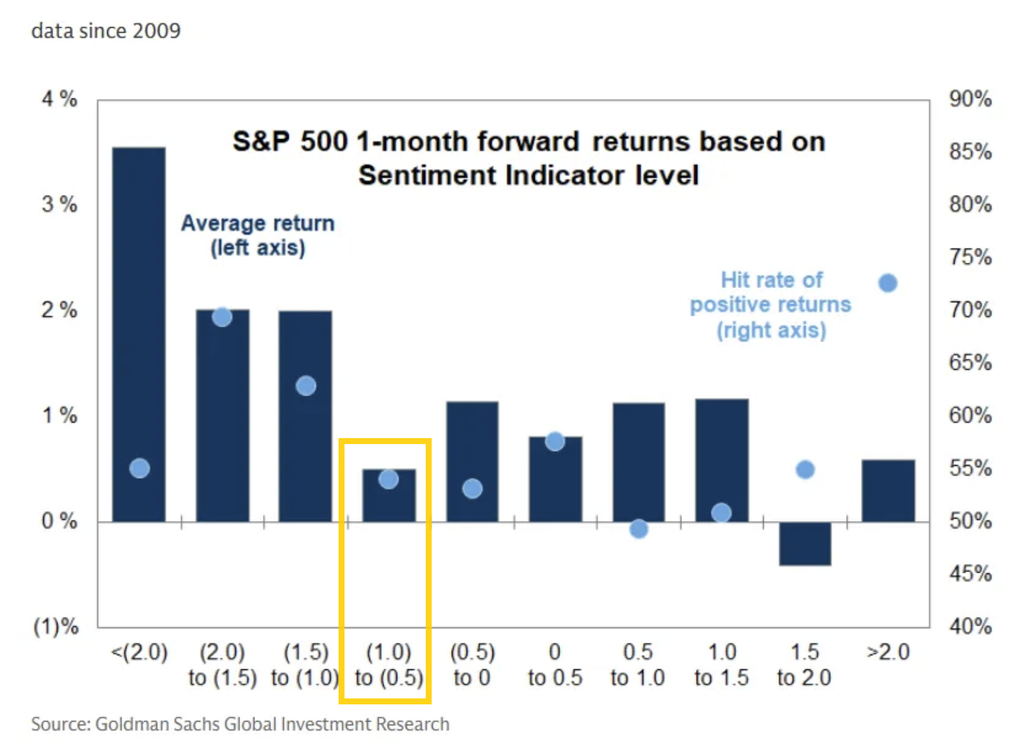
In that regard, the current reading is not a strong signal with a 1-month average return of around 0.4% since 2009 with a positive rate around 53%.
*The indicator combines “six weekly and three monthly indicators that span [across the more than 80% of the US equity market that is owned by institutional, retail and foreign investors]. Readings of +1.0 or higher have historically signaled stretched equity positioning. Readings of -1.0 or lower have signaled very light positioning and have historically been a statistically significant signal for subsequent S&P 500 performance”.
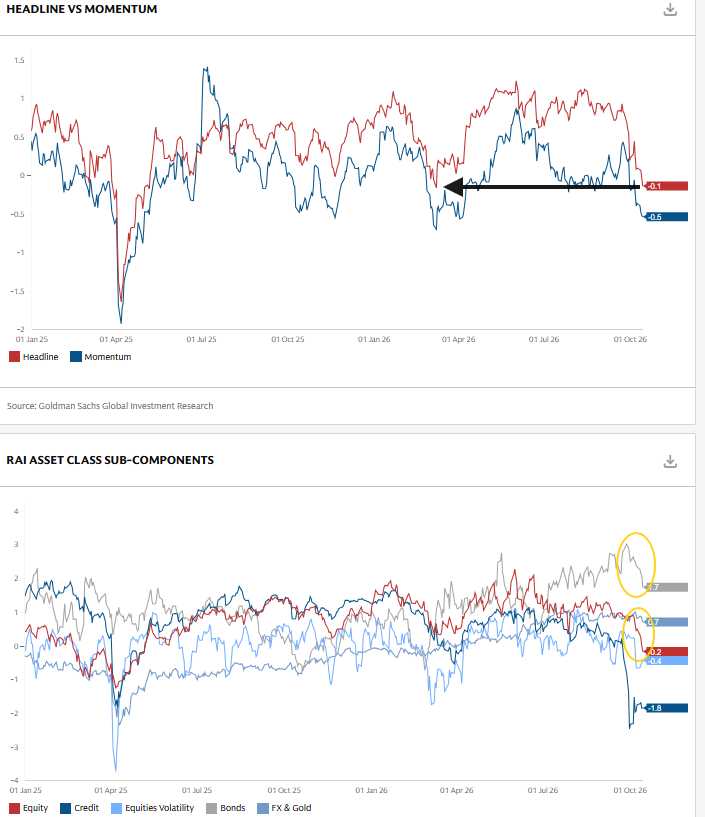
While Goldman’s Risk Appetite Indicator* fell for a third week now down to -0.1, the least since March, down from 0.8 three weeks ago, while the momentum index fell to -0.5, the least since April, this week’s decline led by drop in equities and strength in bonds.
*”Goldman Sachs Risk Appetite Indicator (RAI) aims to track the level of global market risk appetite and risk aversion based on various market variables. A sharp rise in the index can send a warning signal that investors have more risk appetite and are potentially exposed to a correction if consensus views are tested. Similarly, a sharp decline indicates a reduction in risk appetite, and at extreme levels it can indicate that markets may have overshot. RAI signals are most powerful when the level of risk appetite is very low below -1.5, with levels closer to -2.0 giving the clearest signal over longer time horizons, as at such levels the asymmetry of subsequent medium term equity return becomes very positively skewed. RAI momentum is designed to track short term shifts of market risk appetite, and subcomponents of the RAI.”
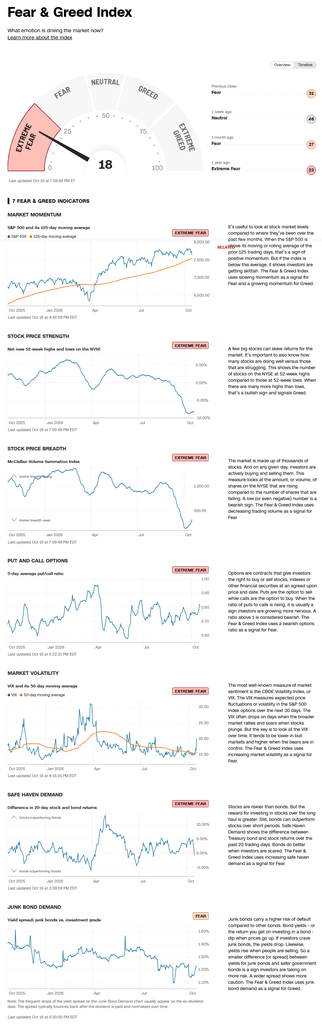
The CNN Fear & Greed Index (blue line) plummeted to 17.9, the least since April 1st, from 45.0 a week ago, falling into “Extreme Fear”.
Now no indicators above Neutral (from three last week) and all seven below (from three).
Extreme Greed = None
Greed = None
Neutral = None
Fear = junk bond demand (vs investment grade) (from Extreme Greed)
Extreme Fear = market momentum (SPX vs 125-DMA) (from Greed); stock price strength (net new 52-week highs); stock price breadth (McClellan Volume Summation Index); put/call options (5-day put/call ratio) (from Fear); market volatility (VIX & its 50-DMA) (from Neutral); safe haven demand (20-day difference in stock/bond returns) (from Greed)
And I noted in previous weeks if you have any questions on the indicator, TheStreet Pro’s own Jason Meshnick is your guy, as he helped create it.
BofA’s Hartnett (Flow Show) says this week the Bull & Bear sell signal has ended:
BofA Bull & Bear Indicator drops sharply from 8.1 to 7.4, driven by deteriorating global stock index breadth, bearish hedge fund positions in oil and S&P 500 futures, less bullish positioning in gold futures, and weaker HY [high-yield] and EM [emerging-market] debt flows, partially offset by stronger tech inflows; Bull & Bear Indicator drop below 8.0 ends ‘sell signal’ triggered May 26th.
The final score: BofA gives the signal a 2–3 month horizon with a 2-3% average decline and 15-20% max drawdown, but three months in (August 28) global stocks were up 3.3%. They finished the run “ACWI [global stocks] +1.1% (max drawdown -4.4%).”
Looking at the components, only fund-manager positioning still reads “very bullish,” at the 100th percentile. Hedge-fund positioning fell to neutral and breadth dropped 20 points. And BofA’s Breadth Rule shows a “net 52% of global equity market indices ‘oversold’ (trading below 50-day & 200-day moving averages) …most since Apr’25,” but a “‘buy signal’ for risk assets will be triggered if net 88% markets trading <50dma/200dma [below those averages]; near-term tough for this to happen unless ‘overbought’ US, Taiwan, Brazil equity indices fall 6%-10%.”
And Helene Meisler‘s followers lean bearish after two weeks of bullishness.
Seasonality Not Quite As Strong This Week But Good In Midterm Years
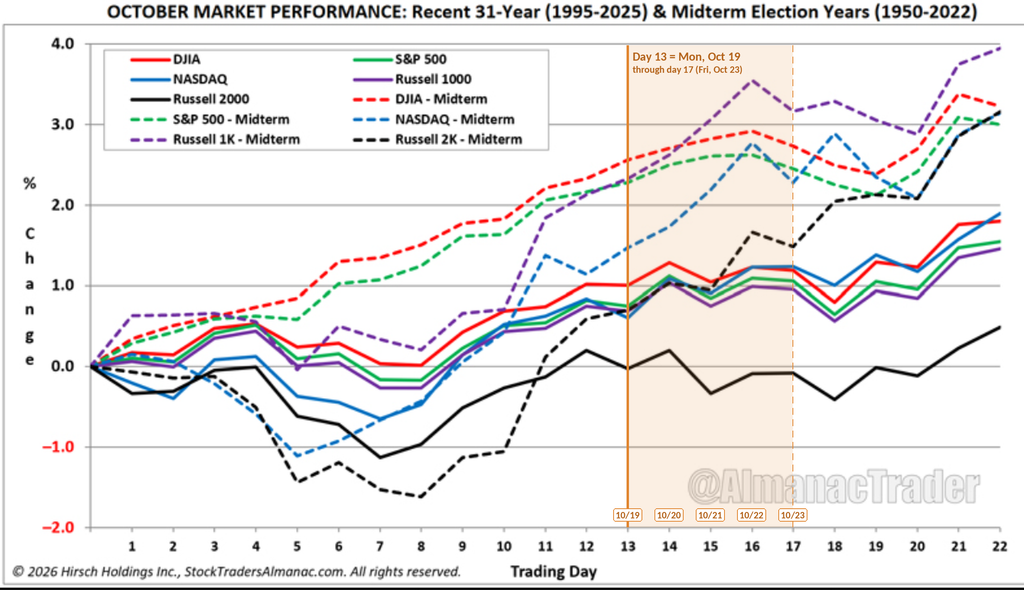
Looking at the seasonality breakdown from Jeff Hirsch, editor of the Stock Trader’s Almanac & Almanac Investor Newsletter, next week has historically been a pause in October’s rally, although midterm years have kept climbing.
Monday is trading day 13. Over the past 31 years the week has been choppy and little changed overall. The Dow, S&P 500 and Russell 1000 have edged up about 0.2%, the Nasdaq about 0.4%, and the Russell 2000 has slipped about 0.3%. Tuesday and Thursday have tended to be up and Wednesday down, with the Russell 2000 giving back about 0.5% on Wednesday alone. 2008 weighs on the average a bit. The S&P fell about 4% over these trading days that year, and without it the S&P’s average gain would be closer to 0.4%.
Midterm years have been stronger, and the Nasdaq and Russells with their shorter histories have again led. The Nasdaq has gained about 1.1%, the Russell 1000 about 1% and the Russell 2000 about 0.9%, while the Dow and S&P have added only 0.3–0.4%. The Russell 1000 and S&P are nearly the same index, so that gap reflects which years are averaged: the Russell data only start with the 1982 midterm, while the Dow and S&P go back to 1950. The gains have come Monday through Thursday. Every midterm line peaks on Thursday before a modest Friday giveback of about 0.2–0.4%.
From there, October has typically finished strong. Across all years, the following Monday (Oct. 26) has been one of the weaker days of the month, with the major indices down about 0.2–0.4%, but the final two sessions (Oct. 29–30) have more than made up for it. From Friday’s close through month-end, the indices have added about 0.5–0.65% across all years. In midterm years, the Dow and S&P have added about 0.5%, the Nasdaq and Russell 1000 about 0.8% and the Russell 2000 about 1.6%. Thursday, Oct. 29 has been the best single day of that stretch.
Wrap-Up – The Rotation Continues
I said on Friday:
“Tech continues along in its consolidation. I continue to expect it’s just that, but as I’ve mentioned all week, according to Deutsche Bank these tend to run several weeks. With that in mind I exited several more positions today that broke support levels. I want to hold off on any further takeaways until I’ve had a chance to go through all the metrics and read some weekend notes, particularly from DB given, as I also mentioned, they’ve called this year as well as anyone.”
Unfortunately, DB didn’t provide further updates on their thoughts on the pullback, but we did hear from another analyst who has pretty much nailed the twists and turns of the markets this year in Citadel’s Scott Rubner who also is looking for a “meaningful test” for equities ahead of an end-of-year rally:
We remain constructive on US equities into Q4, but the next several weeks will be a much more meaningful test of the fundamental backdrop. In our last note, October: The Q4 Reload, we focused on the reset in valuations and positioning, and the potential return of several of the market’s largest buyers. … After months dominated by macro headlines, positioning adjustments, and shifting AI narratives, earnings are returning to the center of the conversation. And with valuations reset, investor demand beginning to recover, and market leadership showing early signs of change, the setup heading into this reporting season looks considerably different than it did just a few months ago. … Our constructive Q4 view remains intact, with several of the dynamics highlighted in our last note beginning to materialize. We continue to favor selective single-stock exposure over simply adding index beta. The recent improvement in participation is promising, but the next several weeks will provide a much more meaningful test of whether it can persist.
And to add to that Goldman’s prime desk similarly said this weekend “We like buying SPXXAI [SPX Ex-AI]. The conditions that justified the concentration in AI are now showing meaningful cracks, and we see an attractive entry point to rotate into the broader, non-AI market.“
They note
-When the marginal cost of capital for AI infrastructure rises, it tends to compress the growth assumptions embedded in related equity valuations. -Recent export figures out of China point to accelerating hardware exports from China into the rest of the world, threatening the bottleneck thesis in US hardware. China is exporting ~36% more hardware vs one year ago. -Stickier inflation, a tightening policy bias, and cooling consumption point to a macro backdrop that is increasingly unfriendly to long-duration, capex-heavy growth narratives, adding a further headwind to the AI trade specifically (as distinct from the broader index).
All the negativity has my contrarian impulses on high alert (I have traditionally liked to go against the grain), but I have a tough time going against both DB and Rubner, and the Goldman prime desk are no dummies. So for now, I will maintain my cautious stance on the Tech trade while being more aggressive with stocks outside of the Tech area which I have increasingly been doing the past couple of weeks as chart setups germinate.
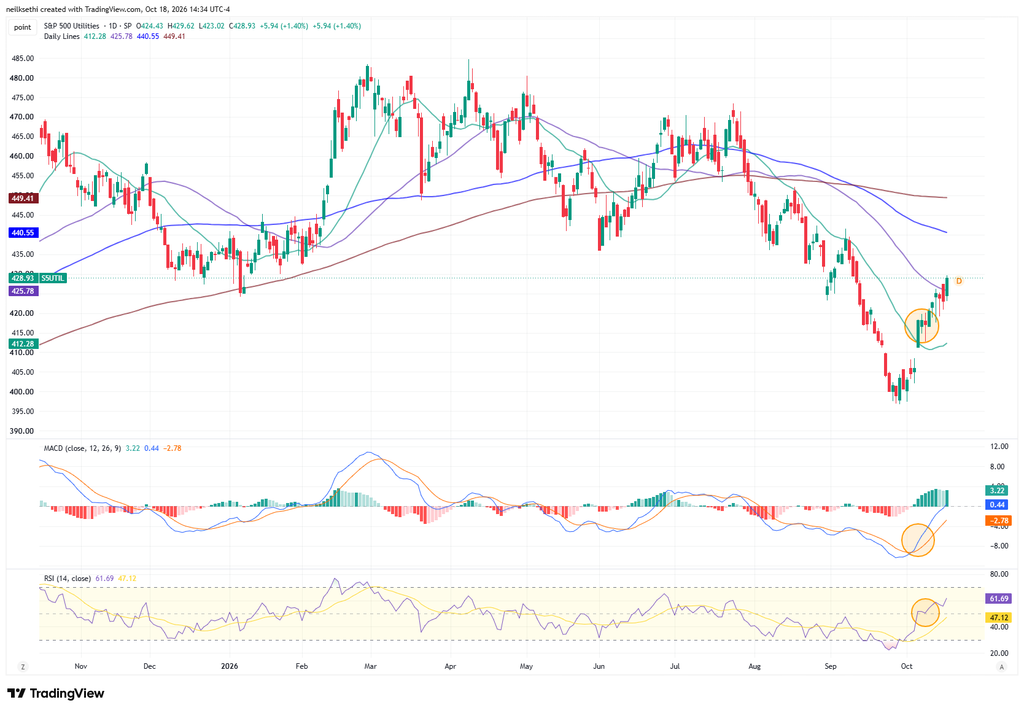
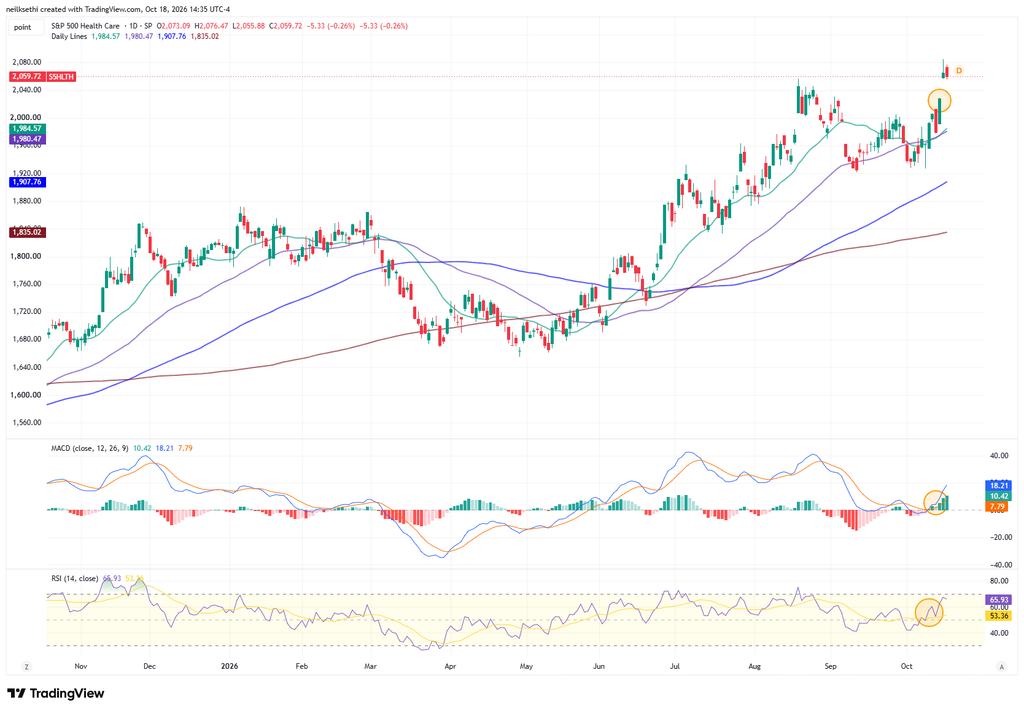
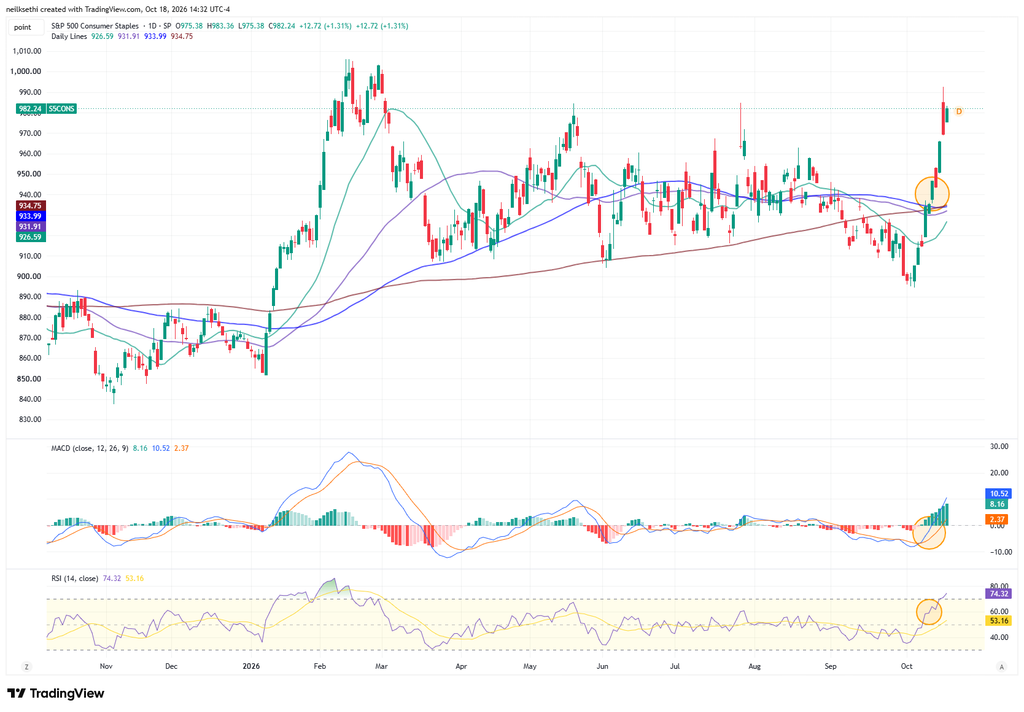
I noted this week charts on many Tech leaders showing them breaking support with negative MACD crossovers and falling RSIs. We see the exact opposite in things like Utilities
and Health Care
and Staples, although in this last case it is more extended so I’d wait for a pullback, but I circled where it hit the simultaneous breakout in price and technicals.
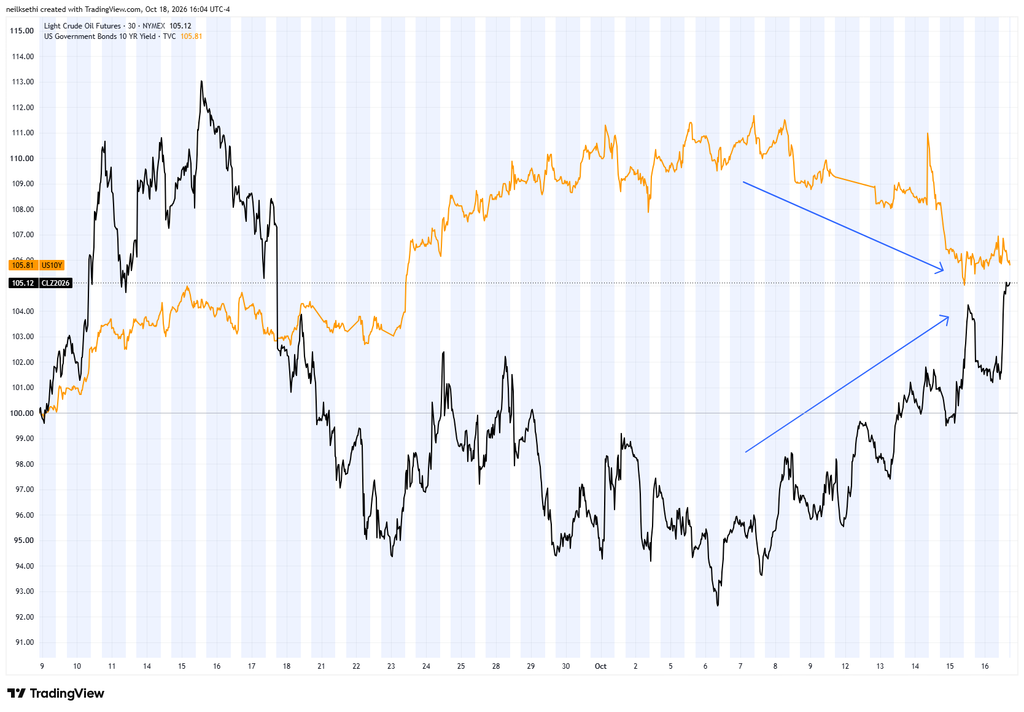
And we still haven’t seen much short-covering in bonds which would add fuel to the rotation. But of course any push higher in yields could just as easily stall it out. And so far the drop in yields has come as oil prices have risen 10%. You have to wonder how long that can continue.
But longer term I continue to be optimistic (as notably do DB, Rubner, etc.), particularly given the cleanout in discretionary stock positioning. In a couple of weeks buybacks will start to re-engage and seasonality continues to be strong. The economy seems in good shape, and now we have more stocks with momentum until Tech gets back on track.
Although I would be remiss not to note that a rebound in Tech may come along with a rebound in bond yields given the tie between the two identified earlier. So AI worries are doing double duty: weighing on Tech while pulling yields lower despite hot inflation, fueling leadership in rate-sensitive and defensive sectors like Utilities, Health Care and Staples.
In the hear and now, we have to navigate these next two weeks of increasingly heavy earnings days, and technicals on the large market-cap weighted indices are a definite concern. The good news is gamma remains positive which should, at least initially, cushion downside. Even so, a 5–10% correction would be completely normal.
Next week the catalysts are almost all earnings, and the Tech names in the mix — Meta, Tesla, Lam Research, Texas Instruments and IBM — will shed some light on whether Tech’s pullback is just a consolidation or something bigger. With the Fed in its blackout and US economic data light, markets will be freer to sort that out on their own.
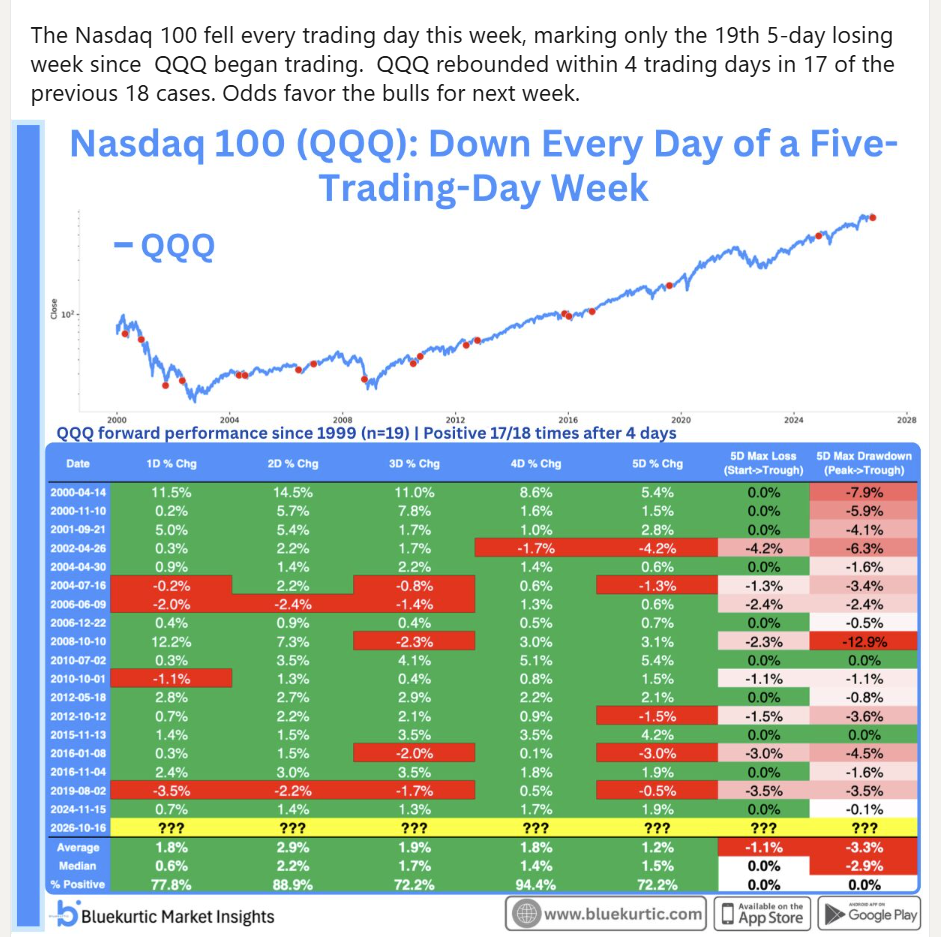
And for the contrarian in me, there’s also this: the Nasdaq-100 fell every day last week, and in 17 of the previous 18 cases it rebounded within four days.
At the time of publication, Sethi was long META, T, SPY, RSP, CPER, was short WDC and had no positions in the other securities mentioned in this article.