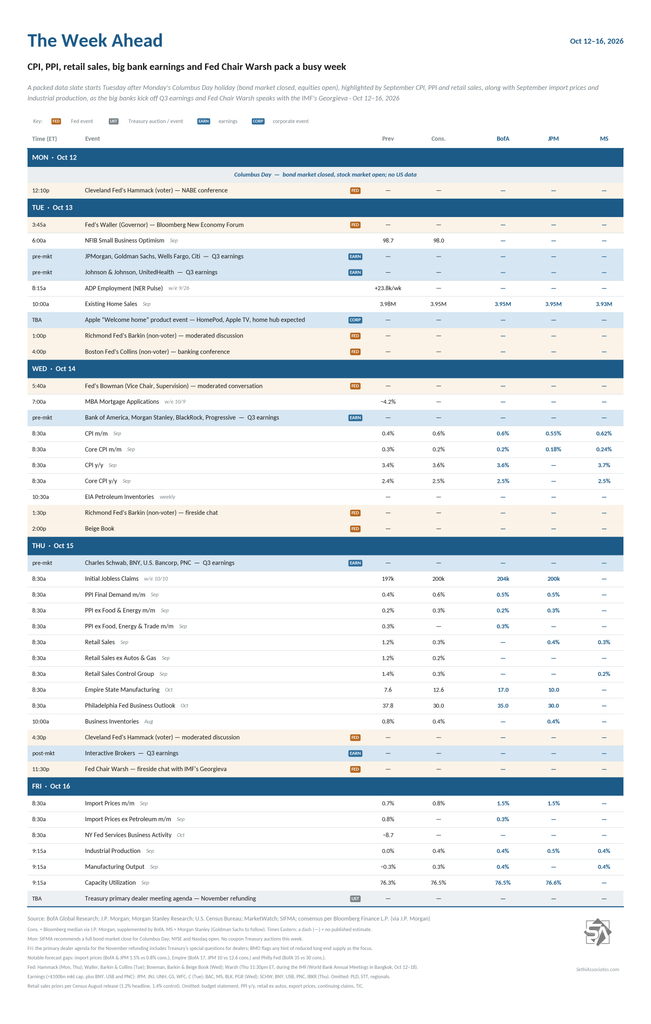
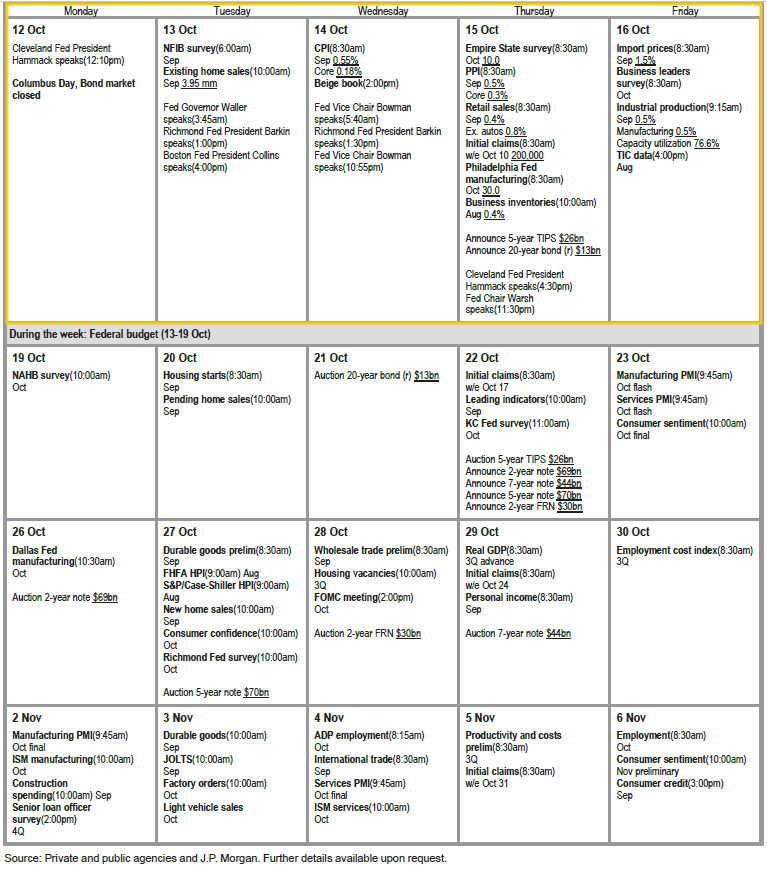
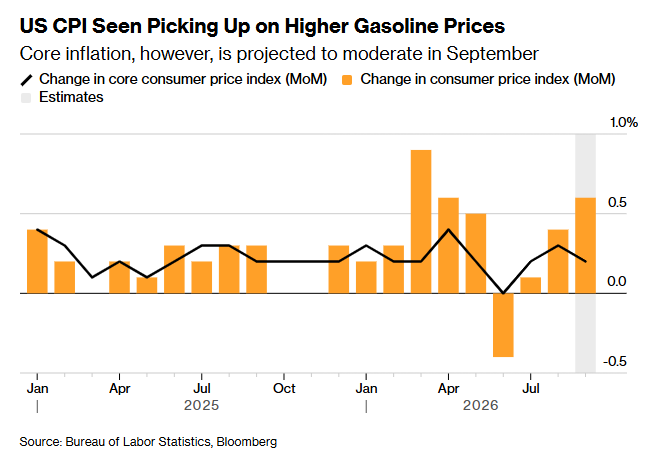
U.S. economic data is heavy next week after we get past Monday’s Columbus Day holiday (bond market closed, but equities open), highlighted by the September CPI report Wednesday and September PPI and retail sales Thursday. Other reports next week include September NFIB small business optimism, existing home sales, import prices, industrial production and the monthly Treasury budget statement, August business inventories and TIC flows, a few regional Fed PMIs plus the normal weekly reports (ADP, MBA mortgage applications, unemployment claims, etc.).
Fed speakers stay busy in the last week before the blackout period ahead of the October 27–28 FOMC meeting, headlined by Fed Chair Warsh, who holds a fireside chat with IMF Managing Director Kristalina Georgieva late Thursday night (Friday morning in Bangkok, where the IMF/World Bank Annual Meetings are being held). We’ll also hear from Governors Waller and Bowman and regional Fed presidents Hammack, Barkin and Collins, with Hammack and Barkin each speaking twice. All of them we’ve heard from in the past two weeks. Wednesday afternoon also brings the Fed’s Beige Book, an anecdotal read on conditions across the 12 Fed districts that’s prepared for the upcoming FOMC meeting. Given how much regional Fed presidents rely on such anecdotes, it’s more important than many think.
No non-Bill (>1yr in maturity) U.S. Treasury auctions next week. But what we will get on Friday is the Treasury primary dealer meeting agenda for the November refunding, flagged by BMO’s Ian Lyngan. As he notes, that will include the special questions Treasury will be asking the dealer community. Focus will be on anything hinting at what is expected to be reduced long-end supply.
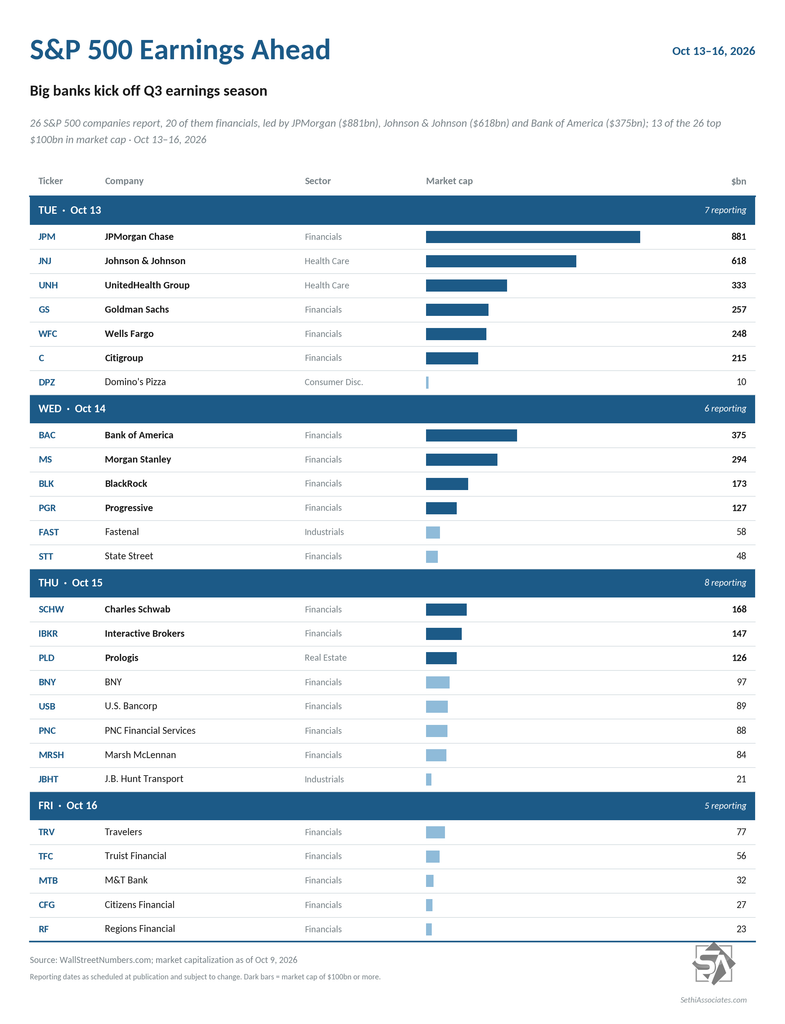
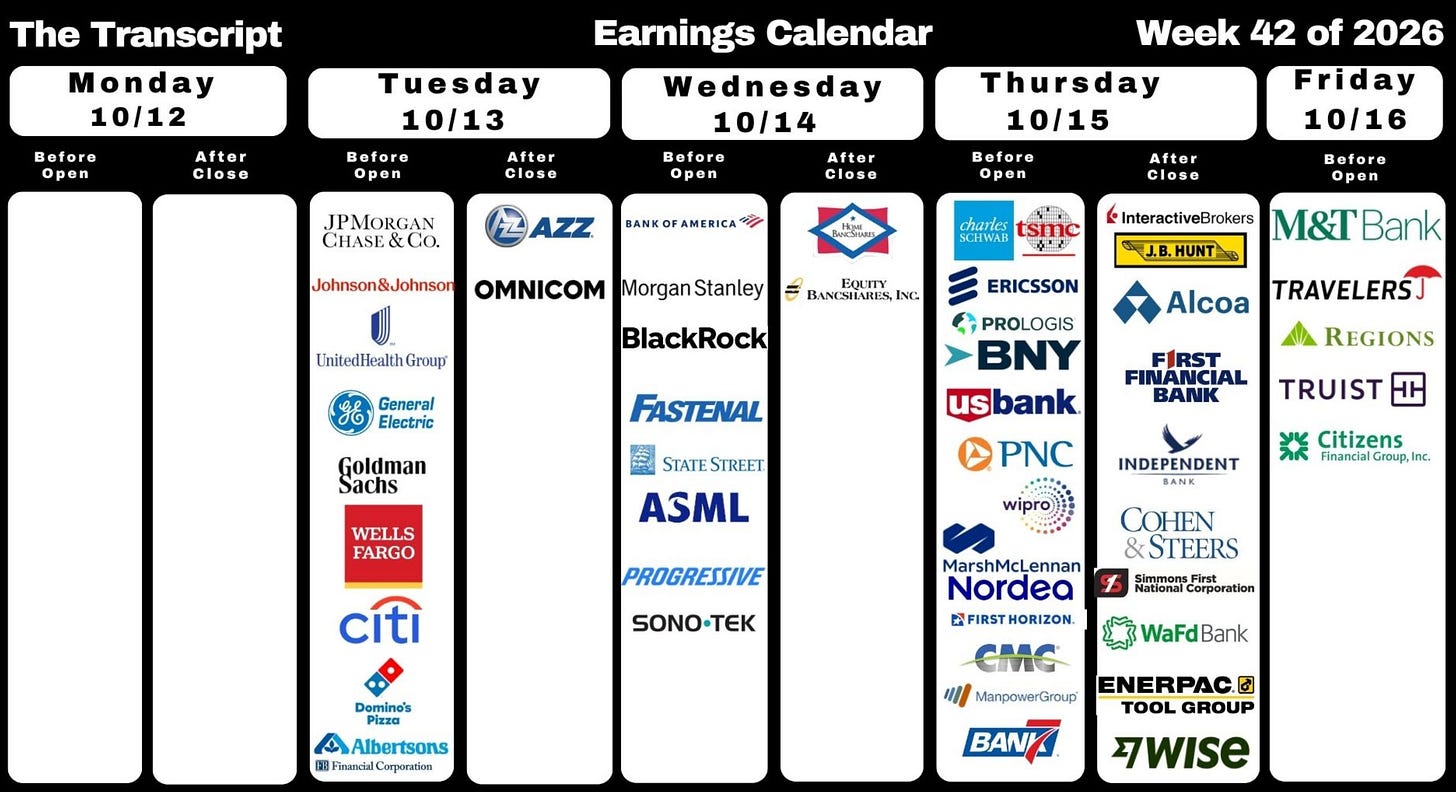
And Q3 earnings season unofficially kicks off Tuesday with the big banks: JPMorgan (JPM), Goldman Sachs (GS), Wells Fargo (WFC) and Citigroup (C) report, along with Johnson & Johnson (JNJ) and UnitedHealth (UNH). Bank of America (BAC), Morgan Stanley (MS), BlackRock (BLK) and Progressive (PGR) follow Wednesday. Charles Schwab (SCHW), BNY (BNY), U.S. Bancorp (USB), PNC (PNC) and Interactive Brokers (IBKR) report Thursday. Outside of the S&P 500 investors will parse results from ASML (ASML) on Wednesday and Taiwan Semiconductor Manufacturing Co. (TSM) on Thursday for signals about the state of AI spending.
In other corporate events, Apple (AAPL) holds its “Welcome home” product event Tuesday. As Chris Versace previewed: “As that [title] suggests, Apple will showcase several new Home products, including refreshed HomePods and Apple TV devices, most likely with Siri AI added. Of greater interest will be the company’s expected HomePad and related connected home product that include a doorbell, thermostat, smart deadbolt lock, and indoor and outdoor security cameras. Those products would challenge Alphabet’s (GOOGL) Nest and other connected device vendors.”
Ex-US highlights from Deutsche Bank:
A busy week for central bank speakers lies ahead, with the IMF and World Bank meetings taking place in Bangkok on October 12–18. The IMF will release its latest World Economic Outlook on Tuesday, while G20 finance ministers and central bank governors will meet on the sidelines on Thursday.
In Europe, the main economic release will be the UK’s August monthly GDP report on Thursday. Following an upside surprise in July, our UK economists expect GDP to be unchanged month over month. Other regional releases include Denmark’s September CPI on Monday. On the political calendar, the European Council’s two-day meeting begins on Thursday.
In Asia, China will release September CPI, PPI, and trade data on Wednesday. Japan’s calendar includes September PPI and bank lending on Tuesday, followed by August core machinery orders on Thursday.
This post will go through in order (in case you want to skip around): the economy, the Fed and interest rates, earnings, valuations, breadth, positioning, sentiment, seasonality, and then my wrap-up.
The Economy Continues To Grow Above Trend
Looking first at the economy, my intro has remained the same since the start of the Iran conflict (and longer term, more or less all of the past five years): “we continue to see it weathering the various storms remarkably well due in large part to resilient consumption (boosted by huge increases in wealth over the past few years despite slowing incomes) and AI-spending… with data of late showing a stable (and perhaps accelerating) economy, but one that is also boosting inflation.”
As noted previously, while things tailed off in July into the start of August, since then we have seen economic momentum rebound outside of the housing sector although as mentioned last week we did see nonfarm payroll growth stall out (which though may simply be a function of a harsh seasonal adjustment) and the relatively weak personal income figure.
Last week was light on data:
The services PMIs saw the S&P’s rise to the strongest since July 2021 with new orders at a 4.5-year high while the ISM eased but marked a 27th straight month of expansion with the 12-month average rising for a ninth straight month. Prices though were elevated in both surveys with the ISM seeing them rise the most since July 2022.
The trade deficit came in the largest since March 2025 (which we knew was coming from the advance look at the goods deficit I talked about last week) but overall remained consistent with a strong economy as capital goods imports hit a record on the back of AI investment (a record monthly jump in semiconductor imports).
The consumer credit data saw revolving balances (credit cards) drop the most since November 2024, while nonrevolving credit (student loan + autos) climbed to a record high.
The NY Fed consumer survey saw inflation expectations rise but so did those for employment, incomes, and spending, although sentiment on finances deteriorated.
As I mentioned last week, “the most concerning item on the list to me at this point is wage growth, but so far that hasn’t dented consumer spending with the large gains in wealth from stock and home prices.”
And as I said six weeks ago “with the recent strength it seems that we’re back in green light territory, and one or two rate hikes (or 5% Treasury yields) won’t change that.”
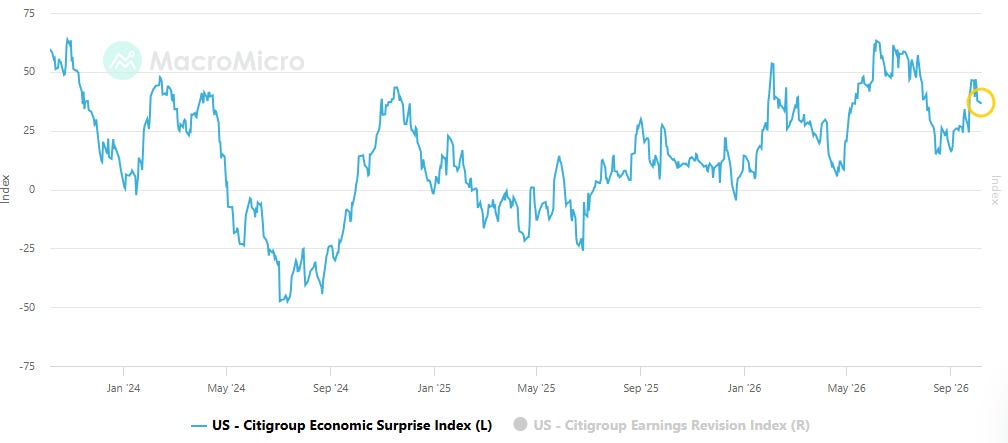
With the light data week the Citi economic surprise index was little changed at 36.1, down a touch from 37.7 the prior week (and 46.5 the week before that which was the best since the end of July).
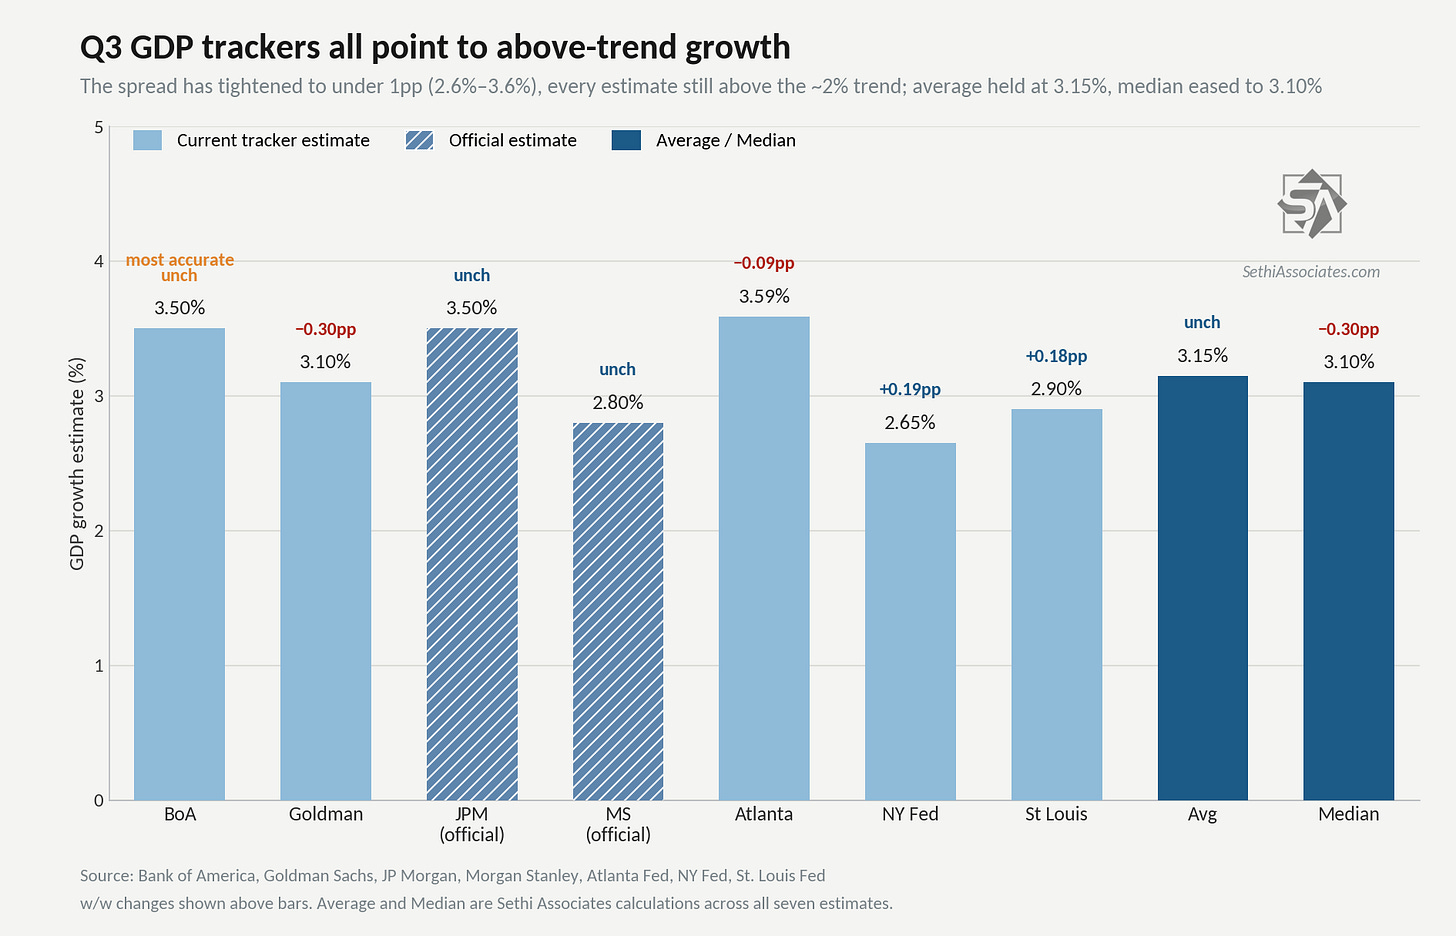
And Q3 GDP estimates were also little changed, with the average unchanged at +3.15%, though the median slipped to +3.10%, still above-trend growth.
BofA (who has been the most accurate over the past year) +3.5% (+3.5% the prior week). Goldman +3.1% (from +3.4%) JPM +3.5% (+3.5%) Morgan Stanley +2.8% (+2.8%) Atlanta Fed +3.59% (from +3.68%) NY Fed +2.65% (+2.46%) St Louis Fed +2.90% (+2.72%) Avg = +3.15% (from +3.15%) Median = +3.10% (from +3.40%)
And JPM’s Feroli remains upbeat about global growth and employment as well:
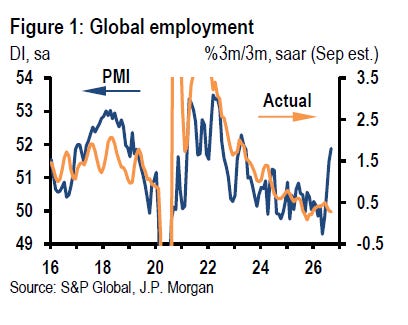
In a relatively quiet week for economic data, business surveys provided the main news. Their message is positive, pointing to continued cyclical momentum this quarter. Following last week’s further jump in September’s global manufacturing output PMI to a five-year high, the services component also strengthened this week. Together, these gains lifted the global composite PMI by nearly a point to its highest level in four years, consistent with global GDP growth of roughly 3.3% at an annualized rate.
…
Perhaps the most important development in this week’s PMI data is the labor-market signal. As we expected, the global employment PMI strengthened further and is now up more than three points since May—the largest four-month increase outside recession rebounds in the survey’s history (Figure 1). The global measure is consistent with employment growth near a 2% annualized pace, well above our already constructive forecast for a pickup to 1%.
This signal supports our view that the recent disappointments in observed labor demand in the US and euro area, along with this week’s reported decline in Canada, should not be taken as evidence of a sustained weakening trend.
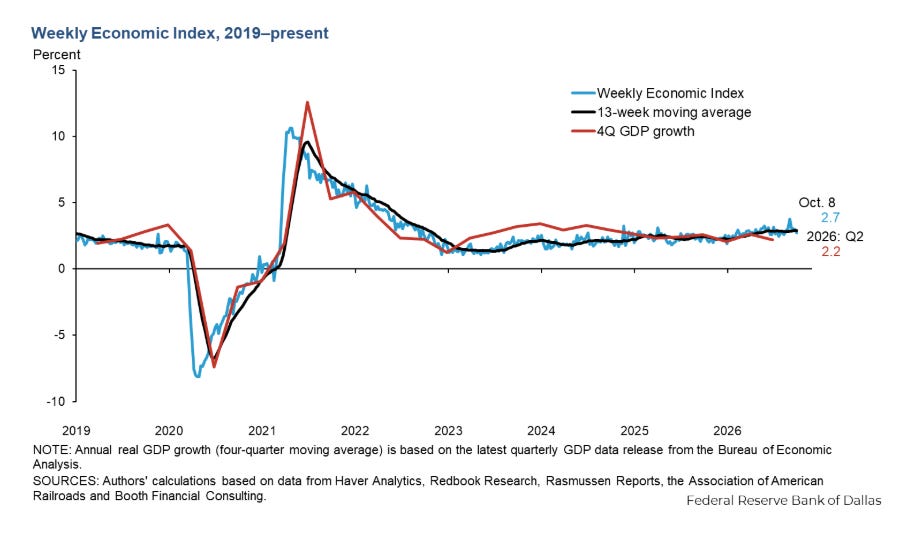
And as you know if you’re a regular reader, one of my favorite GDP trackers is theWeekly Economic Indexfrom the Dallas Fed.*
In the week through October 3rd (so doesn’t have last week’s data) it fell back to +2.71%, from +2.97% the prior week, which had ended a four-week run above 3%, its longest since 2022.
The 13-week average also decelerated to 2.88% from 2.91%, also the best since 2022, still continuing to evidence economic momentum that is above trend.
*The WEI is scaled as a y/y rise for real GDP(so different than most GDP trackers which are Q/Q SAAR) and uses 10 daily and weekly economic series but runs a week behind other GDP trackers.
It has over time had one of the highest correlations with actual GDP of any tracker(see chart)although for Q2 it came in highpredicting +2.80% y/y GDP growth vs the actual first estimate of +2.10%, while for Q1 it predicted +2.48% vs 2.66%. More importantly, it has consistently indicated no recession and relatively healthy growth since the pandemic (which is what we’ve experienced).
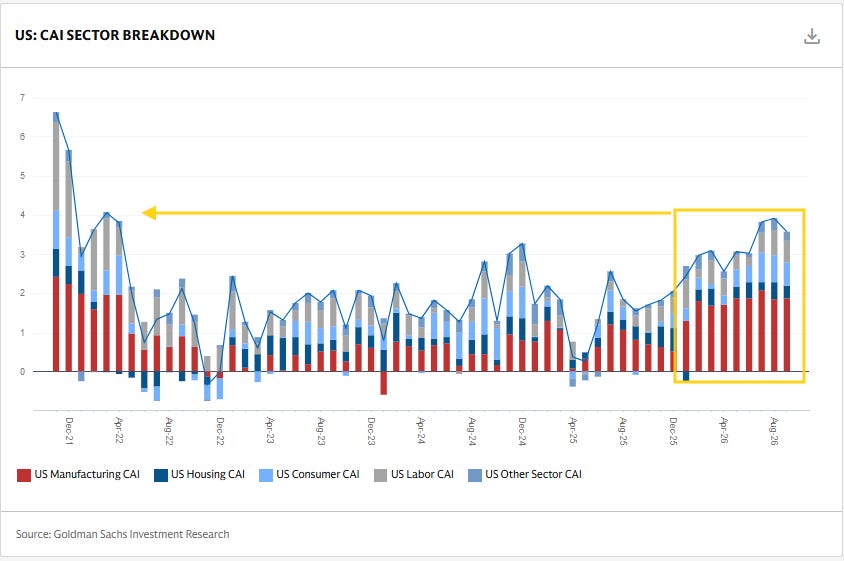
But Goldman upgraded their September US Current Activity Indicator* a tenth to +3.6%, and revised August up to +3.9% making that the best since April 2022. That further confirms the strongest nine-month period since then.
*The CAI is their “real-time measure of inflation-adjusted economic momentum using 37 inputs.”
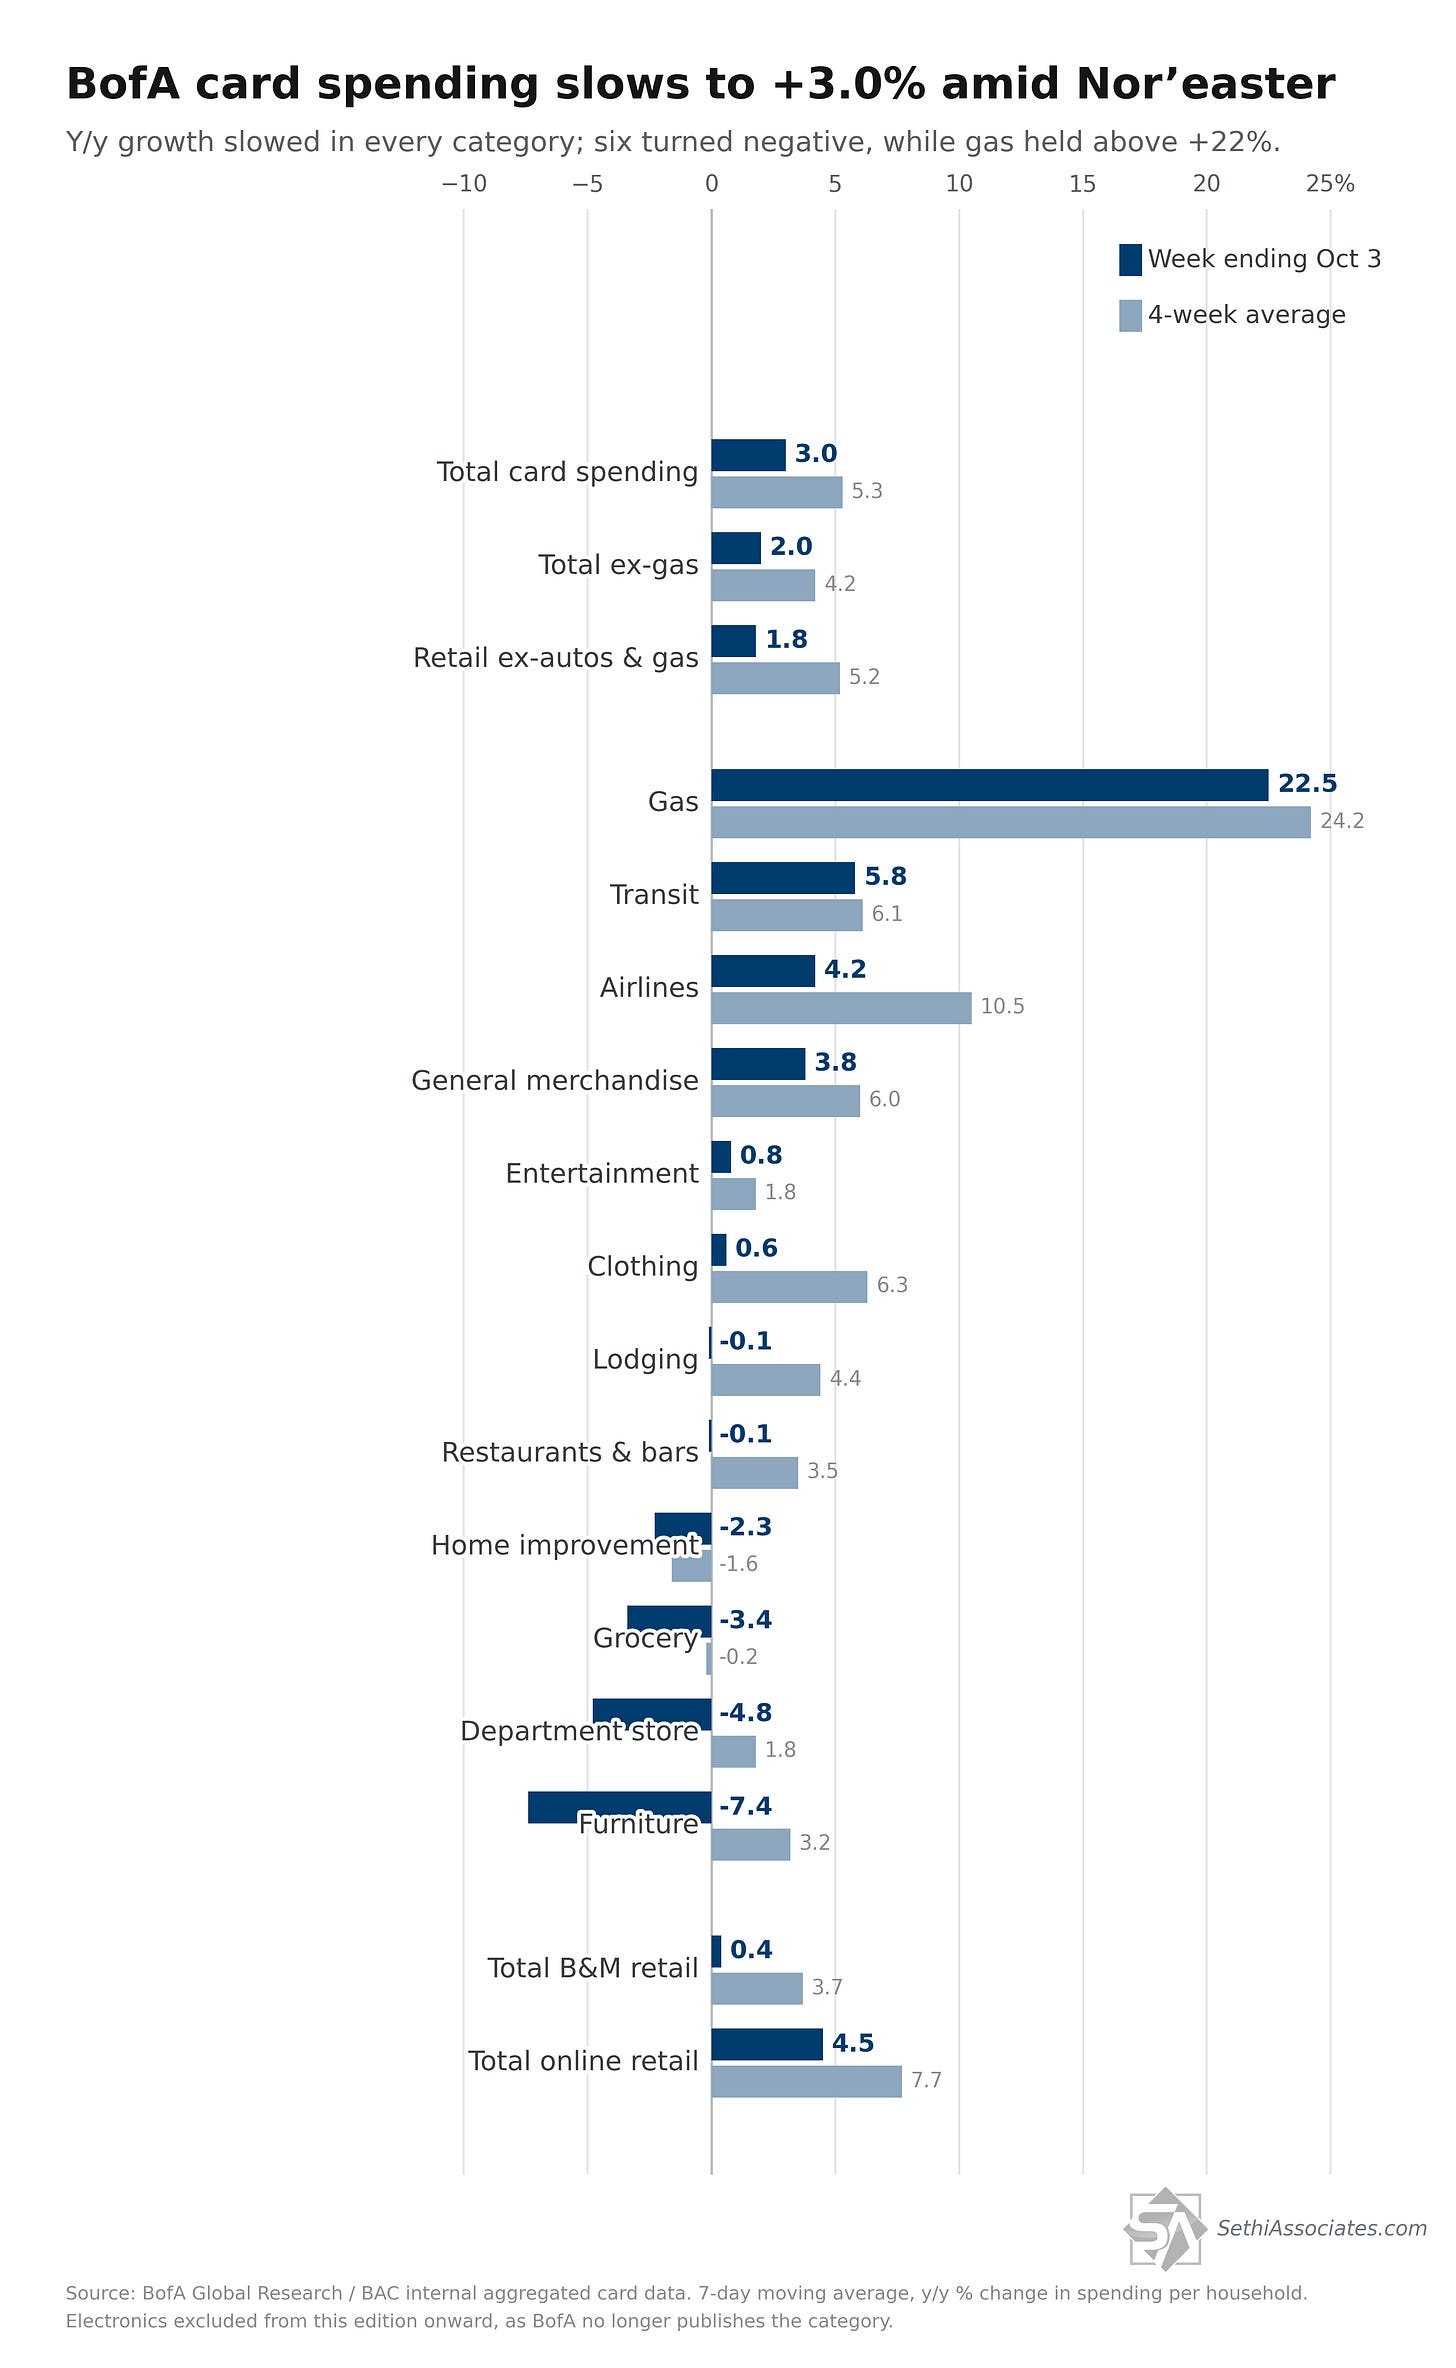
But BofA card spending (credit+debit) slowed sharply to +3.0% versus the year-ago period (y/y) in the week ending October 3rd, down from +5.6% the prior week and excluding gasoline and autos slowed to +1.8% y/y from +5.3%. BofA still called the result healthy and said the Nor’easter likely contributed to the broad-based moderation.
Ex-autos and gasoline +1.8% y/y (+5.2% four-week moving average)
The moderation was about as broad as it gets: y/y growth slowed week over week in every category BofA tracks. On the income split, BofA noted that lower-income spending growth continued to outpace higher-income.
Gasoline eased to +22.5% y/y (from +26.6%) but remained elevated versus a year earlier.
Among categories, beyond gas, only transit (+5.8%), airlines (+4.2%, down sharply from +13.1%) and general merchandise (+3.8%) held meaningfully positive. Entertainment (+0.8%) and clothing (+0.6%, from +6.2%) were barely above zero.
Six categories were negative y/y (vs just one the prior week): furniture (−7.4%), department stores (−4.8%, from +2.4%), grocery (−3.4%), home improvement (−2.3%), and lodging and restaurants & bars (both −0.1%).
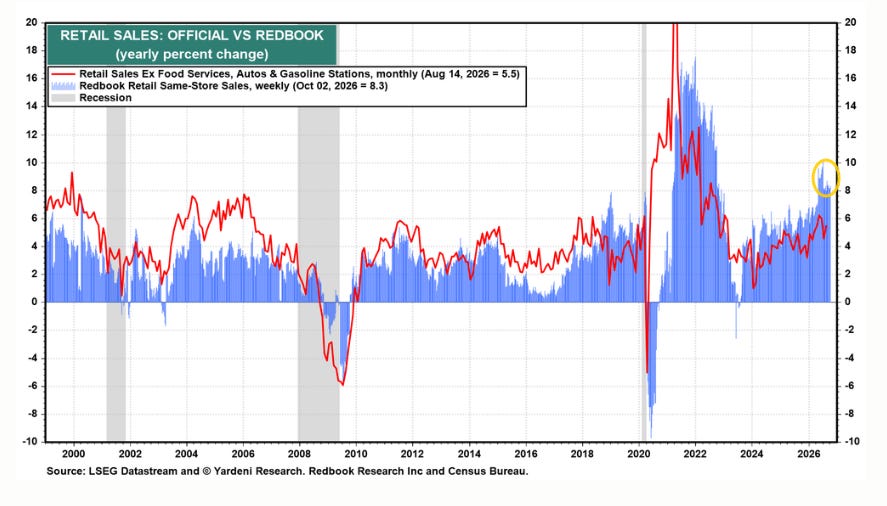
Redbook sales*in the week of October 2nd accelerated to +8.3% y/y growth, continuing to sit well above the 2025 average of +5.8% y/y “and underscoring the consumer’s continued resilience” (Ed Yardeni).
*Redbook sales are same-store sales across a panel of large general-merchandise retailers, such as department stores, discount chains, apparel retailers, drugstores, and warehouse clubs.
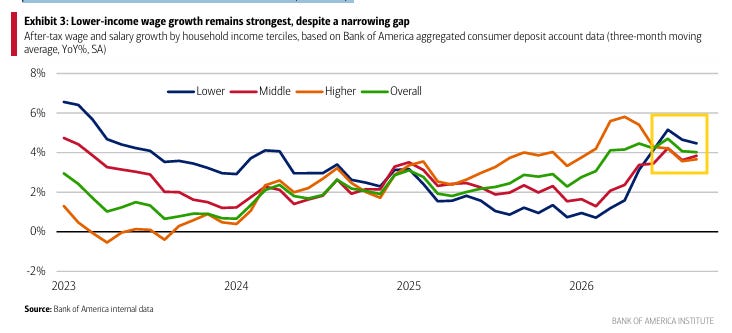
And BofA’s Institute continued to see “lower-income households [with] faster after-tax wage growth than other cohorts, a notable turnaround from the ‘K-shaped’ pattern we observed over much of 2025 and 2026. Lower-income wage growth eased to 4.5% YoY in September from 4.7% YoY in August, while wage growth for middle- and higher-income households rose to 3.8% and 3.7% YoY, respectively. Overall, these changes were modest.”
October Skip, December Hike, 2027?
Turning to interest rates and the Fed, I had noted last week that “the center had spoken”:
we saw two key Fed members come out Tuesday (NY Fed President Williams) and Thursday (Vice-Chair Jefferson) making it clear that the core of the Fed (which is comprised of typically the Chair, Vice-Chair and NY Fed President and also almost certainly includes Powell, so a third of the FOMC) sees “no need for urgency” for a rate hike.
It would be highly unusual for two such high profile Fed members to give such a speech without having cleared it with the Chair. In fact, I think it is not unlikely that they did it in close coordination to try to bring down the market probabilities on an October hike which had exceeded 70%.
That was further confirmed by leading voice Governor Waller (who while not a part of the “core” of the Fed discussed above, has been a leading voice — freer to say where his head is at, often putting him out in front of where the FOMC is headed.
As I mentioned in the Thursday update Waller said “I anticipate additional hikes to support a timelier return of inflation to our 2 percent goal. But there is some flexibility about when those hikes will occur. The hikes do not need to come at consecutive meetings, but they should be in place in an acceptable period of time.” This further confirmed October is off the table, but December is highly likely. See the Thursday report link above for more on Waller’s comments.
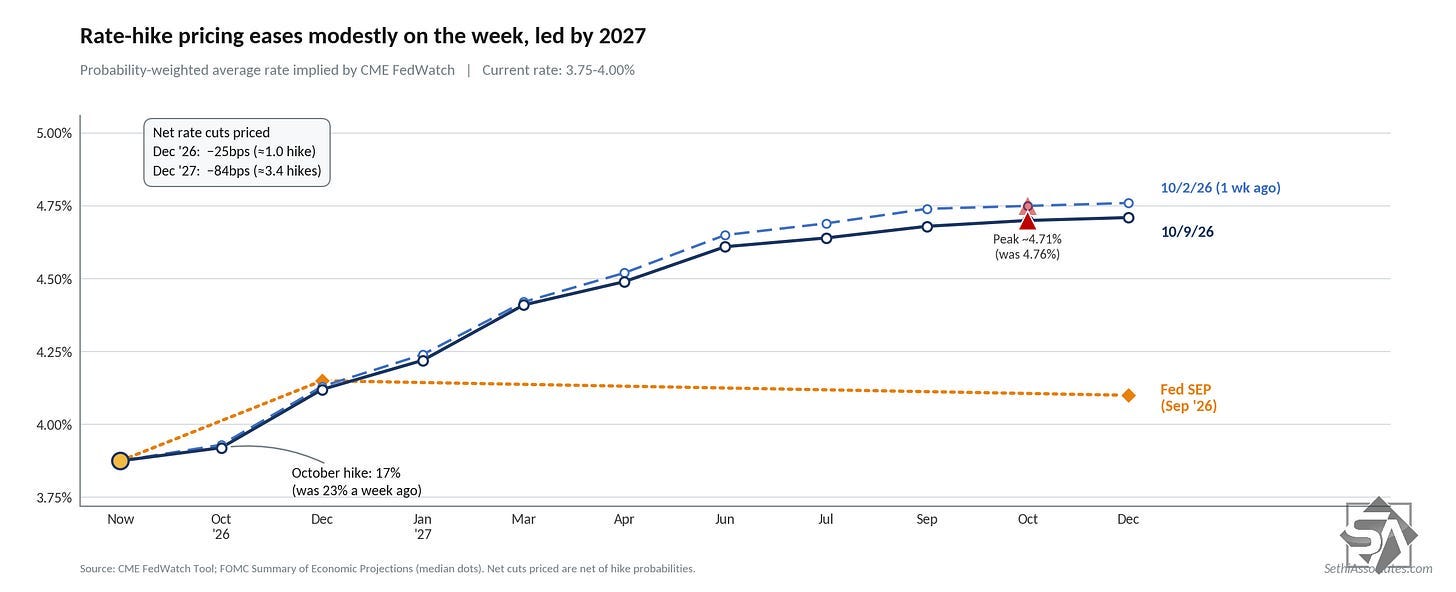
And following Waller market expectations moved further in that direction with just an 17% chance of an October hike but 85% chance of a December hike. For now markets still price in two more hikes in 2027, but that is a lot less certain than I think is pause-and-hike this year.
Still as I wrote last week:
while I thought 70% was a bit high for pricing an October hike, I similarly think 23% [now 18%] may be a bit lowwith September CPI and PPI still ahead. Hot prints on those may very well swing the committee. That is also the view of MS’ Gapen:
While we read this week’s incoming data and Fed speak as pointing toward a measured pace of policy re-calibration, things can still change. The upcoming September CPI report is more important in our eyes than the revisions to PCE inflation and September employment. A hot reading could change the calculus for the Fed.
As well as JPM’s Feroli:
We continue to look for the next hike in December, though it’s still possible that a firm set of September inflation reports could tilt the risks back toward an October hike.
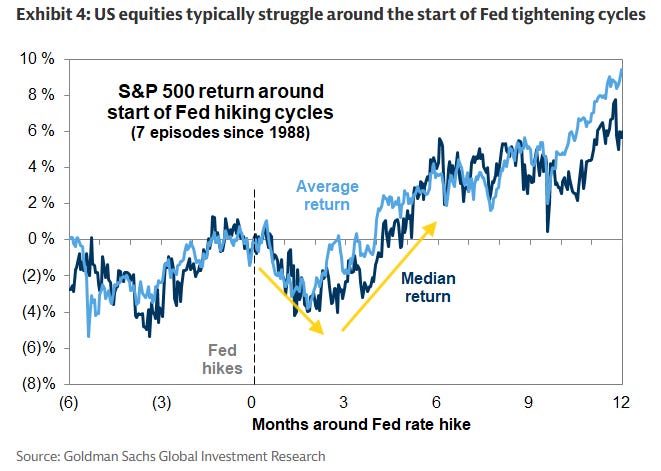
And while historically there has been equity weakness following the start of a hiking cycle — average return according to Goldman is -2% in the three months after (see below) — we’re instead +3% at this point (less than a month later):
Goldman:The S&P 500 has generated an average 3-month return of -2% at the start of seven hiking cycles during the last few decades. However, the S&P 500 then generated an average 12-month return of +9%, with positive returns in every episode but 2022. In 1997, for example, the S&P 500 declined by 10% alongside the Fed’s 25 bp hiking “cycle.”
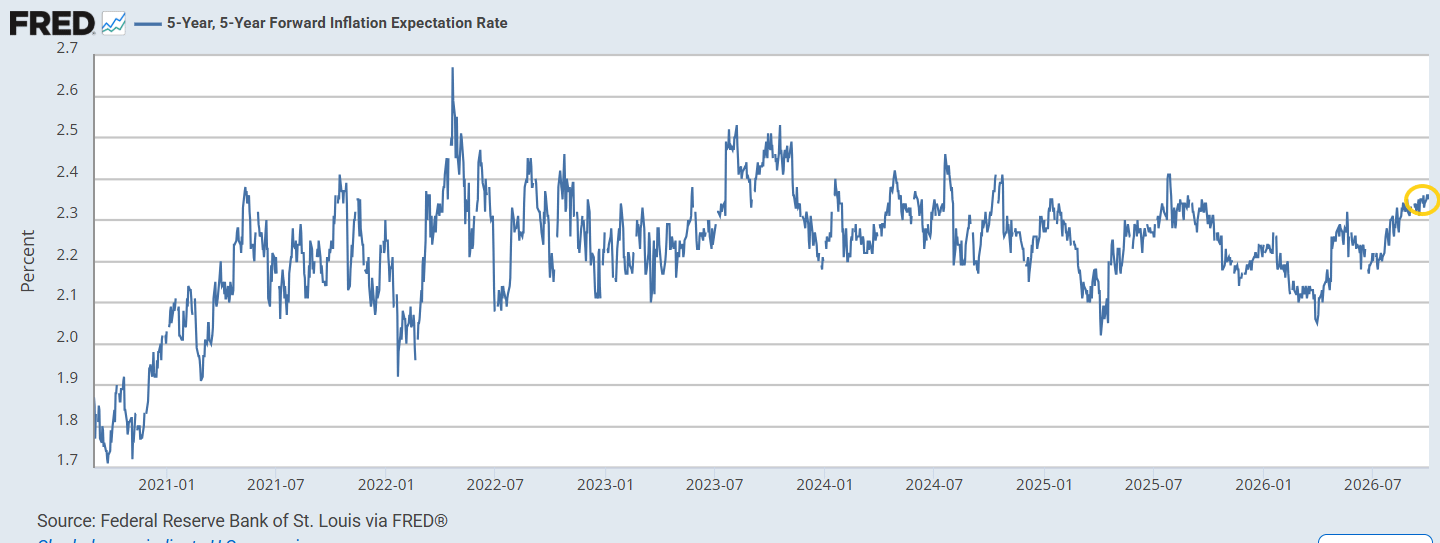
Taking a quick look at inflation expectations those continue to remain well below their post-pandemic highs with the Fed favorite 5-year, 5-year forward rate (expected inflation starting in 5 years over the following 5 years) Friday at 2.32%, a 3-week low. While it is near the highest in a year it’s well below the peaks in 2022 and 2023.
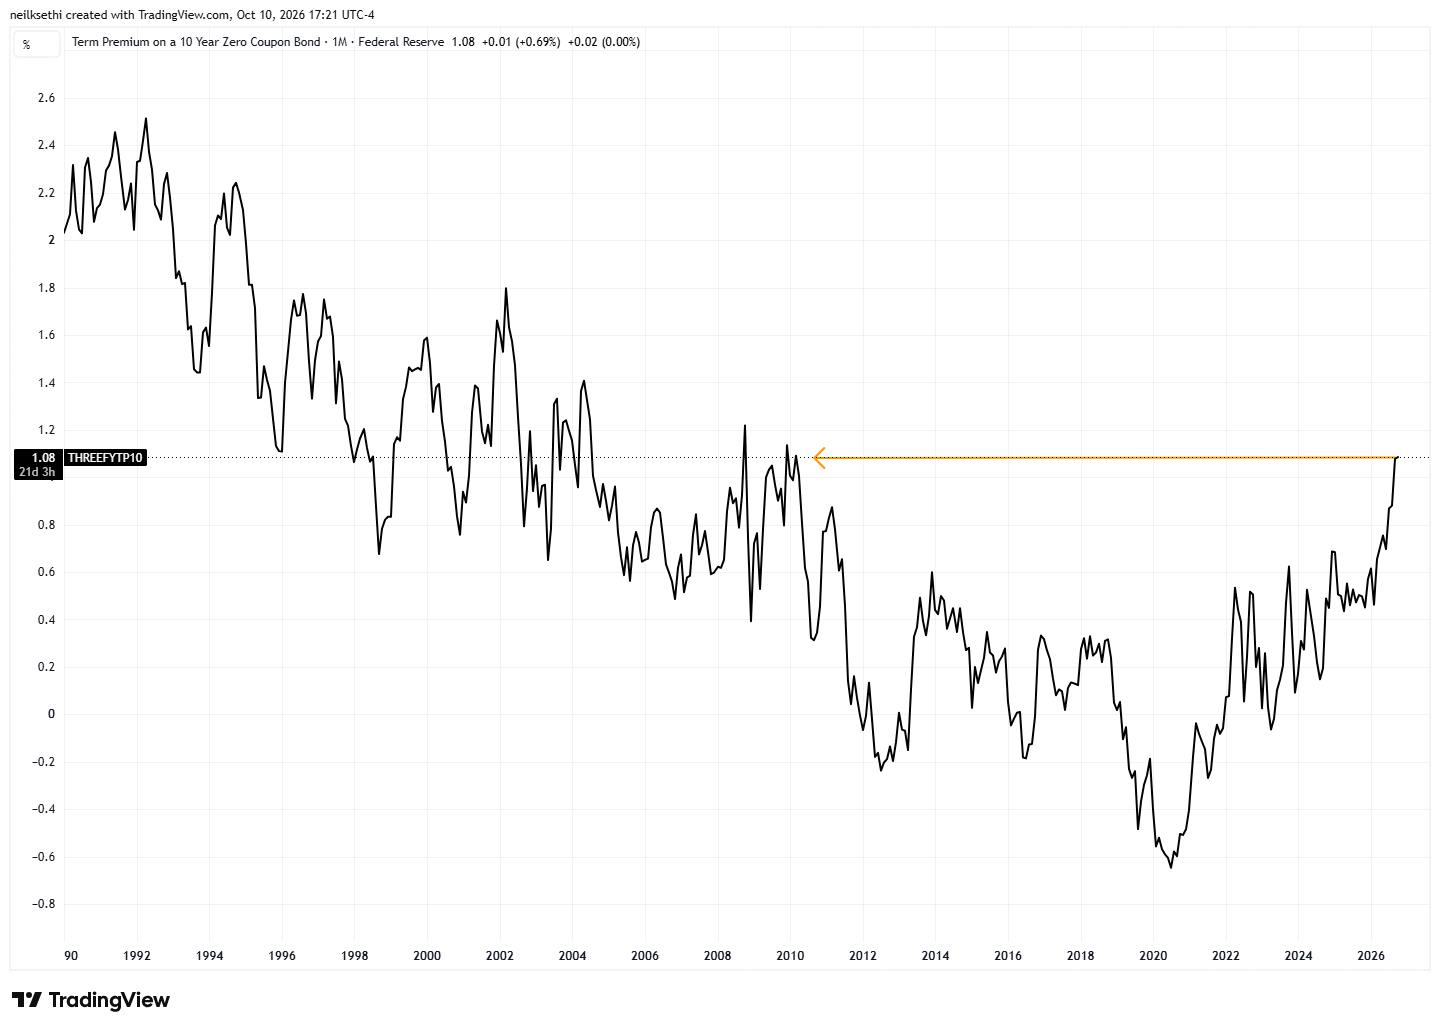
Which continues to leave term premium (extra yield investors demand to hold a longer-term bond instead of continually rolling over short-term bonds for the same period) the main source of pressure on the long-end with the Kim-Wright model for the 10-year pushing to 1.08%, another weekly high and the highest since March 2010.
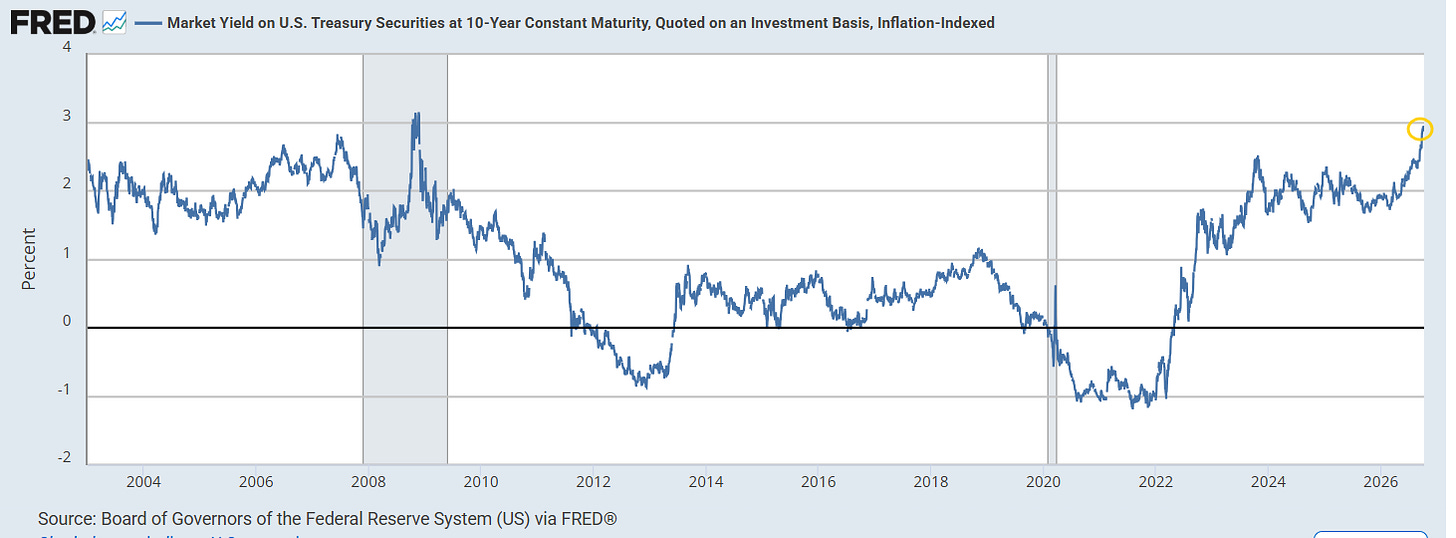
Which in turn is keeping the 10-year real rate (via the hypothetical constant-maturity, 10-year Treasury Inflation-Protected Security) at just off its post-2008 high of 2.88%. Outside of October/November 2008 it’s the highest since at least 2003 (as far back as FRED goes).
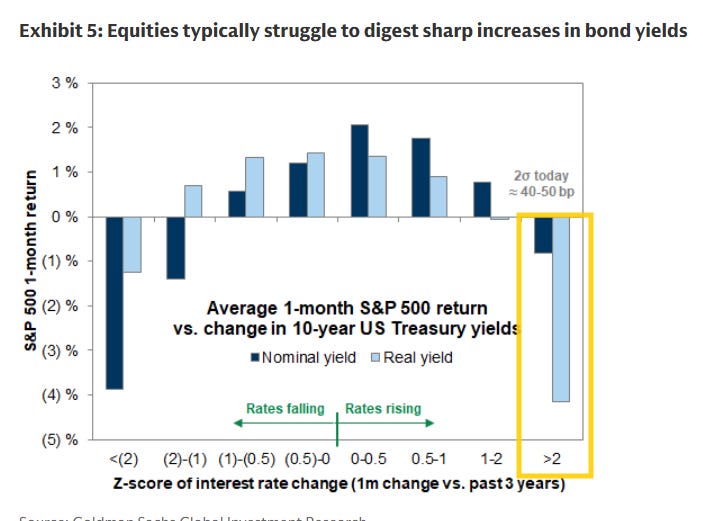
And in another example of how equities have ignored historical patterns, I mentioned two weeks ago the quick rise in real rates should have seen a notable pullback:
The real 10-year US Treasury yield has risen by 53 bp during the past month, crossing the two standard deviation speed limit that has historically been associated with negative equity market returns.
1-month average S&P 500 returns are ~-4% following such a move.
Equities can typically digest rising yields when the changes in interest rates are gradual, especially if those changes are driven by improving economic growth expectations. But this has not been the case in recent weeks.
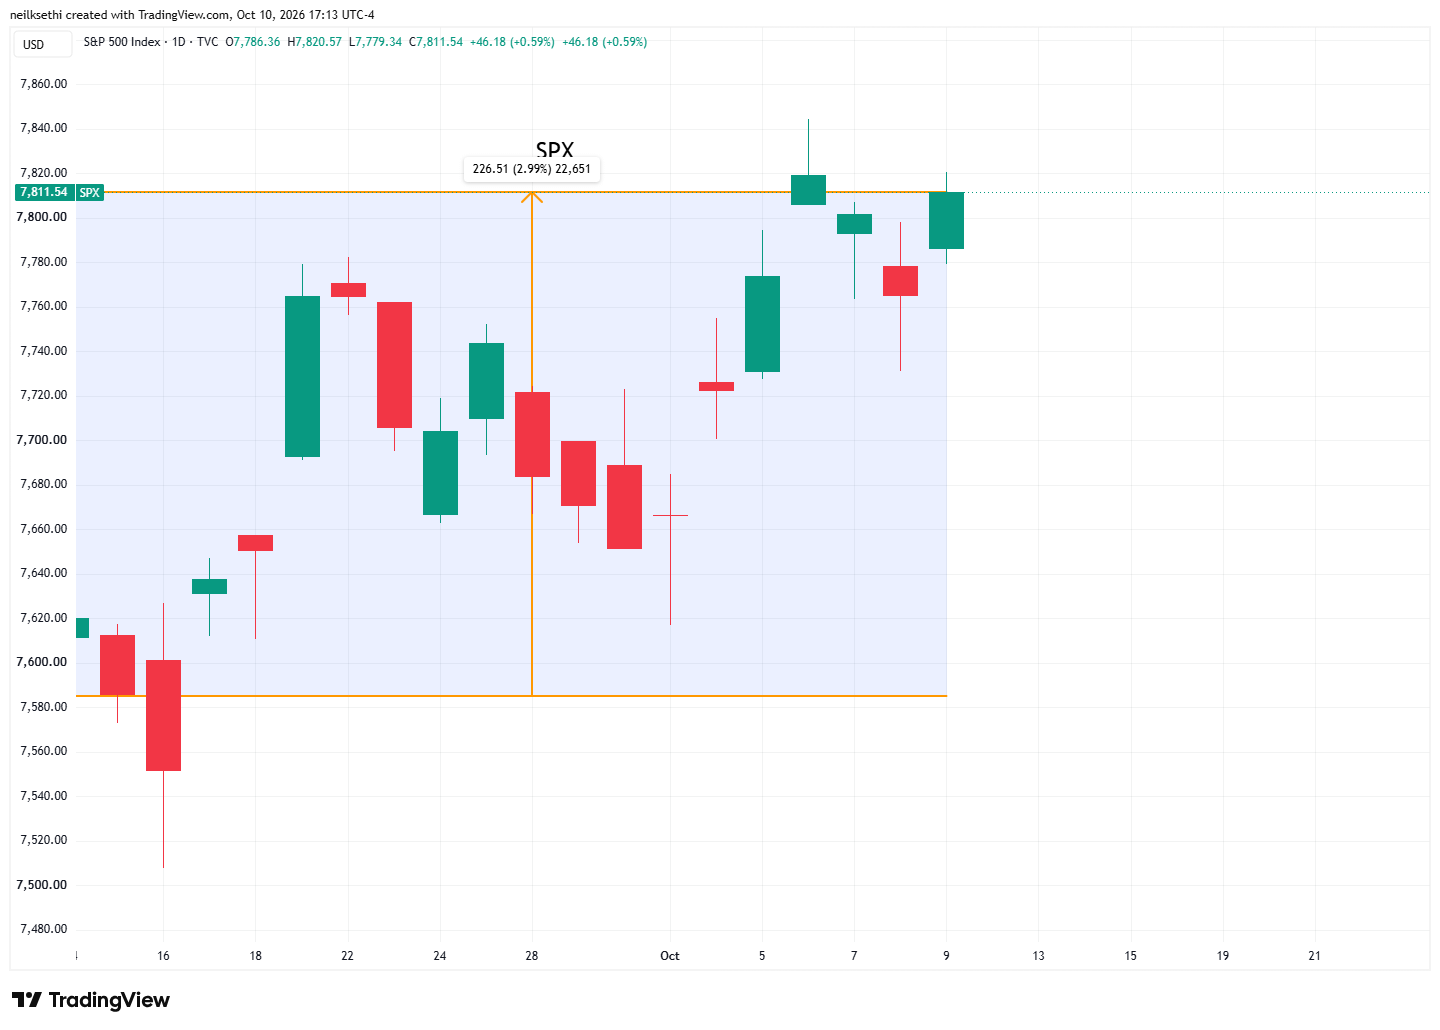
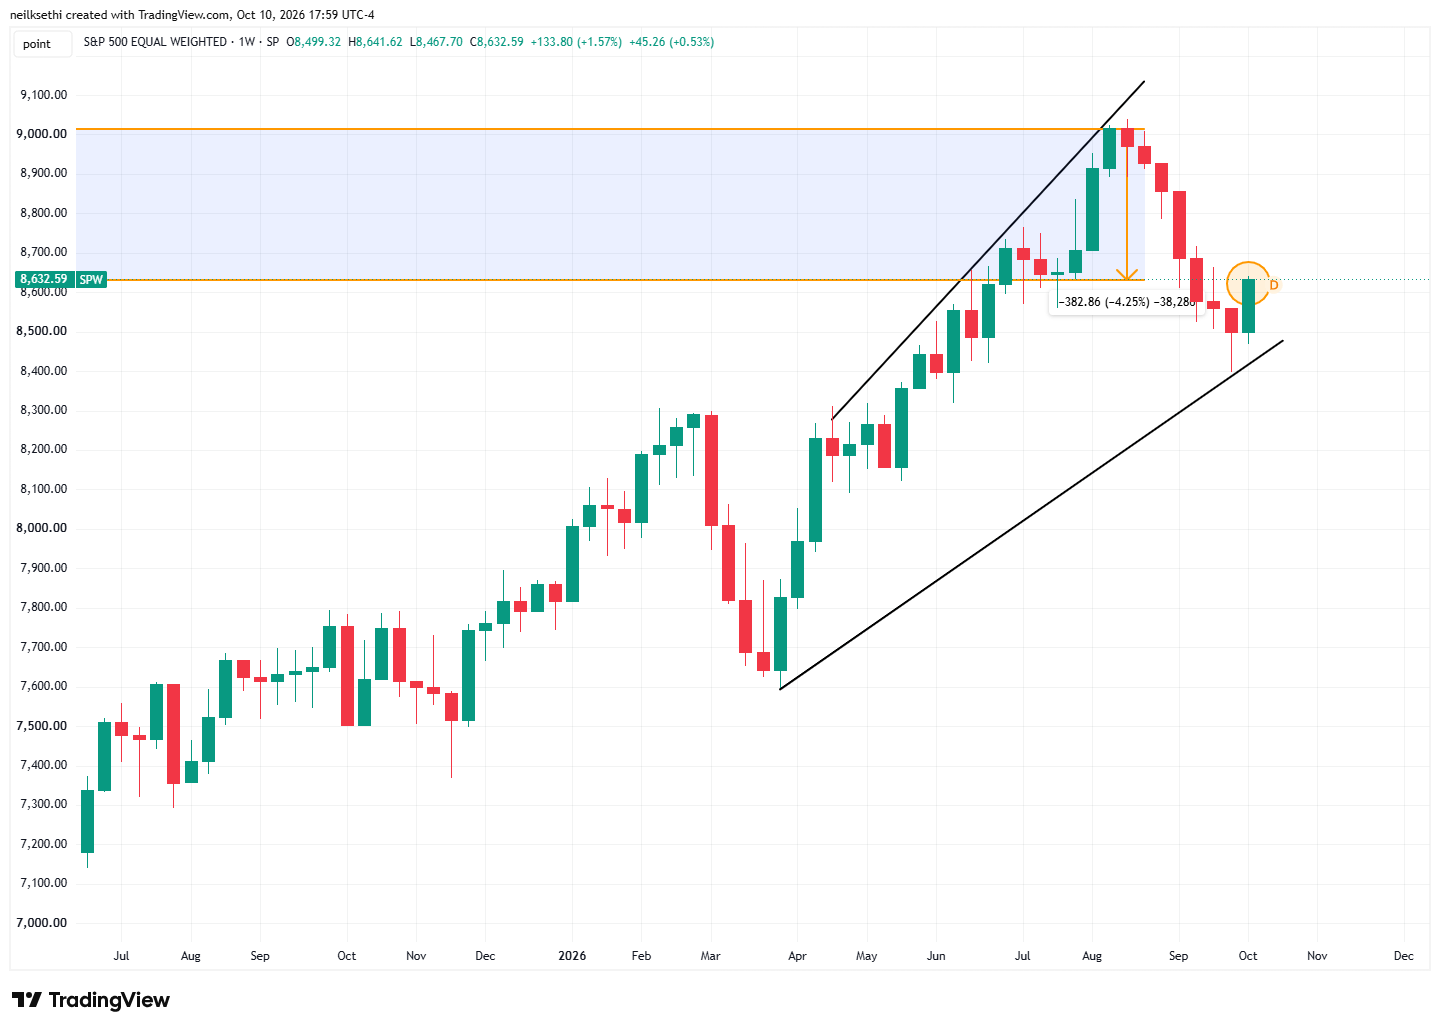
Instead, we’re up around 2% the past three weeks. The equal-weight index, though, is down over 4% from the highs. So this may very well be just another example of the immunity to interest rates of the megacaps that dominate the S&P 500.
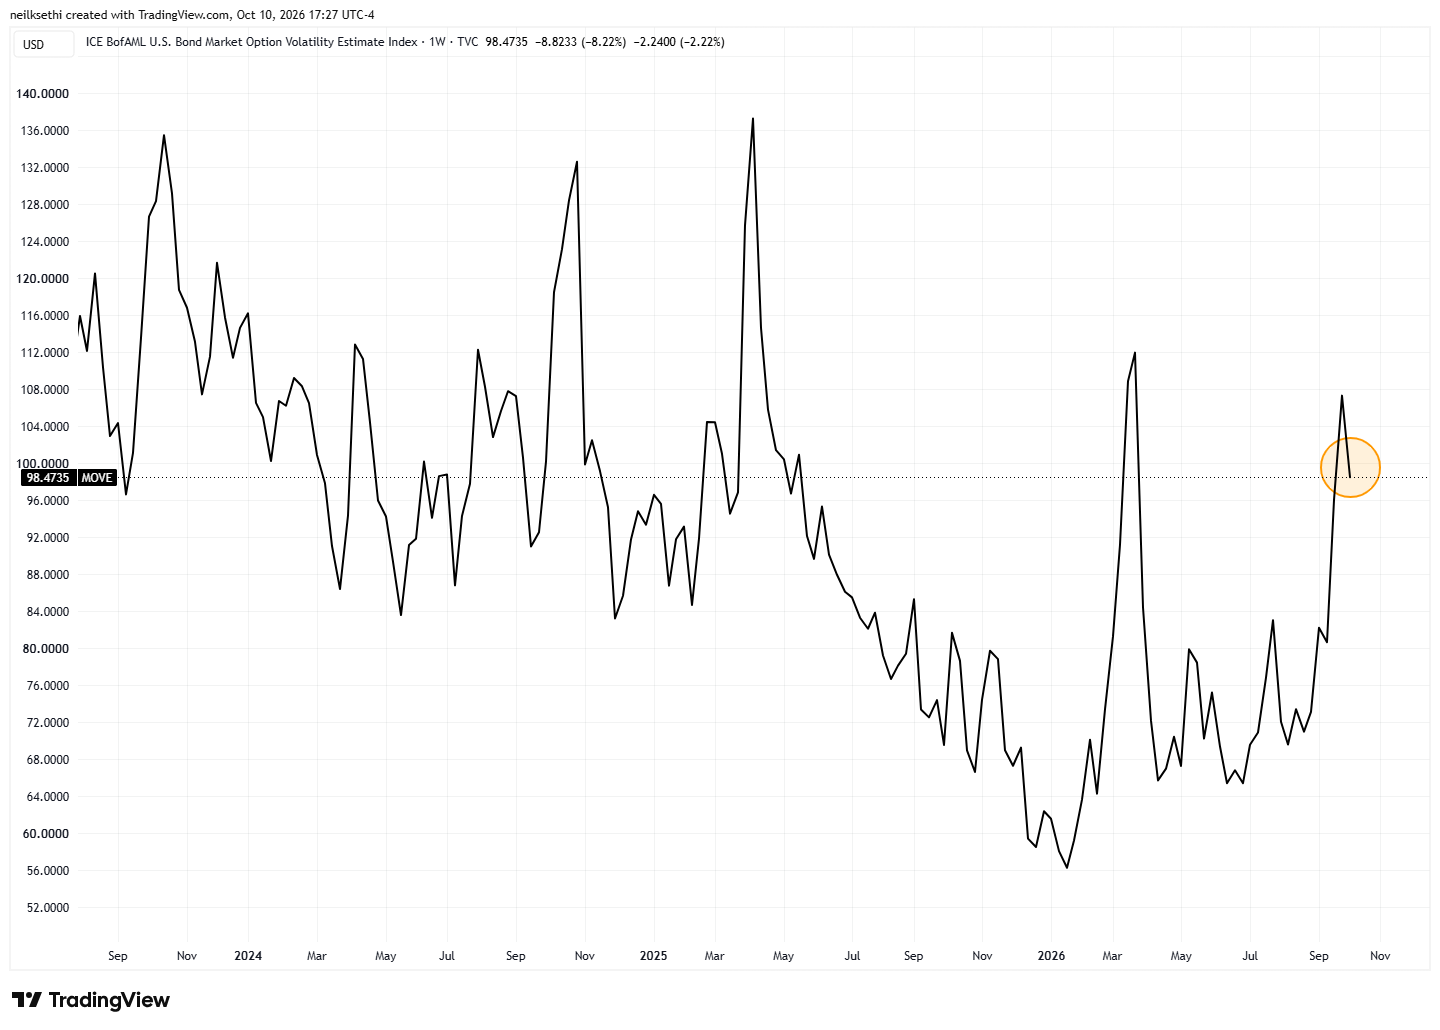
Turning to bond volatility, positively that has started to ease back.
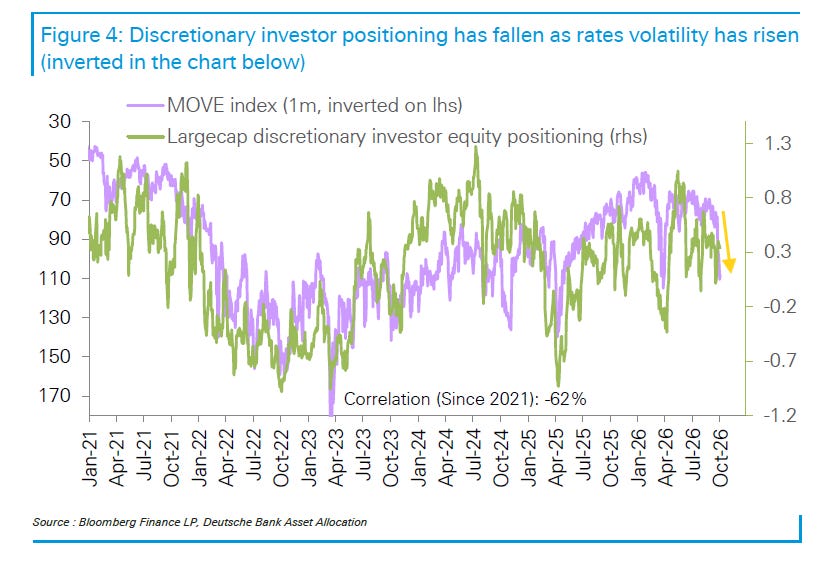
Which as noted last week DB said is the “key for equities,” as opposed to the level of rates.
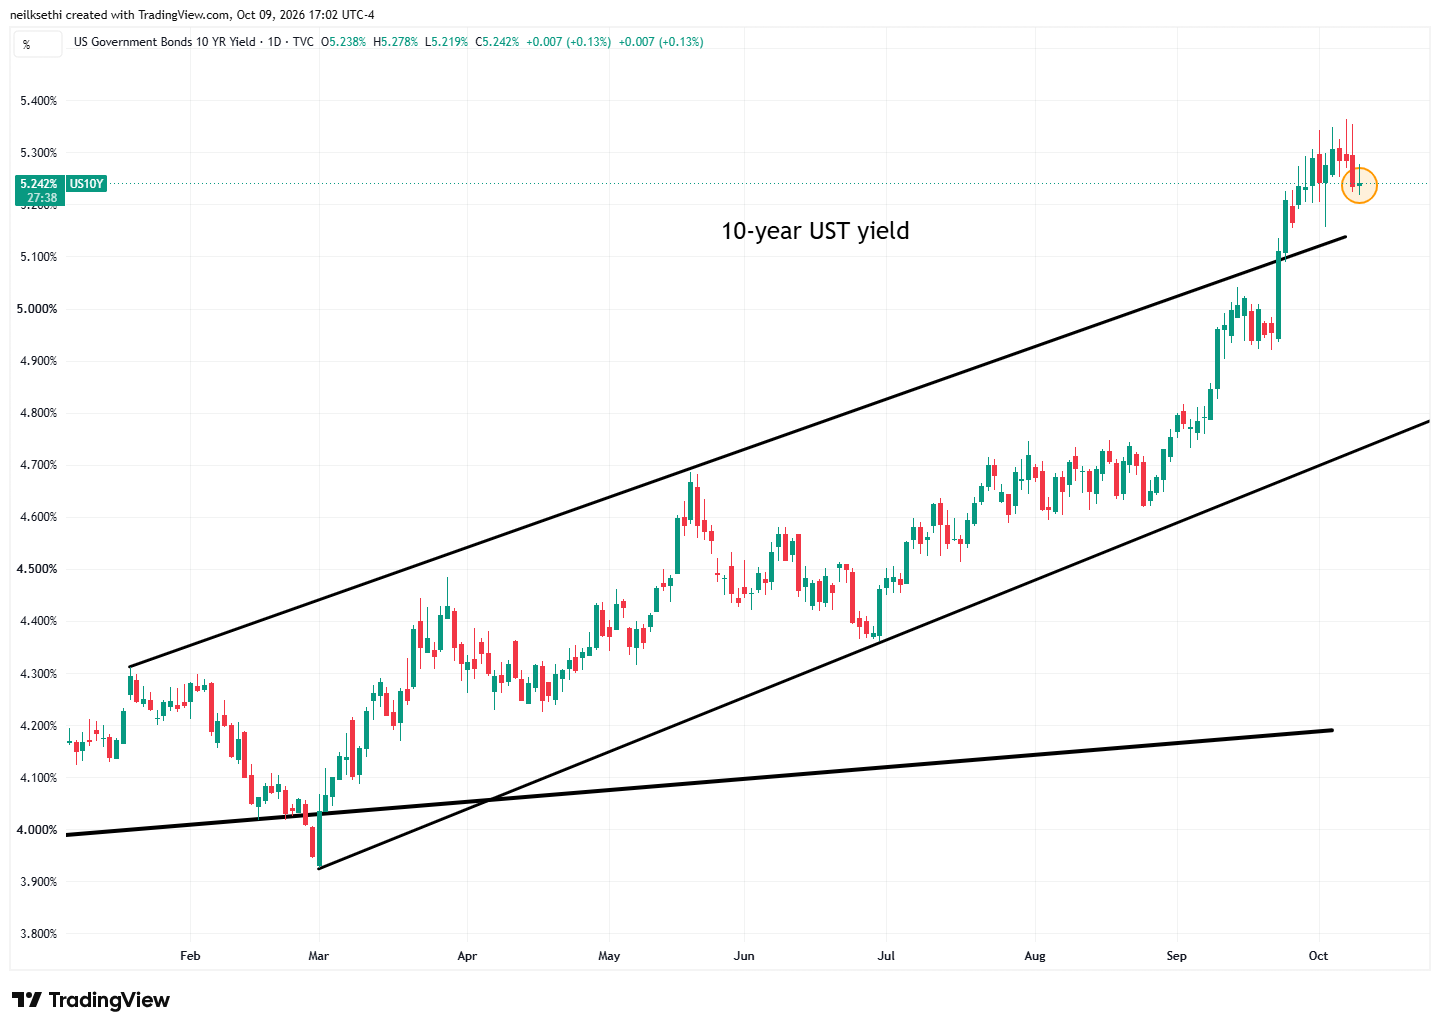
Overall, on yields, as I said two weeks ago, we remain above my new ranges established at the start of August for the 2-year and 10-year: “I still think that 5% on the 10-year and 5.75% on the 30-year represent areas where we will see very strong buying. On the 2-year I think a lot depends on whether the Fed hikes. If they do, there’s potentially another ~30 basis points to the upside (~4.75%). If they don’t, I think we’re going lower from here.”
I still for now think we’ll end the year back in those ranges, but I might change my tune after CPI this week.
FWIW Ed Yardeni agrees:
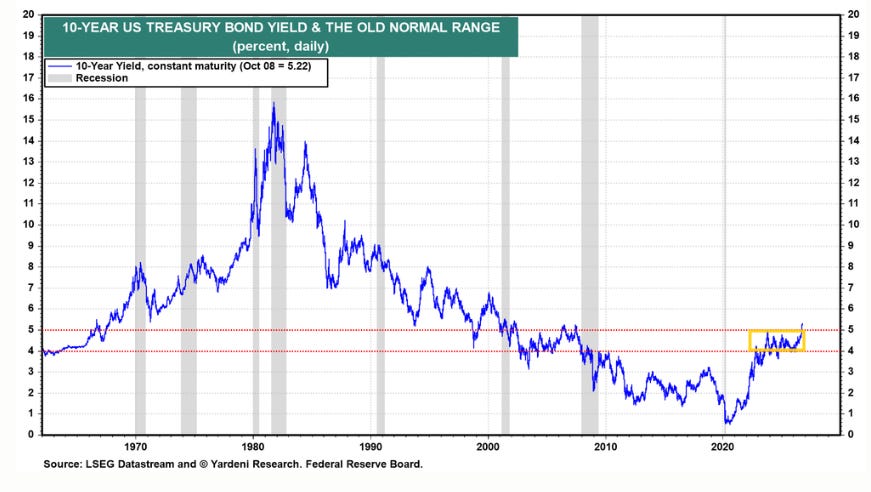
We think the 10-year Treasury bond yield is back to normal this year, i.e., in the 4.00% to 5.00% range (chart). We’ve disputed the widespread notion that “interest rates are likely to remain higher for longer.” That implies that they should come back down at some point. We’ve argued that “interest rates are likely to stay normal for longer.” They were abnormally low between the Great Financial Crisis and the Great Virus Crisis, when central banks rigged the fixed-income markets with zero and near-zero interest-rate policies and quantitative easing.
As bond yields rose in recent months to the top end of what we consider the normal range, we expected buyers to be attracted by higher yields, so we expected the range to be maintained (that’s what happened in 2023, when the yield spiked to 5.00% in late October). This time, the yield spiked above the normal range, to around 5.25% (as it did during the 4.00%-5.00% normal-range period from 2002-07).
In recent conversations with several of our institutional accounts, many expressed interest in buying bonds at levels above 5.00%.
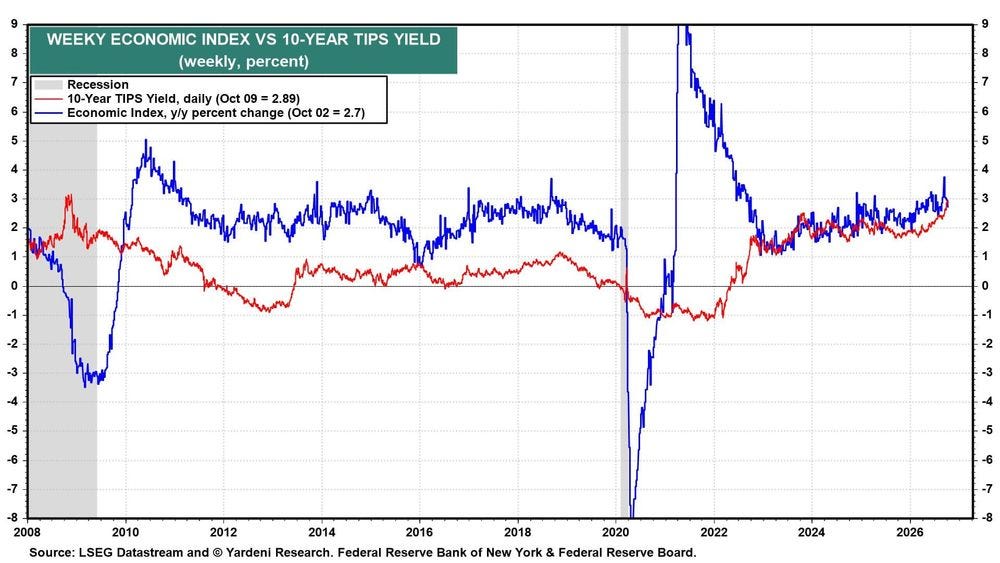
He also notes that the 10-year real yield discussed earlier has tracked recently the Weekly Economic Index which I go over each week in the prior section:
Since 2023, the TIPS yield has closely tracked the Weekly Economic Index, which tracks the growth rate in real GDP on a y/y basis (chart). This supports our view that the increase in US nominal yields has been driven by better-than-expected economic growth.
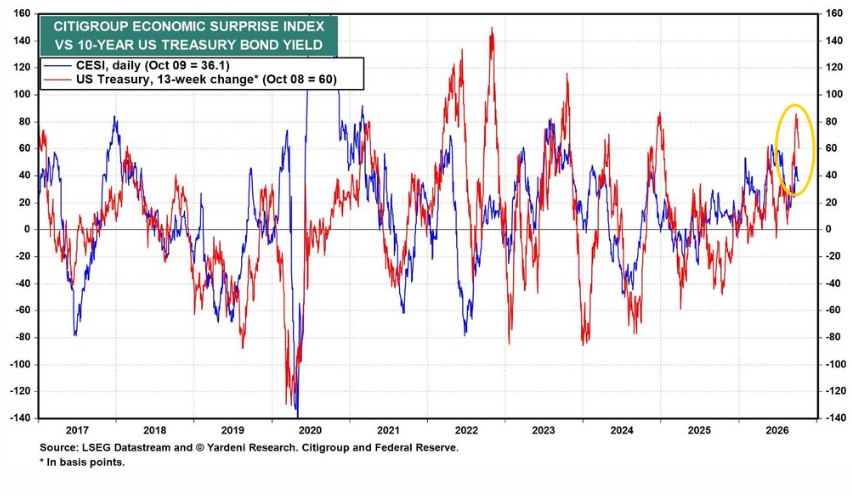
As well as the Citigroup Economic Surprise Index which “suggests that the former’s recent climb should abate.”
And we continue to remain extended in short positioning in bonds (bets on higher yields). Per BofA (they see CPI as a possible catalyst for the big short-covering rally I’ve been waiting on):
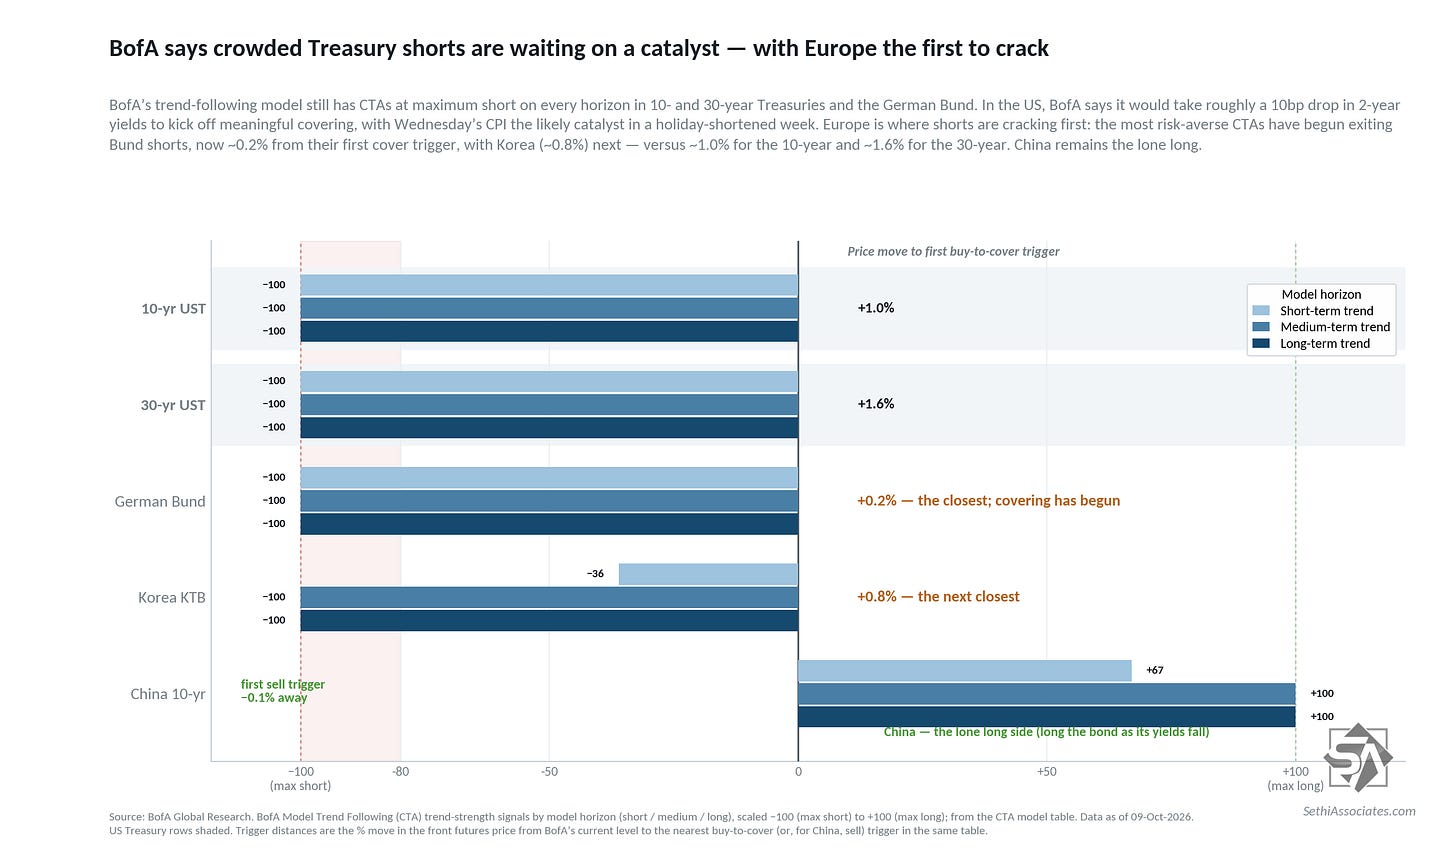
Trend followers remain heavily short global rates markets, although some signs of covering are beginning to emerge outside the US. In Europe, the most risk-averse CTAs have started to exit Bund shorts with more covering possible next week. US Treasury positioning remains stretched short across the curve with roughly a 10bps decline in 2yr yields required to kick off meaningful covering.d
Wednesday’s CPI print could provide the next catalyst for positioning adjustments during the shortened US bond trading week.
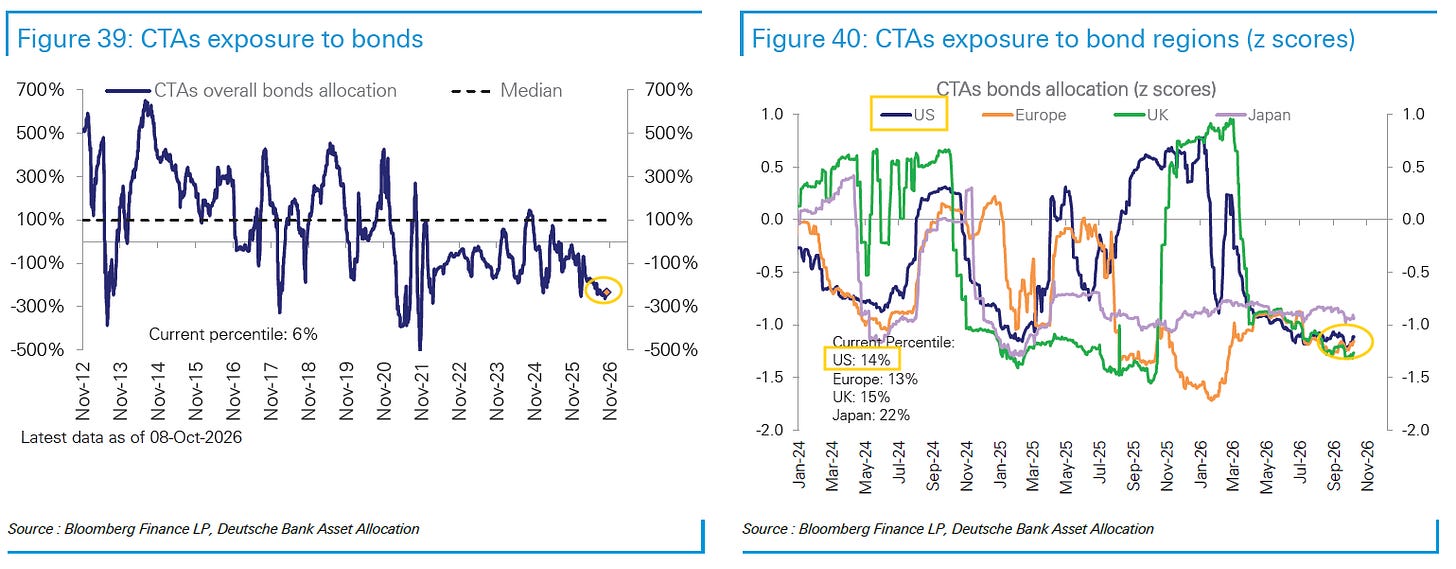
DB similarly says CTA “bond shorts remain extreme” at just the 14th percentile to 2012 for the US. Globally they’re at the 6th percentile, up though from the 4th last week.
And we continue to see evidence of buying:
From MarketWatch:
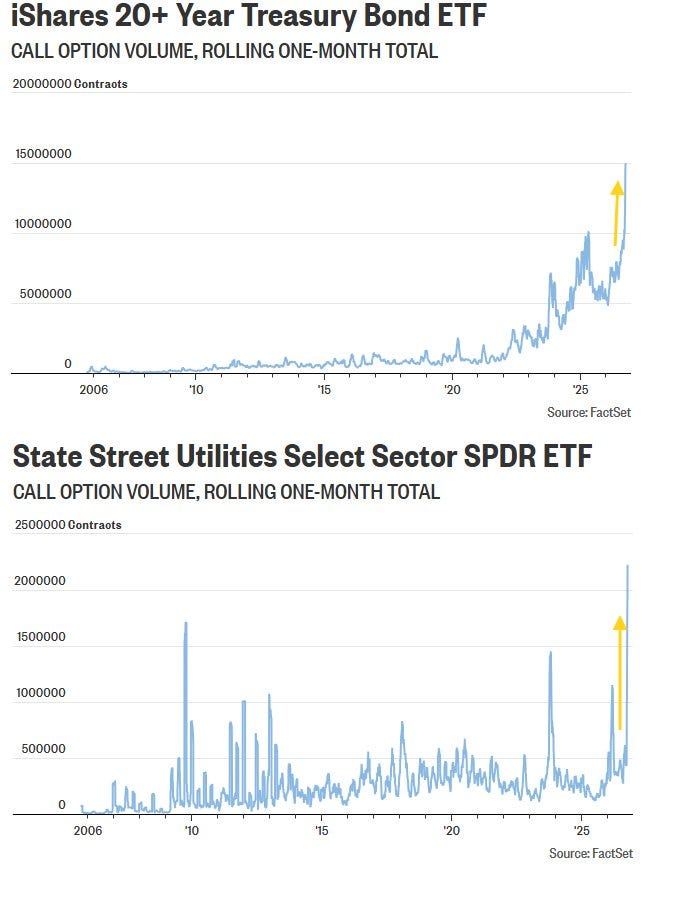
“Investors are aggressively betting on a sudden turnaround in interest rates, and they’re using call options on exchange-traded funds tied to utilities stocks and long-dated Treasury bonds to do it.”
Trading volume in call options tied to popular ETFs like the iShares 20+ Year Treasury Bond ETF (TLT) and the State Street Utilities Select Sector SPDR ETF (XLU) have surged according to Dow Jones Market Data.
That comes after September’s surge in Treasury yields led to the TLT’s worst monthly performance on a total-return basis since December 2024, deepening its third-quarter loss to almost 9%, FactSet data show. XLU lost 13% in the third quarter, its worst since January 2020.
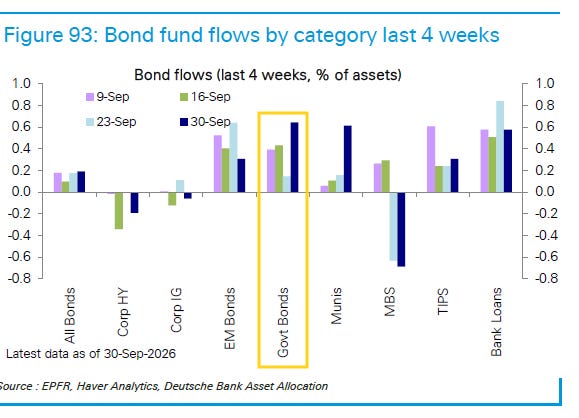
DB saw a second week of four-month high inflows to bond funds ($33.8B) although this week it was “driven primarily by short-term government bonds ($10.7bn),” vs the long-end the prior week.
They also note “money market funds ($166.4B) received massive inflows their biggest since April 2020,” led by the US ($101.3B).
Goldman:
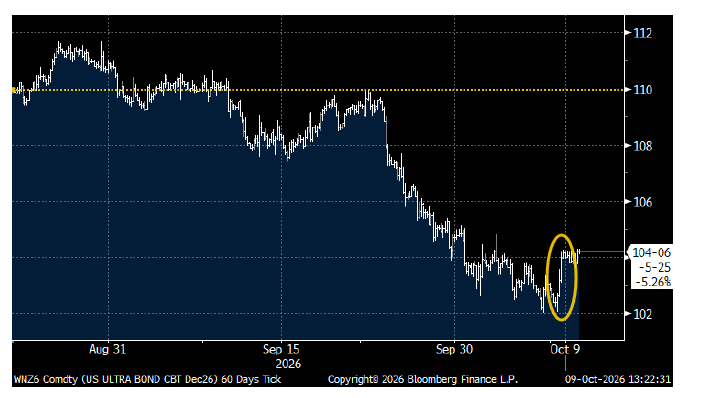
Long bonds may have finally found a bottom this week after having sold off sharply since Warsh’s Hawkish Jackson Hole speech on 8/28. The OpenAI revenue restatement headlines prompted the rally in bond futures on Thursday (Chart 4) and prices have held steady to finish out the week. This reaction in UST futures supports the thesis that expectations for more AI-related bond issuance have helped drive the rise in longer term UST yields as government and corporate issuers compete for the same capital.
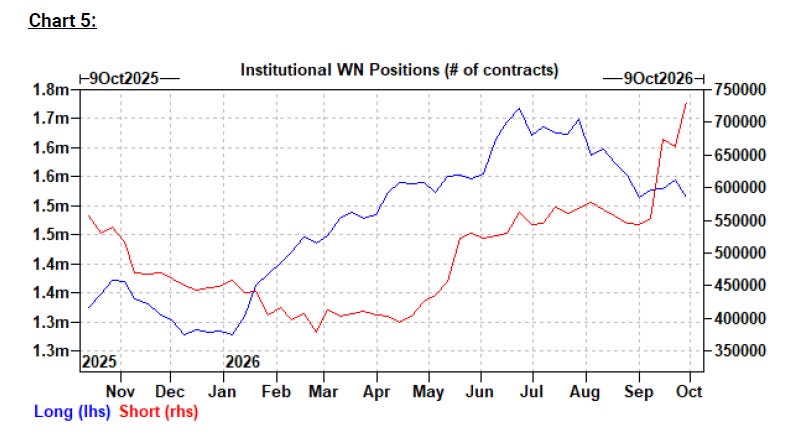
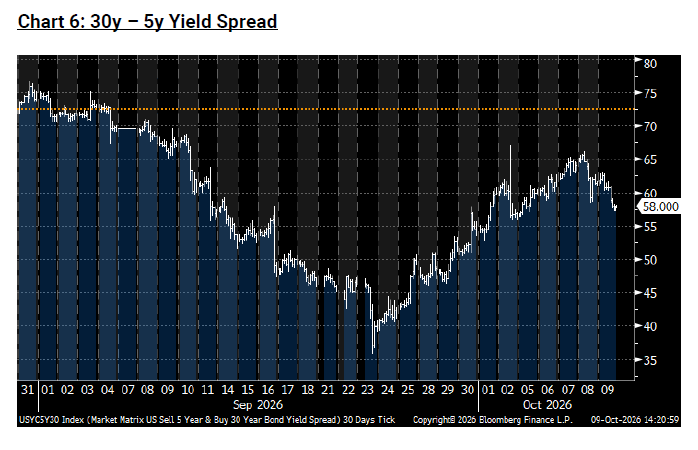
Asset manager shorts in the long bond had risen sharply since mid-September (Chart 5), when the long end began to “catch down” to the move in short end rates (Chart 6 – see 5y/30y curve for context) – if Thursday’s moves prompts these asset managers to begin to cover shorts, we could see further support for bonds into early next week.
And we again saw heavy demand in the 10-year and 30-year auctions this week (particularly the 10-year which was the best in a decade).
So as I said last week:
we remain in a precarious place for bond shorts. There will be that huge short covering rally that will see yields plummet, at least briefly. I had thought a weak NFP number would do the trick but as I mentioned that Friday “the momentum behind the short bonds trade (or perhaps the lack of momentum behind the long bonds trade with Goldman characterizing bonds as “bidless” today) is more powerful than even a notable miss on what has traditionally been the most important economic report we get.”
Notably, it’s clear that bonds are no longer “bidless,” so we’ll see what we get this week. CPI and Chair Warsh will be the major catalysts.
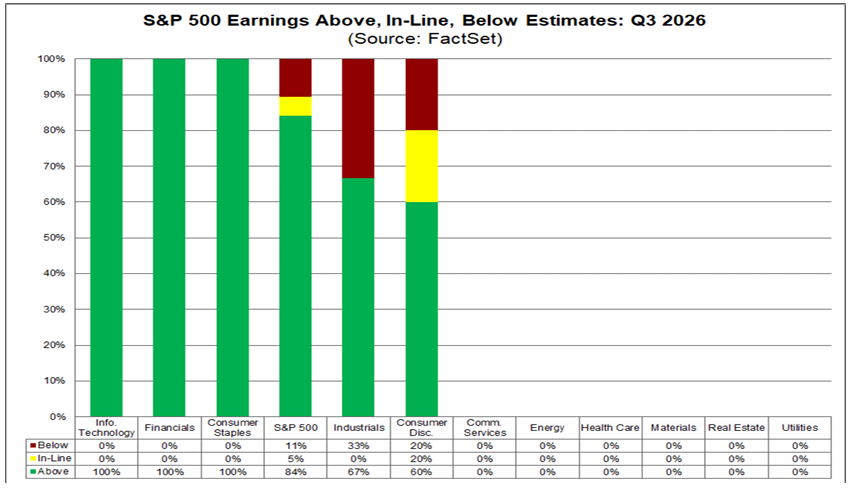
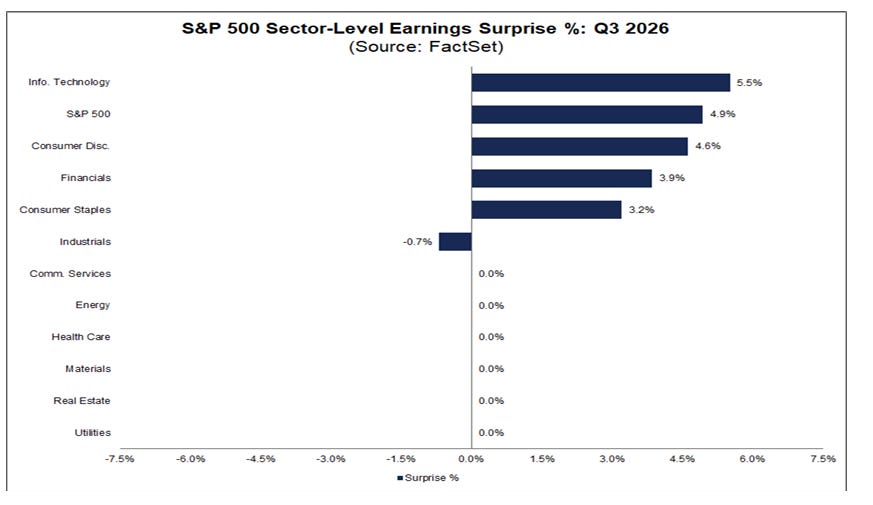
Looking at Q3 earnings, with just 19 companies reporting so far, we have 84% beating, slightly below the 86% beat rate in Q2 (which was the best since Q2 ‘21) and vs the 5yr average of 78% and the 10yr average of 76%.
The magnitude of the beats has been +4.9%, well below the +26.5% in Q2, the best since FactSet began tracking the metric in 2008, but remember Q2 started out similarly before jumping higher when the Tech earnings rolled in. That compares with the 10-year average of 7.4% and the five-year average of 7.0%
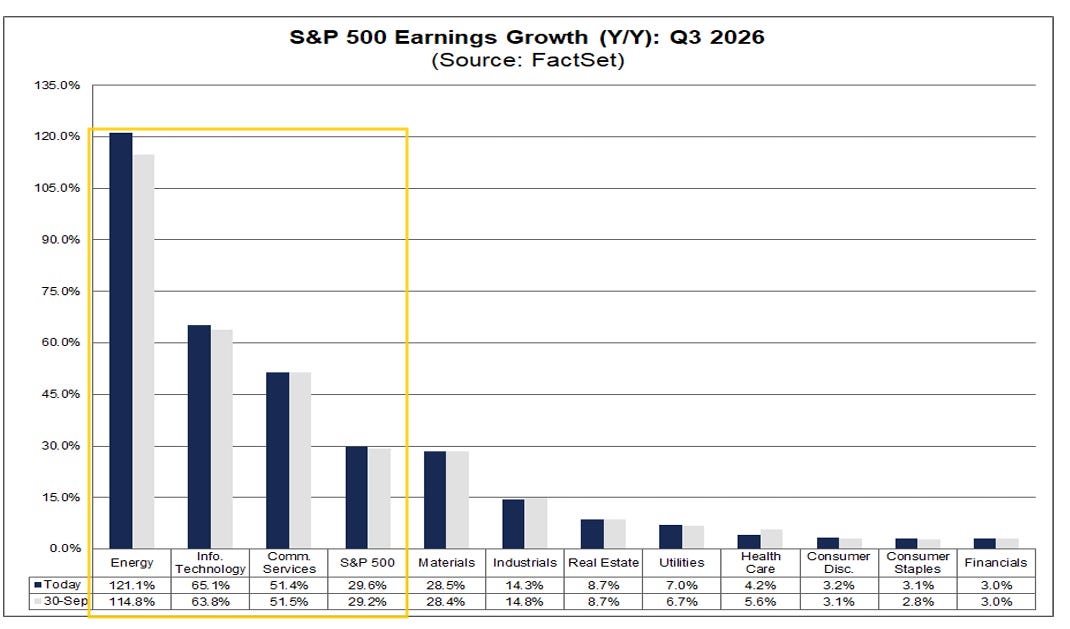
But that along with guidance has boosted Q3 expected earnings growth to +29.6%. As in Q2, Energy is expected to lead at +121.1% y/y growth (up from +79.3% at the start of the quarter — July 1st), followed by Tech +65.1% and Comm Services +51.4%.
Unlike Q2 no sector is expected to have negative y/y growth with Financials the least at +3.0%.
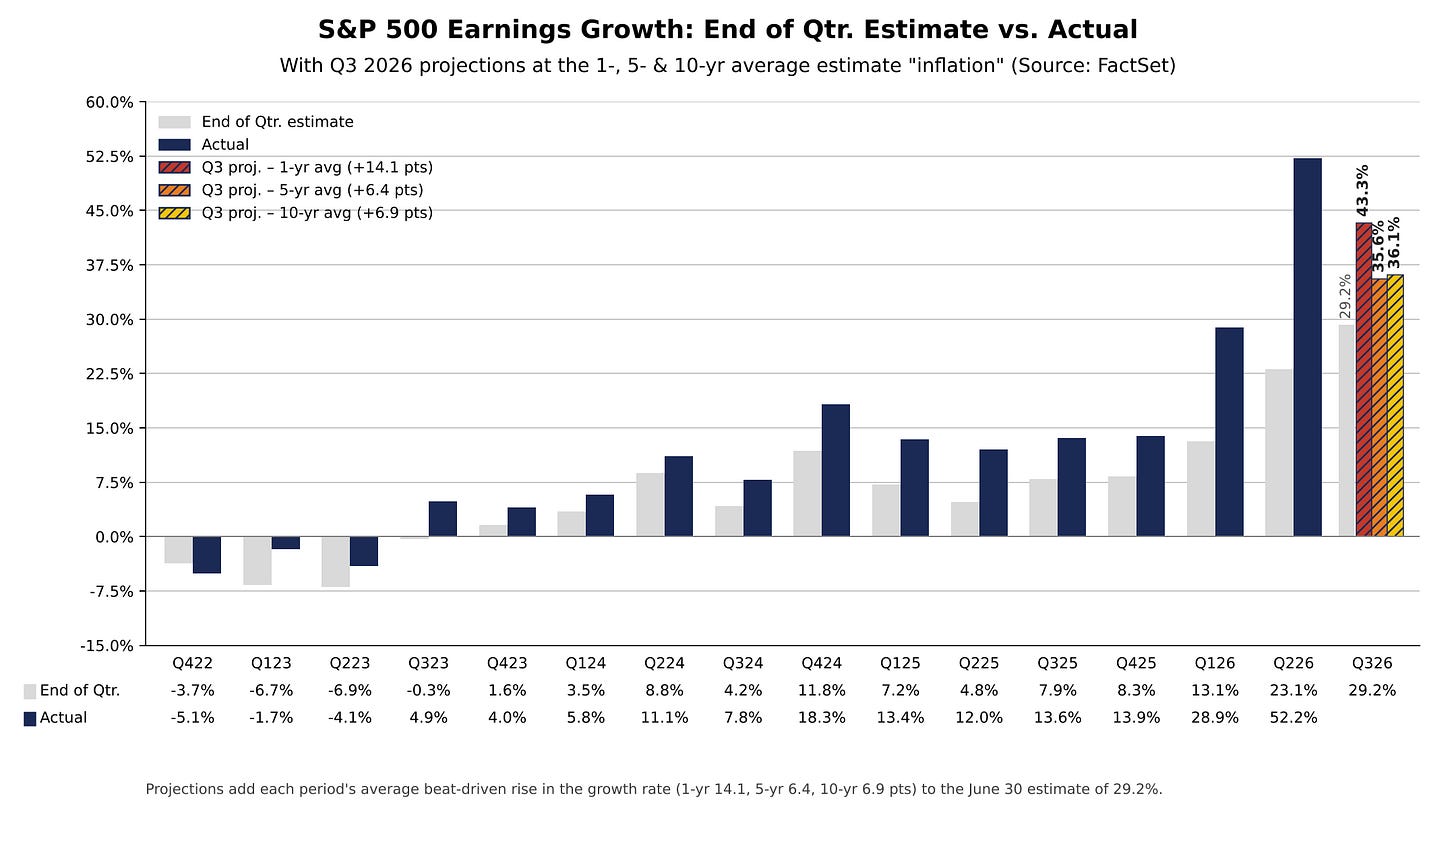
As those who followed me over from Neil’s Newsletter know ahead of each earnings season I discuss how if past is any guide the earnings growth for the coming earnings season can be expected to come in well above expectations at the start of the season.
According to Factset data, over the past 1, 5 & 10 yrs S&P 500 companies have beaten earnings expectations by 13.8%(!), 7.5% & 8.0% respectively, resulting in “inflation” to the earnings estimates on average over the quarter by 14.1%(!), 6.4% & 6.9% respectively over where they stood as of the start of the quarter (in this case June 30 which was 29.2%).
Using those averages would mean Q3 earnings could come in at +43.3%(!), 35.6%, or 36.1% respectively.
Actual earnings by the end of the quarter have failed to surpass expectations at the start of the quarter in only 3 of the past 43 quarters (Q1 ‘20, Q3 ‘22, and Q4 ‘22 are the only exceptions according to Factset).
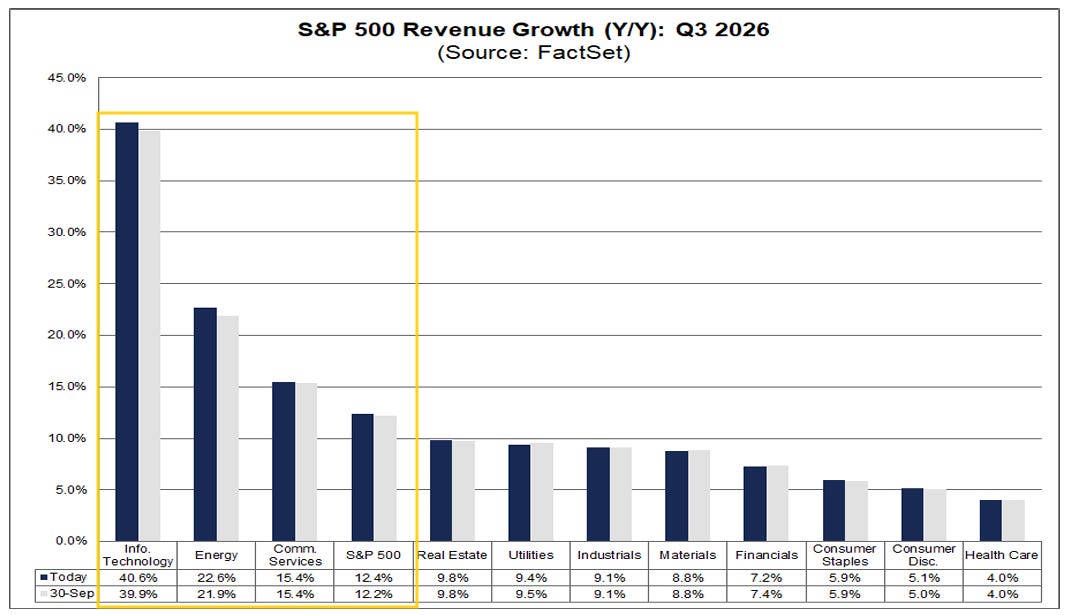
Q3 revenue growth is expected at a likewise stellar +12.4%, down from +15.5% in Q2 which though was the best since Q4 2021 (16.1%). It would mark the third consecutive quarter of double-digit revenue growth for the index.
Expectations are led by Tech (+40.6%), Energy (+22.6%), and Communications (+15.4%).
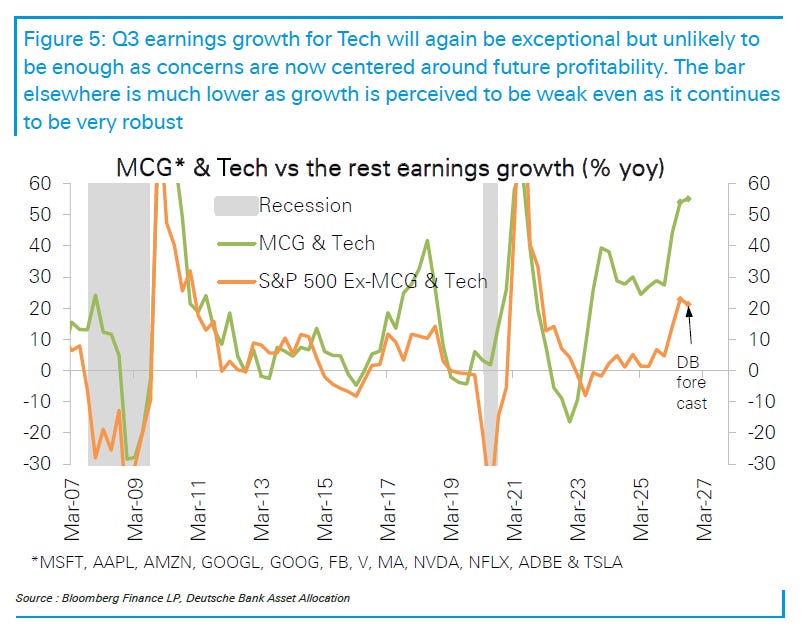
But despite the historically high expected results for Tech, DB says they expect it won’t be enough to lift Tech while the strong earnings elsewhere will see continued broadening:
Extremely strong third-quarter Tech earnings growth is unlikely to be enough to drive the sector higher in the near term, while the bar for other sectors is significantly lower. We expect Tech earnings growth of around 55% in Q3. However, investors’ concerns now center on future profitability and are unlikely to be resolved soon.
In our view, expectations for other sectors are low, reflecting a widespread belief that there is little growth outside Tech. In contrast, we forecast strong ex-Tech earnings growth of 21% year over year, only slightly below the 23% recorded in Q2. We also expect the median S&P 500 company to again deliver robust earnings growth in the mid-teens.
A rotation into other sectors should ease concerns about market breadth. Given Tech’s concentration in the index, periods of sector outperformance typically raise concerns about the narrowness of market gains, and the past two months have been no exception. In our view, a rotation into other sectors and small caps should help alleviate those concerns.
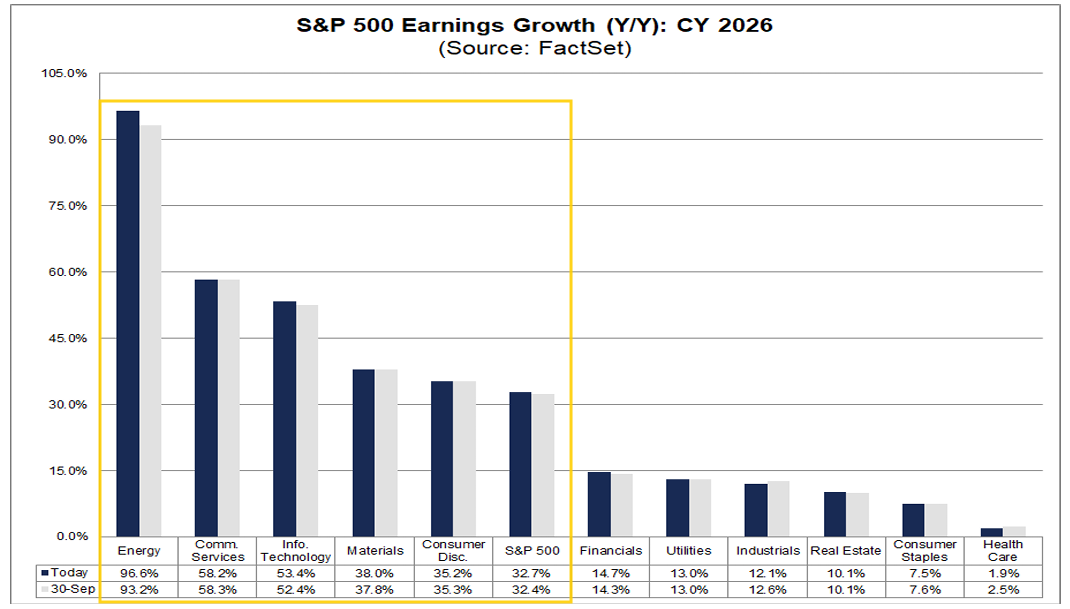
2026 SPX earnings growth expectations also continue to march higher now at +32.7%, up from +24.0% on June 30th, +17.1% on March 31st, and over double the +14.8% at the start of the year.
As in 2025, Tech is a leader with y/y earnings growth of +53.4% (up from +28.6% at the start of the year) but Energy will exceed that (on a percentage basis) at +96.6% (up from +6.4% at the start of the year) along with Communications +58.2%. Those sectors along with Materials (+38.0%) and Consumer Discretionary (+35.2%) represent the five sectors expected to come in above the SPX average.
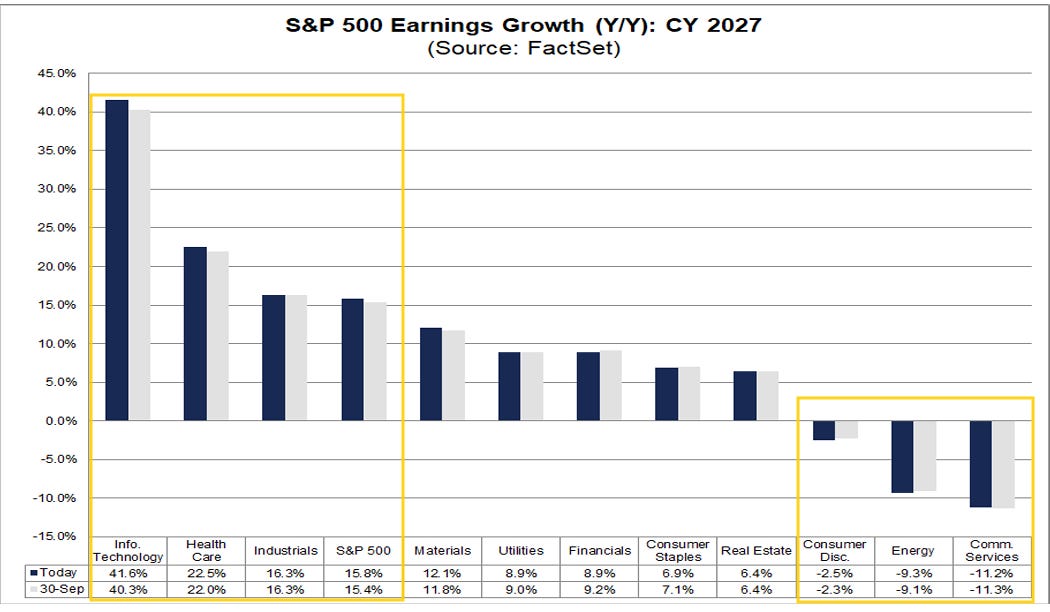
And 2027 earnings are expected to be up another +15.8% on top of the elevated 2026 results, which is down though from +17.5% as of June 30th as analysts are not carrying over all (but still most of) the boosts in 2026 earnings to next year. Still it’s a double digit advance on top of what is expected to be a 30%+ gain in 2026. That would also represent a fourth straight year of double-digit earnings growth for the S&P 500, something we’ve rarely seen.
2027 is expected to be led again by Tech (+41.6%, up from 24.6% at the start of the second quarter on April 1st, despite the huge increase in 2026 estimates since then) followed by Health Care (+22.5%) which is expected to see a big turnaround after lagging in 2026. Industrials (+16.3%) is also above the SPX average.
With hyperscaler investment gains (in Anthropic, OpenAI, etc.) expected to slow, the sectors that have seen the biggest boosts from that are now expected to see negative y/y growth (Comm Services, -11.2% from +8.2% at the start of the third quarter, and Consumer Discretionary, -2.5% from +13.9%) along with Energy (-9.3%) as petroleum prices are expected to soften.
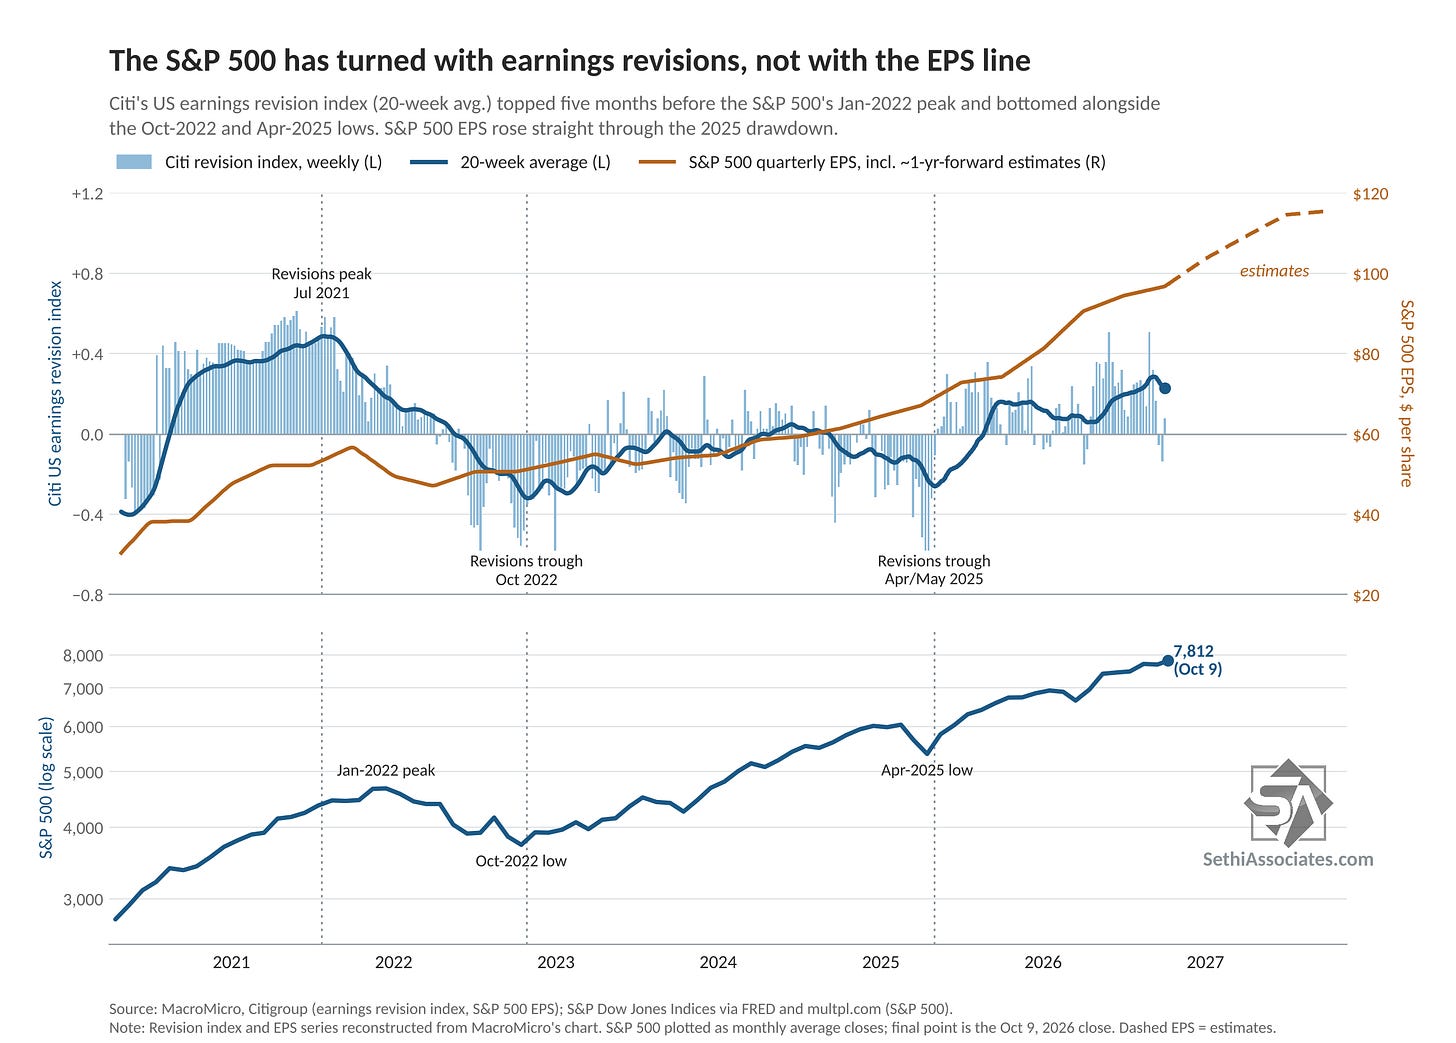
And I noted last week after we had seen two negative weeks of earnings revisions according to Citigroup “I’m not too concerned about a few weeks of that,” and sure enough they have rebounded back into positive territory similar to what we saw just before the start of Q1 earnings.
What I’m watching more closely is the 20-week moving average which does lead the S&P 500 if we see a prolonged softening. So far it’s just been a few weeks, so nothing to raise any alarm.
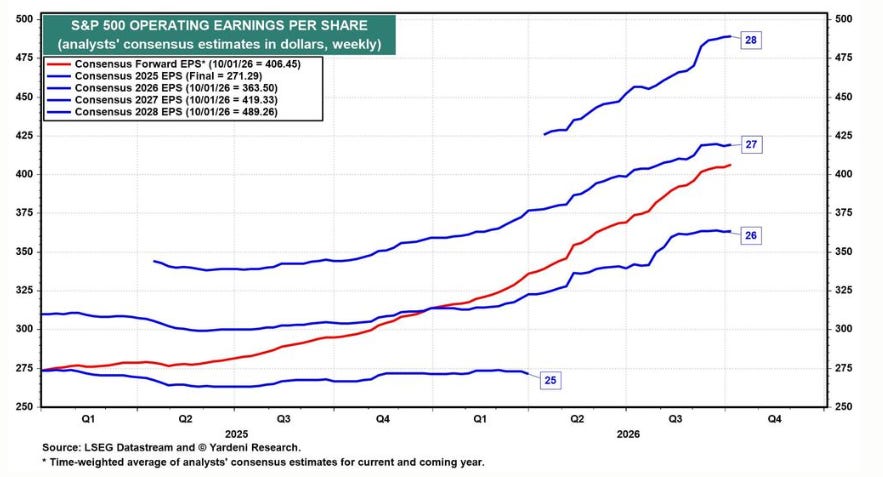
Yardeni: Fabulous Earnings Momentum (FEMO) is clearly visible in industry analysts’ earnings expectations. They currently expect S&P 500 operating earnings [which exclude the investment gains] per share to rise to about $364 per share in 2026 and $419 in 2027, implying growth of roughly 15% in both years (chart).
Toward the end of Q3 each year, we add another year to our Earnings Squiggles framework. This year’s addition is 2028, with earnings projected to rise another 17% that year to about $489 per share.
For now, the analysts are more bullish than we are about earnings prospects over the remainder of the decade. We are projecting $450 per share in 2028, $475 in 2029, and $500 in 2030. If they are right, our S&P 500 target of 10,000 will be achieved well before the end of 2029!
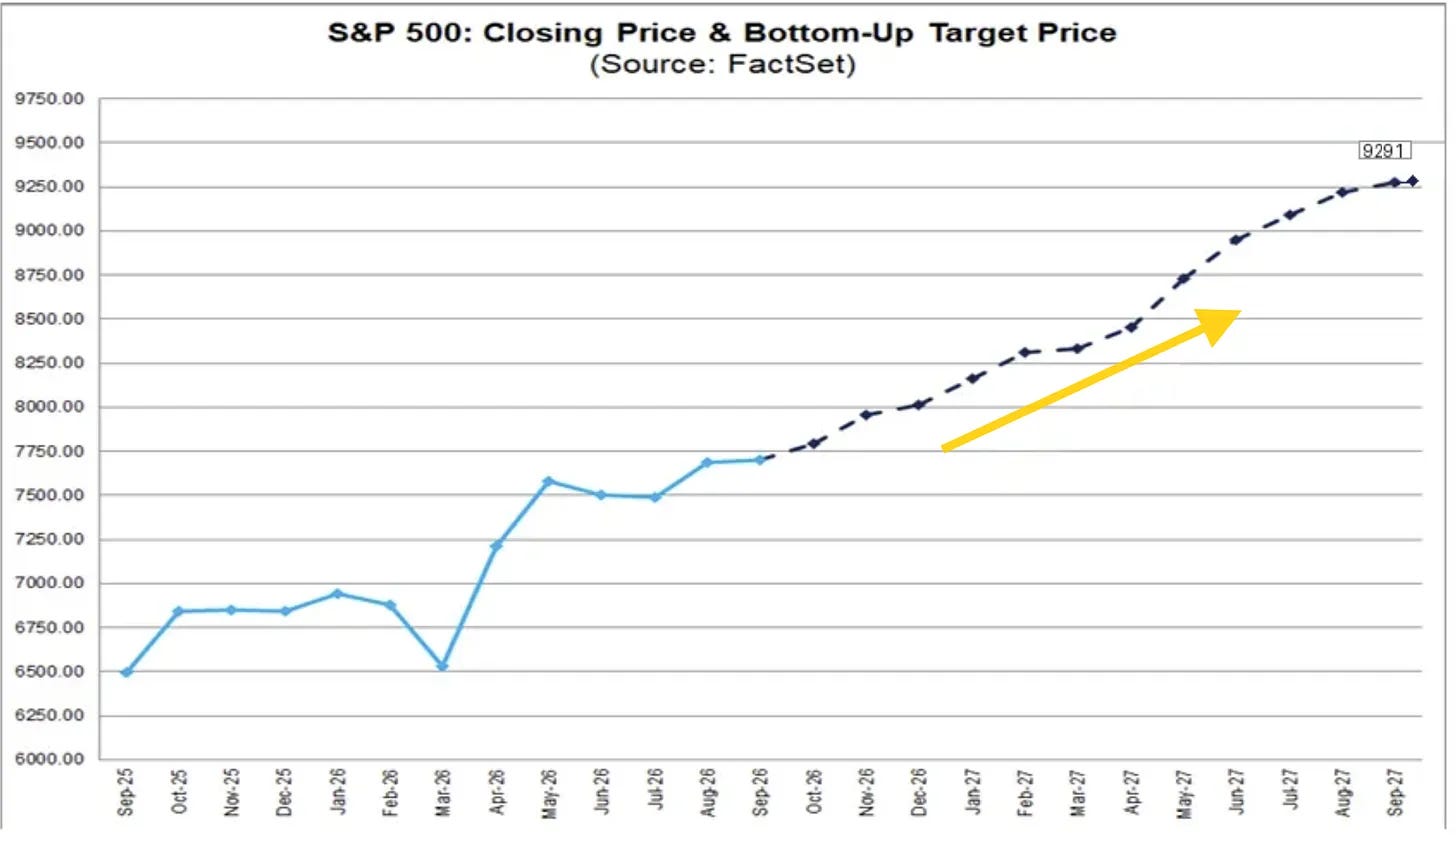
Analysts meanwhile collectively continue to think that the S&P 500 has a lot of upside with FactSet’s compilation of analyst bottom-up SPX 12-month price targets up to 9,291 (+10pts w/w, ~995 pts since March 31st, ~+2,170 pts since Thanksgiving, and ~+3,120 pts since July 1, 2025) although that’s slowed as is typical in between earnings seasons. That would be +19.6% from Thursday’s close, down from +21.3% the prior week as the index’s gain outpaced the target increase.
Industrials (+24.7%) have now overtaken Consumer Discretionary (+24.0%, down from +27.6% the prior week) as the sector expected to see the largest 12-month price increase, followed by Real Estate (+23.5%), while Utilities dropped to +21.1% from +26.8%. On the other side Energy (+8.8%, down from +13.3%) is now the only sector with single-digit expected upside, followed by Consumer Staples (+11.9%) and Health Care (+13.9%).
As a reminder we started the year with a 12-month bottom-up price target of 8,000 and according to FactSet the last 20 yrs (through 2024) analysts have been on avg +5.9% too high from where they start the year, but they have underestimated it five of the past six years (including 2025 when they saw 6,755 at the start of the year and we ended at 6,845). Currently we’re about 3.5% away.
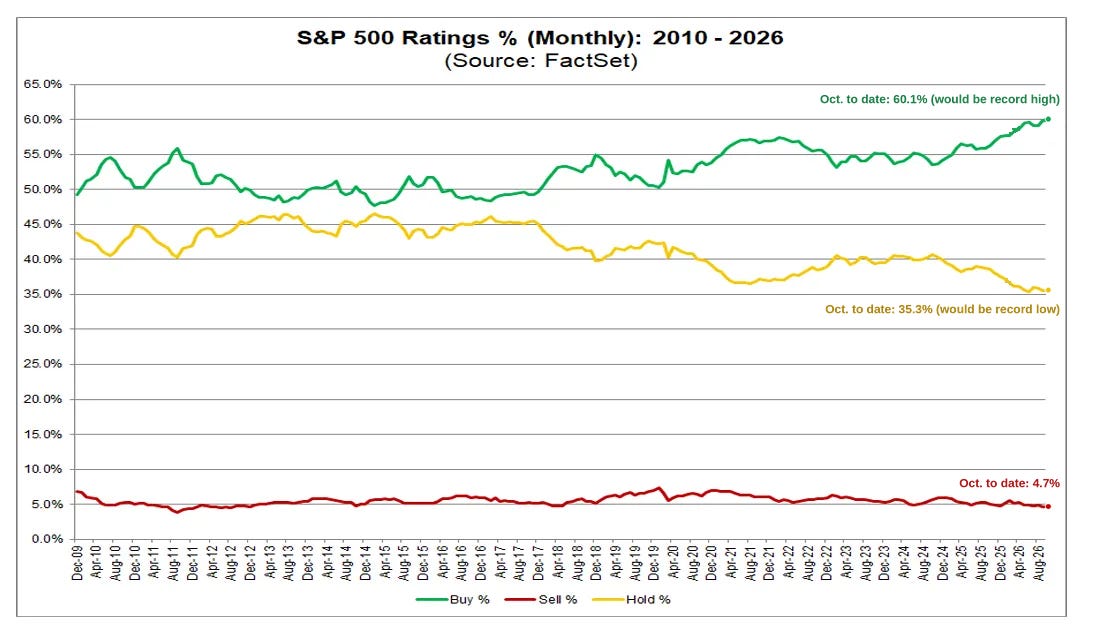
In terms of analyst ratings, buy and hold ratings continue to dominate with buy ratings at 60.1%, which would be a new month-end record high (to 2010) if it holds through the end of October. The 5-year month-end average is 55.8%.
Hold ratings are at 35.3%, which would be a new month-end record low (to 2010) if it holds, vs the 5-year month-end average of 38.7%, with sell ratings at 4.7%, remaining in their narrow range since 2009 but below the 5-year month-end average of 5.6%.
Valuations Still Under Pressure
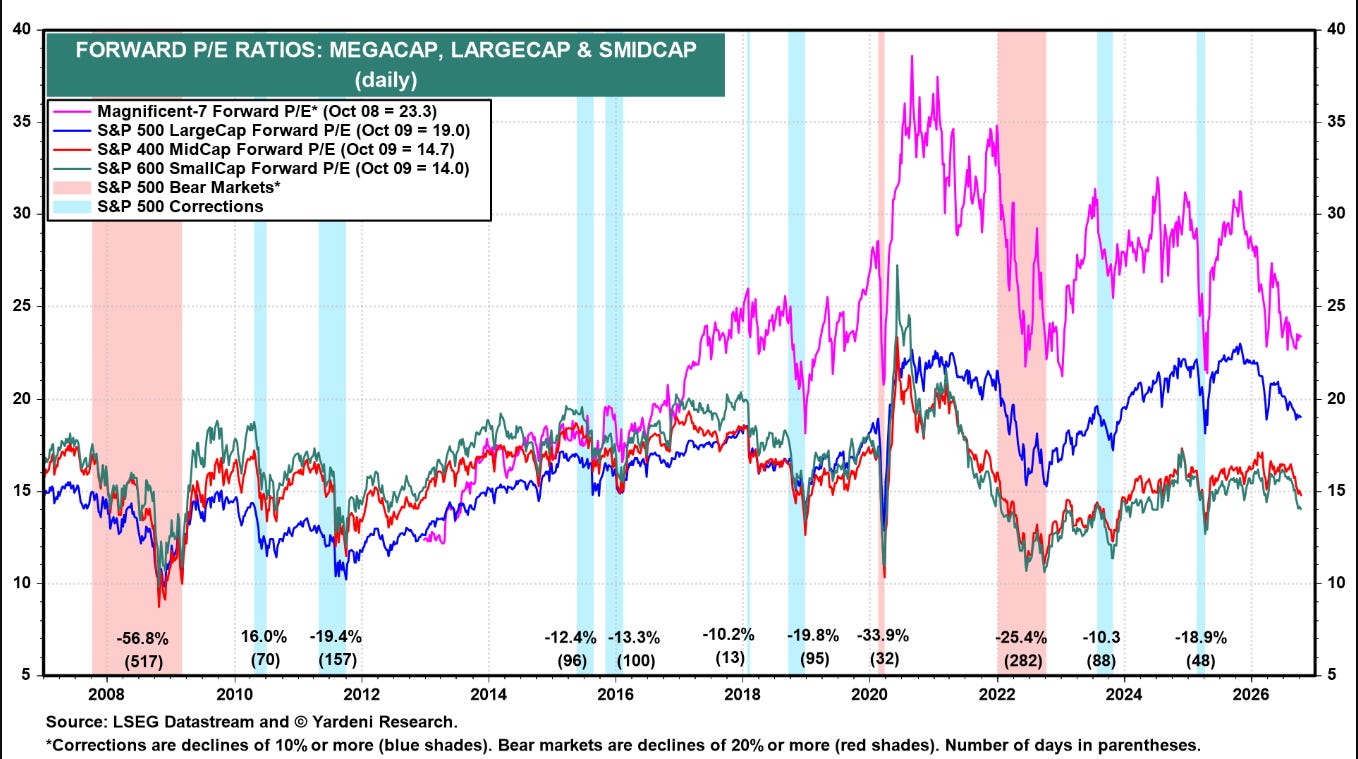
We continue to see valuations remain at or near the lows of the year (small and mid-caps the least since around liberation day).
And a reminder from Goldman two weeks ago. Presumably if we do see yields softening we’ll also see a rerating in stocks:
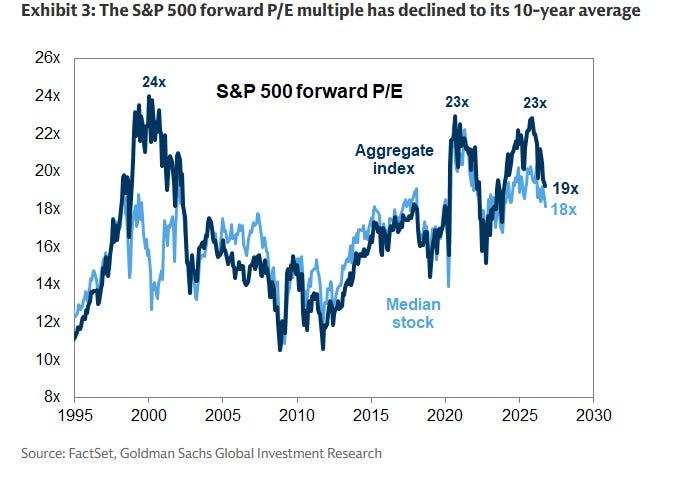
As investor positioning has declined, the S&P 500 P/E multiple has contracted to 19x, and now matches its 10-year average.Year to date, the S&P 500 has risen by 13% but the consensus forward 12-month EPS estimate has risen by 29%. The result is a 13% decline in the forward P/E multiple, which has declined from 23x a year ago to 19x today.
Breadth – Are We Past the Bottom?
Unlike last week, breadth metrics more universally improved this week outside of the Nasdaq.
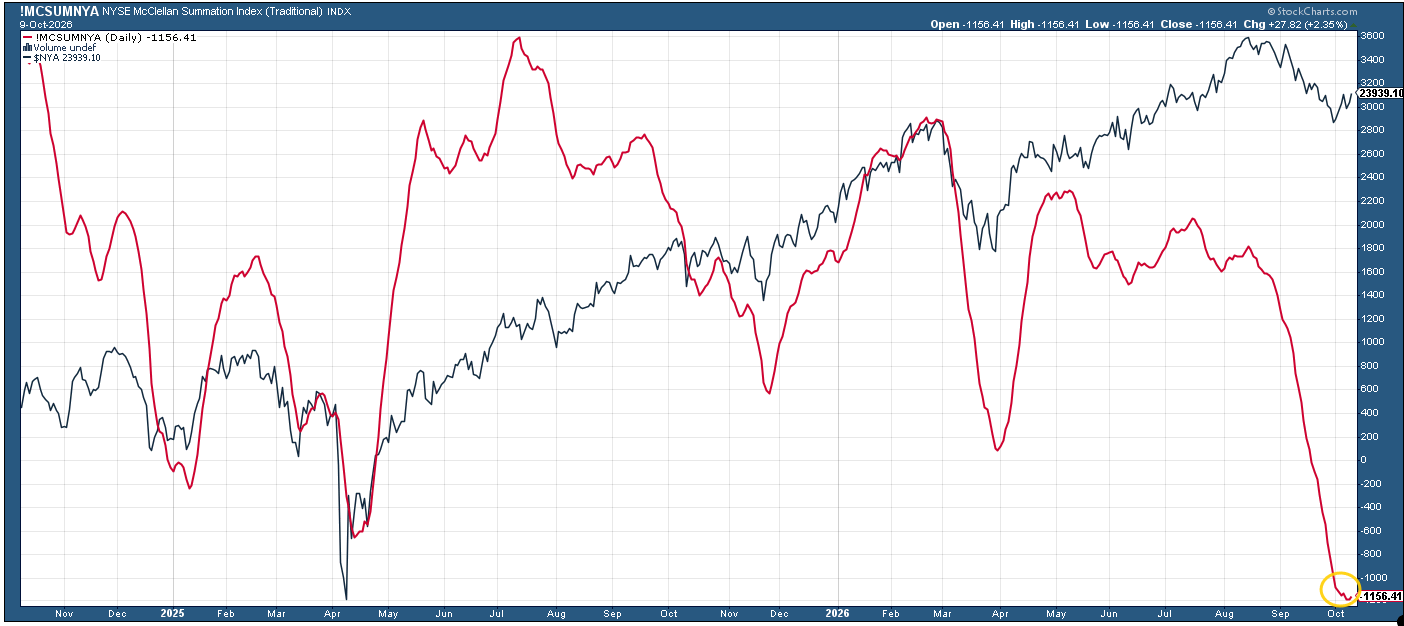
The McClellan Summation Index (red line, broadly whether the typical stock is doing relatively better or worse than the index) finally turned up (if you really squint). As I mentioned two weeks ago “you can see, though, when it does rebound, rallies in the NYSE Composite are generally fairly powerful.”
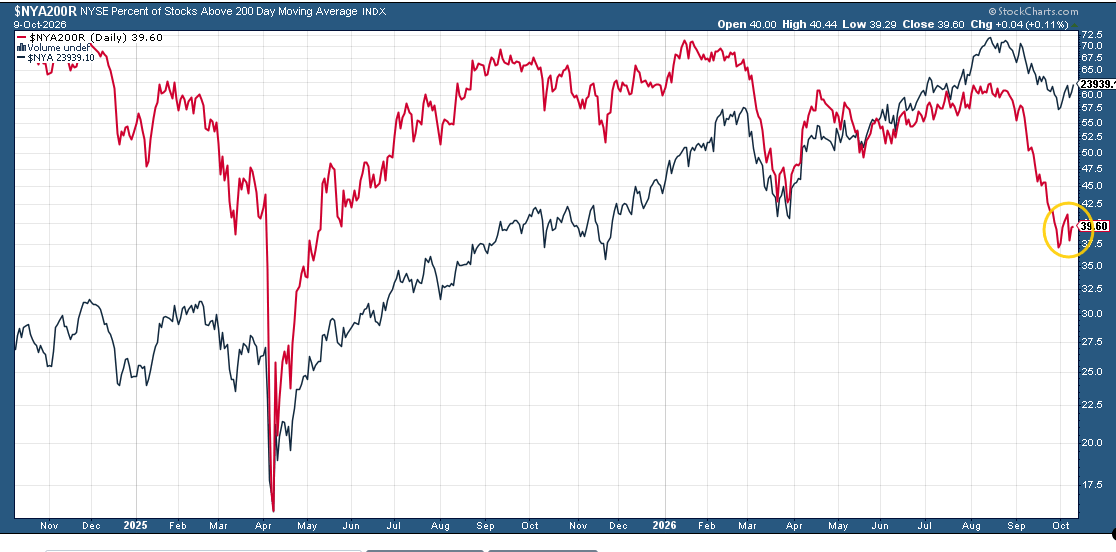
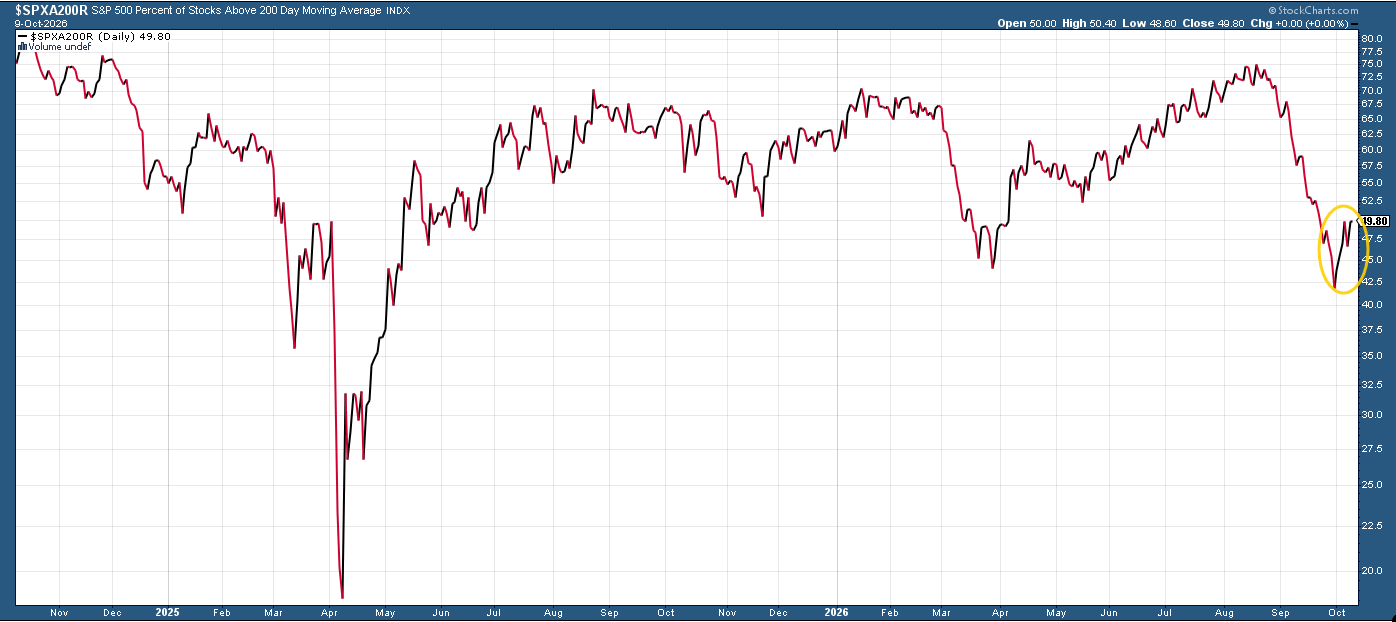
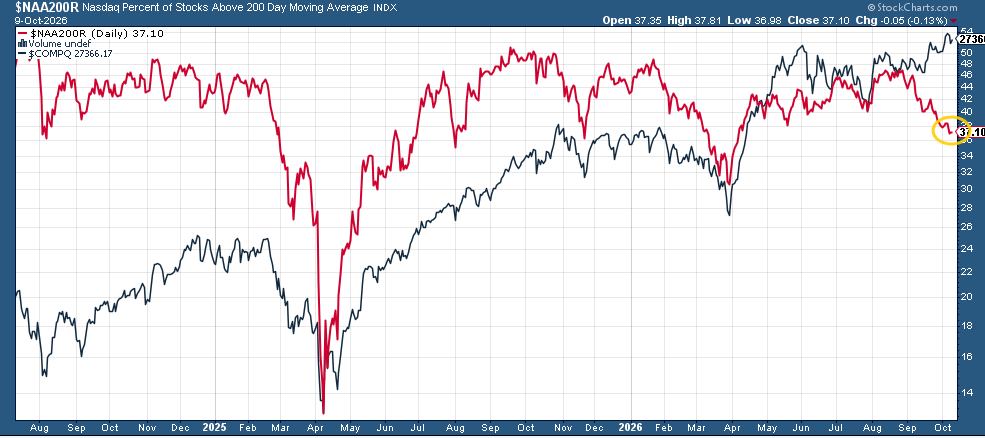
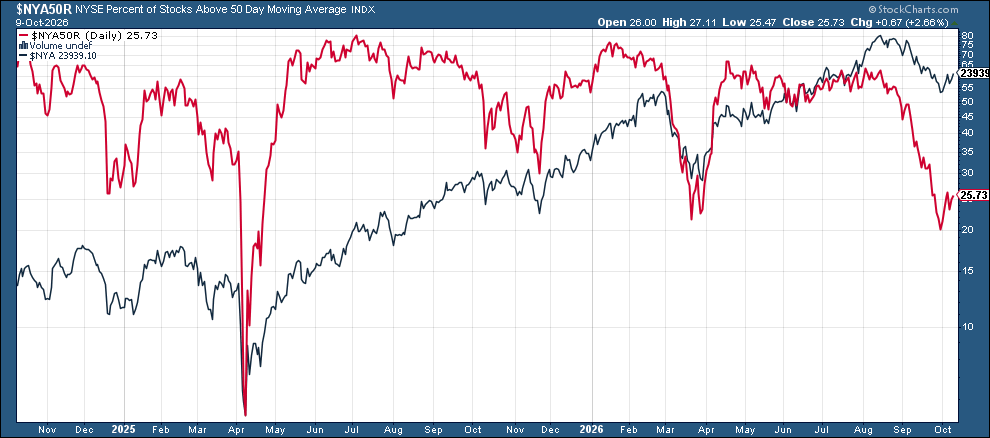
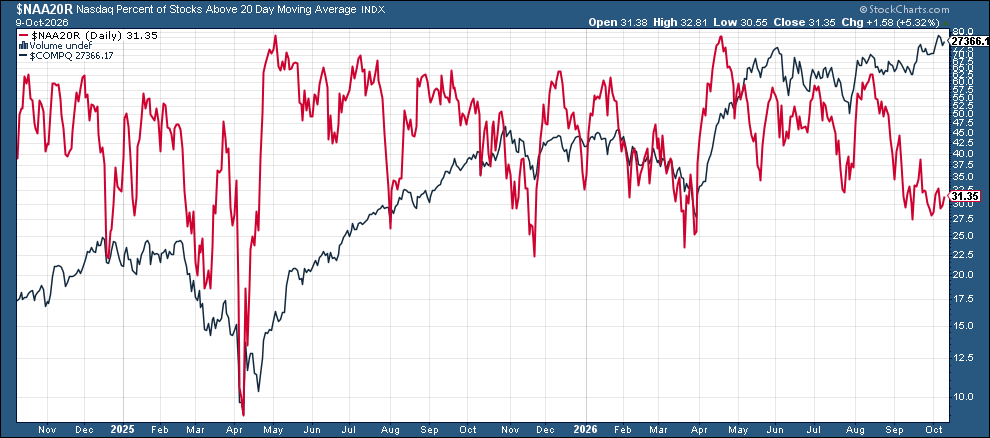
Percentage of stocks over 200-DMAs (red lines), are also all off the lows for the NYSE and S&P 500.
But haven’t bounced yet for the Nasdaq.
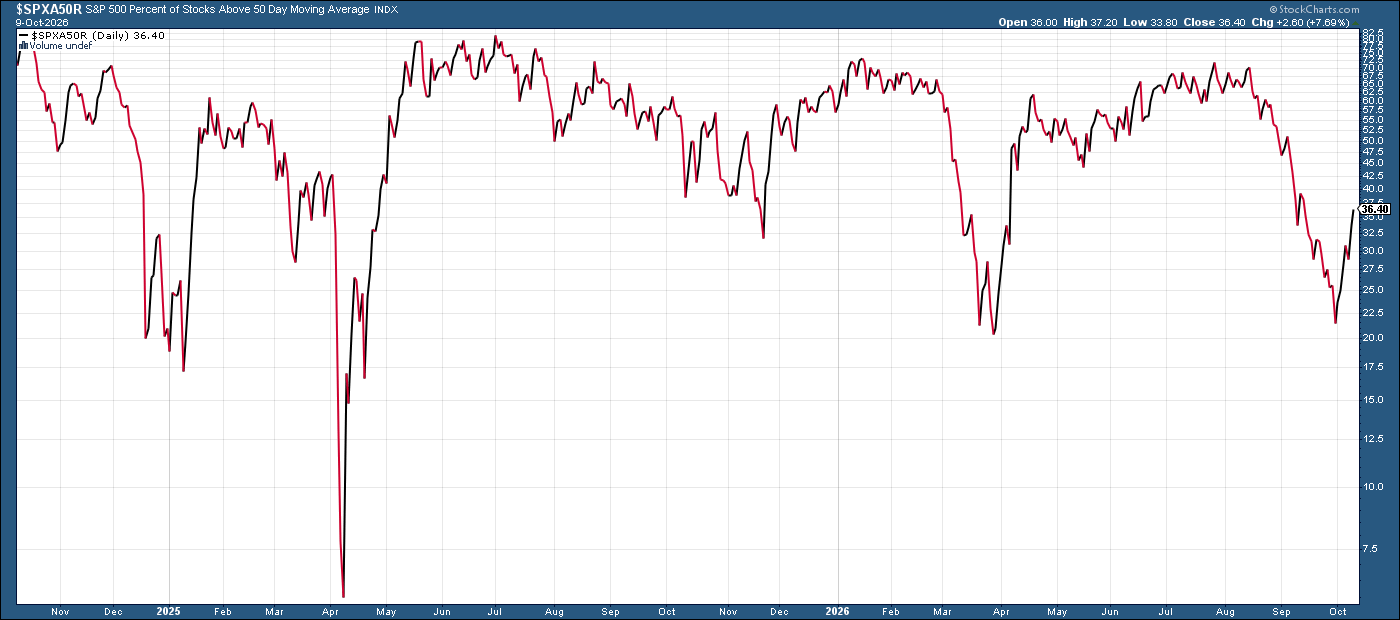
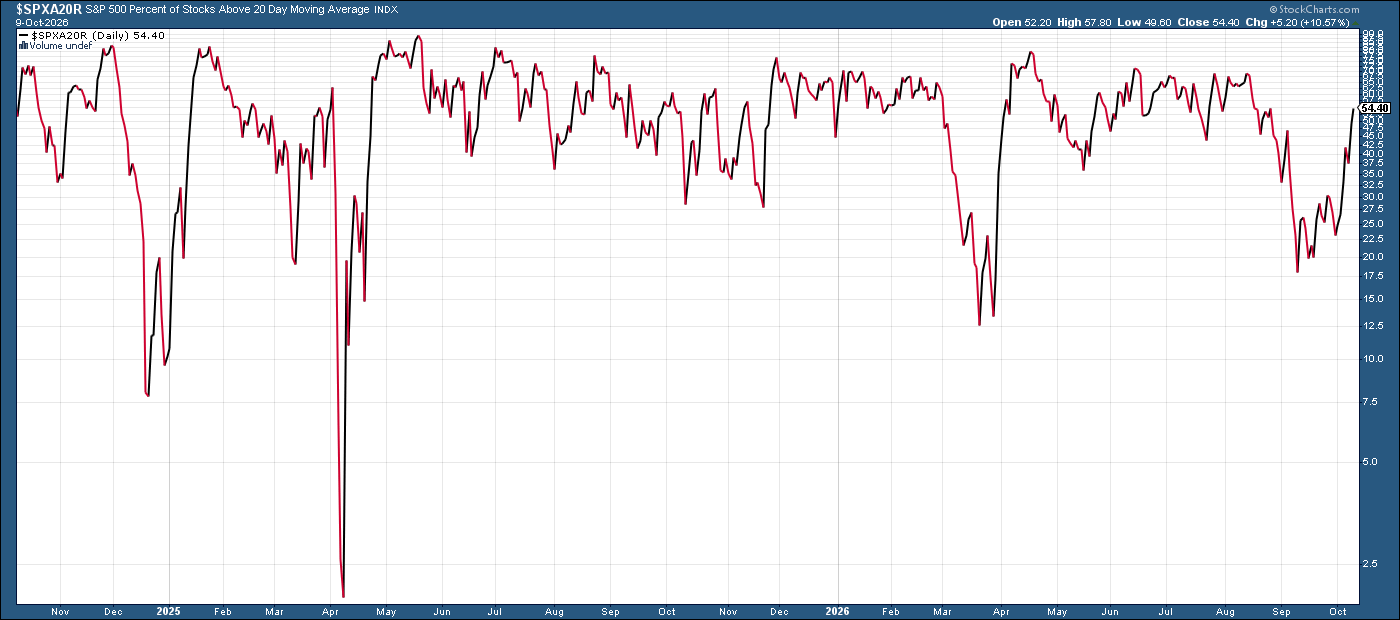
And a similar story for shorter-term 50 & 20-DMAs.
50-DMAs
20-DMAs
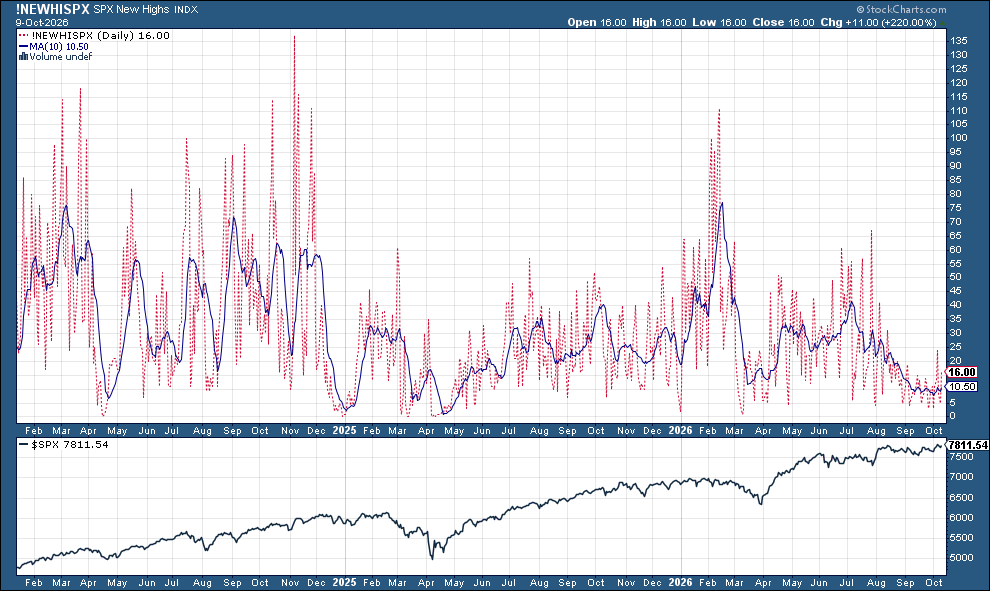
SPX new 52-week new highs also stopped their deterioration (with the caveat they didn’t have much room to fall).
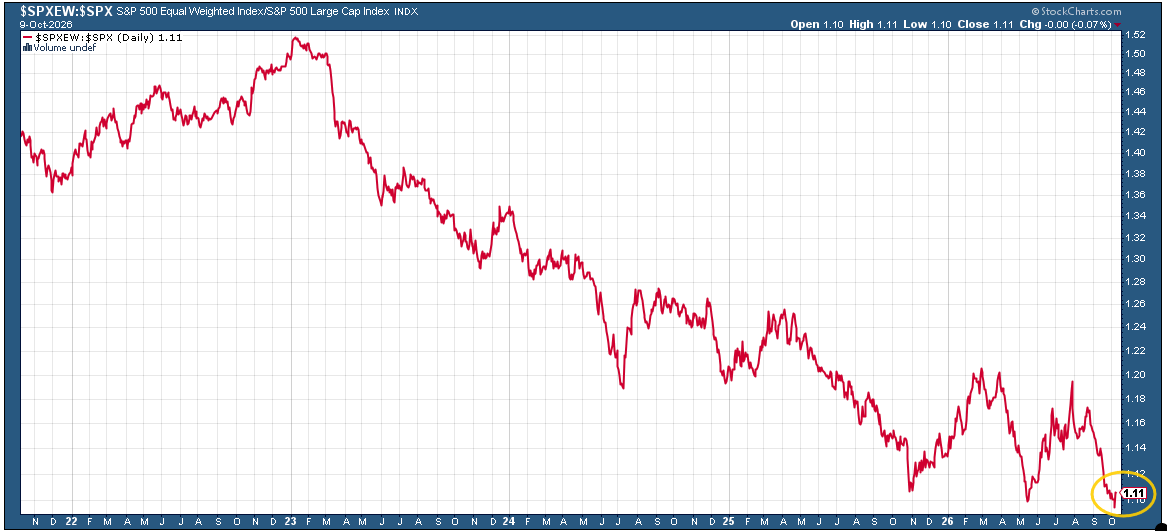
And the ratio of the equal-weight SPX to the cap-weighted bounced after hitting the lowest level since 2003.
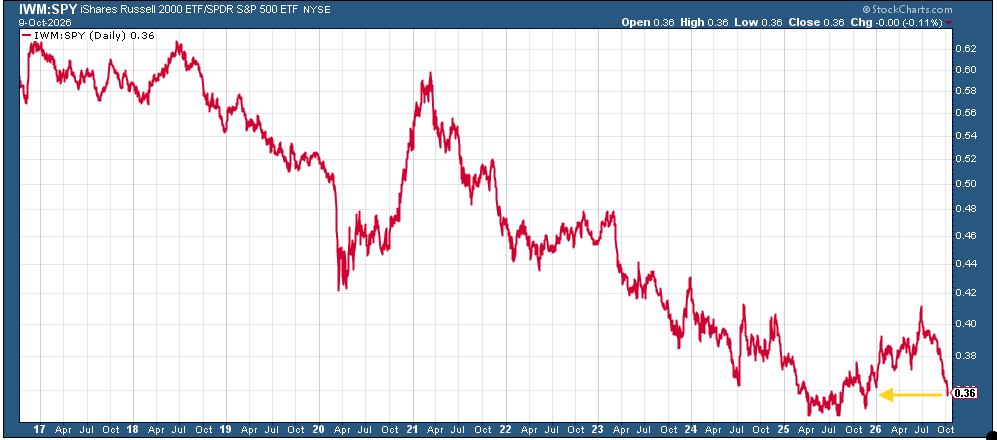
But the ratio of small caps to large caps (Russell 2000 to SPX) continues to drop now at the lows of the year.
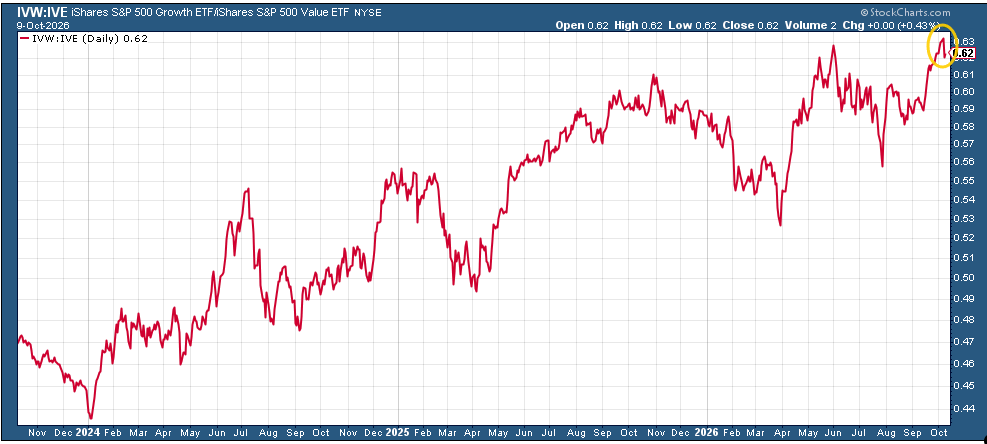
While S&P 500 growth/value fell back after making an all-time high last week.
Positioning Eased But Remains Bifurcated
Deutsche Bank:
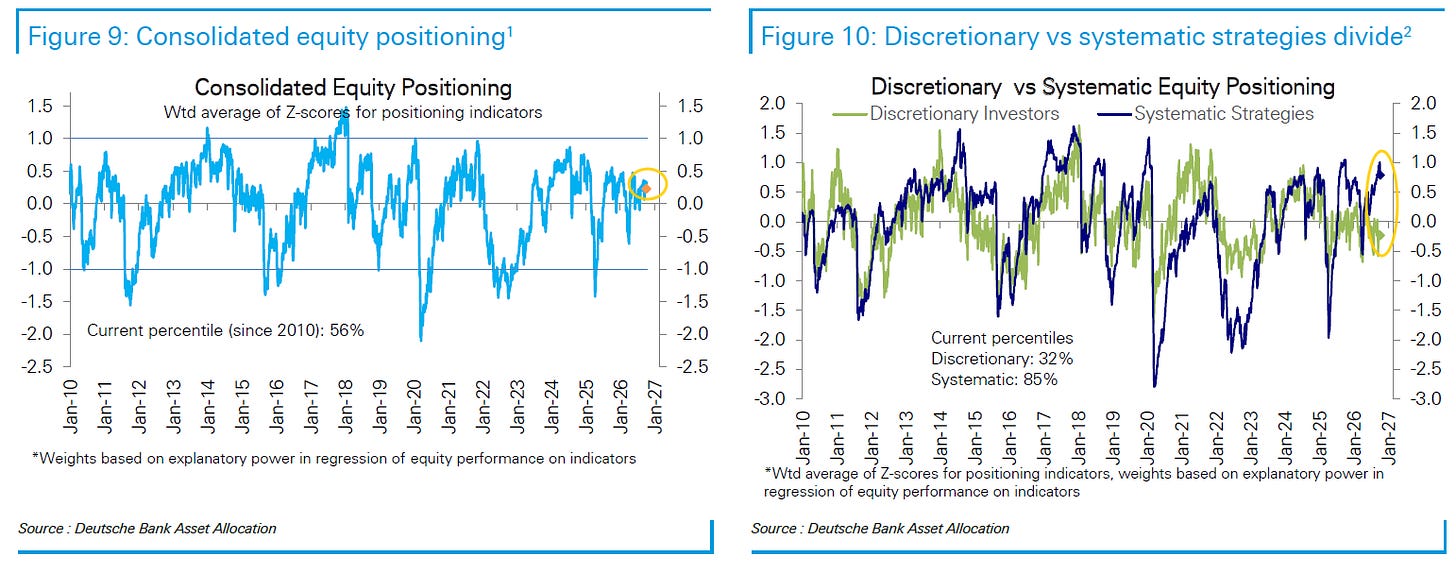
Our measure of aggregate equity positioning edged lower this week but remained modestly overweight, at 0.23 standard deviations above its historical average, or the 56th percentile.
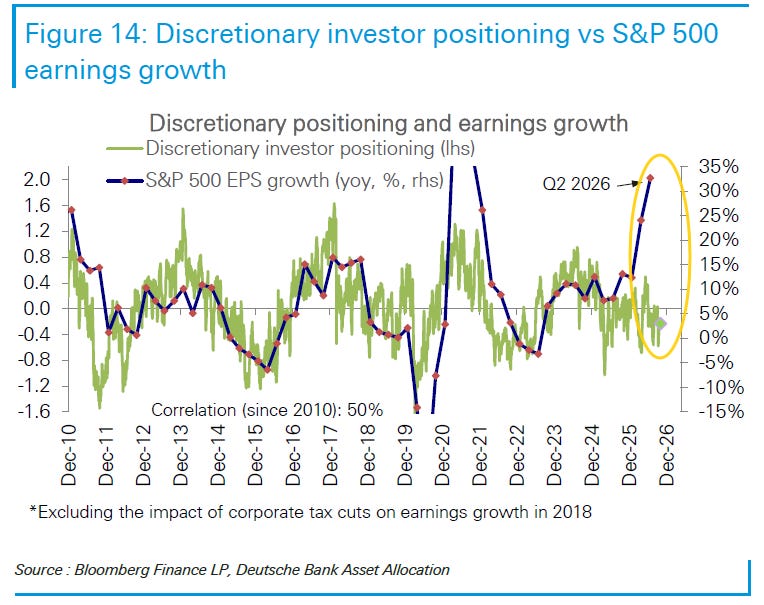
Discretionary investor positioning stayed modestly underweight, at −0.23 standard deviations, or the 32nd percentile.
Systematic strategies’ positioning slipped from elevated levels but remained overweight, at 0.79 standard deviations, or the 85th percentile.
Large-cap positioning inched lower but remained overweight, at 0.53 standard deviations, or the 81st percentile.
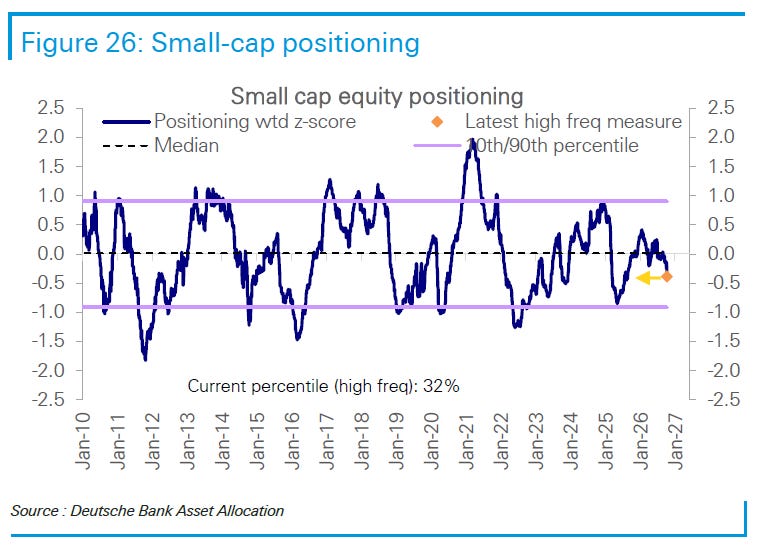
Small-cap positioning became more underweight, falling to −0.39 standard deviations, or the 32nd percentile.
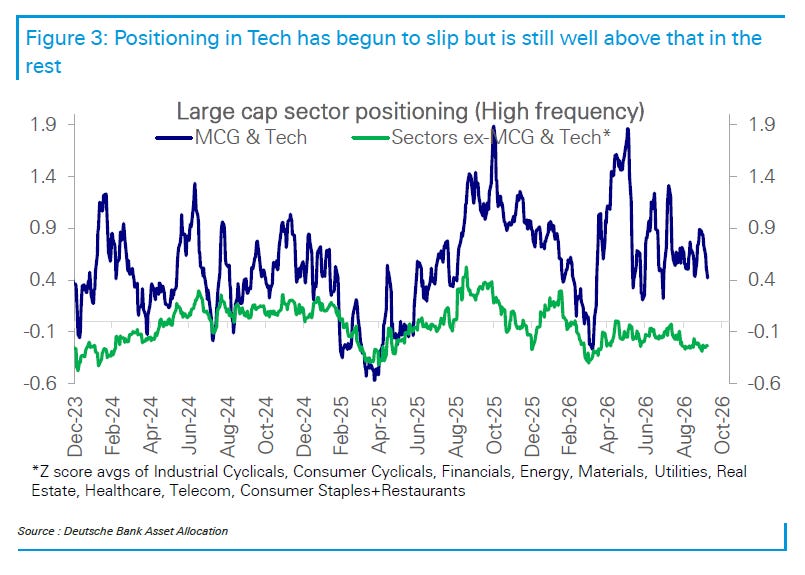
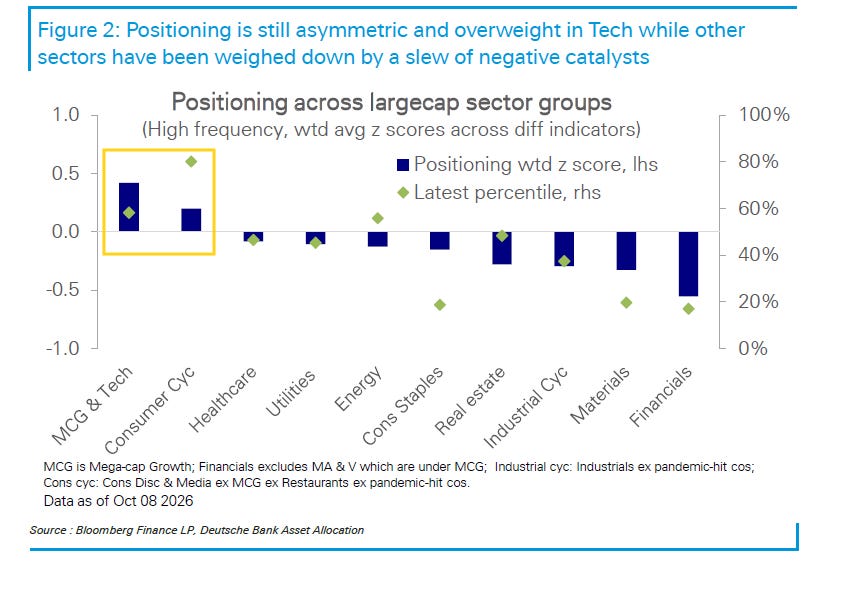
Sector positioning remains asymmetric, with Tech still overweight while other sectors have been weighed down by a series of negative catalysts. Although Tech positioning has begun to decline, it remains overweight. Elsewhere, those catalysts have taken a toll on positioning, even as the broader index has remained resilient.
They also note discretionary positioning continues to trail earnings growth.
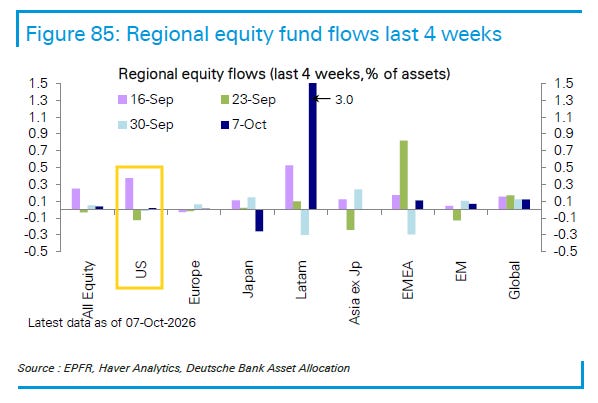
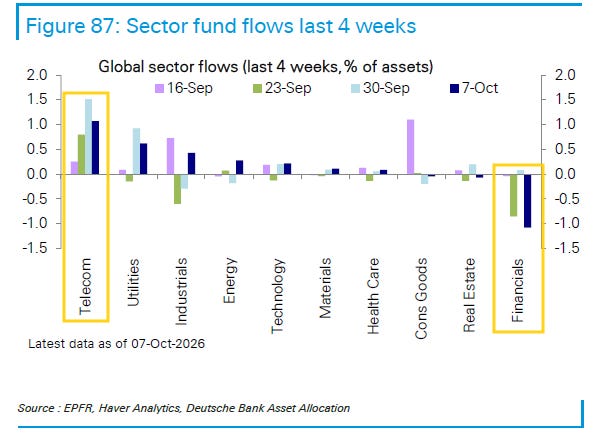
Last week DB did see US inflows at $3.3bn after two weeks of outflows, led by Tech ($3.5bn), although as a percent of assets Communications led for a third week. On the other hand, Financials (-$3.0bn) registered their biggest outflows in seven months.
That though is in direct contrast to Goldman who said
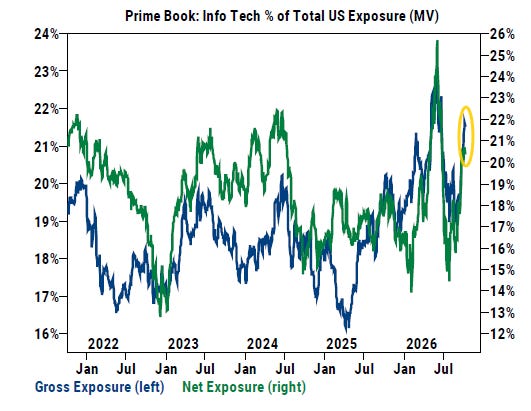
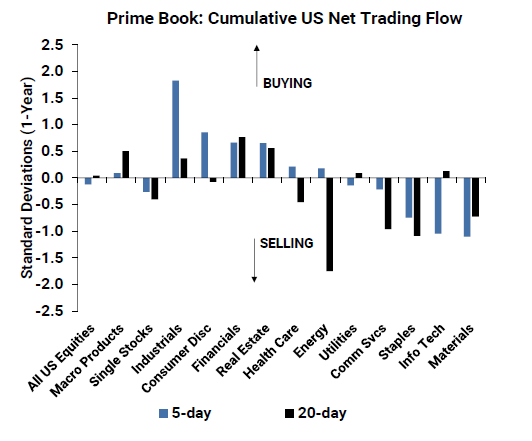
after being the most net bought US sector in 4 of the prior 5 weeks, Info Tech was by far the most $ net sold this week (-1.0 SDs 1-year), driven by long-and-short sales, which points to profit taking and increased hedging activity (especially on Thursday Oct 8th). Tech Hardware, Macro Products, and Semis & Semi Equip were the most net sold, while Software was the most net bought. Info Tech net exposure (as % of total US Prime net MV) now stands at 19.5%, in the 76th/70th percentiles vs. the past year/five years.
They saw outflows led by Health Care:
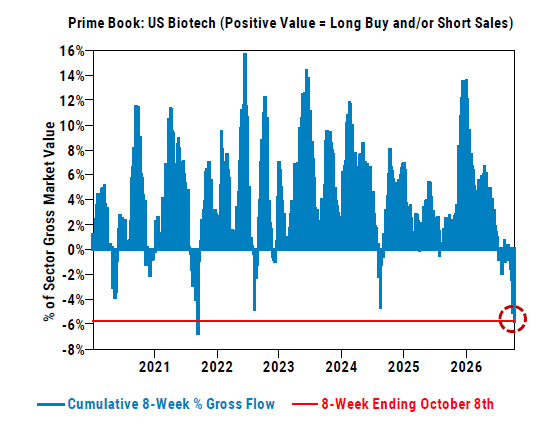
HFs actively unwound risk in US Health Care for a 4th straight week, driven by short covers outpacing long sales (1.6 to 1). Most subsectors saw de-grossing activity this week, led by Life Sciences Tools & Svcs(long sales > short covers) and Biotech (short covers).
On a subsector level, it’s worth noting that 1) Biotech stocks collectively have seen risk unwinds in 7 of the past 8 weeks, driven by long sales and to a lesser extent short covers (~3 to 1), 2) since mid-August, Biotech has seen the largest $ de-grossing activity among all US subsectors (not just within Health Care), and 3) in cumulative % terms on a trailing 8-week basis, magnitude of the recent de-grossing in Biotech stocks is the largest in more than five years.
US Biotech long/short ratio now stands at 3.22 (vs. peak level of 5.36 in Dec ’25), in the 7th/37th percentiles vs. the past year/five years.
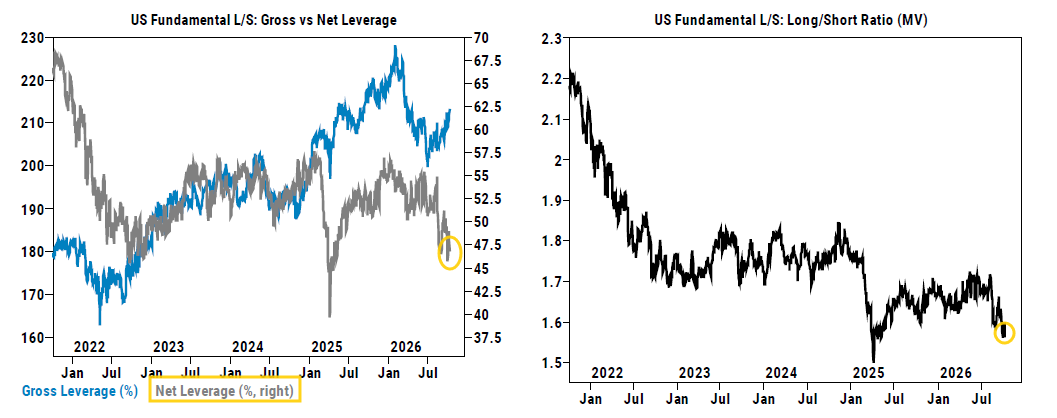
Overall hedge fund positioning according to Goldman remains light with US Long/Short Fund gross leverage at the 53rd percentile one-year (but up from the 34th the prior week and is at the 88th five-year percentile), while US net leverage “increased modestly for the first time in four weeks” from “the lowest level since Apr ’25 (around ‘Liberation Day’)” still at just above five-year lows in the 2nd percentile. The US Fundamental long/short ratio (MV) remained at the 0 percentile one-year (1st five-year). So hedge funds increased longs and shorts proportionately last week, leaving quite a bit of room for hedge funds to reengage with the market.
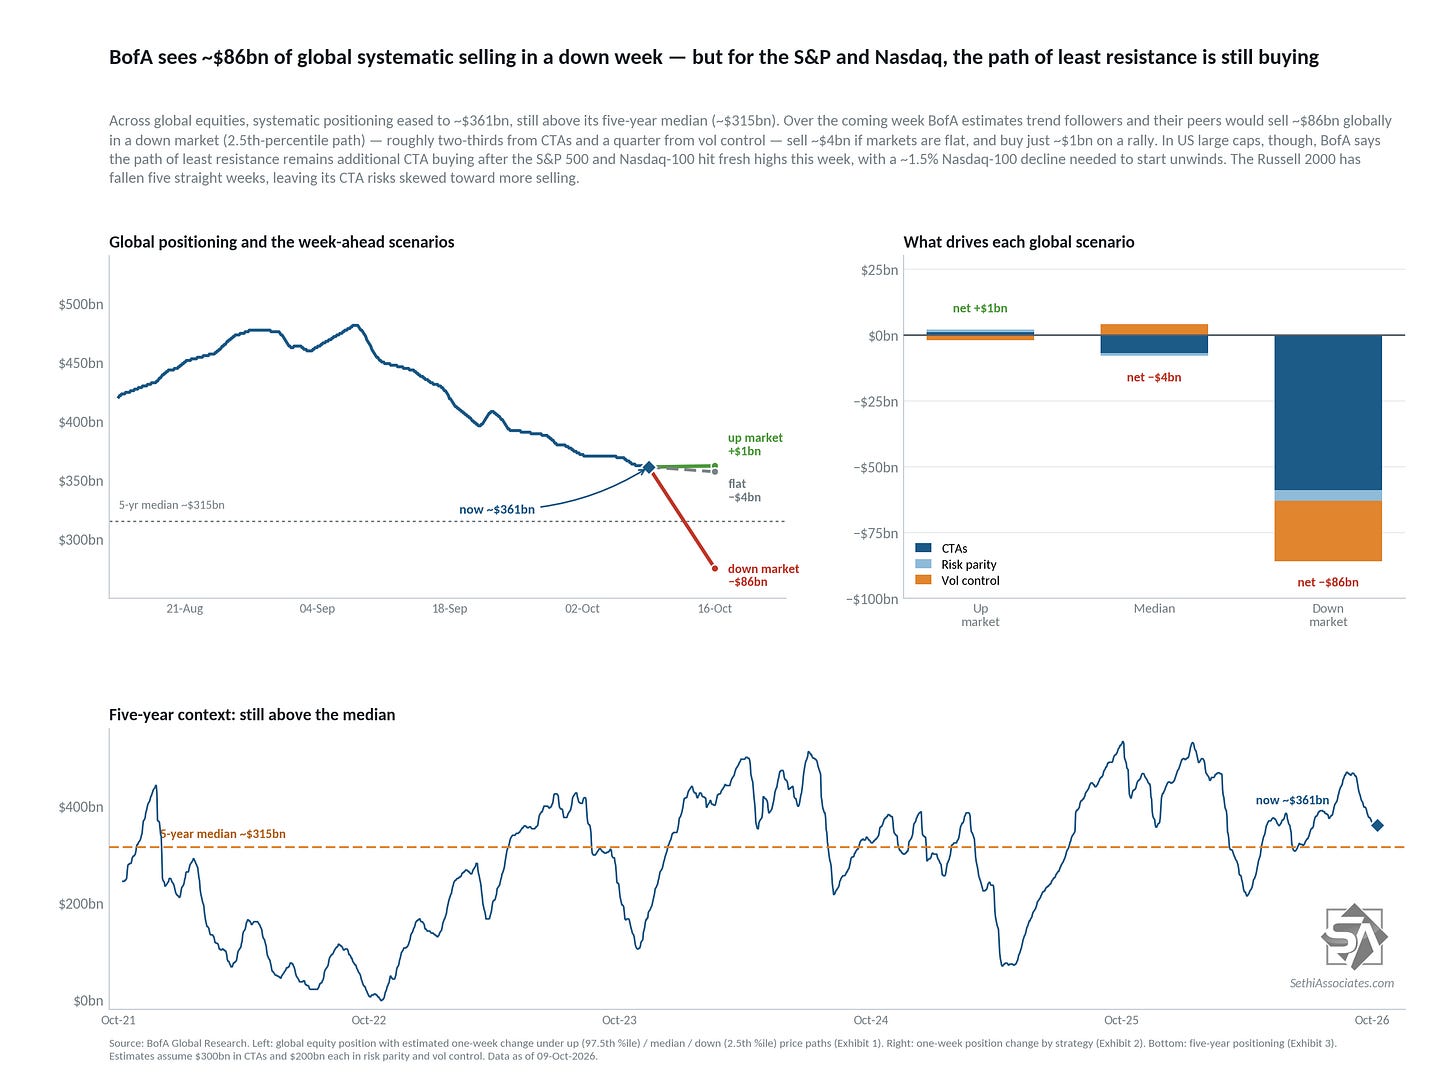
Turning to systematic positioning, BofA again saw selling from CTAs last week, but in the US say trend followers remain “firmly long” large caps with “the path of least resistance… additional buying”:
Trend followers remain firmly long US large cap equities, with both the S&P 500 and Nasdaq-100 reaching fresh highs this week…. The Russell 2000 has now declined for five consecutive weeks, leaving CTA flow risks skewed toward additional selling…. In US large caps, the path of least resistance remains toward additional buying, but a decline of roughly 1.5% in the Nasdaq-100 would be sufficient to trigger a start of unwinds.
The sell trigger for the S&P 500 now sits around −3.0% (from −2.4% last week). The Nasdaq-100 has a listed sell trigger at ~−1.5% (none was listed last week), making it the closest of the three. The Russell 2000 now has triggers on both sides: a sell trigger at −2.4% and a buy trigger at +2.7% (from +2.0%).
Globally they see:
−$4B of selling in a flat market (from −$3B last week), as ~$7B of CTA selling (plus ~$1B from risk parity) more than offsets ~$4B of vol-control buying;
+$1B of buying in an “up” market (from roughly $0 last week), as small buying from CTAs and risk parity slightly outweighs vol-control selling (“up market” defined as the 97.5th percentile price path or ~+3.5%, similar to Goldman); and
−$86B of selling in a “down” market (from −$84B each of the prior two weeks), led by ~$59B from CTAs and ~$23B from vol control, with ~$4B from risk parity (“down market” defined as the 2.5th percentile price path or ~−2.9%, different than Goldman who uses −4.5%).
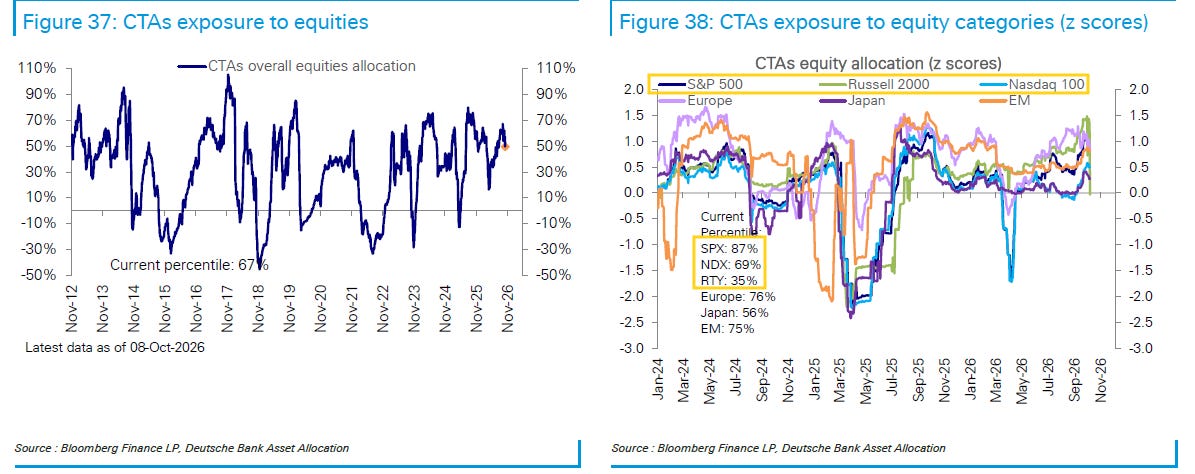
DB says they saw global CTA positioning as having “declined materially this week but remained elevated” at the 67th percentile to 2010 (but down from the 77th the prior week and the 89th four weeks ago), but unlike BofA they US positioning as having fallen to the 67th percentile from the 91st percentile the prior week.
Much of that softening though was in the Russell 2000 which dropped from the 95th percentile to just the 35th. The Nasdaq-100 dropped to the 69th from the 73rd, while the S&P 500 edged to the 87th from the 90th.
“Further increases in equity exposure are still likely to depend more on declining volatility than on stronger trend signals.”
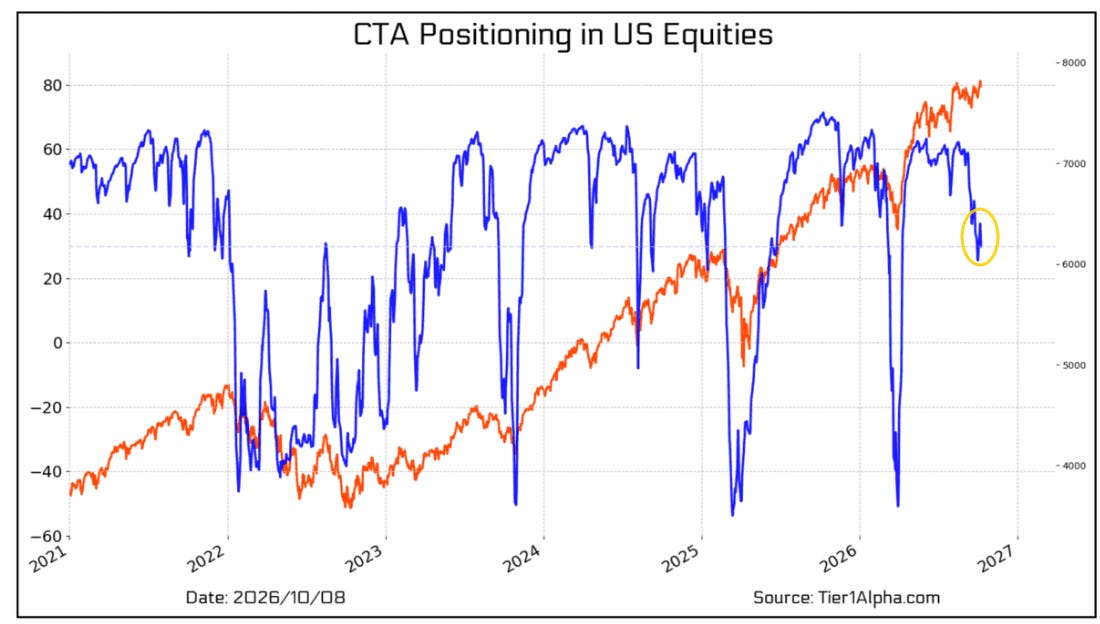
Here was Tier1Alpha’s take from Friday morning:
For now, broader market conditions remain stable, with systematic positioning showing little change. However, continued weakness in momentum could begin to bring some of the key risks we have been highlighting into play, particularly on the volatility side. While this warrants a more cautious approach as we close out the week, conditions still favor closer observation rather than immediate action, at least from a broader risk perspective.
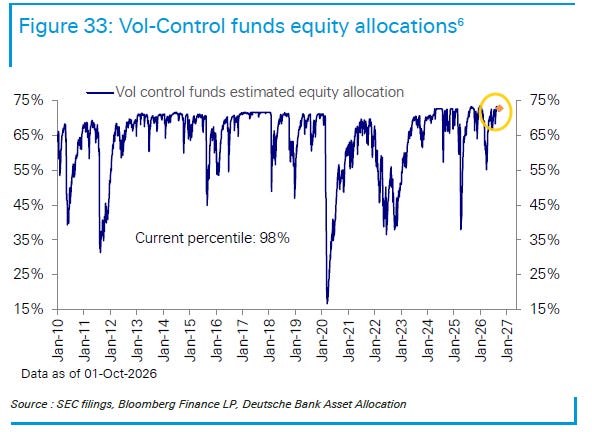
Looking at vol control* positioning, DB finds that it “increased this week and remains elevated” at the 99th percentile, remaining a risk if volatility were to spike. That said, they found:
Their sensitivity to selloffs declined materially, making funds less responsive to downside moves than in the prior week. With positioning still stretched, capacity to add further equity exposure remains limited, although the near term flow backdrop has become more supportive as deleveraging risk under modest market drawdowns has eased.
*vol control strategies enter and exit based on changes in volatility over past windows (mostly 1-month and 3-month).
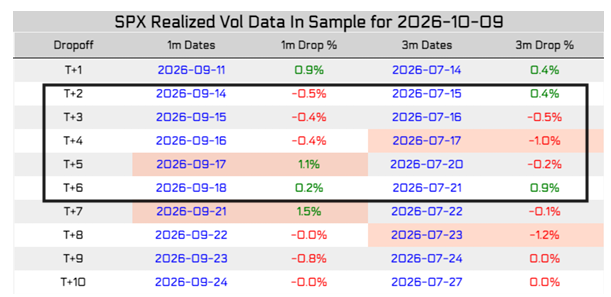
Looking at the upcoming week, it’s also more neutral than what we’ve seen in past weeks for vol control. “One 1%+ day drops off each of the 1-month and 3-month lookbacks, and there are no sub-0.4% days.
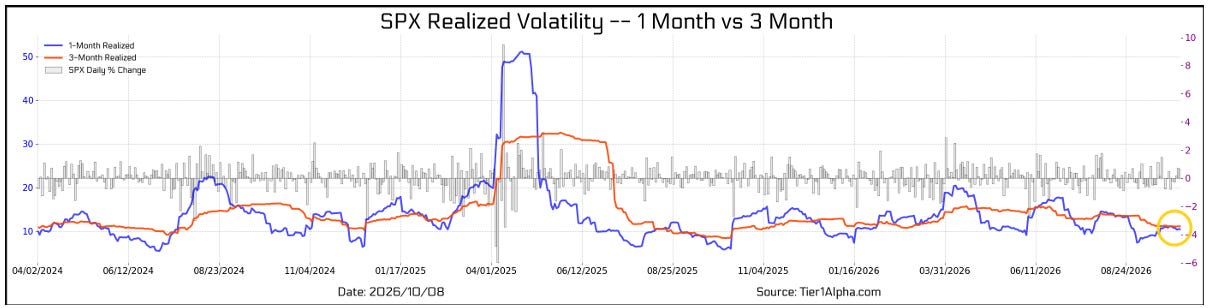
1-month volatility remains just below 3-month leaving the latter as the predominant volatility trigger according to Tier1Alpha.
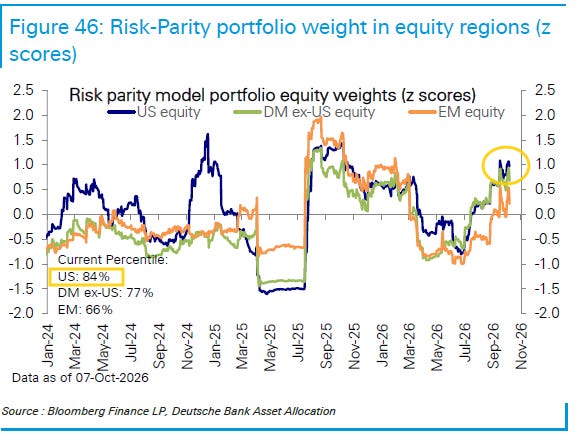
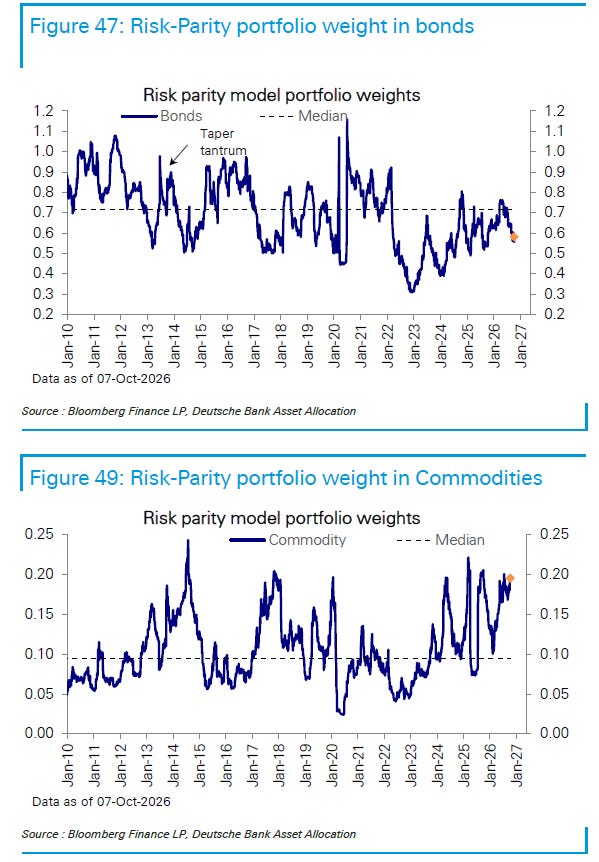
While for risk parity* DB says “equity allocations increased this week,” with the US edging up to the 84th percentile (from the 81st the prior week). Bond exposure though “dropped below historical norms” to the 30th percentile (still up from the 26th three weeks ago) while commodities remain elevated at the 97th percentile (from the 93rd).
If we continue to see more muted bond volatility, though, these could shift in the direction of increased bond exposure.
*Risk parity funds balance risk across asset classes based on relative volatility, often using leverage, to reach a target portfolio risk level.”
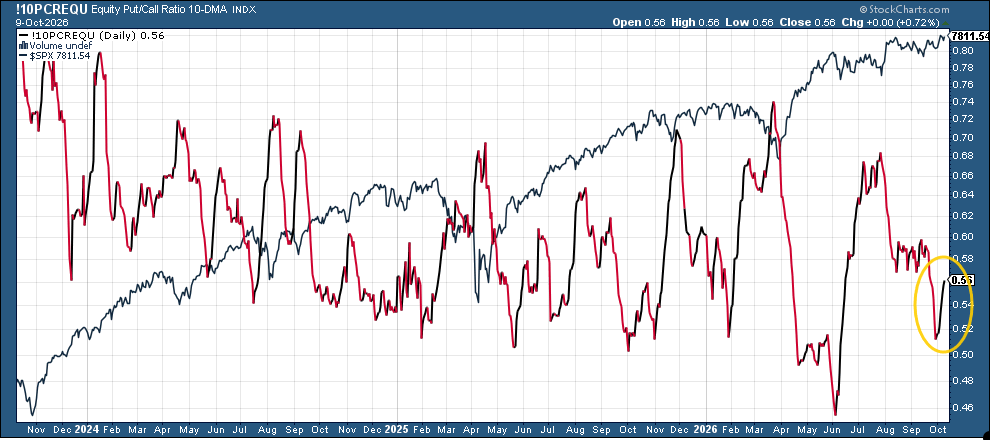
While put/call buying (which adds incremental downside/upside pressure)turned back higher after reaching levels that, as I noted last week, have often seen a rebound (earlier this year being the exception).
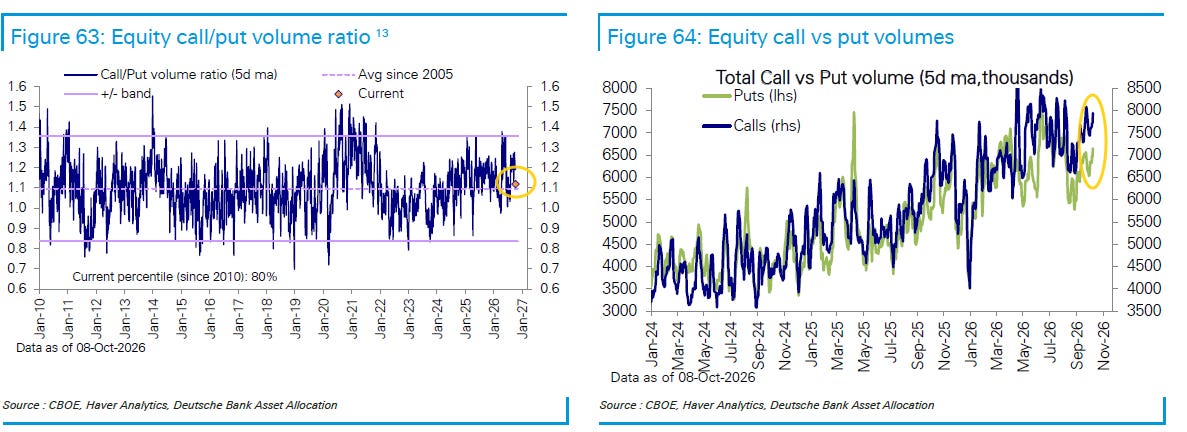
But DB said the 5-DMA of call/put volume decreased for a second week to the 80th percentile from the 90th two weeks ago, “driven again by a decline in net call volume across single-stock and index options. Within single-stock options, volume declined in MCG & Tech while rising in Consumer Cyclicals, Financials, and the defensives.”
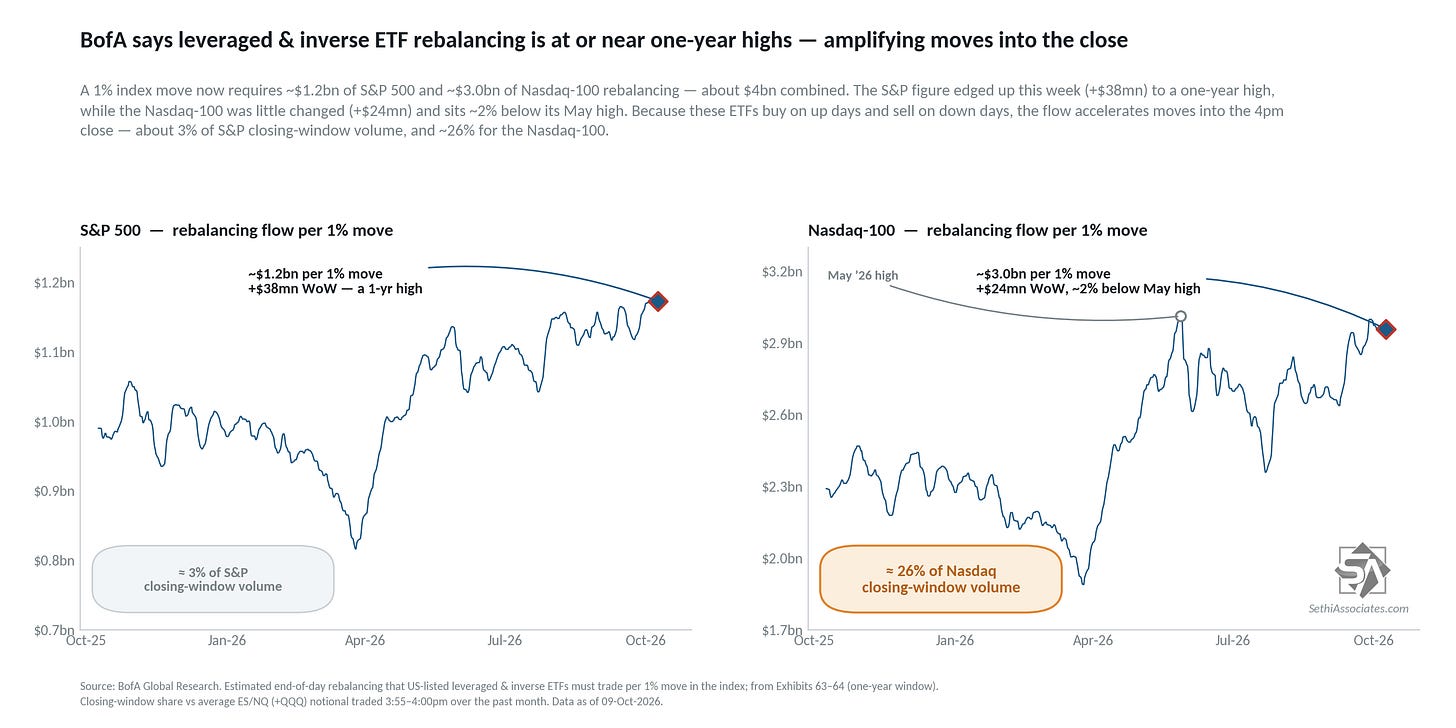
Like call buying, leveraged positioning acts as a “negative gamma source” as Charlie McElligott has put it (meaning that there is added buying/selling pressure from them in the direction of daily flows as they rebalance each day).
Rebalancing flows for SPX and Nasdaq-100 leveraged ETFs rose last week with the former now at the highs of the year and the latter just 1.8% off.
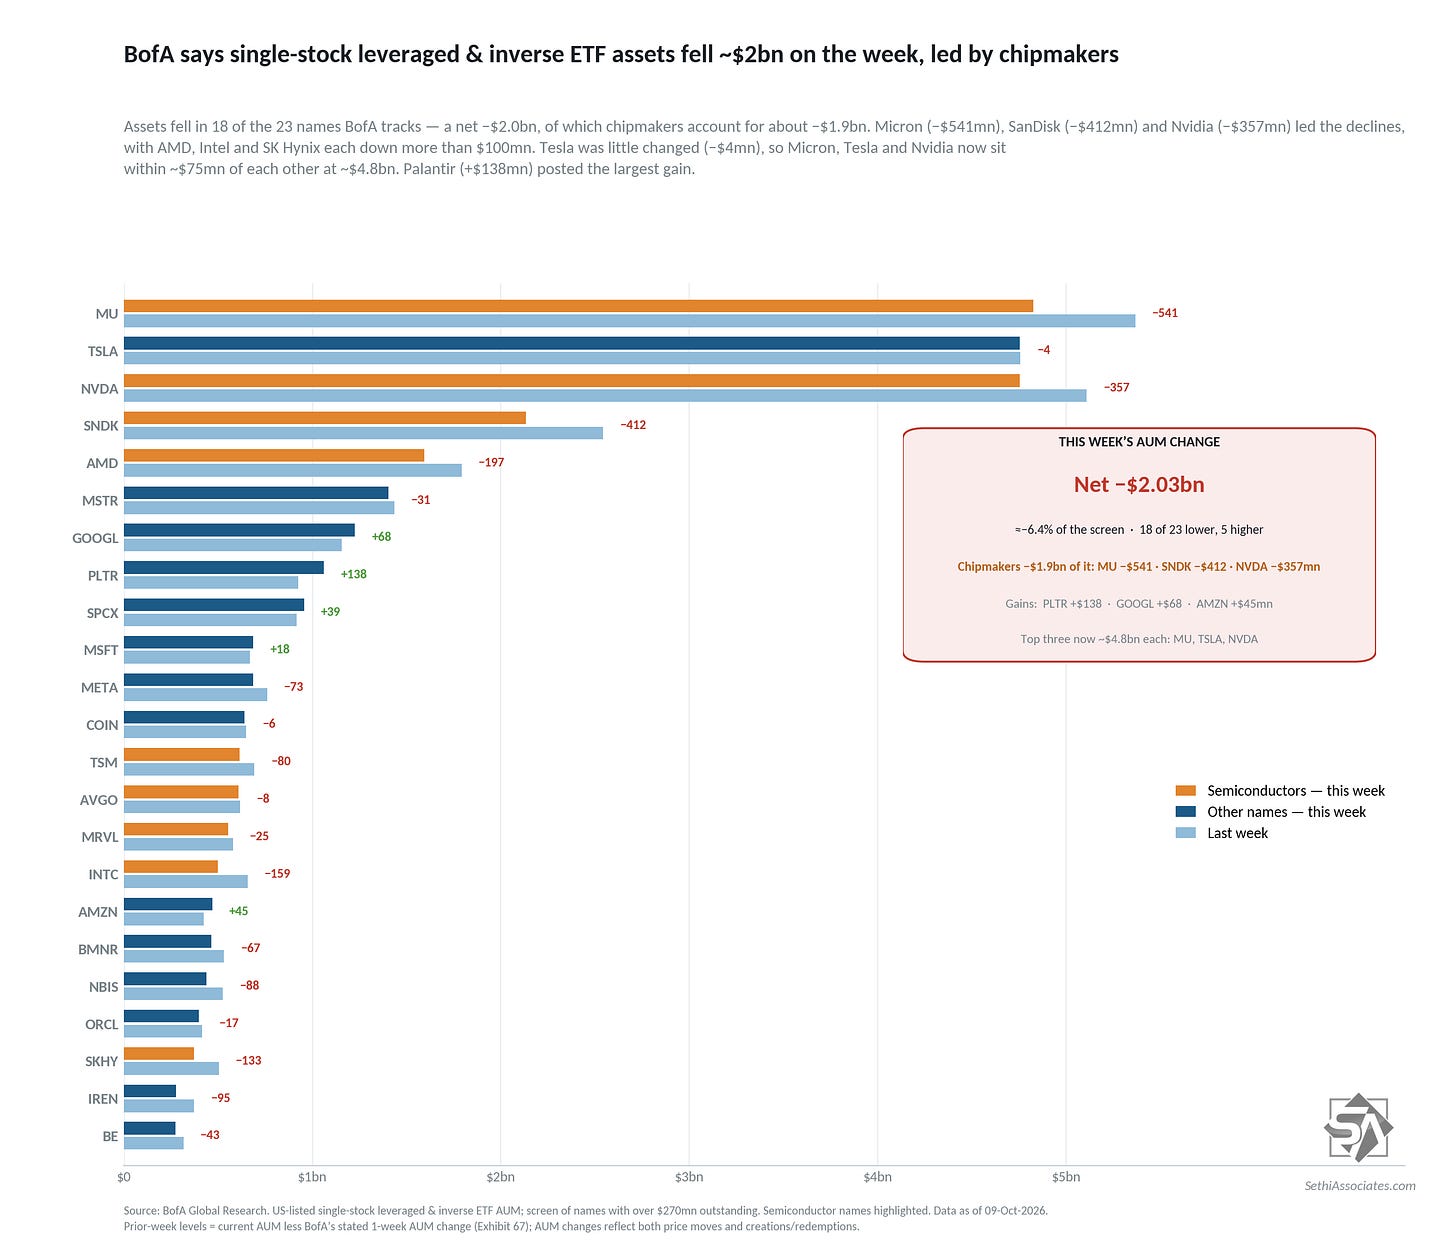
Single-stock leveraged ETF AUM though fell in aggregate for the first time in four weeks driven by semiconductors shedding $1.9B of AUM.
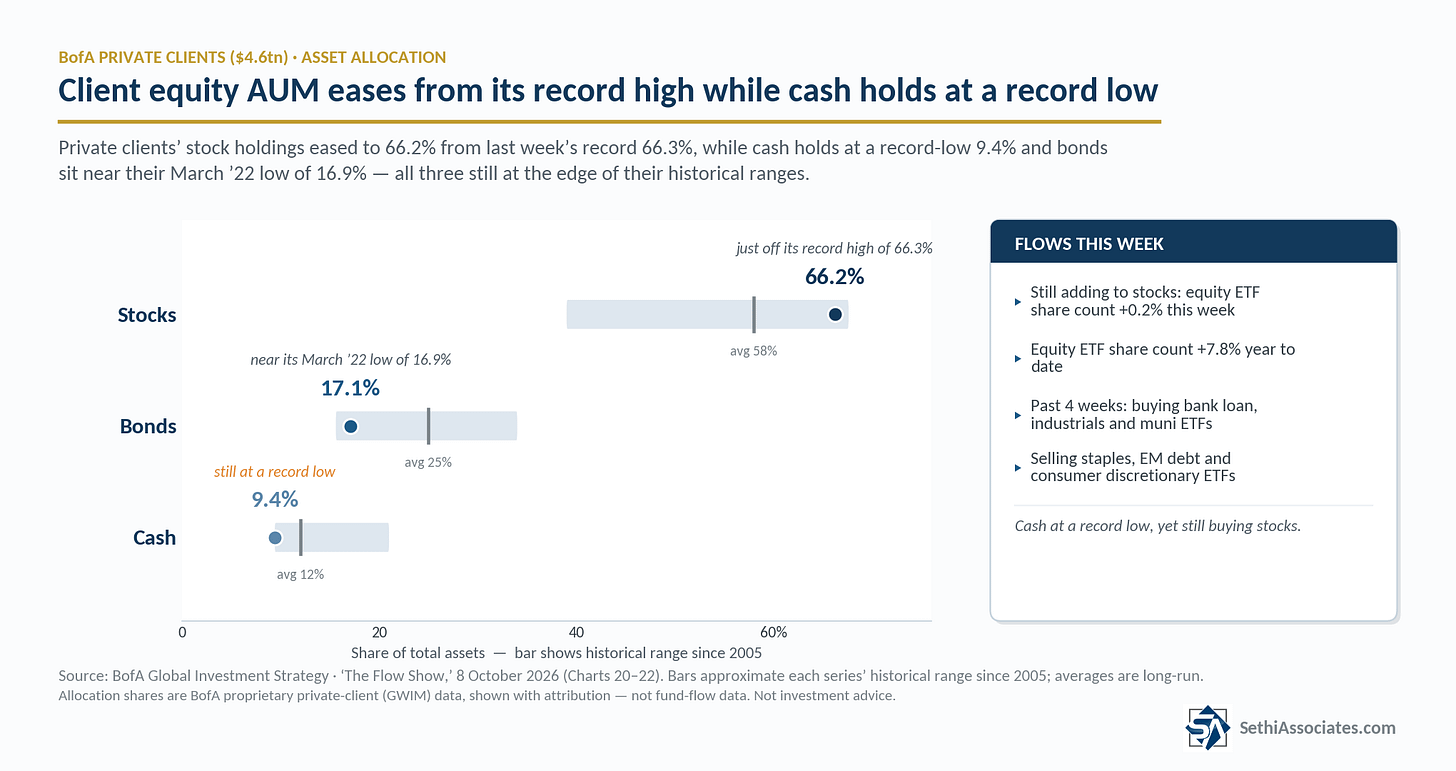
Turning to retail positioning, BofA client retail equity positioning fell back even as they say “clients adding to stocks” with AUM in stocks easing a tenth to 66.2% from a record high, while bonds remained at 17.1% (two tenths above the 16.9% September 4th that was the lowest since March 2022), while cash remained at the 9.4% record low.
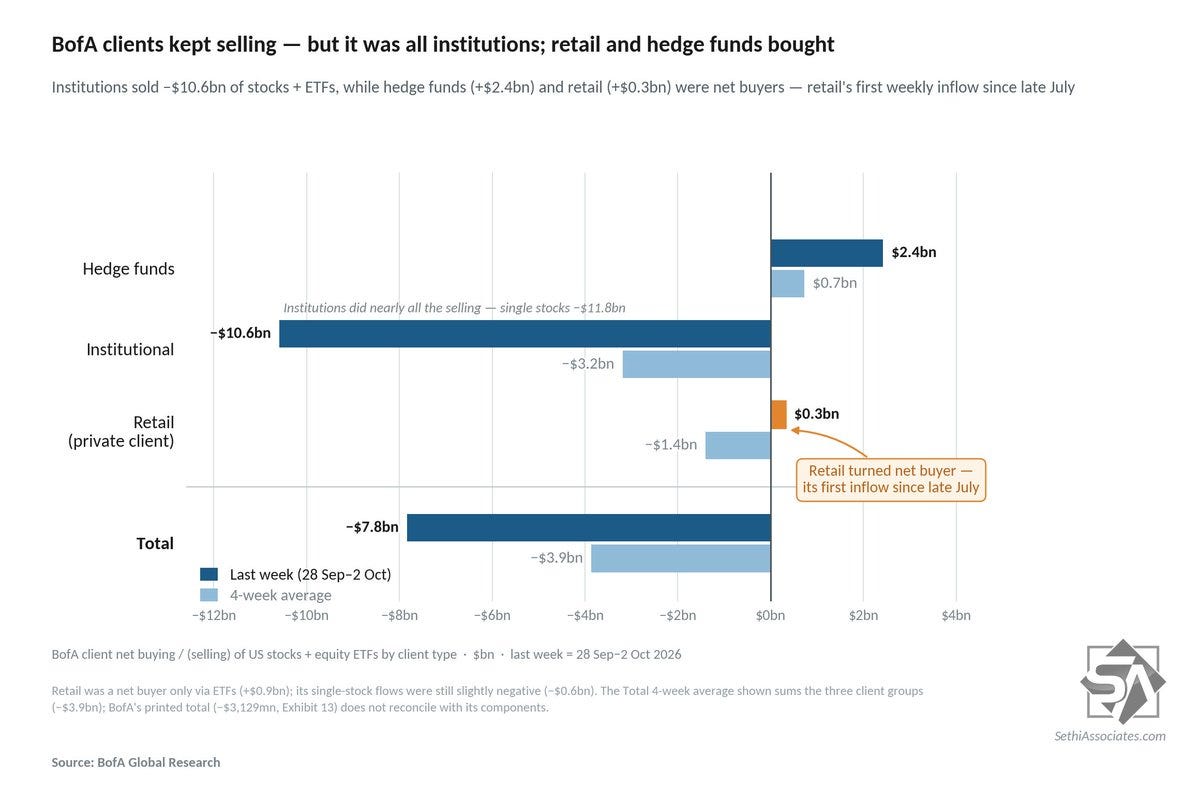
And BofA saw overall retail client flows turn positive the week before last for the first time since late July. Hedge funds also were buyers. In contrast institutions accelerated their selling consistent with seasonal patterns with an October 31 year-end date overwhelming the buying from the other two.
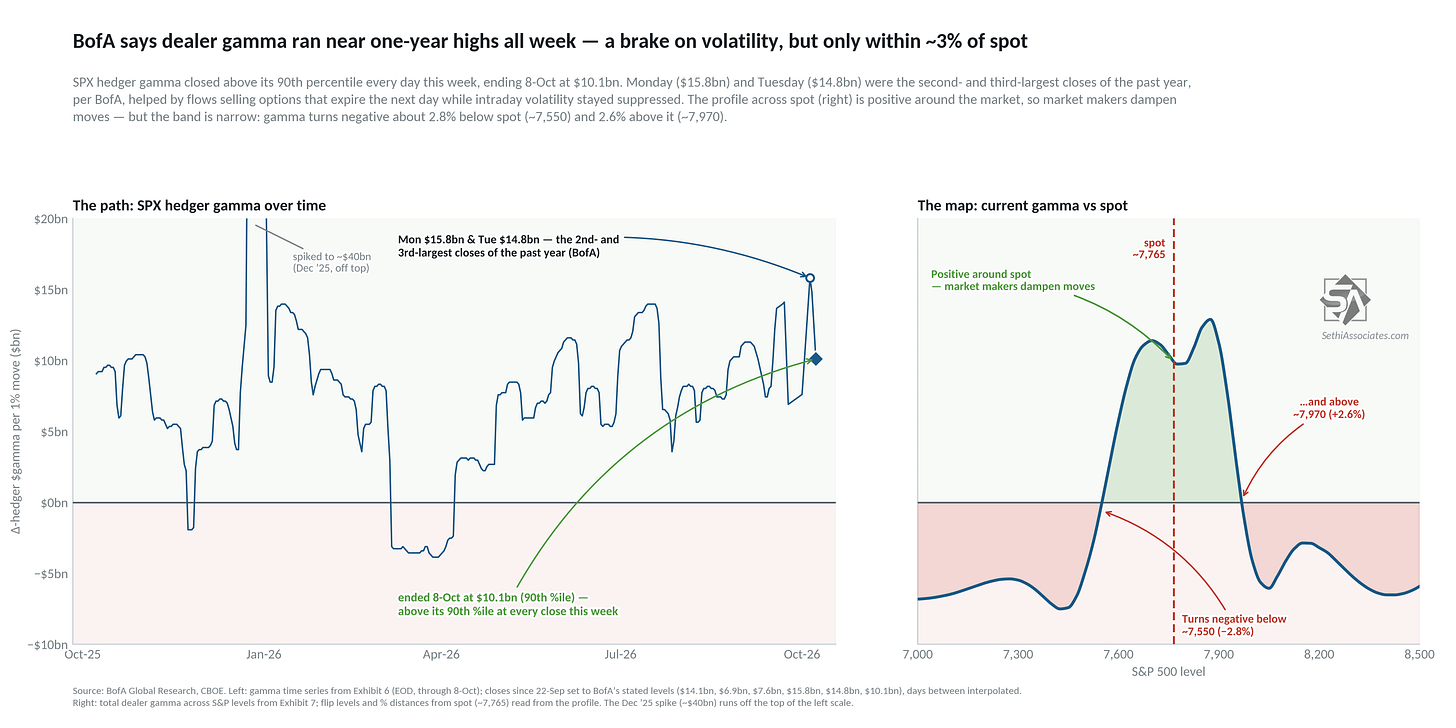
And turning to gamma* BofA saw SPX gamma last week at the 90th one-year percentile or above all week (with Monday and Tuesday “the largest closes of the year”) “as intraday realized volatility remained suppressed.”
They model this continuing into the upcoming week, but notably the curve looks more like a mountain than a hill, very elevated around 2% in either direction but falling sharply if we move outside of that range, turning negative before we even get to 3% (noting though that these are not fixed and will move daily as does spot).
*gamma plays an important if nebulous role in market volatility —positive gamma means options market makers will buy/sell in the opposite direction of moves in price dampening volatility, while negative gamma means the inverse and market makers accelerate rallies/sell-offs adding to volatility.
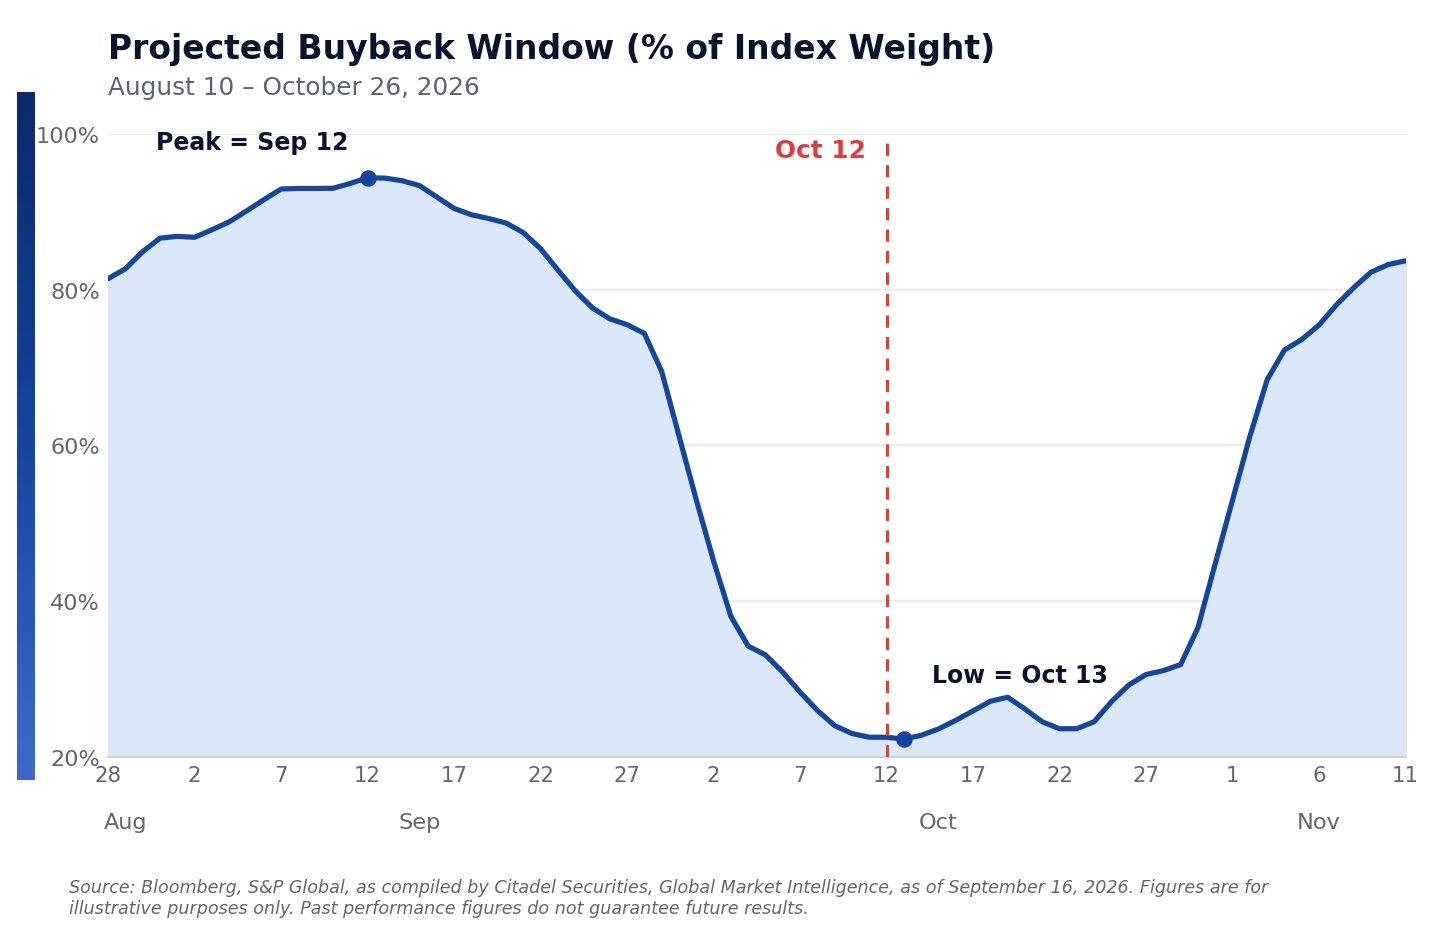
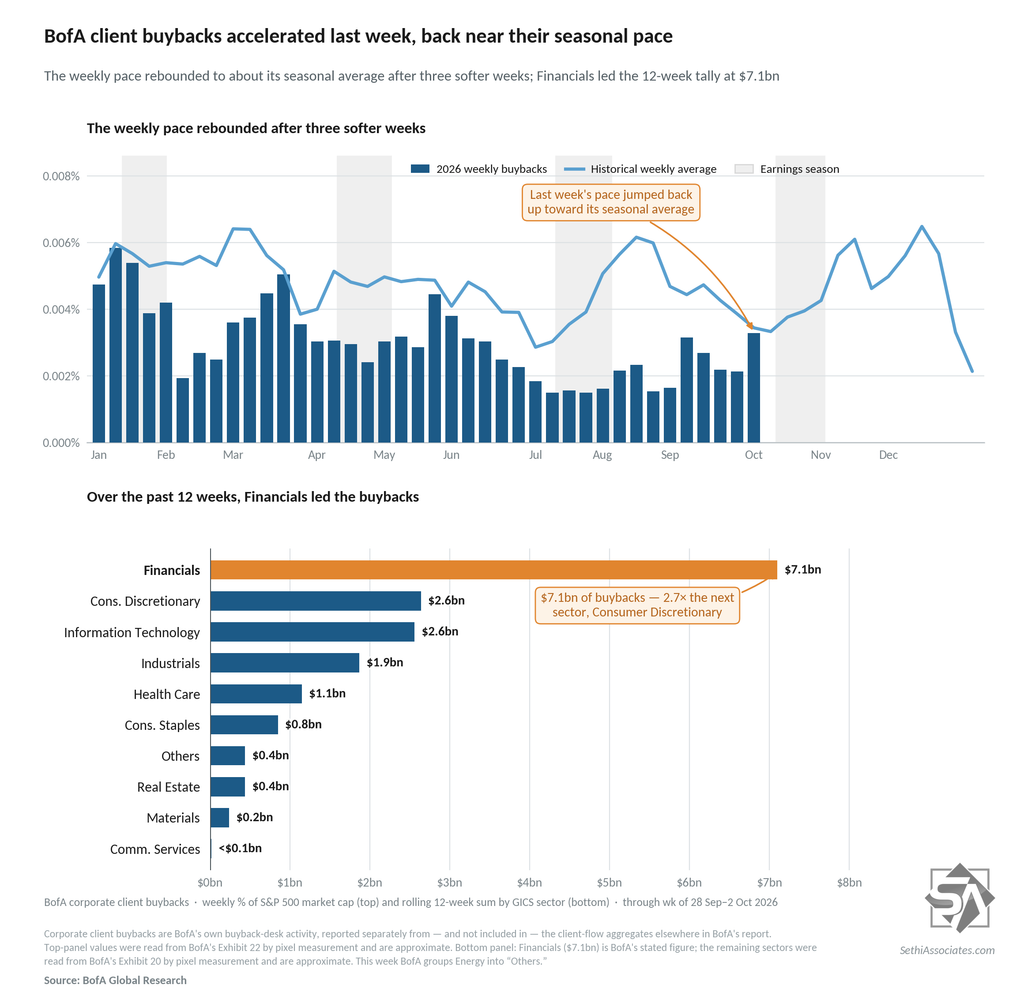
Turning to corporate buybacks (an important source of underlying demand), we remain deeply into the buyback blackout period with just around 20% of discretionary buybacks by index weight for S&P 500 companies active this week on average (discretionary buybacks represent ~30% of all buybacks), and it won’t get back above 30% until we get into November.
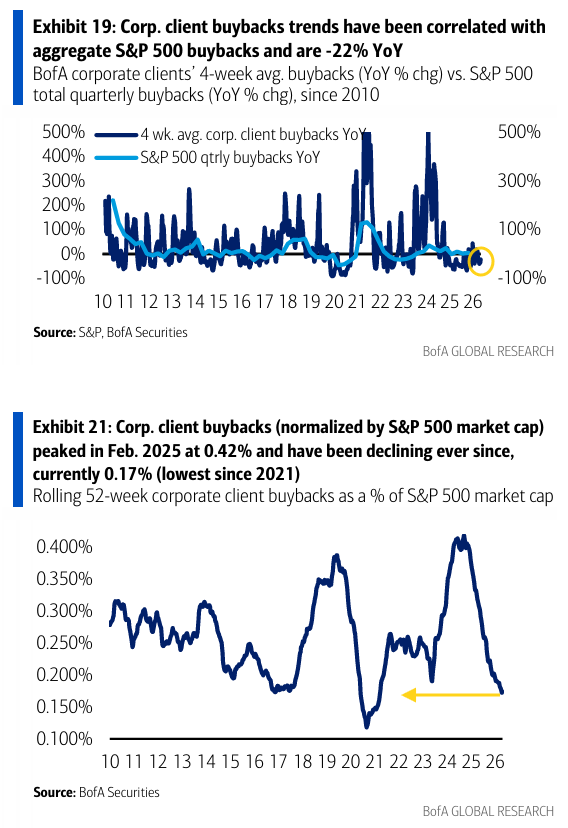
BofA though saw acceleration in buybacks for the first time in four weeks to “slightly above seasonal averages,” and normalized by market cap they were the closest to the seasonal pattern since early June (chart). On a 4-week average basis though they are -22% y/y, still better than the -36% a week ago.
They said a few weeks ago annualized cumulative buybacks YTD were tracking ~25% below 2025 levels and more than 40% below 2024 levels, though above 2010-23 annual levels. “Rolling 52-wk buybacks as a % of S&P 500 market cap are currently the lowest since Aug. 2021.”
Sentiment Remains Mixed
Sentiment (which I treat separately from positioning) is one of those things that is generally positive for equities when it’s above average but not extreme (“it takes bulls to have a bull market”, etc.), although it can stay at extreme levels for longer than people think, so really it’s most helpful when it’s at extreme lows (“washed out”).
Sentiment indices remain very mixed:
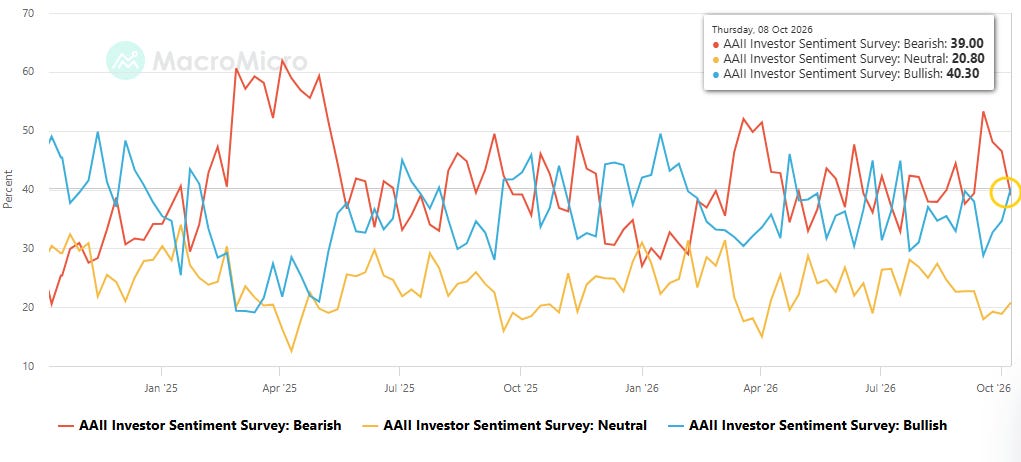
American Association of Individual Investors (AAII) sees Bears fall under Bulls for the first time in five weeks:
AAII Bulls (those who see higher stock prices in 6 mths, blue line) rose to 40.3% from 34.7% and 28.8% three weeks ago, which was the least since September 2025, moving above the long-term historic average of 37.5%.
Bulls also got above the level of the Bears (who see lower stock prices in 6 mths, red line) as the Bears dropped to 39.1% from 46.5% the prior week and 53.3% three weeks ago (the highest since May 2025). That is just the second time in 12 weeks Bulls have been above Bears. Bears still remain above the long-term average of 31.0% for a 34th straight week (and they’ve only been below it 9 weeks since Dec 12, 2024).
The Neutral camp (yellow line) moved to 20.8% from 18.9%. It remains under the long-run average of 31.5% and has been over that only twice since July 2024.
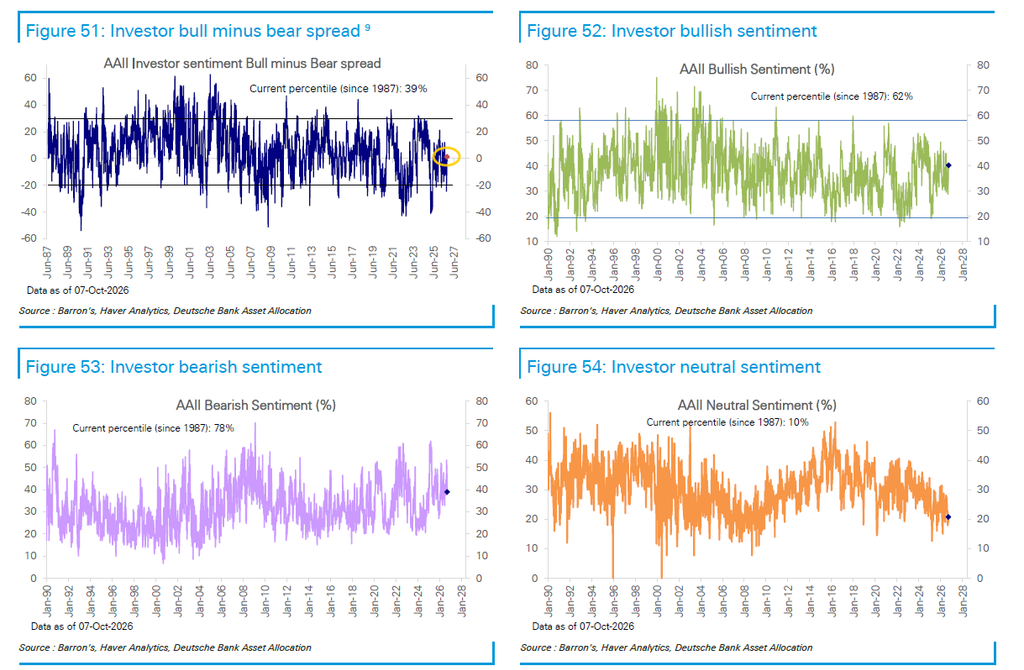
DB notes the bull-bear spread has pushed up to the 39th percentile to 1987 from just the 4th a few weeks ago. Bearish sentiment remains high (78th percentile) although well off where we were at the end of September while bullish sentiment has risen to the 62nd percentile.
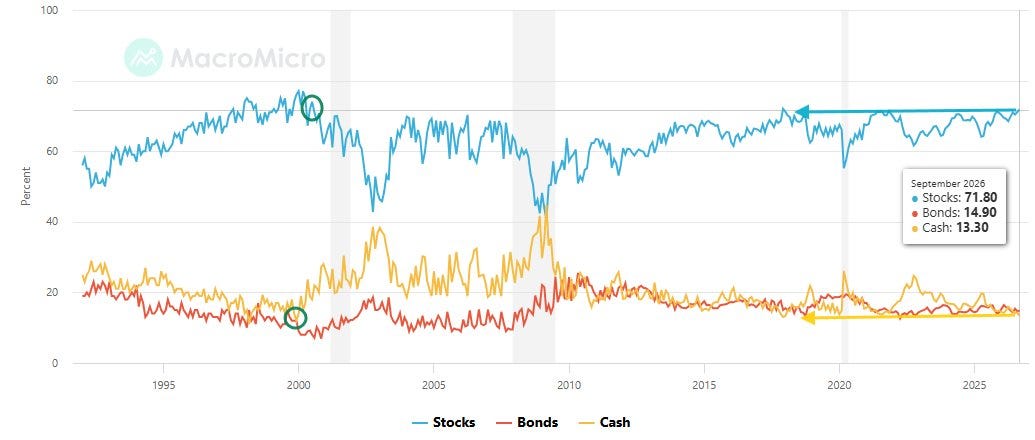
The AAII asset allocation survey in contrast found equity allocations at 71.8%, the highest since December 2017 (and before that July 2000), while cash levels fell to 13.3%, the least since December 2017 (and before that December 1999).
Bonds at 14.9% remain in the range since the start of 2021, around the long-run average.
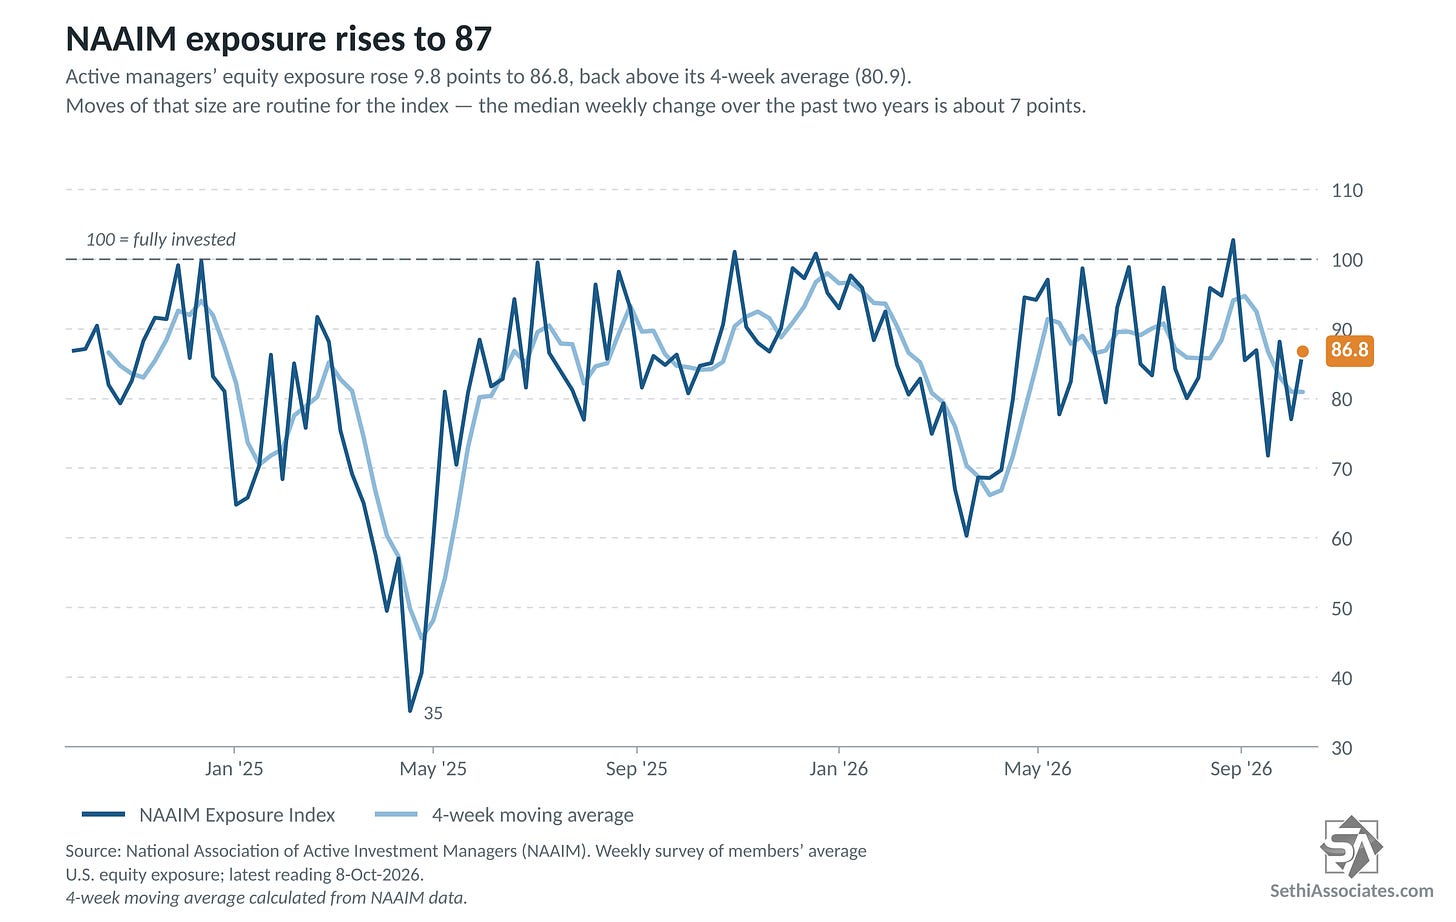
NAAIM’s survey of investment professionals* continues to vacillate back and forth rising to 86.8 from 77.0 the prior week but 88.1 the week before that, overall remaining in the middle of its range since May.
*The index according to NAAIM “represents the average exposure to US Equity markets reported by our members” and which ranges from -200% (2x short) to +200% (2x long).
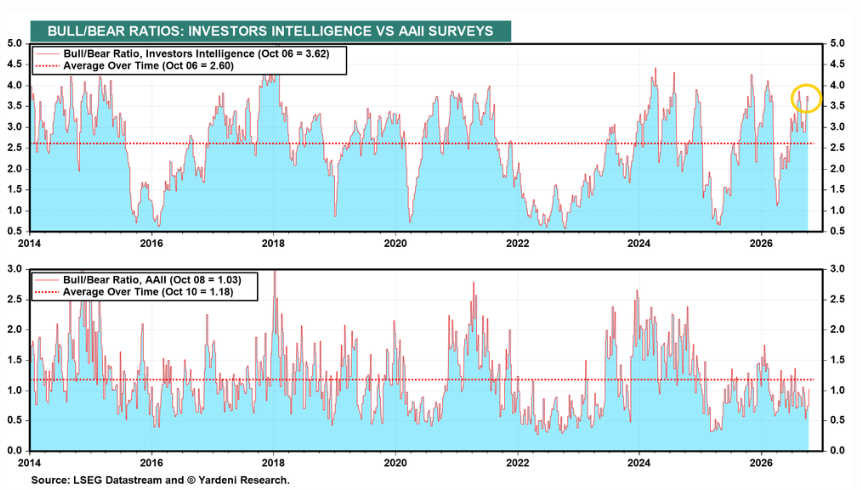
While the Investors Intelligence (independent investment-newsletter writers) survey saw the bull/bear ratio edge back to 3.62 from 3.75 the prior week, but 2.88 three weeks ago remaining above its average since 2008. Ed Yardeni says “Investor sentiment turned more bullish last week according to the two bull-bear ratios we track. (chart). Like the front-page curse, they also tend to be contrary indicators. However, they aren’t bullish enough to be bearish for stocks.”
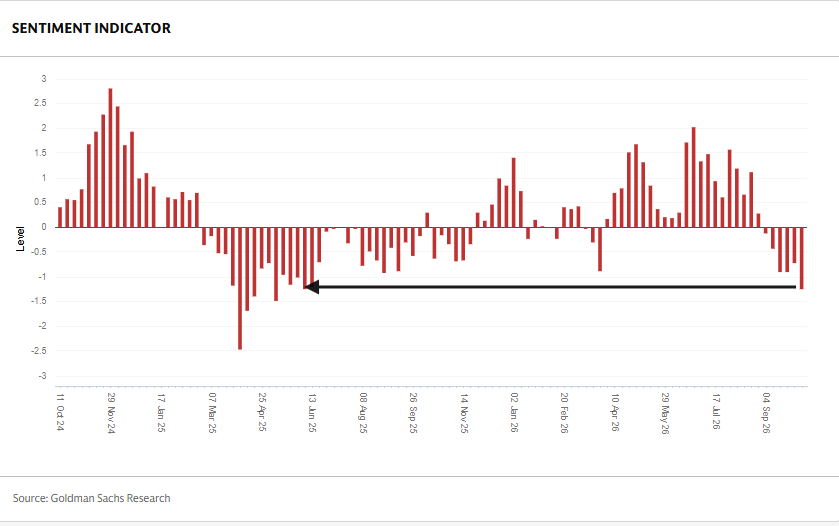
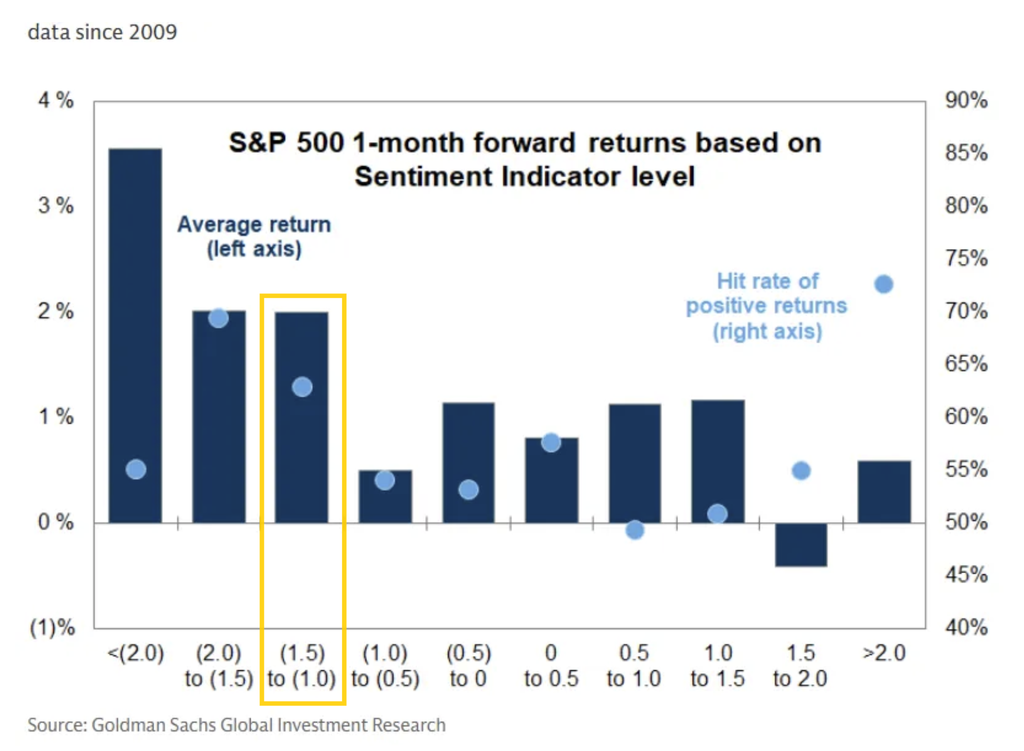
And Goldman’s US Equity Sentiment Indicator*, remained negative for a fifth week at -1.26, the weakest since June 6th, 2025, back below the “statistically significant signal for subsequent S&P 500 performance” according to Goldman.
In that regard, the current reading is consistent with a 1-month average return of around 2% since 2009 with a positive rate around 60%.
*The indicator combines “six weekly and three monthly indicators that span [across the more than 80% of the US equity market that is owned by institutional, retail and foreign investors]. Readings of +1.0 or higher have historically signaled stretched equity positioning. Readings of -1.0 or lower have signaled very light positioning and have historically been a statistically significant signal for subsequent S&P 500 performance”.
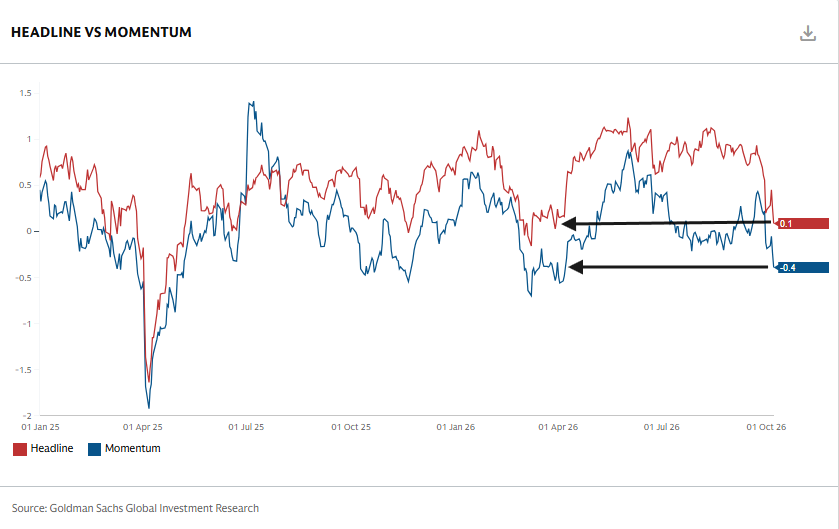
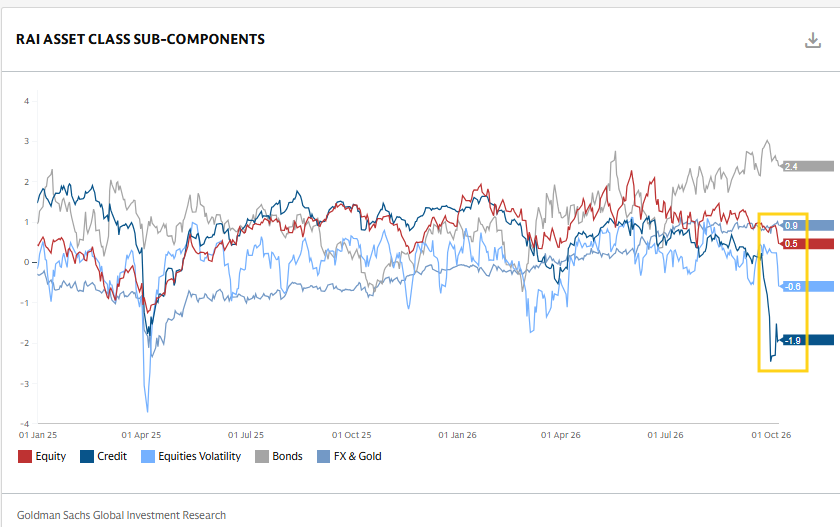
And Goldman’s Risk Appetite Indicator* fell again to 0.1, the least since March, down from 0.8 two weeks ago, while the momentum index fell to -0.4, the least since April, this week’s decline driven by equities and equity volatility.
*”Goldman Sachs Risk Appetite Indicator (RAI) aims to track the level of global market risk appetite and risk aversion based on various market variables. A sharp rise in the index can send a warning signal that investors have more risk appetite and are potentially exposed to a correction if consensus views are tested. Similarly, a sharp decline indicates a reduction in risk appetite, and at extreme levels it can indicate that markets may have overshot. RAI signals are most powerful when the level of risk appetite is very low below -1.5, with levels closer to -2.0 giving the clearest signal over longer time horizons, as at such levels the asymmetry of subsequent medium term equity return becomes very positively skewed. RAI momentum is designed to track short term shifts of market risk appetite, and subcomponents of the RAI.”
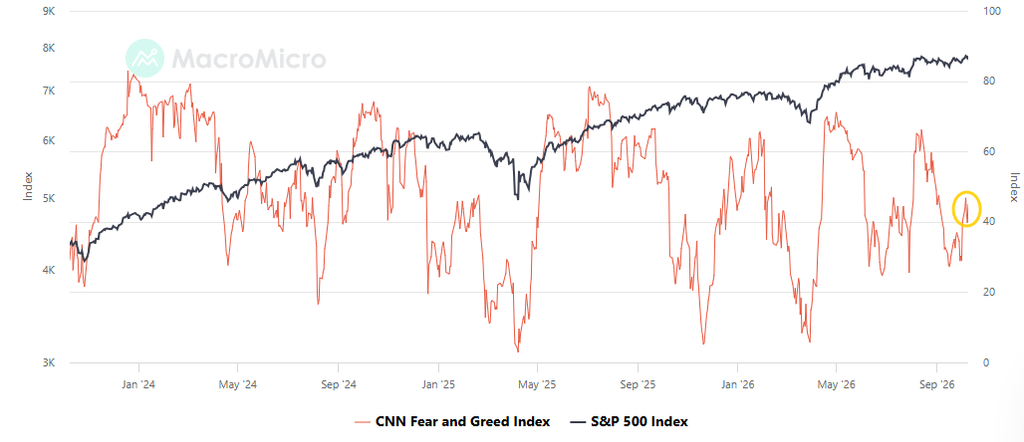
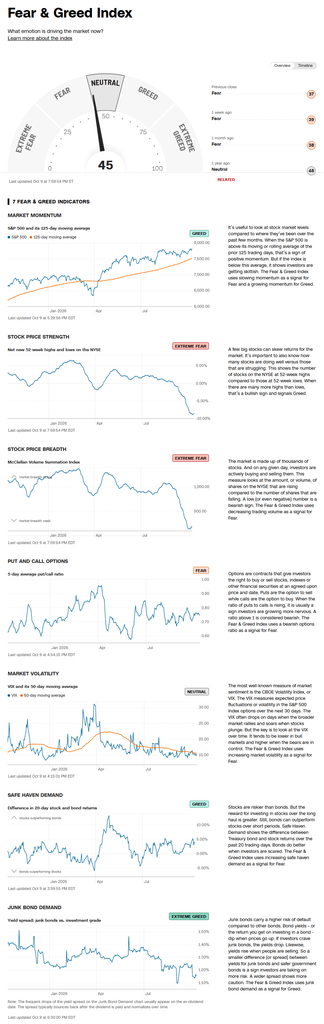
The CNN Fear & Greed Index (blue line) improved to 45.0 from 31.7 a week ago, edging just into “Neutral”.
Now three indicators above Neutral (from none last week) and three below (from five)
Greed = market momentum (SPX vs 125-DMA) (from Fear); safe haven demand (20-day difference in stock/bond returns) (from Neutral)
Neutral = market volatility (VIX & its 50-DMA)
Fear = put/call options (5-day put/call ratio)
Extreme Fear = stock price strength (net new 52-week highs); stock price breadth (McClellan Volume Summation Index)
And I noted in previous weeks if you have any questions on the indicator, TheStreet Pro’s own Jason Meshnick is your guy, as he helped create it.
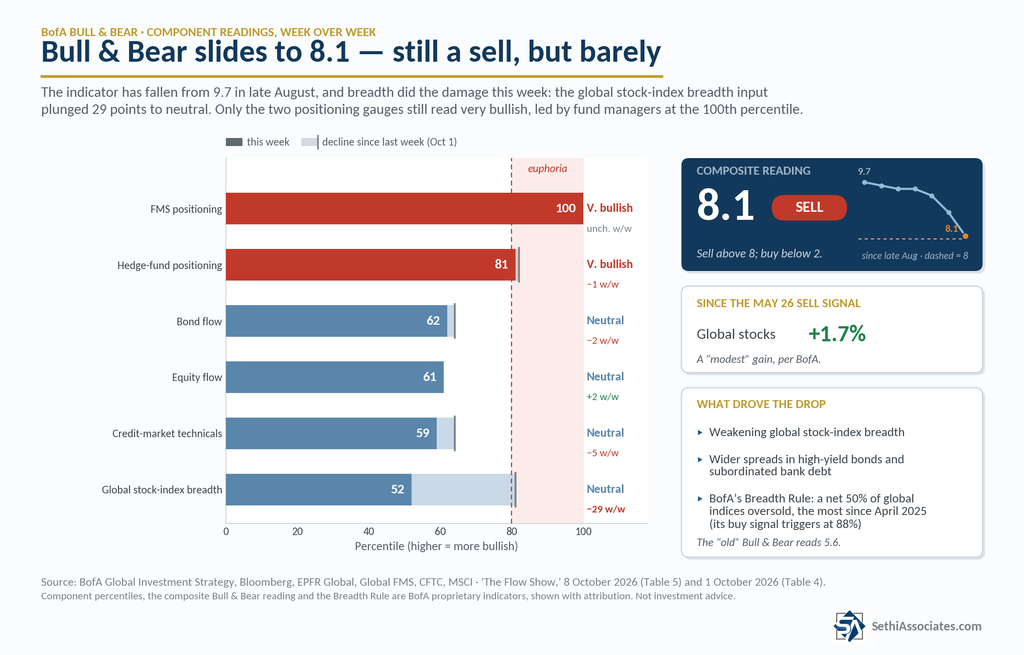
And BofA’s Bull & Bear Indicator eased back another seven tenths after five tenths the prior week to 8.1, now just a tenth above its sell signal (8.0) which it crossed back above the week of May 26th (since then global stocks are +1.7% and the SPX is +3.8%):
down to 8.1 from 8.8 driven by weakening of global stock index breadth, wider spreads in HY bonds & subordinated bank debt…. “old” Bull & Bear Indicator at 5.6
[From prior weeks]:
BofA Bull & Bear “sell signal” remains in place,extreme bull positioning says markets “toppy”, reduce equity exposure, retreat or rotate much smarter summer tactic for risk assets than reload.
17 “sell signals” since ‘02, average loss for global stocks over 2-3 months is 2-3% (hit ratio of ~60%), with max drawdowns of 15-20%(caveats always “tops are a process, lows are a moment”, i.e. greed harder to reverse than fear).
Favorable Seasonality
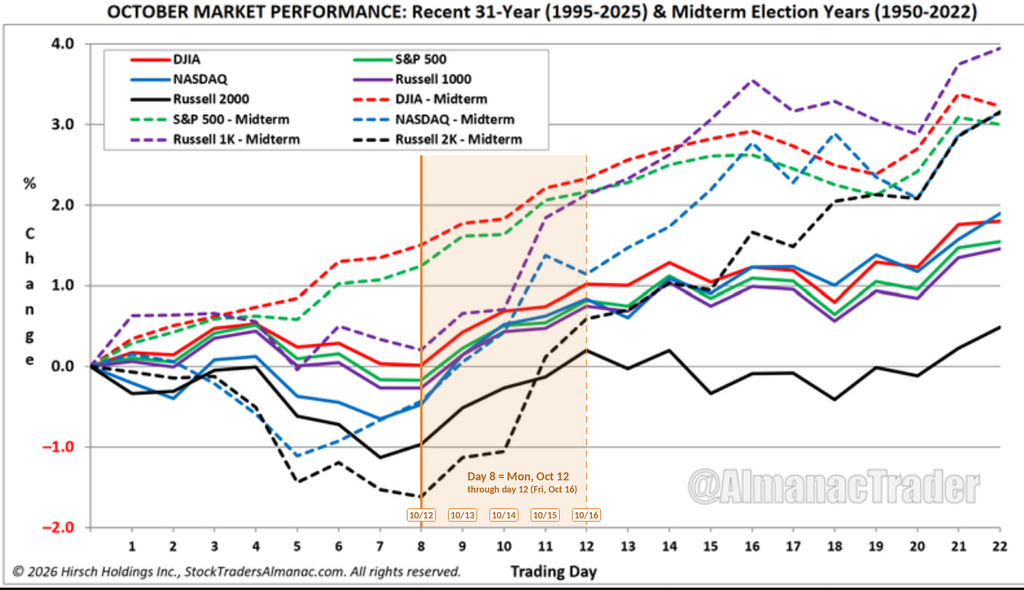
Looking at the seasonality breakdown from Jeff Hirsch, editor of the Stock Trader’s Almanac & Almanac Investor Newsletter, next week we start on the strong October seasonality discussed last week.
Monday is trading day 8. Over the past 31 years, the average path has bottomed last Friday into Monday (days 7–8), and the week has been solidly positive. The Dow, S&P 500 and Russell 1000 have each gained about 1%, the Russell 2000 about 1.3% and the Nasdaq about 1.5%. Unlike last week, 2008 isn’t distorting the average. It had the biggest single-day swings during these trading days, with the S&P up 11.6% on one day and down 9% on another, but the two largely offset. That year’s roughly 4% gain for the week accounts for only a small part of the average.
Midterm years have been even better, and the strength again leans toward the indices whose data only cover recent decades. The Dow and S&P have gained about 1%, while the Nasdaq and Russell 1000 have each gained about 1.8% and the Russell 2000 about 2.1%. The same post-1980 midterms that drove last week’s weakness drive this week’s rebound.
Much of that gain comes on trading day 11 (Thursday). In midterm years the Russell 1000 and 2000 have averaged more than 1% that day alone largely on the back of three years: 1998 (S&P +4.2% after the Fed’s surprise intermeeting rate cut), 2002 (+4.7%) and 2022 (+2.6%).
From there the gains continue through month-end, but more slowly and with more chop. Across all years, the indices add roughly another 0.7–1% after day 12, except the Russell 2000 at +0.3%. In midterm years, the Dow and S&P add another 0.8–0.9%, the Nasdaq and Russell 1000 about 2%, and the Russell 2000 about 2.6%. There are a few soft patches along the way and a strong push over the final two sessions.
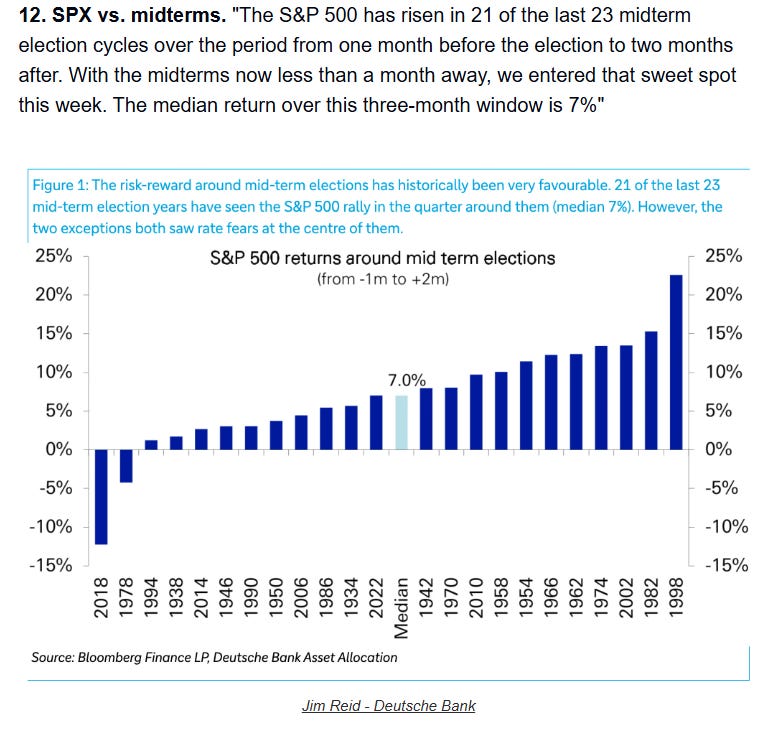
And DB notes (via dailychartbook.com) that “With the midterms now less than a month away, we entered that sweet spot this week. The median return over this three-month window is 7%”
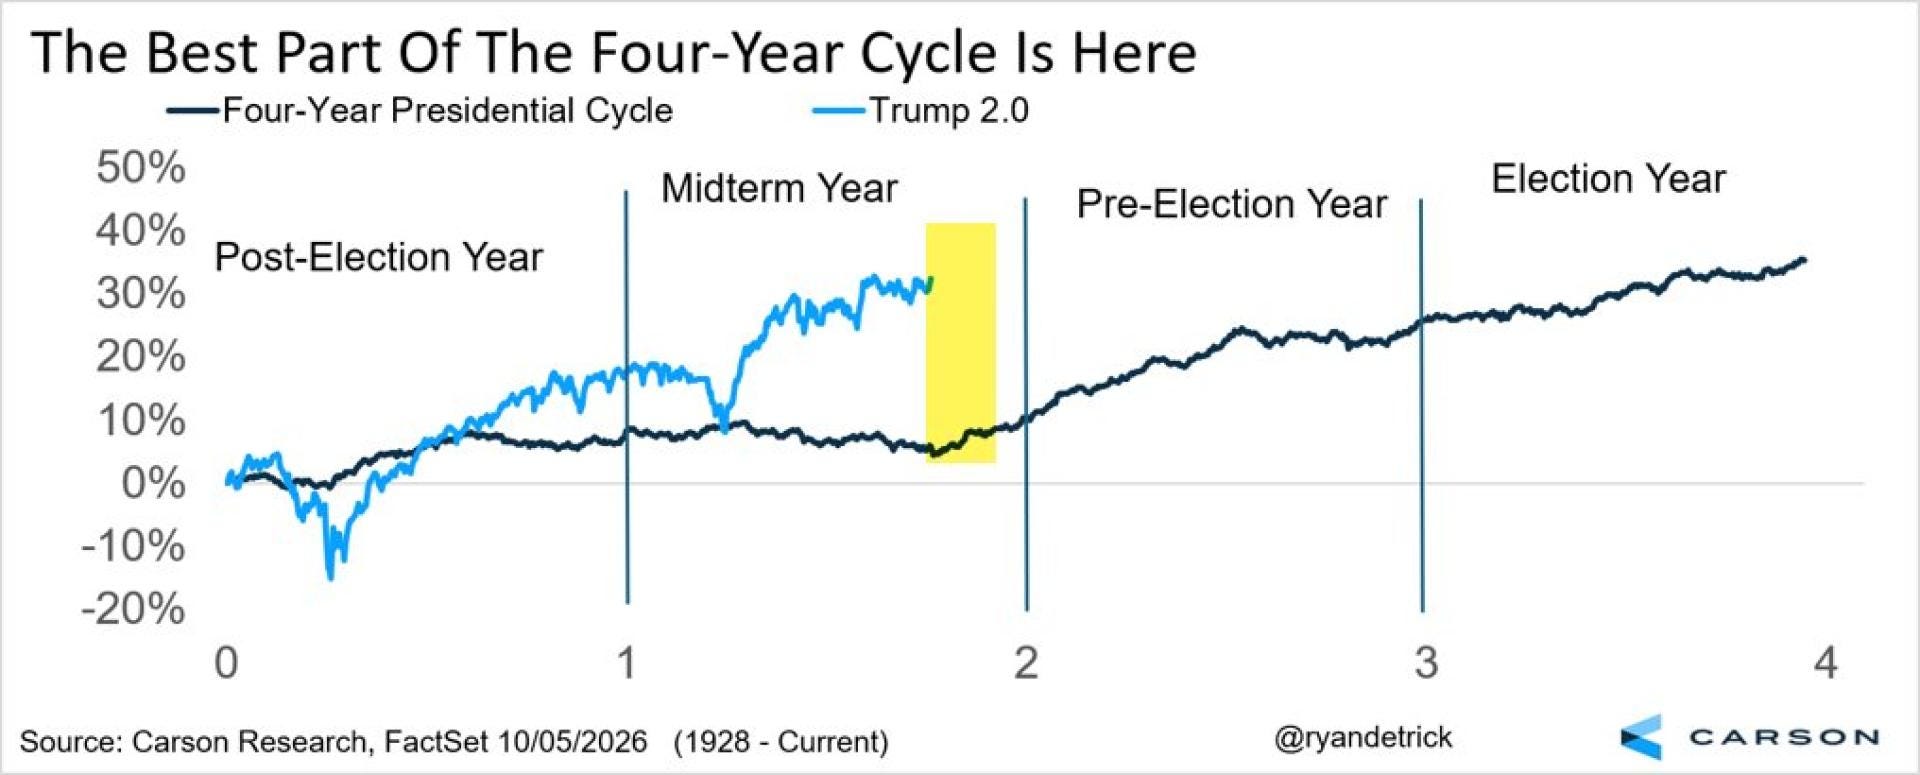
And looking at Ryan Detrick’s presidential cycle clock, the good news is that we’re starting the best part of the cycle. The bad news is we’ve really outrun it and are due for a big mean reversion.
Wrap-Up – Can Tech and Non-Tech Please Rise Together?
I said two weeks ago
I…continue to see many reasons to be bullish, particularly as we get into October and start what, by all accounts, should be another strong earnings season (although I’m less bullish on this quarter than I was last quarter as I’ll discuss in future weeks). The economy is strong, valuations are not demanding, many breadth and sentiment figures are at levels we’ve seen bounces in the past, there is a lot of dry powder on the discretionary side….
These are the ingredients of a bull market. So while there are some short-term headwinds, the longer term picture remains bright, with the caveat that the political wildcard will come back in a bigger way post-midterms. But that’s something we’ll talk about a month from now.
[And from last week] So in the short term the answer to “Can Non-Tech Join the Rally?” looks to be dependent on a softening in the factors that have kept them out.
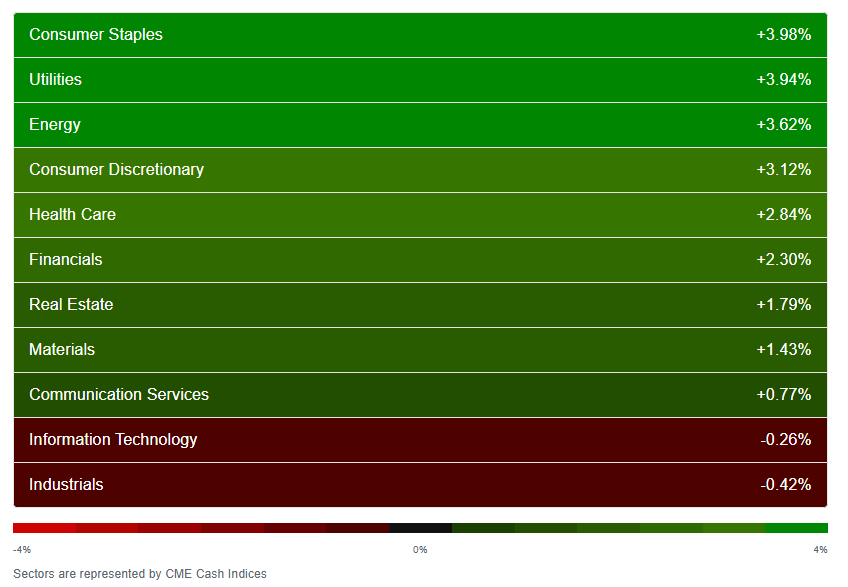
But now things have flipped a bit. Staples had their best week since February (and before that October 2022), one of three non-“growth” sectors up at least 3% (along with Consumer Discretionary). Health Care and Financials were up over 2%; Real Estate and Materials up over 1%. The two red sectors? Tech and Industrials (although neither down much).
Schwab
So now I guess we have to ask “Can Tech Join the Rest of the Market?”. I mentioned last week
I’m slightly concerned by DB’s commentary about Tech starting to hit levels that have seen it pull back in the past. As I’ve mentioned before, they’ve called the past year as good as anyone, so that will be something I’m keeping a close eye on. Micron finishing the week down despite a blow-out earnings report is another reason for caution.
And DB doubled down on their Tech caution this week:
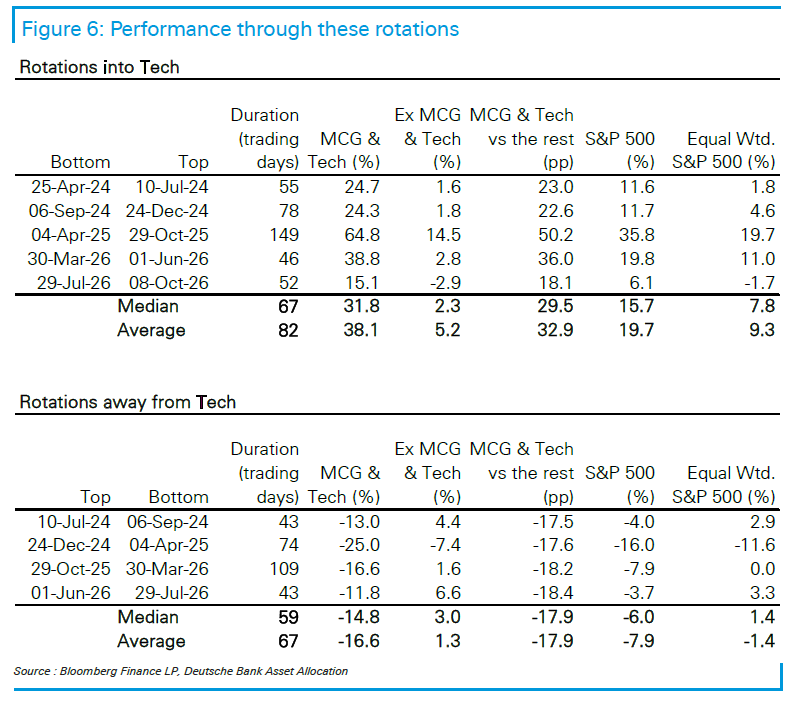
The rotation into Tech has advanced considerably, and the near-term risk-reward no longer looks favorable…. Tactically, the potential upside is now limited to roughly 4 percentage points of further outperformance before reaching the top of the channel, versus potentially 16 percentage points of relative downside if the historical pattern of rotations near the channel’s boundaries holds. Prior rotations have featured inverted-V reversals rather than gradual turns.
Extremely strong Tech earnings growth in Q3 is unlikely to be enough to drive the sector higher in the near term, while the bar for other sectors is significantly lower… investors’ concerns now center on future profitability and are unlikely to be resolved soon.
So far, once again, they’ve proven eerily prescient with the pullback coming the week after their first note. I remain hopeful that Tech can get it back into gear, but it does seem we’re due for a rotation out of Tech, and those have lasted over a month since mid-2024. So if they’re right the answer is no, Tech and non-Tech will not rise together. But let’s not prejudge the outcome.
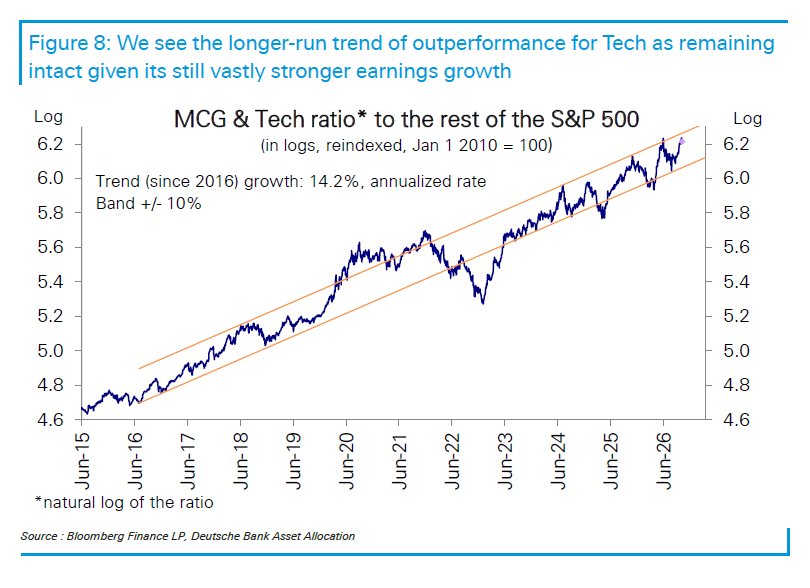
And longer term the Tech trade will likely continue to be a winner. “In our view, the longer-term trend of Tech outperformance remains intact. Over the past decade, Tech has outperformed the rest of the S&P 500 by 14 percentage points annually, underpinned by substantially stronger earnings growth. We do not expect that dynamic to change.”
In terms of the non-Tech trade, it is almost certainly more than coincidence that the strength we saw last week came on the first week in six that 10-year yields softened. Where yields go from here will have a lot to say about whether a broader rally has legs.
But as mentioned at the top of the section, there are a lot of reasons to be optimistic. We do continue to face the headwind of the loss of discretionary buyback support, and we continue to have a relatively weak systematic setup with the potential for a sharp move lower in equity prices if a selloff does get going. That said we did clean out at least some positioning the past couple of weeks, gamma remains high dampening volatility (at least within an ~2% band in either direction), seasonality is favorable, and some sentiment measures have cooled particularly Goldman’s indicator which hit a statistically significant buy level.
Next week is heavy on catalysts, led by CPI on Wednesday. A benign print that keeps yields easing gives the broadening room to run even if Tech takes a breather, and with the bond market primed for the short-covering rally I’ve been waiting for, the impact of a cool print could extend well beyond a session or two. A hot print, on the other hand, likely puts an October rate hike back on the table and probably sends yields to new highs. So a lot is riding on that outcome (and, relatedly, on PPI which also feeds into the Fed’s preferred inflation metric core PCE prices)
We’ll also get Chair Warsh but not until late Thursday night, so any reaction won’t come until Friday’s session. There’s also, of course, the start of Q3 earnings season with a heavy dose of financials. That hasn’t generally been a market moving event though beyond that sector.
For now the setup remains constructive for the reasons mentioned above, so as with last week “I’m starting the week eyeing higher levels — with, of course, a plan if indices go the other way,” particularly keeping an eye on Tech and bond yields.
At the time of publication, Sethi was long ASML, AAPL, GOOG, TSM, TLT, XLU, QQQ, SPY, RSP and IWM and had no positions in the other securities mentioned in this article.
Michael Cembalest (JPM): "only 30% of stocks are outperforming the S&P 500, one of the lowest figures since 1991," and so far "AI is primarily benefiting AI supply chain companies rather than the companies adopting it".
Wowzah. After yesterday’s 3-year Treasury auction stopped through despite a slump in foreign demand, the first test of the long end this month came today in $39 billion of 10-year notes and it was very different, delivering a repeat of last month’s blowout, with foreign demandShow more
investingLive
@investingLive_
The US treasury sells $39 billion of 10 year notes at a high yield of 5.300% versus WI level of 5.317%
investinglive.com/news/the-us-tr…
After Wednesday’s historically strong 10-year auction (and a similarly good 30-year last month) my expectations were high for today's $22 billion auction in 30-years which came in very solid, but not exceptional, a step back from September.
That was despite a clearing yield ofShow more
investingLive
@investingLive_
US treasury sells $22 billion of 30 year bonds at a high yield of 5.618%
investinglive.com/news/us-treasu…