Consumers’ View of Economic Conditions Hits All-Time Low
Sentiment slips to just 1.5 points above its all-time low with current conditions at a record while inflation expectations rise.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
October University of Michigan Sentiment: 46.3 (estimate 47.6; September 48.1)
- Current Conditions: 44.7 (estimate 50.1; September 50.9)
- Expectations: 47.3 (estimate 45.7; September 46.3)
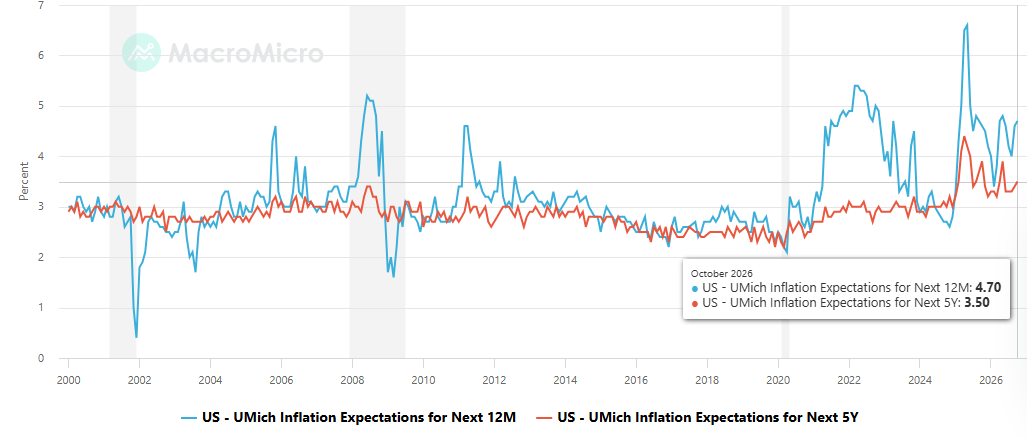
- 1-Year Inflation: 4.7% (estimate 4.8%; September 4.6%)
- 5-10 Year Inflation: 3.5% (estimate 3.5%; September 3.4%)
Executive Summary
● The preliminary read of University of Michigan consumer sentiment for October fell 3.7% to 46.3, the lowest since May and below the 47.6 estimate, now just 1.5 points above the all-time low set in May (44.8).
● Current conditions sank 12.2% to 44.7, the lowest on record, while expectations rose 2.2% to 47.3, the first increase since July. Buying conditions for durables also fell to a record low.
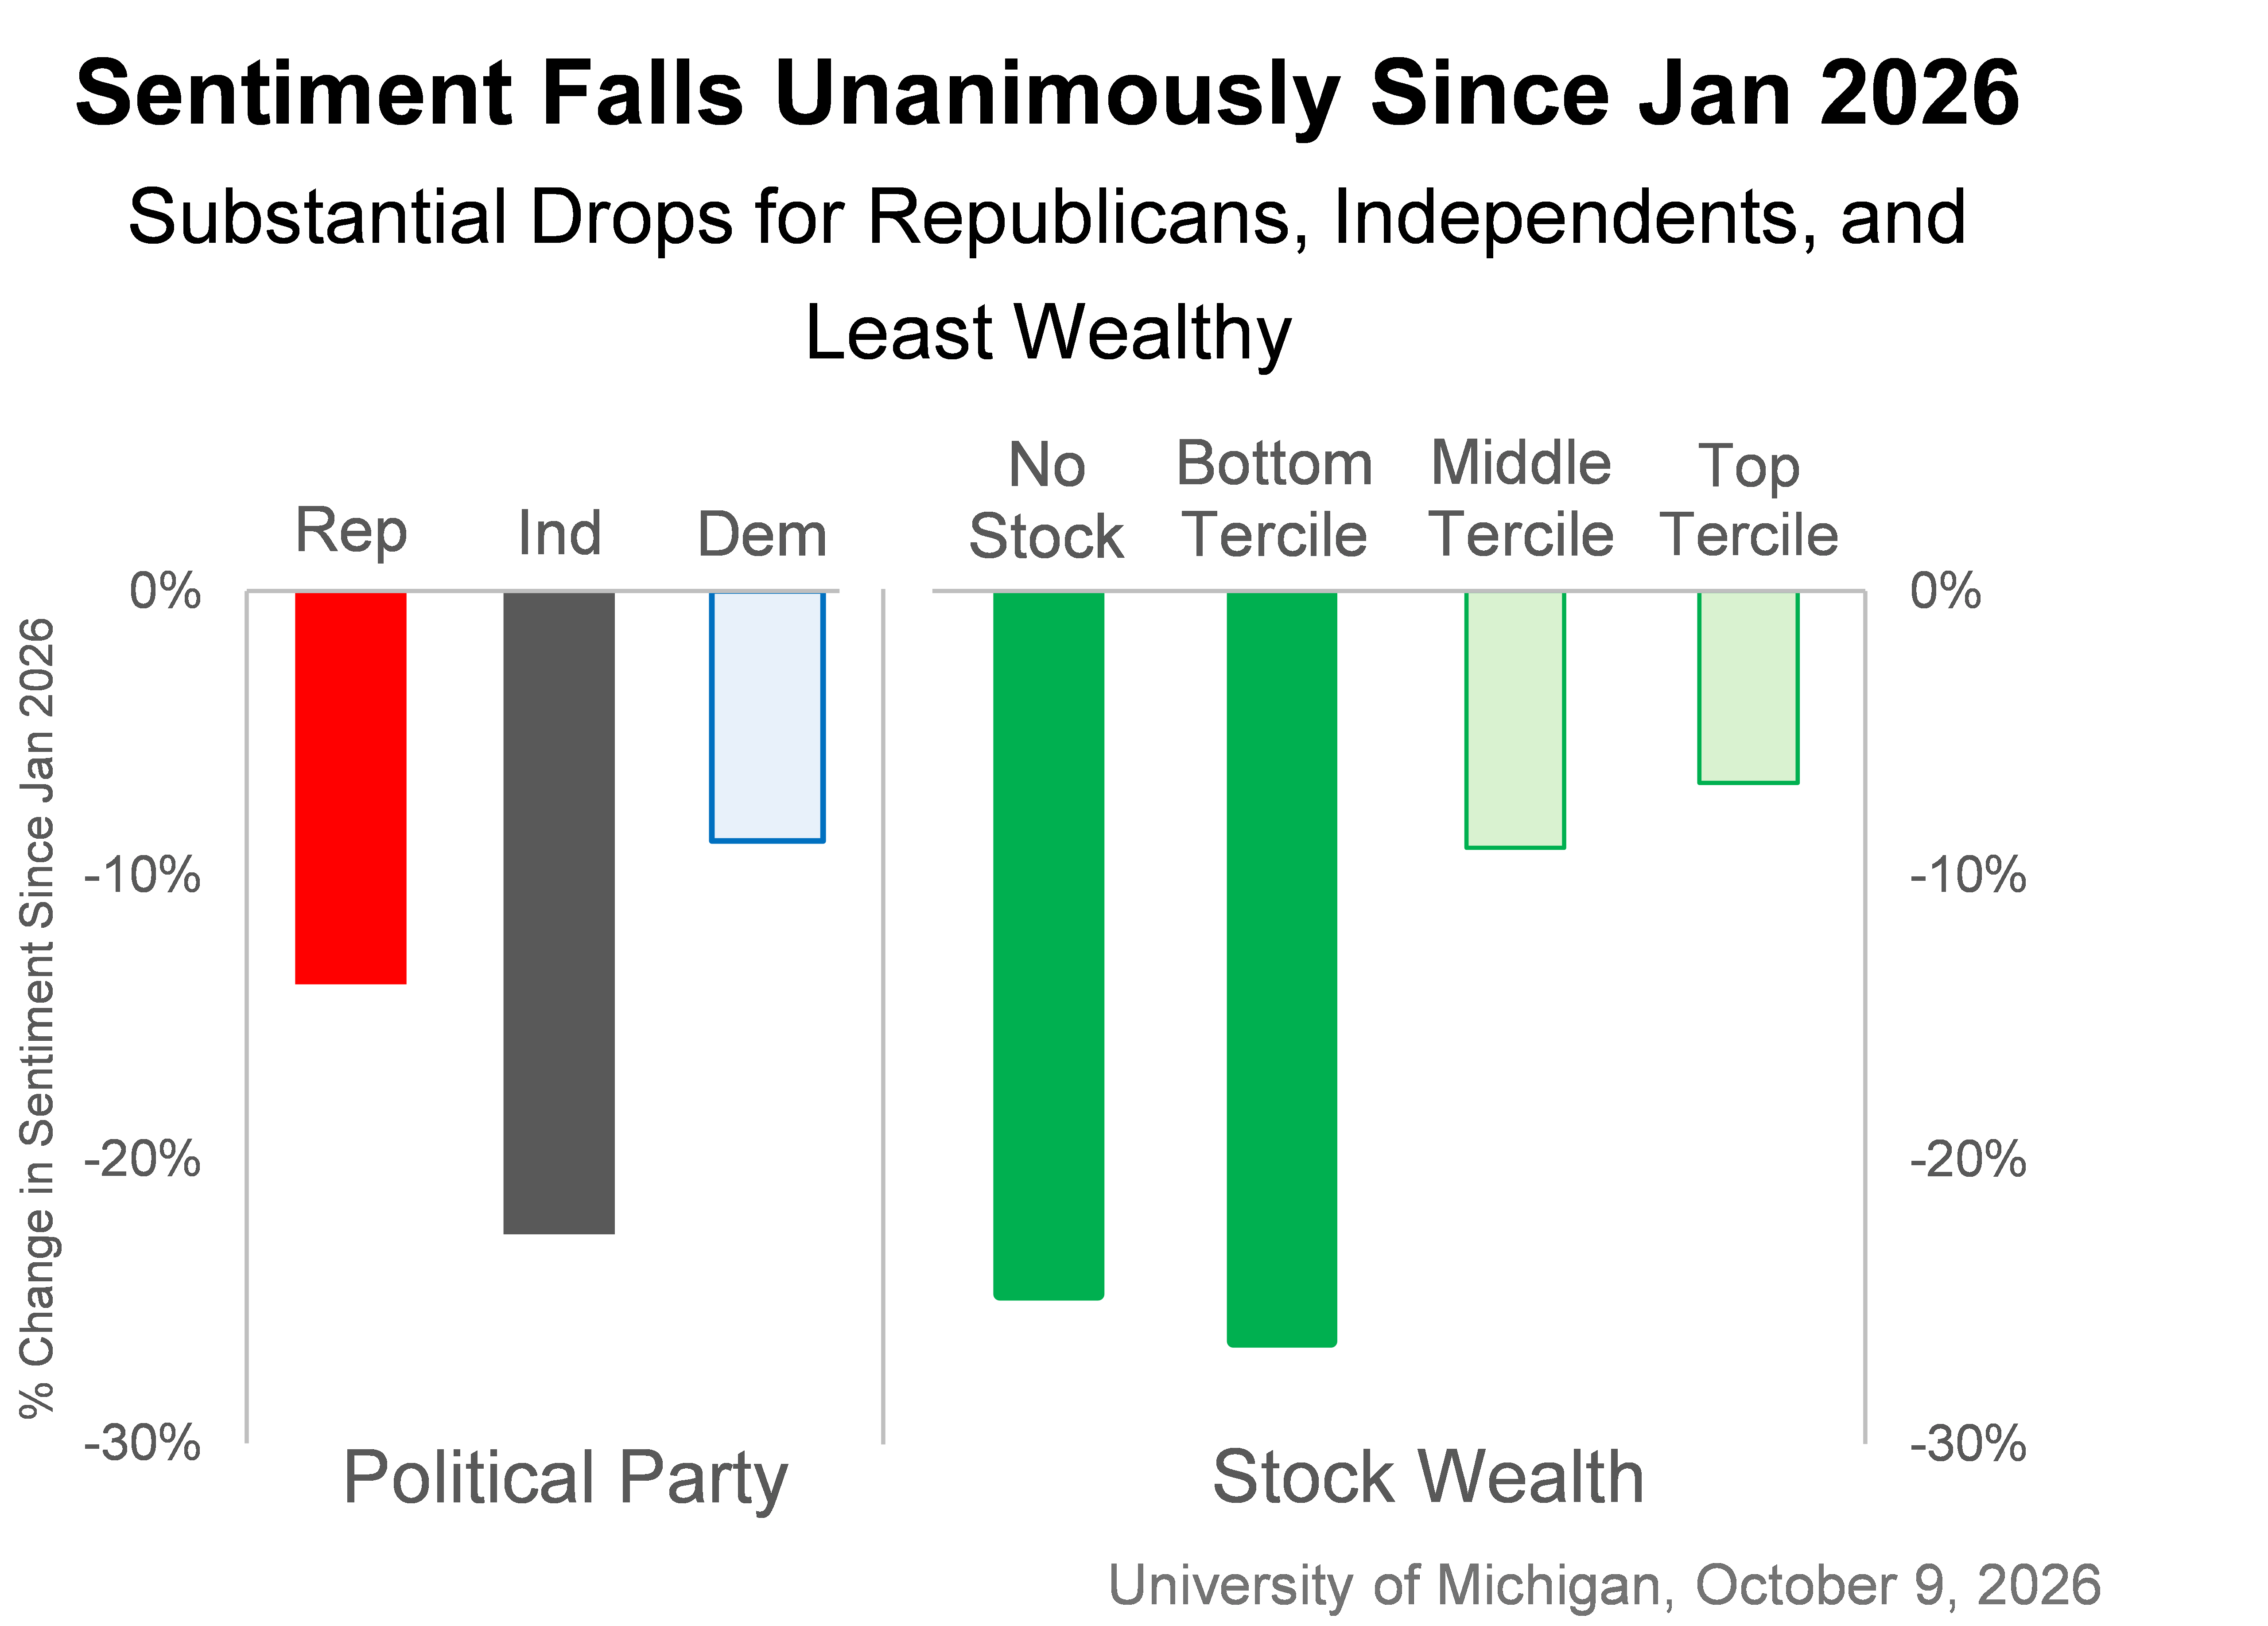
● Since January the decline in sentiment has been “unanimous” across party and stock distribution lines, led by drops among Independents and those with the fewest stock holdings.
● Year-ahead inflation expectations rose to 4.7%, and long-run (5-10 years) expectations rose to 3.5%, both the highest since May and up for a second straight month.
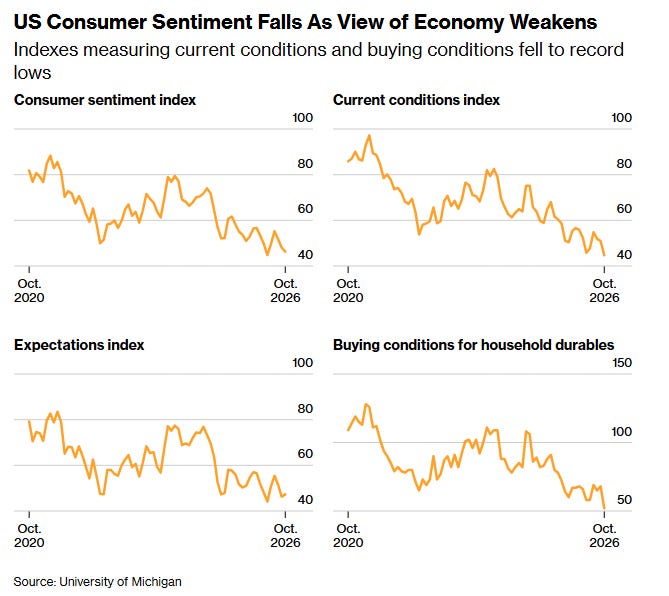
The preliminary read of University of Michigan consumer sentiment for October came in at 46.3, the lowest since May, down 3.7% from September’s 48.1 and below the 47.6 median estimate in a Bloomberg survey of economists, now just 1.5 points above the all-time low set in May (44.8). Per Surveys of Consumers Director Joanne Hsu, via the University of Michigan release, sentiment “was little changed this month, inching down a scant 1.8 index points from September.” The survey period ran September 22 to October 5.
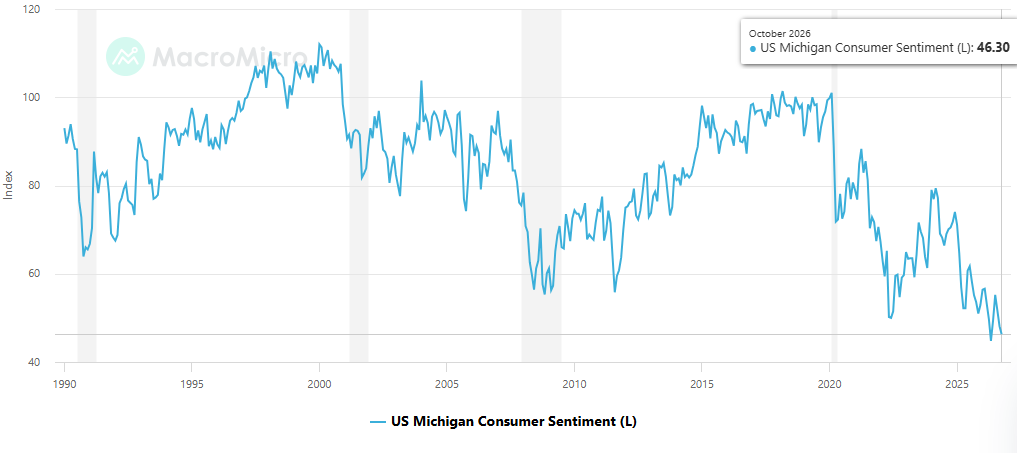
The two components moved in opposite directions. Current conditions (blue line) sank 12.2% to 44.7, the lowest on record, from 50.9 in September and well below the 50.1 estimate, while expectations (green line) rose 2.2% to 47.3, above the 45.7 estimate and per Bloomberg the first increase since July.
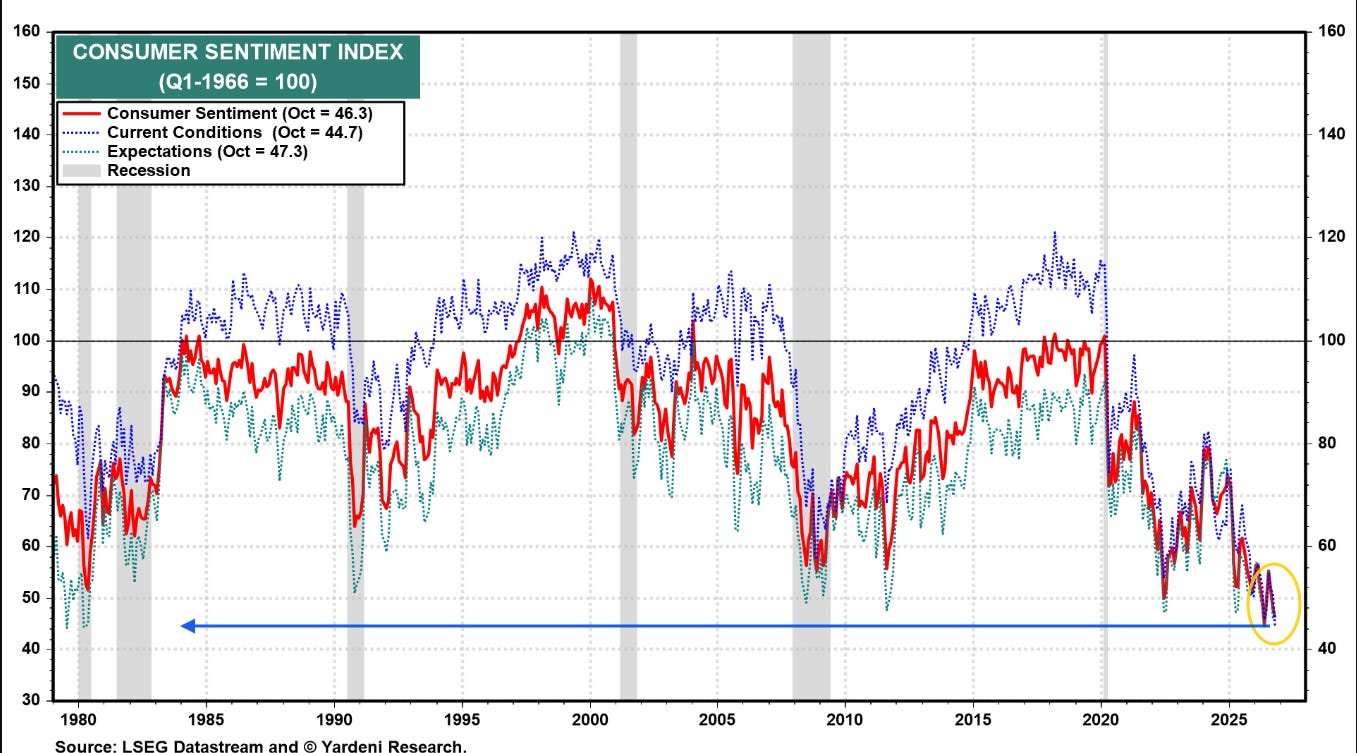
Lower-income consumers hit hardest
Hsu: “Increases in sentiment among Democrats and Republicans were offset by a decline among independents this month. Overall, sentiment for lower-income consumers and those with smaller stock portfolios dropped steeply this month, groups that have fewer resources to weather increases in prices. Frustration over cost-of-living continues to mount, as consumers across the political spectrum believe that the trajectory of the economy has weakened since the beginning of the year.”
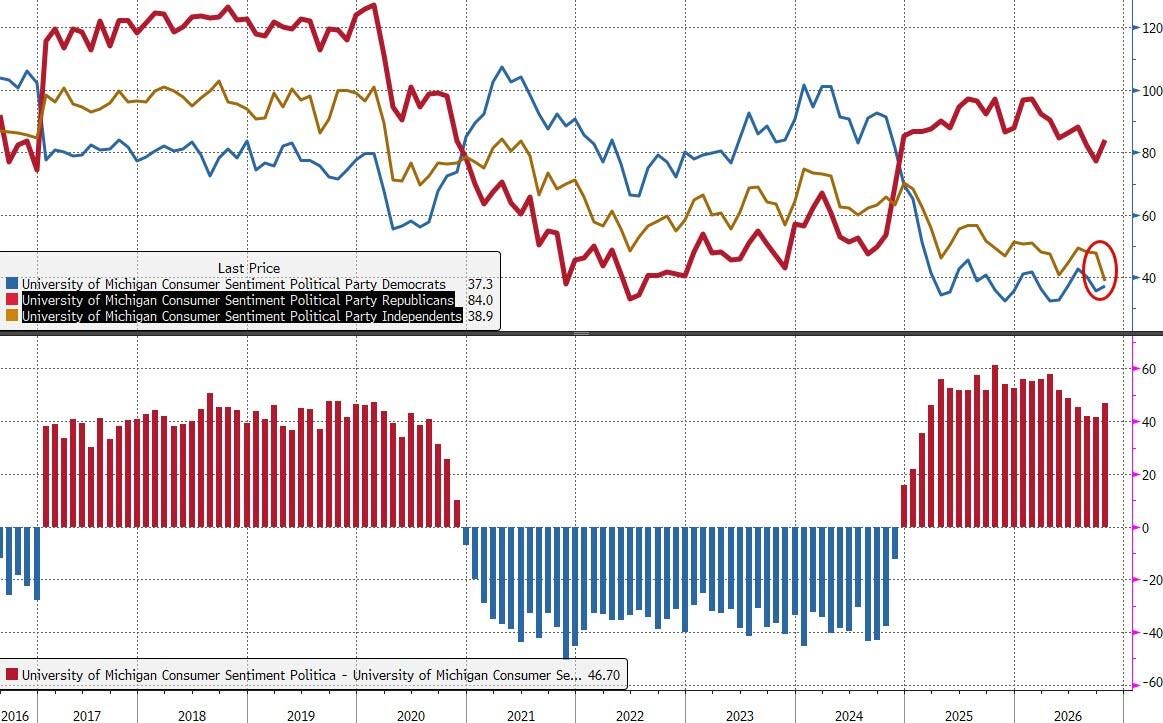
In a statement reported by Bloomberg, Hsu added: “Despite their differences, consumers of all political identifications agree that the outlook for the economy has softened since the beginning of the year prior to the Iran conflict.” A chart accompanying the release noted that since January the decline in sentiment has been “unanimous” across party and stock distribution lines, led by drops among Independents and those with the fewest stock holdings.
Durables buying conditions plummet
Hsu: “While year-ahead expectations for personal finances and business conditions crept up slightly, buying conditions for durables plummeted amid high prices and borrowing costs.” Per Bloomberg, buying conditions for durable goods fell to a record low due to concerns over higher prices and interest rates, while consumers’ perception of their current financial situation held steady. Some 46% said buying conditions are bad due to higher prices, the most since August 2022, while 8% said it was due to higher interest rates, the most since September 2024 according to Bloomberg.
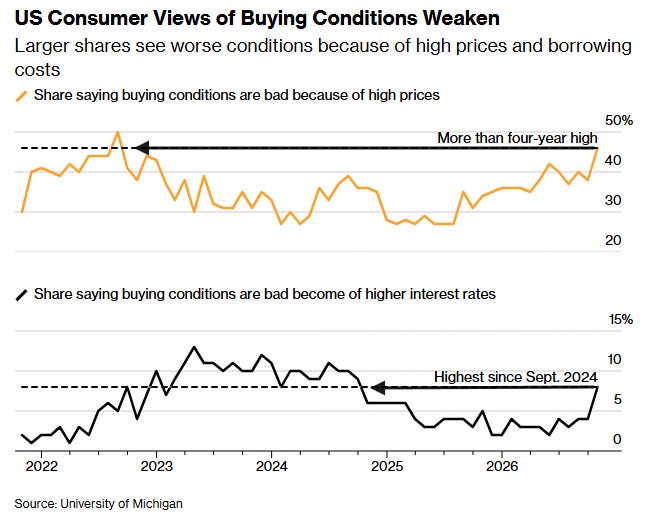
A special report released alongside the survey on consumers’ response to higher gasoline prices found, per Bloomberg, only about 31% expect to spend as usual over the coming year, while just over half said they would cut back spending on items such as household goods, cars, dining out and vacations.
Inflation expectations rise for a second month
On inflation, per Hsu: “Year-ahead inflation expectations [blue line] ticked up from 4.6% last month to 4.7% this month. The current reading substantially exceeds the 3.4% seen in February before the Iran conflict began, along with all 2024 readings.”
Long-run five-to-10-year expectations (red line) stepped up a tenth to 3.5%, per Hsu “notably higher than their 2024 range of 2.8% to 3.2%” and above the sub-2.8% readings in 2019 and 2020; the prior peak was 4.4% in April 2023. Per Hsu, “inflation expectations over both time horizons increased for the second straight month to their highest readings since May.”