Psst: These Two Biotech Plays Look Like Great Under-the-Radar Deals
Let’s check out two biopharma plays that scream ‘growth at a reasonable price.’
You've reached your free article limit
You've read 0 of 1 free Pro articles.
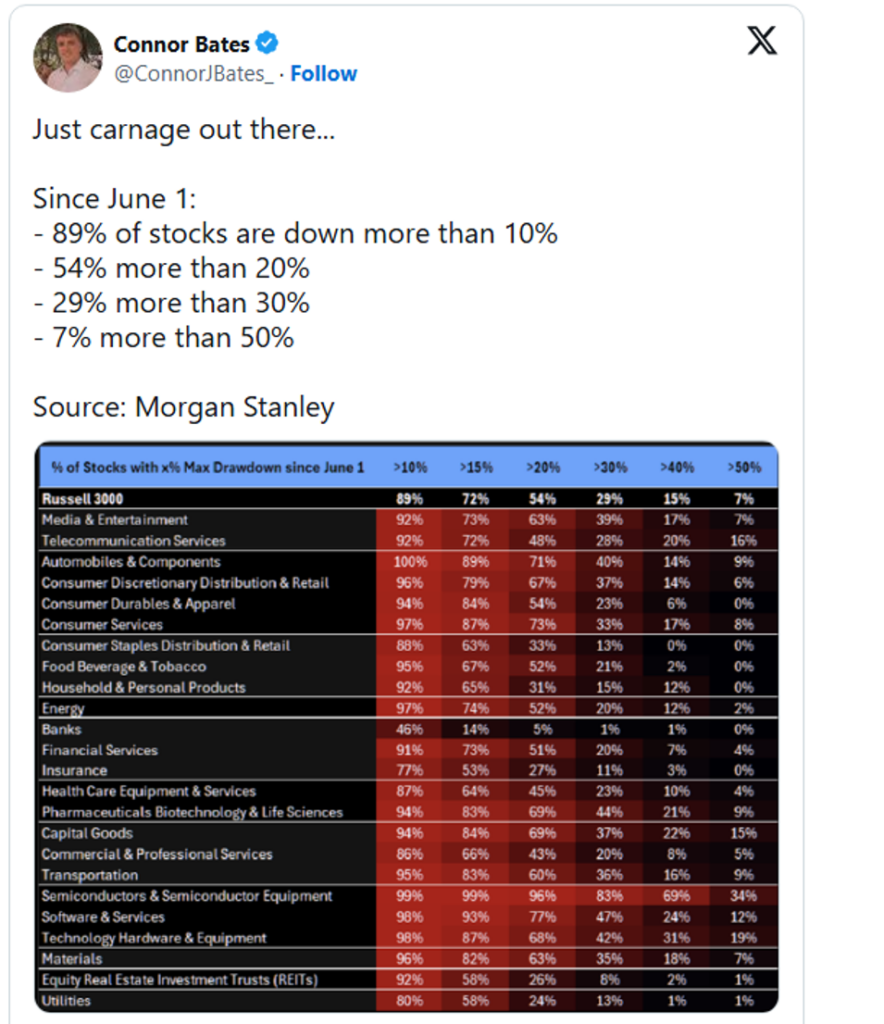
The major indexes have pulled back some after the Nasdaq and S&P 500 hit record highs on Tuesday. The Nasdaq fell around 1.3% on Thursday as AI-related names like Nvidia Corp. (NVDA) dropped after OpenAI posted an annual run rate under previous reported levels. Market breadth remains putrid as can be seen below.
In addition, the major banks — including JPMorgan Chase & Co. (JPM), Morgan Stanley (MS), and Capital One (COF) — are all in official correction territory, sporting declines of 11% to 25% from recent highs. Biotech, one of my favorite hunting grounds, has been a laggard as well with the State Street SPDR S&P Biotech ETF (XBI) down some 13% from its highs in mid-August. Biotech M&A has ebbed since posting a sharp uptick in volume in the first half of 2026. Pacira BioSciences, Inc. (PCRX), which I have a small holding within, was purchased with a solid buyout premium yesterday.
Trying once again to end the trading week on a positive note, today’s column will highlight two solid growth-at-a-reasonable-price plays within the biotech and biopharma sector. I have increased my position within each name this week via covered-call orders.
Let’s start with Arcutis Biotherapeutics, Inc. (ARQT). This small-cap biopharma is not getting credit for a spate of positive news in this weak tape. Its pipeline-in-a-product, Zoryve now has Food and Drug Administration approval for seven conditions including atopic dermatitis and plaque psoriasis. Zoryve is a highly potent and selective phosphodiesterase-4 (PDE4) inhibitor and comes in a variety of foam and topical cream formulations.
Arcutis posted Q2 results in August that easily beat both top and bottom-line expectations. Revenues were up 59% on a year-over-year basis and 23% sequentially from Q1. Management also boosted its full year sales guidance from a range of $480 million to $495 million to $525 million to $540 million. The company is moving toward profitability with earnings of over 40 cents a share projected in fiscal 2026, followed by over $1.30 a share in fiscal 2027 and north of two bucks a share of profit estimated for fiscal 2028. At just over $24 a share, that growth has more than a reasonable valuation. Arcutis also possesses a rock-solid balance sheet.
I have also added to my stake in mid-cap BioMarin Pharmaceutical (BMRN) as the shares are down some 20% from recent highs in mid-August. BMO Capital Markets noted that month the market’s worries around the potential market share erosion of its key asset Voxzogo is overstated and I concur.
BioMarin also just announced it will take an in-process research and development (IPR&D) expense of $283 million. This is tied to its recent purchase of Dutch biotech Alesta in August. It needs to be noted this is a one-time cost. The acquisition brought a candidate that is in mid-stage development for hypophosphatasia, which is a strategic fit for BioMarin’s rare disease pipeline and portfolio. The company easily beat the top and bottom-line consensus when it reported second quarter numbers in August.
Biomarin is one of the few stocks in the biotech sector or the market that has a price/earnings-to-growth ratio nicely under one, making it all the more attractive.
At the time of publication, Jensen was long ARQT, BMRN, PCRX and XBI