S&P Says Service Sector Is Running at Hottest Since 2021
S&P September services PMI shows sharpest rise in activity since July 2021 and new orders at a 4.5-year high.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
US S&P Global Services PMI Sep F: 58.8 (flash 58.7; Aug 56.5)
— Composite PMI: 58.4 (flash 58.4; Aug 56.0)
Executive Summary
- The S&P final September services PMI came in at 58.8, up from 56.5 in August — the fourth successive monthly improvement, the sixth straight month of expansion, and the strongest since July 2021.
- Growth also broadened out — for the first time in 10 months all five broad sectors expanded with information & communication leading.
- New orders accelerated to the fastest in four-and-a-half years on domestic strength, driving job creation to the quickest since June 2022 and pushing backlogs higher for a 19th consecutive month at the sharpest rate in almost four-and-a-half years and “among the most marked on record.”
- But prices also rose sharply. Input cost inflation reaccelerated from August’s 16-month low to the quickest since November 2022 on gas and transportation costs, with output prices rising the second-fastest in just over a year. Sentiment nonetheless hit a one-year high.
- Per Williamson, the services and manufacturing readings together point “to economic growth of around 4% in the third quarter and 5% in September alone, though “concerns that the economy is running too hot will be fueled by the survey’s price gauges.”
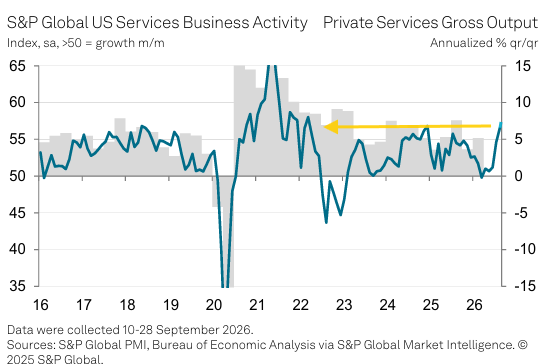
The S&P final September services PMI came in at 58.8, the strongest since July 2021, up from 56.5 in August and revised up marginally from the 58.7 preliminary reading. It was the fourth successive monthly improvement in the index, which “has now signaled increasing business activity in six consecutive months.”
Notably, the strength also broadened out. New orders hit a four-and-a-half year high, employment rose at the fastest rate since June 2022, and backlogs extended their run to 19 months, while sentiment reached a one-year high. The tradeoff was a concomitant rise in prices, with input cost inflation reaccelerating to the highest since November 2022.
Looking more specifically at the components:
- Output “trended higher across all five broad sectors covered by the survey” for the first time in 10 months “as transport & storage activity returned to growth. By far the sharpest expansion was seen in the information & communication sector.”
- New Orders quickened to the fastest in four-and-a-half years on domestic demand, but with exports also rising for a second straight month — “The rapid increase in business activity was in line with a similarly-sized rise in new orders at the end of the third quarter…Although new export orders rose at a much slower pace than total new business, growth was recorded for the second consecutive month and the pace of increase was unchanged from August’s 20-month high.”
- Employment rose for a third straight month at the quickest pace since June 2022, helped by improved ability to fill openings — “With total new orders rising rapidly again in September and some companies able to fill previously vacant positions, workforce numbers increased for the third month running.”
- Backlogs extended their run to 19 months, rising at the sharpest rate in almost four-and-a-half years — “Despite efforts to expand workforce capacity, the strength of the influx of new orders was such that volumes of backlogged work accumulated again…among the most marked on record.”
- Input Prices reaccelerated sharply from August’s 16-month low to the steepest since November 2022, while Output Prices rose at the second-fastest pace in just over a year — “Higher gas prices and an associated rise in transportation costs were widely reported, with some respondents also mentioning increased labor costs.”
- Sentiment hit a one-year high on expected order growth — “Anecdotal evidence linked confidence to expected increases in new orders amid the introduction of new products, the securing of new clients and referrals from existing customers. Hopes for an easing of inflationary pressures were also mentioned.”
The S&P Composite Index (Services + Manufacturing) came in at 58.4, up from 56.0 in August and unchanged from the flash, the strongest in over five years with growth accelerating in both sectors — “The rise in output was in line with a rapid increase in new orders, and companies subsequently hired additional staff at the fastest pace since June 2022. Strong economic growth was accompanied by a considerable rise in input costs, one that was the sharpest since October 2022.”
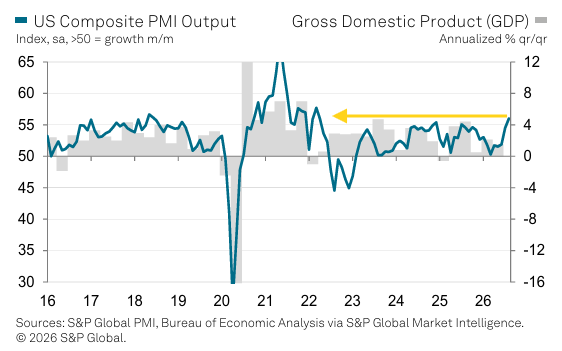
Comments from Chris Williamson, Chief Business Economist at S&P Global Market Intelligence, who notes the data points to ~4% Q3 growth and ~5% in September alone, but warns the price gauges will fuel concerns the economy is running too hot:
“September has seen US business growth surge to its highest for over five years, with rising demand and improved optimism encouraging firms to take on workers at a pace not seen for over four years.
“Combined with the encouragingly solid manufacturing PMI, the strong service sector expansion points to economic growth of around 4% in the third quarter and 5% in September alone, the latter hinting at accelerating momentum into the fourth quarter.
“New orders and backlogs of work are rising at increased rates and growth expectations have recovered to a one-year high, adding to the sense of an economy picking up further pace in the near term.
“Tech companies are reporting by far the strongest growth but the rising tide is now lifting all boats as far as the major sectors are concerned, with accelerating growth also reported for consumer-facing businesses as well as industrials and healthcare, alongside sustained solid growth in financial services.
“However, concerns that the economy is running too hot will be fueled by the survey’s price gauges, which point to accelerating inflation. Measured across goods and services, firms’ input costs are now rising at the fastest rate for nearly four years. While these increased costs in part reflect higher fuel prices, the worry is that selling price growth has also moved higher again to signal sustained stubbornly high inflation, well above the Fed’s 2% target.”