AI Stocks Drag the S&P 500 Back Toward the November 5th Lows
Another slide in Tech ahead of Nvidia’s earnings left the S&P 500 just above its November 5th close, while crude and bitcoin fell to the lowest since August and gold since September 2025.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Executive Summary
Sunday’s Week Ahead (The Week Ahead – Have We Seen the Q4 Bottom?) said a retest of the November 5th lows remained a distinct possibility, and stocks got a lot closer to one Monday as continued Nvidia fallout, exacerbated by new chip export curbs, along with investors “making room” for the upcoming Anthropic IPO, hit Tech again, a day before Nvidia’s earnings.
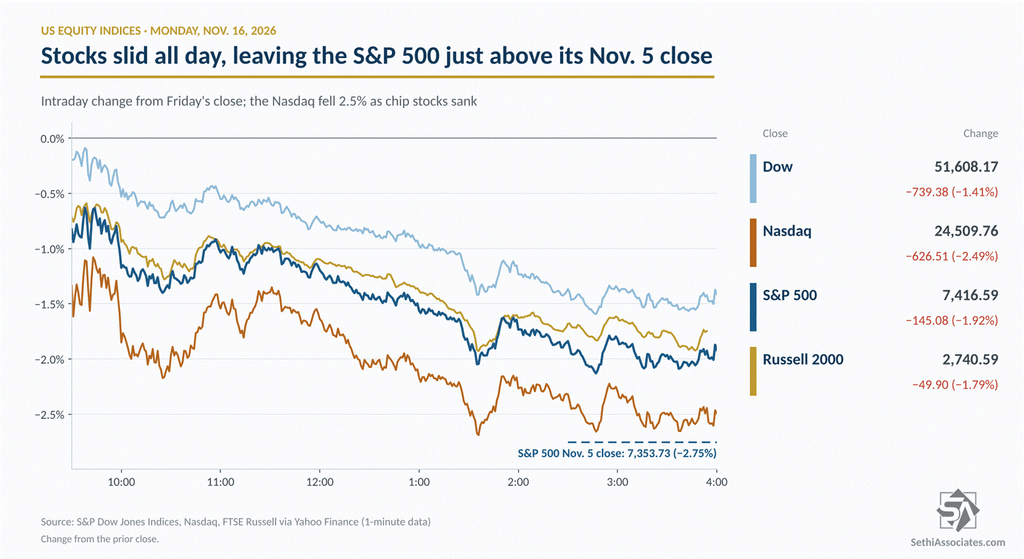
US equity indices opened lower and slid for most of the session, never trading in the green, before steadying in the last hour. The Nasdaq led decliners, down 2.5%, on a broad Tech selloff (-3.0%), followed by the S&P 500 (-1.9%, its worst day since November 5), the Russell 2000 (-1.7%) and the Dow (-1.4%). The S&P 500 closed 0.9% above its November 5th close, its three-session drop is its biggest since June, per Bloomberg.
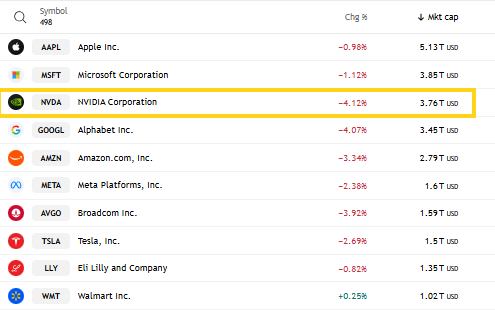
Nvidia (NVDA) fell 4.1% after Treasury Secretary Scott Bessent called over the weekend for an outsider to replace Jensen Huang, and reports today that its board isn’t considering bringing him back, even as Huang’s allies campaign for his return and President Trump backed calls for his reinstatement. Nvidia has now lost more than $2 trillion in market value from its October peak, slipping to the third-largest US company for the first time in 18 months. Adding to the pressure on chip stocks, the Commerce Department announced new restrictions on remote access to advanced US AI chips through overseas data centers.
Fed Chair Warsh, in his first public remarks since the October meeting, discussed how Fed staff have begun modeling how AI could reshape the economy, including scenarios in which it displaces workers.
The VIX jumped 21% to 23.4, its highest close since November 6. Treasuries edged higher, with the 2-year yield down 2 basis points to 4.83% and the 10-year at 5.13%, while the dollar edged up to its highest close since April 2025. WTI crude fell 3.1% to settle at $85.74, its lowest since late August, and gold slipped to its lowest close since September 2025.
Bitcoin futures meanwhile fell 5.6% to 65,070, their lowest close since August 18. The WSJ offered a potential explanation for the malaise: the Anthropic IPO. Bitcoin fell about 21% in the month before SpaceX’s June 12 debut, and it’s down about 20% since mid-October heading into Anthropic’s expected debut Thursday, with some analysts noting investors often trim crypto ahead of high-profile IPOs (WSJ). Last time, though, the selling didn’t end with the listing, as bitcoin kept sliding to its June 30 low, another 8% below where it closed on SpaceX’s debut day. As noted, that same event (the Anthropic IPO) was also blamed by some for the weakness in Tech stocks today.
Tuesday is our busiest day of the week, with numerous economic reports headlined by October retail sales, four Fed speakers and Nvidia’s earnings after the close.
My look at today’s charts follows in a separate post later this evening.
Market Commentary
NVDA:
- “The main task at hand for interim CEO Colette Kress [is to] restore order and give the Street confidence in the Nvidia story going forward,” wrote Dan Ives, analyst at Yorkville Ives. “This starts with earnings and the conference call this week on Tuesday after the bell…we still expect guidance and a typical conference call around robust business metrics with demand metrics that have clearly accelerated since last quarter.”
- “Strong results won’t resolve the questions surrounding Jensen’s departure,” said Jay Woods, chief market strategist at Freedom Capital Markets. “For a company that spent 33 years under one CEO, this is about more than beating expectations. Nvidia now needs to show that the business can continue delivering without the man who built it.”
- “We believe ex-CEO Jensen was viewed as the global dealmaker ‘AI banker,’ and key innovator,” Mizuho analyst Vijay Rakesh said in a note to clients. “The significant NVDA ~32% stock decline from the Oct peak (vs. the SOX down 23%), reflects the ‘Jensen/founder’ premium lost. We believe the CEO departure also adds a 6-7-month management overhang, as [the] company comes under the US gov’t microscope.”
- “Two weeks ago investing in this name looked like a safe journey down a well-lit long hallway,” said Mike Mussio, chief investment officer at FBB Capital Partners. Now, he added, “there are several dark corners that people feel they need to peek around to glean additional information before moving forward.” “There is plenty to digest, and many jumpy investors seem unwilling to stick around for answers,” Mussio continued.
- OpenAI’s Sam Altman said he believes the AI industry will weather the uncertainty prompted by the ousting of Nvidia’s CEO. “The revenues and demand are growing so strongly that I think the industry will be fine,” Altman said on stage at Semafor’s Silicon Valley & The World conference in San Francisco. “But again, I think Jensen has played this extremely special and valuable role as someone to really drive things forward with great vision” (Bloomberg).
Equities:
- Technology stocks got crushed Monday, with investors concerned about the potential for cuts to capital expenditures in the artificial-intelligence sector, said Luke Lango, technology analyst and editor of Innovation Investor. He noted reports Monday that SemiAnalysis cut its AI capital expenditure estimates for 2027 and beyond. Tighter chip controls and weekend reports that Nvidia may retrench as the “piggy bank” for AI, given interim CEO Colette Kress’ more conservative nature than former CEO Jensen Huang’s, emphasize that Wall Street and Washington will both continue to pressure AI spending lower, he said (MarketWatch).
- “There’s been a great deal of noise in the market lately,” said Chris Larkin at E*Trade from Morgan Stanley. “Stocks weathered last week’s Nvidia volatility, but earnings and a high-profile IPO mean this week will likely continue to revolve around tech sentiment.”
- “The bigger question for the AI trade isn’t whether Nvidia or Anthropic delivers, but whether investors are putting new money to work or simply rotating between winners and losers,” said Mark Hackett at Nationwide. “How investors respond to this week’s catalysts could be an important clue in how the tug-of-war between bulls and bears ultimately plays out.”
- “We think Semiconductors have a reasonable chance of being 50% higher in a year,” Adam Parker at Trivariate wrote in a Sunday analysis.
Stock and Sector Breakdown
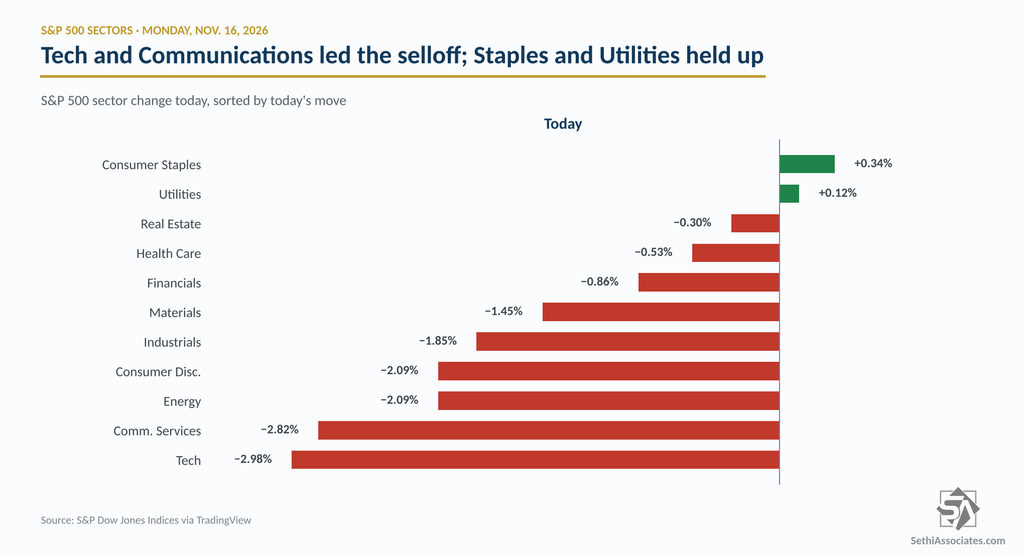
Nine of 11 sectors fell, led by Tech (-3.0%) and Communication Services (-2.8%), followed by Consumer Discretionary and Energy (both -2.1%), while only Consumer Staples (+0.3%) and Utilities (+0.1%) held up.
Staples and Utilities holding up again fits Helene Meisler’s “either/or” market, where there’s always somewhere to hide, though she thinks that with rates backing up, either bonds rally or the bond proxies “are going to have to play some downside catch-up.” Staples are now priced like it’s 1999, and as I noted this morning, in the three times since 1999 that stocks kept falling, Staples kept winning.
Just 145 S&P 500 stocks rose and 356 fell, with six gaining more than 3% and 88 falling that much.
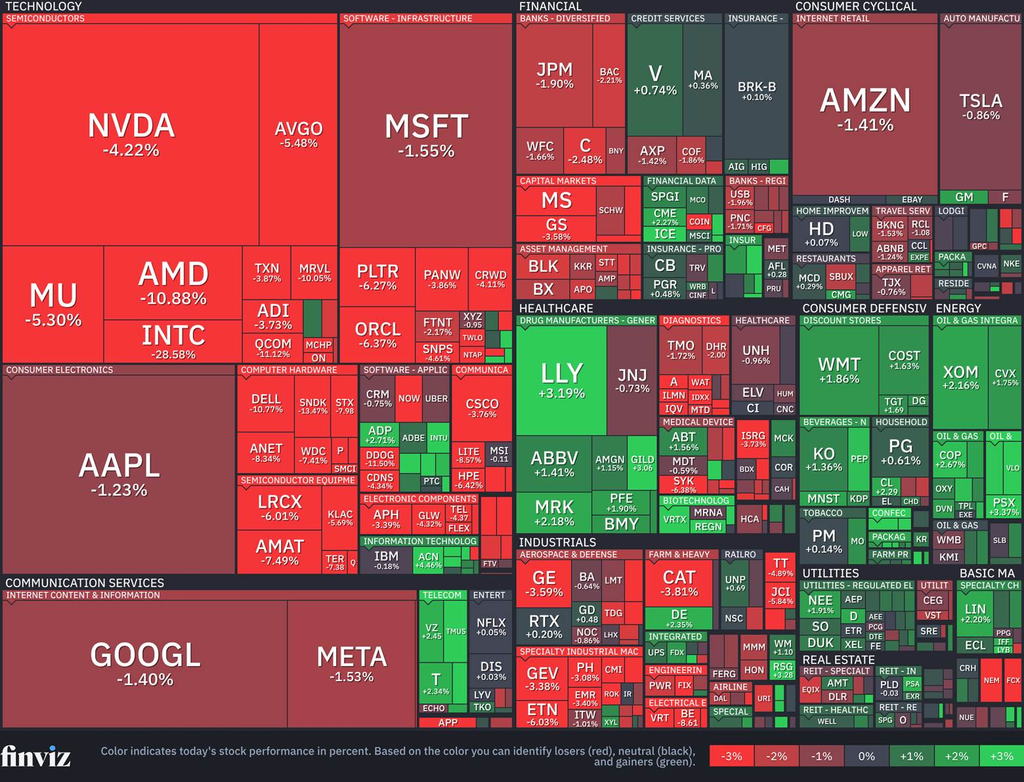
Sandisk (SNDK) was the S&P 500’s worst performer, down 8.6%, as memory, optical and other AI hardware names led the declines, with Lumentum (LITE), Ciena (CIEN), Micron (MU), Marvell (MRVL), Teradyne (TER), Intel (INTC), Super Micro (SMCI), Corning (GLW), Dell (DELL), Coherent (COHR) and Vertiv (VRT) all down 7% to 8.5%, along with Bloom Energy (BE). Nvidia (NVDA) fell 4.1% ahead of its report Tuesday, and, like Friday, rivals didn’t pick up the slack, with AMD (AMD) down 5.6% and Broadcom (AVGO) 3.8%.
Among the other megacaps, Alphabet (GOOGL) fell 4.1%, Amazon (AMZN) 3.4%, Tesla (TSLA) 2.7% and Meta (META) 2.4%, while Microsoft (MSFT) and Apple (AAPL) lost about 1%. Robinhood (HOOD) and Coinbase (COIN) fell 7.5% and 6.1% on the back of the drop in bitcoin, Freeport-McMoRan (FCX) 6.9% as copper fell below $6, and major banks fell amid reports of customers having trouble accessing their accounts in the latest high-profile technology snafu, with JPMorgan (JPM) down 2.3%.
On the upside, Tyson Foods (TSN) led the S&P 500 jumping 8.7% as investors looked past cautious fiscal 2027 guidance to an improving outlook for its struggling beef business, and Coca-Cola (KO) hit another record high. Airlines held up after air traffic control was restored following Friday’s nationwide ground stop, with Southwest (LUV) up 3.3%. Health insurers Centene (CNC, +4.9%), Elevance (ELV, +3.9%) and Humana (HUM, +2.6%) also rose, along with Tractor Supply (TSCO, +4.0%), with no particular news to account for the moves beyond a Bernstein upgrade to Centene.
On the Nvidia saga, Bob Byrne says shareholders should want Jensen Huang back, while Chris Versace thinks bringing him back would be too much of a credibility risk for the board, and Ed Ponsi asks whether Trump is right that Huang should be reinstated. Stephen Guilfoyle notes Nvidia’s insurance may not protect its own balance sheet from the legal costs. Doug Kass has no intention of bottom-fishing Nvidia, but he started trading longs in SPY and QQQ before the open, added twice and bought back Dell.
The bigger issue for the AI trade may be the money. I looked this morning at whether Nvidia’s open checkbook is closing, whoever runs the company, and Peter Tchir says a new CEO backing off Huang’s aggressive financing is the outcome that isn’t priced in yet. Bret Jensen thinks that after the Nvidia news and the jump in rates, a significant slowdown in AI capex growth “feels almost certain in 2027.” Elsewhere, Bob Lang sees a bit of promise in Alphabet’s chart after its post-earnings fall but wants to watch it a little longer.
FedWatch
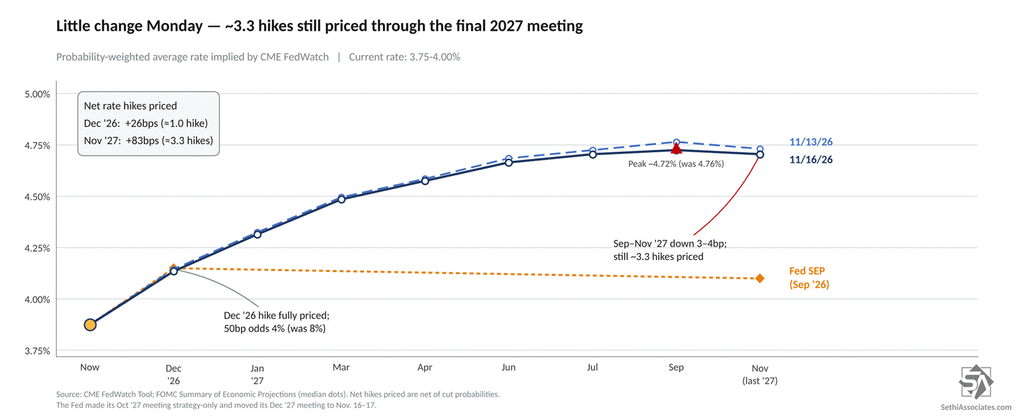
Fed rate-hike expectations were little changed Monday. A December hike remains fully priced, though the odds of a half-point move slipped to 4% from 8% Friday. Markets price 26 basis points of hikes by December and 83bp through the Fed’s final 2027 meeting in November, about three and a third hikes, down from 86bp, per CME FedWatch.
More From TheStreet Pro
Doug Kass’s Diary:
- Oscillator Is a Little Bit Oversold
- Early Monday Morning Trading
- Questions to Nvidia Buyers
- Added to Index Longs
- More Trades
- Diminished AI Expectations
- Chips, Memory, Tech: Down, Down, Down; Upside, Downside Movers in A.M.
- Tech (XLK) Vs. Financials (XLF)
- Boockvar on Nvidia, AI Buildout, China Retail
- SPY, QQQ Adds
- Charting the Late Morning Market
- More Cash for Gold
- Howling About AI Boom Risks
- More Tales From Nvidia: Here Comes The Judge (Issue #282!)
- Afternoon Trading
- Gold Sold
- Today’s Largest Buys
Note: Doug posted 40 Diary entries today; these are the market ones.
And From Me If You Missed It
- Two Months After the Fed’s First Hike, the Historical Playbook Is Holding
- Morgan Stanley Goes ‘Max Overweight’ Global Stocks, Calls 2027 the Year to Embrace Risk
- Is Europe Really the Anti-AI Trade?
Miscellaneous
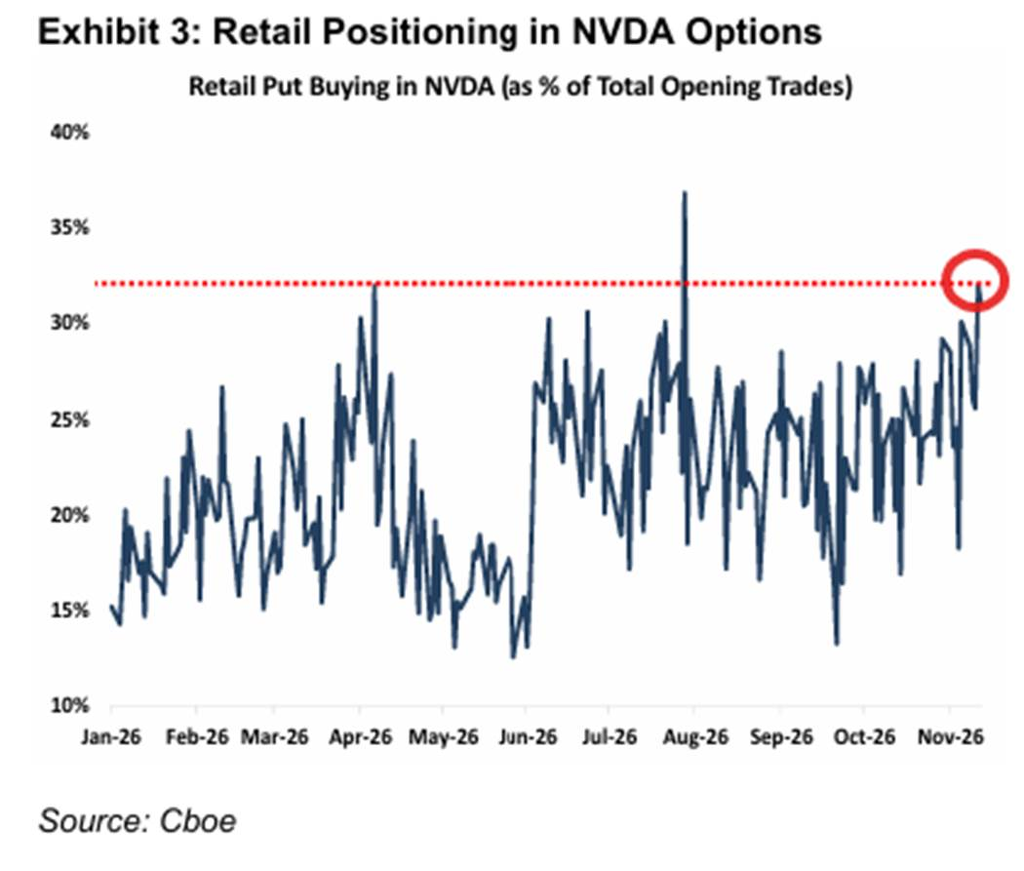
While there have been indications of retail investors piling into Nvidia, CBOE’s Mandy Xu says the options action is not as bullish:
“All eyes on NVDA earnings this Tuesday following the ouster of Jensen Huang. Options are implying a one-day move of 8% on earnings (vs average realized move of 4.8% the past four quarters). NVDA 1M implied volatility gained 2 pts last week to near a 1-year high of 59% (vs. realized vol of 55%).
“While skew flattened on the sell-off in the stock, suggesting overall increased bullish sentiment, retail positioning has turned more cautious. Looking at the retail flow on Cboe’s exchanges, we see a notable uptick in put buying in NVDA, which made up 32% of all retail opening trades on Thursday, over 10 pts higher than the YTD average of 21%. See Exhibit 3.
“Call buying still makes up the bulk of retail activity in NVDA, though the share has fallen in recent weeks and is hovering near the YTD average level of ~46% (vs. high of 62% in Sep).”
Yardeni: Charlie Munger famously warned that there are three ways smart men can go broke: “Liquor, ladies, and leverage.” NVIDIA co-founder and now former CEO Jensen Huang has run into trouble with the second of Munger’s three L’s. He won’t go broke, but he is out of a good job.
Huang’s departure rattled the AI trade, with NVIDIA shares plunging 4.3%, sending its forward P/E to 11.7 (charts). We promised you buying opportunities after the midterm elections. There were a bunch last Thursday and a few more [last week].
Our base case is that NVIDIA’s financing strategy remains intact. Colette Kress, NVIDIA’s longtime CFO and newly appointed interim CEO, has worked closely with Huang since 2013 and helped oversee the company’s strategic investments and financing arrangements. During NVIDIA’s August 26 earnings call, she defended these investments against accusations of circular financing, stating, “We recognize the scale of this support, and we know some will call it circular financing. We see it differently.” She argued that these investments would generate attractive returns while strengthening NVIDIA’s AI ecosystem, suggesting continuity under her leadership. We don’t expect political constraints to meaningfully increase as a result of the controversy. Nor do we expect another trade conflict with China to erupt.
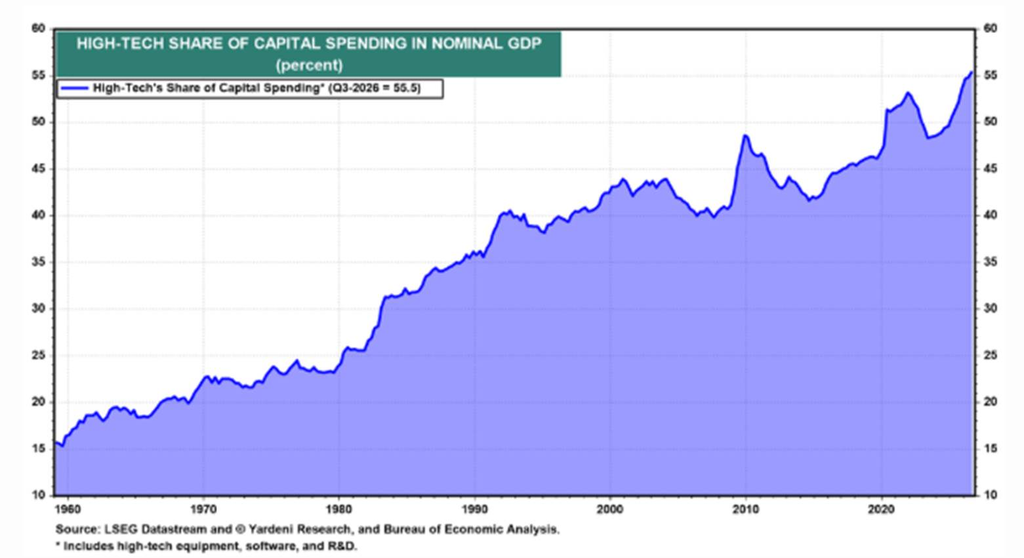
Even if some of the constraints intensify, they would likely turn existing speed bumps into bigger speed bumps rather than roadblocks to the AI investment boom. AI remains the latest evolution in the Digital Revolution that began with IBM’s mainframes, and we expect the investment boom to continue without Huang (chart). We therefore view any resulting selloff as another buying opportunity for the AI trade.
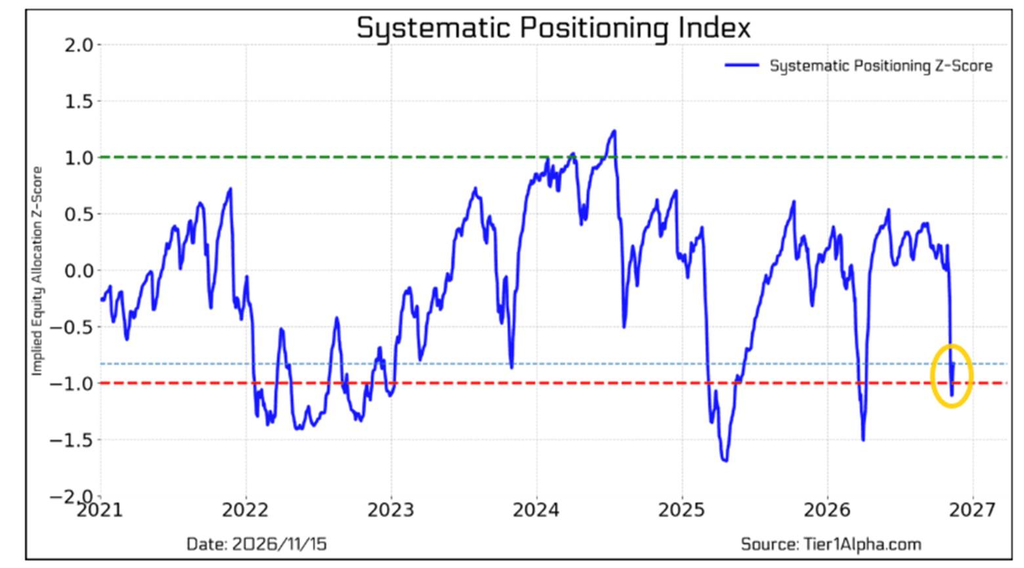
Tier1Alpha says this morning that this week’s options expiration “could provide a potential reset for dealer positioning… we are biased towards a lower-volatility environment following this options expiration.”
“systematic positioning remains low, which means a lower-volatility environment could cause a rapid acceleration in the types of strategies that have led to so many V-shaped recoveries in the past.
“The difference this time is that we’ve already recovered most of the drawdown, which actually favors a setup for markets to potentially push towards new all-time highs in the coming weeks as these flows come back online and create a strong tailwind of mechanical buying.”
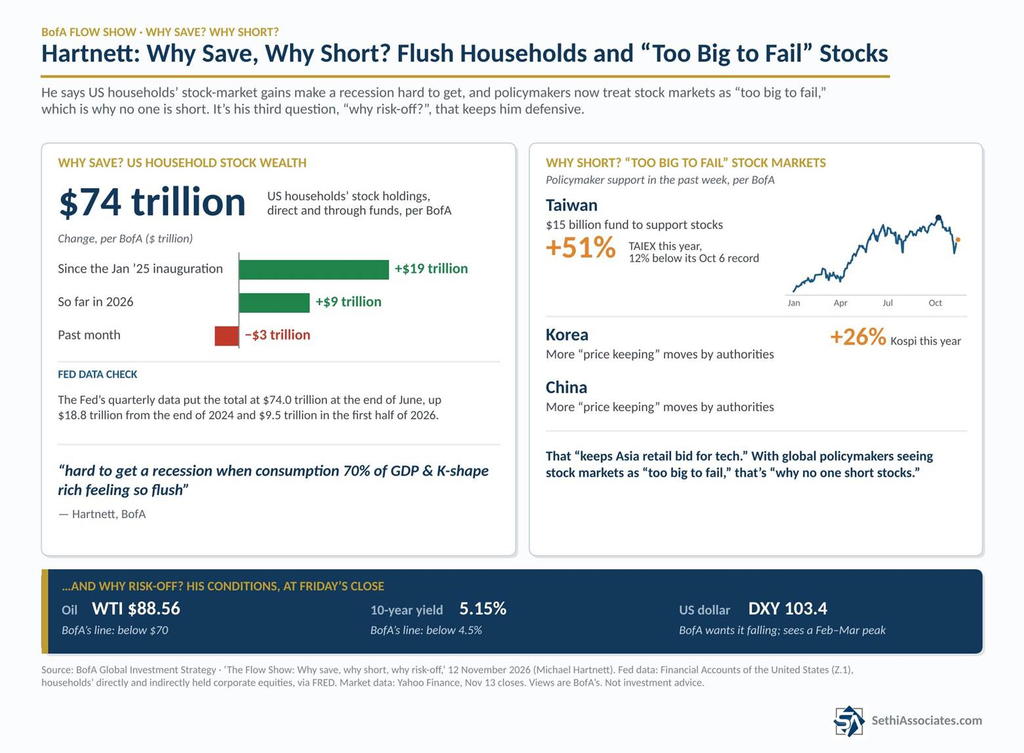
BofA’s Hartnett (Flow Show) asks “why save?” and “why short?”
Why save when US household equity wealth is down about $3 trillion in the past month but still up about $9 trillion this year and $19 trillion since the January 2025 inauguration? He says it’s “hard to get a recession when consumption 70% of GDP & K-shape rich feeling so flush.” The Fed’s own data put households’ stock holdings at $74.0 trillion at the end of June, up $18.8 trillion from the end of 2024.
Why short when this past week Taiwan announced a $15 billion fund to support its stocks, which are up 50% this year but 13% off their highs, while authorities in Korea and China made more “Price Keeping Operation” moves? That “keeps Asia retail bid for tech.” With global policymakers seeing stock markets as “too big to fail,” he says that’s “why no one short stocks.”
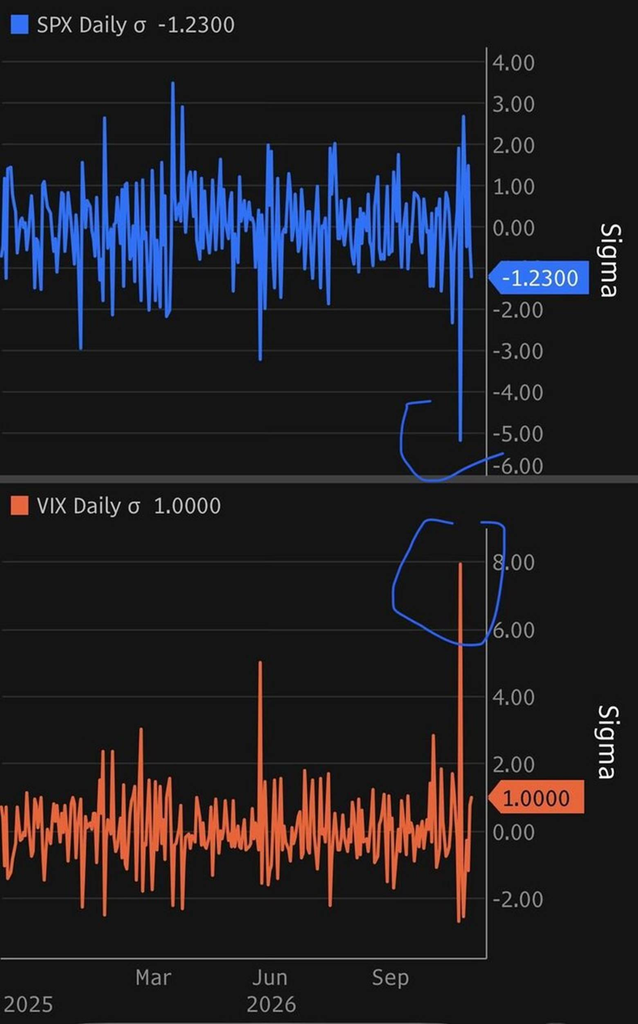
Blackrock’s Wei Li: I should not see [a] 5 sigma SPX move (1-in-3.5 million day event) [or a] 7 sigma VIX move (basically impossible) in my life time. Both happened last week. In fact each happened 3 times [the] last 5 years….
I am not so special, though. Gaussian assumptions systematically underestimate tails by orders of magnitude. We are now in a “polyfurcated” world with wildly different scenarios on the table and, given what we know today, the probabilities might as well be equal.
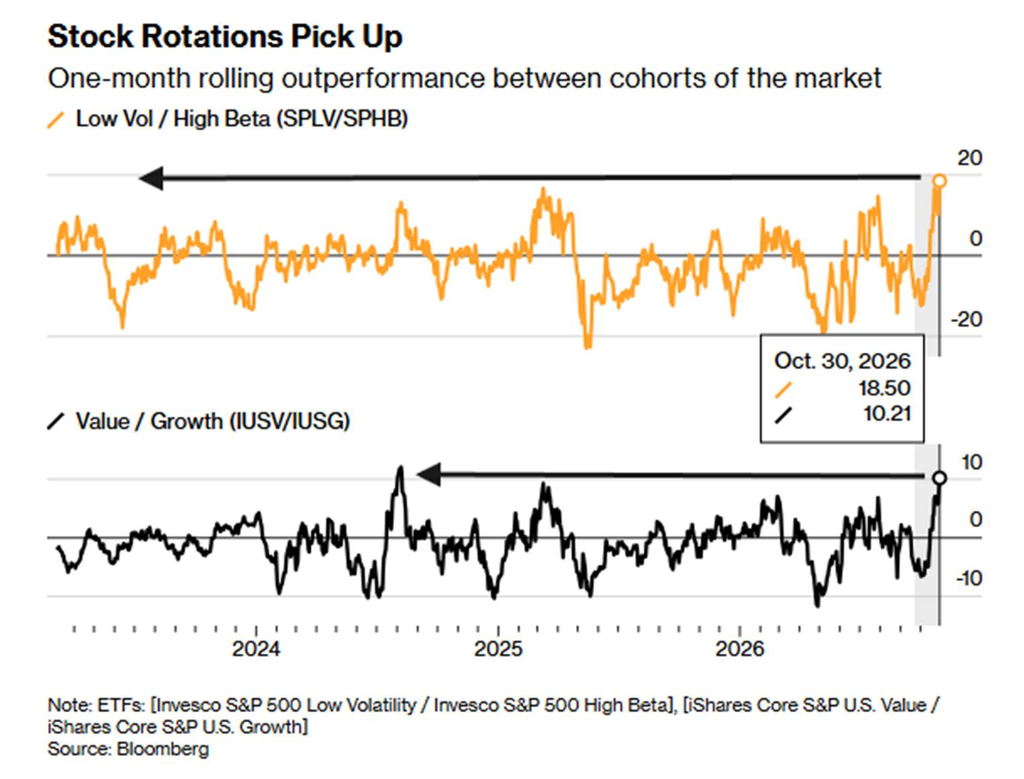
BBG: As of the end of October low volatility had outperformed high beta by the most in the past 3+ years and value over growth by the second most after August 2024.
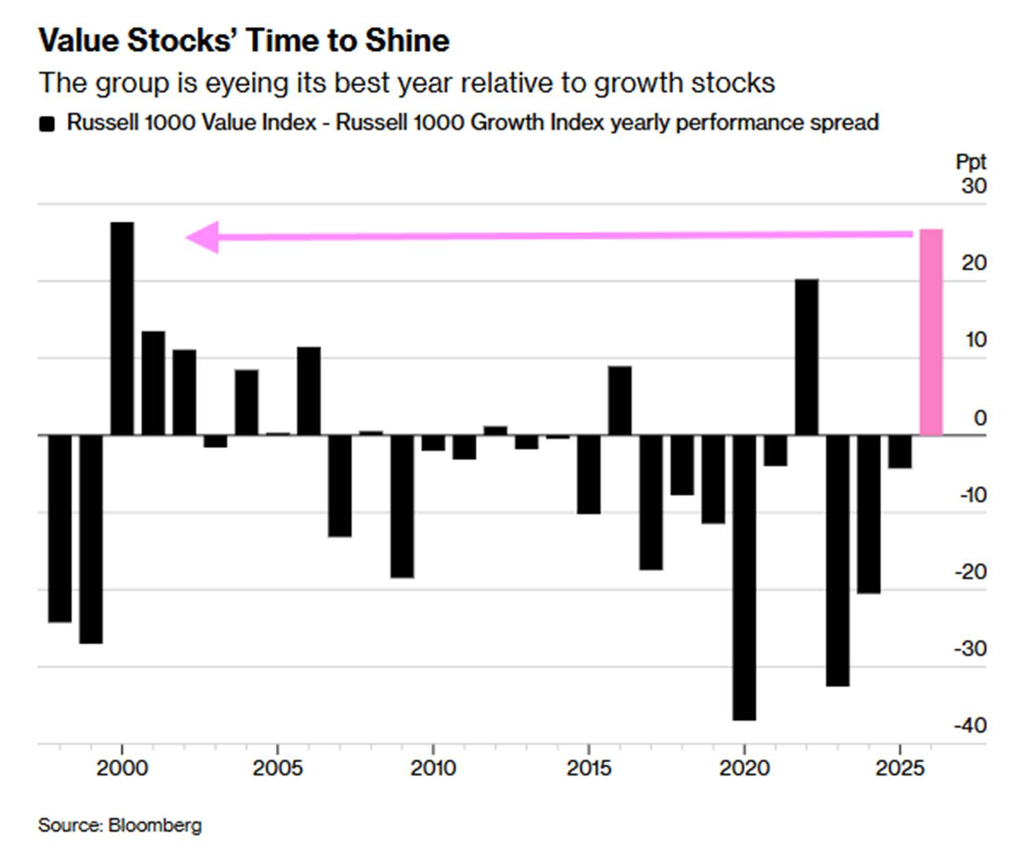
BBG: The Russell 1000 Value Index is on track for its best year since 2000 relative to the Russell 1000 Growth Index. The value stock gauge has gained 25% so far this year. Meanwhile, the Russell growth index is down 1.8%.
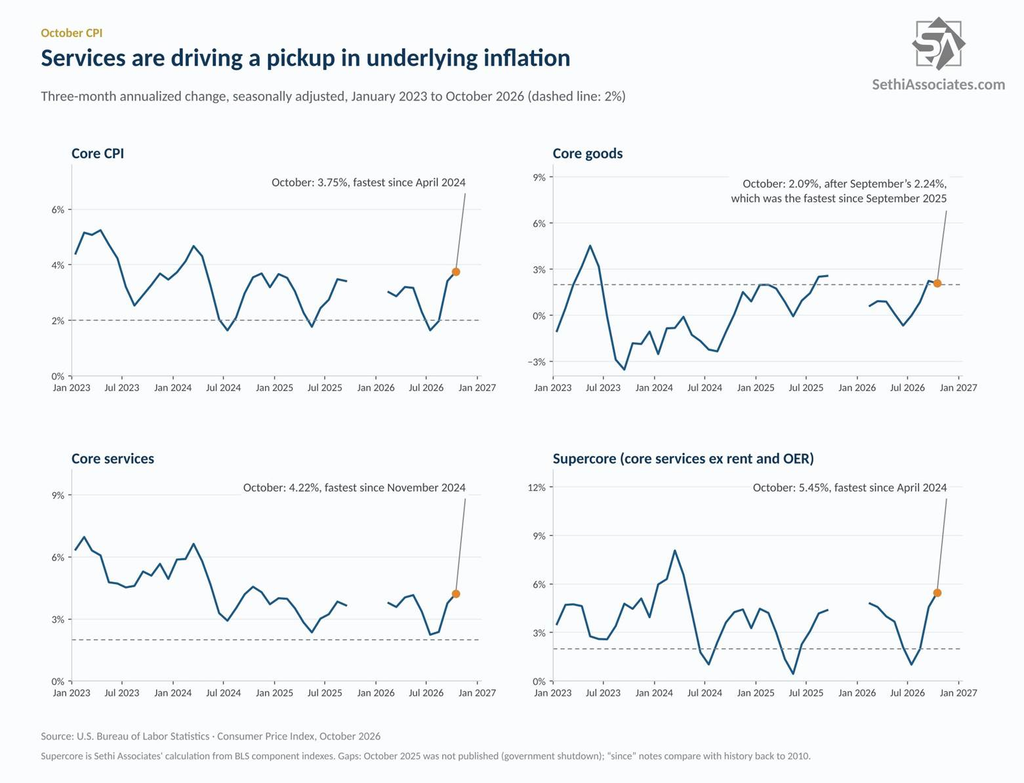
BofA: “The October hold is increasingly looking like a mistake.”
▪ Supercore (core services excluding rent and owners’ equivalent rent) is running at a 5.45% annualized pace over three months, up from 1.01% in July and the fastest since April 2024, by our calculation.
▪ Core services are running at a 4.22% three-month annualized pace, the fastest since November 2024, and core CPI overall at 3.75%, the fastest since April 2024.
▪ Core goods are running at 2.09% annualized, down from September’s 2.24% (the fastest since September 2025) on a 1.22% drop in used car prices in October, but core goods excluding used cars rose 0.39%.
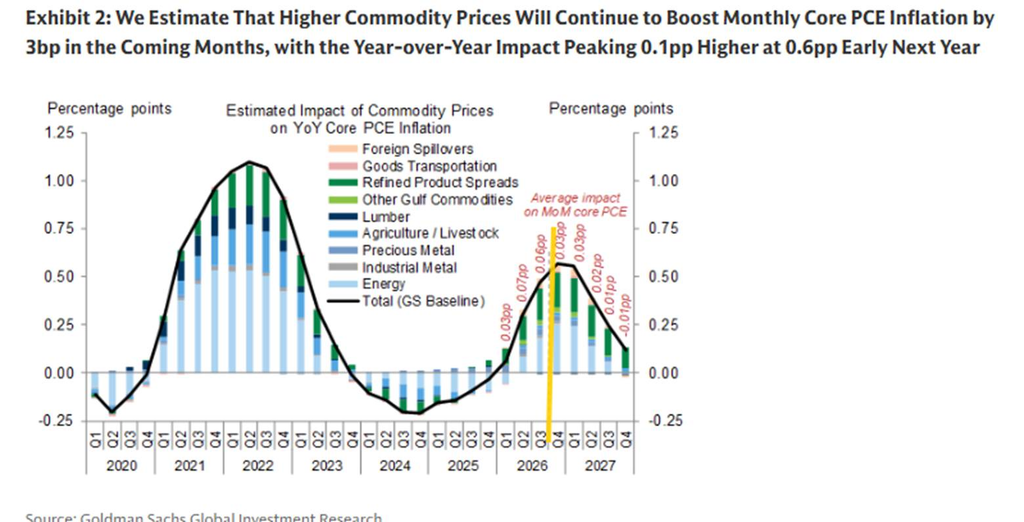
Goldman: We estimate that higher commodity prices are currently boosting year-over-year core PCE inflation by about 0.5pp, with 90% of the effect driven by higher crude prices and wider refined product spreads (Exhibit 2).
In our framework, commodity price increases typically complete their passthrough to consumer prices over 6-12 months, which implies that past commodity price increases will continue to boost core inflation by 3bp per month through 2027Q1 and 1-2bp per month in 2027Q2-Q3.
Taken together, we estimate that roughly two-thirds of the cumulative passthrough to core PCE prices is now behind us and that the impact on year-over-year core PCE inflation should peak at 0.6pp in early 2027 before the initial oil price spike drops out of the year-over-year calculation.
Goldman: Although core inflation forecasts (including our own) should already incorporate the delayed passthrough of upstream price changes, consensus forecasts have historically been somewhat conservative in incorporating these shocks.
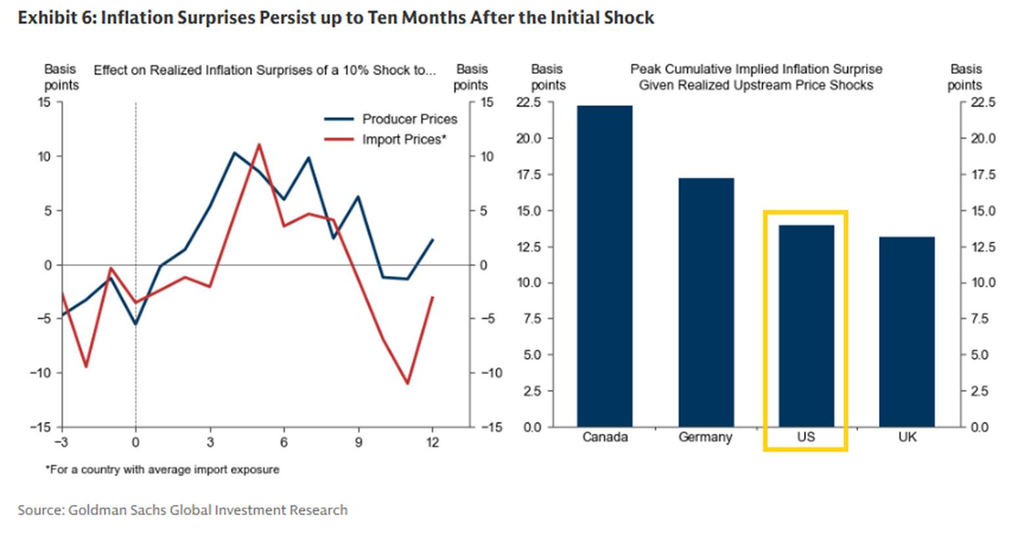
…Applying the historical response of monthly inflation surprises to realized price increases since the start of the Iran War implies that inflation could surprise consensus expectations to the upside by a cumulative 0.1-0.2pp over the next 9 months (right chart, Exhibit 6), some of which may be realized via an upward surprise from a “January effect” at the start of the year.
…If realized, such surprises could prompt modest further tightening from major central banks in early 2027.
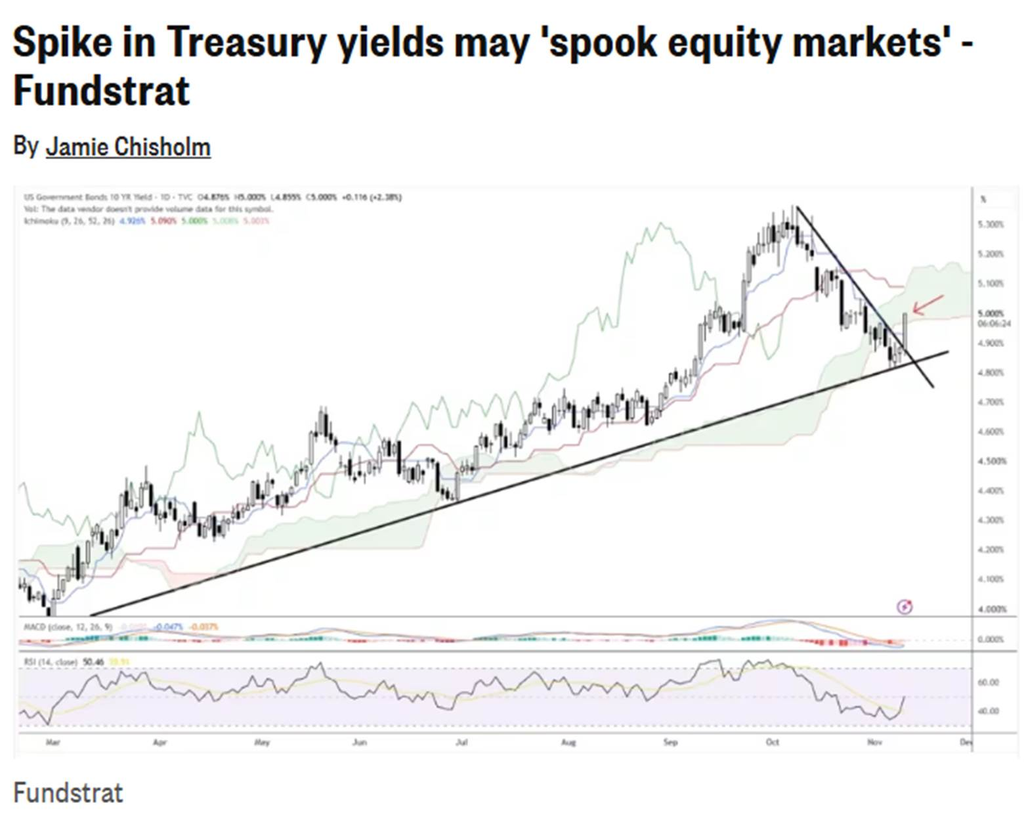
MarketWatch: Fundstrat’s head of technical strategy, Mark Newton, made a prescient call Tuesday noting that the 10-year Treasury yield’s spike back to 5.0% had broken the recent downtrend “and should result in an upward acceleration in rates in the short term.”
We got just that Thursday with the 10-year jumping to 5.10%.
“Above 5.12% could lead to a ‘final’ push up to test and exceed September yield peaks,” he adds. “It’s this kind of return in cross-asset volatility which could spook equity markets when momentum is already quite fragile after last week and near-term trends remain bearish.”
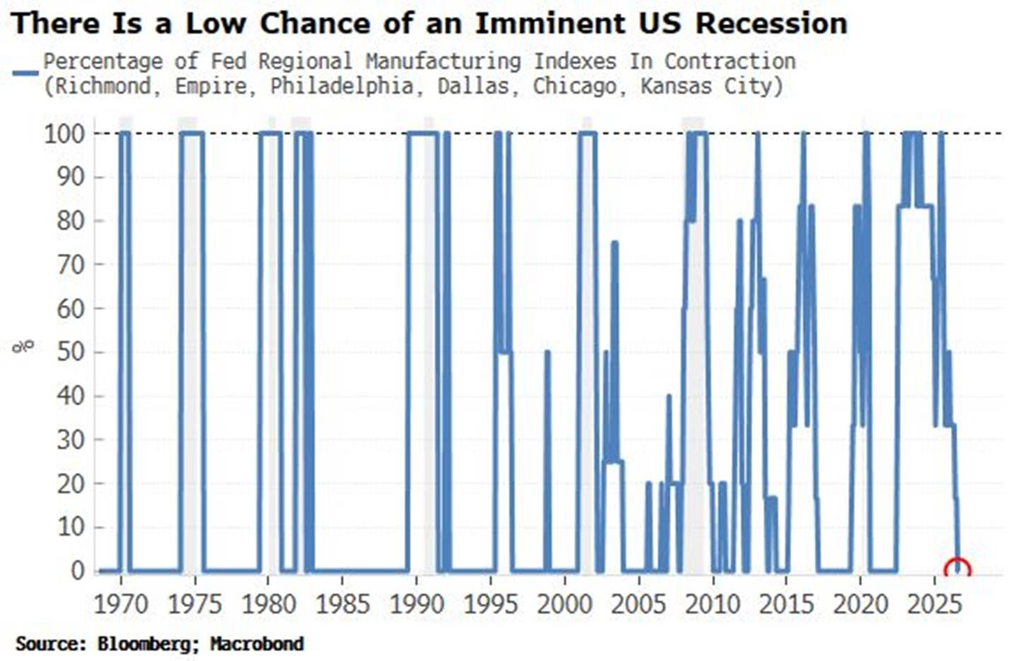
BBG’s Simon White: nominal yields have in the main risen this year not because fiscal risks are expected to get even worse (or, equivalently, because inflation is about to become unanchored) – but because real growth is expected to rise.
The economy’s resilience can be seen in the chart below, showing that now none of the Fed’s six regional manufacturing indices are in contraction. When all are in contraction, that has historically often coincided with a recession. That none are, shows that an imminent recession (say in 3-6 months) has quite a low probability.
The flipside of all this is that a magic level in yields is unlikely to trigger a durable and significant rally. Instead, we’re not likely to see such a move until real growth or inflation are slowing.
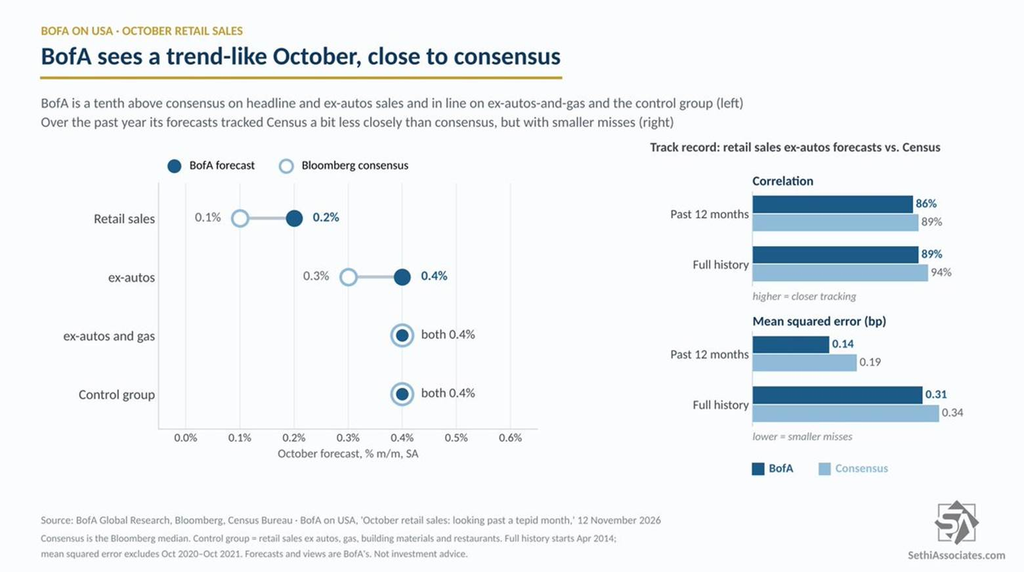
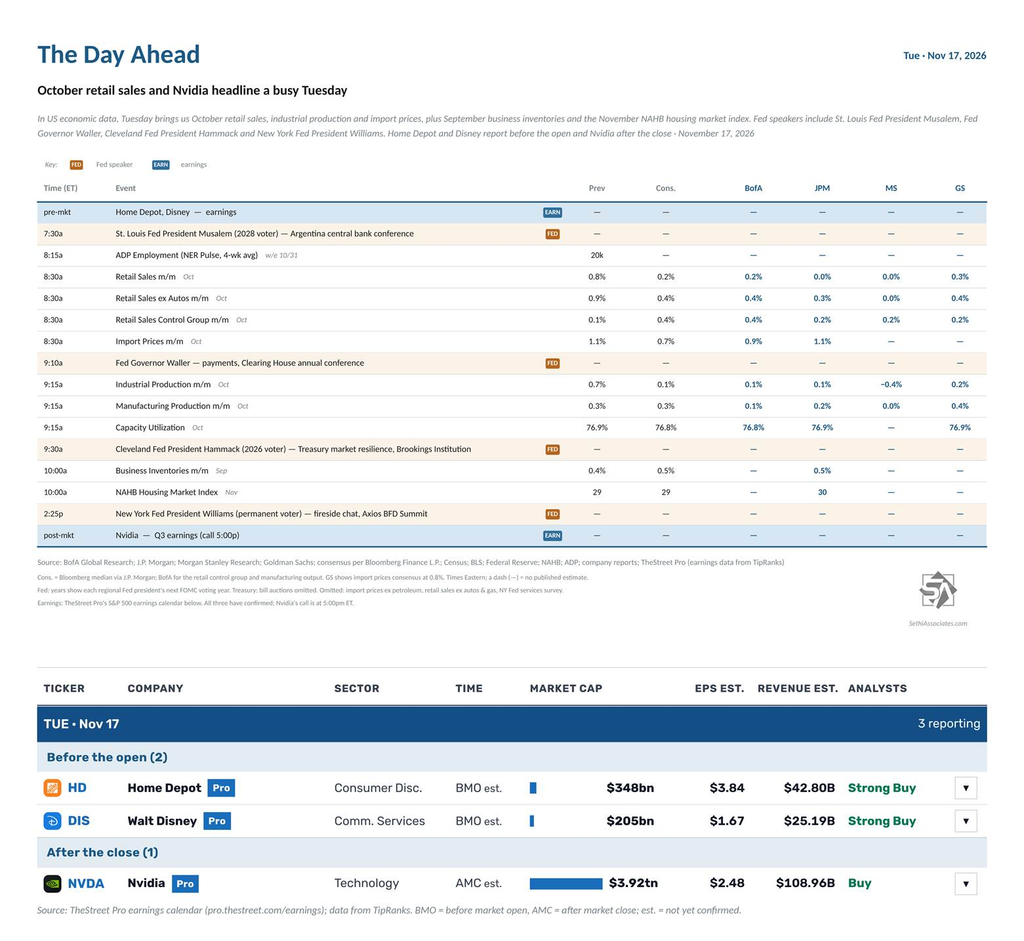
BofA is looking for a trend-like October retail sales report, close to consensus:
▪ Retail sales +0.2% (consensus +0.1%).
▪ Ex-autos +0.4% (consensus +0.3%).
▪ Control group +0.4% (in line with consensus).
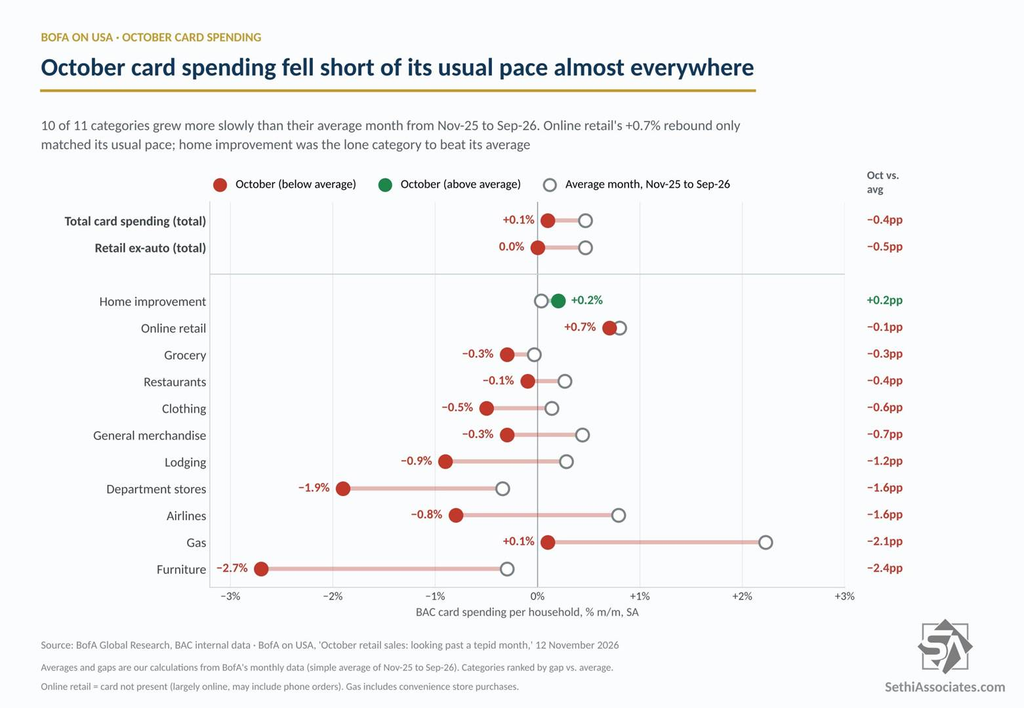
BofA’s own card data was soft, but it expects seasonal adjustment to lift the Census figures by 0.2–0.3pp relative to that signal.
BofA’s card data shows October spending fell short of its usual pace almost everywhere.
By our calculations, 10 of 11 categories grew more slowly in October than their average month over the prior 11 months. Furniture (−2.7%) and department stores (−1.9%) were the weakest, and even online retail’s +0.7% rebound only matched its usual pace.
Total card spending per household rose just 0.1% month over month, the second soft month in a row.
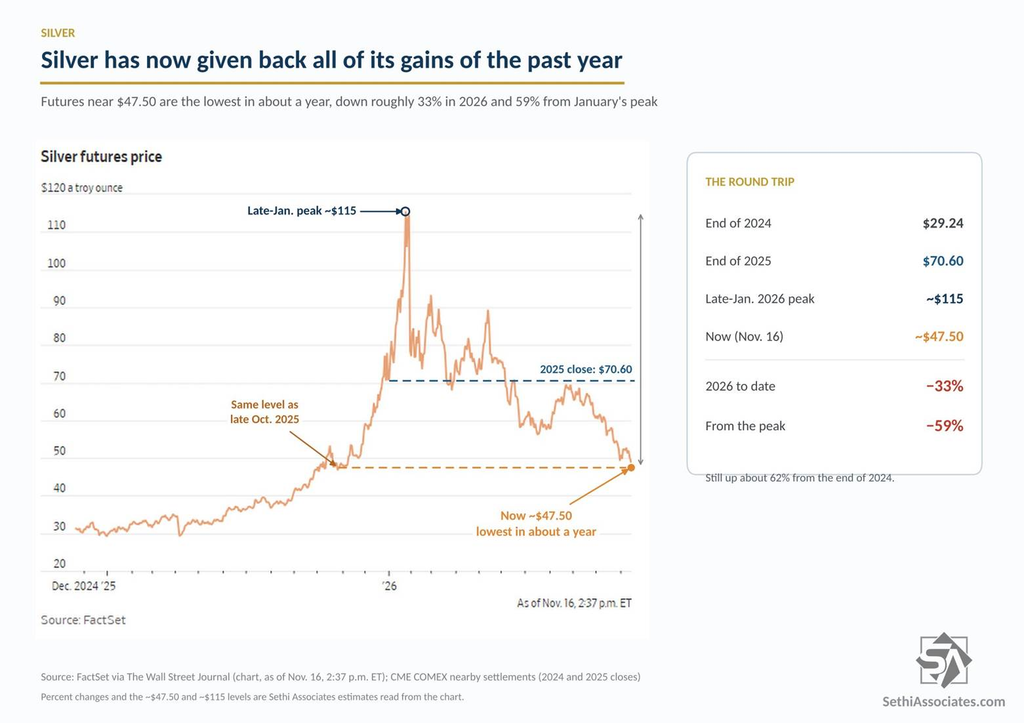
Silver (SLV) has seen an even more dramatic price drop than gold or copper. Futures are near $47.50, the lowest in about a year and back where they traded in late October 2025 (WSJ/FactSet).
▪ Down about 33% in 2026 (2025 close: $70.60).
▪ Down about 59% from the late-January peak near $115.
▪ Still up about 62% from the end of 2024.
Wrap-Up — The Retest Comes Early
I said Sunday that while I was “definitely more bullish than I was a week ago,” a retest of the November 5th lows “remains a distinct possibility” (The Week Ahead – Have We Seen the Q4 Bottom?). It’s starting to look like that’s what we’re going to get, just a lot quicker than we usually see one. Only seven sessions after that low, the S&P 500 had its worst day since, falling 1.9% and coming within about 0.6% of the November 5th close (7,353.73) intraday before finishing 0.9% above it. The Nasdaq Composite closed 0.8% above its November 5th close, the Russell 2000 0.5% and the Dow just 0.2%.
Holding those levels on a closing basis is what matters now. A close below the November 5th lows would turn a retest into a potential breakdown. It would also break several patterns we’ve been following including Goldman’s first-hike playbook, where equities “struggle after the first hike but recover quickly,” with the median trough within two months. Today marked two months since the September 16th hike, and the November 5th close is still the low.
Today also made clear investors aren’t ready to embrace Tech yet. The SOX fell 5.3% and the Nasdaq-100 2.7%, while the equal-weight S&P 500 fell just 1.0%, about half the cap-weighted index’s loss. Rev Shark thinks the crowded AI trade has turned into a stock picker’s market, and that the sharp one-day rallies will keep failing until the forced selling is done. His sign that it’s ending: bad news that no longer pushes these stocks to new lows.
Sunday I laid out the virtuous cycle a calmer market could set off: higher gamma, lower volatility, more systematic releveraging, more discretionary flows and higher prices. Declines like today’s run it in reverse. The S&P 500 is now about 2.5% below where BofA estimated dealer gamma turns positive (~7,605) and about 3% below Tier1Alpha’s flip (~7,657), so market makers are trading even more with moves than they were coming into the session. One-month realized volatility rose to 22.5% (from 21.9%), the highest since May 2025, which will at least pause the systematic releveraging we’d started to see and could reverse it. BofA’s down-market scenario had systematic funds selling about $22B this week, against about $28B of buying if stocks went nowhere. So a lot of not-good things could come out of today’s action.
It also gets at the caution I’ve been expressing about the duration of the pullback: the deleveraging has been there in price, but not in time. Tech’s drop in price on Goldman’s Tech-led drawdown framework went past the median, and DB’s rotation measure fell further than in any of the last four rotations. But at 29 sessions from the October 6th record, we’re still far short of Goldman’s five-month median. At 28 days from DB’s October 7th peak, we’re also short of the 43 days of its two shortest prior rotations (59-day median). Sunday I wondered whether “it’s the depth and not the duration that matters here.” Today argued the duration may matter after all.
The seasonals aren’t much help near term either. Hirsch shows tomorrow (day 12) as the sharpest drop of the month in midterm years, with the mid-month low on Thursday (day 14).
If the November 5th lows hold, though, the positives I laid out Sunday haven’t gone anywhere. Positioning is still light, sentiment has tipped into territory that has historically been followed by gains, and the buyback window is wide open. And remember, negative gamma and high leveraged-ETF AUM mean big moves can happen in both directions.
Tomorrow economic data takes center stage, but the real event will be Nvidia’s earnings after the close. Those have the potential to act as a clearing event, but it might take getting past the Anthropic IPO before we may be able to put a rally back on the table.
As always, let’s see what we get and go from there.
The Day Ahead — Retail Sales and Nvidia Headline a Busy Tuesday
In US economic data, Tuesday brings us October retail sales, industrial production and import prices, plus September business inventories and the November NAHB housing market index. We’ll also get the weekly ADP report.
Fed speakers include St. Louis Fed President Musalem (2028 voter), Fed Governor Waller, Cleveland Fed President Hammack (2026 voter) and New York Fed President Williams (permanent voter).
Three S&P 500 components report, all with market caps over $100B:
Before the open: Home Depot (HD) and Disney (DIS).
After the close: Nvidia (NVDA).
Outside the S&P 500 we’ll hear from JD.com (JD) and Viking (VIK).
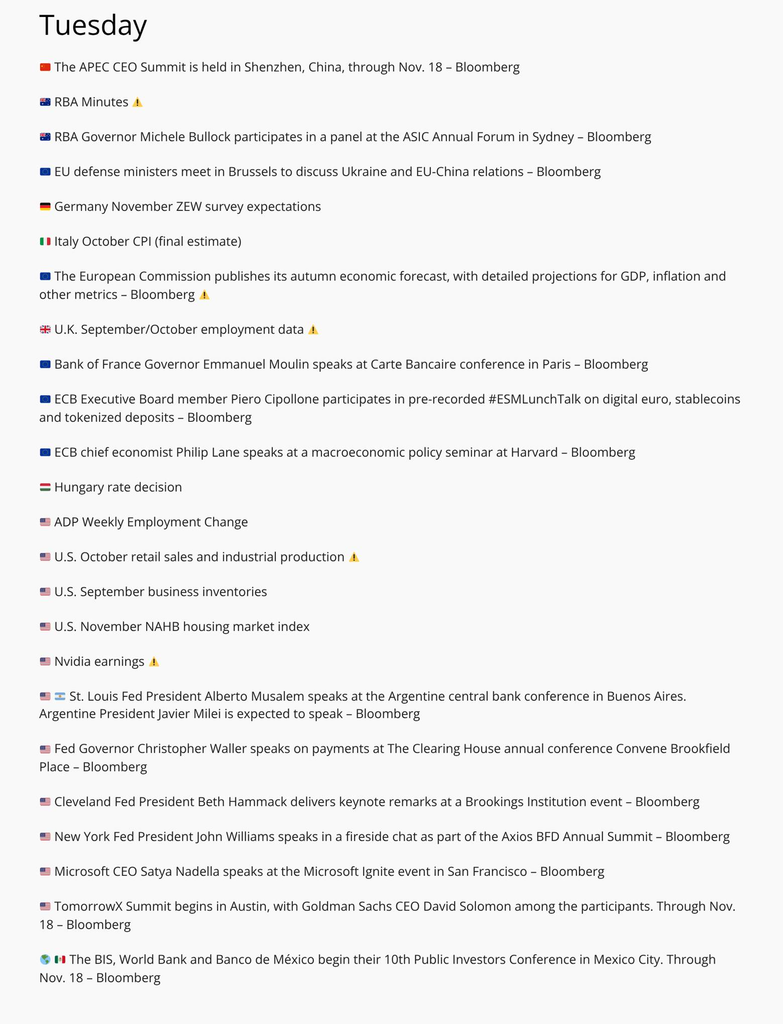
Ex-US highlights include the minutes of the RBA’s November meeting, the UK’s September labor market report, Germany’s November ZEW survey, Italy’s final October CPI and the European Commission’s autumn economic forecast. Hungary’s central bank announces a rate decision, ECB chief economist Lane speaks at Harvard along with Cipollone and Moulin, and RBA Governor Bullock joins a panel. The APEC CEO Summit gets underway in Shenzhen, and EU defense ministers meet on Ukraine and EU-China relations.
From Christophe Barraud’s international Week Ahead rundown:
At the time of publication, in terms of securities mentioned, Sethi was long AMZN, DELL, DIS, GOOGL, IWM, META, MSFT, MU, NVDA, QQQ, RSP, SPY and numerous Treasury ETFs, and short CPER, HOOD, IBIT and MRVL. In the last 24 hours Sethi sold his position in AMD.