Somewhere to Run, Somewhere to Hide
Let’s look at the stubborn Either/Or Market, bonds, the equity bond proxies and what could be next for the ‘others.’
You've reached your free article limit
You've read 0 of 1 free Pro articles.
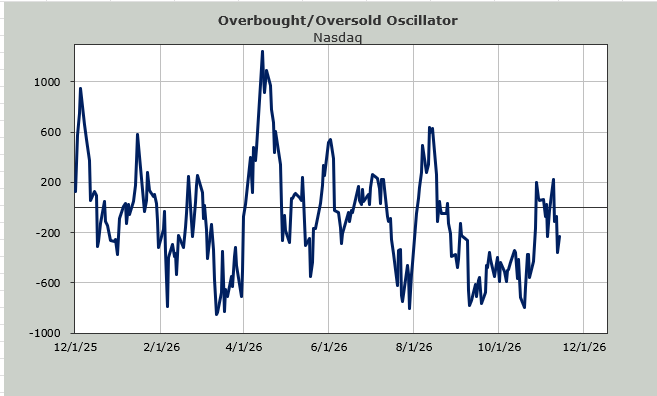
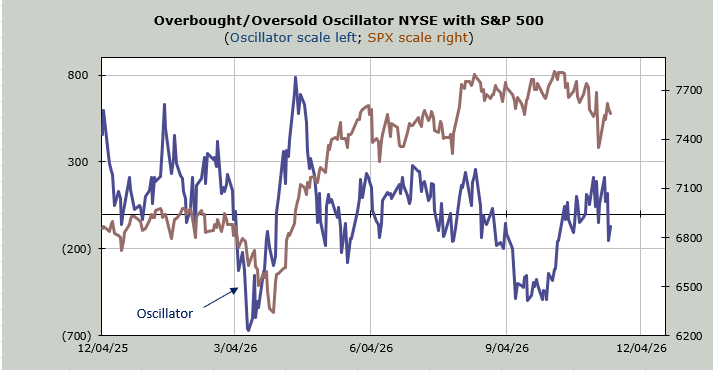
By now we all know the story. The S&P 500 hasn’t budged in six months. And that is mostly because we have been in an Either/Or Market. When there is always somewhere to hide there is no reason for the S&P to go down much.
But hiding doesn’t bring us panic. Oh, it can bring us bearishness, or gloom — that we have — but panic typically arrives only when the index brings everything down together. We came close about 10 days ago when 79% of the volume was on the downside. Are we waiting for something that might not happen? Possible.
But let me note a few things. The bonds took a major hit last week with interest rates on the 10-year flying upward to 5.14% by Friday’s close. I had thought they could/would back up but not that much. This puts them on my radar screen even though I think in the short term they are a little oversold (price), which means I expect rates to get some relief this coming week.
Yet, notice that the equity bond proxies don’t seem to care. Not yet at least. Oh sure the Homies sold off a bit last week, but not like they should have with rates backing up like that. The REITs mostly milled around. Staples continue to do well, despite everyone hating them. And yes, they still hate them because y’know, they are so expensive they say. I still think Staples are okay despite being short-term overbought.
But back to bond proxies. The Utes, despite my thinking they should back off, and with rates doing what they did, this group barely blinked last week. So there is a disconnect. Either bonds are going to rally or those stocks are going to have to play some downside catch-up.
Which brings me to my view on the “others.” As you know by now, I think the window for the others to get overbought (intermediate term) is around Thanksgiving (next week!). But I want to see signs that there is some rolling over, not just overbought-ness.
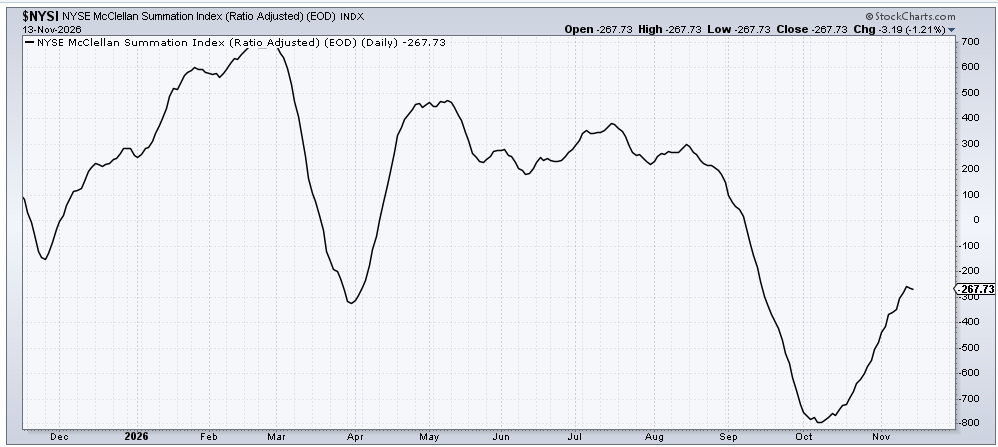
Last week the McClellan Summation Index stopped going up, this despite six of the last 10 days having had positive breadth. It won’t take much to push it back up, but it won’t take much to roll it right over either. An overbought market with the Summation Index rolling over is not good for the others.
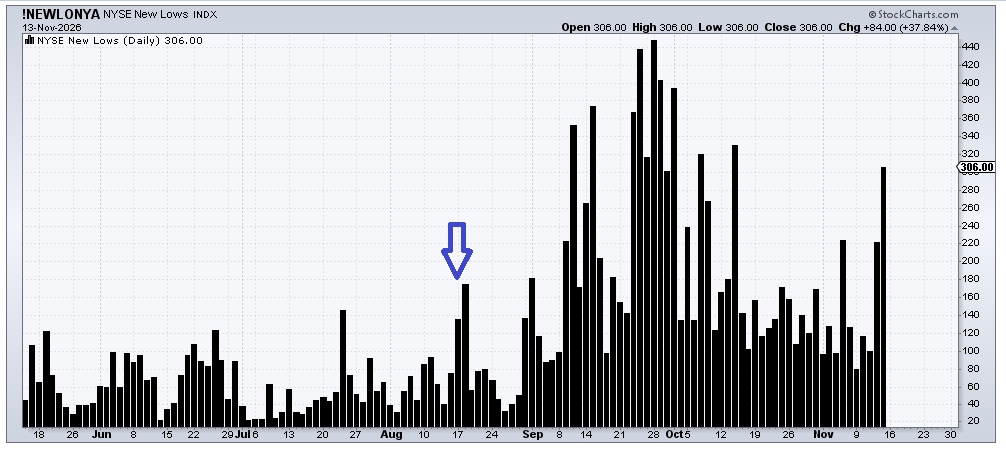
Last week I noted the number of stocks making new lows on the NYSE had started to pick up. That increased again Friday. I recall back in August (blue arrow) when I fussed over the new lows increasing folks argued with me because it was all “interest rate related.”
My argument was that rates matter. So yes, this rise in new lows to levels not seen in a month has my eye.
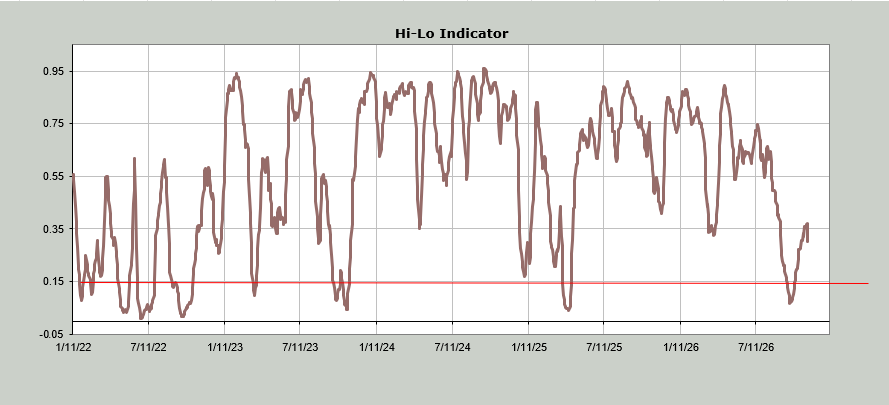
It has also taken its toll on the Hi-Lo Indicator, which has now rolled over again.
The typical pattern should be a pullback and another rally (into Thanksgiving) but the seeds have been planted. I expect the others to start to struggle over the next few weeks.