A Tech Led Rebound to Kick Off the Week
Let’s dig in following an up day on Wall Street to see what’s happened and what to expect.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Quick Summary
- US equity indices rebounded Monday led by Tech as Meta’s announced equity issuance and Anthropic’s S-1 filing supported AI beneficiaries.
- Anthropic’s S-1 showed first-half revenue of about $16.3 billion, up from $1.16 billion a year earlier according to the Wall Street Journal. The company plans to list on the Nasdaq under the ticker ANT as soon as the week of Nov. 16, in a deal that could value it at $1.5 trillion to $2 trillion, per the Journal.
- Meta Platforms (META) meanwhile is seeking to raise as much as $95 billion in common and preferred stock to fund its AI spending (see more here: Meta Wastes No Time), while SpaceX (SPCX) signed a roughly $40 billion equipment-finance lease with Apollo Global Management (APO) for AI chips, per Bloomberg.
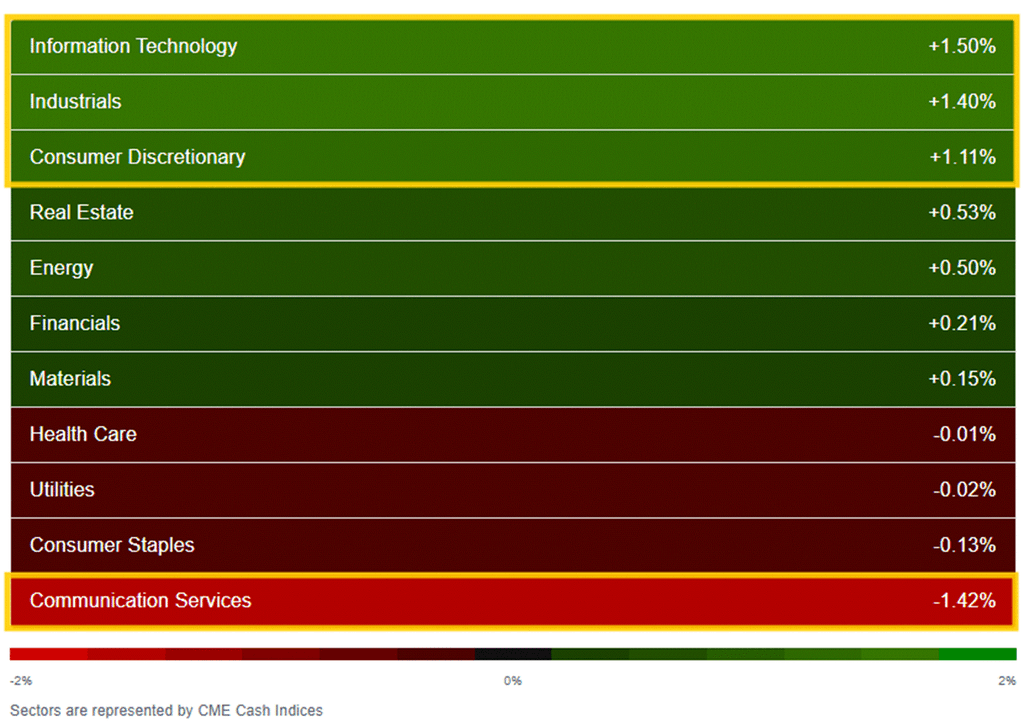
- Still breadth was decent with 7 of 11 sectors higher and none down more than -0.2% other than Communications (-1.4%).
- Treasury yields were mixed. The 2-year yield rose about 3bp after an auction that saw the foreign bid ease but record domestic demand (more here: 2-Year Auction Sees Foreign Bid Ease But Record Domestic Demand), while the 10-year remained under 5%.
- Brent fell 0.8% to $115.81 a barrel, its biggest drop in two weeks, snapping a three-session win streak, and WTI slid 1.7% to $101.57. Natural gas futures at one point hit their lowest level since November 2024. In Brazil, the Bovespa plunged more than 16% after President Luiz Inácio Lula da Silva’s unexpected re-election, on track to surpass its record drop from 1998, and the Real slid against the Dollar.
- Tuesday brings a raft of earnings announcements and economic data, although the most anticipated are not until later in the week.
Schwab
Market Commentary
Equities:
- “There are a lot of balls in the air,” said Nick Giorgi, chief equity strategist at Alpine Macro. “Next week, you have a lot more tech earnings, and right now the market is taking a discerning eye as it relates to all the spending that goes along with artificial intelligence,” Giorgi said. “The market’s just not giving the benefit of the doubt to companies that are spending a ton of money on building this all out, which to us is actually very healthy, but still does augur for some short-term pain.”
- “I think earnings will determine whether this … tech pullback is a buying opportunity, or is there a deeper correction ahead,” said King Lip, chief strategist at BakerAvenue Wealth Management. “What we need is just another round of really strong earnings.”
- “Earnings are critical to the overall confidence level of the AI trade and how much longer the spend will continue,” said Kevin Mahn, president and chief investment officer at Hennion & Walsh Asset Management.
- “The three biggest hyperscalers are reporting this week, and I think what they have to say is absolutely critical to where we go from here,” said Gary Paulin, chief investment strategist at Northern Trust. “We’ve seen quite a severe retracement in some of these names, but that creates a more sustainable outlook. I actually view this period as quite a healthy episode in what I still think is the early stages of an AI boom and we’re still in a bull market.”
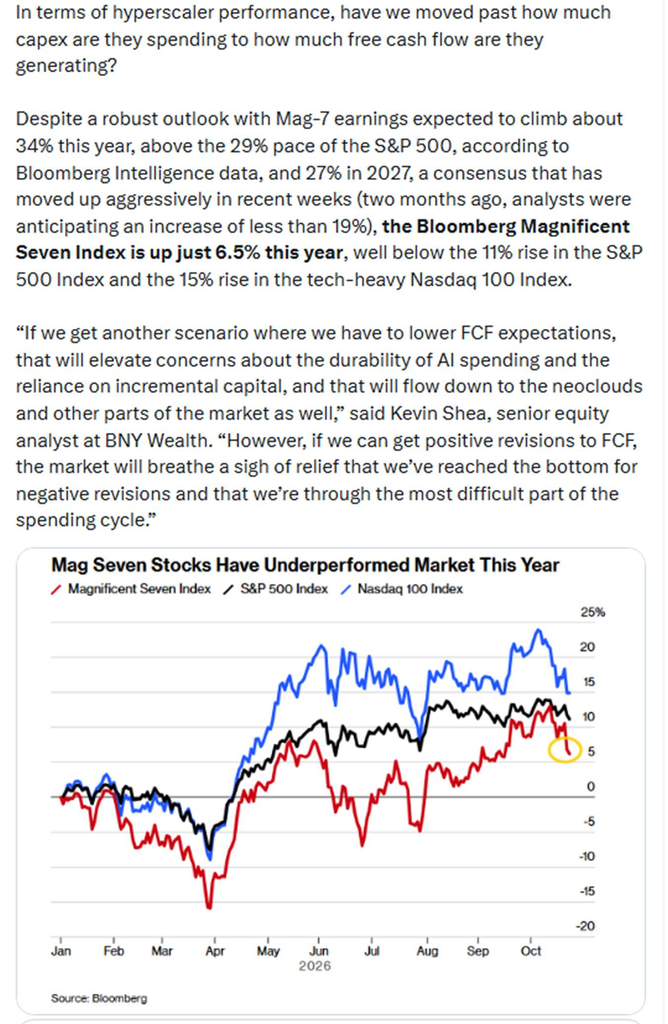
- “The bottom line is that the AI story will be decided in the S&P 493, not the Mag 7, and so far, there is no evidence that revenue growth or margins are improving outside the tech sector,” said Torsten Slok, chief economist at Apollo.
- “The big focus is what these companies expect to spend on AI going forward and whether this spending can continue to be financed by cash flows, or if equity and debt issuance will be necessary,” said Richard Saperstein at Treasury Partners.
- “The market needed this, just like it needed SpaceX,” Jay Woods, chief market strategist at Freedom Capital Markets, said of Anthropic. “This is a big confidence booster, and I anticipate the demand is going to be there because people have been waiting and talking about this one for a long time.”
Bonds/Fed:
- “We still see the Fed on hold through year-end. Higher borrowing costs are working their way through the economy, and there’s a risk that an AI-related market correction around the midterm elections could tighten financial conditions abruptly.” — Bloomberg’s Anna Wong.
- “The communication challenge will be explaining why that does not warrant action this week, with the likely answer that the trend matters more than any single data point,” said UBS.
- “We don’t expect a Fed rate hike on Wednesday, as the bond market has already tightened credit conditions since the Fed’s last meeting,” said Richard Saperstein at Treasury Partners. “We expect to hear tough talk on the inflation front combined with soft action, as uncertainty on the direction of inflation doesn’t warrant more tightening.”
Stock and Sector Breakdown
Schwab
Seven of 11 sectors rose, led by Tech (+1.50%) – the seventh session in the top two or bottom two sectors – Industrials (+1.40%) and Consumer Discretionary (+1.11%). Communication Services (-1.42%) was the clear laggard as Alphabet (GOOGL) (-1.1%) and Meta Platforms (META) (-1.9%) fell along with Netflix (NFLX) (-3.0%), Charter Communications (CHTR) (-5.9%), which hit a new 52-week low, and Verizon (VZ) (-3.5%), whose third-quarter revenue miss overshadowed 406,000 postpaid phone net adds (TipRanks). That’s today’s AI trade in a nutshell: the suppliers rallied while the spenders funding the buildout lagged, with Apple (AAPL) (-1.1%) also lower.
Outside of Communications, though, no sector was down more than -0.2%.
Lumentum (LITE) (+8.2%) was the best performer in the S&P 500 after StoneX initiated coverage with a Buy and a $1,200 target, noting management says its AI-related optoelectronic capacity is effectively committed into early 2029 (TheFly). Fair Isaac (FICO) (-13.2%) was the worst after it kept its wholesale mortgage score price flat at $10 for lenders in its Preferred Program (Seeking Alpha), and JPMorgan cut its price target to $900 from $1,530.
Optical and analog chip names dominated the leaders, including Lumentum, Coherent (COHR) (+5.8%), Texas Instruments (TXN) (+4.7%), NXP Semiconductors (NXPI) (+4.6%), Analog Devices (ADI) (+4.3%) and Intel (INTC) (+4.1%). Tesla (TSLA) gained 5.2% to a three-month high (TipRanks) as analysts turned more bullish with a long-awaited combination with SpaceX edging closer; the share of bearish calls on the stock is at its lowest in more than 11 years, per Bloomberg.
On the downside, DoorDash (DASH) fell 6.1% after The Wall Street Journal reported it’s in advanced talks to buy Instacart, also known as Maplebear (CART), which jumped as much as 8% (TipRanks). Dollar General (DG) lost 3.2% after the Federal Trade Commission, joined by 20 states, sued the discount retailer over deceptive pricing (TheFly). That came the same morning JPMorgan added it to its Analyst Focus List. Rival Dollar Tree (DLTR) also slid.
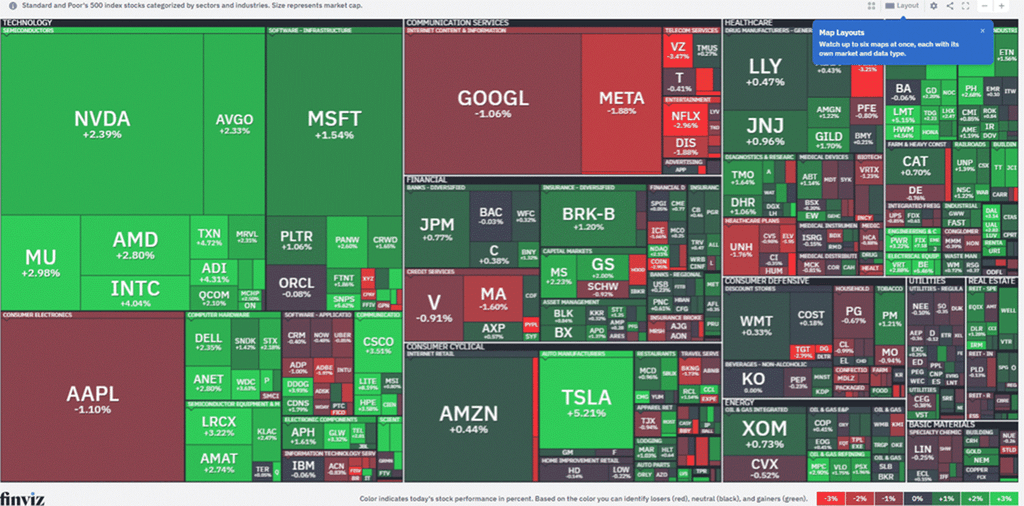
The number of large SPX winners (up over 3%) doubled to about 40 from about 20 Friday, while large losers (down over 3%) fell to 13 from about 50.
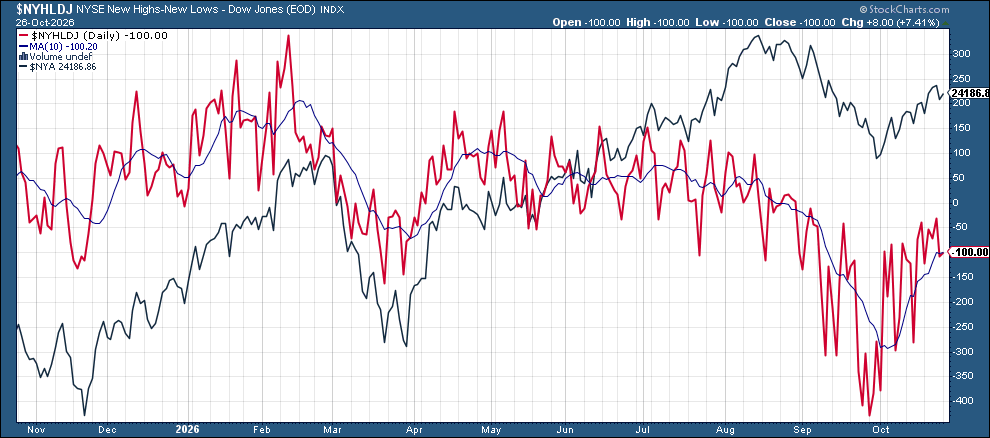
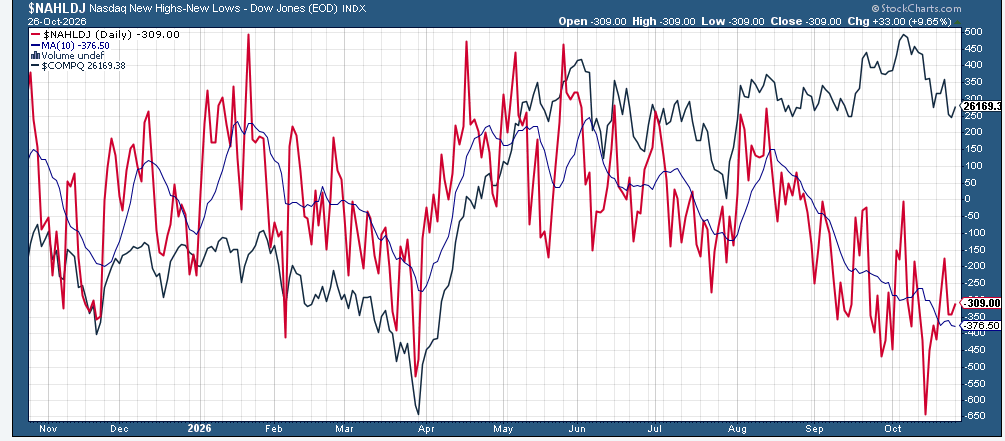
New 52-week highs minus lows improved on the NYSE to -100 (from -108) and on the Nasdaq to -309 (from -351). The Nasdaq reading has now been negative though for 41 straight sessions, two shy of the 43-day stretch that ended April 22, 2025.
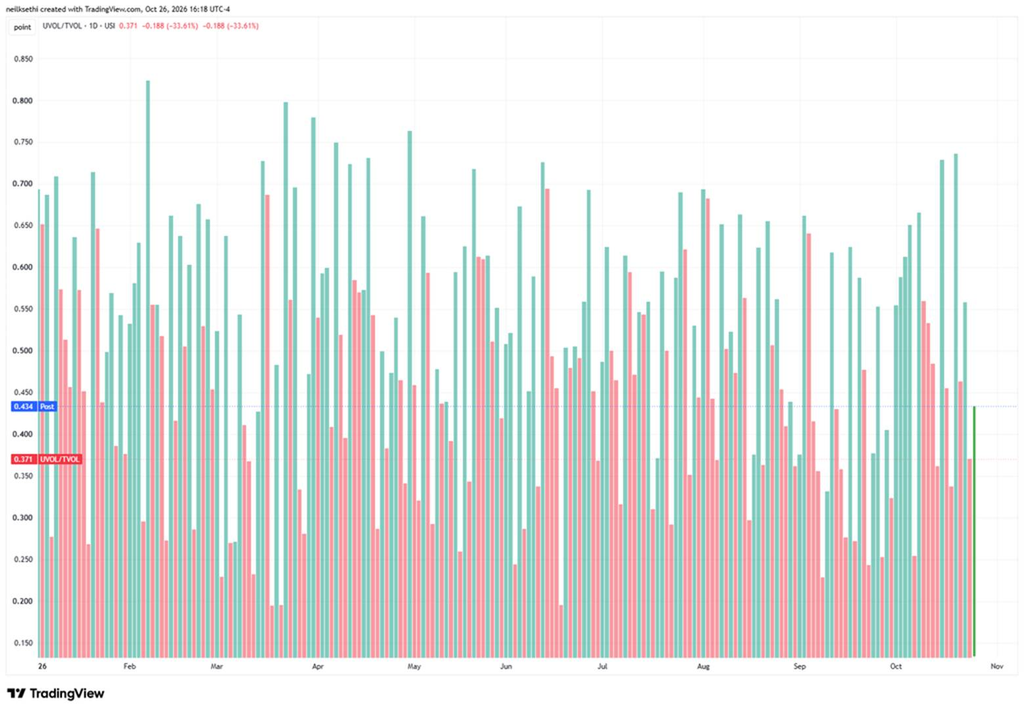
Positive volume was weak at 43.4% on the NYSE despite a 0.29% gain. At least the Nasdaq was positive, but just 51.8% despite a 0.82% index gain.
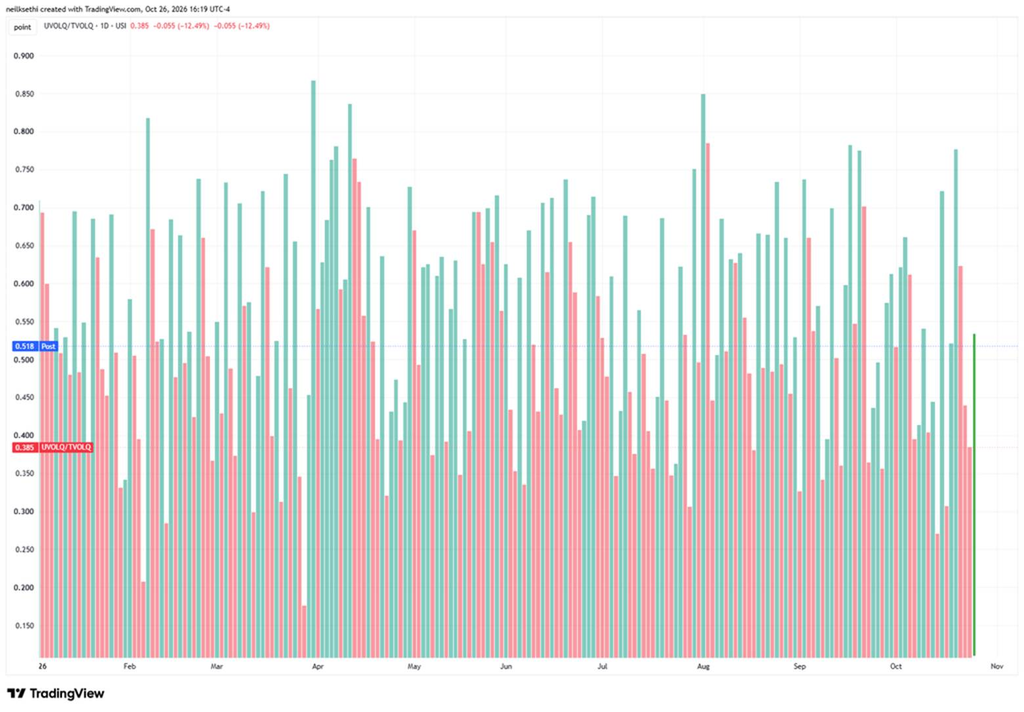
Some other stock-specific commentary from TheStreet Pro:
- Doug Kass flagged the amount of insider selling the Anthropic IPO allows, including right at the time of the offering, as among his biggest concerns (More on the Anthropic IPO).
- Chris Versace — Microsoft Announces Massive Employee Buyout Program: Microsoft (MSFT), which rose 1.5% after opening lower, will offer buyouts to about 60,000 workers.
- Chris Versace — Locking in Gains and Making a Sale With Volatility Ahead: The Portfolio is adding to Morgan Stanley (MS) on an improving investment banking outlook and trimming Waste Management (WM) ahead of its report Tuesday.
- Bob Lang — Chart of the Day: Can Microsoft Save the Magnificent Seven?
- Bob Lang — Options Trading: DataDog Is Ready for a Move Up: Datadog (DDOG) rose 3.9% today.
- Bob Byrne — Elon Musk Just Predicted a Neocloud Bloodbath. CoreWeave Investors Should Listen.: Byrne says it’s too soon to write CoreWeave‘s (CRWV) obituary but argues SpaceX has an edge in renting out compute that CoreWeave can’t easily match.
- James “Rev Shark” DePorre — Love Musk or Hate Him, Here’s How I’m Building My SpaceX Position
- Doug Kass — Added to Apple Short and Netflix Is Still Too Low to Short and Too High to Buy
A Look At The Charts
Note on all charts the colored lines are moving averages (the average price over the lookback period — days on the daily charts, weeks on the weekly charts):
20 = green
50 = purple
100 = blue
200 = brown
Exception is monthly charts where blue is 10-month moving average and brown is 20-month moving average.
MACD = Moving average convergence/divergence line, a measure of momentum that compares longer term and shorter term momentum to gauge if a move is strengthening or weakening. This is probably my favorite individual indicator.
RSI = Relative Strength Index (basically what it sounds like) = measures the strength of the move comparing gains to losses over the given lookback window (I use the standard 14 periods).
SPX
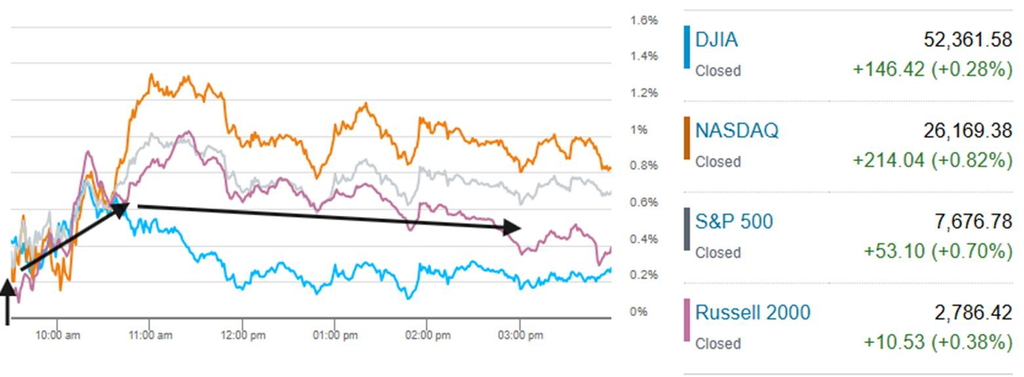
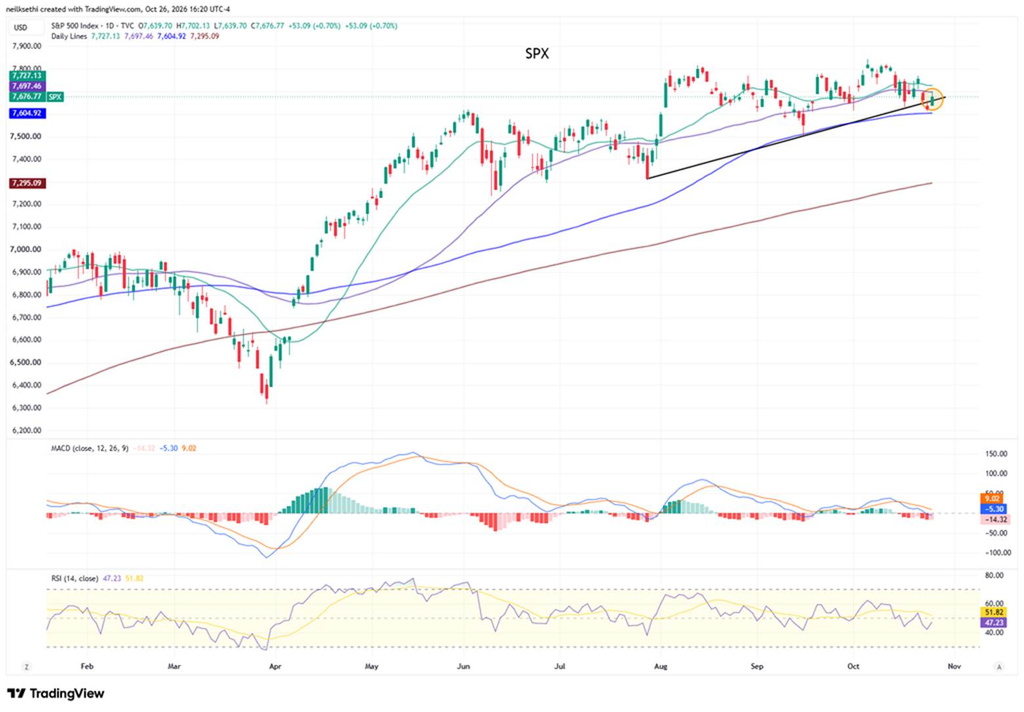
The SPX rose 0.70% to 7,676.77, climbing back over the trendline from the July low after closing just under it Friday. It tagged its 50-DMA (7,697) intraday but closed below it and its 20-DMA (7,727), while the 100-DMA (7,605) continues to hold as it did in September. As I noted, a break of that trendline was my trigger to sell SPY, but with the 100-DMA holding, I’m continuing to hold off. The daily MACD remains in “sell longs” positioning, and the RSI is at 47.
Nasdaq Composite
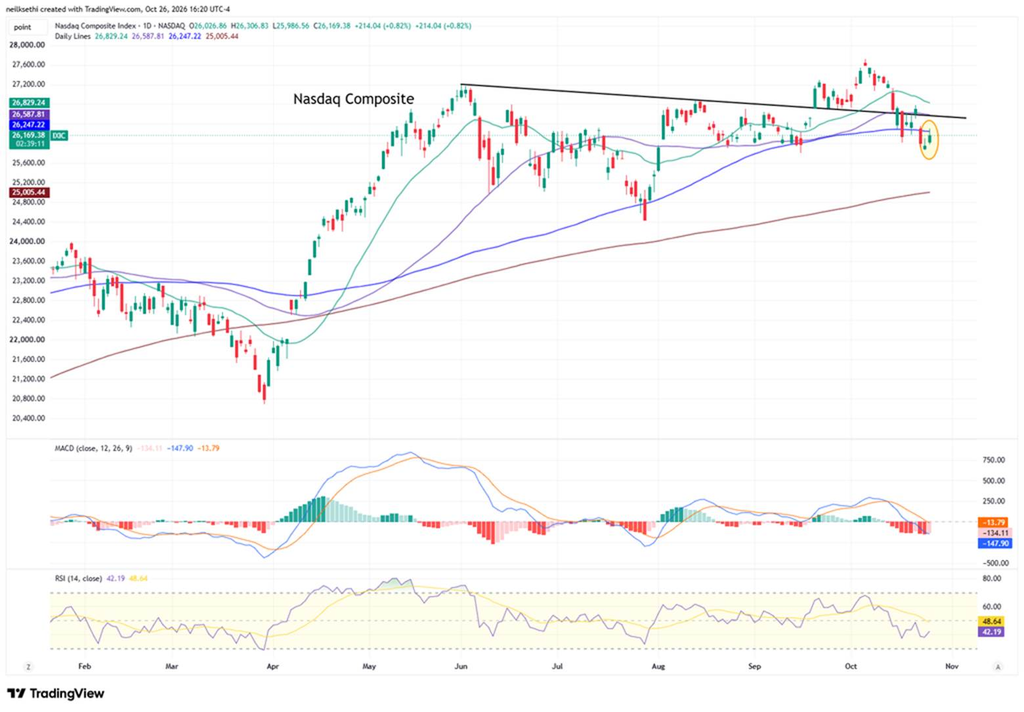
The Nasdaq Composite gained 0.82% to 26,169.38. It got back above its 100-DMA (26,247) intraday but couldn’t hold it, closing between its 100- and 200-DMA (25,005) and still below the downtrend line from the June high. The MACD remains in “sell longs” positioning, and the RSI is at 42. Helene Meisler says she’s seen this Nasdaq chart before, “and that’s not necessarily a good thing” (I’ve Seen This Nasdaq Chart Before). It’s worth a read.
The Nasdaq-100 (QQQ)
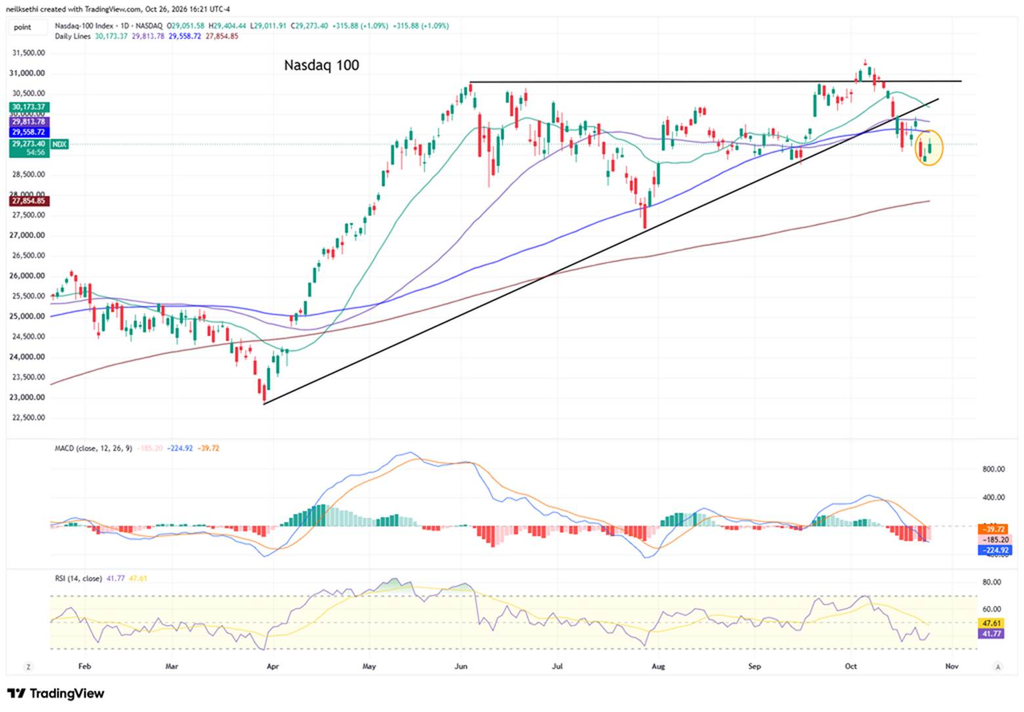
The Nasdaq-100 outperformed, up 1.09% to 29,273.40. With the bounce, the short I said I’d consider on a break of the September lows isn’t in play, but the index remains below its 50-DMA (29,814) and 100-DMA (29,559), and I’d still sell bounces until it reclaims the 50-DMA. The MACD remains in “sell longs” positioning, and the RSI is at 42.
The Russell 2000 (IWM)
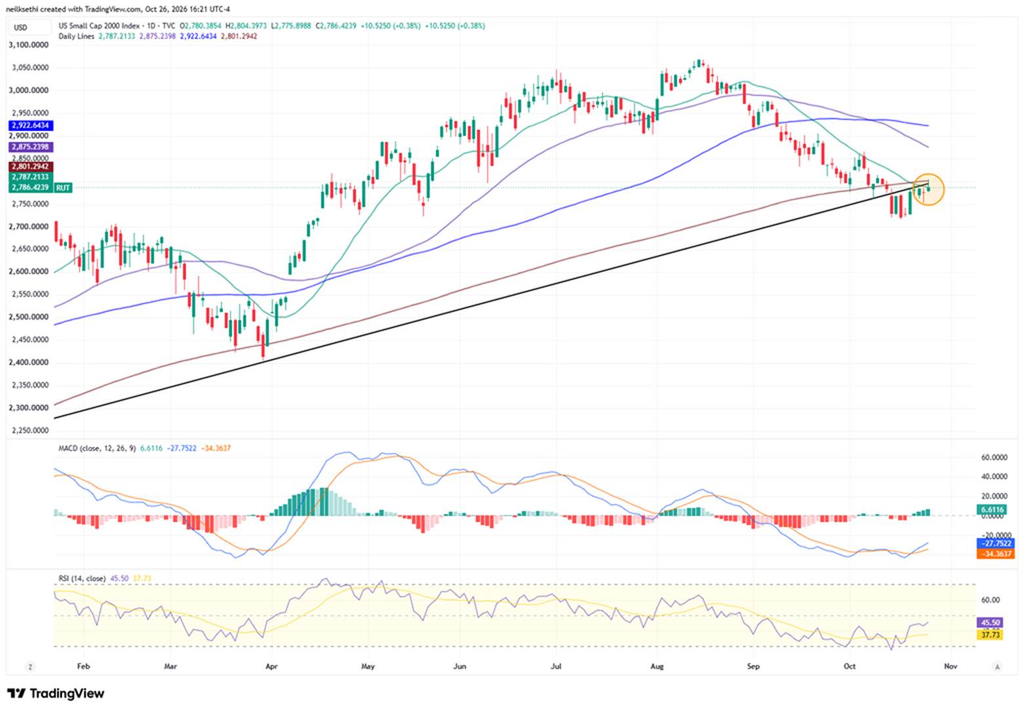
The Russell 2000 added 0.38% to 2,786.42. It got above its 200-DMA (2,801) intraday but was turned back, closing just under both its 200- and 20-DMA (2,787) while sitting on the uptrend line from last year’s low. The MACD has been in “cover shorts” positioning since 10/21, and the RSI is at 46. As I said, I’ll get back in on a move over the 200-DMA.
The equal-weighted SPX (RSP)
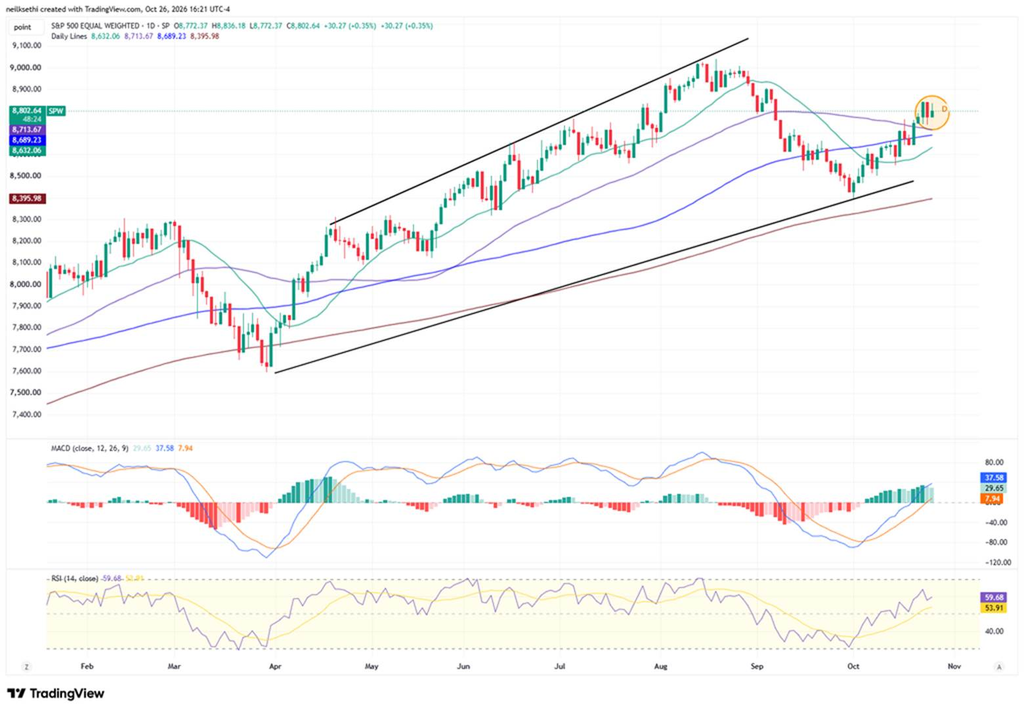
The equal-weighted SPX rose 0.35% to 8,802.64, lagging the cap-weighted index but holding above all its moving averages, with the MACD in “buy longs” positioning and the RSI at 60. It remains the best technical setup of the major indices (I added on 10/21), and as Bloomberg notes, it’s on track for its largest monthly outperformance versus the S&P 500 since April 2009.
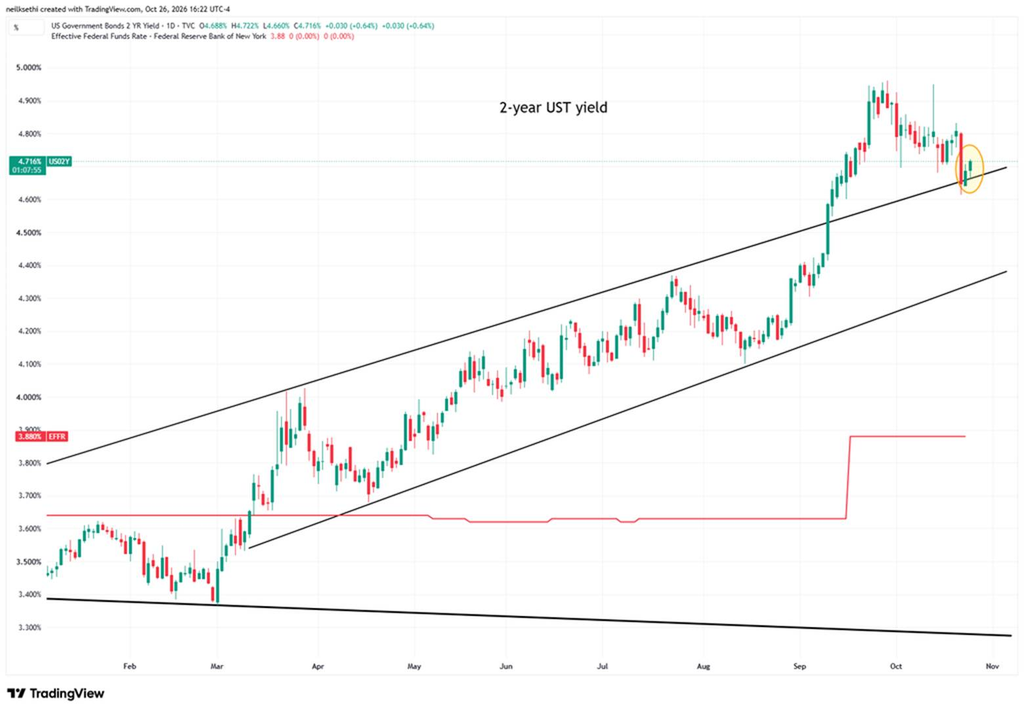
The 2-year yield rose 3bp to 4.716%, bouncing off the top of its old channel (circled), which is now acting as support. That leaves it about 84bp above the EFFR (3.88%). Today’s $69 billion 2-year auction saw the foreign bid ease but record domestic demand (2-Year Auction Sees Foreign Bid Ease But Record Domestic Demand).
Fed rate hike expectations also firmed slightly. October is now a 90.5% chance of a hold, and December is an 81% chance of a hike (from 78% Friday), per CME FedWatch. 2027 expectations see 69 basis points of total hikes priced through December next year (from 68bp).
10-year yields
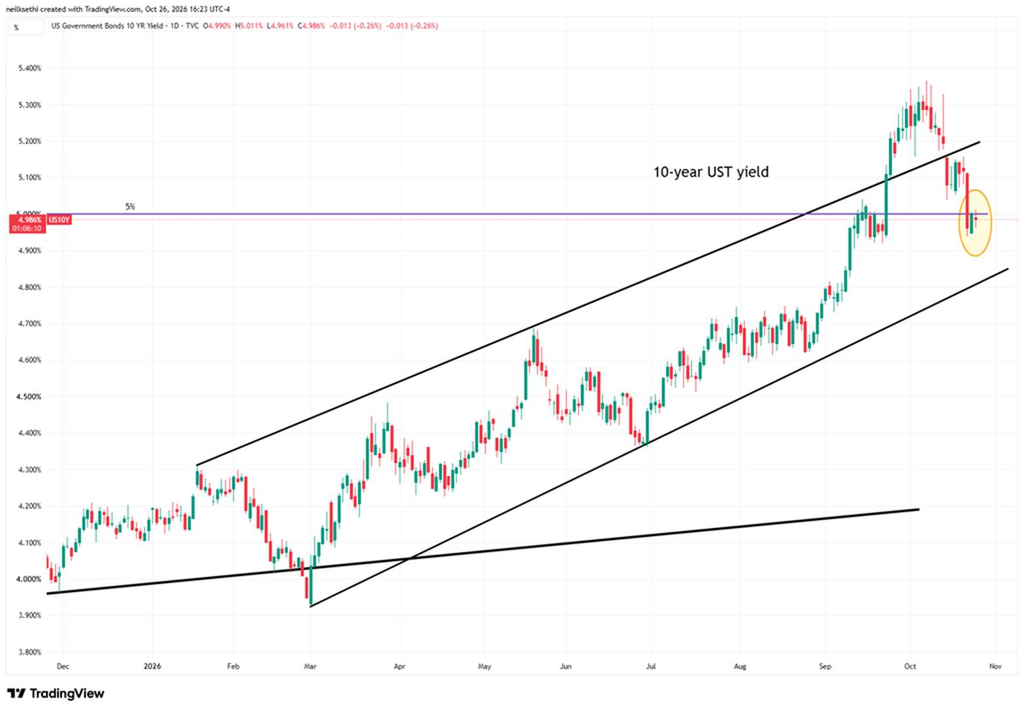
The 10-year yield slipped 1.3bp to 4.986%. It poked above 5% intraday (5.011%) but closed just under it for a second straight session, back inside its rising channel after the early-October breakout failed.
30-year yields
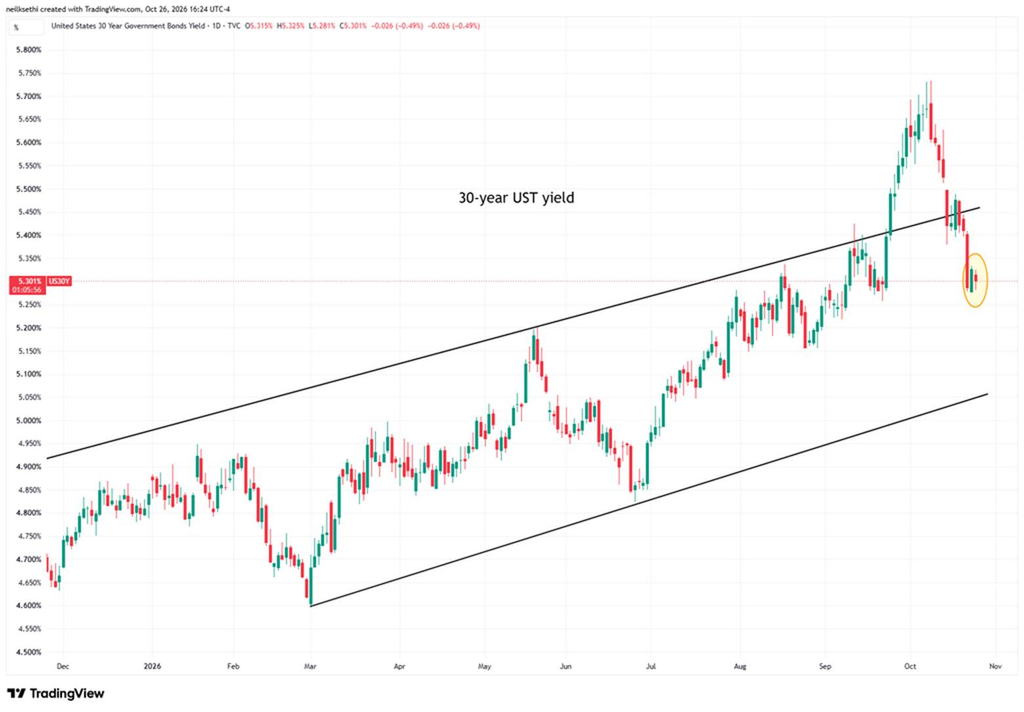
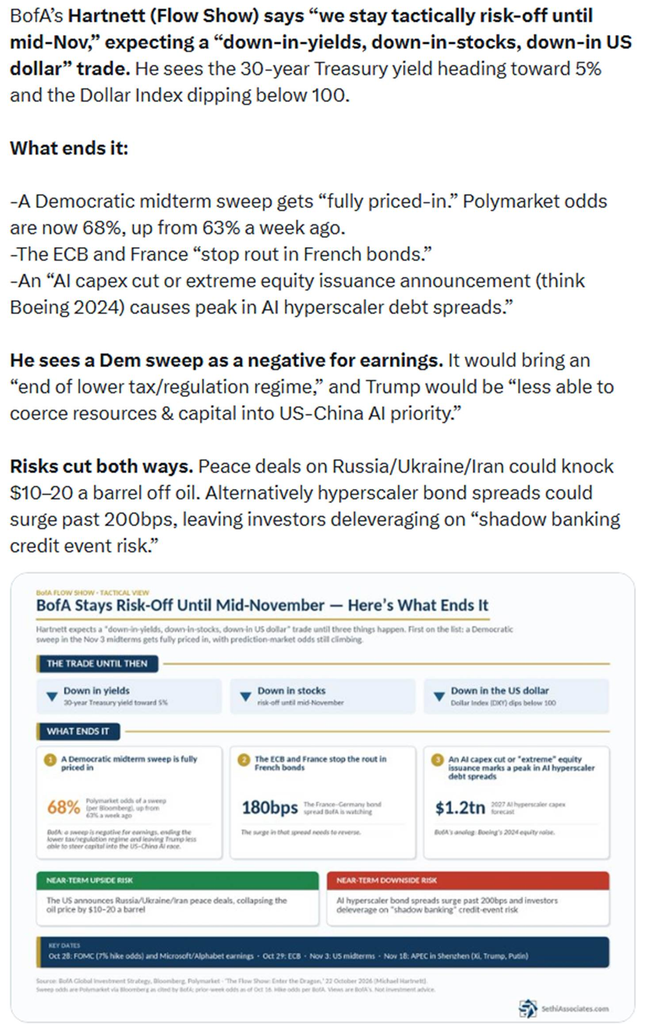
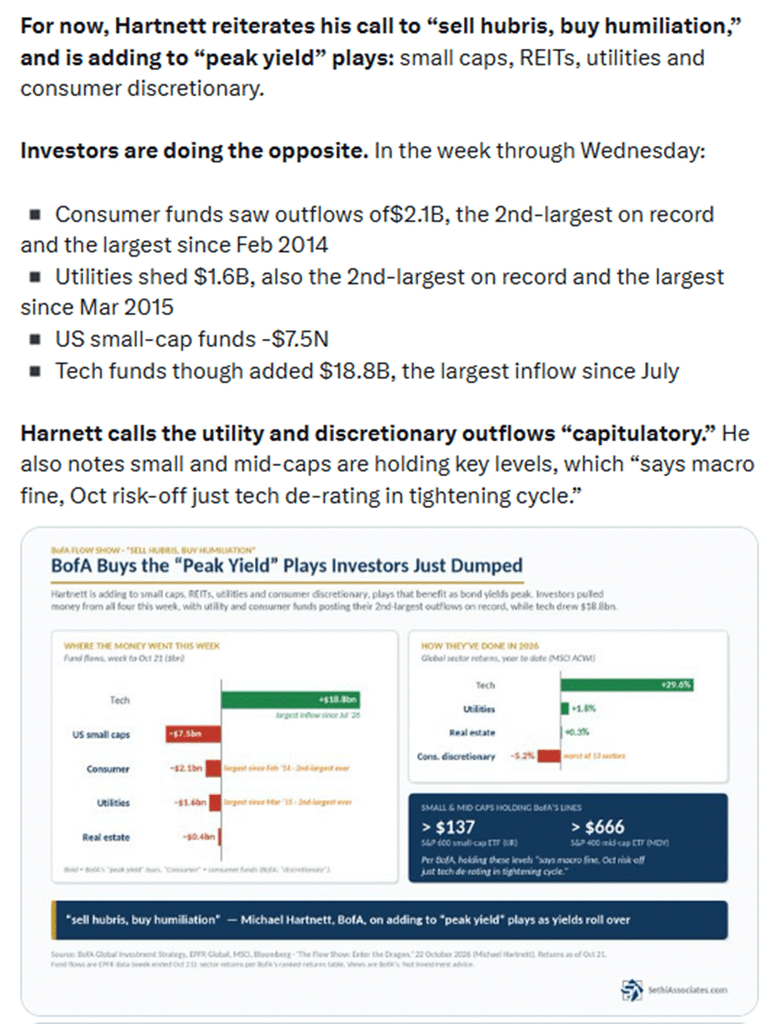
The 30-year yield fell 2.6bp to 5.301%, its lowest close since September 22nd, after slipping back below the top of its channel in mid-October. BofA’s Michael Hartnett sees it heading toward 5% (see Miscellaneous).
VIX
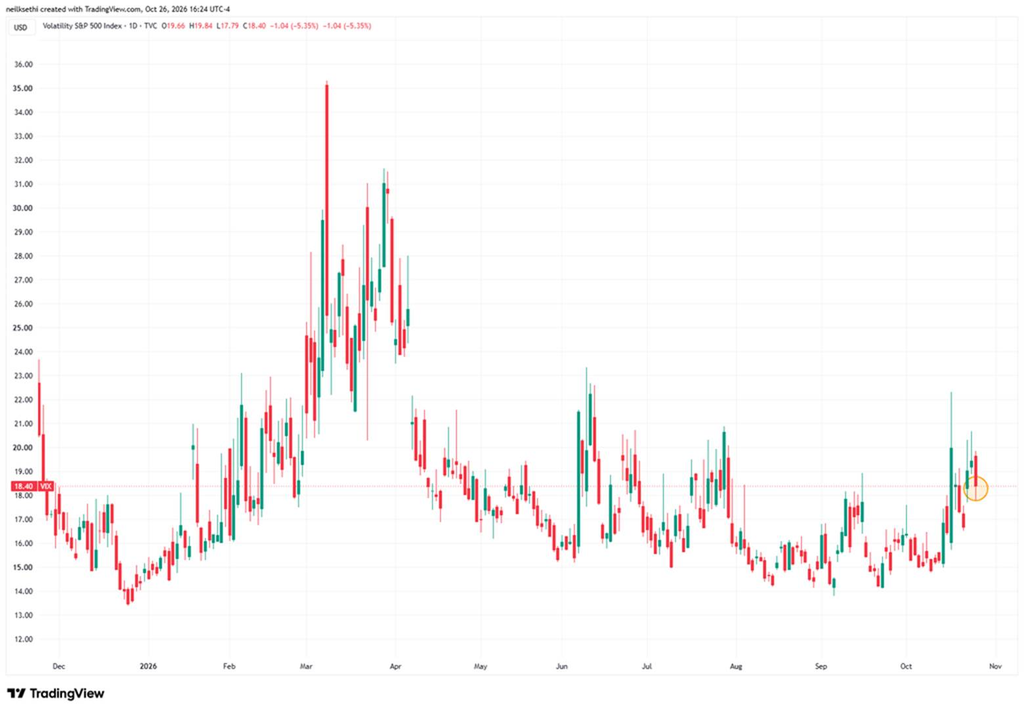
The VIX fell 5.35% to 18.40, implying a daily move of about 1.16% over the next 30 days.
VVIX
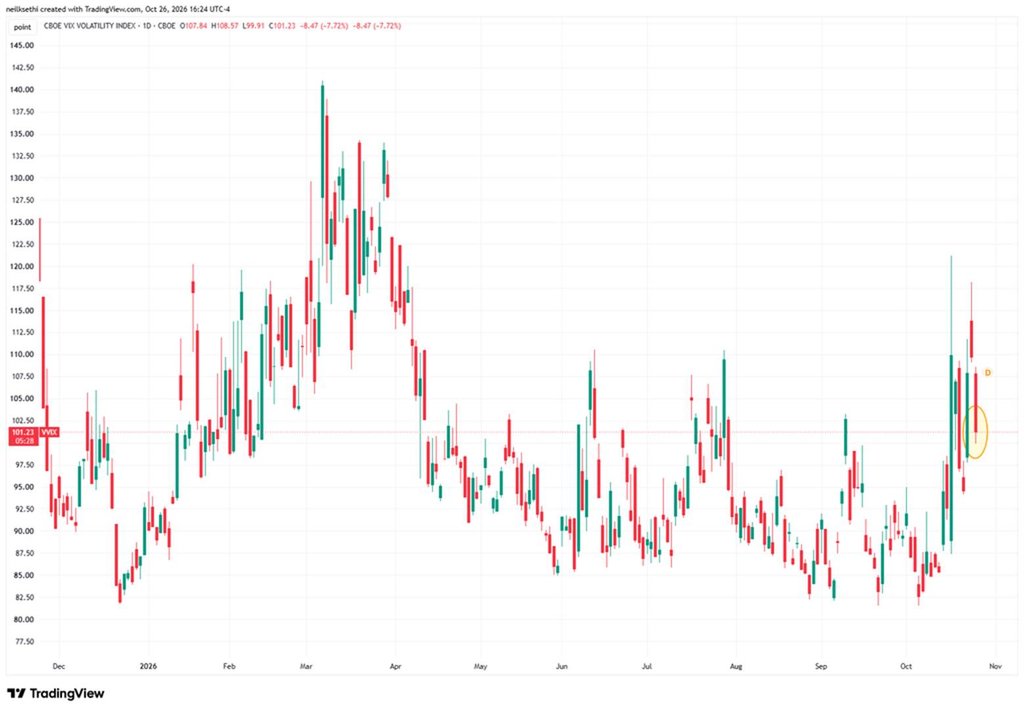
The VVIX (the VIX of the VIX) fell 7.72% to 101.23 from 109.70 Friday. The current level is consistent with “moderately elevated” daily moves in the VIX over the next 30 days (historically, normal is 80-100, although we haven’t been below 80 since July 2024). Above 100 is the level flagged by Charlie McElligott as indicating higher stress.
1-Day VIX
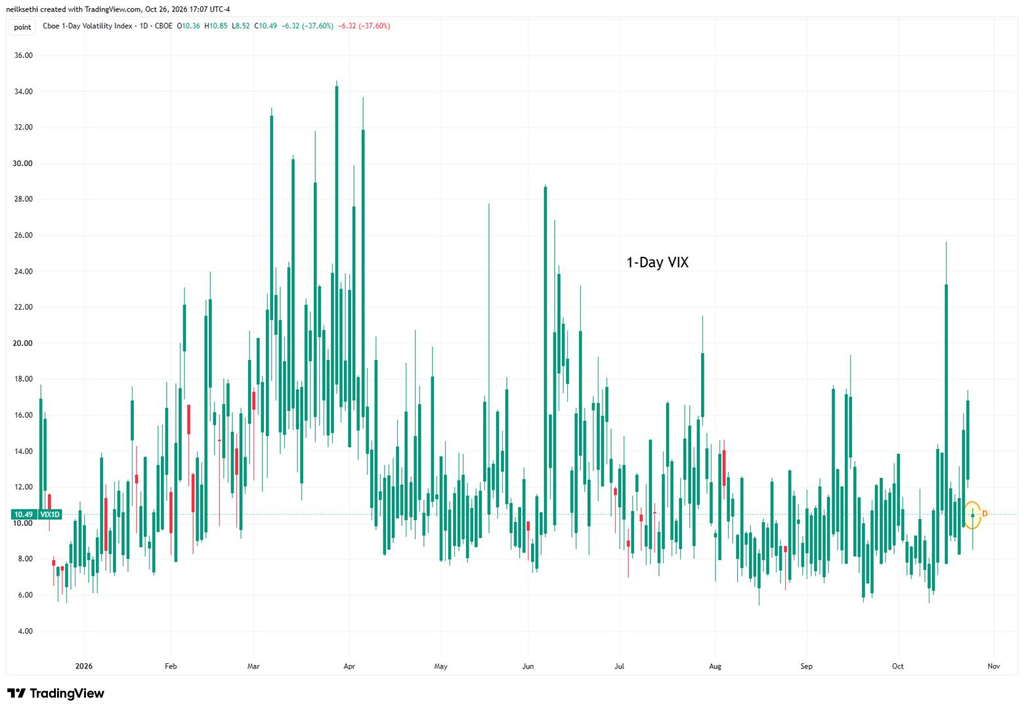
The 1-day VIX fell 37.6% to 10.49 from 16.81 Friday. Friday’s level implied a move of about 1.06% for Monday, and the SPX came in well under that at 0.70%. Tonight’s reading implies a move of about 0.66% for Tuesday.
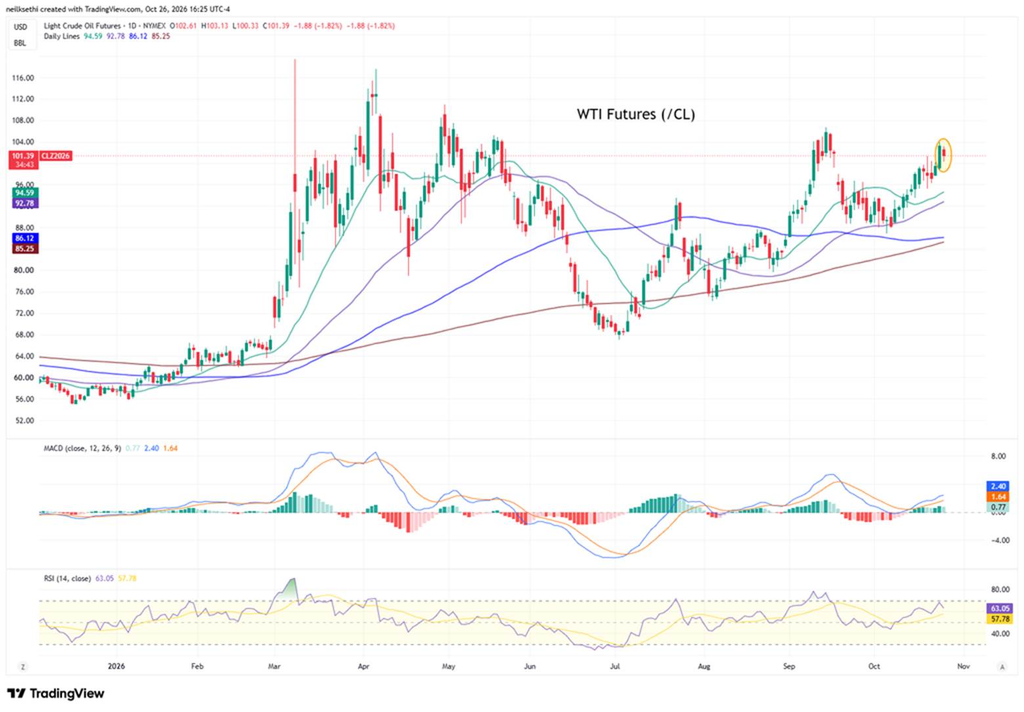
WTI futures (/CL), which TradingView has at December currently,
fell 1.82% to $101.39 after Friday’s 3.8% jump. It remains above all its moving averages, with the MACD in “buy longs” positioning and the RSI at 63. Peter Tchir says diesel, credit and semiconductors will determine the next few weeks of market moves (Three Key Industries to Watch This Week).
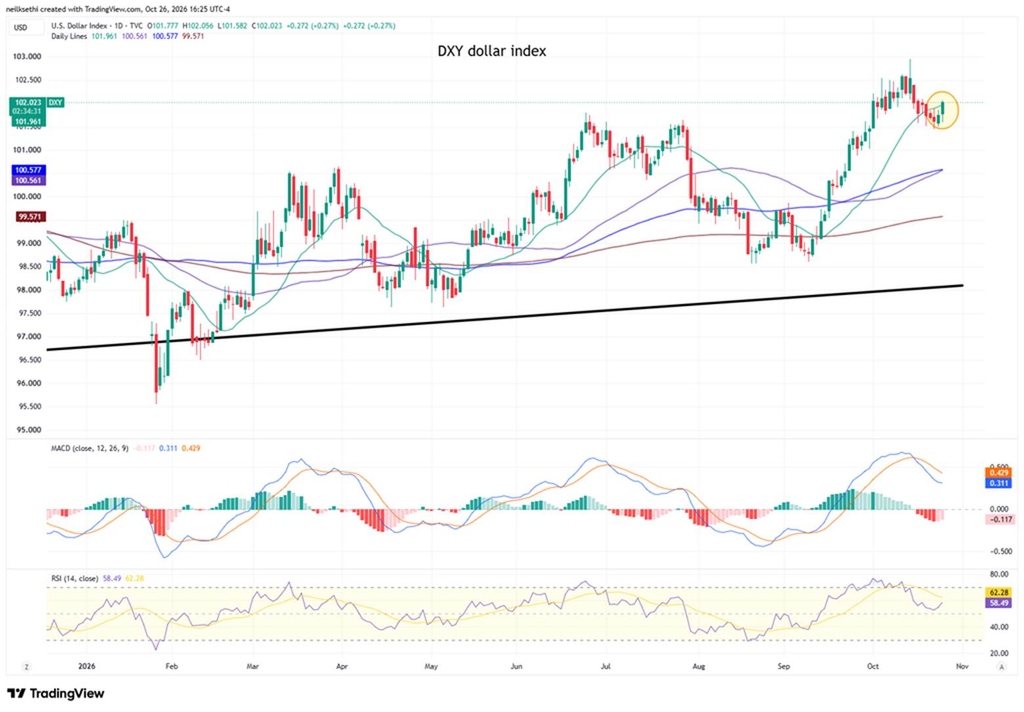
The DXY
The DXY rose 0.27% to 102.023, a second straight gain, and closed back above its 20-DMA (101.961). The daily MACD remains in the “sell longs” positioning it flipped to on 10/16, though, but the RSI is at 58.
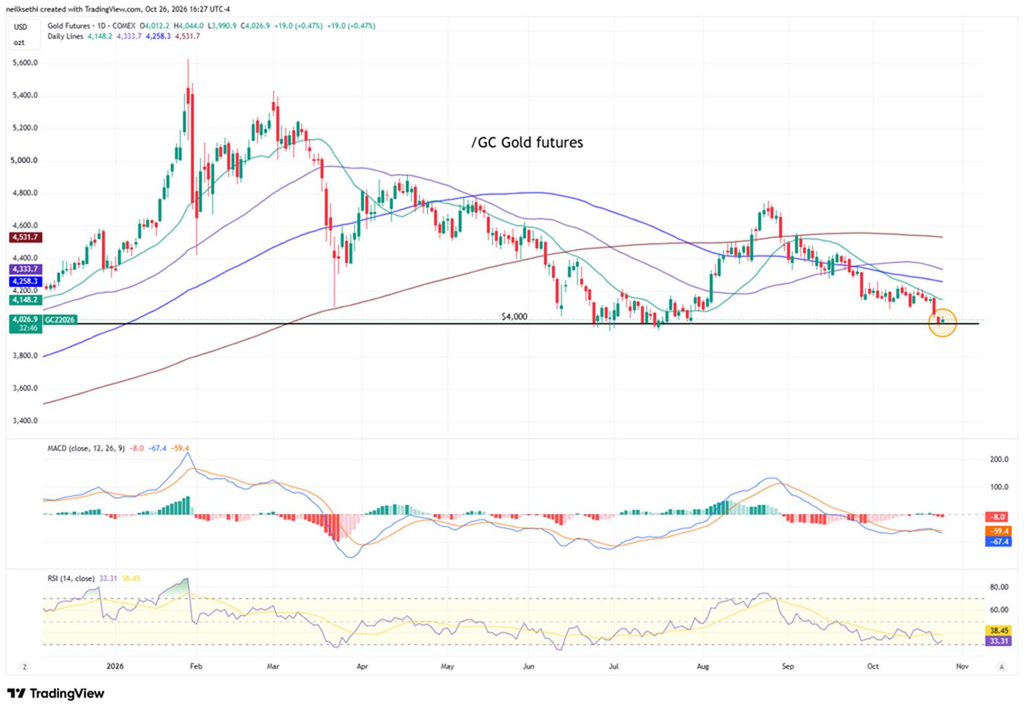
Gold futures (/GC)
Gold futures rose 0.47% to $4,026.90, but only after dipping below $4,000 intraday ($3,990.90). So it held for now. The RSI at 33 is near oversold, while the MACD remains in “sell longs” positioning.
US copper futures (/HG)
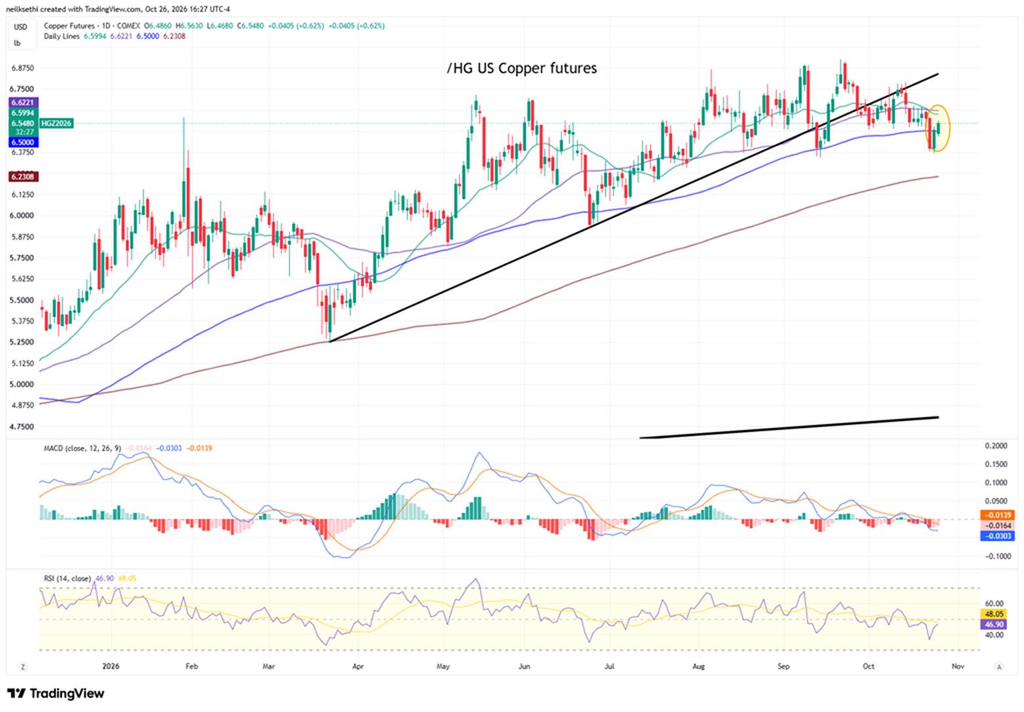
Copper rose 0.62% to $6.548, recovering above its 100-DMA ($6.50) after dipping under it intraday, though it remains below its 20- and 50-DMAs. With the bottom of the range holding, I remain long. The MACD is in “sell longs” positioning though, and the RSI is at 47.
US natural gas futures (/NG)
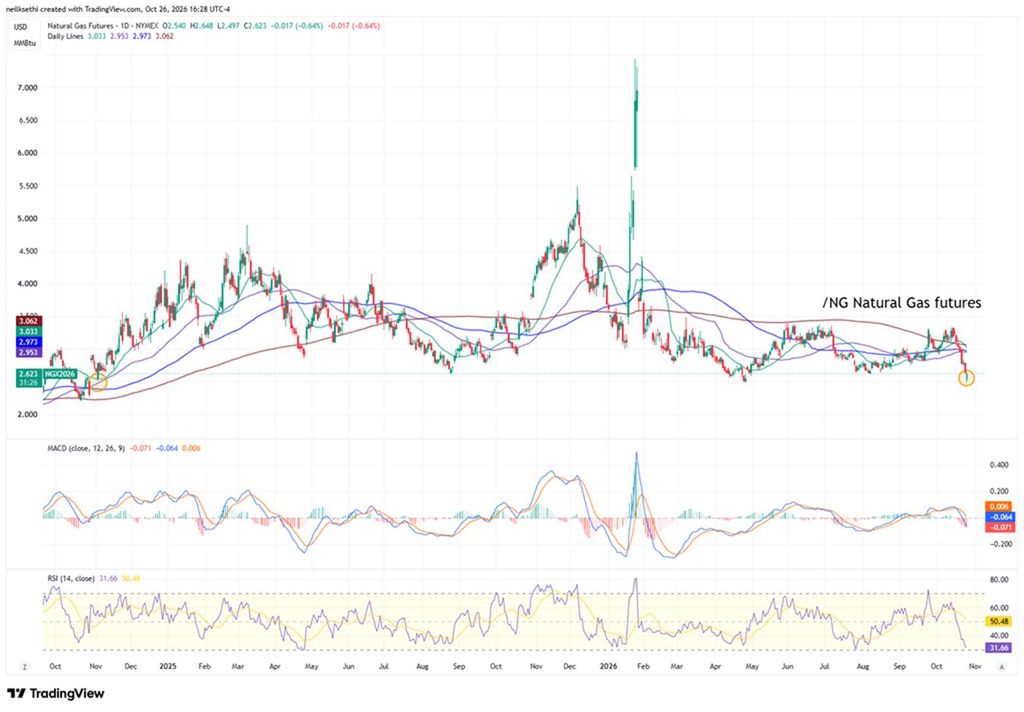
at one point fell to the lowest levels since November 2024 ($2.497) before recovering to close down 0.64% at $2.623. It’s below all its moving averages, and the RSI at 32 is approaching oversold.
Bitcoin futures
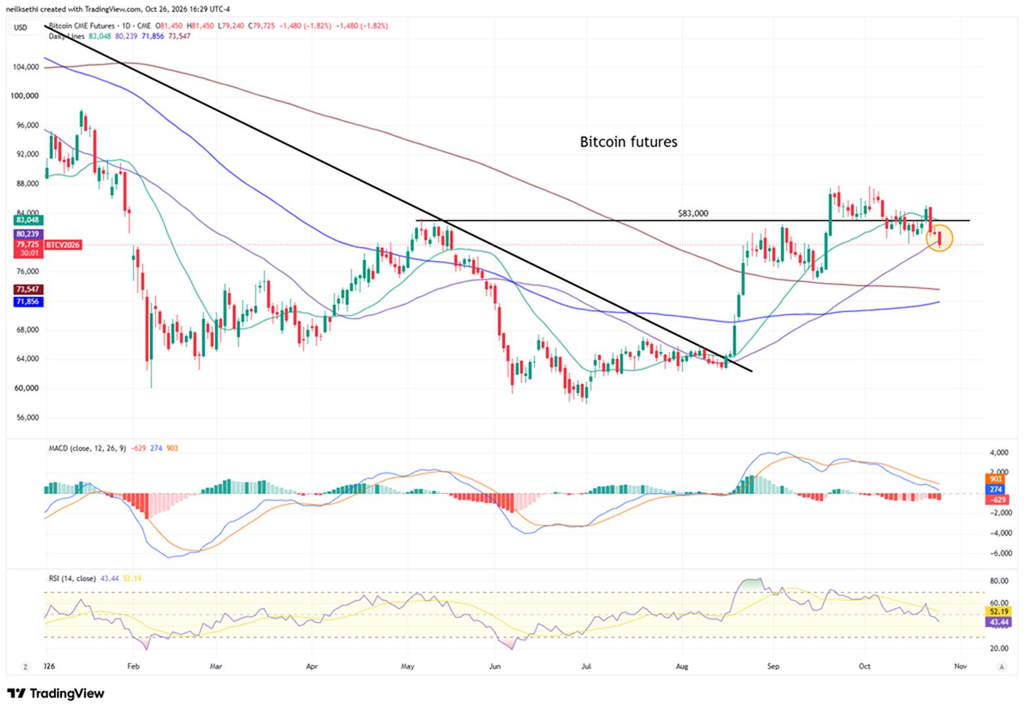
fell 1.82% to $79,725 — I knew I shouldn’t have bought. It broke below last week’s low, the trigger I set to exit the small IBIT position I took on 10/21, so I sold out. It closed below its 50-DMA ($80,239) and back under the $83,000 level that had been support.
More From TheStreet Pro
- Doug Kass — Boockvar on Brazil, Fed, Gold and Earnings and Howling About the U.S. Housing Market
- James “Rev Shark” DePorre — AI Sees Weak Bounce While Anthropic Filing Fails to Resolve Concerns and Neocloud Shakeout Sets Tone for Pivotal Week
- Bret Jensen — Neocloud Providers Become the Canaries in the AI Coal Mine
- Helene Meisler — I’ve Seen This Nasdaq Chart Before and, from Sunday, Are You Paying Attention to the Market’s Subtle Warnings?
- Chris Versace — AWS Sells Out of Capacity Into 2028: 8 Key Items Shaping the Stock Market Monday and VIDEO: Answering Your Questions as We Navigate a Frenetic Week
- Bob Lang — Charting the Markets: Poor Weekly Closes Become a Pattern
- Peter Tchir — Three Key Industries to Watch This Week
And From Me If You Missed It
- The Week Ahead: Can Big Tech Earnings Save the Day? (Sunday)
- A Quiet Start to the Week
- Is Japan Selling of Treasuries a Risk?
- Meta Wastes No Time
- Expect Small Earnings From the Market’s Biggest Movers
- AI’s Math Problem: $8.5 Trillion Needed, $3.6 Trillion Expected
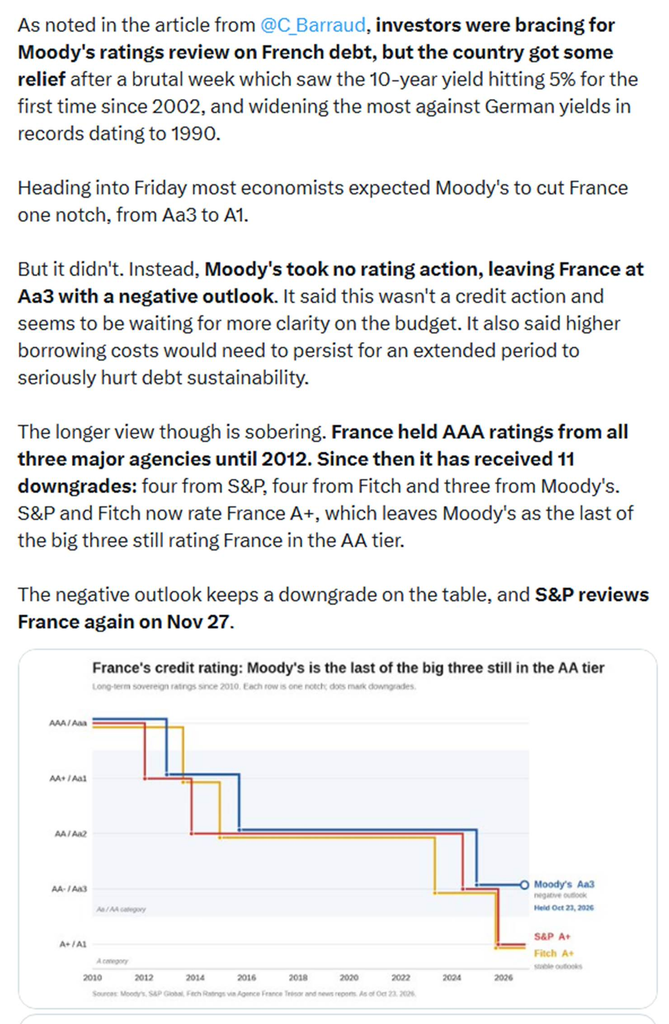
- France Gets a Reprieve
- 2-Year Auction Sees Foreign Bid Ease But Record Domestic Demand
Miscellaneous
Wrap-Up — The Rotation Continues
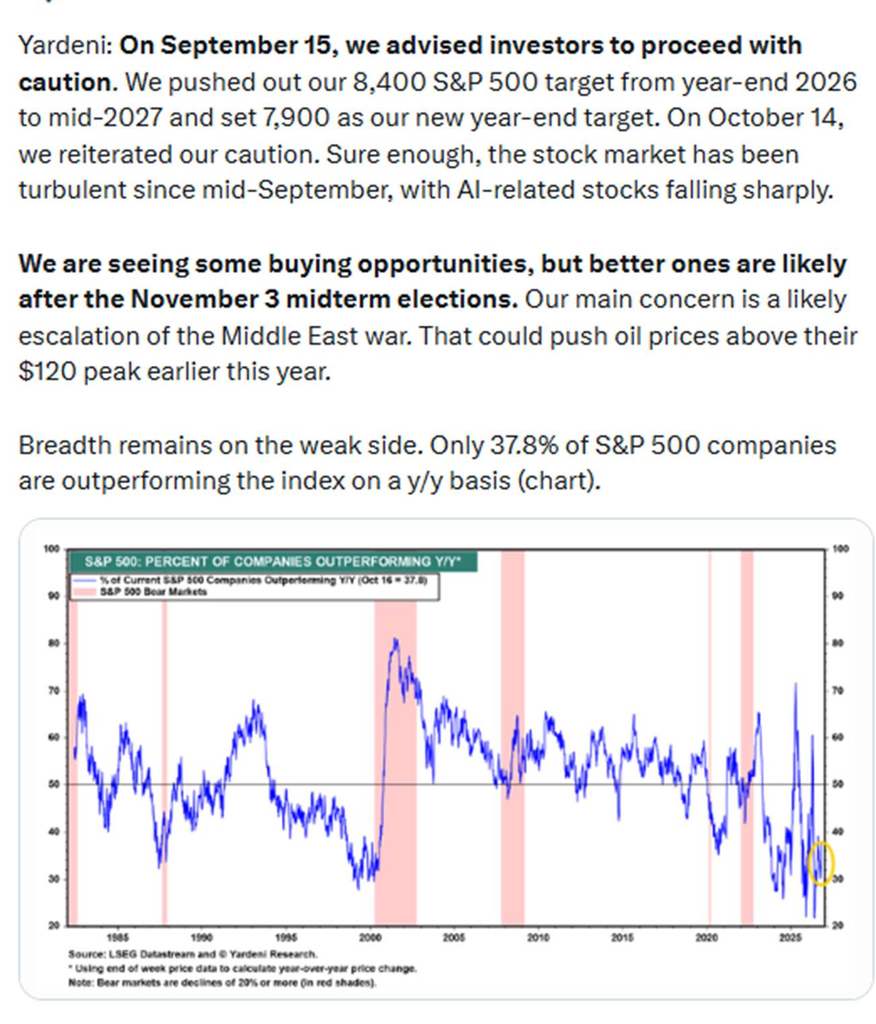
As I said Sunday, I think a year-end rally, once whatever is going to happen post-midterms with Iran is completed, is quite likely. But:
Between now and then, though, we have some treacherous waters to navigate, particularly with thin (or negative depending on who you ask) gamma support. CTAs are within 0.5% of sell triggers on the S&P 500, and this week brings the Fed, GDP and PCE, plus earnings from Alphabet, Microsoft and Amazon.
Today was a nice bounce in some beaten down names on the back of what is apparently going to be another huge round of AI spending but for now it’s just that. As I mentioned several times last week, it takes more than a day or two to establish a trend. Or as Rev Shark put it, today looked more like short covering in the most beaten-down AI names ahead of the big reports than investors deciding it’s time to own them again.
But otherwise we continue to see relative strength in many sectors, even if they trailed the AI beneficiaries today. Tomorrow brings a lot of data, but none likely to move any needles. The broad swath of earnings though will see those stocks move.
As always, let’s see what we get and go from there.
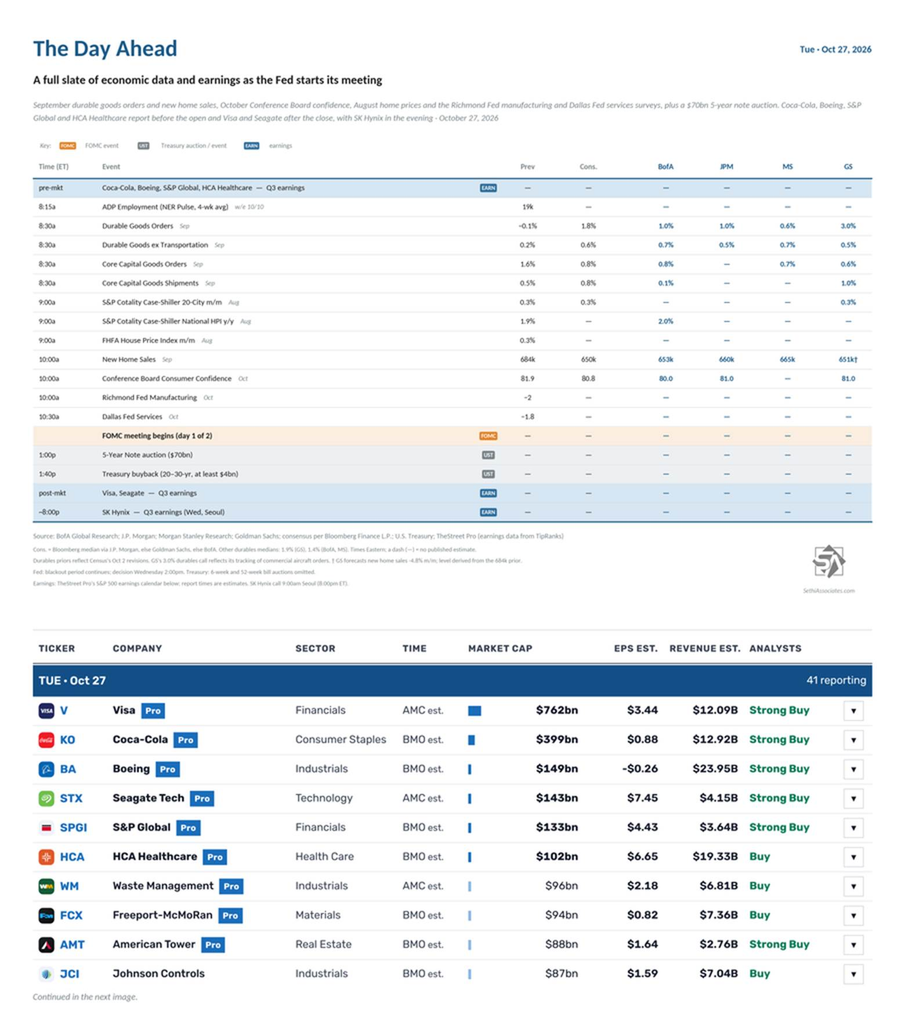
The Day Ahead — Things Pick Up
It’s a full slate of economic data and earnings as the Fed starts its meeting. September reports include durable goods orders and new home sales. October reports include Conference Board consumer confidence and the Richmond Fed manufacturing and Dallas Fed services surveys. For August, we get the S&P Cotality Case-Shiller and FHFA home price indexes. We’ll also get the weekly ADP NER Pulse.
The FOMC begins its two-day meeting, with the decision Wednesday at 2pm ET.
Non-Bill (>1yr in maturity) US Treasury auctions include $70bn of 5-year notes. Treasury will also conduct a buyback of 20- to 30-year securities.
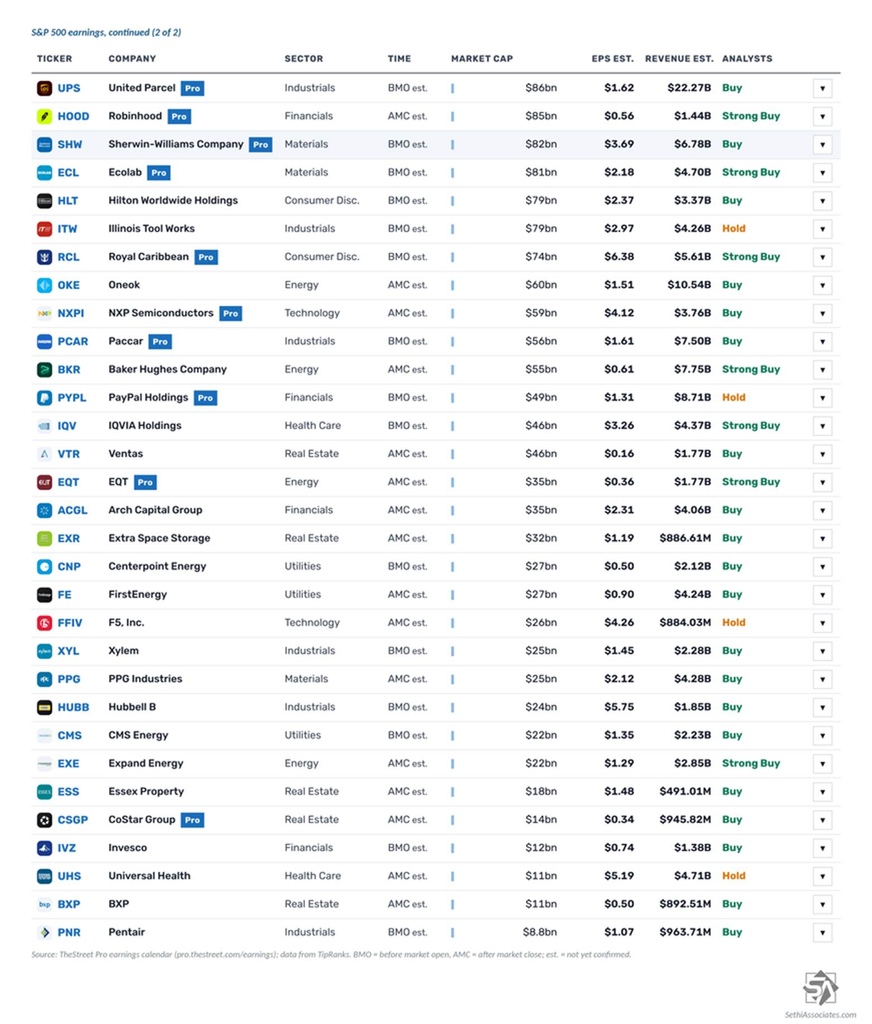
41 S&P 500 components report, six of them with market caps over $100bn:
Before the open: Coca-Cola (KO), Boeing (BA), S&P Global (SPGI), HCA Healthcare (HCA), Freeport-McMoRan (FCX), American Tower (AMT), Johnson Controls (JCI), UPS (UPS), Sherwin-Williams (SHW), Ecolab (ECL), Hilton (HLT), Illinois Tool Works (ITW), Royal Caribbean (RCL), Paccar (PCAR), PayPal (PYPL), IQVIA (IQV), CenterPoint Energy (CNP), Xylem (XYL), Hubbell (HUBB), CMS Energy (CMS), Invesco (IVZ) and Pentair (PNR)
After the close: Visa (V), Seagate Technology (STX), Waste Management (WM), Robinhood (HOOD), Oneok (OKE), NXP Semiconductors (NXPI), Baker Hughes (BKR), Ventas (VTR), EQT (EQT), Arch Capital (ACGL), Extra Space Storage (EXR), FirstEnergy (FE), F5 (FFIV), PPG Industries (PPG), Expand Energy (EXE), Essex Property Trust (ESS), CoStar Group (CSGP), Universal Health Services (UHS) and BXP (BXP)
Outside the US, Novartis (NVS) and Porsche (DRPRY) also report, followed by SK Hynix (SKHY) in the evening.
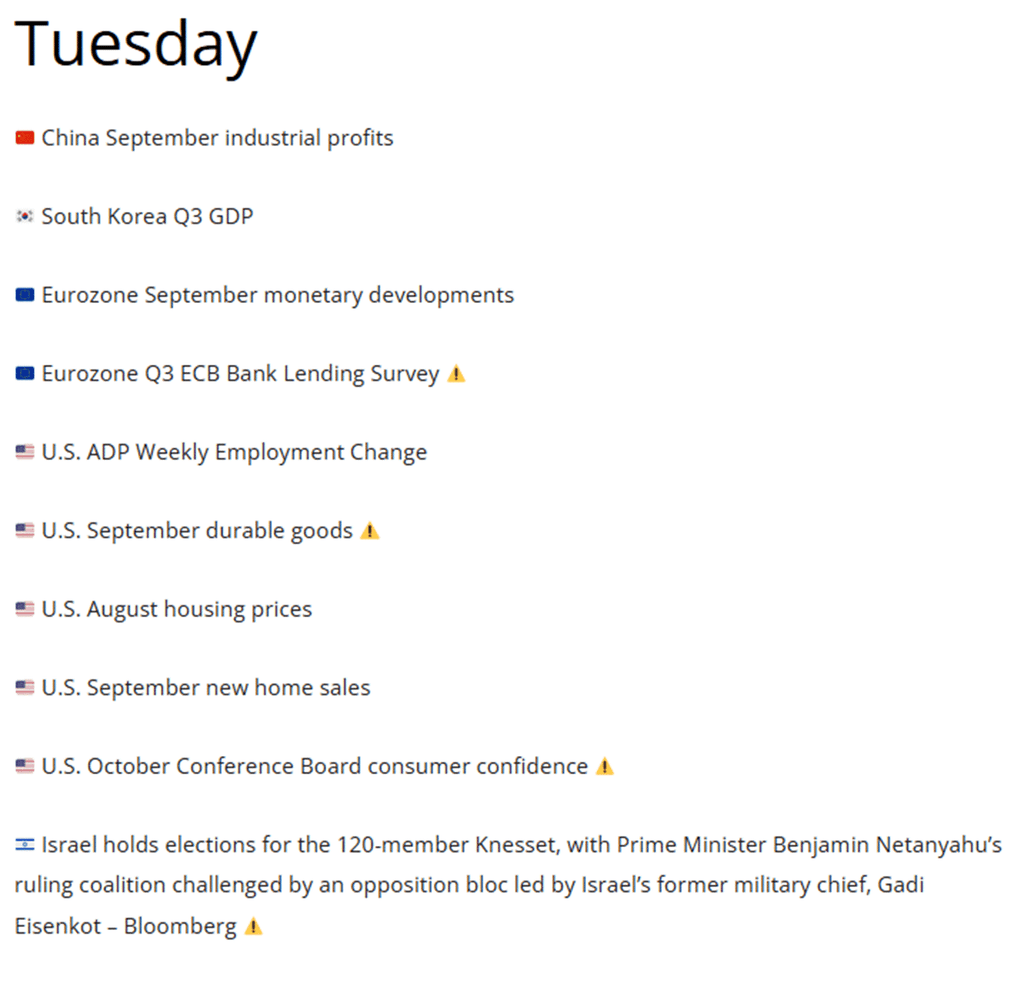
Ex-US highlights include China September industrial profits, South Korea Q3 GDP, France October consumer confidence, Eurozone September M3 and the ECB’s Q3 Bank Lending Survey. Israel also holds parliamentary elections.
From Christophe Barraud’s international Week Ahead rundown:
At the time of publication, in terms of securities mentioned, Sethi was long AAPL, GOOGL, INTC, META, MSFT, NFLX, PYPL, SPCX, SPGI, AMT, BA, WM, SPY, RSP, CPER, and numerous Treasury ETFs.