The Bounce Runs Into a Hawkish Fed
Core CPI rose 0.3% for a third straight month and two current FOMC voters hinted at faster hikes, sending the 2-year yield up the most since April 2025, but the S&P 500 recovered much of its intraday losses despite Nvidia sliding again.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Executive Summary
The CPI report I flagged in last night’s update (AI Bounce Drives Broad Market Rally) as the next catalyst came in hot, and two Fed officials made the case for the Fed to consider quickening the pace of rate hikes, taking the steam out of Monday’s bounce, although stocks pared back losses by the close.
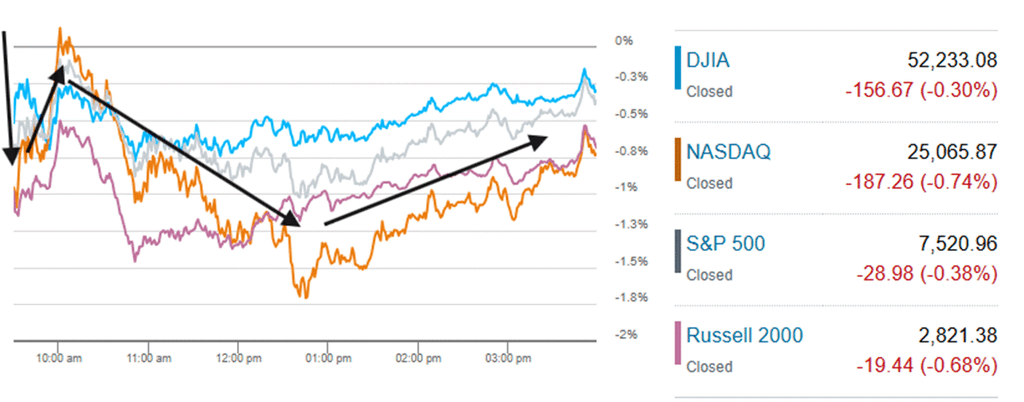
The S&P 500 would finish down 0.4% and the Nasdaq 0.7%, both less than half of their intraday lows (1% and 1.7% respectively). The Russell 2000 would also finish 0.7% lower and the Dow Jones Industrial Average 0.3%, while the equal-weighted S&P 500 ended about flat, with weakness today driven by the megacap Technology sector.
Schwab
Core consumer prices rose 0.3% in October, a third straight month of 0.29% or more, and headline prices rose 0.35%, both above expectations (more here: Core CPI Comes in Hot Again, Putting a Half-Point Fed Hike on the Table). While a year-over-year figure was not available due to the government shutdown a year ago, as detailed in the CPI post, the imputed measure saw inflation moving in the wrong direction across a wide range of inflation metrics, as did inflation breadth, a key metric focused on by Chair Warsh.
The core CPI reading was right at the threshold Fed Governor Waller set before the report for considering a 50 basis point hike in December (Fed’s Waller Floats a Half-Point Hike if CPI Runs Hot). Dallas Fed President Logan, a 2026 voter, said later the Fed needs “at least two more 25-basis-point rate increases” and may be able to move “more rapidly this winter” (Dallas’ Logan Adds to 50 Basis Point Speculation).
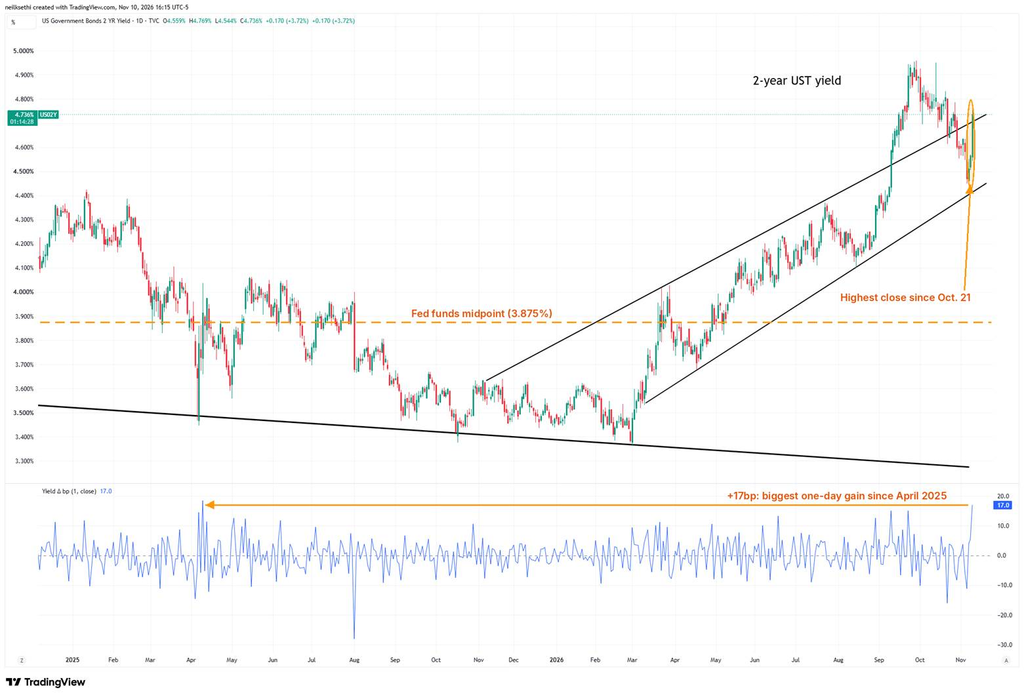
The 2-year Treasury yield jumped 18 basis points (including after-hours), its biggest one-day gain since April 2025, and the 10-year briefly topped 5% not helped by a poor 10-year Treasury auction. The $42 billion 10-year auction tailed, with the biggest drop in indirect (which includes foreign) demand since 2016 (Foreign Demand for Benchmark 10-Year Auction Sees Biggest Drop Since 2016), a day after Monday’s 3-year sale also tailed on the back of weak foreign demand (Foreign Demand for U.S. Treasury Auctions Remains Tepid as 3-Year Tails).
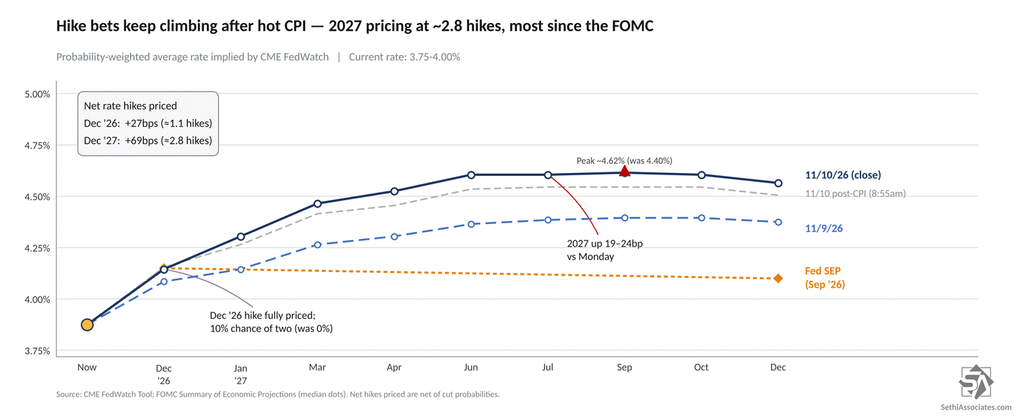
Markets now fully price a December hike, with a 10% chance of a half-point move, and nearly three hikes through December 2027, up from two Monday.
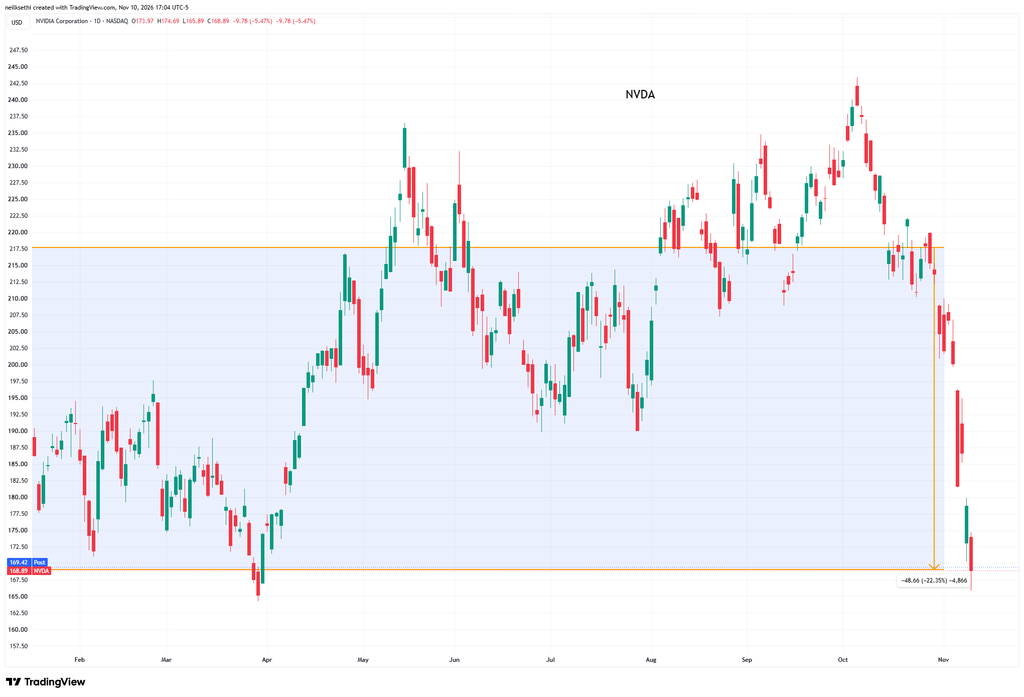
Tech was the worst sector, falling 1.4%, as Nvidia (NVDA) fell another 5.5% after Bank of America dropped it from its US 1 list, while Financials led. Nvidia is now down over 22% the past two weeks.
The VIX fell again even as the S&P 500 dropped 0.4%. A spot-down, vol-down day that size has come on only 4% of comparable S&P 500 down days since 1990, and it’s the first since March 2025. It’s typically a sign of volatility easing off after a spike: 69 of the 100 prior cases came with the VIX already at 19 or higher, including the session two days after the Brexit spike in June 2016 discussed in An Unprecedented Whipsaw in Investor ‘Fear’. The dollar rose 0.6%, while gold fell 2.1% and bitcoin 1.5% (including after hours).
Oil fell as much as 3.4% on hopes for a deal with Iran, then pared its losses after Iran’s top security official said there were no current talks with the US. WTI settled down 0.9% in the cash session.
In other data, ADP’s weekly hiring estimate rose to its best since late September (ADP Weekly Hiring Strengthens to Best Since September 26).
Wednesday brings a light calendar, with the bond market closed for Veterans Day but stocks trading. Remember to thank a veteran for their service.
As a reminder, my look at today’s charts follows in a separate post later this evening.
Market Commentary
AI:
“It is only natural that there is some discussion now about waiting and seeing how things play out for a little while,” said SoftBank CFO Yoshimitsu Goto.
“We have anywhere from a trillion to a trillion and a half projected in [capital expenditures] for the hyperscalers next year,” said Jack Herr, senior investment analyst at GuideStone Funds. “Is that really going to stop if the fed-funds rate is 50 [basis points] or 100 bps higher? We don’t think so.” He added: “The Federal Reserve’s rate tool may not slow down the economy or put a damper on inflation the way it would 20 to 30 years ago.”
Bonds/Fed:
- “The Fed could push for a more-aggressive tightening cycle with CPI continuing to print strong,” said Lindsay Rosner at Goldman Sachs Asset Management. “A December hike is our firm base case despite wider AI jitters, and stubborn inflation means we cannot rule out further hikes in 2027.”
- “It’s clear the Fed can hike a little bit more in an effort to calm inflation without harming the labor market, as the labor market is already on sound footing,” said Skyler Weinand at Regan Capital.
- “With December’s meeting on the horizon, this report strengthens the case for another rate hike and puts even more pressure on policymakers to remain vigilant,” said Karen Manna, fixed income investment strategist at Federated Hermes. “The longer inflation stays elevated, the narrower the Fed’s path becomes to bring prices under control without causing further damage to growth.” She added that “the concern for investors is that inflation forces the Fed to maintain a restrictive stance well into 2027.”
- “With the near-term trend looking worse, a December Fed hike is a given unless financial conditions tighten materially further or markets are very volatile on the eve of the meeting,” said Krishna Guha at Evercore. “The larger question is why inflation has come in hotter in recent months, and what this means for policy in 2027.”
- “Today’s inflation report is a warning shot,” said Seema Shah, chief global strategist at Principal Asset Management. “A December hike now looks locked in, with the upside surprise extending well beyond energy and into both core goods and services.” But she said the report doesn’t settle the argument for an outsized move, which would require evidence that inflation is accelerating decisively, expectations are becoming unanchored or the economy is overheating. “We are not there yet. Chris Waller has put 50 basis points on the table, and today’s numbers give that debate credibility. For now, however, the broader picture still favors a more cautious approach.”
- “The bigger risk is not simply higher yields, but a higher rate path,” said Bret Kenwell at eToro. “That could create another headwind for equities at a time when volatility in the AI trade has already weighed on the major indices, even as the broader rotation outside of tech has been resilient.”
- “Today’s release will be a headwind to risk assets as investors price the possibility of a 50bp hike in December and additional hikes beyond, with higher front-end yields and a stronger dollar weighing on equity valuations,” said Jeff Schulze, head investment strategist at the Franklin Templeton Institute.
- “Given the higher-than-desired inflation, it is even more likely now that the Fed will raise rates in December and although some are calling for a 0.5% increase in the Fed Funds target rate, we expect that they will only raise rates by 0.25% next month,” said Chris Zaccarelli, chief investment officer for Northlight Asset Management.
Note more quotes in today’s CPI post.
Stock and Sector Breakdown
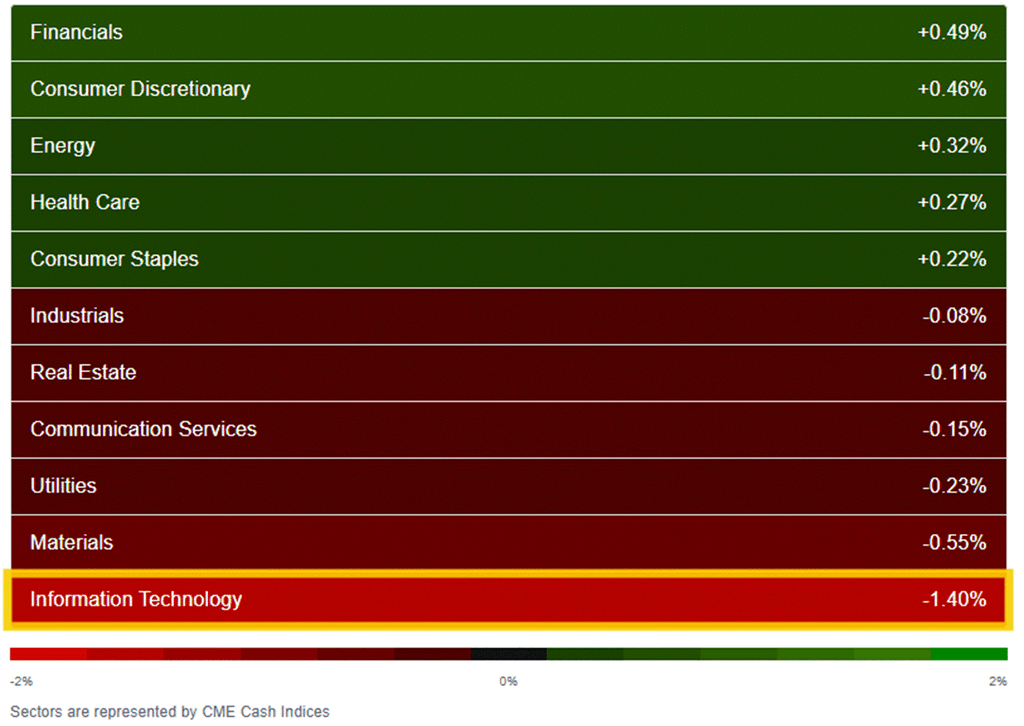
“Six of 11 sectors fell, but Tech (-1.4%) the only down more than -0.6%. Financials (+0.5%) and Consumer Discretionary (+0.5%) led the gainers with none up more than that amount as well.
247 S&P 500 stocks rose and 250 fell, with 13 gaining more than 3% and 26 falling that much (from 158 and six Monday).
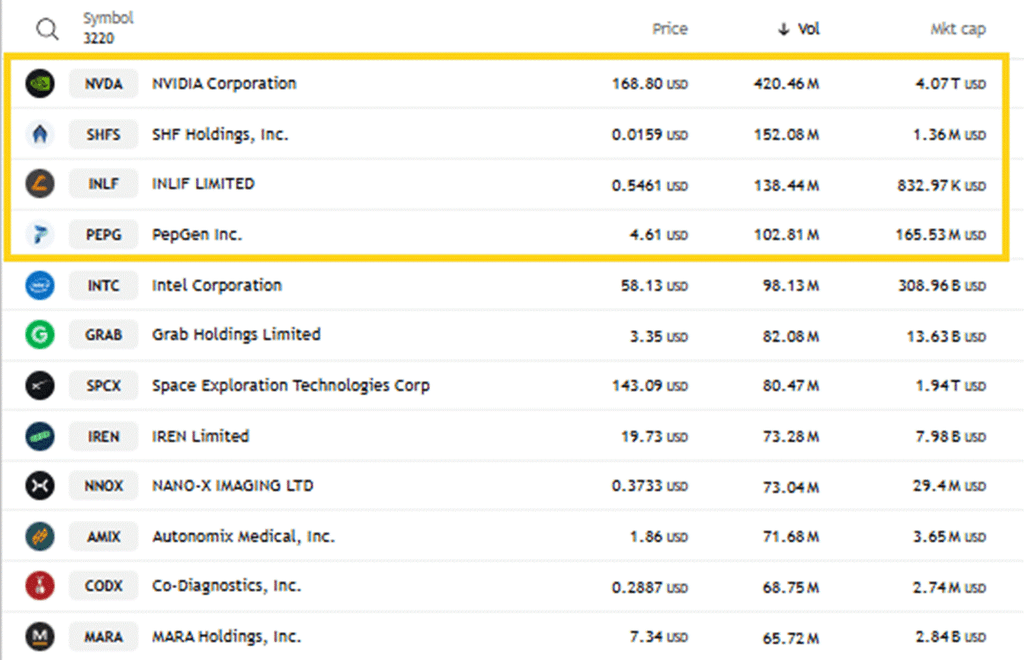
Also speculation has dried up on the Nasdaq. Outside of Nvidia, only three stocks traded more than 100 million shares, two of them penny stocks.
Charter Communications (CHTR) led the S&P 500 with a gain of almost 11% as Citigroup analyst Michael Rollins maintained Charter with a Buy and raised the price target from $140 to $150 (Benzinga), while Skydance (SKYD) was the worst performer, down 7.6% after its first earnings report Monday evening disappointed
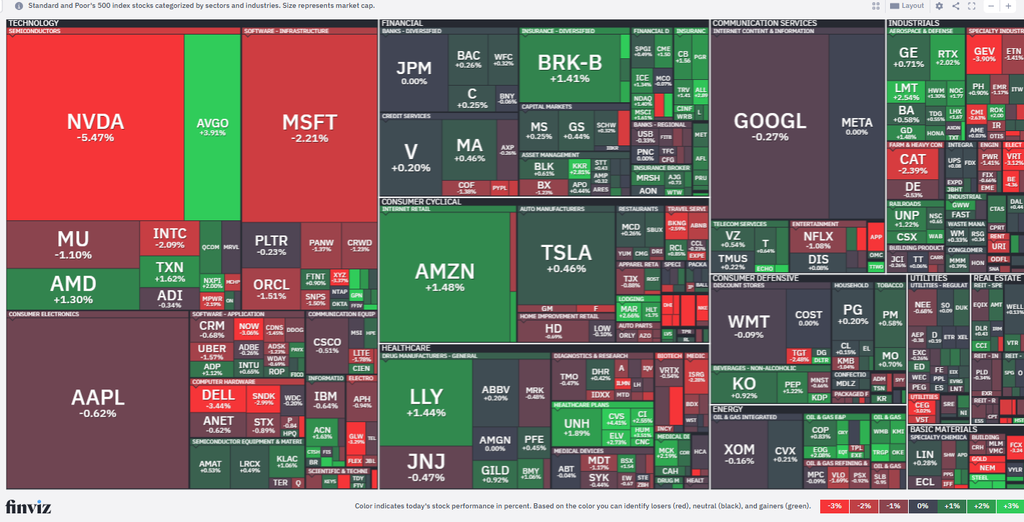
As noted above, Nvidia added to Monday’s slide. Besides Bank of America’s move, a Citi analyst cut his price target, and investors are still weighing the fallout from the board’s investigation of Jensen Huang. As Rev Shark noted, Nvidia’s weakness is benefiting other chip names, with Broadcom (AVGO) up 3.9% and AMD (AMD) 1.3%.
Among the other megacaps, Microsoft (MSFT) fell 2.2% after Anthropic launched beta versions of Claude Whiteboards and Claude Sheets, which will reportedly sharpen competition in workplace software, while Amazon (AMZN) rose 1.5%.
Rate-sensitive homebuilders fell as yields jumped, with Lennar (LEN) down 5.1%, NVR (NVR) 4.6%, D.R. Horton (DHI) 3.8% and PulteGroup (PHM) 3.7%.
Banks held up, which is how Doug Kass says he’s playing the long side right now, and he added to his financials on the afternoon weakness.
Among reporters, Take-Two (TTWO) jumped 8.9% after its report Monday evening.
Anthropic also disclosed in an amended S-1 filing that it will offer 825 million shares at an estimated $70 to $78, putting it on track for an IPO before Thanksgiving.
After the bell, CoreWeave (CRWV) rose about 2% after the neocloud company reported a big surge in its revenue and order backlog.
FedWatch
I covered Fed hike expectations in my CPI post (Core CPI Comes in Hot Again, Putting a Half-Point Fed Hike on the Table). Here’s the update for how they finished:
By the close, December pricing had eased a touch, with the chance of a 50 basis point hike at 10% (from 14% about an hour after the report) and 27 basis points priced (from 28bp). But hike pricing further out kept building, with 69 basis points now priced through December 2027, nearly three hikes, up from 63bp after the report and 50bp Monday, per CME FedWatch.
More From TheStreet Pro
Helene Meisler — Market Rallies, but Steam Is Running Out
Rev Shark — A Change in Market Character Is Brewing, but It Still Needs Proof
Stephen Guilfoyle — Not Quite Back Where We Started
Stephen Guilfoyle — Caterpillar Could Be a Buy After Michael Burry Takes Profit
Peter Tchir — My Take on the Election and What to Watch in This Mind-Boggling Market
Alex Frew McMillan — How SoftBank Is Taking a Hit While AI Ambitions Have Yet to Pay Off
Chris Versace — Anthropic’s Pending IPO Will Be a Must-Watch Event for Investors
Bob Lang — Chart of the Day: Morgan Stanley Fights Its Way Back
Doug Kass’s Diary:
- Oscillator Further Overbought
- Waller on a December Hike
- There Will Be More EPS Cuts to Come in the Semis
- Bank Boost
- Bond Alert
- Boockvar on a Soft 10-Year Auction
- More Tales From Nvidia: The President Responds and the ‘WeWork II’ IPO Readies (Issue #275!)
- Howling About Spiking Yields
- Boockvar on Waller, Warsh and More
Note: Doug posted 26 Diary entries today; these are the market ones (three more are linked above).
And From Me If You Missed It
A Look at the Charts — Room to Run, Except for the Nasdaq-100
The Day Ahead: October CPI Headlines a Busy Tuesday
Miscellaneous
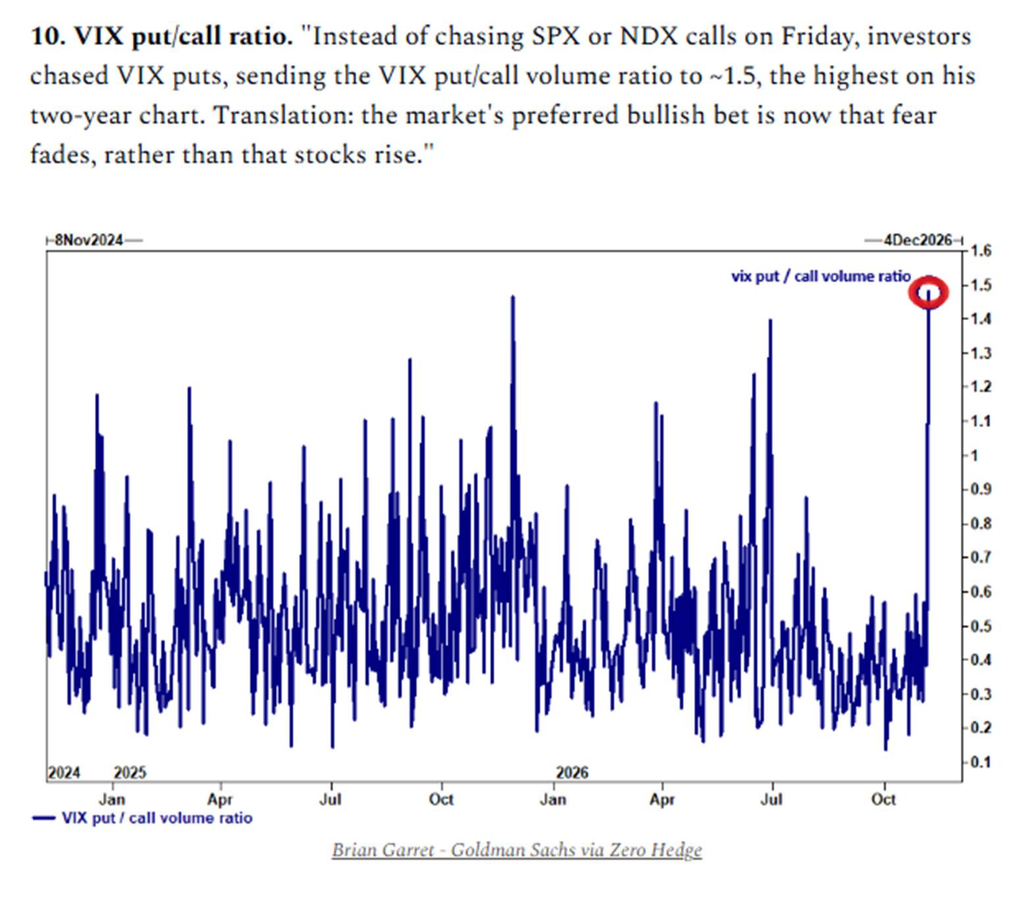
I noted last night that the VIX had its biggest one-day percentage drop since April 2025 (and wrote more about it on the Stock Market Today page – An Unprecedented Whipsaw in Investor ‘Fear’). Traders were ready for it.
Goldman’s Brian Garrett notes (via ZeroHedge/DailyChartbook.com) that instead of chasing S&P 500 or Nasdaq-100 calls on Friday, they piled into VIX puts, sending the VIX put/call volume ratio to about 1.5, the highest in at least two years.
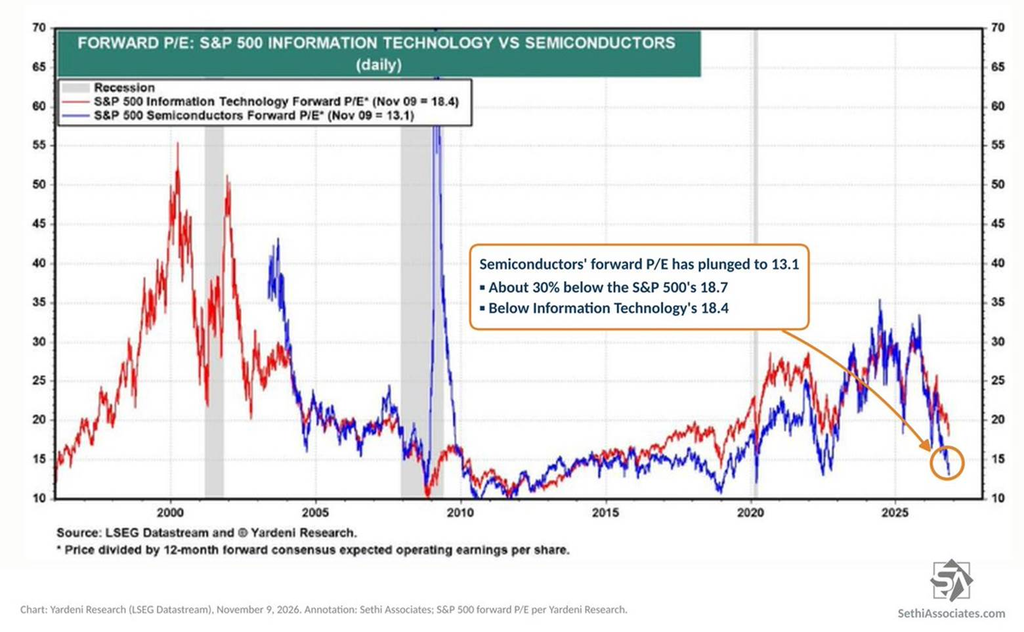
Ed Yardeni is staying bullish on semiconductors: “Soaring earnings estimates and the recent decline in stock prices have compressed [semiconductor] valuations. The industry’s forward P/E has plunged to just 13.1, well below the S&P 500’s 18.7 and the Information Technology sector’s 18.4.”
“Historically, Semiconductor P/Es have tended to bottom near earnings-growth peaks and recover as earnings-growth expectations bottom and turn higher. We suspect that such a recovery could cushion stock prices as forward earnings growth moderates to more sustainable levels, with speed bumps slowing—but not derailing—the AI investment boom.”
Wrap-Up — The Bounce Runs Into a Hawkish Fed
I said last night that CPI was the next catalyst and that a hot print could put a damper on things. Well, it was definitely hot, and it definitely put a damper on things. But bonds (particularly at the short end) saw the worst of it, with stocks finding their footing and making a third straight lower high (meaning the lowest levels hit today were higher than the previous day).
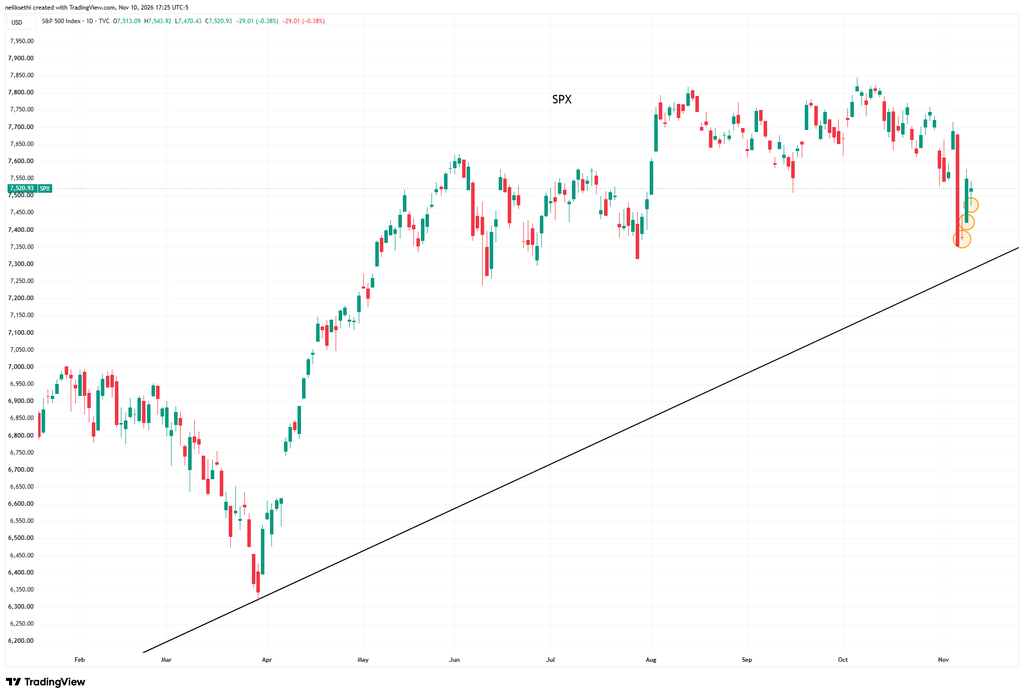
That’s a sign that buyers are coming in and not waiting for a retest. I’m still not confident we won’t get that retest, but it’s a good start. As Rev Shark put it, “A year ago, a hot consumer price index and a hawkish Fed governor on the same morning would have produced a much uglier day.”
That said, the coast is far from clear. The Nasdaq-100 (NDX), the one I said to watch, ran right up to its 200-DMA again early before rolling over to close down 0.6%. So far that’s the scenario I laid out for putting on my tactical QQQ short. And as Helene noted this morning, after a day like Monday “we see some choppiness and give back as stocks digest the rally,” though her indicators are no longer oversold and she sees a path back to overbought around Thanksgiving.
That echoes the caution from Tier1Alpha yesterday on reading too much into moves in either direction given the negative gamma. Wednesday brings a breather, with an extremely light calendar due to the Veterans Day holiday. I’m not sure how volumes will be on the equity side, so as always, let’s see what we get and go from there.
The Day Ahead — A Light Calendar for Veterans Day
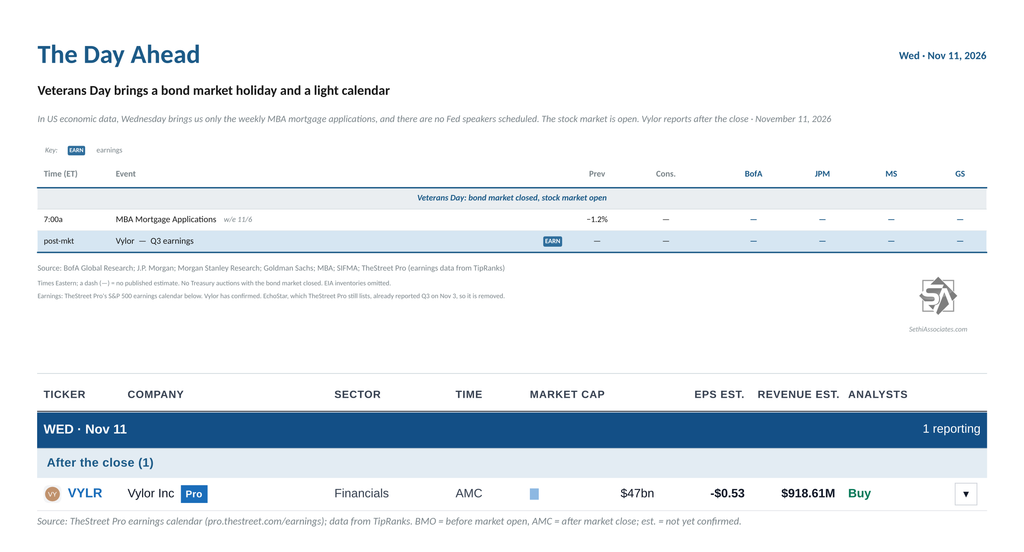
In US economic data, with the bond market and government offices closed in honor of Veterans Day, Wednesday brings us only weekly MBA mortgage applications. U.S. stock markets are open.
There are no Fed speakers or Treasury auctions scheduled.
Just one S&P 500 component reports, and its market cap is under $100B:
After the close: Vylor (VYLR).
Remember to make it a point to thank a veteran Wednesday!
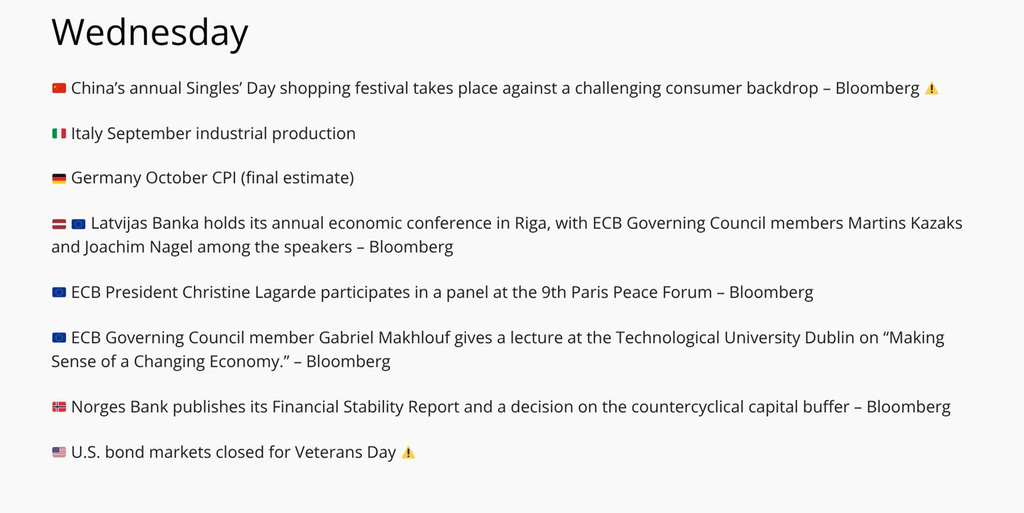
Ex-US highlights include China’s Singles’ Day shopping festival, Germany’s final October CPI, and ECB President Christine Lagarde on a panel at the Paris Peace Forum, with ECB policymakers Joachim Nagel, Martins Kazaks and Gabriel Makhlouf also speaking.
From Christophe Barraud’s international Week Ahead rundown:
At the time of publication, in terms of securities mentioned, Sethi was long AMZN, AVGO, MSFT, SKYD, SPY, TDG and numerous Treasury ETFs, and short AMD and QQQ. In the last 24 hours Sethi covered his GEV short and went long TDG.