Caterpillar Could Be a Buy After Michael Burry Takes Profit
The “Big Short” investor made a notable move in his construction holding.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Caterpillar (CAT) is having a rough day.
The shares are trading a couple of percentage points lower. As a matter of fact, CAT is having a rough half year or so. The stock gave up 23.5% in July, and another 2.1% in August. Then CAT held its own in September (+1.7%) before being sucker-punched for another 23.2% in October. So far for November, CAT has puked another 6.6%. Good times… not.
Since peaking at $1,073 on June 30, these shares have lost 45.7% of their value.
CAT gave up 10.3% just last week, which provoked famed short-seller Michael Burry to, according to his newsletter, Cassandra Unchained, reduce his bearish position in in this name by 75% after his long put options on the construction equipment maker had roughly quadrupled in value. Burry added that the market value of his remaining position is now more or less equal to what he initially invested when he opened the trade at the end of the second quarter. In other words, he took all of his profit off of the table. Like Burry or not, he nailed this one.
For those wondering, Burry also quite famously, according to his posts, still holds bearish positions involving Oracle (ORCL), Palantir (PLTR) and MetLife (MET) in addition to Caterpillar as well as in the Van Eck Semiconductor ETF (SMH). Readers know that I agreed with Burry on ORCL. That said, after making some dough, I covered that short long ago. I am flat that name. I had sold a lot of PLTR and bought a portion of it back during last Thursday’s meltdown. I am not in MET and never have been.
As for the semis, you all know the trades I have made the last few weeks into last week, but in individual names (closed (INTC), closed (SNDK), closed (MU). Sold large portions of (NVDA) and (TSM). Sold large portions of (AMD) and then bought that entire amount back, then I bought more AMD). We’re already up more than 28% on those recent AMD purchases. That stock is now the most heavily weighted long position in the Sarge-folio.
But, Back to CAT…
So, if Burry took his football and went home, and the stock has almost been halved in less than half a year, is it time to take another look at Caterpillar? You see, the problem is this: The data center buildout had become a primary driver for sales growth for not just Caterpillar, but for the entire construction industry. This has reshaped the company. Yes, CAT still manufactures traditional construction and mining equipment, which is needed, but has and is evolving into a major supplier of AI power infrastructure.
The core business still provides a massive revenue base, but surging demand for on-site data center power has driven the firm’s sales growth, increased profit margins and record order backlogs in the third quarter, which was reported in late October. That’s nearly double what it was a year earlier during the same period. Customer orders for large reciprocating engines and turbines stretch all the way out to 2029 and 2030.
So, if you believe that due to the midterm electoral results, that the data center buildout is done for, then the stock’s weak performance has more room to go. However, if you believe that all of that capital investment that states like Texas wish to forego will either still land in that state or at least move to states where it will be treated better, then this business can still thrive.
The Chart
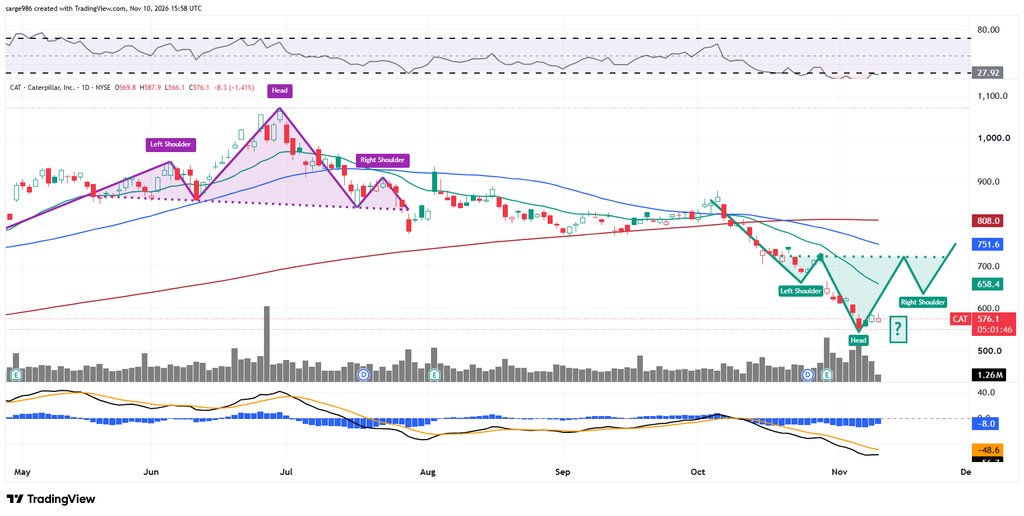
This is no sure thing, but it may be worth a small speculative effort.
Readers will easily see the head-and-shoulders pattern of bearish reversal that looks quite clear in hindsight stretching from this past spring into summer. Wow, did that setup ever work like a charm.
Yeah, I missed it. Burry did not. The stock traded sideways from July into October, then it sold off some more.
What I see there, potentially, is about half, maybe a little more than half, of a possible inverse head-and-shoulders pattern of bullish reversal. The pattern still needs a right shoulder, and the pivot is so far off ($730) that it could serve as a target. That said, there is something to this technical setup. If it comes to fruition, wouldn’t you rather buy it at the head or even the shoulder than at the neckline?
Relative strength is anything but and the daily MACD is in awful condition, so I can see why Burry held onto something. However, I can see taking on a smallish, non-top-15 type position and seeing if it does anything. We can do this. Why? Because we have the 8% rule. It saves us more often than it curbs profitability.
At the time of publication, Guilfoyle was long AMD, NVDA and TSM equity.