Market updates and conversation from TheStreet Pro team. Follow the latest and join the conversation below.
Stock Market Today: November 12, 2026
Newest first · All times Eastern · 7 updates
DATE:
By Neil Sethi
Another Treasury Auction Sees Weak Demand Led by Indirect Bidders
Thursday’s $25 billion 30-year bond auction tailed, meaning it sold at a higher yield than the market expected, as demand from indirect bidders (which include foreign buyers) fell below its six-month average. That follows tails at Tuesday’s 10-year and Monday’s 3-year auctions, which also saw weak indirect demand. It’s the first time since May that all three of these auctions tailed.
Indirect bidders took 68.1%, the lowest since August, down from 72.3% in October and below the six-month average of 70.5%.The indirect share fell at all three auctions this week. Direct bidders took 20.5%, little changed from 20.9% in October and close to the six-month average of 20.0%. That left dealers, who take whatever other bidders don’t, with 11.4%, the most since August. That’s up from 6.8% in October and compares with a six-month average of 9.5%.
The bid-to-cover ratio measures how many dollars were bid for each dollar of bonds sold. It fell to 2.36, the lowest since June, from 2.54 in October, against a six-month average of 2.44.
The bonds sold at a high yield of 5.441%, 0.4 basis point above the 5.437% when-issued yield just before the 1 p.m. ET bid deadline, according to investingLive and ZeroHedge. It was the second straight tail and the biggest since June; August’s was also 0.4 basis point. The six-month average is a 0.1 basis point stop-through, meaning an auction sells below the expected yield. The high yield was down from October’s 5.618%, which was the highest since August 1999, but it was still the second-highest since 2001. The six-month average is 5.211%. The new bonds carry a 5.375% coupon, the highest since February 2001, according to Treasury data.
ZeroHedge said the auction “was not pretty… at all,” though “not as ugly as Tuesday’s terrible 10Y auction.”
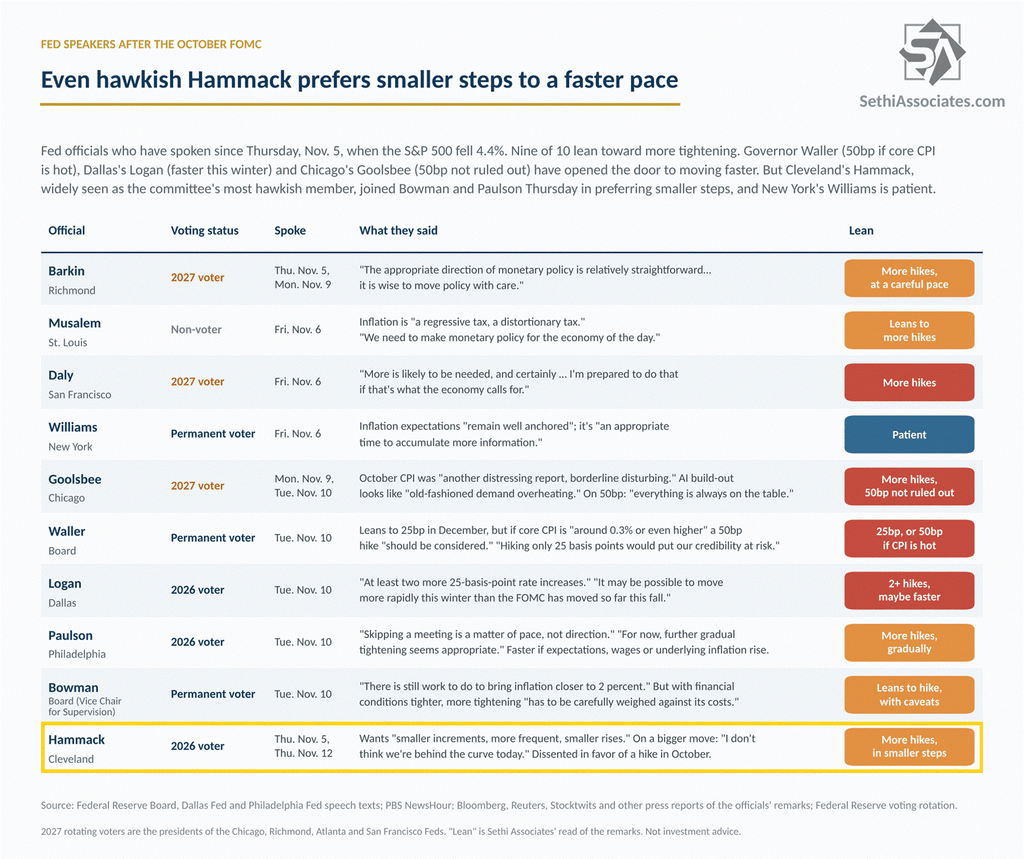
Cleveland Fed President Beth Hammack, a 2026 voter who is widely considered the most hawkish member of the committee (she has dissented three times this year, all on the hawkish side, most recently in favor of a quarter-point hike in October), interestingly didn’t join Governor Waller in saying a larger rate hike should be a live debate at this point.
Like nearly every Fed official who has spoken over the past week, she wants more tightening. “We need to move to a restrictive stance of policy to help bring inflation back down to that 2% objective, which is critically important,” Hammack said at an event in Columbus, Ohio, according to Bloomberg. “If we don’t, I worry that an inflationary mindset could start taking hold.” She said October’s CPI showed progress on inflation had “really stalled,” and “we’re moving away from that 2% goal, rather than back down towards it.”
But she wants to get there in “smaller increments, more frequent, smaller rises,” which she said is “less disruptive to the overall economy than moving in sharper, more aggressive movements.” A bigger move is only on the table if the Fed falls behind: “I don’t think we’re behind the curve today, but if we get behind the curve, then that might be something that we need to consider,” she said. “I’ll certainly have an open mind walking into that December meeting.”
She remains on the hawkish side, though. As mentioned, Hammack dissented in favor of a quarter-point hike in October, so her “more frequent” increments point to a hike at every meeting.
Meanwhile, Chicago Fed President Goolsbee (a 2027 voter) kept up his warnings at Yahoo Finance’s Invest conference Thursday, saying “inflation, in several ways, looks like it’s going the wrong way,” and that it’s “in the wrong, more disturbingly persistent categories like services, healthcare, a series of things that really can’t be coming from tariffs or oil prices.” “I think it’s worth being sober minded at a moment like this that we’re inching our way into a territory that’s historically a tough spot for any central bank to try to get rid of that inflation,” he said. “We’d do well to try to prevent it from getting worse.” But he didn’t tip his hand on the size of a December move, saying he didn’t want to prejudge policy.
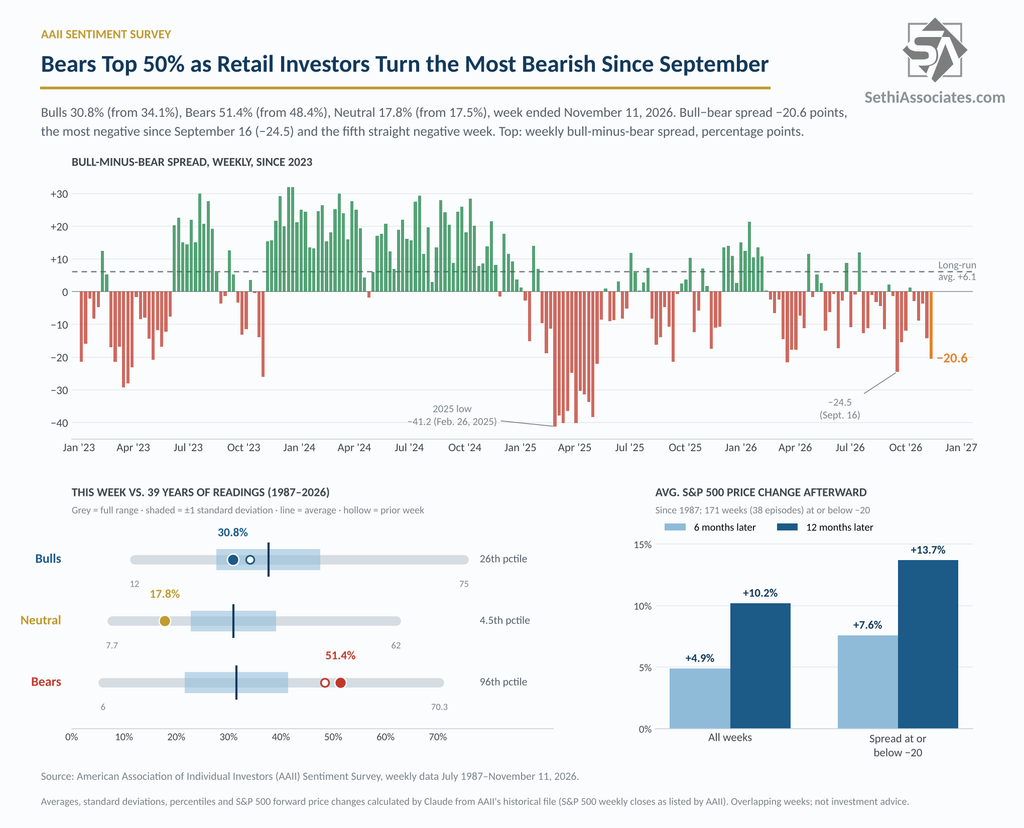
AAII Bulls (those who see higher stock prices in six months) fell to 30.8%, the least in eight weeks, from 34.1% the prior week (still though above the 28.8% eight weeks ago, which was the least since September 2025), and remained below the long-term historical average of 37.5% for a second week.
Bulls also remained below the level of the Bears (who see lower stock prices in six months), as the Bears rose to 51.4%, the most in eight weeks, from 48.4% the prior week (still though below the 53.3% eight weeks ago, the highest since May 2025). That puts Bears in the 96th percentile of all readings since the survey began in 1987. They also remain above the long-term average of 31.5% for a 40th straight week (and they’ve only been below it nine weeks since December 12, 2024).
That took the bull-bear spread to −20.6 points, the most negative since September 16 (−24.5), and its fifth straight negative week. That’s lower than 92% of all weekly readings since 1987 (8th percentile), compared with a long-run average of +6.1. It also leaves Bulls above Bears just twice in the last 17 weeks.
The Neutral camp was little changed at 17.8% from 17.5% (still just above the 17.3% three weeks ago, which was the least since early April), in just the 4.5th percentile historically. It remains under the long-run average of 31.0% and has been over that only four times since August 2024.
By our calculations from AAII’s data, when the spread has been at or below −20 (171 weeks in 38 separate episodes since 1987), the S&P 500 rose an average of 7.6% over the next six months and 13.7% over the next 12. That compares with 4.9% and 10.2% for all weeks. The edge has come from bigger gains rather than better odds, though. The S&P 500 was higher six months later 76% of the time, about the same as the 74% for all weeks, and 80% of the time at 12 months for both.
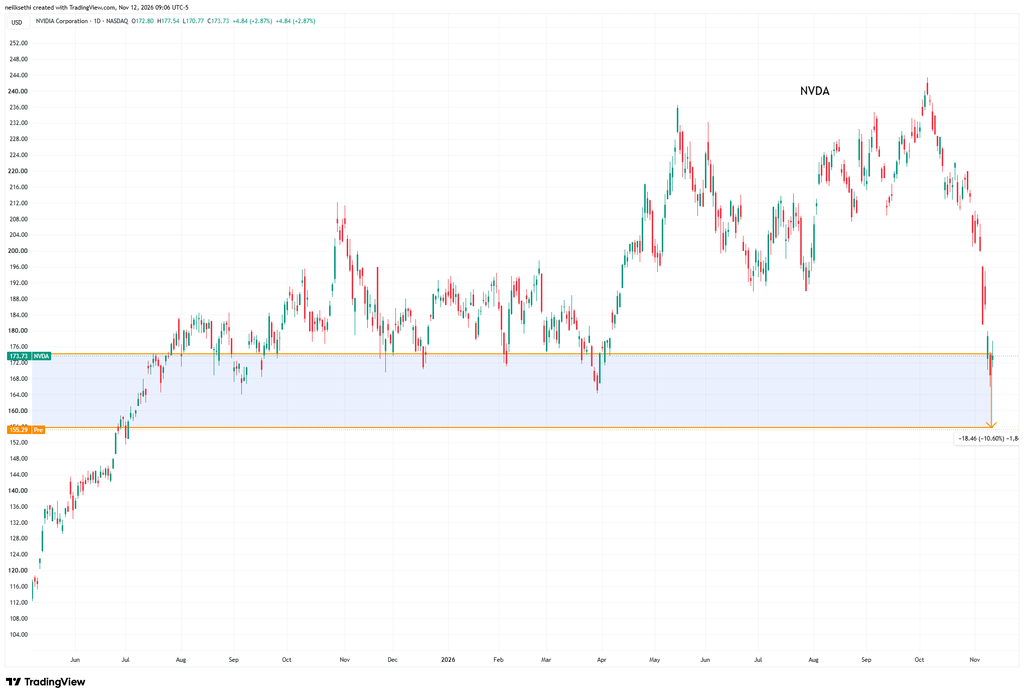
Jensen Huang has been ousted as CEO of Nvidia (NVDA), and CFO Colette Kress was named interim CEO, per Bloomberg. Shares added another couple percent to their losses and are down 10.6% premarket as of 9:05 a.m. ET.
Kress has been CFO for 13 years, after stints at Microsoft (MSFT) and Cisco (CSCO), but her public role has been limited to the numbers. Huang handled nearly all of Nvidia’s communication with Wall Street and its customers. People in the industry are floating outside names for the permanent job, including AMD’s (AMD) Lisa Su, Arm’s Rene Haas and Micron’s Sanjay Mehrotra, per Bloomberg.
This leaves open the key question surrounding the deals Huang made. Bernstein’s Stacy Rasgon, who downgraded the stock overnight, cutting his price target to $200 from $400 (Nvidia’s Problem Is Bigger Than Its CEO), said the business fundamentals “are clearly still intact,” but “we wonder what will happen to the company’s myriad of investments in the space, various backstops and residual guarantees,” per Bloomberg. That’s the risk the market has been pricing overnight into CoreWeave (CRWV), Nebius (NBIS) and Nvidia’s other investees as discussed in Nvidia’s Selloff Ripples Down the ‘Circular Web’ of Companies It Backs as Board Weighs Huang’s Future.
Kress’s first test comes quickly. Nvidia reports third-quarter results November 17, and lawmakers still want answers on Megaspeed at the House briefing the next day.
At the time of publication, in terms of securities mentioned, Sethi was long NVDA.
Initial Jobless Claims Four-Week Average Holds at Lowest Since 1969
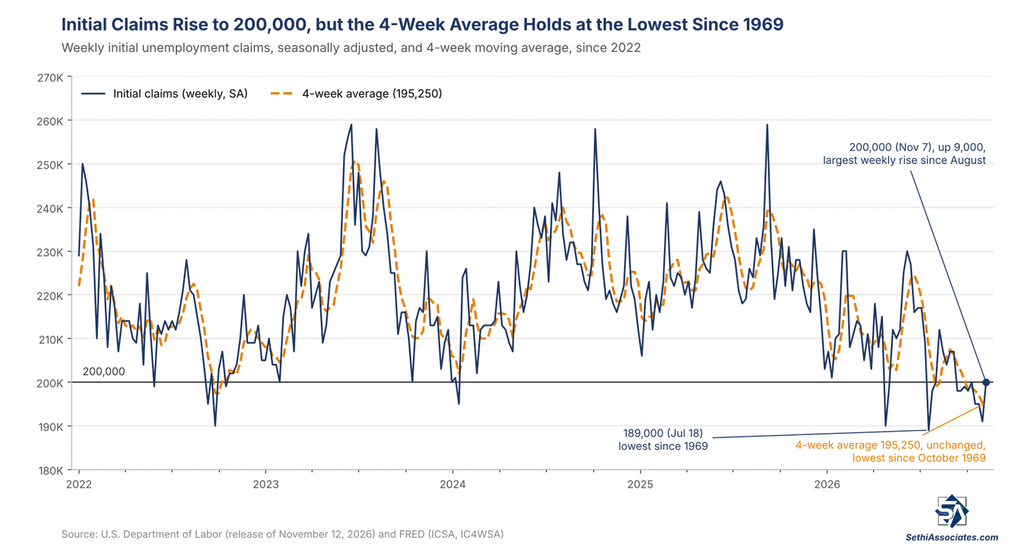
Initial jobless claims for the week ending November 7: 200,000 (estimate 195,000; previous 189,000; revised previous 191,000)
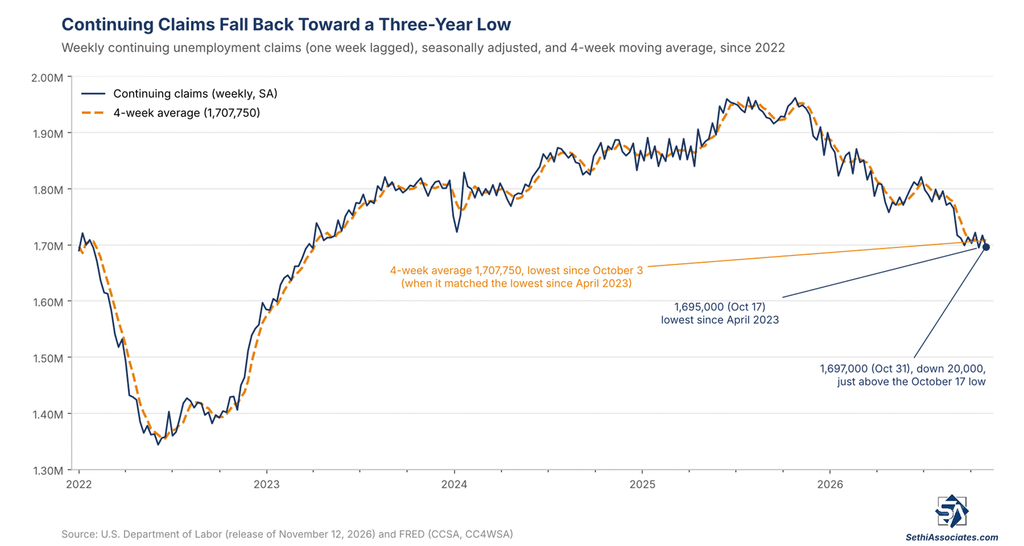
Continuing claims for the week ending October 31: 1,697,000 (previous 1,718,000; revised previous 1,717,000).
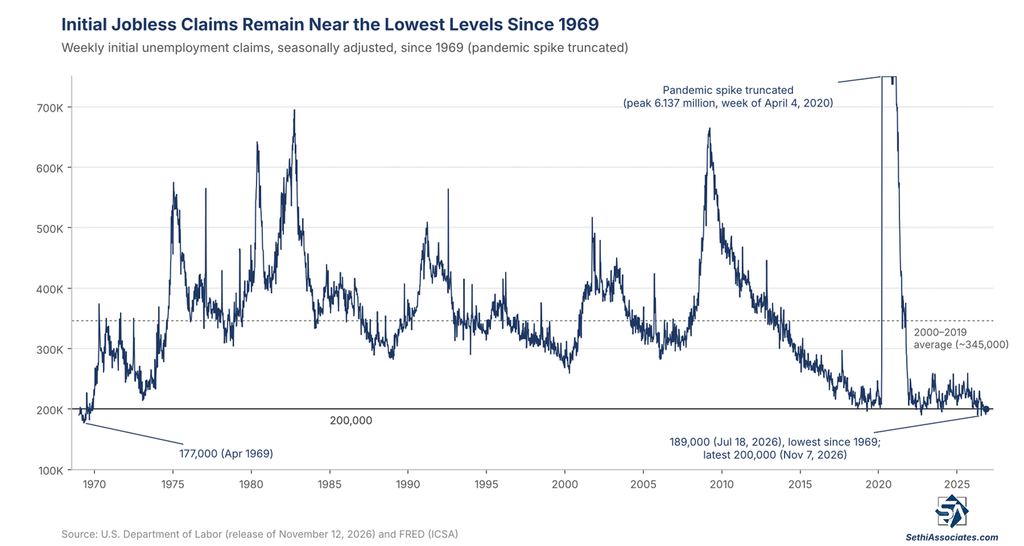
After bottoming at 189,000 in mid-July — the lowest reading since 1969 — initial jobless claims have barely budged. In the week through November 7 they rose 9,000, the most since August 8, but very subdued historically, to 200,000, the highest in four weeks. That ends a three-week run below 200,000, leaving the count at 18 weeks below that mark since 1969 (the four-week run from September 12 through October 3 was the longest since 1969), with claims still near cycle lows at the bottom of the relatively narrow range that has held since November 2021.
The four-week average was unchanged at 195,250, matching the prior week’s upwardly revised level as the lowest since October 1969 (31,750 lower year-over-year).
Continuing claims (seasonally adjusted) in the week through October 31 (one week lagged) fell 20,000 to 1,697,000 (after a 1,000 downward revision to the prior week), just above the 1,695,000 two weeks earlier that was the lowest since April 2023. That leaves them towards the bottom of the roughly 1.70 million to 2.0 million range that has held since mid-2023 — historically low, though not as low as initial claims.
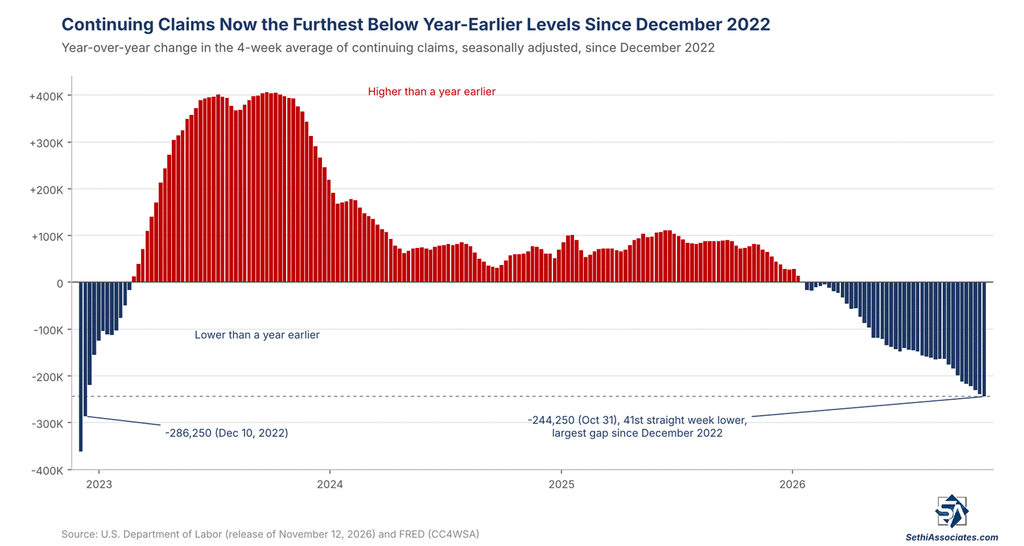
The four-week average of continuing claims fell 1,500 to 1,707,750, the lowest since October 3 when it matched the lowest since April 2023 (after a 250 downward revision to the prior week), and remains lower year-over-year for a 41st straight week (down 244,250) — the largest such gap since December 2022.
The 20-year pre-pandemic average for initial claims is 345,000 and continuing claims roughly 2.9 million.
While the Fed’s Doves See More Hikes, They’re in Less of a Hurry
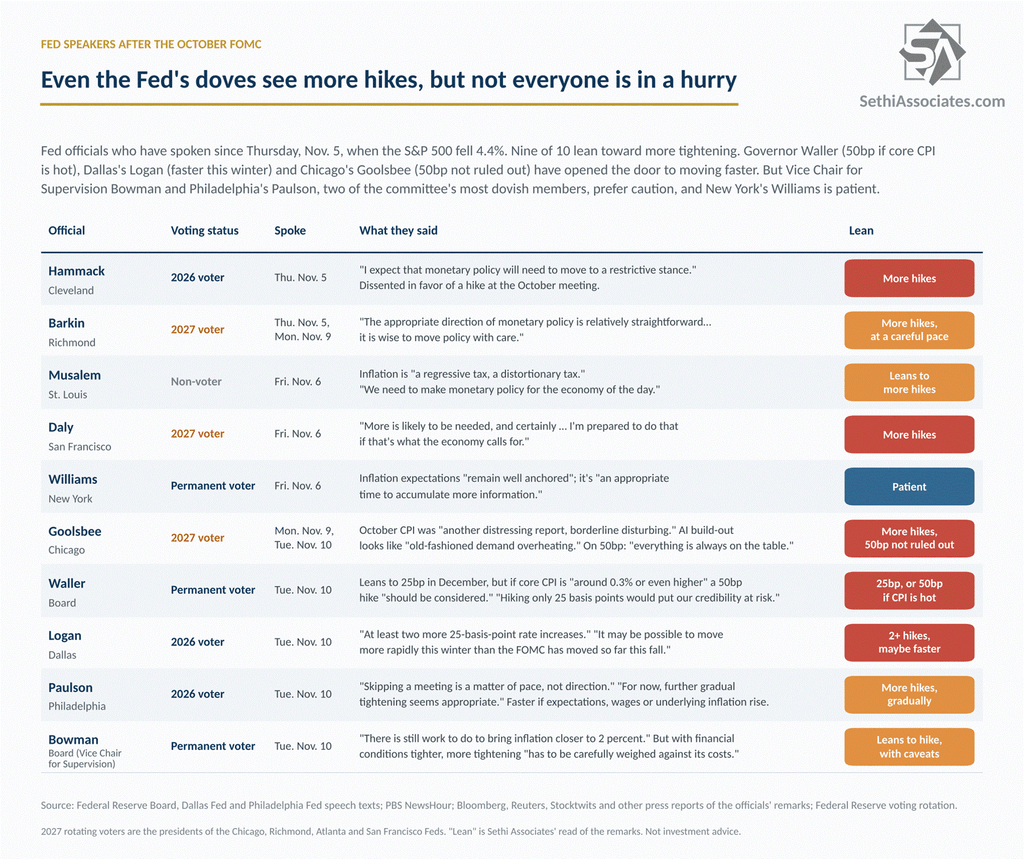
As things with the Fed are moving at a blurring pace (for the Fed), I thought I’d lay the groundwork ahead of the six Fed speakers to come today, including a couple of the more “core” members in Governor Barr and New York Fed President Williams.
After Governor Waller (Fed’s Waller Floats a Half-Point Hike if CPI Runs Hot) and Dallas Fed President Logan (Dallas’ Logan Adds to 50 Basis Point Speculation) opened the door to faster rate hikes Tuesday, Chicago Fed President Goolsbee (a 2027 voter) called October’s CPI “another distressing report, borderline disturbing” in an interview with PBS NewsHour, adding that “services inflation is not coming down” and “we have got a real inflation issue on our hands.” Asked about a half-point hike, he said “everything is always on the table, and we must get inflation back down to target, and it’s going the wrong way at this point.”
So momentum toward a quicker hiking pace is building, but it’s important to note there’s another side to this argument. Two of the committee’s most dovish members, Vice Chair for Supervision Michelle Bowman and Philadelphia Fed President Anna Paulson, made clear Tuesday that while they’re on board with more hikes, they’re in less of a hurry.
Bowman said in a speech that “there is still work to do to bring inflation closer to 2 percent,” that Tuesday’s CPI suggests core PCE “likely moved up further to 3.3 percent in October,” that pressures “may be broadening,” and that she’s “more attentive to the inflation side of our mandate,” she added more caveats than the hawks. Financial conditions “have tightened a bit recently because of lower equity prices, higher private interest rates, and a stronger dollar,” so “the benefit of additional policy tightening has to be carefully weighed against its costs for interest-rate-sensitive sectors.” She also sees tariffs, energy and AI-related pressures each driving “roughly one-fourth” of above-target core PCE inflation, which she says are mostly “relative price shocks in specific sectors,” and expects core PCE “to move closer to 2 percent next year.”
That’s a very different read than Goolsbee, who worries AI-driven demand is starting to “drift out into just overall overheating prices of a whole bunch of things, including services.” Bowman also added a dose of caution about the AI trade, saying the risks “seem to be concentrated in only a few large firms that provide AI services,” with “the appearance of circular financing,” and that a shortfall in AI revenues could bring “a sharp correction in equity prices for AI firms, higher financing costs, and reduced access to credit.” That takes on added importance given the issues with Nvidia (NVDA).
Paulson, who votes in December before Philadelphia rotates off the committee, said in her speech that “skipping a meeting is a matter of pace, not direction. There is likely more work to do,” but “for now, further gradual tightening seems appropriate.” For a dove, like Bowman, she is still relatively hawkish: “Underlying inflation is above target, and it hasn’t come down. That tells me that elevated inflation isn’t just about factors that will go away on their own.”
Still she argues that going gradually “gives households, businesses, and the financial sector time to adjust.” In addition it “lets me learn as we go,” she said, noting “big swings in the stock market and in oil prices” and that “some of the strength in consumer spending is tied to the stock market, and that may prove less durable than we expect.” She would “act more quickly if inflation expectations drift up, if wage pressures build, or if underlying inflation moves higher. Right now, that’s not what I’m seeing.”
So nine of the 10 officials who have spoken since last Thursday’s selloff lean toward more tightening, but with Bowman and Paulson preferring caution, Richmond Fed President Barkin saying “it is wise to move policy with care” and New York Fed President Williams calling it “an appropriate time to accumulate more information,” a half-point move in December looks like a tougher sell. We’ll hear more today from Goolsbee, Williams, Cleveland Fed President Hammack, San Francisco Fed President Daly, Kansas City Fed President Schmid and Governor Barr. Of those Williams, Hammack and Barr will vote in December.
Nvidia’s Selloff Ripples Down the ‘Circular Web’ of Companies It Backs as Board Weighs Huang’s Future
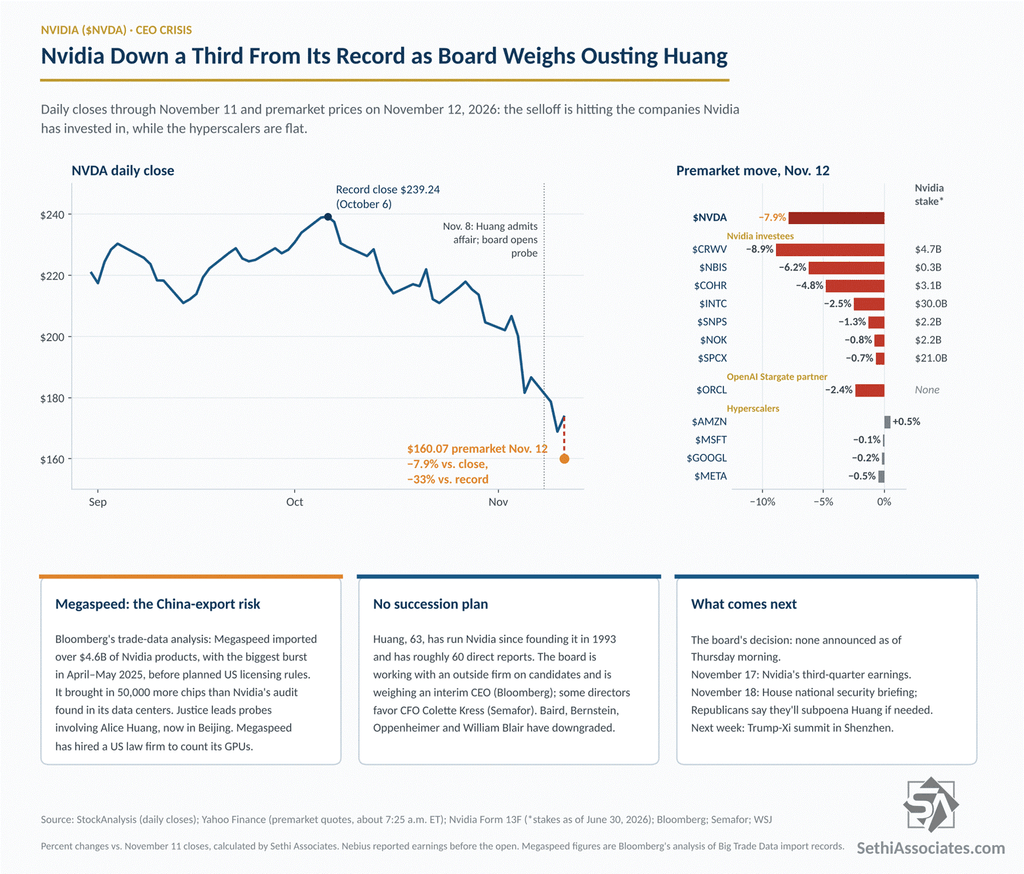
Nvidia (NVDA) is down about 8% premarket to around $160 after The Wall Street Journal reported Wednesday evening that the board is preparing to oust CEO Jensen Huang. The board met late Wednesday, but as of this morning it hasn’t announced a decision, per Bloomberg’s live blog. At $160, the stock is down a third from its October 6 record close of $239.24, erasing Wednesday’s 2.9% bounce and then some.
Bloomberg reports the board is working with an outside firm on candidates and weighing an interim CEO, and, citing Semafor, that some directors favor CFO Colette Kress. Wall Street is stepping back: Baird, Bernstein, Oppenheimer and William Blair have all downgraded the stock this week, and Morgan Stanley dropped it as a top pick (Bloomberg).
The Selloff Is Hitting Nvidia’s Investees, Not Its Biggest Customers
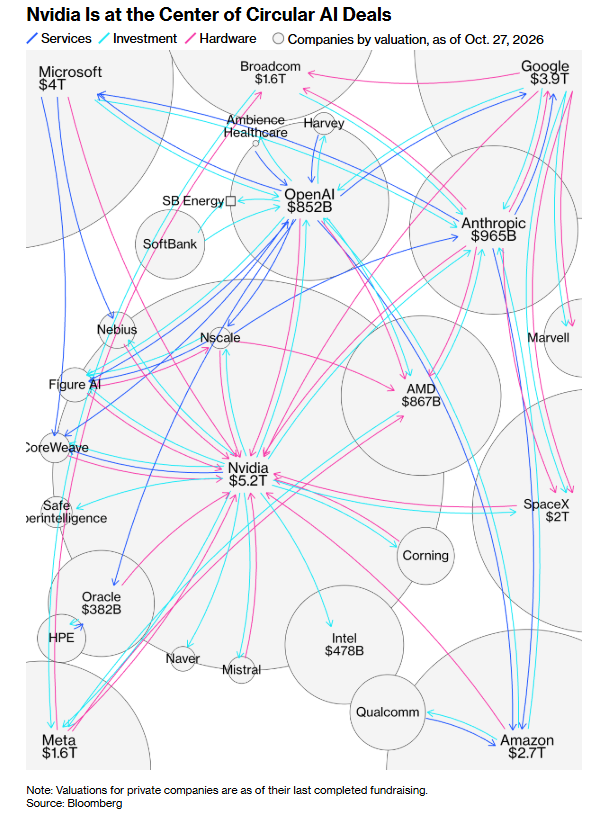
A telling signal is who’s falling with Nvidia: the circular web of companies it funds that in turn buy its chips. All seven of Nvidia’s major public stakes, per its latest 13F filing, are lower premarket: CoreWeave (CRWV) down 9.7%, Nebius (NBIS) 9.2%, Coherent (COHR) 4.9%, Intel (INTC) 3.0%, Synopsys (SNPS) 1.3%, Nokia (NOK) 1.3% and SpaceX (SPCX) 0.6%. Oracle (ORCL), tied in through OpenAI’s Stargate project rather than an Nvidia stake, is off 2.8%.
Meanwhile, the hyperscalers that buy the bulk of Nvidia’s chips are flat: Amazon (AMZN) +0.2%, Microsoft (MSFT) −0.1%, Alphabet (GOOGL) −0.2% and Meta (META) −0.6%. Rivals Advanced Micro Devices (AMD) and Broadcom (AVGO) are higher, as investors bet they could pick up business (Bloomberg).
Two caveats: CoreWeave jumped nearly 25% Wednesday on strong results (more on that here), so it’s only giving back part of that gain, and Nebius reported third-quarter results this morning.
Washington and Megaspeed
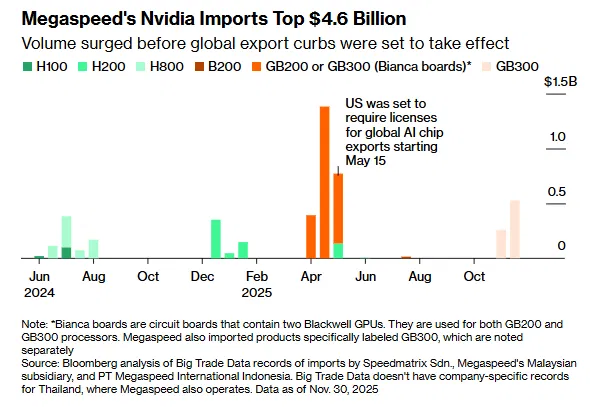
The bigger long-term issue is national security. Huang has admitted an affair with Alice Huang (no relation), a former executive at Megaspeed, a Singapore-based Nvidia cloud partner, whom U.S. officials reportedly suspect of working for Chinese intelligence. Bloomberg’s analysis of trade records shows Megaspeed imported more than $4.6 billion of Nvidia products and brought in 50,000 more chips than Nvidia’s own audit found in its data centers. Overnight, Megaspeed said it had hired a U.S. law firm to count its GPUs and review its export compliance, and Bloomberg reports Alice Huang has resurfaced in Beijing.
Bloomberg
On Capitol Hill, House China committee chair John Moolenaar and House Foreign Affairs chair Brian Mast say they’ll likely subpoena Huang if he doesn’t agree to a closed-door briefing. Sen. Kevin Cramer said Huang should resign, and Sens. Elizabeth Warren and Chris Coons have asked the administration to preserve all records on Nvidia chip exports. Bloomberg notes the scandal also complicates next week’s Trump-Xi summit in Shenzhen.
Strong Demand
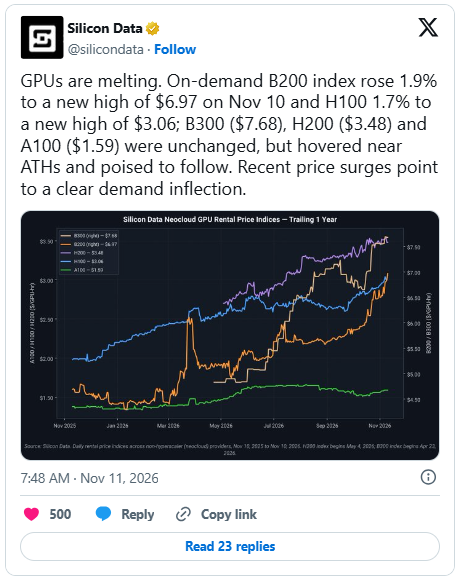
Whatever happens with Huang, though, there remains fierce demand for Nvidia’s products. November 10, at $6.97 and $3.06 an hour. The B300 and H200 are hovering just below theirs, and the H100 is up roughly 50% from a year ago. That comes on top of CoreWeave saying this week it has 10x as much qualified demand as capacity through 2027, showing the market for Nvidia’s chips going into this was as tight as it’s been.
It also matters for the circular-financing worry: rental rates are what back the GPU-collateralized loans to the neoclouds, so firm prices mean that collateral is holding up for now at least.
What to Watch
A quick decision that names an insider such as Kress would signal continuity, but either way the stock is likely to stay under pressure without a successor who was groomed for the job.. ClearBridge’s Michael Feldman warned of a shift from “a Jensen premium to an execution discount” (Bloomberg). Nvidia will report third-quarter results on November 17, the day before Huang is due before House national security committees. For CoreWeave, Nebius and the rest of the companies Nvidia has backed, the question is whether Nvidia keeps writing checks under new leadership.
More on TheStreet Pro
Rev Shark argues the bigger risk is the financing system Huang built, from the OpenAI commitments to the $500 billion customer-financing plan (Nvidia’s Problem Is Bigger Than Its CEO).
Conversation 0 Comments
One ongoing discussion across all days. Everyone can read; sign in to take part.
Your voice matters. Discussions are moderated for civility. Read our guidelines .
Log in to join the conversation