Market updates and conversation from TheStreet Pro team. Follow the latest and join the conversation below.
Stock Market Today: November 10, 2026
Newest first · All times Eastern · 3 updates
DATE:
By Neil Sethi
Foreign Demand for U.S. Treasury Auctions Remains Tepid as 3-Year Tails
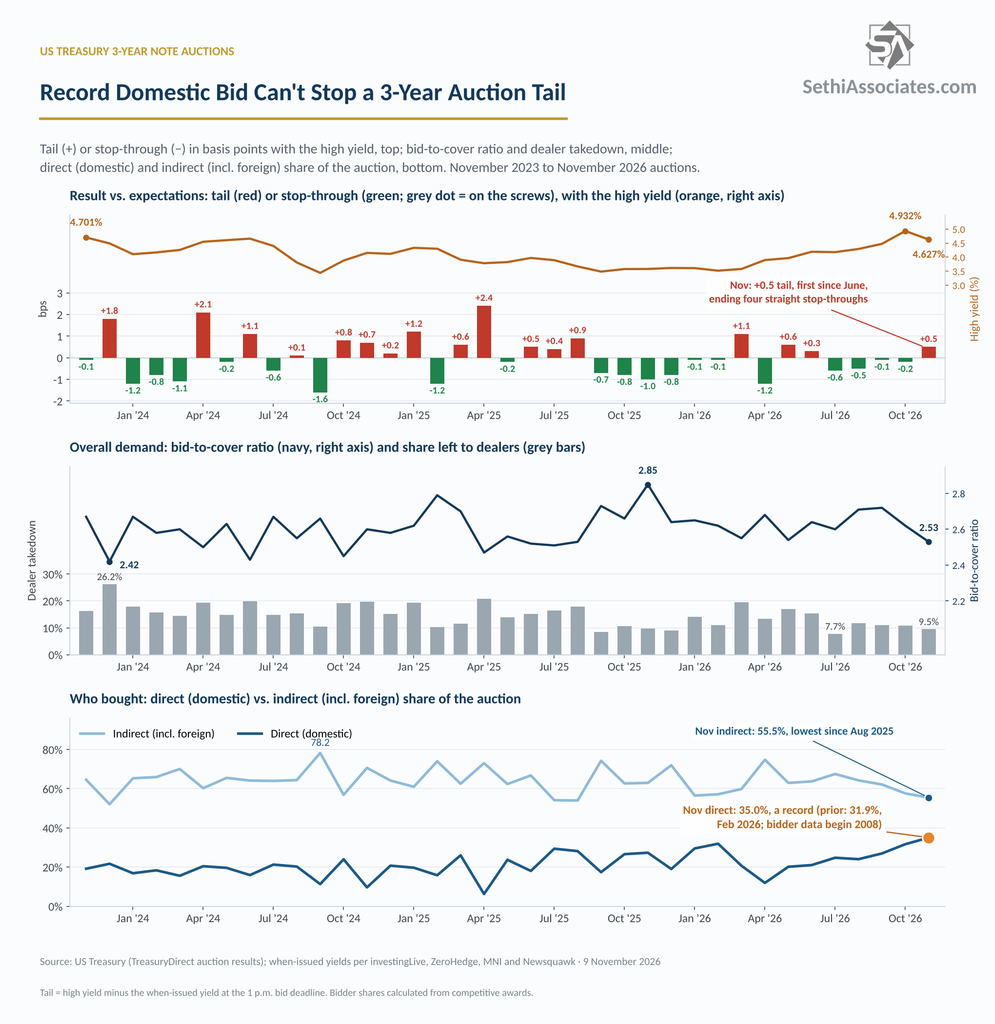
Monday’s $58 billion 3-year Treasury auction, the first of this week’s three coupon sales (more than one year in maturity), tailed (yield above expectations) for the first time since June. That ended a run of four straight stop-throughs (yield below expectations). That was even as direct (domestic) bidders took a record share, not enough to offset softer demand from indirect bidders, a group that includes foreign buyers.
The auction cleared at 4.627%, down from 4.932% in October (the highest since May 2006). That was 0.5 basis points above the 4.622% when-issued yield at the bid deadline, and compares with an average stop-through of 0.1 basis points over the prior six auctions.
Looking at the rest of the metrics:
–Overall demand (bid-to-cover) fell to 2.53, the lowest since August 2025, from 2.62 in October and below the six-month average of 2.64.
–Indirect bidders (which include foreign buyers) slipped to 55.5%, the lowest since August 2025, from 57.6% in October and well below the six-month average of 63.0%.
–Direct (domestic) bidders rose to 35.0%, the highest in Treasury data going back to 2008 (topping 31.9% in February), from 31.7% in October and well above the six-month average of 24.8%.
-That left dealers with 9.5%, the lowest since July, down from 10.7% in October and below the six-month average of 12.2%.
It’s the same story as the 2-year, 5-year and 7-year auctions two weeks ago: domestic buyers took an outsized share while the indirect bid stayed below average. That kept dealers’ share low, but softer overall demand still left a small tail.
The 10-year follows this afternoon and the 30-year Thursday.
Fed’s Waller Floats a Half-Point Hike if CPI Runs Hot
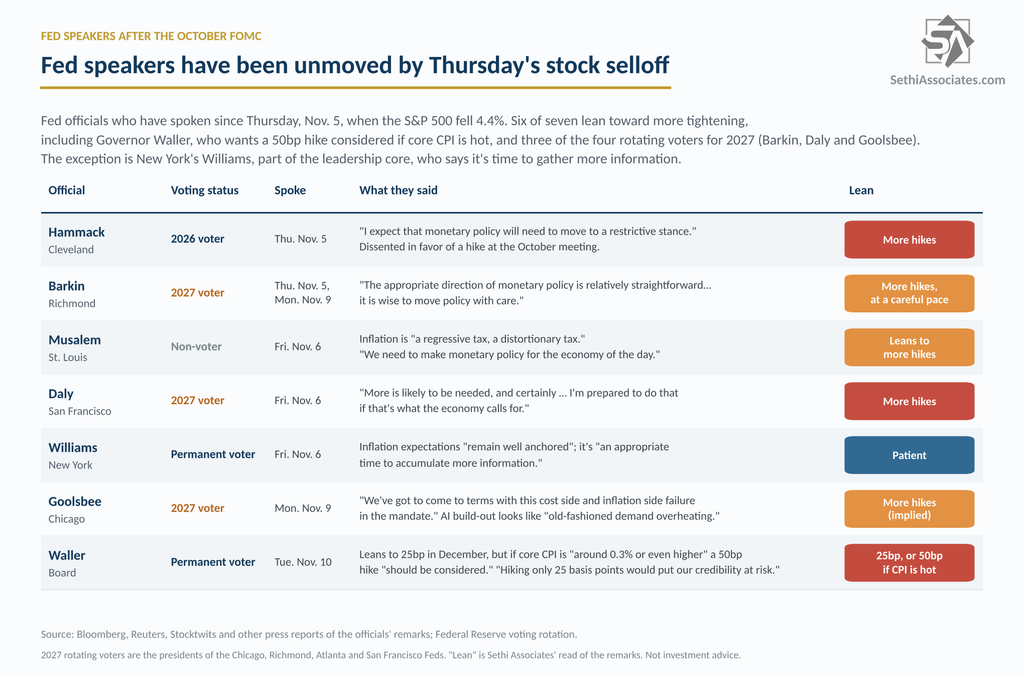
Also from the Week Ahead (The Week Ahead: CPI and Equity Flows Test a Shaken Market), I noted the Fed speakers we heard from during and after Thursday’s selloff, which included Cleveland’s Hammack, Richmond’s Barkin, San Francisco’s Daly, and New York’s Williams, were unmoved by the equity declines, with none mentioning it, instead reiterating their views that inflation remains too high.
Monday added Chicago Fed President Austan Goolsbee, a 2027 voter, to the mix.
“We’ve got to come to terms with this cost side and inflation side failure in the mandate,” Goolsbee said Monday at a Leadership Greater Chicago event, according to Bloomberg. With the labor market and growth stable, he said “the big problem has all been on the inflation side,” and “once it gets overheated, it’s extremely painful to get rid of.”
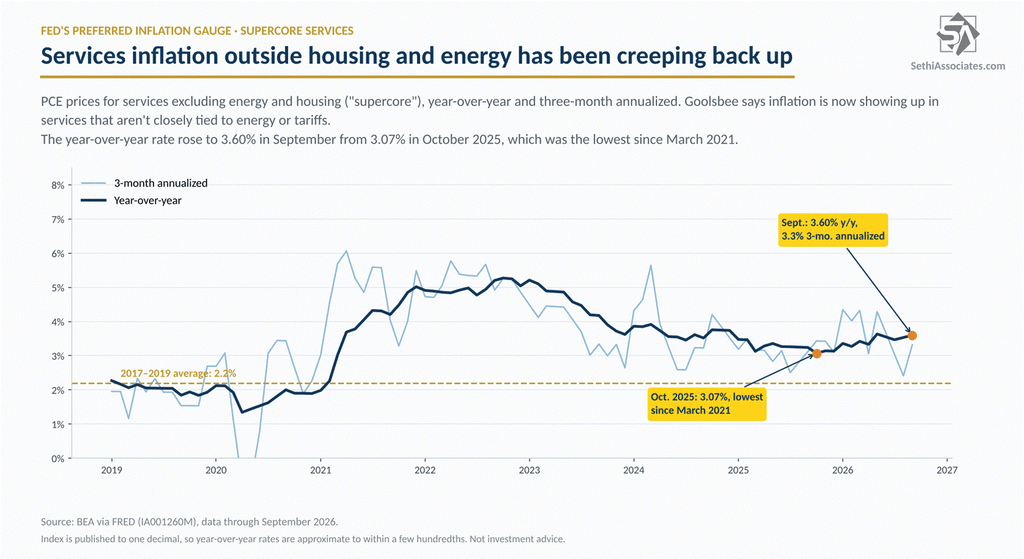
I thought I’d elaborate on a couple of points. First, he says inflation is now showing up in services that aren’t closely tied to energy or tariffs. “Supply shocks are supposed to go away,” he said. “What we’re grappling with is why hasn’t it gone away sooner?” “The PCE data from September back this up, and it’s something to watch in today’s CPI. “Supercore” services inflation (excluding energy and housing) rose to 3.60% year-over-year in September from 3.07% in October 2025, which was the lowest since March 2021.
Second, not only did Goolsbee not mention the potential issues with the AI buildout, he went the other way. “This stuff with the AI data center buildout is, to my eye, starting to look more just like old-fashioned demand overheating,” he said, citing rising costs for land, electricity, chips and construction, and trouble hiring skilled workers like HVAC technicians, per Stocktwits. He also said AI could ultimately mean “long-run deflation,” but anticipation of those gains “can lead to inflation right now,” as rising equity valuations encourage spending, the wealth effect I noted Sunday. “The bigger the hype, the more nervous I am that we’re going to overheat what the economy is capable of in the next six months,” he said, adding, “I’m not saying that it’s a bubble, but it’s certainly almost unprecedented levels of physical investment.”
As noted Sunday, that cuts against how the market has been trading, with AI weakness priced as a reason for fewer hikes. Instead the hawks continue to see AI spending as part of the inflation problem.
Barkin also spoke again Monday, more explicitly talking down risks to the AI buildout. “It’s a big country,” he said. “If they need to build data centers, I would imagine they’ll find some county that wants to.” He said more companies feel pressure to pass on “broad-based” costs, from fuel to chips to health insurance. That said he was more in the Williams camp on pace. “The appropriate direction of monetary policy is relatively straightforward,” he said. “However, risks to the demand outlook remain easy to envision. Because of that, it is wise to move policy with care.”
That puts three of the four 2027 rotating voters (Goolsbee, Barkin and Daly) on record leaning toward more tightening.
The fourth is the Atlanta Fed, which has not named its replacement for Raphael Bostic, who retired when his term ended February 28, 2026. Cheryl Venable, the bank’s first vice president and chief operating officer, has been interim president since March 1.
Then came this morning Fed Governor Christopher Waller, a permanent voter and a leading voice at the Fed, who took it a step further Tuesday morning. He said that if October inflation improves, as he expects, “I am leaning toward supporting an increase in our policy rate of 25 basis points.” But if core CPI comes in “around 0.3% or even higher,” like the past two months, “I believe a 50 basis point hike in the policy rate should be considered at the December meeting,” adding, “Hiking only 25 basis points would put our credibility at risk, a risk I am not eager to take.”
He also said the Fed should “at a minimum, probably take back the three insurance cuts that we put in last year,” which would mean getting back to 4.25%–4.5%, two more quarter-point hikes from the current 3.75%–4% range, and that policy hasn’t been “nearly as restrictive as I thought it was,” according to Bloomberg.
That said he also added in a Q&A the Fed does not want to “slam the economy down.”
“It’s not that we’re going to jack up the policy rate 150 basis points or 200 basis points,” he said. “We are looking forward and saying we need to do something; at a minimum, probably take back the three insurance cuts that we put in last year.”
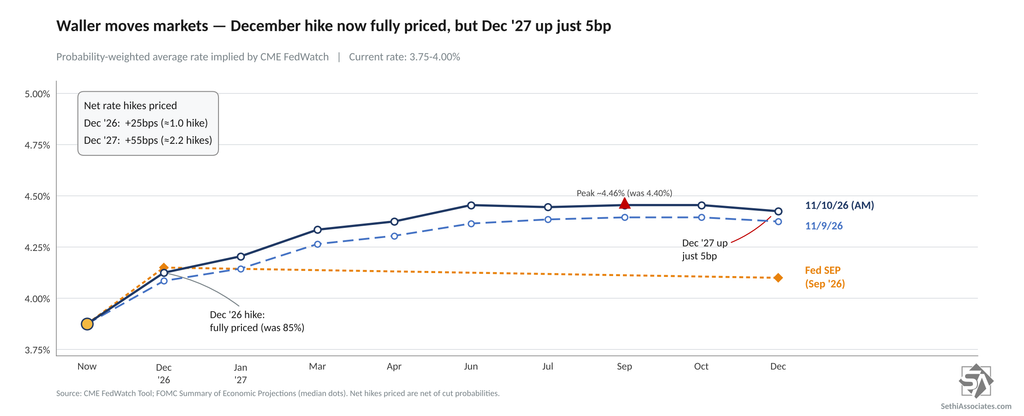
And with the AI trade rebounding Monday, the correlation I noted Sunday between equity moves and hike pricing remained intact. CME FedWatch odds of a December hike rose to 85% Monday from 77% Friday, but Waller extended that move, so they are now pricing a 100% chance of a December hike (1.4% chance of a 50 basis point hike). Down the line, though, less change with just 5 basis points added to December 2027 (55 basis points).
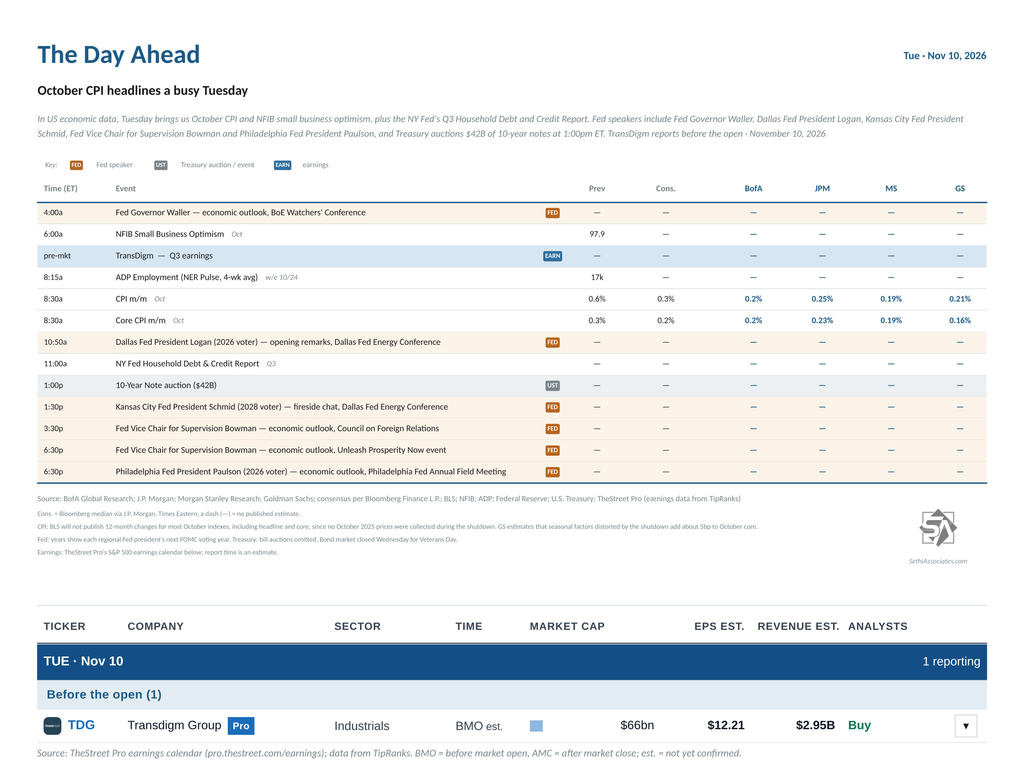
The Day Ahead: October CPI Headlines a Busy Tuesday
In US economic data, Tuesday brings us October CPI and NFIB small business optimism, plus the NY Fed’s Q3 Household Debt and Credit Report. Note that BLS won’t publish 12-month changes for most CPI indexes, including headline and core, since no October 2025 prices were collected during the shutdown. For a CPI preview, see CPI Preview: Cooler, but Probably Not Enough to Stop a December Hike.
Fed speakers include Fed Governor Waller, Dallas Fed President Logan (2026 voter), Kansas City Fed President Schmid (2028 voter), Fed Vice Chair for Supervision Bowman and Philadelphia Fed President Paulson (2026 voter).
Non-Bill (>1yr in maturity) US Treasury auctions bring us a $42B 10-year note sale at 1:00pm ET.
But outside the S&P 500 a lot of focus will be on CoreWeave (CRWV). We’ll also hear from Petrobras (PBR), Sea (SE), Vodafone (VOD), Venture Global (VG), and On Holding (ONON).
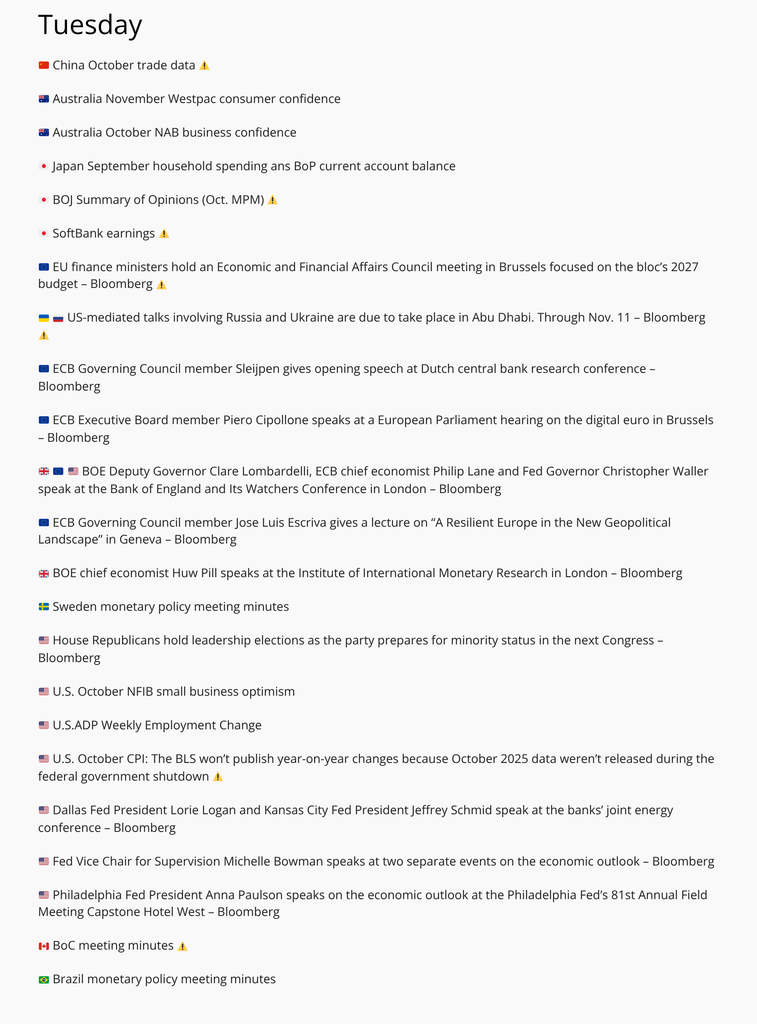
Ex-US highlights include China’s October trade balance, Japan’s October Economy Watchers survey and September household spending, and October CPI in Norway and Denmark. The Bank of Canada releases the Summary of Deliberations from its last meeting (1:30pm ET) and Brazil’s central bank its Copom minutes, while the ECB’s Cipollone, Lane and Escriva and the BoE’s Lombardelli and Pill speak. US-mediated talks between Russia and Ukraine are expected Tuesday and Wednesday.
Conversation 0 Comments
One ongoing discussion across all days. Everyone can read; sign in to take part.
Your voice matters. Discussions are moderated for civility. Read our guidelines .
Log in to join the conversation