CoreWeave Posts Embarrassment Even as Revenues Explode
The beleaguered neocloud name looks like a trade.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Maybe you are off on Wednesday. Maybe you’re not focused on the markets on this Veterans Day. If you are, you’ve noticed the run being made by the beleaguered neocloud name CoreWeave (CRWV).
CoreWeave went to the tape on Tuesday night with the firm’s fiscal third quarter financial results. CoreWeave lost money, but a lot less than expected. Revenues exploded higher.
The firm had been the poster child for the AI trade and all that had been going wrong with that trade of late. Out of control capex spending coupled with a runaway debt load load can be a dangerous combination. The shares are up more than 25% as we approach lunchtime on Wednesday, after closing 65% off of the stock’s high for 2026 back in early May.
For the period ended September 30, CoreWeave posted a GAAP EPS of -$1.27 on revenue of $3.661 billion. While that bottom-line print may not look pretty, these results beat Wall Street decisively across the board. In addition, that sales print was good for year-over-year growth of 169.1%. The firm claims that its “revenue backlog” ended the quarter at $132.5 billion.
Now, I’ve heard of the “order” backlog. I’ve heard of “remaining performance obligations.” What is the “revenue” backlog? CoreWeave explained that this is “remaining performance obligations, plus other amounts we estimate will be recognized as revenue in future periods under committed customer contracts, in each case, subject to the satisfaction of delivery and availability of service requirements.”
Oh. OK. I like that “we estimate” part.
It is key to understand that the firm had increased prices across its portfolio of offerings by roughly 25% in July, followed by another 10% price increase later in the quarter. Management indicated on Tuesday night that prices continued to rise in the current quarter, with increases more than offsetting cost increases. Pricing power is important. in this environment. Management also indicated that demand for its computing capacity was about 10 times available capacity through 2027, while demand for 2028 was several times greater than capacity that can be brought to market.
The CEO
Co-founder, chair and CEO Michael Intrator commented in the press release:
“This was a breakout quarter for CoreWeave, with revenue increasing by more than $1 billion sequentially and adjusted operating margins reaching double digits a quarter ahead of plan. Our growth is supported by multiple sources of funding, including financing backed by customer contracts, operating cash flow, and approximately $9 billion in customer prepayments and deposits expected in the next three months alone. That financial flexibility positions us to keep delivering the infrastructure and software customers need to build, run, and scale AI.”
Operations
As revenue grew more than 169% to $3.661 billion, operating expenses increased 163% to $3.454 billion. That left operating income at $207 million, up from $52 million for the year-ago period as operating margin grew from 4% to 6%. After accounting for interest, other income and expenses as well as taxes, the firm’s net income/loss dropped to -$709 million from -$110 million. This took the firm’s GAAP EPS down to -$1.22 from the year-ago comparison of -$0.22. Better than expected? Yes. Losing a lot more money than last year? Yes.
Guidance
CoreWeave raised the firm’s full year revenue guidance to $13 billion to $13.3 billion. Wall Street was looking for $12.9 billion, so that was a beat. The firm also increased its full-year 2026 adjusted operating income guidance to a range of $1.275 billion to $1.375 billion, representing a 26% increase at the midpoint. However, the firm now expects full year 2026 capital expenditures of $37 billion to $39 billion. Prior guidance had been $35 billion to $39 billion. This is as a result of our expectation to deploy infrastructure and deliver it to customers sooner than planned. A negative that could be a positive? Wall Street is taking it that way.
Fundamentals
For the period, CoreWeave generated operating cash flow of $1.975 billion. Out of that number came capex spending of $9.441 billion. This left the firm’s three month “free” cash flow at -$7.466 billion, down from -$1.59 billion for the year-ago comp. The firm is obviously in no position to return capital to shareholders.
Turning to the balance sheet, CoreWeave ended the quarter with a cash position of $5.589 billion. That left current assets at $10.806 billion. Current liabilities add up to $24.389 billion, including short-term debt of $10.572 billion and $2.269 billion in deferred revenue. That leaves the firm with a headline current ratio of 0.44, which is beyond horrendous. Adjusted for those deferred revenues, this ratio rises to 0.48. Still well below anything in my wildest dreams, that I might even consider to be a bare minimum.
Total assets amount to $91.481 billion, almost all of which is tangible. They have that going for them. Total liabilities less equity comes to $87.456 billion. There is long-term debt on the books of $36.301 billion which absolutely dwarfs the firm’s cash position. In fact, the short-term debt dwarfs the firm’s cash position. There are more deferred revenues on the balance sheet not considered to be current in nature. I guess that’s a positive.
Bottom line? In forty years of analyzing balance sheets, I have rarely come across anything this bad. This is one of the worst looking balance sheets I have ever seen. Guess Oracle’s (ORCL) off the hook for now. We have an even worse example of sloppy fundamentals to look at.
Opinion
There are some things to like here. Sales growth is terrific. The guidance is mixed to positive. That said, the firm is losing a lot of money. The cash flow situation is a bonfire, and the balance sheet is “atrocious” at best. I see good reasons to trade this stock.
If I were the kind that invests and does something else occupationally, while paying only peripheral attention, I would not get involved in anything with fundamentals like this. These numbers would be an embarrassment for any legit CFO to put his name on. Yeah, I know he worked at Alphabet (GOOGL) and Amazon (AMZN) and he’s getting paid, but his stomach must churn at night looking at these tables.
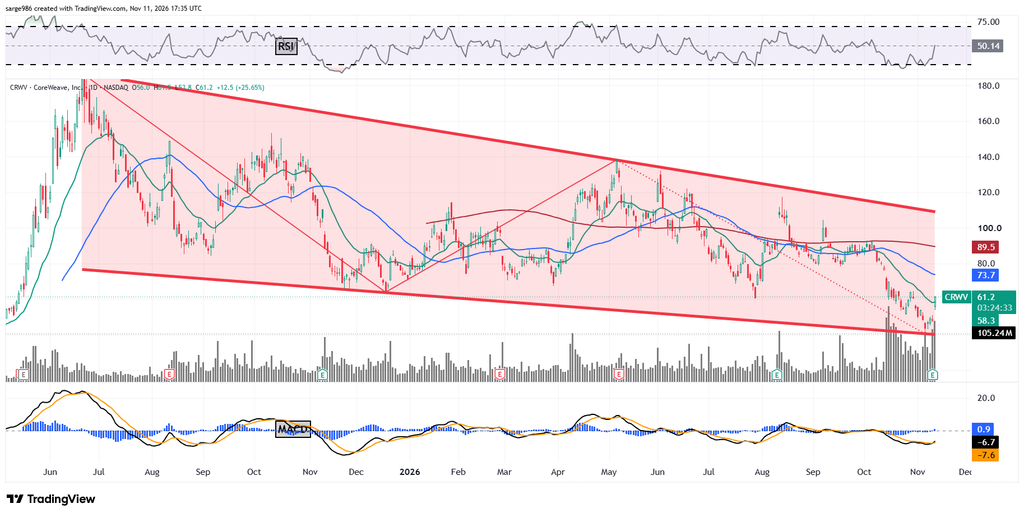
Even with today’s 25% surge, the stock is only trying to take back its 21-day EMA. The real fights are up at the 50-day SMA and 200-day SMA. Those two lines are still a ways off. Taking and holding the lines that professionals watch would impress me. Today’s activity, in my opinion, is a mix of swing trader activity and short covering. Remember, CRWV came into earnings with a short position that amounted to a rough 24% of the entire float.
At the time of publication, Guilfoyle was long AMZN equity.