SpaceX Lights a Fire Under Tech
Blowout SpaceX results lifted a swath of AI names, sending the Nasdaq up over 1%.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Quick Summary
- Tech retook the lead as SpaceX’s blowout quarter revived enthusiasm for the AI trade, lifting a host of associated stocks and sending the Nasdaq up more than 1%.
- The Nasdaq rose 1.1%, the Dow Jones Industrial Average was up 0.7%, the S&P 500 gained 0.6% and the Russell 2000 added 0.2%. Indices slipped off their highs in the afternoon on a report that the U.S. was ordering staff out of embassies across the Persian Gulf, although they recovered much of the dip quickly after the State Department said the order applied only to non-emergency personnel in Saudi Arabia.
- While Tech led, seven of 11 sectors rose. SpaceX (SPCX) jumped nearly 8% after reporting 161% revenue growth, with its AI business growing ninefold. Elon Musk also said SpaceX and Tesla (TSLA) have formed special committees to discuss a merger. Super Micro Computer (SMCI) rose 9.5% on strong results and guidance, the PHLX Semiconductor Index (SOX) gained 2%, and Nvidia (NVDA) rose 2.5%.
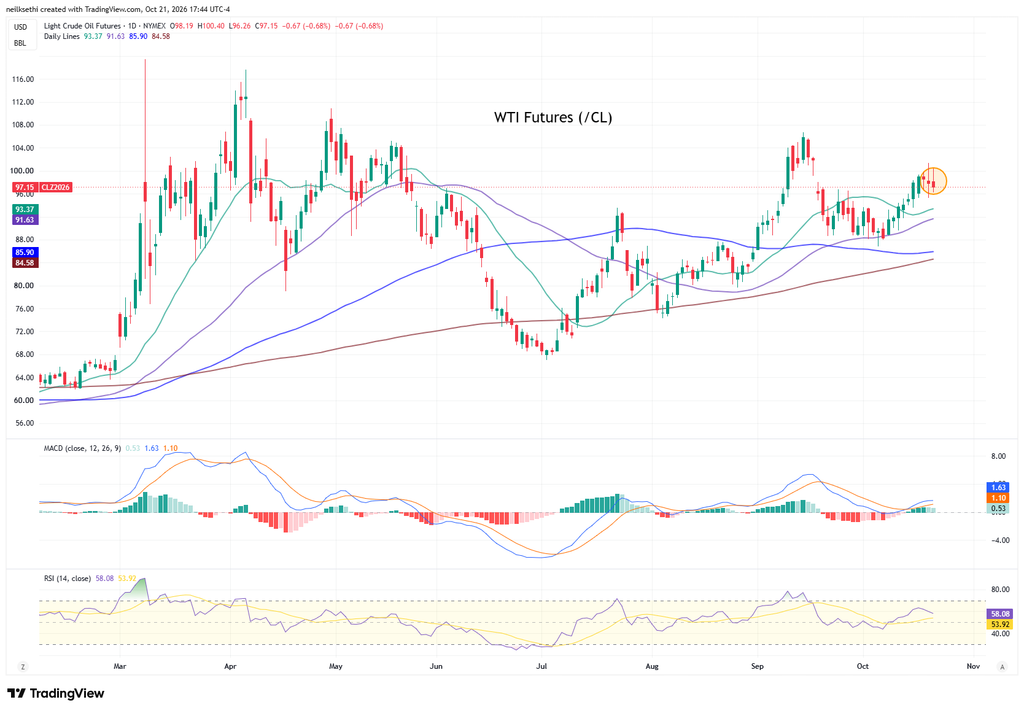
- Treasuries slipped on late selling, with the 2-year and 10-year yields each up 3bp in the cash session, to 4.82% and 5.15%, respectively, although the 10-year yield would soften in the after-hours. December WTI, now the front month, fell about 0.7% to settle near $97.
- Thursday brings weekly jobless claims and earnings from Procter & Gamble (PG), Union Pacific (UNP), Blackstone (BX), Western Digital (WDC), and Lockheed Martin (LMT), among others

Market Commentary
Equities:
- “The big picture is, there’s almost certainly bubbles within this moment in time, and any radical transformation of our economy is generally intertwined with a bubble,” the founder of fund giant Citadel and electronic market maker Citadel Securities said last night. “I just wish I’d kept my Amazon stock from that moment in time,” Griffin told an interviewer at Citadel Securities’ Future of Global Markets conference. “And the internet, which was the great bubble, could it be more a part of our daily life today than it is?”
- “So, does this signal that the worst is over when it comes to the selloff across tech, and in particular chip stocks, seen since the beginning of this month? Maybe,” said David Morrison at Trade Nation. “Certainly, there has been yet another impressive start to the earnings season.”
- “The reality is, nobody knows what the demand is going to be in 12 months,” Altimeter Capital CEO and vociferous AI bull Brad Gerstner told CNBC on Wednesday. “Most of us who are in the game are saying this is accelerating. We’re forecasting that demand is going to accelerate. But of course there’s a distribution of future unknown probabilities.”
- “Despite hedge funds sharply reducing tech exposure, the market isn’t giving up on AI,” said Mark Hackett at Nationwide. “Investors simply want to see the payoff, and SpaceX earnings may be an early sign of that.”
- Investors likely are waiting for Meta and Tesla earnings to “confirm AI buoyancy prior to breaching the critical technical level” of the 50-day moving average said José Torres, Senior Economist at Interactive Brokers, in emailed comments Wednesday. “Such a development would meaningfully strengthen this broad advance if the tech sector can resume its uptrend, and from what’s been communicated so far, all arrows point to accelerating momentum in the coming sessions as we approach the most favorable seasonal period of the year.
Stock and Sector Breakdown:
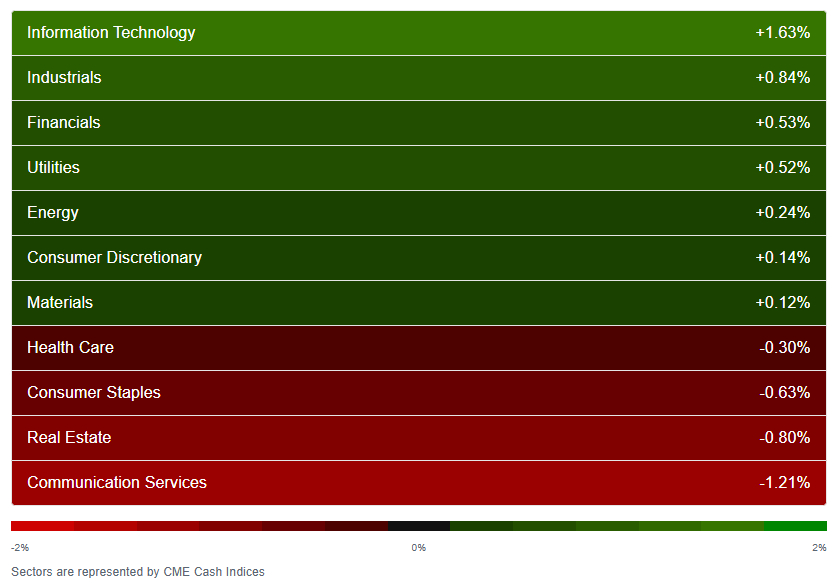
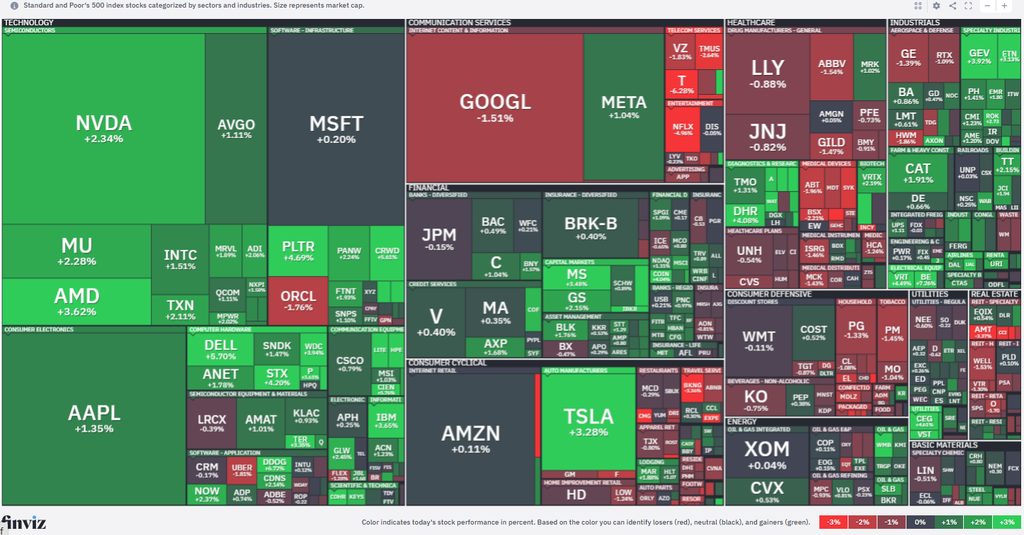
Seven of 11 sectors were higher (down from 9 Tuesday, up from 4 Monday), with another reversal in Tech, which rose to the top of the sector chart, the fourth session of flipping between the top two and bottom two sectors. Tech’s 1.6% gain lifted the S&P 500, more than offsetting the 1.2% loss in the Communications sector, which was weighed down by Netflix (NFLX), telecoms, and Alphabet (GOOG) -1.6%, as discussed in part below.
SpaceX (SPCX) shares were a big winner. For more on the details:
- SpaceX Rises After Earnings
- SpaceX Climbs as Musk Floats Tesla Merger
- Speculative SpaceX Price Target as Tesla Rumor Boosts Stock
SpaceX’s earnings call had less positive knock-on impacts outside of tech, though, as AT&T (T) -6.5% fell despite quarterly earnings that came in better than expected although subscriber growth slowed from the prior quarter, while Verizon (VZ) -2.2% and T-Mobile (TMUS) -2.5% also ended in the red as SpaceX reaffirmed plans to expand its Starlink satellite service beyond broadband and into the wireless market, putting it in more direct competition with established telecom companies, per the WSJ. Starlink Mobile, as the business is called, could ultimately generate “several hundred billion dollars in revenue a year,” Musk told analysts on the earnings call, hinting at other plans that SpaceX has yet to make public.
Tech was also bolstered by early results for the September 30th quarter released by Super Micro Computer (SMCI) +9.5%, the second best performer in the S&P 500. You can read more about that here: More Bullish Tech Headlines
Nvidia (NVDA) +2.5% was another semiconductor winner after announcing agreements with South Korea’s Samsung Electro-Mechanics and U.S.-based semiconductor packaging and test-services provider Amkor Technology (AMKR) +4.8%. Overall the Philadelphia Semiconductor Index (SOX) rose 2.0%, although its technical picture remains weak for now.
Skydance (SKYD) +11% led the S&P 500 after media kingpin John Malone suggested that Skydance might turn to SpaceX for cash, with Skydance looking for between $8 billion and $10 billion from the commercial space operation.
Shares in medical tech firm Charles River Laboratories (CRL) +9.3% jumped on no company specific news, but after peer Thermo Fisher (TMO) raised its fiscal 2026 revenue view to $47.7B-$48.2B from $47.4B-$48.18B.
On the other side, Netflix (NFLX) shares ended the day down over 5% after its earnings, as covered last night on the Stock Market Today page: Netflix Shares Drop After Cutting Sales Forecast.
After the close, we got earnings from Meta (META) and Tesla (TSLA), both of which were initially higher. More here:
- Meta Rises After Raising Guidance and Introducing New Share Class
- Tesla Shares Get Modest Bump After Surprise Positive Cash Flow
- Good News for Tesla and Meta, But Good Enough to Attract New Buyers?
- Will Meta Break Hyperscaler Bond Drought?
However it appears subsequently Tesla has turned lower. I’ll update in the Stock Market Today page in the morning.
We also heard from IBM (IBM) whose shares were up 5% after it announced better than expected sales from its infrastructure unit which services AI buildouts, and Texas Instruments (TXN), the biggest maker of analog and embedded processing chips, which gave a strong revenue forecast for the current period, lifted by demand from automotive and industrial customers, both per Bloomberg. Shares of TXN were little changed, but it is up 64% this year. Less positive was the reaction to chipmaker Lam Research (LRCX) with shares falling 5%, but that looks to be a victim of high expectations as the headline numbers all appeared to beat.
The number of large SPX winners (up over 3%) edged down to ~40 from ~45 but up from 17 Monday. The number of large losers (down over 3%) edged up to 12 from 8. As mentioned previously, both of these metrics have been very (extremely?) subdued since the start of August, rarely getting above 50 and only twice above 100.
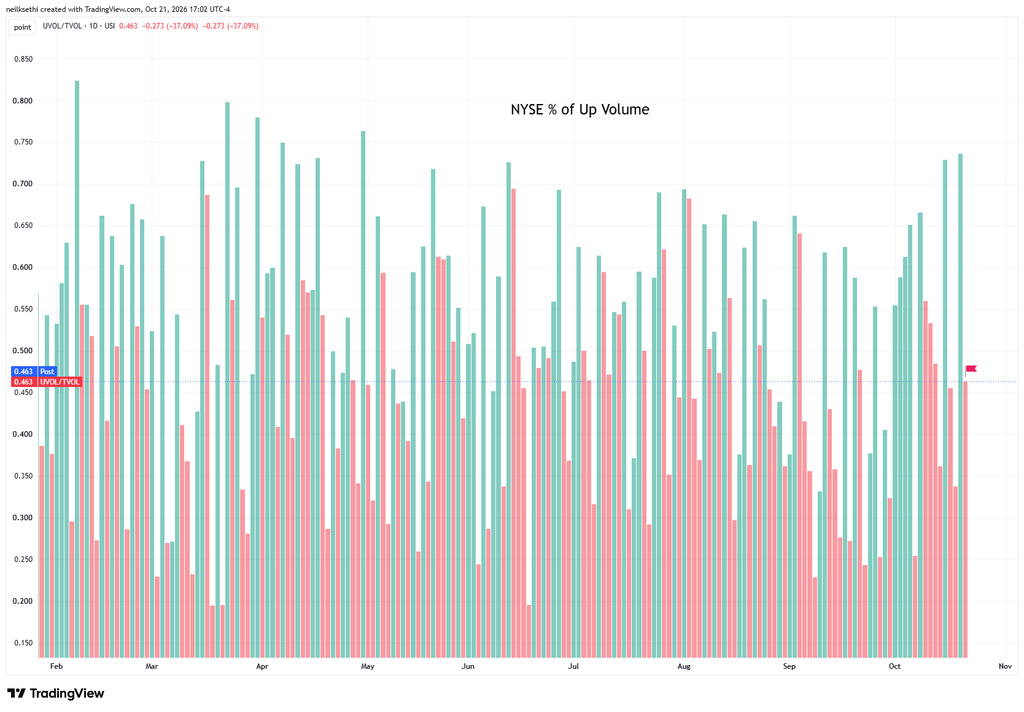
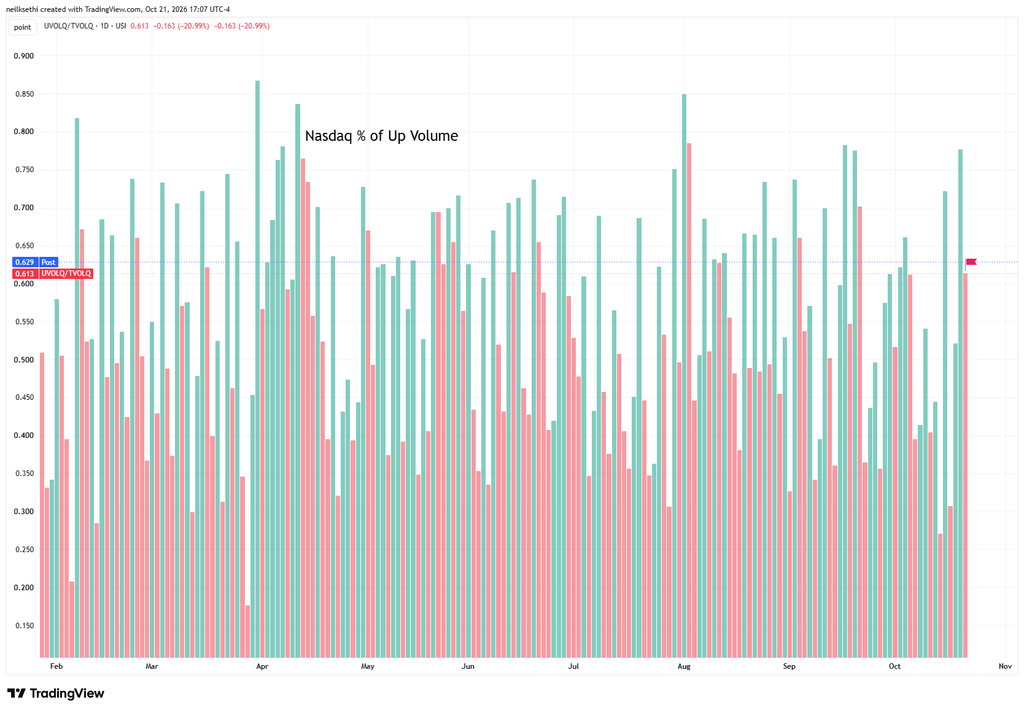
Remember that great breadth I told you about yesterday? Well we got the opposite today. Very weak on the NYSE at 46.3% from 73.6% Tuesday even as the gain extended to +1.18% from +0.93%, and the Nasdaq decelerated to 61.3% from 74.6% even as the gain jumped to +1.05% from a loss of 0.02%.
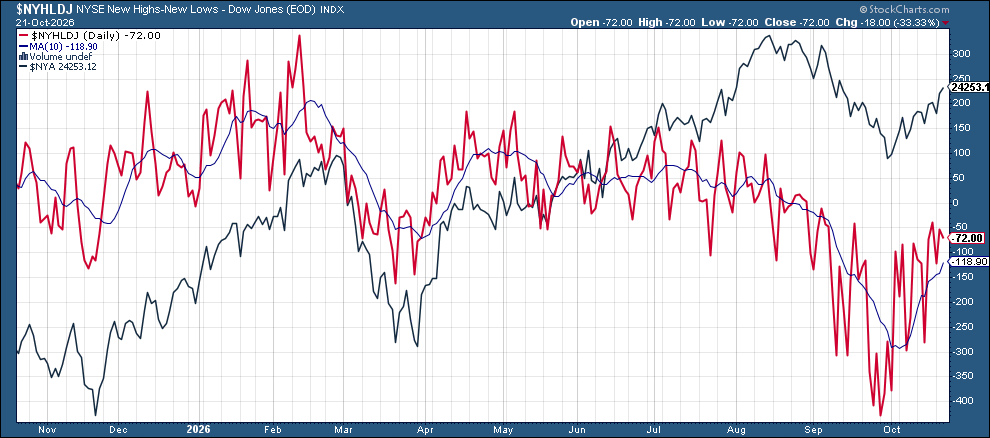
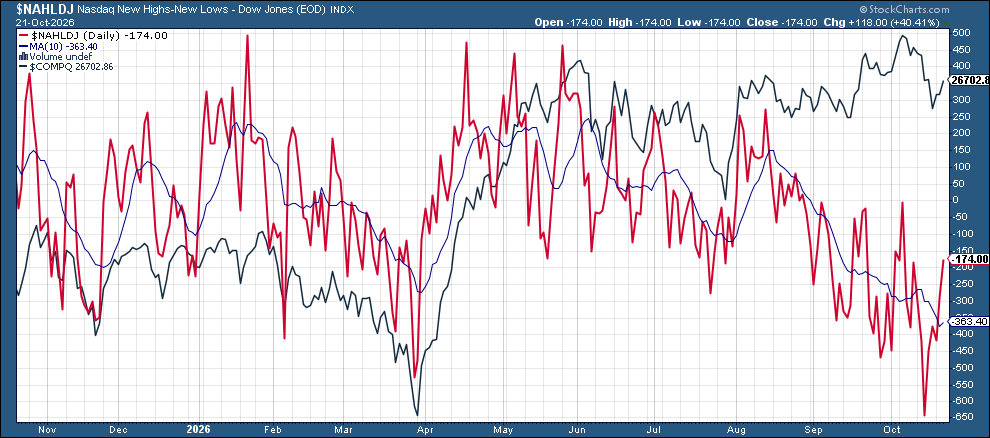
New 52-week highs minus lows stayed negative on both the NYSE at -72 and the Nasdaq -174, though the 38th straight session of new lows outnumbering new highs on the Nasdaq, the longest such streak since the 43-day stretch that ended April 22, 2025.
Some other stock-specific commentary from TheStreet Pro:
- Chris Versace – CyberCartel Used Claude and Grok to Attack Banks
- Stephen Guilfoyle – New Planet Labs Price Target After SpaceX Satellite Launch
- James “Rev Shark” DePorre – SpaceX Beats, but the Test Is Whether It Can Build on the Gains
- Bob Lang –
- Ed Ponsi – ‘The Google of China’ Suddenly Looks Like a Great Deal
- Bret Jensen – My Portfolio Is Getting Some ‘Energy’
- Bob Byrne – The AI Selloff Looks Like a Bear Trap. Follow the Bottleneck Instead.
A Look At The Charts
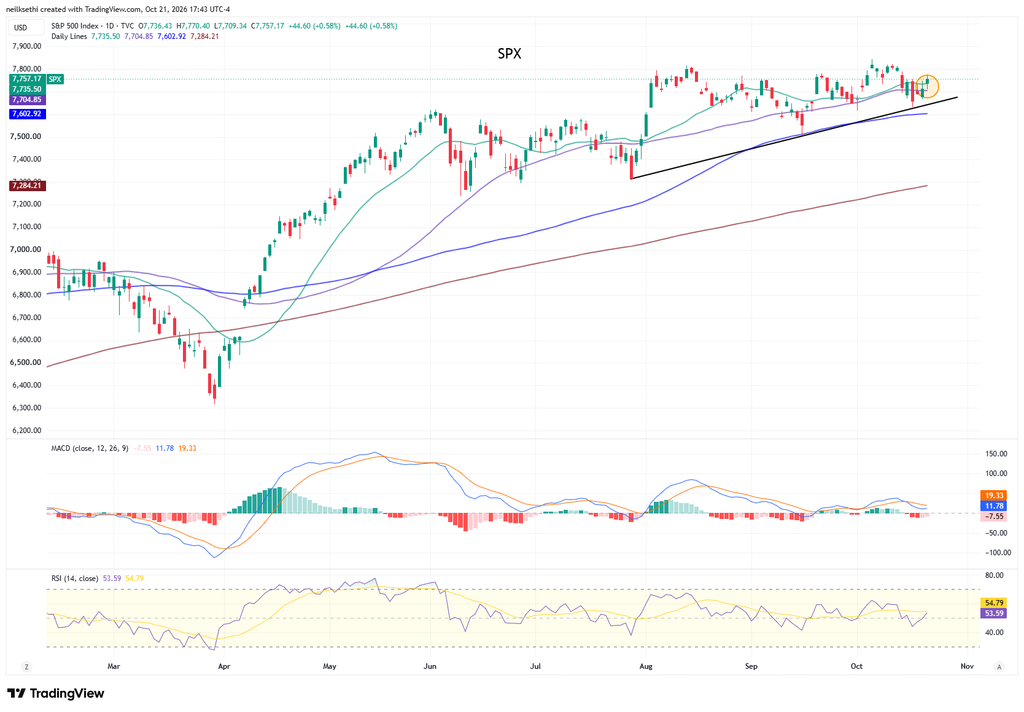
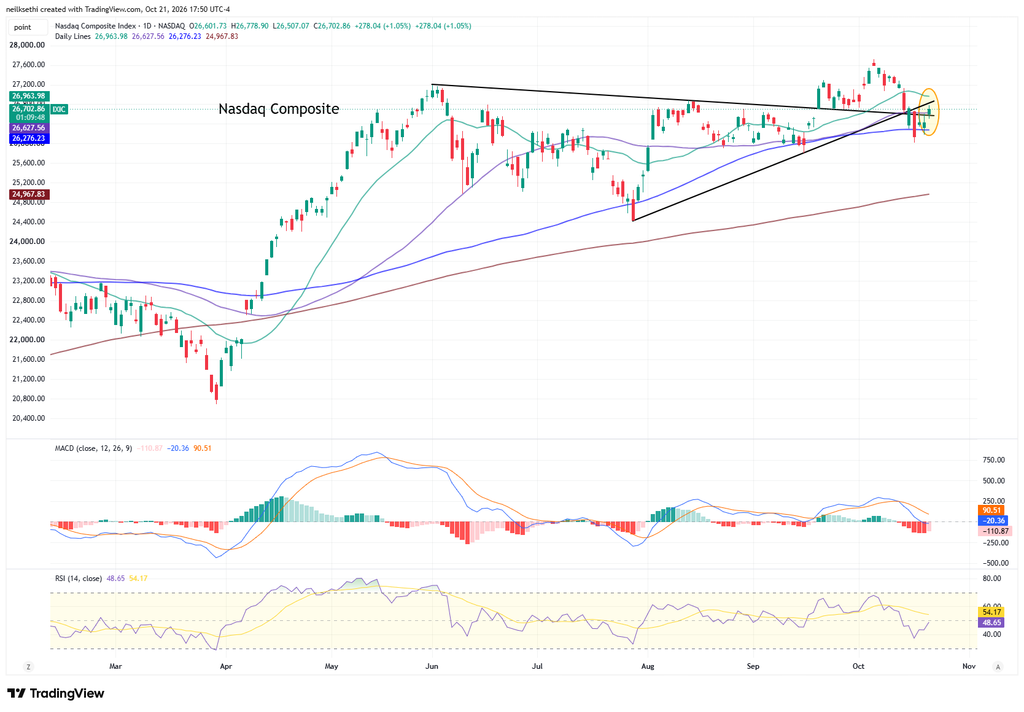
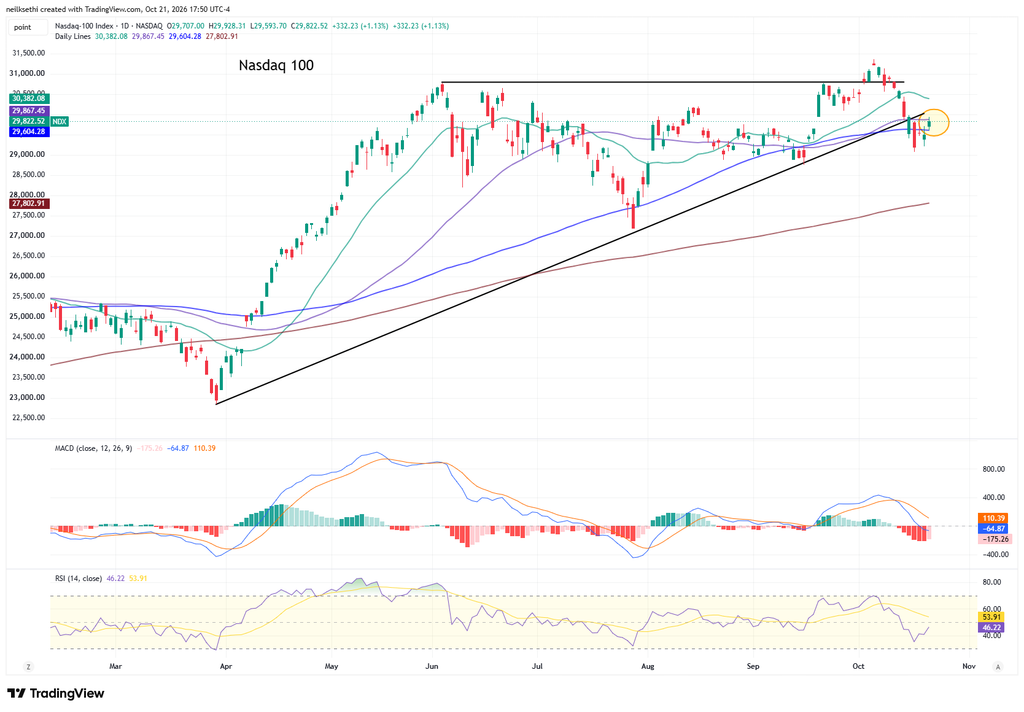
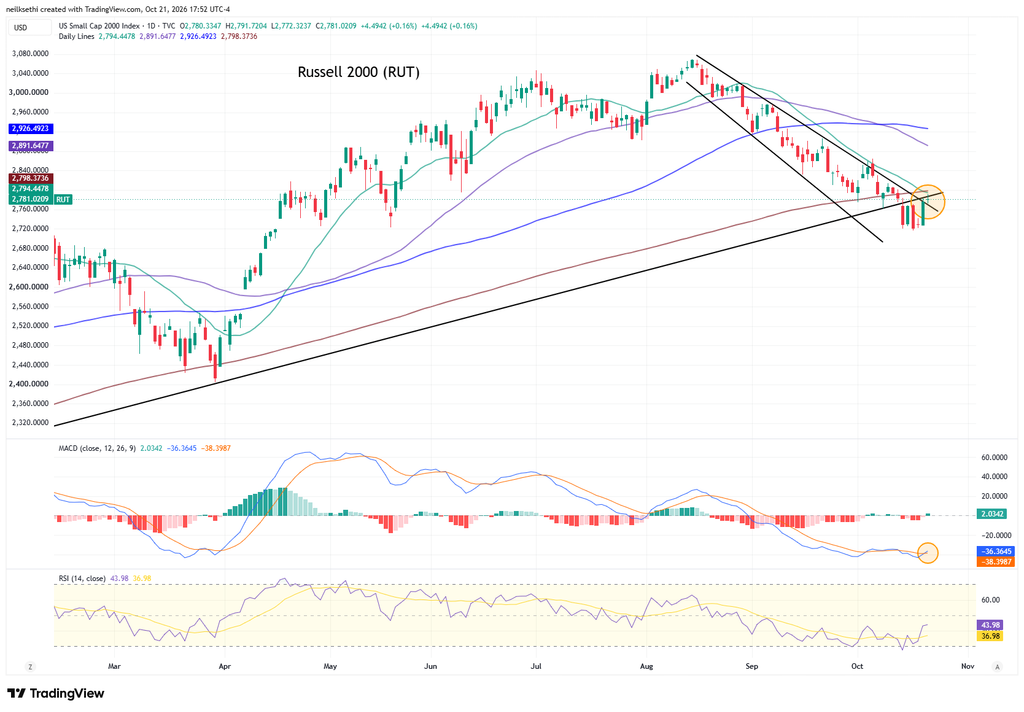
Note on all charts the colored lines are moving averages (the average price over the lookback period — days on the daily charts, weeks on the weekly charts):
20 = green
50 = purple
100 = blue
200 = brownException is monthly charts where blue is 10-month moving average and brown is 20-month moving average.
MACD = Moving average convergence/divergence line, a measure of momentum that compares longer term and shorter term momentum to gauge if a move is strengthening or weakening. This is probably my favorite individual indicator.
RSI = Relative Strength Index (basically what it sounds like) = measures the strength of the move comparing gains to losses over the given lookback window (I use the standard 14 periods).
SPX continued its bounce now conclusively through its 50-DMA. As noted last week the daily MACD and RSI had slipped negative but they’re improving.
Nasdaq Composite also made it over its 50-DMA. As I noted last week, it has a MACD sell signal and the RSI has fallen under 50, but both are improving.
The Nasdaq-100 (QQQ) made it back to its 50-DMA. Per my message from Monday, if it can make it over, I’ll get back in, although smaller position size until we get confirmation from daily MACD and RSI.
The Russell 2000 (IWM) a weaker session but it took it above the channel line, although still below its 200-DMA. The MACD though crossed to “cover shorts” positioning and the RSI is moving back towards 50, so if it gets over the 200-DMA I’ll get back in.
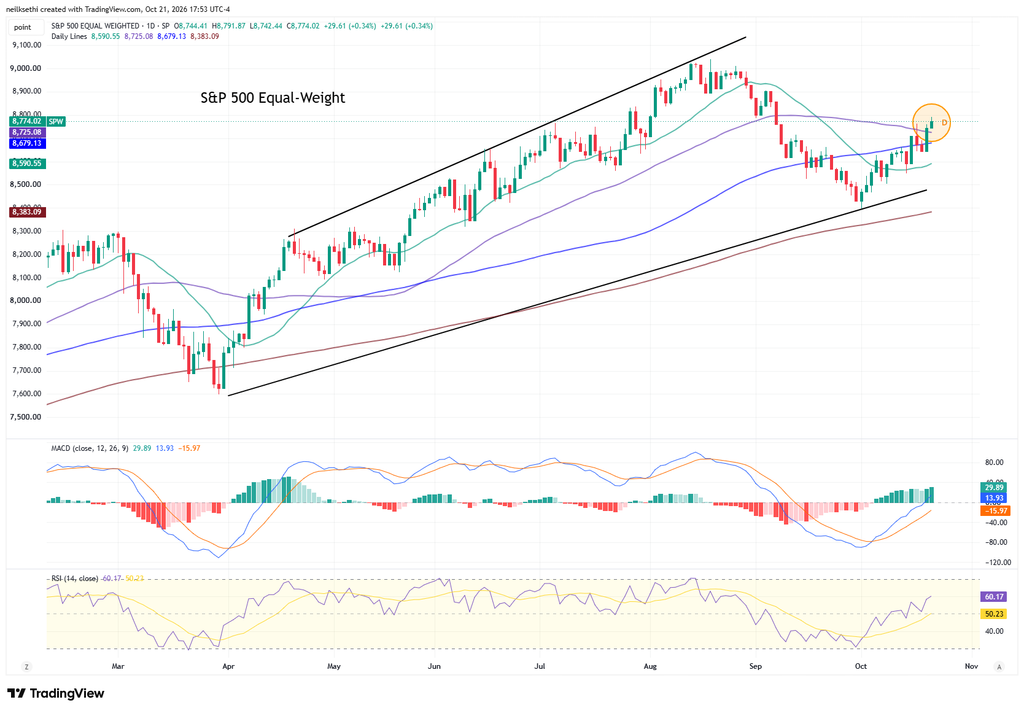
The equal-weighted SPX (RSP) which I have said has been “able to hold up better” the past couple of weeks extended further above its 50-DMA, so I did go ahead and add to my position. It continues to have by far the best technical setup.
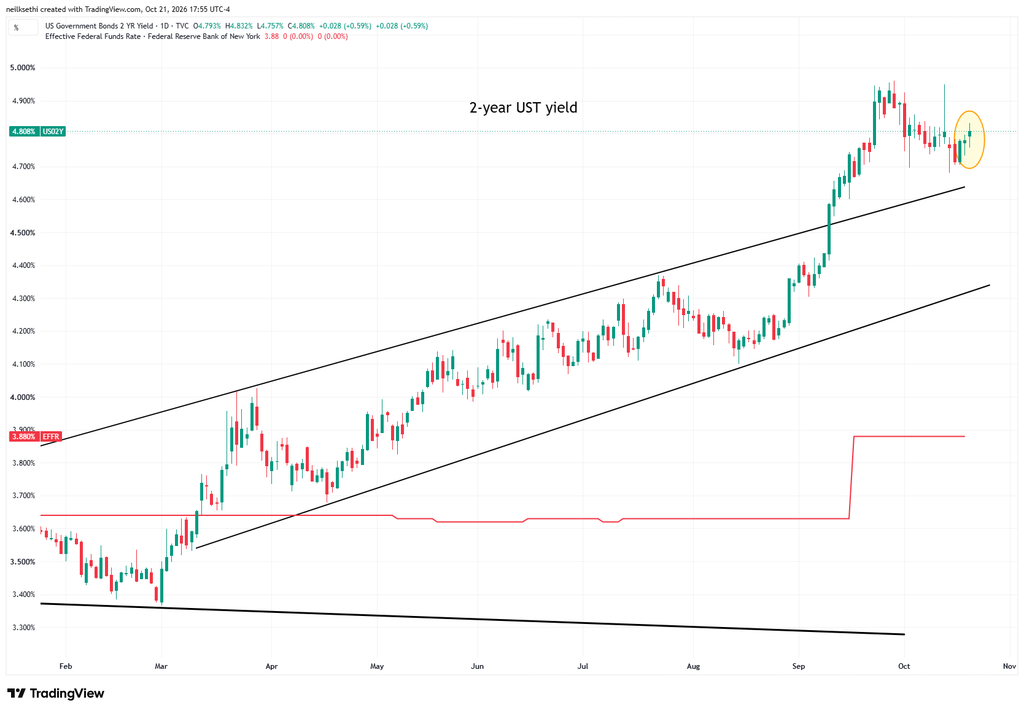
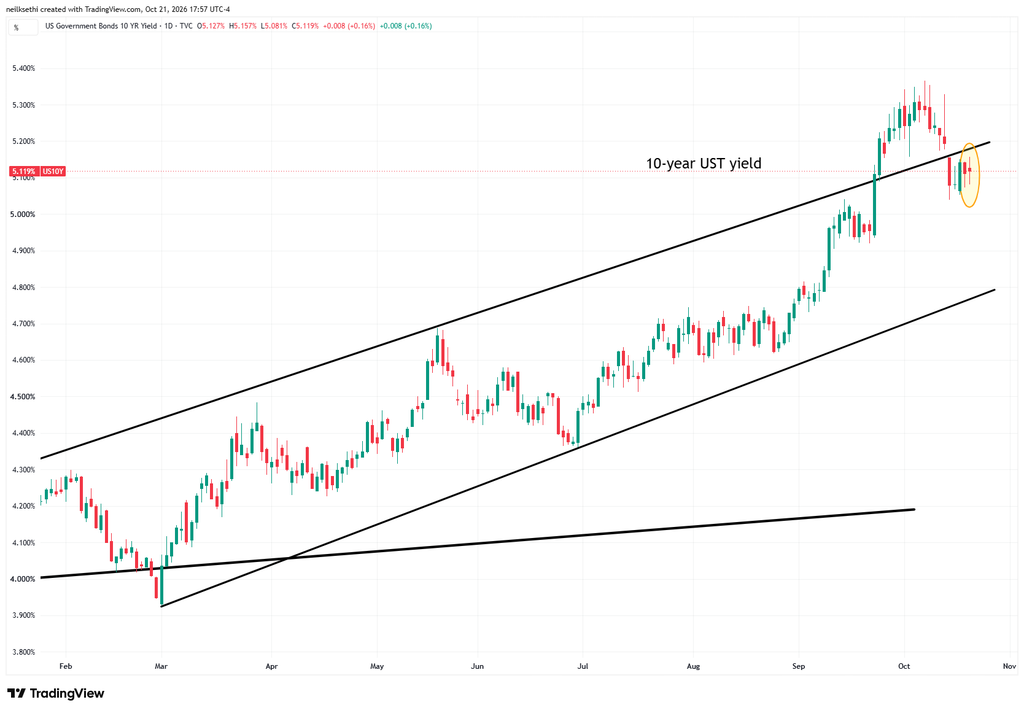
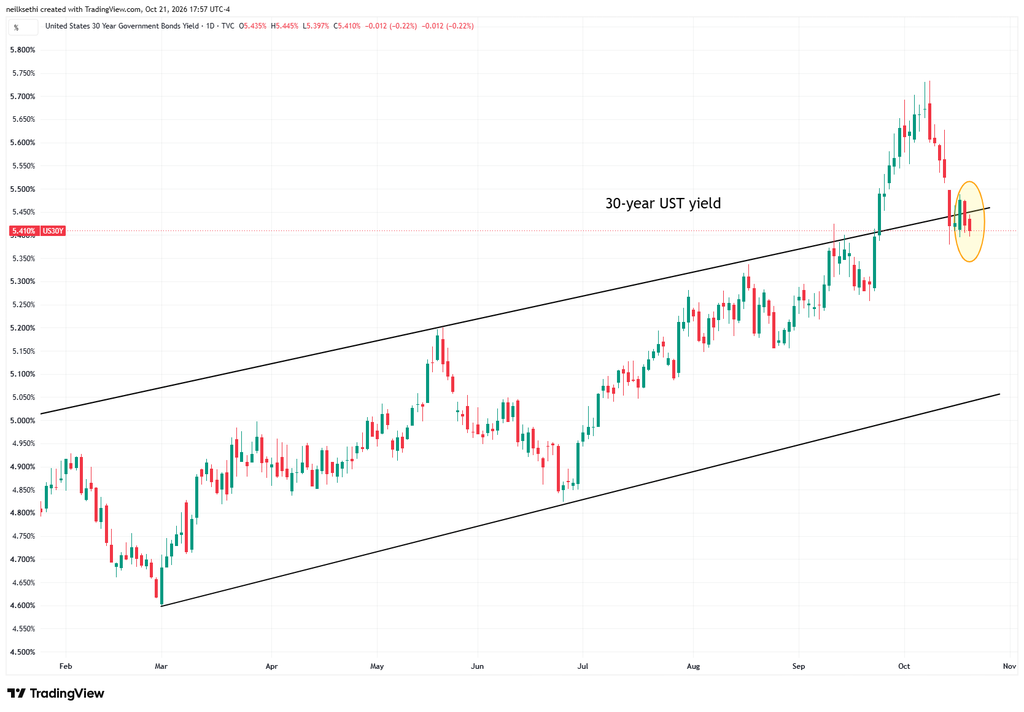
Treasury yields “twisted” rising at the front end but easing at the very long end.
The 2-year Treasury was up three basis points to 4.81% (including the after-hours).
It is ~93 basis points above the Effective Fed Funds rate, so calling now for a couple of rate hikes (it historically has traded 25-50 basis points above the Fed Funds midpoint).
Fed rate hike expectations were also little changed with October 15% priced, December 88% priced, and two more after December next year (83 basis points of total hikes).
10-year yields up one basis point to 5.12% (including after-hours).
30-year yields down one basis point taking the yield to 5.41% (including after-hours).
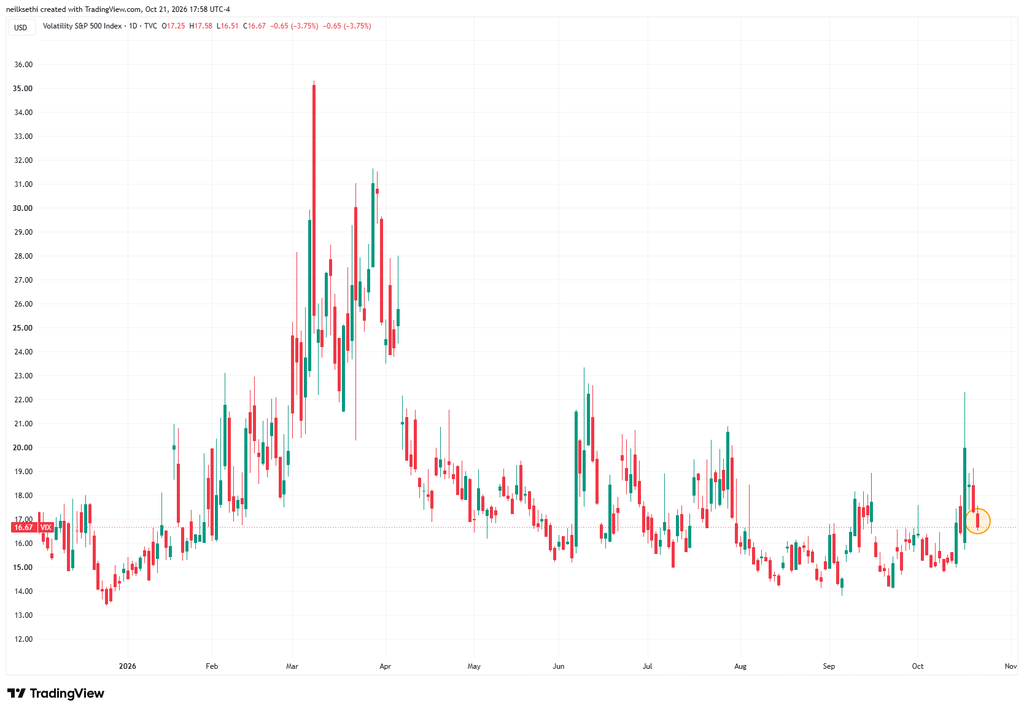
VIX eased back further to 16.7. The current level is consistent with ~1.04% average daily moves in the SPX over the next 30 days.
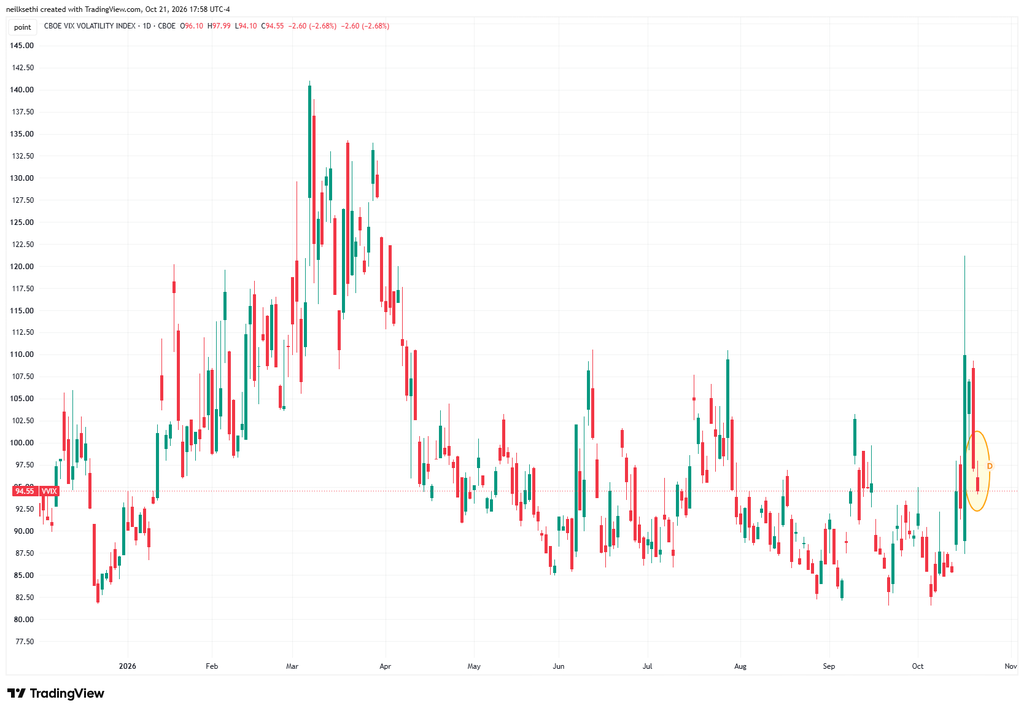
The VVIX (VIX of the VIX) eased back to 94.6. The current level is consistent with “moderate” daily moves in the VIX over the next 30 days (historically, normal is 80-100, although we haven’t been below 80 since July 2024). Above 100 is the level flagged by Charlie McElligott as indicating higher stress.
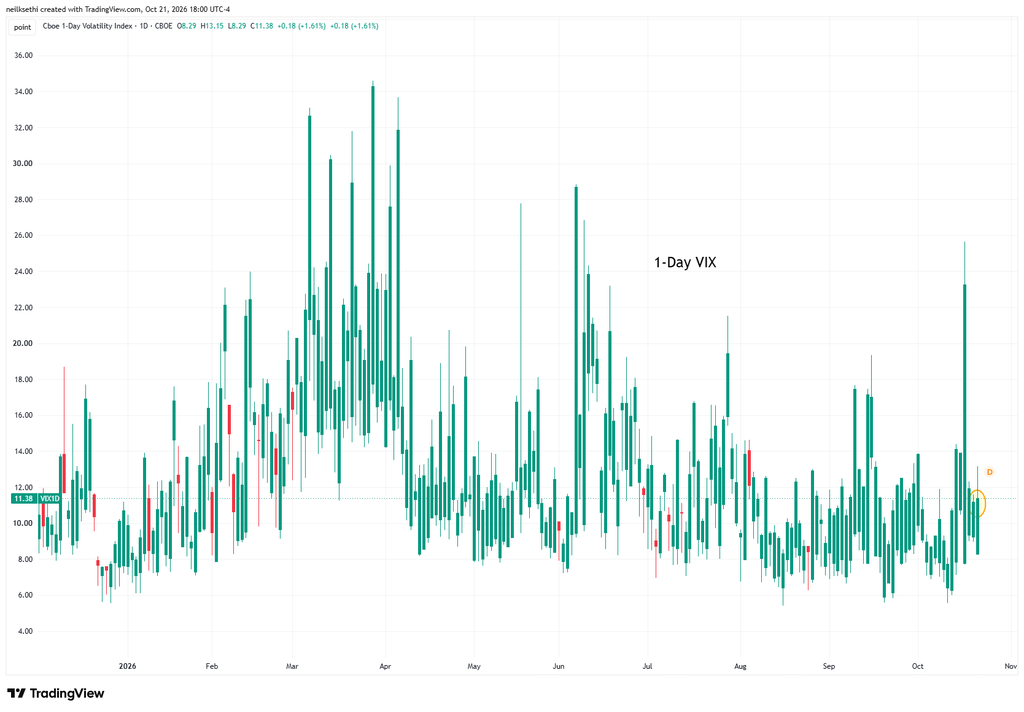
1-day VIX edged up to 11.4. The current reading is consistent with a move of 0.72% in the SPX next down from ~1.5% on Friday.
WTI futures (/CL), which TradingView has at December currently, eased back for a third session (including after-hours).
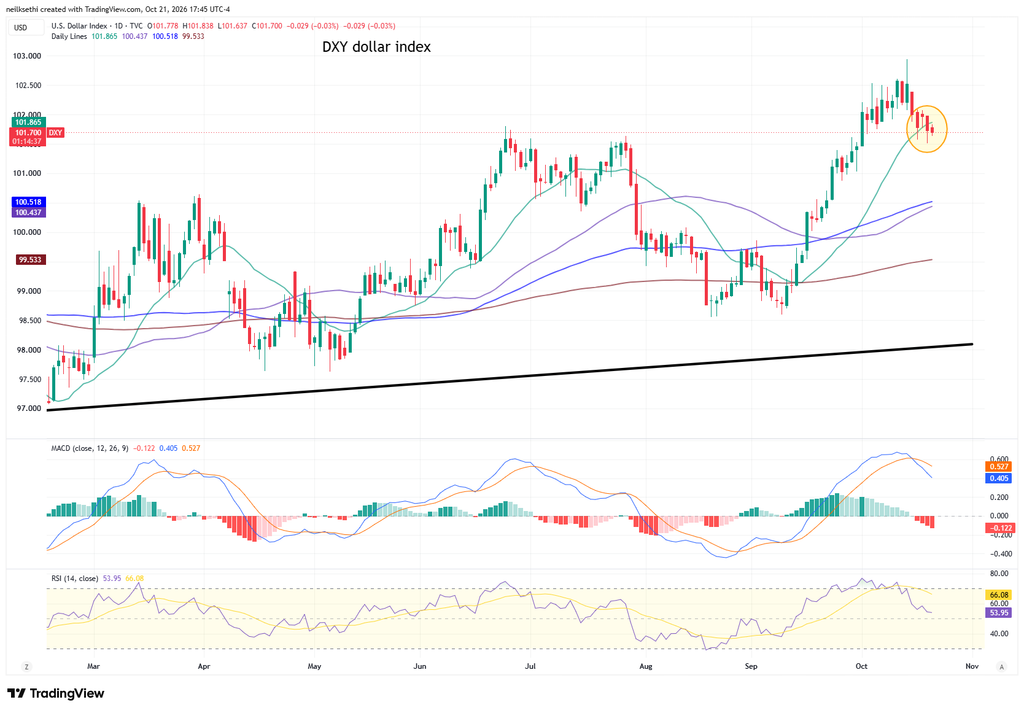
The DXY dollar index (which is fixed weighted with a heavy 57% weighting vs the euro) also eased back slipping further under its 20-DMA. As I mentioned Friday “The daily MACD flipped to a ‘sell longs’ positioning while the RSI has fallen from over 70 to well under, both of which would argue for a consolidation.”
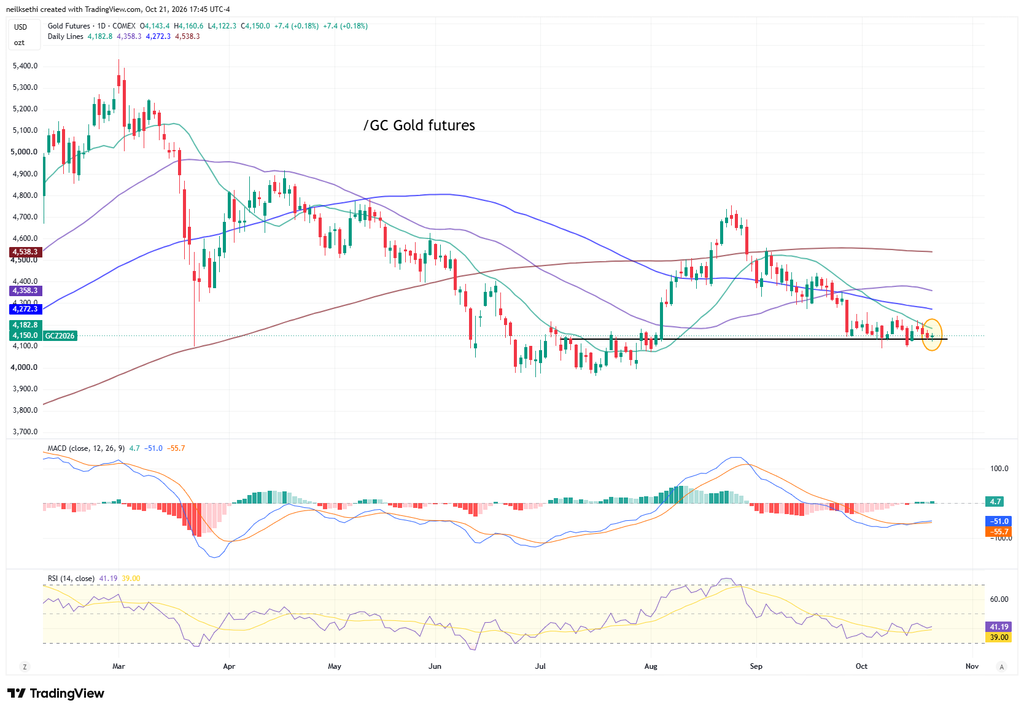
Gold futures (/GC) continue to trade just above support. The daily MACD is slightly positive but the RSI is still under 50. As I mentioned Thursday “It’s worked itself into a position for a rally if it wants to take advantage.”
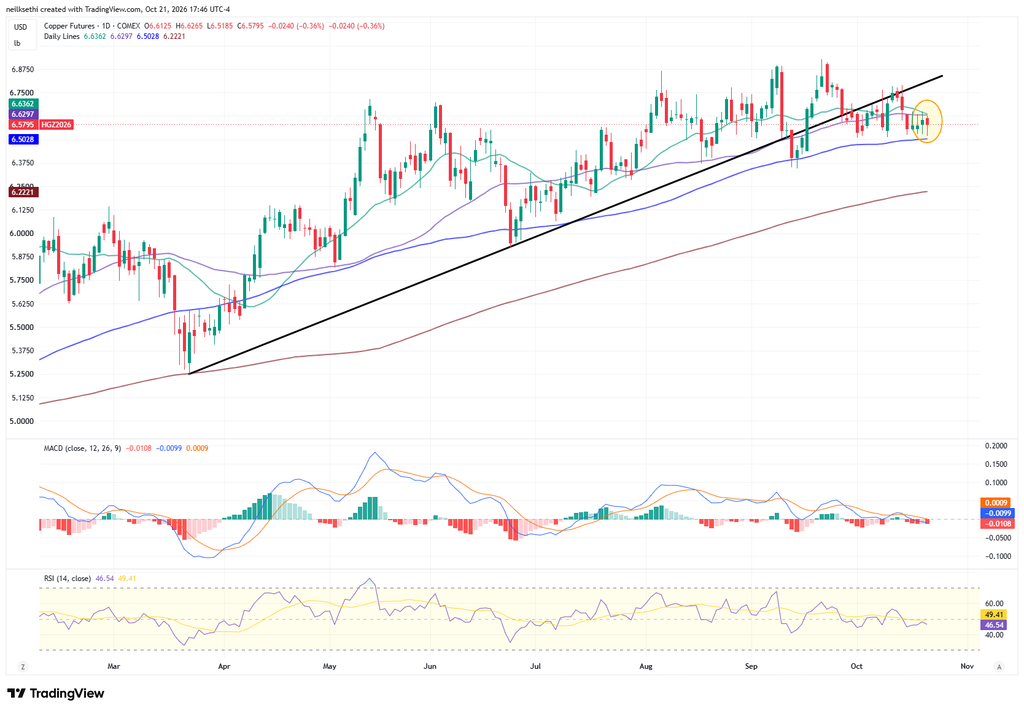
US copper futures (/HG) edged lower. Overall they still remain range bound. Daily MACD and RSI remain slightly negative.
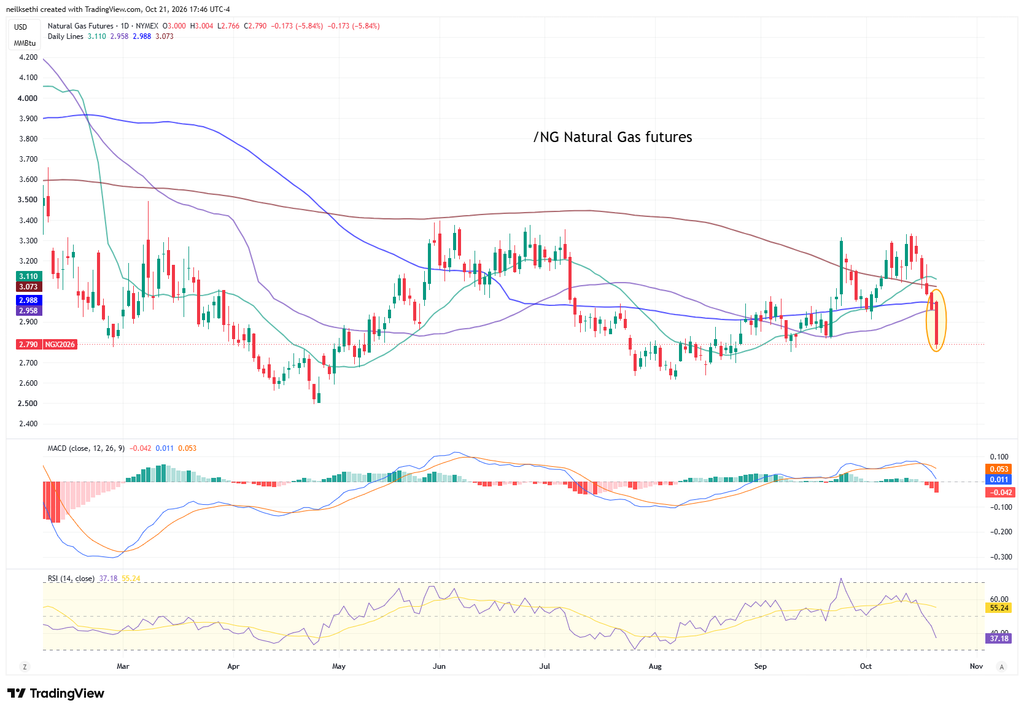
US natural gas futures (/NG) fell for a fifth session and at nearly 6% the most since early July, the lowest close since August, now to the lower half of their range since March.
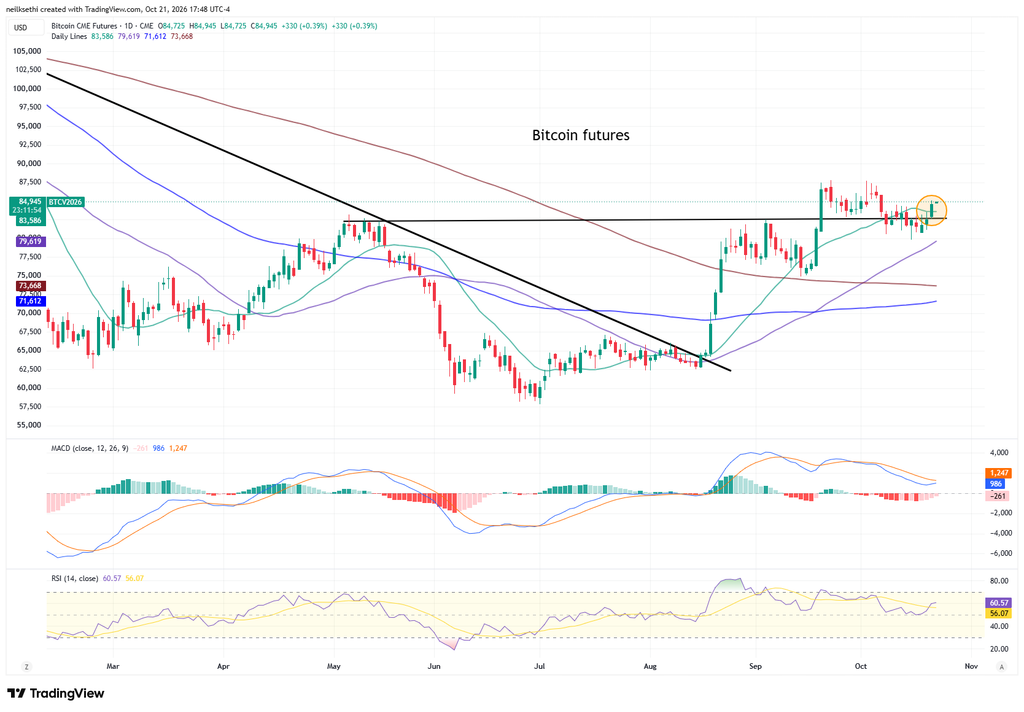
Bitcoin futures broke over support. I probably shouldn’t but got back in with a small position in the iShares Bitcoin ETF (IBIT). Daily MACD is getting close to flipping positive, and the RSI is over 50.
More From TheStreet Pro:
- Doug Kass – Move Over Warsh, Nvidia Might Be Lender of Last Resort
- Chris Versace –
- Helene Meisler – Tech Stock Charts Don’t Look Good, but the Market Is Oversold
- Stephen Guilfoyle – The Crude Conundrum
And From Me If You Missed It:
- Meanwhile, in France
- U.S. Crude Inventories Extend Slide to Lowest Since October 1983
- Mortgage Applications Drop for 7th Straight Week Despite Easing Rates
- Data Center Blues
Miscellaneous:
Wrap-Up – Might We Finally Get Our Broad Rally?
I said Tuesday:
Tech gets a big test tomorrow with Meta after the close along with chipmakers Lam Research and Texas Instruments and AI-related names IBM and Tesla. They’ll give us several early datapoints on hyperscaler capex, demand for chipmaking equipment (Lam), the industrial and analog chip cycle (Texas Instruments), and how enterprises are actually adopting AI (Meta, Tesla and IBM).
But what I didn’t anticipate was that, in between, SpaceX would light a fire under the AI trade. That looks like it might be sustained based on the earnings from the other noted companies which mostly came in very strong, at least as far as the AI part of things goes. Lam Research is lower, but that appears to be more due to missing whisper numbers as the headline numbers were a beat.
And notably today we didn’t see Tech suck the oxygen out of the market with six other sectors green on the day. Also, long bond yields didn’t follow Tech higher. So a number of positive developments. No names on the scale of today’s headliners tomorrow, so we’ll see how markets digest tonight’s batch.
The Day Ahead – Another Day Focused on Earnings
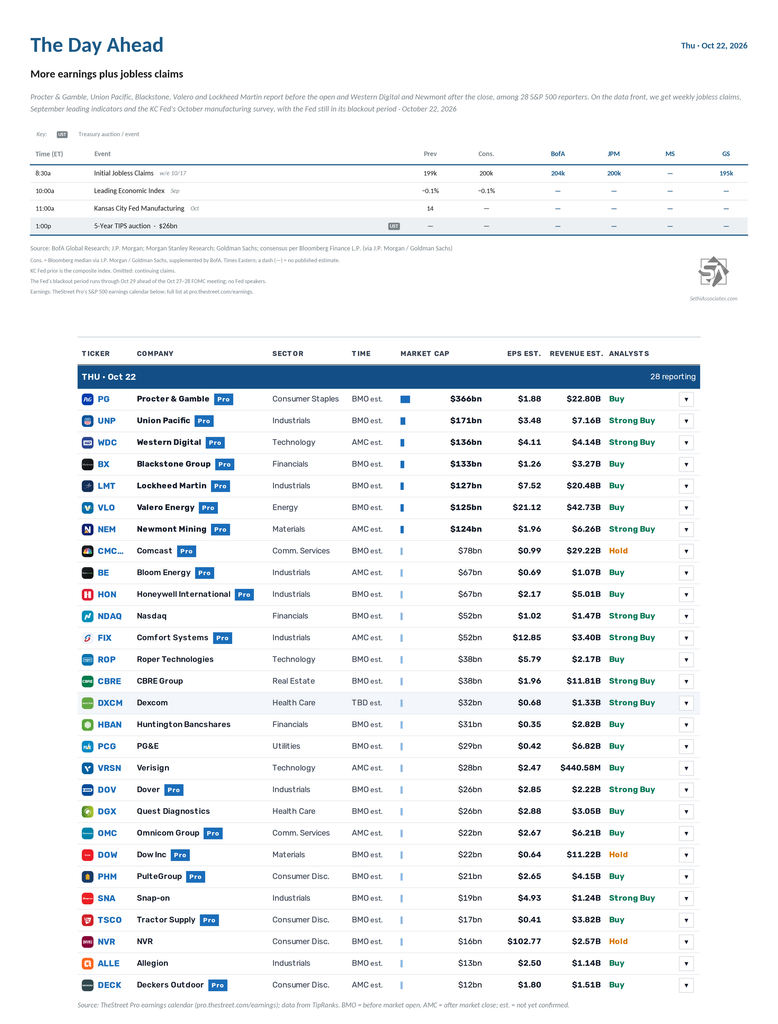
US economic data remains light with weekly jobless claims, September leading and coincident indicators and the Kansas City Fed’s October manufacturing survey.
The Fed remains in its blackout period ahead of next week’s October 27–28 FOMC meeting.
Non-Bill (>1yr in maturity) US Treasury auctions continue with a $26bn 5-year TIPS auction.
Q3 earnings season continues with 27 S&P 500 components: Procter & Gamble (PG), Union Pacific (UNP), Western Digital (WDC), Blackstone (BX), Valero Energy (VLO), Lockheed Martin (LMT), Newmont (NEM), Comcast (CMCSA), Norfolk Southern (NSC), Bloom Energy (BE), Honeywell (HON), Nasdaq (NDAQ), Comfort Systems USA (FIX), CBRE Group (CBRE), PG&E (PCG), Roper Technologies (ROP), Huntington Bancshares (HBAN), VeriSign (VRSN), Quest Diagnostics (DGX), Dover (DOV), PulteGroup (PHM), Dow (DOW), Snap-on (SNA), Tractor Supply (TSCO), NVR (NVR), Allegion (ALLE) and Deckers Outdoor (DECK).
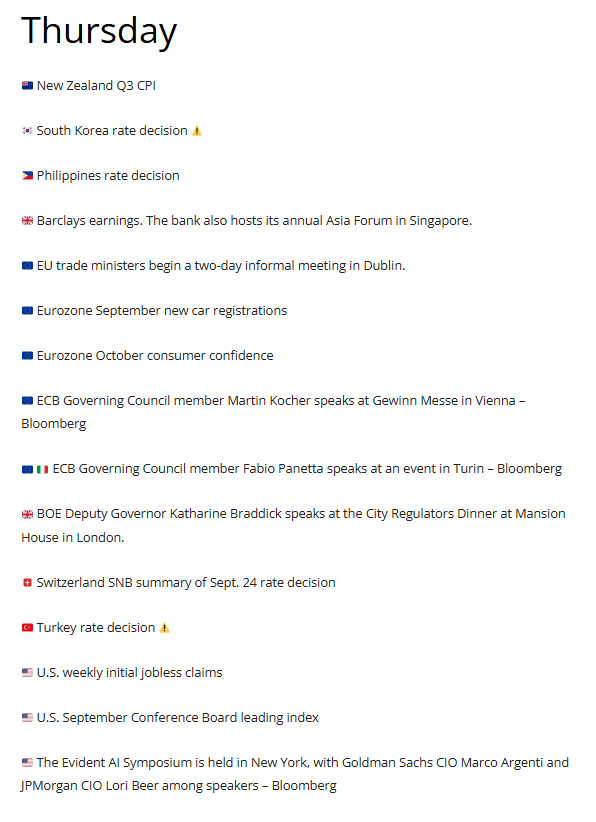
Ex-US highlights are France October business confidence, EU27 September new car registrations, Eurozone October consumer confidence, Canada September industrial product price index, and a policy decision in South Korea.
From Christophe Barraud’s international Week Ahead rundown:
At the time of publication, in terms of equities mentioned, Sethi was long GOOG, TSLA, META, NFLX, SPCX, T, IBM, SPY, RSP, CPER, IBIT, and numerous equities in the energy sector.
As a reminder comments are encouraged. If they are directed at me, please put @NeilSethi in front.