Retreating Yields Lift Stocks and Broaden Market Gains
Treasury yields reversed from two-decade highs, helping stocks recover morning losses as gains broaden beyond Tech, but higher oil prices remained a headwind.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Quick Summary
- Stocks eked out modest gains to open October, recovering from a morning drop as Treasury yields eased back — though another jump in oil on Middle East escalation fears kept the advance in check.
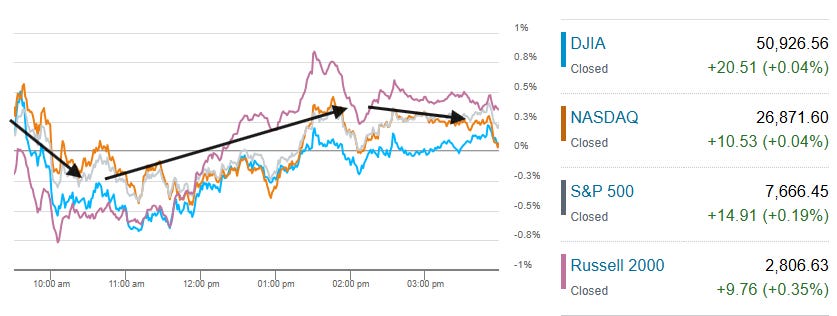
- The headline gains were slim — the S&P 500 +0.2%, Nasdaq +0.04%, and Dow Jones Industrial Average +0.04% — but the broader market did better, with the equal-weighted S&P 500 +0.5%, the Russell 2000 also +0.5% and the S&P MidCap 400 +1.1%, a welcome breadth improvement after September’s narrow leadership.
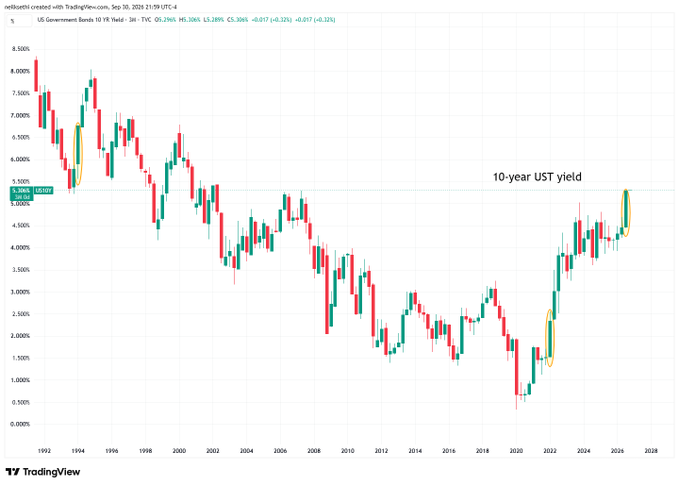
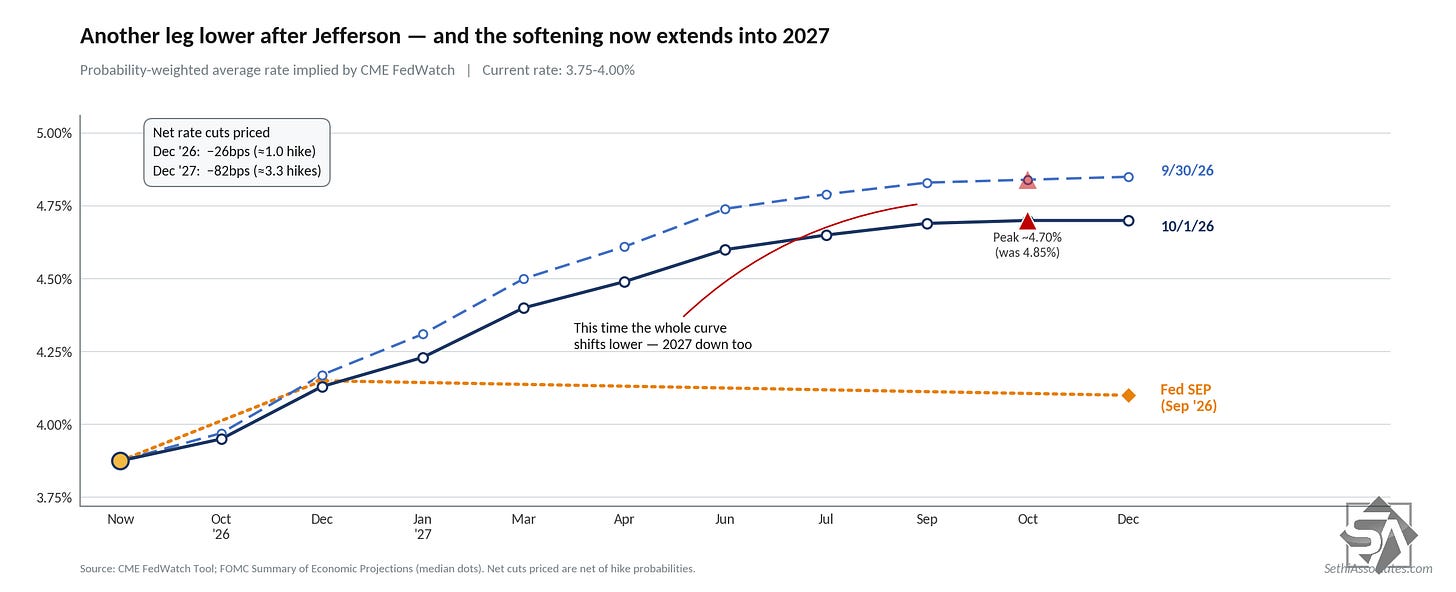
- The yield reversal was a key driver: the 10-year hit an intraday 5.34% (its highest since 2002) and the 30-year a 24-year high before both turned lower — the 10-year settled -6bp to ~5.24% and the 30-year -2bp to 5.60% in cash trading. The biggest move, though, came at the front end, as the 2-year fell 10bp to ~4.79%, helped by Fed Vice Chair Jefferson saying further hikes ‘may take more time,’ echoing NY Fed President Williams’s no-urgency message Wednesday. Odds of an October hold rose to ~72% from ~62% Wednesday (CME FedWatch).
- Breadth was not stellar but still the best of the week — 5 of 11 sectors higher (after 2 Wednesday), with super-heavyweight Tech (+0.8%) again among them boosted by semiconductors (SOX) +1.6%.
- Oil was a drag though — WTI +2.7% to ~$93 after a report the U.S. is sending a third aircraft-carrier group and up to 10,000 troops to the Middle East which comes after President Trump said he may resume attacks on Iran after the midterm elections in a Time interview.
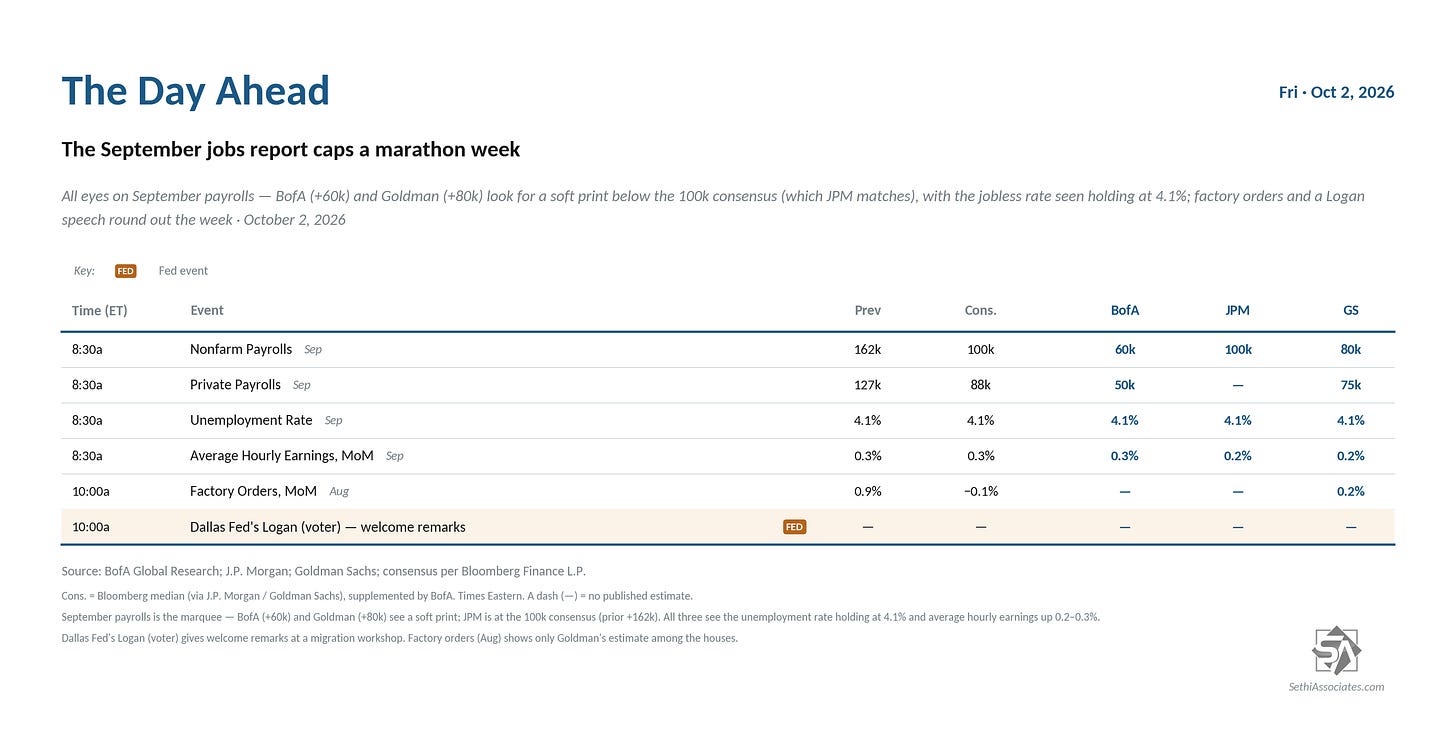
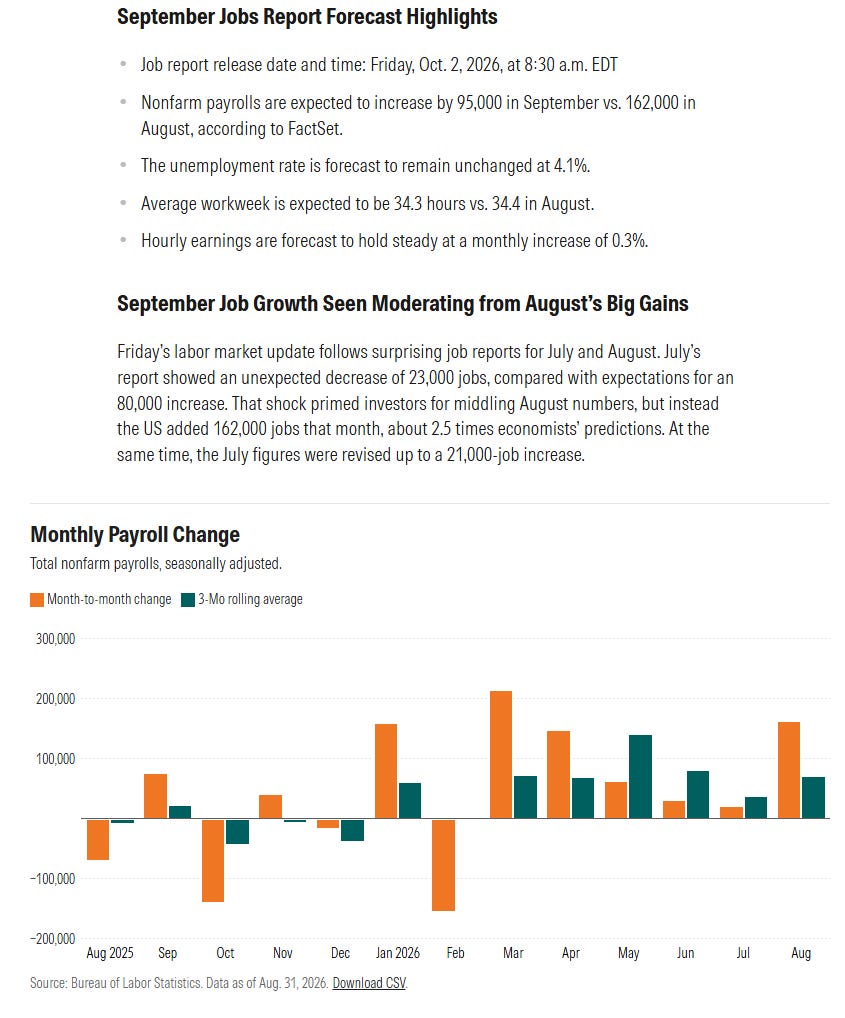
- All eyes now turn to the September jobs report Friday morning (NFP +90K expected, unemployment 4.1%).
Market Commentary
Equities:
- “Take a look at the Nikkei or Nasdaq futures, there’s clearly little gloom and doom,” said David Kruk, head of trading at La Financiere de l’Echiquier in Paris. “The next driver is the third-quarter earnings season which should be strong, just as the last one.”
- “It’s a new month now, and stocks at least can derive some comfort from Micron’s ebullient earnings report, which delivered just about everything an AI or semiconductor bull could have asked for.” — Cameron Crise, Macro Strategist, Markets Live
- “While [some] factors remain headwinds, corporate earnings have continued to show resilience,” said Tracie McMillion, head of global asset allocation strategy at Wells Fargo Investment Institute. “The key question is whether that earnings strength can continue as borrowing costs remain elevated.”
Bonds:
- “We’ve identified 5.5% on US 10-year bonds as the level at which pressure really starts kicking in on equity markets,” said Florian Roger at BNP Paribas CIB. “We’re nearly there and that’s when valuations can start looking excessive.”
- “I think there’s some fatigue in the bond market. We moved 50 basis points in 18 trading days after Fed Chairman [Kevin] Warsh kind of messaged at Jackson Hole that indeed a rate hike was coming,” said Jeff Kilburg, CEO of KKM Financial. “I think there’s also a little bit of optimism that this is going to be a short-lived move to 5%. Of course there has to be an Iranian solution for that to be enabled.”
- “It’s getting a little bit messy in markets,” said Gennadiy Goldberg, head of U.S. rates strategy at TD Securities, adding that there weren’t obvious catalysts for the reversal today.
Fed:
- “Continued employment resilience should help support household income and consumer spending, helping sustain economic growth,” said Brian Therien at Edward Jones. “A solid labor market also gives the Fed greater flexibility to remain focused on inflation.”
Stock and Sector Breakdown:
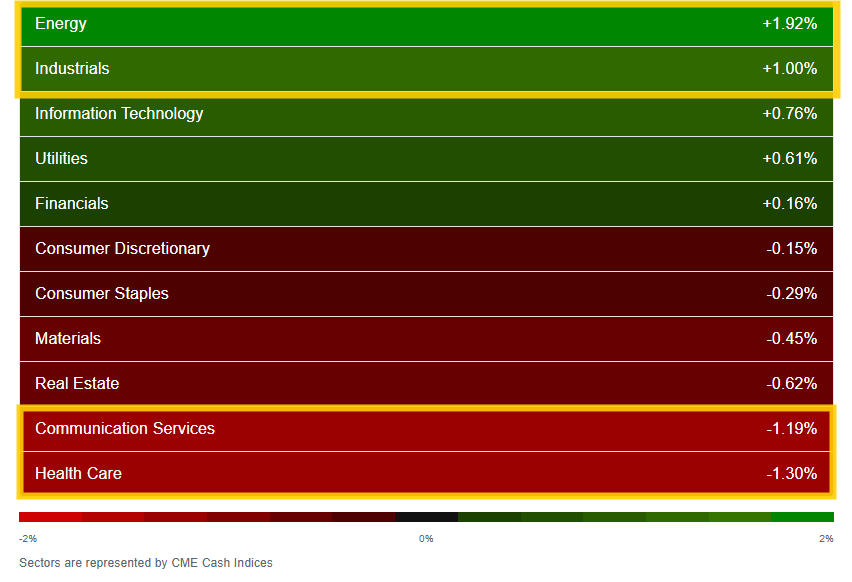
While there were only 5 of 11 sectors higher Thursday it was still the best this week (after 2 Wednesday, 4 Tuesday, 3 Monday) and importantly super-heavyweight Tech (~40% of market cap) was again one of them +0.8%. Two were 1% or more (Energy and Industrials). Two were also down 1% or more in Communications Services and Health Care.
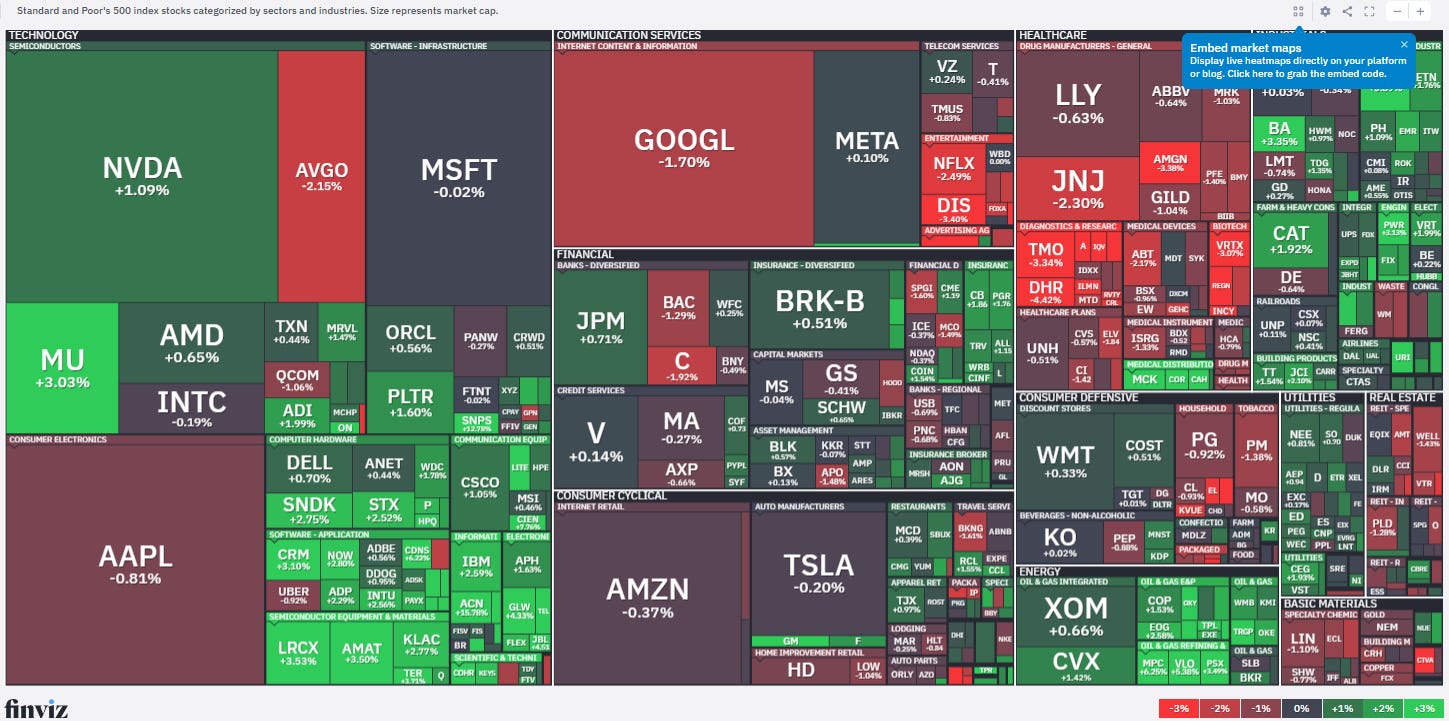
Tech was supported by the PHLX Semiconductor Index (SOX) advancing 1.6%. Micron (MU) +3.0% was a notable, albeit volatile, contributor to the semiconductor group’s strength after reversing an early post-earnings decline and finishing higher. The turnaround followed an initially cautious response to the company’s better-than-expected Q4 results and strong Q1 guidance discussed yesterday, as enthusiasm was dampened by some gross margin pressures due to increased compensation spending. For more on Micron, Sarge Guilfoyle wrote New Micron Price Target After Blowout Earnings Prove Wall Street Wrongon TheStreet Pro today and TipRanks has a number of articles as well.
Accenture (ACN) +16.0% was the best performer on the S&P 500 after the consulting and technology-services giant reported fiscal fourth-quarter results that beat expectations across revenue, earnings and bookings increasing confidence that AI is becoming a growth driver rather than a disruption risk for the company.
At the other end of the standings, a drag on the indices were several megacaps including Alphabet (GOOG) -1.7% after reversing an opening gain that followed the unveiling of Gemini 4 Argon. Bloomberg reported a federal judge allowed thousands of publishers to move forward with claims tied to Google’s advertising technology business. According to the report, roughly 5,000 publishers can seek about $1.7 billion. Broadcom (AVGO) -2.2% was lower after agreeing to lend Anthropic as much as $42 billion to lease its chips, according to Reuters, an arrangement that could add to concerns about circular dealmaking between the key players in the AI boom.
Paramount Skydance (PSKY) -9.6% was the worst performing stock on the S&P 500 — excluding Corteva (CTVA) -83.8% after it completed the spinoff of its advanced seed and genetics business — as investors digested the news that Judge Araceli Martinez-Olguin accepted the settlement with the states allowing its merger with Warner Bros. Discovery (WBD) +0.00% to close on October 6th.
While not in the S&P 500, Mattel (MAT) +18.9% jumped after media reports surfaced that the toymaker has received a $6 billion takeover offer from privately held Authentic Brands.
[Note: chart uses futures prices.]
The number of large SPX winners (up over 3%) up to ~45 from just 9 Wednesday, ~20 Tuesday, two Monday, while the number of large losers (down over 3%) fell to 14 from 17, six, and ~40. As mentioned previously, both of these metrics have remained very subdued since the start of August rarely getting above 50 and only once above 100.
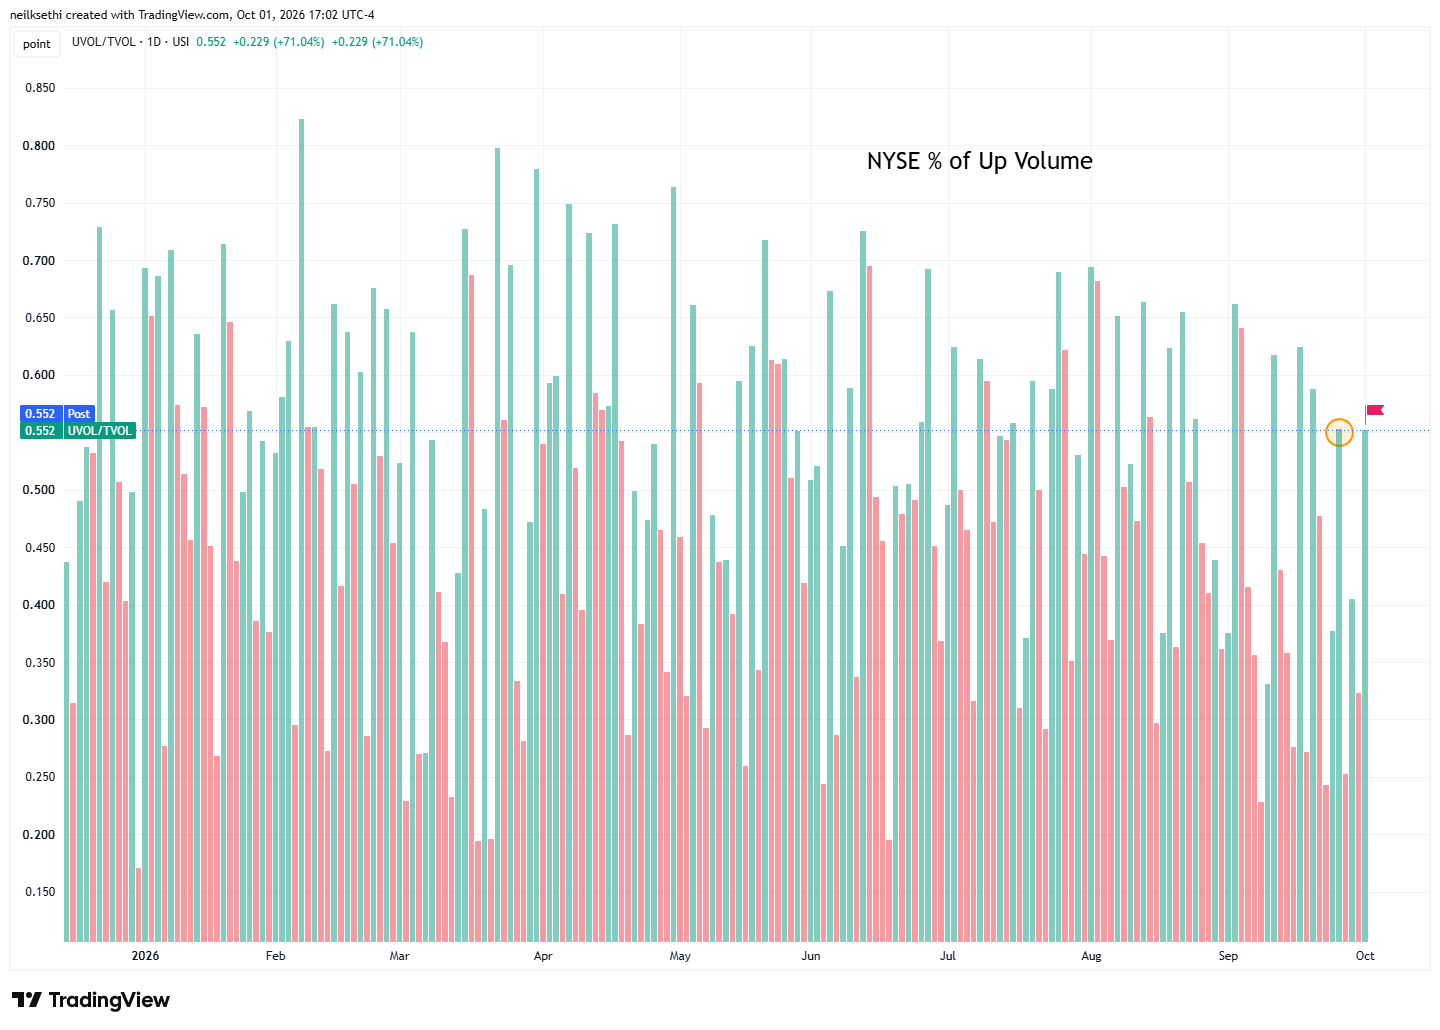
And for a third day some breadth metrics improved on the NYSE. Positive volume came in at 55.2% on the NYSE. Compare that to Friday when it was 55.3% but on a larger +0.40% gain vs today’s +0.15%.
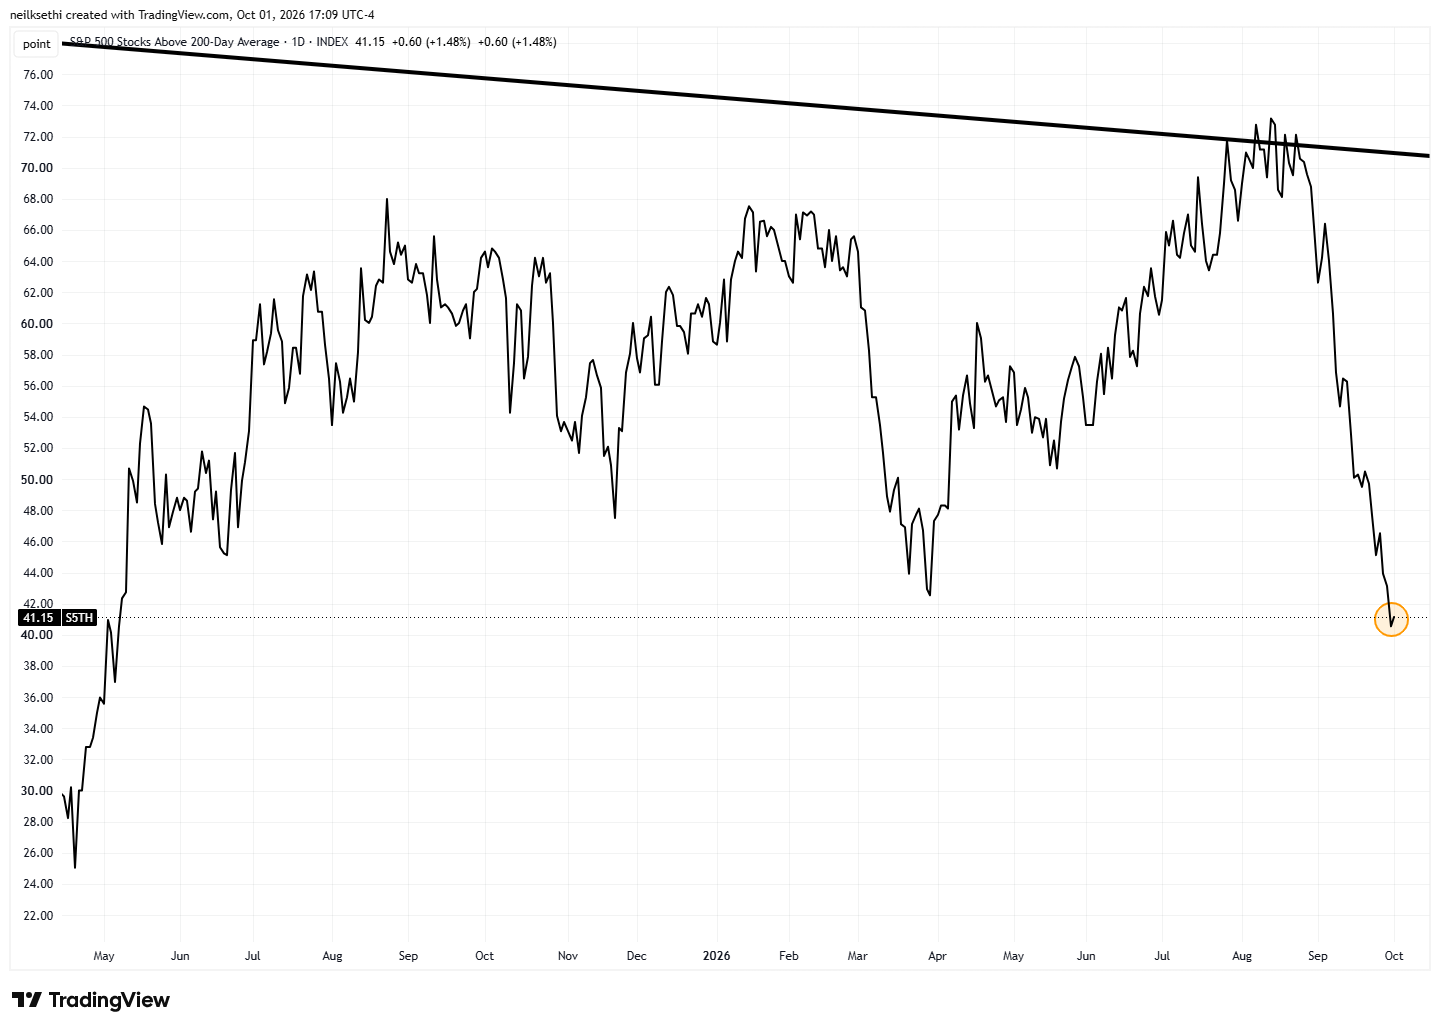
And we did see a small turn higher in the percent of S&P 500 stocks trading above their 200-day moving average (if you squint).
That said, other metrics were less positive. New 52-week highs vs lows fell to -379 from -280 on the NYSE despite the positive session. It was worse on the Nasdaq (which finished +0.04%) where they went to -446, just off the least since April, from -283.
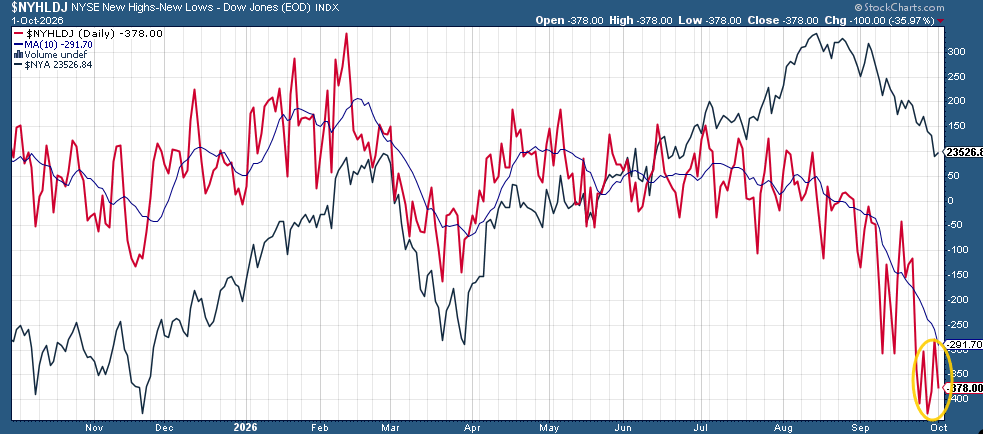
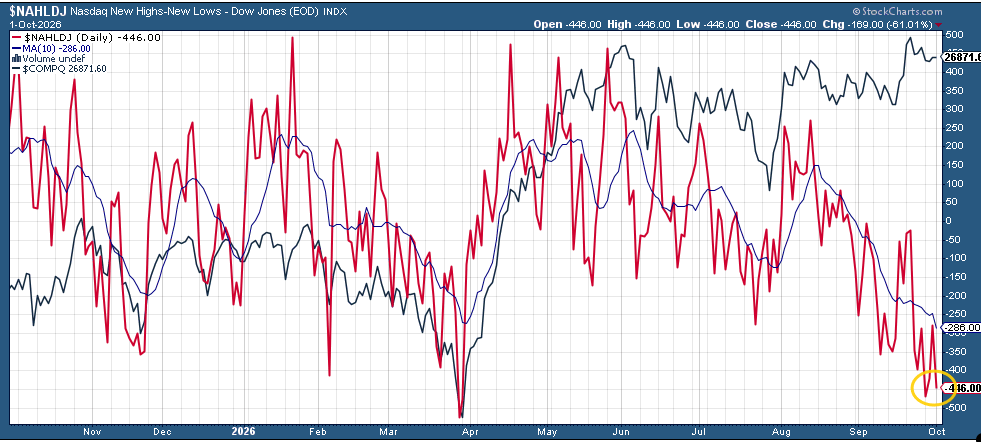
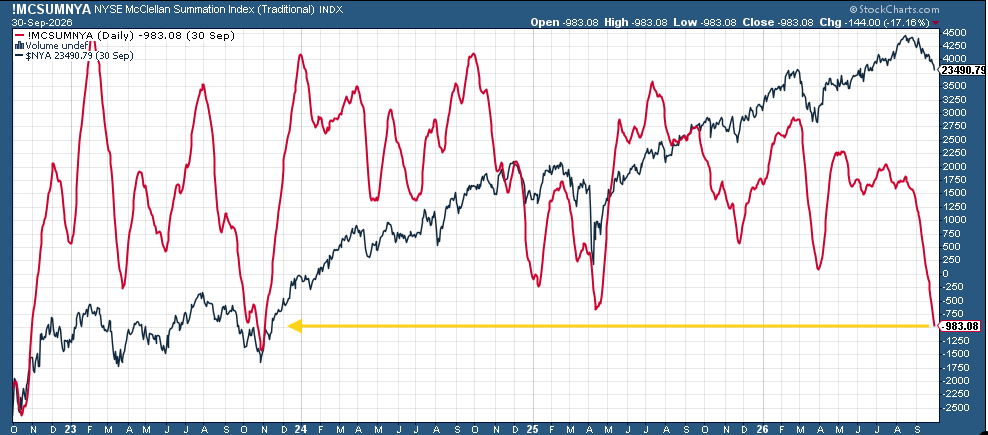
And the McClellan Summation Index (red line, broadly whether the typical stock is doing relatively better or worse than the index) continues to plummet to new post-November 2023 lows.
Some other stock-specific commentary from TheStreet Pro:
- Chris Versace –
- Stephen Guilfoyle – Selling Smith & Wesson After Gains
- Doug Kass – Now’s Best Time Ever for Pot
- James “Rev Shark” DePorre – Goldman’s Amazon Move Adds Conviction to My Trade
- Ed Ponsi – Eyeing This Bond ETF Amid Treasury Selloff
- Alex Frew McMillan – What’s Next for Asian Stocks as Year Ends?
A Look At The Charts
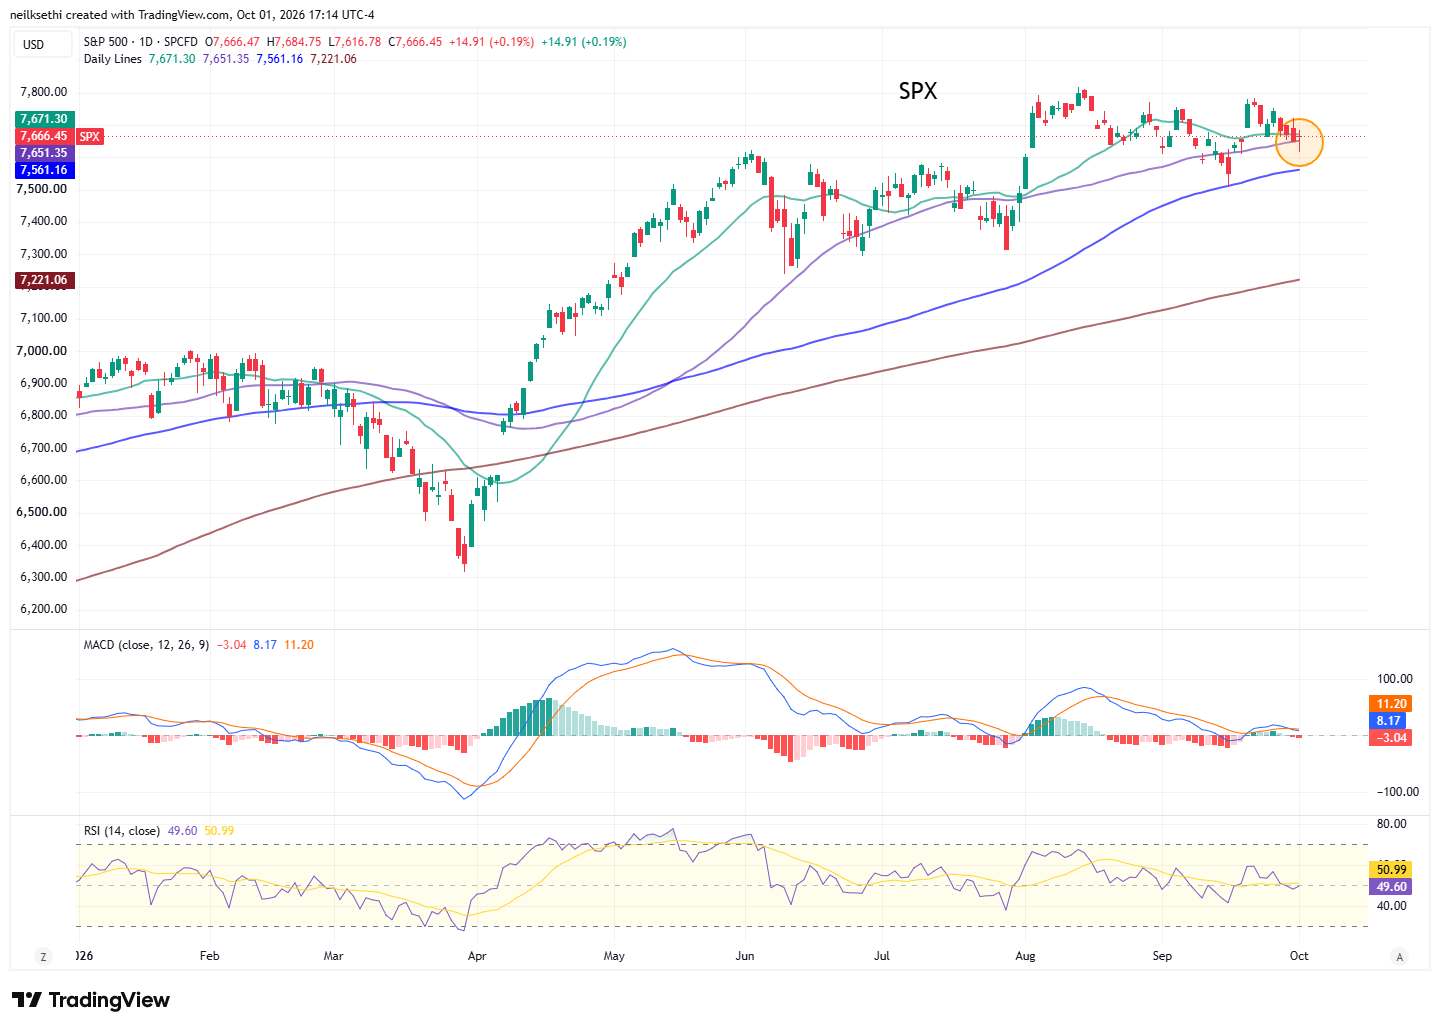
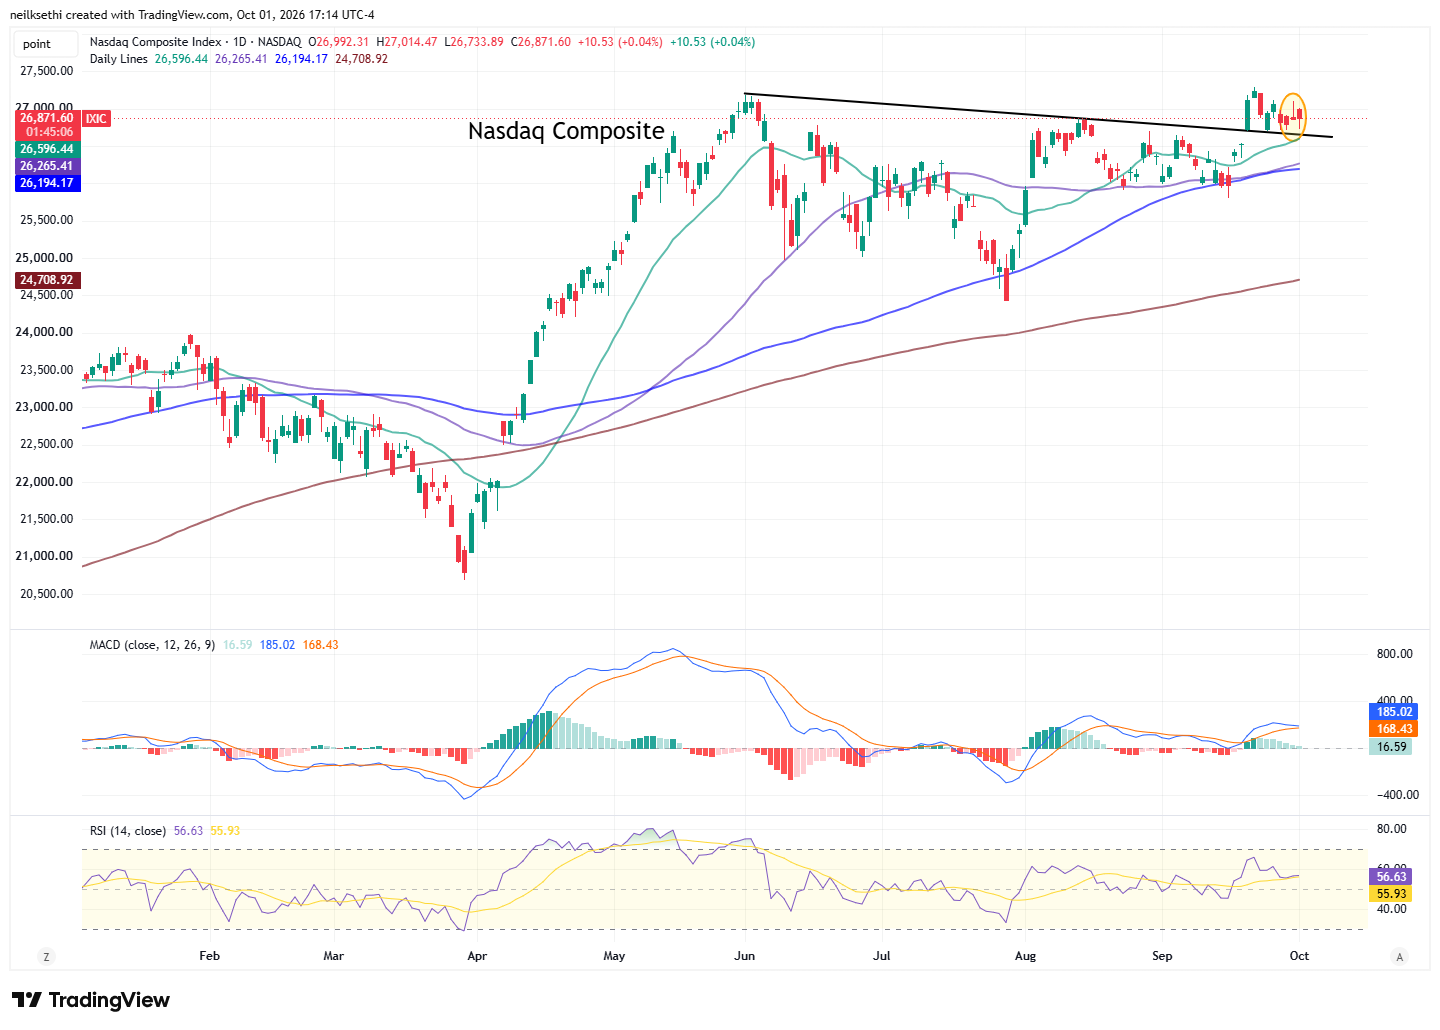
Note on all charts the colored lines are moving averages (the average price over the lookback period — days on the daily charts, weeks on the weekly charts):
20 = green
50 = purple
100 = blue
200 = brownException is monthly charts where blue is 10-month moving average and brown is 20-month moving average.
MACD = Moving average convergence/divergence line, a measure of momentum that compares longer term and shorter term momentum to gauge if a move is strengthening or weakening. This is probably my favorite individual indicator.
RSI = Relative Strength Index (basically what it sounds like) = measures the strength of the move comparing gains to losses over the given lookback window (I use the standard 14 periods).
SPX fell below but recovered the 50-DMA. The daily MACD and RSI as mentioned Wednesday have now softened to slightly bearish.
Nasdaq Composite continued its sideways drift just below all-time highs.
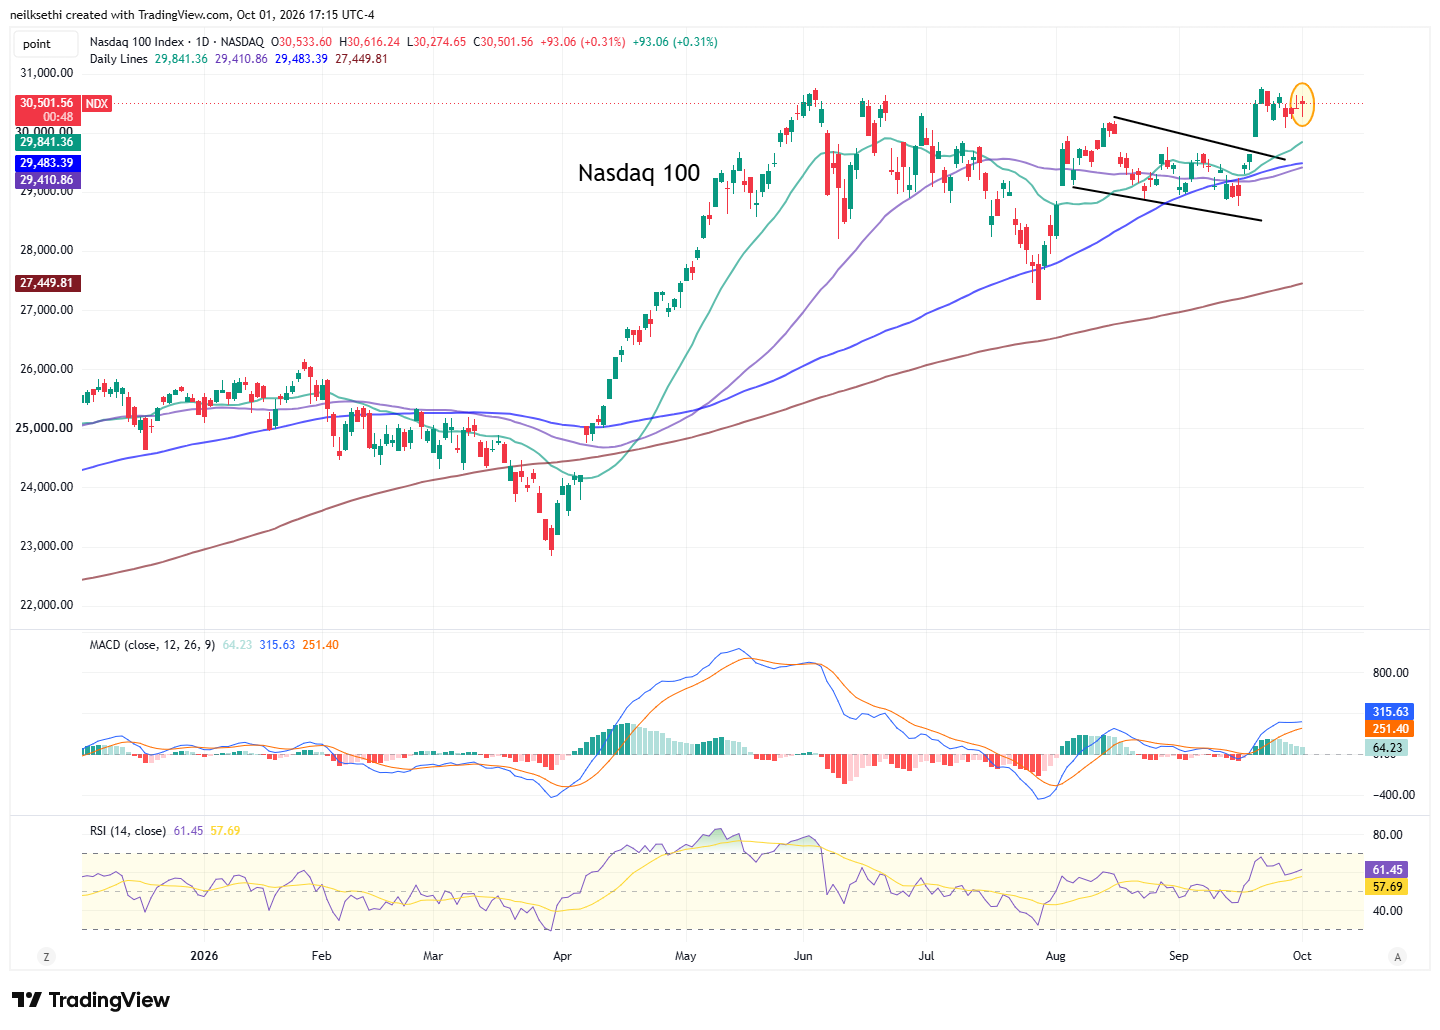
The Nasdaq-100 (QQQ) also remains just below its all-time high. Daily MACD and RSI also positive here.
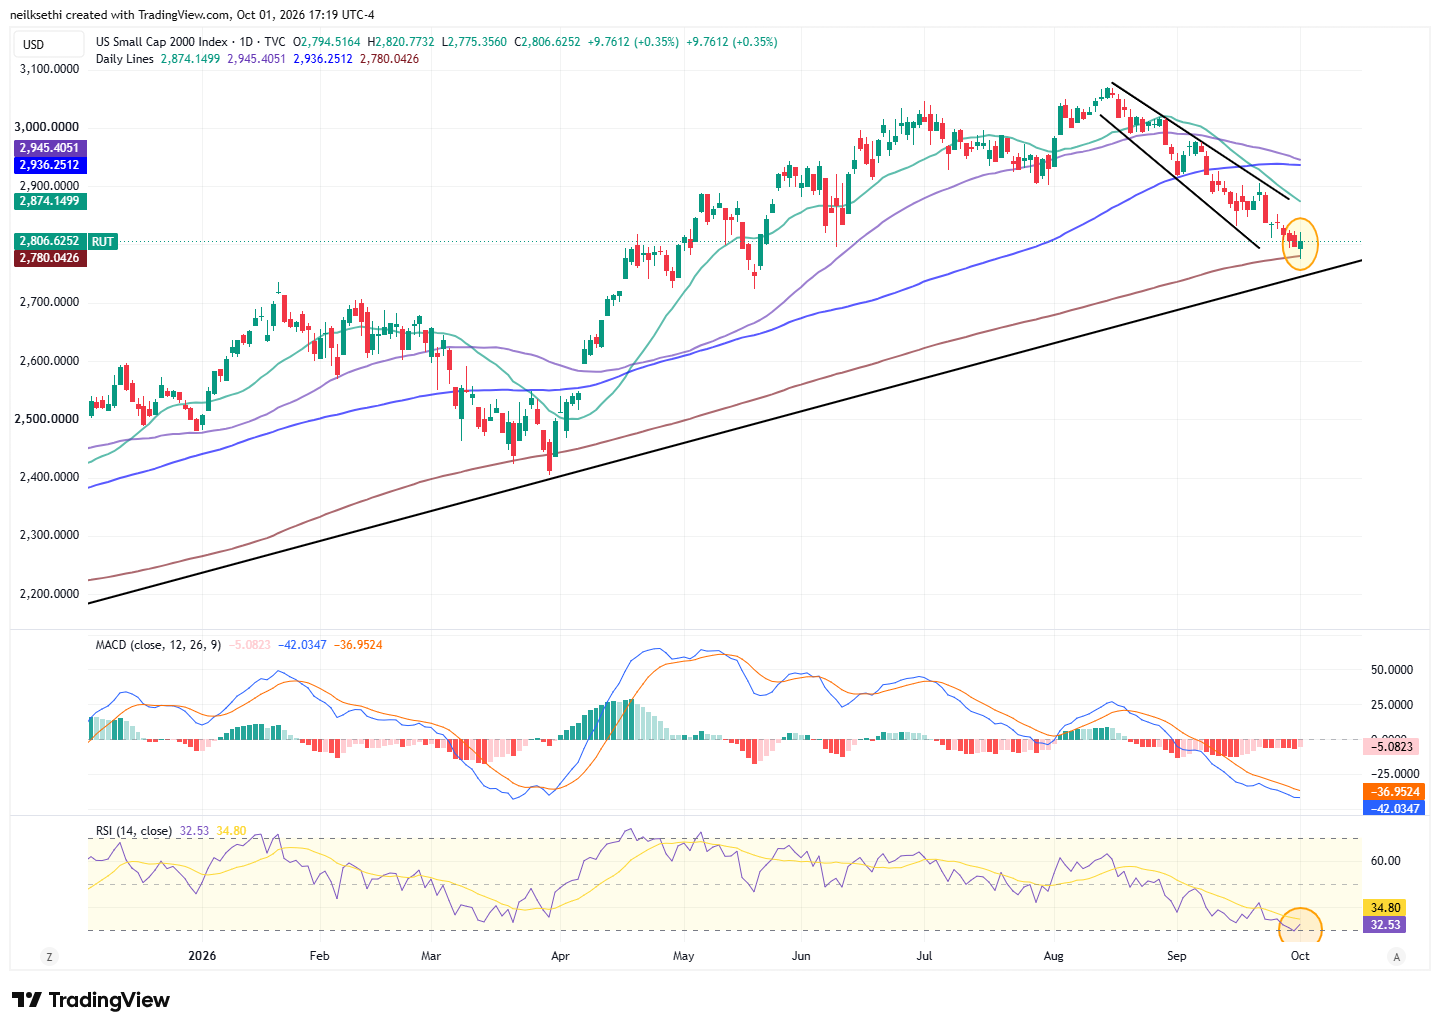
The Russell 2000 (RUT) I said at the end of August was “much more problematic,” but it finally has found its way to the test of the 200-DMA I mentioned two weeks ago. That held, at least initially, so I did buy some (IWM) with a stop at $271.Its daily MACD remains in “go short” positioning, but the RSI inflected higher at the 30 mark which can be the sign of a reversal. I’d like it if the MACD can get a crossover soon.
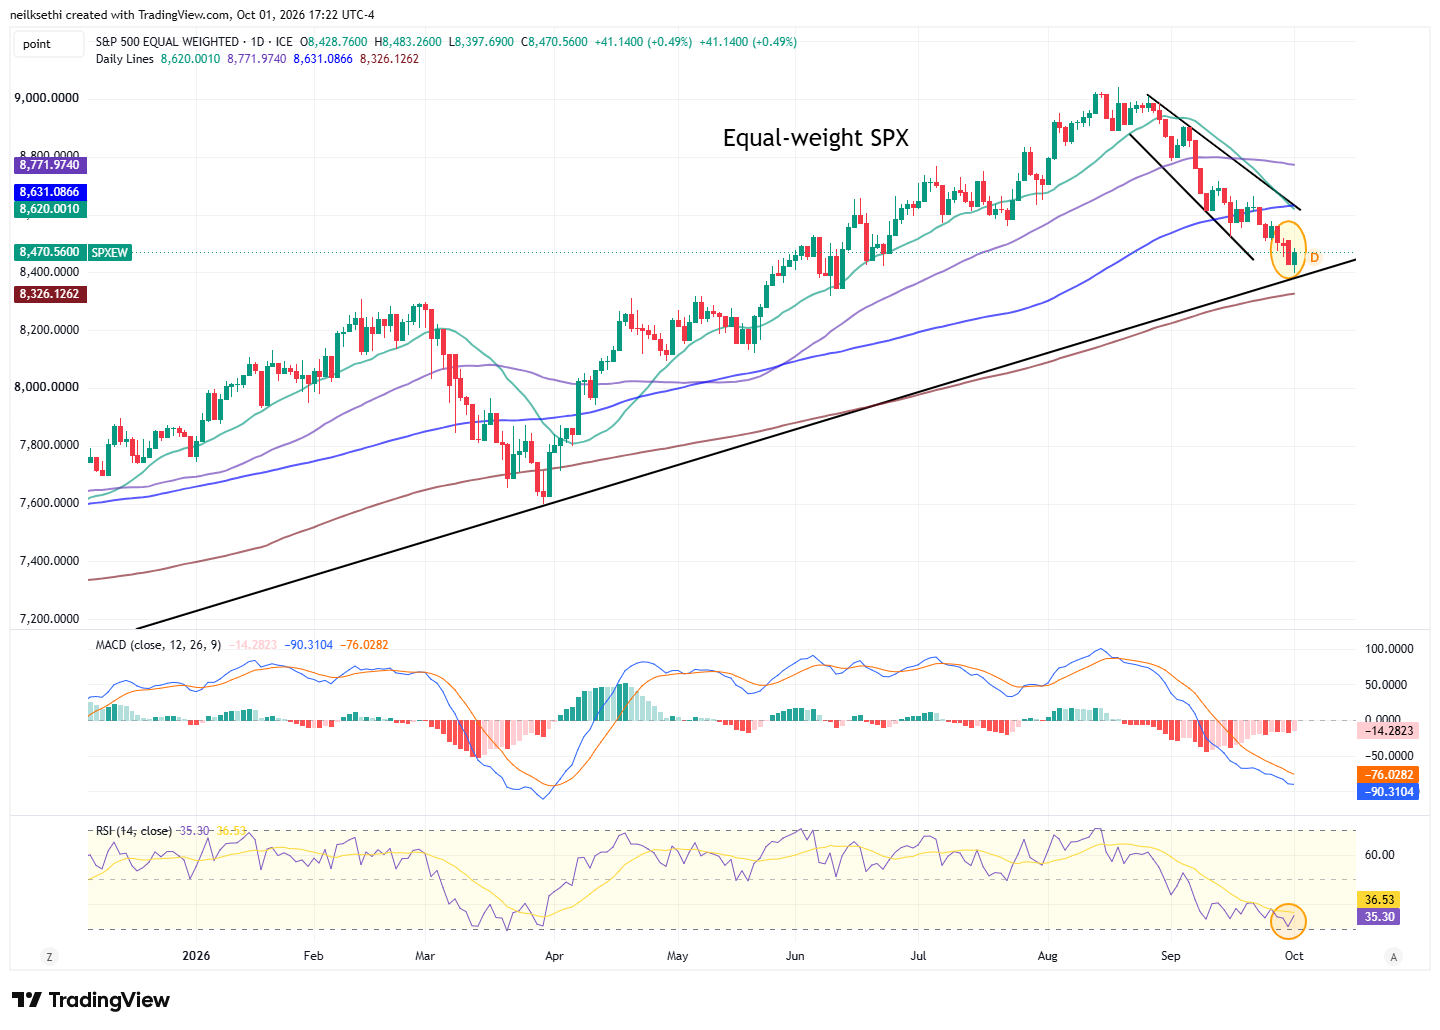
The equal-weighted SPX I said three weeks ago is “back to concerning,” but that too made it to the uptrend target which I indicated “might be a place to buy” so I did make an initial purchase of (RSP) with a stop at $204.50.Like the RUT daily MACD and RSI are weak but RSI has inflected higher from around the 30 area.
Treasury yields fell across the curve in a bull steepening (shorter yields falling more):
The 2-year Treasury fell over 10 basis points (including the after-hours), the largest drop since last August.
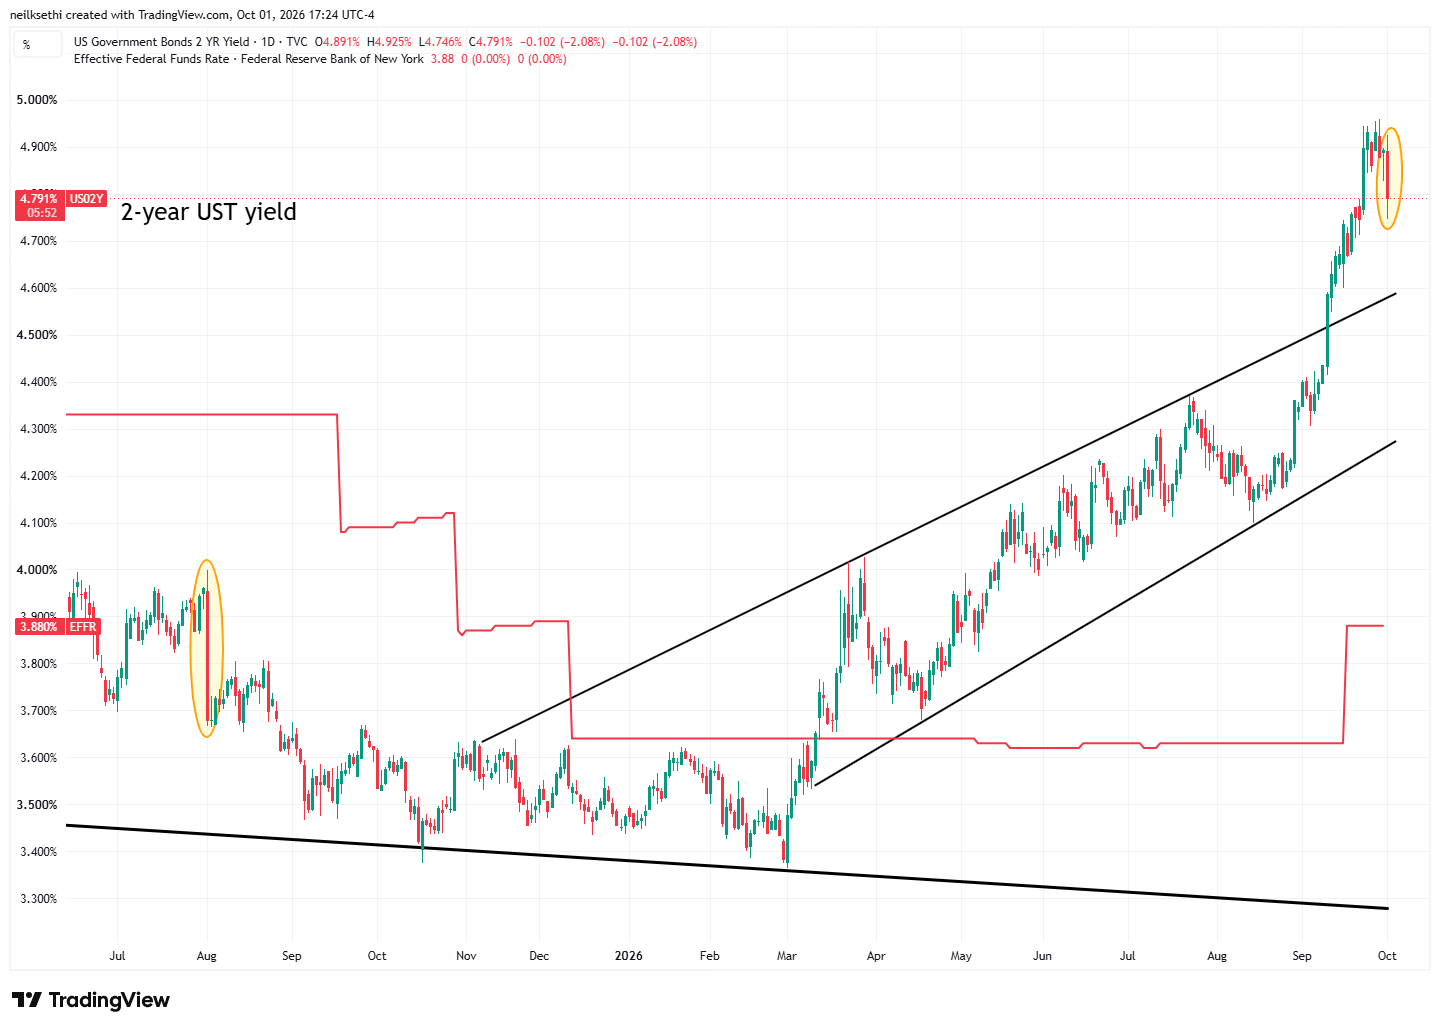
It is ~102 basis points above the Effective Fed Funds rate, so still screaming for (at least a couple) more rate hikes.
In that regard, we saw October rate hike bets soften to just a 28% chance of a hike (down from 70% last week), with now just a 21% chance of two hikes this year. But unlike Wednesday when near term rate hikes were pushed into 2027, today those softened as well with total hikes through the end of next year falling to 82 from 97 (hence the drop in the 2-year yield).
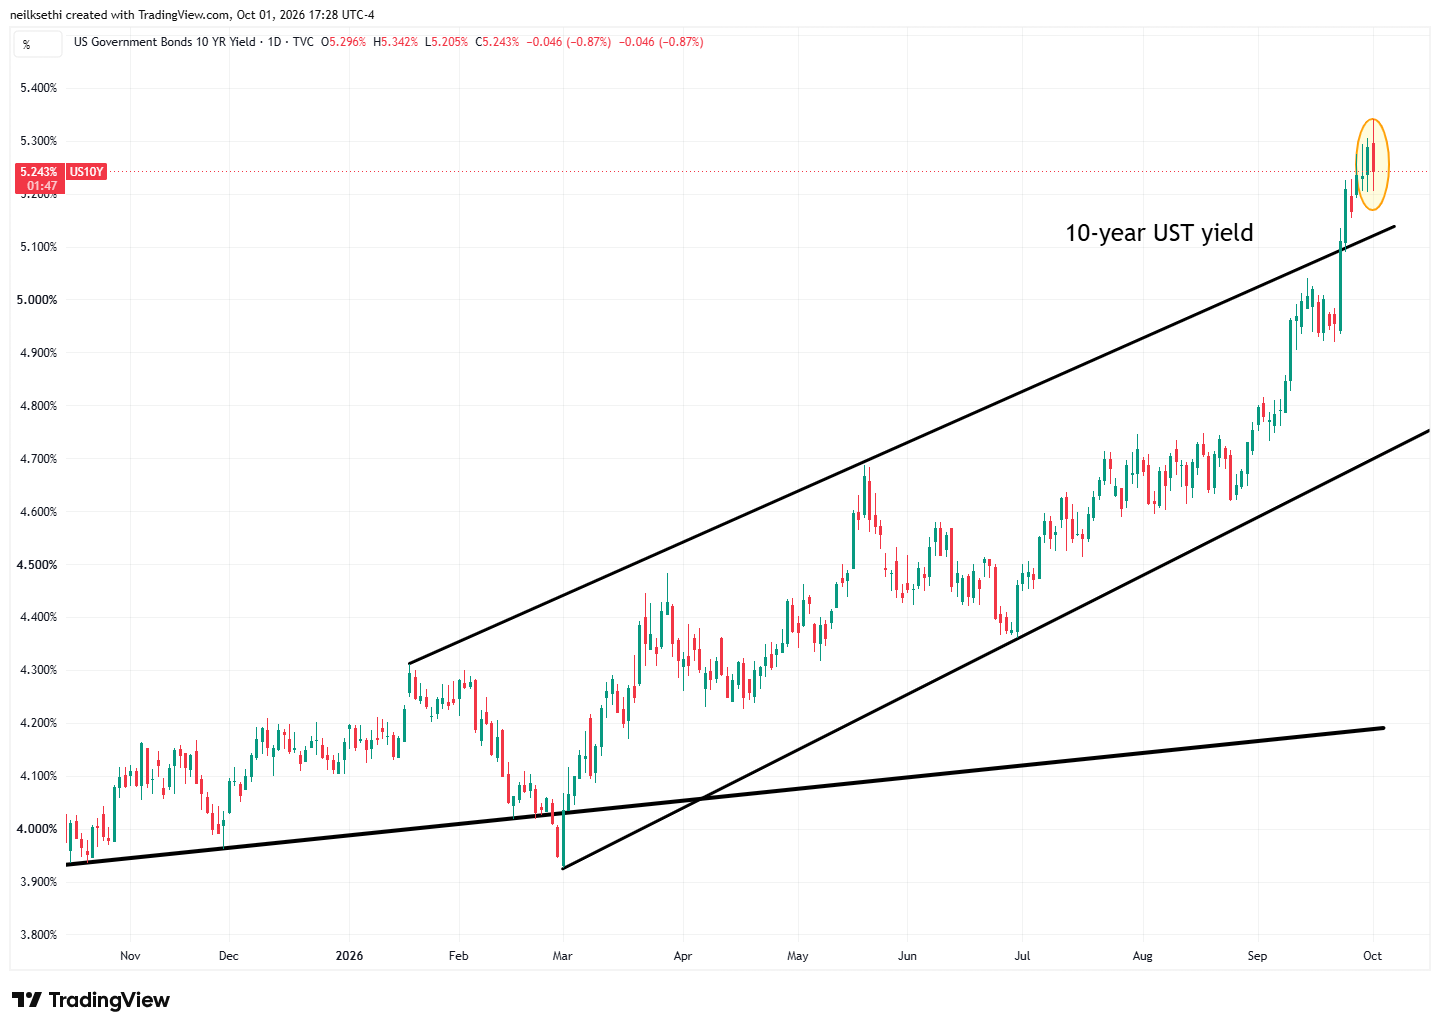
10-year yields down 5 basis points to 5.24% (including after-hours) just giving back Wednesday’s move to the highest since 2002.
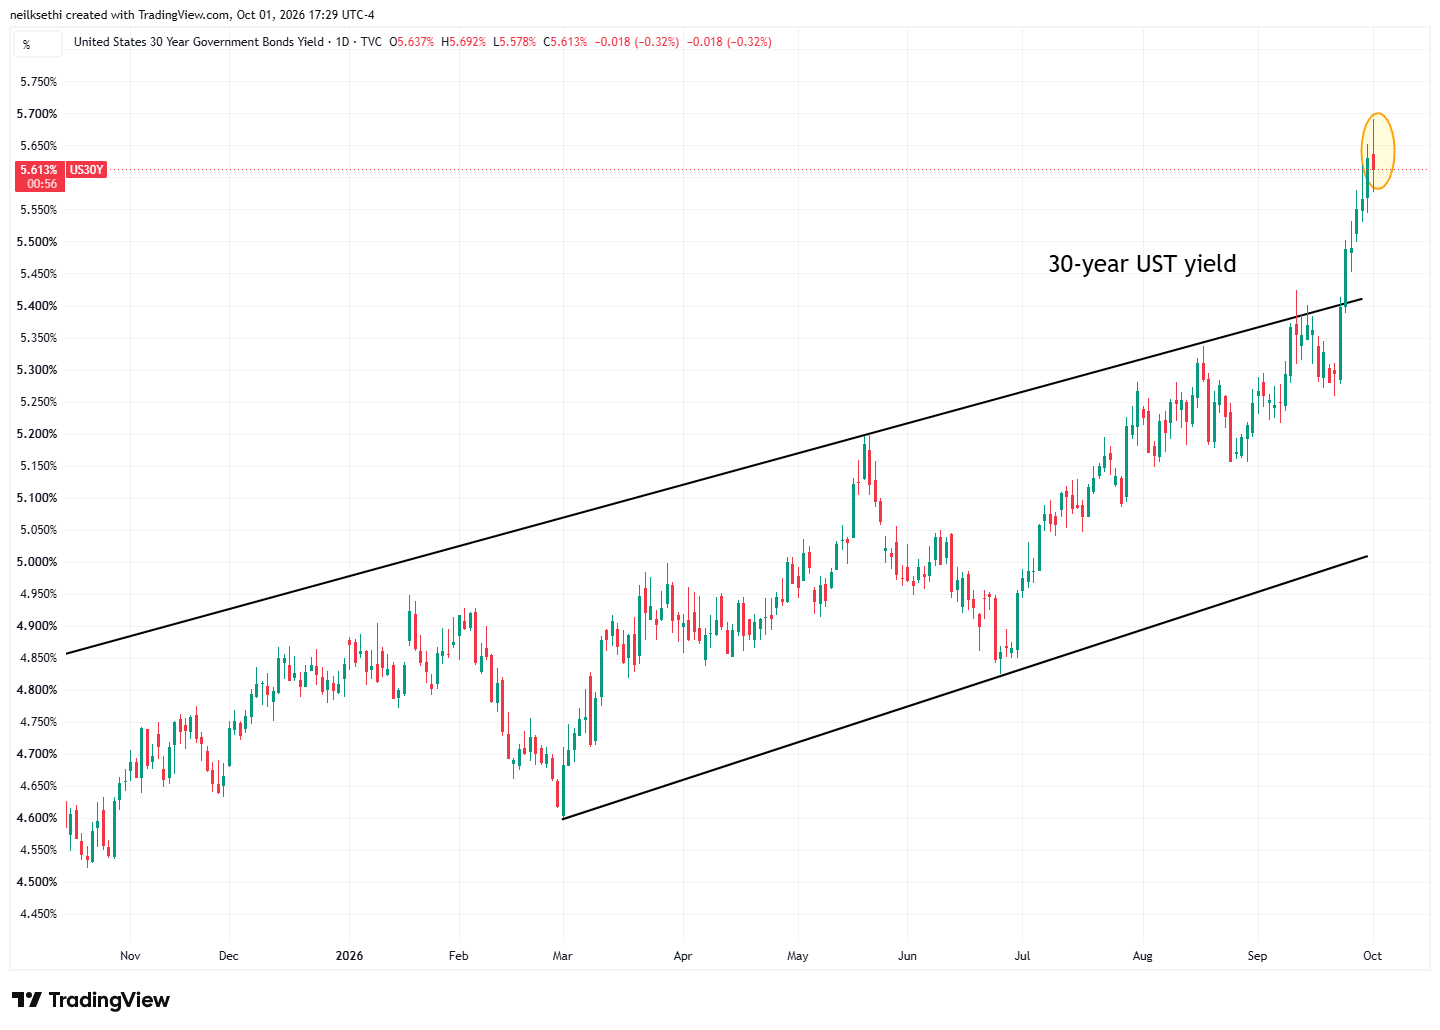
30-year yields down two basis points to 5.61%, from the highest close since May 2002.
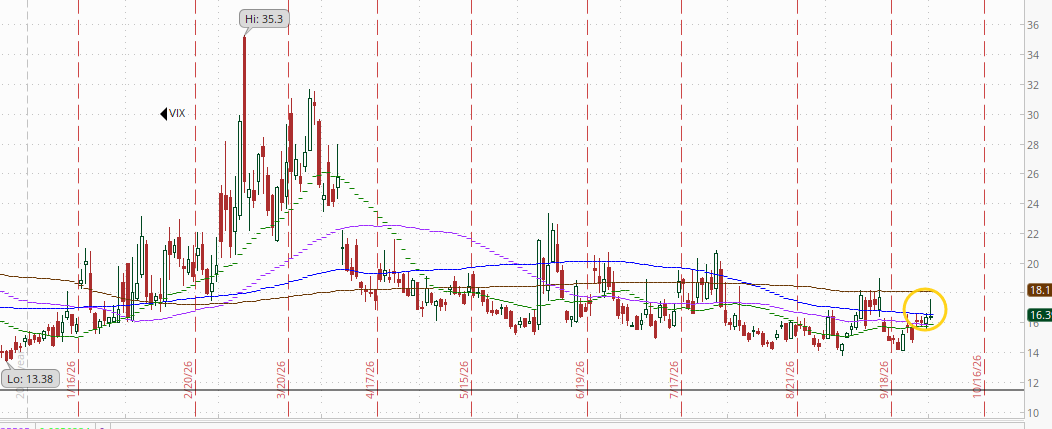
VIX edged up to 16.4. That’s consistent with ~1.03% average daily moves in the SPX over the next 30 days.
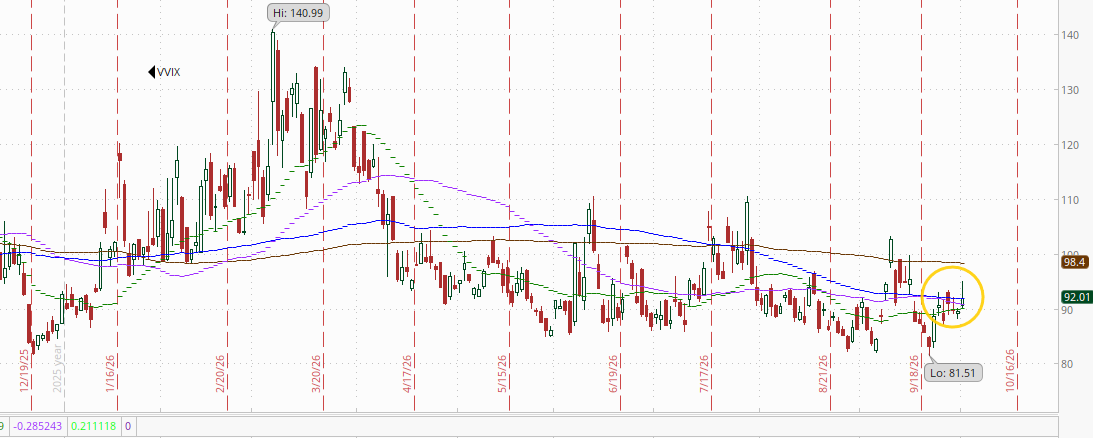
The VVIX (VIX of the VIX) edged up to 92.0, also remaining very subdued.
The current level is consistent with “moderate” daily moves in the VIX over the next 30 days (historically, normal is 80-100). Above 100 is the level flagged by Charlie McElligott as indicating higher stress.
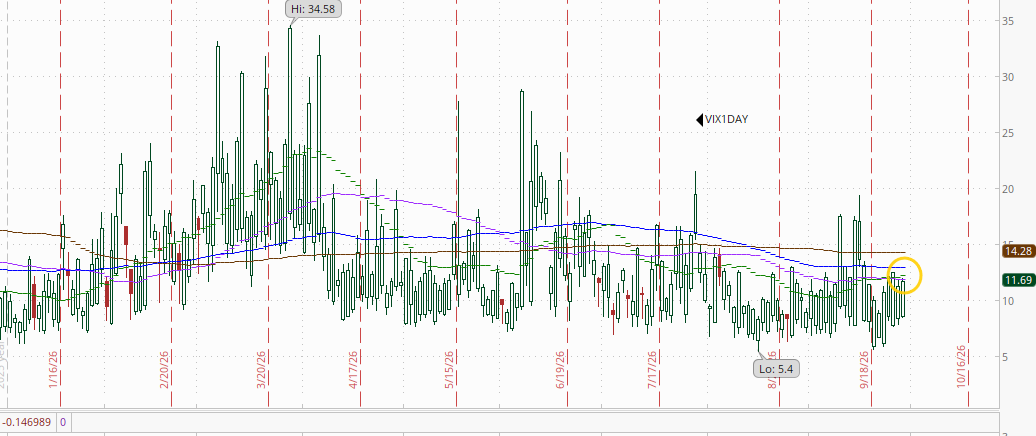
I had said the 1-day VIX “should move higher tomorrow with NFP Friday,” but it was unchanged at 11.7 meaning markets are not expecting a big reaction following the payrolls print. The current reading isconsistent with a move of 0.73% in the SPX next session.
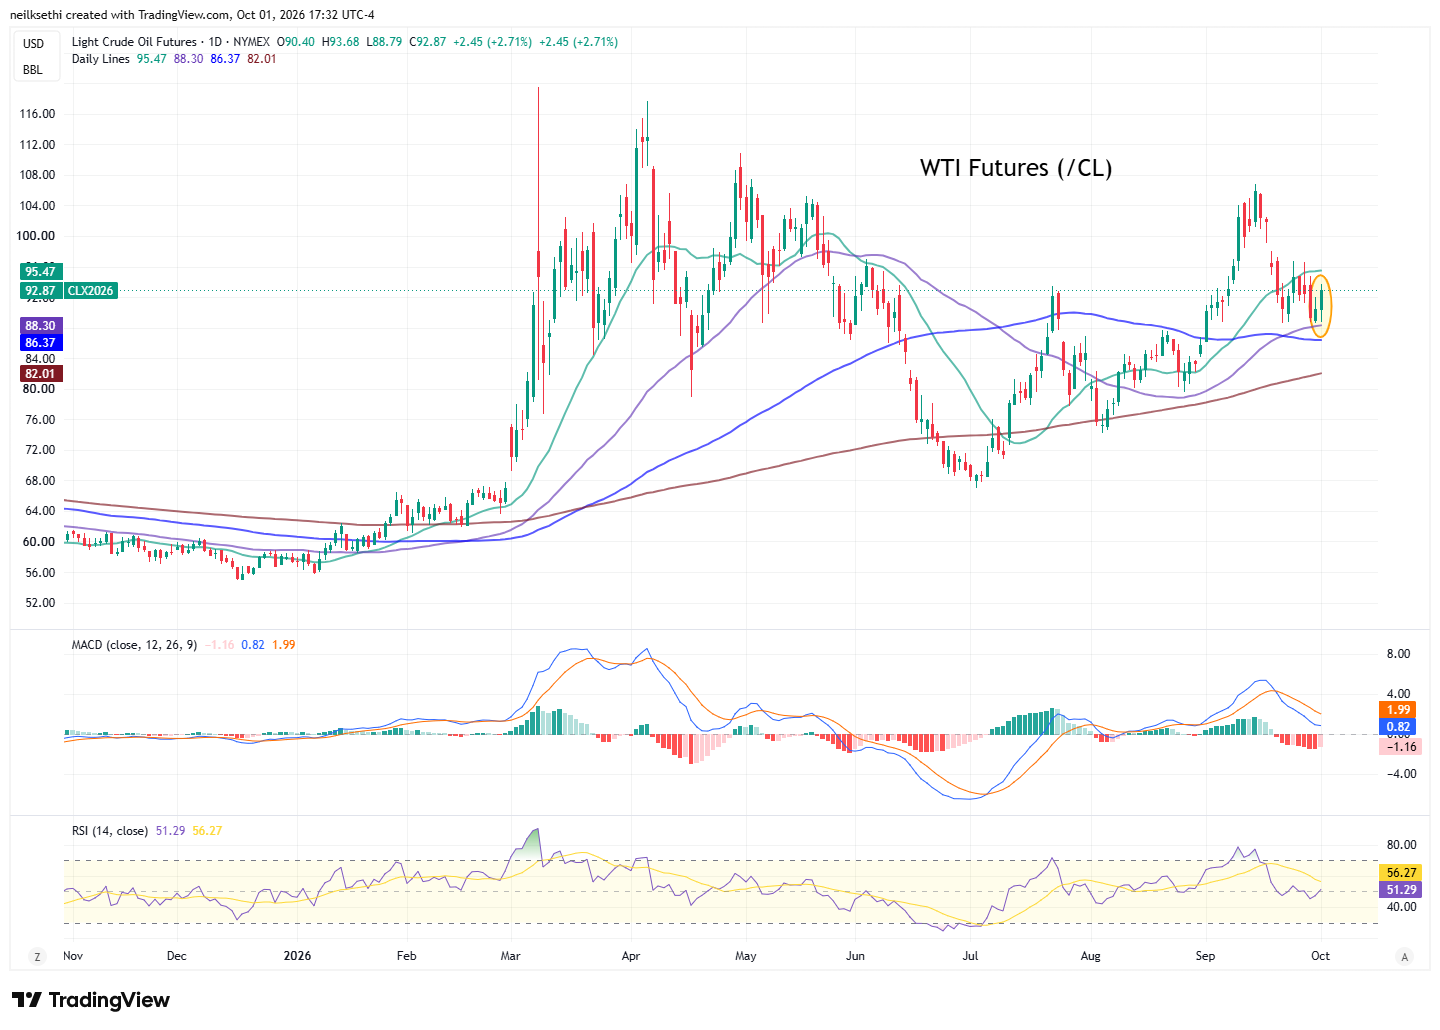
WTI futures (/CL) up 2.7% (including after-hours) remaining in the middle of their post-war range.
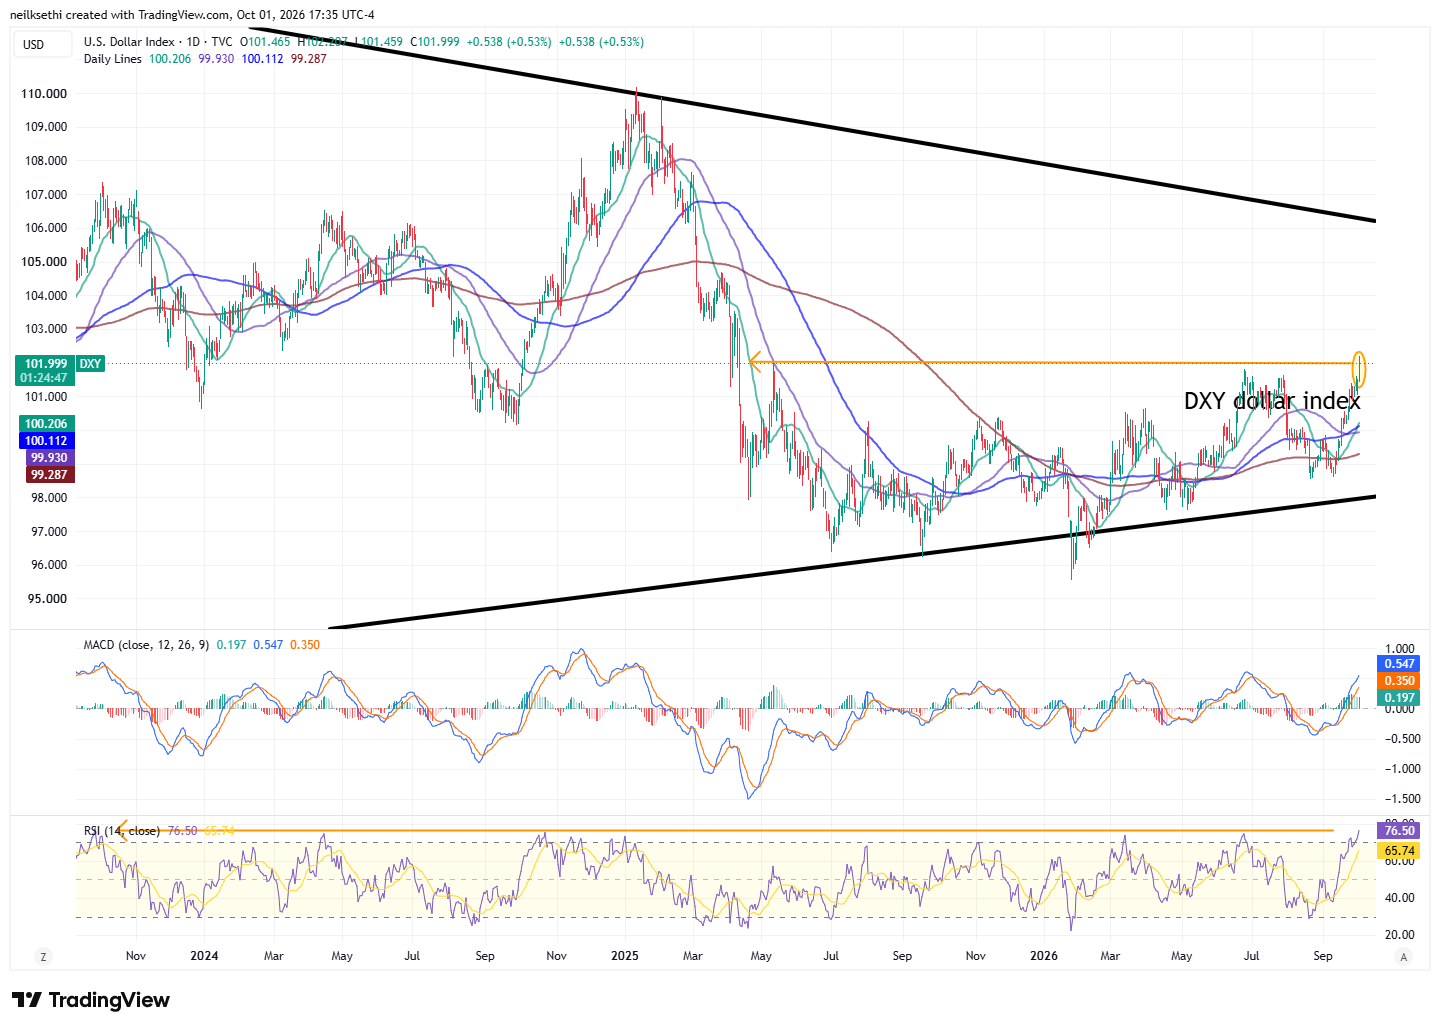
The DXY dollar index (which is fixed weighted with a heavy (57%) weighting vs the euro), shot higher to the highest close since April 2025 (which comes after its best month since June).
As I mentioned two weeks ago “The daily MACD remains positive and the RSI is above 60 so it continues to have strong technical support.” This opens up a run higher, although it’s the most overbought since September 2023.
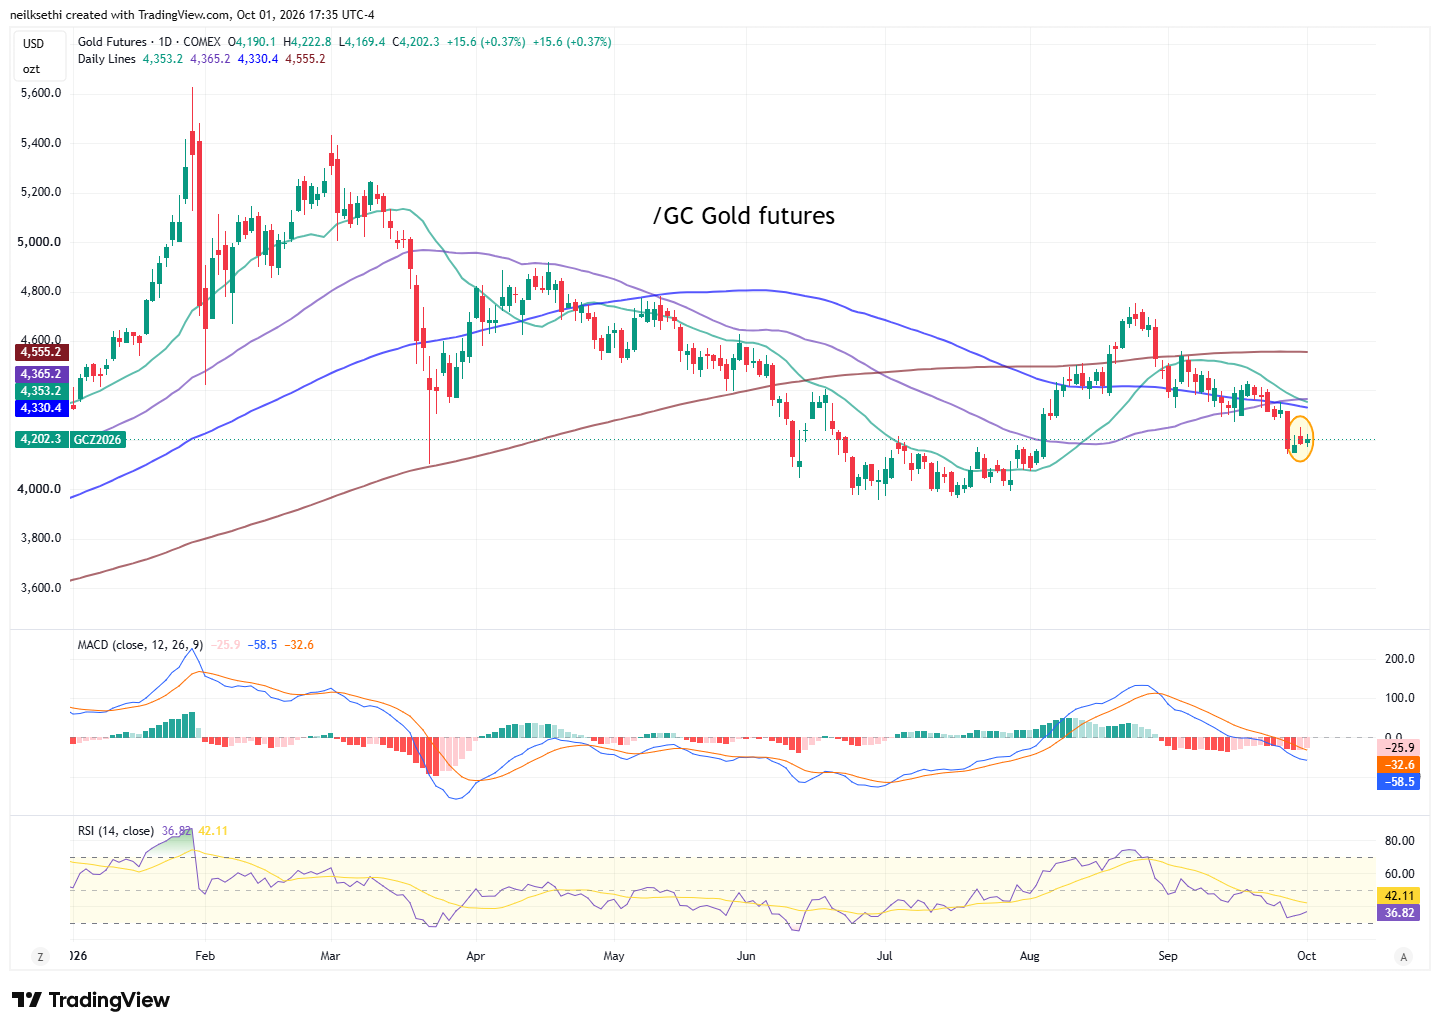
Gold futures (/GC) continue to stabilize. As I said earlier this week, “the daily MACD remains negative and the RSI is under 40 so it’s going to take some time.“
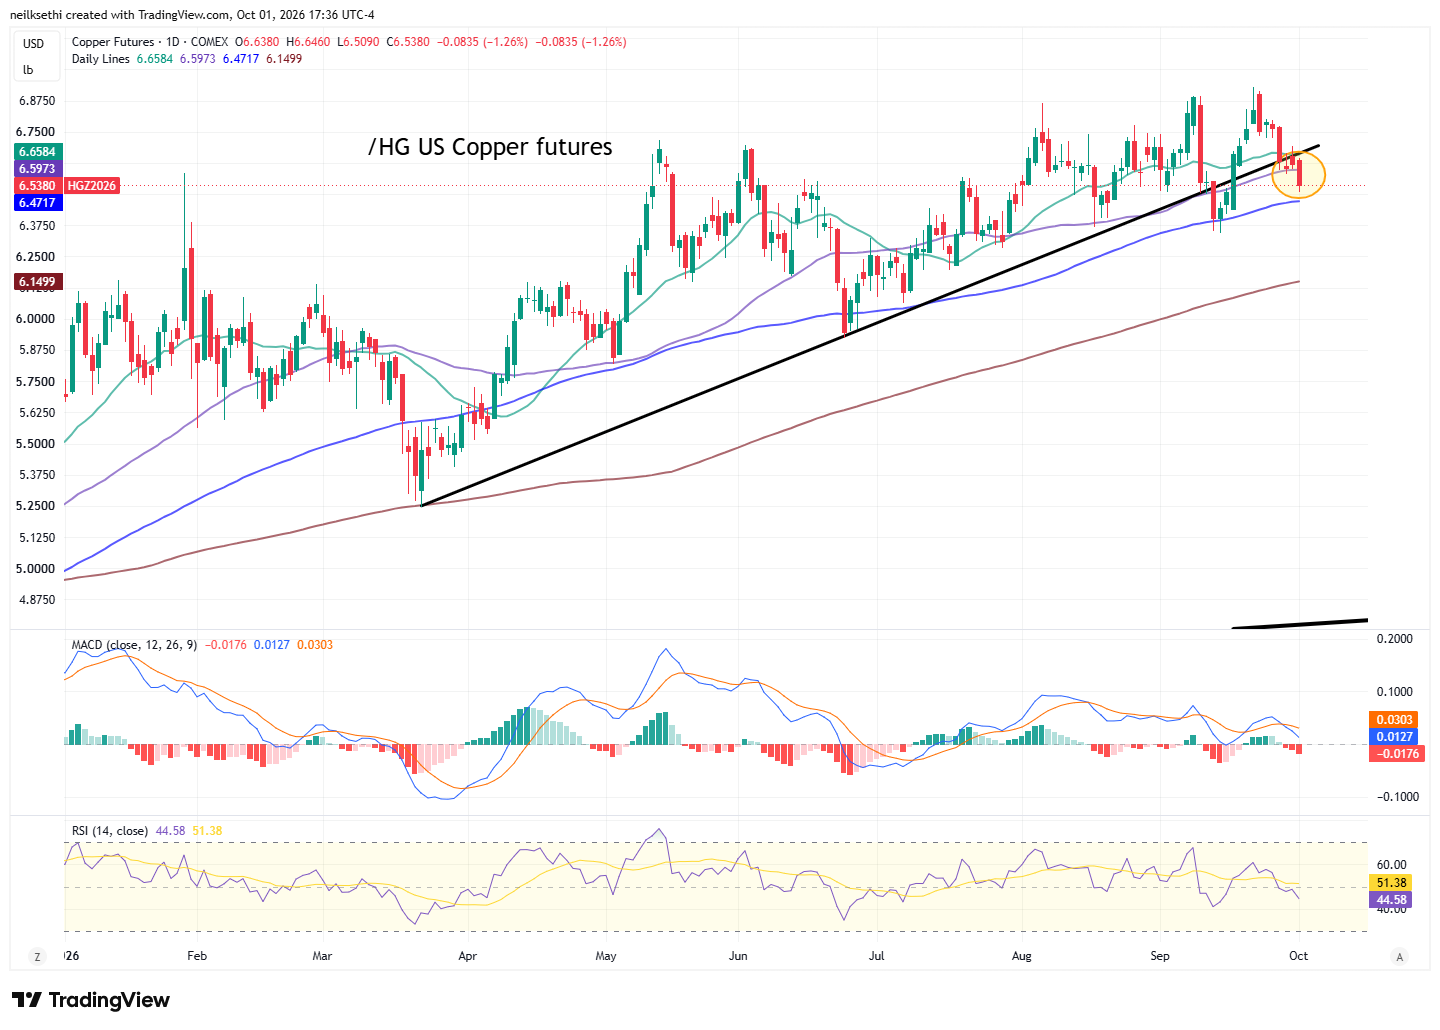
Despite the strength in the AI-trade today, US copper futures (/HG) dropped over 1% through the 50-DMA. As noted Tuesday the daily technicals have now softened to negative. As I said then “Given it made its stand at the start of the month at the 100-DMA, I’m going to give it that room again this time.” Looks like that will be tested soon.
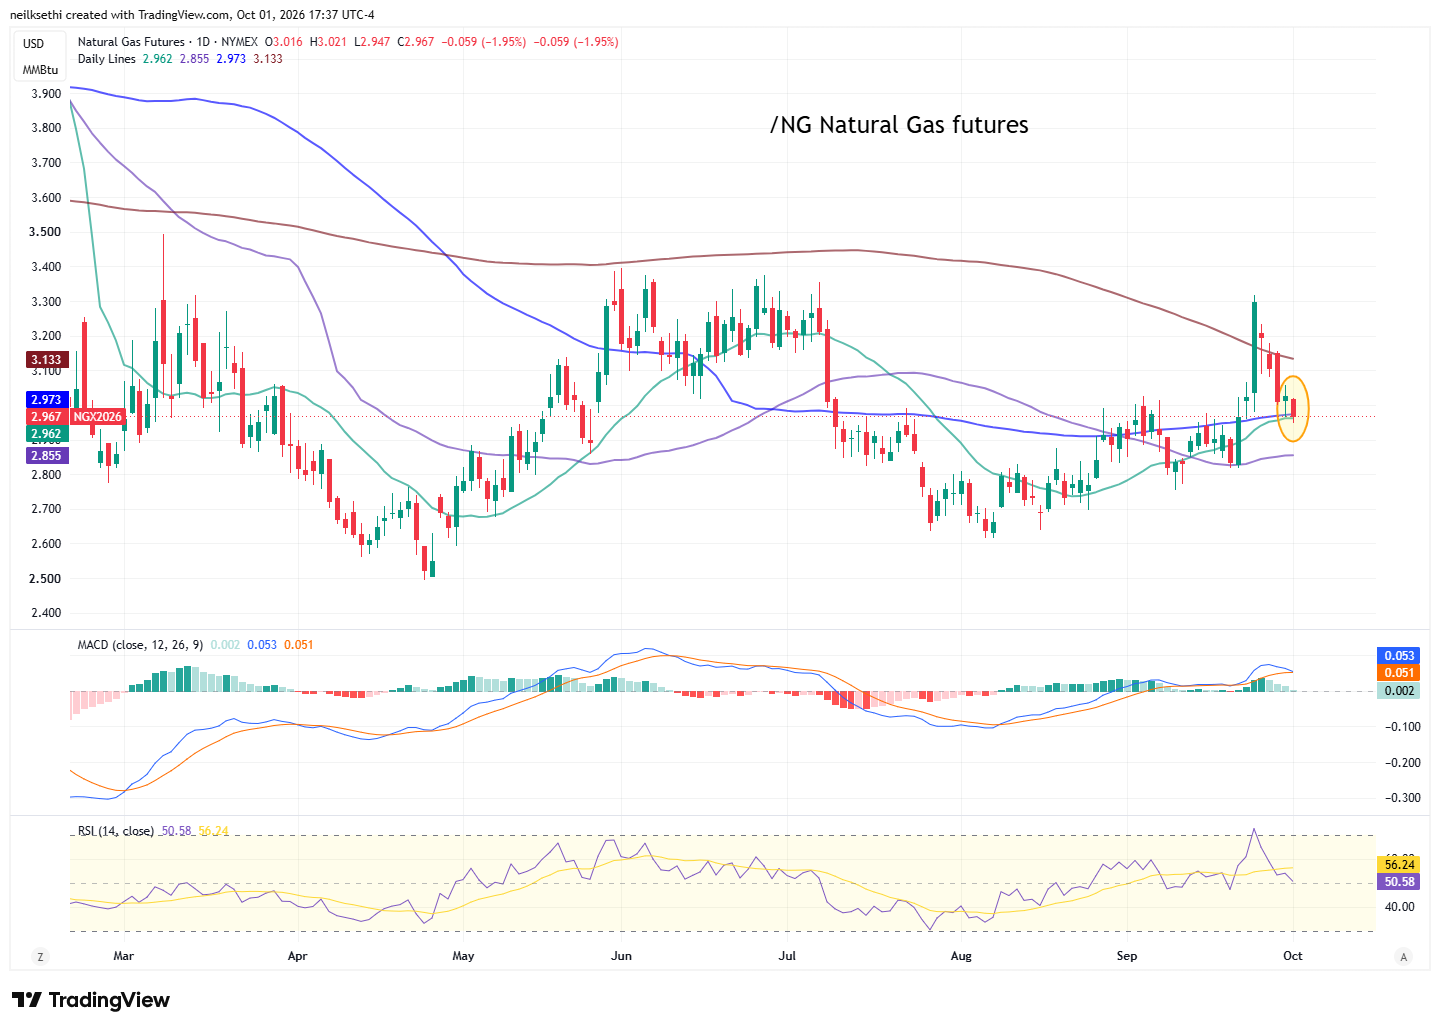
US natural gas futures (/NG) fell back for a fourth day in five in the middle of what is now a larger trading range stretching back to March.
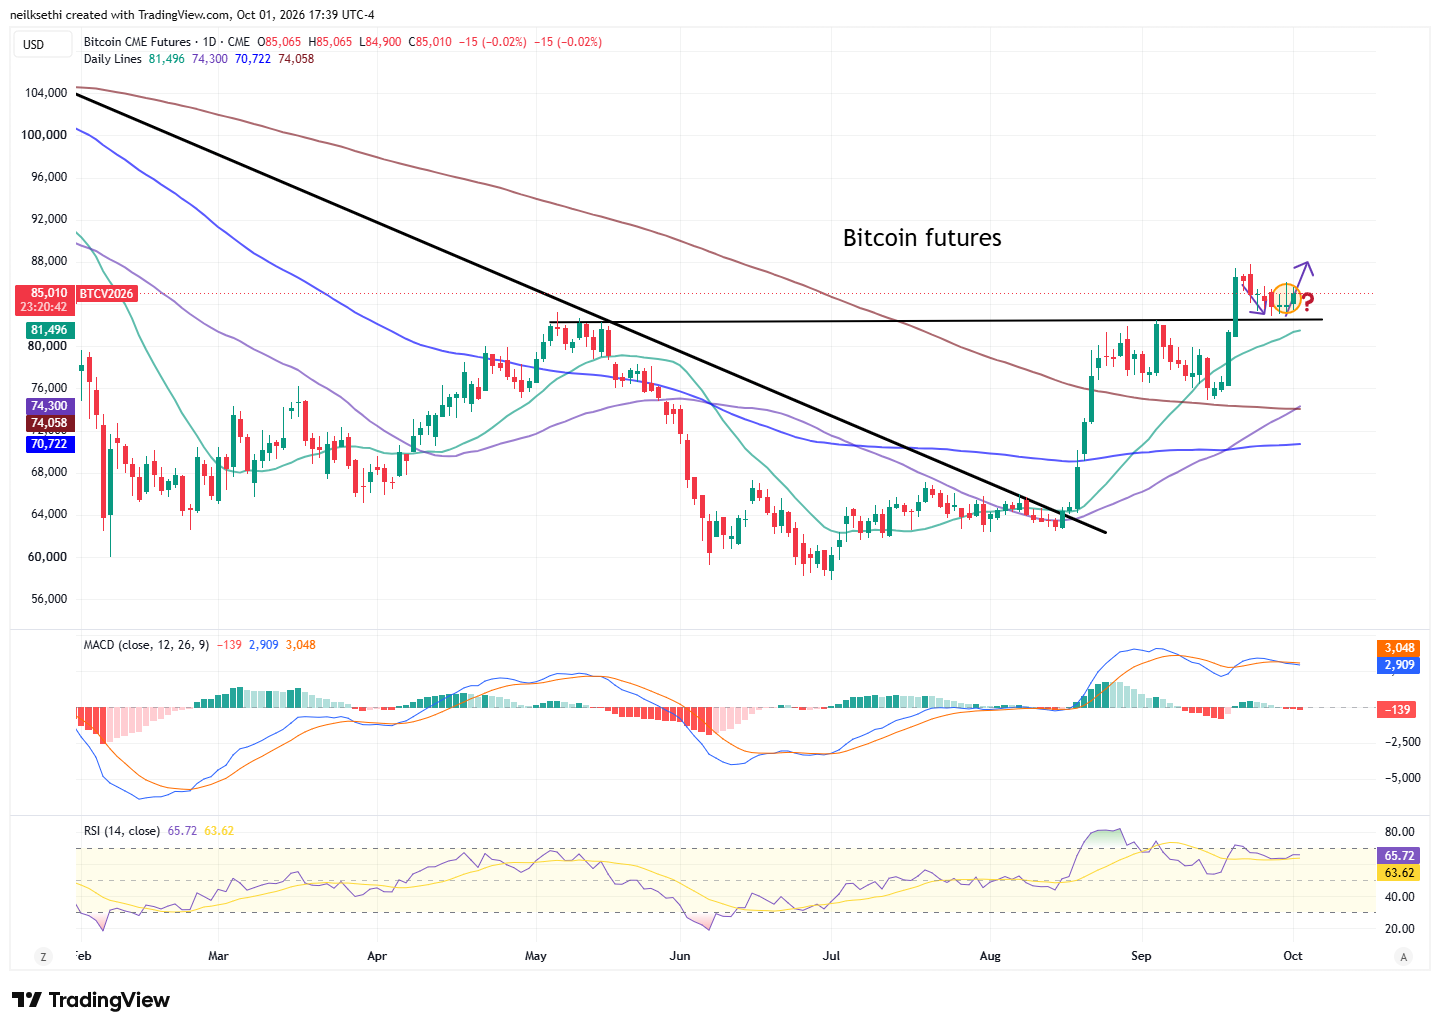
Bitcoin futures up over 1%, for now keeping alive the “natural path” (for bulls) I laid out over a week ago (in purple). Daily MACD has slipped negative while the RSI remains solidly positive for now.
More From TheStreet Pro:
- Stephen Guilfoyle – Bonds Crash the Party
- James “Rev Shark” DePorre –
And From Me If You Missed It:
- Job Cuts Hit 4-Year Low but September Hiring Plummets
- Initial Jobless Claims Remain Near 57-Year Lows; Continuing Claims a 3-Year Low
- ISM Sees Manufacturing Remaining Robust, Pushing Up Input Prices
- S&P Manufacturing PMI Eases From Flash Read, but Still Best Since May 2022
Miscellaneous:
Wrap-Up – A Reason For Hope (Episode III)?
I noted Monday
today was a reprise of Wednesday’s action. A push higher in interest rates sucking the life out of even the previously strong Tech trade. As to Tech that was a one-day blip and the trade came back Thursday and Friday. Will we see something similar this time as well?
As to the non-Tech trade, I will continue with my now well-worn statement that we have gotten to a place where things are very stretched in terms of the rout in bonds and non-Tech areas of the market. As I have noted, though, these things can continue well beyond where they “should,” so your guess is as good as mine as to when we see at least a short-term reversal. It will come at some point, so all we can do in the meantime is wait and try to stick with what’s working.
And as I said Tuesday
today was tracking along with Monday’s action, right up until NY Fed President Williams’ speech discussed above. Could that mark a turning point in this seemingly never-ending press higher in yields? Certainly too early to tell, but we can always hope right? As noted we’re also seeing more and more calls to buy bonds, and we know that pension funds are modeled to be big buyers this week.
And Wednesday I noted
now the list of positives grows somewhat. The pension rebalance is behind us, and we embark on the seasonally strong first half of October. The first of the month will also bring new 401(k) flows, and we saw evidence that the tech trade is reengaging.
Doug Kass also noted today that “the S&P Short Range Oscillator remains in a deep oversold at -4.98% vs. -5.37%”. That -5% level is one that has often been flagged as buyable.
And while it’s early days, we at least broke the streak of higher yields, lower stocks we saw the last three sessions with both bonds and stocks rallying (or at least moving higher) together. And we did also get a second day of bounceback in the Tech/AI trade. Too soon to call these trends, but let’s at least call them a good start.
Big day tomorrow with the employment situation report, although I think a little heat was taken out with the back-to-back comments from Williams and Jefferson implying an October rate hike is unlikely (making this data point less important). However, a big surprise to the downside could catalyze that larger pullback in yields I’ve been insisting is coming. Not exactly sure how equities would react.
The Day Ahead – The Grand Finale
US economic data Friday culminates in the September Employment Situation Report. A blurb from Morningstar is below. We’ll also get August factory orders.
Fed speakers light with just Dallas Fed President Logan making welcoming remarks.
Non-Bill (>1yr in maturity) US Treasury auctions off this week.
No SPX components reporting Friday.
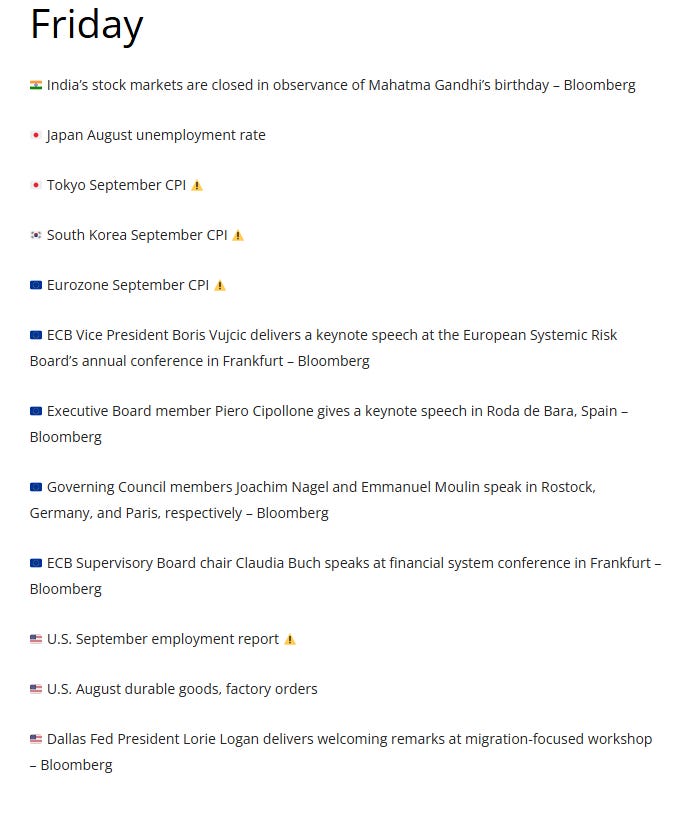
Ex-US highlights are Japan September Tokyo CPI, monetary base, August jobless rate, job-to-applicant ratio, Italy August retail sales, Eurozone September CPI.
China will be on holiday through October 7th for National Day (Golden Week). India’s stock markets will be closed Friday in observance of Mahatma Gandhi’s birthday.
From Christophe Barraud’s international Week Ahead rundown:
At the time of publication, Sethi was long MU, GOOG, AVGO, PSKY, QQQ, SPY, RSP, IWM, CPER, IBIT, and numerous equities in the energy sector.
As a reminder comments are encouraged. If they are directed at me, please put @NeilSethi in front.