New Micron Price Target After Blowout Earnings Prove Wall Street Wrong
The memory chip design king just posted video game numbers in its latest release.
You've reached your free article limit
You've read 0 of 1 free Pro articles.

On Wednesday afternoon, memory chip design king Micron Technology (MU) released the firm’s fiscal fourth quarter financial results. For the period ended September 3, Micron posted an adjusted EPS of $33.42 (GAAP EPS: $32.87) on revenue of $54.229 billion. These top- and bottom-line results simply crushed Wall Street’s expectations while that sales print was good for year-over-year growth of 379.3%. These numbers are the stuff of fantasy. They are like video game results.
Chairman and CEO Sanjay Mehrotra commented in the press release:
“Micron delivered record fiscal 2026 results, and we expect an even stronger fiscal 2027. AI is becoming Super Intelligence (SI), and memory enhances this intelligence and the competitiveness of our customers’ platforms. We are increasing our investments in technology, products and manufacturing to help drive SI forward with our customers, and our Strategic Customer Agreements provide added confidence in the durability of Micron’s financial performance.”
Operations
As revenue generation popped for growth of 379.3%, the cost of goods sold increased 14.7% to $7.182 billion. That left a gross profit of $47.047 billion (+830.9%) as gross margin soared from 44.7% to 86.8%. Video game numbers. GAAP operating income grew 109.7% to $43.751 billion as GAAP operating margin popped from 32.3% all the way to 80.7%.
After accounting for interest, other income and expenses as well as taxes, GAAP net income hit the tape at $37.701 billion (+107.8%). This works out to $32.87 per fully diluted share, up from the year-ago comparison of $2.83. After adjustments for patent licensing charges and stock-based compensation, that EPS result lands at $33.42, fully diluted, versus $3.03 a year ago.
Business Unit Performance
Cloud Business Memory: Generated revenue of $16.283 billion (+258.4%), producing a gross margin of 83% (up from 59%) and an operating margin of 76% (up from 48%)
Core Data Center: Generated revenue of $18.002 billion (+1,041.5%), producing a gross margin of 90% (up from 41%) and an operating margin of 85% (up from 25%)
Mobile and Client: Generated revenue of $13.114 billion (+248.8%), producing a gross margin of 90% (up from 36%) and an operating margin of 88% (up from 29%)
Automotive and Embedded: Generated revenue of $6.824 billion (+375.9%), producing a gross margin of 84% (up from 31%) and an operating margin of 79% (up from 20%)
Guidance
For the current quarter, Micron is projecting revenue of $60 billion to $63 billion, which brings the low end of the range more than $2 billion above the $57.9 billion that Wall Street had been looking for. This also implies annual sales growth of more than 350%. The firm sees gross margin at 86.25% adjusted or 85.95% (GAAP). Operating expenses are seen at roughly $2.06 billion adjusted or $2.31 billion (GAAP). This would lead to an adjusted EPS of $37.15 to $39.15. Wall Street was looking for $35.92. This is a major beat.
Fundamentals
For the period reported, Micron generated operating cash flow of $43.973 billion. Out of that number came net capex spending of $10.774 billion. This left free cash flow of $33.199 billion (up from $803 million). Out of this number, the firm repurchased $650 million worth of common stock under the existing authorization and paid out $610 million in cash dividends to shareholders. The firm also paid down $10.043 billion in existing debt.
Turning to the balance sheet, Micron ended the quarter with a cash position of $73.453 billion, of which $30.019 billion is in longer-term or non-current marketable investments. That leaves “current” cash of $43.434 billion. The firm also has inventories of $10.372 billion on the books. That puts current assets at $91.07 billion. Current liabilities add up to $27.482 billion, including shorter-term debt of just $491 million. That puts the firm’s current ratio at 3.31, which is quite robust. If the entire cash position is counted, which is how every other firm does this, the current ratio rises to 4.41, which is superb.
Total assets amount to $195.888 billion. Less than 1% of that number is in intangibles. Total liabilities less equity comes to $57.51 billion, which includes long-term debt of $4.688 billion. Simply put, Micron could take care of what is left of its total debt load almost 15 times over, just out of cash.
Opinion
What’s not to like? The quarter was simply amazing. The guidance is just as amazing. Margins are off the charts. Cash flows are off the charts. The balance sheet is solid gold. The firm is even paying down its debt load. Talk about doing things right when it’s your time in the sun. Can this time in the sun last? Well, MU is trading at less than seven-times forward looking earnings and just posted video game numbers as well as video game guidance. It would be very difficult, as cyclical as this business has been in the past, to argue that MU is not grotesquely undervalued by the marketplace.
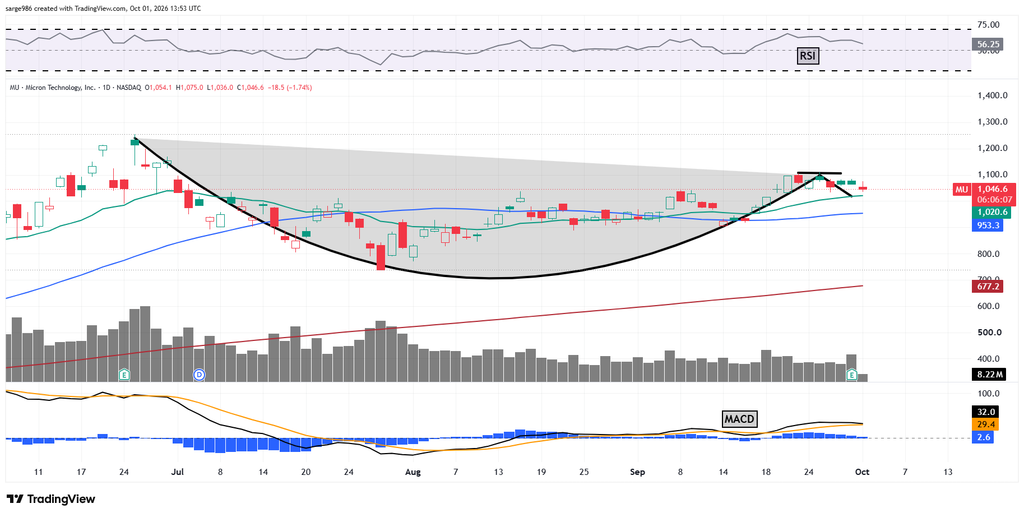
On the daily chart, MU has developed a cup-with-handle pattern with a $1,109 pivot. The indicators such as the RSI and daily MACD are no longer screaming, but both remain bullishly constructive.
Micron Technology (MU)
Target Price: $1,390
Pivot: $1,109
Add: Between 21-day EMA and 50-day EMA
Panic: Loss of 50-day EMA (currently $953)
At the time of publication, Guilfoyle was long MU equity.