More on AI Debt
Positions: None.
BY Doug Kass · Oct 28, 2026, 10:20 AM EDT
 Doug KassDoug Kass
Positions: None.
BY Doug Kass · Oct 28, 2026, 10:20 AM EDT
The following is from Peter Boockvar:
Kevin Warsh’s personal choice of relative silence about what he wants to do in the future we know has not been followed by many of his colleagues but he is the only one we hear from today and brief will be the statement and brief will be the press conference.
A quick review of some overseas news and economic data before I get to a flood of earnings calls. The Reserve Bank of New Zealand was expected to hike rates by 25 bps to 3% but they chose not to and the Kiwi is down 1.4% in response. They did though say rates are still likely to rise but the pause this meeting was a complete surprise.
The Bank of Thailand held its benchmark rate unchanged at 1% as expected. Australia said its trimmed mean September CPI was up 3.6% y/o/y as expected. We know the RBA has completely reversed its previous rate cuts post the inflation spike.
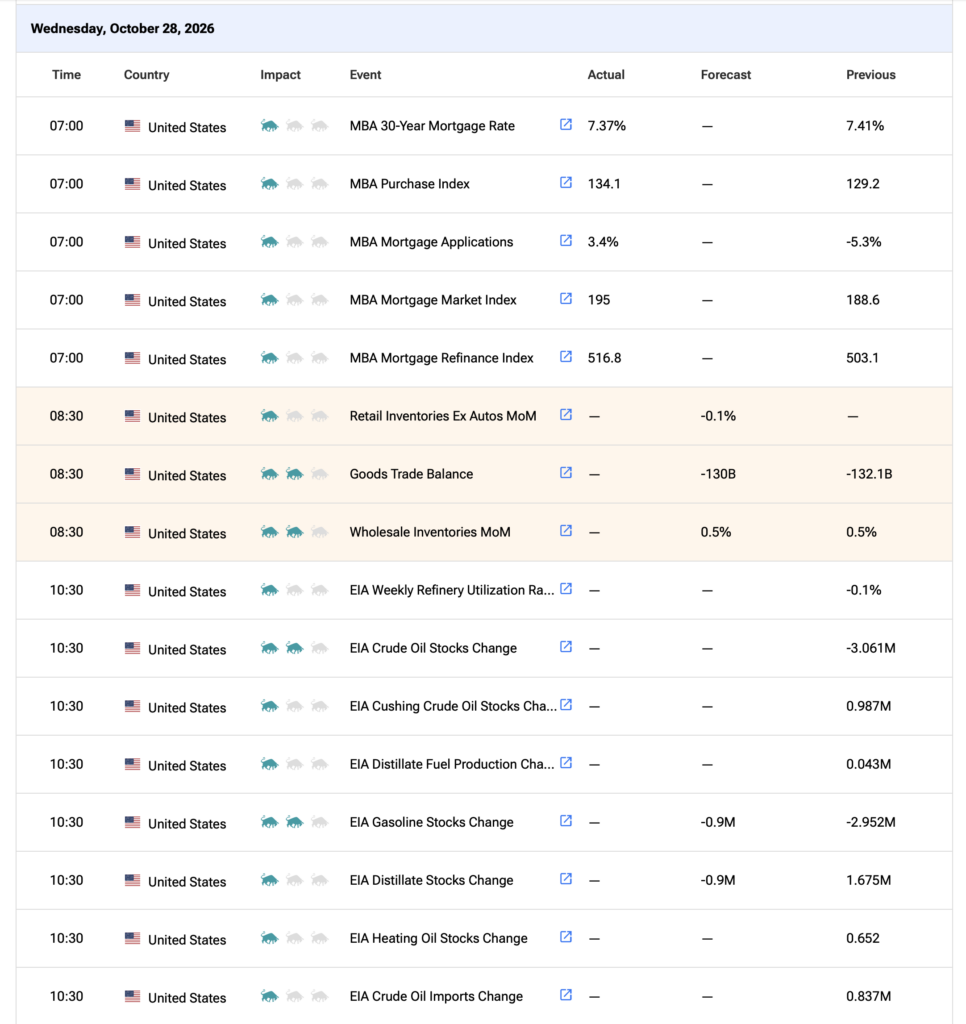
In the US, with the slight dip in mortgage rates, purchase applications rebounded by 3.8% w/o/w after 7 weeks in a row of declines. Refi’s rose 2.7% w/o/w after 9 consecutive weeks lower.
The economic message from the earnings calls continues to be the same, consumers are prioritizing experiences and travel spend, more discerning on other things and data center and some other non-residential construction are also economic outperformers.
From Coca Cola, down 1.6% yesterday and a stock own:
“the global operating environment continues to evolve. Geopolitical disruptions affect several parts of the world, cost pressures have accelerated, and all of these has an impact on many consumers.”
“While our own business continues to have a lot of momentum across those channels, I think the underlying pressure across the consumer landscape is there.”
“I think you’re seeing a stronger business at home versus away from home, largely driven by consumer pressures that we’ve talked about in the past. And while our own business continues to have a lot of momentum across those channels, I think the underlying pressure across the consumer landscape is there, and I think it will be there for the rest of the year as we go into ‘27.”
Specifically in North America, “Across our total beverage portfolio, we had strong volume growth from many brands, including trademark Coca Cola, Fairlife, Powerade, Fresca, and Smartwater.”
“Our commodity exposure overall remains manageable. However, we are seeing elevated cost pressures in aggregate, driven by increased logistics and transportation costs.”
From Hilton Worldwide, down 2% yesterday:
“Strength in travel demand supported by favorable macro trends is driving RevPAR outperformance, a trend we expect to continue into 2027.”
“RevPAR outperformance reflected strength in business and group demand, continued momentum following the World Cup and favorable calendar and holiday shifts….Leisure transient RevPAR was up 1.6% as demand normalized following a strong summer travel period.”
“In the US, we are seeing middle class real wage growth despite higher inflation, contributing to broad based strength we have described as a C-shaped economy. We believe we are uniquely positioned to benefit from this demand given our exposure to business travel, especially small and medium sized companies.”
To the question of whether higher interest rates are impacting the development of new hotels, “People are still able to get things financed, probably not as much as they’d like, but they’re obviously getting financed if our starts are up. And this is self-serving, but true, we’re more financeable. So in a world where not much is getting done, we just continue to take, I think, more and more share of the lessor amount that is getting done.” I bolded.
More on the leisure business, from Royal Caribbean, up 5.5% yesterday:
“we continue to see accelerated momentum as consumers prioritize our vacations and experiences. Travel remains the number one leisure category where consumers intend to increase spending. Traveling more is a top priority for a third of Americans, and consumers see cruising as a good value due to high quality onboard amenities, pricing that includes meals, accommodations, and entertainment, and the ability to visit multiple destinations in one trip.”
“That confidence is reflected in our booking activity. Since the last earnings call, booking volumes have increased in the mid-teens y/o/y, and bookings for 2027 sailings up in the high teens, demonstrating strong demand as we continue to build a strong base of business for 2027.”
And it’s not just boomers taking the cruise, “half of our guests are millennial and younger. And so, weekend getaways, three, four – they take more trips. They basically spend as much as they would on a short trip as a 6 or 7 night type itinerary.”
Lastly of note with Royal, “onboard spend has been much stronger than we thought it was going to be.”
With its fuel exposure, they hedge about half of it.
From Nucor, up 5% yesterday:
“Turning to our demand outlook, Nucor continues to expect steel mill shipments growth to finish closer to the higher end of our 5% to 10% range for 2026, supported by several durable underlying drivers.” Here is what they cited:
1)Infrastructure, “While the IIJA (Infrastructure Investment & Jobs Act) was passed about five years ago, the infrastructure investment activity it was meant to spur is still accelerating…Today, many projects are underway, but new ones are still being approved, and over $135 billion of funding has yet to be spent as of August.”
2)Reshoring and digital infrastructure, “supportive federal actions on tax, trade, and regulatory fronts have helped stimulate considerably higher levels of manufacturing construction…This is broader than the chip fab activity first encouraged by the CHIPS Act, and now includes sectors like pharma, automotive, appliances, and electrical components. And data center construction has gone from a small niche to a significant driver of non-residential building construction activity.”
3)Energy, “Rising demand, aging infrastructure, and the need to strengthen the grid are driving substantial investment in the power sector. Utilities plan so spend nearly $1.4 trillion over the next five years, with steel intensive investments ranging from generation and substations to transmission upgrades. Beyond power, we’re seeing strong demand across the oil and gas sector, including LNG terminals and pipeline construction and growing domestic production of oil tubular goods.”
From Corning, down 1% yesterday:
“Enterprise grew sales 84% y/o/y, with GenAI product sales growing more than 100% y/o/y, significantly outpacing GPU unit growth.”
From Johnson Controls, up about 5% as it’s become a data center play with its HVAC offerings:
“The demand environment also accelerated as we exited the year. Orders increased 44% driven by continued data center demand along with strong growth across other mission critical verticals including battery and semiconductor manufacturing and large research universities.”
From NXP Semiconductors, down premarket with results not good enough and a bit light with the guidance due to its auto business:
Data centers though are the main growth driver but small. Given the strength we’re seeing year-to-date, we now expect our revenue to exceed the $500 million outlook provided earlier this year. Given the new products we’re developing, combined with expanding customer engagements, we now expect this business to be over $1 billion in a couple of years.”
From UPS that rallied almost 6% in response to earnings:
“In the US, we are now past the inflection point on several key elements of our strategy, with clear evidence in our volume, operating profit and operating margin performance.”
Internationally, “The momentum we saw in the 2nd quarter across the China to US and Asia-to-Asia trade lanes continued in the 3rd quarter, supported by investments we’ve made across the region. In addition, US inbound volume rebounded in September further strengthening our 3rd quarter performance.”
“Demand from SMB (small, medium sized businesses) customers was strong, with average daily volume up 3.7% y/o/y, with growth coming from nearly all industries, including healthcare.”
“Turning to the holiday season. US consumers remain resilient and the outlook for holiday demand is strong. Industry forecasts for holiday online retail sales project an average increase of approximately 9% compared to last year.”
In the challenged part of the US economy, housing, this is what Whirlpool said and whose stock fell 6% Monday and rallied almost 4% yesterday:
Sales were “impacted by softer industry demand in North America.”
“More recently, we announced an additional 7% price increase, effective November 1 in Canada and December 3 in the US” and “we expect this action, combined with our structural cost takeout actions to further expand margin in 2027.”
To the question of whether these price hikes where it’s been almost 20% in North America this year are being absorbed, “by and large, it’s sticking. I absolutely, today, do not see an impact on the overall category demand from a consumer perspective. Again, it’s a replacement market…So the elasticity, if you want to say so, is very limited.”
Finally with WHR, “While we made progress on our pricing and cost takeout actions, this progress was partially offset by higher raw material, fuel and logistics costs.”
From Sherwin Williams, down 2.7% yesterday:
Impacting gross margin in part was “higher raw material and supply chain related costs…From a cost perspective, we are not immune from inflation. We will continue to manage this variable through targeted pricing actions as needed, disciplined control of general and administrative expenses, and simplification initiatives that drive speed and efficiency.”
“Given our current visibility, we expect raw material inflation to be in the low to mid single-digit range for 2027, with the largest y/o/y impact in the first half of the year before moderating in the second half. We also expect other parts of the cost basket to inflate, including energy, fuel, healthcare, wages and technology and software licensing.”
“From a demand perspective, we expect a continuation of softer for longer, with continued choppiness across most end markets. The leading indicators we track point to few positive catalysts at this time.”
From SoFi and whose stock popped by 13%:
“Member activity remains very strong. We continue to attract above average earners while spending, saving and investing trends remain positive. Credit performance once again improved and remains firmly in line with our expectations with all-in personal loan net charge-offs of 3.4%.”
“We are not seeing evidence of a slowdown in how many members borrow, spend, save, or invest…For personal loans, we saw very strong credit performance for the quarter.”
More on credit card use, from Visa, trading down premarket:
“US payments volume grew 10% y/o/y, generally consistent with Q3, as we saw several factors from Q3 continuing to play a role, including the cost of fuel, retail, strong Visa Direct growth, and FIFA World Cup related spend.”
“Growth across consumer spend bands remained relatively consistent with prior quarters, with the highest spend band continuing to grow the fastest. We did not see signs of the lower spend consumer weakening in our volumes.“ I bolded to highlight.
“Anyone in this country who wants a job for the most part has a job and that strength of employment, despite consumer uncertainty, is delivering the strength that you’re asking about and ultimately, I think, driving the strength in spending.”
On the use of Muse and Instinct and other agents doing buying for you, “I think it’s still very early. If you just look at just even the user numbers that are public for Muse, it’s still very early in terms of the number of consumers that are doing this. And certainly in the big scheme of things in our overall business, it’s a very small amount. Having said that, we remain very excited and have deep conviction about agentic commerce and the promise that it offers, not just for buyers and sellers, but for Visa.”
BY Doug Kass · Oct 28, 2026, 10:15 AM EDT
$KO: JPMorgan raised the firm’s price target on Coca-Cola to $98 from $95 and keeps an Overweight rating on the shares. The firm views the company’s Q3 report as strong.
KO: Morgan Stanley analyst Dara Mohsenian raised the firm’s price target on Coca-Cola to $103 from $100 and keeps an Overweight rating on the shares. “Solid” Q3 results highlight sustained higher organic sales growth than peers, with robust pricing power, sustained share gains, and strong Fairlife growth, the analyst tells investors.
KO: Piper Sandler raised the firm’s price target on Coca-Cola to $103 from $102 and keeps an Overweight rating on the shares. The firm remains bullish on Coca-Cola and its long-term growth outlook and continues to believe its best-in-class execution positions the company more favorably vs. peers, even in a tough consumer environment.
KO: Wells Fargo raised the firm’s price target on Coca-Cola to $100 from $90 and keeps an Overweight rating on the shares. The firm says Coca-Cola is entering a “great” debate. After a year in which virtually every key metric was great, and the stock’s performance matched, investors are beginning to ask whether “great” this year makes it harder to exceed expectations next year. That narrative is still in its early stages, but becoming the focus of that debate may be the stock’s next key challenge, the firm argues.
KO:Citi analyst Filippo Falorni raised the firm’s price target on Coca-Cola to $103 from $102 and keeps a Buy rating on the shares.
$KMB: UBS analyst Peter Grom raised the firm’s price target on Kimberly-Clark to $113 from $106 and keeps a Neutral rating on the shares. Kimberly-Clark’s Q3 results missed on revenue but beat earnings on better SG&A and below-the-line items, while reiterated FY26 guidance was better than feared and drove a share rally likely amplified by positioning, the analyst tells investors in a research note.
Long KO VS KMB VS
BY Doug Kass · Oct 28, 2026, 9:45 AM EDT
From “Meet” Bret Jensen:
Bret Jensen
1h ago
I am sure this is nothing to worry about dept.
US life insurers now own about 15% of all public data center credit, and up to 85% of some individual deals. At Athene, Barclays’ tally of digital infrastructure holdings comes to 105% of statutory surplus.
Positions: None.
BY Doug Kass · Oct 28, 2026, 9:25 AM EDT
BY Doug Kass · Oct 28, 2026, 8:59 AM EDT
Source: TipRanks
BY Doug Kass · Oct 28, 2026, 8:48 AM EDT
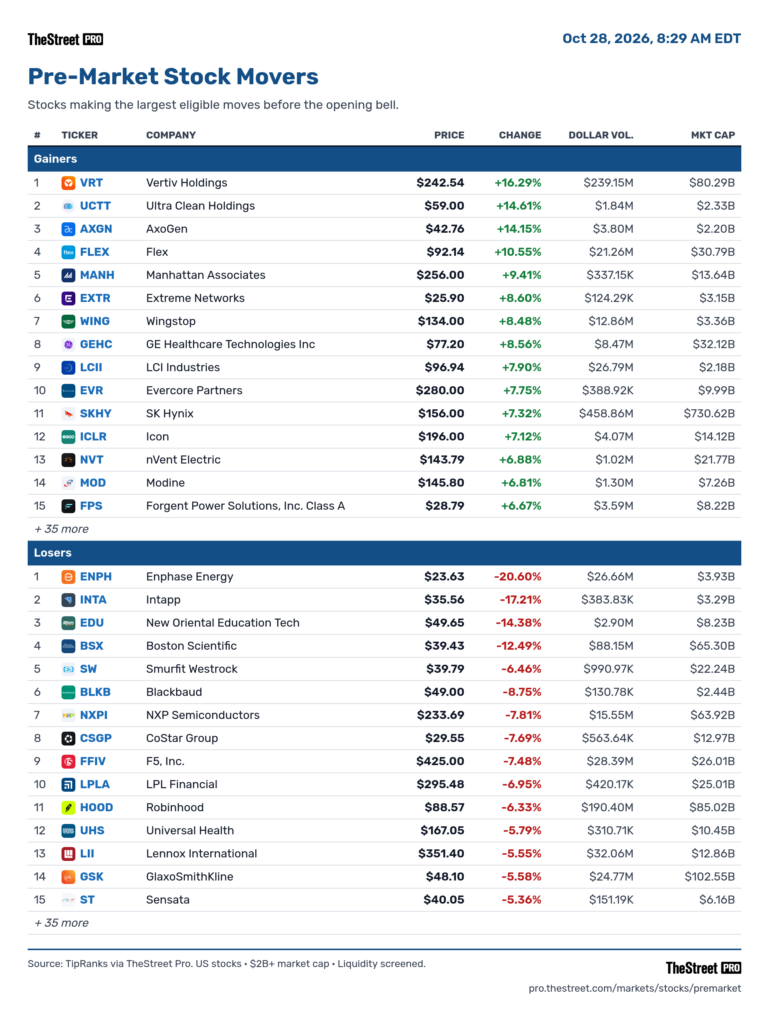
– ULBI +145% (agrees to be acquired for $16.00 a share in cash)
– BOOM +21% (Q3 sales and adjusted EBITDA exceeded the high end of guidance as backlog and cash flow strengthened)
– AXGN +16% (Q3 beat and full-year revenue guidance was raised)
– VRT +16% (Q3 organic orders more than doubled and full-year sales guidance was raised by $650 million)
– UCTT +15% (Q3 results and outlook drove a sharp upside reaction)
– LUNG +12% (Q3 results and outlook drove a sharp upside reaction)
– GEHC +9.7% (Q3 beat, full-year EPS and free-cash-flow guidance was raised, and a $945 million acquisition was announced)
– FLEX +9.5% (fiscal Q2 beat and the full-year outlook was raised)
– LCII +7.6% (confirms an unsolicited $101-a-share cash acquisition proposal)
– SKHY +7.5% (quarterly revenue exceeded 100 trillion won for the first time)
– STLA +6.9% (Q3 net loss narrowed about 90% and the 2026 outlook was reaffirmed)
– ETSY +6.6% (announces a leadership transition)
– SNDK +4.2%, MU +3.6% (memory names rise after SKHY posted record quarterly revenue)
– GEV +2.4% (Q3 orders surged 96%, backlog reached $197 billion, cash-flow guidance was raised and the buyback authorization doubled)
– RAPP -23% ($350 million of stock and convertible-note offerings priced alongside a $30 million private placement)
– ENPH -19% (Q3 revenue missed and the Q4 sales guide was roughly 20% below consensus amid weak US residential-solar demand)
– INTA -17% (quarter beat, but the fiscal-year outlook failed to clear elevated expectations)
– EDU -13% (fiscal Q1 results disappointed investors)
– BSX -12% (Q3 EPS missed and Q4 and full-year profit guidance came in below consensus)
– LOGI -12% (holiday-quarter sales guidance called for a decline and included a $70 million–$80 million supplier-incident hit)
– SEDG -8.7% (solar-equipment sympathy decline following ENPH’s weak demand commentary and Q4 guide)
– NXPI -8.1% (Q3 beat, but the Q4 guide was only roughly in line and fell short of elevated expectations)
– FFIV -7.6% (Q4 beat, but fiscal 2027 growth guidance disappointed and operating margins contracted)
– HOOD -6.4% (revenue missed as crypto revenue fell 55%, outweighing an EPS beat and record total revenue)
– GSK -5.8% (headline Q3 beat was offset by weak vaccine sales, soft new-product performance and unchanged guidance)
– LII -4.7% (Q3 profit fell, segment margin contracted 240 basis points and the full-year EPS outlook disappointed)
– STX -2.5% (fiscal Q1 results prompted a modest sell-the-news reaction)
– V -1.7% (fiscal Q4 earnings and revenue missed forecasts despite healthy payment-volume growth and a 16% dividend increase)
BY Doug Kass · Oct 28, 2026, 8:38 AM EDT
BY Doug Kass · Oct 28, 2026, 8:33 AM EDT
Knowledge@Wharton Why Narcissistic Leaders Don’t Like Remote Work.
Why Narcissistic Leaders Don’t Like Remote Work – Knowledge at Wharton
Positions: None.
BY Doug Kass · Oct 28, 2026, 7:50 AM EDT
Position: None
BY Doug Kass · Oct 28, 2026, 7:39 AM EDT
Beginning at around 6 AM I shorted more indices on a scale.
Here is my cost basis today:
* SPY $771.07
* QQQ $724.38
Position: Short SPY (M) QQQ (VS)
BY Doug Kass · Oct 28, 2026, 7:20 AM EDT
Subscriber jryan (below) delivered some reasonable comments and criticism yesterday in the Comments Section.
Basically he said he is “getting sick of reading about cannabis and Fin TV commentary” — and he wants more (long) stock suggestions, etc.
I wanted to respond in the first column of the day.
* Few longs have represented value to me as I have been unduly negative for a lengthy period of time. I take ownership of that.
* The stocks that I have owned have recently been Staples (KO, PEP, PG and KMB), selected cannabis names and some others. The consumer nondurable stocks have been fine recently (and I have taken profits in them). We shall see about cannabis — a speculative sector and my focus has been intermediate-term based on the improved likelihood of rescheduling and other factors clearly delineated in my Diary.
*As to the CNBC constructive criticism. I point these out not only as an advocate of the retail viewer that should see timestamps (panelists taking ownership) and observe better company interviews, but so they can evaluate the merits and process of the panelists’ recommendations and become better-informed investors through more hard-hitting interviews (that serve more than as a marketing tool of companies).
* But the criticism directed to Fin TV also is intended to highlight investment recommendations from panelists and guests that I strongly disagree with. Choosing stocks to avoid (in that FIN TV criticism) can be as valuable or even more valuable than choosing stocks to buy. Consider my negative comments towards BA, BABA, META, UBER, NFLX, RDDT, TTAN, DIS, CLF, MRNA and UNH (a few years back) etc. that were mostly confidently and strenuously recommended on CNBC.
* My “More Tales From Nvidia” series is intended to deliver the idea that the functionality, productivity and ROIC on the enormous capital spend may disappoint the many and multitude of optimists on AI. I have felt that my contrarian and non herd-like observations were valuable in a backdrop of near-universal bullishness (that is readily and frequently available from the buy/sell sides, panelists and guests). My view was that dwelling on “More Tales” had statistical value in that over 40% of the S&P is comprised of large-cap tech.
* As to specific AI beneficiaries, I have admitted (often) of missing MSFT and GOOGL. The valuation on AAPL seems foolish to me — the shares have prospered and I have been wrong. But the others (META, AMZN and even NVDA) have not set the world on fire this year. As to memory and chip stocks, they have been “the world’s fair” up until the summer but awful since late June. Not only do I think these companies are “overearning,” but the volatility is not for me and not consistent and doesn’t conform with my appetite for risk.
* The financial stocks were quite strong until early summer. I repeatedly cautioned not to embrace banks, brokers and private equity shares (I successfully shorted BX, KKR and APOL since then). Viewed by panelists as perhaps the best “value play,” financials have been dismal over the last four months. We avoided this decline (in C, JPM, BAC, GS, MS et al).
* The stocks that I have been short in the AI sphere have been terrific (to the downside) — ORCL and CRWV. (Avoiding them as longs has also been a valuable contribution.) My recent foray into shorting NVDA was profitable also.
* As to my preoccupation with CNBC I suggest taking the number of words written about FIN TV and divide it by the number of words written on other subjects daily. You will find my criticism is dwarfed by my other columns. In the scheme of things my criticism is de minimis.
* Finally, to jryan I say there are many other contributors that actively recommend longs and provide a valuable service.
All this said I am imperfect.
I take ownership of my mistakes.
The transparency of my Diary exposes my blemishes.
I believe jryan has some good points and I will purposefully look for more long ideas in the future.
I truly appreciate jryan’s comments and I have tried to respond to his concerns:
jryan
Just a thought. There used to be a lot of different investment ideas, stock suggestions etc., but all it seems to be now is cannabis and CNBC commentary, which I don’t watch anyway. Kind of getting sick of it, especially the cannabis info, is it ever going to pay off? Likely, but it will be quite a while from today, if ever. But at least it’s easier to scroll through the commentary and use less time.
Position: Long KO (VS), PG (VS), KMB (VS), MSOS common (VL) and calls (VS), VRNO (VS), GLAS (S), GTBIF (S), TRLV (VS), CURLF (VS); Short AAPL (S)
BY Doug Kass · Oct 28, 2026, 6:30 AM EDT
Position: None
BY Doug Kass · Oct 28, 2026, 5:58 AM EDT
The S&P Short Range Oscillator remains in overbought at 0.91% vs. 0.80%.
Yesterday I re-shorted the indices.
Position: Short SPY (M), QQQ (VS)
BY Doug Kass · Oct 28, 2026, 5:35 AM EDT
Wall Street Bankrolled the AI Debt Boom for Months Now It’s Shocked There’s Too Much of It Tech giants raised tens of billions this week. They still need trillions more. “The concern is that, with trillions more in debt needed over the coming years, there appears to be a Show more


OIL: continues to signal higher 3-year Cycle Highs and we remain long of it in Brent terms

Welcome to AI finance: one data centre, a dozen claims on it. The SPV borrows against the building. The hyperscaler leases it. The lease payments back the bonds. The bonds get an A+ rating off the hyperscaler's name. Banks fund the SPV. Banks also fund the investors buying Show more