Based on a Truist composite chart of midterm seasonality since 1950, the S&P 500 is normally up only about 1% at the end of October, then finishing up about 5%. This year, though, the S&P 500 was already up 10.7% through October.
Bulls, though, can argue that while equities generally rise from the start of October into the election, in this case they are down approximately 3.5% from the October peak.
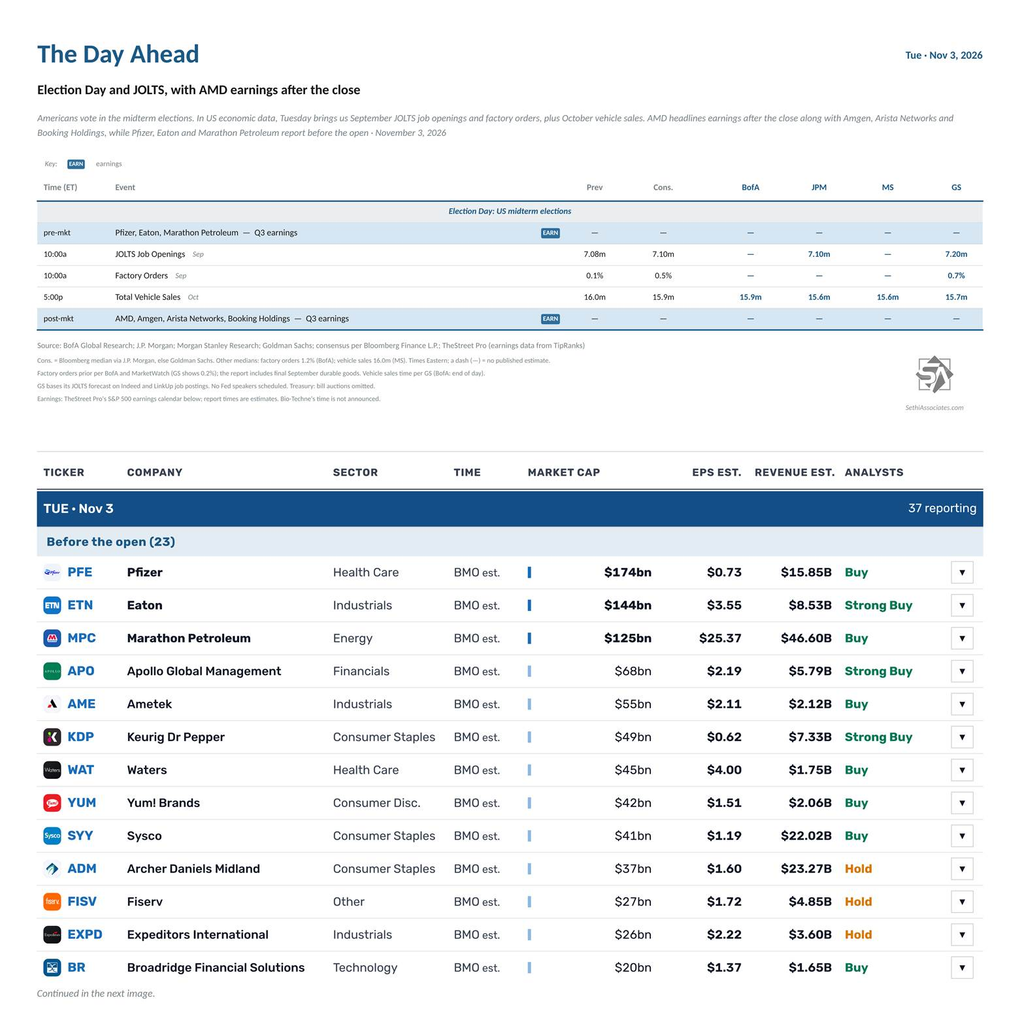
Elections, JOLTS, and AMD Highlight Tuesday’s Calendar
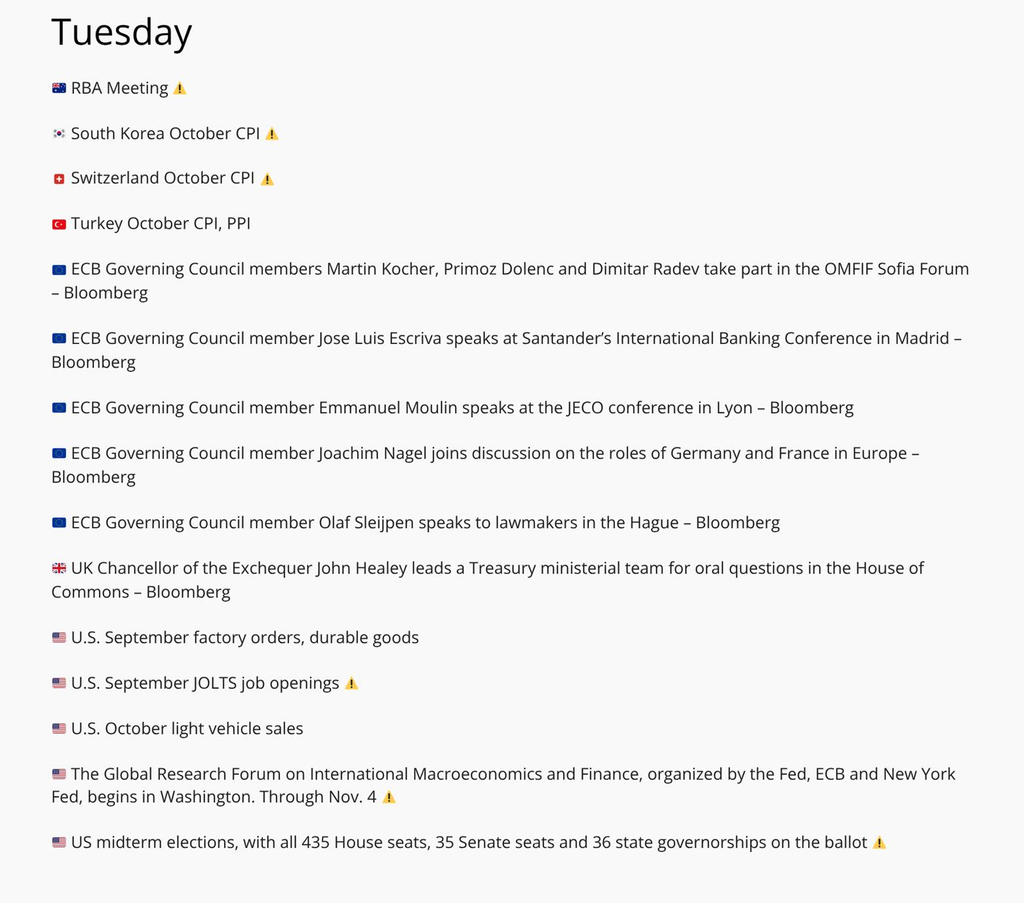
It’s Election Day, with Americans voting in the midterm elections (all 435 House seats, 35 Senate seats and 36 governorships are on the ballot).
In US economic data, Tuesday brings us September JOLTS job openings and factory orders (which include final durable goods), and October vehicle sales.
There are no Fed speakers scheduled, although the Global Research Forum on International Macroeconomics and Finance, organized by the Fed, ECB and New York Fed, begins in Washington (through November 4), so there may very well be media interviews.
There are no non-Bill (>1yr in maturity) US Treasury auctions this week.
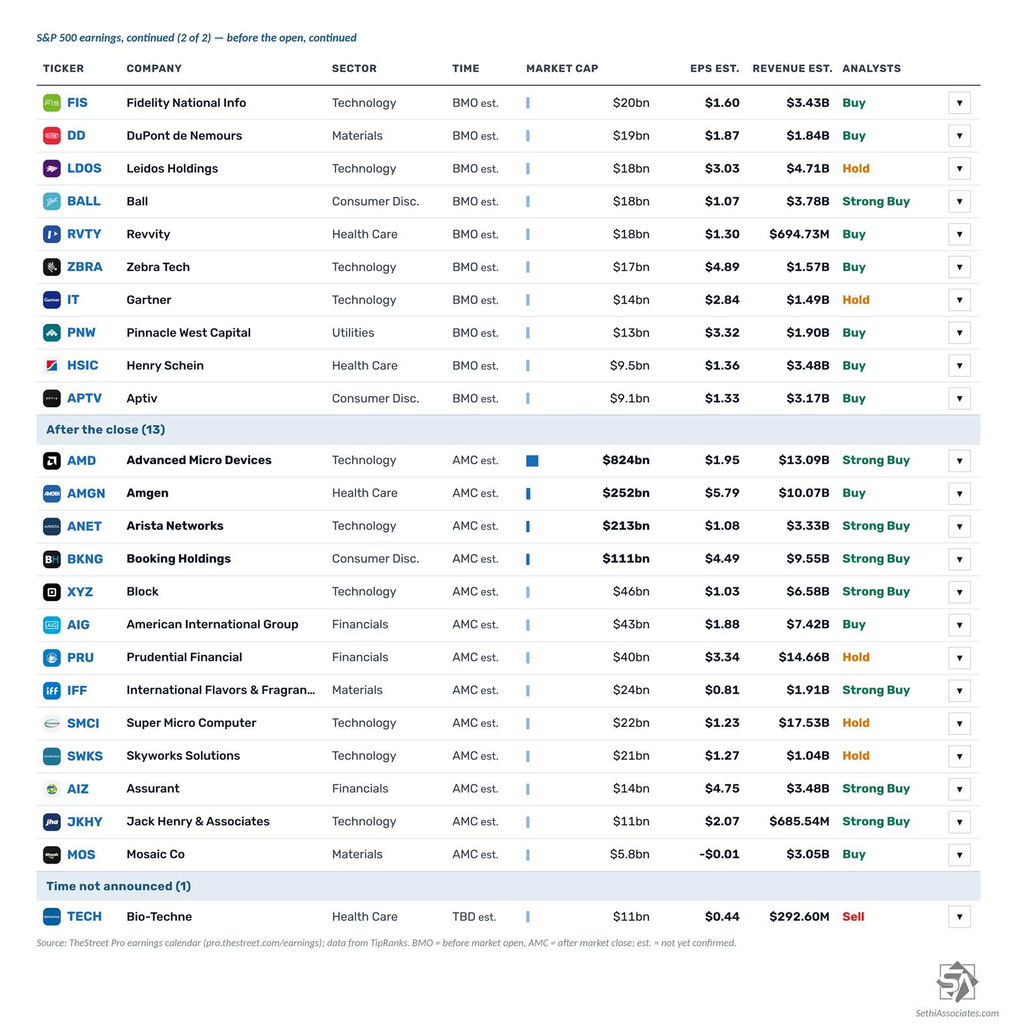
37 S&P 500 components report, seven of them with market caps over $100bn:
After the close: AMD (AMD), Amgen (AMGN), Arista Networks (ANET), Booking Holdings (BKNG), Block (XYZ), AIG (AIG), Prudential Financial (PRU), International Flavors & Fragrances (IFF), Super Micro Computer (SMCI), Skyworks Solutions (SWKS), Assurant (AIZ), Jack Henry & Associates (JKHY) and Mosaic (MOS)
Before the open: Pfizer (PFE), Eaton (ETN), Marathon Petroleum (MPC), Apollo Global Management (APO), Ametek (AME), Keurig Dr Pepper (KDP), Waters (WAT), Yum! Brands (YUM), Sysco (SYY), Archer-Daniels-Midland (ADM), Fiserv (FISV), Expeditors International (EXPD), Broadridge Financial (BR), Fidelity National Information Services (FIS), DuPont (DD), Leidos (LDOS), Ball (BALL), Revvity (RVTY), Zebra Technologies (ZBRA), Gartner (IT), Pinnacle West (PNW), Henry Schein (HSIC) and Aptiv (APTV)
Outside the S&P 500, Shopify (SHOP), Energy Transfer (ET), Ferrari (RACE), Bayer (BAYRY) and Intesa Sanpaolo (ISNPY) report.
Ex-US highlights include the Reserve Bank of Australia’s decision (10:30pm ET Monday; Deutsche Bank expects a hold), October CPI from Switzerland, South Korea and Turkey (plus Turkey PPI), New Zealand’s Q3 labor force survey, Japan’s October monetary base and France’s September budget balance. ECB Governing Council members Kocher, Dolenc, Radev, Escriva, Moulin, Nagel and Sleijpen speak, as do the Bank of Canada’s Macklem and Rogers, and UK Chancellor of the Exchequer Healey takes oral questions in the House of Commons.

Conversation 0 Comments
One ongoing discussion across all days. Everyone can read; sign in to take part.
Your voice matters. Discussions are moderated for civility. Read our guidelines .
Log in to join the conversation