Weekly Roundup: Riding Out the Blue Wave Whiplash With Cash and a Shopping List
We added to three holdings, introduced two new Bullpen contenders and locked in big gains across three positions.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
What a week. It began with Marvell Technology (MRVL) going forward with a deal to acquire Lumentum (LITE), which weighed on the shares of both companies and only continued from there. Tuesday’s midterm elections delivered a Democratic “Blue Wave,” with Democrats taking control of both the House and Senate. Wednesday, the market responded with a classic post-midterm relief rally on expectations of legislative gridlock, helped by blowout tech earnings and a sharp drop in oil prices as investors bet the results could accelerate efforts to end the war with Iran.
However, as we all saw first-hand, that rally didn’t last. Concerns that the Blue Wave washing over Congress and governorships will slow approvals for new data center construction rippled through AI and data-center infrastructure stocks, with comments from Texas Governor-elect Gina Hinojosa calling to pause data-center construction becoming the face of those worries. On Thursday, the climb in the Volatility Index paired with the Fear & Greed Index back in “Extreme Fear” gave rise to a more widespread selloff that culminated in the worst post-midterm day on record. More precisely, the S&P 500 fell more than 4% on Thursday, and the Nasdaq Composite more than 5%.
As we discussed Thursday and Friday morning, that pushed the Tech sector into an oversold condition. And while Friday brought a rebound as the market clawed back some of Thursday’s losses, a stronger-than-expected October Employment Report put the Fed’s focus squarely on inflation.
Still, as we pointed out our early Friday morning, the market rarely makes a bottom on Friday. Helene Meisler wrote Thursday night we could see that early next week, but we will want to cross-reference several indicators to assess that likelihood. For us, we’ll be looking for a turn up in the MACD indicators for the S&P 500 and the Nasdaq Composite.
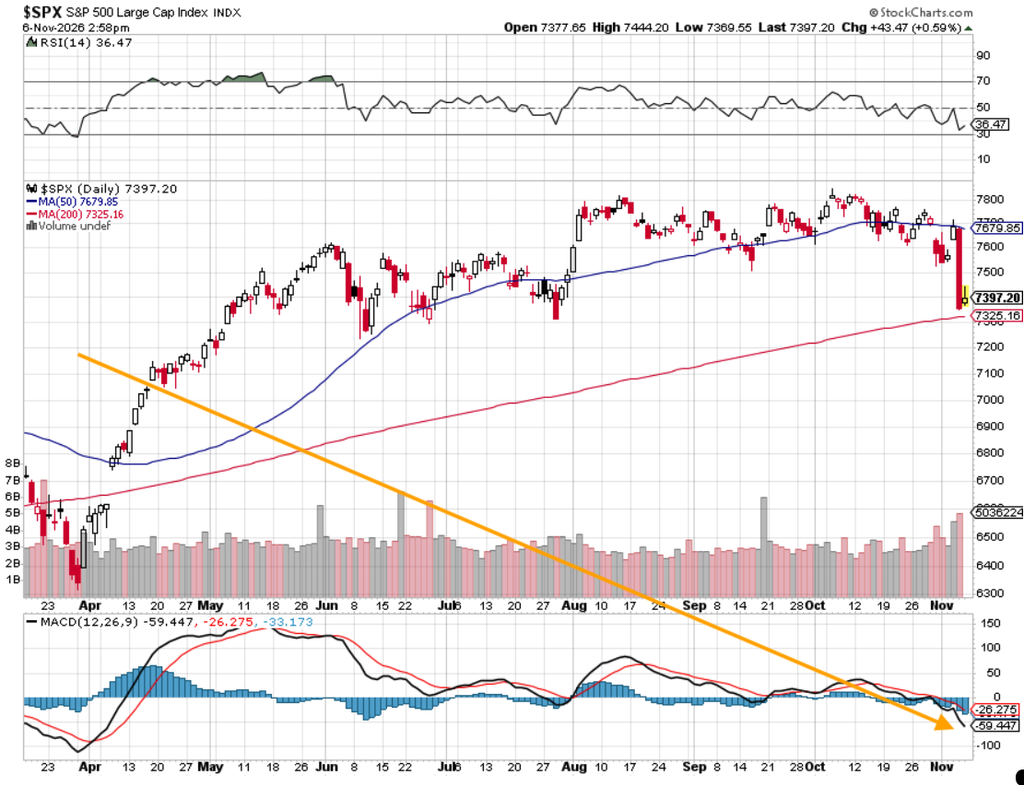
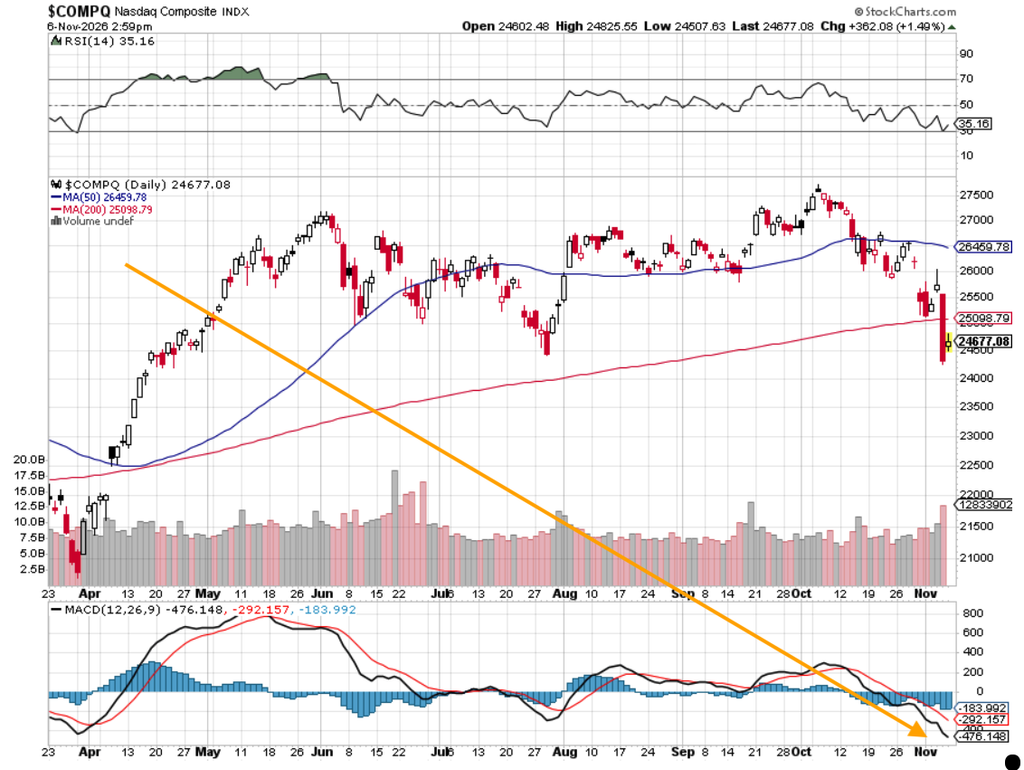
Picking the absolute bottom is extremely difficult in normal times, and it’s a lot harder when the market is flashing “Extreme Fear.” As the market finds its footing, there could be a head fake or two and that means being extra patient and prudent.
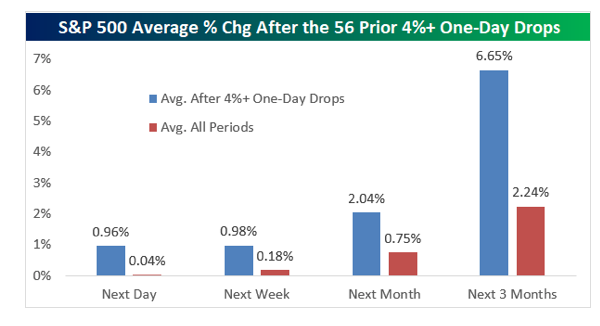
Source: Bespoke
Based on the historical data, which you can see above, following the initial one-day bounce following a dramatic market selloff, the net move over the ensuing trading sessions tends to be rather modest. More than likely that means we won’t be the only investors watching and waiting on the sidelines for the market to bottom out and re-test so stocks can move higher on a sustained basis.
No doubt, some are champing at the bit to put capital to work, but that time will come. When it does, we’ll pick our spots carefully most likely taking a series of smaller bites with a position or set of positions to get us where we ideally want to be. The goal is to set ourselves up to capture the larger move that tends to follow in the market over the coming months.
The list of positions on our shopping list that we shared Friday morning includes Alphabet (GOOGL), Applied Materials (AMAT), Broadcom (AVGO), Marvell (MVRL), Nvidia (NVDA), Palantir (PLTR), Axon (AXON), and VanEck Uranium and Nuclear ETF (NLR). We also want to be mindful of what’s in the Bullpen, including the additions we made this week with Hershey (HSY) and International Flavors & Fragrances (IFF).
The odds that we will be picking up shares in every one of those companies is low. Our cash position closing out the week is around 10.5% of the Portfolio’s assets. More than likely that means any first moves we make will be in high-conviction holdings.
As the market recovers, we will also be mindful of positions that are bumping up against technical resistance, are in an overbought condition, or have moved past a 4.5% position size. In other words, if prudent portfolio management is called for, we may have some more cash on hand. That would give us some added flexibility.
When we come back on Monday, we’ll share an updated Portfolio Table, and we’ll look to collect questions for our next Office Hours video midweek. Remember to ask your questions in the Forum and flag them #OfficeHours.
Enjoy your weekend, Saturday’s signals alert, and we’ll see you back here, bright and early on Monday.
Catching Up on the Portfolio This Week
Following the market’s rebound Friday, the week-to-week decline in the S&P 500 and the Nasdaq Composite, discussed above, plus the specific declines in Marvell (MRVL) and Axon (AXON) shares weighed heavily on the Portfolio’s individual stock positions and the EPS All-Stars basket. Amid the lead up to the midterm elections and the post-election market meltdown, we made several moves this week, locking in some big, but rather timely gains.
Monday, Nov. 2: We added International Flavors & Fragrances (IFF) to the Portfolio’s Bullpen. The company’s divestitures should lift margins for the ongoing business, and a sustained drop in oil prices would be a tailwind for its Scent segment. With the shares falling below $85 late in the week, we’ll be keeping a close eye on this differentiated, non-Tech candidate.
Tuesday, Nov. 3: We trimmed our Apple (AAPL) price target to $360 from $375, reflecting incrementally softer December-quarter gross margins on rising memory costs, and kept our Two rating. Demand for the new lineup is strong, and the revenue guide points to a record quarter.
Following a beat-and-raise quarter from Palantir Technologies (PLTR), we reiterated our $220 price target and Two rating. We’re inclined to revisit that rating and add to the position should the shares settle out near $170.
After a beat-and-raise quarter from Eaton (ETN), we kept our $500 price target and upgraded the shares to a One from Two. We held off on adding to the position until we clear the midterm elections and the October ISM data.
Wednesday, Nov. 4: We picked up more shares of Meta Platforms (META) near $631 and upgraded the name to a One rating. We kept our $850 price target and reset our checkpoint to $560. In that same alert, we started a new position in the VanEck Uranium and Nuclear ETF (NLR) with an initial price target of $113, a checkpoint of $78 and a Two rating.
Later that day, with Apple’s position size topping 4.5% of the Portfolio and the shares moving toward our $360 target, we trimmed the position, locking in a gain of more than 1,700%. If you don’t believe it, check the Portfolio Holdings page.
Following a beat-and-raise quarter from Arista Networks (ANET), with initial 2027 guidance well ahead of expectations, we lifted our price target to $240 from $225 and upgraded the shares to a One from Two.
Thursday, Nov. 5: This was a busy day for the Portfolio as we picked up more shares of Bank of America (BAC) just below $52. In that same alert, we used the then near 50% drop in Marvell (MRVL) shares to increase the Portfolio position size. We made that move reflecting the demand for AI and data-center chips continuing to outstrip supply, the likelihood the Blue Wave concern will prove to be overdone, and the increasing odds the Lumentum deal terms get reset or the deal is called off. However, we have room to grow the position further.
We also placed Hershey (HSY) back in the Bullpen as cocoa prices fall amid rising stockpiles. We’ll be watching cocoa, sugar and dairy costs to gauge whether Hershey still faces higher year-over-year cocoa costs in the first half of 2027.
Following Costco’s (COST) October sales report, with adjusted comparable sales up 7.3% and e-commerce comps up 22.5%, we lifted our price target to $1,175 from $1,150. However, the move in the shares following that report and investors flight to safer ports amid the market meltdown, led COST shares to an overbought condition. That and the position size moving past 4.5% of the Portfolio led us to trim back the position and lock in a gain of 119% on that slug of shares. We also downgraded COST to a Two from One and raised our checkpoint to $950 from $900.
Later that day, we sold all 580 shares of the Health Care Select Sector SPDR Fund (XLV) at or near $189, closing out a position that returned more than 15% since mid-September. Much like Costco, the shares moved into overbought territory as the market fled to safer havens; XLV shares have since fallen back near $185. Following the trade, we placed XLV back in the Bullpen for future consideration.
Those moves lifted the Portfolio’s cash position back above 10%. With the Technology Select Sector SPDR Fund (XLK) now oversold, we’re doing fresh homework on holdings that have fallen far and fast, and watching key support levels, including Palantir’s 200-day moving average near $153.56 and Nvidia’s (NVDA) 100-day moving average on the weekly chart near $174.42.
Friday, Nov. 6: Early Friday, we introduced our new and improved Portfolio Table, which now includes consensus EPS figures out to 2029 along with P/E and PEG ratios. Following Axon’s (AXON) September-quarter miss and lower outlook tied to the timing of federal Dedrone deployments, we cut our price target to $600 from $700. We also shared our intention to let trading volume clear out momentum investors and short sellers, and move to improve our cost basis as the shares and the market find their footing.
Now let’s see what others on Wall Street had to say about the Portfolio’s holdings during the week:
Monday: Phillip Securities upgraded Amazon (AMZN) to Buy from Accumulate. Following the Marvell-Lumentum deal announcement, BofA downgraded Marvell to Neutral from Buy, Stifel downgraded Lumentum to Hold from Buy, Raymond James upgraded Lumentum, and Bernstein cut its Lumentum price target to $900 from $1,220. Elsewhere, Wells Fargo trimmed its Alphabet (GOOGL) target to $365 from $371, and Cantor Fitzgerald lifted its Palantir target to $207 from $156 ahead of the company’s earnings. UBS raised its targets on American Express (AXP) to $346 from $345 and Morgan Stanley (MS) to $240 from $236, while cutting its Bank of America (BAC) target to $62 from $67.
Tuesday: TD Cowen downgraded Marvell to Hold from Buy, and Marvell price targets fell at Wells Fargo ($285 from $365), Cantor Fitzgerald ($225 from $350), RBC Capital ($250 from $425) and B. Riley ($275 from $365). Apple target changes following its earnings were mixed: JPMorgan ($355 from $360), Morgan Stanley ($350 from $355), TD Cowen ($390 from $400) and Goldman Sachs ($380 from $390) trimmed theirs, while Barclays ($261 from $245), Baird ($340 from $330), and UBS ($340 from $296) raised theirs. Palantir targets moved higher at Citi ($265 from $250), Morgan Stanley ($233 from $205), Piper Sandler ($235 from $231), and Deutsche Bank ($240 from $225). Freedom Broker also lifted its Amazon target to $330 from $255, while Morgan Stanley trimmed its Applied Materials (AMAT) target to $538 from $563.
Wednesday: DZ Bank downgraded Apple to Sell from Hold, while Bernstein lifted its Apple target to $380 from $370. Following Arista Networks’ results, Piper Sandler ($261 from $240), UBS ($291 from $259), JPMorgan ($270 from $250), Morgan Stanley ($230 from $220) and Truist ($240 from $234) raised their price targets, while Barclays ($236 from $289) and Wells Fargo ($245 from $255) cut theirs. On Eaton, RBC Capital raised its target to $539 from $526, while Wells Fargo trimmed its target to $485 from $503. Palantir targets rose again at Barclays ($273 from $265) and Freedom Broker ($250 from $230).
Thursday: JPMorgan raised its Costco price target to $1,150 from $1,015.
Friday: TD Cowen trimmed its Axon price target to $650 from $800, JPMorgan went to $640 from $755, and Barclays lowered its target to $507 from $688.
Key Global Economic Readings
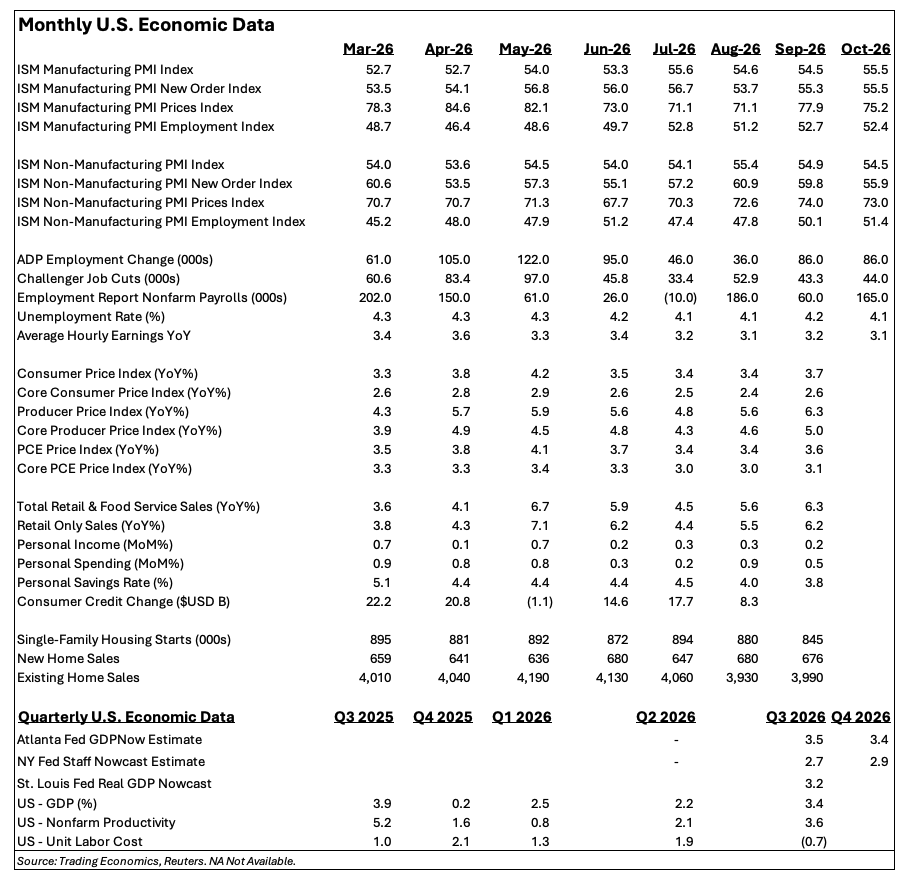
Chart of the Week: Financial Select Sector SPDR Fund
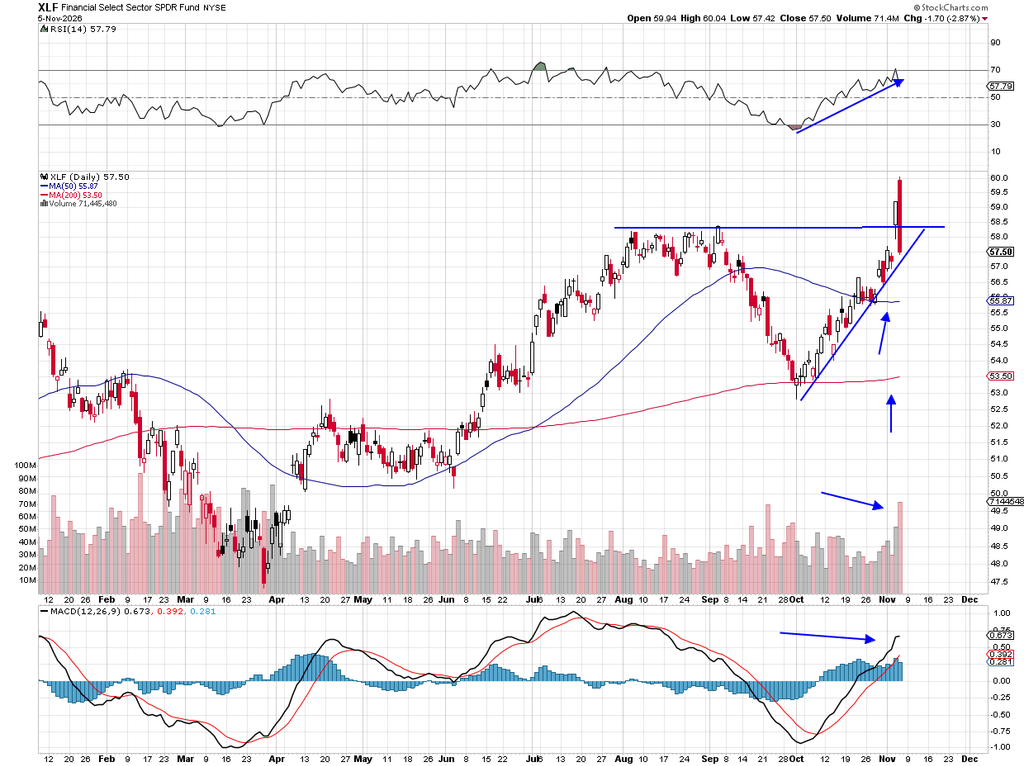
What spectacular days in the markets this week. Following the midterm elections, we saw the bulls stampede to a massive gain on good volume only to be followed by a day of concentrated selling. It was the biggest volume day of the year by far for the indices, and nothing was spared. This begs the question of whether the bulls can turn the ship around or if there is more punishment to be doled out.
The financials were looking fine Tuesday, with some of the bigger names such as JPMorgan Chase (JPM) right up against all-time highs. The Financial Select Sector SPDR, or the XLF, had risen to all-time highs on that day following a huge gap up. But Nov. 5 was a different story; the negative appearance of an outside day (higher high, lower low) is typical of a “change in character.”
We could argue, of course, this is simply a corrective move that needed to occur. Prior “wide” sessions like Thursday can be seen in September, March and February of this year. The ETF bounced back each time.
Yet, this one feels a bit different and we want to wait before jumping at these lower prices, just to be sure we are not falling through a black hole. We can see the uptrend remains intact by connecting the bottoms, but these vicious days often see follow-through, and if so that uptrend will break easily.
The 50-day moving average is about 4% down while the 200-day is about 5% lower. If those are tested the XLF will firmly be in a correction. From high to low on Thursday the XLF moved 5%, an unprecedented move that is quite rare. MACD remains on a buy signal, and the RSI is simply moving away from overbought.
So, did the financials escape the vicious selling that took place in tech? Yes, we can say that happened, and if the banks show some bullish leadership here, they just might lead buyers back in, if it is safe to go back in shark-infested waters.
Other charts we shared with you this week were:
Monday, November 2: S&P 500 – Charting the Markets: The S&P 500 Is Following a Script
Monday, November 2: Chart of the Day: Palantir Is Not Immune From the Selling
Tuesday, November 3: Chart of the Day: Axon’s Flat Base Gives Bulls Some Hope
Wednesday, November 4: Chart of the Day: Arista Networks Tries to Break Downtrend
Thursday, November 5: Chart of the Day: Bank of America Resets Its Price
The Week Ahead
October’s ISM data showed an economy that continues to expand, with price pressures that remain sticky. This week we learned the ISM Manufacturing PMI rose to 55.5 from 54.5, just shy of July’s high for the year, as new orders climbed to 55.5 and the Employment index held in expansion at 52.4. The Prices index eased to 75.2 from 77.9 but remains well above the 71.1 readings of July and August. On the Services side, the ISM Services PMI slipped to 54.5 from 54.9 as new orders cooled, but the Employment index rose to 51.4, its highest reading of the year, and the Prices index held at an elevated 73.0. ADP’s October report showed private employers added 86,000 jobs, ahead of the 69,000 consensus.
Friday’s October Employment Report confirmed that strength. Employers added 165,000 jobs, well above the 65,000 consensus, and August and September were revised higher by a combined 84,000. That combination keeps the Fed’s attention squarely on inflation, and per the CME FedWatch tool, the odds of a rate hike at the Fed’s Dec. 8-9 meeting rose to 73%.
Following the step-up for CPI and PPI in September to 3.7% and 6.3% on a year-over-year basis, respectively, next week’s October CPI report Tuesday and October PPI report Friday will go a long way toward determining whether the Fed raises rates in December, and if so by how much. As we write this edition of the Weekly Roundup, we see 12 Fed speaker engagements next week, but as you can imagine, we’ll be focusing on the ones that come after each round of October inflation data.
Wednesday is Veterans Day, so the bond market will be closed while stocks trade. Other data include NFIB small business optimism, the New York Fed’s Survey of Consumer Expectations, weekly jobless claims and existing home sales.
Here’s a closer look at the economic data coming at us next week:
U.S.
Monday, Nov. 9
Wholesale Inventories (Sept.) – 10:00 AM ET
NY Fed Survey of Consumer Expectations (Oct.) – 11:00 AM ET
Tuesday, Nov. 10
NFIB Small Business Optimism Index (Oct.) – 6:00 AM ET
ADP Employment Change Report (Weekly) – 8:15 AM ET
Consumer Price Index (Oct.) – 8:30 AM ET
Real Earnings (Oct.) – 8:30 AM ET
Wednesday, Nov. 11
Veterans Day – Bond market closed; stock market open
MBA Mortgage Applications (Weekly) – 7:00 AM ET
Thursday, Nov. 12
Initial & Continuing Jobless Claims (Weekly) – 8:30 AM ET
Existing Home Sales (Oct.) – 10:00 AM ET
EIA Natural Gas Inventories (Weekly) – 10:30 AM ET
EIA Crude Oil Inventories (Weekly) – 11:00 AM ET
Treasury Monthly Budget Statement (Oct.) – 2:00 PM ET
Friday, Nov. 13
Producer Price Index (Oct.) – 8:30 AM ET
International
Monday, Nov. 9
China: CPI (Oct.)
China: PPI (Oct.)
Japan: Leading Economic Index (Sept., prelim.)
Eurozone: Eurogroup Meeting
Tuesday, Nov. 10
China: Trade Balance, Exports & Imports (Oct.)
Japan: Bank Lending (Oct.)
Japan: BoJ Summary of Opinions
Japan: Eco Watchers Survey (Oct.)
UK: BRC Retail Sales Monitor (Oct.)
Wednesday, Nov. 11
Germany: CPI & HICP (Oct., final)
Japan: Machine Tool Orders (Oct., prelim.)
Thursday, Nov. 12
UK: GDP (Q3, prelim.)
UK: Industrial & Manufacturing Production (Sept.)
Japan: PPI (Oct.)
Friday, Nov. 13
Eurozone: GDP (Q3, 2nd est.)
Eurozone: Employment Change (Q3, prelim.)
Eurozone: Trade Balance (Sept.)
Germany: Wholesale Prices (Oct.)
Following this week’s barrage of reports, don’t be lulled into thinking the current earnings season is over. While we have a bit of lull next week, now that we’ve closed the books on October, around the corner we will have earnings from retailers and related consumer-facing companies as well as a few chip stocks like our own Nvidia (NVDA), Marvell (MRVL), and Broadcom (AVGO) in the coming weeks.
The next Portfolio holding to report is Applied Materials (AMAT). We’ll get that as well as the company’s updated outlook after Thursday’s market close. Ahead of that report we’ll resume our work connecting the dots from the companies that report back to the Portfolio and potential candidates being considered.
Next week that list of reports to sink our teeth into includes CoreWeave (CRWV), Cerebras (CBRS) Nebius (NBIS), and Cisco (CSCO) for our Tech positions. For our consumer-facing ones, Edgewell Personal Care (EPC), Sally Beauty (SBH), StubHub (STUB) and a few others. As it relates to our holdings with advertising business models, we’ll look to see what The Trade Desk (TTD) has to say about the spending environment, potential disruption from OpenAI and others, as well as the overall competitive landscape.
Here’s a closer look at the earnings reports coming at us next week:
Monday, Nov. 9
Open: Barrick Mining (B), CNH Industrial (CNHI), Constellation Energy (CEG), Ferguson Enterprises (FERG), KKR (KKR), NRG Energy (NRG)
Close: Casella Waste (CWST), Ethan Allen (ETH), Occidental Petroleum (OXY), Onto Innovation (ONTO), Rocket Lab (RKLB), Skydance (SKYD), Take-Two Interactive (TTWO), The Trade Desk (TTD)
Tuesday, Nov. 10
Open: On Holding (ONON), Sally Beauty (SBH)
Close: CoreWeave (CRWV), StubHub (STUB)
Wednesday, Nov. 11
Close: Corteva (CTVA)
Thursday, Nov. 12
Open: Edgewell Personal Care (EPC), National Vision (EYE), Nebius Group (NBIS), YETI Holdings (YETI)
Close: Applied Materials (AMAT), Cerebras Systems (CBRS), Cisco (CSCO),
Portfolio Investor Resource Guide
Economic Data: Here’s a List of Links to the Key Economic Data We Closely Watch
Investing Terminology: 16 Key Terms Club Members Should Know
10-Ks: Want to Know About a Stock? Read the Company’s Reports
10-Qs: Unlock the Numbers and Key Information Behind Your Stock With the 10-Q
Income Statement: Our Cheat Sheet to Understanding This Financial Document
Balance Sheet, Cash Flow Statements, and Dividends: How to Know If a Company Is Off-Kilter? Read Its Balance Sheet
Valuation Metrics: Everyone Wants a Value. Here’s How Investors Can Find
Thematic Investing 101 Webinar
Like the Benefits of ETFs? Let’s Talk About Models
The Portfolio Ratings System
1 – Buy Now (BN): Stocks that look compelling to buy right now.
2 – Stockpile (SP): Positions we would add to on pullbacks or a successful test of technical support levels.
3 – Holding Pattern (HP): Stocks we are holding as we wait for a fresh catalyst to make our next move.
4 – Sell (S): Positions we intend to exit.