Slower Wage Growth vs. Inflation Keeps Us Bullish on These Holdings
Inflation picked up in the Services sector, but so did overall activity.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
In reviewing the back-to-back September Services PMI reports out today from S&P Global and ISM, we conclude overall activity in that part of the economy, which drives 85%-90% of domestic GDP, continues to grow at a brisk clip. And when we combine that with the September Manufacturing PMI data, especially from ISM, we see that to an even greater degree. The fuller picture from ISM also paints a picture of strengthening job creation compared to July and August, but it also shows one of increased inflation pressures.
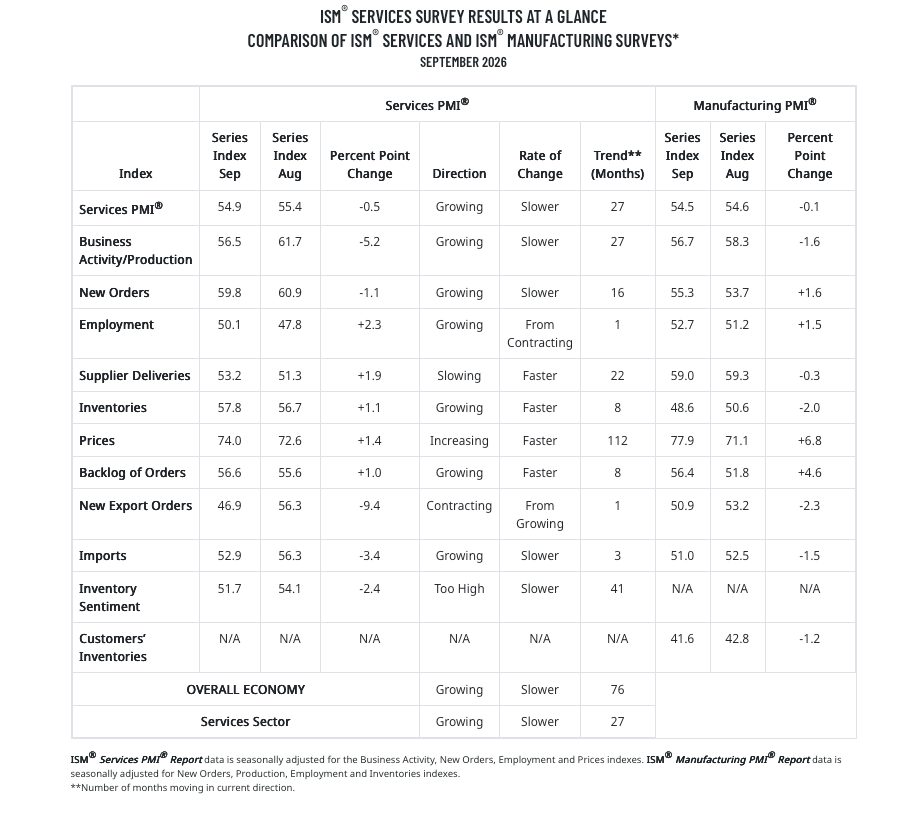
The view on job creation offered by ISM is a stronger picture compared to last week’s September Employment Report and one more in sync with the sequential step-up in job creation found in ADP’s September Employment Change Report. Our thinking is the continued growth in new order demand and increases in backlogs of work is spurring hiring activity.
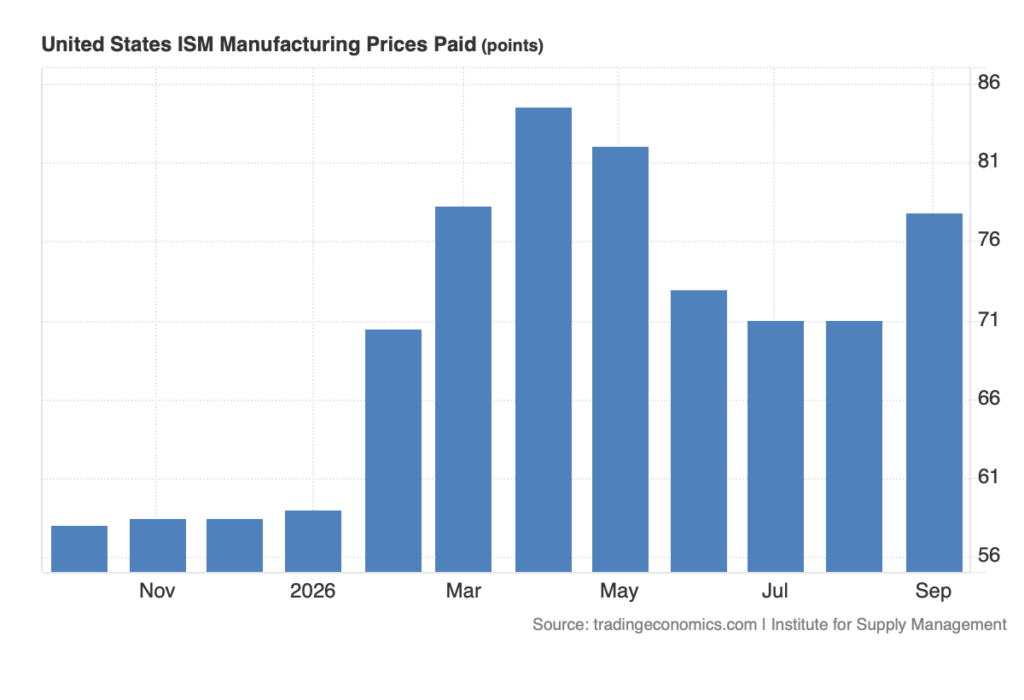
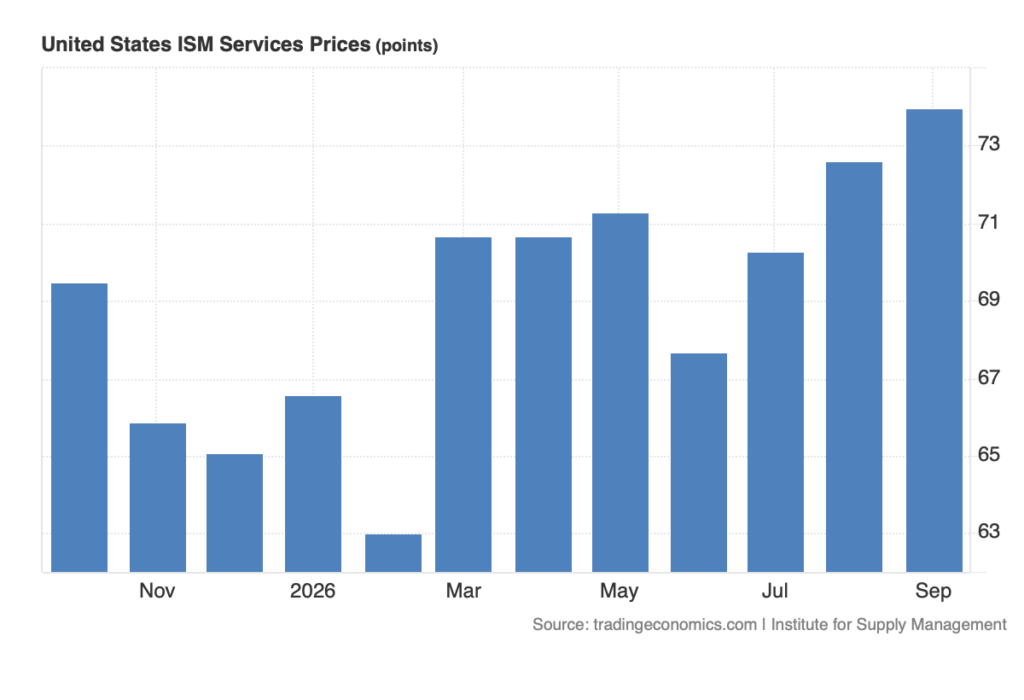
Looking at ISM’s Prices data for September, in both parts of the economy, we see a sequential increase. No surprise given all that we’ve discussed about the double-digit climb in energy prices in September alone. But looking past the September ISM data with an eye on the last few months, we see the rise in those pressures. That helps explain the comments from S&P Global that the pace of output price increases rose in September in both Manufacturing and Services:
“Having eased to a 16-month low in August, input cost inflation accelerated sharply in September and was the steepest since November 2022. Higher gas prices and an associated rise in transportation costs were widely reported, with some respondents also mentioning increased labor costs. Similarly, output prices also rose at a faster pace, with inflation the second-fastest in just over a year (behind only July).“
When we look at the latest gas and diesel price data from AAA, we see that both have fallen by about a dime per gallon each over the last week. Even so, both remain at lofty levels compared to this time last year. What those 39% and 71% year-over-year figures tell us is that year-over-year comparisons might improve some in the coming weeks, but not at a pace that is likely to have the consumer or companies with truck fleets feeling much better in the near-term.
With that in mind, we’ll be paying close attention to the promotional activity from retailers as Amazon’s (AMZN) Prime Big Deal Day’s event is held tomorrow (October 6) and Wednesday (October 7).
Thoughts on Upcoming September PPI and CPI Data
Looking at the collected data points from ISM and S&P Global suggest we should see another step-up in September PPI figures on both a year-over-year and sequential basis. The Cleveland Fed’s Inflation Nowcast model already called for September headline CPI to reach 3.6% on a year-over-year basis compared to August’s 3.4% figure. That model also sees the core CPI figure unchanged at 2.4% for September but given the output price comments captured by S&P Global above, we’ll want to revisit the Inflation Nowcast model later this week.
Should the published September CPI and PPI data rise more than expected compared to their corresponding August figures, that could spark another shift in market expectations for an October rate hike. We’ll be ready to dig into that report next week, sharing our findings as we do so.
One of the keys for us when we get the September CPI report will be to compare its year-over-year figures against the analogous one for wage gains found in the September Employment Report and ADP’s Employment Change Report for the month. As you can see in the chart below, wage gains have slowed and are lagging inflation data.
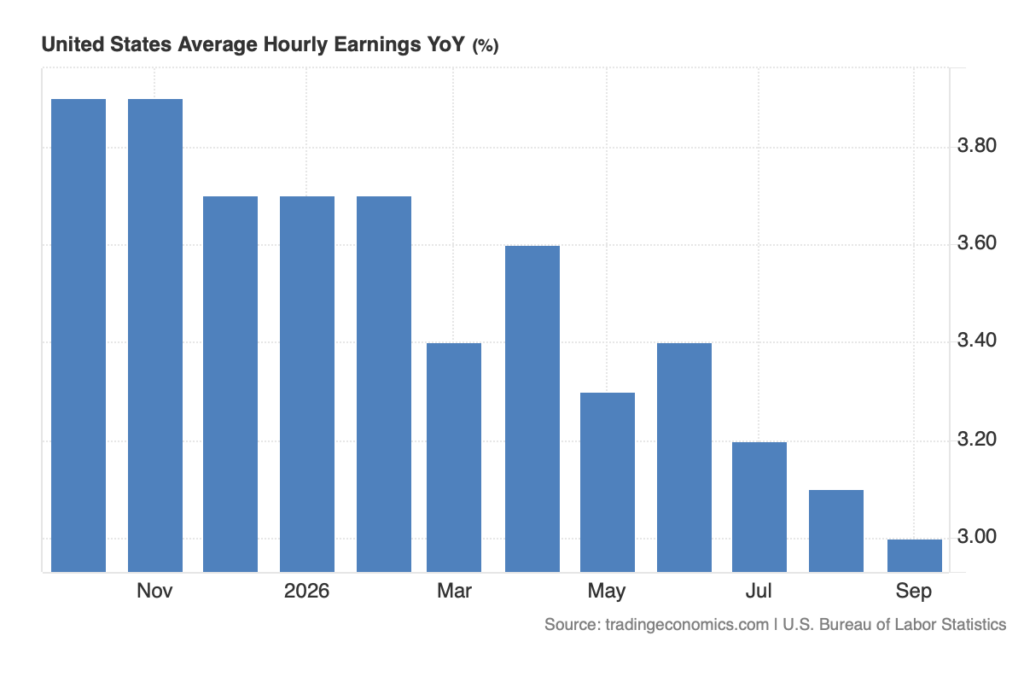
This suggests a few things to us. First, it reaffirms our thinking about Costco (COST) and TJX (TJX) in the Portfolio. Second, we’re likely to see the holiday shopping season spread out across October, November, and December. It also means the last part of the holiday shopping season, and by that we mean the returns and clear-out activity, could be stronger than currently expected. Third, we could see a highly promotional holiday shopping season, which to us always raises the question about retailer margins — even more so this time around, given rising input and transportation prices.
More Pro Portfolio:
- We’re Adding to This Holding After Averted Strike and Multiple Wins
- 26 Signals Across 9 Portfolio Themes
- Weekly Roundup: Waiting for the Market to Show Its Hand
At the time of publication, TheStreet Pro Portfolio was long AMZN, COST and TJX.