Despite Warnings, Tomorrow Won’t Bring the Market Bottom
An updated look at S&P 500 support levels as we stick to the sidelines.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
While the market started off in positive territory on Tuesday, it has since retreated from those levels and then turned lower despite the fall we are seeing in oil prices.
The culprit is one we’ve seen a few times this month, and with that I’m referring to the renewed climb in treasury yields. As of this writing, the 30-year treasury yield reached 5.60%, a relatively small distance from its 2002 high of 5.613%. The 10-year, which as we know is a benchmark for mortgage borrowing, auto loans and credit card debt, has risen to 5.268%.
While both gas and diesel prices are off several pennies from their highs reached last week, they are still at very lofty levels compared to those a year ago. On Monday, Texas Governor. Greg Abbott declared a statewide disaster over soaring diesel prices and a worsening fuel shortage created by wars abroad. The 30-day disaster declaration, which can be extended indefinitely, allowed Abbott to lift some restrictions on commercial transportation, which he said will alleviate some of the elevated costs. That includes the use of dyed diesel on Texas roads and was a reminder that the bulk of U.S. freight, and therefore of the U.S., runs on diesel. Trucking carries roughly 72% of all freight tonnage in the U.S.
Building on those and other inflation concerns that are helping lift Treasury yields, the CME FedWatch Tool now sees a 68% probability for another rate hike 29 days from Tuesday.
At the same time, market breadth, as pointed out by Helene Meisler, Bob Lang and others here at TheStreet Pro and elsewhere, is in a word, horrible. In the past month, only one S&P 500 sector has risen, information technology, and in the last two months, only four of the 11 sectors have advanced. Other analysis finds that five stocks have delivered more than 90% of the S&P 500’s gains since late July — Microsoft (MSFT), Meta (META), Apple (AAPL), Alphabet (GOOGL) and Nvidia (NVDA). Fortunately, those are all Portfolio holdings, as are Arista Networks (ANET), Marvell (MRVL), Palantir (PLTR) and a few others that have allowed us to maintain our year-to-date lead over the S&P 500.
However, in addition to that market breadth and climb in treasury yields that run the risk of pulling capital from the market, as we discussed with you last week, the follow through of renewed inflation pressures are likely to weigh on market expectations for S&P 500 EPS prospects. With companies closing their books for the quarter on Wednesday, and the Q3 2026 earnings season getting underway in force after the Columbus Day holiday on October 12, there is ample time for negative earnings pre-announcements. Given S&P Global’s Flash September PMI warning over margin pressure, we would be surprised if no other companies follow the recent negative announcements from Nucor (NUE), Steel Dynamics (STLD) and JB Hunt (JBHT).
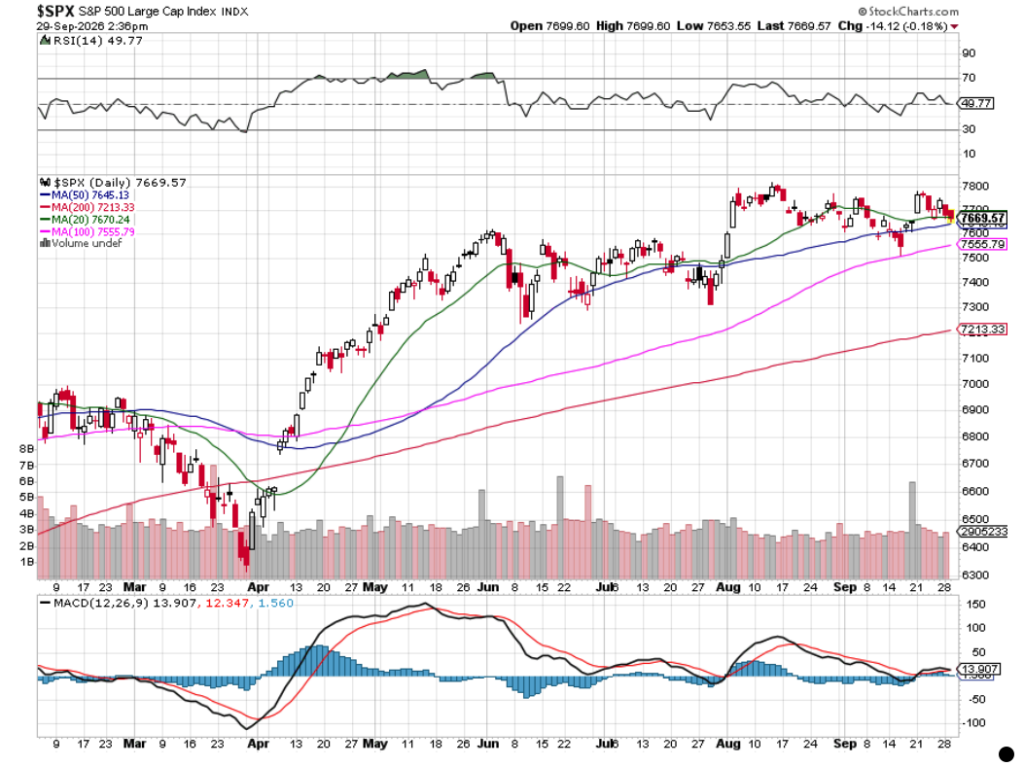
As we navigate those coming days, we’ll continue to track the S&P 500 relative to its technical setup. As you can see below, the index is battling its 20-day moving average, with the next layer of support near 7,7645, which is rather short distance away. Next up is the 100-day moving average near 7,556 and then the 200-day moving average near 7,213. We point out these levels because so far the S&P 500 has only one 5% pullback so far this year. Typical, there are three or more in a calendar year. While past performance does not indicate future returns, there are multiple reason to be wary as we get ready to close September and move into the Q3 2026 earnings season and the mid-term elections, especially if the U.S.-Iran war is still underway.
For those reasons, we may not see a market bottom on September 30 as suggested by Citadel Securities. We indicated to you that our thinking suggested this in late September, and as we get ready for Wednesday, the probability for September 30 not being the market bottom is high.
That means even though we are moving forward with our quarterly rebalance of the EPS All-Stars strategy on Wednesday, we will largely remain on the sidelines even though there are more of the Portfolio’s holdings in oversold territory. We are keeping close tabs on those and others flirting with such a condition, but as we’ve said many times before, we need to be aware of the market environment and mindful of investor mood and how that combination can impact the S&P 500’s next move.
More Pro Portfolio
- Charting the Markets: Leaving an Ugly September Behind
- 26 Signals Across 9 Portfolio Themes
- Weekly Roundup: Waiting for the Market to Show Its Hand
At the time of publication, TheStreet Pro Portfolio was long AAPL, ANET, GOOGL, META, MRVL, MSFT, NVDA and PLTR.