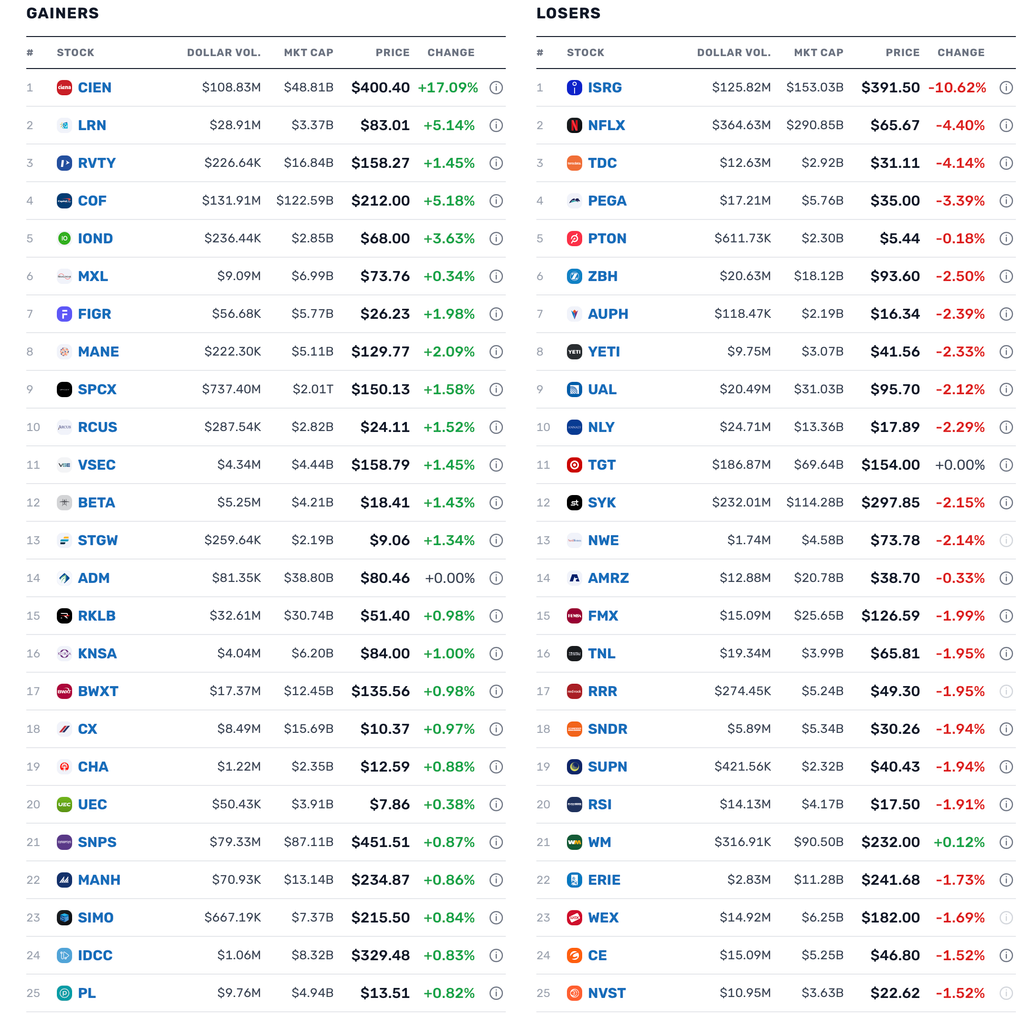
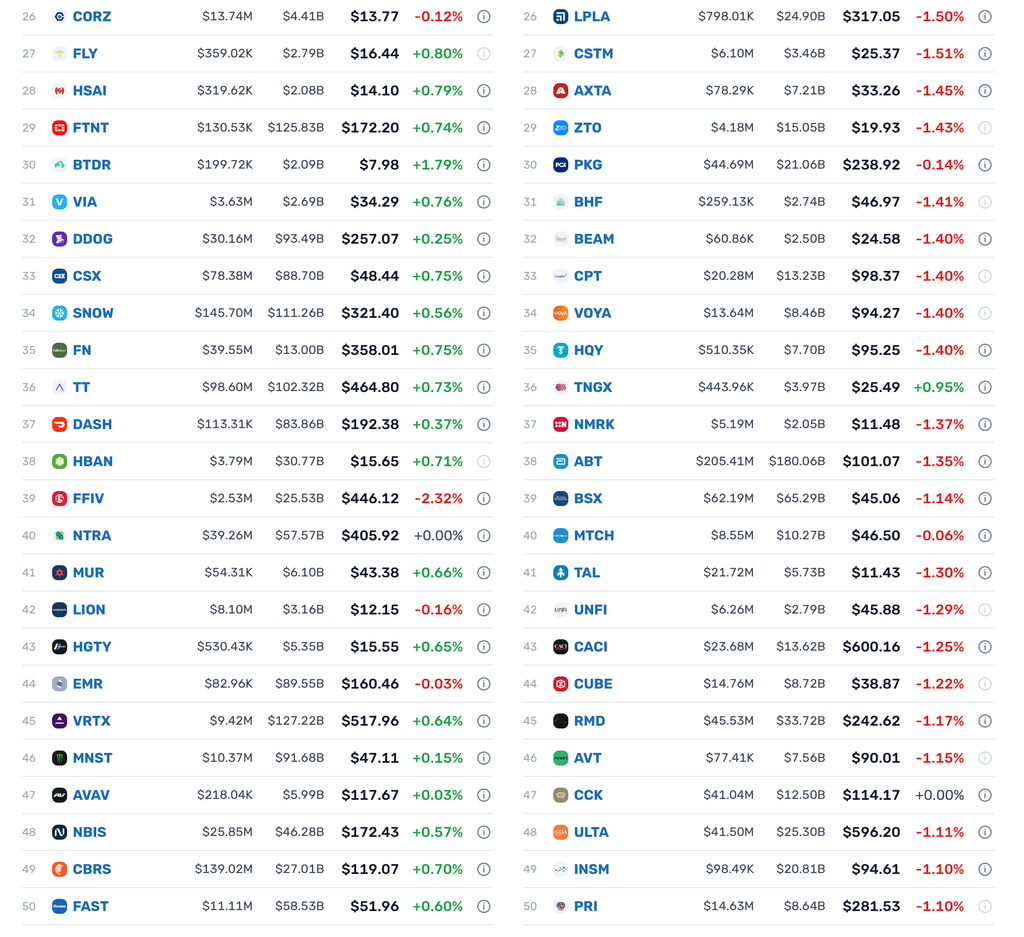
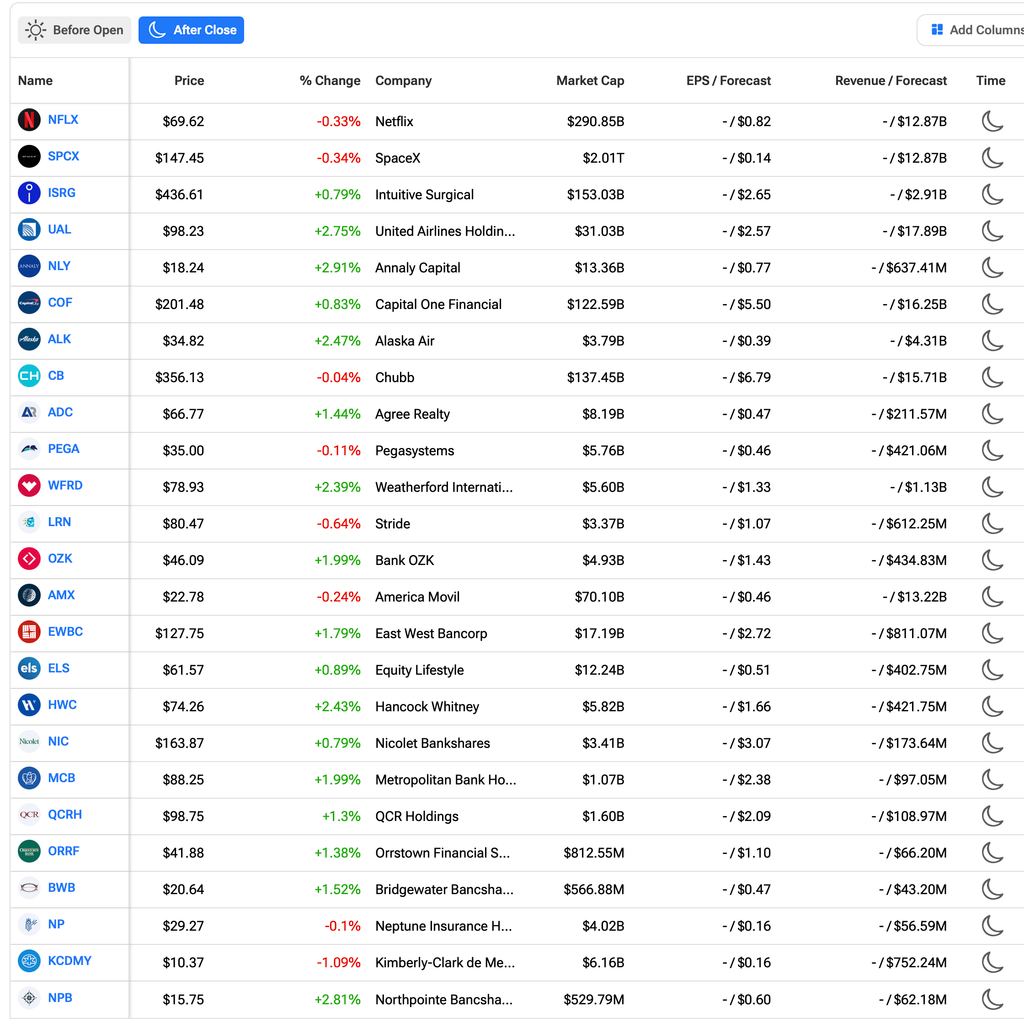
Tuesday’s After-Hours Advancers and Decliners
BY Doug Kass · Oct 20, 2026, 4:40 PM EDT
 Doug KassDoug Kass
BY Doug Kass · Oct 20, 2026, 4:40 PM EDT
Closing Volume
– NYSE volume flat to its one-month average
– NASDAQ volume 3% below its one-month average
– VIX index: down 5.86% to 17.36
Breadth
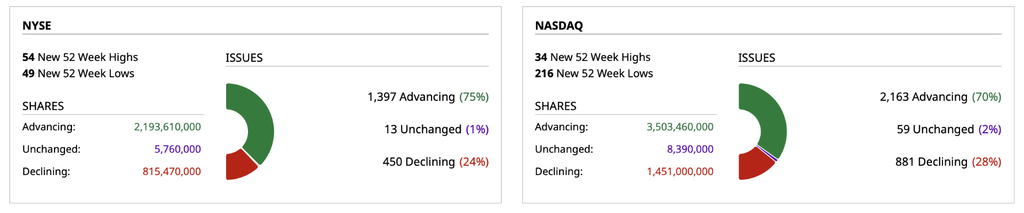
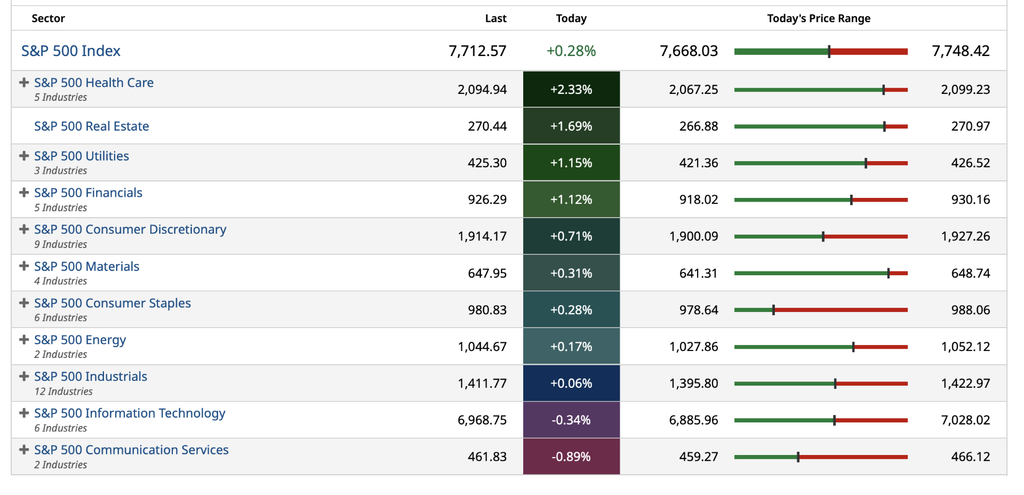
S&P 500 Sectors
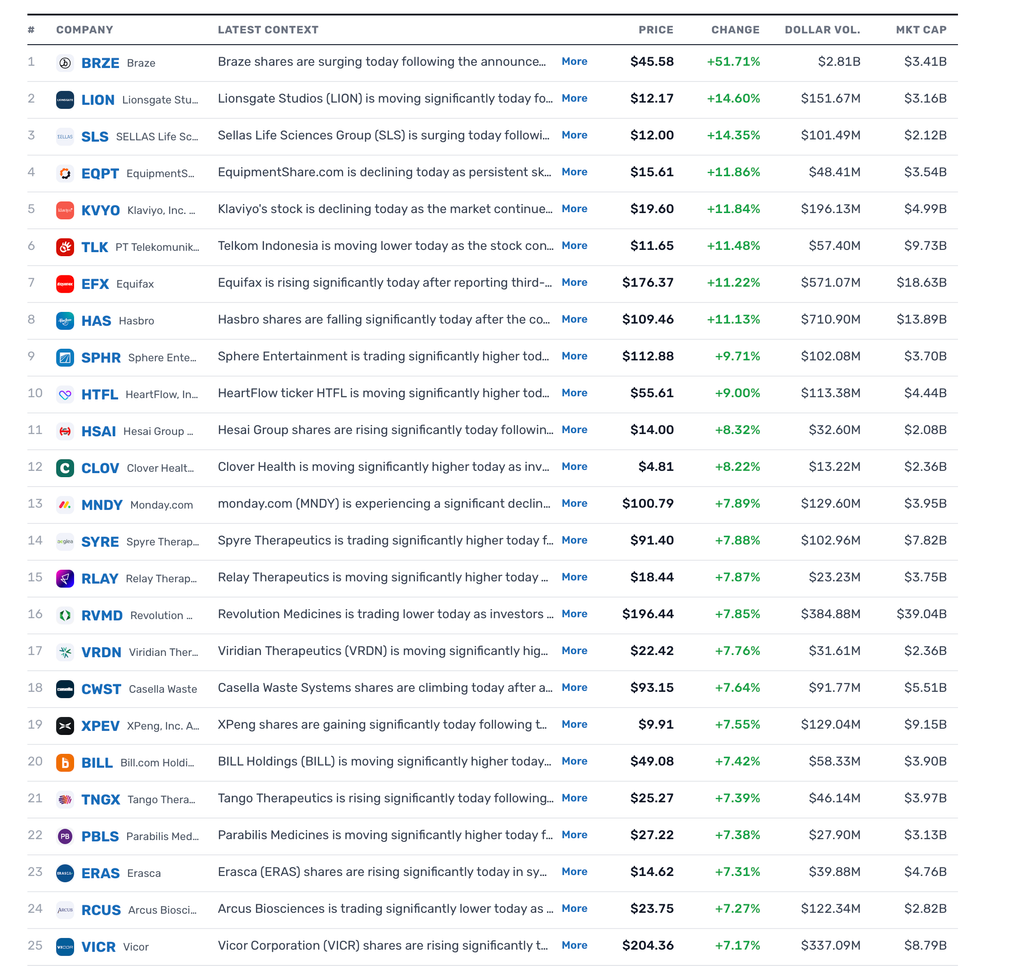
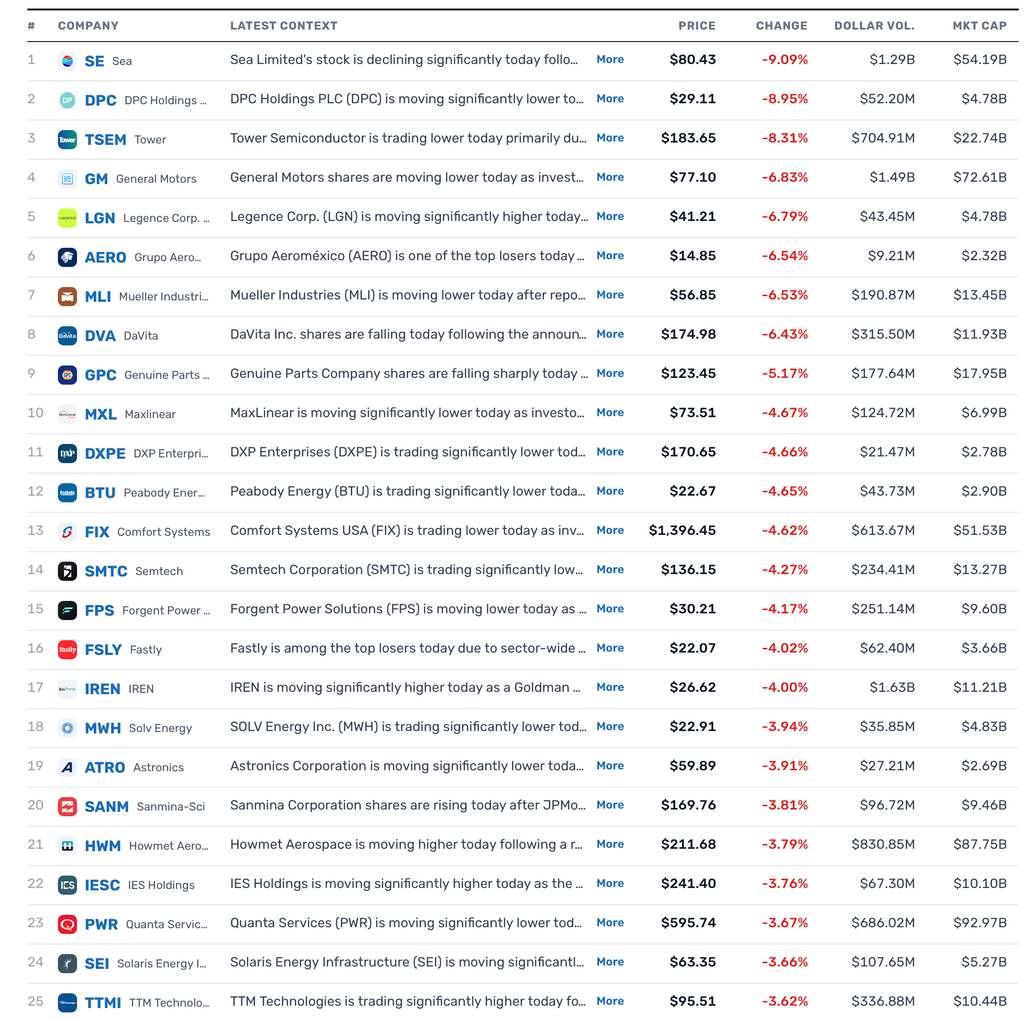
% Movers
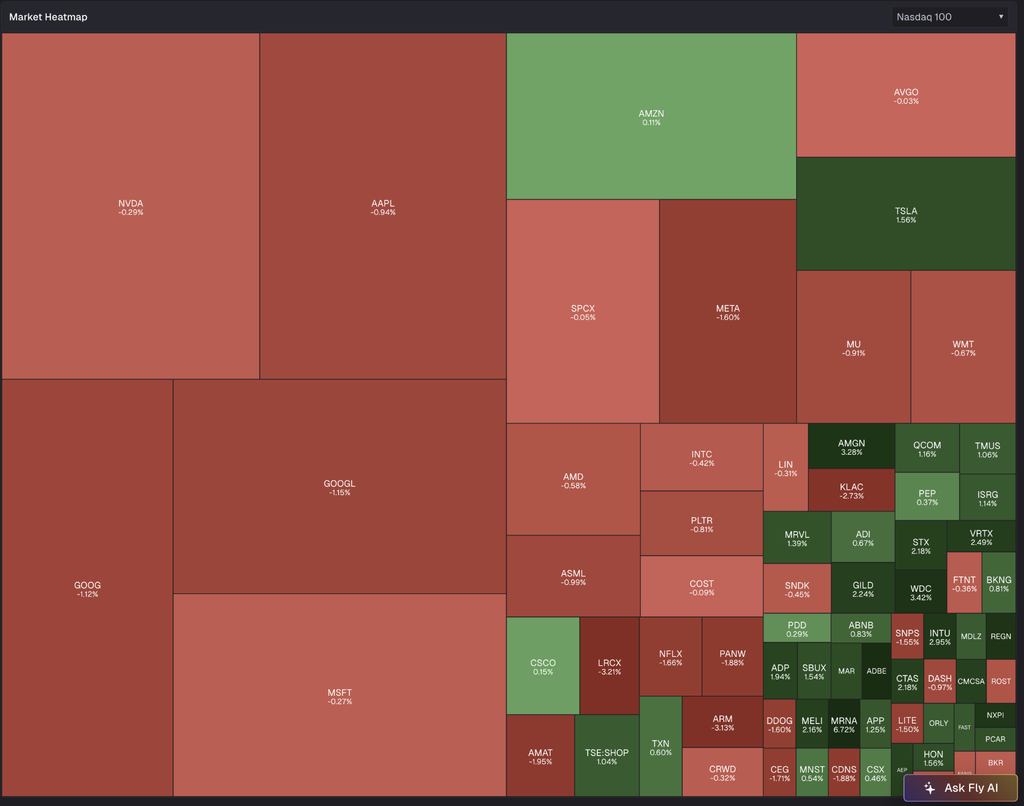
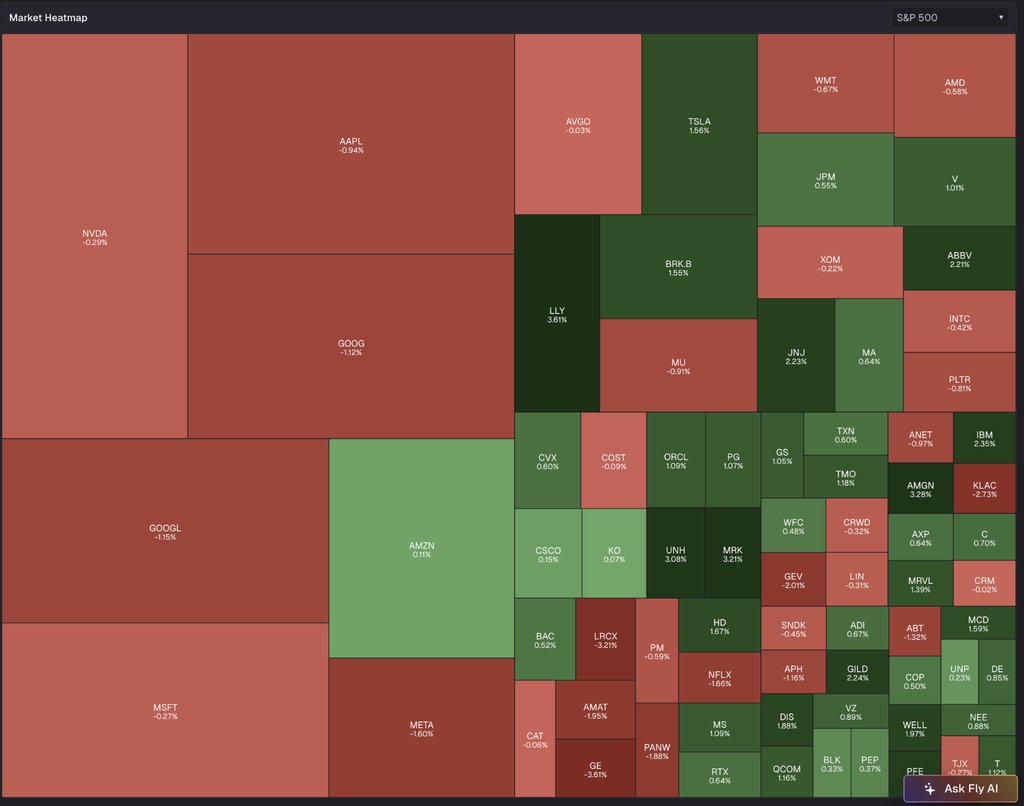
Heat Maps
Position: None
BY Doug Kass · Oct 20, 2026, 4:30 PM EDT
Repeating for emphasis, I would not bottom fish in Netflix (NFLX).
I expect in line-to-better 2Q2026 results but a possible lower forward guidance as margins are pressured.
From last month:
I would continue to avoid buying (and “bottom fishing”) in Netflix (NFLX) for the reasons I have previously mentioned:
* Netflix has nearly saturated the domestic market (as well as many other developed countries). These markets are significantly more profitable than the non developed arena.
* Future Netflix sales/profit growth will come from developing country markets that provide substantially less revenue (and income) per subscriber.
* Netflix’s original content programming has been unspectacular over the last 12 months (or more) — and existing content has suffered.
In the past I have been short NFLX, but it is no longer priced as an attractive short.
Position: None
BY Doug Kass · Sep 22, 2026, 1:50 PM EDT
Position: None
BY Doug Kass · Oct 20, 2026, 4:09 PM EDT
Yesterday there was a large market on close sell order (over $8 billion). Today there is no real imbalance.
Position: None
BY Doug Kass · Oct 20, 2026, 4:01 PM EDT
From my pal Vitaliy:
Position: None
BY Doug Kass · Oct 20, 2026, 3:53 PM EDT
From Randorama:
Randy
PayPal Reports Lobbying Congress on Marijuana Banking Reform in Third Quarter
The SAFE Banking Act would establish federal protections for financial institutions providing services to state-legal marijuana businesses, addressing longstanding concerns about access to banking and payment processing services within the industry.
Beyond marijuana banking, PayPal’s third-quarter disclosure identifies lobbying on cryptocurrency regulation, small business lending, artificial intelligence, consumer financial protections, taxation and trade policy.
Position: None
BY Doug Kass · Oct 20, 2026, 3:50 PM EDT
No trades since last report.
On several research missions.
Position: None
BY Doug Kass · Oct 20, 2026, 3:32 PM EDT
Position: None
BY Doug Kass · Oct 20, 2026, 1:35 PM EDT
My index trades are not A Random Walk Down Wall Street — though, to some, they may seem to be based on “gut.”
To understand my moves I turn back to my mentor The Chief — who was arguably the best tape trader I have ever met.
Let’s begin with Jerry’s SS or slow stochastic. This has a longer timeframe, which takes time to develop. But, when the SS got to the bottom of the page, it is an excellent buy signal.
Jerry also invented and I use his SS RJ (and the CSJ which is a 15-minute version of it). The SS has a weekly timeline. It utilizes daily data but the highs and lows play out over a longer-term timeframe.
So, when the SS is at the bottom of the page it is as strong a signal to buy as when it is a signal to short at the top of the page. (The Chief would say that that his indicator is far better at the bottom of the page than at the top!)
That’s all I am going to give you or The Chief would sent out a hit on me.
Position: None
BY Doug Kass · Oct 20, 2026, 1:05 PM EDT
Here are today’s things:
* I shorted SPY at $770.96 and covered the short at $768.98.
* I added to MSOS at $3.85.
Position: Long MSOS common (VL) and calls (VS)
BY Doug Kass · Oct 20, 2026, 12:48 PM EDT
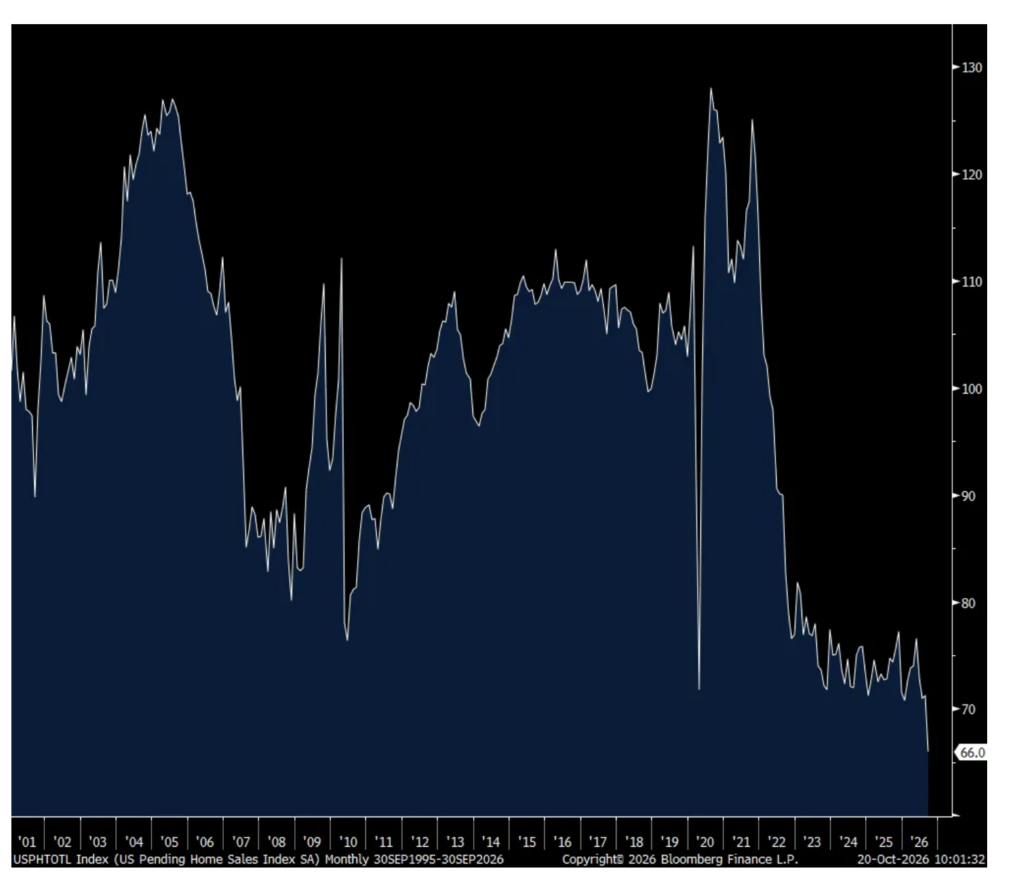
Wolf Street howls about the record low in pending home sales.
Position: None
BY Doug Kass · Oct 20, 2026, 12:25 PM EDT
The following is from Peter Boockvar:
Home construction and sales in September
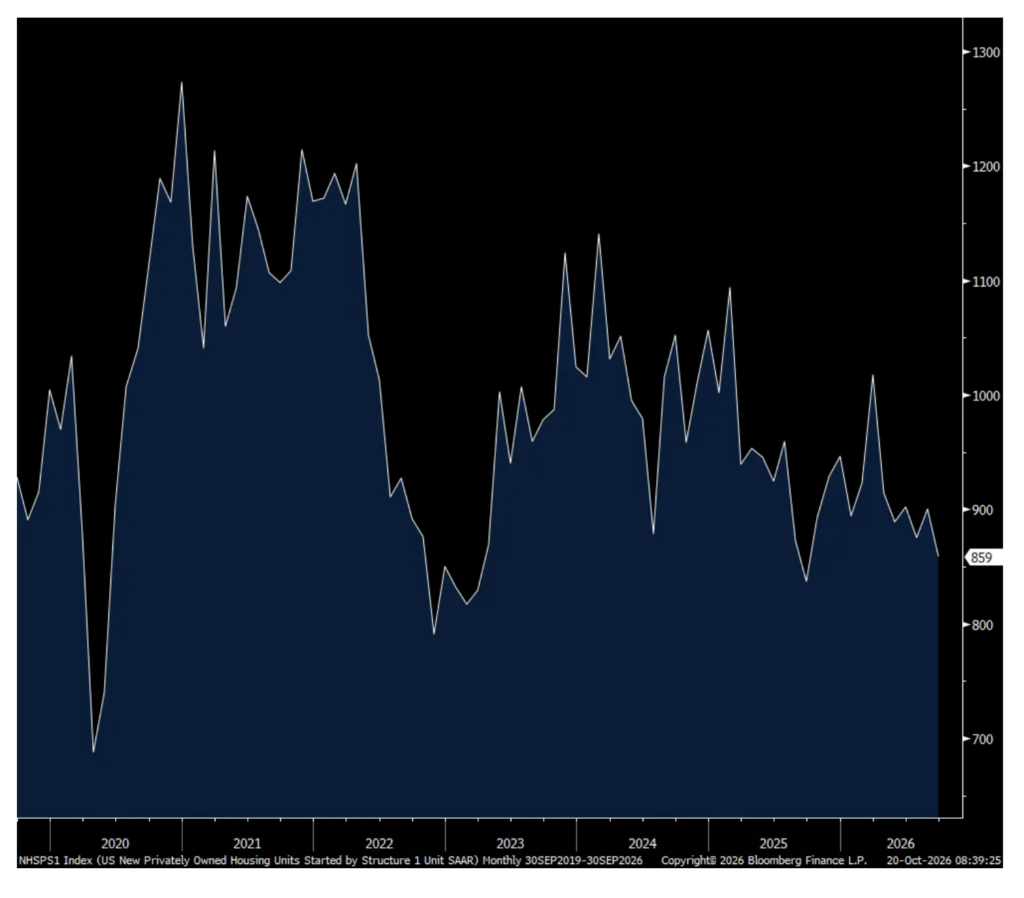
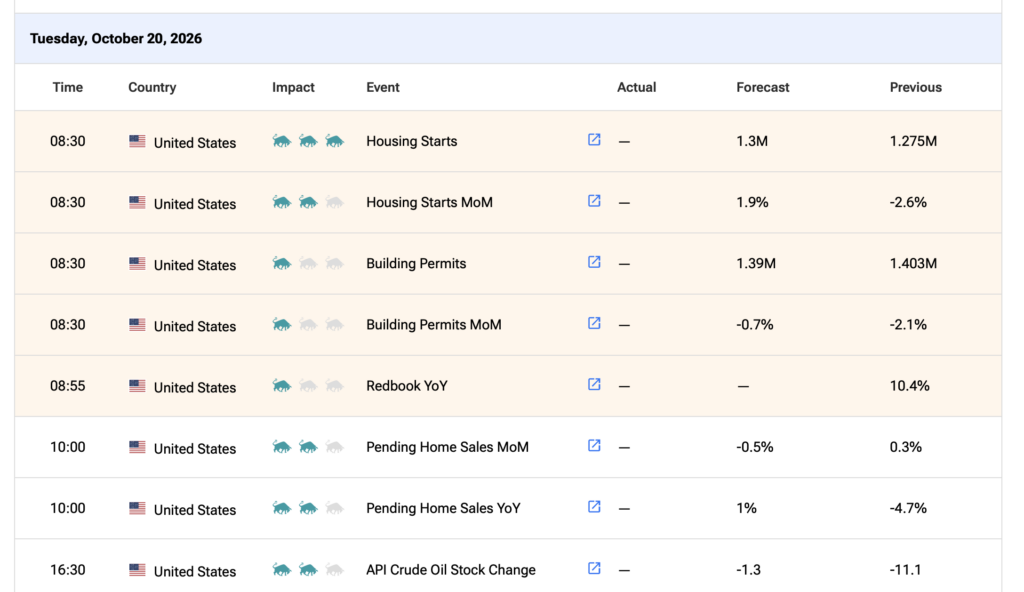
September single family housing starts fell to 859k from 900k and vs 875k in the month before. That’s the least in a year but not surprising considering what we’ve heard from the homebuilders, the affordability challenges the buyer faces and the supply issued builders face.
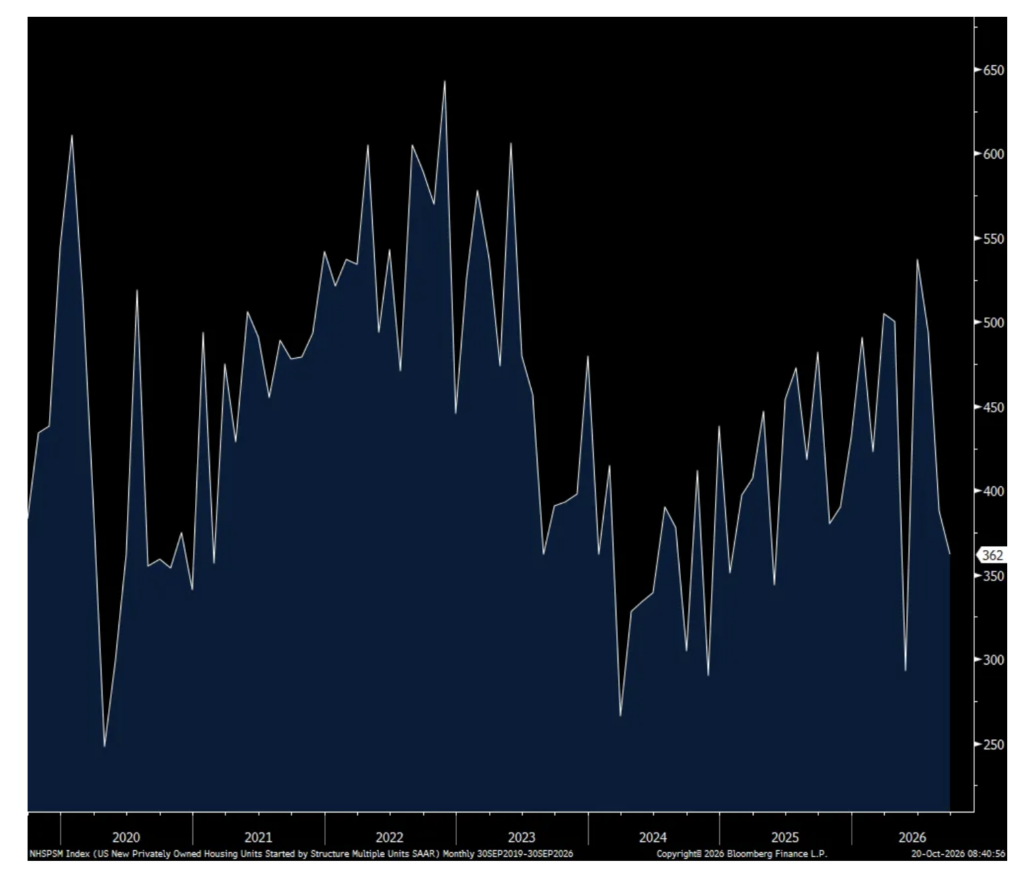
Multi family starts slowed to 362k from 388k in August and vs 494k in July. This is a very volatile monthly figure but most relevant hearing from the publicly traded multi family REITS, sunbelt construction has slowed dramatically. I do believe though new starts have picked up in the coastal states and apparent in the Tri-State area burbs that I see.
Permits for single family homes fell to 845k and that is the lowest since March 2023. They rose to 555k from 523k for multi family.
With buying a home for a first time interested buyer ever more difficult, I think the excess apartment supply in parts of the country will get further absorbed and in 2027 we’re going to see an inflection up in rents again. Single family starts will remain challenged until income gains catch up to the price increases and/or mortgage rates fall.
And on the supply side, I’ll mention here again what was said in yesterday’s NAHB report: “tight lending conditions and elevated land, labor and construction costs persist” and “Builders also continue to face higher material costs, rising gas and diesel prices and persistent labor shortages. In some markets, builders report that increased immigration enforcement is discouraging legal workers from reporting to job sites.”
Single Family Housing Starts
Multi Family Starts
With regards to pending home sales in September, they plunged by 7.3% m/o/m, well worse than the estimate of down just .5%. It now sits at a fresh low for this data point back about 25 years. The weakness was across all four main regions.
The reason is obvious, “Market conditions weakened in September due to fast-rising mortgage rates” said the NAR. Nothing more to add as we know exactly the challenges being faced in this key part of the US economy.
Pending Home Sales
BY Doug Kass · Oct 20, 2026, 12:15 PM EDT
Positions: None.
BY Doug Kass · Oct 20, 2026, 11:55 AM EDT
I have covered my SPY short at $768.98 for a quick profit.
Position: None
BY Doug Kass · Oct 20, 2026, 11:39 AM EDT
Break in!
Equities are taking a leg lower based on reports (from “Trade The News“) that an Iran/U.S. ceasefire deal is “close” is untrue.
Position: None
BY Doug Kass · Oct 20, 2026, 11:33 AM EDT
BY Doug Kass · Oct 20, 2026, 11:05 AM EDT
From Toddo:
Positions: None.
BY Doug Kass · Oct 20, 2026, 10:55 AM EDT
With S&P cash +37 handles I have begun to short SPY at $770.24
I am scale seller on strength.
Positions: Short SPY
BY Doug Kass · Oct 20, 2026, 10:45 AM EDT
I moved from VS to S SPY short at $772.04
Positions: Short SPY S
BY Doug Kass · Oct 20, 2026, 10:33 AM EDT
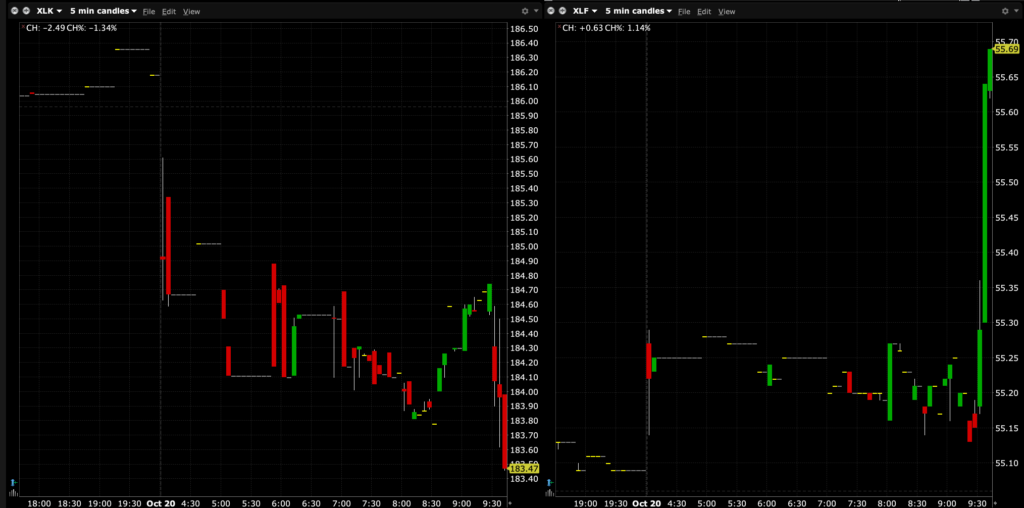
Chart from 9:40 a.m. ET
BY Doug Kass · Oct 20, 2026, 10:15 AM EDT
The following is from Peter Boockvar:
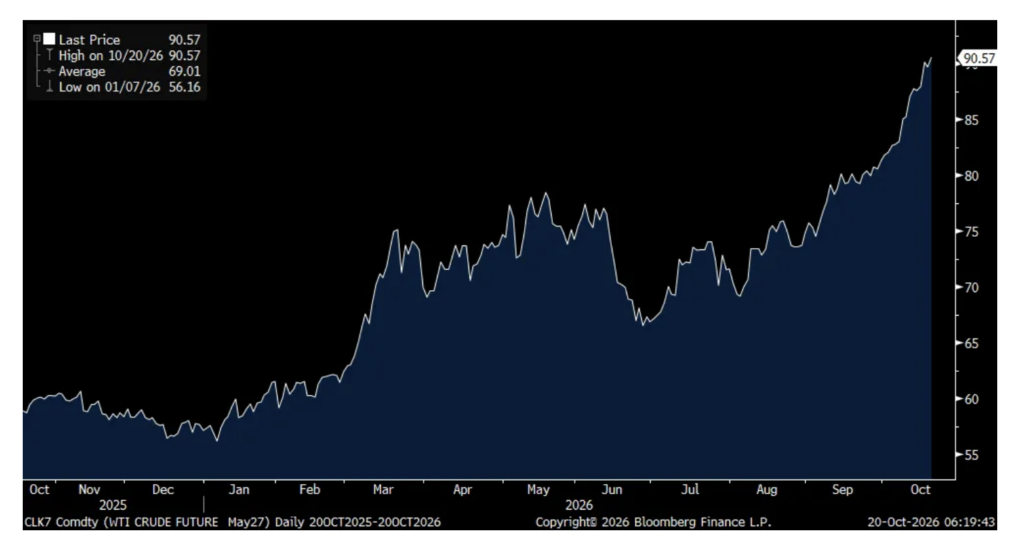
Not only is the November WTI futures contract making a new high in this cycle, up $5 today to $109, noteworthy too is the 2027 contracts are moving higher as well as the possible reality of higher for longer oil prices sink in. For example, the May 2027 WTI futures price is now above $90 for the first time. While not good for users of crude, aka the refiners in terms of margins and consumers of their products, it’s what investors such as us in E&P and service companies want to see.
May 2027 WTI futures price
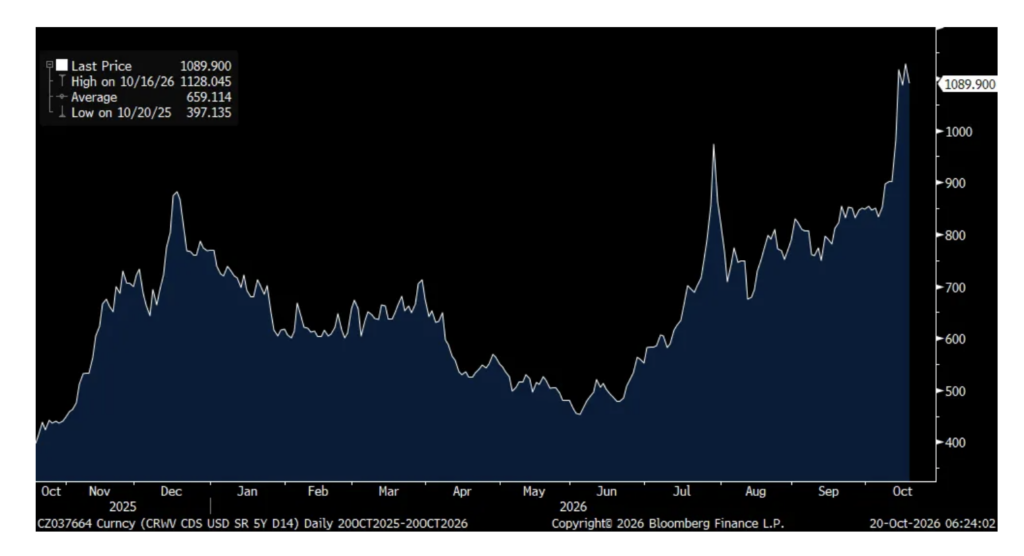
Talking about Coreweave again, the stand off between credit and equity participants is quite fascinating. While Coreweave still has about $35 billion of equity market cap currently, the 5 yr CDS yesterday closed at 1089 bps (down 38 on the day) which means it cost almost $1.1mm per year for 5 years to hedge against $10mm worth of Coreweave bonds. That implies about a 55% chance of default and, which means if it were to be the case, the equity would likely have no value. Who will be right?
Coreweave 5 yr CDS
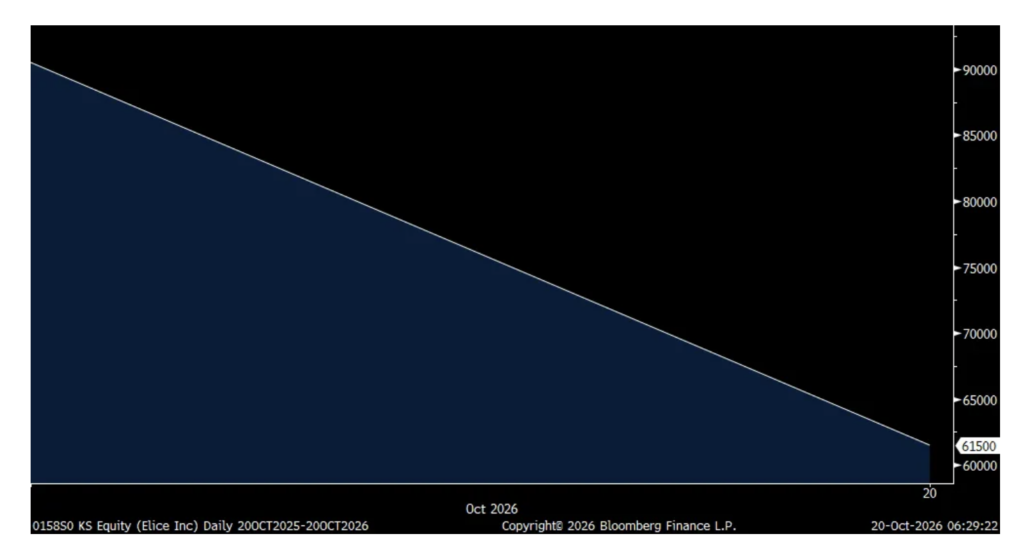
I never heard of the company Elice until today. It is a South Korean based neocloud that went public overnight in a disastrous debut. They priced its shares at 90,500 won and the stock closed at just 61,500 won, a decline of 32%. The main reason for this is that the initial pricing took place on October 6th and we know a lot in the neocloud world has happened since. I’m not clear why this is their IPO process, allowing two weeks to pass before letting a stock trade publicly.
In a fast moving tech world, who in their right mind in South Korea would fund their next IPO with such a large gap in time between pricing and trading?
Elice
To a few earnings calls of note.
From Cleveland Cliffs, a company that has been a vocal supporter and financial beneficiary of steel tariffs in contrast to those who use that steel as an input and whose stock popped 16% yesterday:
“All three of our major profit drivers improved. Shipments increased, selling prices rose in line with our expectations, and costs performed better than we had guided.
“One thing that has become very clear over the past year is that a healthy domestic steel industry happens when trade blocks are enforced and when foreign producers are no longer allowed to dump steel into our markets without consequences.”
“As a consequence of the renaissance of manufacturing in the US, we are currently selling steel under the best price environment in three years.”
And that customer of theirs will certainly have to pay, “All these contracts reset on January 1st of next year and nearly all of these customers want more steel under contract in 2027 than in 2026. Suffice to say that we have been very successful in renewing these contracts.”
From Fifth Third Bancorp, up marginally yesterday and one of my go to regional bank calls:
“On credit, performance remained in line with our expectations. Net charge-offs were $139 million, or 31 bps, up 1 bp sequentially, and at the low end of our 30 bp to 35 bp range we guided to in July.”
“We are focused on limiting exposures most sensitive to higher rates and continue to grow in categories where we have long underwriting histories and structural protections. Our exposure to non-depository financial institutions was 8% of total loans at quarter-end, concentrated in subscription and capital call facilities, corporate facilities to traditional financial institutions, and secured lending to mortgage related entities, with private credit exposures representing less than 1% of total loans.”
“We expect average loan growth of 1% to 2% sequentially, led by continued commercial loan growth, primarily in C&I and CRE.”
On the impact of higher rates on the decision making of their customers with respect to taking out a loan, “Certainly as people talk about high rates, it influences how they think about the world, but I think in general, the feedback that we’re hearing overwhelmingly is that it is still a growing economy, and high rates are not the meaningful driver of decision making from here. It’s like they need investment because they’re worried about continued inflation and input costs and things where they know they need to make this investment, they want to go ahead and get it done. Another 50 bps to 100 bps on rates does not impact their view.”
“They do worry about demand from here, if there were a broader slowdown because of rates. But in general, most of our clients are saying that they are going to continue to move forward with investment.”
There was a negative preannouncement from Werner Enterprises, the trucking company that said the same thing that JB Hunt did last week and whose stock fell 8% yesterday:
“Financial results for the 3rd quarter 2026 were negatively impacted by approximately $.18 per share of cumulative cost headwinds compared to the 2nd quarter of 2026, primarily consisting of: rapidly rising fuel prices; driver recruitment and retention investments; and a late quarter insurance reserve adjustment related to past claims.” This is offsetting strong revenue growth mostly driven by higher trucking rates.
The CEO of Ryanair, the European airline, was speaking today ahead of their earnings on November 2nd and said this:
“You’re going to see the biggest increase in airfares, I would say, in history in Europe in the next 12 months. The question is, will that increase in airfares be enough to cover the dramatically higher oil bills? I don’t think it will be.”
The overseas data of note was out of Germany and the UK. The German October ZEW investor expectations survey on their economy fell to 28.1 from 34.7. The estimate was 30. The Current Situation though did improve to -35.9 from -47.1. ZEW said “The German economy is slowly emerging from stagnation, but the recovery is not self-sustaining. Private consumption and investment remain weak because of high energy prices: They put real incomes under pressure, increase production costs and keep inflation higher for longer.”
This is not market moving as the IFO is more relevant but does highlight the challenges for German business.
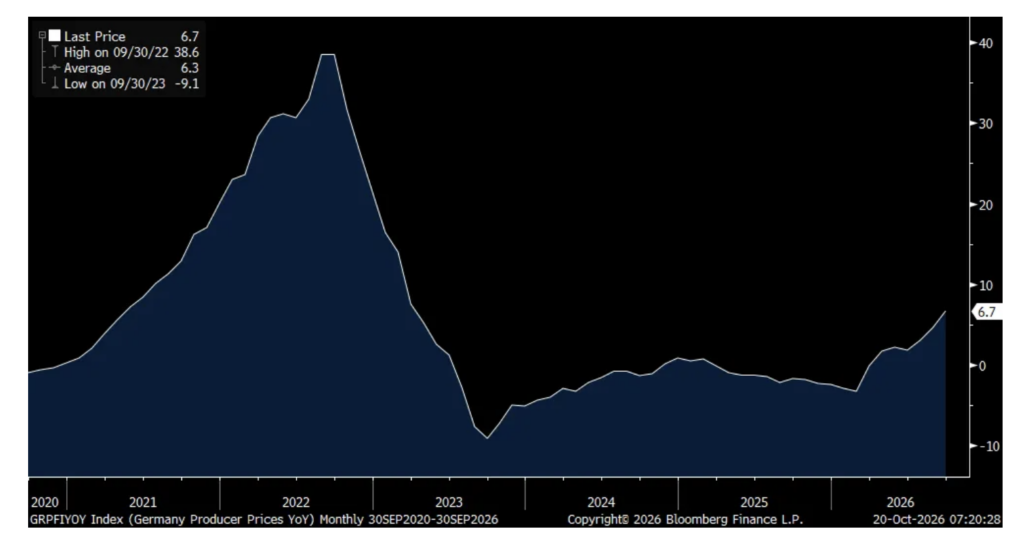
Germany also said its September PPI rose 6.7% y/o/y, up from 4.6% in August. That is well above CPI, similar to the story in the US.
In September, the UK jobs number was better than expected with a gain in those employed rising by 13k vs the estimate of down 8k. Also, August was revised up to a gain of 1k, up from the initial print of down 26k. Jobless claims though jumped by 30.3k but August was revised down by 20k.
Thru August, the UK unemployment rate held at 4.7% and wage growth ex bonus rose 3.7% y/o/y which is decent but really only just keeping up with inflation.
The better jobs data has the pound higher while the 2 yr gilt yield is up by 3 bps and the 10 yr gilt yield is higher by 1 bp. The FTSE 100 is lower by .6%, though up 8% ytd.
German PPI y/o/y
BY Doug Kass · Oct 20, 2026, 9:55 AM EDT
Adding small to MSOS ahead of tomorrow’s DEA decision.
Positions: Long MSOS common VL and calls VS
BY Doug Kass · Oct 20, 2026, 9:42 AM EDT
Lake Street has lowered the firm’s price target on GlassHouse (GLAS) to $7 from $17 and keeps a Buy rating on the shares after the company reported “mixed” preliminary Q3 results. Following the pre-announcement, the firm reduced its 2026 and 2027 adjusted EBITDA estimates to reflect softer pricing, unfavorable product mix, and a more gradual margin recovery.
Long: GLAS S
BY Doug Kass · Oct 20, 2026, 9:35 AM EDT
I am not sure I agree with Dalio – but here you go:
Positions: None.
BY Doug Kass · Oct 20, 2026, 9:28 AM EDT
* Like Fundstrat’s Tom Lee…
Positions: none
BY Doug Kass · Oct 20, 2026, 9:27 AM EDT
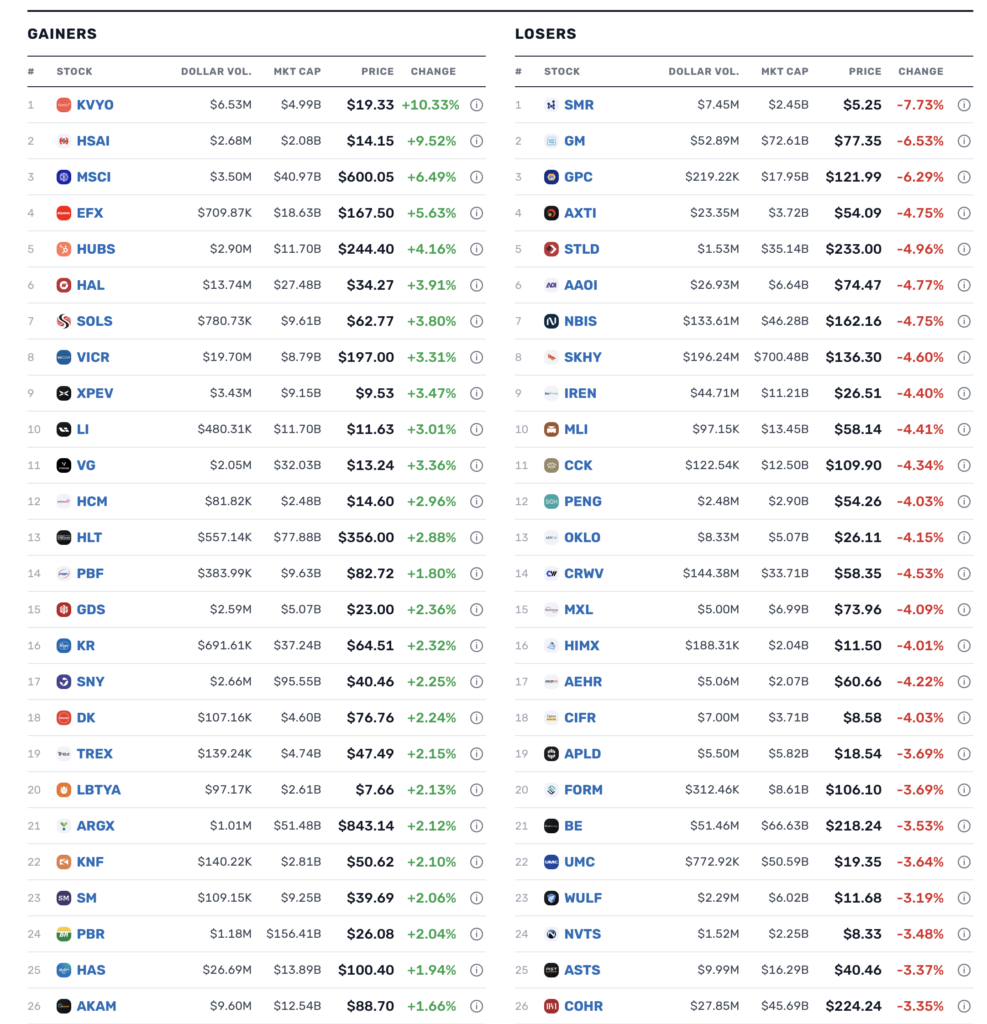
– RAPP +26% (Phase 2 RAP-219 trial met the primary and secondary endpoints in bipolar mania)
– MSCI +5.9% (Q3 earnings and revenue topped expectations)
– EFX +5.5% (sharply positive initial reaction to Q3 results released before the bell)
– HTZ +5.0% (Oro Mobility secured an $80 million strategic equity investment to accelerate its standalone growth)
– HAL +4.4% (Q3 earnings and revenue beat expectations)
– SNY +2.4% (no clear fresh catalyst identified; unusually strong, liquid ADR move)
– APA +1.9%, XOM +1.2%, CVX +1.4%, COP +1.5%, OXY +1.6%, SLB +1.4% (energy names rise as crude jumps on renewed Middle East supply risks)
– VICR +1.7% (Q3 product and royalty revenue surged and gross margin expanded sharply)
– GM -7.6% (Q3 beat, but the full-year profit range was narrowed with the upper end cut, disappointing expectations for another guidance raise)
– GPC -6.3% (quarter narrowly beat, but the full-year earnings range was narrowed and its upper end cut)
– STLD -5.4% (Q3 profit missed consensus and fell below the company’s own guidance despite a revenue beat)
– AAOI -4.6%, SKHY -4.8%, COHR -3.5%, SNDK -3.2%, MU -2.7%, LITE -2.7% (AI hardware, memory and optical names fall as renewed bubble concerns and a weak Korean AI listing pressure the trade)
– CCK -4.3% (Q3 reaction turns negative as rising input costs offset strong beverage-can volume growth)
– CRWV -3.9%, NBIS -4.4%, IREN -4.3% (debt-heavy AI-infrastructure names fall as borrowing-cost and funding concerns deepen)
– GE -3.6% (Q3 beat and the outlook was raised, but shares slip in a high-expectations sell-the-news reaction)
– BHP -3.0% (quarterly copper production fell 19% on lower grades, maintenance and operational disruptions)
– AAPL -1.4% (Loop Capital downgrades to Hold from Buy and cuts its target on weaker iPhone shipment expectations)
BY Doug Kass · Oct 20, 2026, 9:00 AM EDT
Positions: None.
BY Doug Kass · Oct 20, 2026, 8:55 AM EDT
Source: TheStreet Pro
BY Doug Kass · Oct 20, 2026, 8:45 AM EDT
BY Doug Kass · Oct 20, 2026, 8:33 AM EDT
Positions: Long KO VS
BY Doug Kass · Oct 20, 2026, 8:15 AM EDT
Tomorrow is D-Day for Rescheduling news:
Position: None
BY Doug Kass · Oct 20, 2026, 8:05 AM EDT
Position: None
BY Doug Kass · Oct 20, 2026, 7:54 AM EDT
* Monday was another day of divergences — with interest rates moving higher and foul market breadth.
* Meanwhile, momentum-based products and strategies (that know everything about price and nothing about value) followed the strong intraday price momentum and ignored the aforementioned divergences.
The S&P Short Range Oscillator moved further into oversold territory at -0.66% vs. -0.08%.
As I mentioned in yesterday’s “Regrets” column, I missed an opportunity to short the gap higher yesterday because of machine/algo-derived market uncertainty and volatility.
Let me explain…
Today’s market structure, as I have previously noted, has produced an unpredictable short-term pattern of equity prices. The ever-growing treasure chests of index funds control stock floats and the pods and other momentum-based quant funds have become the marginal buyer/seller (in which unemotional machines and algorithms dominate much of the trading activity of passive strategies and structures).
Yesterday the “buyers lived higher” — serving to exaggerate the day’s advance. The problem I have and others have is that one simply doesn’t easily know when the buying will be sated and how high the machines will take stocks higher.
On Monday, with S&P futures more than +65 handles, the buying just stopped (without a catalyst) and the S&P fell by about -30 handles into a large ($8 billion) market on close imbalance. This morning S&P futures are -5 handles (-0.05%). (The Nasdaq, in percentage terms, is down more -0.40%.)
Importantly Monday’s advance was featured by the conspicuous divergences of higher interest rates and poor breadth — two signposts that usually lead me to short the indices:
* Another rise in interest rates (TLT ended at the day’s lows).
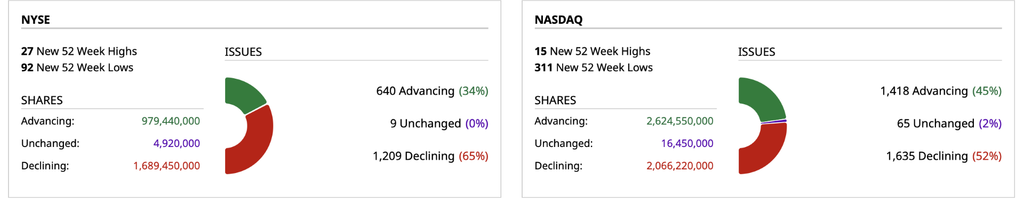
* Market breadth was foul:
“Kill the machines before they kill our markets.”
Position: None
BY Doug Kass · Oct 20, 2026, 7:30 AM EDT
Much like politicians, the narratives from the “Permas” always change …. to fit the view.
Position: None
BY Doug Kass · Oct 20, 2026, 7:05 AM EDT
Position: None
BY Doug Kass · Oct 20, 2026, 7:00 AM EDT
$CRWV Every AI related company with questionable accounting hoping @1CoastalJournal doesn’t come for them “…On a GAAP basis, CoreWeave LOST -$290.5 million in Q2. But with the stroke of an “adjusted EBITDA” wand, it suddenly became $753 million in profit with a 62% margin.


This is really pretty incredible. US household holdings of equities and mutual funds reached a record 278% of disposable personal income in the second quarter of 2026, up from just 29% in 1982, amplifying the stock market’s influence on consumer spending and economic activity.

🇺🇸 cannabis 🌿

The market gave up on Pepsi. PepsiCo's forward P/E just fell to about 14x, its lowest since 2009 and a deep discount to Coca-Cola near 24x. Same aisle, same shopper, opposite verdict. A staple priced this cheap against its rival is the market calling it a broken growth story.Show more

BREAKING: US margin debt jumped +$26 billion in September, to $1.48 trillion, the 2nd-highest level on record. Since the start of 2026, margin debt has surged +$255 billion, or +21%. As a % of GDP, this metric is up to a record 4.5%, surpassing the previous peak of 3.6% set in Show more

During the pandemic, Peloton could not keep up with demand for its bikes. At one point it was spending $100 million just on air freight to get bikes to customers faster, and it committed $400 million to build its own factory. At the height of demand, management was forced to Show more
“When it neorains, it neopours.” @business bloomberg.com/news/articles/…

Dr. KOSPI: AI Bubble Crash resumed overnight, down another -3.7% closing below last week's lows and -39.1% from #MOAB

10-Year Real Yield hits highest level since the Global Financial Crisis 🚨 🚨 🚨

This is fascinating from Ray Dalio. Gold ETFs currently account for 87% of his portfolio. As he likes to say: “If you don’t own gold, you know neither history nor economics.” tavicosta.substack.com/p/shortage-of-…

Joe Rogan on Trump Administration rescheduling marijuana: “Another thing the Trump administration has done with marijuana, they're moving marijuana into Schedule 3. So instead of it being this thing that has ‘no medical use’- well of course it has medical use. It helps cancer Show more
Hey remember when NVIDIA announced a completely imaginary $500 billion “ai infrastructure deal,” announced on CNBC with the heads of multiple private equity funds, everyone wrote about it how it was real and then absolutely nothing happened?

Per Bloomberg, Goldman, Blackstone and Apollo have been having "slow progress" on AI data center debt deals, but Jensen Huang decided to rush out the $500 billion announcement, which has "no obvious provenance." So I guess it was all BS then? bloomberg.com/news/articles/…


