Daily Diary

Doug KassDoug Kass
DATE:

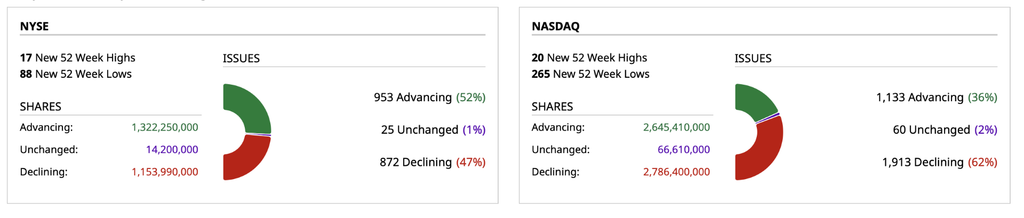
Friday’s Closing Market Statistics

Volume

– NYSE volume 25% below its one-month average 

– NASDAQ volume 1% below its one-month average 

– VIX index: up 3.48% to 19.35

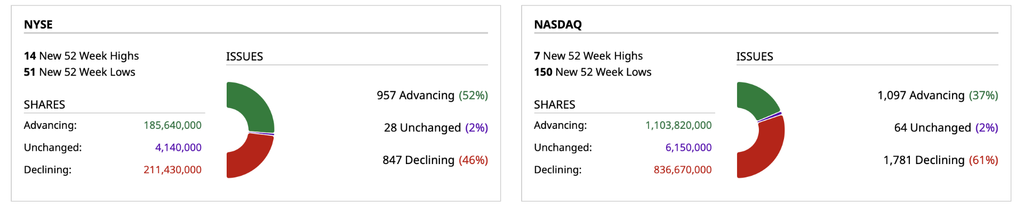
Closing Breadth

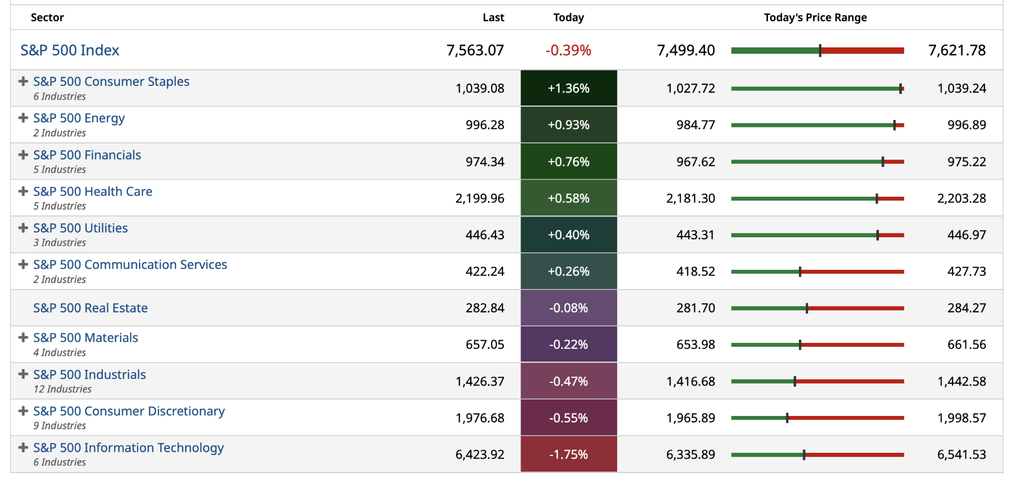
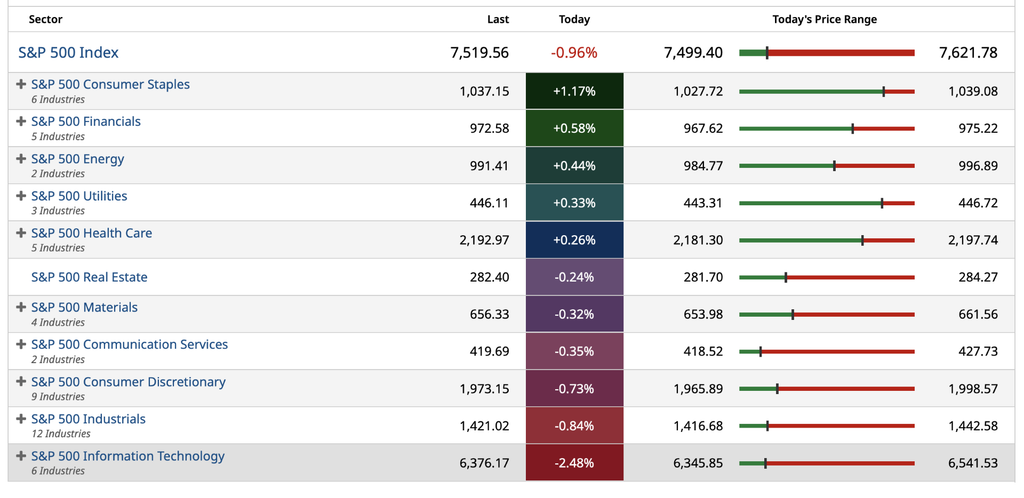
S&P 500 Sectors

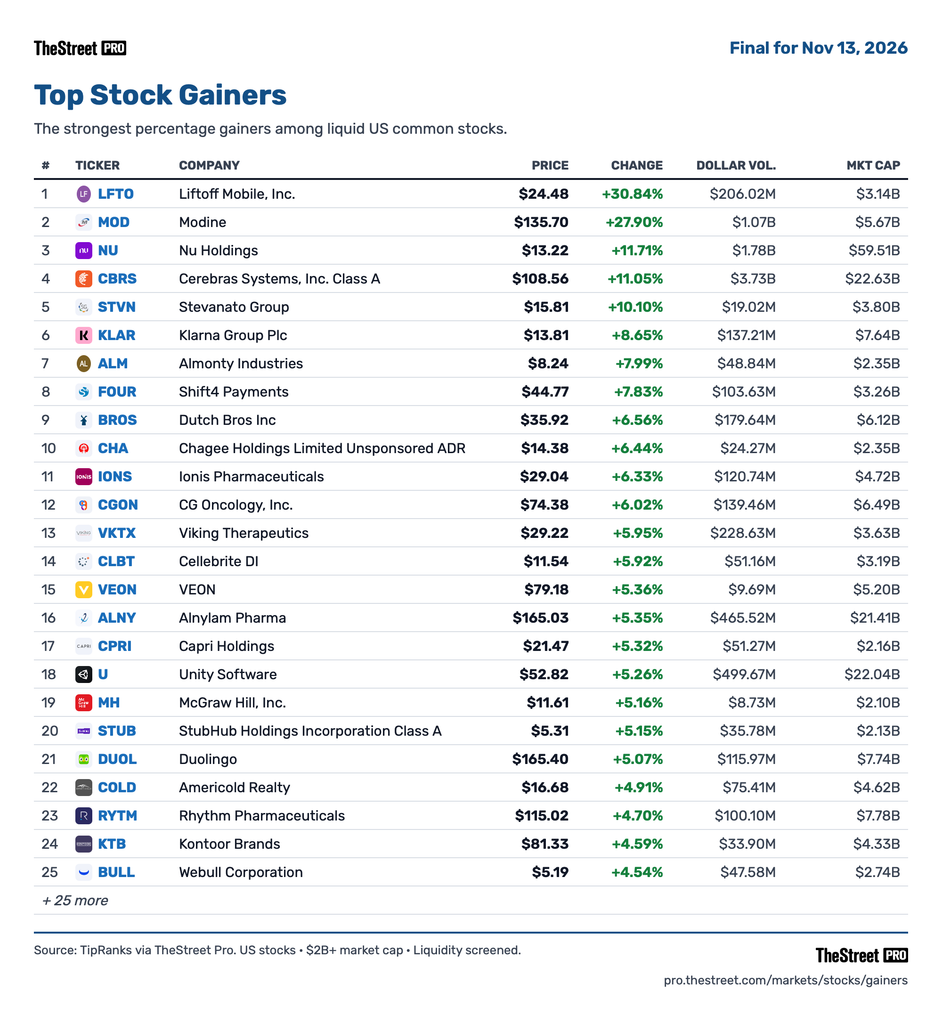
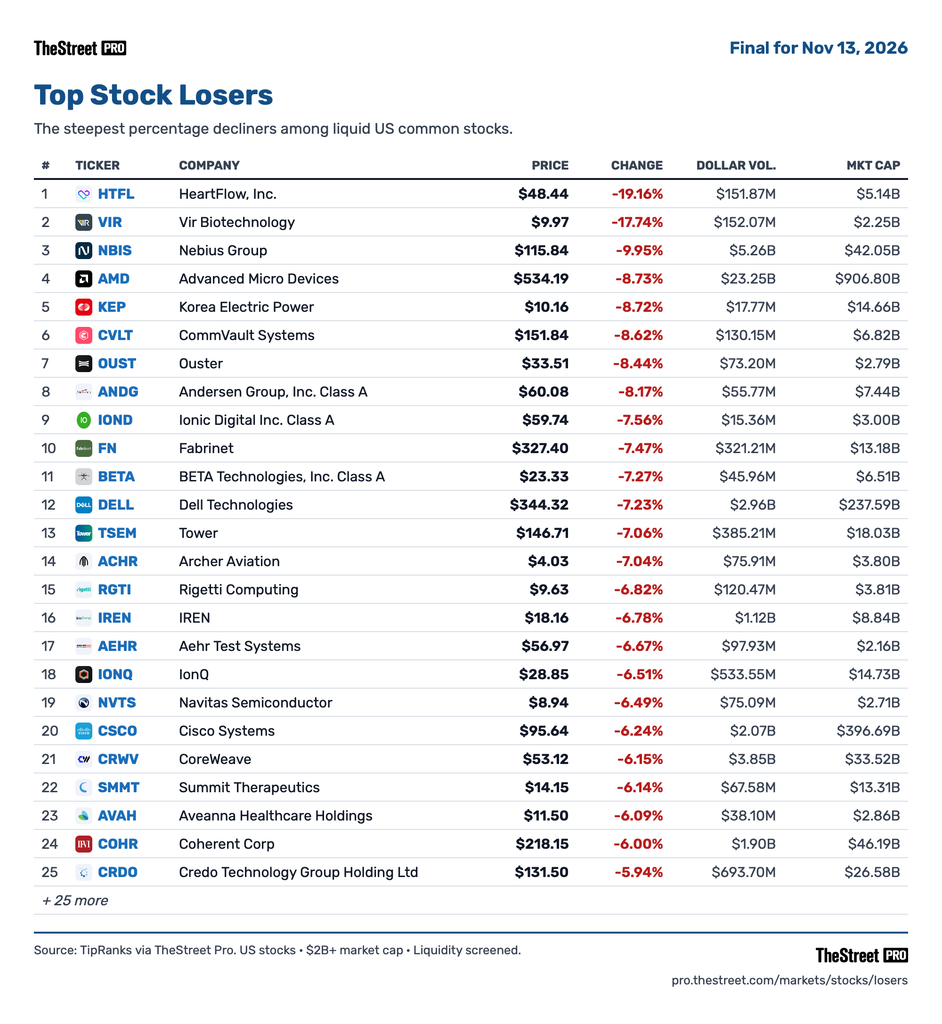
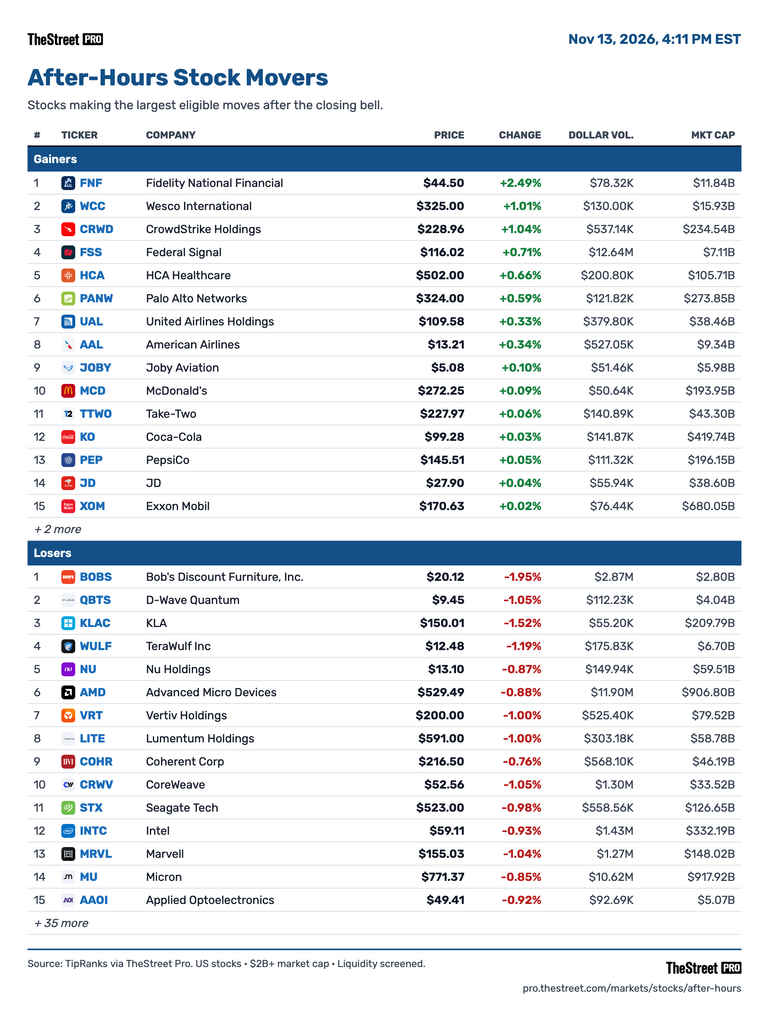
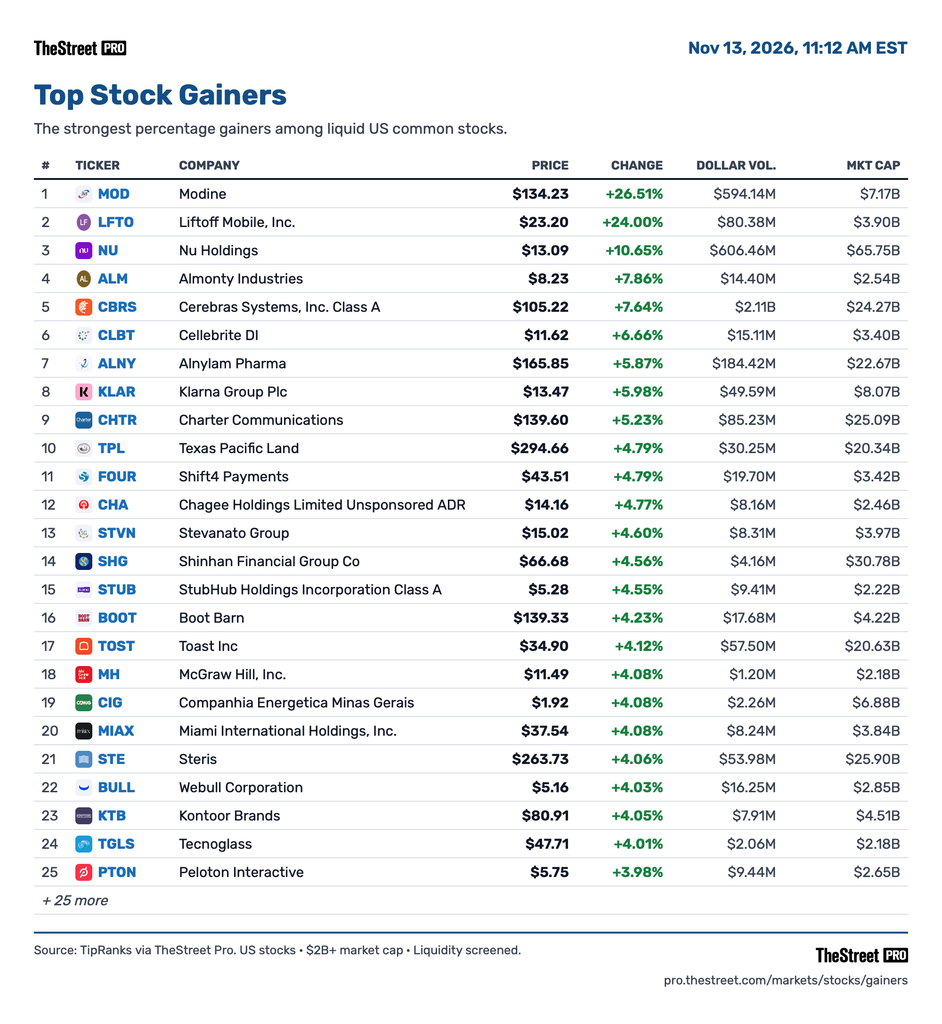
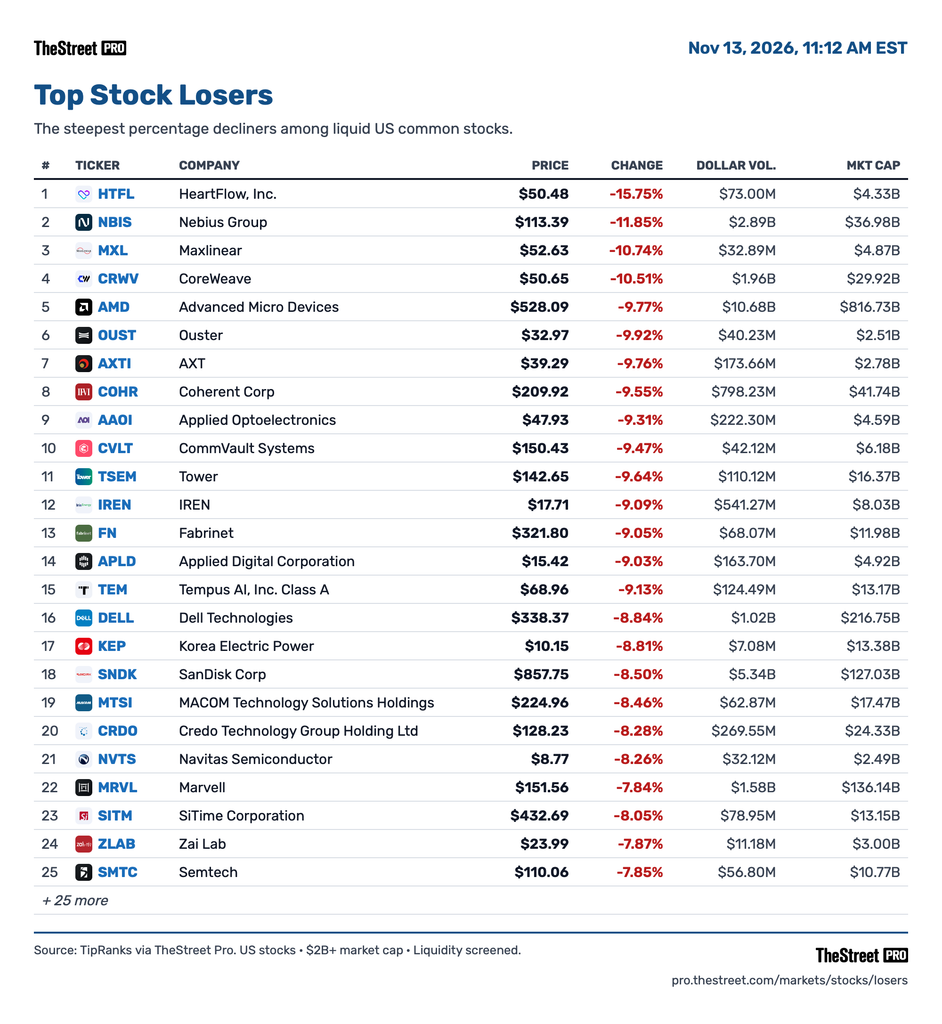
% Movers

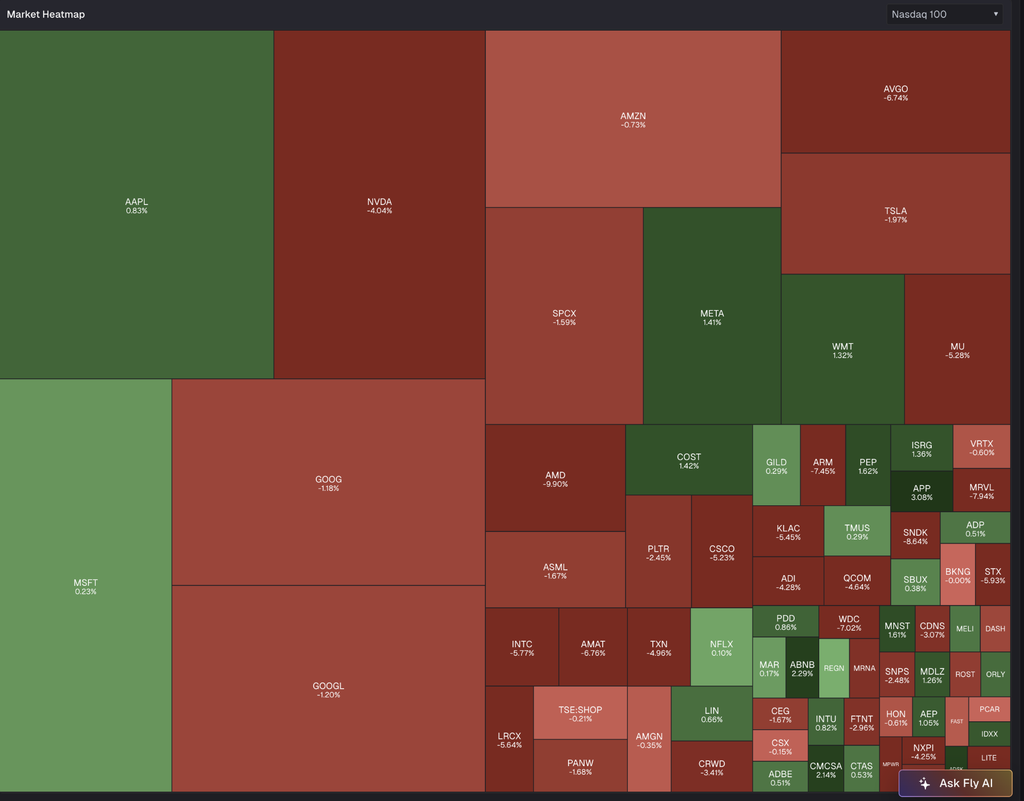
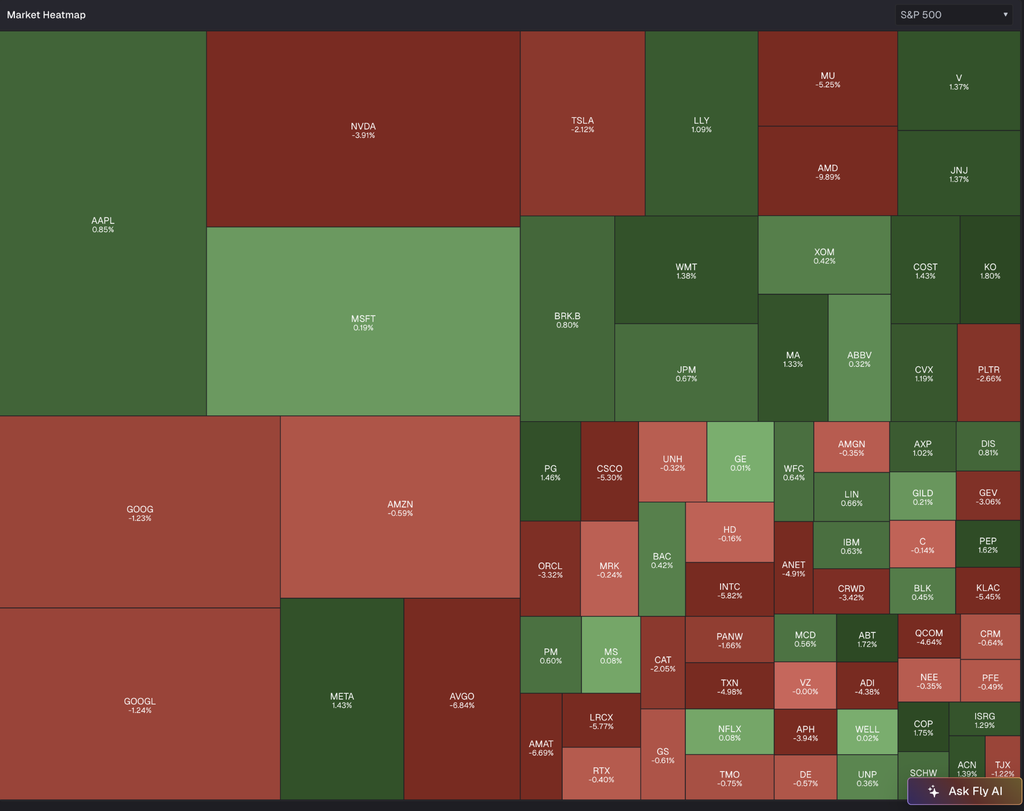
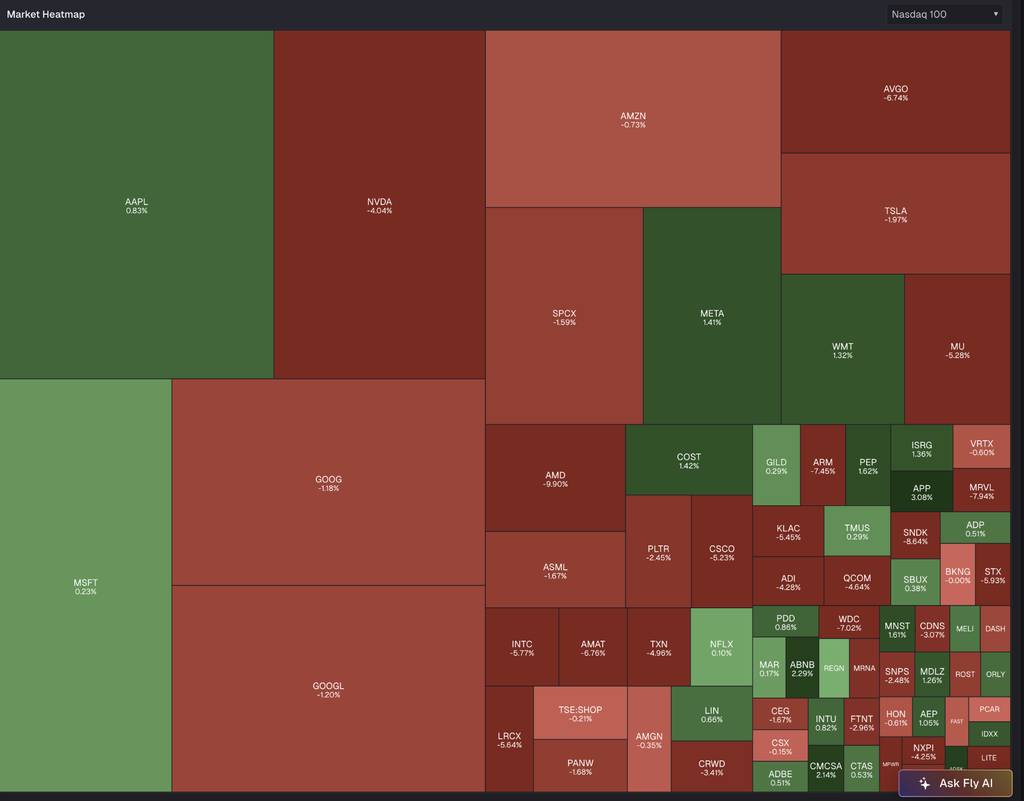
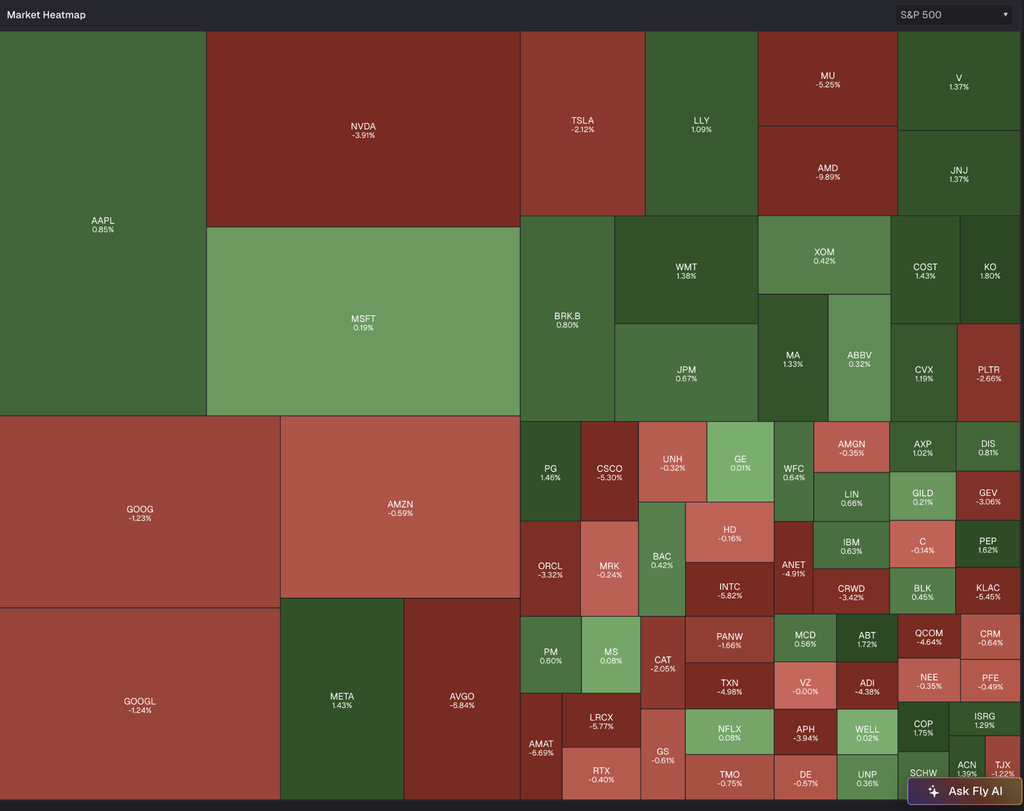
Heat Maps

Position: None

BY Doug Kass · Nov 13, 2026, 4:50 PM EST

Boockvar Sums Up a Busy Week

From Peter Boockvar:

Positives,

1)Initial jobless claims rose 9k w/o/w to 200k and that was 6k above expectations but still remaining very low. The 4 week average remains the same at 195k as a print of 200k dropped out. Continuing claims remained low, falling to 1.697mm from 1.717mm.

2)On the macro, ZipRecruiter mentioned “we are growing again despite a low, hire, low fire market.”

3)With the help of another dip in mortgage rates, down for a 4th straight week to 7.21% on average, purchase applications rebounded by 7.5% w/o/w and refi’s were higher by 4.5%.

4)From CoreWeave: “Revenue is growing rapidly. Margins are rising faster than planned. Customer demand remains extremely strong, and our newest contracts are among the most profitable we have ever underwritten. Our original fleet of cloud infrastructure is re-contracting at premiums, producing cash flow in excess of what we assumed when we made those early investments. And our funding is anchored by secured lending, customer prepayments, and operating cash flows.

5)From Nebius: “Demand is strong. Our customers are committing to us for longer, at higher prices, and they are paying more upfront. Prices keep rising.

6)From Cisco: “Our strong start to fiscal year ‘27 demonstrates the criticality of networking and security together as agentic AI accelerates.”…We believe we are still early in the networking super cycle driven by AI deployments with enterprise adoption just beginning.”

7)From Legence: “Conversations with our data center customers post-election indicate a continuation of their plans to build.”

8)From Ferguson: “Our diversified exposure across large capital projects, public works, municipal and water and wastewater treatment helped us offset ongoing weak new residential construction.” Their commercial/mechanical business rose 17% and “This momentum was driven by our disciplined execution on large capital projects such as data centers, pharma, biotechnology and general manufacturing.”

9)From Cummins: “Growth was driven primarily by improved demand in North America heavy and medium duty truck markets and continued strength in global power generation, particularly from data center customers.”

10)From Maersk: “At a macro level, market demand in ocean remained resilient, driven by strong export activity from the Far East and imports into Africa, Latin America and North America, in particular. A growing share of the incremental volume growth is coming from verticals with green shoots and AI related technology, which are growing two or three times the speed of the overall market.”

11)From Richemont: “in the first half, group sales grew by 17% at constant exchange rates with broad based strength across business areas and regions. This included a remarkable 19% growth at the Jewelry Maisons, a robust double digit rise at specialist watchmakers, and a solid high single digit performance at the other business area, which includes fashion and accessories Maisons…In addition, most regions posted double digit growth, led by Japan, the Americas, and Asia Pacific. Impacted by the ongoing conflict in the region, sales in the Middle East and Africa experienced a modest decline overall.”

12)From Bloomin’ Brands: “we’re cautiously optimistic on the consumer. There’s some macro choppiness. But what we’re seeing with the consumer is casual dining is still an affordable luxury. Consumers, they’re resilient financially, they are cautious and they continue to be discerning about when, where, and how often they dine out.”

13)From Starwood Property Trust: “I want to step back a little bit and talk about the real estate asset class as a whole because with all the chaos of the interest rate markets and the volatility of political politics, real estate is healing. The underlying asset classes are getting better and better, and at an increasingly better pace.”

14)From Camden Property Trust: Good for them, not so much for renters, “On a macro level, things are also improving as apartment completions in the Sunbelt markets have fallen to a 7 yr low with peak supply firmly in the rearview mirror. Rising interest rates, commodity prices, and labor shortages are further hampering new construction starts to mid 2010s levels or below, meaning we should have a long runway with continued low levels of future supply. Apartment absorption remains robust with year-to-date figures exceeding expectations across many markets…Market rental prices and vacancy trends are also improving. Effective rents for new units have recovered from their lows, though they remain below peak levels in most markets, and rent growth momentum is increasing.”

15)In China, October consumer price inflation remained benign, up .7% headline and .8% core and is a good thing for a consumer there that is still reluctant to spend.

Negatives,

1)It’s a sad moment to see the downfall of one of the greatest entrepreneurs of our generation.

2)October headline CPI rose .4% m/o/m and by .3% core with both one tenth above expectations. Helping to drive the top line was the .7% m/o/m gain in energy with a 1% rise in gasoline, 2% increase in fuel oil and a .9% jump in electricity prices. Gasoline prices are receding since this print but electricity prices we know helped in part to drive the election results. ‘Food at home’ saw prices up .4% m/o/m and by .5% for ‘food away from home.’ Services prices ex energy rose another .3% m/o/m with OER also up by .3%. On the core goods side, prices rose .2% after a .3% gain in September.

3)Including the revision to September, the October PPI stats were right in line with expectations with a .3% headline and core increase from 1.4% and .8% respectively in the month before. But, the y/o/y gains are 6.5% and 5%, remaining hot and running about 250 bps above consumer price inflation. Core goods prices (ex food/energy) rose .5% m/o/m and 5.2% y/o/y led by organic chemical pricing which jumped by 3.9%. Service prices were up .2% m/o/m and 5% y/o/y.

4)Existing home sales in October totaled just 3.75mm, a similar pace seen 30 years ago with 80 million less people living in the US. The NAR said simply, “Home buying is difficult when mortgage rates have climbed to their highest levels since 2000.” The positive was that the median home price rose just .4% y/o/y, allowing wage growth to exceed the gains and thus a step closer to improving affordability.

5)From the Dallas Fed’s Banking Survey: “Loan volume continued to grow at the same pace as the prior period. Credit standards and terms tightened, and loan pricing increased broadly. Despite the higher interest rate, loan demand increased further. Overall loan performance weakened slightly after having improved for the last two surveys. Bankers reported a decrease in general business activity on net. Outlooks are mixed. Survey respondents expect an increase in loan demand but a decline in business activity six months from now, as well as a deterioration in loan performance.”

6)In the NY Fed’s Consumer Expectations Survey, one year inflation expectations held at 3.9%. Elsewhere they said this, “Labor market expectations were mixed with unemployment and job loss expectations deteriorating, while job finding expectations improved. Expectations of an increase in unemployment reached the highest level since April 2020. Conversely, job finding expectations reached their highest level since November 2025. Income and spending growth expectations were broadly stable while delinquency expectations deteriorated.”

7)The October NFIB Small Business Optimism index was little changed m/o/m at 97.8 vs 97.9. The bottom line from the NFIB, “There was little change in optimism among small businesses in October as owners navigated enduring challenges, though there were some encouraging developments. Even with inflation pressures continuing to strain operations, more Main Street owners reported their businesses in good or excellent health, and actual sales improved. Looking ahead, continued strength in consumer spending will support economic growth, while persistent inflation, labor shortages, and policy risks will weigh on the small business outlook.”

8)From Nebius: “Building at this scale is hard, and delays are part of our industry right now. We are not immune. For example, some of our co-location sites, including New Jersey, are behind schedule.” And, “CapEx for 2026 is now expected to be around $27 billion, up from $20 billion to $25 billion previously.”

9)From Cisco: Answering a question about the sequential downtick in AI orders, “So, while I don’t expect there’s normal linearity in this business at all, I think you’re right, it’s going to be lumpy. And there’s going to be some quarters that are going to be big, others that are going to be smaller.”

10)From Brightview Holdings: “The slowdown in development was driven by three key factors. A sharpening decline in the residential construction end market, delays on several large jobs and delayed bid awards as customers navigate a volatile macro environment underpinned by higher interest rates and inflation. Since 2024, our development revenue related to residential projects has softened in line with the broader slowdown in residential construction.”

11)From Yeti: “Looking ahead, we anticipate the consumer environment will remain cautious and put pressure on demand in Q4.”

12)From On Holdings: “Throughout our markets, we held full price discipline despite online traffic being a little softer in a promotional environment.”

13)From Bloomin’ Brands: “The only thing I would say in terms of sensitivity, which we flagged in previous quarters, there’s a little bit of sensitivity on check with households that are under that $75,000 range. And it’s a little bit on the older guests where we’re seeing some check management.”

14)From Papa John’s Pizza: “North America continues to be challenged, driven primarily by the same factors we discussed last quarter, including an intensely promotional environment and softer new customer acquisition…clearly the K shaped economy is what everybody’s been talking about. Some of the consumer sentiment, consumer trends that we talked about in the 2nd quarter continued into the 3rd quarter.”

15)From Under Armour: “By region, North America revenue declined 7%, reflecting continued traffic pressure in our direct-to-consumer business and softer wholesale sell-through. Growth in select apparel franchises helped, but did not fully offset broader demand pressure.” Revenue also fell in EMEA and APAC but rose in Latin America due to FX, though was down ex this.

16)Japan said its October PPI jumped by 7.1% y/o/y, above the estimate of 6.5% and up from 6.8% in September.

17)In China, October PPI rose 5.7% y/o/y as higher commodity prices, among others, impact them as it is everyone. That was up from 5% y/o/y growth in September and 4 tenths above the estimate.

18)In the 10 months of 2026, China’s trade surplus is already at $1 trillion after today releasing its October data where exports rose 35% y/o/y and imports jumped by almost 42%.

Position: None
BY Doug Kass · Nov 13, 2026, 4:30 PM EST

FAA Ground Stop

Break in!

Position: None

BY Doug Kass · Nov 13, 2026, 4:09 PM EST

Remember This: We Warned Everyone in ‘More Tales’

Give ’em the old razzle dazzle
Razzle Dazzle ’em
Give ’em an act with lots of flash in it
And the reaction will be passionate
Give ’em the old hocus pocus
Bead and feather ’em
How can they see with sequins in their eyes?

What if your hinges all are rusting?
What if, in fact, you’re just disgusting?

Razzle dazzle ’em
And they’ll never catch wise!

– Chicago (Billy Flynn), Razzle Dazzle   Chicago | 1976 Tony Awards

Position: None

BY Doug Kass · Nov 13, 2026, 3:50 PM EST

Much Appreciation

With 30 minutes to go in this week’s trading I am going to take an early leave as I am exhausted.

I want to sincerely thank all our subscribers for providing me with this platform since 1997.

I also want to thank our editorial staff for dealing with my run on sentences (etc.) and for getting up at 5 AM every morning to start reviewing my Diary’s columns. 

I honestly don’t know where the time has gone.

Enjoy the weekend.

Be safe. 

I am going to try to score my age in golf tomorrow. Wish me luck as I will need it

Position: None

BY Doug Kass · Nov 13, 2026, 3:30 PM EST

Doubling Up on Dell

I doubled up on DELL.

Position: Long DELL (M) 

BY Doug Kass · Nov 13, 2026, 1:35 PM EST

Added to 6 Longs

I added to GLD, TLT, C, MS, WFC and BAC.

Position: Long GLD (M), TLT (L), C (M), MS (M), WFC (S), BAC (M)

BY Doug Kass · Nov 13, 2026, 12:57 PM EST

First Buy of the Day

I am buying back DELL at $336.71 — after selling much yesterday ($361-$381):

My Dell Trade

Good sale of Dell (DELL) yesterday (between $361-$381):

From Diary:

Sold More Dell

I just sold some more DELL at $381.55.

Position: Long DELL (VVS)

BY Doug Kass · Nov 11, 2026, 11:53 AM EST

From Comments Section:

Brucetrader

Good Morning all. Thank you Doug, I followed you on the DELL trade and it paid for my subscription for the rest of my life. Impeccable timing entry and exit. 

Dougie Kass

Love!

Last sale is under $360 in premarket trading.

I am a buyer under $350.

Position: Long DELL (VVS)

BY Doug Kass · Nov 12, 2026, 6:58 AM EST

Position: Long DELL (S)

BY Doug Kass · Nov 13, 2026, 12:00 PM EST

Dan Niles on Nvidia

Position: None

BY Doug Kass · Nov 13, 2026, 11:54 AM EST

Late Morning Market Stats

Volume

– NYSE volume 23% below its one-month average 

– NASDAQ volume 15% above its one-month average 

– VIX index: up 7.43% to 20.09

Breadth

S&P 500 Sectors

% Movers

Heat Maps

Position: None

BY Doug Kass · Nov 13, 2026, 11:34 AM EST

Boockvar on ‘The Bank of Nvidia’, Tech and the Consumer

The following is from Peter Boockvar:

The breadth & reach of The Bank of Nvidia/Other tech news, consumer too/Williams wants another hike

As we now try to figure out what the fate of the Bank of Nvidia will be, let alone their core business with new leadership, this was a thorough piece from Bethany McLean laying out the extent of its financing reach. I mentioned yesterday the $99 billion of equity investments as of Q2 along with the other vendor financing and lease obligations but this goes much deeper into detail.

https://hntrbrk.com/investigations/nvidia

The other AI related news of note yesterday was the results from Nebius whose stock fell 17% after rallying by 15% on Wednesday in response to the CoreWeave earnings report. From their earnings call:

The positive case, “Demand is strong. Our customers are committing to us for longer, at higher prices, and they are paying more upfront. Prices keep rising. Q3 agreements closed above $25 million per megawatt, another step up from the $20 million to $25 million per megawatt we achieved in Q2. Our customer agreements are getting larger in size.”

And the make up of their contracts, “we sell on three horizons, and we choose the best mix between the three. First is on spot and short-term at a premium price. Another is one to three year contracts, and this is our core business. And a limited number of five year agreements that diversify our contracts, tenures, and further help us to finance our build out. The second and third are covered by prepayments.” And those prepayments “now cover more than 100% of the capital needed to bring this contracted capacity online.”

But, “Building at this scale is hard, and delays are part of our industry right now. We are not immune. For example, some of our co-location sites, including New Jersey, are behind schedule. Customers have been kept informed, and none of that capacity is canceled. Some of it has shifted to 2027. This means that a portion of this year’s planned revenue moves into the start of next year. But with our own sites, we remain on track and even ahead of schedule.” As a result, “For 2026 we are seeing some third party capacity shifts into the second quarter of 2027. We now expect revenue of $3 billion to $3.2 billion compared with our previous range of $3 billion to $3.4 billion.”

Also hitting the stock, “CapEx for 2026 is now expected to be around $27 billion, up from $20 billion to $25 billion previously.”

From Cisco and whose stock is down premarket as order growth rates outside of Asia Pacific moderated:

“Our strong start to fiscal year ‘27 demonstrates the criticality of networking and security together as agentic AI accelerates.”…We believe we are still early in the networking super cycle driven by AI deployments with enterprise adoption just beginning.”

Maybe why the stock is down, to an analyst question “it looks like we had a little bit of a sequential downtick in AI orders taken from microscales in the quarter. I know the industry is somewhat lumpy and not linear. Can you maybe talk to kind of how you’re seeing that develop as the year progresses and characterize the depth of your conversations.”

The answer from Chuck Robbins, the CEO, “So, while I don’t expect there’s normal linearity in this business at all, I think you’re right, it’s going to be lumpy. And there’s going to be some quarters that are going to be big, others that are going to be smaller.”

A company benefiting from the data center buildout has been Legence, as they “specialize in designing, fabricating and installing HVAC, process piping and other mechanical, electrical, and plumbing systems for new facilities” along with upgrading existing facilities. From their call yesterday:

“We also expect solid growth in data center activity, including in regions such as Northern Virginia, where certain tighter regulatory conditions have actually been in place starting in early 2026…Opportunities in the region extend several years out, and that pipeline remains significant. While the DMV (DC, Maryland and VA) is a substantial region for us, we also serve data center clients nationwide, shipping fabricated products across multiple regions and supporting clients wherever they choose to build. Conversations with our data center customers post-election indicate a continuation of their plans to build.”

They have other customers too, “Now beyond data centers, we expect the semiconductor and memory chip market to be quite robust going forward. Our other end markets, such as life science, education and state and local governments, provide diversification and exposure to other target rich clients that have historically delivered solid growth.”

Shifting gears to retail and the consumer, this was a call from last week but one I always find helpful to go through. From Simon Property, the largest mall operator in the country and who owns the Short Hills Mall that I just gave some money too this week:

“Traffic growth accelerated in the third quarter, furthering a trend we have seen throughout 2026. Sales productivity is a record levels for each of our platforms, underscoring the health of the retailers in our centers and the quality of our real estate.”

“Tenant demand remains widespread from established national and international brands to emerging fast growing concepts.”

On what they are seeing with the pace of customer spend, “it is very broad based. It is across platforms, across geographies, across categories that we have seen growth…And it’s the same story that we talked about in the second quarter, athleisure, juniors, brands, luxury, watches, jewelry. One thing that is a nice story is we had actually the best quarter in three years in the restaurants in the third quarter which that business has obviously been sort of flattish, I guess I would say.”

“And so, we really haven’t seen any slowdown in October traffic, in line with the third quarter in sort of that mid 3% growth range. And so, what we’re hearing from the retailers is optimism for the holiday season, which as you know, is our Super Bowl, our time to shine.”

On the high end of consumer spend, Richemont reported today and its stock is down 4.5% in Switzerland as jewelry sales were just below the estimate. From them:

“in the first half, group sales grew by 17% at constant exchange rates with broad based strength across business areas and regions. This included a remarkable 19% growth at the Jewelry Maisons, a robust double digit rise at specialist watchmakers, and a solid high single digit performance at the other business area, which includes fashion and accessories Maisons.”

“In addition, most regions posted double digit growth, led by Japan, the Americas, and Asia Pacific. Impacted by the ongoing conflict in the region, sales in the Middle East and Africa experienced a modest decline overall.”

NY Fed president John Williams is joining some of his colleagues in expressing the need for more rate hikes. “Inflation is far too high and it continues to be high even in the latest data. We’ll need to take actions over time that will ensure that we get inflation back to our 2% goal in a timely manner on a sustained basis…I feel that the data is speaking very clearly to us, the economy is strong, labor market continues to strengthen and inflation is persistent. We still have work to do in terms of getting monetary policy to the right place.”

I will be definitely wrong about the December rate increase, assuming the situation then holds vs today, but I still believe the pace of the AI CapEx and its influence on the stock market is going to be a big Fed topic next year and will limit the pace of 2027 hikes, because how can it not be?

BY Doug Kass · Nov 13, 2026, 11:20 AM EST

Programming Note

I have an annual eye exam at 11 a.m. ET this morning.

I will be back at noon.

Positions: None.

BY Doug Kass · Nov 13, 2026, 11:00 AM EST

Boockvar on the Producer Price Index

The following is from Peter Boockvar:

PPI stats, hot but we’ll take in line

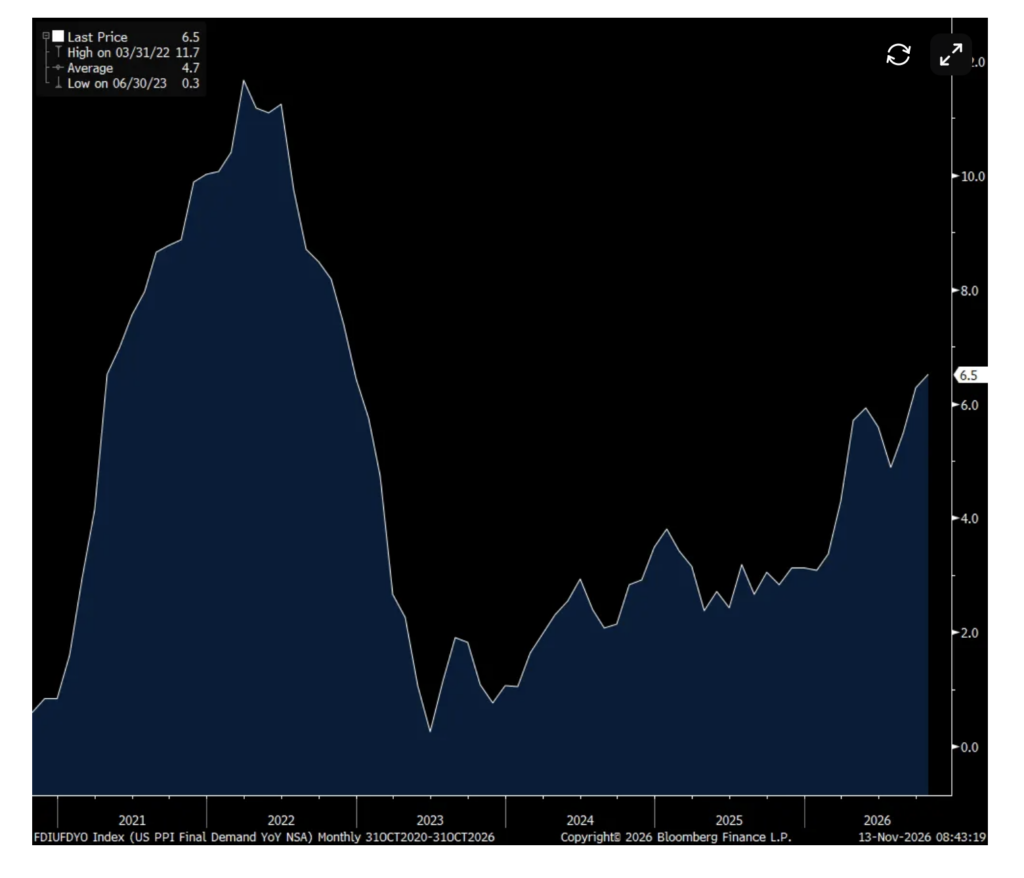
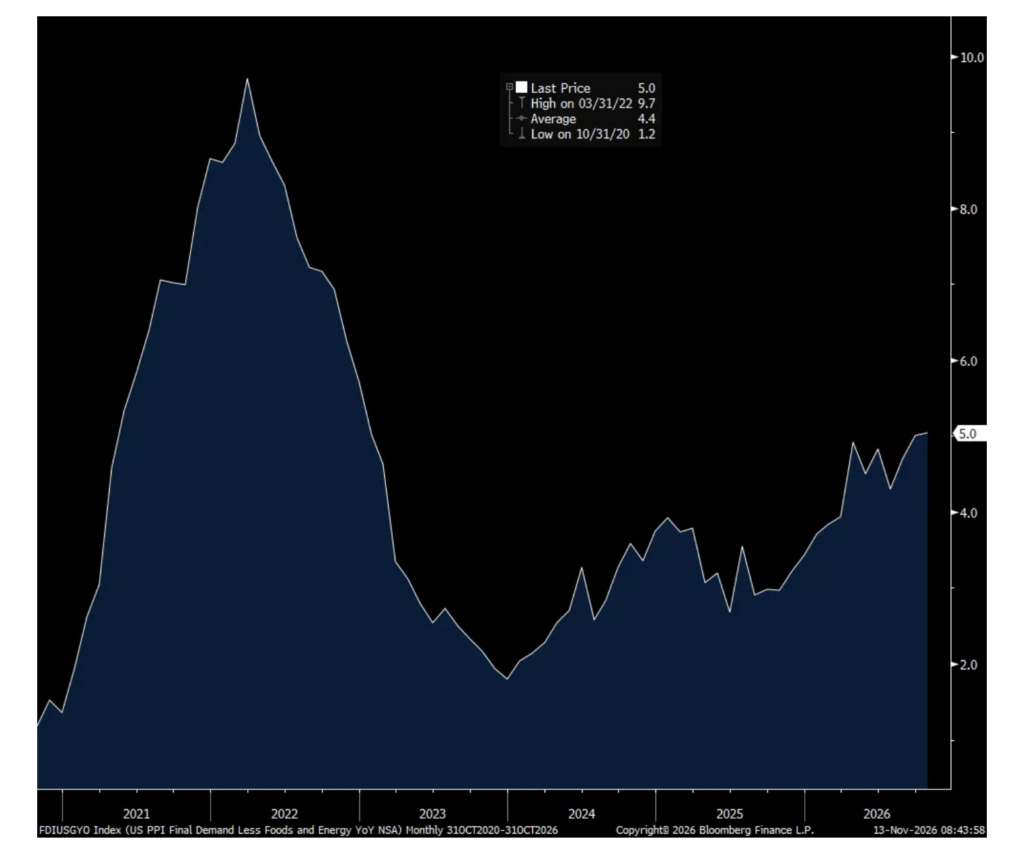
Including the revision to September, the October PPI stats were right in line with expectations with a .3% headline and core increase from 1.4% and .8% respectively in the month before. The y/o/y gains are 6.5% and 5%, running about 250 bps above consumer price inflation. After a 10% spike in September, energy prices were flat m/o/m, though up 37% y/o/y. Food prices were up another 1.3% m/o/m and by 1.7% y/o/y. We know energy prices have moderated since but core inflation still running hot.

Core goods prices (ex food/energy) rose .5% m/o/m and 5.2% y/o/y led by organic chemical pricing which jumped by 3.9%.

Service prices were up .2% m/o/m and 5% y/o/y with a big jump in ‘truck transportation of freight’, up 3.9% in the month, by 25% y/o/y and something I’ve been pointing out for a while now. Prices for ‘air transportation of freight’ were flat for a 2nd month but up 6.3% y/o/y. Prices were up too in ‘health/beauty/optical goods retailing along with ‘hospital outpatient care’ and ‘traveler accommodation services.’ Prices fell of note in margins for machinery/vehicle wholesaling, down 4.2% m/o/m and in ‘system software publishing’ and ‘airline passenger services’ (in contrast to what was seen in CPI).

While PPI is still running red hot, the Treasury market will take ‘in line with estimates’ and yields are down a few bps in response. Inflation breakevens are flat today, while up between 2-5 bps this week depending on maturity, though remaining benign highlighting again that most of the interest rate rise has been REAL. The TIPS market just doesn’t believe that the current inflation will last much longer and maybe due to a market that still wants to fade higher oil prices.

I’ll argue again, the complete inflation picture must include producer prices as only analyzing consumer prices in light of the robust wholesale price inflation is missing the margin squeeze some businesses are facing that don’t have pricing power.

Headline PPI y/o/y

Core PPI y/o/y

BY Doug Kass · Nov 13, 2026, 10:49 AM EST

Adding to GLD, TLT

Adding to GLD and TLT.

Positions: Long GLD M TLT M

BY Doug Kass · Nov 13, 2026, 10:47 AM EST

Long, but Low Conviction, GLD

I am now long (small) GLD at $355.75. (Low conviction)

Positions: Long GLD S

BY Doug Kass · Nov 13, 2026, 9:56 AM EST

Long Time, First Time

I purchased  a non trivial amount of TLT at $79.39.

Positions: Long TLT M

BY Doug Kass · Nov 13, 2026, 9:26 AM EST

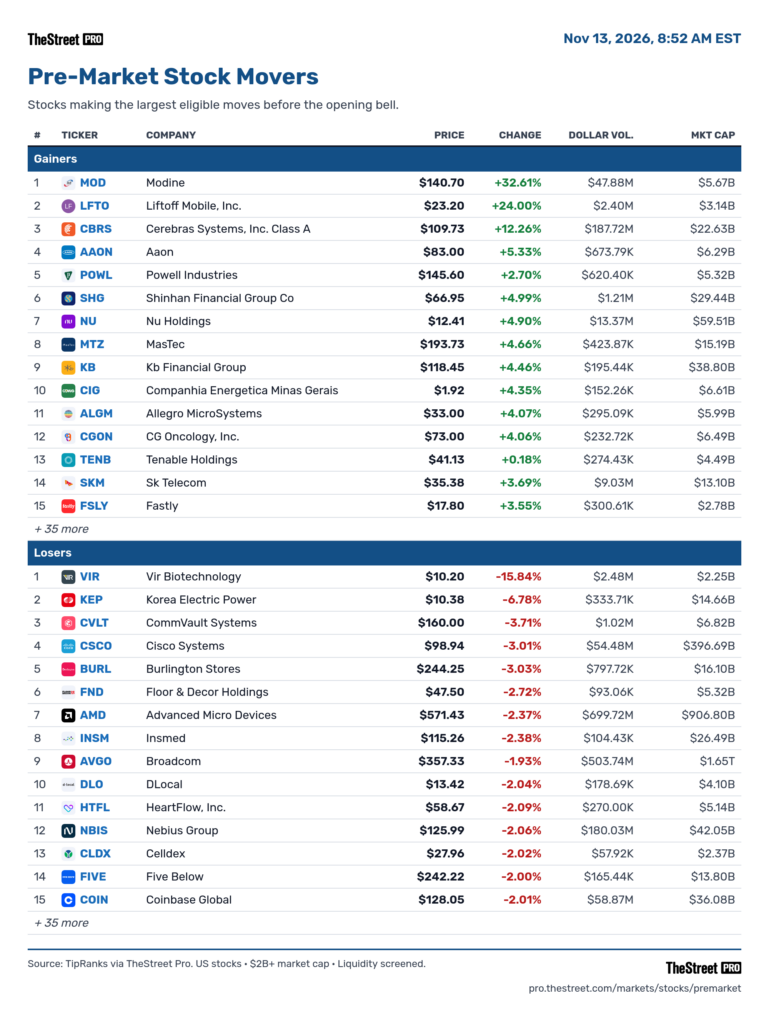
Modine Manufacturing Up; Virgin Galactic Down: Upside, Downside Movers in A.M.

Upside

– MRLN +40% (Q3 revenue rose 80% year over year, while new U.S. special-operations and autonomous-CASEVAC awards strengthened the defense pipeline)

– MOD +38% (Samsung reportedly in talks to acquire the data-center cooling supplier, with a potential deal possible within weeks)

– SLSN +32% (Q3 revenue grew 38% and the company swung to record net income)

– VTSI +31% (Q3 bookings jumped 87% sequentially, backlog reached $27.6M and a new CBP contract carries up to $14M of value)

– LFTO +27% (Q3 came well above prior guidance as revenue grew 32% and adjusted EBITDA margin expanded to 61%)

– NMAX +20% (record underlying revenue and a second consecutive quarter of positive adjusted EBITDA)

– HAWK +12% (revenue surged 84%, backlog reached $300M and FY revenue and EBITDA guidance was raised)

– CBRS +11% (Q3 beat, 2026 outlook raised and a new Microsoft partnership announced)

– SLS +5.8% (Q3 update says the Phase 3 REGAL AML primary-endpoint readout is due this month while Phase 2 SLS009 enrollment reached 40 patients)

– NU +4.7% (record profit, customer growth and improved efficiency outweighed a modest revenue miss)

– ENVX +3.0% (record gross margin, debt retirement and a 2027 revenue outlook implying 75%–128% growth)

– PANW +2.6% (KeyBanc upgrades to Overweight, citing accelerating security budgets through 2027)

– NVDA +1.6% (rebounds as investors reassess the leadership fallout and reports show growing support for Huang to return)

– TSLA +1.0% (reportedly advancing merger talks with SpaceX, with a potential deal targeted by December)

Downside

– NPCE -41% (Q3 revenue missed and FY revenue guidance was cut to $91M–$92M from $99.5M–$101.5M)

– CADL -32% (wider Q3 loss, prostate-cancer BLA timing pushed toward mid-2027 and a new $50M ATM programme)

– VIR -15% ($150M public offering priced at $10 per share)

– YSS -12% (Q3 sales missed and fell 7% as the adjusted EBITDA loss widened and a large goodwill impairment hit results)

– FLO -8.0% (Q3 missed on earnings and revenue and full-year guidance was lowered)

– SPCE -7.6% (new $250M ATM programme announced alongside the Q3 update)

– KEP -7.0% (Q3 operating profit fell 71% and missed consensus sharply as fuel and purchased-power costs surged)

– CSCO -3.4% (quarter beat and FY guidance rose, but sharp product-margin compression and elevated expectations drove a sell-the-news reversal)

– COIN -2.6%, MSTR -2.2%, IREN -1.2% (crypto-linked stocks fall as Bitcoin slides nearly 5%)

– AMD -2.4%, AVGO -2.1% (chip rivals give back part of Thursday’s Nvidia-succession rally as investors reassess durable market-share benefits)

– MSFT -1.2% (global Microsoft 365 outage continues to disrupt Outlook, Teams and Copilot)

BY Doug Kass · Nov 13, 2026, 9:21 AM EST

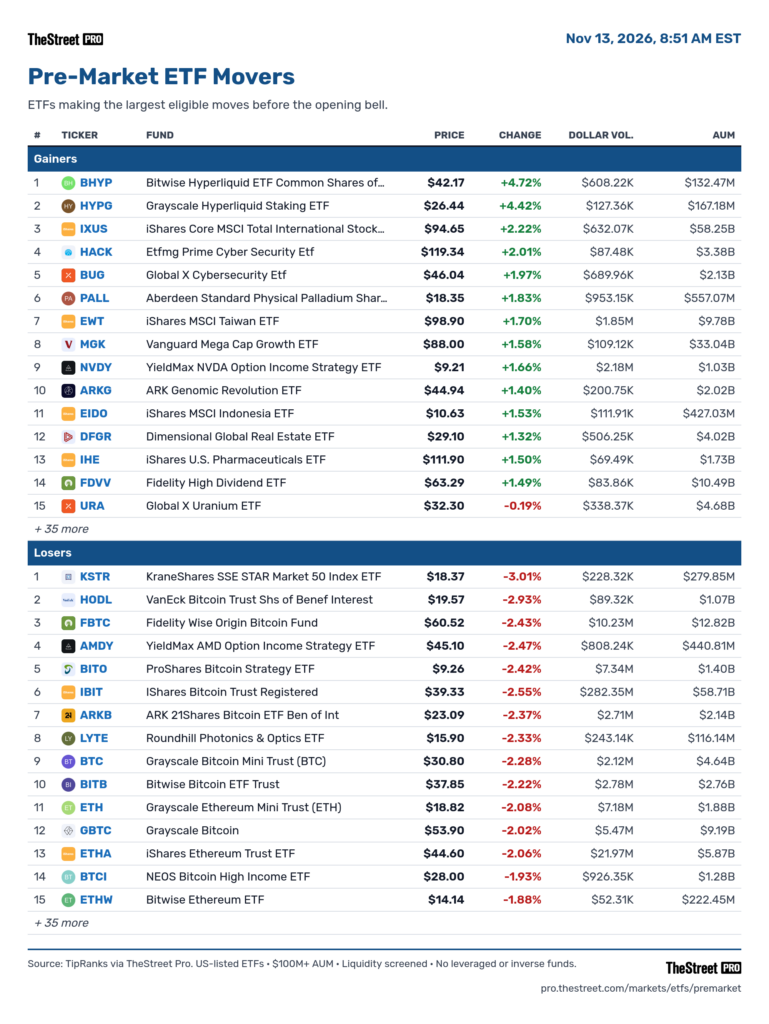
ETF Action in the A.M.

Source: https://pro.thestreet.com/markets/etfs/premarket

BY Doug Kass · Nov 13, 2026, 9:07 AM EST

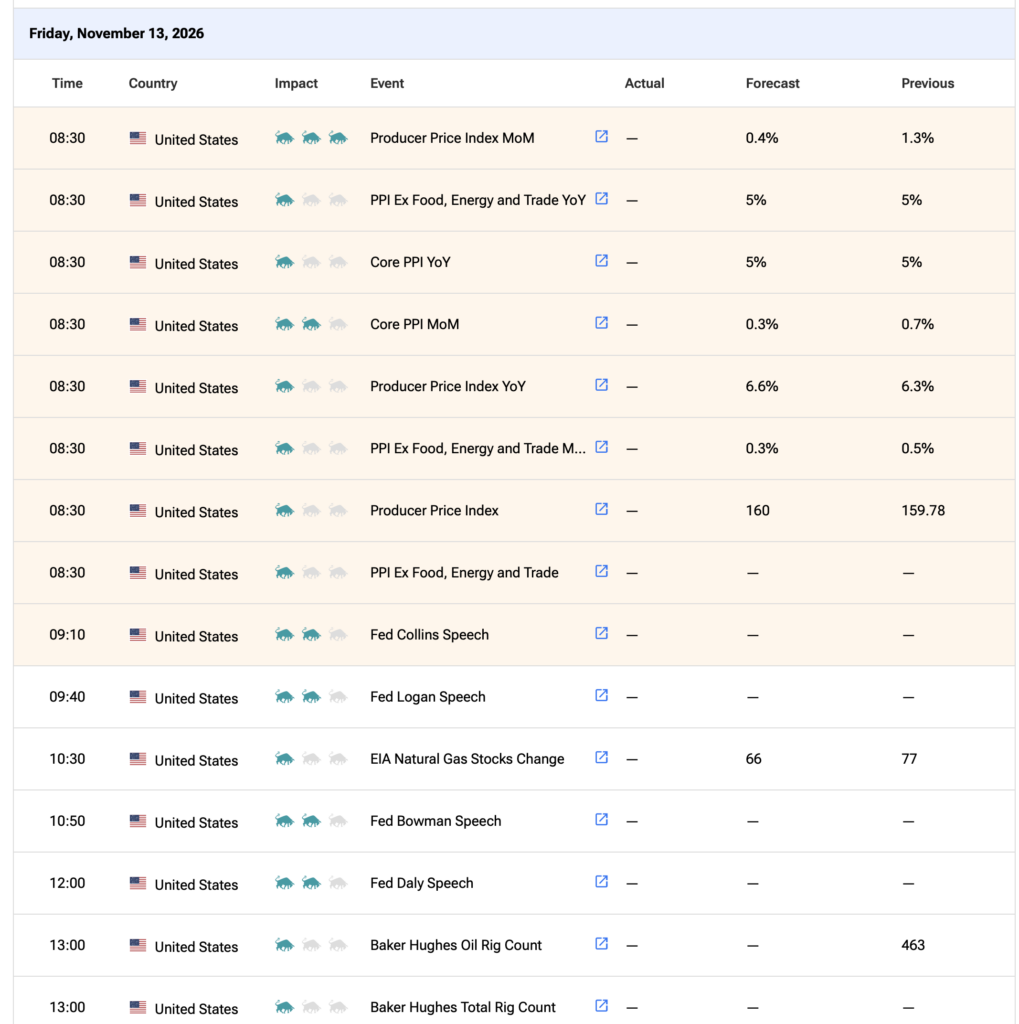
Economic Calendar for Today

Source: Tip Ranks

BY Doug Kass · Nov 13, 2026, 8:57 AM EST

A Repeated Refrain of Mine: Buy Financials

I continue to view financials/banks as a benefit of market rotation (possibly away from technology).

* Financials, on average, are about  25% off of their 52 week highs. 

* Valuations are now reasonable.

* Major money center banks and brokers have spent massive amounts on technology – a lot of which is already “sunken costs. This provides the “best in class” and largest banks (as first adopters to AI) to be differentiated against the broad universe of smaller sized banks (who will not be able to catch up and compete). 

* As I see it, the yield curve will be normalizing – benefiting net interest margins and income.

* The slowdown in AI spend (which I anticipate) should elongate the domestic economic cycle – improving the credit outlook and asset growth.  

* An improving equity augurs well for capital market activity.

* Finally, while the unrealized losses on their investment portfolio is underwater – the likelihood that interest rates may have peaked augurs well for that line item to appreciate in the time ahead. 

Positions: Long MS M GS S BAC M C M WFC S

BY Doug Kass · Nov 13, 2026, 8:50 AM EST

Fed Speakers Today

9:10 a.m.: Fed Bank of Boston President Collins (Non-Voter) gives opening remarks before the “Residential Realities: Understanding Challenges and Considering Solutions in the U.S. Housing Market” 70th Economic Conference hosted by the Federal Reserve Bank of Boston, Boston, MA (Embargoed text available. No Q&A. Livestream at https://www.youtube.com/@BostonFed/streams; and at 

10:35 a.m.: Fed Bank of Boston President Collins (Non-Voter)  participates in live interview with Bloomberg Television; 

9:40 a.m.: Fed Bank of Dallas President Logan (Voter) gives opening remarks before the Bank Funding Conference 2026: “Bank Funding in the Age of Instant Finance” at the Federal Reserve Bank of Dallas, Dallas, TX (Text and livestream available. No audience Q&A); 

10:50 a.m.: Fed Vice Chair for Supervision Bowman (Voter) participates virtually in “Supervision and Regulation” discussion before the Connecticut Bankers Association Annual Meeting and Conference 2026, Washington, DC ( No text. Q&A from moderator and audience. Livestream available, details forthcoming); 

12:00 p.m.: Fed Bank of San Francisco President Mary Daly (Non-Voter) participates in moderated discussion before the University of Nevada, Las Vegas Center for Business and Economic Research (CBER) Forecast event, Las Vegas, NV (No prepared remarks. Livestream and in-person attendance details forthcoming. No group media interview); 

7:00 p.m.: Fed Vice Chair Jefferson (Voter) speaks on “New Technology, Old Questions: Assessing Productivity Puzzles and Their Implications for Macroeconomic Activity” before the University of California San Diego Economics Roundtable. (Text available. Audience Q&A expected); 

https://www.cfasociety.org/sandiego/events/eventdescription?CalendarEventKey=02350250-0739-478a-a213-01a0c45bdea0&CommunityKey=4307dcbb-c44e-4e8d-888a-0185e47c07a0&Home=%2Fcommunities%2Fcommunity-home%2Fmanage-events

BY Doug Kass · Nov 13, 2026, 8:39 AM EST

Are Tech Stocks ‘Cheap’ or ‘Value Traps?’

Positions: None

BY Doug Kass · Nov 13, 2026, 8:32 AM EST

More Tales From Nvidia: There Is Always More Than One Cockroach (Issue #281)

Positions: None.

BY Doug Kass · Nov 13, 2026, 8:19 AM EST

A Few Tweets and Pearls of Wisdom From Ed Zitron

Position: None

BY Doug Kass · Nov 13, 2026, 7:50 AM EST

Oscillator Shifts to Oversold

The S&P Short Range Oscillator shifted to an oversold at -1.26% vs. 1.03%.

I have no index positions.

Position: None

BY Doug Kass · Nov 13, 2026, 7:15 AM EST

More Tales From Nvidia: The National Security Issue (Issue #280!)

* It’s been a good week for China hawks

* As the plot thickens…

I have now written 280 columns on Nvidia (NVDA) (in my “More Tales” series) covering a broad list of concerns including Nvidia’s aggressive revenue/profit recognition, roundtripping, double/triple ordering, circular financing, the efficacy of AI (and contribution to society), whether the AI capital spending spree would yield an adequate return on the invested capital (and net productivity gains), deals with China, etc.

I even coined the phrase Central Bank of Nvidia (now routinely used by CNBC but without attribution!), which described the wide-ranging global influence of the company and of Jensen Huang.

The Most Powerful Banker in the World? The Central Bank of Nvidia

The newest allegation that Jensen Huang has been having an extended affair with a Chinese spy raises the ante as it could be a national security issue.

With a change in Washington leadership, scrutiny of Huang’s multi-dimensional relationships to others (including President Trump’s inner circle and leadership) will likely commence. There will be numerous questions about the Jensen Huang situation and the Administration’s oversight and protocol — including but not restricted to:

* It is believed that Secretary of State Marco Rubio knew about the relationship for over a year.

*  Was President Trump informed of the relationship?

*  Despite the supposed existential war between China and the U.S. regarding the AI race, after knowledge of the affair with a possible Chinese spy why was Jensen Huang invited on a state visit to China — on Air Force 1?

*  Why did Commerce Secretary Lutnick ignore the relationship and look the other way?

*  Was there a coverup and, if so, why — and did anyone benefit?

*  Was the breakdown in our government’s reporting of the relationship willful and intentional?

*  According to AI and industry reports Jensen’s Huang’s paramour worked at Megaspeed, a Singapore-based company that is an empty storefront with only 2-10 employees. 

It seems to me that as soon as Secretary Rubio got the information and had reason to believe she was a spy, President Trump, the Congress, the Intelligence Committee and others (including Jensen Huang) should have been informed. Who knew and when?

Did Secretary Rubio (who apparently has his eyes on the Republican Presidential nomination) sit on the information? If he did, why? 

This week, President Trump has said he knew nothing about the spy. When did he find out and more importantly, what did he do with the information? 

Did the president just want to hang out with Huang or did anyone in Trump’s sphere benefit from Nvidia and the company’s relationship to China? (There is precedent).

Position: None

BY Doug Kass · Nov 13, 2026, 7:00 AM EST

More Tales From Nvidia: Was the Microsoft Outage an AI Failure? (Issue #279!)

This is interesting re the Microsoft outage, which is massive and unprecedented:

At first I thought it might be an AI hack. But maybe not, maybe it is an AI failure. Ergo the fault of garbage code written by AI. If I remember correctly, Amazon AWS had several outages that were likely caused by poorly written AI code as well. That was not the only incident. I believe there have been several, although nothing even close to this in scale.

At any rate, this seems to be more than coincidence. This outage is so bad, and so prolonged, it is most likely a function of what has changed, which is generative AI writing code, which does not work nearly as well as has been portrayed. Something tells me you will soon be able to add Microsoft (MSFT) to the list of companies that starts hiring back the people they fired due to AI, and using less AI at the same time. 

Hello Anthropic and Open AI!

Post Script

Side note, this Nvidia (NVDA) Jensen Huang thing is not primarily about sex, although that was what did him in. He was most likely illegally sending stuff to China in an indirect fashion, and misrepresenting what was going on. The notion that this whole thing is a setup by China is quite misguided. He was the guy that was sending them the parts, when he wasn’t supposed to be doing so. Now China is going to get cut off completely, so this whole thing was most certainly not an operation by China to get him out of there. He was helping those guys out.

It is also amazing how venal people have become. Due to their interest in their stock portfolios, many were willing to look right past this, and offer support to the guy who was likely selling the country out and lying to everyone at the same time, to further his own self interest, whatever that exactly is.  IMHO he is far from a national hero, and if anything, he is the exact opposite and should be a complete and total pariah.

Position: None

BY Doug Kass · Nov 13, 2026, 6:13 AM EST