January Bounce Candidates in Financials
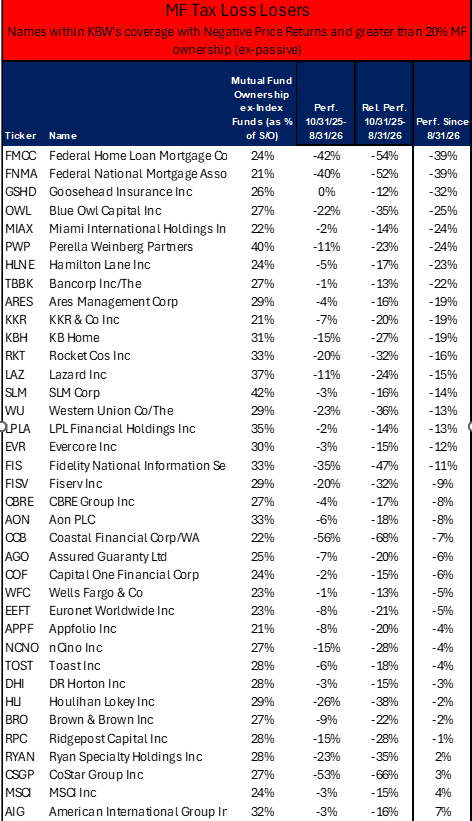
Here is a good menu for possible January bounces in the financial sector (after tax selling over the next two months):
Position: None
BY Doug Kass · Oct 21, 2026, 2:25 PM EDT
 Doug KassDoug Kass
Here is a good menu for possible January bounces in the financial sector (after tax selling over the next two months):
Position: None
BY Doug Kass · Oct 21, 2026, 2:25 PM EDT
Staples (consumer non-durables) are getting hit over the last few hours.
A reminder, I am down to VS on KMB, PG and KO.
I sold out my entire PEP holdings.
I would be a buyer of the space on weakness — but not at current prices.
Position: Long KMB (VS), PG (VS), KO (VS)
BY Doug Kass · Oct 21, 2026, 2:15 PM EDT
Here is the WSJ’s review of Apple’s iPhone Duo.
iPhone Duo Review: Apple’s $1,999 Pocket-Friendly Folding Tablet Is…a Lot – WSJ
Position: None
BY Doug Kass · Oct 21, 2026, 2:06 PM EDT
At $773.55, I moved to medium-sized short SPY.
Position: Short SPY (M)
BY Doug Kass · Oct 21, 2026, 1:11 PM EDT
Position: None
BY Doug Kass · Oct 21, 2026, 12:45 PM EDT
Dougie Kass
I couldn’t disagree more with Joe Terranova on Halftime now (I am not posting on Twitter!).
Though I am not high on large cap tech my disagreement is not that I don’t think AI related stocks will begin to outperform.
It is the degree of confidence/hubris that he is expressing in his view that the AI momentum trade will resume.
Position: None
BY Doug Kass · Oct 21, 2026, 12:25 PM EDT
I have a business luncheon — out from noon to about 1:30 PM
Position: None
BY Doug Kass · Oct 21, 2026, 12:10 PM EDT
Positions: None
BY Doug Kass · Oct 21, 2026, 12:00 PM EDT
A great MRKT Call today with Dan and Carter.
Lets go to the tape.
MRKT Call – Wednesday, October 21st
Position: None
BY Doug Kass · Oct 21, 2026, 11:47 AM EDT
I wanted to make one more point on the circularity, which continues to fly under the radar.
The revenue quality issue.
See tweet below:
The circular financing goes well beyond Nvidia (NVDA) and others funding their customers. It is also the Venture Capital firms who are financing the consumers of the compute, in the hopes that another greater fool takes them out at a higher valuation.
These companies that the VCs are financing are consuming the bulk of compute, NOT corporate America, which actually has a balance sheet and sustainable businesses of their own volition. There is no shortage of data coming out that corporate America is finding little utility from AI. In fact the data shows the opposite and it is becoming more clear that AI is just a cost.
At the end of day, AI is really all sort of an inter-linked Ponzi scheme and money recycling operation, underpinned by public market valuations that I believe have been goosed by Nvidia. The demand for compute is coming from businesses that really should not, and do not need to exist, and are just being financed by VCs that effectively are funneling money to compute infrastructure, in the hopes that valuations remain high and a greater fool takes them out of their investment.
But most will go the way of Character AI – with $2.7 billion in market capitalization to near zero… in a heartbeat.
Position: None
BY Doug Kass · Oct 21, 2026, 11:30 AM EDT
I just added to my SPY short at $771.48.
I am a scale seller on more strength.
Position: Short SPY (S)
BY Doug Kass · Oct 21, 2026, 11:22 AM EDT
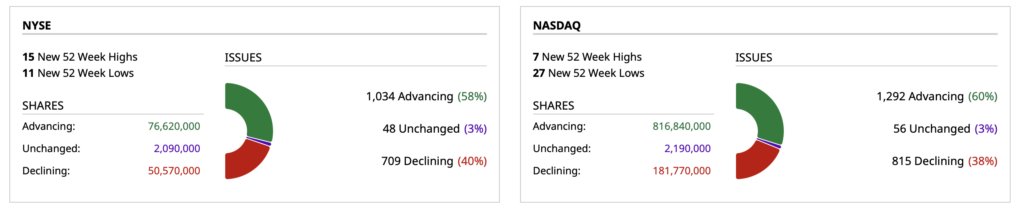
SOURCE: Barchart
SOURCE: Barchart
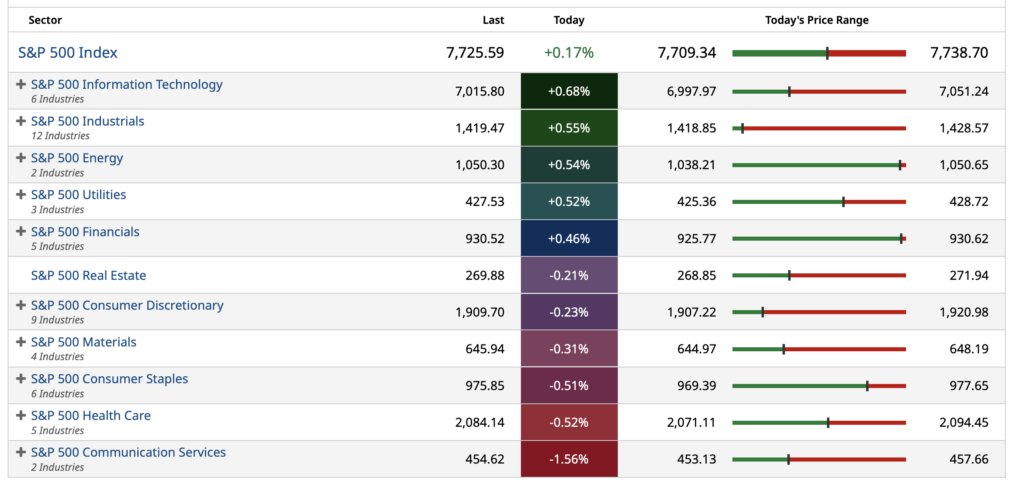
SOURCE: TheStreet Pro
SOURCE TheFly
BY Doug Kass · Oct 21, 2026, 11:00 AM EDT
The following is from Peter Boockvar:
I never heard of them either/Other notable stuff
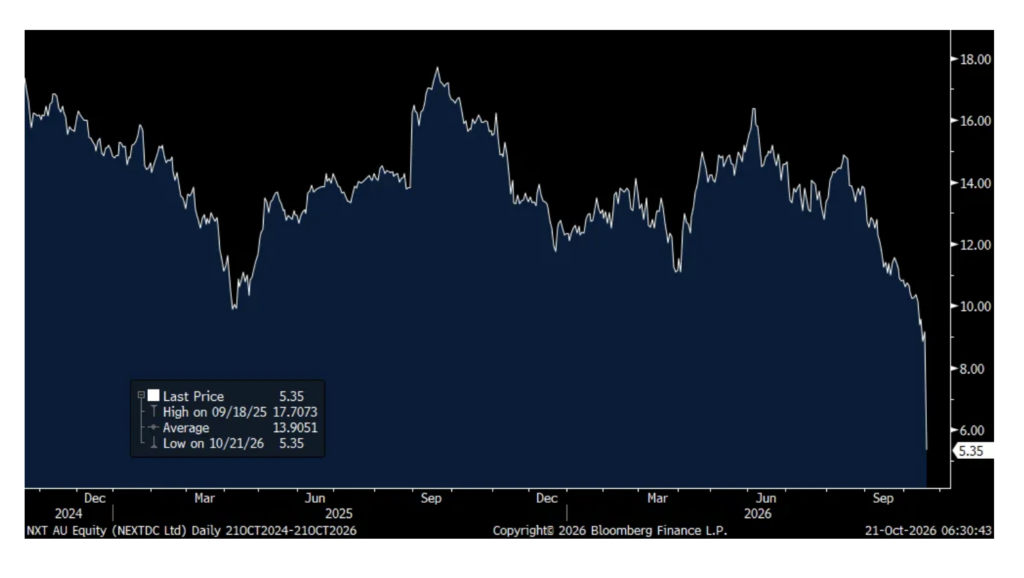
Every hear of NEXTDC Ltd based in Brisbane, Australia? I didn’t until today but it develops data centers and its stock plunged by 42% overnight. They preannounced negatively and said this on their call as for why. “The main reason is M3 Melbourne. The timing of power to that site is no longer certain and I’ll explain why…Jemena in Victoria is the distributor that supplies power to M3. Jemena suspended parts of network works that deliver the next step up in grid supply to the site. Jemena has attributed the suspension to community and stakeholder opposition to the works. And to the local council not giving its consent until more community consultation takes place on the program for installation of poles and wires. Jemena told us formally they don’t expect to restart before February next year.”
M3 Melbourne is defined by the company as a “225MW Tier IV certified data center engineered as a new digital gateway for Victoria…Purpose built for hyperscale growth and high-density compute, M3 Melbourne spans more than 41,000 m2 of technical space.”
I guess the bottom line here, along with the Firmus and AirTrunk IPO postponements, the Coreweave financial concerns, the disastrous Elice IPO and Volta, the UK data center company having to raise money recently at 11%, is that on one hand if there are less data centers that end up being built, less stuff that goes in them gets ordered. On the other hand, the ones that do get built maybe will be able to maintain some pricing power for longer on leasing out GPUs because at the end of the day, the price of technology products and services typically goes down and that will eventually be the case for the lease prices of GPUs. I don’t know when but they will if history is any guide.
NEXTDC
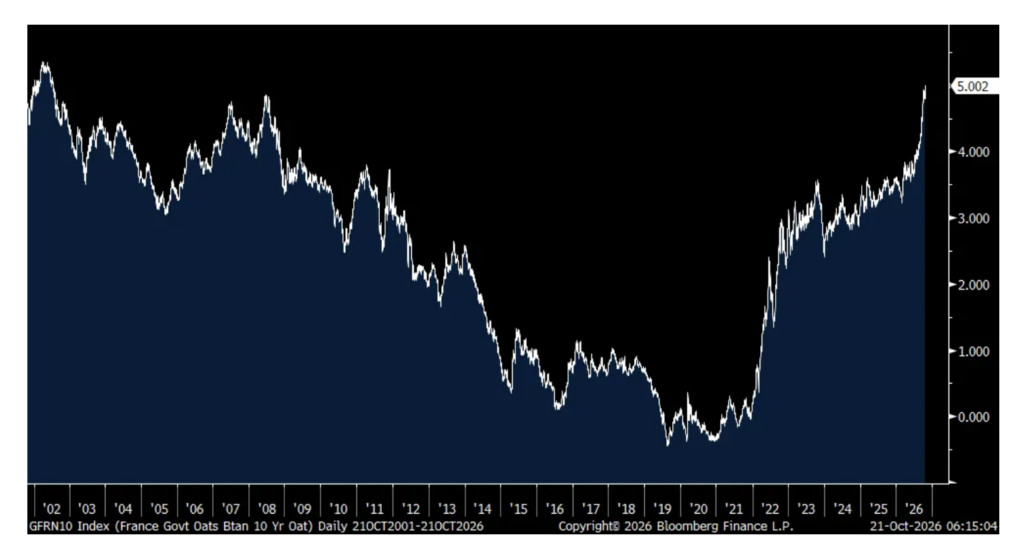
The French 10 yr bond yield is touching 5% for the first time since July 2002. I know everyone has their view on why rates are rising globally and I continue to say ‘all of the above.’ French yields are not rising because of robust growth, but because debts and deficits matter. What also matters is the behavior of foreigners in their market as they own about 50% of the French oat market and the Japanese in particular own about 7%. Japanese JGB yields, when including the cost of FX hedging, are looking more and more attractive to Japanese domestic investors and money is coming home.
French 10 yr Yield
Staying with the Japanese, they reported September export growth of 16.7% y/o/y but while solid it was below the estimate of 21.3%. Of course, the shipments of semiconductors and chip equipment led the way, higher by more than 40% for each. Auto exports were up by 15%. Exports to the US rose 23%, to the EU by 10.5% and to China by almost 9%. Imports were higher by 19%, just under what was forecasted.
Nothing market moving on this data though.
Yesterday we saw that in the UK, weekly earnings ex bonus rose 3.7% y/o/y in August. Today, September CPI in the UK is out and it rose 3.5% y/o/y with a core rate of 2.8%. Essentially running to stand still financially.
With respect to wholesale prices, PPI input prices were up by 8.3% y/o/y and output charges were higher by 4.6%. Quite the margin squeeze and another country that is seeing PPI well above CPI and I’ll say for the umpteenth time, one must look at both CPI and PPI in order to have a full picture on inflation.
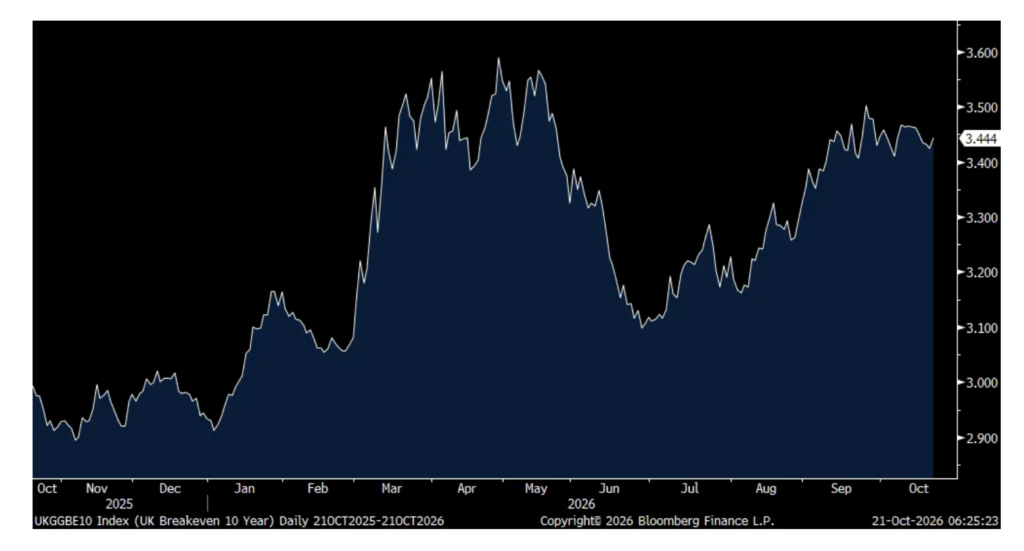
As the data was about in line, gilt yields are little changed and the 10 yr UK inflation breakeven is higher by 2 bps to 3.44% but remaining in a 3.4-3.5% range it’s been in over the past month.
UK Inflation Breakeven
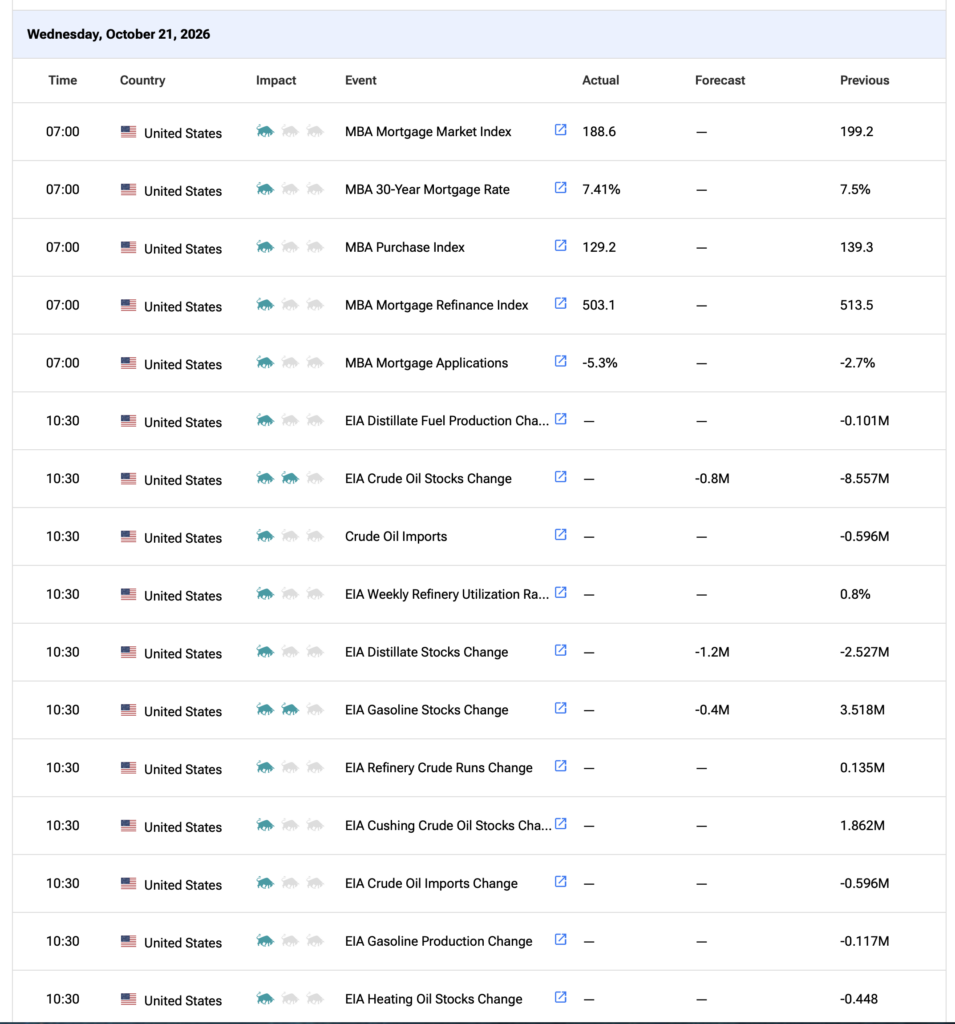
In the US, the rise in interest rates is impacting commercial construction. The September Architecture Billings Index weakened to 44.7 from 47.2 with 50 being the breakeven. Commercial/industrial (which includes data centers) is the only category remaining above 50 while the other three, including multifamily, is below. The AIA said “This is an increasingly difficult environment for architecture firms. Weakening billings are being compounded by a soft economy, challenging project financing and growing caution among clients. With fewer projects moving forward, there is little reason to expect a meaningful improvement in business conditions in the near term.”
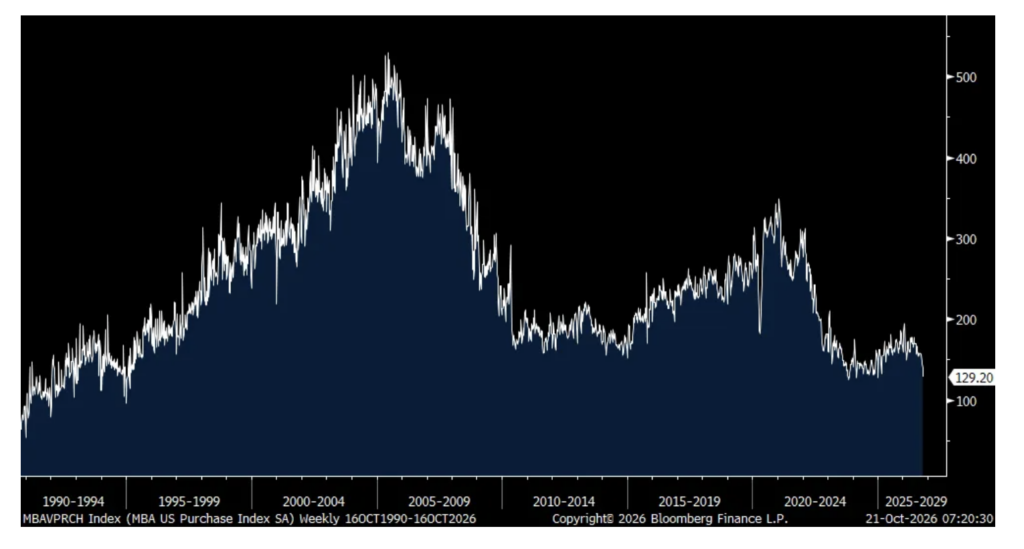
Higher mortgage rates continues to freeze the housing market. While the average rate of 7.41% was down 9 bps, the elevated level resulted in a 7.3% w/o/w drop in purchase applications and down 18% y/o/y. They now sit at the lowest since January 2025. Refi’s dropped for a 6th week, by 2% w/o/w and by 59% y/o/y.
Purchase Applications
To some earnings calls of note:
From MMM, up 6% yesterday:
“We continue to see strong momentum in general industrial and safety, with second half growth accelerating to high single digits, above our prior expectations. In electronics, we’re seeing increasing strength in semiconductors and data centers, which is partially offsetting a weaker consumer electronics market, especially in LCD displays. Auto OE and aftermarket are trending in line with prior expectations, with a modest improvement from down low single digits in the first half to about flat in the second, and with auto OE a bit softer and aftermarket a bit better.” Aerospace is doing well too.
And, “The consumer business, which contributes about 20% of sales, improved sequentially to about flat in the second half as modest improvement in consumer POS spending is partially offset by channel inventory adjustments at a few specific retailers.”
From GM, down 7% yesterday because of higher costs:
Revenue was up 3% y/o/y. “As this quarter’s results and our revised guidance show, our business is performing well, even with a major launch underway and the inflationary pressures we’re experiencing in areas like logistics, commodities and memory.”
They sold 670,000 vehicles in the quarter, of which 645,000 were internal combustion engine. They are still losing money on their EV business with not enough hybrid models out. And, “turning to our international operations, we expect continued ongoing softness in GM International, reflecting headwinds from the dynamic environment in the Middle East.”
“The US market remains resilient. We expect total SAR to be in the mid 16 million unit range for the full year, which implies approximately 16 million for the rest of the year, consistent with what we are seeing in October.” Perspective though, in 2019 we were seeing annualized vehicle sales of over 17mm.
Staying with the car business, from Ally Financial, up 1% yesterday:
Auto loan originations rose 10% y/o/y and “consumers have continued to demonstrate resilience as they navigate an evolving macro backdrop, and we remain encouraged by the performance we’re seeing across the portfolio.”
“Consolidated net charge-offs of 117 bps were up 6 bps sequentially due to seasonality and were roughly flat y/o/y.”
“Our coverage levels continue to balance stable credit trends across our portfolios against broader macroeconomic uncertainty. Consumers have continued to demonstrate resilience, but we monitor several factors, including persistent inflation, affordability pressures, elevated oil prices, and lower personal savings rates. It is important to note that our underwriting approach is not static.”
Of note, “While the portfolio is performing largely in line with our expectations, our late 2025 and early 2026 vintages are showing higher early life delinquency, which are being closely monitored.” I bolded to highlight.
From Capital One and whose stock is rising pre-market:
They lowered their reserves for bad debt by releasing $250 million of allowance in their domestic card business. “The allowance release was driven by continued favorable observed credit in the quarter, partially offset by greater consideration to downside economic scenarios related to geopolitical risks.”
Net charge-offs fell and “are benefiting from the steady improvement in delinquencies that we observed in the first half of this year and from strong recoveries’ performance.”
BY Doug Kass · Oct 21, 2026, 10:14 AM EDT
I added to my SPY short on the early strength.
Position: Short SPY S
BY Doug Kass · Oct 21, 2026, 9:58 AM EDT
Is Nvidia (NVDA) now the central bank and lender of last resort? Is the Federal Reserve’s Kevin Warsh the boss, or is it now Nvidia’s Jensen Huang?
Who really is the most powerful banker in the world right now?
Who has more impact on rates and the economy?
See the link below:
https://www.tipranks.com/news/nvidia-may-be-helping-finance-oracles-ai-data-centers-td-cowen-says
It does not stop. Now Nvidia needs to finance and backstop Oracle (ORCL) along with everything else?
The Nvidia balance sheet soon may be bigger than the Fed’s at the rate the company is financing the economy to dig holes and fill them back up, so Nvidia can recognize revenue. The balance sheet and cash flow statement tell a very different story than earnings do. Amazing GAAP allows for this.
Then I still wonder: Does this industry have any chance of working? It still seems at the frontier lab-level, which underpins everything, the more numbers that come out, the less it makes sense. It seems this business does not and cannot scale. With every dollar of additional revenue, even at this size, comes more than an additional dollar of expense. As noted in “More Tales” this morning, Anthropic ex the accounting charge still lost $8.7 billion on $16 billion of revenue in the first six months of 2026.
Sixteen billion dollars is a lot of revenue and Anthropic still lost 50 cents on every dollar. This is why the company resorts to trying to report earnings before expenses. They have $518 billion of commitments over the next decade.
Do they have a bat phone connected to the Central Bank of Nvidia?
Positions: None.
BY Doug Kass · Oct 21, 2026, 9:41 AM EDT
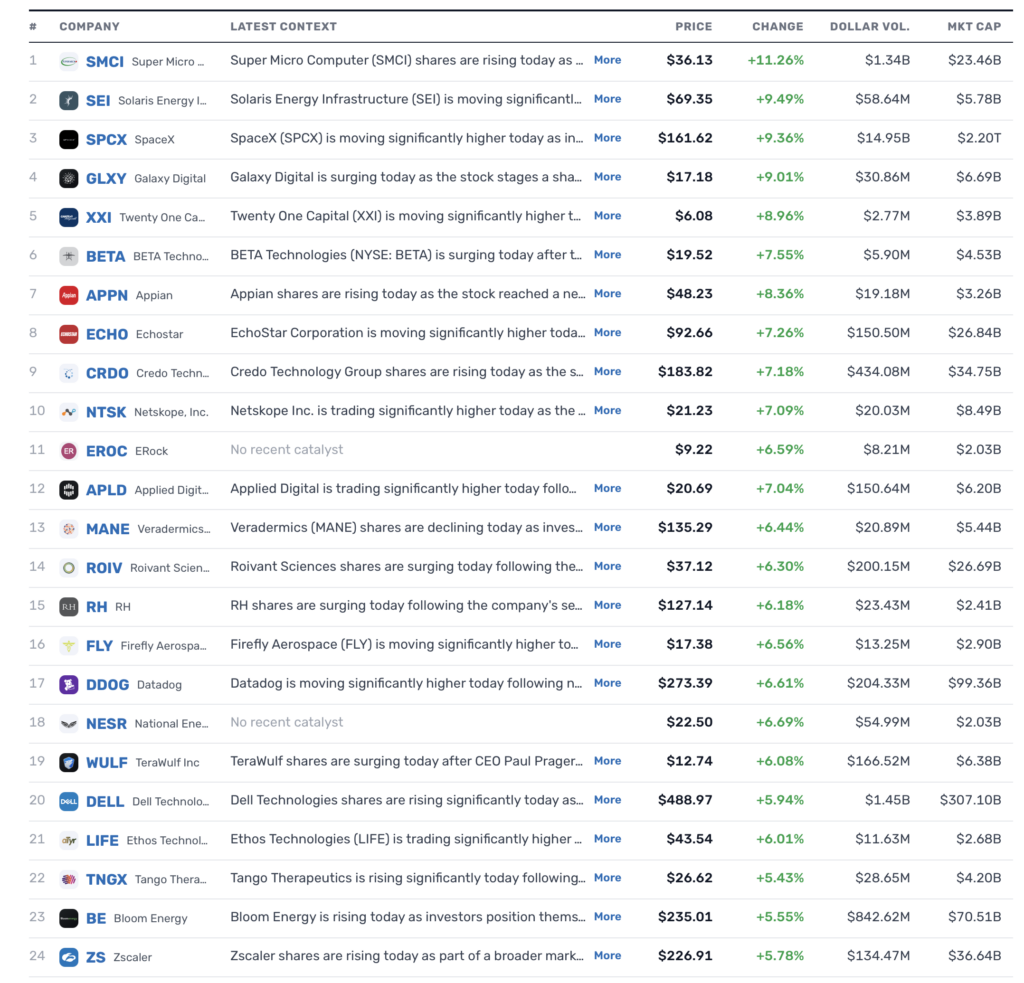
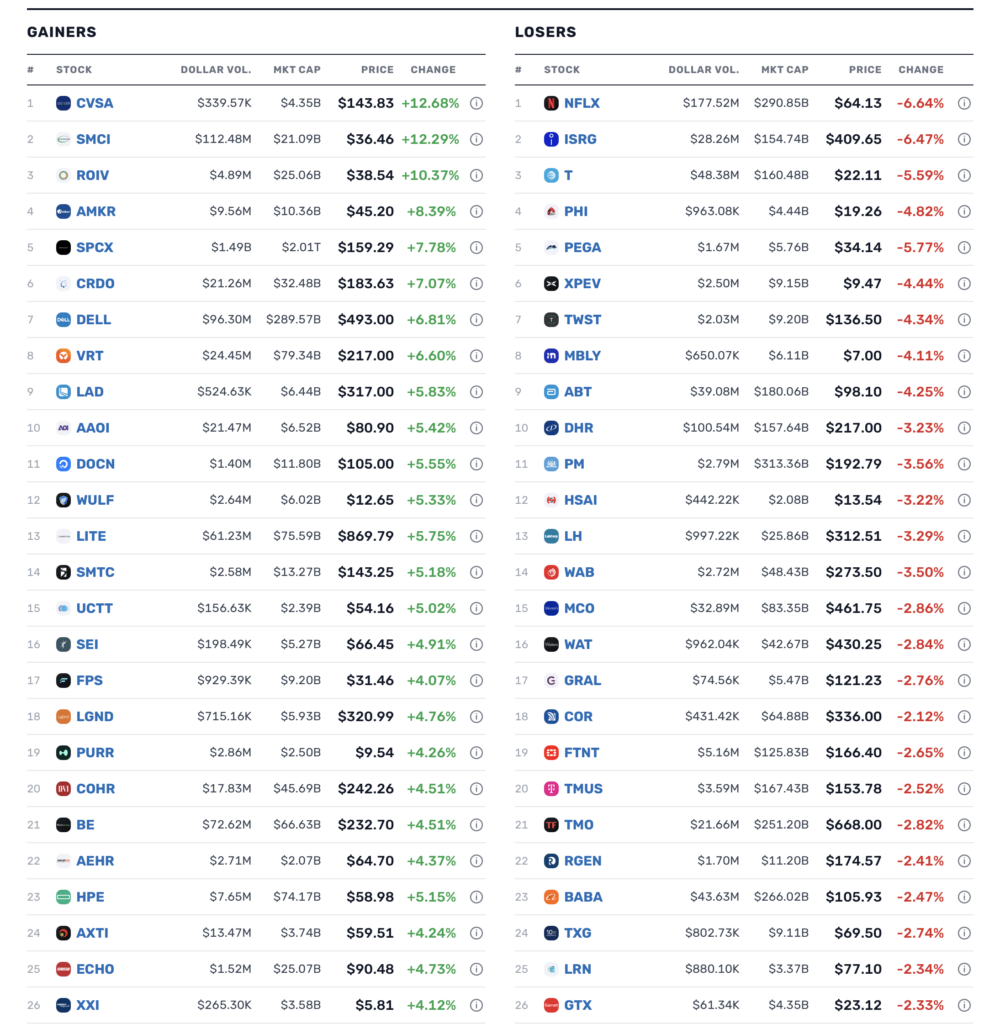
– SMCI +12% (preliminary fiscal Q1 revenue outlook was raised well above expectations, with gross-margin upside)
– SPCX +8.2% (Q3 revenue and profit crushed expectations, marking its first quarterly profit since the IPO, while special committees evaluate a potential TSLA merger)
– CRDO +7.2%, VRT +6.7%, DELL +6.9%, LITE +5.6%, HPE +5.0%, COHR +4.6% (AI-infrastructure suppliers rise as the SMCI outlook and SPCX AI-compute results reinforce data-center demand)
– WDC +4.0%, SKHY +3.7%, SNDK +3.7%, STX +3.6%, MU +3.1% (memory and storage names gain on the stronger AI-infrastructure demand read-through)
– APLD +4.0% (Texas AI data-center agreement and bullish analyst action)
– INTC +2.3%, AMD +2.1%, NVDA +2.0% (chip stocks rise as strong AI-compute and server demand updates lift the broader complex)
– TSLA +1.4% (special committee formed with SPCX to evaluate a potential merger ahead of earnings)
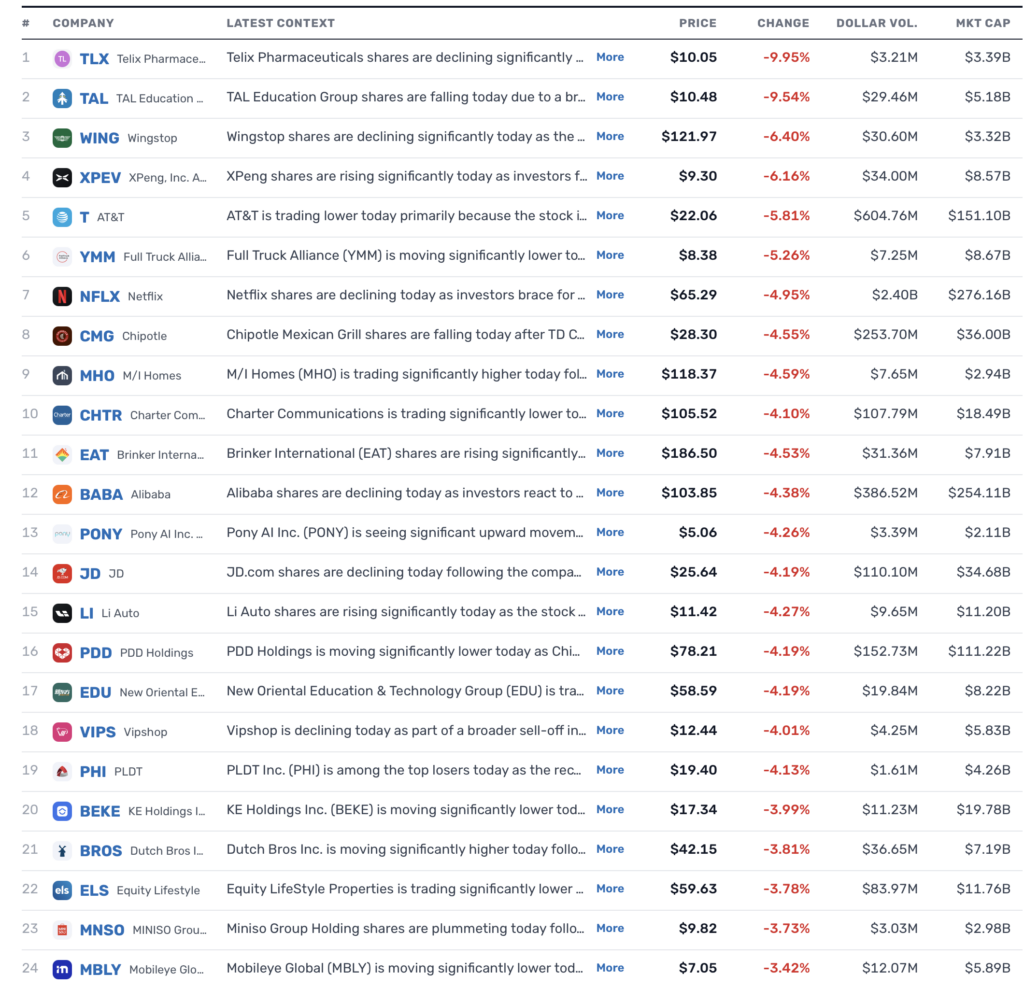
– TKNO -30% ($40M primary offering priced at $5 per share, a steep discount to the prior close)
– NFLX -7.0% (Q3 profit beat, but the Q4 sales outlook missed and the 2026 advertising-revenue forecast was cut to $2.7B from $3B)
– ISRG -6.7% (Q3 beat, but U.S. procedure growth slowed, instrument pricing reductions were outlined and the high end of the procedure-growth outlook was cut)
– T -5.6% (Q3 beat and FY EPS guidance was raised, but postpaid phone additions missed expectations amid satellite-competition concerns)
– DHR -3.6% (Q3 beat and FY EPS guidance was raised, but the Q4 core-growth outlook remained modest with a respiratory-revenue headwind)
– TMO -3.0% (sell-the-news reaction after a Q3 beat and raised FY guidance)
– ACN -1.5% (Baird downgrades to Neutral from Outperform on valuation and slower organic growth)
BY Doug Kass · Oct 21, 2026, 9:02 AM EDT
BY Doug Kass · Oct 21, 2026, 8:35 AM EDT
Source: TipRanks
BY Doug Kass · Oct 21, 2026, 8:25 AM EDT
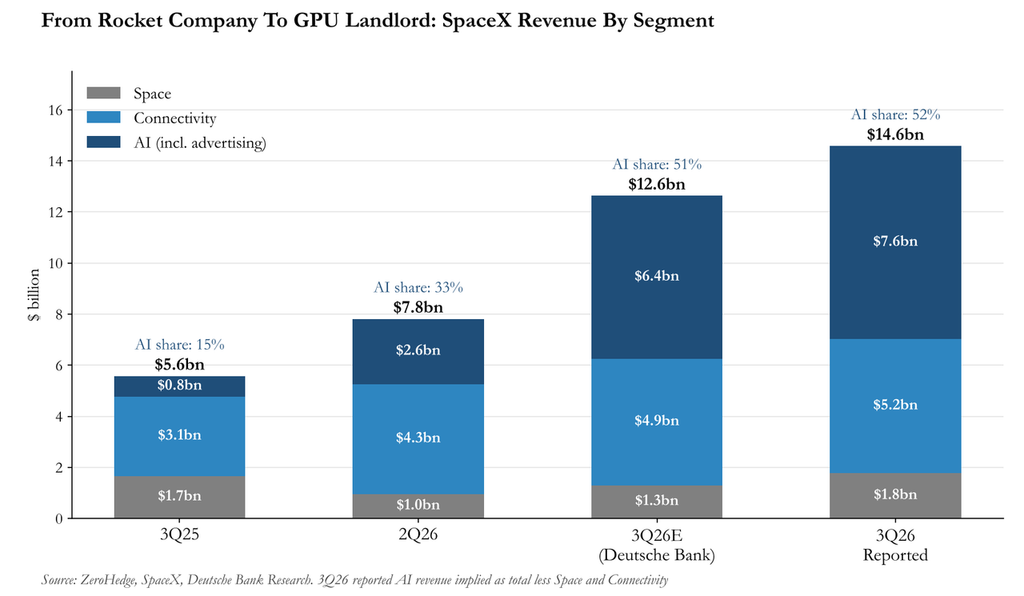
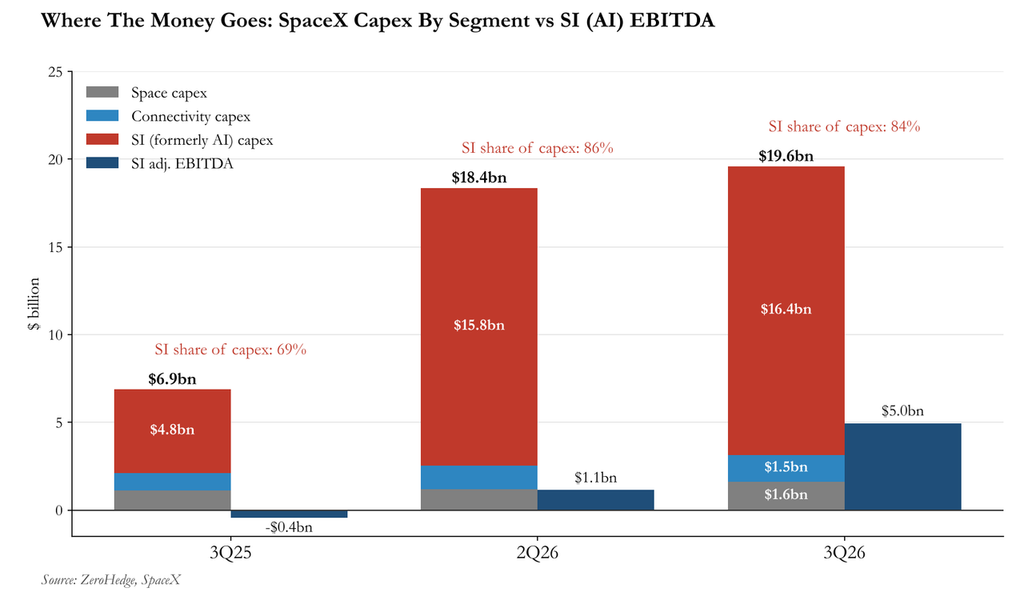
Below are two charts that speak volumes about the economics of AI.
SpaceX (SPCX) just reported 3Q2026.
All of a sudden, AI (ergo data centers) is their biggest business. Along with that, cash and cash equivalents came in at $51.29 billion, versus an estimate of $91.2 billion. CAPEX for their AI segment was $16.4 billion versus $5 billion of EBITDA. Is this compelling?
I guess they can buy all the revenue they want; good thing the cost of financing it is so low??? Feels like double dilution is on the come here. Continued issuance to do whatever they are doing chasing WeWork landlord revenue, and dilution to potentially acquire Tesla (TSLA), which is becoming more and more apparent.
Clearly Elon Musk wants to goose SPCX stock where he has much more of his net worth (~70%) to acquire TSLA (~25%) to hide it, on more favorable terms for SPCX (ergo himself).
This is the same trick Musk used when Tesla acquired Solar City. Hide the biz that can’t meet its promises, then to the next B.S. story.
Boy did that thing burn cash, holy heck, never seen a whiff this bad. Good thing borrowing costs are low these days. Oopsie:
In any case, at the rate AI is burning cash (and sucking down credit and equity), the 10-year Treasury will be yielding 6% in no time!
Position: None
BY Doug Kass · Oct 21, 2026, 7:45 AM EDT
Position: None
BY Doug Kass · Oct 21, 2026, 7:15 AM EDT
Despite the protestations from the value cabal, I have been cautious on financials/banks all year:
Position: None
BY Doug Kass · Oct 21, 2026, 7:00 AM EDT
Fan fave Netflix (NFLX) materially reduced forward guidance after the close of trading — and its shares are trading -$4 (or -6%) in premarket trading.
Here is the company’s release: FINAL-Q3-26-Shareholder-Letter.pdf
From my Diary yesterday afternoon and last night on Netflix:
Repeating for emphasis, I would not bottom fish in Netflix (NFLX).
I expect in line-to-better 2Q2026 results but a possible lower forward guidance as margins are pressured.
From last month:
I would continue to avoid buying (and “bottom fishing”) in Netflix (NFLX) for the reasons I have previously mentioned:
* Netflix has nearly saturated the domestic market (as well as many other developed countries). These markets are significantly more profitable than the non developed arena.
* Future Netflix sales/profit growth will come from developing country markets that provide substantially less revenue (and income) per subscriber.
* Netflix’s original content programming has been unspectacular over the last 12 months (or more) — and existing content has suffered.
In the past I have been short NFLX, but it is no longer priced as an attractive short.
Position: None
BY Doug Kass · Sep 22, 2026, 1:50 PM EDT
Position: None
BY Doug Kass · Oct 20, 2026, 4:09 PM EDT
Post Script:
Netflix, according to AI, was among the most recommended equities of the panelists on the “Show:” But viewers, in light of no timestamping or memorializing of recommendations, probably have no clue.
Though, as seen by my tweet above, I have stopped using X as a forum for my constructive criticism, I have a clue. Here is a recent recommendation of Netflix by one of the more particularly smug panelists seen on the Noon Show:
Trade Tracker: Steve Weiss buys more Netflix
We will likely never hear the name (Netflix) again from this particular panelist — or any of the others. As night follows day none of the panelists have modelled Netflix, spoken to management (and its competitors) or have performed any serious analysis.
Images and franchises are polished by panelists showing successful investment recommendations and not their conspicuous and frequent investment boners.
Instead the shows and panelists will likely all discuss SpaceX (SPCX) today (whose shares are up by 6% after their EPS release)..
Position: None
BY Doug Kass · Oct 21, 2026, 6:45 AM EDT
Positon: None
BY Doug Kass · Oct 21, 2026, 6:35 AM EDT
But the magnitude of the selloff in precious metals doesn’t appear to be as substantial as many think based on the long-term chart of gold:
For now I am approaching GLD as a “trading sardine” and not yet as an “investment.”
Position: None
BY Doug Kass · Oct 21, 2026, 6:32 AM EDT
Position: None
BY Doug Kass · Oct 21, 2026, 6:25 AM EDT
* As the bursting of the AI bubble comes into sharper focus…
Position: None
BY Doug Kass · Oct 21, 2026, 6:15 AM EDT
Today is yet another important judicial decision on cannabis rescheduling.
You can get a heads up by watching the documents loaded on this governement site:
Position: None
BY Doug Kass · Oct 21, 2026, 6:05 AM EDT
This tweet from Graham Farrar, president of Glass House (GLAS), could bring some stability to GLAS shares:
I have still not spoken to management.
Position: Long GLAS (S)
BY Doug Kass · Oct 21, 2026, 5:55 AM EDT
The S&P Short Range Oscillator slipped from modestly oversold to neutral at -0.06% vs. -0.66%.
Yesterday I traded SPY from the short side and made a small profit on the move lower from the highs.
Last night I reloaded on the short side:
Dougie Kass
I am back shorting SPY at $771.57.
I am a seller on a scale higher tonite.
Position: Short SPY (S)
BY Doug Kass · Oct 21, 2026, 5:42 AM EDT
DEA’s $MSOS response is due today. If the ALJ denies the reopening motion, he admits the GAO report, allows one short briefing round, then rules on rescheduling. Recommendation before midterms is still in play 🤞

NEW: A DEA judge is ordering the agency to respond to marijuana rescheduling opponents' request to reopen a hearing on the proposal for additional testimony and document discovery—saying "this matter remains STAYED to allow time for a response and to allow time for the tribunal
Gold has already corrected nearly as much as it did in 2008. Yet many are acting as if the selloff has only just begun. I see an opportunity. If this is the secular bull market I believe it is, we won’t get many chances to buy after a pullback like this, in my view. Show more

Bank of America just gave back its entire year. The stock peaked near $64.50 in September and has since fallen to about $51, erasing all of 2026's gains in weeks. When Wall Street decides the problems will linger, it sells first and asks questions later. A 20% round-trip in aShow more
The AI boom is now a debt boom. US dollar AI-related bond issuance is set to hit about $410 billion in 2026, up from roughly $210 billion last year and under $90 billion in 2021. Hyperscalers, data centers, and neoclouds like CoreWeave are funding the buildout with borrowedShow more
This is what the top of an AI bubble looks like. Nscale, a data-center startup, listed 10,000 megawatts of "potential" capacity in its IPO filing. It has actually built or leased less than 1% of it. The stock flamed out on debut, and neocloud peers like CoreWeave and Nebius areShow more
Netflix revenues hit a record $12.9 billion in Q3, up 12% YoY. This was the slowest revenue growth rate since Q3 2023. Net Income of $3.7 billion was up 44% YoY. Operating margins moved up to a record 34.6%. The stock was down 45% over the past year heading into earnings. $NFLX


whoa: SPCX cash and cash equivalents $51.29 billion, estimate$91.2 billion

*SPACEX 3Q ADJ. EBITDA $8.81B, EST. $6.59B *SPACEX 3Q NET INCOME $4.40B, EST. $1.88B
The global debt crisis has never been worse. Japan now has a gross government Debt-to-GDP ratio of 204.4%, the highest among any major world economy. Italy follows at 138.4%, while the United States stands at 125.8%, which is only below the ~132.0% record set during the 2020 Show more

David Einhorn explains why the value investing industry has been defeated, and walks through how it leaves Greenlight as a "dinosaur" “The market structure has changed, and there has been what I consider to be a broken market, or the value investing industry, I think, is Show more

Dan Sundheim explains why real risk management has to happen before the trade, not after “Yeah, you could follow Reddit tweets all day long, but what does that tell me? The stock went up 100%. There’s a bunch of people who like the stock. Obviously, if I read the Reddit, they
1% of companies represent 90% of AI spending. Of that 90%, 80% of this spend are from unprofitable VC backed companies. So, roughly, $0.70-75 of every dollar of AI spending right now comes from AI companies spending VC investment dollars. As a result, the revenue quality in Show more

BREAKING: Citadel founder Ken Griffin says AI is "almost certainly" a bubble, noting that companies are struggling to turn AI spending into productivity gains. However, Griffin says he is bullish on AI's long-term potential.


This tracks. I watch something on YouTube every day. Netflix is a dormant subscription for me. YouTube has very low costs of content creation. Netflix has $14B of debt that has financed their content library. Another lesson in the halls of mismatching assets and liabilities? Show more


