The following is from Peter Boockvar:
The breadth & reach of The Bank of Nvidia/Other tech news, consumer too/Williams wants another hike
As we now try to figure out what the fate of the Bank of Nvidia will be, let alone their core business with new leadership, this was a thorough piece from Bethany McLean laying out the extent of its financing reach. I mentioned yesterday the $99 billion of equity investments as of Q2 along with the other vendor financing and lease obligations but this goes much deeper into detail.
https://hntrbrk.com/investigations/nvidia
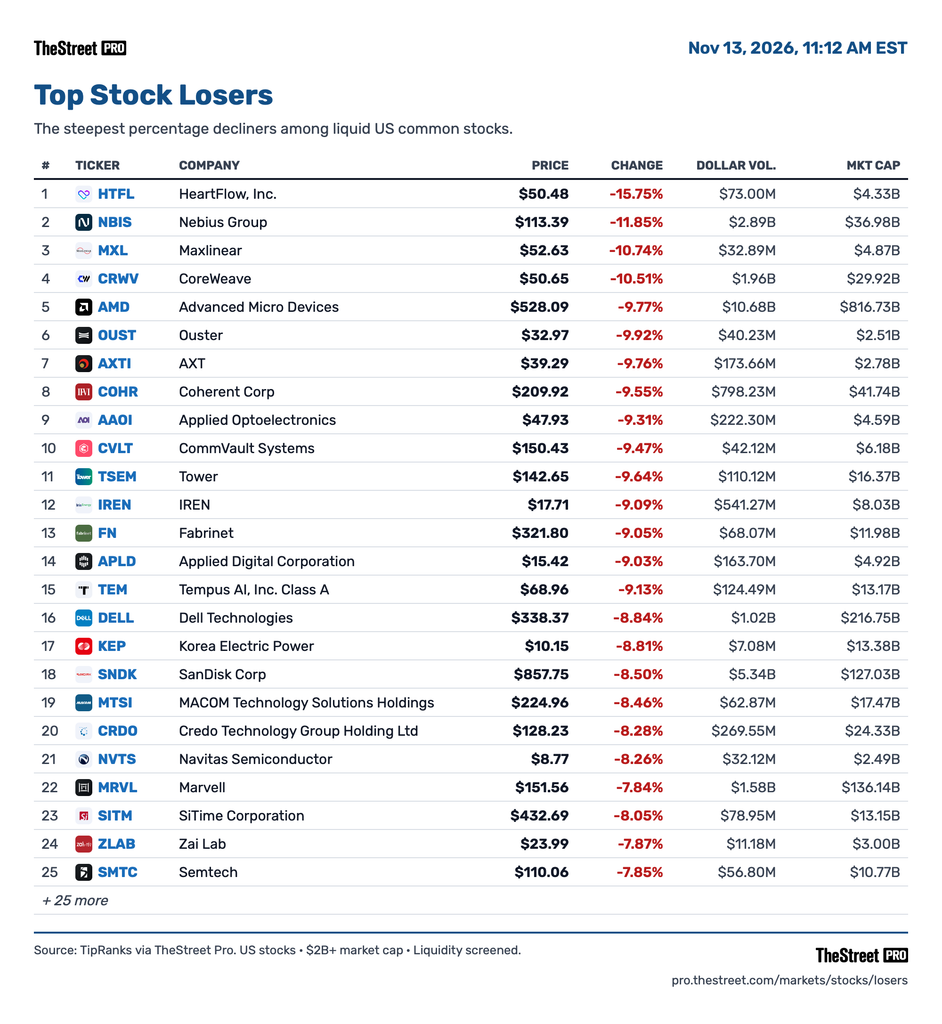
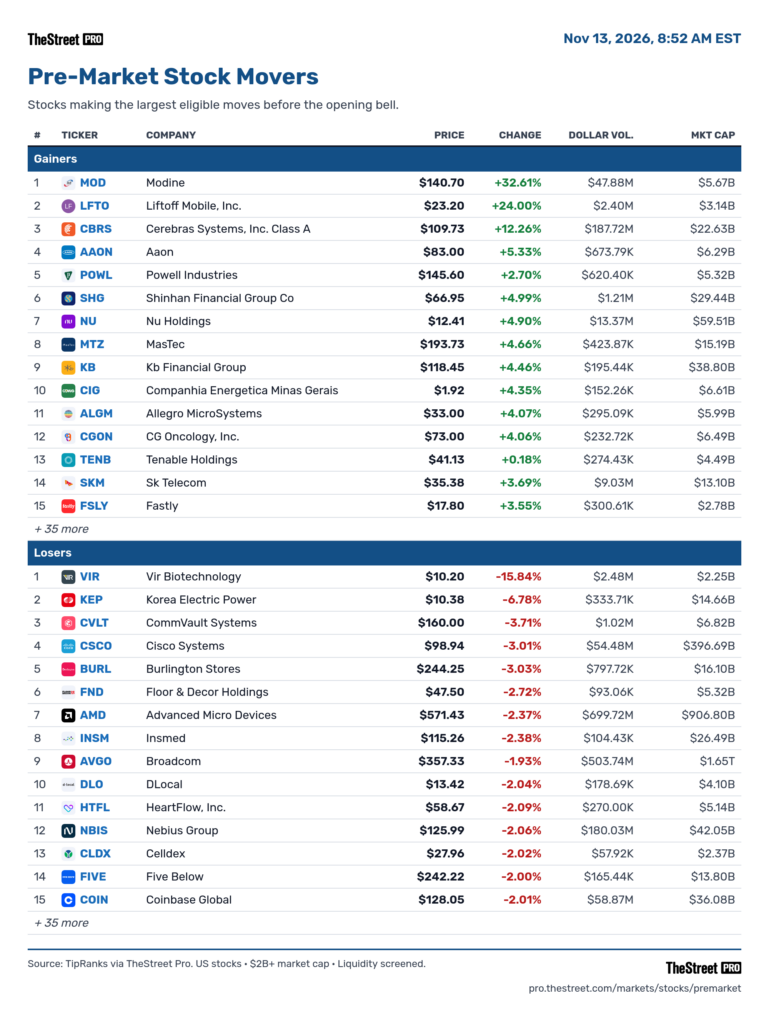
The other AI related news of note yesterday was the results from Nebius whose stock fell 17% after rallying by 15% on Wednesday in response to the CoreWeave earnings report. From their earnings call:
The positive case, “Demand is strong. Our customers are committing to us for longer, at higher prices, and they are paying more upfront. Prices keep rising. Q3 agreements closed above $25 million per megawatt, another step up from the $20 million to $25 million per megawatt we achieved in Q2. Our customer agreements are getting larger in size.”
And the make up of their contracts, “we sell on three horizons, and we choose the best mix between the three. First is on spot and short-term at a premium price. Another is one to three year contracts, and this is our core business. And a limited number of five year agreements that diversify our contracts, tenures, and further help us to finance our build out. The second and third are covered by prepayments.” And those prepayments “now cover more than 100% of the capital needed to bring this contracted capacity online.”
But, “Building at this scale is hard, and delays are part of our industry right now. We are not immune. For example, some of our co-location sites, including New Jersey, are behind schedule. Customers have been kept informed, and none of that capacity is canceled. Some of it has shifted to 2027. This means that a portion of this year’s planned revenue moves into the start of next year. But with our own sites, we remain on track and even ahead of schedule.” As a result, “For 2026 we are seeing some third party capacity shifts into the second quarter of 2027. We now expect revenue of $3 billion to $3.2 billion compared with our previous range of $3 billion to $3.4 billion.”
Also hitting the stock, “CapEx for 2026 is now expected to be around $27 billion, up from $20 billion to $25 billion previously.”
From Cisco and whose stock is down premarket as order growth rates outside of Asia Pacific moderated:
“Our strong start to fiscal year ‘27 demonstrates the criticality of networking and security together as agentic AI accelerates.”…We believe we are still early in the networking super cycle driven by AI deployments with enterprise adoption just beginning.”
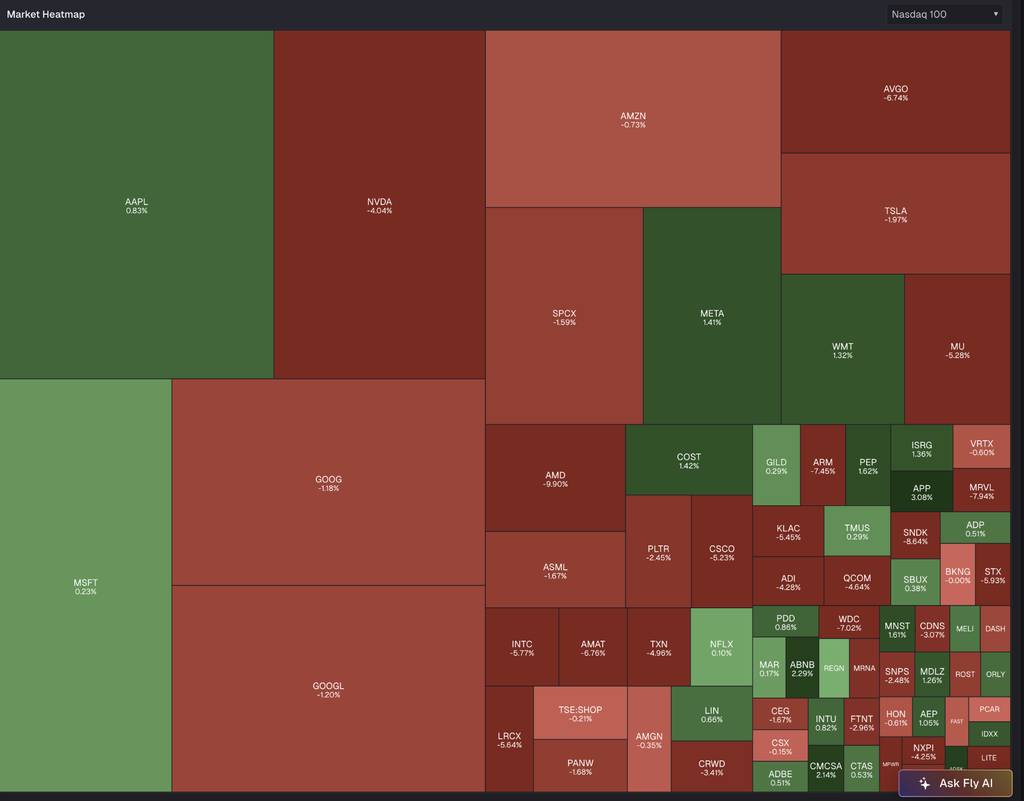
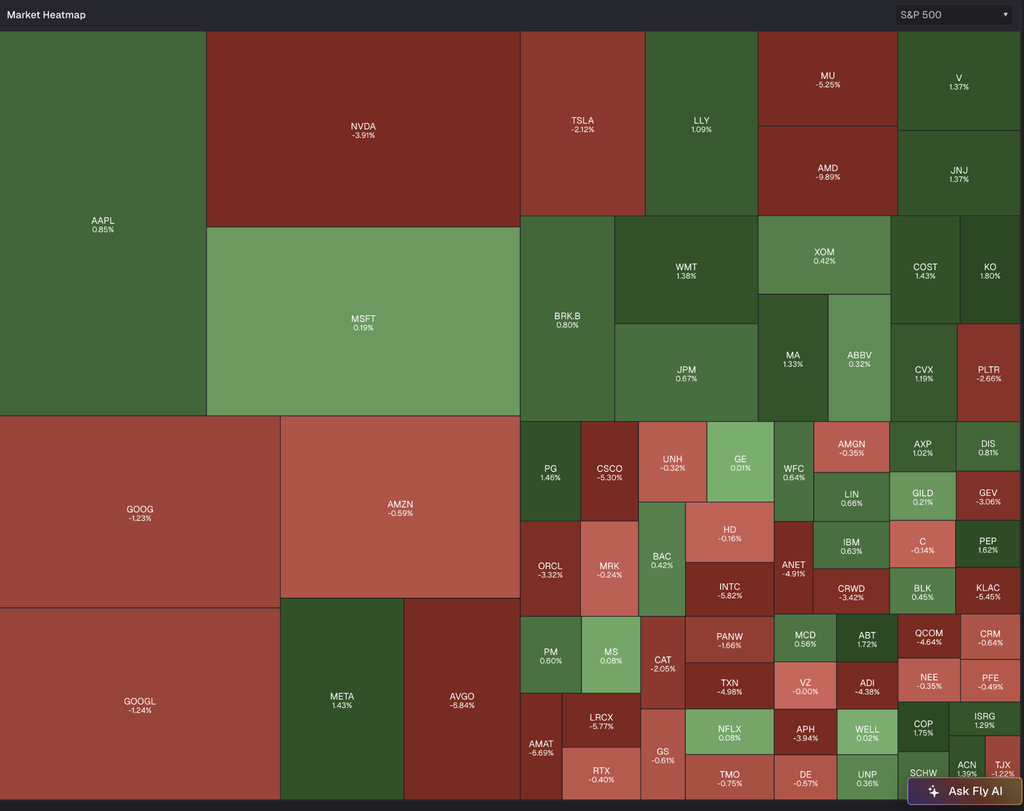
Maybe why the stock is down, to an analyst question “it looks like we had a little bit of a sequential downtick in AI orders taken from microscales in the quarter. I know the industry is somewhat lumpy and not linear. Can you maybe talk to kind of how you’re seeing that develop as the year progresses and characterize the depth of your conversations.”
The answer from Chuck Robbins, the CEO, “So, while I don’t expect there’s normal linearity in this business at all, I think you’re right, it’s going to be lumpy. And there’s going to be some quarters that are going to be big, others that are going to be smaller.”
A company benefiting from the data center buildout has been Legence, as they “specialize in designing, fabricating and installing HVAC, process piping and other mechanical, electrical, and plumbing systems for new facilities” along with upgrading existing facilities. From their call yesterday:
“We also expect solid growth in data center activity, including in regions such as Northern Virginia, where certain tighter regulatory conditions have actually been in place starting in early 2026…Opportunities in the region extend several years out, and that pipeline remains significant. While the DMV (DC, Maryland and VA) is a substantial region for us, we also serve data center clients nationwide, shipping fabricated products across multiple regions and supporting clients wherever they choose to build. Conversations with our data center customers post-election indicate a continuation of their plans to build.”
They have other customers too, “Now beyond data centers, we expect the semiconductor and memory chip market to be quite robust going forward. Our other end markets, such as life science, education and state and local governments, provide diversification and exposure to other target rich clients that have historically delivered solid growth.”
Shifting gears to retail and the consumer, this was a call from last week but one I always find helpful to go through. From Simon Property, the largest mall operator in the country and who owns the Short Hills Mall that I just gave some money too this week:
“Traffic growth accelerated in the third quarter, furthering a trend we have seen throughout 2026. Sales productivity is a record levels for each of our platforms, underscoring the health of the retailers in our centers and the quality of our real estate.”
“Tenant demand remains widespread from established national and international brands to emerging fast growing concepts.”
On what they are seeing with the pace of customer spend, “it is very broad based. It is across platforms, across geographies, across categories that we have seen growth…And it’s the same story that we talked about in the second quarter, athleisure, juniors, brands, luxury, watches, jewelry. One thing that is a nice story is we had actually the best quarter in three years in the restaurants in the third quarter which that business has obviously been sort of flattish, I guess I would say.”
“And so, we really haven’t seen any slowdown in October traffic, in line with the third quarter in sort of that mid 3% growth range. And so, what we’re hearing from the retailers is optimism for the holiday season, which as you know, is our Super Bowl, our time to shine.”
On the high end of consumer spend, Richemont reported today and its stock is down 4.5% in Switzerland as jewelry sales were just below the estimate. From them:
“in the first half, group sales grew by 17% at constant exchange rates with broad based strength across business areas and regions. This included a remarkable 19% growth at the Jewelry Maisons, a robust double digit rise at specialist watchmakers, and a solid high single digit performance at the other business area, which includes fashion and accessories Maisons.”
“In addition, most regions posted double digit growth, led by Japan, the Americas, and Asia Pacific. Impacted by the ongoing conflict in the region, sales in the Middle East and Africa experienced a modest decline overall.”
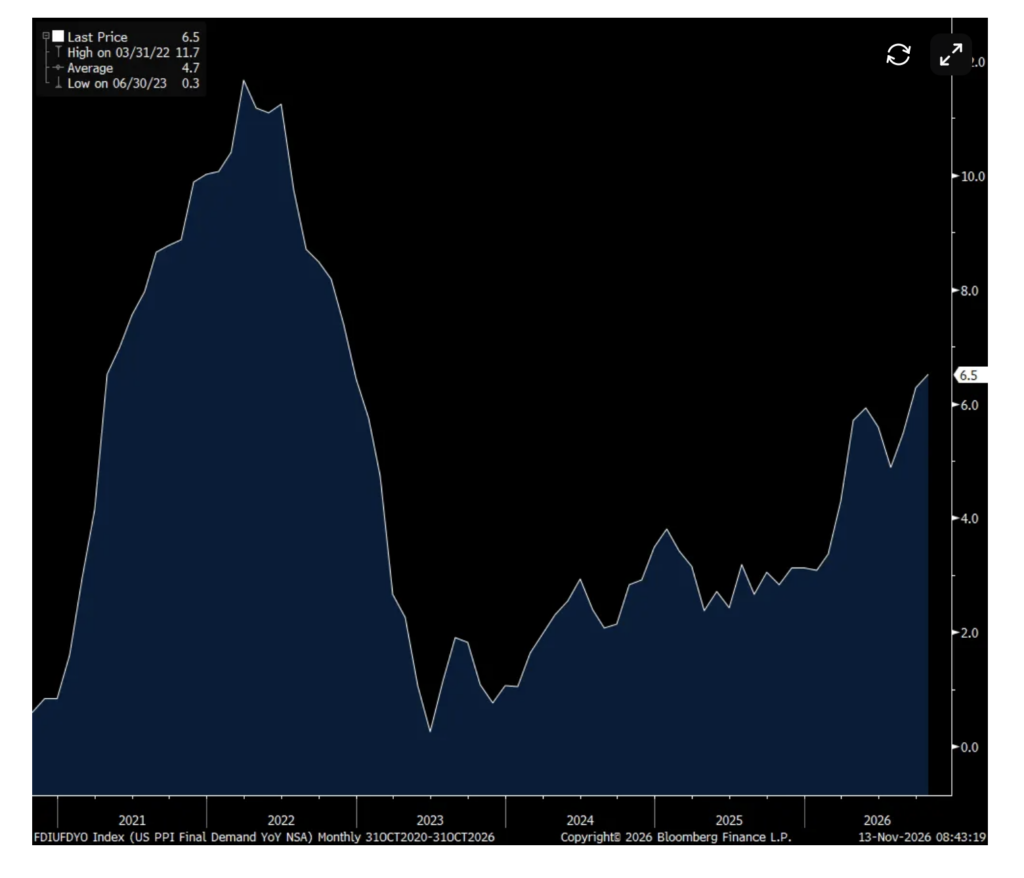
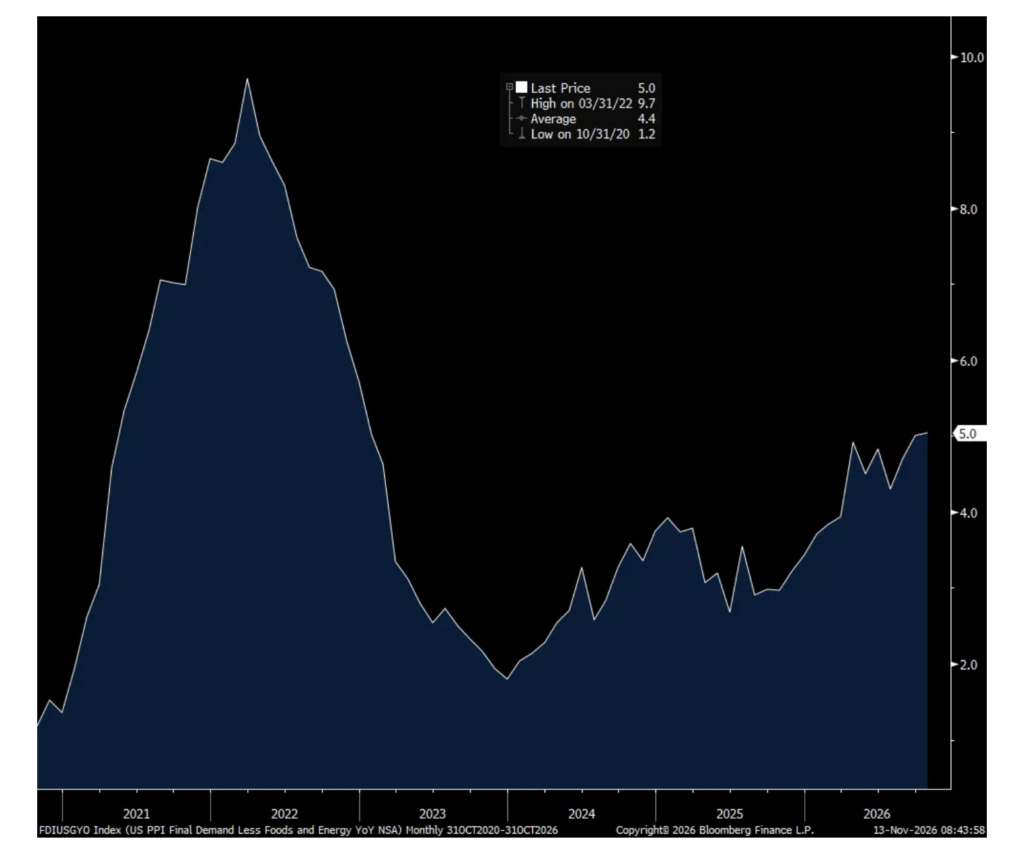
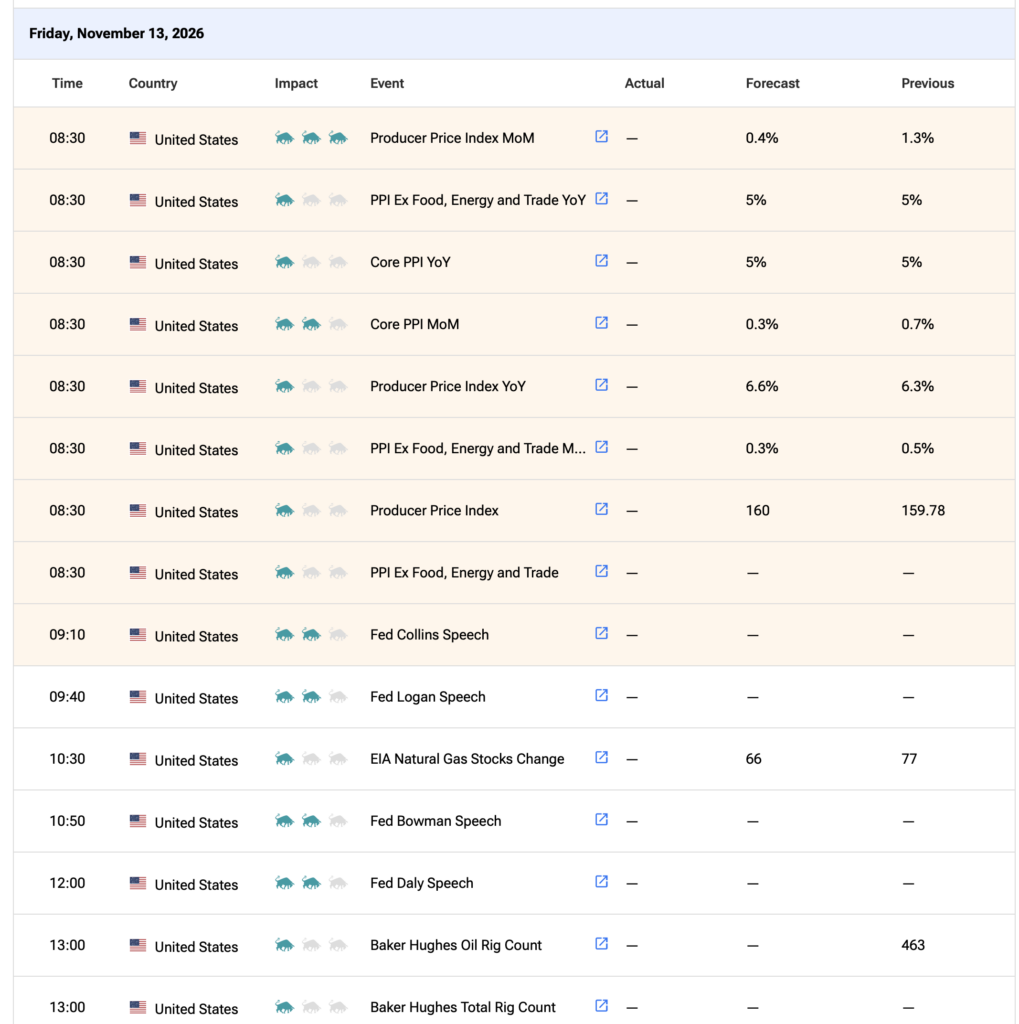
NY Fed president John Williams is joining some of his colleagues in expressing the need for more rate hikes. “Inflation is far too high and it continues to be high even in the latest data. We’ll need to take actions over time that will ensure that we get inflation back to our 2% goal in a timely manner on a sustained basis…I feel that the data is speaking very clearly to us, the economy is strong, labor market continues to strengthen and inflation is persistent. We still have work to do in terms of getting monetary policy to the right place.”
I will be definitely wrong about the December rate increase, assuming the situation then holds vs today, but I still believe the pace of the AI CapEx and its influence on the stock market is going to be a big Fed topic next year and will limit the pace of 2027 hikes, because how can it not be?