Tech Leads a Subdued Open on a ‘Triple Witching’ Friday
U.S equities are mixed Friday morning with Tech names providing some boost while other names lagged as bond yields rebounded.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
U.S. equities are mixed Friday morning with a continued rebound in Tech names lifting the Nasdaq to modest gains while other names lagged as bond yields rebounded seeing the S&P 500 with a modest loss.
Alphabet (GOOGL) +2.3% and Meta Platforms (META) +1.2% are leading mega-cap tech names while hardware suppliers including semiconductor makers are seeing more modest gains with the Philadelphia Semiconductor ETF (SOXX) +0.3%. Optical stocks are another winner such as Lumentum (LITE) +1.7% and Coherent (COHR) +1.4%.
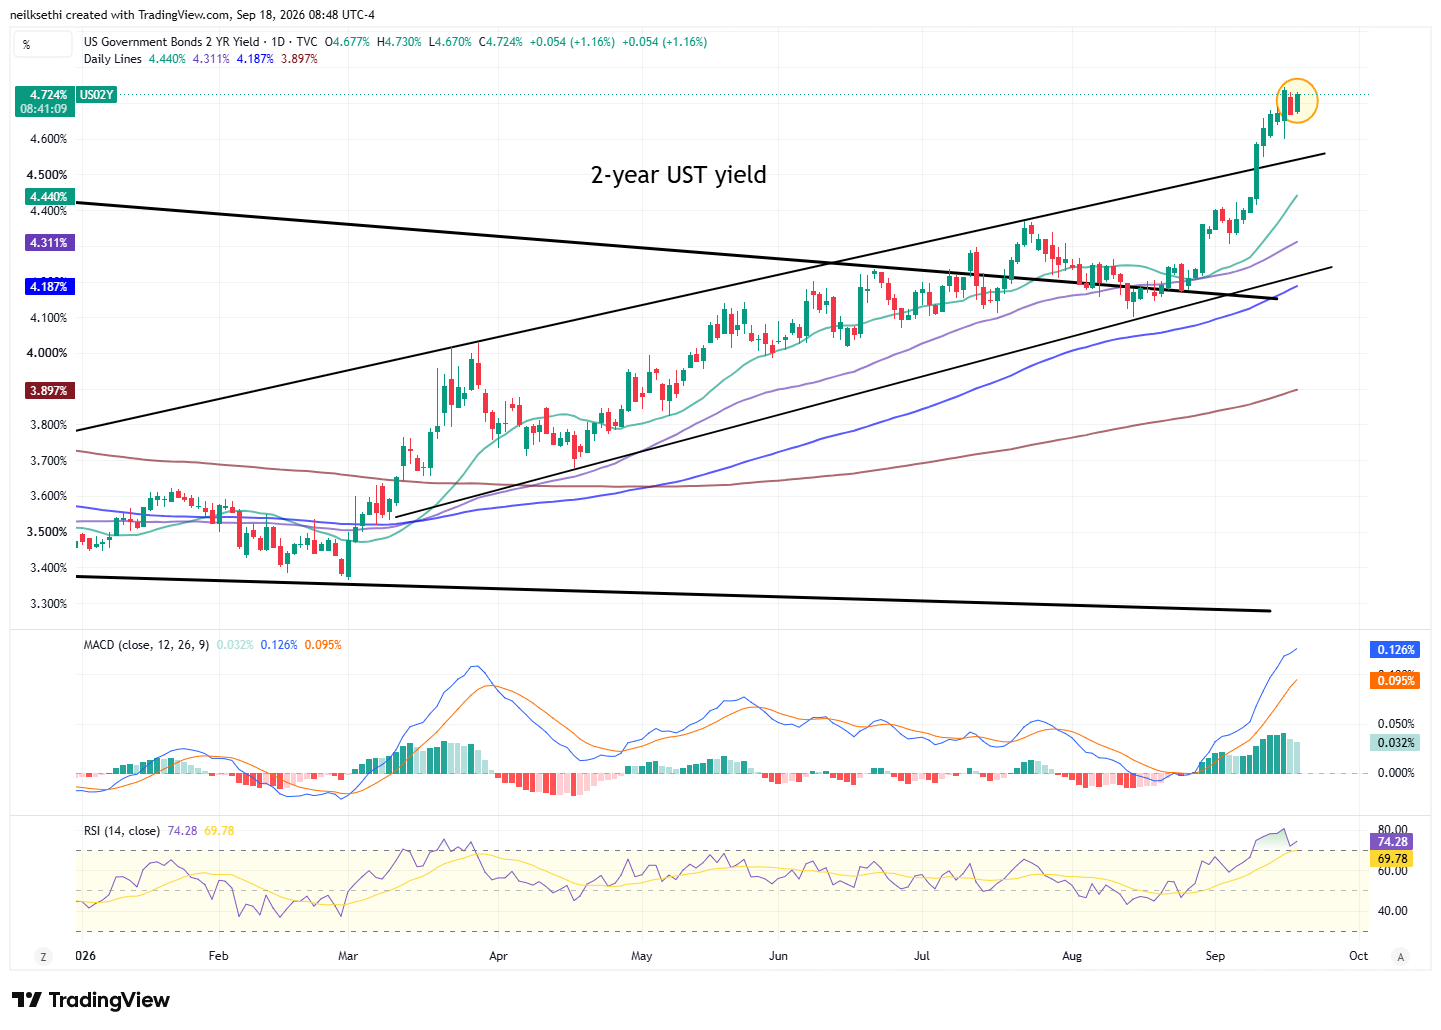
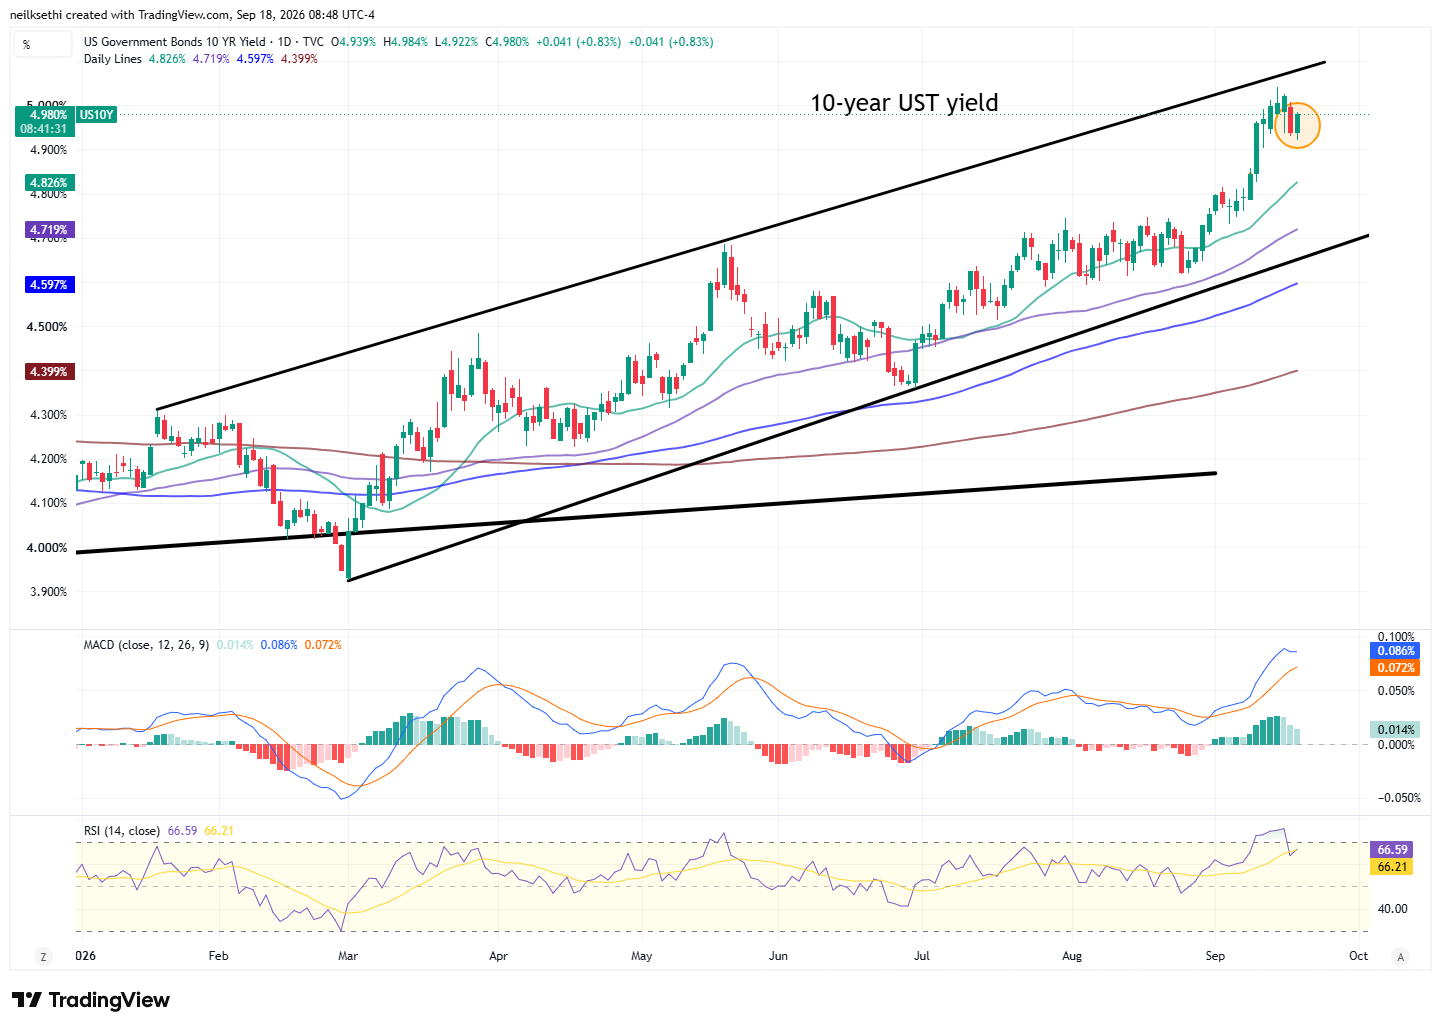
Treasuries fell across the curve (yields higher) led by the short end with the 2-year yield up five basis points at 4.72%. The 10-year yield was up four basis points to 4.98%.
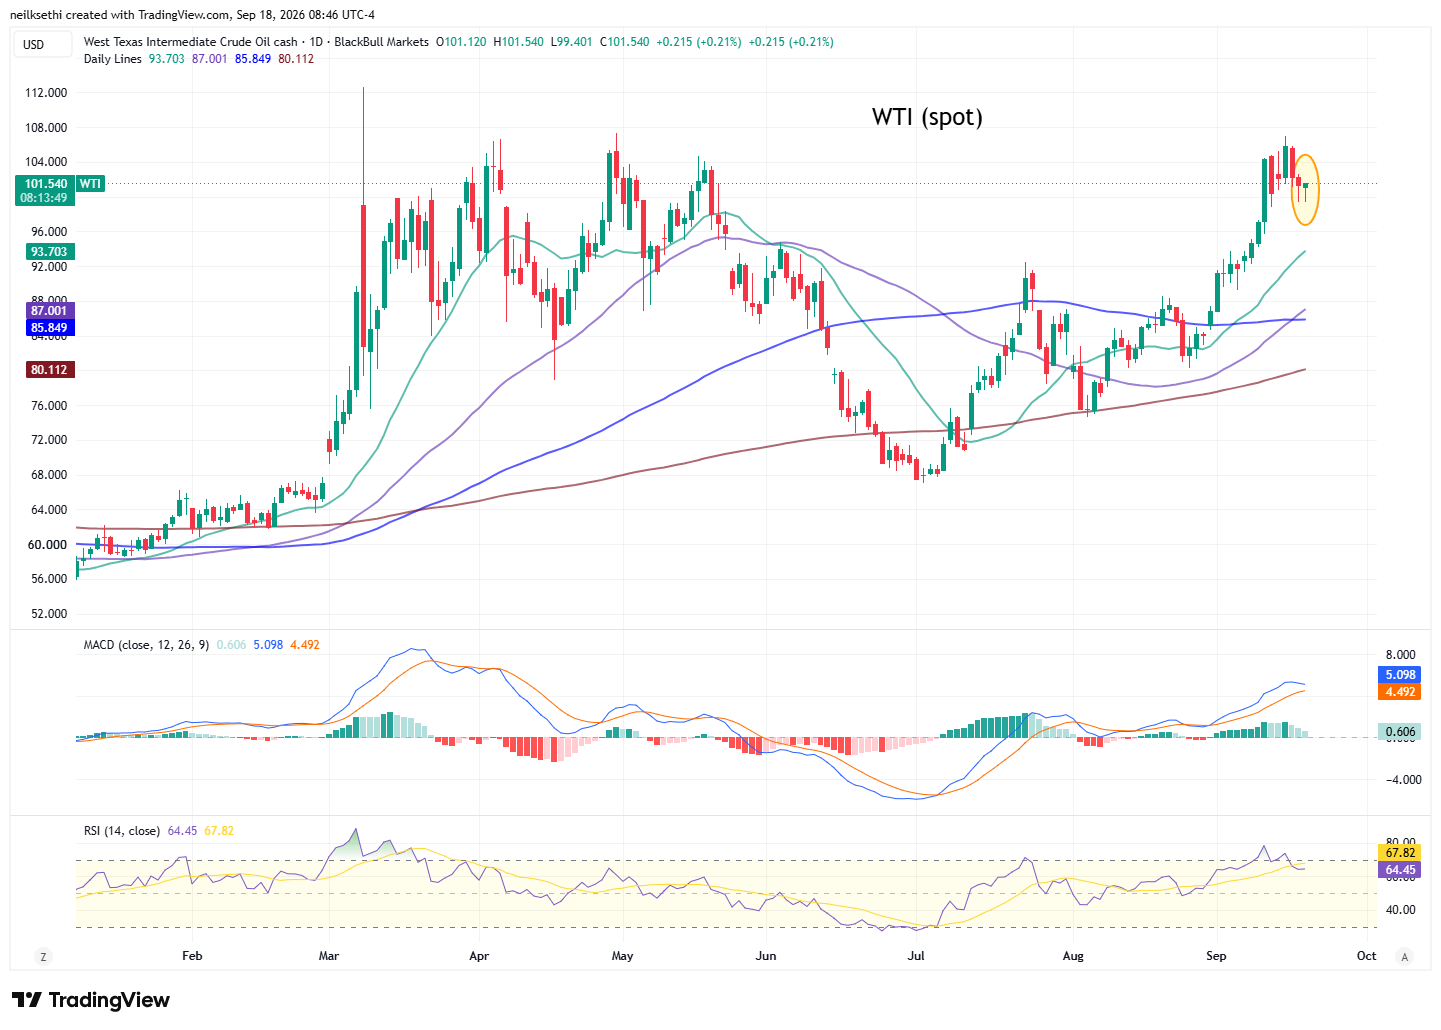
Oil prices softened for a third day even as Saudi Aramco told at least two oil refining customers in Europe that they will be allocated no crude oil next month after the kingdom’s key pipeline to the Red Sea was attacked, people informed of the decision said.
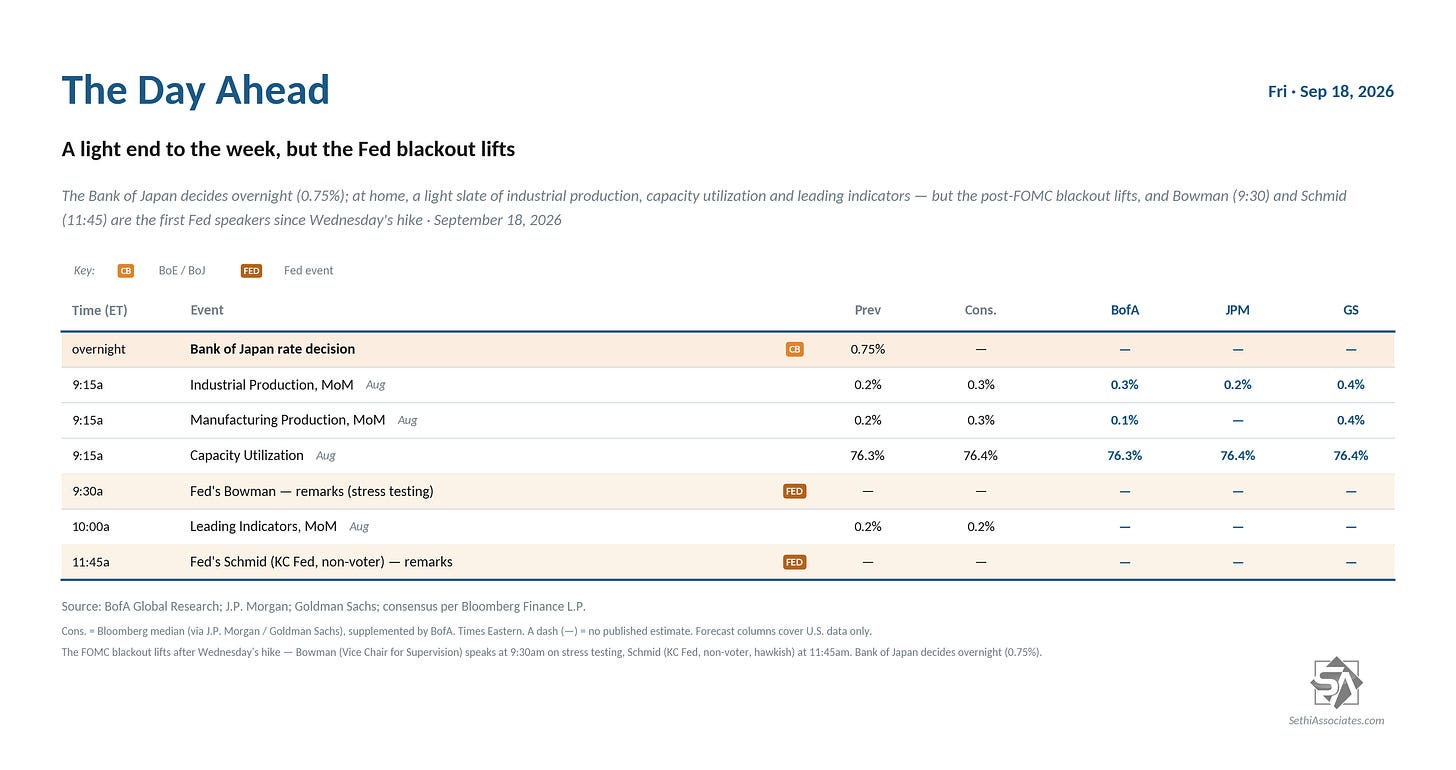
Friday is lighter on the U.S. economic calendar with just industrial production (our most wholistic look at the manufacturing sector) later in the morning.
The Fed speaking blackout is over and we have two speakers on the calendar in Governor Bowman (who is thought to be one of the few remaining doves) and Kansas City Fed President Schmid (a hawk but not a voter until 2028). It’s not unlikely we’ll have some media interviews as well.
Also Friday is a “triple witching” options expiration which could see some pockets of market volatility. Citadel Securities estimates about $7 trillion of options notional value is set to expire, one of the largest ever.
As of 8:50 am ET, the S&P 500 was indicated to open -0.1% while the tech-heavy Nasdaq-100 index was +0.2%, and the small-cap Russell 2000 -0.4%.
[Note the International Update is below the US update]
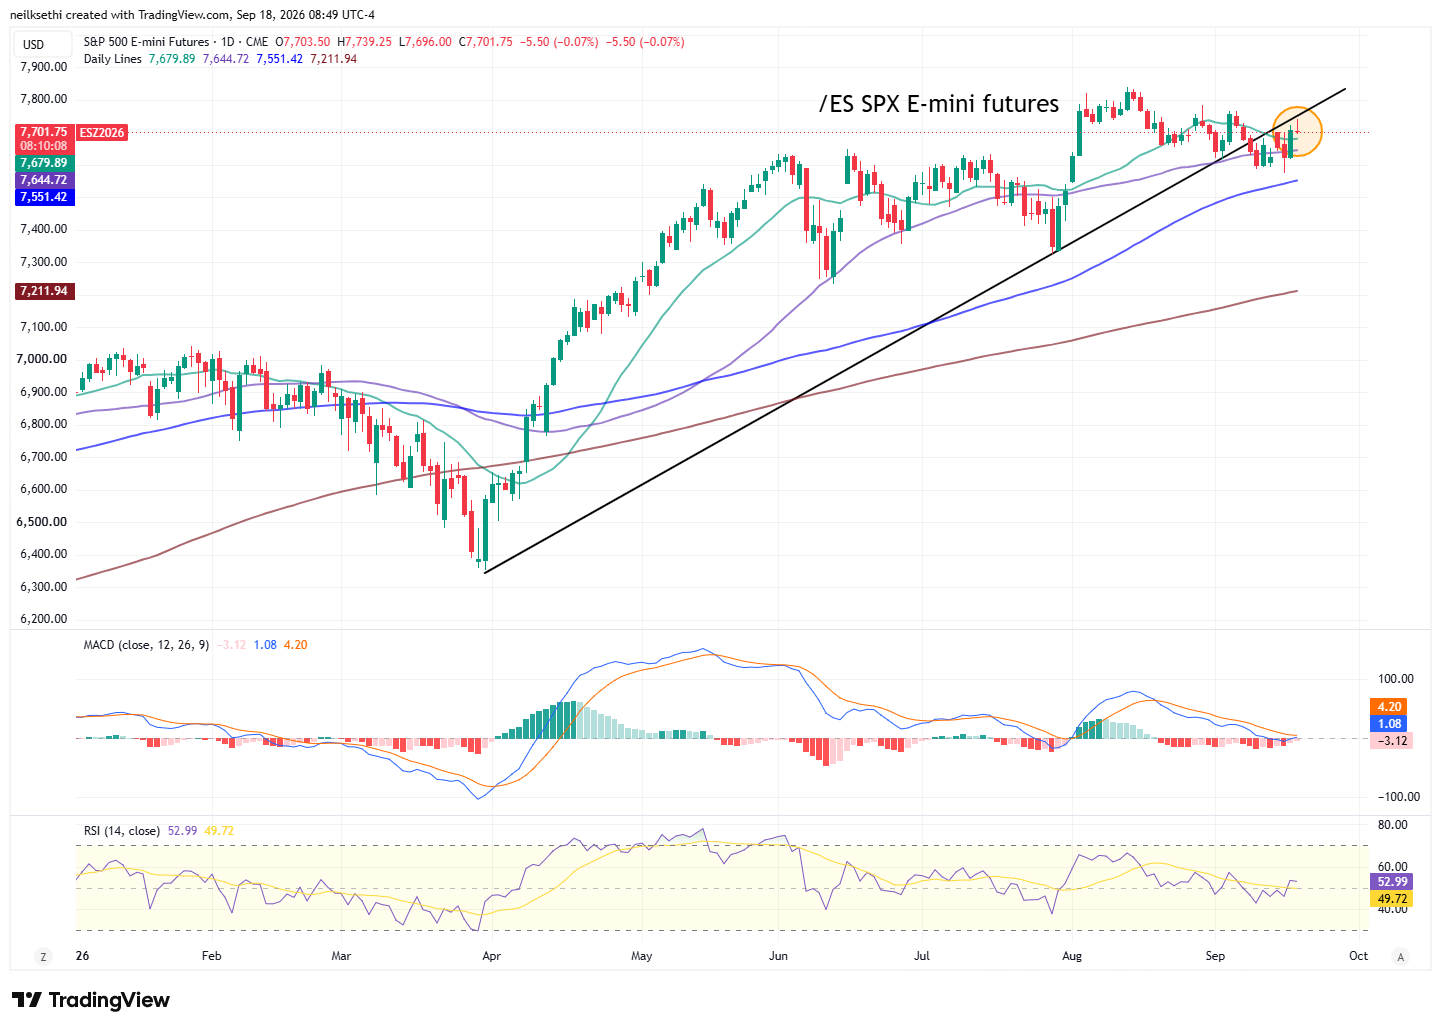
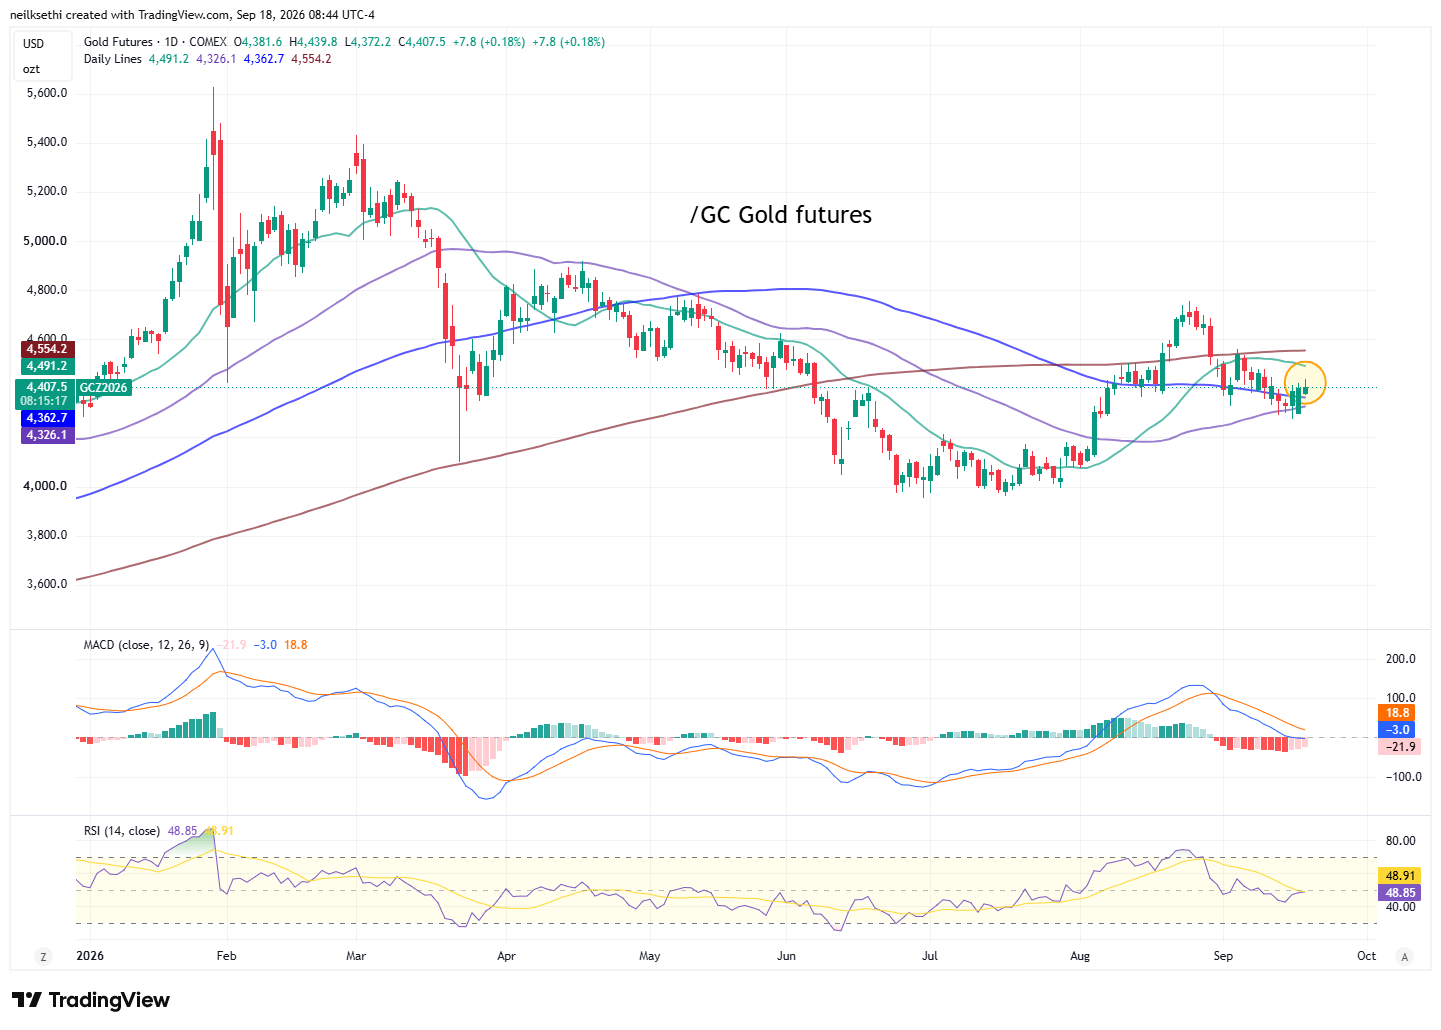
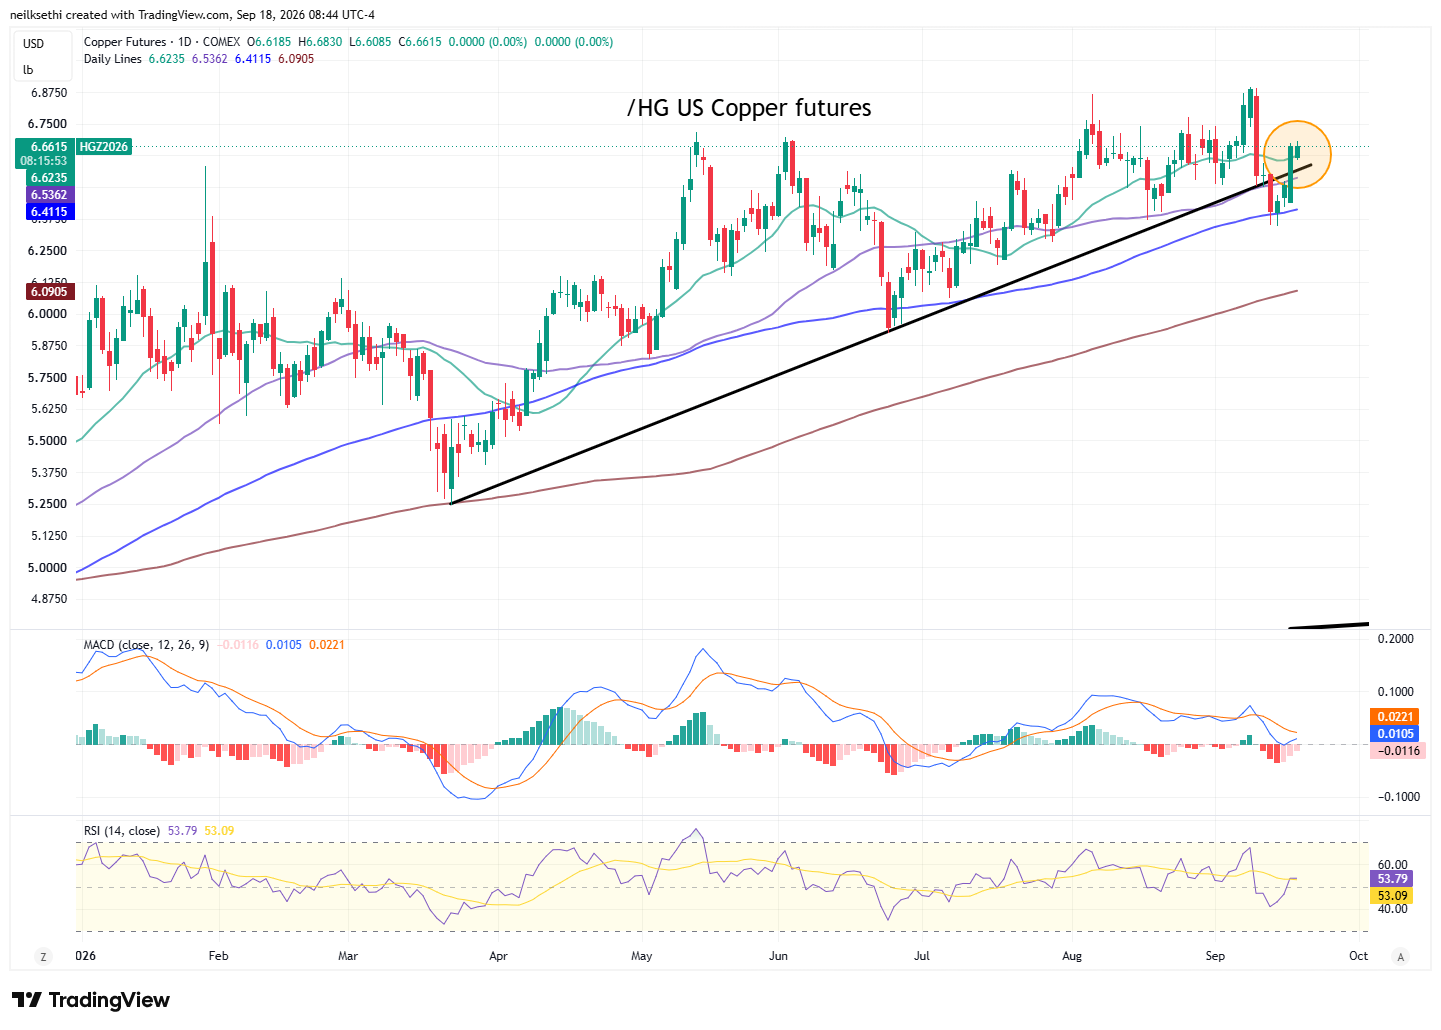
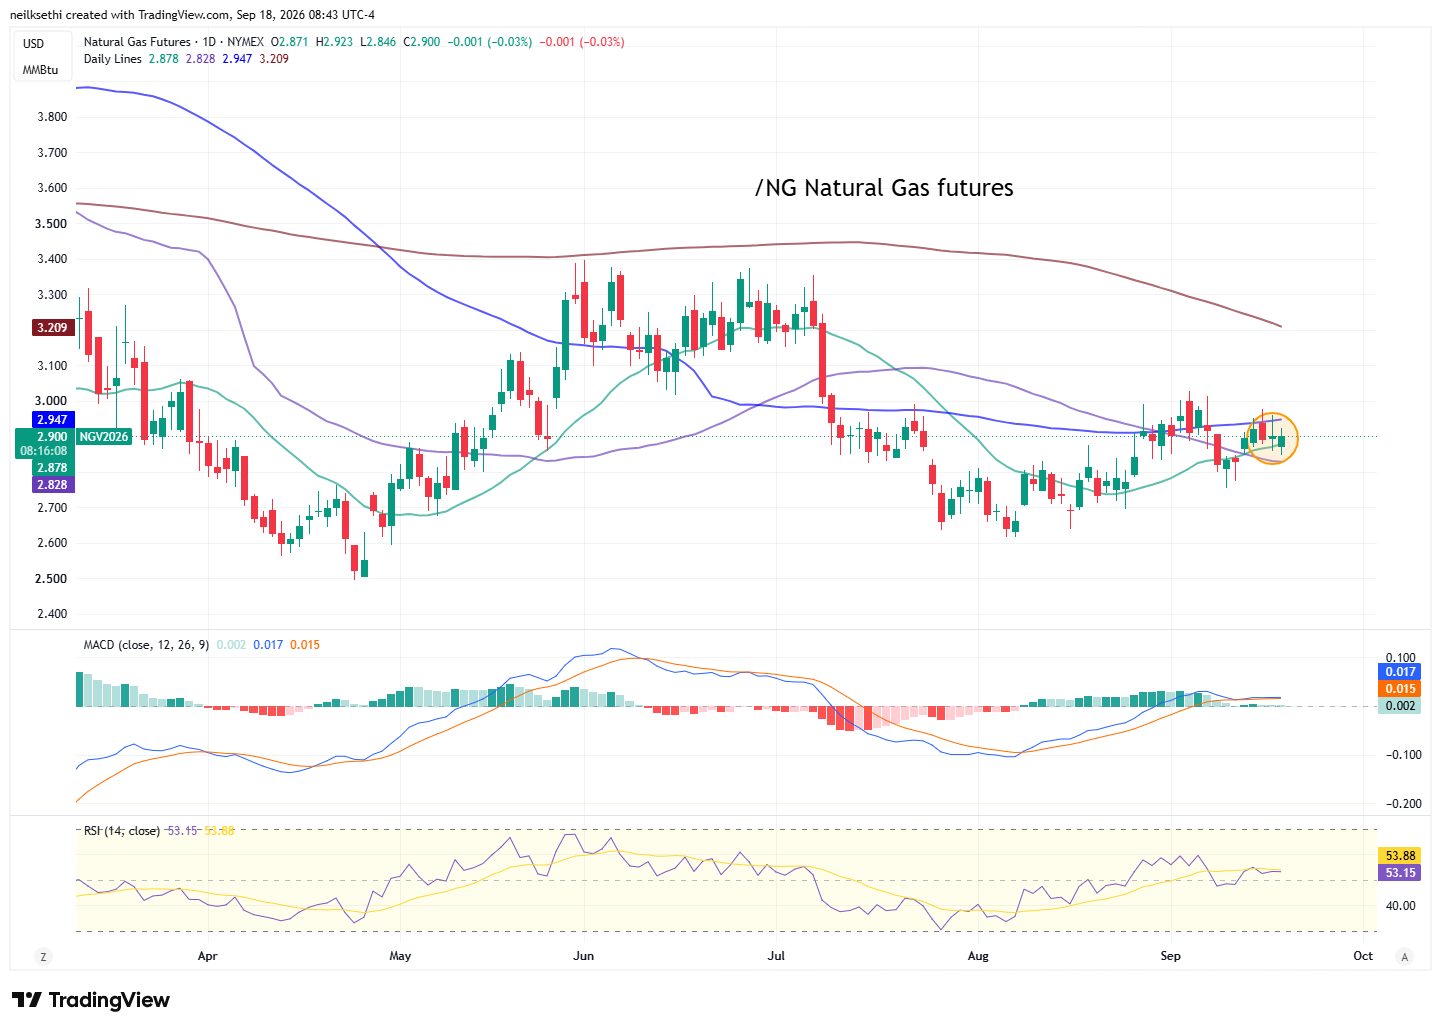
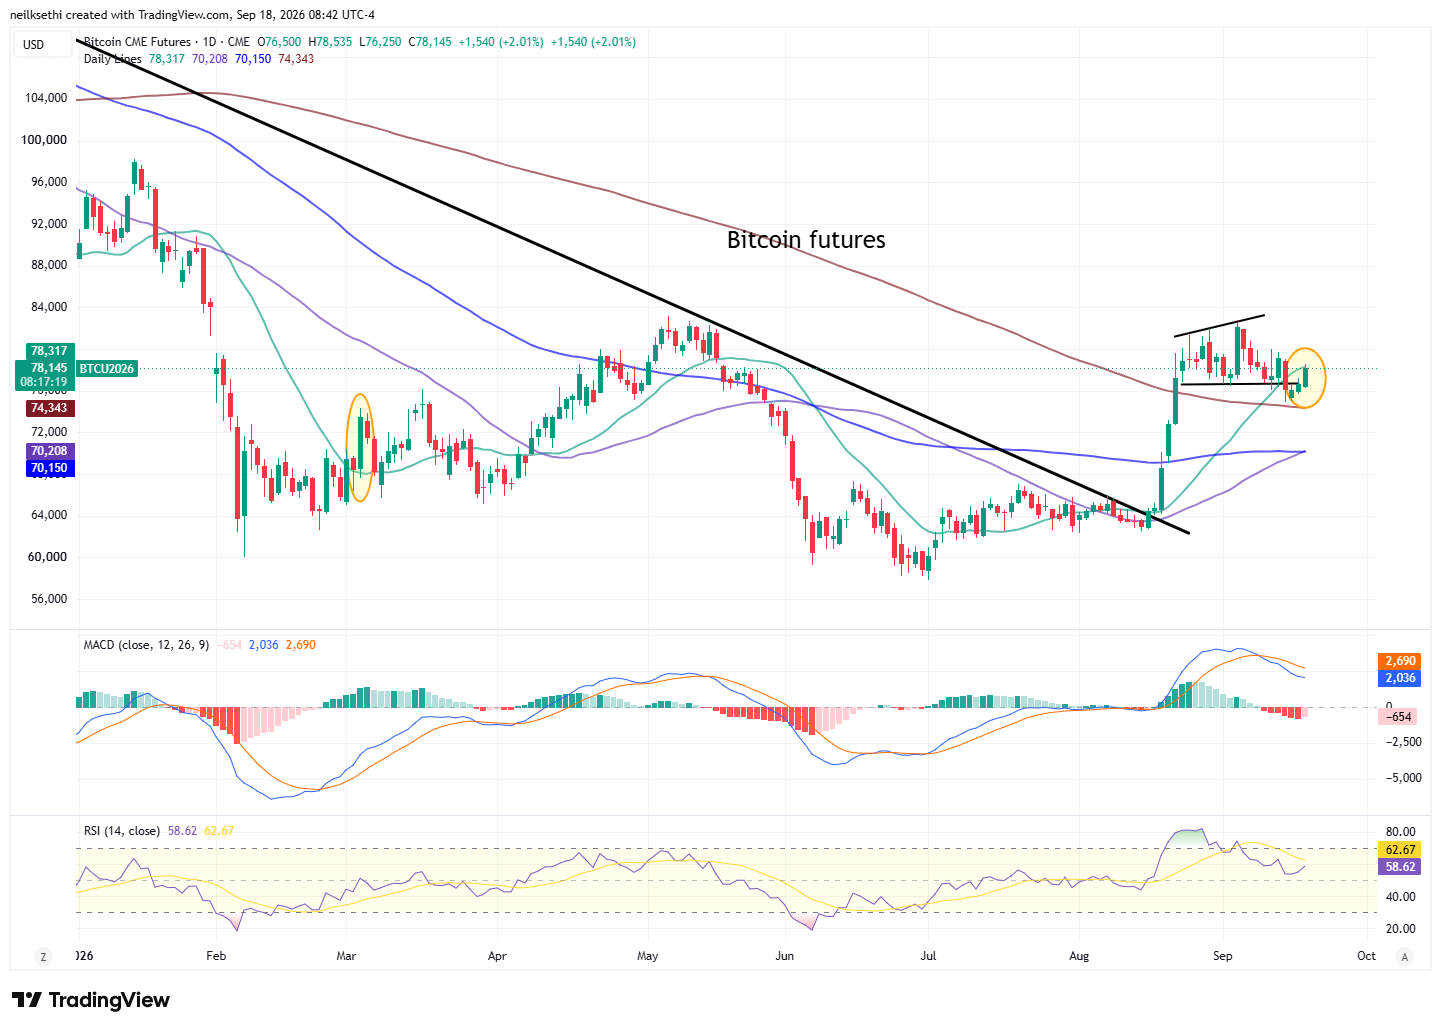
Note on all charts the colored lines are daily moving averages (the average price over the given number of days):
20 = green
50 = purple
100 = blue
200 = brownThe middle panel is MACD = Moving average convergence/divergence line, a measure of momentum that compares longer term and shorter term momentum to gauge if a move is strengthening or weakening. This is probably my favorite individual indicator (it’s also the favorite of Katie Stockton, a very fine technician).
The bottom panel is RSI = Relative Strength Index (basically what it sounds like) = measures the strength of the move comparing gains to losses over the given lookback window (I use the standard 14 periods).
Charts as of 8:45 am
SPX Futures (/ES) – little changed.
2-year yield – back to testing the highest levels since July 2024.
10-year yield – rebounding after first session lower in nine.
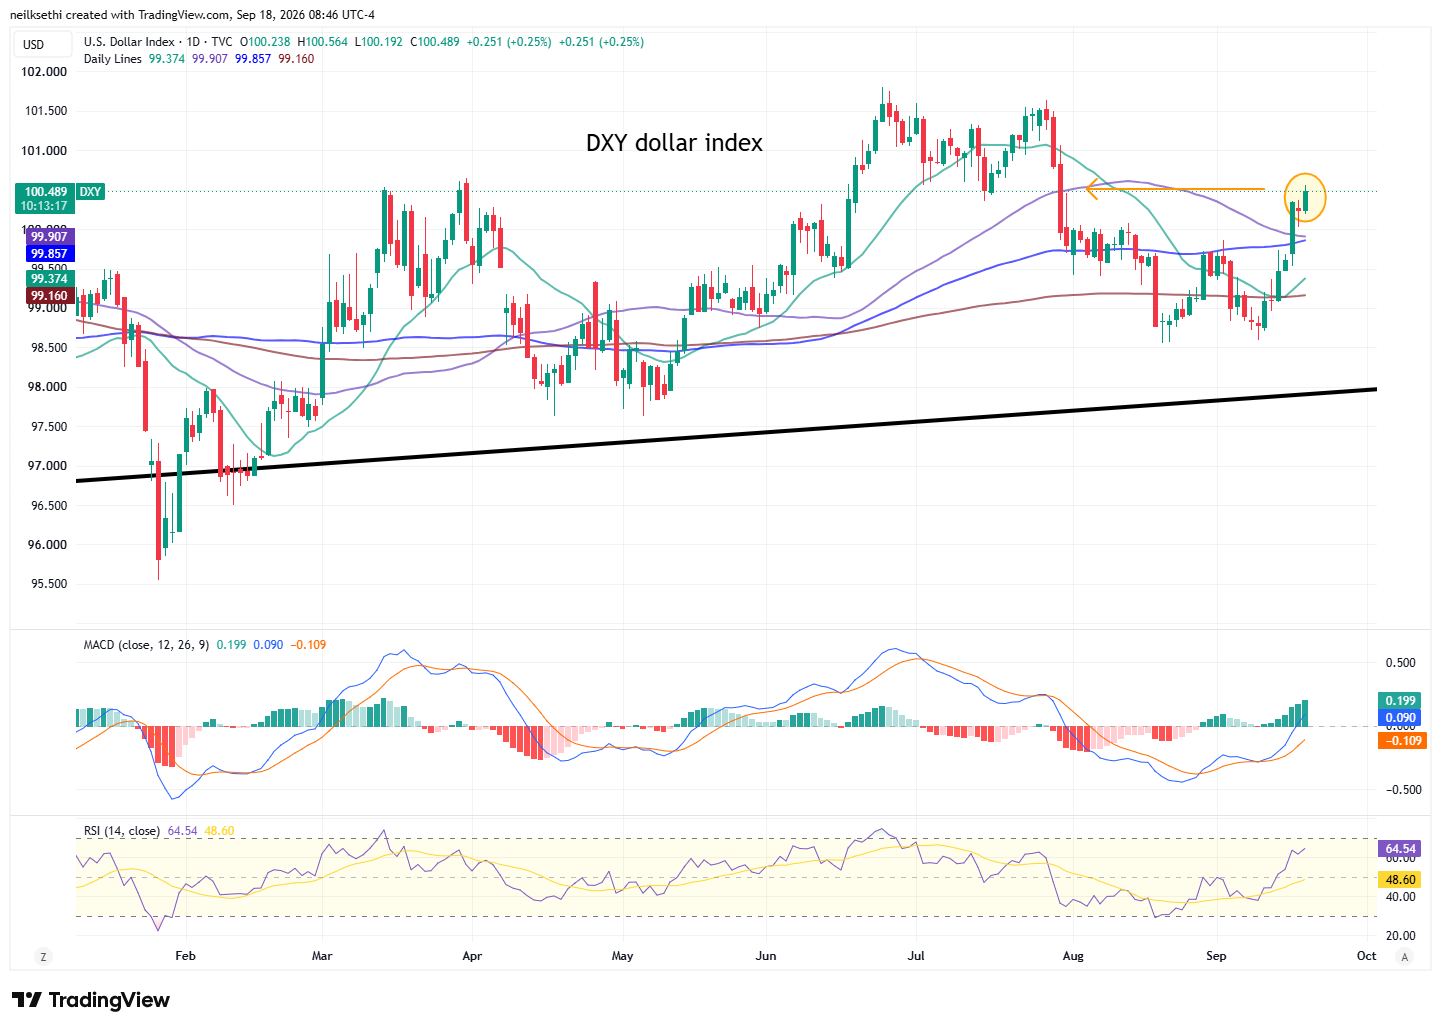
DXY US dollar index – up for 6th session in 7 on track for best week since May.
WTI (cash – not using futures because of a data error) – little changed.
Gold futures (/GC) – up for a third session.
US copper futures (/HG) – up for a fourth session continuing to follow the AI-trade now back over its 50-DMA and uptrend line (if it holds into the cash open I’ll add back what I took off when it broke).
US natural gas futures (/NG) – remaining in their range since early July.
Bitcoin futures – rebound continues for a third day.
Some Premarket Company News
- Steel Dynamics (STLD), Nucor (NUE)— Shares of both steel producers fell more than 1.5% after they delivered third-quarter earnings guidance that showed weaker-than-expected results compared to analysts polled by FactSet’s consensus estimates.
- Netflix (NFLX)— The streamer declined more than 3% after Wells Fargo downgraded the stock to underweight.
- Xenon Pharmaceuticals (XENE) — The stock sank 25% after the company announced it was pausing enrollment for new patients in its clinical studies for treatments for major and bipolar depression.
- Berkshire Hathaway (BRK.B) – Berkshire Hathaway has named Howard Buffett as chair, replacing his father Warren, who will become chair emeritus of the company he spent six decades building into America’s best-known conglomerate.
- Lockheed Martin (LMT), unveiled on Thursday details of a next-generation air-to-air missile developed to counter threats from China and a new agreement with the Defense Department to boost production as the Pentagon rebuilds munitions stockpiles.
- General Motors (GM) – The automaker is supplying parts for Lockheed Martin’s Patriot missiles, the military contractor said Thursday—a potential lift to U.S. munitions supplies depleted by the conflicts in Ukraine and the Middle East.
Stock-Specific Articles From TheStreet Pro
- Stephen Guilfoyle – The Sun Rises on Wall Street
- Helene Meisler – A Shift in Sentiment as Investors Jump the Fence and Join the Bear Party
- James “Rev Shark” DePorre – Investors Are Out of Position — And That Is Supporting the Indexes
Other Headline Articles
- WSJ – Two weeks after a swarm of AI agents broke out of containment at OpenAI to hack the company Hugging Face, the ChatGPT maker learned about another AI-powered intrusion—and this time it was the target. Independent security researchers had used Anthropic’s Claude software to gain access to an OpenAI employee’s ChatGPT account, giving them a way to read and suggest changes to the company’s private cache of software.
- WSJ – Top staff at OpenAI and Microsoft (MSFT) knew that scraping news websites to train their artificial intelligence models may eventually damage or even destroy those publications. They did it anyway, according to a legal filing unsealed Thursday in a high-stakes copyright infringement case.
- FT – OpenAI has disclosed a batch of “concerning behaviour” by its AI models and set out a new framework to track and report such incidents, as the industry battles deepening fears over the safety of the technology.
- BBG – Artificial intelligence pioneer Andrew Ng said warnings about existential AI risks from researchers at top model makers are “science fiction” that may be detrimental to ensuring the technology’s maximum benefits to society.
- BBG – Private Credit Defaults Are 1%, 6% or 19%, Depending Who You Ask
- WSJ – Rising Rates Will Make Private Equity’s Bad Year a Lot Worse
- BBG – Energy prices have been the scourge of bond markets this year. Now investors worry that the next inflation spike will come from food.
International Highlights
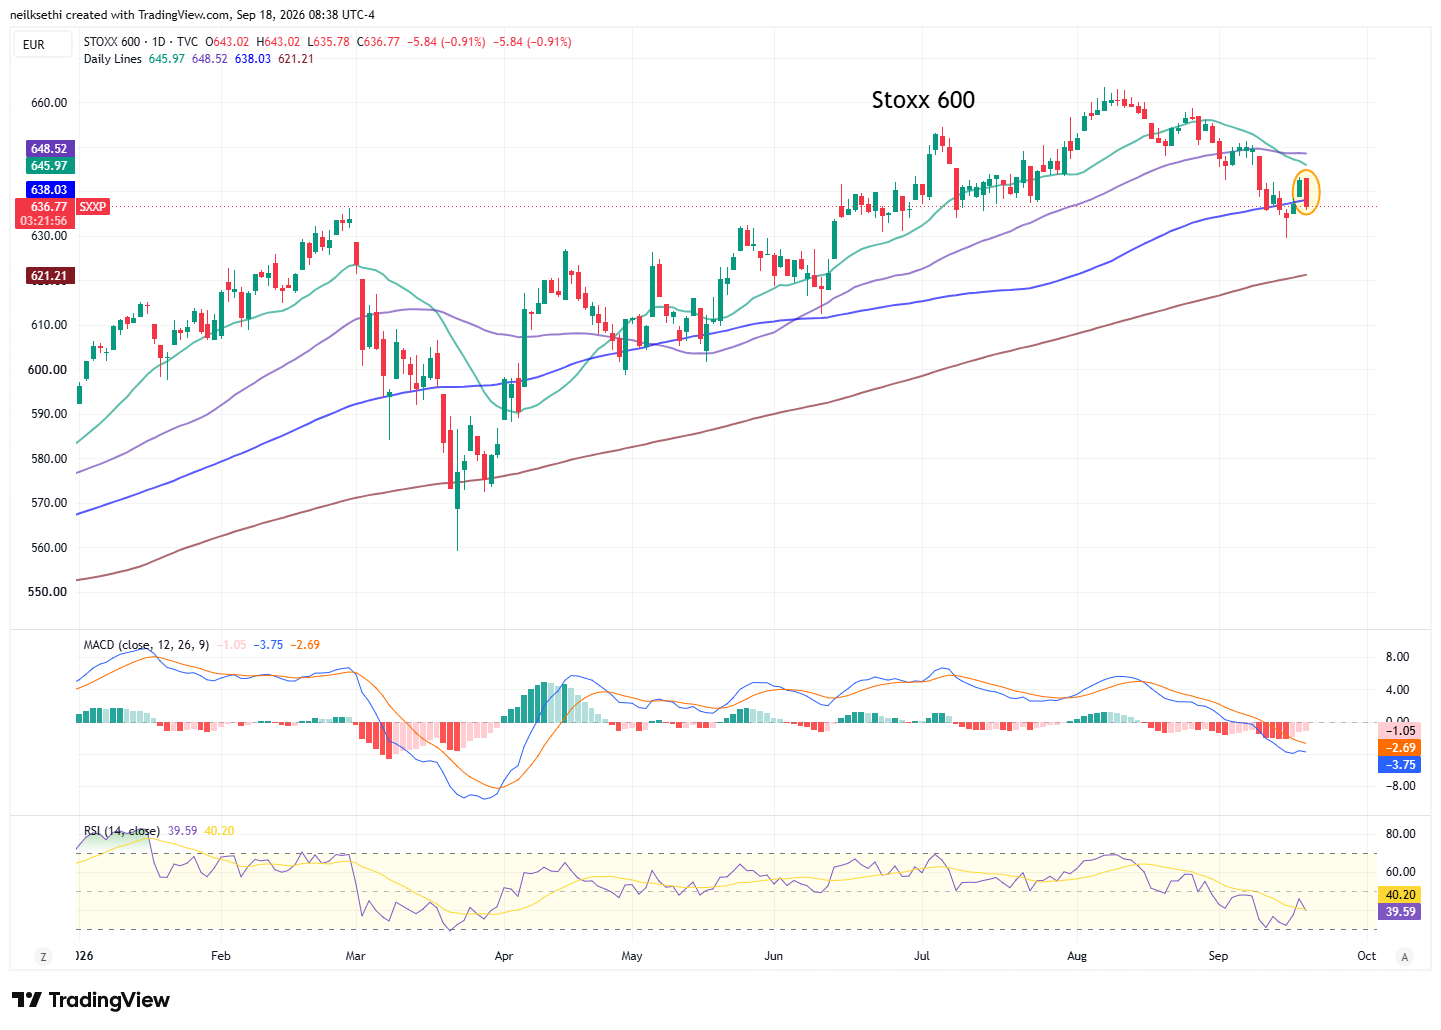
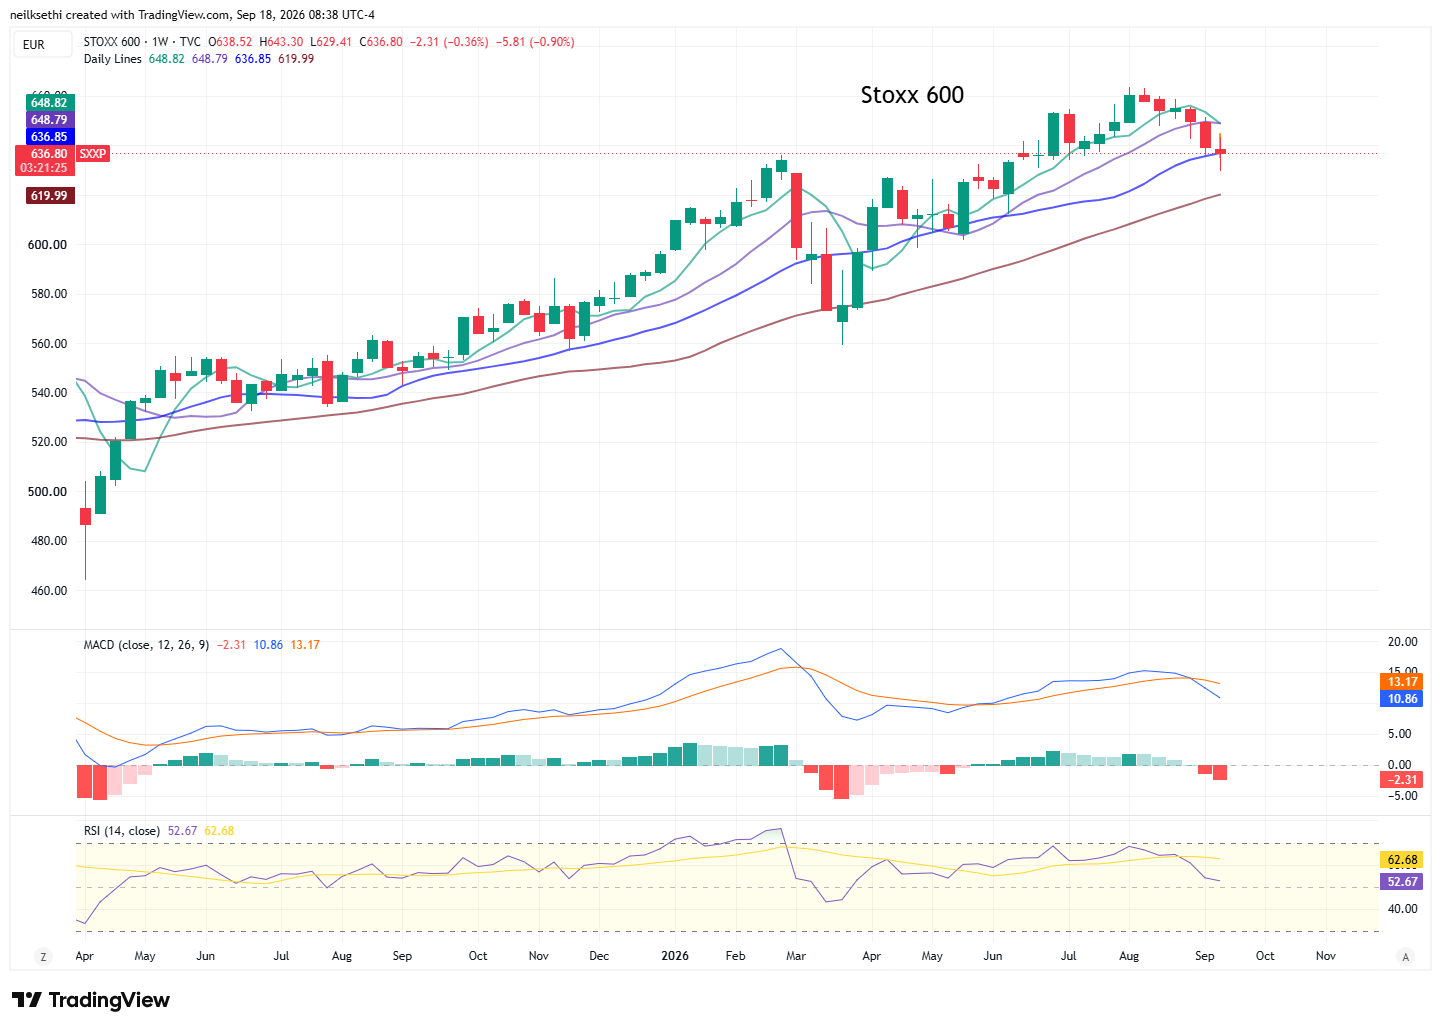
Europe’s benchmark STOXX 600 as of 8:35 am ET was -0.9% giving back all of Thursday’s gains, on track for its fifth down week in six.
Germany’s DAX: -0.9%, U.K.’s FTSE 100: -0.8%, France’s CAC 40: -0.9%, Italy’s FTSE MIB: -1.2%, Spain’s IBEX 35: -1.1%.
Weekly chart
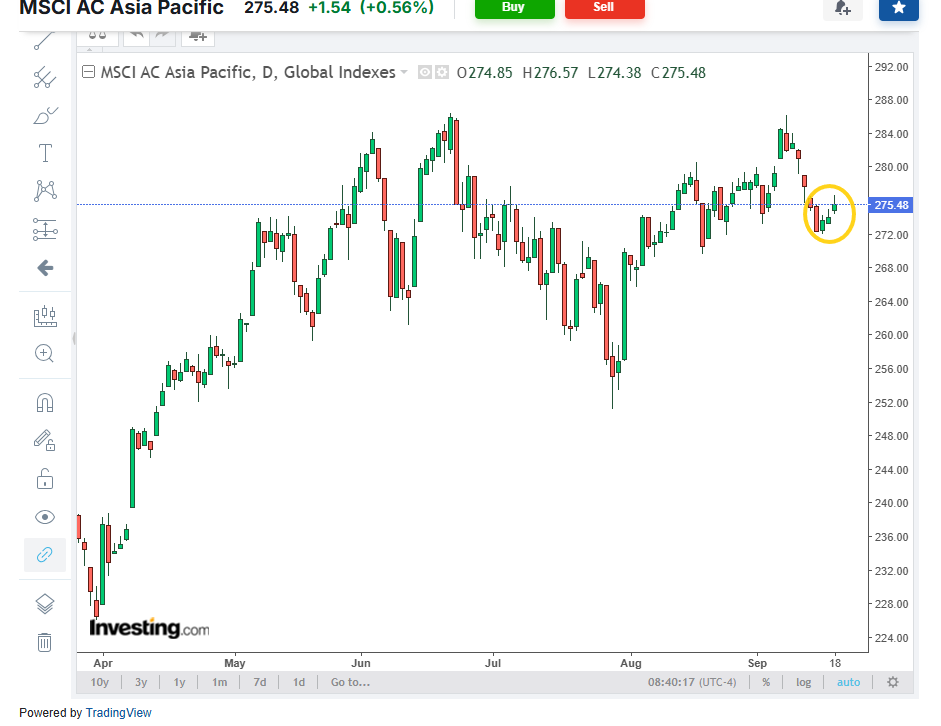
The broad MSCI AC Asia Pacific Index saw a third day of rebound +0.6% to end the week as chip makers including SK Hynix rose, sending the Kospi and other indexes higher. Still it was on track for a second lower weekly close.
Japan’s Nikkei: +1.4%, Hong Kong’s Hang Seng: +0.6%, China’s Shanghai Composite: +0.9%, India’s Sensex: UNCH, South Korea’s Kospi: +2.7%, Australia’s ASX All Ordinaries: +0.1%.
Some Ex-US Highlights
- BBG – The US is expected to delay the announcement of new tariffs over allegations of trading partners’ excess manufacturing capacity at least until after next week’s planned summit between Presidents Xi Jinping and Donald Trump, according to people familiar with the matter.
- Axios – President Trump told Axios Thursday that he’s approaching a critical juncture in the Iran war over whether to restart massive attacks in an effort to bring the conflict to a close.
- FT – Iran activates land routes to bypass US blockade. Donald Trump’s naval campaign deepens Tehran’s trade reliance on land neighbours such as Turkey.
- BBG – German Chancellor Friedrich Merz said the era of “unconditional” ties between the US and Europe built since World War II is over, at least for now, the latest pronouncement of a breakdown in relations under Donald Trump’s presidency.
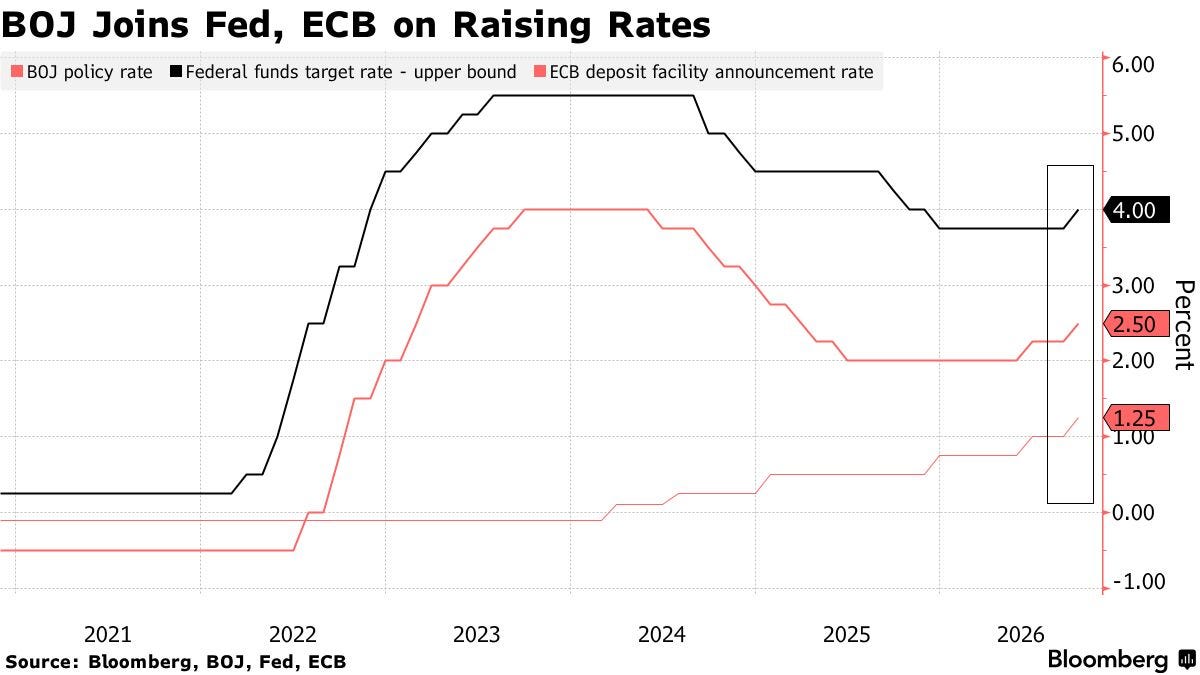
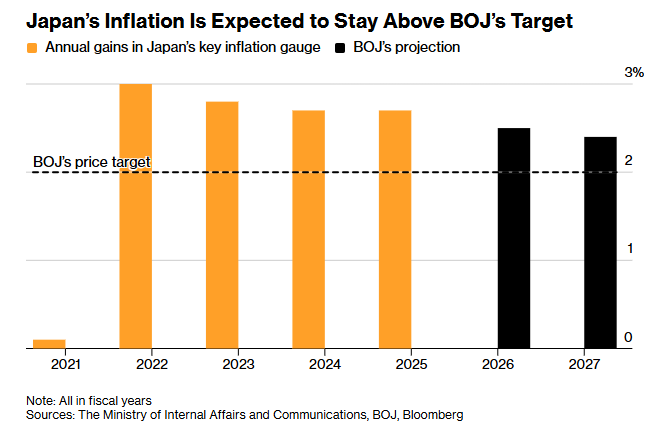
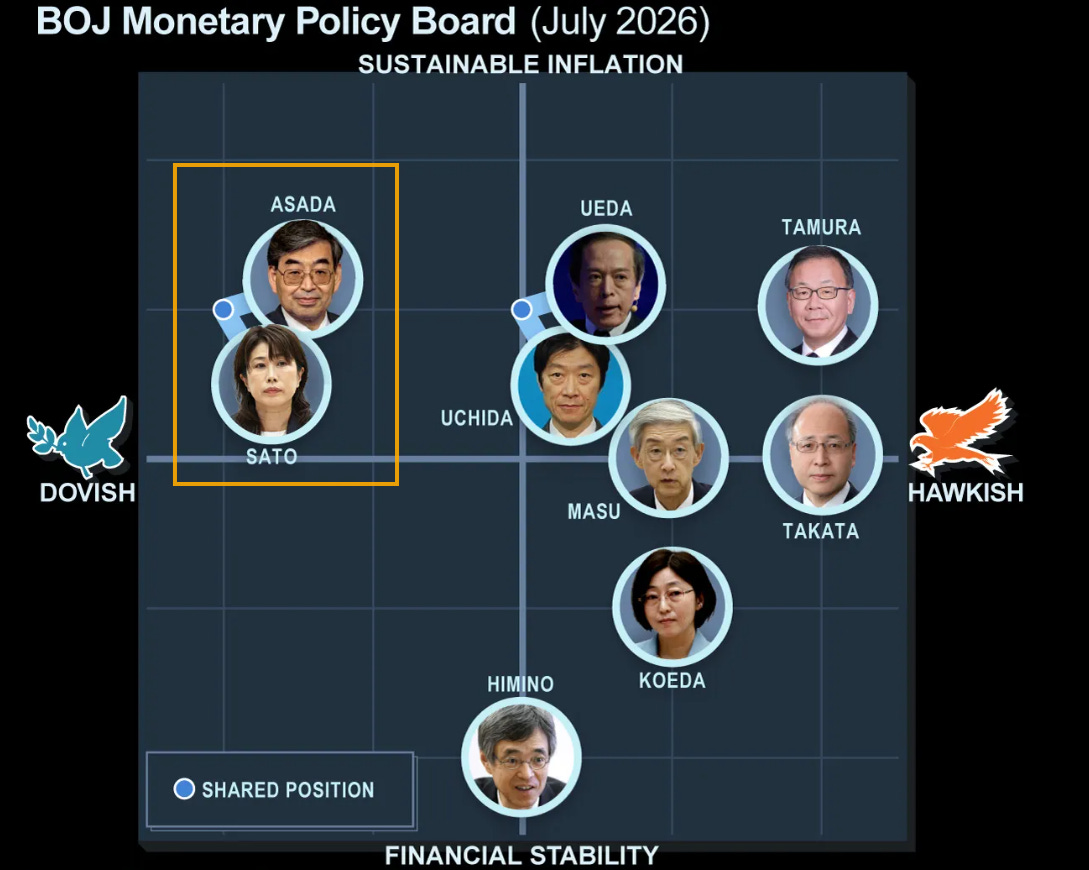
- The yen is on track for its largest one-day weakening vs the dollar this year as the decision from the Bank of Japan and the follow-up press conference from Governor Ueda did not clear the hawkish bar. As a side note, according to BBG, this is the first month ever that the Fed, ECB, and BoJ have raised rates in the same month.
- BBG – European Union officials insist they need to see a credible effort from China to rebalance its trade relationship with the bloc by next month or they will use all “tools” at their disposal to fix the situation.
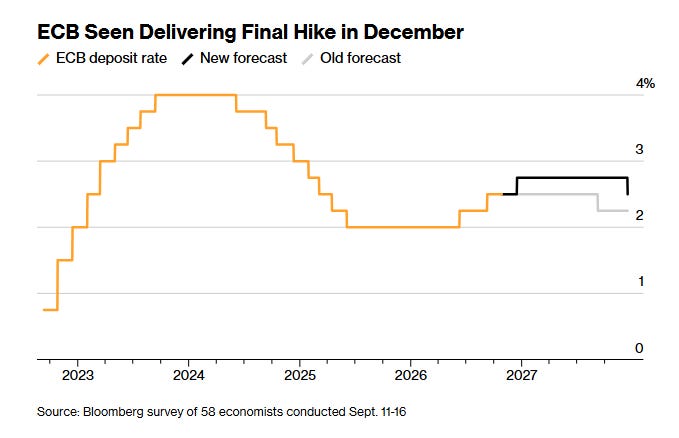
- BBG – The European Central Bank will wait until December before delivering a final interest-rate increase to quell inflation triggered by conflict in the Middle East, according to economists.
- RTRS – Bank of England Governor Andrew Bailey said on Thursday the outlook was too unpredictable when asked whether markets were right to price in almost four interest rate hikes over the next year, adding that his officials had not discussed that.
- BBG – The State Department notified Congress that it plans to sell Saudi Arabia up to 48 F-35 warplanes in a first-time sale that could be worth as much as $24.3 billion.
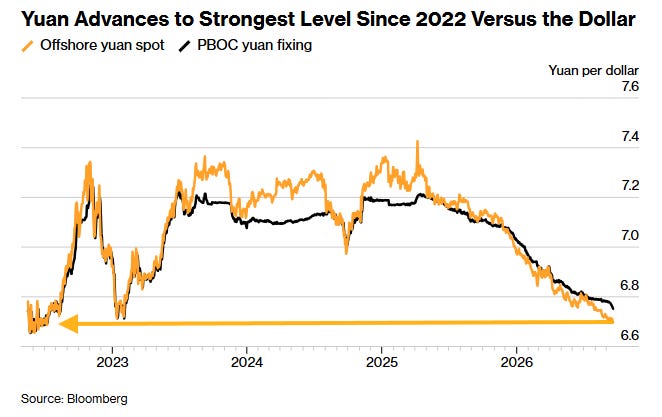
- BBG – The yuan climbed to its highest level against the dollar in more than four years, extending an advance underpinned by broad Chinese export strength and support from the central bank.
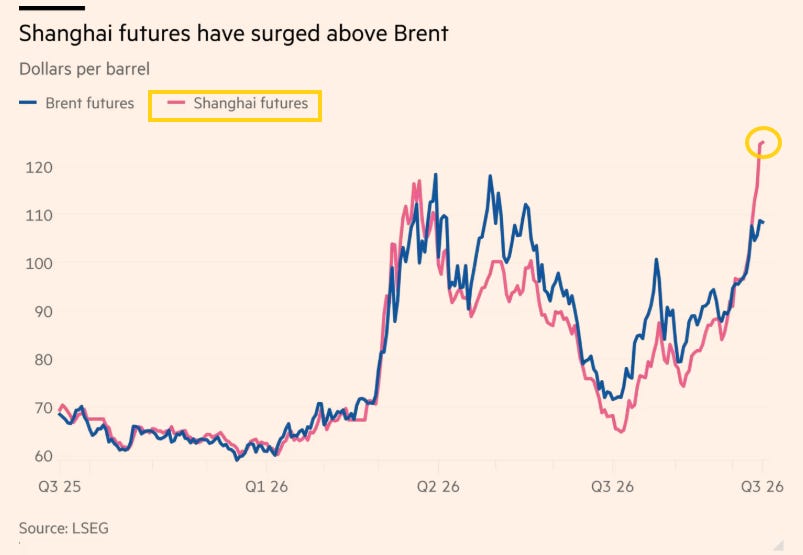
- I mentioned yesterday that Reuters reported that China had reached out to Tehran at Saudi Arabia’s request to urge them to slow the aggression of the Houthi militants threatening Saudi oil exports around the Bab el-Mandeb Strait. Perhaps it was in part due to the impact the news had on prices the Chinese were paying as the FT reports.
- FT – Chancellor John Healey will on Friday urge EU finance ministers to avoid repeating the mistakes of a failed defence partnership with the UK and to design the bloc’s “Made in Europe” industrial policy to include Britain.
- FT – France’s minority government has said it aims to reduce the country’s deficit next year by proposing a budget that includes a €54bn savings drive, paving the way for a showdown with parliament that could lead to its collapse.
- FT – Ulf Kristersson has resigned as Sweden’s prime minister after his centre-right coalition was defeated by the leftwing opposition in the country’s closest ever election. The final tally, released on Thursday after four days of counting, gave the leftwing bloc led by former prime minister Magdalena Andersson 176 seats to 173 for Kristersson’s rightwing bloc. “The election result has created a complicated situation for the formation of the next government, as parties’ different statements before election day could pose obstacles for any potential prime minister or coalition,” Kristersson wrote to the Speaker.
As a reminder, if you do put a comment in for me on a post please be sure to put @NeilSethi in front.