The Best Argument to Buy Alphabet and Meta Now
Here’s why I initiated a position in Alphabet and added to Meta after their selloffs.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Shares of Alphabet (GOOG, GOOGL) were crushed on Thursday, after the tech giant posted a huge miss on third-quarter earnings. As a result, Alphabet had one of its worst days ever on the market, as shares tumbled 12.5%.
Alphabet earned just $2.12 per share, far below estimates of about $2.95. Revenues of $127.5 billion for the quarter were slightly below analysts’ estimates of $128 billion.
Analysts were looking for about $65 billion in search revenue, but Alphabet only produced $63.4 billion. Consumers are increasingly bypassing traditional search engines in favor of AI-based queries, resulting in fewer ad clicks. It’s a trend that’s likely to continue.
Reasonable Valuation
The good news is that Thursday’s selloff places Alphabet at a more reasonable valuation.
The Mountain View, CA-based tech giant now trades with a forward price-earnings ratio of about 20. Recently, that figure was near 25. Meanwhile, the large-cap S&P 500’s forward PE is currently near 19.
Alphabet’s trailing 12-month P/E ratio, currently about 15, compares well to the S&P 500’s trailing 12-month P/E ratio of about 24.
Charting Alphabet
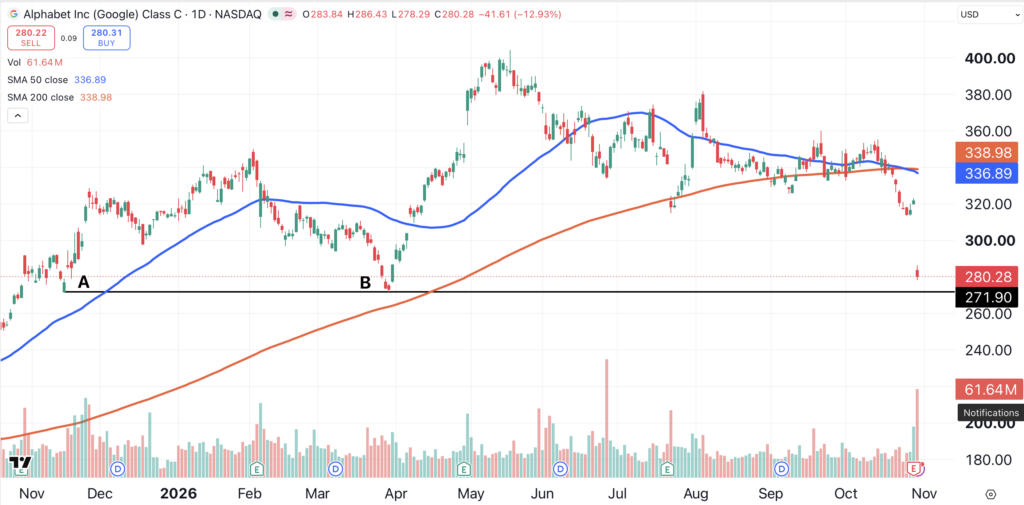
Alphabet has a support level nearby at $271, which matches the stock’s 52-week low (black line). The stock bounced sharply from that level in November of last year (point A), and in March of this year (point B).
We’re opening a small position in Alphabet at current levels. If the stock falls below support at $271, we’ll reevaluate our position.
Adding to Meta Platforms
Meta Platforms (META) has filled the gap left behind from September 9 (point A). We were able to add to our long position in Meta below $625 (point B), as part of the strategy indicated here. This gives us a cost basis of about $630.
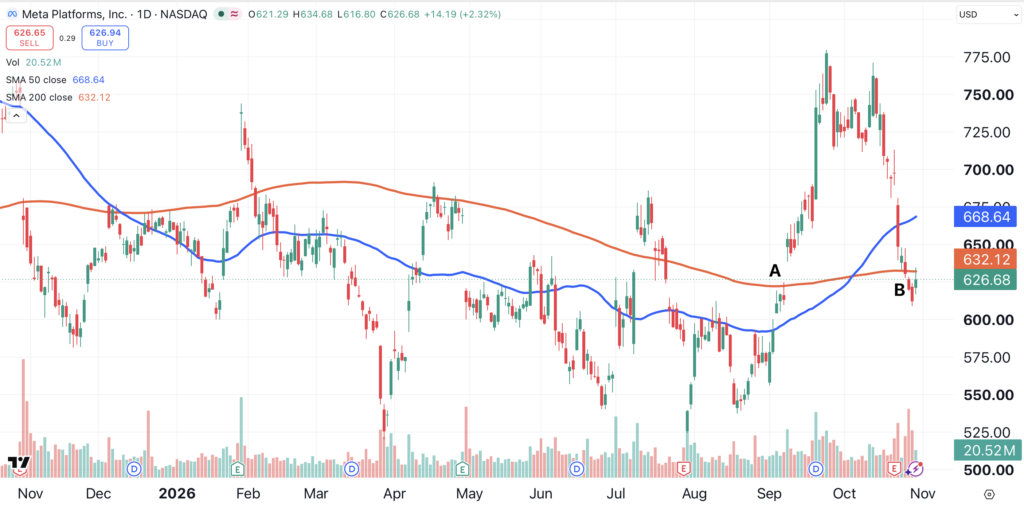
Meta currently trades with a forward P/E ratio of about 18, and a trailing 12-month P/E ratio of about 21. Both figures show the social media and tech giant trading at a reasonable valuation when compared with the overall market.
Bottom Line
The reasonable valuations of Alphabet, Meta Platforms, and other tech leaders remains the best argument as to why the current market, despite its heroic gains, has little in common with the dot-com bubble of the late 90’s. Back then, market leaders like Microsoft (MSFT) and Intel (INTC) saw their P/E ratios climb above 50, while Cisco Systems (CSCO) saw its valuation rise well above 100x earnings.
At the time of publication, Ponsi was long GOOG and META.