Amazon Shares Down as Cash Burn Accelerates
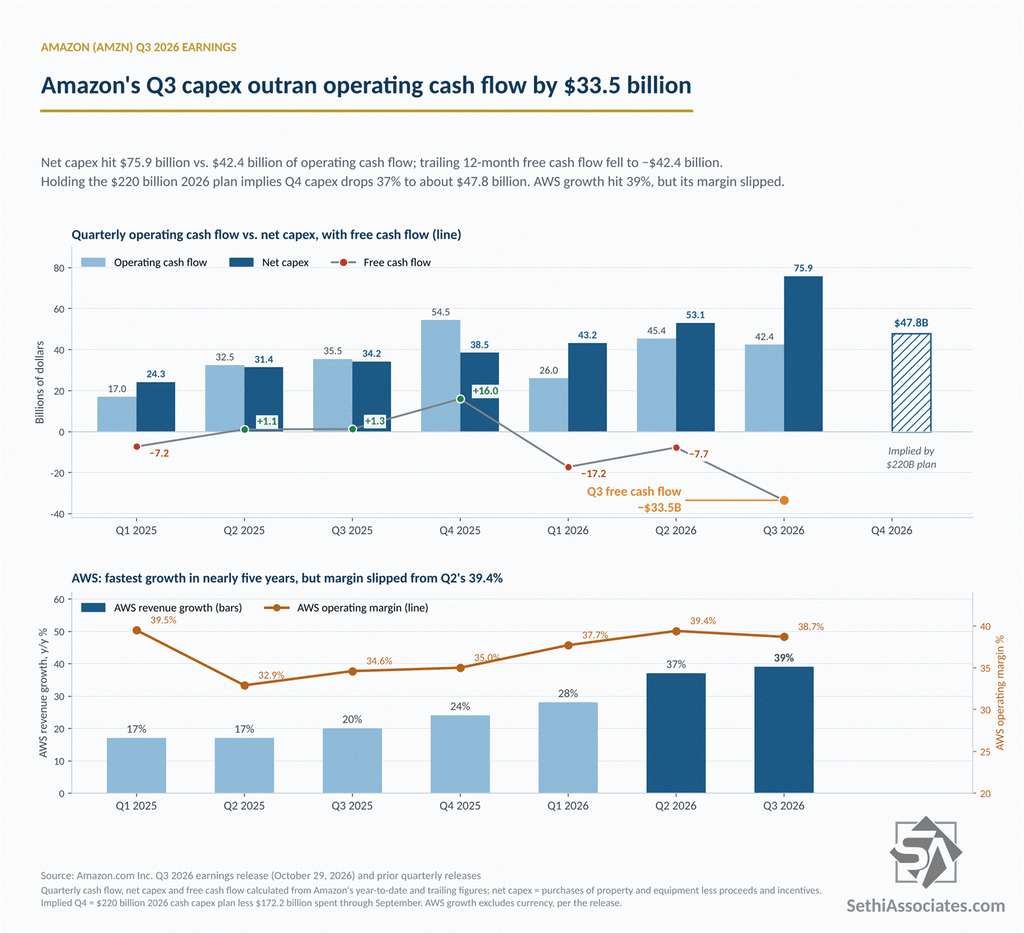
Amazon (AMZN) shares are down by nearly 6% after hours after the company missed on both the top and bottom lines, per TipRanks, even as Amazon Web Services posted its fastest growth in nearly five years. The bigger story is cash: Amazon spent $75.9 billion on capital expenditures, net of proceeds and incentives, in the third quarter against $42.4 billion of operating cash flow, a $33.5 billion quarterly cash burn.1 The stock had already fallen in the regular session to close at $243.79, per Bloomberg.
Revenue, Operating Income and EPS
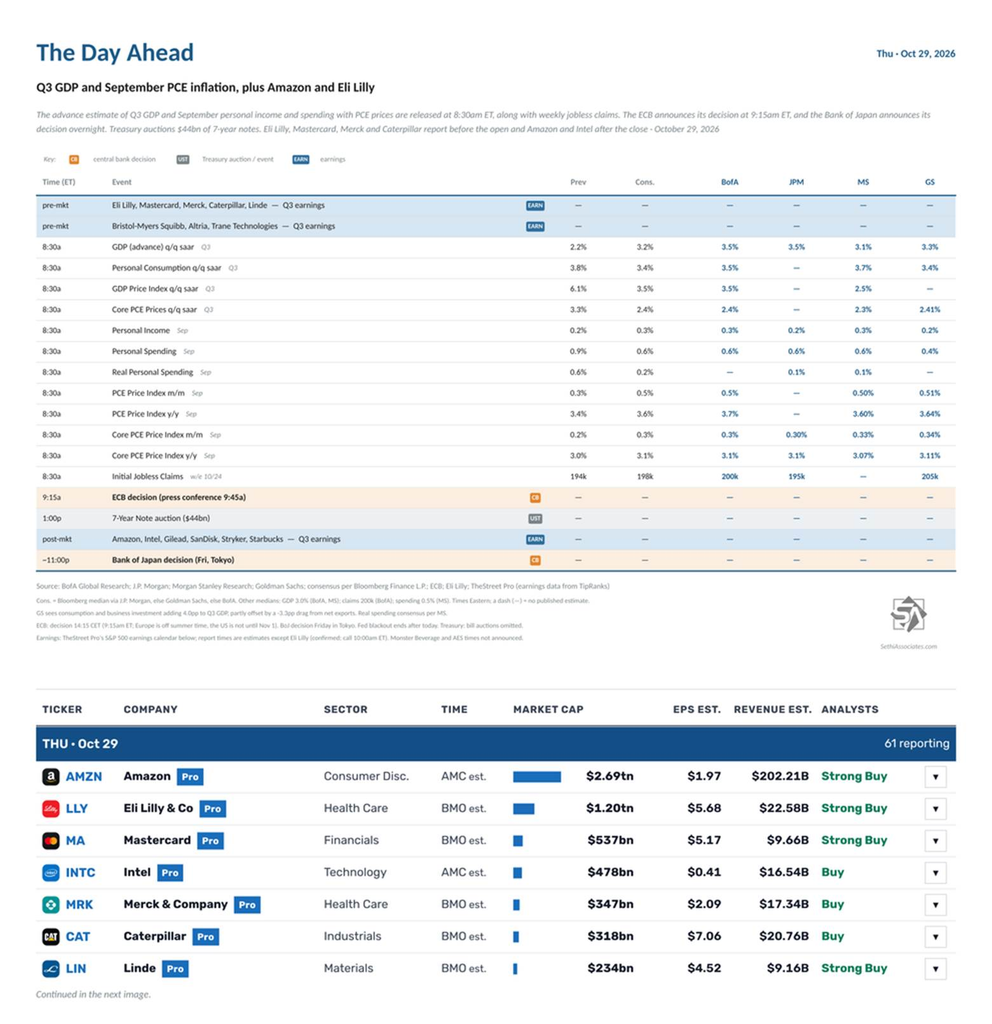
Net sales rose 12% (13% excluding currency) to $201.9 billion, per Amazon’s earnings release, just under the top of the company’s $197 billion to $202 billion guidance range and short of the $202.31 billion consensus cited by TipRanks.
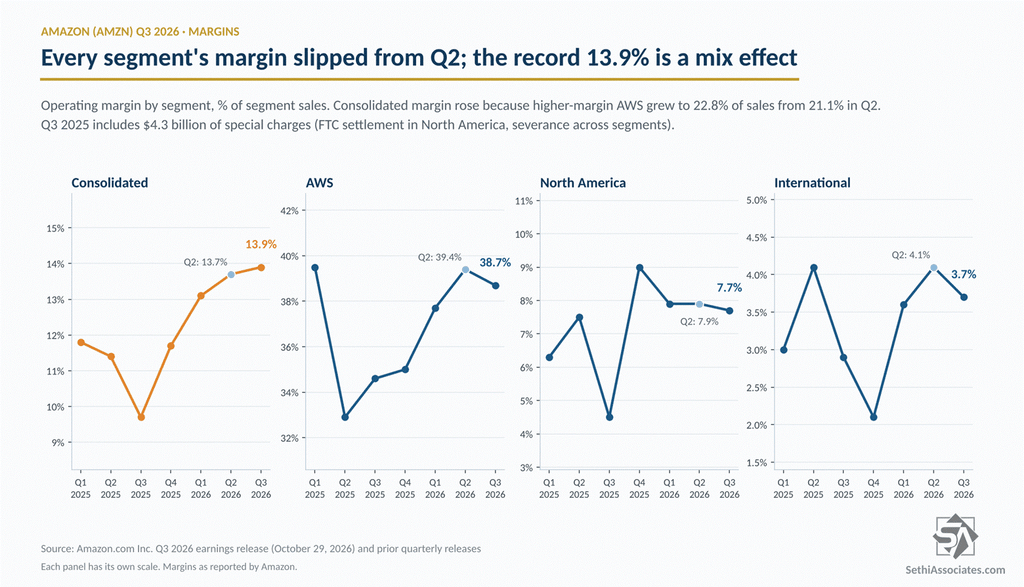
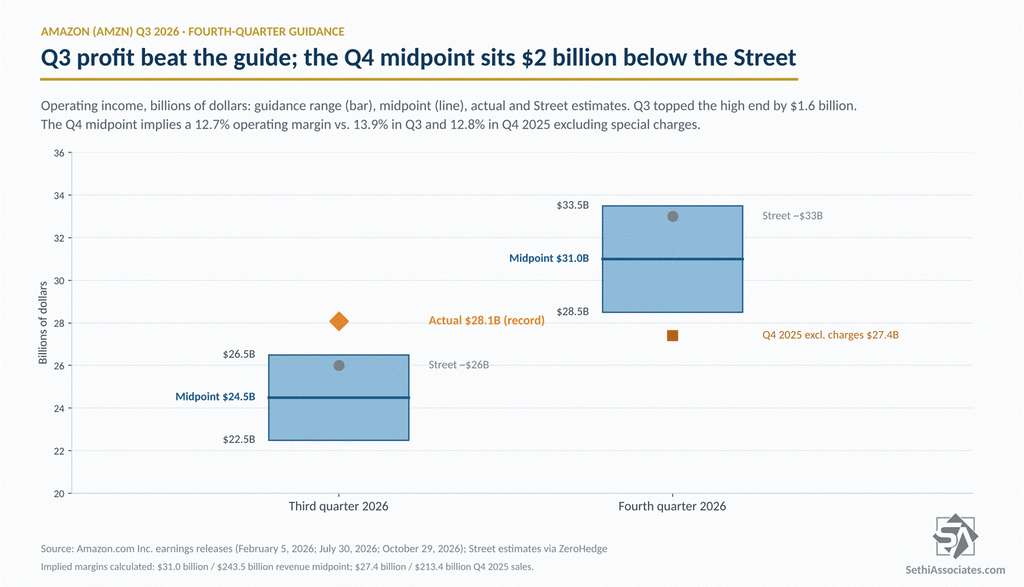
The miss on earnings was despite record operating income of $28.1 billion, a 13.9% margin that Amazon called its highest ever. That cleared the top of the $22.5 billion to $26.5 billion guidance range by $1.6 billion and beat the roughly $26 billion Street estimate, though it only matched the roughly $28 billion buyside whisper, per ZeroHedge.
That said the 61% year-over-year jump in operating income overstates the improvement. The year-ago quarter carried a $2.5 billion charge for the FTC settlement and $1.8 billion of severance, per Amazon’s third-quarter 2025 release. Against that quarter’s $21.7 billion figure excluding charges, operating income rose 29%.4 North America’s 82% gain shrinks to 19% against its $7.3 billion figure excluding the FTC charge.4
Earnings per share of $1.89 missed the $1.96 consensus, per TipRanks. The EPS miss came below the operating line: non-operating items were a $1.2 billion drag, including a tripling of interest expense to $1.7 billion, which now exceeds Amazon’s $1.2 billion of interest income, and a $703 million loss in other income, versus a $10.7 billion gain a year earlier when Amazon booked $9.5 billion of pre-tax gains on its Anthropic stake.
AWS Remains the Growth Driver
AWS accounted for 59.6% of the $21.8 billion year-over-year revenue increase, with North America contributing 30.2% and International 10.2%.2 AWS rose to 22.8% of total sales from 18.3% a year earlier, while North America fell to 55.9% from 59.0% and International to 21.3% from 22.7%.2 Excluding AWS, revenue grew 6.0%.2
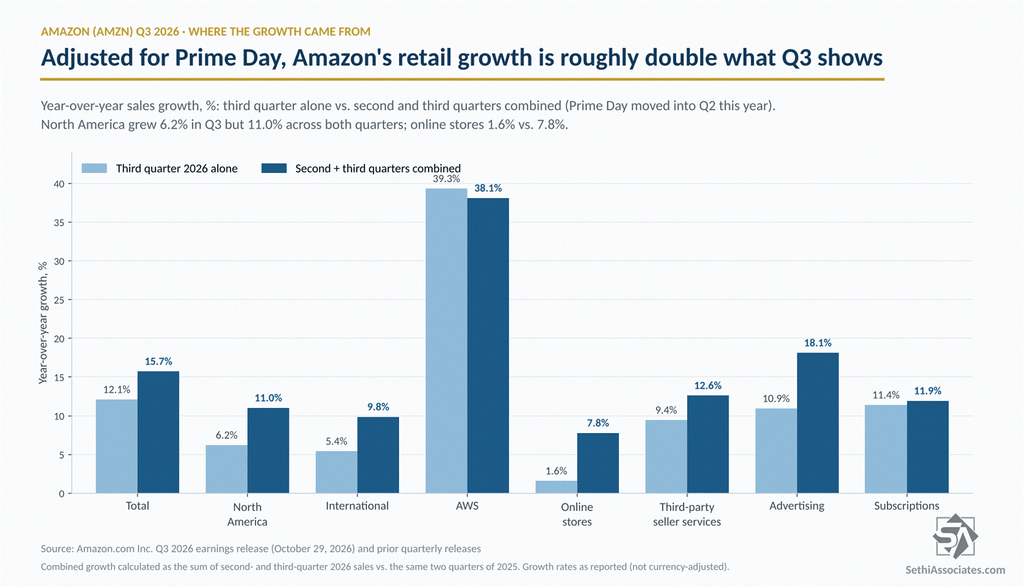
The Prime Day shift distorts the year-over-year comparison. Amazon held Prime Day in the second quarter in most large countries this year, versus entirely in the third quarter in 2025, and said third-quarter growth would have been about 400 basis points higher without the shift. Combining the second and third quarters to wash out the timing, total revenue rose 15.7%, North America 11.0%, International 9.8% and AWS 38.1%.3 Adjusted for Prime Day, the retail business is growing closer to 11% than 6%.3
Margins
Sequentially, all three segment margins slipped: AWS to 38.7% from 39.4%, North America to 7.7% from 7.9% and International to 3.7% from 4.1%. Operating margin outside AWS was 6.6%, down from 6.8% in the second quarter but up from 4.1% a year ago.2 The record consolidated margin is a mix effect: it edged up because higher-margin AWS rose to 22.8% of sales from 21.1% in the second quarter.2
But AWS Lagged Its Peers
AWS revenue rose 39.3% to $46.0 billion, beating the $45.29 billion consensus, per TipRanks, and accelerating from 37% in the second quarter. It still fell short of the roughly 42% the buyside was looking for, per ZeroHedge. AWS operating income rose 55% to $17.8 billion, and CEO Andy Jassy said Amazon is projecting AWS “revenue growth rates of over 40% both in 2027 and in 2028.”
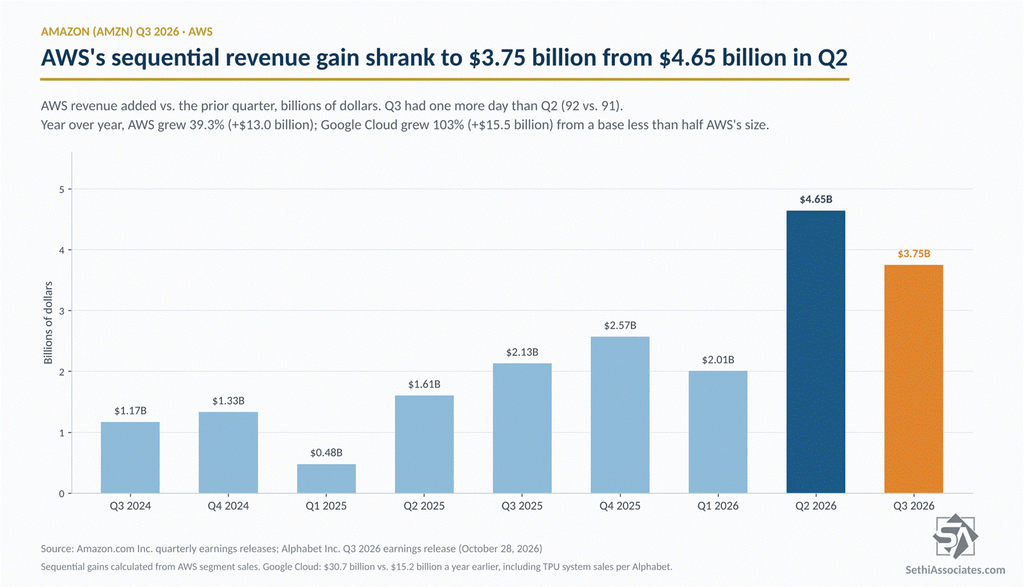
Two numbers look weaker under the beat. AWS added $3.75 billion of revenue sequentially, down from $4.65 billion in the second quarter, despite the third quarter having one more day.5 And its operating margin slipped 0.7 percentage point to 38.7%, against a buyside hoping for the low 40s, per ZeroHedge citing UBS.
For comparison, Microsoft’s (MSFT) Azure grew 48% and Alphabet’s (GOOGL) Google Cloud grew 103% to $30.7 billion, per Alphabet’s release, a figure that includes TPU system sales. Google Cloud added about $15.5 billion of revenue year over year, more than AWS’s $13.0 billion, from a base less than half the size.6
Advertising and Retail
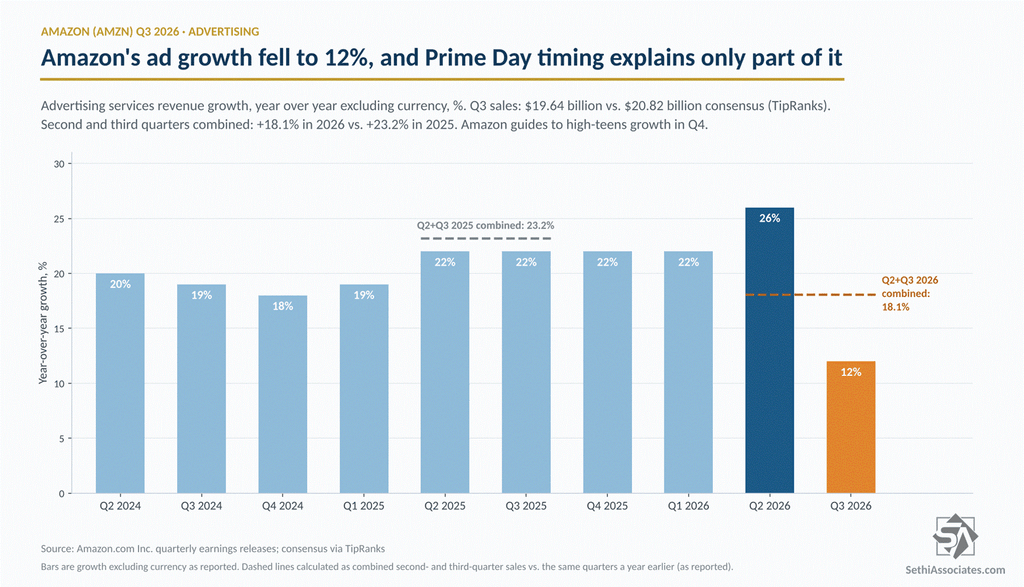
Advertising revenue rose 11% (12% excluding currency) to $19.64 billion, missing the $20.82 billion consensus by 5.7%, per TipRanks, and slowing from 26% growth in the second quarter.7 Amazon blamed “timing anomalies primarily related to Prime Day” and guided to high-teens growth in the fourth quarter. Even washing out Prime Day, advertising grew 18.1% across the second and third quarters, down from 23.2% over the same stretch of 2025.3
Online stores sales rose 1.6% (2% excluding currency) to $68.5 billion, below the $69.68 billion FactSet estimate cited by MarketWatch, while third-party seller services grew 9%. North America sales rose 6% to $112.9 billion, also below the $113.2 billion forecast, per MarketWatch.
Capex and Free Cash Flow
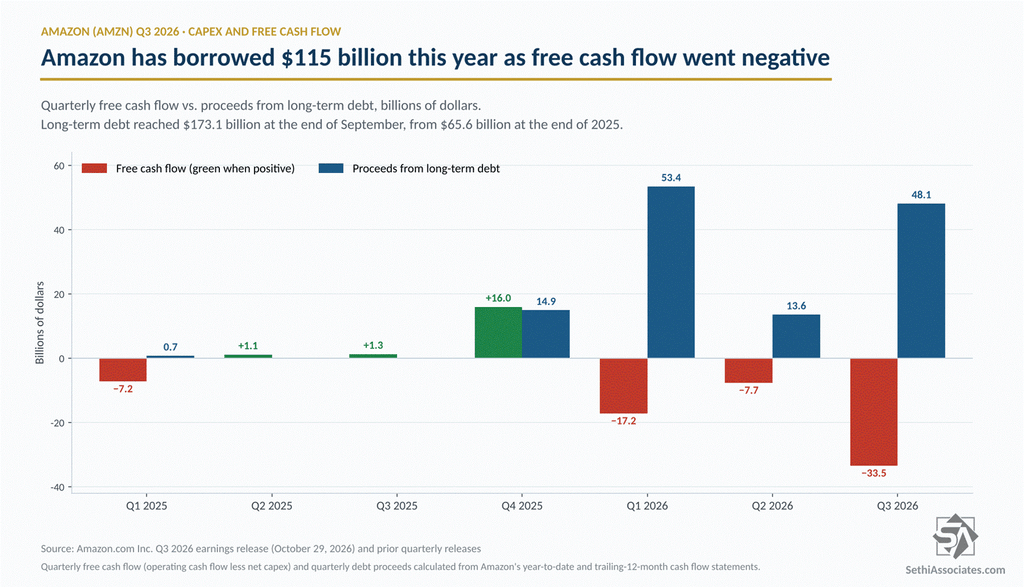
Purchases of property and equipment were $77.3 billion in the quarter, or $75.9 billion net of proceeds and incentives, far above analyst estimates, per Bloomberg. Net capex rose 43% from $53.1 billion in the second quarter and more than doubled from $34.2 billion a year earlier.1
That left a free cash outflow of $33.5 billion for the quarter,1 versus the $7.7 billion outflow Bloomberg consensus expected, per ZeroHedge. On the trailing 12-month basis Amazon reports, free cash flow fell to an outflow of $42.4 billion from an outflow of $7.6 billion in the second quarter and an inflow of $14.8 billion a year earlier.
Amazon said it continues to expect about $220 billion of 2026 cash capex. With $172.2 billion already spent through September, that implies about $47.8 billion in the fourth quarter, 37% below the third quarter.1 So either fourth-quarter capex falls 37% from the third quarter even as Amazon says demand still exceeds supply, or the $220 billion plan gets exceeded. Amazon gave no 2027 figure; Evercore ISI forecasts $320 billion, per MarketWatch. Cash capex also leaves out $26.8 billion of property and equipment acquired but not yet paid for over the trailing 12 months, plus $4.5 billion acquired under finance leases.
Debt is funding the gap. Amazon raised $48.1 billion of long-term debt in the quarter and $115.1 billion year to date, lifting long-term debt to $173.1 billion from $65.6 billion at the end of 2025. Cash and equivalents fell to $55.8 billion from $86.8 billion, though including marketable securities, liquidity fell a more modest $8.8 billion to $114.2 billion.
Fourth-Quarter Guidance
Amazon guided fourth-quarter net sales to $240 billion to $247 billion, up 12% to 16%, including about 60 basis points of currency drag. The $243.5 billion midpoint is just below the $244.17 billion FactSet consensus cited by MarketWatch.
Operating income guidance of $28.5 billion to $33.5 billion has a $31.0 billion midpoint, below the roughly $33 billion Street estimate, per ZeroHedge. The midpoint implies a 12.7% operating margin, below the third quarter’s 13.9% and roughly flat with the 12.8% of last year’s fourth quarter excluding special charges.8 Against last year’s $27.4 billion fourth-quarter figure excluding charges, per Amazon’s fourth-quarter 2025 release, the midpoint is up 13%.8
Despite the misses, TipRanks shows a Strong Buy consensus among 44 analysts, with an average price target of $331.54.
Notes
1 Calculated from Amazon’s cash flow statements. Net capex is purchases of property and equipment ($77.26 billion in the third quarter; $54.21 billion in the second) less proceeds from sales and incentives ($1.38 billion; $1.13 billion). Quarterly free cash flow is operating cash flow ($42.42 billion) less net capex ($75.88 billion). Implied fourth-quarter capex is $220 billion less nine-month net capex of $172.19 billion.
2 Calculated from Amazon’s segment information.
3 Calculated as combined second- and third-quarter sales versus the same two quarters a year earlier (2025 versus 2024 for the advertising comparison).
4 Calculated using the figures excluding charges in Amazon’s third-quarter 2025 release.
5 Calculated from AWS segment sales: $45.98 billion in the third quarter, $42.23 billion in the second and $37.59 billion in the first.
6 Calculated: Google Cloud revenue of $30.7 billion versus $15.2 billion a year earlier; AWS $45.98 billion versus $33.01 billion.
7 Calculated: $19.64 billion actual versus $20.82 billion consensus.
8 Calculated: $31.0 billion divided by the $243.5 billion revenue midpoint; $27.4 billion divided by $213.4 billion fourth-quarter 2025 sales.
Conversation 0 Comments
One ongoing discussion across all days. Everyone can read; sign in to take part.
Your voice matters. Discussions are moderated for civility. Read our guidelines .
Log in to join the conversation