A Lighter Thursday Schedule in the U.S.
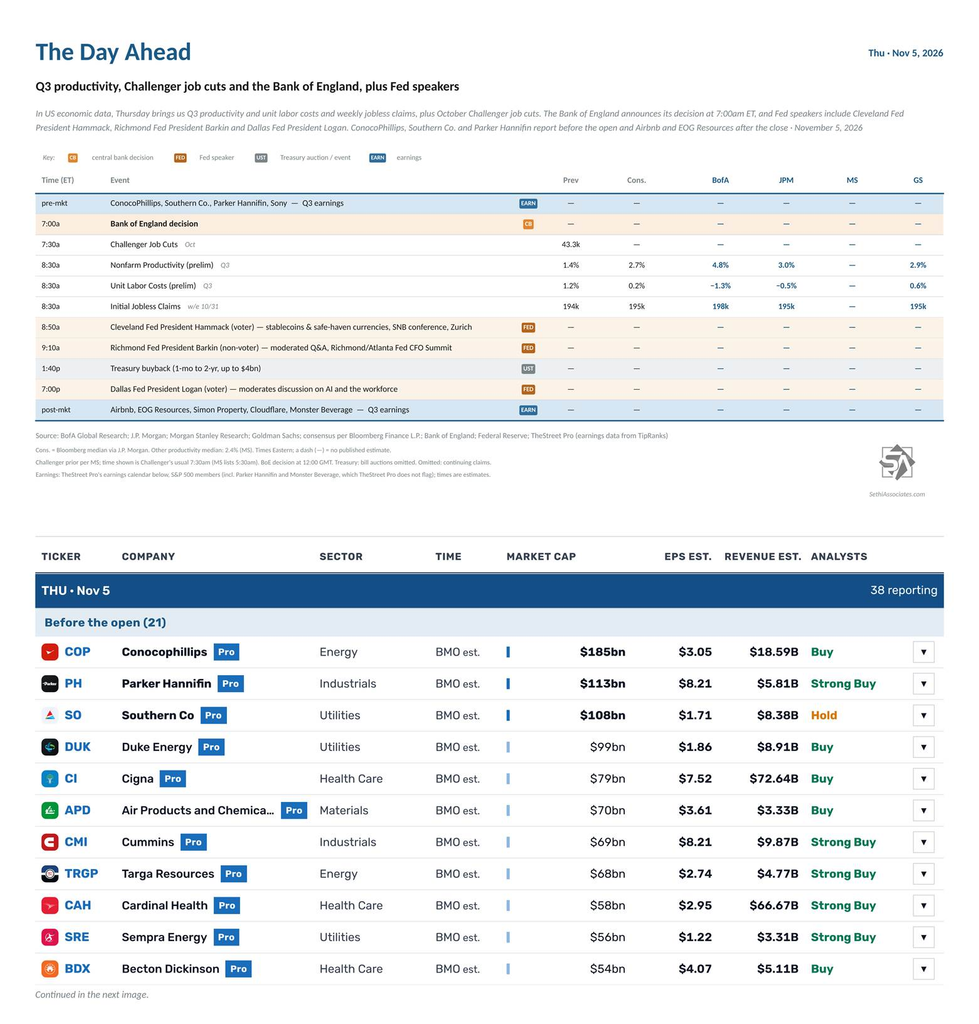
In U.S. economic data, Thursday brings us Q3 productivity and unit labor costs, plus October Challenger job cuts/hires. We’ll also get the weekly unemployment claims.
Cleveland Fed President Hammack (voter) speaks on stablecoins and safe-haven currencies in Zurich at 8:50am ET, Richmond Fed President Barkin (non-voter) participates in a moderated Q&A at 9:10am ET, and Dallas Fed President Logan (voter) moderates a discussion on AI and the workforce at 7pm ET.
The Bank of England announces its decision at 7am ET.
There are no non-Bill (>1yr in maturity) U.S. Treasury auctions, but Treasury holds a buyback of up to $4 billion of 1-month to 2-year securities at 1:40pm ET.
Also, a White House committee is scheduled to hold a closed hearing on allegations against Fed Governor Lisa Cook and whether there’s cause for her removal, per Bloomberg (via @C_Barraud).
38 S&P 500 components report, three of them with market caps over $100bn:
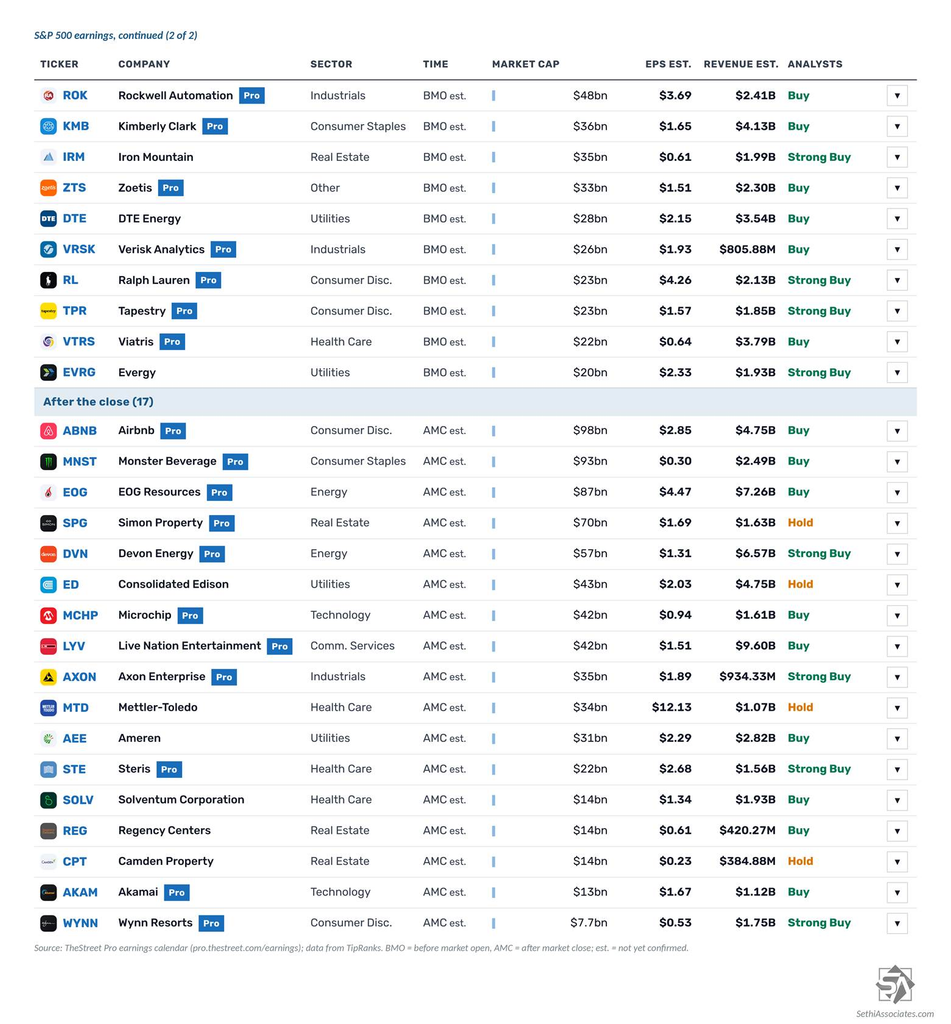
Before the open: ConocoPhillips (COP), Parker Hannifin (PH), Southern Co. (SO), Duke Energy (DUK), Cigna (CI), Air Products (APD), Cummins (CMI), Targa Resources (TRGP), Cardinal Health (CAH), Sempra (SRE), Becton Dickinson (BDX), Rockwell Automation (ROK), Kimberly-Clark (KMB), Iron Mountain (IRM), Zoetis (ZTS), DTE Energy (DTE), Verisk Analytics (VRSK), Ralph Lauren (RL), Tapestry (TPR), Viatris (VTRS) and Evergy (EVRG)
After the close: Airbnb (ABNB), Monster Beverage (MNST), EOG Resources (EOG), Simon Property (SPG), Devon Energy (DVN), Consolidated Edison (ED), Microchip Technology (MCHP), Live Nation (LYV), Axon (AXON), Mettler-Toledo (MTD), Ameren (AEE), Steris (STE), Solventum (SOLV), Regency Centers (REG), Camden Property (CPT), Akamai (AKAM) and Wynn Resorts (WYNN)
Outside the S&P 500, Sony (SONY), National Grid (NGG) and ArcelorMittal (MT) report before the open, Cloudflare (NET) after the close, and Toyota (TM) at a time not yet announced.
Ex-U.S. highlights include U.K. October new car registrations and construction PMI, Japan September labor cash earnings, Germany September factory orders and October construction PMI, France September industrial production, Italy September retail sales, Eurozone September PPI and Sweden October CPI.
Besides the BoE, Norges Bank, Malaysia and Mexico announce rate decisions, ECB President Lagarde speaks, the ECB opens its annual money markets conference, Canada releases its 2026 federal budget and the China International Import Expo begins in Shanghai.
Conversation 0 Comments
One ongoing discussion across all days. Everyone can read; sign in to take part.
Your voice matters. Discussions are moderated for civility. Read our guidelines .
Log in to join the conversation