Weekly Roundup: Renewed AI Concerns Weigh on the Market and Portfolio
We added to six holdings, and upgraded and lifted a price target on another as favorable AI data conflicted with market emotion.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
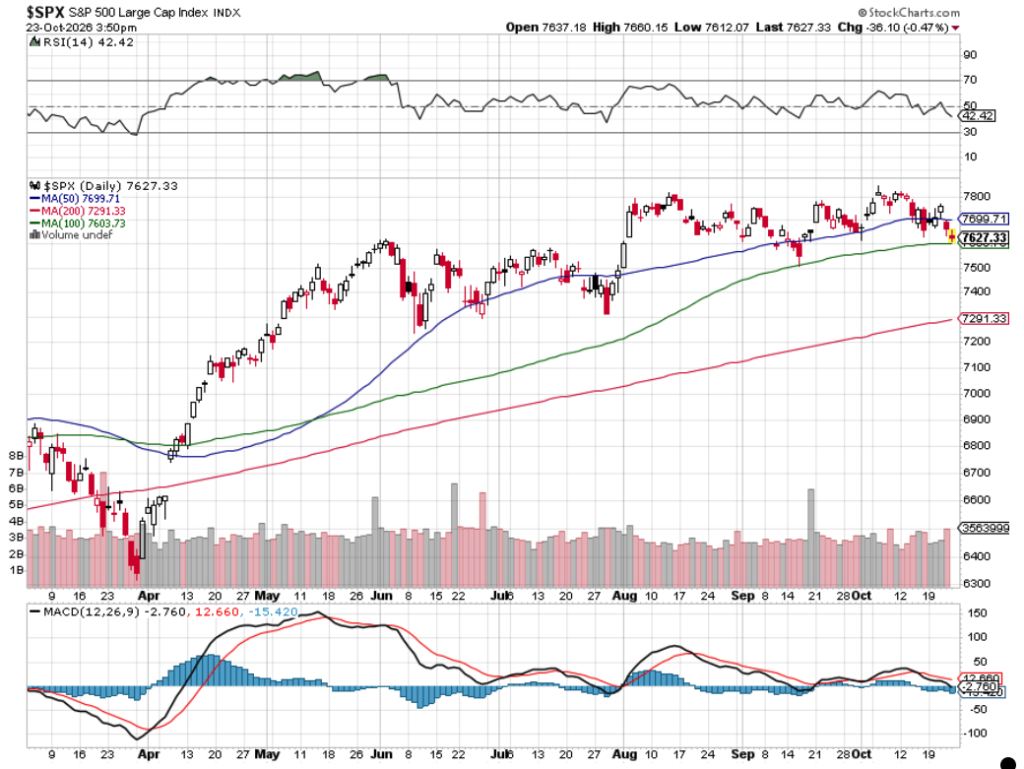
A confluence of factors weighed on the market and Portfolio this week, with the S&P 500 tumbling below its 50-day moving average. Renewed concerns over AI infrastructure funding following upsized capital spending from SpaceX (SPCX), Meta (META) and Anthropic weighed on the Tech sector. Those concerns overshadowed numerous data points for AI infrastructure demand exceeding supply and pushed the Nasdaq Composite below its 100-day moving average.
We saw similar dynamics in 2025 and earlier this year, and the smart call was to follow the data while keeping the market’s emotional reactions in check. During those periods of conflicting favorable data and market emotion, characterized by Extreme Fear on the Fear & Greed Index and elevated readings for the Volatility Index, like we have now, the right move was to cautiously put capital to work.
We did some of that this week, but because we see several hurdles ahead that could keep the market volatile, our moves were modest in size. Those hurdles include the sea of earnings reports next week and the week after, the Fed’s policy decision that will likely bring incrementally hawkish comments, the U.S. midterm elections, prospects for renewed fighting between the U.S. and Iran, and possibly several significant equity offerings.
Depending on your perspective, market volatility can be painful, or it can bring opportunity to buy well-positioned companies at better stock prices. Fortunately for us, even though we have taken some bruising in the last two weeks, we raised the Portfolio’s cash levels. Even after the aggregate moves we made last week and this week, the Portfolio’s cash level stands around 10% of its assets. That gives us ample room to maneuver with about a dozen of our existing holdings as well as room for a new one or two.
As more companies report next week, we will continue our dot-connecting exercises, but we will also be mindful of the S&P 500 and where it is trading relative to its 100-day moving average. Should we see that index push below that support level of a sustained basis, the next support level is more than 4% lower near 7291, which is the 200-day moving average. With that in mind, if the 100-day support level fails to hold, the prudent move would be to boost our cash levels further.
Next week is shaping up to be a big week for the market, but we’ll be here to guide you through it. Enjoy your weekend and Saturday’s Signals alert, and we’ll see you back here, bright and early Monday.
Catching Up on the Portfolio This Week
With both the S&P 500 and the Nasdaq Composite falling week over week, it won’t come as a surprise the Portfolio did the same. Week-to-week gains in shares of Apple (AAPL), Axon (AXON), the First Trust Nasdaq Cybersecurity ETF (CIBR), Palantir (PLTR), Waste Management (WM) and other non-Tech holdings, were offset by the continued pressure on the Tech sector.
Meta (META) was the biggest drag on the Portfolio following its Q3 2026 results and market chatter about an equity offering that could approach $40 billion. Other Tech and Tech-adjacent positions, including Applied Materials (AMAT), Eaton (ETN), and Arista Networks (ANET), outweighed our gainers and other relative S&P 500 outperformers.
The pain in the Tech sector and more specifically AI infrastructure plays rippled through to the EPS All-Stars basket, adding to the strategy’s quarter-to date drag. We’ve gotten some questions about a potential earlier-than-usual reconstitution for the basket, but that would violate the rules and regs of the model. We concede the downturn in the model’s results over the last few weeks has become rather frustrating, but as we look ahead, upcoming quarterly earnings and potential clearing events such as the Anthropic IPO and other capital raises, like one potentially from Meta, should allow the market to get back to focusing on fundamentals. As we discussed with you on Thursday, when we do just that, the outlook for our Tech holdings and EPS All-Star model constituents remains very bright.
During the week, looking to take advantage of the market’s pullback and data points that signaled favorable demand dynamics, we made small buys in several existing positions. On Monday, we added to Boeing (BA), Broadcom (AVGO), Eaton (ETN) and Marvell (MRVL). As we closed out the week on Friday, we made similar-sized moves with Arista Networks (ANET) and Paccar (PCAR). In between those moves, we raised our price target for the First Trust Nasdaq Cybersecurity ETF (CIBR) and lifted our rating on those shares to One from Two.
Given the slate of developments coming at us over the next few weeks, the moves we made were designed to leave the Portfolio with ample cash on hand should those developments weigh further on the market. If that comes to pass, we’ll continue to weigh individual stock opportunities against the market backdrop and their technical setups.
Exiting the week, our cash level stands near 10% of the Portfolio’s assets, and we should see a modest increase as Marvell pays its next quarterly dividend on October 29.
Now let’s see what others on Wall Street had to say about the Portfolio’s holdings during the week:
Monday: Wells Fargo raised its target on Welltower (WELL) to $268 from $266, and Bernstein made a similarly modest increase on Microsoft (MSFT), to $662 from $660. KeyBanc moved the other way on Alphabet (GOOGL), cutting its target to $410 from $435. Morgan Stanley offered the day’s most notable call, naming Amazon (AMZN) a Top Pick and raising its target to $350. Morgan also lifted its Meta Platforms target to $820 from $775. Morgan Stanley (MS) itself got a slightly lower target from BMO Capital, down $5 to $210 from $215.
Tuesday: Piper Sandler noted federal prime-deal strength and large wins across state and local but lowered its price target on Axon to $561 from $732 and maintained its Overweight rating on the shares. MoffettNathanson lowered its price target on Apple to $283 from $304. Loop Capital downgraded Apple to Hold from Buy with a price target of $330, down from $370. BMO Capital raised its price target on Alphabet to $480 from $465 and took its target for Microsoft to $600 from $515.
Thursday: Mizuho lifted its Meta target to $950 from $750, JPMorgan increased its to $940 from $920, and Evercore adjusted its target by $10 to $870. Tigress Financial initiated coverage of Broadcom with a Buy rating and $600 price target. Citi added $5 to its Palantir target, landing it at $250.
Friday: Piper Sandler bumped up its Palantir target by $1 to $231… interesting and we’re wondering why bother.
Key Global Economic Readings
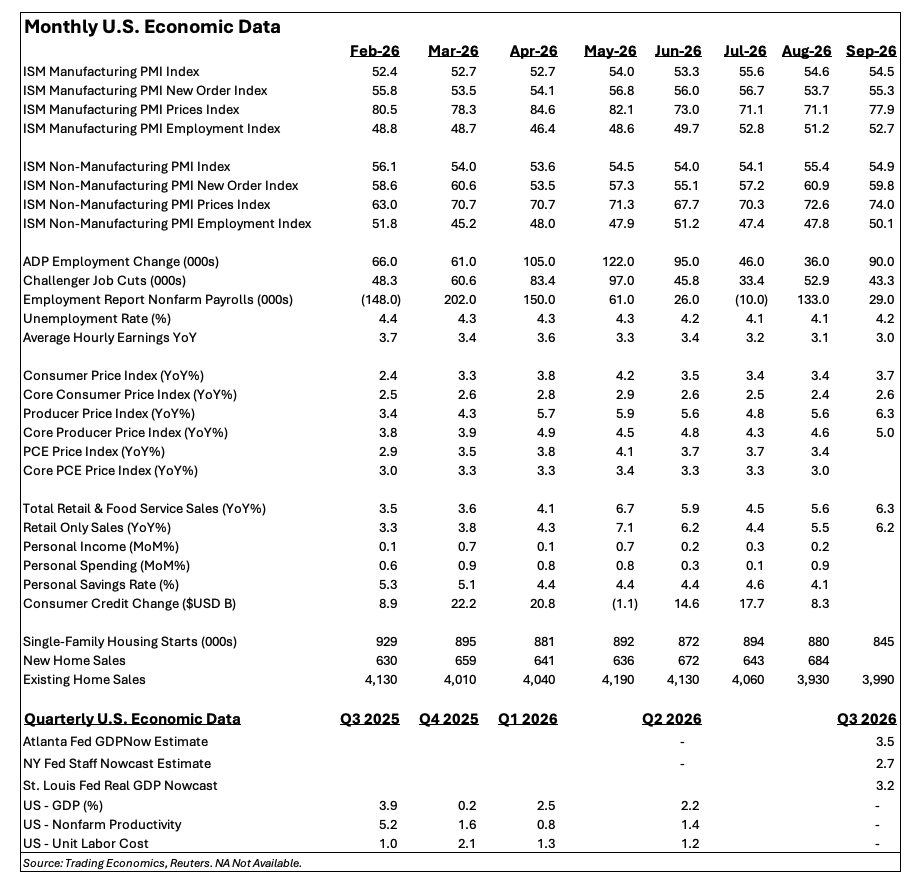
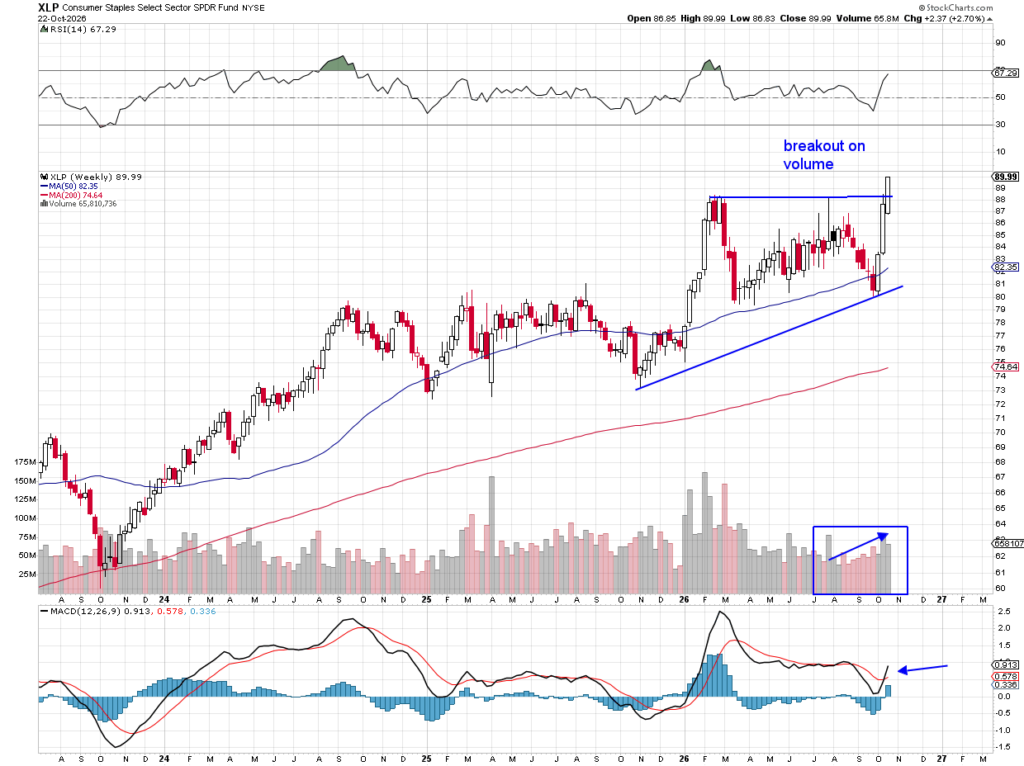
Chart of the Week: State Street Consumer Staples Select Sector SPDR ETF
Searching for where the power is in the stock market? Look no further than Consumer Staples, and that means examining the State Street Consumer Staples Select Sect SPDR ETF (XLP).
This ETF is having a remarkable October, up more than 10% on the month as it leads all groups by a mile. These names are your usual household products and supplies, not your data centers, semiconductors, software or AI-related energy companies. No, this is Walmart (WMT), Procter & Gamble (PG), Coca-Cola (KO), Target (TGT) and Colgate-Palmolive (CL), the boring stuff you find in your grocery aisle.
But sometimes boring can be profitable, and if you’re in these names this month you are certainly very pleased. Investor’s Business Daily (IBD) ranks the top 40 groups each day and most of the Staples groups are in the top 15. That should come as no surprise. You can see from this weekly chart of the XLP the very strong price action over the last three weeks. But the interesting thing is how quiet this move has happened.
Staples are not your big growing companies that are going to lift GDP to new heights, but nobody is talking about them. A 10% rise in a month is highly unusual but not unprecedented. Notice a 14% increase earlier in the year over the first two months of 2026 then a huge drop after the Iran War commenced. Now we see Staples right back up and at new all-time highs, yet financial media seems more obsessed with what is happening (or not) in the AI field.
We like the Staples group as we have Costco (COST) and TJX Companies (TJX), stocks that have participated in the recent runup. Relative strength for the XLP is on the rise and not quite overbought, so there could be more upside. Volume trends are bullish as well, while the MACD just turned bullish confirmed for the first time since late 2025.
Maybe it is time to recognize the stocks that are driving performance for the rest of the stock market, because Staples are not often the leader. Let’s give credit where it’s due.
Other charts we shared with you this week were:
Monday, October 19: S&P 500 – The S&P Is Still Bullish. But for How Long?
Monday, October 19: American Express (AXP) – American Express Shows Some Life
Tuesday, October 20: First Trust Nasdaq Cybersecurity ETF (CIBR) – Cyber Stocks Aren’t Immune to the Sell Button
Wednesday, October 21: Dell (DELL) – Dell Got Hammered. Now We’re Watching for a Potential Entry
Thursday, October 22: Broadcom (AVGO) – Broadcom Looks Bearish. A Time to Buy?
The Week Ahead
Next week will be one of the busiest of the year. Between 179 S&P 500 companies reporting, the Fed’s next monetary policy decision, several pieces of economic data, and whatever develops on the geopolitical front, odds are the market will continue to trade day to day based on the latest developments. We’ll continue to keep our head down, focused on connecting the dots across company reports and factoring the latest data into our thinking.
In terms of economic data, October Consumer Confidence and September Home Sales are out Tuesday.
The Fed is widely expected to leave the Fed Funds rate unchanged Wednesday afternoon, but following the learnings from S&P Global’s Flash October PMI and Q3 2026 earnings season comments thus far, we are likely to hear incrementally hawkish comments from Fed Chair Warsh that afternoon. While expected by us, the risk is those comments fuel market chatter for larger action by the Fed ahead.
Thursday brings a double dose of data, with an advance look at third-quarter GDP and September personal income and spending, including the PCE price index, the Fed’s preferred inflation gauge. As of now both the headline and core PCE price index figures for September are expected to tick higher on a year-over-year basis compared to August. If the initial Q3 2026 GDP print resembles something between the 3.2%-3.5% figures modeled by the Atlanta Fed and St. Louis Fed, the market will expect the Fed to rightly focus on inflation pressures continuing to move in the wrong direction.
Here’s a closer look at the economic data coming at us next week:
U.S.
Monday, October 26
Dallas Fed Manufacturing Survey (Oct) – 10:30 AM ET
Tuesday, October 27
ADP Employment Change Report (Weekly) – 8:15 AM ET
Durable Goods Orders (Sept) – 8:30 AM ET
S&P CoreLogic Case-Shiller Home Price Index (Aug) – 9:00 AM ET
Conference Board Consumer Confidence (Oct) – 10:00 AM ET
New Home Sales (Sept) – 10:00 AM ET
Richmond Fed Manufacturing Index (Oct) – 10:00 AM ET
FOMC Two-Day Meeting Begins
Wednesday, October 28
MBA Mortgage Applications (Weekly) – 7:00 AM ET
Advance Economic Indicators: Goods Trade Balance, Retail & Wholesale Inventories (Sept) – 8:30 AM ET
Housing Vacancies & Homeownership (Q3) – 10:00 AM ET
EIA Crude Oil Inventories (Weekly) – 10:30 AM ET
FOMC Policy Statement – 2:00 PM ET
Fed Chair Press Conference – 2:30 PM ET
Thursday, October 29
GDP – Advance Estimate (Q3) – 8:30 AM ET
Personal Income & Spending, PCE Price Index (Sept) – 8:30 AM ET
Initial & Continuing Jobless Claims (Weekly) – 8:30 AM ET
EIA Natural Gas Inventories (Weekly) – 10:30 AM ET
Friday, October 30
Employment Cost Index (Q3) – 8:30 AM ET
Chicago PMI (Oct) – 9:45 AM ET
International
Monday, October 26
Germany: Ifo Business Climate (Oct)
Japan: Leading Economic Index – Final (Aug)
Tuesday, October 27
China: Industrial Profits (Sept)
U.K.: BRC Shop Price Index (Oct)
Wednesday, October 28
Canada: Bank of Canada Interest Rate Decision
Germany: GfK Consumer Confidence (Nov)
Thursday, October 29
Eurozone: Economic Sentiment (Oct)
Eurozone: Consumer Confidence – Final (Oct)
Eurozone: ECB Interest Rate Decision & Press Conference
Japan: Consumer Confidence (Oct)
U.K.: BoE Consumer Credit (Sept)
Friday, October 30
Eurozone: GDP – Flash (Q3 2026)
Eurozone: Unemployment Rate (Sept)
Germany: GDP – Flash (Q3 2026)
Germany: CPI – Preliminary (Oct)
Japan: Bank of Japan Interest Rate Decision & Outlook Report
Japan: Tokyo CPI (Oct)
Japan: Retail Sales (Sept)
Saturday, October 31
China: NBS Manufacturing & Non-Manufacturing PMIs (Oct)
As noted above, over one-third of the S&P 500 will report Q3 2026 quarterly results next week. From a Portfolio perspective we have seven holdings in that camp, and that means we will have our work cut out for us.
Our dot-connecting effort across that sea of reports will continue and help us refresh our investment mosaic while also testing investment thesis for our holdings. Read-throughs include KLA Corp. (KLAC) for semi-cap equipment demand and Applied Materials (AMAT). NXP Semi (NXPI), Teradyne (TER), Intel (INTC), ServiceNow (NOW) for AI and data center demand as well as overall chip capacity constraints.
GE Vernova (GEV), Vertiv (VRT), Amphenol (APH), Caterpillar (CAT) and Quanta Services (PWR) for electrification and data center buildouts tied to Eaton (ETN). Visa (V) and Mastercard (MA) for consumer spending and American Express (AXP). UPS (UPS) and Old Dominion Freight Line (ODFL) for freight and transports. Fortinet (FTNT) for cybersecurity, and Eli Lilly (LLY), Merck (MRK), AbbVie (ABBV), Bristol-Myers Squibb (BMY) and Gilead (GILD) for the Health Care Select Sector SPDR Fund (XLV).
Here’s a closer look at the earnings reports coming at us next week:
Monday, October 26
Open: Verizon Communications (VZ)
Close: Brown & Brown (BRO), Cadence Design Systems (CDNS), Nucor (NUE), Public Storage (PSA), Welltower (WELL)
Tuesday, October 27
Open: Boeing (BA), Coca-Cola (KO), Corning (GLW), Freeport-McMoRan (FCX), HCA Healthcare (HCA), Hilton Worldwide (HLT), Illinois Tool Works (ITW), Johnson Controls (JCI), Paccar (PCAR), PayPal (PYPL), Royal Caribbean (RCL), S&P Global (SPGI), Sherwin-Williams (SHW), United Parcel Service (UPS)
Close: Baker Hughes (BKR), NXP Semiconductors (NXPI), Robinhood Markets (HOOD), Seagate Technology (STX), Teradyne (TER), Ventas (VTR), Visa (V), Waste Management (WM)
Wednesday, October 28
Open: Amphenol (APH), Automatic Data Processing (ADP), Boston Scientific (BSX), GE HealthCare (GEHC), GE Vernova (GEV), Old Dominion Freight Line (ODFL), Otis Worldwide (OTIS), Phillips 66 (PSX), TE Connectivity (TEL), Vertiv (VRT)
Close: Alphabet (GOOGL), Chipotle Mexican Grill (CMG), eBay (EBAY), Equinix (EQIX), Ford Motor (F), Fortinet (FTNT), KLA (KLAC), Microsoft (MSFT), O’Reilly Automotive (ORLY), ServiceNow (NOW), T-Mobile US (TMUS)
Thursday, October 29
Open: Bristol-Myers Squibb (BMY), Carrier Global (CARR), Caterpillar (CAT), Eli Lilly (LLY), Intercontinental Exchange (ICE), Linde (LIN), Mastercard (MA), Merck (MRK), Quanta Services (PWR), Trane Technologies (TT)
Close: Amazon.com (AMZN), Coinbase Global (COIN), Gilead Sciences (GILD), Intel (INTC), Mondelez International (MDLZ), Republic Services (RSG), SanDisk (SNDK), Starbucks (SBUX), Stryker (SYK)
Friday, October 30
Open: AbbVie (ABBV), Chevron (CVX), Colgate-Palmolive (CL), Exxon Mobil (XOM), General Dynamics (GD), Regeneron Pharmaceuticals (REGN)
Portfolio Investor Resource Guide
Economic Data: Here’s a List of Links to the Key Economic Data We Closely Watch
Investing Terminology: 16 Key Terms Club Members Should Know
10-Ks: Want to Know About a Stock? Read the Company’s Reports
10-Qs: Unlock the Numbers and Key Information Behind Your Stock With the 10-Q
Income Statement: Our Cheat Sheet to Understanding This Financial Document
Balance Sheet, Cash Flow Statements, and Dividends: How to Know If a Company Is Off-Kilter? Read Its Balance Sheet
Valuation Metrics: Everyone Wants a Value. Here’s How Investors Can Find
Thematic Investing 101 Webinar
Like the Benefits of ETFs? Let’s Talk About Models
The Portfolio Ratings System
1 – Buy Now (BN): Stocks that look compelling to buy right now.
2 – Stockpile (SP): Positions we would add to on pullbacks or a successful test of technical support levels.
3 – Holding Pattern (HP): Stocks we are holding as we wait for a fresh catalyst to make our next move.
4 – Sell (S): Positions we intend to exit.