Tech Leads Equity Markets Higher
Continued gains in AI beneficiaries lead a broader rally Monday morning.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
US equities are on track for strong gains to start the week with a continued rebound in Tech names lifting indices (see the Week Ahead – Can Tech Lead the Market Higher?), although today’s gains are broader than what we saw Friday.
As of 8:50 am the Nasdaq-100 was leading major indices thanks to a rally in chip makers and other AI-related stocks premarket. (INTC) Intel stock is up more than 5%, while (AMD) AMD has gained over 2% and (NVDA) Nvidia is up over 1% on broader Tech strength and company-specific developments.
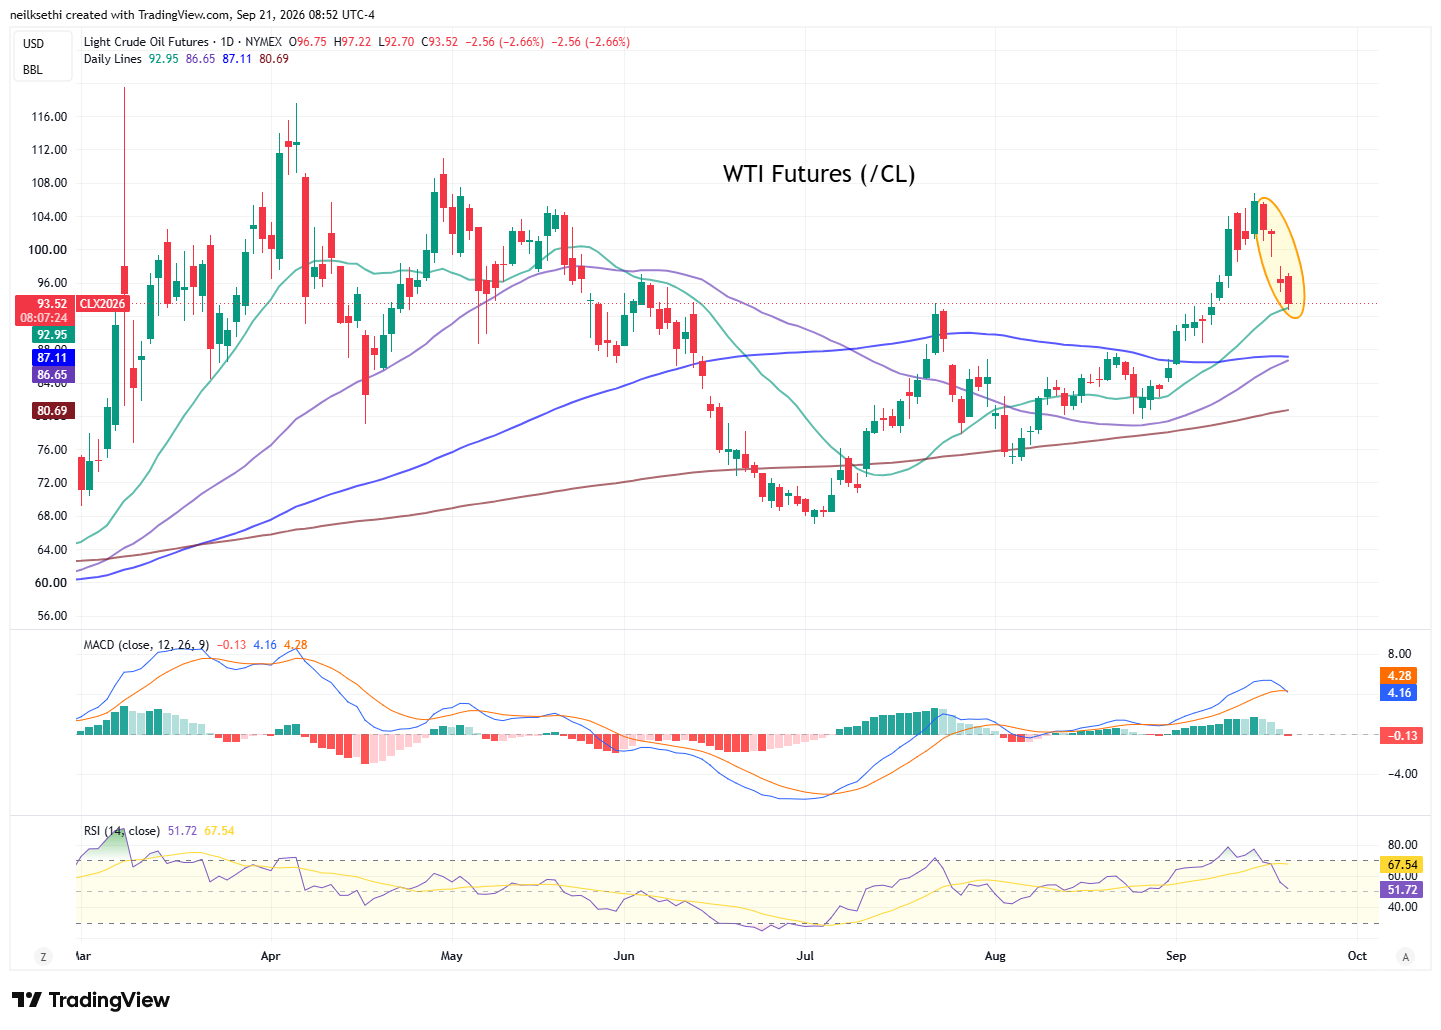
Oil prices falling for a fourth session was adding fuel to equity gains. The gains come despite an airborne attack targeting jet-fuel storage at the airport in Saudi Arabia’s capital Saturday, marking the first direct assault on Riyadh in months as Yemen’s Houthi rebels squeeze the kingdom’s Red Sea route for its oil exports.
Offsetting that was the IRNA news agency reporting that Iranian President Masoud Pezeshkian will fly to New York for the United Nations General Assembly. That leaves open the possibility he would meet with US President Trump. Trump told Fox News over the weekend he would “probably be open” to a meeting.
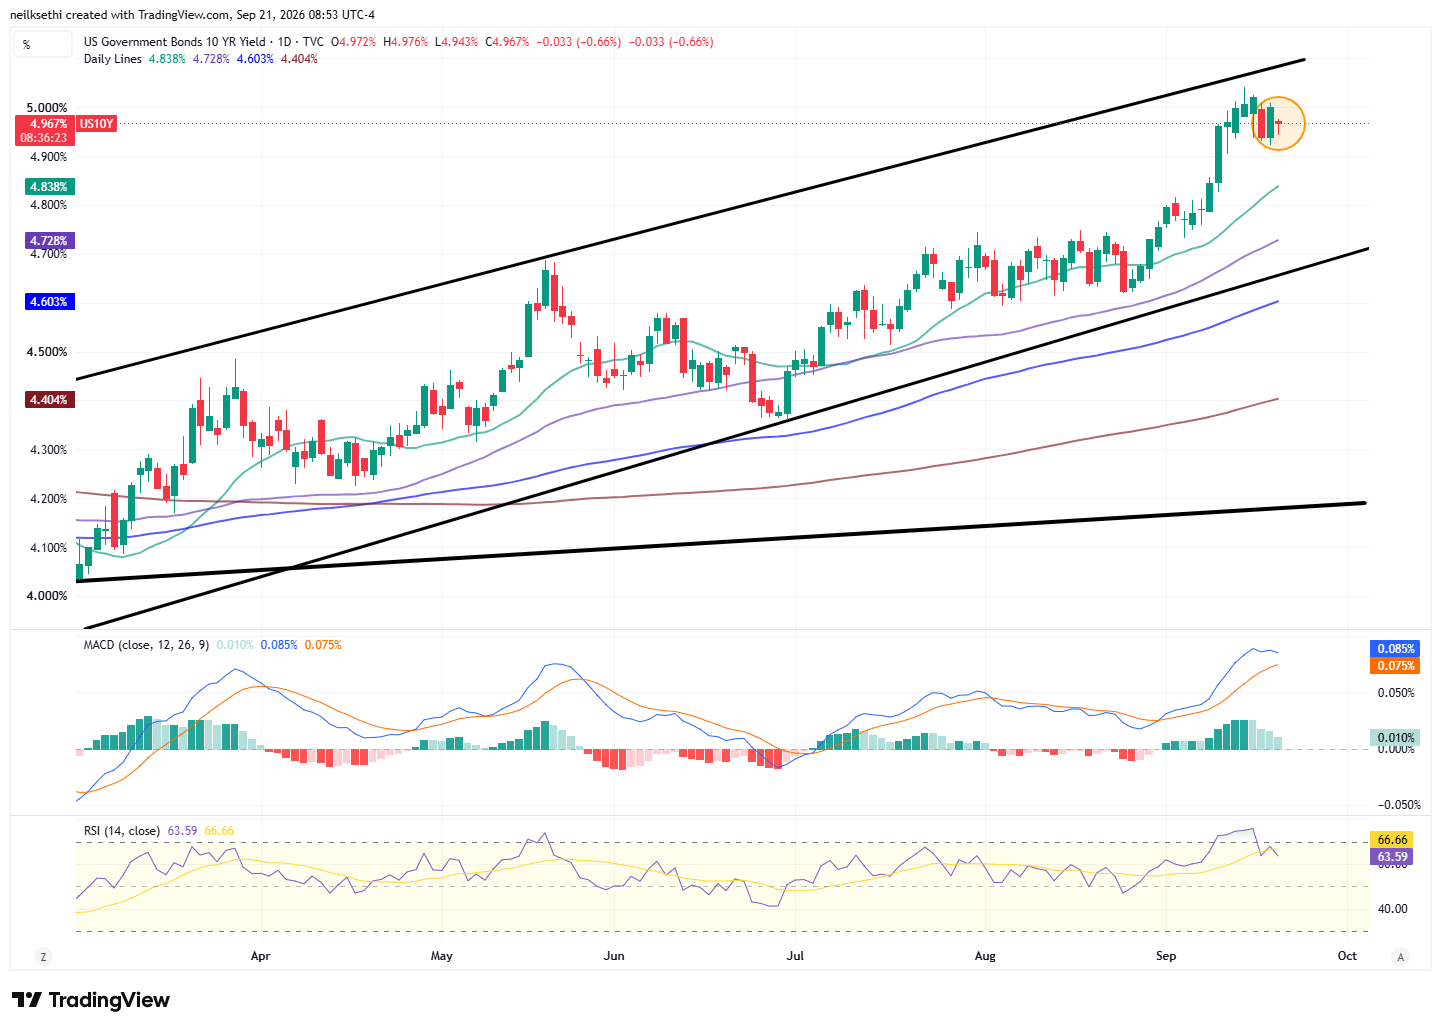
Treasuries rose across the curve (yields lower) with the 2-year yield down three basis points at 4.72%. The 10-year yield was down four basis points to 4.96%.
As discussed in the Week Ahead, the week is very light on the US economic calendar with just the Chicago Fed National Activity Index (a good concurrent read on GDP) today.
The Fed speaking blackout is over but today is lighter on that front (at least in terms of scheduled speakers) with just Chicago Fed President Goolsbee earlier this morning.
As of 8:55 am ET, the S&P 500 was indicated to open +0.6% while the tech-heavy Nasdaq-100 index was +1.1%, and the small-cap Russell 2000 +0.7%.
[Note the International Update is below the US update]
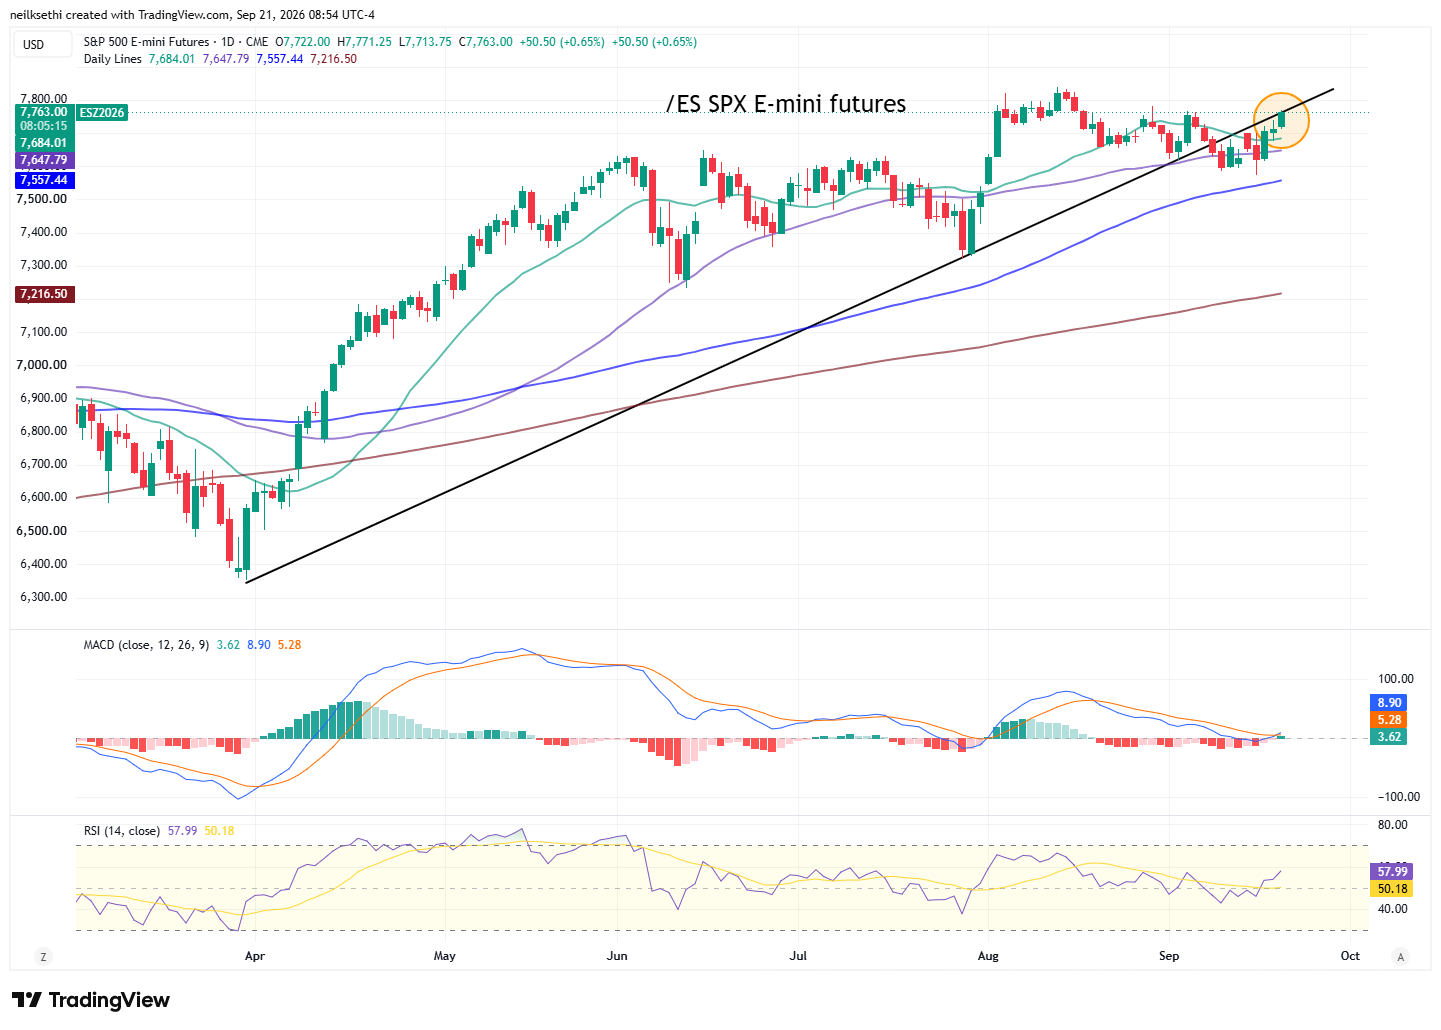
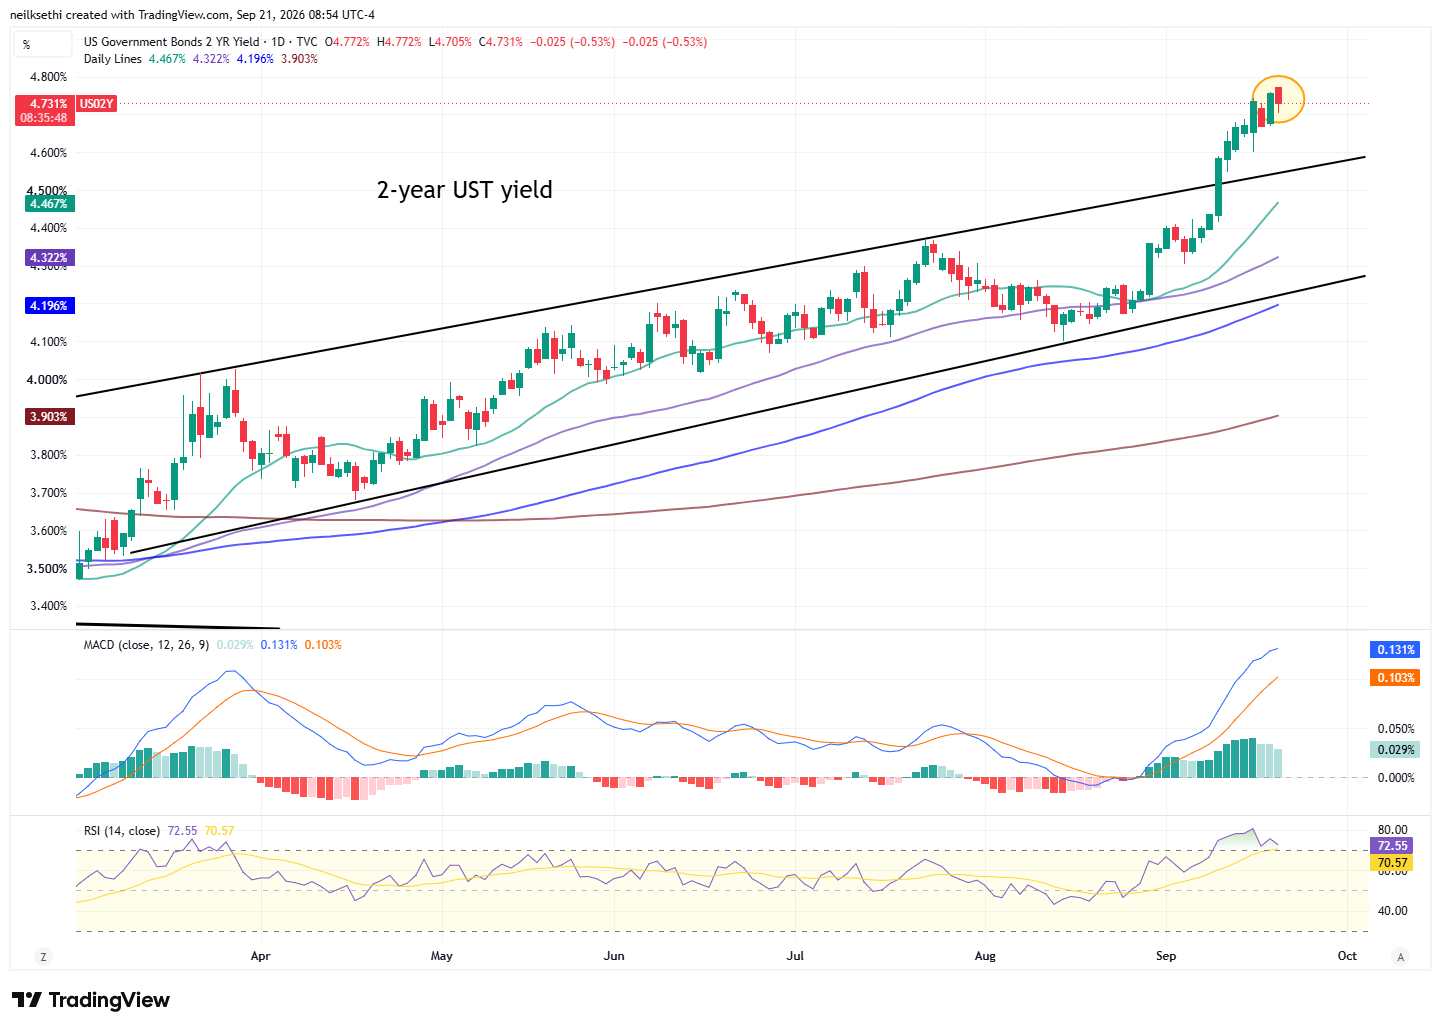
Note on all charts the colored lines are daily moving averages (the average price over the given number of days):
20 = green
50 = purple
100 = blue
200 = brownThe middle panel is MACD = Moving average convergence/divergence line, a measure of momentum that compares longer term and shorter term momentum to gauge if a move is strengthening or weakening. This is probably my favorite individual indicator (it’s also the favorite of Katie Stockton, a very fine technician).
The bottom panel is RSI = Relative Strength Index (basically what it sounds like) = measures the strength of the move comparing gains to losses over the given lookback window (I use the standard 14 periods).
Charts as of 8:45 am
SPX Futures (/ES) – looking to break out of trading range over the past month.
2-year yield – easing back after having hit new post-July 2024 highs.
10-year yield – easing back.
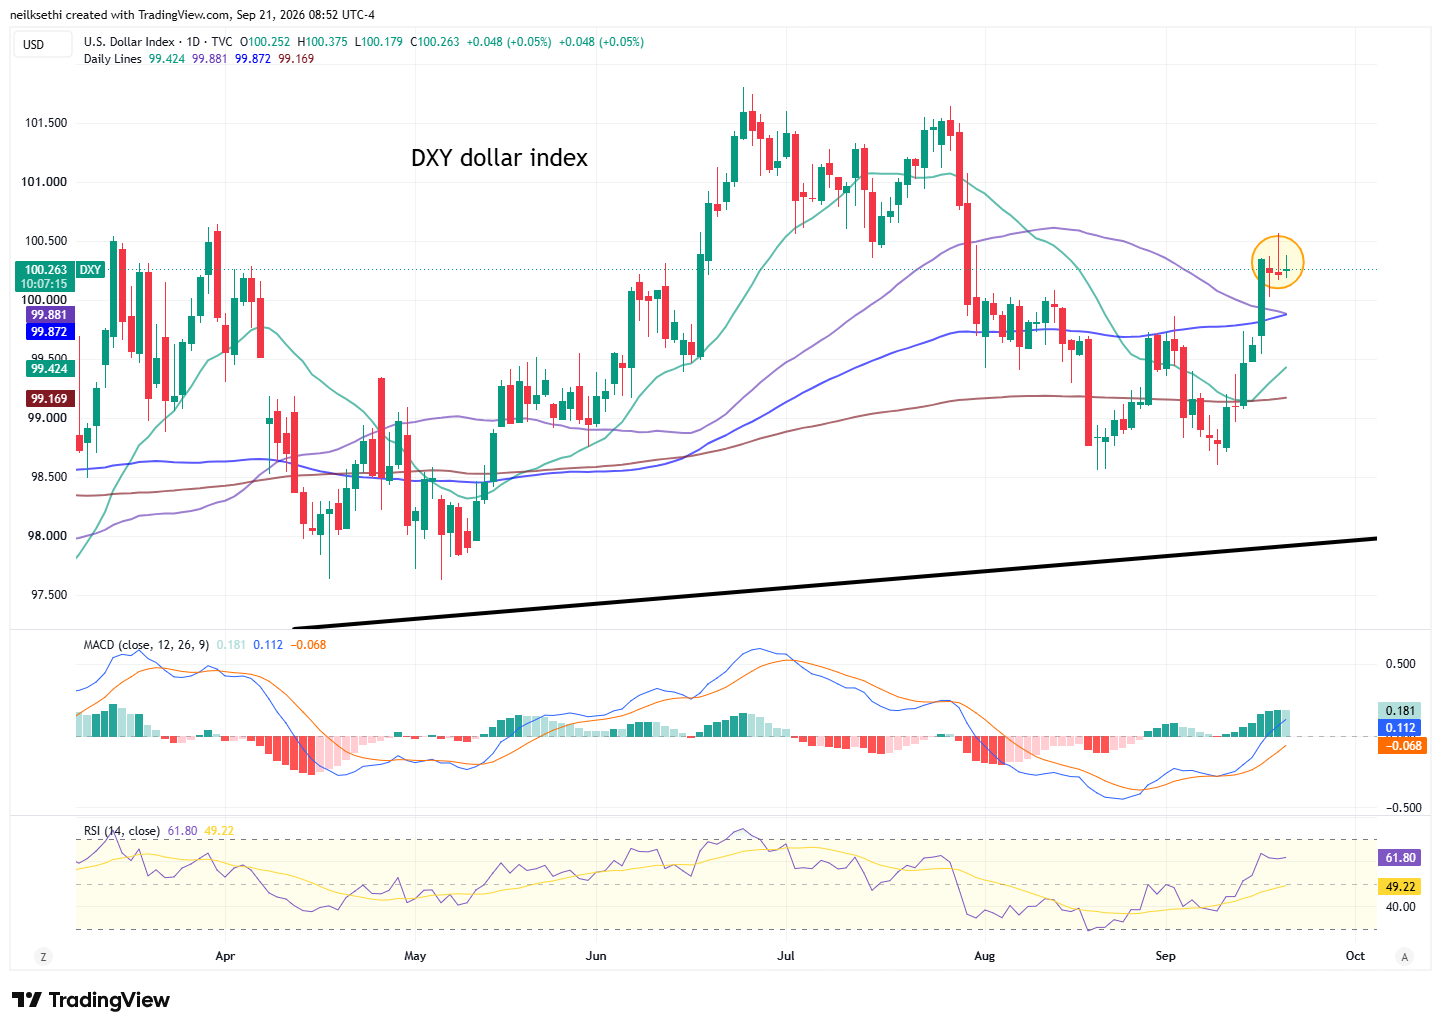
DXY US dollar index – little changed for third session after big move last week.
WTI futures (/CL) – down for fourth straight session.
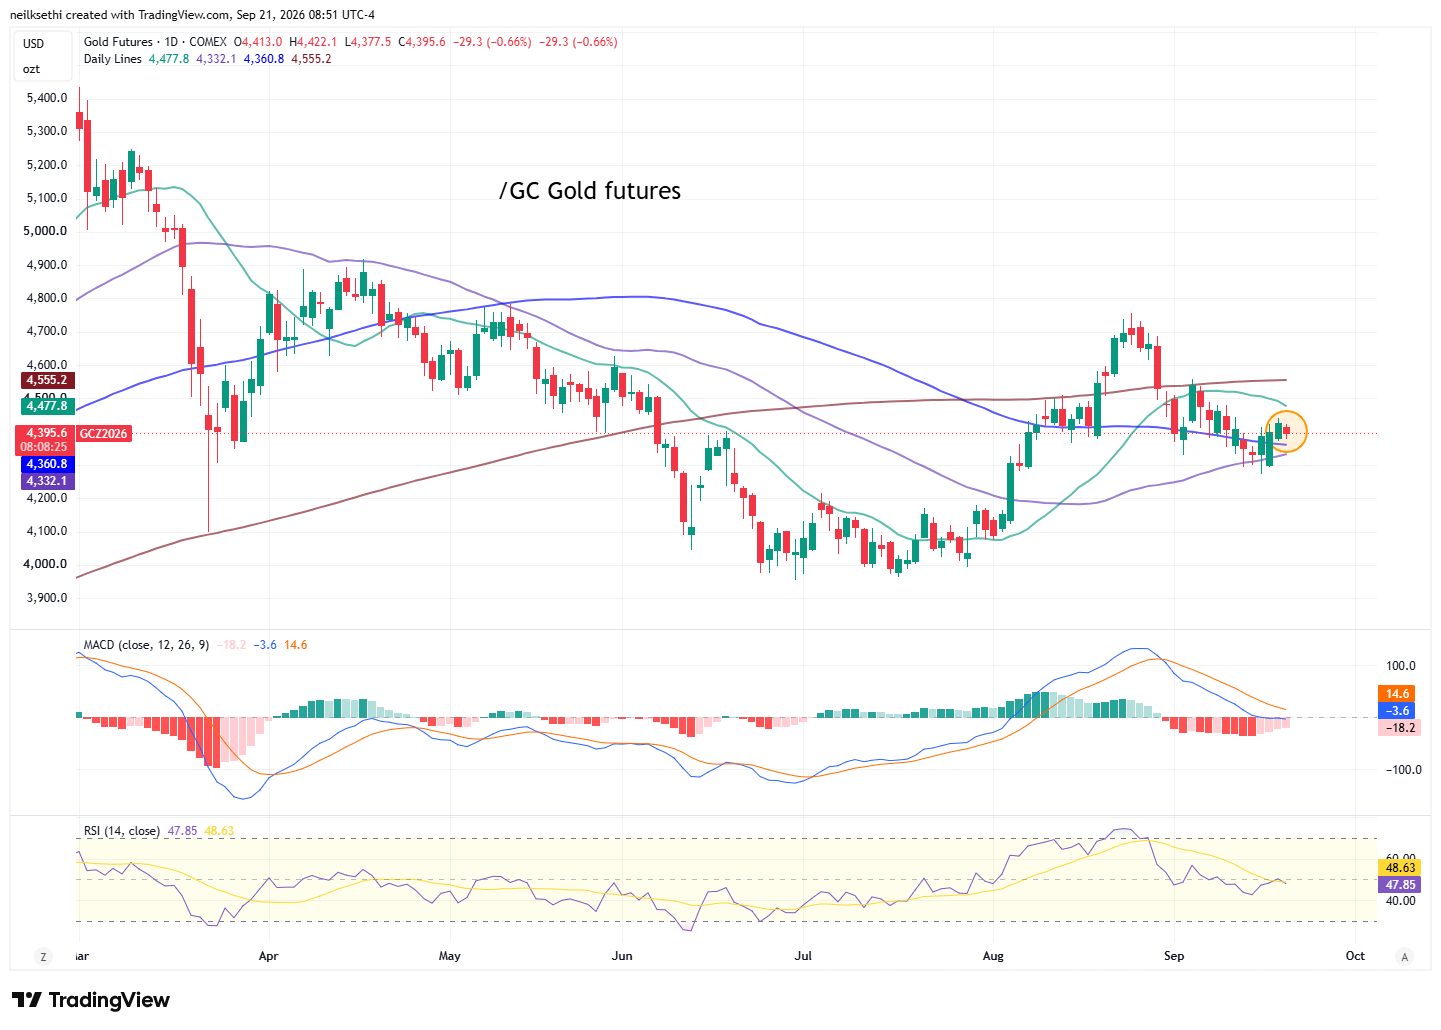
Gold futures (/GC) – not joining equities higher.
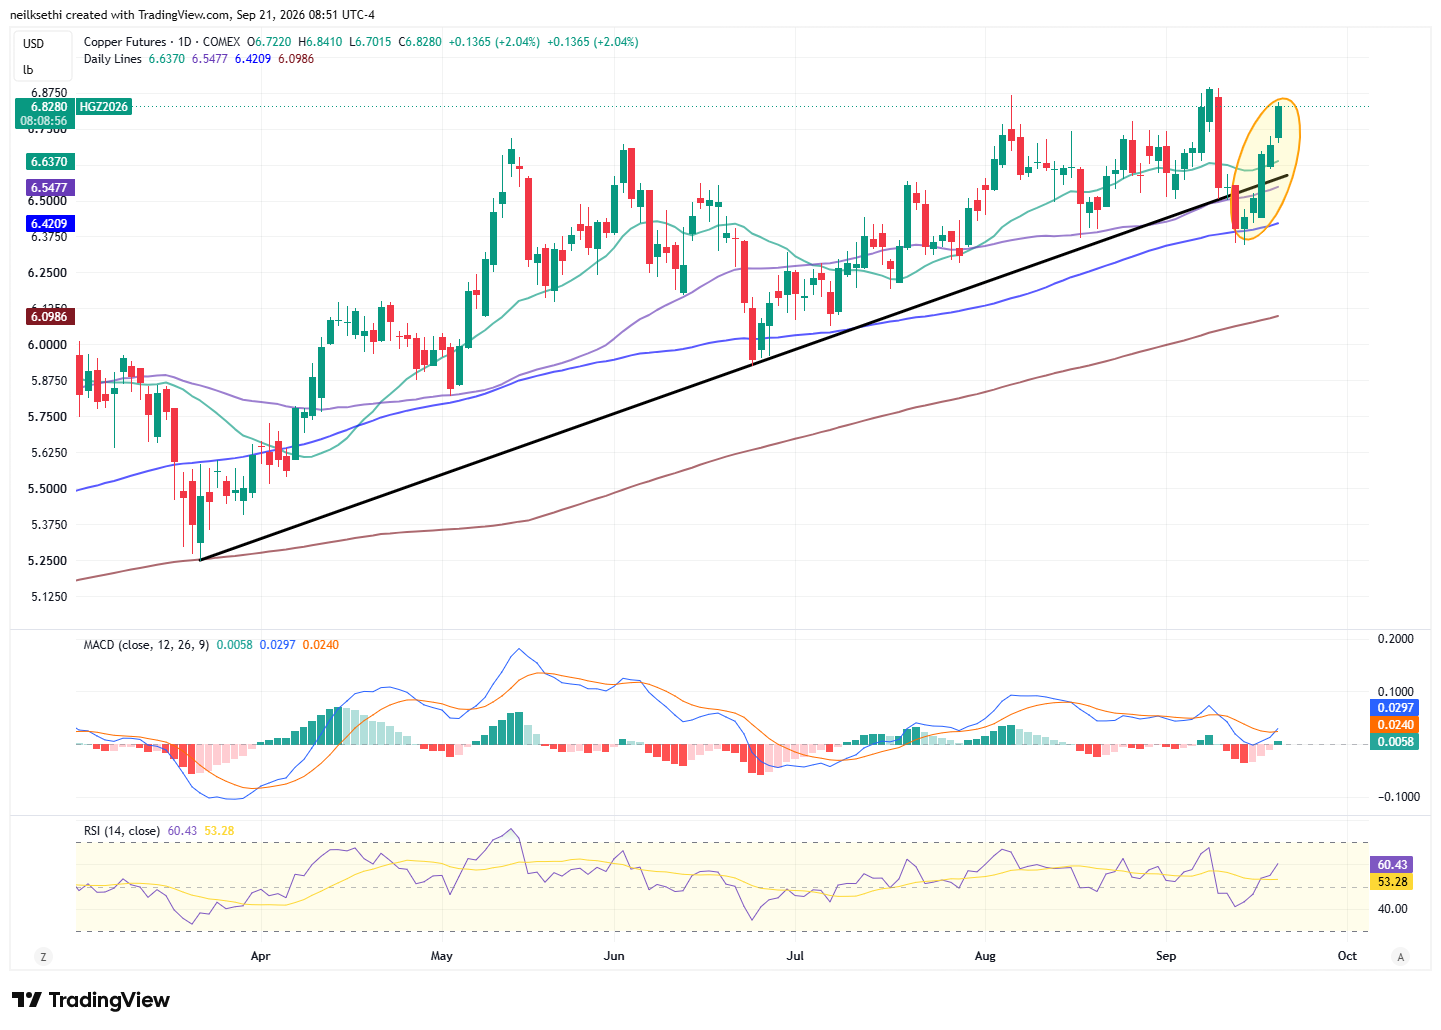
US copper futures (/HG) – up for a fifth session continuing to follow the AI-trade and approaching all-time high territory.
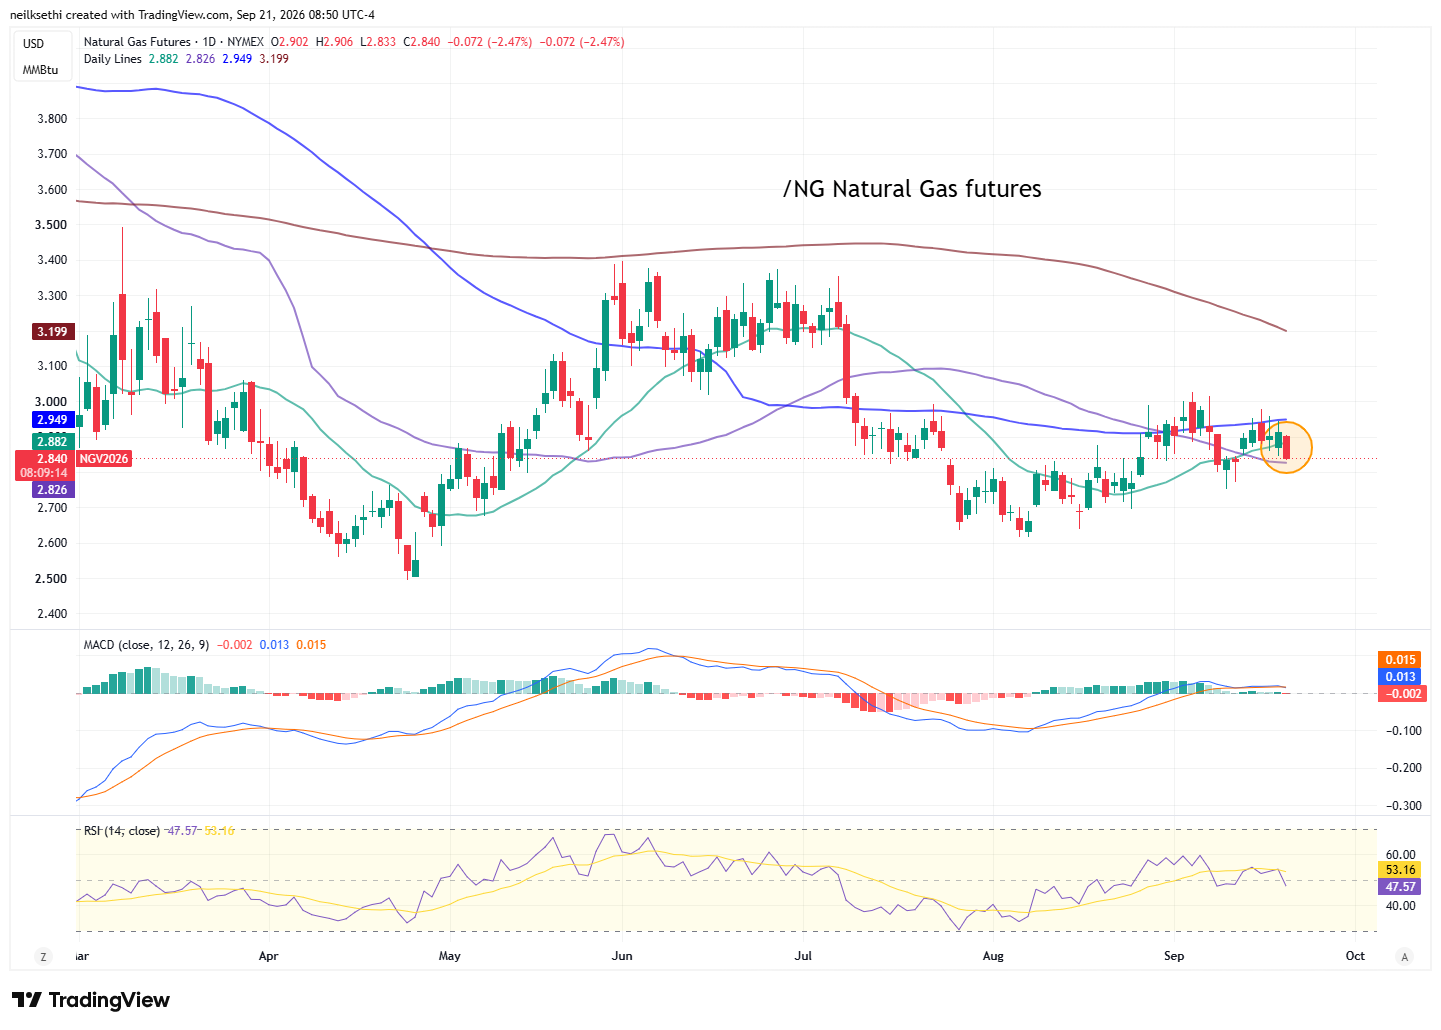
US natural gas futures (/NG) – remaining in their range since early July.
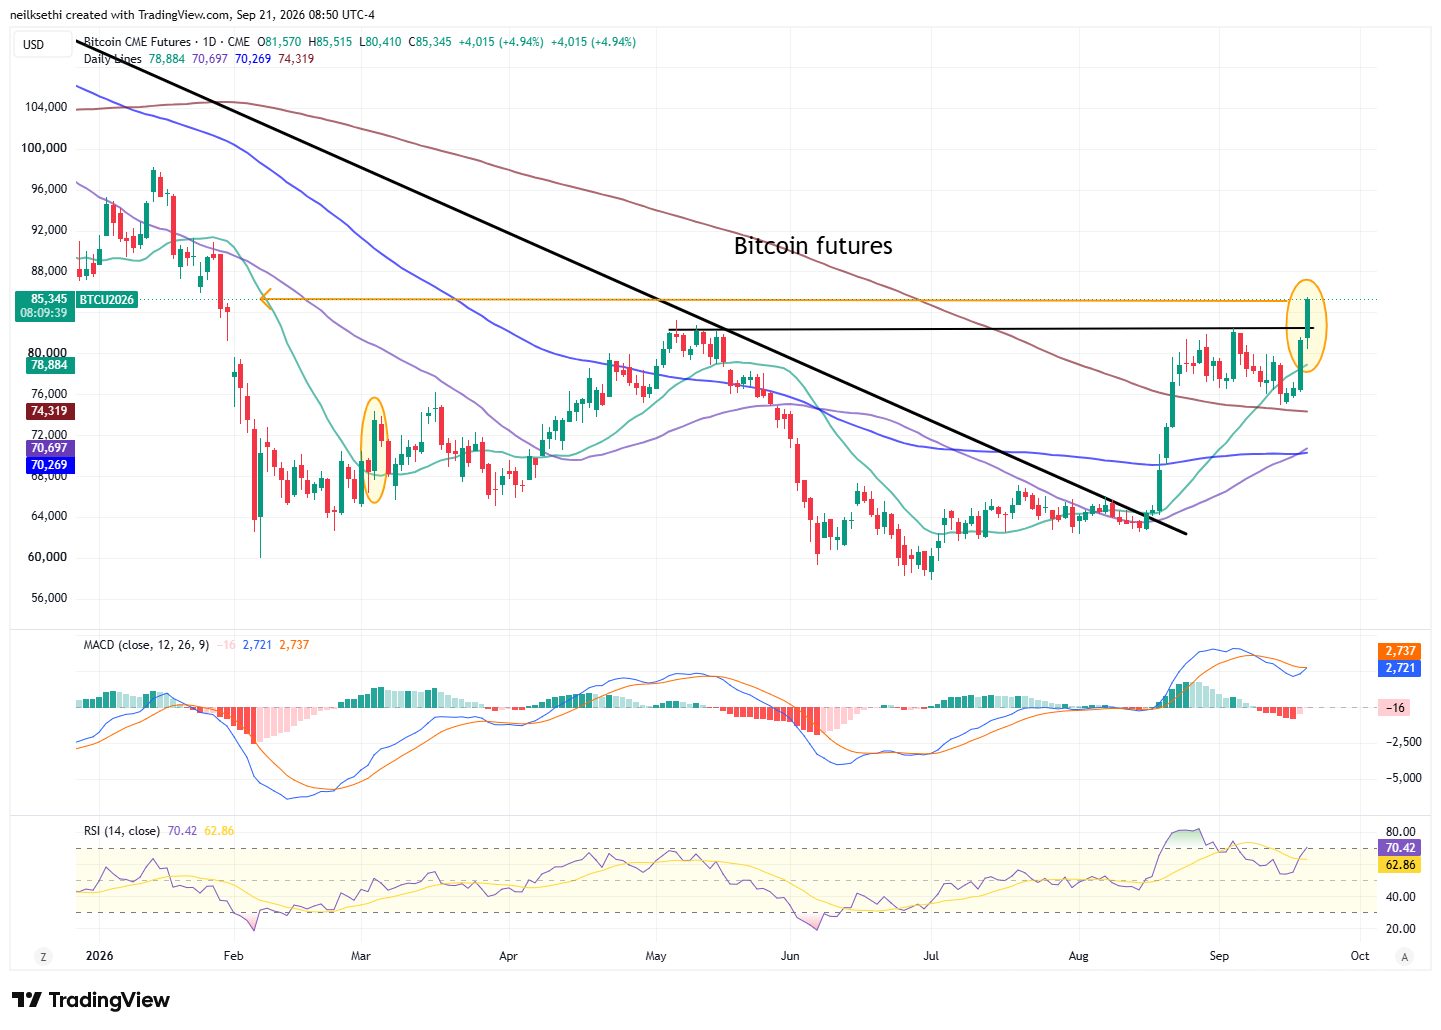
Bitcoin futures – breaking out to the highest levels since January.
Some pre-market company news:
- Robinhood (HOOD), Coinbase (COIN), and Circle Internet Group (CRCL) are jumping in premarket trading Monday. The gains came as Bitcoin presses above $85,000 for the first time since January and after analysts at Goldman Sachs and Citizens pointed to new revenue opportunities in digital-asset infrastructure as the SEC (U.S. Securities and Exchange Commission) advances its framework for tokenized U.S. stocks.
- Accenture (ACN) shares rose 6% in premarket trading Monday after the company said late Friday that it would embed a team of evaluators inside Anthropic to stress-test its AI models.
- Paramount Skydance (PSKY); Warner Bros. Discovery (WBD): Paramount executives and a coalition of states that sued to block the company’s $81 billion merger with Warner have been working to agree on a possible settlement according to the WSJ.
- Novo Nordisk (NVO): Shares slid nearly 5% after investors were left unimpressed by the company’s long-term goals about competing with the weight loss market.
From TheStreet Pro:
- Stephen Guilfoyle – Call Me Foolish, But I See Some Potential Market Catalysts Emerging
- Helene Meisler – This ETF Indicates That Economic Trouble Is Brewing& Just When I Thought Complacency Had Been Pushed Off the Table, It’s Back.
- James “Rev Shark” DePorre – The Weakest Week of the Year Meets an Iran Bounce and Hawkish Fed& The Chart Pattern Is Half the Equation. Here’s the Other Half
- Bret Jensen – How to Buy the Uber Dip With a Covered-Call Strategy
- Bob Lang – Charting the Markets: Why the Nasdaq 100 Could Be the Next Leader & Bearish Bets: 3 Stocks Getting Hammered With Little Chance to Recover
Other headline articles:
- BBG – US President Donald Trump’s talks with China’s Xi Jinping are one of the week’s pivotal event, covering crucial issues from tariffs to technology related to the world’s two largest economies.
- BBG – The soaring cost of moving oil around the world is making some long-distance crude trades uneconomical, threatening to disrupt flows at a time when fuel markets have never been tighter.
- FT – Investors are questioning whether Anthropic can sustain its extraordinary growth as competition, price-sensitive customers and the potential for AI to destroy humanity cloud its blockbuster IPO.
- FT – The Bank of England and US Federal Reserve have stepped up scrutiny of bank exposures to large trading firms after turmoil at AI-focused hedge fund Situational Awareness caused large losses at Jane Street.
International Highlights:
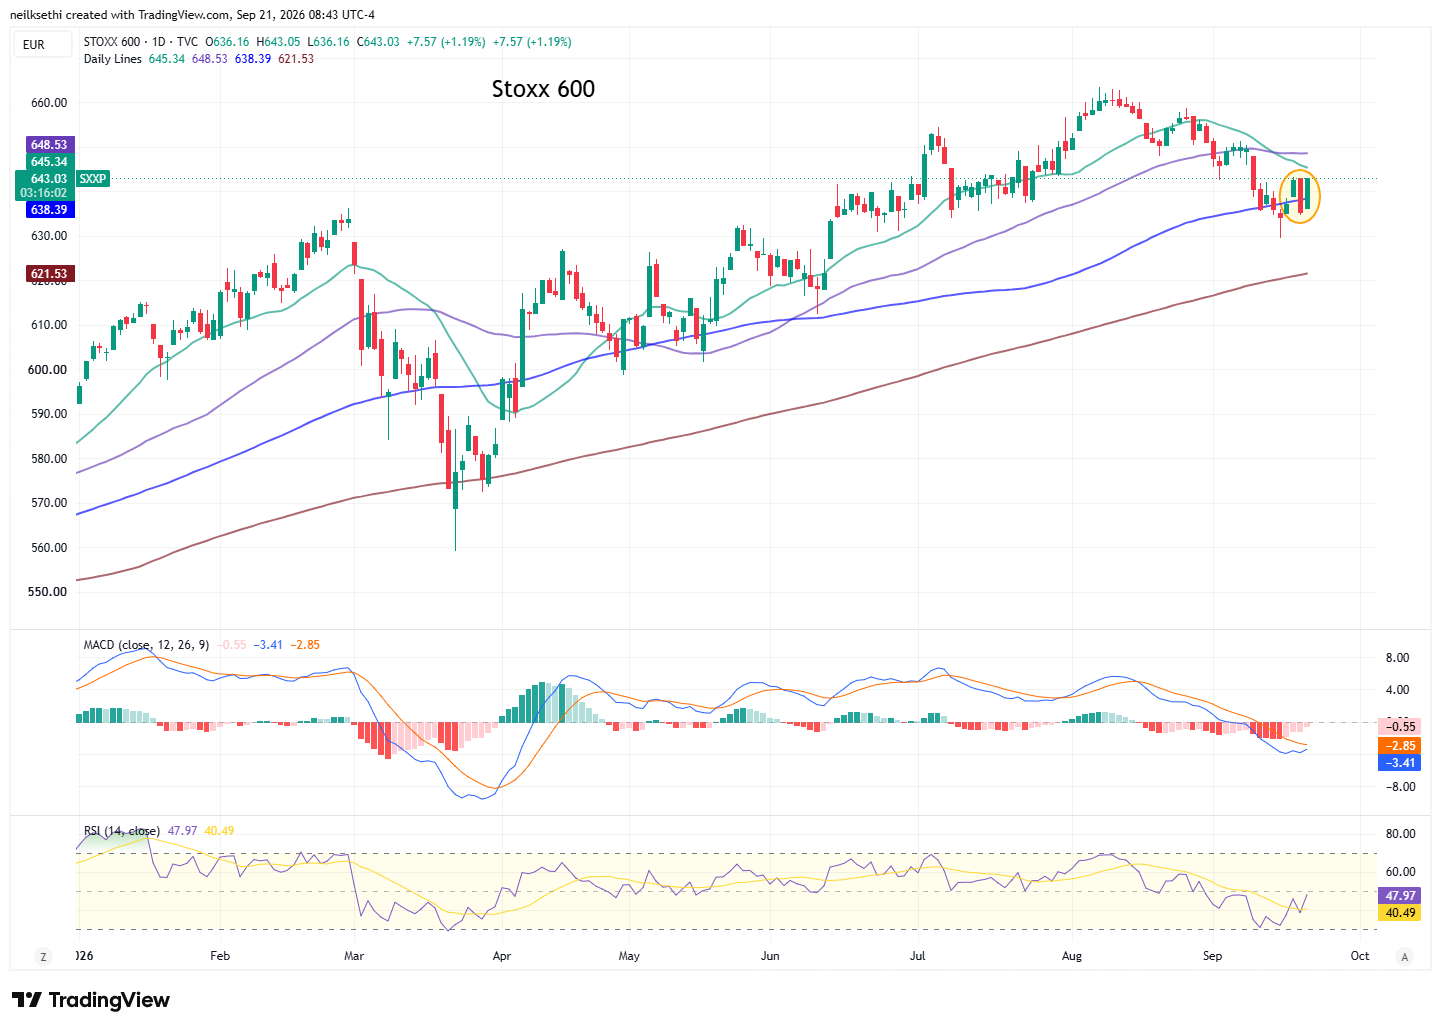
Europe’s benchmark STOXX 600 as of 8:40 am ET was +1.2% getting back all of Friday’s losses after closing out its fifth down week in six last week.
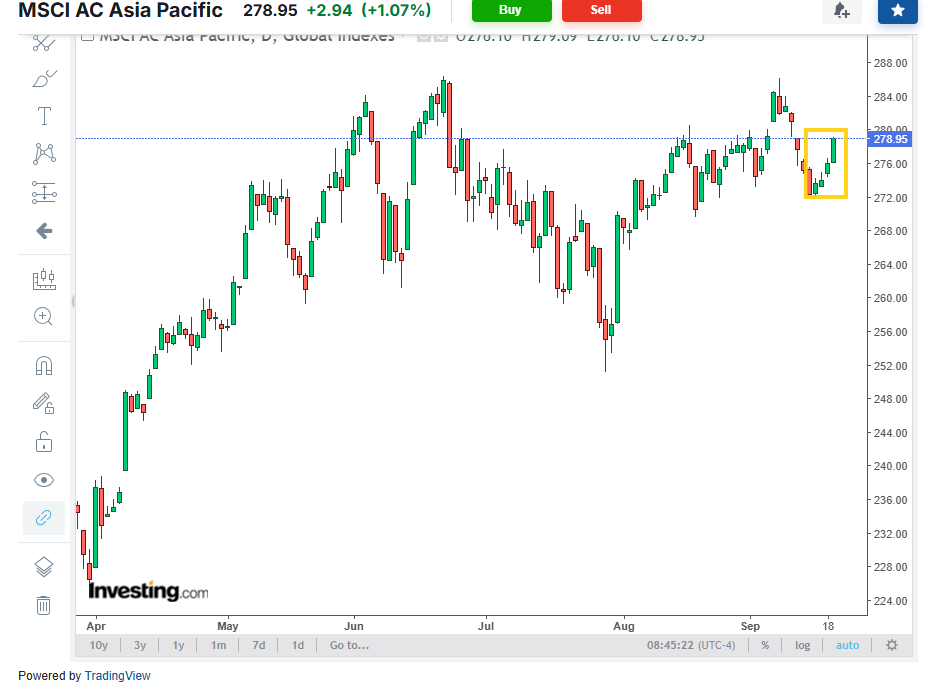
The broad MSCI AC Asia Pacific Index was up for a fourth straight session Monday +1.1%, as in the US lifted by AI names.
Some ex-US highlights:
- BBG – US Treasury Secretary Scott Bessent lauded “very successful” talks with his Chinese counterparts that spanned artificial intelligence, trade and investment ahead of this week’s summit between leaders Donald Trump and Xi Jinping. China’s top trade negotiator, Li Chenggang, said the talks were held in a “good atmosphere” as he left JPMorgan Chase & Co.’s headquarters in New York on Sunday.
- FT – Donald Trump pressed his Ukrainian counterpart Volodymyr Zelenskyy in a call on Sunday to halt Kyiv’s strikes on Russian refineries over concerns that the attacks are exacerbating a global diesel shortage and pushing up prices, according to people familiar with the call.
- RTRS – Denmark and Greenland on Saturday said any agreement with the United States would not compromise Greenland’s sovereignty, after President Donald Trump said the deal would give Washington “permanent control” over the Arctic island’s security, leaving its precise scope unclear. The United States, Denmark and Greenland said late on Friday they had reached an agreement for the US to develop a significant military presence on Greenland, while prohibiting US adversaries from building their own bases on the island.
- BBG – Hedge funds turned positive on the yen for the first time since July 2025, a noteworthy shift in sentiment weeks after US and Japanese authorities intervened in the market to support the currency
- On the sharp decline in the ratio of younger to older workers.
- On South Korea exports:
- On China credit growth:
- On global consumer sentiment:
- On BofA’s European Style Cycle:
As a reminder, if you do put a comment in for me on a post please be sure to put @NeilSethi in front. Comments are encouraged!