Qualcomm Faces the Semiconductor Abyss
On Wednesday evening, chip designer Qualcomm ($QCOM) released the firm’s fiscal fourth quarter financial results. For the period ended September 27, Qualcomm posted an adjusted EPS of $2.17 (GAAP EPS: $1.17) on revenue of $10.322 billion. These numbers were good for beats of Wall Street’s expectations on the top- and adjusted bottom-lines, despite the fact …
You've reached your free article limit
You've read 0 of 1 free Pro articles.
On Wednesday evening, chip designer Qualcomm (QCOM) released the firm’s fiscal fourth quarter financial results. For the period ended September 27, Qualcomm posted an adjusted EPS of $2.17 (GAAP EPS: $1.17) on revenue of $10.322 billion. These numbers were good for beats of Wall Street’s expectations on the top- and adjusted bottom-lines, despite the fact that revenue dropped 8.4% year over year. Qualcomm also missed the GAAP EPS expectation quite badly.
Qualcomm president and CEO Cristiano Amon commented in the press release:
“We are pleased to deliver fourth quarter non-GAAP revenues at the high end of our guidance, along with 36% year-over-year growth in combined QCT Automotive and IoT revenues. Fiscal 2027 marks the start of our non-handset revenue inflection, including the ramp of our Data Center business. Non-handset revenues are projected to grow by more than 60% year-over-year, and we are reiterating our fiscal 2027 Data Center revenue target of $5B.”
Operations
As revenue generation contracted 8.4% year over year to $10.322 billion, total GAAP costs and expenses increased 7.4% to $8.966 billion. This left a GAAP operating income of $1.356 billion (-53.5%).
After interest, other income and expenses and taxes, GAAP net income printed at $1.251 billion (up from -$3.117 billion a year ago, which was a tax issue). This works out to a GAAP $1.17 per fully diluted share, up from -$2.89 for the year-ago comp. The firm made sizable adjustments for share-based compensation and expenses tied to Qualcomm Strategic Investments. After those adjustments were made, net income lands at $2.3332 billion (-28%) and EPS prints at $2.17, down from $3.00.
Segment Performance
QCT (Qualcomm CDMA Technologies) generated revenue of $9.015 billion (-8%), producing earnings before taxes of $2.142 billion (-26%)
QTL (Qualcomm Technology Licensing) generated revenue of $1.304 billion (-7%), producing earnings before taxes of $918 million (-10%).
Guidance
For the current quarter, Qualcomm is guiding revenue towards a range spanning from $10.4 billion to $11.2 billion. That takes the midpoint above the $10.56 billion that Wall Street was looking for. The firm also sees an adjusted EPS of $2.15 to $2.35. That, at the midpoint, falls short of what Wall Street had in mind. GAAP EPS is projected at $1.03 to $1.23. For the full year, Qualcomm is targeting non-handset revenue growth of more than 60% and data center-driven revenue of $5 billion. This guidance was largely seen as disappointing.
Fundamentals
For the full year, Qualcomm generated operating cash flow of $11.145 billion. Out of that number came just $2.494 billion in capex spending leaving free cash flow of $8.651 billion (-32.5%). “Out of that number,” the firm repurchased $7.817 billion in common stock and paid out $3.854 billion in cash dividends to shareholders.
Turning to the balance sheet, Qualcomm ended the quarter/year with a cash position of $7.681 billion (-38.4%) and inventories of $8.64B million. This left current assets at $22.272 billion (-13.5%). Current liabilities are running at $11.978 billion including short-term debt of $2.492 billion. That puts the film’s current and quick ratios at 1.86 and 1.14, respectively.
Total assets amount to $60.829 billion, of which 30.1% is labeled as either good will or other intangibles. While this is not yet alarming, it is a little much for my liking and is up from 24.9% a year ago. Total liabilities less equity comes to $30.428 billion including long-term debt of $11.978 billion. Let’s be clear. This is not a “bad” balance sheet, but the deterioration in its quality year over year is quite visible.
Opinion
There’s a lot to not like here. The quarter was not all that hot. Sales contracted. Cash flows are positive but in a state of steep decline. For the year, the firm returned far more capital to shareholders than free cash flow provided for. The guidance is disappointing. I don’t know if Qualcomm gave anyone a reason to buy this stock on Wednesday night and that’s how Wall Street is treating the shares. The market is trading broadly lower on Thursday, but Qualcomm is leading the beatdown. Let’s go to the chart:
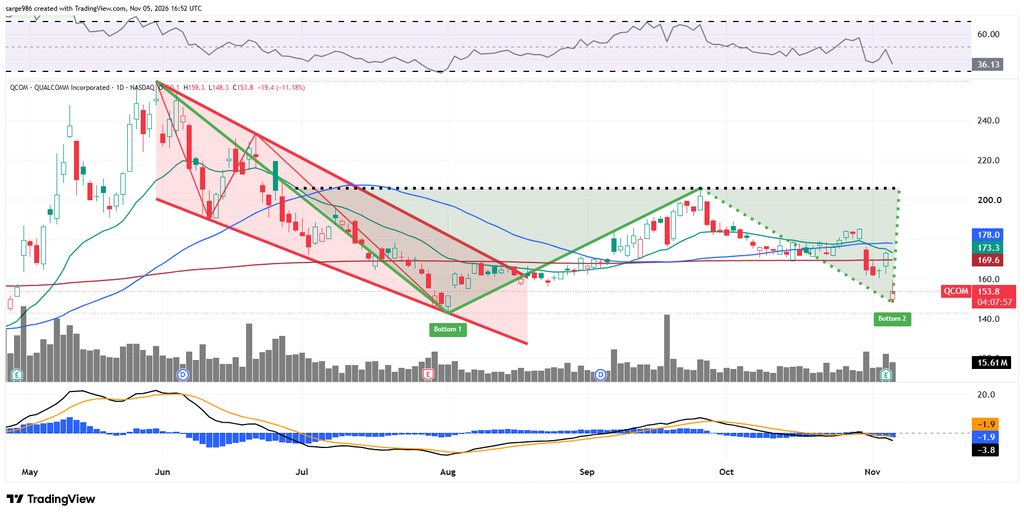
Readers will see that Qualcomm is well into the abyss of sorrow on Thursday morning. I do have something for the bulls, however. QCOM rebounded out of falling wedge of bullish reversal that did its job in August. The stock went on to develop what might be a double bottom of bullish reversal with a $206 pivot. That is, if the share scan just stop going lower here in the $140s. So far so good on that.
Looking at the indicators, relative strength is weaker than neutral and still losing altitude. The daily MACD, below the chart, is flashing bearish signals as well. The histogram of the nine-day EMA is now below the zero-bound and falling. In addition, the 12-day EMA has dropped below the 26-day EMA with both in negative territory. That’s undeniably bearish.
Buy Qualcomm on this weakness? C’mon, dude. I’ve been reducing exposure to the semis all week. You want semiconductors on weakness? There are so many semiconductors I’d rather buy or buy back.
positions: none