Anthropic Rocks Wall Street
The market parties on Anthropic filing (as company warns it might need more cash, and signals AI may take coding jobs and have catastrophic risks to mankind).
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Party on, dudes! Equities rallied nicely on Monday. Or did they? As I had taken the day off to get my loved one home and situated, I watched with interest as the world, yet again, functioned just fine without my participation. Equities closed higher on Monday, at least at the index level, snapping a two-day losing streak and coming off of a two-week losing streak.
The driver appeared to be the official filing of a Form S-1 by Anthropic PBC with the U.S. Securities and Exchange Commission, meaning that the high-tech / artificial Intelligence company plans to go public and list on the Nasdaq under the symbol “ANT.” This reignited a fuse under the AI trade, at least for the day. This also came after a confidential filing back in June.
Anthropic reported revenue of $16.29 billion for the six-month period ended in June. This amounts to annual growth of a mere 1,304%, up from $1.16 billion for the comparable period one year ago. For a little background, Anthropic was founded by CEO Dario Amodel and others after defecting from chief rival OpenAI. Expansion really hit a higher level this past year due to the growing popularity of the Claude coding tool and the Claude Fable and Claude Mythos models that followed. This action put a bid under the AI trade and semiconductor companies in particular.
Marketplace
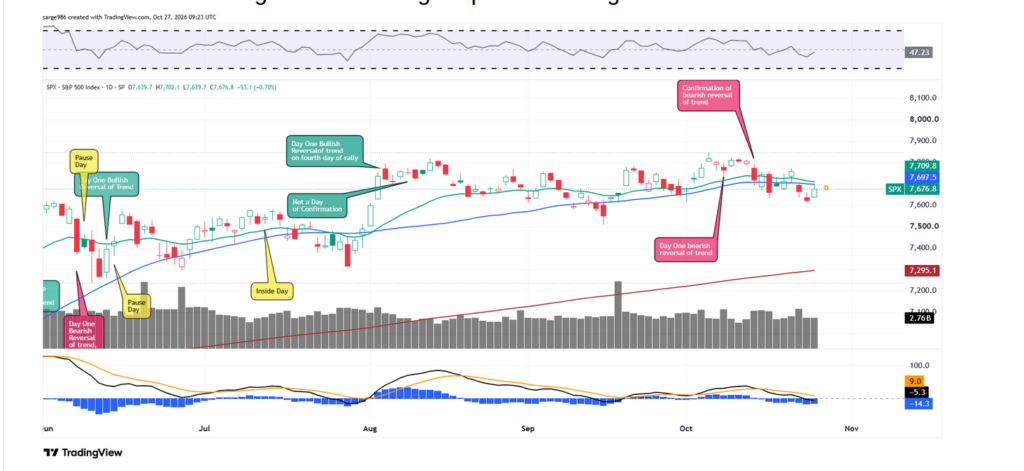
For the day on Monday, the S&P 500 popped for a gain of 0.7% and re-established contact with its 50-day simple moving average. That may or may not be a big deal. Actually, capturing that line would have mattered more. Perhaps that was a bit too much to ask ahead of the federal open market committee policy decision to be made on Wednesday afternoon and the huge number of higher profile earnings to be released later this week.
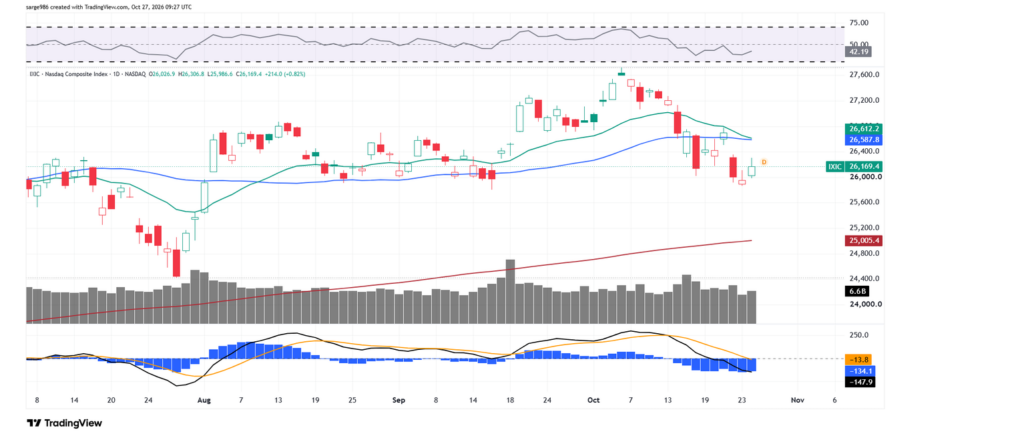
As readers can see below, the Nasdaq Composite, despite tacking on 0.82%, is nowhere near taking back that important line, but in fact, may soon be up against a “mini” or swing traders’ death cross.
For the day, everyone but the utilities partied. The small to mid-cap indexes traded higher as did the Dow Transports, the KBW Banks and of course the Philadelphia Semis. That index stole the show with an upward run of 2.82%.
Code Word: Out of Work
Anthropic also warned that the it may need to seek additional funding sooner than it had previously anticipated.
Oh, and remember when learning to code as the wave of the future? Yeah, about that — in September, more than 90% of all contributions to Anthropic’s codebase were written by Claude itself and not humans.
The average daily volume of code contributions over that time period was a whopping 45-times higher than the daily average recorded during the entire calendar year of 2024. Turns out that while AI is coming for all of us, it will be putting the kids that went to college to learn tech out of work long before it gets to the kids that enlisted, went to trade school or took their local police exam. Times? Are changing’.
Banking on AI…
So, it appears that Hock Tan, CEO of chip maker Broadcom (AVGO) spent almost two months trying to get banks to commit to the largest AI debt deal ever, according to reports at the Wall Street Journal and other outlets on Monday. The deal was meant to allow Anthropic to lease specialized chips that Broadcom is currently developing with Alphabet’s (GOOGL) Google.
Bank of America (BAC), Blackstone (BX), Citi (C), and Morgan Stanley (MS) appear to be leading a $64 billion transaction to finance and deploy AI compute capacity, using Broadcom’s (AVGO) technology for Anthropic. The deal will be executed through a new special purpose vehicle with committed financing from the lead financial partners. Blackstone as the sole provider of the committed portion of the second lien financing. Broadcom is providing residual value support to the SPV for the amount equivalent to the first lien portion of the financing.
While Anthropic’s prospectus itself, states…
“As AI systems become more capable, the potential severity of harm from misaligned or misused models increases correspondingly, and a wide range of stakeholders, including researchers and policymakers, have raised concerns that sufficiently advanced AI systems could pose catastrophic or existential risks to society if not developed and deployed responsibly.”
… it is reassuring to know that Blackstone’s commitment reflects its confidence in demand for the technology. Oh, baby. Party on, dudes.
‘Nuff Said
“Be excellent to each other”
– Bill (Alex Winter)
“Party on, dudes!”
– Ted (Keanu Reeves)
– From the 1989 film, “Bill & Ted’s Excellent Adventure”
Breadth
On Monday, there was some mild demand for U.S. Treasuries while Crude oil sold off a bit from elevated levels. As for equities, the part was a lot less exciting than the headlines suggest. Yes, seven of the 11 S&P sector SPDR ETFs closed out the day in the green, led by Tech (XLK) and the Industrials. Yes, only three of these funds closed in the red, led lower by communication services (XLC) (health care (XLV) closed unchanged).
That said, the day was not one of pure euphoria. Not even close. Winners beat losers by a narrow seven-to-six margin at the NYSE and an even narrower 12-to-11 margin at the Nasdaq. Advancing volume? Took a less than impressive 52.9% share of composite Nasdaq-listed activity on Monday and an embarrassing (for an up-day) 41.3% share of composite NYSE-listed trade. Does that even count as an “up” day? I’m not even sure.
Economics (All Times Eastern)
08:15 – ADP Employment Change (Weekly): Last 18.5K.
08:30 – Durable Goods Orders (Sep): Expecting 1.6% m/m, Last -0.1% m/m.
08:30 – ex-Transportation (Sep):
Expecting 0.6% m/m, Last 0.3% m/m.
08:30 – ex-Defense (Sep): Expecting 0.0% m/m, Last 0.1% m/m.
08:30 – Core Capital Goods (Sep):
Expecting 0.7% m/m, Last 1.6% m/m.
08:55 – Redbook (Weekly): Last 9.0% y/y.
09:00 – Case-Shiller HPI (Aug): Expecting 2.5% y/y, Last 2.5% y/y.
09:00 – FHFA HPI (Aug): Expecting 0.2% m/m, Last 0.3% m/m.
10:00 – Consumer Confidence (Oct): Expecting 81.1, Last 81.9.
10:00 – New Home Sales (Sep): Expecting 651K, Last 684K SAAR.
10:00 – Richmond Fed Manufacturing Index (Ocy): Expecting 0, Last -2.
16:30 – API Oil Inventories (Weekly): Last -4.93M.
The Fed (All Times Eastern)
Fed Blackout Period.
Today’s Earnings Highlights (Consensus EPS Expectations)
Before the Open: CNC (.10), UPS (1.62), KO (.88), AMT (1.64), SOFI (.16), BA (-.25)
After the Close: HOOD (.56), STX (7.45), V (3.44)
At the time of publication, Guilfoyle was long SOFI equity.