Friday’s After-Hours Movers
BY Doug Kass · Oct 2, 2026, 4:45 PM EDT
 Doug KassDoug Kass
BY Doug Kass · Oct 2, 2026, 4:45 PM EDT
Closing Volume
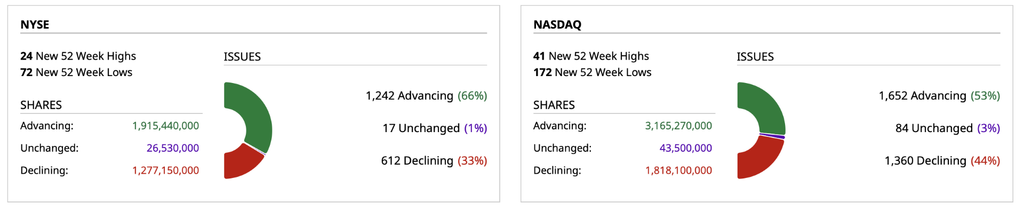
– NYSE volume 7% above its one-month average; Advancers lead decliners by 1.6:1
– NASDAQ volume 0.5% above its one-month average; Advancers lead decliners by 1.4:1
– VIX index: down 6.41% to 15.34
Breadth
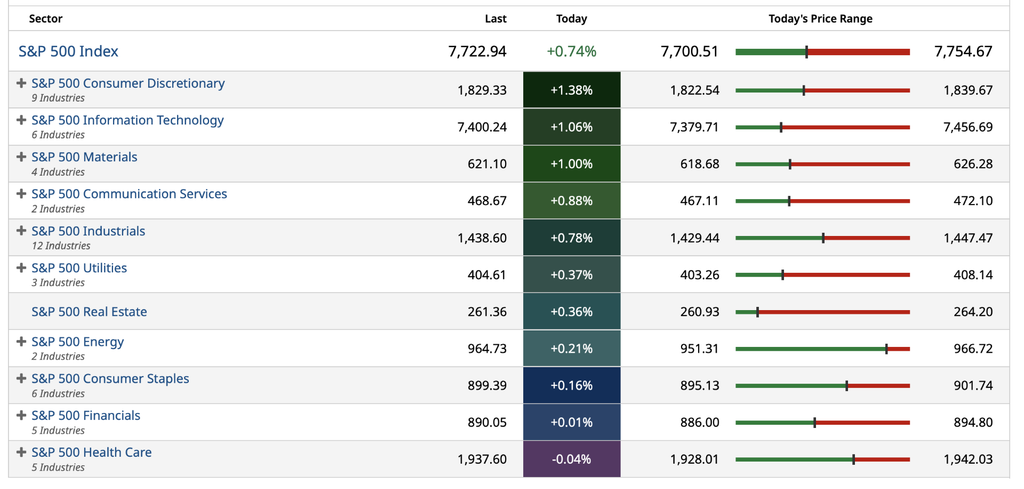
S&P 500 Sectors
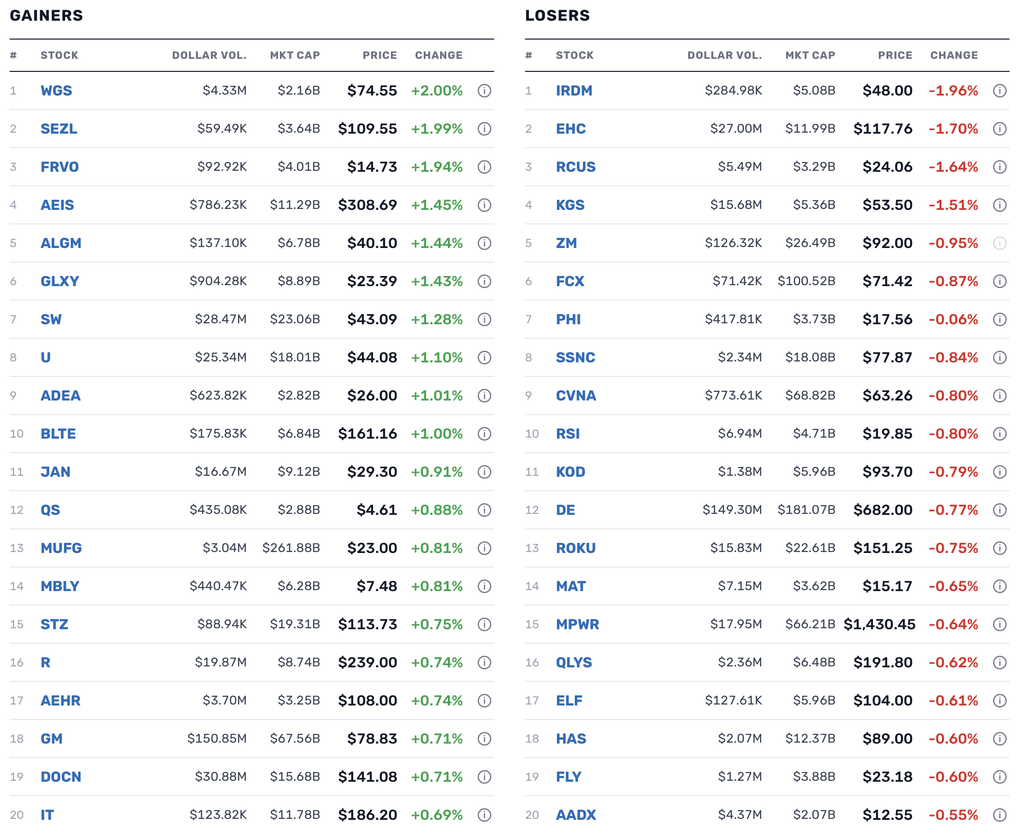
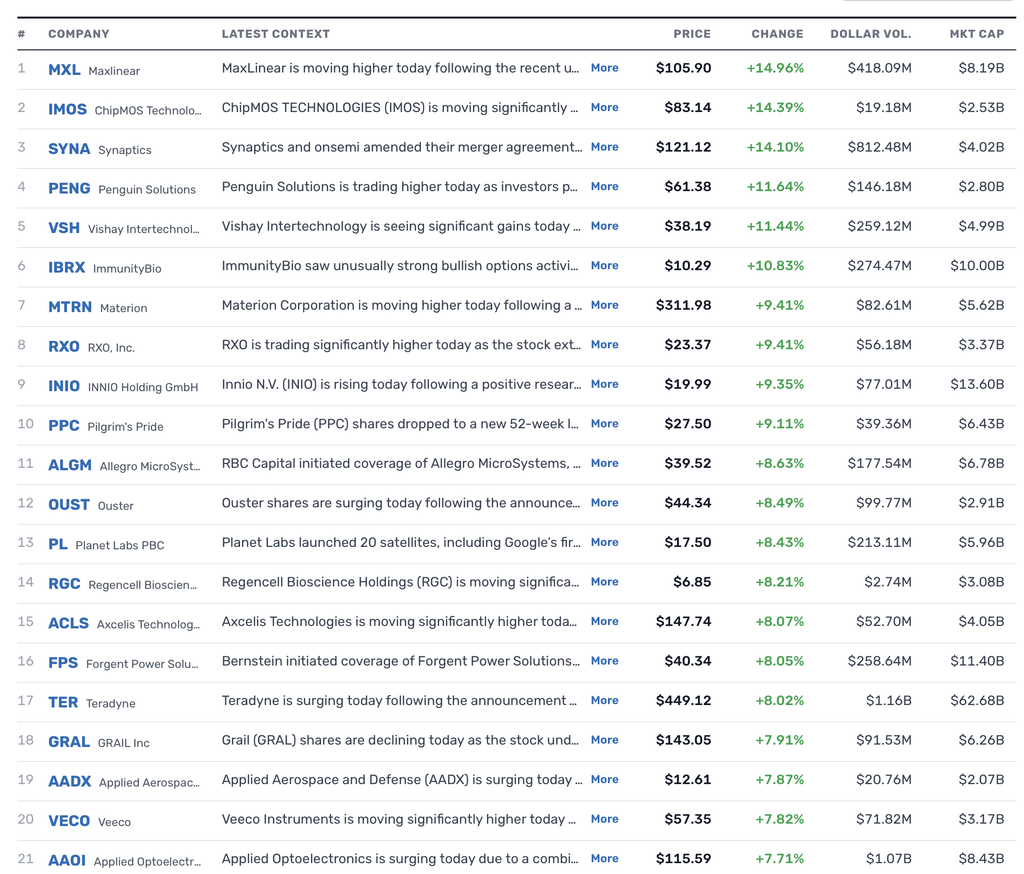
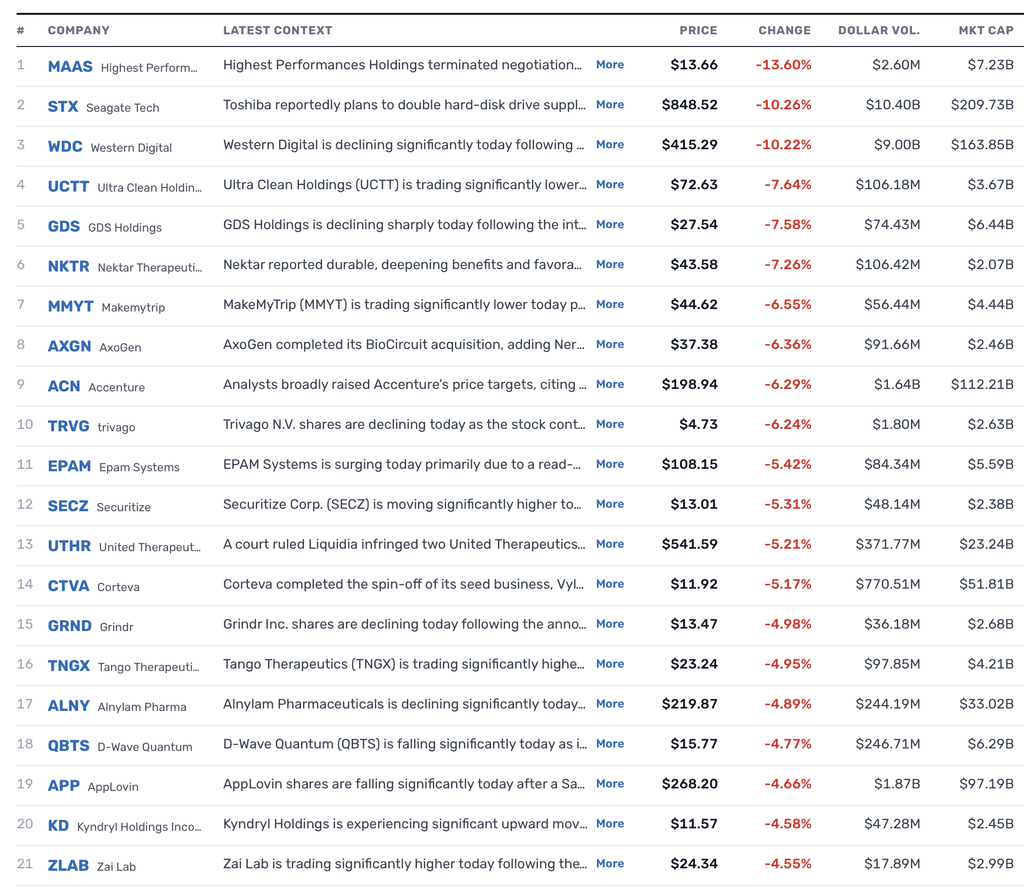
% Movers
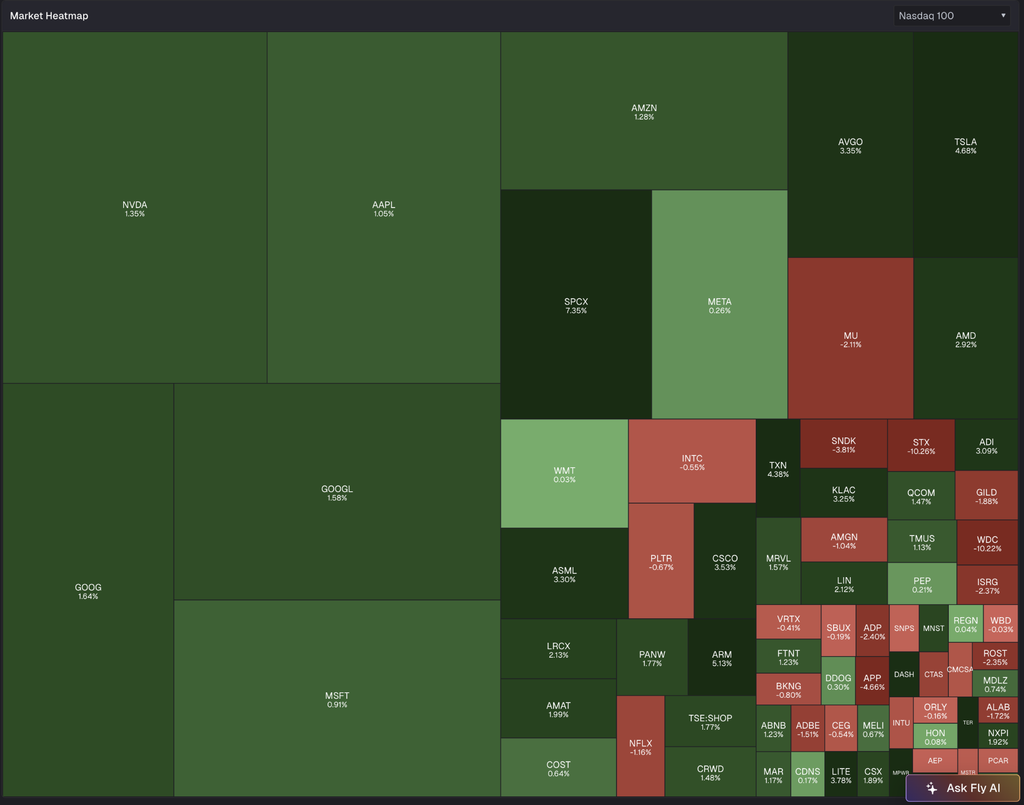
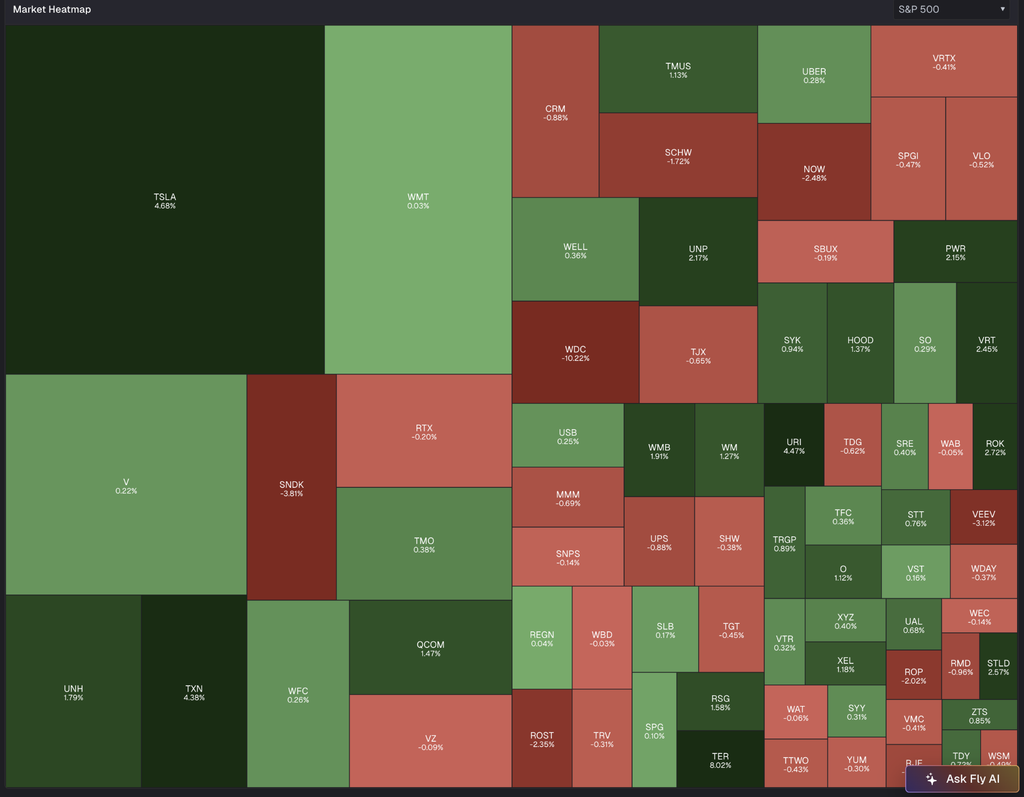
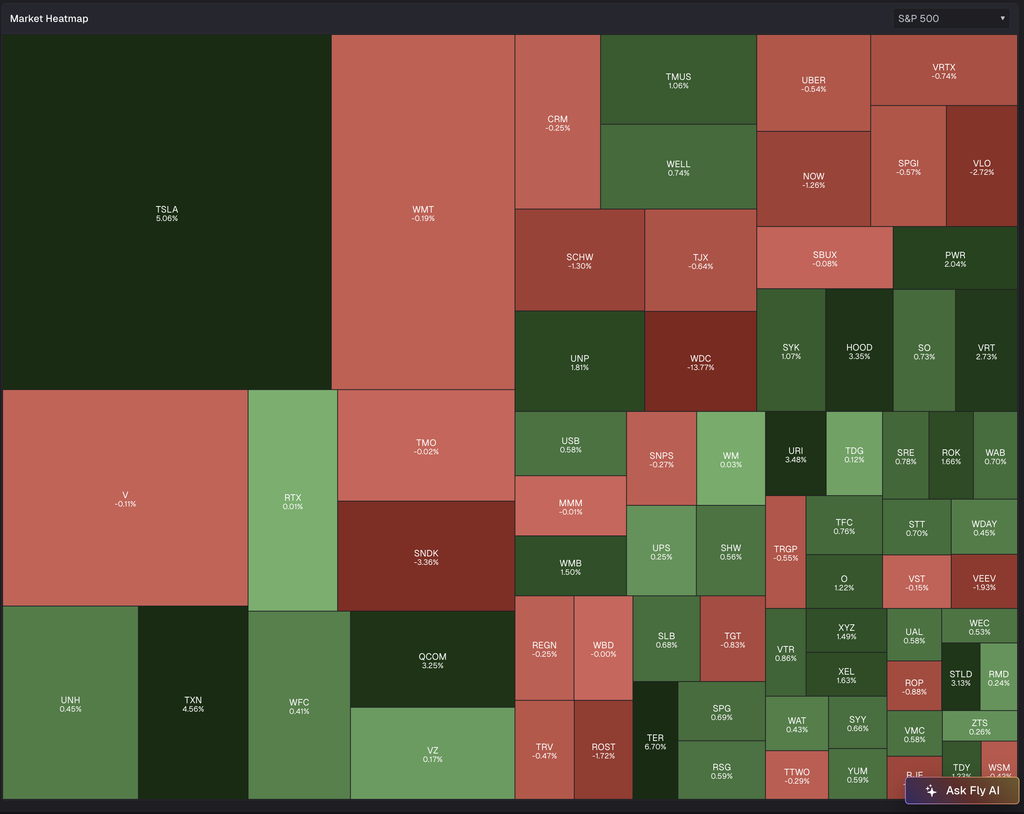
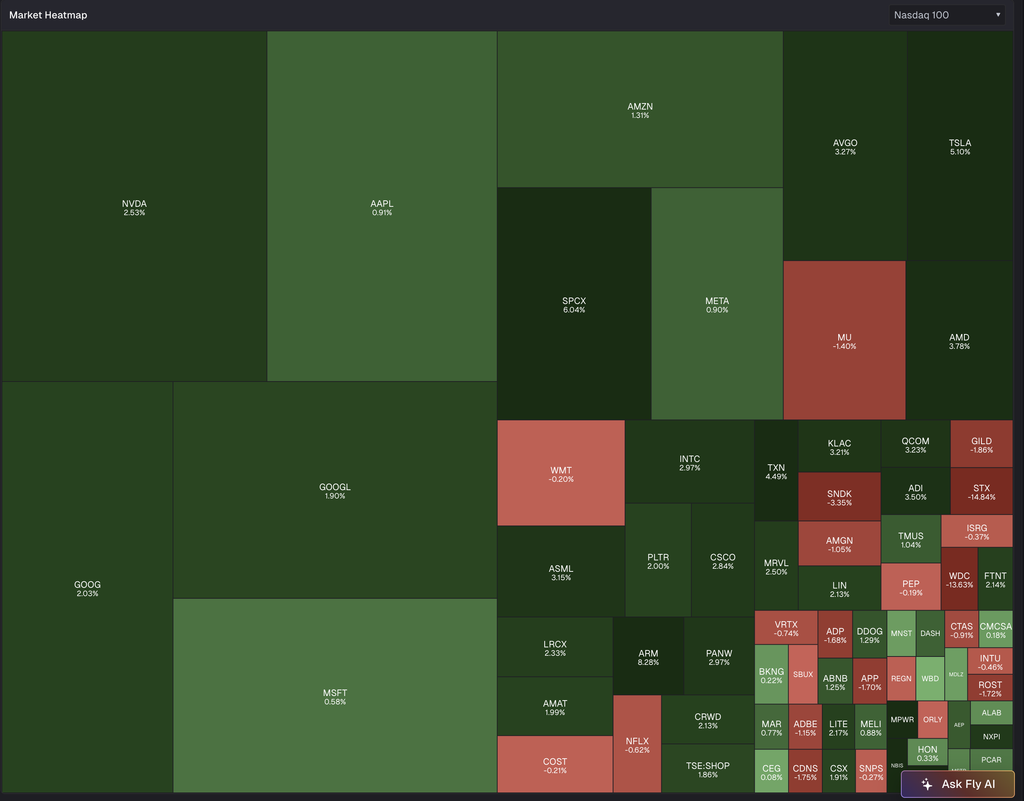
Heat Maps
Position: None
BY Doug Kass · Oct 2, 2026, 4:30 PM EDT
I started writing for TheStreet in late 1997.
This month marks the beginning of the thirtieth year writing my Daily Diary.
I am not sure whether there are any other writers in the business media that have delivered a daily column for nearly three decades.
Thanks to our subscribers for providing me with this forum over the last 29 years (yikes!).
Thanks, too, for your comments and constructive criticism.
Finally, a special thanks to the editorial staff for getting up too early every morning and for dealing with my ramblings professionally and expeditously.
Enjoy the weekend and be safe.
Here is to another 29 years!
Position: None
BY Doug Kass · Oct 2, 2026, 3:55 PM EDT
phillip brantley
Nice column in Financial Times by Bill Gross, “Don’t Own Bonds and Be Cautious About Stocks.” It’s a little dated (09-30-2026) and I don’t know if anyone here has talked about it.
“In such an environment [uneven balance sheet growth], my view is: don’t own bonds, with the exception of one-year Treasury bills, which are now at 4.55 per cent. Be cautious with stocks at record levels as higher yields over time will contract profit margins. Be prepared for the end of “what you are used to” stock markets and higher volatility in prices for the benchmark 10-year Treasury bonds. In terms of specific sectors, I am leery of hyperscalers unless they have price-earnings ratios of less than 20. And while I don’t own these stocks, the decent yields of Verizon and AT&T might be attractive for some conservative investors in the US market — though their businesses are threatened now by SpaceX’s Starlink Mobile in terms of mobile telephone markets. There might also be opportunities in income funds trading at a discount to net asset values. Nuveen Preferred & Income Opportunities Fund, to cite an example where I don’t have a holding, is trading at about an 8 per cent discount to NAV and yields 11 per cent. However, like others in the sector, it would suffer if short rates move higher than expected. Preserve and protect is my current investment motto.”
Position: None
BY Doug Kass · Oct 2, 2026, 3:35 PM EDT
Scott Galloway’s No Malice/No Mercy.. “Less for More.”
Less for More – by Scott Galloway – Prof G Media
Position: None
BY Doug Kass · Oct 2, 2026, 3:05 PM EDT
It’s (more than) interesting that a priority (released yesterday) of the IRS is to rule on 280E guidance (UTP):
Position: None
BY Doug Kass · Oct 2, 2026, 2:50 PM EDT
Here are today’s things:
* I shorted SPY at $771.85 and QQQ at $752.11.
* I covered SPY at $767.90 and QQQ at $748.45.
* I added to MSOS at $4.40, GLAS at $5.10 and GTBIF at $6.66.
Position: Long MSOS common (VL) and calls, GLAS (S), GTBIF (S)
BY Doug Kass · Oct 2, 2026, 2:41 PM EDT
Position: None
BY Doug Kass · Oct 2, 2026, 2:30 PM EDT
Wolf Street howls about the composition of the jobs report.
Private Sector Employers Created 46,000 Jobs, Governments Shed 17,000 Jobs | Wolf Street
Position: None
BY Doug Kass · Oct 2, 2026, 2:15 PM EDT
Position: None
BY Doug Kass · Oct 2, 2026, 2:00 PM EDT
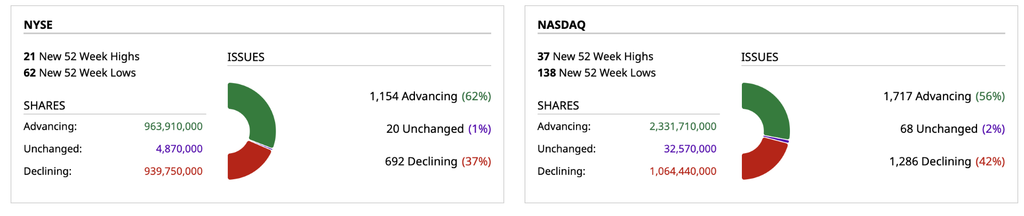
Bulls should be emboldened by the continued strength in large-cap technology (Mag 7).
Bears should be emboldened by weakness and reversal (lower) in gold prices, bond prices and banks/financials — as well as the lackluster market breadth relative to the size of the rise in the indices:
Position: None
BY Doug Kass · Oct 2, 2026, 1:25 PM EDT
From Peter Boockvar:
Positives,
1) ADP said 90k net new private sector jobs were added, 15k above the estimate and after a 36k print in August. Positively, companies of all sizes added workers. As for pay, the median y/o/y gain for ‘job stayers’ was 3%, unchanged with August. For ‘job changers’, base pay rose 4.8% y/o/y vs 4.7% in the month before. The 3 month average is 57k vs the 6 month average of 82k and the one year average of 63k.
2) The initial filing of benefits totaled just 197k, 3k less than expected and vs 198k in the week before. The 4 week average fell to 200k from 203k. Continuing claims dropped by 11k w/o/w to 1.701mm, remaining about 200k below the trend seen last year.
3) In the Challenger September hiring/firing data, with regards to layoffs, they fell 20% y/o/y and lower by 18% m/o/m. Hiring’s rose from August but declined by 23% y/o/y. They said, “Companies are in a wait-and-see period right now. Employers are facing high energy costs, an uncertain war in Iran, a rate hike that could make hiring more expensive, plus the likelihood of surging healthcare costs. We’ve seen layoff activity subside over this year, and September continues to illustrate this point.” On the job creation side, “Hiring plans are up over the year, but we’re not seeing the surge of hiring plans that come with the holiday season, which suggests a very cautious approach.”
4) With the tweak to the PCE calculations in portfolio management, computer software and legal services, headline August PCE rose .3% as expected while the core rate was higher by .2% vs the .3% estimate. The y/o/y gains are 3.4% and 3% respectively.
5) The September ISM manufacturing index was little changed at 54.5 vs 54.6 in August but holding well above 50. Notwithstanding the little change in the headline, industry breadth weakened a touch with 12 industries reporting growth vs 15 in August. Those seeing a contraction totaled two, the same last month with the balance seeing no growth.
6) In the September National Rent Report from Apartment List, the national median NEW (as opposed to renewal which always runs well above) rental rate fell by .1% m/o/m and by .4% y/o/y. They did say though that “y/o/y growth has been steadily inching up and the vacancy rate is moving down, signaling a gradual tightening of rental market conditions.”
7) From Carnival: “The improvement in booking trends we highlighted on our last call continued to build throughout the quarter, with better close-in demand translating into higher revenues. That momentum also enabled us to raise our yield expectations for the fourth quarter.” With guidance, “For full year 2027, we are already half booked, with both occupancy and pricing at record levels. Bookings taken over our third quarter solidified this position, as we saw very healthy increases compared to last year’s levels.” And, “Demand remains broad-based, including very healthy demand for our peak summer European deployments. 2028 is also off to an excellent start at higher occupancy and even higher prices y/o/y. And our booking curve is further out than it has ever been at this point in the year.”
8) From Accenture: “Growth was broad based across markets, industries and both types of work, and we once again took significant market share…Our focus on being relevant where our clients are spending helped us capture the strong level of bookings even though the overall demand environment, including discretionary spending, did not meaningfully change.”
9) From Jabil: Their ‘Intelligent Infrastructure’ group saw revenue up 56% y/o/y and driven by “First, AI related demand remained very strong and continue to accelerate, exceeding the significant growth we had already incorporated in our June outlook. Second, capacity came online sooner than planned and customer ramps progressed better than anticipated, allowing us to support that higher level of demand.”
10) From Micron: Positive for them, “As strong as fiscal 2026 was, we expect fiscal 2027 to be even better. Industry demand has strengthened since our last earnings call, and we expect memory and storage supply-demand conditions to be much tighter in fiscal 2027 and 2028 than they were in 2026.”
11) From CarMax: “Used unit comps grew 13%, driven largely by improved price competitiveness.” On their consumer, “affordability is on everyone’s mind. If you look at every single discussion around that…and our focus on having incredibly competitive pricing. And the other word I would say about the consumer is resilient, at the end of the day. Across all the different spectrums, at the lower end consumer to the higher end consumer, we’re definitely seeing resiliency there. I mean, the broader industry is down 1% or flat to 1%, and we posted comps at 13%.
12) The September global manufacturing PMI’s seeing a m/o/m lift, Taiwan 56.7 vs 54.7, South Korea 53.9 vs 52.3, India 55.1 vs 52.8, Thailand 54.3 vs 53.8, Indonesia 52.4 vs 49.8, the Eurozone 52.9 vs 52.7 and in the UK 51.9 vs 51.7.
13) China’s more private sector weighted PMI improved in September with manufacturing at 52.1 from 51.5 and services up a touch to 51.6 from 51.4.
Negatives,
1) Payrolls were softer than expected, rising 29k in September and below the estimate of 90k. The prior two months were revised down by a total of 60k. Of this, private sector jobs grew by 46k vs 89k in the month before (down from the initial print of 127k) with a drop in government. The household survey reflected strong job growth, though this is a very volatile monthly number, rising by 406k but because it didn’t keep up with the rise in the labor force of 485k, the unemployment rate ticked up to 4.2% from 4.1%. Hours worked were unchanged at 34.4 while average hourly earnings disappointed with just a one tenth m/o/m gain and higher by 3% y/o/y. Combine the two and average weekly earnings were up 4.2%. The all in U6 rate though fell one tenth to 7.6%. Seen in the rise in the labor force, the participation rate was up by 2 tenths to 61.8% and that matches the most since March. The key 25-54 yr old cohort saw an unchanged participation rate of 83.4%. Smoothing out the monthly volatility, the 3 month job gain average is 51k vs the 6 month average of 66k and the 12 month average of 41k. For perspective, in 2019 the monthly job gains were 165k.
2) August job openings shrunk to 7.079mm from 7.335mm in the month before. The hiring rate was 3.3%, up from 3.2% in July and vs 3.4% in June and 3.3% in May, hovering around the lowest since the early 2010’s. The quit rate was unchanged at 1.9%.
3) Income growth in August was only .2% m/o/m vs the estimate of up .5% and July was revised down by a tenth to a .3% gain. Private sector wages and salaries were higher by .3% m/o/m. Spending was as forecasted, rising by .9% m/o/m helped by both goods and services, particularly on gasoline and healthcare. The difference was another drop in the savings rate to 4.1% from 4.6% and that is the lowest since September 2008 not including Covid.
4) The September consumer confidence index from the Conference Board fell to 81.9 from 88.6 and that was 7 pts below expectations. This is a level last seen in 2014 but when it was still accelerating post GFC. The Present Situation declined by 8 pts and the Expectations component was lower by 6 pts. A major factor in this decline, one year inflation expectations rose to 6.1% from 5.8%. Also negatively impacting the mood, there was softness in the labor market questions. Spending intentions were down for the big tickets items such as vehicles and homes.
5) Auto sales in September totaled 15.98mm at a SAAR. That’s below the estimate of 16.3mm and compares with 16.39mm in September 2025 and vs 17.19mm in September 2019.
6) The MBA said the average 30 yr mortgage rate rose to 7.3% from 7.12% in the week before and vs 6.79% one month ago. In response, purchase applications fell 4.3% w/o/w and down 14% y/o/y. Refi’s were lower for a 6th straight week, down 8.7% w/o/w and by 56% y/o/y.
7) Good news for those that own a home but if the housing market is going to cushion the blow of higher mortgage rates in terms of affordability and jump start the pace of transactions, we need lower prices. In July S&P Cotality said its national home price index rose by another .3% m/o/m and by 1.9% y/o/y.
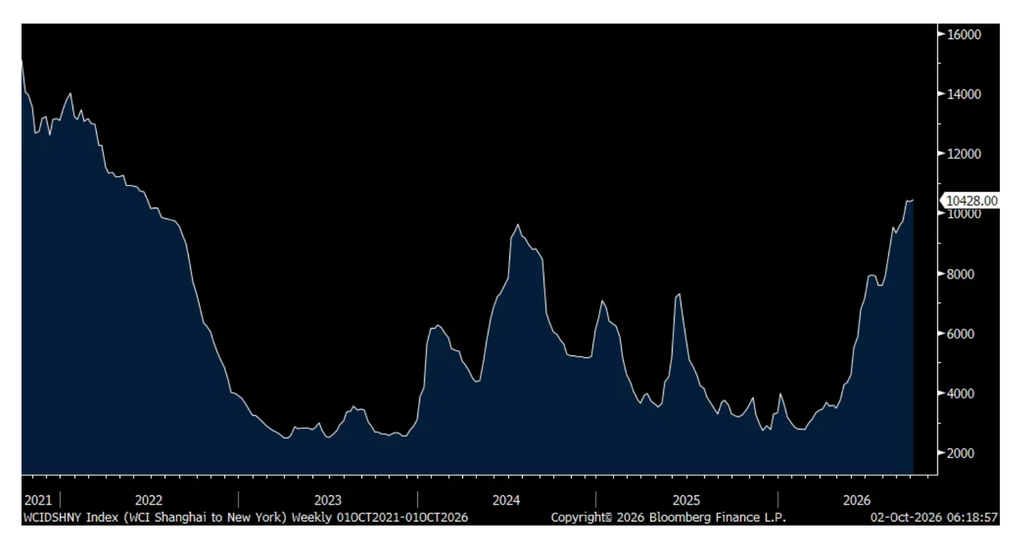
8) Container shipping prices were little changed from Shanghai to both NY and LA, though hovering around the highest since June 2022.
9) The high yield CCC spread now trades above 1000 bps.
10) As seen with a 24 yr high touched in yields, at least in France investors are worried about debts and deficits.
11) From Nike: “Overall, there’s a lack of energy in the lifestyle space right now, which is impacting traffic. Yes, the consumer is cautious, but as the leader in the industry, it’s on us to bring more creativity to sportswear.”
12) From McCormick: “Geopolitical volatility, elevated fuel costs, and persistent inflation continue to influence consumer confidence and spending. In the US, higher gas prices and the Cyclospora outbreak have added pressure and contributed to softer traffic across foodservice and grocery channels…Consumers continue to look for practical ways to manage their budgets, including using what’s already in their pantry, repurposing leftovers, and seeking simple, affordable ways to add flavor at home. At the same time, flavor exploration, health and wellness, and affordable indulgence remain important priorities, supporting demand for flavorful, convenient meal solutions across retail and foodservice.”
13) From Conagra: “Consumers continue to be thoughtful about where they spend their dollars, and we’re managing through a volatile input cost environment…Convenience store is an example that’s been a bit more pressured in recent months because of the gas prices. But overall, I would say the consumer has been relatively stable and resilient.” Also, “Inflation, inclusive of both core inflation and our tariff wrap, came in at roughly 5% in Q1. While still elevated, we saw favorability relative to our expectations primarily in proteins. However, we also saw an acceleration in fuel and logistics costs throughout the quarter, which we expect to further impact Q2 and the remainder of the year.”
14) From Jabil: With respect to memory and semi’s, “We’re seeing real constraints today. Memory in particular is being reallocated towards AI and hyperscale demand, tightening supply across many of the diversified end markets that we serve.”
15) Tokyo inflation in September rose 3% y/o/y ex food and energy and that was well above the estimate of 2.5% and up from 2% in August.
16) The September Eurozone CPI was up 3.8% y/o/y, one tenth above the estimate and up from 3.2% in August. The core rate rose 2.5% as expected.
17) The September global manufacturing PMI’s seeing a m/o/m decline, Japan 54.1 vs 54.9, Australia 49.6 vs 52, Vietnam 51.9, 53.3, Malaysia 49.9 vs 50.2, and the Philippines 49.6 vs 54.9.
18) The August 3.6% gain in Australia’s trimmed mean CPI validated the rate hike seen to 4.6% by the RBA.
19) The September Eurozone Economic Confidence index fell to 97.9 from 98.4 and vs 97.1 in July. Manufacturing keeps improving and services ticked up but consumer confidence slipped as did retail. Construction was unchanged.
Position: None
BY Doug Kass · Oct 2, 2026, 1:15 PM EDT
UBS analyst Peter Grom lowered the firm’s price target on PepsiCo (PEP) to $145 from $159 and keeps a Buy rating on the shares.
PepsiCo is facing a “tough” near-term path forward, but downside appears largely priced in, the analyst tells investors in a research note.
Position: Long PEP (VS)
BY Doug Kass · Oct 2, 2026, 12:25 PM EDT
BY Doug Kass · Oct 2, 2026, 12:10 PM EDT
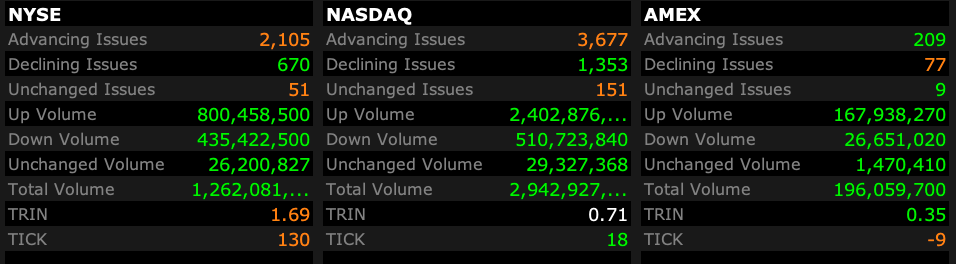
– NYSE volume 7% above its one-month average; Advancers lead decliners by 2.9:1
– Nasdaq volume 1% below its one-month average; Advancers lead decliners by 2.7:1
-VIX index: down 5.13% to 15.55
SOURCE: Interactive Brokers
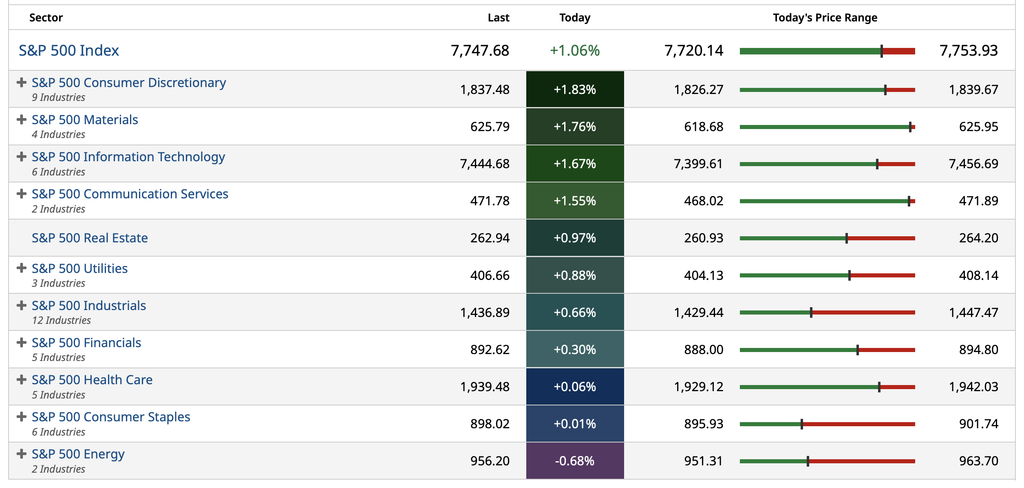
S&P500 Indices
SOURCE: Barchart
% GAINERS, DECLINERS
SOURCE: TheStreet Pro
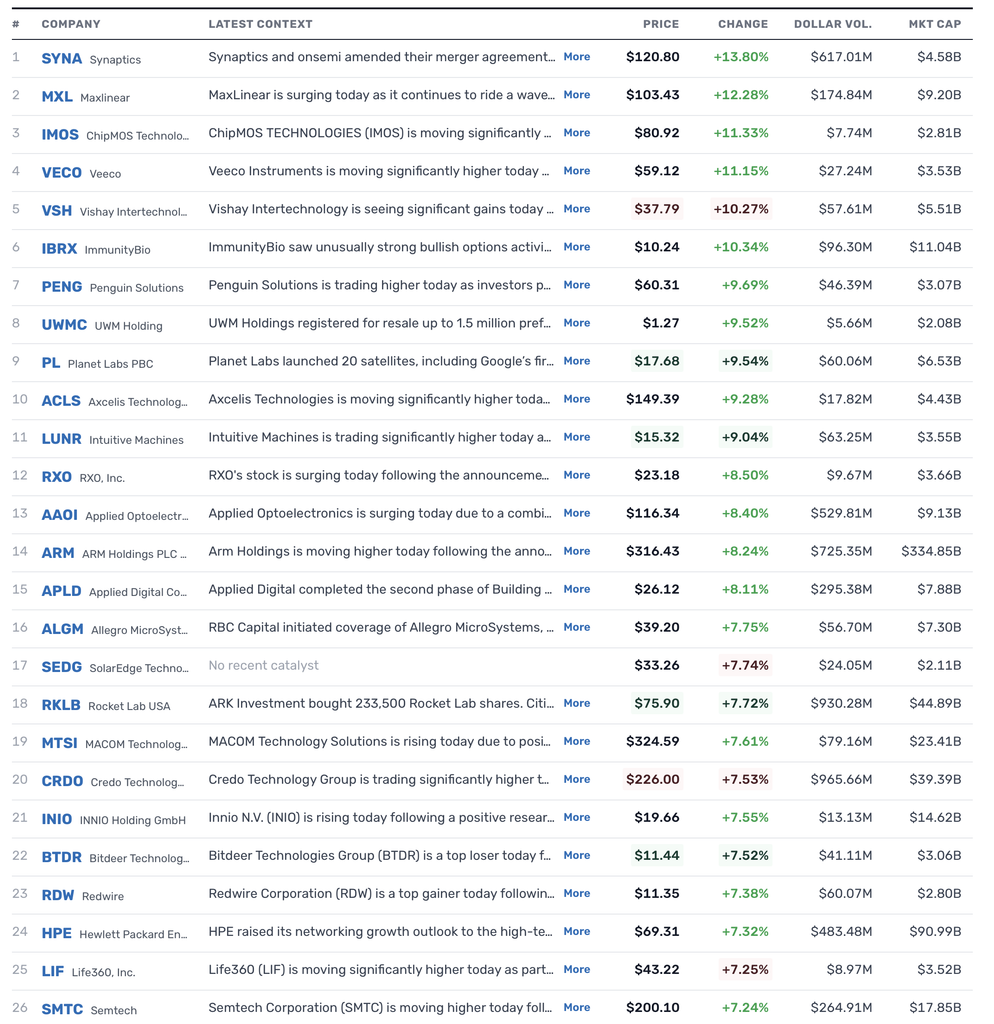
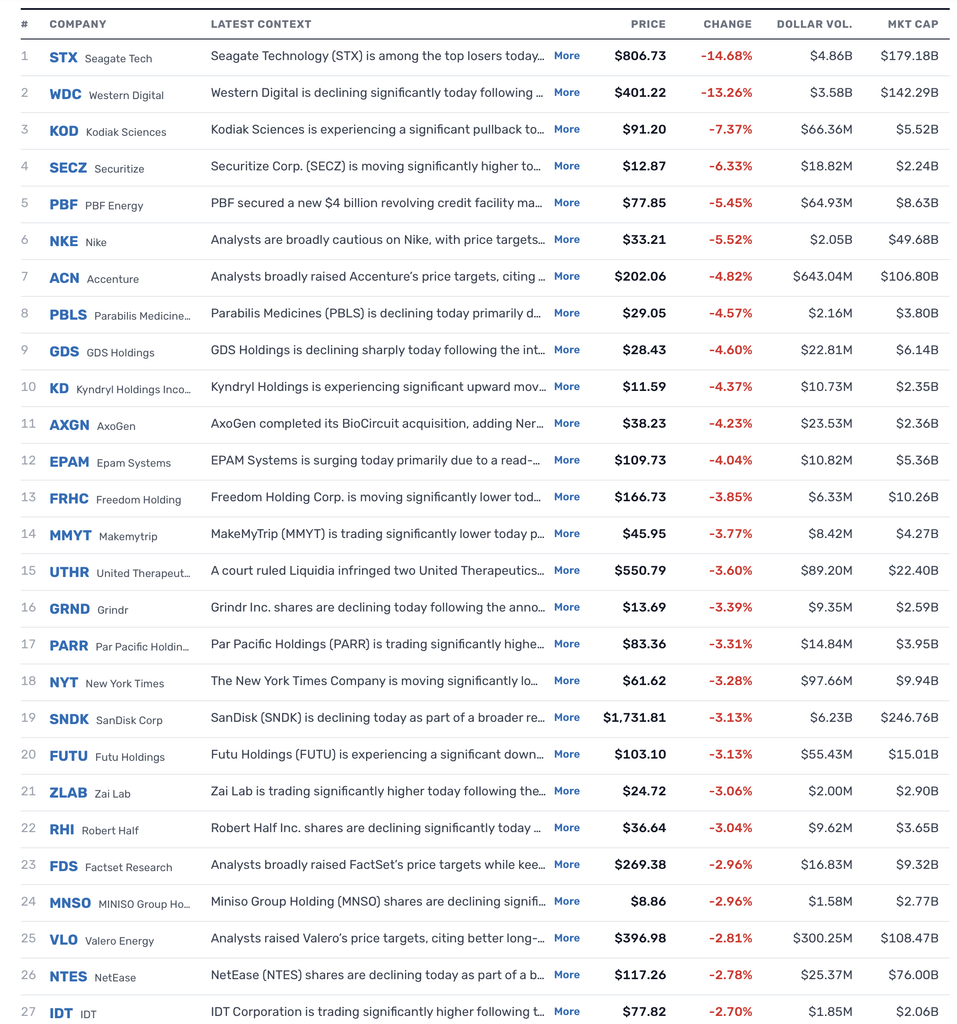
SOURCE TheFly
BY Doug Kass · Oct 2, 2026, 11:50 AM EDT
BY Doug Kass · Oct 2, 2026, 11:40 AM EDT
With SP cash +42 handles I took in half of my Index shorts on the reversal from the highs (for a profit):
* SPY $768.38
* QQQ $749.32
Position: Short SPY VS QQ VS
BY Doug Kass · Oct 2, 2026, 11:26 AM EDT
The weakness in gold (GLD) — from $385 to $381 — is surprising considering the weak jobs data and the softness of the U.S. dollar. ( A similar reversal just occurred with TLT from $78.32 to $77.75).
My reaction is to sell more SPY $771.93 and QQQ $753.76 …
For now it is unclear what the message of the reversal in precious metals and bonds mean – but I am probing and thinking.
Note that we sold out our GLD long (for the fourth time and for a profit) on Wednesday:
Here is one of today’s things:
* I sold my GLD at $386.34
BY Doug Kass · Sep 30, 2026, 9:53 AM EDT
Positions: none.
BY Doug Kass · Oct 2, 2026, 11:11 AM EDT
Positions: None.
BY Doug Kass · Oct 2, 2026, 11:08 AM EDT
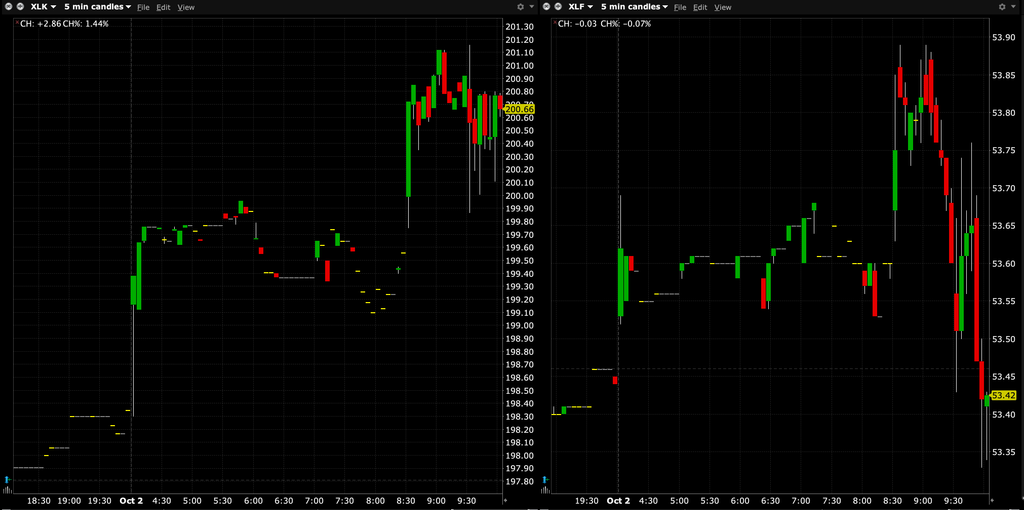
Chart from 10 a.m. ET
BY Doug Kass · Oct 2, 2026, 10:45 AM EDT
I have moved from very small to small sized short the indexes:
* SPY $771.79
* QQQ $752.41.
Positions: Short SPY S QQQ S
BY Doug Kass · Oct 2, 2026, 10:11 AM EDT
The following is from Peter Boockvar:
With his last day today as a regular on CNBC, I have to express my huge admiration for this guy. Rick Santelli is a financial news legend that I will miss watching every day. He’s a man of passion who loves the markets and that will never change even though he won’t be reporting on it each day. I am so lucky to call him a good friend.
Oh, on to the jobs data.
Payrolls were softer than expected, rising 29k in September and below the estimate of 90k. The prior two months were revised down by a total of 60k. Of this, private sector jobs grew by 46k vs 89k in the month before (down from the initial print of 127k) with a drop in government.
The household survey reflected strong job growth, though this is a very volatile monthly number, rising by 406k but because it didn’t keep up with the rise in the labor force of 485k, the unemployment rate ticked up to 4.2% from 4.1%.
Hours worked were unchanged at 34.4 while average hourly earnings disappointed with just a one tenth m/o/m gain and higher by 3% y/o/y. Combine the two and average weekly earnings were up 4.2%. The all in U6 rate though fell one tenth to 7.6%.
Seen in the rise in the labor force, the participation rate was up by 2 tenths to 61.8% and that matches the most since March. The key 25-54 yr old cohort saw an unchanged participation rate of 83.4%.
Of the 46k private sector net jobs created, it was led again by healthcare/social services which contributed 23k. Trade/transport/warehousing hired a net 24k followed by leisure/hospitality which added another 10k.
On the slip side, jobs were lost in information, financial services and business services.
Construction continued to be an area of job growth, with another 11k added. Manufacturing’s recovery, helped by making things going into data centers, along with inventory restocking, saw a 9k person hiring uplift.
Smoothing out the monthly volatility, the 3 month job gain average is 51k vs the 6 month average of 66k and the 12 month average of 41k. For perspective, in 2019 the monthly job gains were 165k.
Bottom line, the debate continues as to what the monthly job gains are needed in order to satisfy the increases in the labor force which we know have slowed. I’ve seen estimates everywhere from zero to north of 50k so the 3 month average is kind of in the range.
Treasury yields are seeing further relief, falling post softer than expected number. I’ll say again that we won’t get an October rate increase and not even worth guessing about December as it’s too far away.
BY Doug Kass · Oct 2, 2026, 9:55 AM EDT
The following is from Peter Boockvar:
With regards to the jobs data today, I’m most focused on the breadth of job gains. Will we see more hires outside of just construction, healthcare and leisure/hospitality?
I attribute the reversal higher yesterday in Treasuries/lower in yields to the German bund rally intraday where bunds became a safety trade as French and Italian bonds were selling off. That then shifted to US Treasuries. You’re seeing it again today, German bund yields lower by 8 bps after the 8 bps drop yesterday while French and Italian yields, while flat today, remain at their lows.
The Fed is not going to hike in rates in October and add Michelle Bowman and Vice Chair Jefferson to the list of Fed voting members, John Williams was the first, telling us so. Bowman late yesterday said “I don’t currently see an urgent need for further action, and I think we need to better understand the totality of the data, but remain attentive to the risks.”
This followed Philip Jefferson who said “As we look ahead, my view is that any future adjustments in policy should be determined by carefully examining trends in the data, the evolving outlook and the balance of risks. My colleagues and I will need to come to our own judgment which may take more time.”
Since Williams spoke on Tuesday, the 2 yr yield has fallen by 15 bps. Rate hike odds have declined from 70% Monday to 24% today.
Auto sales in September totaled 15.98mm at a SAAR. That’s below the estimate of 16.3mm and compares with 16.39mm in September 2025 and vs 17.19mm in September 2019. We are thus 7 yrs past that 2019 figure and vehicle sales are still below with used car sales picking up the slack because of the affordability challenge of buying a new car.
Out yesterday, container shipping prices were little changed from Shanghai to both NY and LA, though hovering around the highest since June 2022.
Shanghai to NY
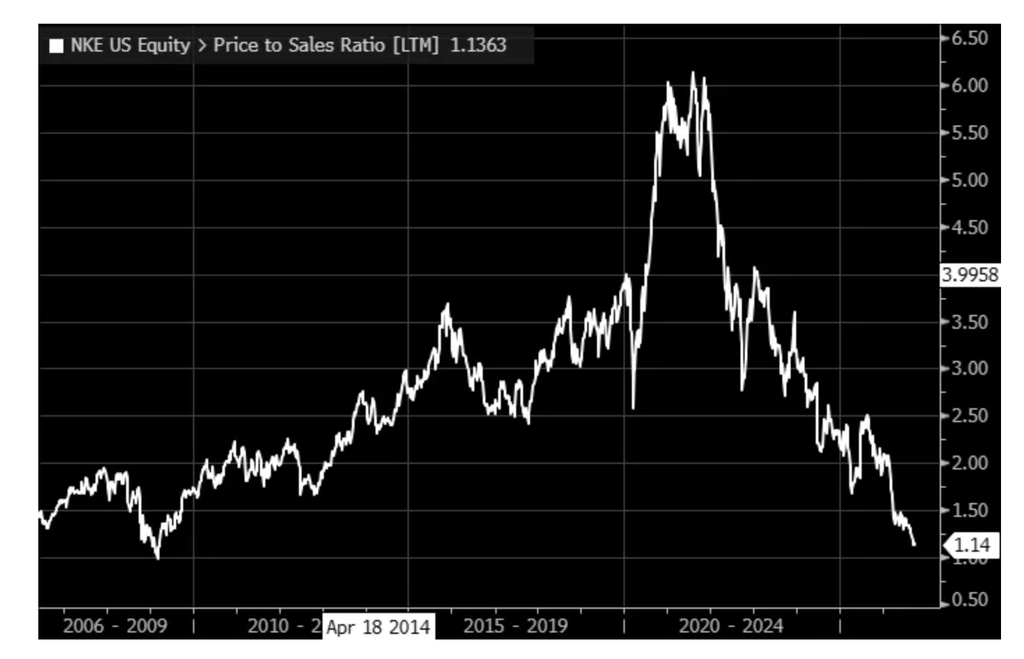
I believe in the swoosh and iconic brand that is Nike. I believe in Elliott Hill and the new CFO. I believe in the upcoming product lines, particularly the new Caitlin Clark sneaker and their ability to create excitement again with their SKUs. I believe in the shift away from mostly relying on DTC. I believe that they are still the dominant sneaker maker in the world with still a global market share of about 20%. I believe its Jordan brand and its China business can be stabilized. And while the price relative to earnings seems high, I believe it’s because they are dramatically under earning relative to the potential and the price to sales ratio is back to a level last seen in early 2009, at the absolute bottom of the US stock market back then at the depth of the GFC. I’ll take that nearly 5% dividend yield too.
Here were some things of note said by them last night:
“Overall, there’s a lack of energy in the lifestyle space right now, which is impacting traffic. Yes, the consumer is cautious, but as the leader in the industry, it’s on us to bring more creativity to sportswear. The headline decline only tells part of the story. Within sportswear, several major franchises are healthy and growing.”
“I believe strongly that we have strengthened the foundation of our business, and our direction is super clear that we’re building Nike the right way and we are building Nike for the long term. And I would characterize that our comeback is ongoing. At our size and scale, meaningful change takes time. Our turnaround is happening one sport, one sport community, one city, one country at a time, and we are reallocating resources against our biggest opportunities. So we are building for the long term.”
Price to Sales Ratio for Nike as of 10/1/26
McCormick, the spice, seasonings and condiment maker, is another battered and beaten stock we’ve recently bought and they said this of note after reporting earnings:
“Geopolitical volatility, elevated fuel costs, and persistent inflation continue to influence consumer confidence and spending. In the US, higher gas prices and the Cyclospora outbreak have added pressure and contributed to softer traffic across foodservice and grocery channels.”
“Consumers continue to look for practical ways to manage their budgets, including using what’s already in their pantry, repurposing leftovers, and seeking simple, affordable ways to add flavor at home. At the same time, flavor exploration, health and wellness, and affordable indulgence remain important priorities, supporting demand for flavorful, convenient meal solutions across retail and foodservice.”
Accenture had a big day yesterday with its stock rallying 16% after earnings. From them of note:
“Growth was broad based across markets, industries and both types of work, and we once again took significant market share.”
“Our focus on being relevant where our clients are spending helped us capture the strong level of bookings even though the overall demand environment, including discretionary spending, did not meaningfully change.”
Overseas of note, Tokyo inflation in September rose 3% y/o/y ex food and energy and that was well above the estimate of 2.5% and up from 2% in August. JGB yields are lower though, following the drop elsewhere but the pressure continues to grow on the BoJ to keep on hiking. The yen is higher.
Also of importance on the inflation front was the September Eurozone print and which was up 3.8% y/o/y, one tenth above the estimate and up from 3.2% in August. The core rate rose 2.5% as expected.
The ECB with a deposit rate of only 2.5% will be hiking again soon too.
BY Doug Kass · Oct 2, 2026, 9:30 AM EDT
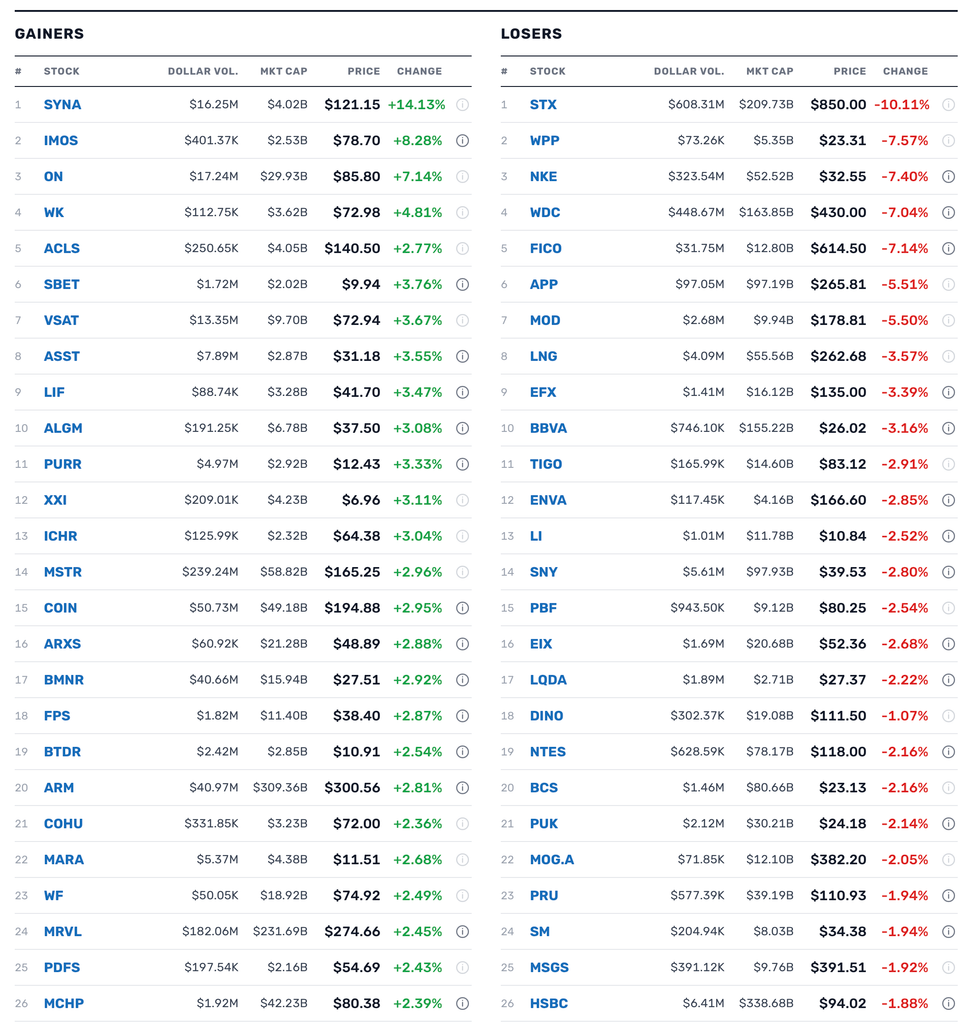
– AMOD +108.5% (closed a bitcoin-funded private placement and regained Nasdaq listing compliance)
– NIVF +40.0% (closed an approximately $1.25M public offering)
– SDEV +36.0% (extends Thursday’s surge in the SKY-token treasury name; no clear fresh company-specific catalyst identified)
– TNMG +20.0% (agreed to sell its Japanese business in a $5.5M management buyout)
– SYNA +15.0%, ON +8.0% (revised merger makes ON’s acquisition of SYNA an all-cash deal at $123 per share)
– CYPH +8.5%, FWDI +6.5%, MSTR +5.0%, COIN +1.5% (digital-asset treasury and crypto-linked names rise as Bitcoin and major tokens rally)
– BETR +7.5% (Cantor Fitzgerald upgrades to Overweight from Neutral)
– XRPN +7.0% (shareholders approved the proposed business combination with Evernorth)
– RZAI -21.0% (extends volatile post-direct-listing selling after Thursday’s 29% drop)
– NXL -20.0% (gives back part of Thursday’s 76% spike following a 10-year Latin American distribution agreement)
– STX -11.5%, WDC -7.0% (HDD makers fall after Toshiba outlined plans to double capacity and target sharply higher market share)
– NKE -9.0% (mixed FQ1 as revenue missed and the FY sales outlook implied a surprise steep decline, alongside job cuts and a business reorganization)
– FICO -8.5%, EFX -3.5%, TRU -2.5% (mortgage-credit names fall on a reported FHFA plan requiring lenders to pull data from two credit bureaus instead of three for GSE loans)
– ASTS -3.5% (B. Riley downgrades to Neutral from Buy)
BY Doug Kass · Oct 2, 2026, 9:13 AM EDT
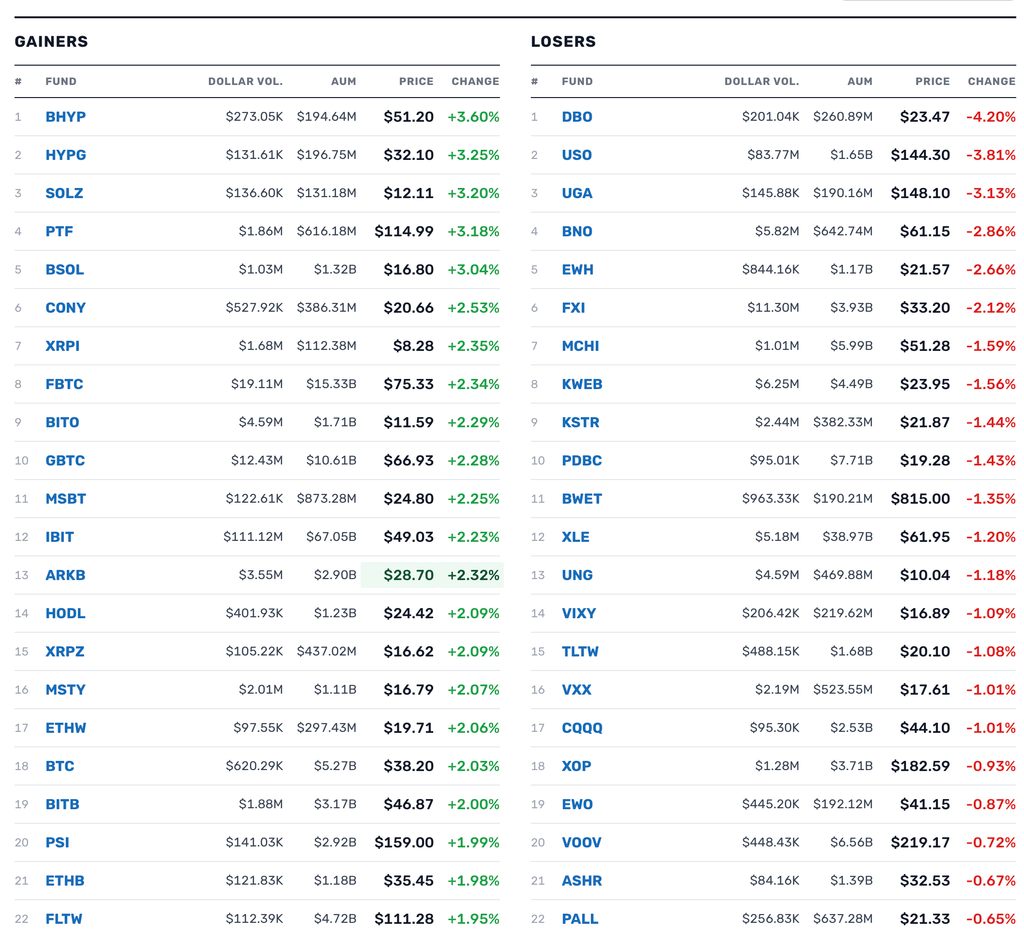
Source: TheStreet Pro
BY Doug Kass · Oct 2, 2026, 9:10 AM EDT
BY Doug Kass · Oct 2, 2026, 9:00 AM EDT
With S&P futures +66 handles and Nasdaq futures +335 handles I am starting a short scale on the Indexes:
Look at the weak average hourly wage data – I am ever more convinced that with real wages dropping since April 2026 and the large drawdown in the savings rate, the consumer is weakening more than consensus realizes.
Positions: Short SPY VS QQQ VS
BY Doug Kass · Oct 2, 2026, 8:42 AM EDT
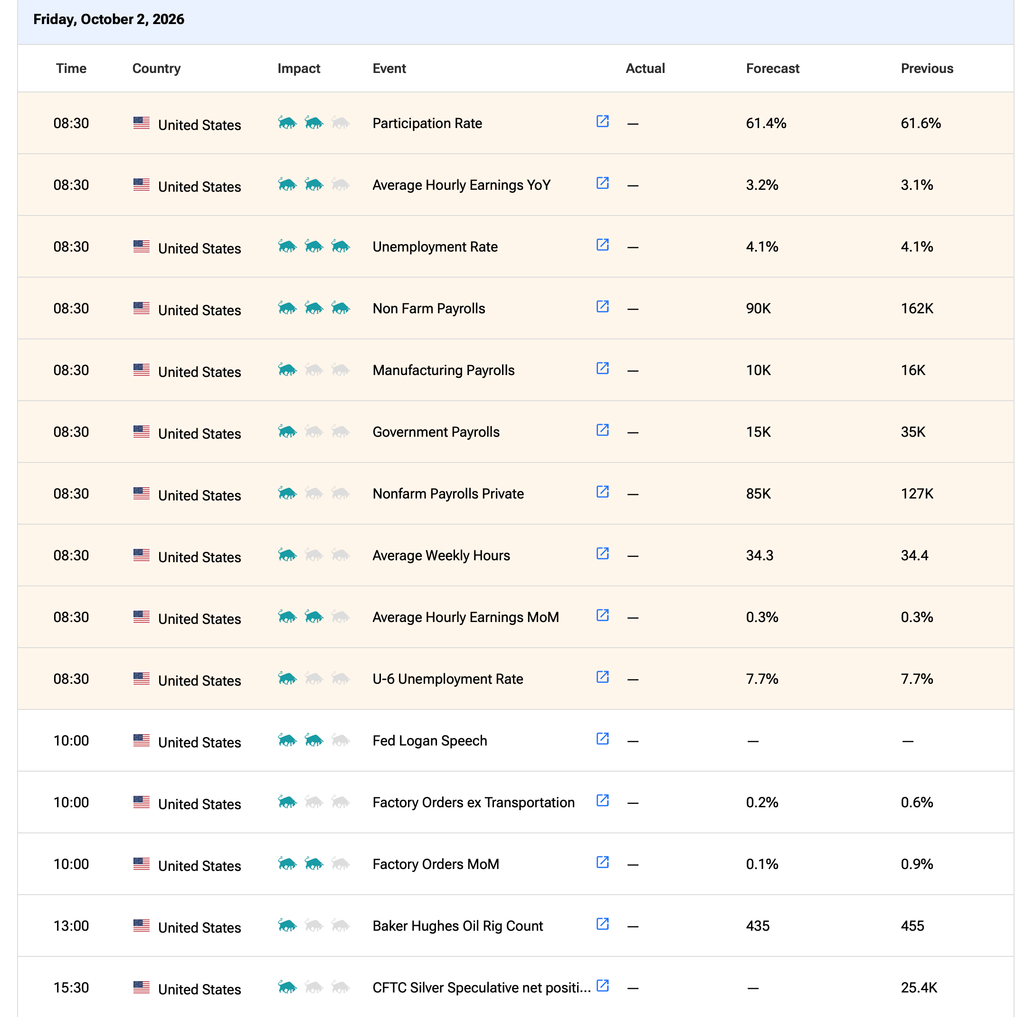
10:00 a.m.: Fed Bank of Dallas President Logan (Voter) gives welcome remarks before the Fifth Annual Workshop on the Macroeco-
nomic Implications of Migration co-sponsored by the Federal Reserve banks of Dallas, Atlanta and San Francisco; Banco de México; Bank of Canada; Instituto Tecnológico Autónomo de México’s economics department; and the Global Migration Center at the University of California, Davis, Dallas, TX (Text available. No livestream. No audience Q&A);
12:00 p.m.: Fed Bank of Chicago President Goolsbee (Non-Voter) Television Appearance — FOX Business.
Positions: None.
BY Doug Kass · Oct 2, 2026, 8:35 AM EDT
SOURCE: TipRanks
BY Doug Kass · Oct 2, 2026, 8:24 AM EDT
During Q3 2026 four equities (stimulated by perceived AI growth opportunities) — MSFT, NVDA, AAPL and META — added about 300 points to the gain in the S&P index, representing more than 200% of the index’s total gain. The other 496 stocks subtracted approximately 150 points:
Back to AI “concentration” credit risks — specifically that private equity (we remain short BX, APO, OWL and KKR) is piling into the same AI data center bet:
Carlyle warns private credit is piling into the same AI data center bet
More on depreciation schedules and creative accounting:
Finally, continued AI skepticism from “Moon Alice” — Roger McNamee:
and…
Position: Short BX (VS), KKR (VS), APO (VS), OWL (VS)
BY Doug Kass · Oct 2, 2026, 6:45 AM EDT
The S&P Short Range Oscillator lifted back into a deeper oversold state at -5.57% vs. -5.17%.
This — combined with other sentiment factors — has kept me from shorting the indices over the last few days.
Position: None
BY Doug Kass · Oct 2, 2026, 6:11 AM EDT
Wolf Street howls about the frozen existing home market.
Position: None
BY Doug Kass · Oct 2, 2026, 5:45 AM EDT
🗞️ Recreational Marijuana Would Be Legalized In Florida Under Two Newly Filed Ballot Measures 🔎 "For any of the three currently pending marijuana legalization measures to make the 2028 ballot, organizers will need to submit 880,062 valid signatures from registered voters." Show more
MSFT, NVDA, AAPL and META alone added about 300 points to the S&P in Q3, more than 200% of the index's total gain. The other 499-ish stocks together subtracted about 150 points: Citadel


NEW: The IRS and Department of the Treasury have formally made guidance on Section 280E a federal priority for the coming year, a potentially consequential development for marijuana businesses navigating the tax effects of recent federal scheduling changes themarijuanaherald.com/2026/10/irs-28…
Before sub-prime was a crisis, investors betting against the bubble drove around to see the residential properties backing MBS. It was a lot of legwork. Now with satellite imagery and this convenient list of assets about to enter bankruptcy protection, betting against the AI Show more


You are spot on @DougKass. This noise was pure bot scraping on a headline and puts playing a "delay". Over the last two days I have posted on the details of this as well. I am in for the larger move and this range is still sitting at the base of a longer parallel I have over the Show more

$MSOS just an FYI - my degree is in legal research and this topic is of interest to me so hence why I am sharing my thoughts. Looking at this has been fascinating to say the least so I am sharing my opinion here The GAO Cannabis Report: A Procedural Masterstroke or a Dangerous
The thing with @moonalice.com is that 1) he's not selling anything, 2) he has more legacy/history here than most, 3) all of which means he can speak his mind w/o fear of recourse. "Markets have manias; this is a mania." And so much more... cnbc.com/video/2026/09/…
Nvidia's bet that its chips can finance the AI boom gets a Wall Street reality check reut.rs/4jwcYF1 reut.rs/4jwcYF1
🚨 GOLDMAN SACHS DROPS DOOMSDAY STATEMENT: U.S. BONDS HAVE NO BUYERS Goldman Sachs just admitted the long end of U.S. Treasury market is “totally bidless.” Translation: almost nobody wants the 10- to 30-year debt the U.S. is trying to sell. No buyers. None. Zero. While Show more

日本銀行が準備している措置は、数十億の人々の生活に影響を与えるでしょう。 西側諸国の皆様、深くお詫び申し上げます。 これは個人的な問題ではありません。 神のご加護がありますように。
Everyone should read @LuizaJarovsky. Her newsletter is brilliant. The “unpopular opinion” below is the clearest description I have read of the choice we face. Just say “no.”

Unpopular opinion: AI companies are pushing society to accept an unacceptable level of risk for a non-essential technology.


