Staples Slide
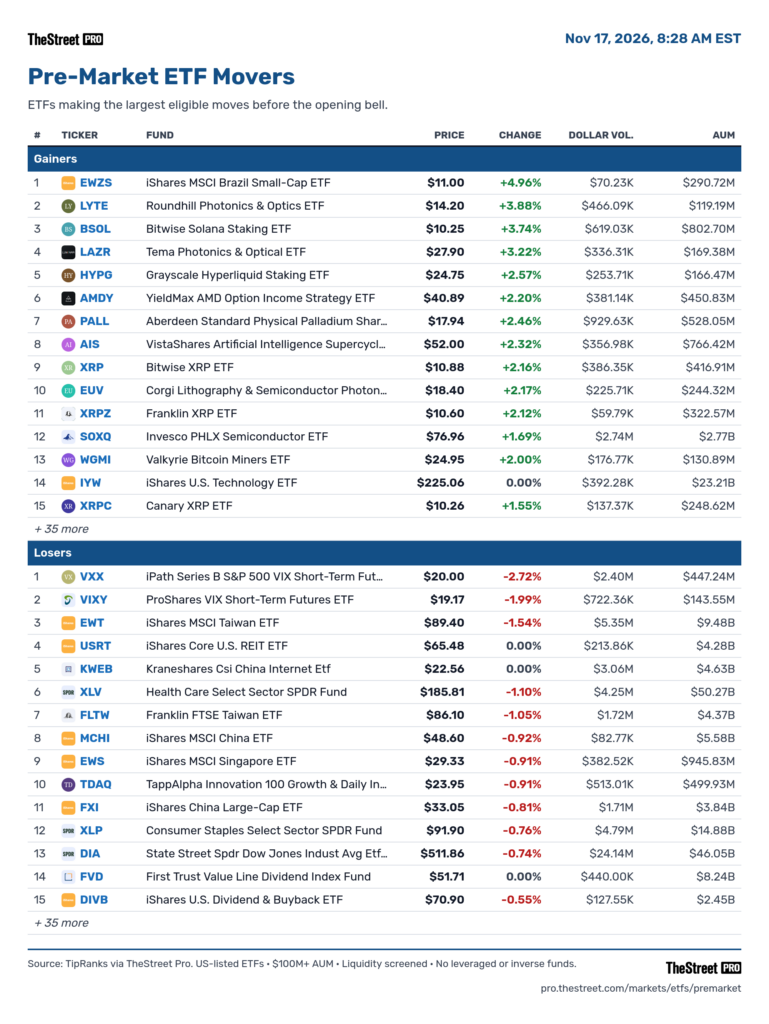
Consumer staples stocks are in shambles today (we previously sold 99% of our positions): PEP -$4.20, KMB -$3.15, PG -$1.09, KO -$0.55.
Position: Long KMB (VVS), PG (VVS), KO (VVS)
BY Doug Kass · Nov 17, 2026, 3:05 PM EST
 Doug KassDoug Kass
Consumer staples stocks are in shambles today (we previously sold 99% of our positions): PEP -$4.20, KMB -$3.15, PG -$1.09, KO -$0.55.
Position: Long KMB (VVS), PG (VVS), KO (VVS)
BY Doug Kass · Nov 17, 2026, 3:05 PM EST
From the Fed’s Williams:
* Inflation is not moving in the right directions, Fed still has more work to do
* Economy is strong and getting stronger but inflation not moving in correct direction; Inflation is stubbornly high
* Seeing signs of shocks spilling over into broader inflation data
* Economy is resilient and the labor market is solid
* Fed must bring inflation down to 2% target; Tariffs and energy shock still affecting inflation readings
* Tariffs are “mostly behind us”
* Do not believe the situation calls for dramatic policy action; Seeing drivers of inflation, not sure of broadening
*Asserts 2025 rate cuts were the “right call at that time”
* Financial conditions are still pretty supportive of growth; Seen a bit of normalization of financial conditions
* Seeing more opaque, complex financing of AI; Do not yet see financial stability risk from AI
* Financial markets are functioning very well
* Demand is clearly winning the race with supply
* Cyber security issues continue to be an area of concern
Position: None
BY Doug Kass · Nov 17, 2026, 3:00 PM EST
chrisideker
There is a lot of misinformation out there. Please allow me to weigh in. As a reminder, I led the group at a Big 4 firm that advised our audit practice when there were allegations of financial impropriety (AFI) or illegal acts (IA) against an audit client.
The INDEPENDENT directors of NVDA have retained counsel (Wachtel Lipton, “WL”) to advise them regarding Jensen Huang. They have probably formed a special investigative committee.
1) Much has been made about the lead partner of WL being a former AUSA. That is a nothing burger- almost every one of these are led by an attorney with that background. I used to insist on it.
2) We don’t know the scope of the investigation. Is it related to export controls? Is it accounting fraud? Is it Huang’s relationship with vendors?
3) I have not read that WL retained a forensic accounting firm. I would imagine they have- if the scope encompasses AFI or IA, through export controls.
4) These investigations take time. They don’t know a lot right now, unless Kress (former CFO, interim CEO) has been singing.
5) As Dougie has repeatedly written, NVDA has- at the least- engaged in aggressive accounting. Aggressive accounting is not fraud, but does reduce the quality of earnings.
6) If Huang, or someone like his nephew has engaged in unwritten side deals and failed to disclose that to the CFO, that could affect revenue recognition. If material, that could necessitate a restatement.
7) If Huang knowingly circumvented or violated export laws, that would constitute an illegal act. That is covered by auditing guidance, AS 2405: Illegal Acts by Clients.
8) PwC is NVDA’s auditor. They must meet with the audit committee and “sign off” on the earnings release.
9) PwC is in a difficult position, as they are being asked to sign off while an investigation is in its preliminary stages.
10) We know Huang resigned, but we don’t know why. Something arose early in the investigation. If it is just his relationship with an employee which violated their code of conduct, PwC would sign off on the earnings release.
11) If, on the other hand, there are indications of AFI or IAs, PwC would likely not sign off. NVDA could release anyway, but that is risky and would generally be disclosed.
12) I absolutely guarantee that PwC has been debriefed by WL. We can infer at least preliminary findings based on watching what PwC does.
If NVDA releases earnings as normal, that would tell me that, at least at this point, there are no credible allegations of AFI or IA.
So, I will buy NVDA after a normal release- for a trade- if the stock drops or is stable.
I understand that there are other issues. The Huang bank is closed. The supply chain was Huang-dependent. Beancounters generally make lousy CEOs- interim or not. They could see a brain drain. They still have earnings quality issues. None of these things will go away.
But, I think at least two concerns- AFI and IA- willl be off the table for the short term.
Another note. NVDA usually files its 10-Q the same day they release earnings. They could file for a 5 day extension. That is a big deal, because the CFO and CEO are required to file SOX 302 and 906 certifications as to the accuracy of the filing. Those certs are built on a mountain of sub certs from employees and carry civil and criminal penalties. IME, the certification process during an investigation sometimes leads to other concerns and allegations.
An extension would be a red flag.
Position: None
BY Doug Kass · Nov 17, 2026, 2:45 PM EST
douglas cassel
Former senior NSA official Anne Neuberger says AI is allowing organizations to discover vulnerabilities in their own systems faster than ever, but attempts to patch those weaknesses may be triggering unexpected failures. Her comments follow disruptions at major US banks and the NSA’s highly classified internal communications network. Neuberger suspects cybersecurity teams are deploying multiple security patches to stay ahead of AI-powered attackers, inadvertently bringing critical systems offline. She emphasized that hacking cannot yet be ruled out, but believes defensive security operations are a more likely explanation. The NSA outage reportedly forced staggered employee arrivals and disrupted classified communications. Neuberger warned that these failures highlight how dependent banks, intelligence agencies, and critical infrastructure have become on interconnected digital systems.
Position: None
BY Doug Kass · Nov 17, 2026, 2:20 PM EST
Position: None
BY Doug Kass · Nov 17, 2026, 2:18 PM EST
Here are today’s things:
* I added to index trading long rentals:
SPY $734.71
QQQ $656.78
* I added to GTBIF at $5.94 and VRNO at $3.97
* I added to C at $120.14 and WFC at $84.16
* I added to DELL at $315.42
* I initiated some Mga 7 buys: MSFT at $500.15, META at $618.27, GOOGL at $280.41 and AMZN at $255.83
Position: Long SPY (M), QQQ (M), MSFT (S), META (S), GOOGL (S), AMZN (S), C (M), WFC (S), DELL (M)
BY Doug Kass · Nov 17, 2026, 1:38 PM EST
From the Peter Boockvar:
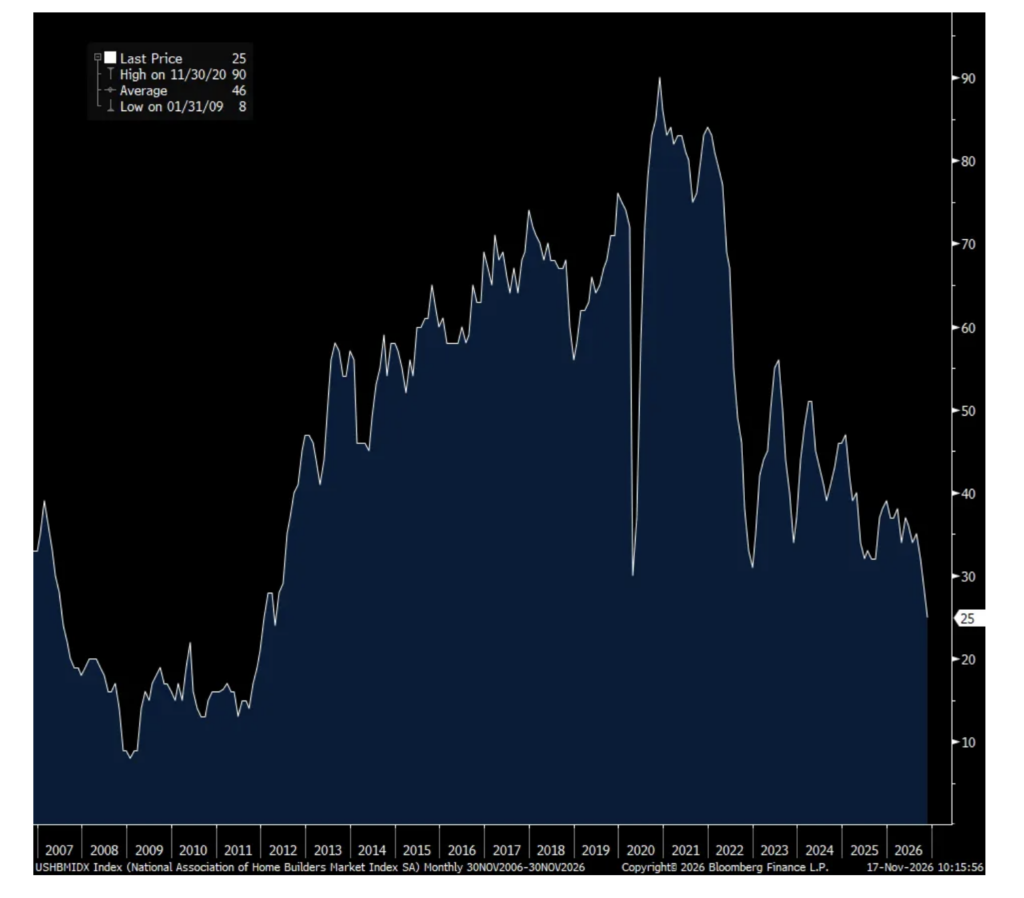
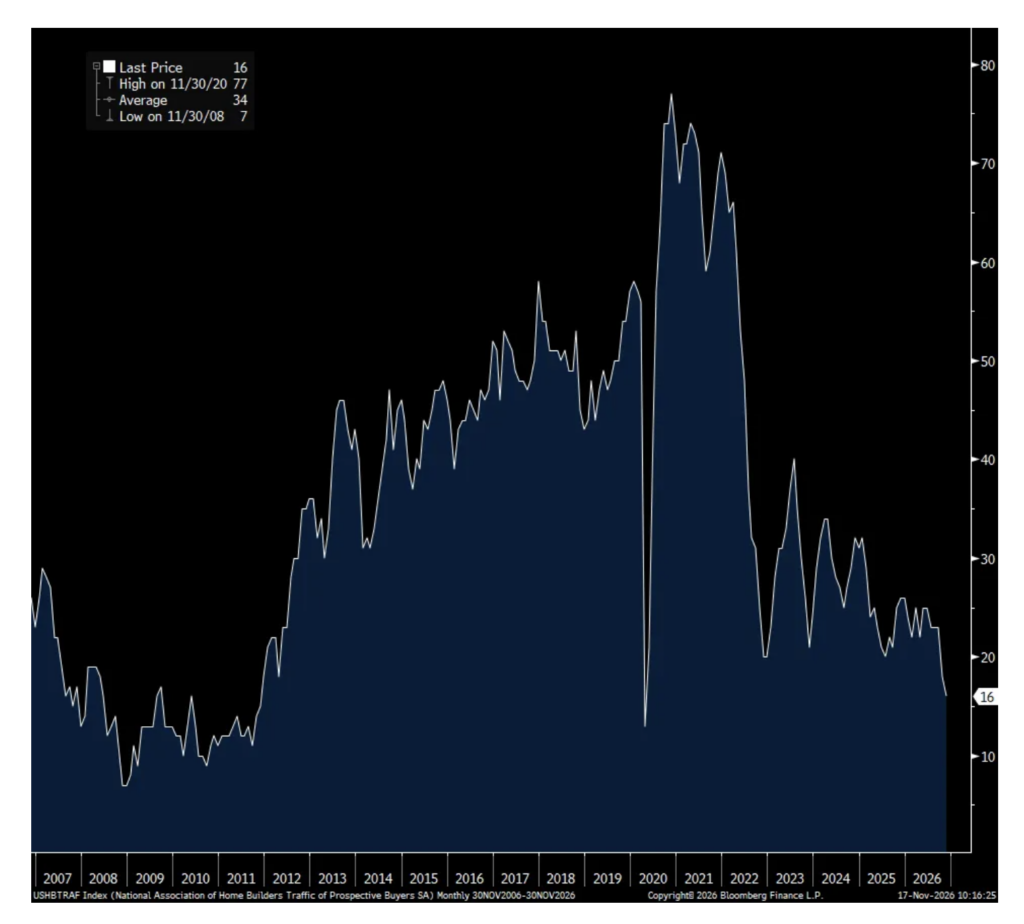
Home builder sentiment for November remained in the dumps, falling to just 25 from 29 and vs the estimate of no change vs the breakeven of 50. Both the Present and Future outlook fell too while Prospective Buyers Traffic stood at just 16 vs 18 in October and 23 in the three months prior.
Nothing that we don’t already know for this most challenged part of the US economy, the NAR said builder confidence fell “to a 14 year low, dragged down by high mortgage rates, ongoing inflation pressure, elevated energy and material costs, rising labor shortages and hesitant buyers.”
Further, “Stepped-up immigration enforcement is keeping legal workers off job sites, deepening labor shortages and driving up costs. Higher fuel prices are prompting subcontractors to raise their rates sharply, and with fewer buyers in the market, more builders are scaling back construction.
And to what builders are doing to sell homes, “In November, 46% of builders reduced prices, the highest share in the post-Covid period, according to the latest HMI survey. The average price reduction held at 6% for an eighth straight month. Meanwhile, 68% of builders offered sales incentives, also a post-Covid high, marking the 20th consecutive month in which at least 60% of builders used them.”
Bottom line, housing remains in a recession and my answer to the constant question of what can improve this situation if it’s not going to be via mortgage rates, I believe it needs to be a period of time where wage growth far outpaces home price gains (even if it means home prices need to drop or at best flat line), thus to improve affordability and the demand for homes that hopefully builders can meet and if at the same time we can improve the supply of inventory on the existing home side.
NAHB
Prospective Buyers Traffic
BY Doug Kass · Nov 17, 2026, 12:15 PM EST
NSA is saying that it was not a cyber attack — helping to explain the rally off of the lows…
Position: None
BY Doug Kass · Nov 17, 2026, 12:12 PM EST
I added further to my index trading rental longs:
Position: Long SPY (M), QQQ (M)
BY Doug Kass · Nov 17, 2026, 12:06 PM EST
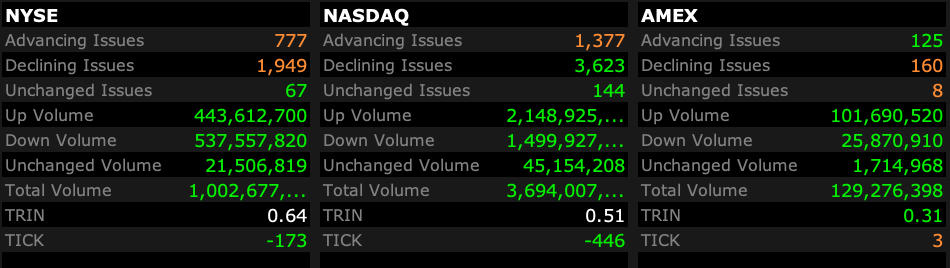
– NYSE volume 13% below its one-month average;
– Nasdaq volume 17% above its one-month average;
– VIX index: up 8.03% to 24.75
Breadth
SOURCE: Interactive Brokers
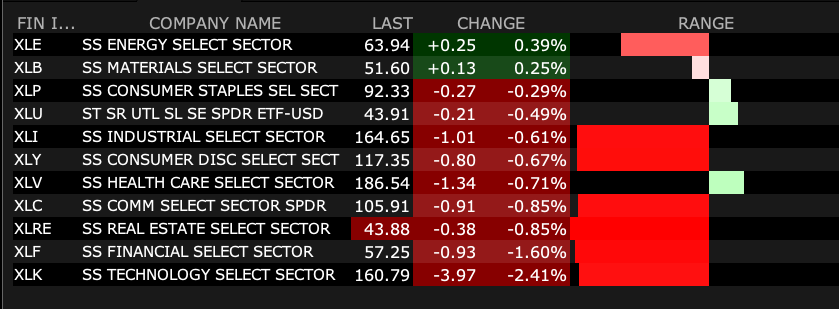
S&P500 Sectors ETFs
SOURCE: Interactive Brokers
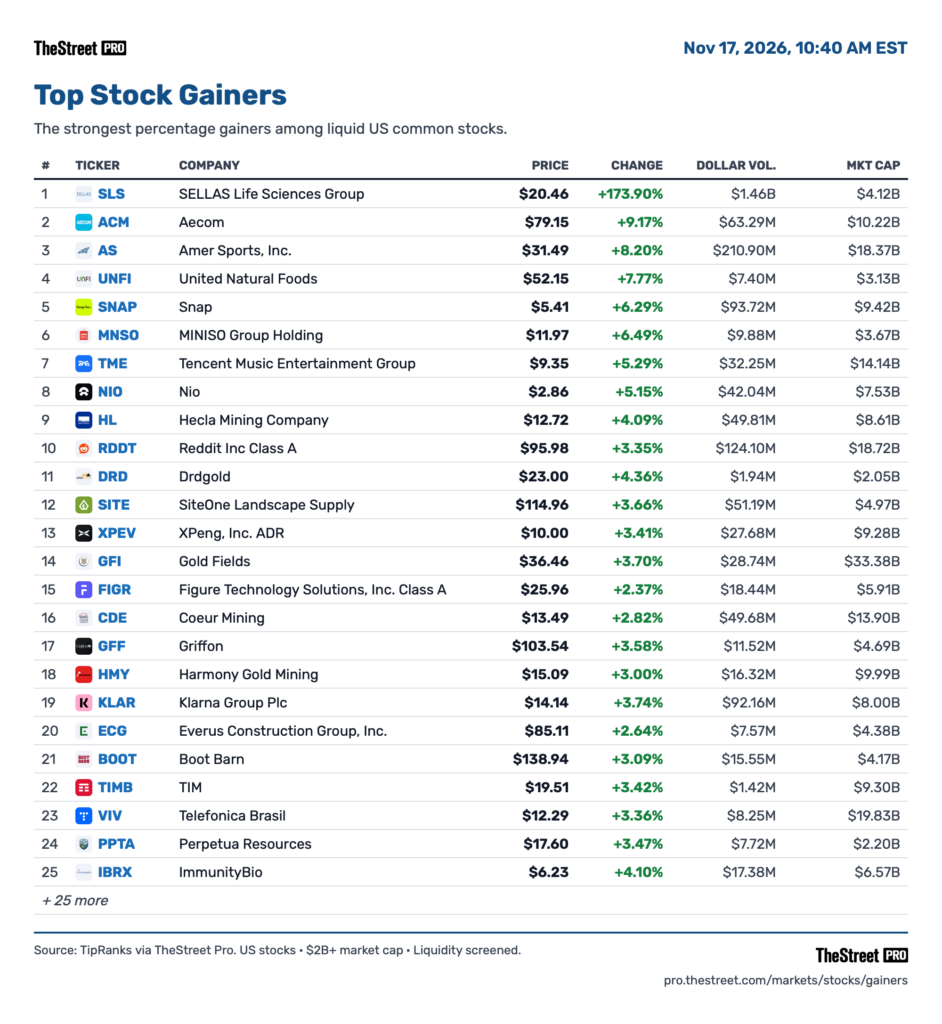
% GAINERS, DECLINERS
SOURCE: TheStreet Pro
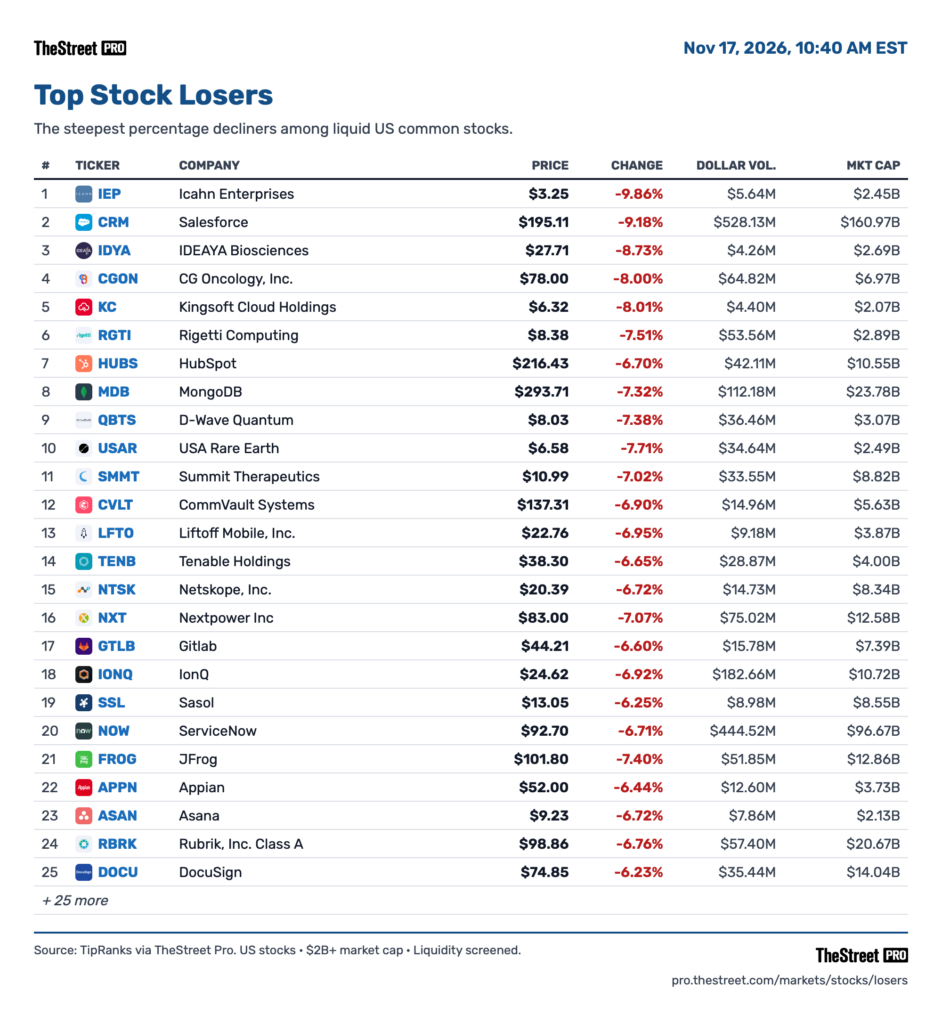
Nasdaq 100 Heat MapSOURCE TheFly
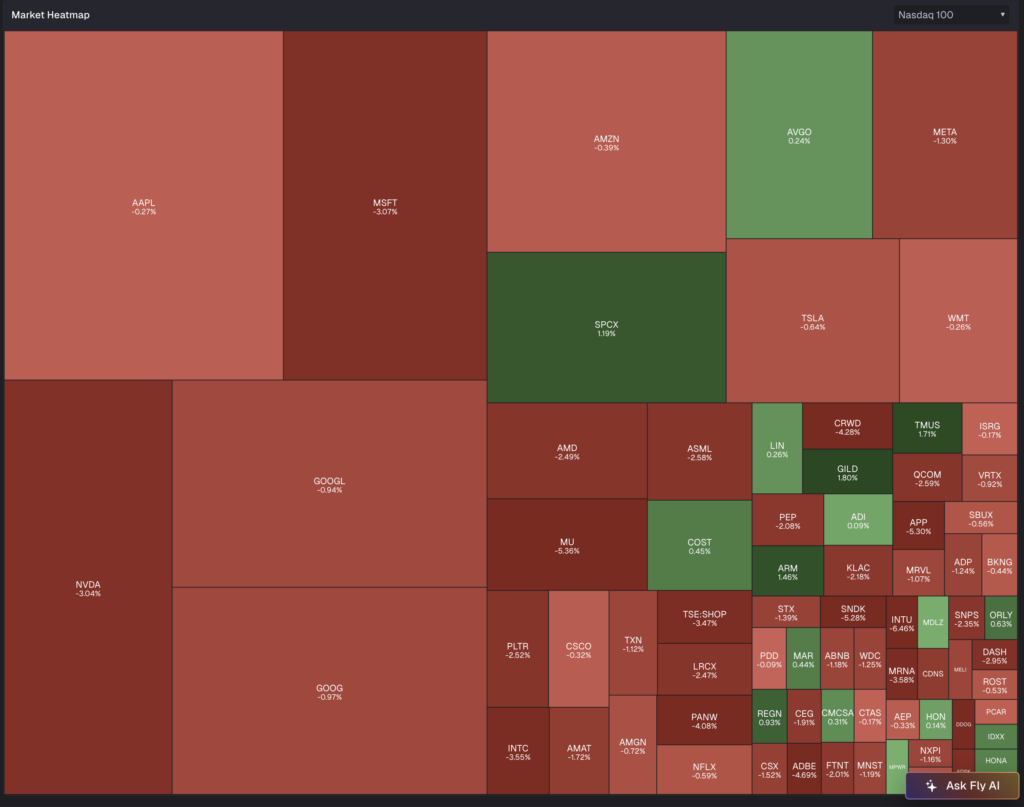
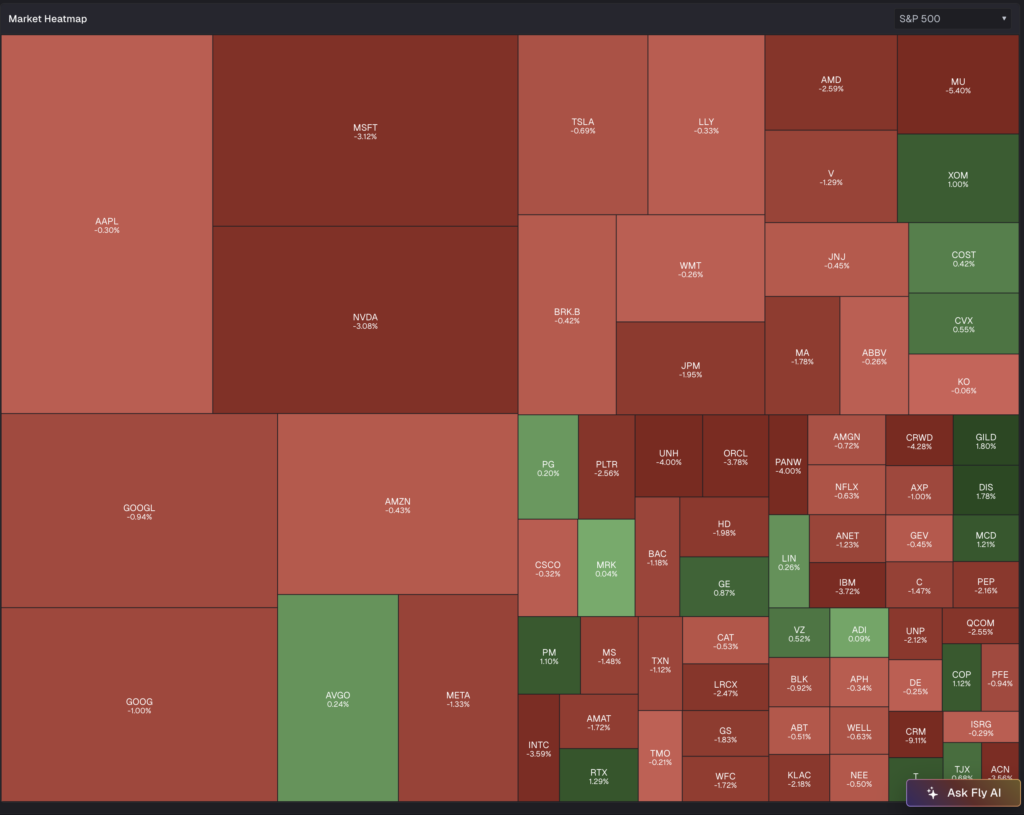
BY Doug Kass · Nov 17, 2026, 11:45 AM EST
BY Doug Kass · Nov 17, 2026, 11:25 AM EST
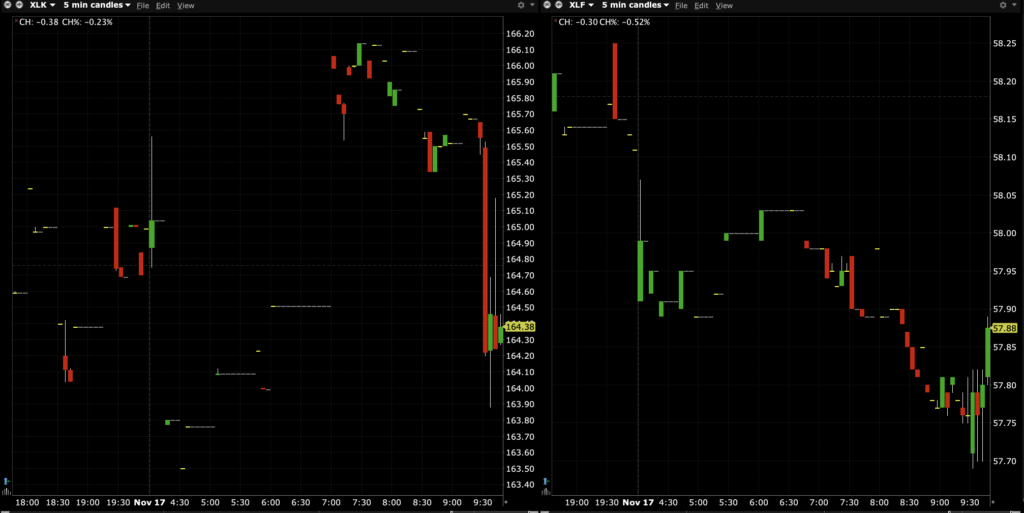
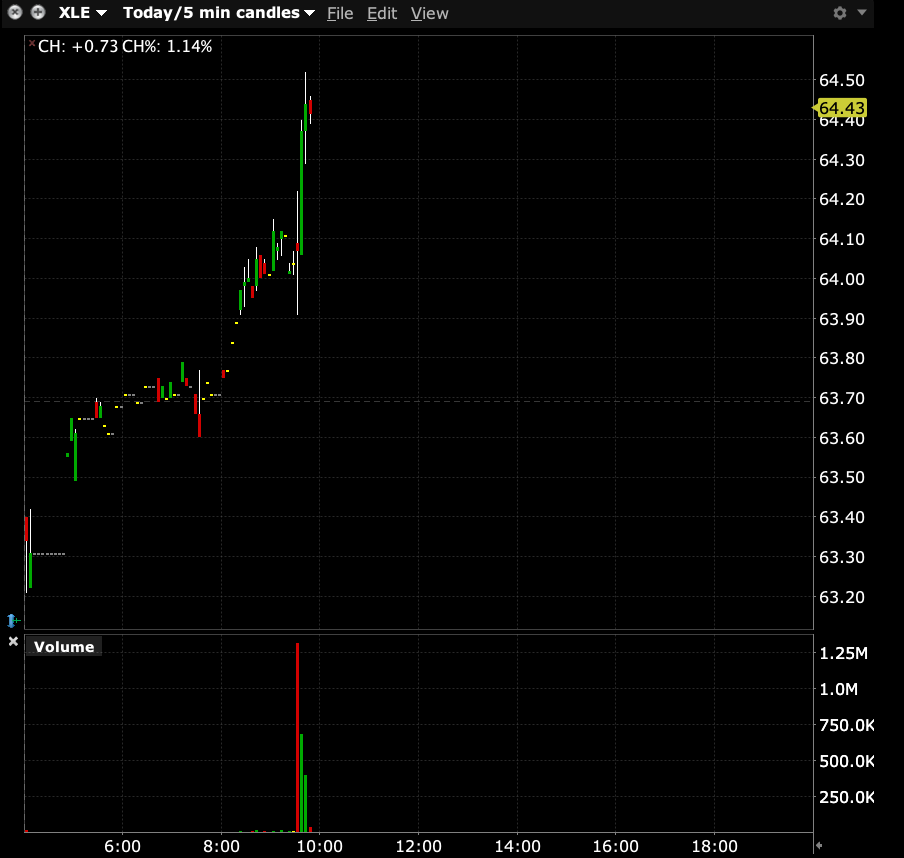
Charts from 9:46 a.m. ET.
BY Doug Kass · Nov 17, 2026, 11:15 AM EST
I have initiated long positions in META $618.27, AMZN $255.83, GOOGL $280.48 and MSFT $500.15.
Positions: Long META VS AMZN VS GOOGL VS MSFT VS
BY Doug Kass · Nov 17, 2026, 11:11 AM EST
BY Doug Kass · Nov 17, 2026, 10:19 AM EST
I am back from the eye doctor but I can barely see!
Getting my sea legs back..
Positions: None.
BY Doug Kass · Nov 17, 2026, 10:16 AM EST
The following is from Peter Boockvar:
As we now await earnings from Nvidia, the direction of the stock will no question be influenced by who the next CEO will be (I’m sure will be very capable and talented) and the extent to which their China business (either direct or indirect) gets negatively impacted by US policy changes but also, and I think the biggest factor, they will be subject to the broader level of industry CapEx spend. Nvidia’s stock is not just falling because of the loss of Jensen and the China scrutiny but at the end of the day, they are also another picks and shovels company selling their wares into the data center buildout and we’ve seen what’s happened to many of those stocks, they are down sharply.
I argue again that 2027 will mark peak CapEx spend on data construction in terms of dollars spent and 2026 will see the peak in terms of rate of change. Yesterday, the well known semi/AI/hardware tech research firm SemiAnalysis reduced its estimate for AI accelerator spend by almost 30%. This was due to the expected reduced pace of data center construction in response to the midterm election results, the rising cost of capital that will also slow building and they also cut token revenue expectations from the frontier labs.
Also of note, all the picks and shovels providers to the data center construction in Asia all sold off overnight in response to tightening rules around selling stuff to the Chinese, either direct or indirect. So, not only are we possibly going to see a slower rate of data center construction spend in the US, it’s about to happen in Asia too as China is such a big customer.
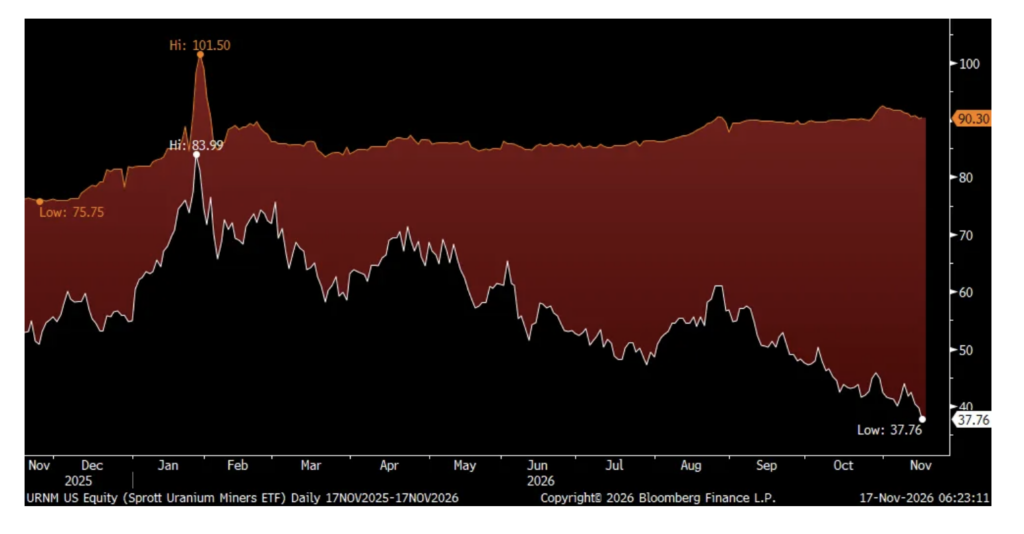
Something that I think is mistakenly getting caught up in the data center construction concerns is uranium. Uranium spot prices have remained steady at around $90 a pound. The longer term contracted price is near $100 a pound, also little changed recently but at a record high. However, because people associate nuclear power and its renaissance with data center buildouts, the uranium stocks have gotten crushed. We are long and have been and just want to highlight this big disconnect seen in the chart below. The nuclear renaissance is so much more than just the building of data centers and their power needs. It’s the cleanest, most reliable form of 24 hr/7 day per week energy for whatever the purpose, including for turning the lights on. And, after seen with the conflict of the Middle East, it helps tremendously with energy independence.
Uranium spot price in orange/URNM etf in white
The US dollar has been stronger with the rise in rates and firm expectations that not only will the Fed hike next month but give us a few more next year (which I question if the AI trade/CapEx spend further weakens). As the entire world is loaded up with US tech stocks, at some point I do expect the direction of the US dollar to mimic the US tech trade.
Cass Freight reported its October shipments data and said it rose 5.9% y/o/y and 1.7% m/o/m. They said “The recovery in freight demand continues, with several factors at work. Slow growth in retail and industrial activity, inventory restocking ahead of the holidays, and to some extent, the IEEPA tariff refunds are all supporting activity. Still, demand will be limited by elevated inflation and rising interest rates squeezing consumers and businesses, and the temporary nature of the IEEPA tariff refunds.”
We know freight rates are up sharply this year. Yesterday, DAT said “Linehaul rates are about a third more than last year. Linehaul rates are 36% above last year for van, 34% for reefer, and 31% for flatbed, against a 2025 market that was still in a freight recession.”
Home Depot reported top and bottom line numbers just above the estimate and better than expected comps but there was no commentary on the macro and the housing market in their press release. We await their call as also they announced a new CEO.
From Walt Disney, a stock we own, who beat both top and bottom line forecasts and I’ll focus here just on their parks business for clues on the consumer:
“Our continued growth in both guests and guest spending at Experiences once again highlights the differentiated strength of our diversified global portfolio. Per capita guest spending increased 4% across our domestic parks and 5% across our international parks in the fourth quarter, with strength at Disneyland Paris more than offsetting incremental weakness relative to the third quarter at our Hong Kong and Shanghai parks. It was another strong quarter for our largest site, Walt Disney World, where a steady run of new offerings, our IP, and a commercial strategy focused on domestic guests drove strong growth, aided by favorable comparisons to the prior-year quarter.”
“We continued to see headwinds from lower international attendance at our domestic parks in the quarter, but as expected, those headwinds moderated from the year-over-year impact observed in the third quarter. Domestic parks attendance was up 11% in the quarter (3% excluding the 53rd week).”
“Meanwhile, Disneyland Paris continued to deliver strong growth, benefiting from recent investment and expansion, including World of Frozen. In contrast, attendance at our Hong Kong and Shanghai parks worsened during the quarter and we expect this pressure to continue in fiscal 2027. We expect growth in global guests to continue in the first quarter of fiscal 2027, despite consumer softness in Hong Kong and Shanghai.”
From Tyson Foods, up 9% yesterday in a really tough tape because of the current popularity with protein:
The CEO was “fired up about the opportunities in front of this great company. My dad is 95 years old. My wife is 60 years old. My kids are 23 and 25. Besides me, what do they have in common? Their doctors and influencers are telling them, eat more protein. I’ve been in this industry over 40 years, many with Proctor & Gamble. No one ever said do more laundry or change more diapers. This place is exciting. Selling more laundry and diapers is hard. Selling more protein is fun. Protein is the biggest opportunity in food, a $273 billion retail category growing faster than overall food.”
“Seven in ten Americans say they are trying to eat more protein. Younger households spend more than three times what their parents spend on protein each week.”
Specifically, “Chicken had a fantastic year” with volume up 2.1%, “our 8th consecutive quarter of volume growth.”
“In beef, the cattle cycle remains the dominant factor. Fourth quarter sales were $4.9 billion, down 10.5% as volume fell 12.7% on tight cattle supplies.”
Pork saw volume up 7% as “Increased hog availability expanded industry supply and product values.”
Overseas, the October UK jobs data was disappointing, falling by 34k vs the estimate of up 10k, slightly offset by a 7k person revision up for September. Jobless claims also jumped by 33.2k but mostly mitigated by a downward revision of about 20k to the September print.
Thru September, private sector wage growth was up 3.1% y/o/y which compares to September CPI of 3.5% and the October print to be seen tomorrow is expected to be up 3.6%. Still, REAL wage challenges.
Not much of a market response to the UK data with gilt yields and the pound little changed and the FTSE 100 trading lower along with every other foreign market after the US selloff.
The November German ZEW investor confidence index in their economy rose to 35.6 from 28.1 and above the estimate of 28.8. The Current Situation was up a touch to -33.2 from -35.9. The ZEW said “Expectations improved in November. The German economy remains on its recovery track, albeit moving at a slow rate. Increasing manufacturing orders and falling oil prices are likely to underpin the upturn. The mainstay of the recovery has been government expenditure so far, but this leads to rising concerns about the sustainability of public debt.”
Nothing market with this stat as well today.
BY Doug Kass · Nov 17, 2026, 10:15 AM EST
The following is from Peter Boockvar:
Core retail sales in October were stronger than expected with a .6% m/o/m gain, twice the estimate and September was revised up by four tenths to a .5% gain. Above this line, auto sales fell for the 3rd month in four, down 1.6% m/o/m while up 1.2% y/o/y. Building materials rose .5% m/o/m after falling by .8% last month. Spending at the gas station was up 1.5% m/o/m and 30% y/o/y but which should reverse lower in November.
Elsewhere, it was mixed. There was strength with online retailers with sales up 1.2% m/o/m and up 10.1% y/o/y and rose 1.5% for health/personal care. Sales were flat m/o/m for electronics, down by 2.3% for furniture, lower by .7% each for clothing and sporting goods, down by .2% for food/beverages (supermarkets, liquor stores) and higher by .2% for bars/restaurants.
Bottom line, with the help of inflation, retail sales were better than forecasted but as stated, the contributions were very uneven.
Import prices remained hot in October with a 1.1% m/o/m gain (no y/o/y data available because of government shutdown last year), above the estimate of up .7%. Ex petro, prices rose .8% m/o/m after a .6% increase in September which was about as expected when including the revisions. Taking both food and fuels saw prices jumping .9% m/o/m.
Component wise capital goods prices jumped 1.5% in the month, autos/parts were up by .4%, consumer goods prices ex autos saw prices higher by .5% and non durable goods prices ex petro were up by .4%.
Bottom line, these are all very robust monthly price gains which feeds right into higher business costs with some able to pass them on while others are not so fortunate.
BY Doug Kass · Nov 17, 2026, 9:33 AM EST
– GP +113% (extends a speculative surge after sequential revenue improvement; the filing also flagged going-concern and lender-covenant risks)
– AYTU +46% (agrees to a $2.70-per-share all-cash acquisition)
– SPAI +22% (record Q3 revenue jumped 2,539%, AI gross margin reached 79% and the first Army prime contract was awarded)
– GLAS +13% (Q3 revenue more than doubled, biomass production hit a record and production costs declined)
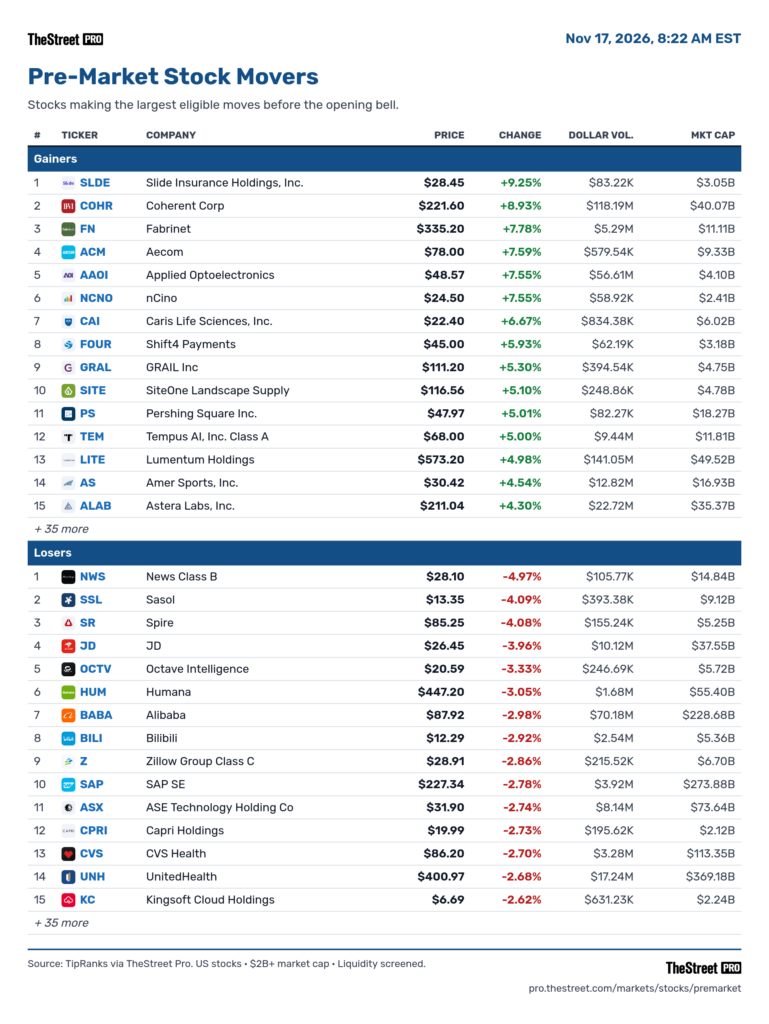
– COHR +9.0%, AAOI +7.6%, LITE +4.9%, MRVL +4.2% (optical-connectivity names rebound sharply from Monday’s AI-hardware selloff ahead of NVDA results)
– SLS +7.1% (pivotal Phase 3 REGAL trial met its primary endpoint, cutting the risk of death by 41% in AML)
– ACM +6.3% (record backlog and margins, FCF above prior guidance and a strong FY27 outlook)
– TEM +5.7% (high-beta AI name rebounds from Monday’s selloff ahead of NVDA’s post-close results)
– SITE +5.1% (set to join the S&P SmallCap 600 before Thursday’s open)
– NVDA +1.1% (rebounds ahead of its first post-leadership-change earnings report; the board formed an export-control oversight committee)
– RCAT -35% (Q3 missed expectations and the FY26 revenue target was withdrawn as funding and contract awards progressed more slowly than expected)
– GMM -25% (gives back part of Monday’s Anthropic-investment spike after the company did not disclose the size of its indirect exposure)
– CSAI -15% (Q3 revenue missed, the net loss widened and the filing retained substantial going-concern doubt)
– OMH -15% (updated an up-to-$300M shelf registration, renewing dilution concerns)
– JD -4.0% (mixed Q3 as modest sales growth and a slight retail-margin decline overshadowed stronger profit)
– DB -3.6% (falls after leaked-document reports renewed scrutiny of dealings with controversial clients)
– PRG -3.6% (Loop Capital downgrades to Hold from Buy)
– BABA -3.0% (China technology shares weaken on tighter US AI-chip-access restrictions and soft peer results ahead of earnings)
– OPRA -2.9% (results reached the top end and FY guidance rose, but Q4 growth normalization and planned investment triggered a sell-the-news reaction)
– HD -2.0% (quarter beat, but customer traffic declined, margins contracted and FY adjusted EPS growth remains near 2%)
– PEP -1.8% (Bernstein downgrades to Underperform on earnings-shortfall and valuation concerns)
– DIS -1.3% (Q4 beat, but FY27 double-digit EPS growth was only reiterated as content spending is set to increase)
BY Doug Kass · Nov 17, 2026, 9:00 AM EST
BY Doug Kass · Nov 17, 2026, 8:55 AM EST
BY Doug Kass · Nov 17, 2026, 8:45 AM EST
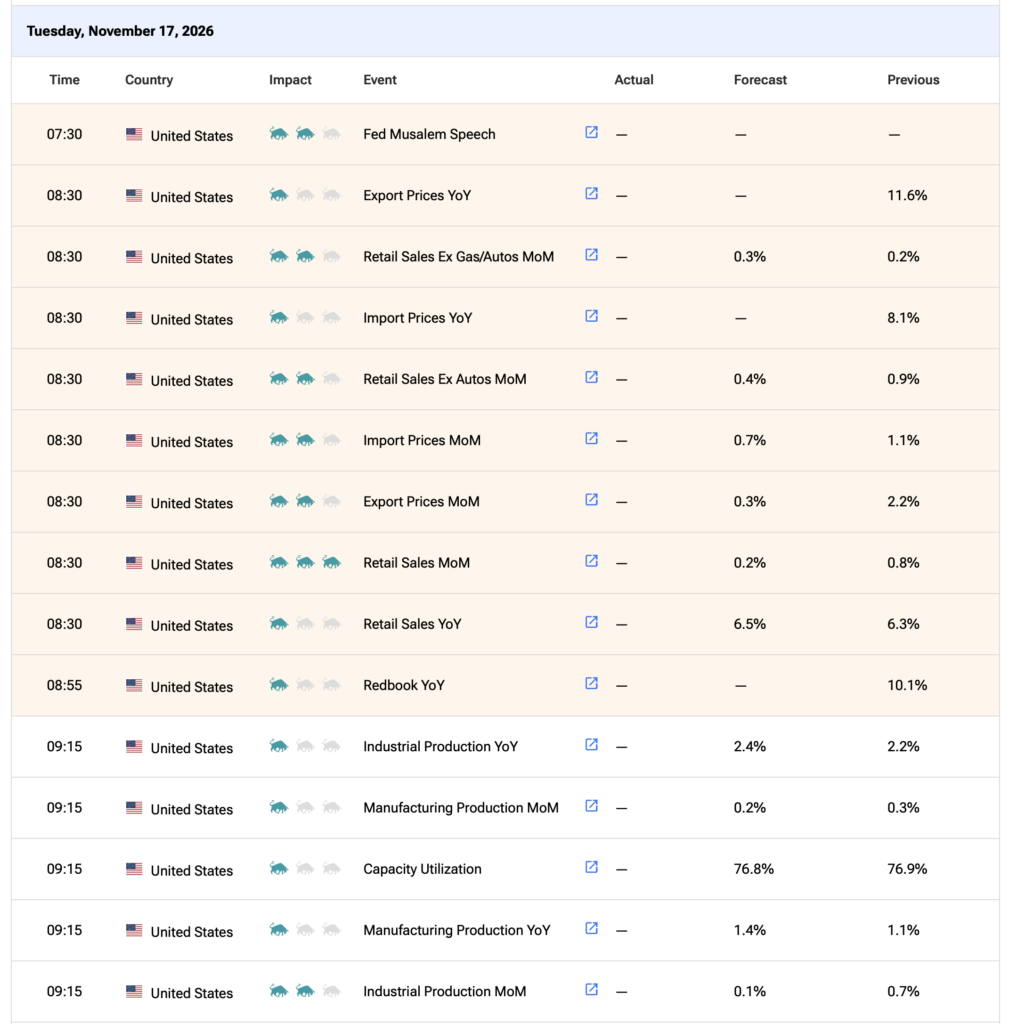
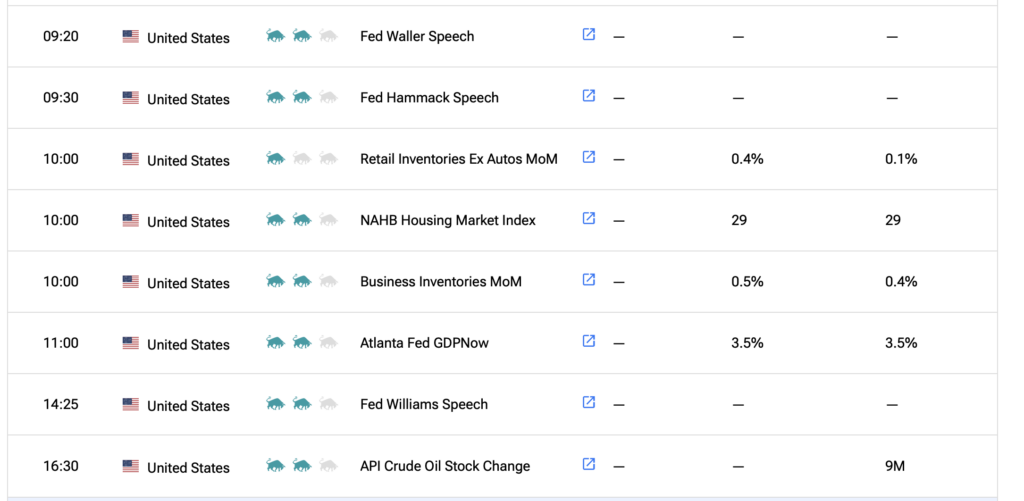
7:30 a.m.: Fed Bank of St. Louis President Musalem (Non-Voter) speaks on “Looking Ahead: Scenarios for the U.S. Economy and Monetary Policy” before the 2026 Money and Banking Conference: “Growth, Productivity and Inflation” at the Banco Central de la República Argentina, Buenos Aires, Argentina (Moderated Q&A follows. Text anticipated. In-person and virtual options);
9:10 a.m.: Fed Board Governor Christopher Waller (Voter) speaks on “Payments” before The Clearing House (TCH) Annual Conference, NYC (Text available. Q&A from moderator. Livestream at https://avdusa.zoom.us/j/81071533579);
9:30 a.m.: Fed Bank of Cleveland President Hammack (Voter) gives keynote on strengthening the resilience and liquidity of the U.S. Treasury market before the Brookings Institution, Washington, DC (Moderated conversation follows. Text available);
2:25 p.m.: Fed Bank of New York President Williams (Voter) participates in fireside chat before the Axios BFD Annual Summit, NYC (No text. Moderated Q&A expected)
Source of calendar below: TipRanks
BY Doug Kass · Nov 17, 2026, 8:25 AM EST
I have a routine eye examination at 8:30 AM.
I will be back for the opening.
Position: None
BY Doug Kass · Nov 17, 2026, 7:37 AM EST
Position: None
BY Doug Kass · Nov 17, 2026, 7:09 AM EST
* Brad Gerstner (Part Deux) …
Give ’em the old razzle dazzle
Razzle dazzle ’em
Give ’em a show that’s so splendiferous
Row after row will crow vociferous
Give ’em the old flim flam flummox
Fool and fracture ’em
How can they hear the truth above the roar?
Throw ’em a fake and a finagle
They’ll never know you’re just a bagel
Razzle dazzle ’em And they’ll beg you for more!
– Chicago, Razzle Dazzle Chicago: Razzle Dazzle
The big bambooz-a-ler on CNBC continues:
Let’s go to the tapes:
Altimeter’s Brad Gerstner: Colette Kress is very capable to run Nvidia in the interim
Watch CNBC’s full interview with Altimeter Capital’s Brad Gerstner
Position: None
BY Doug Kass · Nov 17, 2026, 6:25 AM EST
At 4:40 AM (and as the oversold Oscillator expands) I added to my index trading long rentals:
* SPY $736.25
* QQQ $657.81
Position: Long SPY (M), QQQ (M)
BY Doug Kass · Nov 17, 2026, 5:55 AM EST
The S&P Short Range Oscillator moved further into an oversold at -2.45% vs. -0.40%.
Yesterday afternoon I went long the indices.
Position: Short SPY (M), QQQ (M)
BY Doug Kass · Nov 17, 2026, 5:45 AM EST
If there's one INVESTING lesson to be learned from the @nvidia - @JensenHuang fiasco is that the market as a collective (and that includes investors, financial reporters, traders etc.,) have played with real fire allowing a bunch of meme-holding yahoos to degrade the practice Show more
Local man goes on CNBC to aggressively hype the AI trade in Q3 while simultaneously buying insurance against a crash in the AI trade in Q3 Why do these people have any credibility whatsoever?

Altimeter's Brad Gerstner hedging a chip crash in Q3. NVDA still top position by far.

Over the past week, I’ve been overwhelmed by the love and support of friends, industry colleagues, and people I've never met. Thank you to everyone who has shown kindness to my family and me. It means the world to me. I came to the United States 53 years ago, and becoming an Show more