A Look at After-Hours Intraday Movements
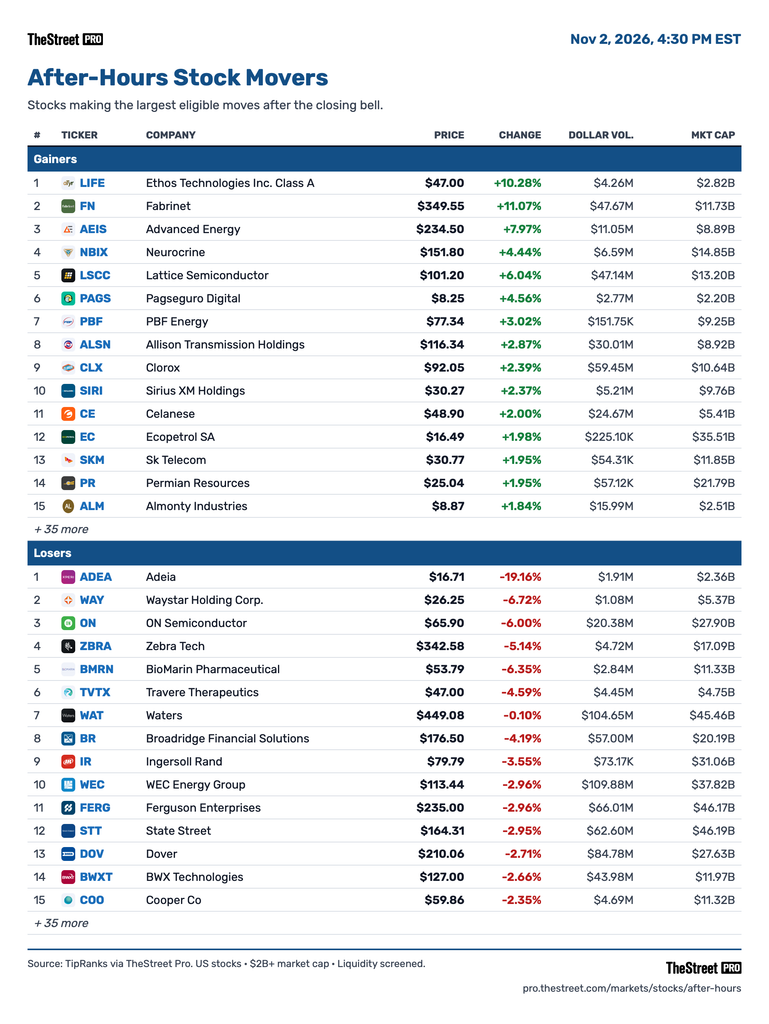
As of 4:33 p.m.:
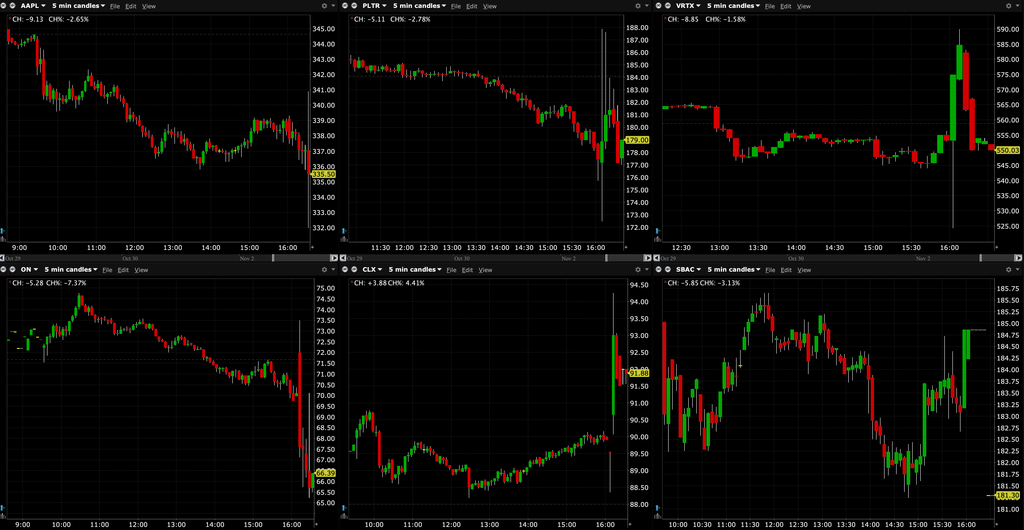
Position: None
BY Doug Kass · Nov 2, 2026, 4:43 PM EST
 Doug KassDoug Kass
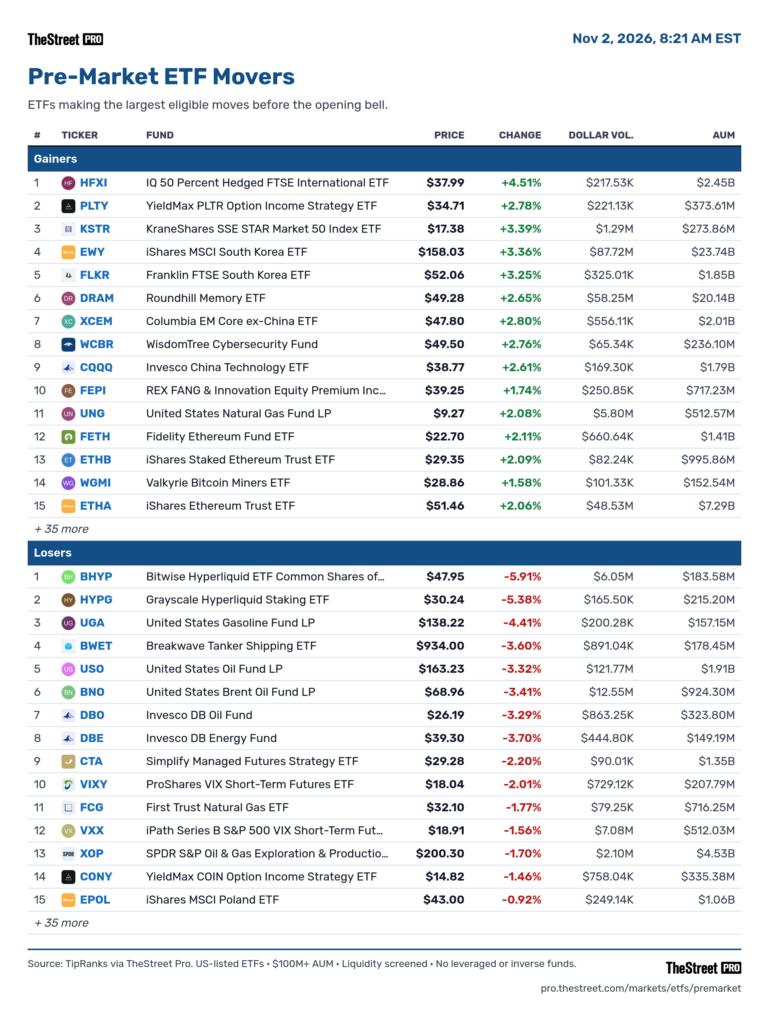
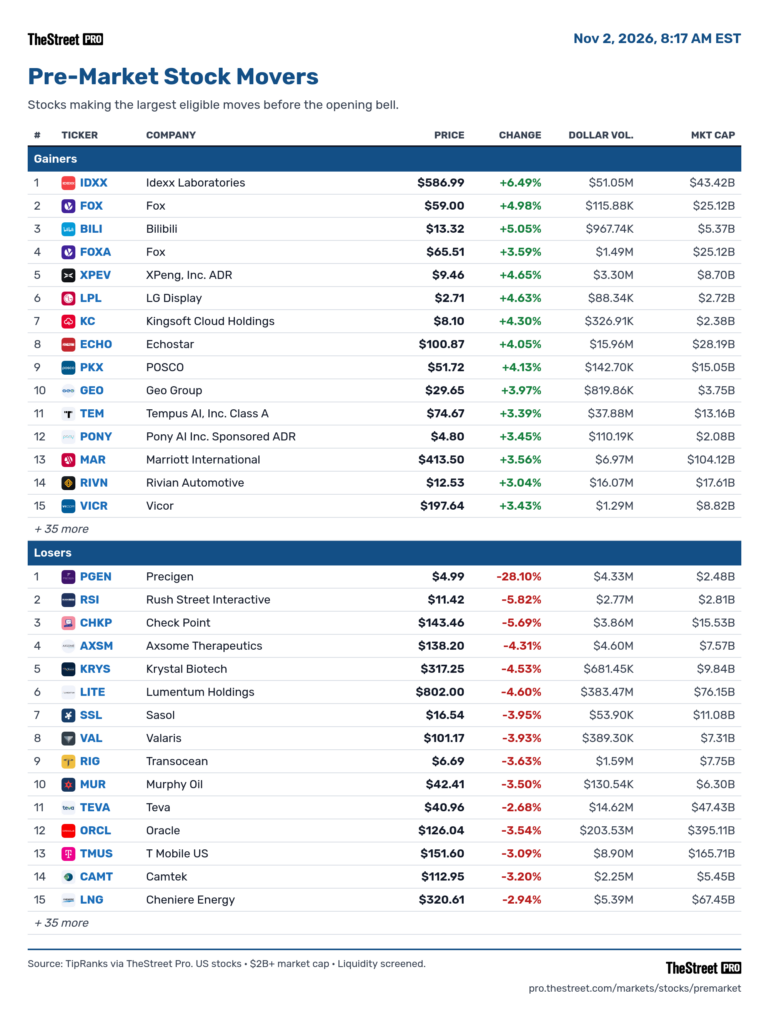
As of 4:33 p.m.:
Position: None
BY Doug Kass · Nov 2, 2026, 4:43 PM EST
Position: None
BY Doug Kass · Nov 2, 2026, 4:40 PM EST
Volume and VIX
– NYSE volume 7% above its one-month average;
– NASDAQ volume 16% above its one-month average;
– VIX index: up 8.91% to 21.15
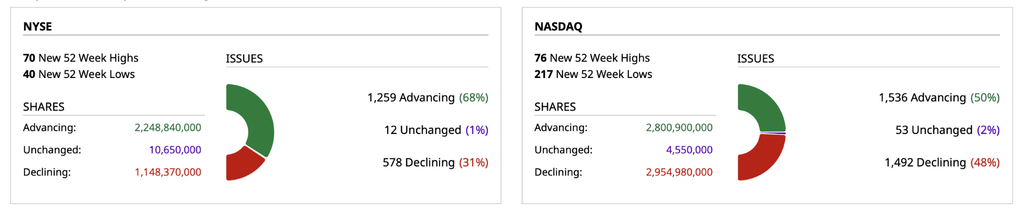
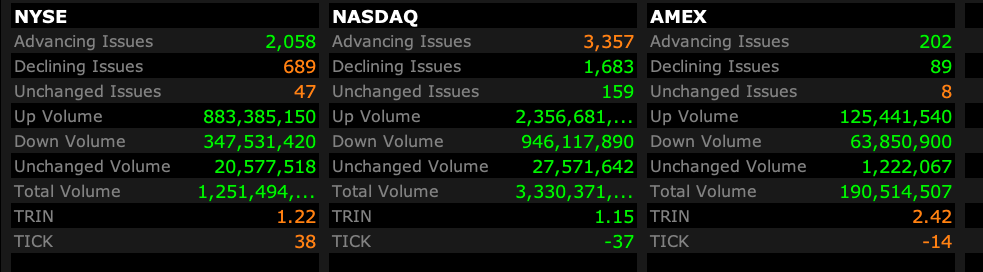
Closing Breadth
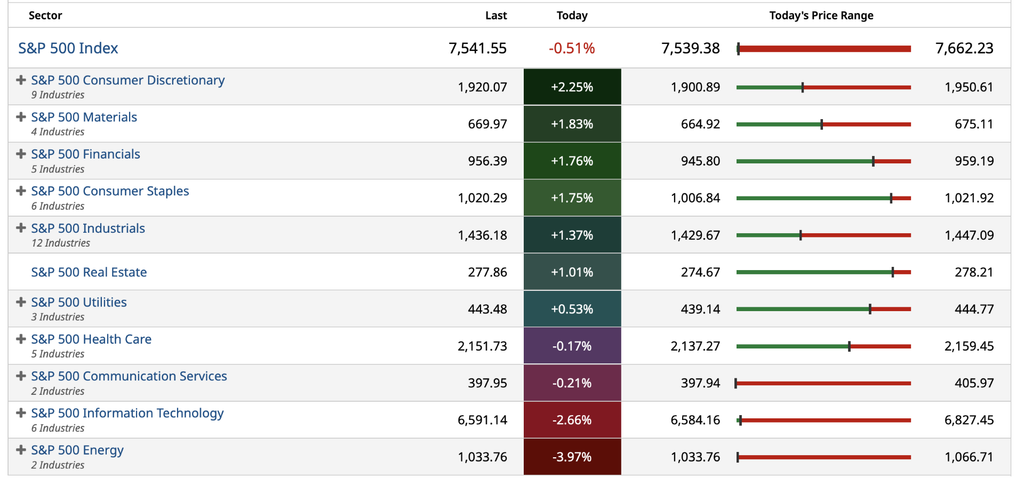
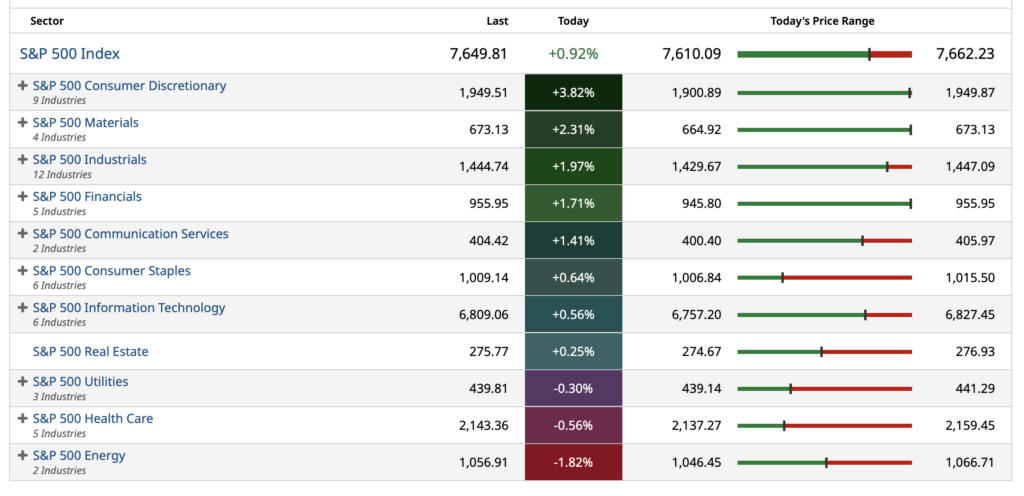
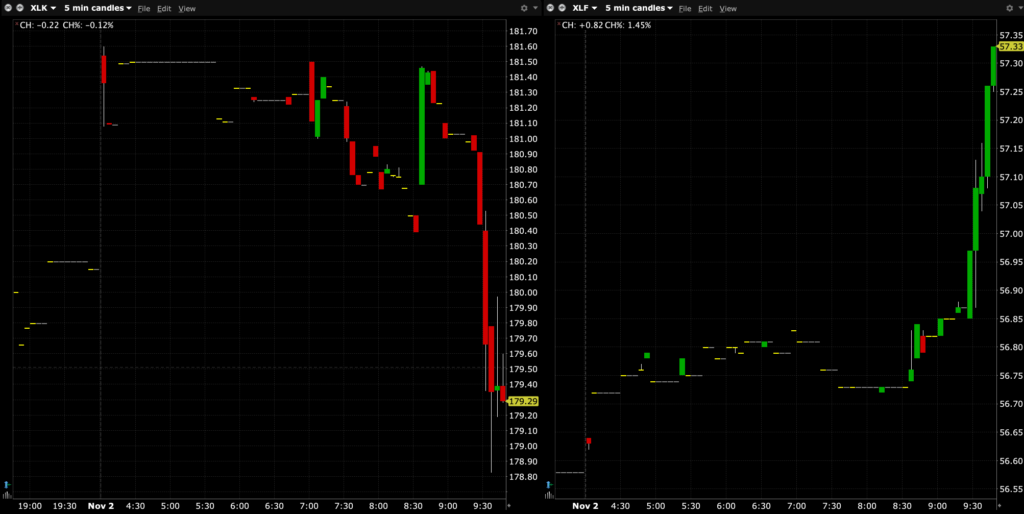
Sectors
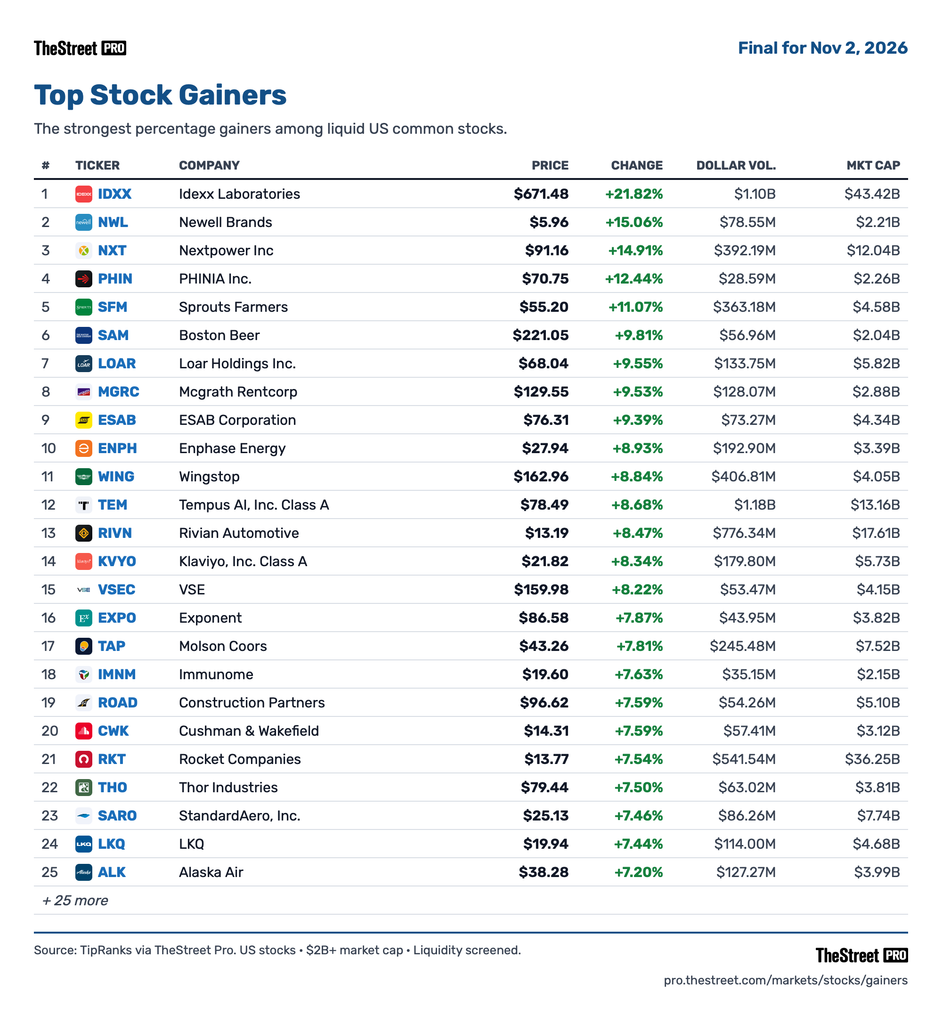
Gainers/Decliners
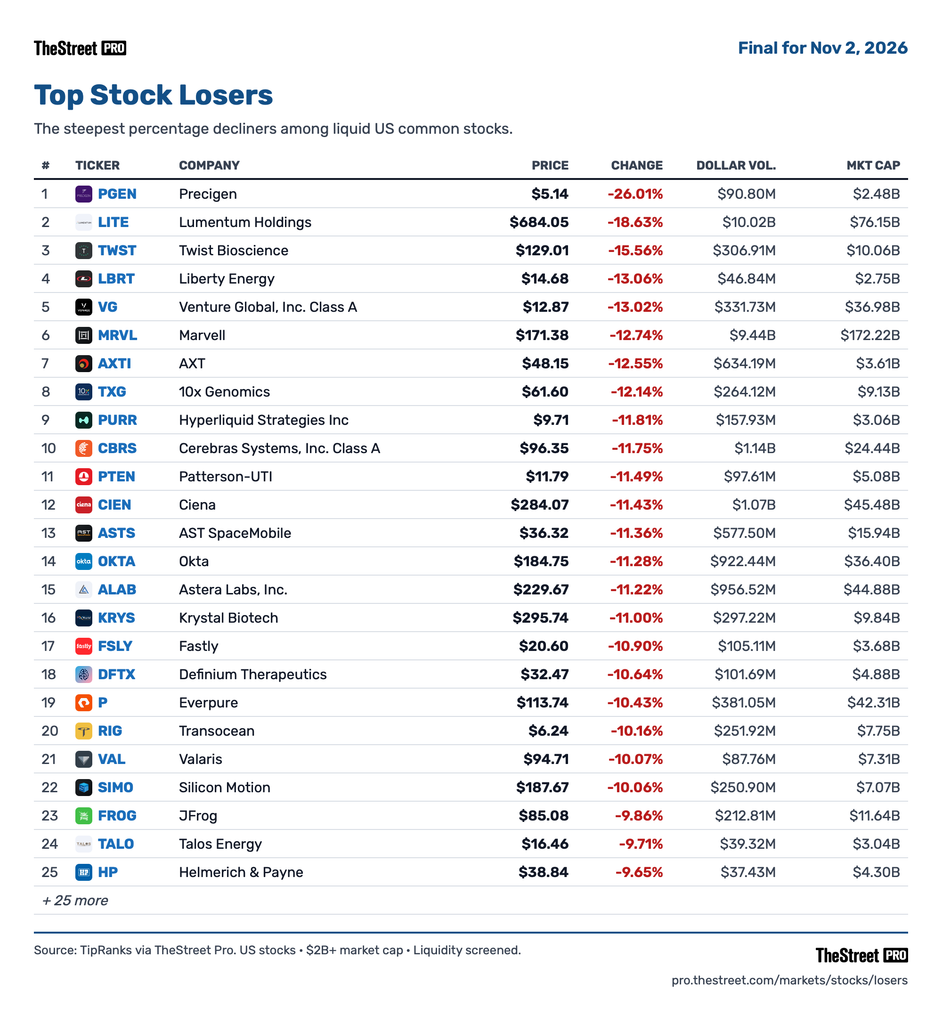
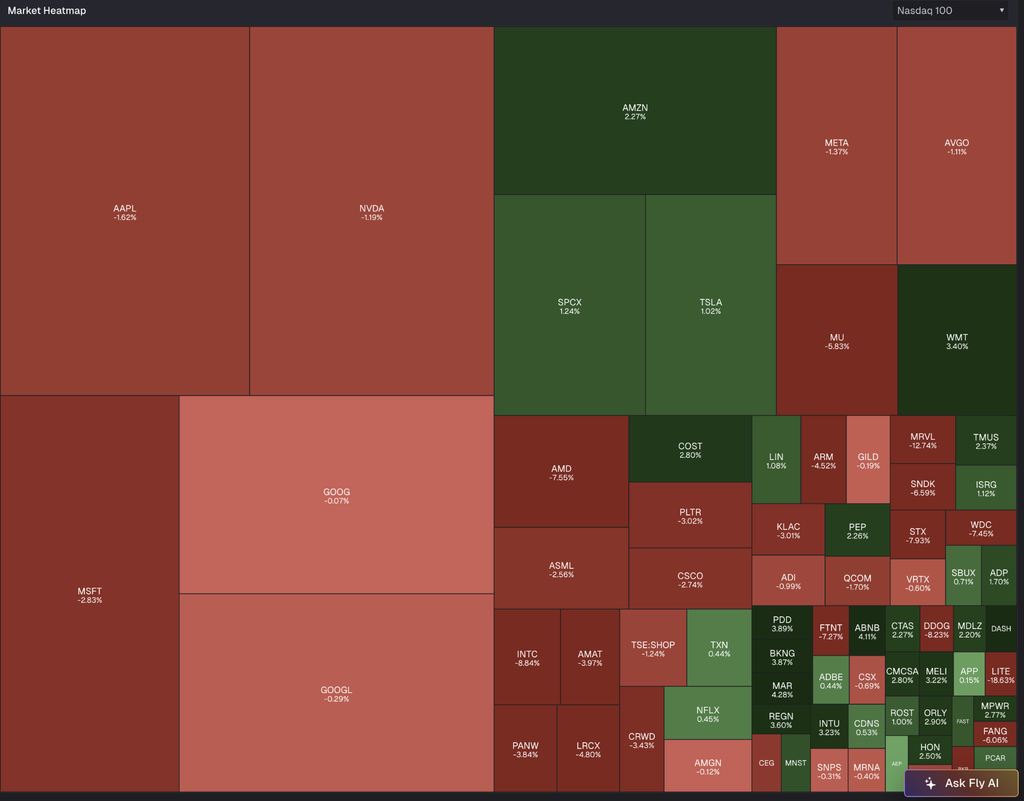
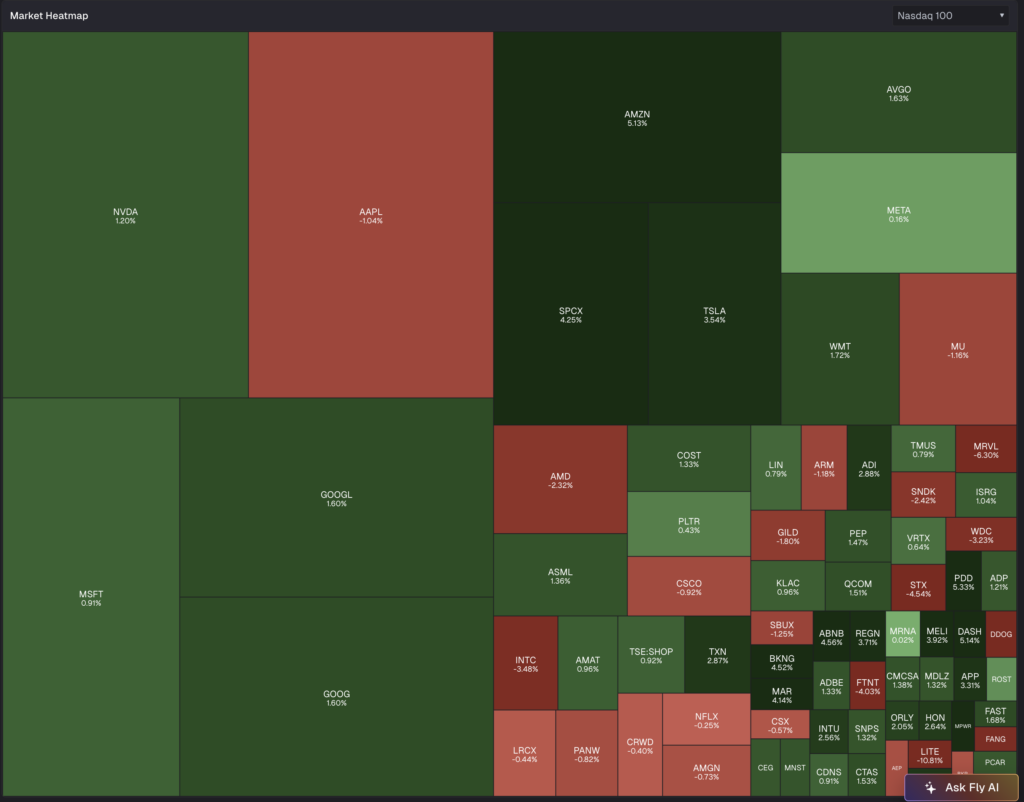
Nasdaq 100 Heat Map
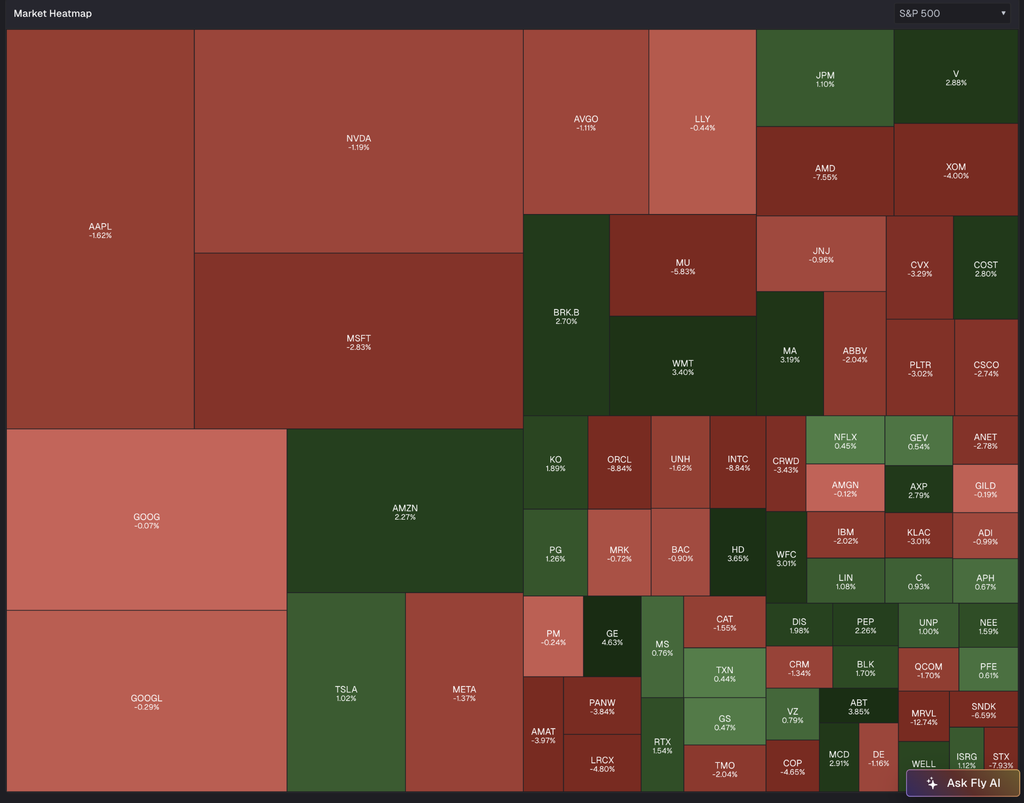
S&P 500 Heat Map
Position: None
BY Doug Kass · Nov 2, 2026, 4:32 PM EST
Position: None
BY Doug Kass · Nov 2, 2026, 3:46 PM EST
Good stuff from Gene Munster:
Position: None
BY Doug Kass · Nov 2, 2026, 2:50 PM EST
Mira
Dougie reckons big mistake covering Apple short. More like missing a few more Pennies in front of the freight train. Agree, Apple is currently richly valued and perhaps one of its highest PE ratios historically, if not the highest.
However, having read Dougie’s columns for many years, he has consistently missed one of the greatest runs and successes in history. Same old same old.
Habits die hard.
Dougie Kass
Correct. I have never understood Apple’s valuation.
It has been a capital allocation story (it certainly has not been a top line story) – and that is what I missed.
But Mira it’s important also not to dwell on investing/trading mistakes.
Mistakes happen often – it’s how you manage risk (your mistakes) that counts.
As for me I am often wrong and always in doubt.
Finally though some profess perfection, no one has a concession on the truth in the investing game.
Position: None
BY Doug Kass · Nov 2, 2026, 2:45 PM EST
EARNINGS AFTER THE CLOSE MONDAY NOV. 2
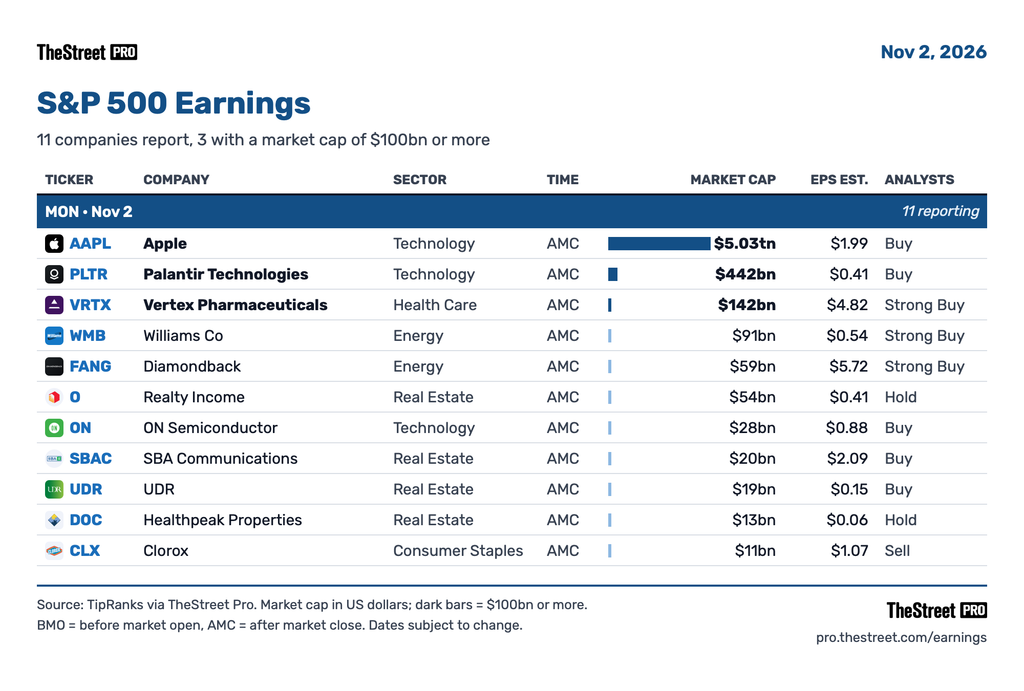
EARNINGS BEFORE THE OPEN TUESDAY, NOV. 3
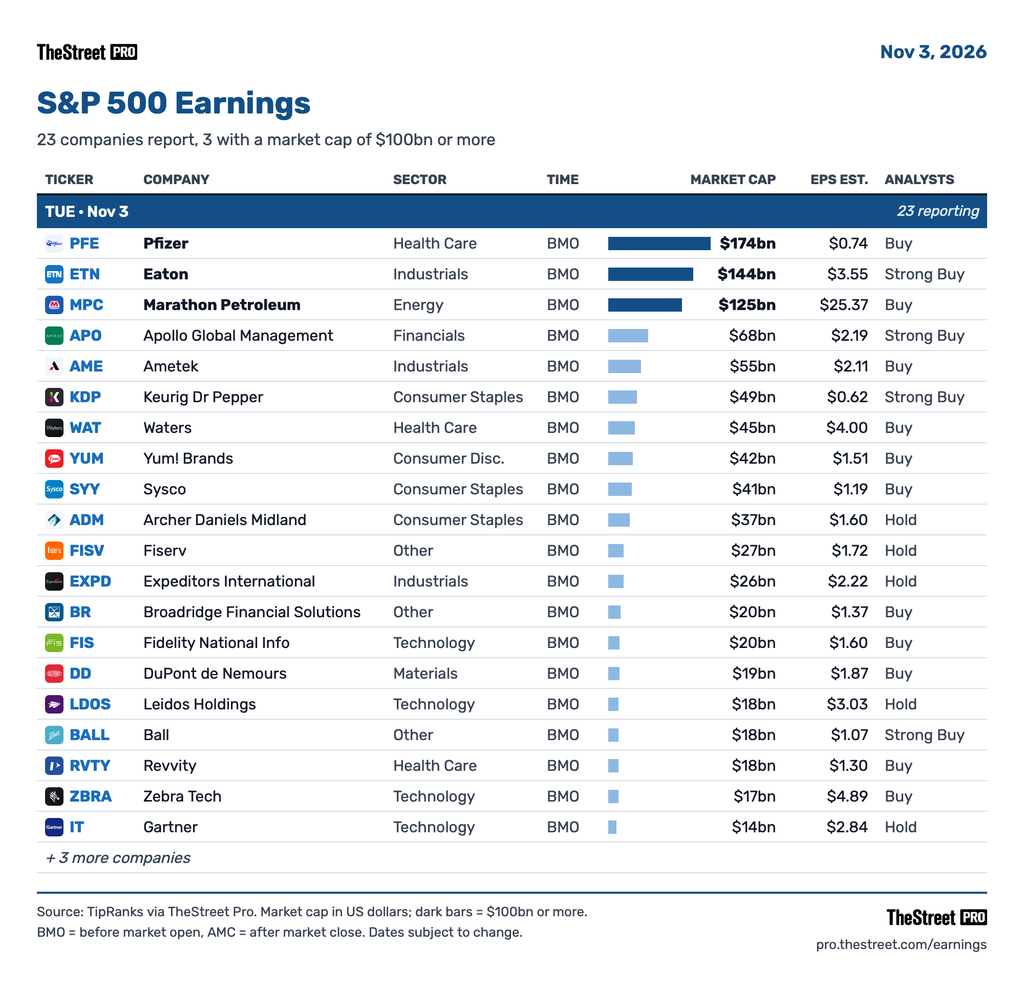
Position: None
BY Doug Kass · Nov 2, 2026, 2:45 PM EST
Wolf Street howls about data centers.
Position: None
BY Doug Kass · Nov 2, 2026, 2:27 PM EST
Third-quarter numbers are out and the picture keeps getting worse:
* Operating loss back to a whopping $567 million (about -34%)
* Commitments are up to $895.4 billion
My guess is the deterioration post Q3 2026 should be even worse, as token prices are still dropping as is their market share, while expense (cost of compute per unit) continues to go up, which they even disclosed in the initial S-1 (page 134).
How can this company be allowed to go public?
Consider the combination of the valuation, governance issues, insider unlocks and the fundamental picture relative to the valuation.
As I stated before, I have an easier time getting to less than zero than I do $2 trillion or even frankly $1 trillion. And I stand by my statement that WeWork and Adam Neumann were a better deal, and that IPO didn’t happen after the S-1 was filed, and that ended up being worth less than zero too!
Position: None
BY Doug Kass · Nov 2, 2026, 2:20 PM EST
I made a big mistake covering my Apple (AAPL) short on Friday!
Position: None
BY Doug Kass · Nov 2, 2026, 1:13 PM EST
Housekeeping items.
I have sold my bank trading long rentals (BAC, C and WFC) for a quick profit from Friday afternoon.
I have also sold out my trading long rentals in UBER and NFLX, also for a gain.
Position: None
BY Doug Kass · Nov 2, 2026, 12:07 PM EST
Zombie Apocalypse – The Credit Strategist
Position: None
BY Doug Kass · Nov 2, 2026, 11:39 AM EST
– NYSE volume 7% above its one-month average;
– Nasdaq volume 17% above its one-month average;
– VIX index: down 5.05% to 18.44
SOURCE: Interactive Brokers
SOURCE: Barchart
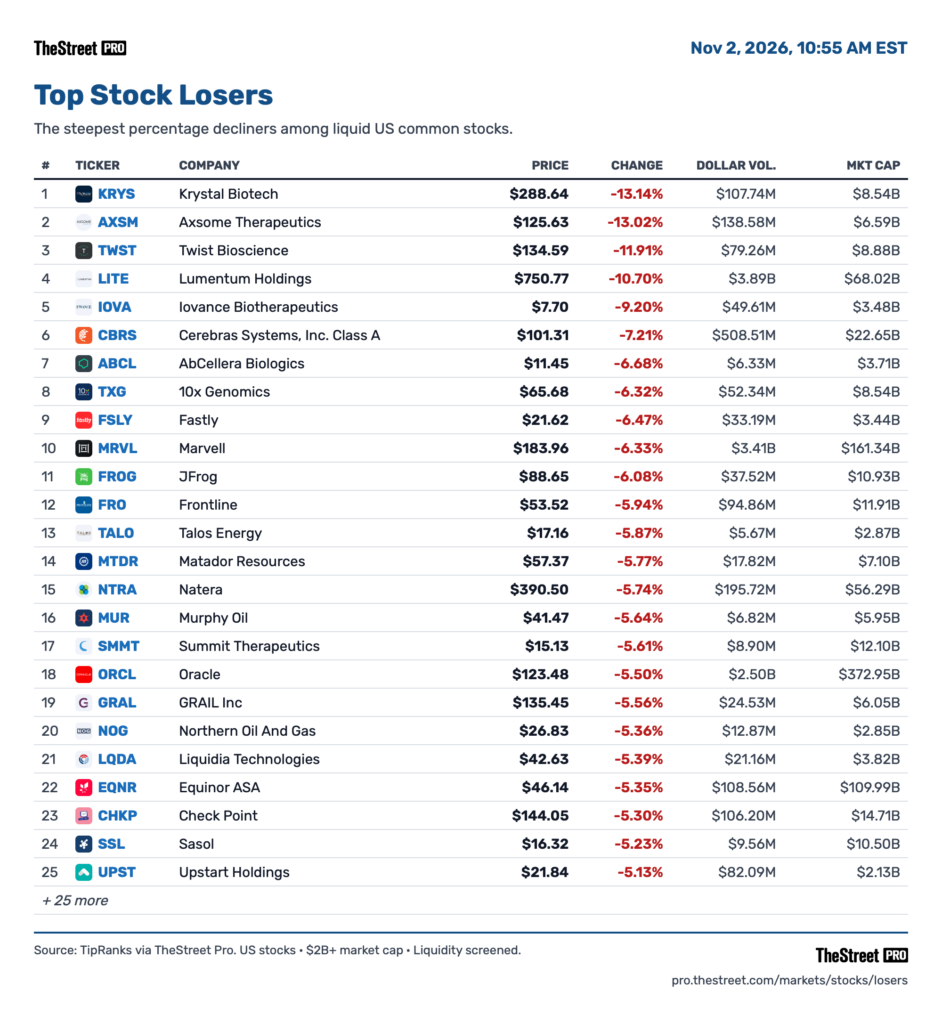
SOURCE: TheStreet Pro
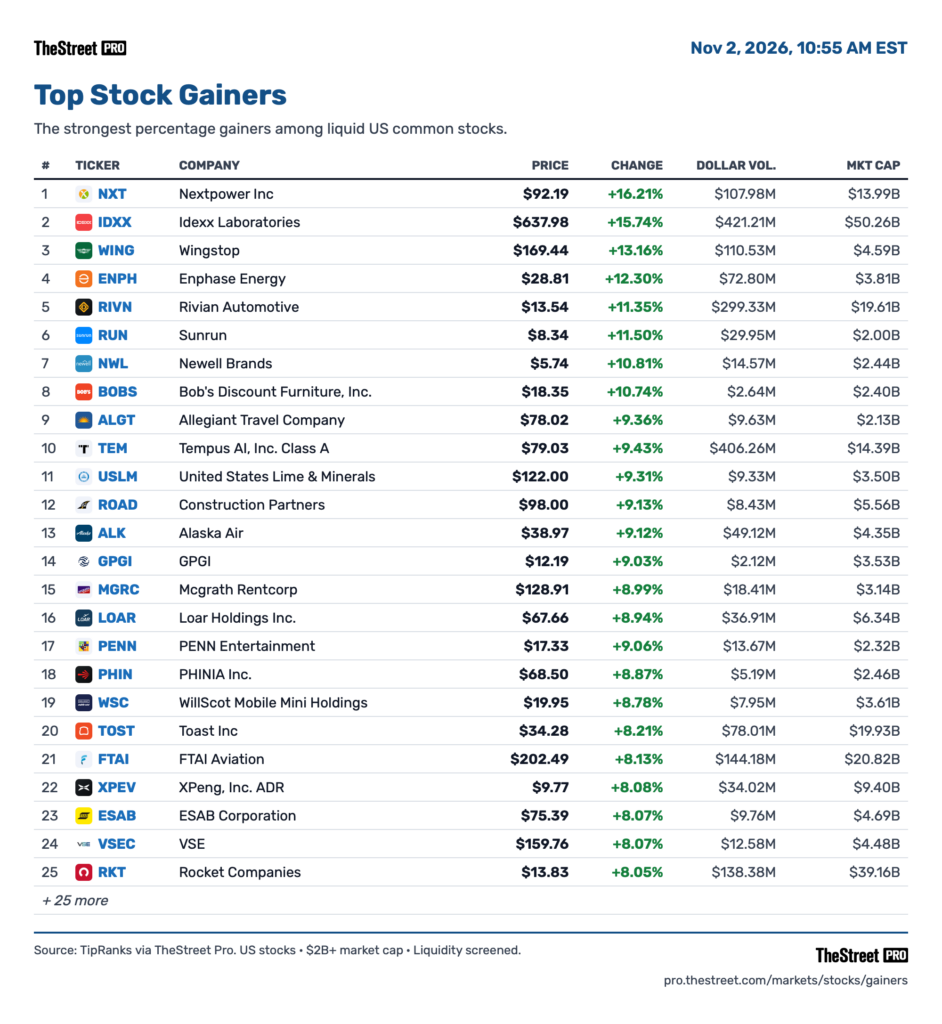
SOURCE TheFly
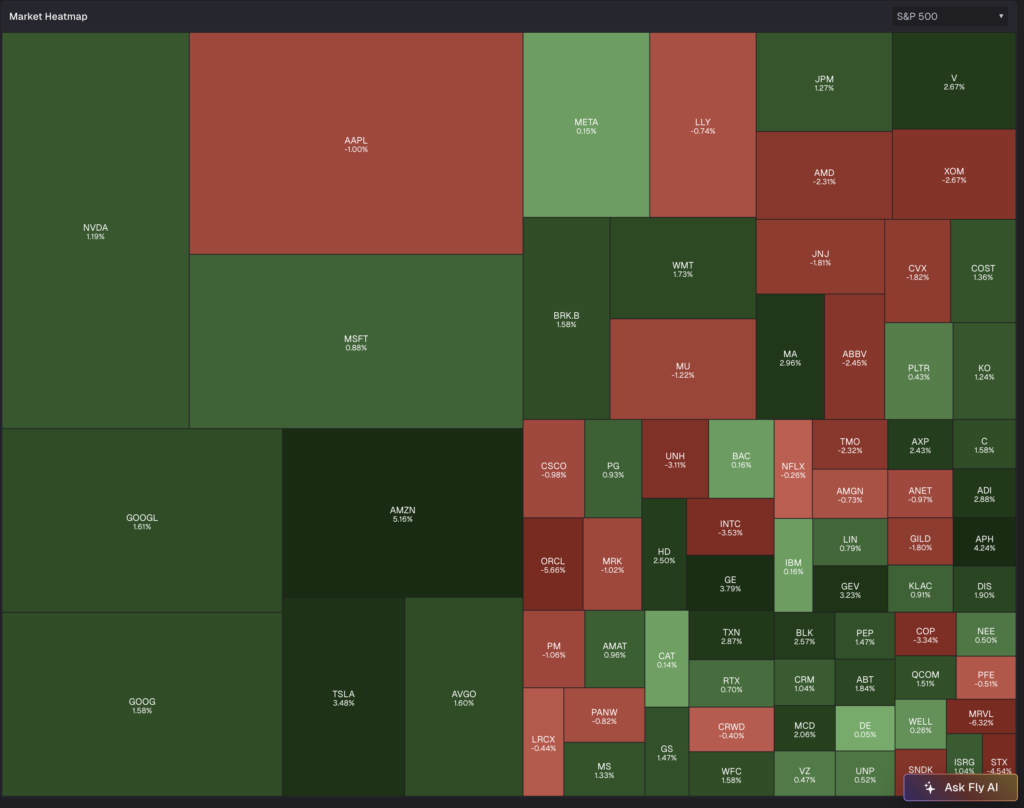
BY Doug Kass · Nov 2, 2026, 11:20 AM EST
The weakness in the former is one of the reasons I sold out of the latter!
From earlier:
I am taking advantage of the sharp move back into the hyperscalers this morning – for some quick profits:
* AMZN $249.79 (+$9.44) Note: AMZN was purchased at $225.56 on Friday!
* META $613.35 (-$1.65)
* MSFT $526.01 (+$4.11)
* GOOGL $286.16 (+$6.33)
At the time of publication, Kass was long AMZN VS META VS MSFT VS GOOGL VS
BY Doug Kass · Nov 2, 2026, 9:55 AM EST
Positions: None.
BY Doug Kass · Nov 2, 2026, 11:12 AM EST
BY Doug Kass · Nov 2, 2026, 10:45 AM EST
* Sold all my BABA $103.68 (+$5.64)
* Eliminated hyperscaler longs:
AMZN $253.04 (+$12.69)
GOOGL $285.49 (+5.65)
MSFT $528.76 (+$6.85)
META $617.95 (+$2.96)
Positions: None
BY Doug Kass · Nov 2, 2026, 10:40 AM EST
BY Doug Kass · Nov 2, 2026, 10:35 AM EST
Marino7777
18m ago
Hi Doug Jsut curious abt your large cap tech purchases. Are these structural longs or trading longs? Do you have a time frame in mind? I know people are talking abt PE’s being cheapest since 2019 but we all know they have issued crazy amounts of debt since then. So is this a play on year end rally or something looking further out ? Or even shorter term than year end? Jsut curious. Ty.
Reply
Dougie Kass
just now
i have a series of tweets that i demonstrate the pe contraction and derisking in the hyperscalers.
in large part this derisking reflects the concerns i have expressed in “more tales” over the last 18 months
again – first level v second level thinking
in other words the valuation contraction has created the “start” of an opportunity as headwinds begin to be discounted
but i am small sized at the get go
in all likelihood these are investments and trading long rentals – in the fullness of time.
but unlike some i can’t calculate with precision the “bottom” in the hyperscalers so i will buy ginerly with a scale lower… at least that is my thinking now.
Positions: None
BY Doug Kass · Nov 2, 2026, 9:55 AM EST
I am taking advantage of the sharp move back into the hyperscalers this morning and reducing from small to very small – for some quick profits:
* AMZN $249.79 (+$9.44) Note: AMZN was purchased at $225.56 on Friday!
* META $613.35 (-$1.65)
* MSFT $526.01 (+$4.11)
* GOOGL $286.16 (+$6.33)
At the time of publication, Kass was long AMZN VS META VS MSFT VS GOOGL VS
BY Doug Kass · Nov 2, 2026, 9:55 AM EST
The following is from Peter Boockvar:
I mention this not as something that will majorly influence Japanese stocks but to highlight when a central bank goes so deep into the market fray with intervention, getting out is extraordinarily difficult. The Japanese yield curve certainly has seen that with the end of NIRP and YCC as 5 years ago the 10 yr JGB yield was at just .04% vs nearly 3% today. Not getting much coverage last week at the BoJ meeting was the news that they are quickening their annual pace of ETF stock sales. At the current pace it was going to take 110 years to sell all of the holdings. With the upcoming new cadence, that will shrink to ‘just’ 43 years. The interesting thing too is because their holdings have gains in them, any excess surplus at the BoJ that is created from the sales will get remitted to the government which can they get spent in the next Takaichi budget.
On Friday Fitch released its Q3 default rate data for its private credit coverage companies. It rose to 6.3% for the trailing 12 months and that is up from 6% in Q2 and the highest since they’ve been doing this. They said “Private credit default rates remained elevated in 3Q26, with stressed maturity extensions, interest deferrals, and payment-in-kind introductions continuing to account for most default events. Persistently high real interest rates are maintaining pressure on highly leveraged borrowers’ debt service capacity and refinancing options.”
While we know this year a big focus of the private credit scrutiny was on software companies, their default rate was just .6%. Instead, the headline figure was driven by Industrials and Manufacturing, and Consumer Products and Services with default rates at 9.7% for each. Healthcare providers had a default rate of 8.7%, though down from 9.4% in Q2.
Late last week the Apartment List October National Rent Report was released and we know rents (both new and renewed) are a key part of CPI. Rents fell .3% for new leases only m/o/m “as the rental market enters its off-season.” They are basically flat y/o/y, up .1% but “marking the first time in over three years that y/o/y rent growth is positive.” The vacancy rate fell one tenth to 7% “remaining elevated compared to long-run norms, but continuing to decline after peaking earlier this year.”
Rent concessions remain elevated with 32% of properties nationally offering them, “four percentage points higher than at this time last year.” And, “Concessions can take many forms, including discounted rents, cash back offers, gift cards, or free amenities” and they are “valued at one month of free rent or greater.”
Regionally, “The decline in our national index in recent years has largely been driven by markets throughout the Sun Belt and Mountain West regions, but we are now beginning to see these regions rebound. Meanwhile, many markets in the Northeast, Midwest, and parts of the West Coast continue to see prices trend up.”
The bottom line from Apartment List, “For years, the U.S. rental market has been experiencing a prolonged period of sluggishness, as a large wave of multifamily construction had been driving soft pricing and occupancy. However, we’re now at the tail end of that construction boom, and the market has been gradually moving toward more balanced conditions. This month’s data marks a significant milestone in that transition, as year-over-year rent growth flipped positive for the first time in over three years.”
I’ll add, not included here are renewal rates and they are running higher by 3-4% based on what I’ve heard from the publicly traded REIT’s. And, I think we’ll continue to see further absorption of the excessive supply in the sunbelt and mountain states as home buying remains unaffordable for many first-time buyers.
To some calls from late last week providing more color on the state of economic activity and the cost pressures many are dealing with.
From Colgate Palmolive, up 2.3% Friday in the tough tape with consumer staples stocks the safety trade and my favorite group, as expressed here before:
“Our strong results were broad based with organic sales growth in all four of our categories and four of our five divisions.”
The division that did not see growth was North America, “impacted by continued softness in the United States. Returning to sales growth in North America remains a key priority.”
“The US market backdrop remains challenging; consumer behavior is volatile, and sentiment is weak given increasing fuel prices. Overall, categories remain under pressure.”
“Raw material, packaging and logistics costs remain elevated, driven by the conflict in the Middle East, which has increased oil prices as well as other commodity costs. We are broadly locked in for the remainder of the year based on our cost projections, which may differ from spot prices.” The ‘other’ commodity costs include resins, petrochemicals and pulp/paper.
From Restaurant Brands, the owner of Burger King, Tim Horton’s and Popeyes and whose stock fell last week:
Burger King is experiencing a renaissance with US comps up 8.4%. “We widened our gap to burger QSR peers to nearly 10 points and after years of hard work, we are incredibly proud to have reclaimed the number 2 position in the US burger category.”
Tim’s Canada had a comp gain of 1.8%, “an encouraging improvement from the 2ndquarter.”
Popeyes had a negative comp of 1.8%.
From Mohawk Industries, the flooring company and whose stock rallied 7.3% Friday:
“We grew sales and executed price increases in response to rising inflation.”
“In our US market, where we generate a little more than half of total company sales, market conditions remain challenging. Following the recent rises in rates, demand weakened exiting the quarter and has remained soft across most products and channels during October, particularly in the builder channel.”
“In residential repair and remodel, which we estimate represents approximately half of our US sales, consumers continue to defer larger projects, and the outlook for existing home sales has weakened, entering seasonally slower months. Activity through the specialty retail channel is holding up better and improved sequentially, while larger format retail point of sale trends remain slow.”
From Eastman Chemical, whose stock was down on Friday but up for the week:
“Input costs continued to elevate, and the Eastman team successfully implemented higher sequential price increases in our specialties. We remain on track to implement approximately $500 million of selling price increases in 2026 compared to our expectations from before the Middle East conflict began.”
“In addition, sequential sales volume/mix decreased due to seasonal declines across our key end markets and softening underlying demand in automotive and consumer durables.”
From Exxon, up about 2% Friday:
“We recognize the impact high prices have on people’s lives and economic growth. We always have, which is why we have been constantly focused on efficiently growing advantaged production to keep market supplied. That focus and commitment pays off in times like this.”
“Our global outlook projects that global energy demand will continue to grow through 2050, with oil and natural gas supplying more than half of the world’s energy. Meeting that demand reliably will require continued investment across the industry, including in the Middle East.”
From Schneider National, the trucking company and down a touch last week:
“Looking at the freight environment, the supply thesis remains intact. Though capacity attrition occurred at a more measured pace than what we experienced in the first half of the year, we are continuing to see an overall constrained supply picture despite spot rates now having moved higher for nearly a year.”
“Capacity has remained hampered by driver availability, elevated operating costs, and increased barriers to entry. Further, we continue to see several factors that should support additional rationalization going forward.”
“At the same time, fuel costs have increased meaningfully. Driver wages are on the rise and smaller carriers are facing increasing economic pressure. Together, these dynamics are limiting the ability of supply to respond to improving pricing conditions and with noncompliant capacity exiting the market, we continue to expect supply to behave rationally as we move further through this up cycle.”
“While supply dynamics remain constructive, freight activities are a modest step back versus 2nd quarter, a reflection of anticipated seasonal patterns coming out of the Fourth of July holiday. Consumer spending remained resilient overall, though this varied by category. Higher interest rates and affordability constraints continued to weigh on certain key end markets such as housing and automotive.”
“Altogether, we believe 3rd quarter freight volume activity reflected typical seasonality and some normalization of inventory patterns rather than a deterioration of underlying demand trends which remained stable.”
Ahead of the US October ISM, here were the manufacturing PMI’s out today overseas and most remain above 50:
China 52 vs 52.1
Japan 53.3 vs 54.1
South Korea 51.3 vs 53.9
Taiwan 54.9 vs 56.7
Australia 49.6 vs 49.6
India 54.7 vs 55.1
Vietnam 52.3 vs 51.9
Thailand 54.8 vs 54.3
Indonesia 54 vs 52.4
Malaysia 51 vs 49.9
Eurozone final 52.7 vs 52.9
UK final 52.8 vs 51.9
For China specifically, RatingDog said ““Output expanded for the eleventh successive month, and at the sharpest rate since April, on the back of strong client demand and better production capacity, with growth broad based across all three monitored sub-sectors for the third month running and steepest in investment goods. Total new orders rose for the seventeenth consecutive month, with the pace of increase sharp and broadly in line with September, helped by new product launches, improved production capabilities and business development efforts. New export orders rose for the fourth month in a row, with anecdotal evidence pointing to greater volumes of new work from clients in Asia, Europe and Africa, though the pace of expansion eased to a three-month low and was modest, with growth slowing among consumer and intermediate goods makers while accelerating for investment goods firms.”
With Taiwan, S&P Global said manufacturing remained strong, we know helped by AI infrastructure and “The supply chain story was broadly consistent, as firms continued to face difficulties procuring inputs in a timely manner. The conflict in the Middle East, freight delays and the added supply chain pressure caused by the current AI wave were key contributing factors here.”
On the inflation side, “The cost environment remained challenging amid instances of material shortages and solid demand. Some firms even reported front-loading their purchasing to hedge against future price increases and to cushion the impact of supply chain disruption. There was some evidence that cost pressures had softened, however, and a subsequent drop in the rate of selling price inflation was also reported.”
With the Eurozone, from S&P Global “Another solid PMI reading extends the eurozone’s best growth spell for manufacturing for over four years. The sustained growth recorded since February paints an encouraging picture of resilience for the manufacturing sector, which has been buffeted by the headwinds of tariffs and conflicts in the Middle East and Ukraine, and in particular the surge in costs and supply difficulties that these have caused. Instead, increased defence spending, precautionary inventory building, diversification and changing trade patterns due to US tariffs have created growth opportunities for many producers.”
“However, growth is by no means broad-based, with manufacturers in France and Italy in particular continuing to struggle, the former suffering the additional stress of domestic political uncertainty.”
BY Doug Kass · Nov 2, 2026, 9:50 AM EST
I am out of GLD at $362.31.
Positions: None.
BY Doug Kass · Nov 2, 2026, 9:38 AM EST
Here is a short follow up to my last two More Tales.
With regard to Gen AI being dis-economic and resource inefficient, We Work being a better deal than Anthropic (and Open AI), and Adam Neumann being more qualified than Dario Amodei (or Sam Altman) to be a public company CEO, which granted, would make Neumann the world’s tallest small person.
Here is Sam Altman basically stating that nobody should be allowed to have a PC (or presumably a handset or anything else) so he can have all the memory, at better prices.
Uh Sam, whose fault is it that DRAM prices have gone through the roof? Do you realize what a pain in the ass this is for every normal person, the overall inflationary impact on the economy, and all of the knock on effects borne from that?
These people are complete and utter sociopath’s who have built their business on the backs of stealing IP from others, and numerous other unsavory behaviors. The whole industry is a collection of sociopaths, stock promoters, and greater fools, culminating in trying to dump a $2 trillion pile of junk with a broken technology on the public at large.
Even worse, the Anthropic IPO is structured in such a way to leave permanent control with these types of people, while they sell their own stock. This cannot be allowed to happen. It is absolutely ridiculous to centralize this much power and influence with a bunch of loonies that will have no form of external governance to moderate their self-serving behavior and sociopathic whims.
If they have it their way, nobody will have a computer, nobody will have a cell phone, and who knows what else they want nobody but them to ultimately have?
This is interesting too. A junk rating for a 2 trillion dollar company with all of that cash? Hmmm. Yeah, it is junk because it is a $2 trillion dollar pile of garbage with massive future commitments (ergo functionally debt) with deteriorating fundamentals and poor and misleading disclosure (Q3 blank for example), awful governance, and crazy insider unlocks, that loses money hand over fist, which is being dumped on the public. Should not be allowed to happen. We Work was a better deal IMO, and We Work ended up being worth less than zero, despite the banker’s initial valuation attempts and all the hype surrounding it as well.
From Jeffrey Gundlach:
Positions: None
BY Doug Kass · Nov 2, 2026, 9:30 AM EST
I moved to very small on GLD at $361.68.
Positions: Long GLD VS
BY Doug Kass · Nov 2, 2026, 9:25 AM EST
– INO +262% (FDA grants accelerated approval to VOCERYQ to reduce surgery frequency in adults with recurrent respiratory papillomatosis)
– PERI +31% (agrees to be acquired by Affle for $11.70 a share in cash, valuing the deal at about $420M)
– IDXX +7.8% (Q3 beat and FY revenue and EPS outlooks were raised, outweighing a slightly lower margin range)
– BABA +3.3% (China adds liquidity through a 100B-yuan swap facility, while reports point to BABA support for AAPL’s China AI rollout)
– SKHY +3.2%, MU +1.1%, WDC +1.0%, SMTC +1.3% (memory and connectivity names rebound from Friday’s chip rout as Deutsche Bank turns bullish on US technology)
– GFI +3.1%, AG +1.7%, HL +1.9% (gold and silver miners rebound as precious-metal prices recover)
– RIVN +3.0% (UBS upgrades to Buy on valuation after the recent selloff)
– CRWD +2.6% (Deutsche Bank upgrades to Buy)
– EL +2.3% (Q1 beat with strong margin expansion and the FY sales, margin and EPS outlook raised)
– AU +2.2% (TD Cowen initiates at Buy as gold rebounds)
– FORM +1.7% (Freedom Capital upgrades to Buy after record Q3 results and the recent pullback)
– CRWV +1.4%, BE +1.2%, VRT +1.3% (AI-infrastructure names rebound with technology after the sharp three-week selloff)
– KPTI -69% (files Chapter 11 and names Ayrmid as lead bidder in a court-supervised sale process)
– PGEN -28% (falls on new RRP competition after the FDA approves INO’s VOCERYQ)
– KOS -9.2% (Q3 profit and revenue missed expectations as crude prices retreat)
– CHKP -6.3% (Q3 revenue slipped and missed expectations as management said the recovery is taking longer than anticipated)
– EQNR -2.9%, OXY -2.0%, APA -1.9%, XOM -1.3%, CVX -1.1% (oil producers fall as crude drops nearly 4% on renewed US-Iran diplomacy)
BY Doug Kass · Nov 2, 2026, 9:15 AM EST
I am reducing my GLD holding (at $361.74 or +$6) from medium-sized to small-sized on the move that just occurred.
I added early this morning (at $357.08):
I have added to my GLD long at $357.08 in the premarket.
Position: Long GLD (M/L)
BY Doug Kass · Nov 2, 2026, 6:25 AM EST
Position: GLD S
BY Doug Kass · Nov 2, 2026, 9:00 AM EST
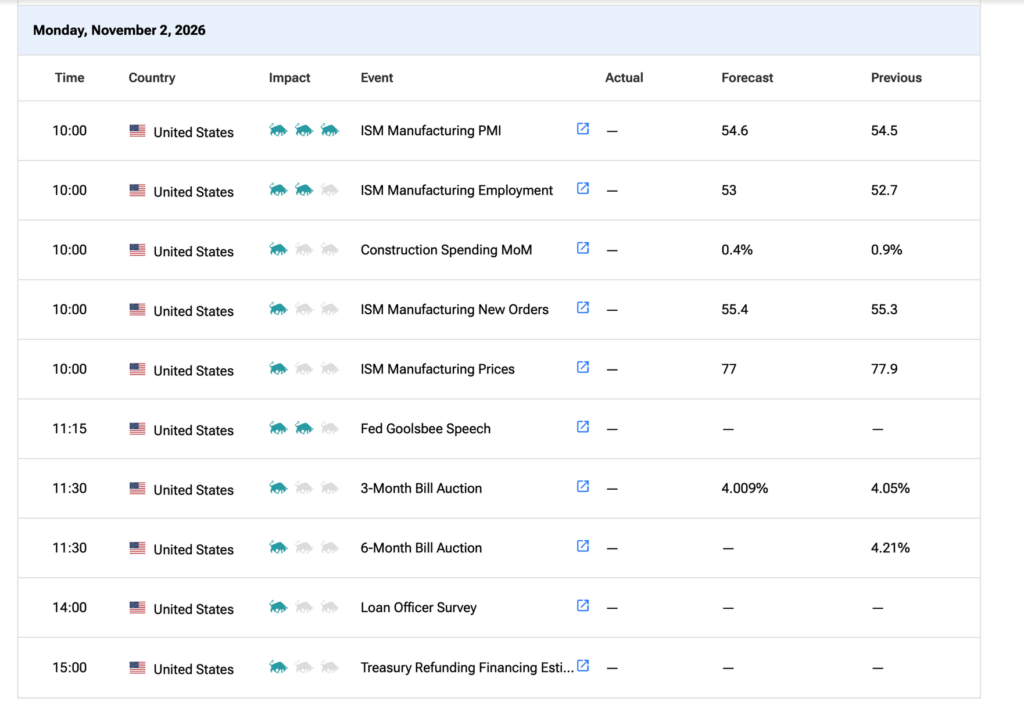
11:15 a.m.: Fed Bank of Chicago President Goolsbee (Non-Voter) moderates a discussion before the Financial Markets Group Fall Conference, Chicago, IL (Livestream available. No embargoed text)
SOURCE: TipRanks
BY Doug Kass · Nov 2, 2026, 9:00 AM EST
BY Doug Kass · Nov 2, 2026, 8:55 AM EST
BY Doug Kass · Nov 2, 2026, 8:45 AM EST
From the Iranian Press – the Iran Supreme Leader has reportedly granted government authority for talks.
Futures rise on the news.
Positions: None
BY Doug Kass · Nov 2, 2026, 8:42 AM EST
I have written nearly 270 columns (“More Tales From Nvidia”) on The StreetPro.
I have expressed a number of concerns (from a lay person’s perspective) — some of which Roger McNamee and I share in common:
* Society is ill prepared for the negative consequences and safety issues associated with AI.
* The AI creators and practitioners take no responsibility for those consequences and issues. Indeed, they are trying to the opposite — evading accountability.
* The reality of AI has fallen far short of expectations and applications.
* Thus far the apparent presence of enterprise customers (who pay more for AI services than it costs a vendor to provide them), the benefits of scaling training sets and data centers and the widely anticipated productivity gains have been slow to materialize.
* The limitations of large language models is growing more apparent. The systems are inherently probabilistic — resulting in varying degrees of errors and non-predictive results. Those shortcomings are not being overcome by scaling computer power.
* A one size fits all product requires massive amounts of time and money to integrate into existing systems — with limitations already developing on funding.
* The speed to market and scale of AI investment failed to wait for innovation to drive down the price of infrastructure (in fact, the opposite is happening with costs rising) and has created not only a timing problem between outlays and revenues but (also) potential risk to the bond and the broader economy far worse than the internet era.
* Though more than two handfuls of companies are in competition with different AI products, history shows that only a few will likely be successful. The potential for hundreds of billions of dollars of writeoffs is rising.
* The size of AI infrastructure investment and the amount of debt being employed is inflationary, raises interest rates and crowds out other borrowers. Already investors’ appetite appears to becoming sated and companies like CoreWeave (CRWV) (a short) and Oracle (ORCL) (also a short) are already “in distress” with extended balance sheets and offshore financing.
* Other risks from AI products include fraud, cybersecurity, deskilling workers and students and social isolation.
* AI concentrates power in the hands of a few — some of whom have previously expressed authoritarian tendencies.
From Roger McNamee:
Position: None
BY Doug Kass · Nov 2, 2026, 8:30 AM EST
Positions: None.
BY Doug Kass · Nov 2, 2026, 8:10 AM EST
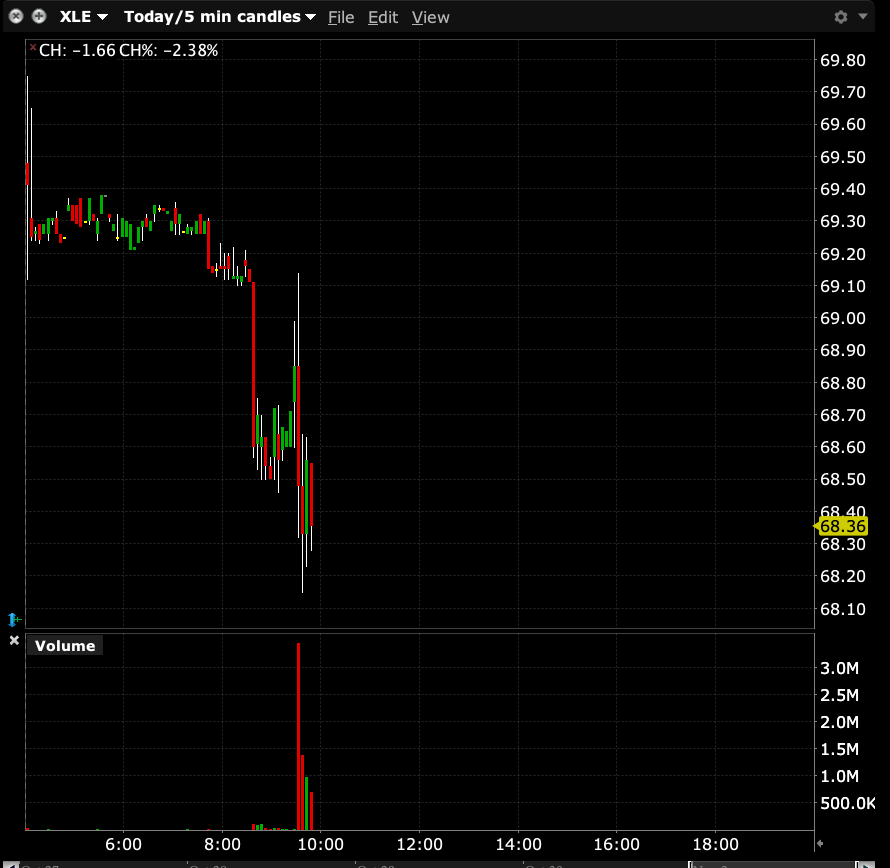
Investors derisk the hyperscalers (I initiated positions on Friday):
Position: None
BY Doug Kass · Nov 2, 2026, 7:55 AM EST
Position: None
BY Doug Kass · Nov 2, 2026, 7:45 AM EST
Position: None
BY Doug Kass · Nov 2, 2026, 7:25 AM EST
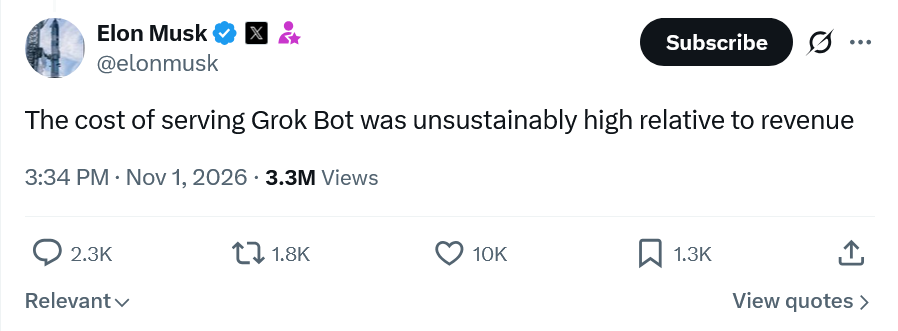
Well look at who just made my big-picture point without realizing the implications of what he was saying! I guess they are putting usage caps in place now from what I can tell. Many of the things the frontier models do, Muse, and other apps are even worse in this regard.
I am screenshotting this one too, so he can’t delete it:
Position: None
BY Doug Kass · Nov 2, 2026, 7:15 AM EST
Position: None
BY Doug Kass · Nov 2, 2026, 7:05 AM EST
Position: None
BY Doug Kass · Nov 2, 2026, 6:55 AM EST
I purchased four hyperscalers in Friday’s schmeissing — in part because of the oversold in the space:
I had been waiting patiently…
Position: Long AMZN (VS), MSFT (S), GOOGL (S), META (S)
BY Doug Kass · Nov 2, 2026, 6:45 AM EST
Dougie Kass
As of Friday’s close I was about 15% net long...
Position: None
BY Doug Kass · Nov 2, 2026, 6:35 AM EST
I have added to my GLD long at $357.08 in the premarket.
Position: Long GLD (M/L)
BY Doug Kass · Nov 2, 2026, 6:25 AM EST
Position: None
BY Doug Kass · Nov 2, 2026, 6:15 AM EST
I call B.S:
Position: None
BY Doug Kass · Nov 2, 2026, 6:02 AM EST
Here were Friday’s things:
* I initiated trading long rentals in AMZN at $225.56, BABA at $98.70, GOOGL at $279.56, META at $615.36, UBER at $65.18, NFLX at $62.08 and MSFT at $524.50.
* I initiated trading long rentals in BAC at $50.12, C at $122.02 and WFC at $83,73.
* I covered my ARKK short at $80.03 and my FIGS short at $21.16.
* I covered my AAPL short at $345.70.
* I added to MSOS at $3.93, GTBIF at $6.25, GLAS at $2.23 and VRNO at $5.03.
* I added to GLD at $362.10.
Position: Long MSOS common (VL) and calls (VS), GLD (M), GTBIF (S), VRNO (VS), GLAS (S), AMZN (S), BABA (S), GOOGL (S) META (S), UBER (S), NFLX (S), MSFT (S), BAC (S), C (S), and WFC (S).
BY Doug Kass · Nov 2, 2026, 5:50 AM EST
The S&P Oscillator remains in overbought at 1.10% vs. 1.47%
Position: None
BY Doug Kass · Nov 2, 2026, 5:40 AM EST
Mag 7 P/E 21.7x... very close to the cheapest since early 2019 @yardeni It was 10 turns higher 12 months ago

ANTHROPIC Q3 2026 FINANCIAL HIGHLIGHTS: - Revenue: $17.0B, +1,127% YoY & 47% QoQ - Oper Loss: $567M (vs. $974M profit in Q2) - Net Loss: $23.3B, vs. $12.1B YoY - Adj. Oper Income: $2.5B - Adj. Oper Margin: 15%, down from 19% in Q2 - 9M Revenue: $33.2B Anthropic attributed itsShow more

HIGH YIELD OAS Spread widened a big +17bps on Friday


Officially, nobody bought Norwood $MPT Imminent Eminent Domain
@TheStreetPro I suppose if your make four short term market calls in less than a month... one will be correct. CNBC doesn't memorialize recommendations - they don't timestamp panelists and guests recs. But the internet does: (1) … on X: "@DougKass THIRD TIME in the last Show more


🚨 $BMNR BITMINE CHAIRMAN TOM LEE @fundstrat ON WHY THE AI SELL-OFF IS A "COILED SPRING": "This is what I view as a coiled spring because the fundamentals have been holding in" His history lesson: "In 1997, 3 years after the launch of the public internet... Cisco, which was
Market breadth just had one of its best weekly improvements in the last 20 years... GS

The embedded tweet could not be found…
@TheJudgeCNBC Scott, Slink et al have the same discussion that Kelly and Brian did with their guest who also highlighted the strong EPS growth. Scott see below (debunking the relationship between s and p eps and s and p prices). It is also the quality of the EPS and EPSShow more

Sully and Kelly @SullyCNBC @KellyCNBC Your guest, like many on @CNBC use the strong EPS story as a foundation to their Bull argument. However: * This is known (see first level v second level thinking) and appears to have been discounted. * I debunk the relationship between S&P

The cost of serving Grok Bot was unsustainably high relative to revenue
Remember, it is not uncommon to see declining P/Es when earnings are peaking. The magic of the market's discounting function is at play.

“Low” P/Es don’t matter if the “E” built into the equity will decline in the future. Just a reminder.
The carnage in AI stocks has $QQQ's P/E below 20 after the nearly 33 peak in the 4th qtr of 2025. Bulls, with perhaps a bit of concern, see opportunity. Bears see blood. A violent bounce vs the repercussions of the bounce failing? Chart courtesy of @johnauthers

MS: hedge funds have now moved underweight the broader AI trade for the first time since early 2023, and the combined summer and October de-grossing marks "the largest sustained stretch of L/S fund de-risking in over 15 years, as gross exposure never fully recovered between Show more


Splash Zone: Hedge Funds Go Underweight AI For First Time Since 2023 As Record De-Grossing Meets Record-Low Correlation zerohedge.com/markets/splash…
Anthropic hoping to get an investment grade bond rating is simply absurd. Any rating agency that might give such a rating should be investigated/shut down immediately.