Heading Back
I will be back in my office at 2 p.m.
That was a quick trip to NYC and back!
Positions: None
BY Doug Kass · Oct 7, 2026, 1:40 PM EDT
 Doug KassDoug Kass
I will be back in my office at 2 p.m.
That was a quick trip to NYC and back!
Positions: None
BY Doug Kass · Oct 7, 2026, 1:40 PM EDT
By Peter Boockvar:
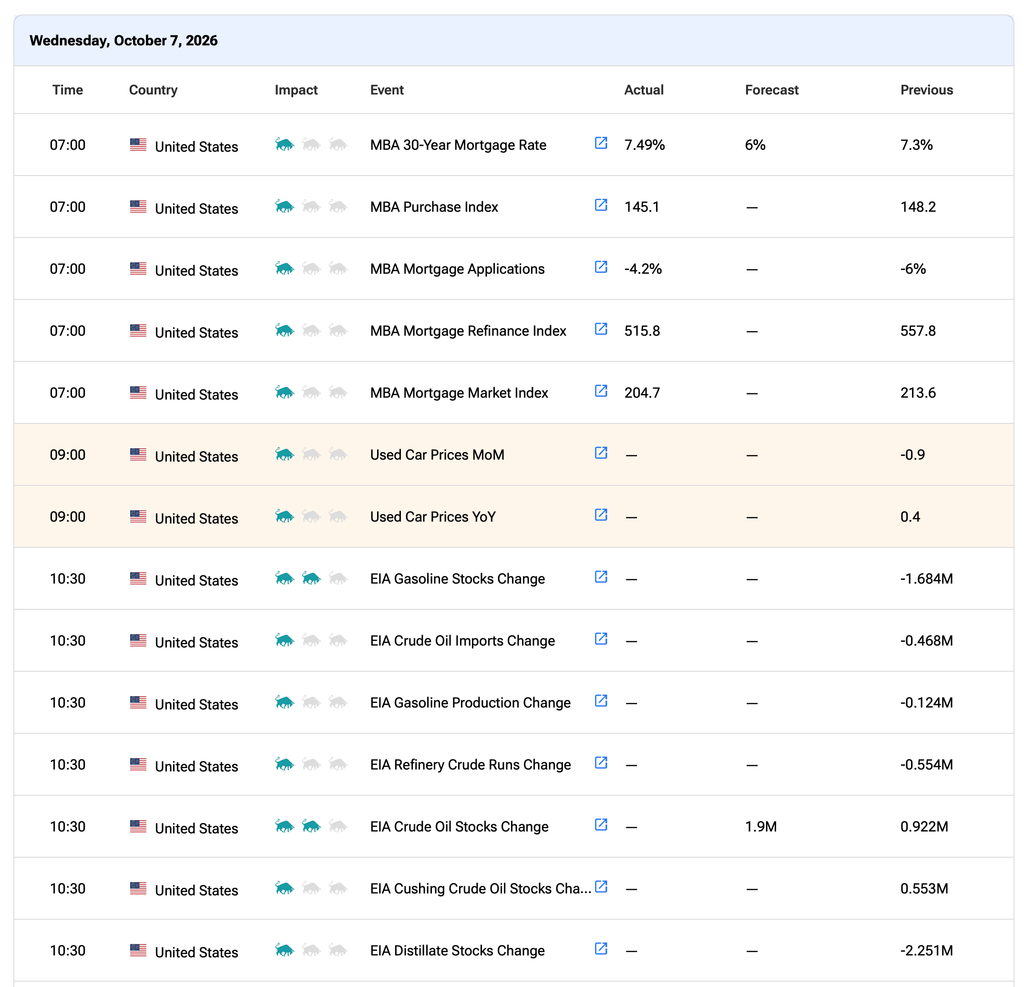
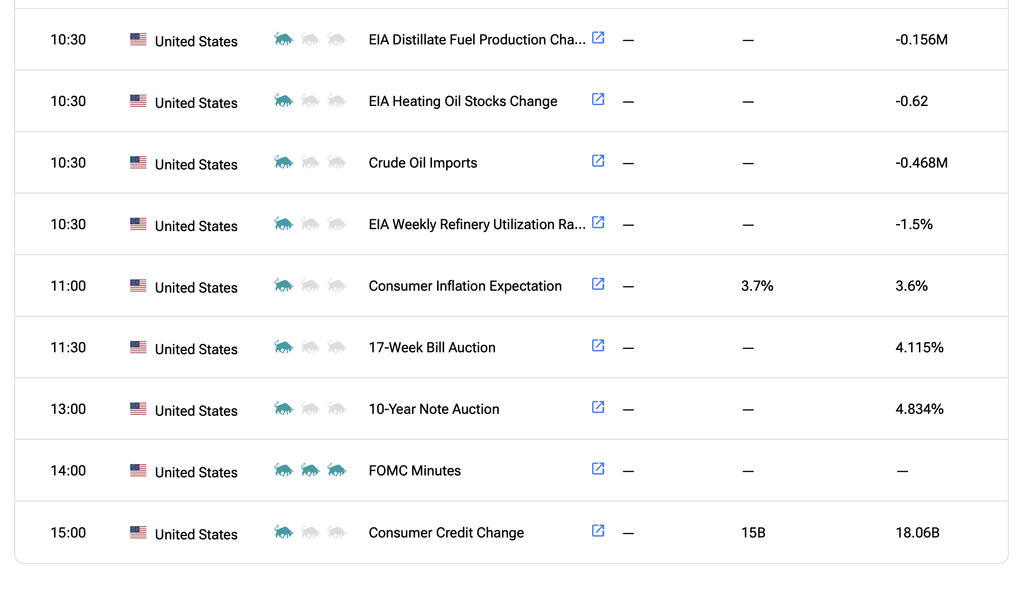
The 10 yr note auction, with yields hovering around 24 year highs, was solid. The yield of 5.30% was almost 2 bps below the when issued pricing. The bid to cover of 2.77 was well above the one year average of 2.51 and that matches the highest since late 2014. Also, direct and indirect buyers took down 97.5% of the auction which is the most I’ve seen.
Bottom line, for whatever reason, likely the 24 yr highs in rates, brought out the buyers and resulted in a great auction. In response, the 10 yr yield has backed off to 5.27% from 5.31% just prior to the results.
Positions: None
BY Doug Kass · Oct 7, 2026, 1:30 PM EDT
By Peter Boockvar:
That SOS call was rejected, for now/The uncertain path to profitability/Oil/Other
The selloff in French bonds is resuming, in turn taking yields up across the Euro region and in the US too, as the Governor of the Bank of France and ECB Council member Emmanuel Moulin himself said “The ECB is not there to deal with the fiscal problems of countries – it is there to fight inflation and have inflation around 2%. So the conditions are not met today for an intervention from the ECB.” Not that market players expected the ECB to step in anytime soon but this was a reminder.
Interesting stat from Goldman Sachs that I read in the FT, “more than a quarter of investment grade French companies had a lower yield on their bonds than comparable government debt as of the end of September.” This would include LVMH and Sanofi.
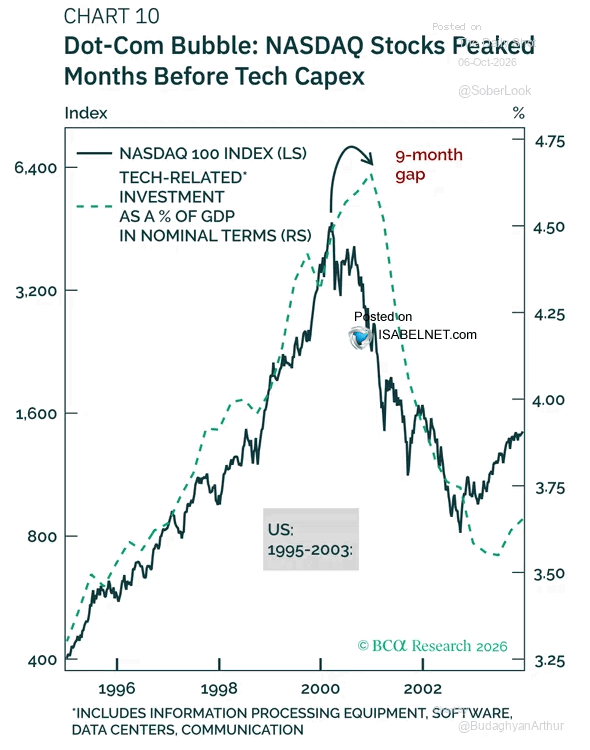
Because of the continued dominance of AI spend both on the US economy and US stock market any prudent investor, market watcher and business person has to always be on the lookout for when the spend slows or is disrupted in anyway.
I took note of a piece in the FT last week titled “Corporate America eyes cheaper AI options” which said this is because of “spiraling IT expenses push executives to look for alternatives to Anthropic and OpenAI’s frontier systems.” And that “So-called open weight models, which users can customize and run on their own hardware, can be far cheaper for businesses to run than paying for access to the most advanced versions of Chat-GPT or Claude.” Not that we don’t know open models are cheaper but highlighted the growing take rate of them.
Further, “While the shift is most pronounced among techology groups, a cross-industry swath, including PNC Financial Services, logistics group CH Robinson and industrial giant Siemens, have discussed using open-weight models.”
“In August, open weight models accounted for 56% of all tokens processed through Vercel’s AI Gateway, up from 7% in December. A similar pattern is visible on OpenRouter, where open-weight models from Chinese labs dominate the top 10 by tokens processed.”
https://www.ft.com/content/d9de4776-1fc9-4f2b-aaaf-9961c35d8acd?syn-25a6b1a6=1
And you’ve heard me say many times before, the Chinese won’t stop with their growing competitive presence on the global tech stage. In an article in Nikkei News yesterday, “China’s artificial intelligence development drive is showing no signs of slowing, with DeepSeek, Xiamoi and others rolling out models last month despite calls from Anthropic CEO Dario Amodei to slow down as risks mount.”
It followed by saying, “According to a Nikkei tabulation, 10 of China’s leading AI companies – including startups like DeepSeek as well as tech giants Alibaba Group, Tencent Holdings and Xiaomi – launched a combined 16 models in September. The count is only newly developed models, including those for image and audio generation, and excludes models that merely modify existing systems developed by other companies.”
I continue to bring this up because so much of the US AI tech trade is dependent on OpenAI and Anthropic and the crucial path to profitability for them both because of the massive financial obligations they’ve created for themselves that flows through the entire infrastructure spending ecosystem.
With respect to oil and gas stocks, we remain long and positive, especially after hearing from the CEO of Saudi Aramco again who spoke Monday at the Energy Intelligence Forum in London. With the caveat that he’s talking his book, he said that we entered the conflict with Iran with about 10 billion barrels of oil inventory globally. We’ve lost 3 billion barrels of gross oil supply which is about half the crude and refined products that would have transited the Strait normally. Add in another 1 billion barrels that have been drawn down from commercial inventories and you have 6 billion barrels left but Amin Nasser, the CEO, said that those are not “practically available” and the supply cushion is “Scarily thin.” He believes that even if the Strait fully reopened today, it could take up to two years to normalize global inventories again.
The CEO of Vitol Group, the large trading firm, speaking at the same conference said “We need about 10,12, 14 million barrels to come out via the shipping route in order to keep things in balance as we go through the winter. Because there aren’t any more inventories to drain in the West.”
According to the Mortgage Bankers Association, the average 30 yr mortgage rate as of 10/2 jumped to 7.49% vs 6.85% one month ago and it sent purchase applications down by 2.1% w/o/w, lower for the 5th straight week and to the lowest since February 2025. Refi’s declined by 7.5% and lower for the 7th straight week and to the slowest pace since early 2025.
Overseas, Japanese wage earners saw another solid increase in base pay in August of 3.8% y/o/y, matching the best since the early 1990’s. The BoJ has every reason to raise rates again at the end of the month meeting but rate hike odds are only at about 10% as the market believes they will wait until the December meeting to hike again.
After a soft factory orders figure for August in Germany, today they said industrial production was better helped by spending on defense.
BY Doug Kass · Oct 7, 2026, 1:15 PM EDT
Adding to my (GRNY) short at $28.51.
Positions: Short GRNY (M)
BY Doug Kass · Oct 7, 2026, 12:49 PM EDT
I am in the process of writing a column about the circular financing of AI.
It is revealing and I believe damaging to the bullish thesis — it ties and quantifies the risks in a way I haven’t seen anyone do.
But it is also at a deep dive that I am fearful that I will lose our readers in the first paragraph.
A part of me wants to complete it but it will take a lot more time.
A part of me wants to complete it and provide a summary.
Stay tuned.
Positions: None
BY Doug Kass · Oct 7, 2026, 12:35 PM EDT
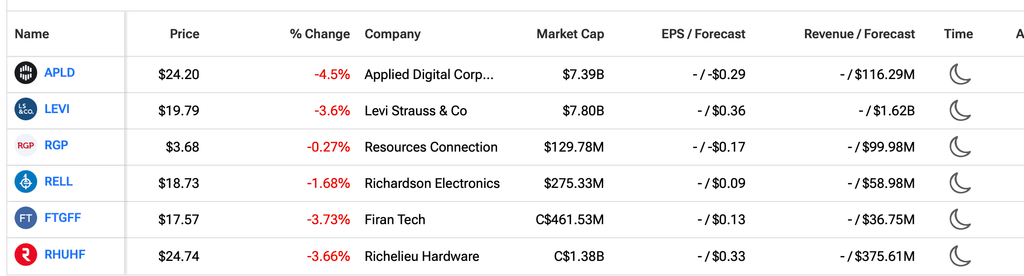
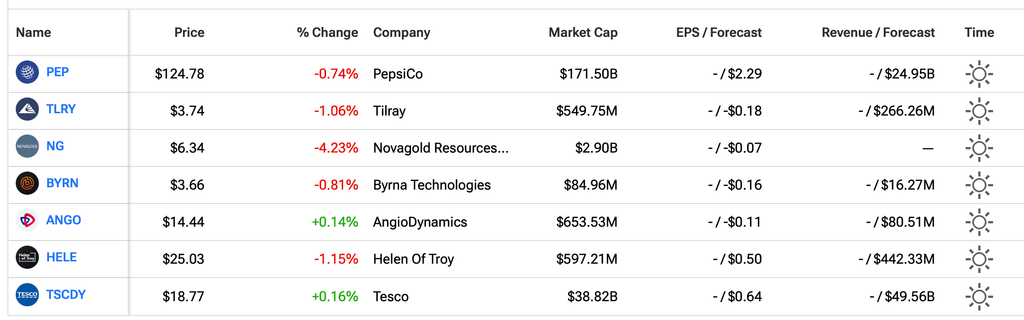
SOURCE: TipRanks
Earnings After Close 10/07/2026
Earnings Before the Open 10/08/2026
BY Doug Kass · Oct 7, 2026, 12:20 PM EDT
I plan to reshoot into a rally.
Positions: None
BY Doug Kass · Oct 7, 2026, 12:08 PM EDT
At 11:36 AM:
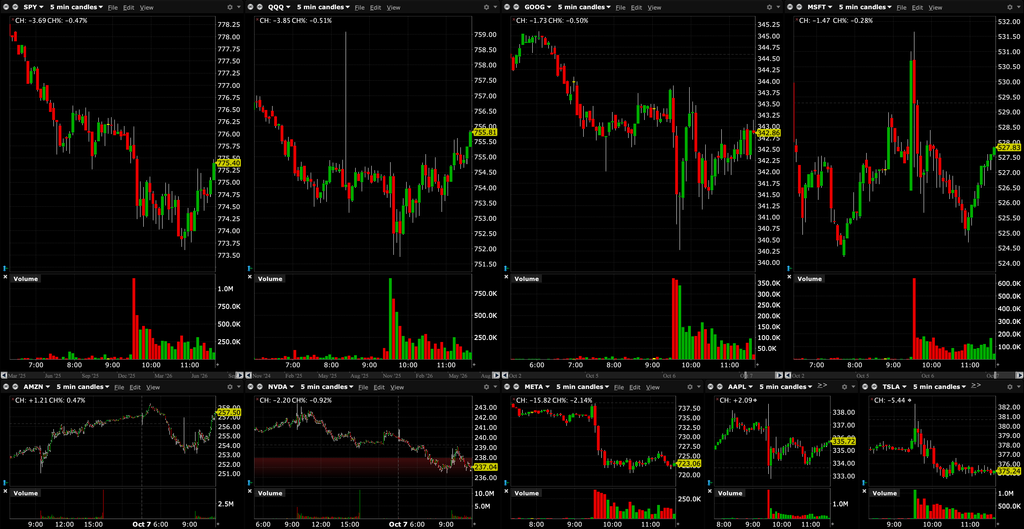
Position: None
BY Doug Kass · Oct 7, 2026, 11:50 AM EDT
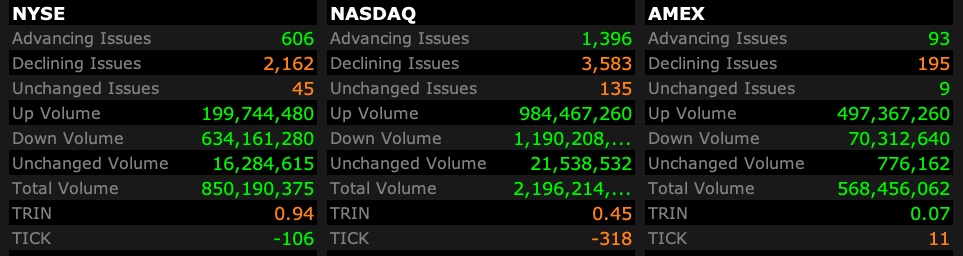
– NYSE volume 7% below its one-month average;
– Nasdaq volume 13% below its one-month average
– VIX index: up 4.53% to 15.69
SOURCE: Interactive Brokers
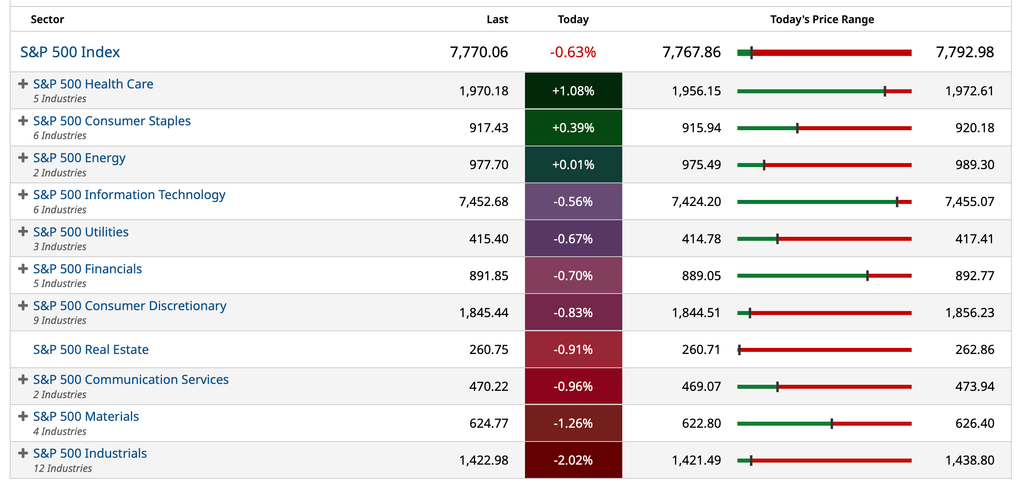
SOURCE: Barchart
SOURCE: TheStreet Pro
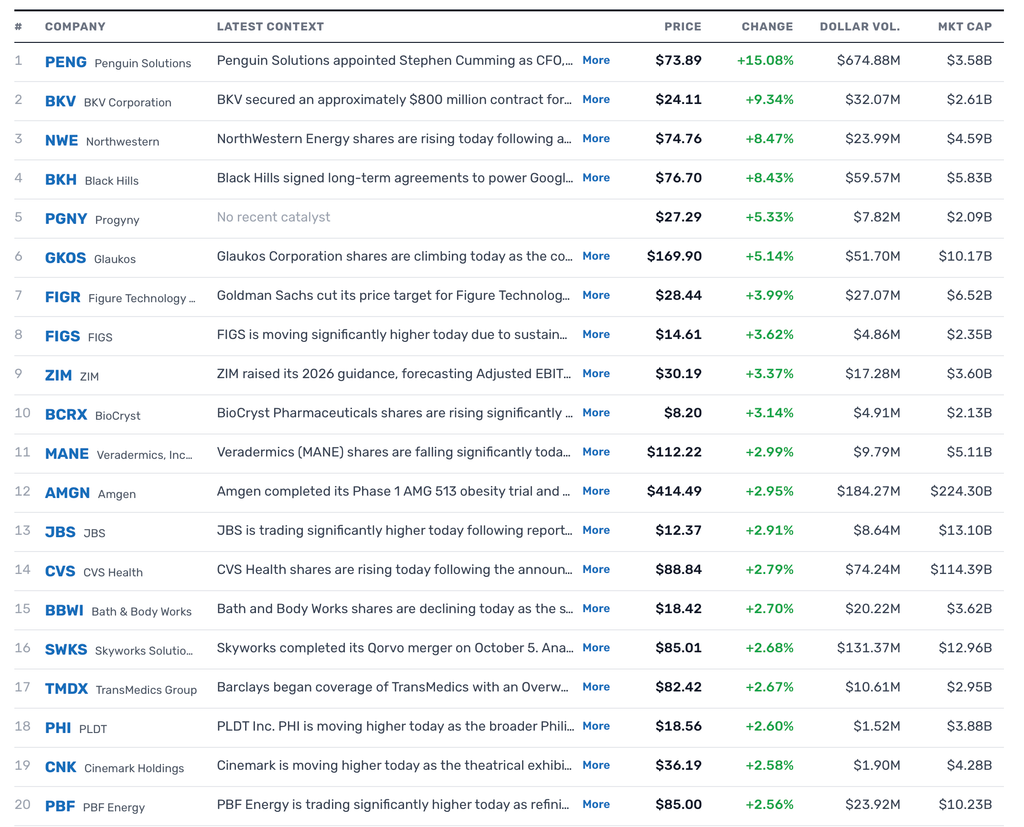
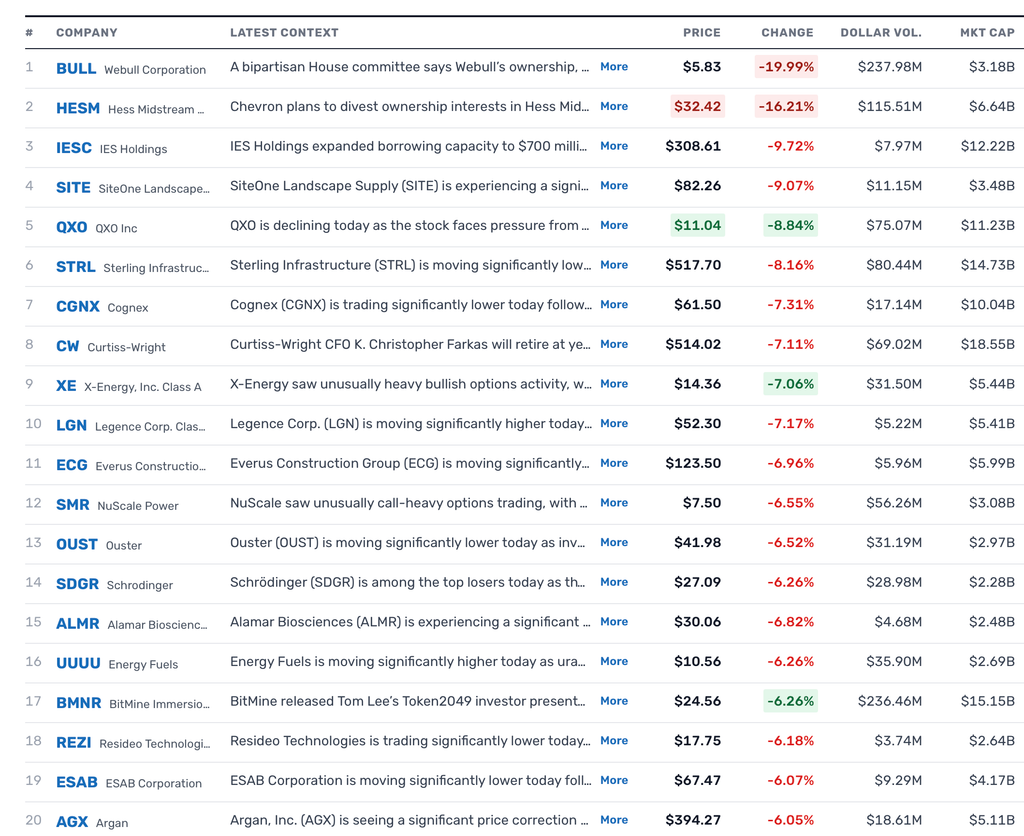
SOURCE TheFly
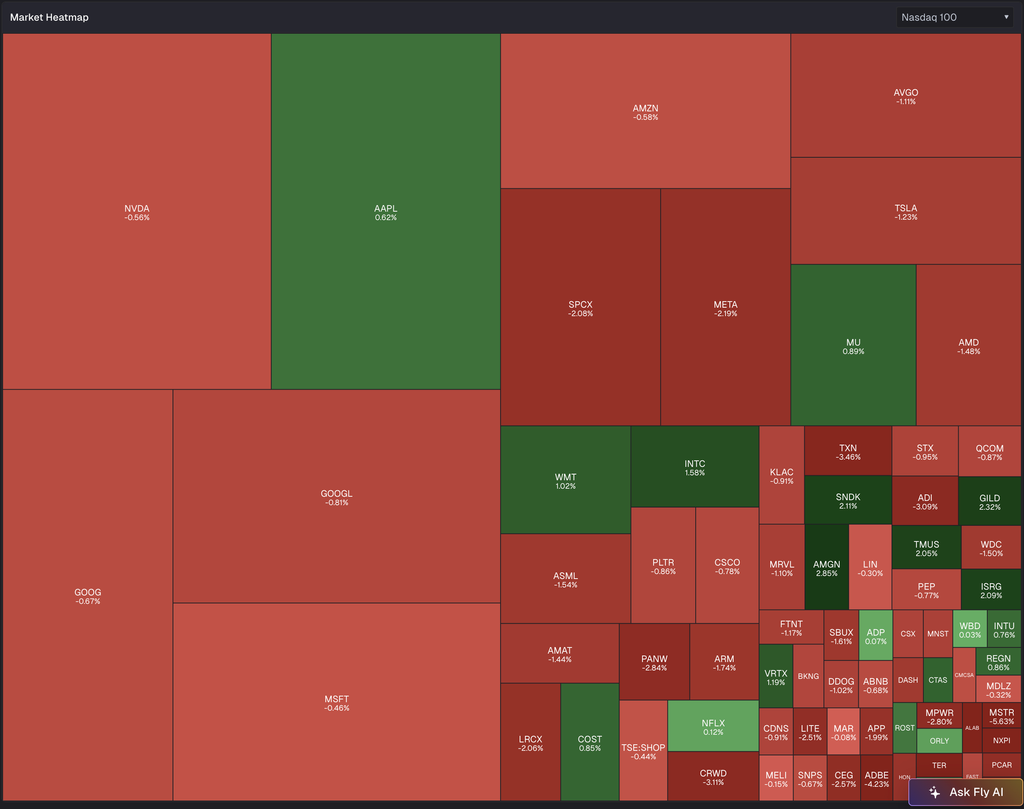
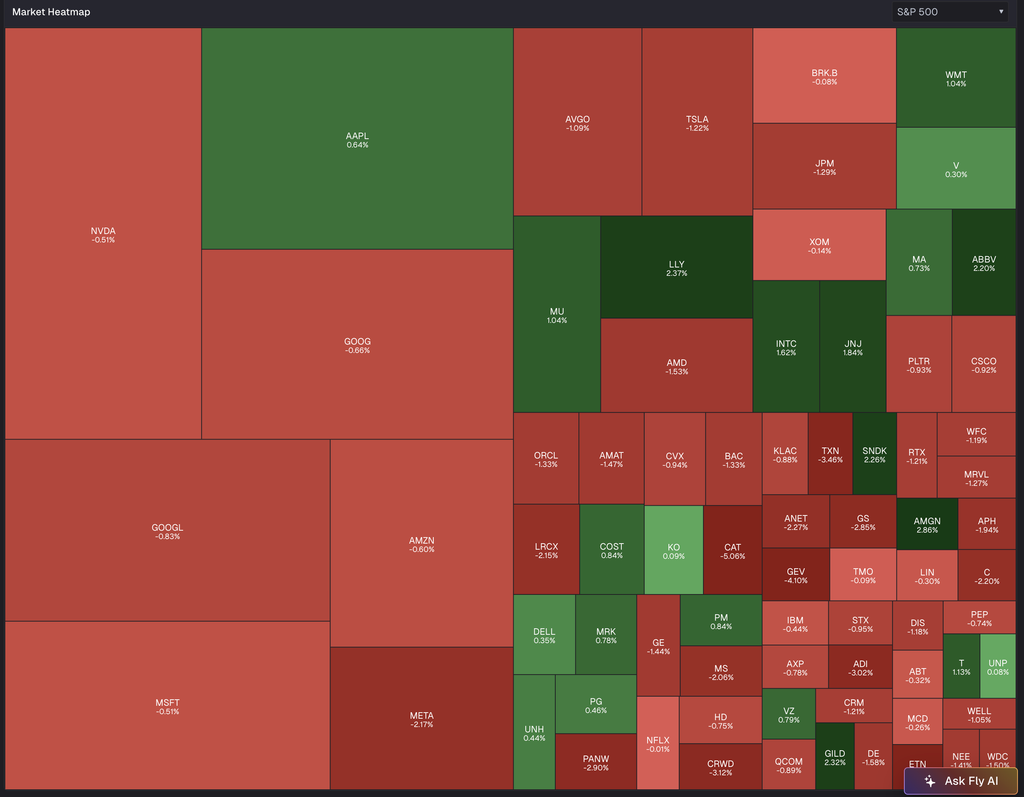
BY Doug Kass · Oct 7, 2026, 11:14 AM EDT
I moved from medium- to small-sized just now on the indexes:
*SPY $774.44
* QQQ $752.28
Positions: Short SPY s QQQ s
BY Doug Kass · Oct 7, 2026, 10:24 AM EDT
BY Doug Kass · Oct 7, 2026, 9:55 AM EDT
I have covered no shorts today!
Positions: None
BY Doug Kass · Oct 7, 2026, 9:44 AM EDT
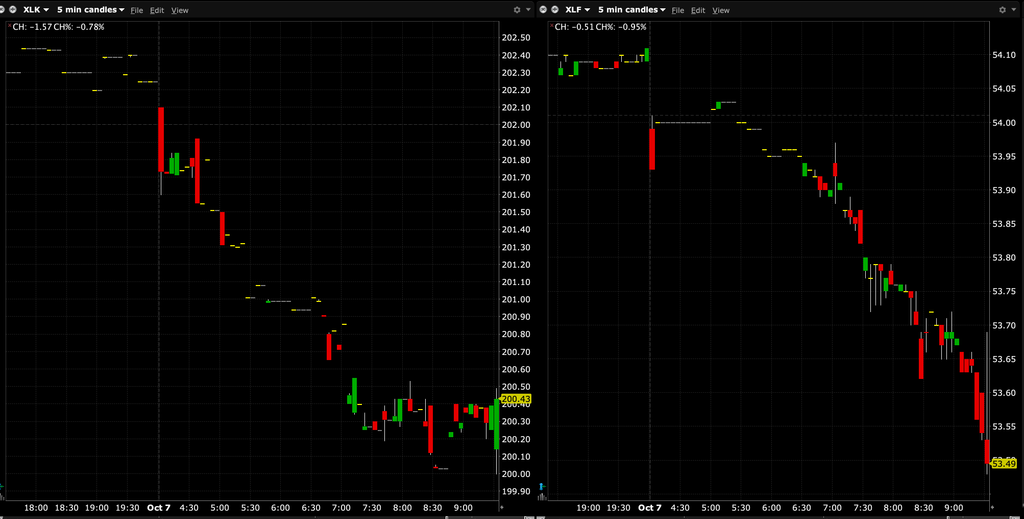
Chart, which is from Interactive Brokers, is from 9:34 a.m. ET:
BY Doug Kass · Oct 7, 2026, 9:42 AM EDT
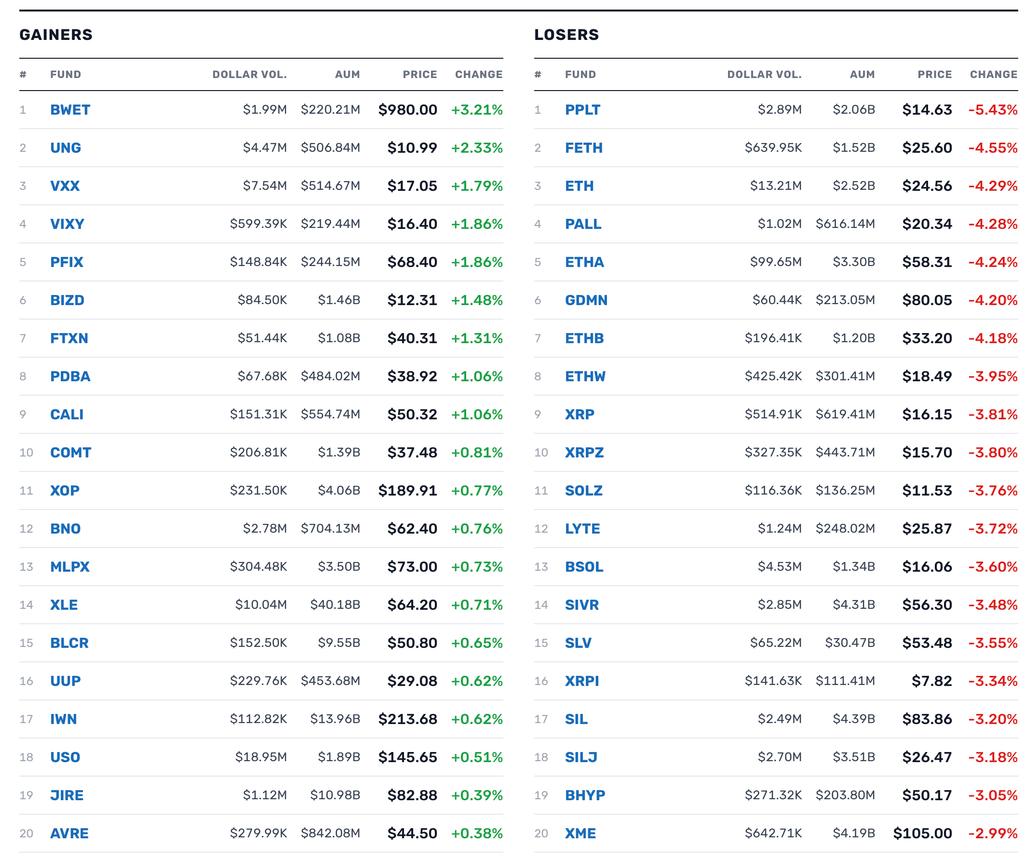
Source: TheStreet Pro
BY Doug Kass · Oct 7, 2026, 9:20 AM EDT
Source: TipRanks
BY Doug Kass · Oct 7, 2026, 9:10 AM EDT
Source: TipRanks
BY Doug Kass · Oct 7, 2026, 9:03 AM EDT
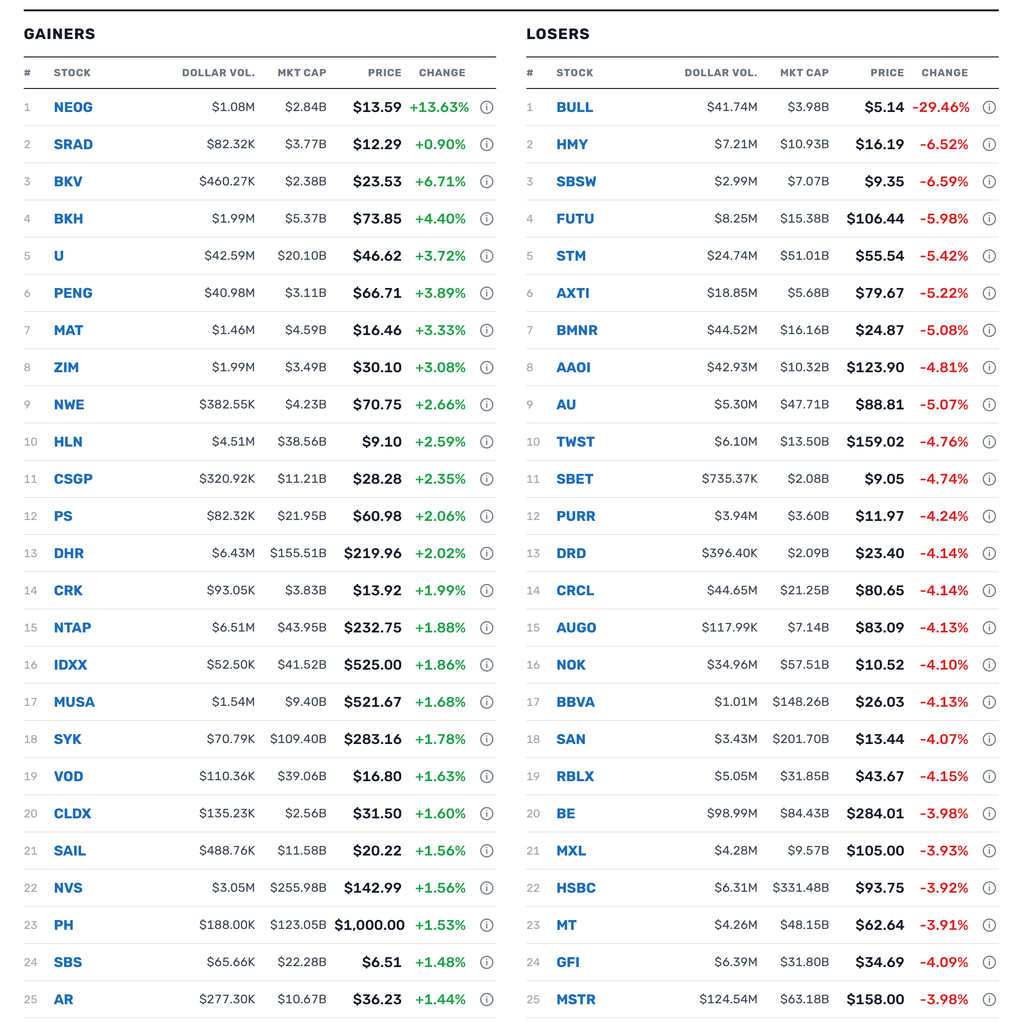
– LPCN +40% (Health Canada approves TLANDO for testosterone replacement therapy)
– APUS +9.4% (extends a high-volume rally tied to the BlockAssure agreement to build and operate the AssureChain insurance network)
– PENG +4.3% (Q4 beat and FY27 sales and EPS outlook topped prior guidance and Street expectations on accelerating AI-infrastructure demand)
– CNQ +1.6%, APA +1.2%, OXY +1.0%, COP +1.0% (oil producers rise as crude climbs back above $100 a barrel)
– CRBU -42% (launches a strategic-alternatives review, discontinues two allogeneic CAR-T programs and plans substantial workforce reductions)
– BULL -30% (bipartisan House panel report says structural China ties pose national-security and US-user-data risks)
– STM -5.4%, TER -3.0%, ASML -3.0%, AMAT -2.7%, LRCX -3.0%, MU -2.8% (chip stocks fall in the risk-off technology tape as oil-driven inflation concerns pressure rate-sensitive growth shares)
– BMNR -5.0%, CRCL -4.0%, MSTR -3.8%, COIN -3.1%, HOOD -3.0% (crypto-linked stocks fall as digital-asset prices weaken)
– AAOI -4.8%, CIEN -3.8%, MTSI -3.0%, COHR -3.2%, GLW -3.3% (AI-networking and optical winners pull back after sharp recent rallies as technology exposure is reduced)
– DB -4.7%, SAN -4.2%, HSBC -3.9%, NWG -3.5%, BCS -3.3% (European-bank ADRs fall as oil-driven inflation and sovereign-bond stress deepen fiscal concerns, with UK lenders also facing budget-tax fears)
– STZ -3.9% (quarter beat, but adjusted FY guidance was merely reiterated and beer depletions declined)
– BE -3.8%, CEG -3.5%, EME -1.9% (AI-power and data-center infrastructure winners give back part of recent gains amid the broader risk-off rotation)
BY Doug Kass · Oct 7, 2026, 8:59 AM EDT
The IRS proclamation that they will looking at 280E guidelines (earlier this week) and the DEA info below seem to be concrete signposts that rescheduling of adult-use cannabis is very likely over the near term:
I added to MSOS, GLAS and GTBIF yesterday.
Positions: MSOS common VL calls S GLAS S GTBIF S
BY Doug Kass · Oct 7, 2026, 8:35 AM EDT
* As we treat it as a “trading sardine”… and not as a foundational long
I treat all commodities and commodity-related equities as “trading sardines.”
While I view gold as a prime beneficiary of the profilgate spending in Washington, D.C. (and continued currency debasement) – I still see precious metals as a trade and not (yet) as a foundational position, particularly with interest rates on the ascent.
We traded in and out (profitably) three times in GLD over the last 45 days or so – buying weakness and selling strength.
This morning is GLD is down by almost five beaners as the US dollar advances higher and rates resume their rise:
Positions: None
BY Doug Kass · Oct 7, 2026, 8:20 AM EDT
Positions: None.
BY Doug Kass · Oct 7, 2026, 8:05 AM EDT
* And second level thinking…
Positions: None.
BY Doug Kass · Oct 7, 2026, 7:55 AM EDT
I am clueless and not an authority about the price of bitcoin but this drop (last night) was abrupt:
I have been adding to my @GRNY short – which has a lot of crypto exposure.
Positions: Short GRNY M
BY Doug Kass · Oct 7, 2026, 7:45 AM EDT
In my consumer is spent up and not pent up series I have discussed the impending weakness in the consumer — sticky and cumulative inflation (since 2020), a five month decline in real wages, a drawdown in the savings rate and the weakness in housing prices.
Should energy prices continue their ascent I am fearful of an abrupt drop in personal consumption.
Moreover, the price of oil is likely to be a meaningful political issue in the mid terms.
Positions: None.
BY Doug Kass · Oct 7, 2026, 7:35 AM EDT
I have been recently highlighting the deterioration in market breadth.
The stench of bad breadth was conspicuous yesterday:
For now, the S&P and the Nasdaq don’t care that the Russell isn’t crowing.
My guess/bet is that this is not a permanent condition.
Position: Short SPY (M), QQQ (M)
BY Doug Kass · Oct 7, 2026, 7:25 AM EDT
The rise in interest rates is a global phenomenon which few are focused on.
Again, today, rates are on the rise:
Many in the Comments section are asking about buying Treasuries now.
However, given the stickiness of inflation, the continued mad rush of the AI spend, a sovereign retreat away from our Treasuries from non-U.S. nations (for political and non-political reasons), the (still) lack of fiscal discipline in Washington D.C. and the massive supply of Treasury and (AI) related corporate offerings, I am not there yet, even as the real interest rate expands.
Stay tuned on this…
Position: None
BY Doug Kass · Oct 7, 2026, 7:10 AM EDT
* Not necessarily…
“If you build it, he will come.”
– Ray Kinsella, Field of Dreams
If You Build It, He Will Come – Field of Dreams (1/9) Movie CLIP (1989) HD – YouTube
Position: None
BY Doug Kass · Oct 7, 2026, 7:00 AM EDT
* I continue to be short in a bull market…
Once again, I thought underneath the hood there was less than meet’s the eye.
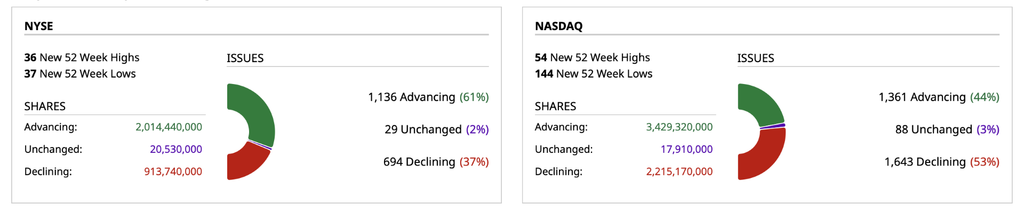
Though the averages showed a robust gain, Nasdaq breadth was negative:
And, Nvidia (NVDA), which was +$5 per share on the day at its high, basically closed flat.
Treasuries were modestly higher but it looked more like a dead-cat bounce than a reversal to lower yields. This morning TLT is -$0.40, so Tuesday’s slightly lower bond yields have been reversed.
“Forward thinking” financials continued to show no spark.
Finally, despite the record high in the indices, there were twice as many lows as highs on the NYSE:
We moved from small to medium-sized short the indices on yesterday’s market advance.
Position: Short SPY (M), QQQ (M)
BY Doug Kass · Oct 7, 2026, 6:45 AM EDT
Position: None
BY Doug Kass · Oct 7, 2026, 6:35 AM EDT
Wolf Street howls about the drop in home listing prices.
Position: None
BY Doug Kass · Oct 7, 2026, 6:25 AM EDT
I am in route to NYC to take a family member to have a checkup after surgery.
I will be operating on a laptop today so my posts will be shorter and less frequent.
Position: None
BY Doug Kass · Oct 7, 2026, 6:10 AM EDT
* And higher yields…
And this:
Meanwhile, the equity risk premium deteriorates further — lending a further argument to lower forward market returns.
Position: None
BY Doug Kass · Oct 7, 2026, 6:00 AM EDT
The S&P Short Range Oscillator remains in a (less) oversold state at -3.86% vs. -4.56%.
I am medium short SPY currently.
Position: Short SPY (M)
BY Doug Kass · Oct 7, 2026, 5:54 AM EDT
Diesel futures jumping 16 cents

The conundrum.🚨 A historic, systemic divergence is taking place right before our eyes. As shown in the chart below, the Nasdaq continues to push upward in complete isolation, while the broader engine of the economy the Russell 2000, Dow Jones, Dow Transportation, and the Show more

BREAKING: Bitcoin falls nearly -$2,000 in 20 minutes as $400 million worth of levered longs are liquidated in under one hour.

US Equity Supply Is Back: Net Issuance Turns Positive After 20 Years The 20-year shrinkage of US public equity supply is over. Net issuance: +$45bn in Q1, +$152bn in Q2, the largest quarter ever. Anthropic ($100bn), SB Energy ($50bn) and Inspire Brands ($20bn) are still to come. Show more

U.S. 10-Year Yield ripping again 📈 📈

🇺🇸 Hyperscalers Cloud revenue growth at the hyperscalers hit 48% in Q2. Goldman Sachs equity analysts forecast 55% in Q3. It's an encouraging sign, but not proof that the AI spending boom will pay off 👉 isabelnet.com/blog/ h/t @dailychartbook #AI $spx #spx

$DXY The Dollar Index is higher again this morning at 102.303 +0.45%. It continues at levels not seen since the middle of April, 2026.

Japan is dumping US treasuries hard again

More new 52-week highs vs. lows at an ATH cannot be made into a positive. No matter how much lipstick you put on that pig, it is still a pig.

Over on the Nasdaq new 52-week highs vs. lows improved to -5 from -187. So while that makes it the 27th straight session that the Nasdaq saw more new 52-week lows than new highs, we’re the closest we’ve been to positive territory in a month.

Corporate Profits now account for more than 12% of GDP, the most in history 🚨

S&P 500 $SPY closed at a record high. With twice as many lows as highs on the NYSE. Here's every date the S&P closed at a record and the NYSE low/high ratio was > 2: 6/22/29...2.1 12/3/99...2.0 12/21/99...4.2 12/22/99...4.1 12/23/99...2.3 12/29/99...2.4 10/6/26...2.6


