Exiting Nvidia, Pivoting to This AI Competitor With Upside
The stock appears to face a bullish reversal after a sector drawdown.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Readers already know that I had jettisoned Nvidia (NVDA) from the Sarge-folio. I sold the last few shares on Wednesday night. Readers have known for several days that I have proclaimed Advanced Micro Devices (AMD) the new “AI king” as I believe that Nvidia may be poison for a while. Yes, even with Huang Jensen out, especially if the firm ends up facing huge penalties should national security issues be uncovered by the now multiple ongoing investigations.
Readers also know that I had, outside of AMD and Taiwan Semiconductor (TSM), over the past month, gone flat on all of the other chip names that I had been in. Even with what is an oversized long position in AMD, I am actually underexposed to semiconductors. Not anymore. I used Thursday morning’s pre-opening weakness to initiate Marvell Technology (MRVL) to the Sarge-folio. It’s been a while since this one has been on my book.
Marvell is a real player in the AI chip and infrastructure space, maybe more on the custom silicon side and as high-speed connectivity specialist than a pure-play general-purpose designer like Nvidia or AMD, but a player.
The Guts…
Marvell designs custom AI accelerators as well as “XPU-attach” chips for all four major hyperscalers. These chips are used to aid in networking, storage and inference. The company has expanded existing partnerships, with Alphabet (GOOGL) tied to its TPU ecosystem, and with Amazon (AMZN) on its Trainium program.
The firm’s Core design strengths are in ethernet switch silicon, PAM4 (doubling data capacity), coherent optical DSPs, and data-center interconnect modules. These are critical for scaling AI clusters. Data center-related products now account for roughly three-quarters of Marvell’s revenue generation and is the firm’s main driver of growth.
The Deal
Almost two weeks ago, Marvell announced that the firm would acquire optical and laser components maker Lumentum Holdings (LITE) in an all-stock transaction then valued at an implied enterprise value of $115 billion. While there is always a risk of this deal failing to be completed, what interest me and certainly interested Marvell is this:
Lumentum has become a key supplier to data centers. Large AI clusters require optical connectivity for scale-out and scale-up links due to bandwidth, power and distance limits. Lasers, high-speed modules and optical switching are a step towards addressing these needs. Lumentum experienced sales growth of 136% for its most recently reported quarter and is projecting sales growth of about 140% for the current quarter.
Earnings
Marvell is not expected to report for another three weeks or so. Wall Street is looking for an adjusted $1.10 per share on sales of $3.16 billion. That would compare very well to the $0.76 posted for the year-ago period while reflecting annual revenue growth of better than 52%. Of the 32 sell-side analysts that I know to cover MRVL, 27 have increased their earnings estimates since the start of that quarter, while just one has revised his estimate lower. Wall Street seems to be optimistic.
The Chart
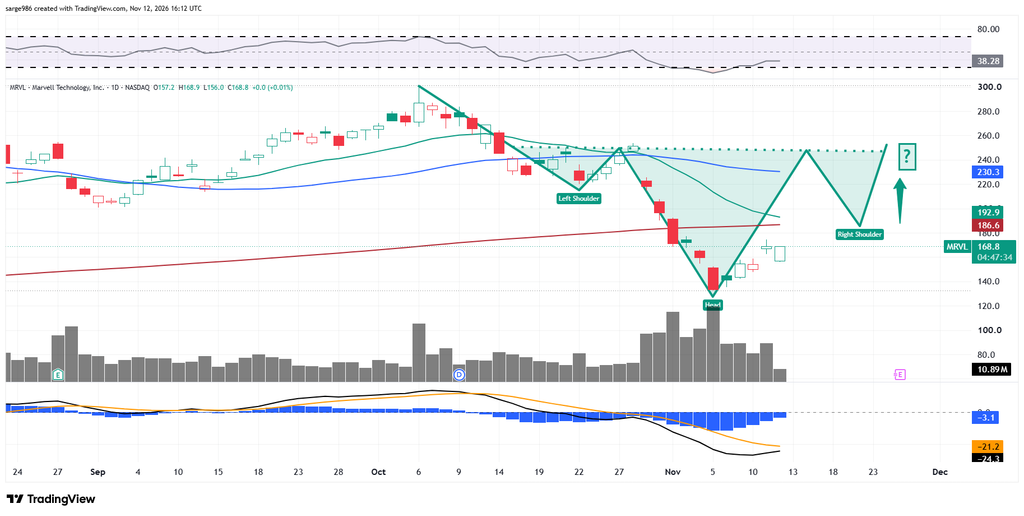
Readers will see that after the recent deep drawdown in the share price of MRVL, that the stock has now developed more than two-thirds of what could end up looking like an inverse head-and-shoulders pattern of bullish reversal with what could be a pivot close to $245. For now, the pivot is the 200-daySMA at $168. That would get the prose back on board. That also allows us with a still bearish (but improving) daily MACD to set a realistic target price of $230, which is currently where the stock runs into its 50-day SMA.
At the time of publication, Guilfoyle was long AMD, TSM, MRVL and AMZN equity.