After Ondas Reports Beat, Let’s See If It’s a Buy
Here’s my plan after $10K Portfolio holding Ondas posts Q3 earnings this morning.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
Portfolio holding Ondas (ONDS) posted fiscal third-quarter financial results, revealing an unadjusted loss per share of $0.10 on revenue of $167.489 million – top- and bottom-line results that beat Wall Street’s consensus view. The sales print was good for growth of 1,558% annually and growth of 99.9% sequentially.
That kind of growth was largely due to acquisitions. On a pro forma organic basis, assuming the current portfolio of business was owned throughout both periods, Q3 2026 revenue increased 64% year-over-year. The firm ended Q3 with $835 million in backlogged orders.
The CEO
“Our businesses are gaining access to larger customers, broader channels, and stronger production and field-support capabilities, allowing mission-ready technologies to move more quickly from evaluation into deployment,” said Ondas Chair and CEO Eric Brock in the release. “The next phase is about disciplined execution: delivering on customer commitments, integrating our capabilities, and converting demand to sustainable growth and improving profitability.”
Brock went on: “Our differentiation increasingly comes from combining autonomous systems, mission software, AI, and critical components into solutions that can be deployed and supported across multiple domains. Ondas Sentinel strengthens our ability to pursue and execute complex U.S. defense programs, while Regna AI extends our sovereign AI capabilities and creates opportunities to serve customers beyond our own hardware platforms.”
Finally, in closing, Brock wrote, “We expect a strong finish to 2026, with momentum accelerating in the fourth quarter as volume deliveries ramp across existing programs and we convert pipeline opportunities into customer programs. Our order book remains healthy, our pipeline continues to expand, and our ability to produce, deliver, and sustain solutions for customers continues to strengthen.”
Operations
Readers must understand that Ondas has grown the business through acquisitions this year to the point that these numbers are not truly comparable to the year-ago period. The business was very small at that time. As revenue grew like a weed to $167.489 million, the cost of that revenue grew wildly also, to $130.989 million, leaving gross profit of $36.5 million on a gross margin of 21.8%. Operating expenses printed at $226.006 million, leaving a GAAP operating loss of $189.506 million.
After accounting for interest and other income & expenses, as well as taxes, unadjusted net loss attributable to shareholders landed at -$62.567 million. That works out to an unadjusted loss per share of $0.10, fully diluted, down from the year ago comparison, as if it matters, of -$0.03.
Guidance
Ondas now expects its recent momentum to continue and is now targeting at least $550 million in revenue for the full year. This is up from prior guidance for $525 million to $550 million. That’s also a lot better than the $537 million that Wall Street had in mind. For the current quarter, the company is targeting revenue of more than $250 million. Wall Street was looking for $254 million, so this guidance is a beat with a potential miss mixed in. Most interestingly, the firm is issuing a revenue target of $1.1 billion for 2027. That could be good for growth of 100% and is far better than the $1.01 billion consensus.
Additionally, Ondas continues to project adjusted EBITDA profitability in Q4 2026 at the operating platform level, which includes OAS and Ondas Sentinel. Ondas also expects company-wide adjusted earnings before interest, taxes, depreciation, and amortization profitability by Q3 2027. This would be one quarter earlier than previously issued guidance.
Balance Sheet
Ondas ended the quarter with a cash position of $820.336 million and inventories of $110.719 million. That left current assets at $1.297 billion. Current liabilities add up to $382.652 million, including short-term debt of just $909,000, but deferred revenue of $37.822 million. That puts the company’s current and quick ratios at a headline 3.39 and 3.09 respectively. That’s quite solid. Adjusted for deferred revenues, those ratios rise to 3.76 and 3.44. Ondas will have no problem meeting the firm’s short to medium-term obligations.
Total assets amount to $4.028 billion, of which 62.7% is labeled as either goodwill or other intangibles. I can’t say that I am thrilled about that. Total liabilities less equity comes to $1.657 billion. The company has long-term debt and warrant liabilities totaling $924.73 million. That’s a lot, but it’s almost all in the warrant liabilities. This balance sheet is moderately complicated, but it is in good shape.
My Take and the Chart
The stock is trading lower after this release, but I don’t find it all that discouraging. The company sees adjusted EBITDA profitability in the near-term. Sales are exploding. The guidance is better than I expected. The balance sheet is solid. The firm is sitting on a lot of cash. Oh, and there’s still a huge short position that comes to 42.5% of the float.
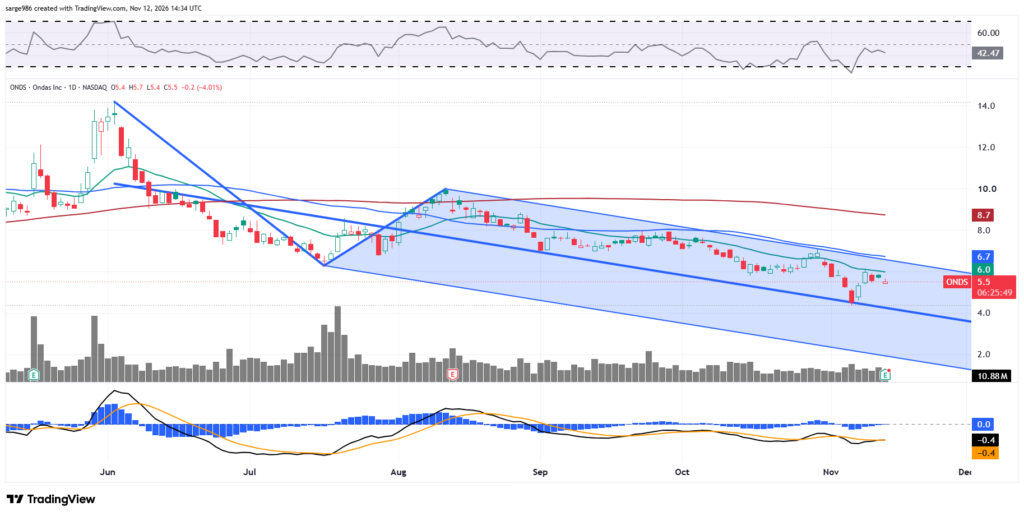
Readers will see that for ONDS, the May into the present selloff fits nicely within the confines of the upper chamber of a Schiff Pitchfork model. Notice that the 50-day simple moving average is running concurrently with the upper trendline of that model. That is our pivot. Taking and holding that line could also attract professional investment. Relative Strength is close to neutral. The daily moving average convergence divergence is still postured bearishly, but not nearly as negatively as it was earlier in November. The portfolio is reducing its target price from a now unrealistic $12 to $10.
Wednesday’s Intentions Vs. Actual Trades
– Purchase 25 shares of EVLV at or close to the last sale of $4.56.
– Bought 30 shares of EVLV at $4.451. (Overbought 5 shares in error)
Thursday’s Intentions
– Purchase 20 shares of ONDS at or close to the last sale of $5.38.
Current Positions
Long 80 shares of ASPN at $5.0263. Target Price: $8. Last sale: $6.32.
Long 80 shares of EVLV at $5.0061. Target Price: $7.50. Last sale: $4.48.
Long 200 shares of OCUL at $7.7263. Target Price: $10. Last sale: $6.52.
Long 330 shares of ONDS at $7.5402. Target Price: $10. Last sale: $5.38.
Long 100 shares of PTON at $5.2708. Target Price: $9. Last sale: $5.64.
Long 20 shares of RKLB at $50.942. Target Price $84. Last sale: $65.44.
Long 150 shares of SOFI at $15.947. Target Price: $24. Last sale: $16.01.
Cash: $331.78.
Portfolio Value: $8,837.34, -11.6% from inception on March 24.
At the time of publication, Guilfoyle was long ASPN, EVLV, OCUL, ONDS, PTON, RKLB, SOFI.