Is Tech Ready to Rebound?
The question coming out of last week is whether the AI selloff has run its course, and those I follow the most are split. This morning’s Nvidia headline though provides a real-time test.
Over the weekend, Jensen Huang acknowledged an affair with a woman reported to be a suspected Chinese intelligence operative, and Nvidia’s board opened an independent investigation. Nvidia (NVDA), already down 22% from its October high, is down another 6% in the premarket.
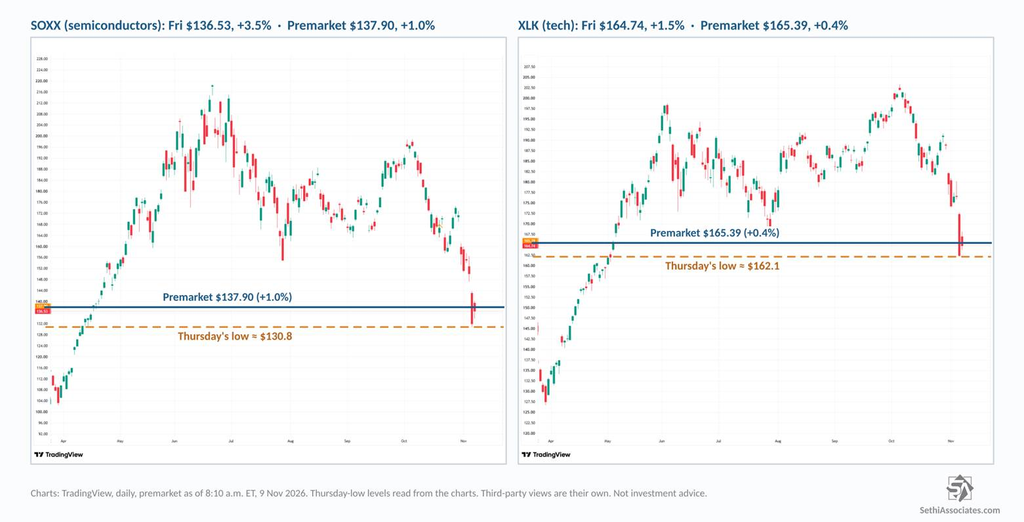
But the groups that took the brunt of last week’s selling aren’t following it lower. The iShares Semiconductor ETF (SOXX) is up over 1.0% premarket and the Technology Select Sector SPDR ETF (XLK) 0.5%, building on Friday’s bounce (SOXX +3.5%, XLK +1.5%). Semis rising while the sector’s bellwether drops 7% is the kind of divergence you’d want to see if positioning has truly been cleaned out. The line in the sand is Thursday’s low: about $131 on SOXX and $162 on XLK.
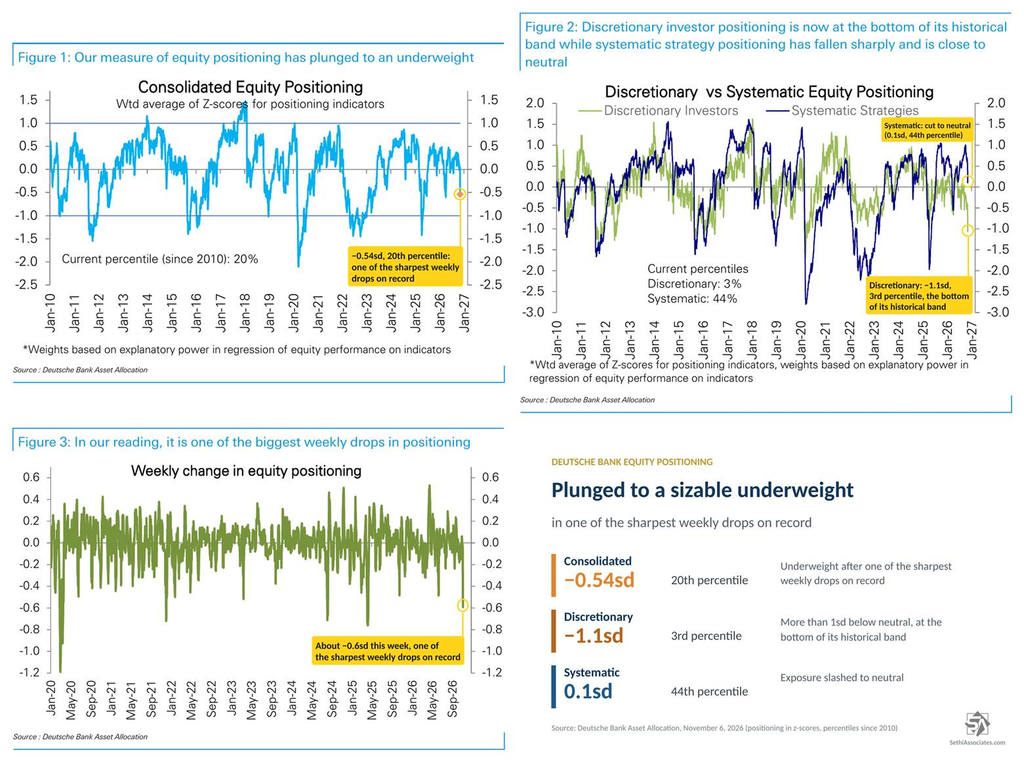
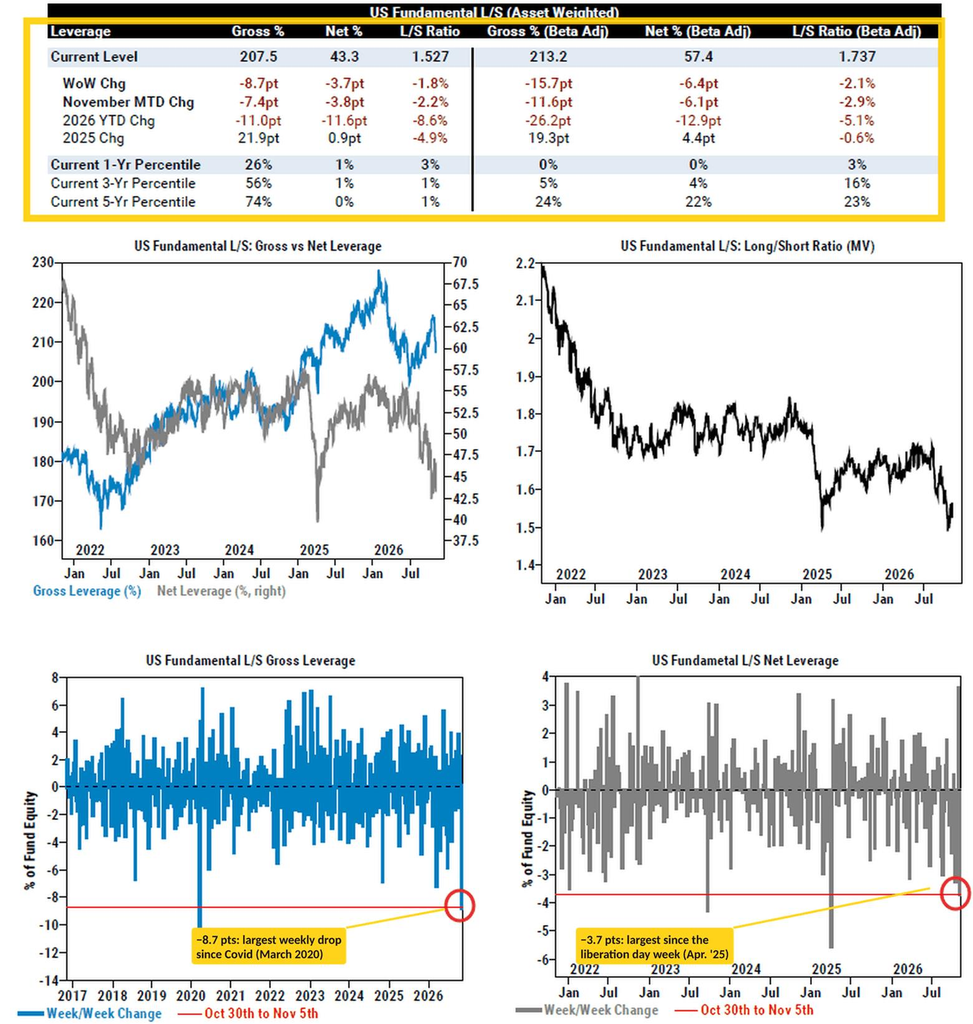
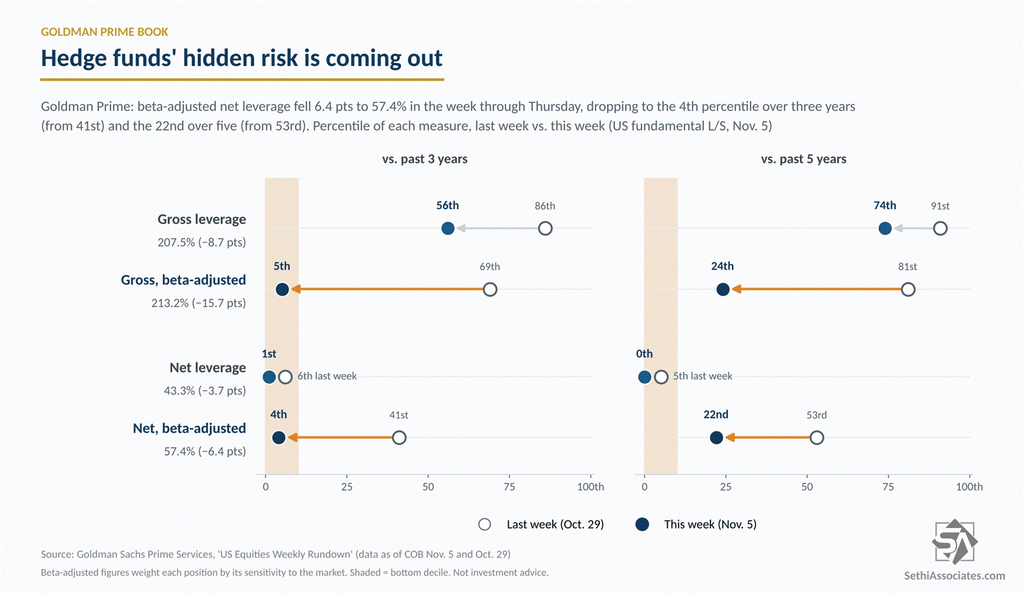
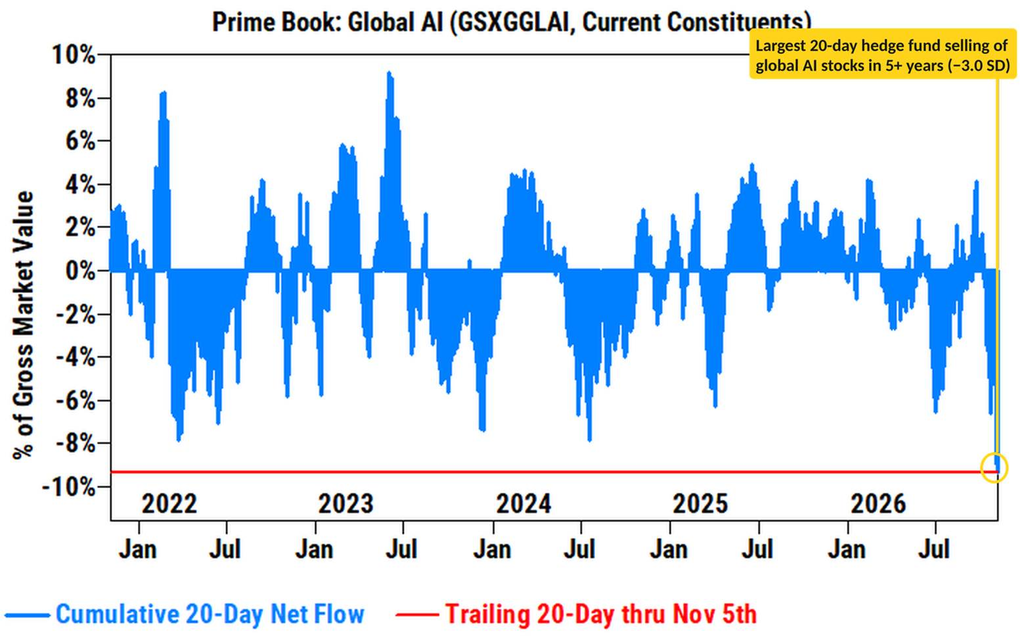
Among the strategists I covered in Sunday’s Week Ahead (The Week Ahead – CPI and Equity Flows Test a Shaken Market), Deutsche Bank doubled down on its Tech overweight on Friday, saying “with the plunge this week, the risk-reward is now even more favorable,” and that the selloff was “largely driven by a forced positioning unwind” rather than the election.
Citadel’s Scott Rubner has also turned more positive, seeing “a compelling setup for US equities into year-end,” while Ed Yardeni says Thursday’s selloff delivered the post-midterm buying opportunities he expected, though he isn’t calling a bottom yet.
Not all are on board, though. Helene Meisler thinks “we should get a short-term rally” (Nasdaq and the Sentiment Cycle: Where Are We Right Now?), but notes, “I think we’re only talking about an oversold rally at this point. But it ought to be tradable” (A Market Washout May Be Setting Up the Next Tradable Rally). And on Friday, HSBC’s Max Kettner said he wasn’t ready to step in yet.
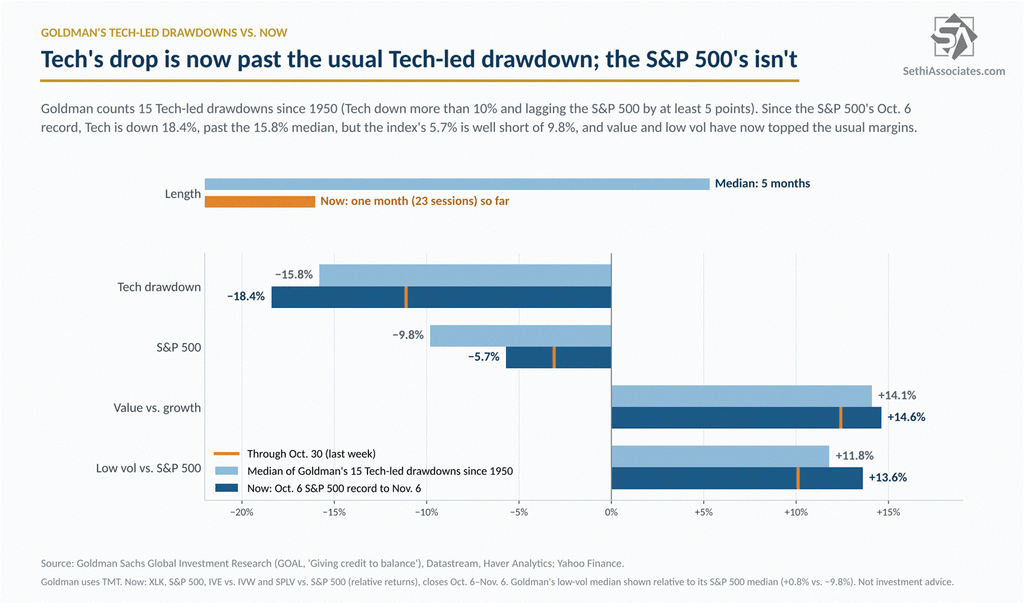
One thing keeping some on the fence is the duration of the selloff. In depth, this rotation out of Tech is already in line with, or past, prior ones. On my update of DB’s table from two Sundays ago, mega-cap growth and Tech have trailed the rest of the S&P 500 by about 20 points since October 7th, more than any of the four prior rotations in the past 2½ years. And on Goldman’s framework, Tech’s 18.4% drop from the S&P 500’s October 6 record is past the 15.8% median for Tech-led drawdowns since 1950.
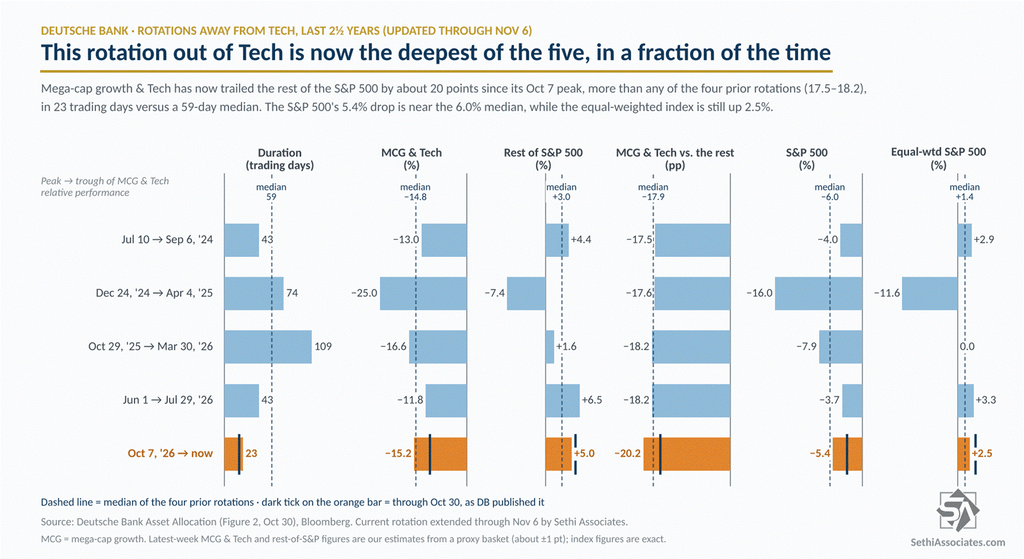
But it’s taken just 23 trading days, versus a 59-day median in DB’s table, and Goldman’s median Tech-led drawdown lasted about five months, with the S&P 500 falling 9.8% versus 5.7% so far this time.
As Goldman noted after its panic indicator spiked, “the immediate path has been much less reliable, particularly while still in price discovery mode.”
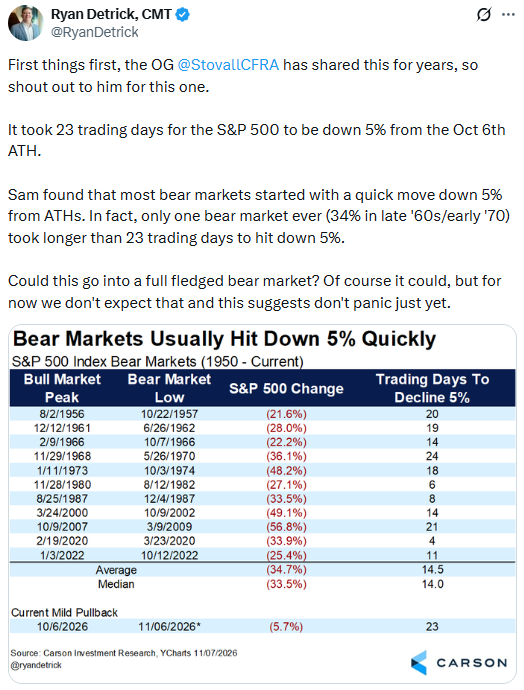
And the bears will point out that sharp down moves are characteristic of bear markets. Carson Group’s Ryan Detrick, crediting CFRA’s Sam Stovall, notes in the post below that “only one bear market ever (34% in late ’60s/early ‘70) took longer than 23 trading days to hit down 5%,” and this one took exactly 23. Detrick himself doesn’t expect a bear market, saying “this suggests don’t panic just yet,” and 23 days is at the slow end of that range (the median is 14), but it isn’t outside it.
So while today’s early action is encouraging, I’m a long way from declaring the coast is clear.
There’s a lot more on this subject in Sunday’s The Week Ahead – CPI and Equity Flows Test a Shaken Market.
Conversation 0 Comments
One ongoing discussion across all days. Everyone can read; sign in to take part.
Your voice matters. Discussions are moderated for civility. Read our guidelines .
Log in to join the conversation