Stock Market Today

Market updates and conversation from TheStreet Pro team. Follow the latest and join the conversation below.

Stock Market Today: October 29, 2026

Newest first · All times Eastern · 2 updates

DATE:
By Neil Sethi

Q3 GDP Trackers Cluster Near 3.3%, but GDPNow’s History Says Watch for an Upside Miss

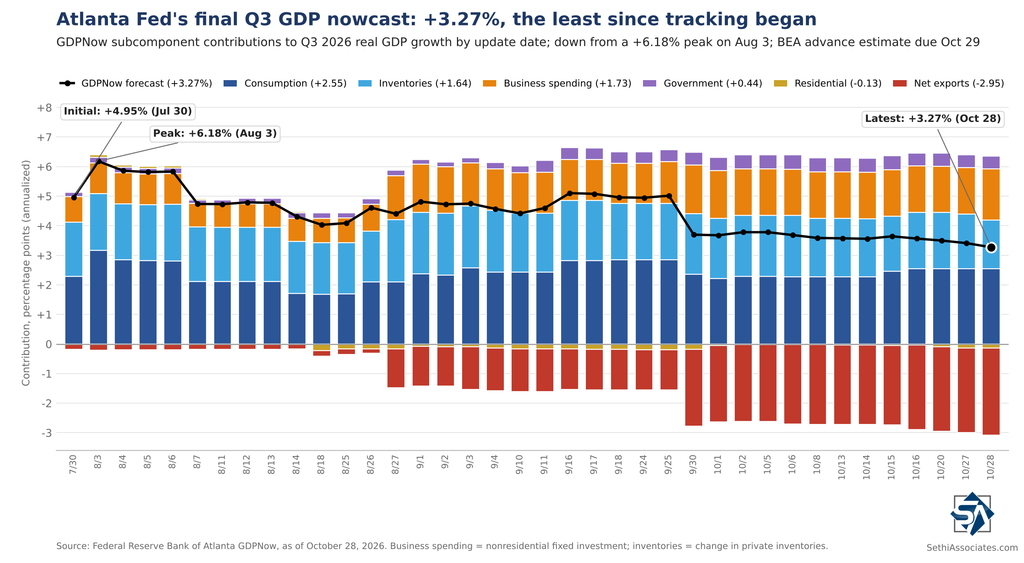
Ahead of Q3 GDP later this morning the Atlanta Fed’s GDPNow final Q3 nowcast came in at 3.27% Wednesday, the least since it initiated tracking for the quarter, down from its 6.18% peak on August 3.
Over the past two years, GDPNow’s last reading before the advance GDP report has been either very close or well off, with little in between. It was within a tenth in four of the last eight quarters (Q3 and Q4 2024, Q2 2025 and Q2 2026) and off by 0.75 percentage point or more in the other four.

Over its history since 2014 (excluding 2020), GDPNow’s average miss has been 0.59 point. It has been within half a point half the time and within a point 84% of the time.
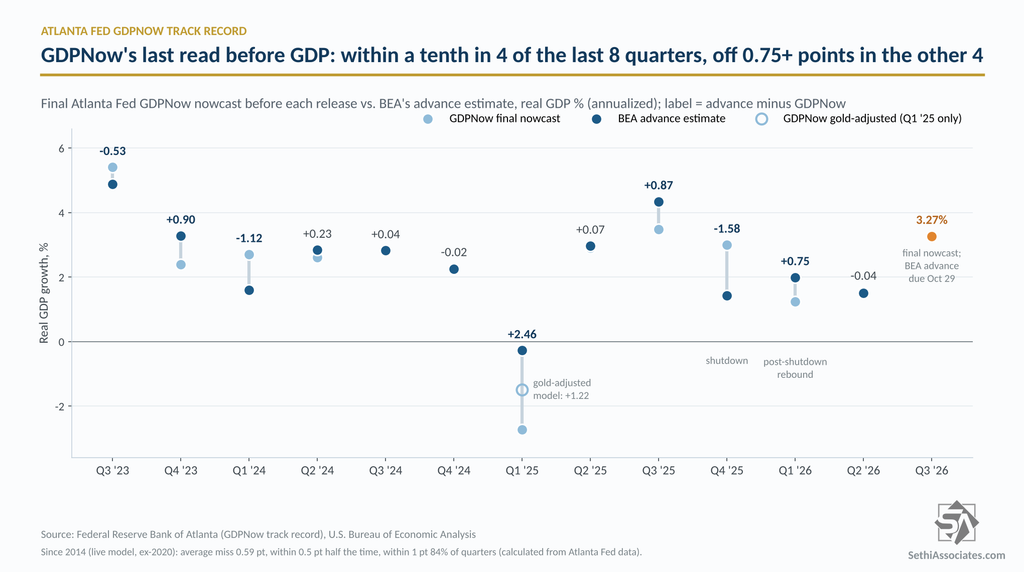
But a couple of unique historical tendencies are worth keeping in mind:

▪ GDPNow’s final reading usually falls from where it stood a month before the release (34 of 56 quarters excluding 2020). That’s what we saw in Q1 and Q2, and now Q3, down 1.75 points from 5.02% on September 25. But when it has fallen more than half a point in that final month, the actual print has come in above its final reading in 16 of 22 quarters.

▪ In third quarters specifically, the advance print has come in above GDPNow’s final reading in 10 of 14 quarters (excluding 2020), by an average of 0.31 point.

Here’s GDPNow’s final breakdown of the components as of October 28 and changes from my last update October 20:

Consumption = +2.55% (0.00%)

Business spending (nonresidential fixed investment) = +1.73% (+0.16%)

Inventories = +1.64% (−0.21%)

Government = +0.44% (0.00%)

Residential investment = −0.13% (−0.03%)

Net exports = −2.95% (−0.09%)

GDPNow Forecast: +3.27% (−0.23%)

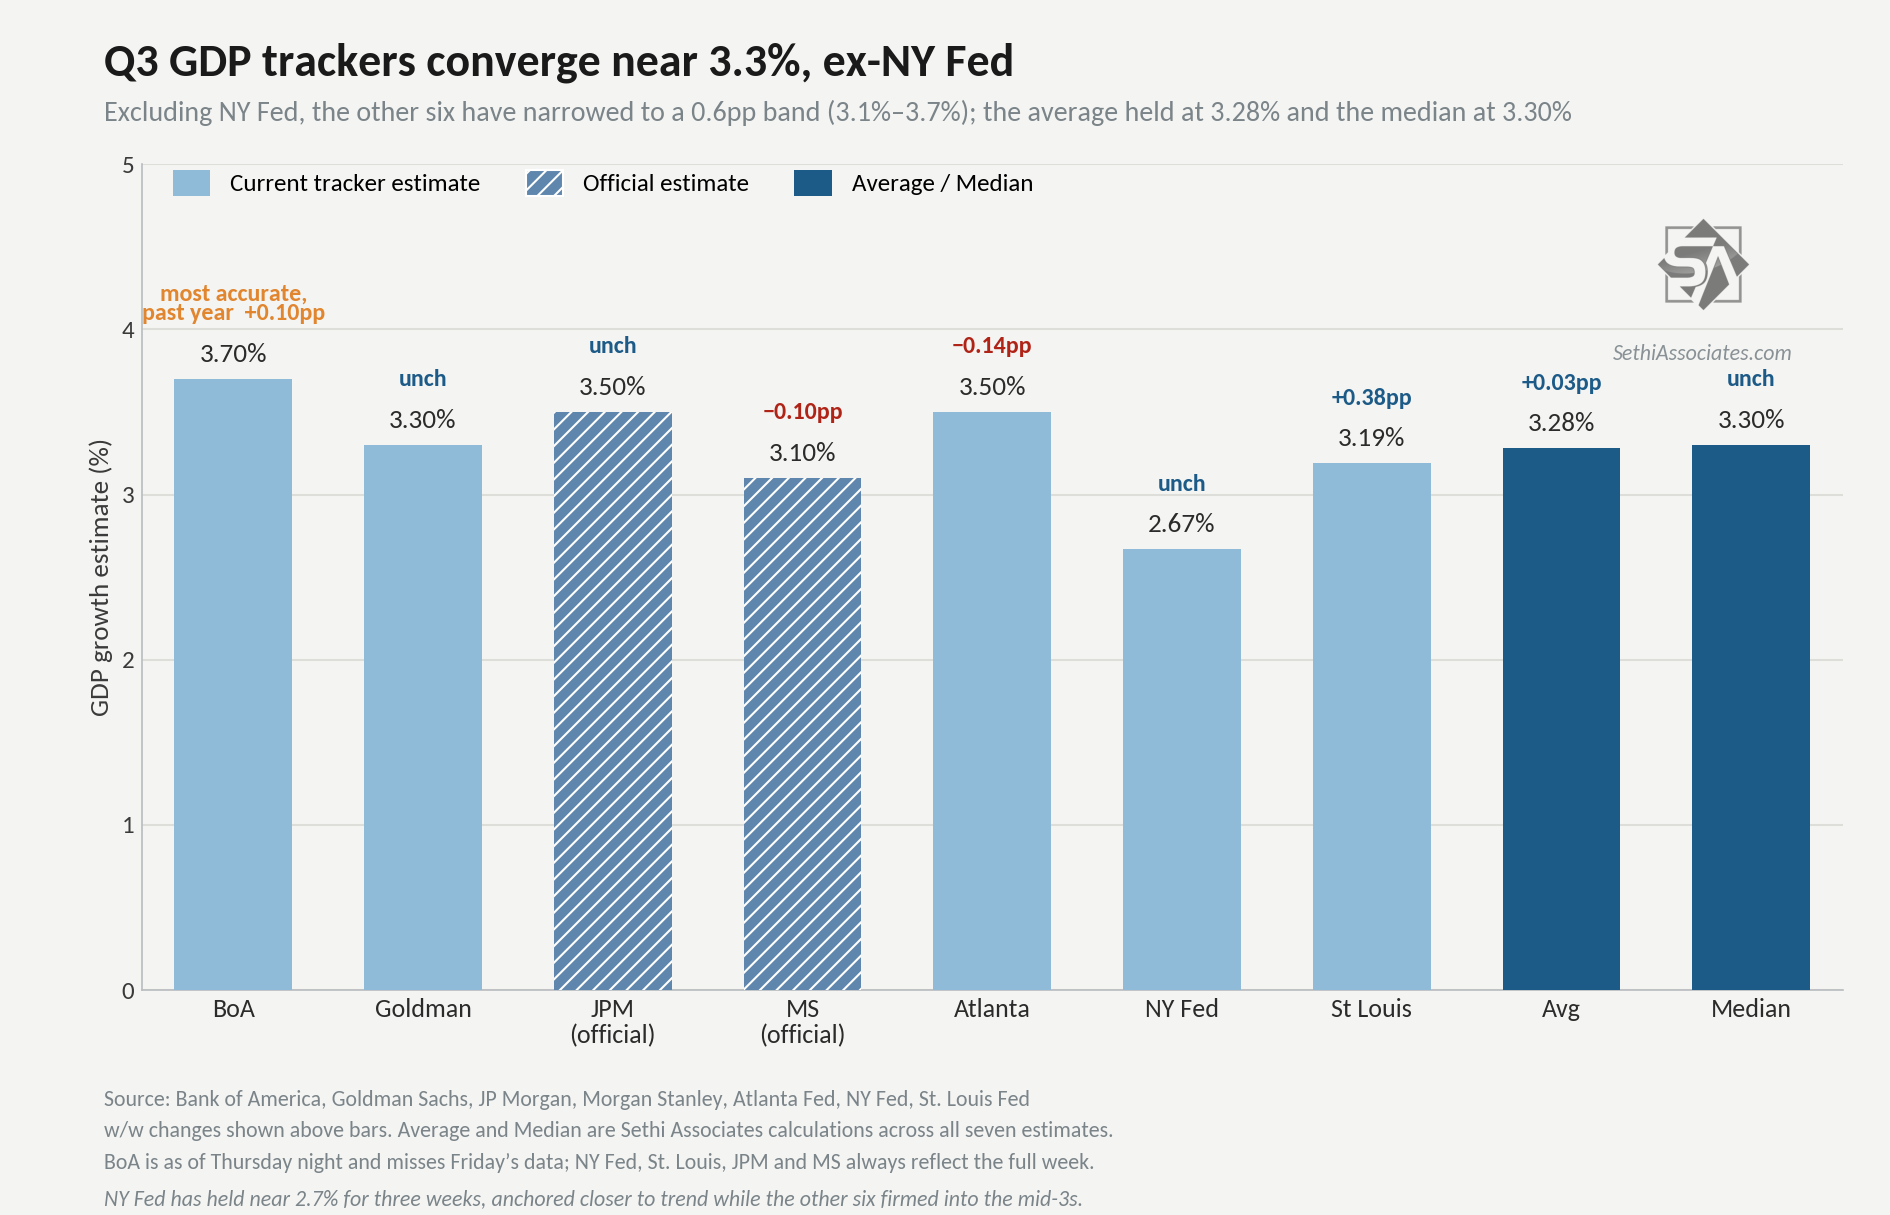
GDPNow, though, has plenty of company this quarter. As of Friday, six of the seven major trackers I follow were between 3.1% and 3.7%. The outlier is the New York Fed’s Staff Nowcast at 2.67%, where it has held for three weeks. The average as of Friday was 3.28% and the median 3.30%.

Bank of America’s tracker has been the most accurate of the group over the past year and is the highest this quarter at 3.70%.
By Neil Sethi

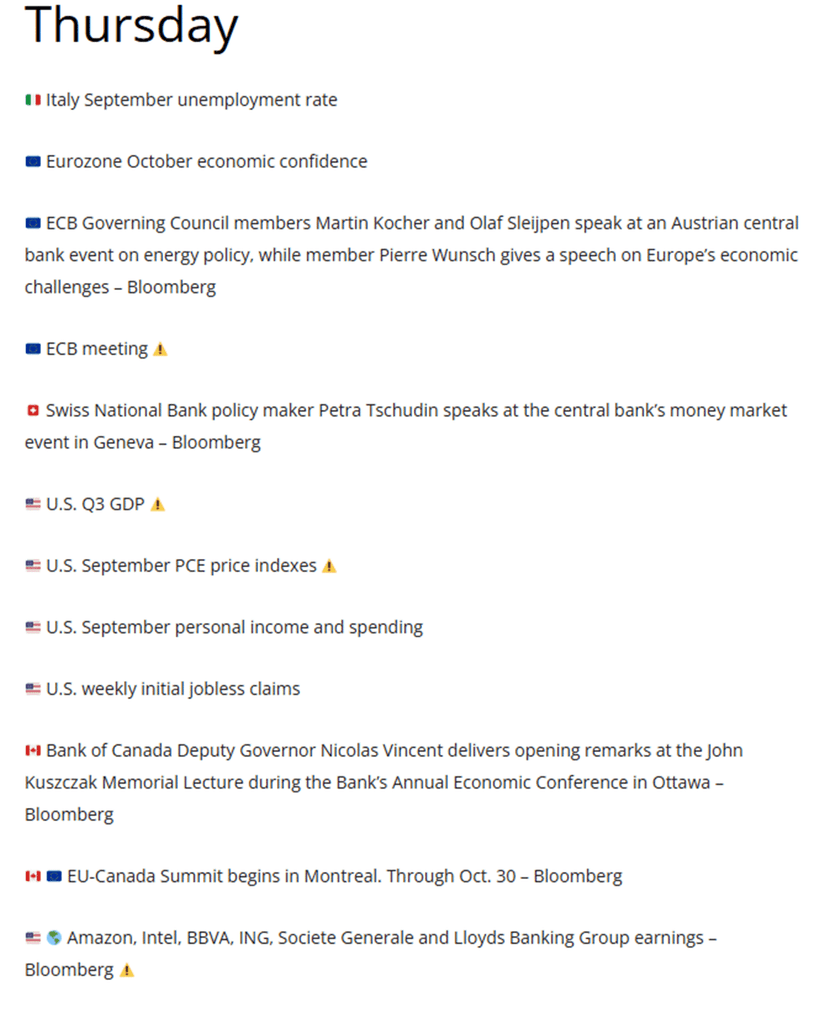
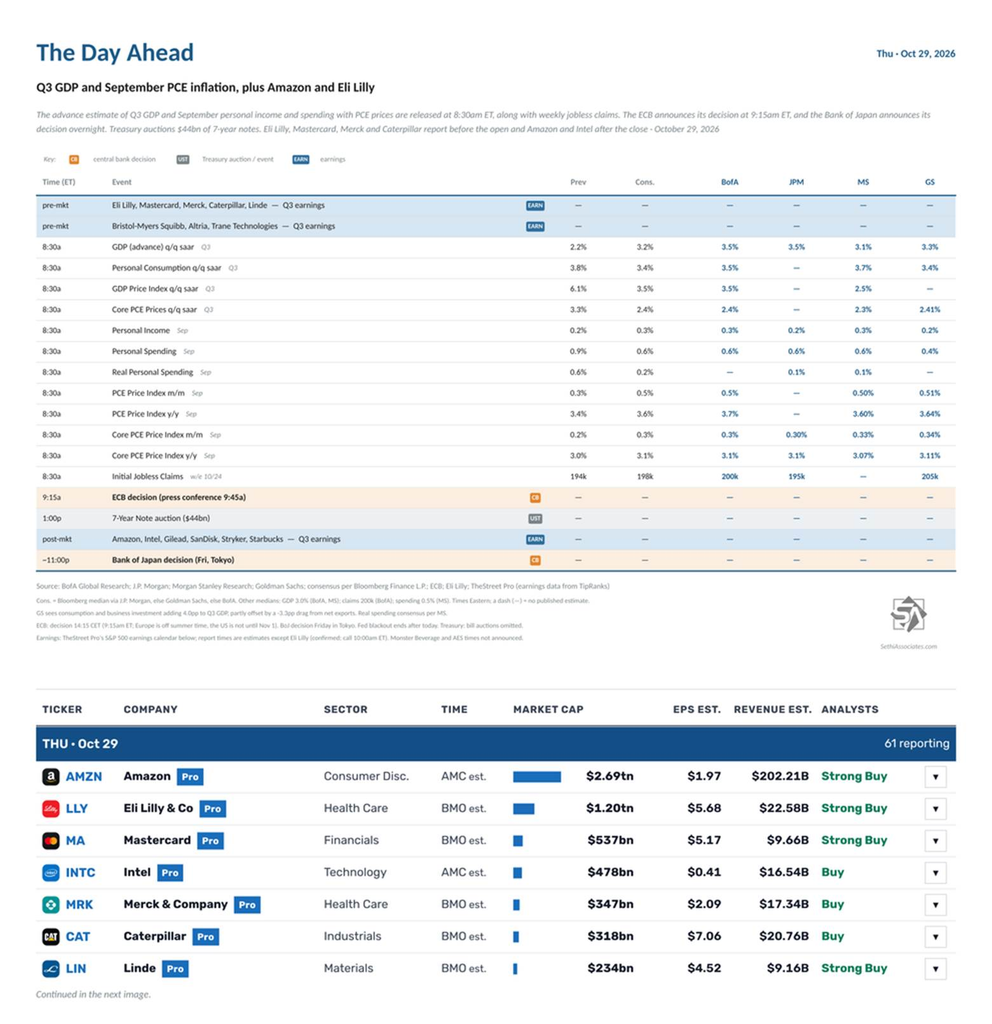
Thursday’s Schedule: GDP and Amazon Headline Another Busy Day

US economic data includes the advance estimate of Q3 GDP, which will incorporate September personal income and spending with PCE prices that will also be separately reported. We’ll also get weekly unemployment claims.

The Fed’s blackout period extends until midnight, with Fed speakers resuming Friday.

The non-Bill (>1yr in maturity) US Treasury auction is $44bn of 7-year notes.

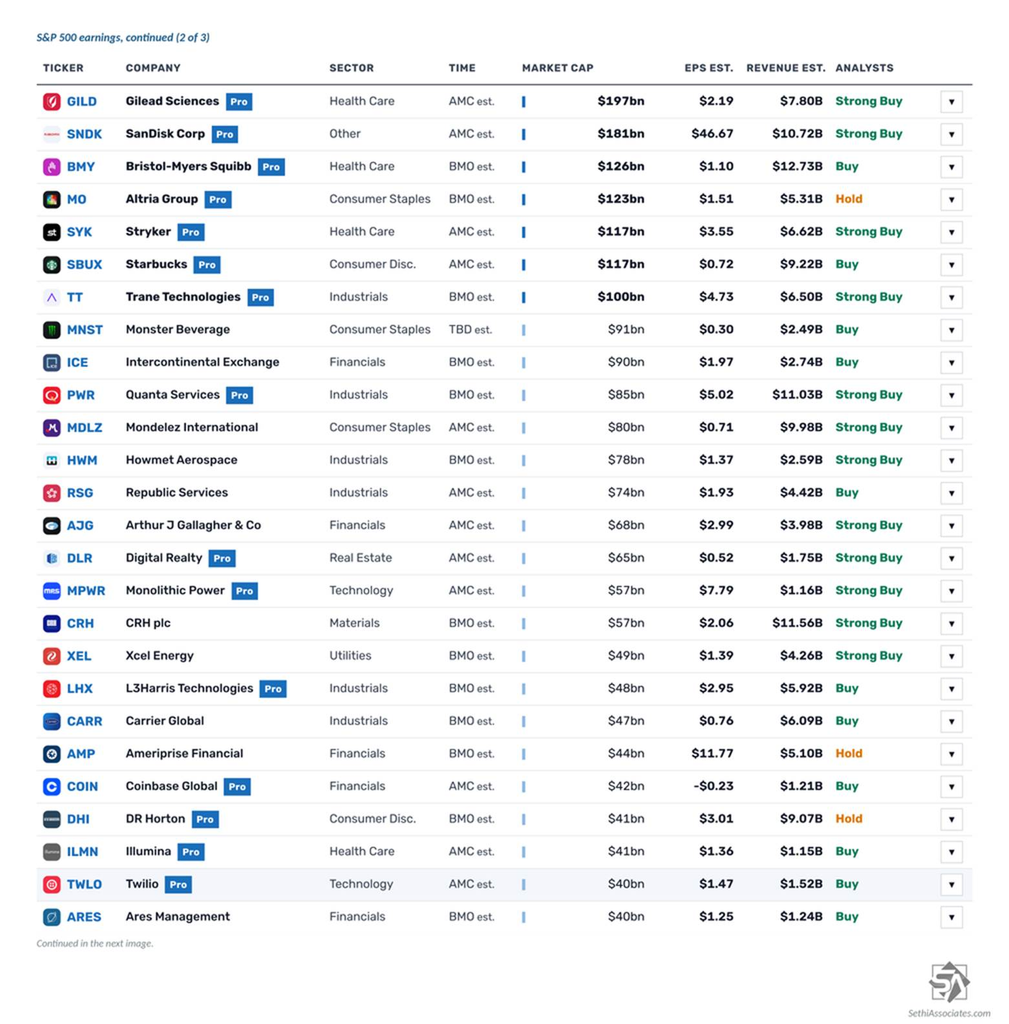
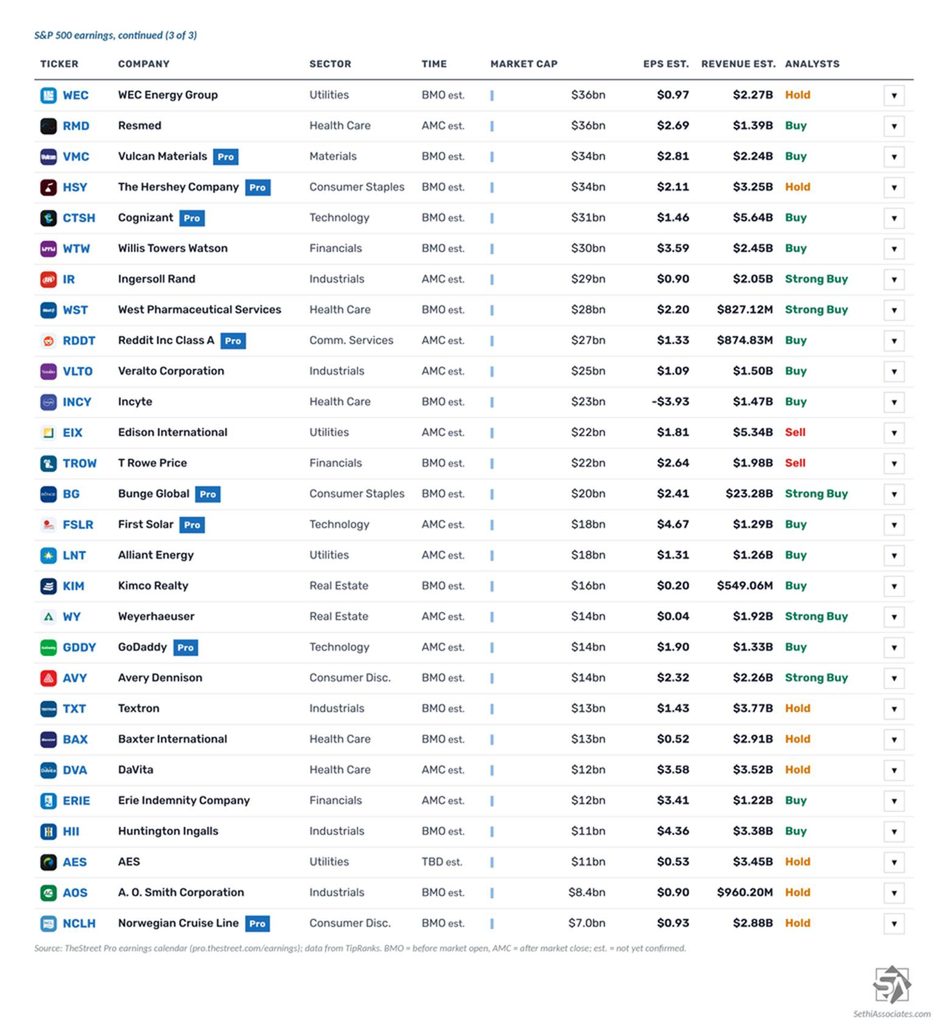
61 S&P 500 components report, 14 of them with market caps over $100bn:61 S&P 500 components report, 14 of them with market caps over $100bn:

Before the open: Eli Lilly (LLY), Mastercard (MA), Merck (MRK), Caterpillar (CAT), Linde (LIN), Bristol Myers Squibb (BMY), Altria (MO), Trane Technologies (TT), Intercontinental Exchange (ICE), Quanta Services (PWR), Howmet Aerospace (HWM), CRH (CRH), Xcel Energy (XEL), L3Harris (LHX), Carrier (CARR), Ameriprise (AMP), D.R. Horton (DHI), Ares Management (ARES), WEC Energy (WEC), Vulcan Materials (VMC), Hershey (HSY), Cognizant (CTSH), WTW (WTW), West Pharmaceutical (WST), Incyte (INCY), T. Rowe Price (TROW), Bunge (BG), Kimco Realty (KIM), Avery Dennison (AVY), Textron (TXT), Baxter (BAX), Huntington Ingalls (HII), A.O. Smith (AOS) and Norwegian Cruise Line (NCLH)

After the close: Amazon (AMZN), Intel (INTC), Gilead (GILD), SanDisk (SNDK), Stryker (SYK), Starbucks (SBUX), Mondelez (MDLZ), Republic Services (RSG), Arthur J. Gallagher (AJG), Digital Realty (DLR), Monolithic Power (MPWR), Coinbase (COIN), Illumina (ILMN), Twilio (TWLO), ResMed (RMD), Ingersoll Rand (IR), Reddit (RDDT), Veralto (VLTO), Edison International (EIX), First Solar (FSLR), Alliant Energy (LNT), Weyerhaeuser (WY), GoDaddy (GDDY), DaVita (DVA) and Erie Indemnity (ERIE)

Time not announced: Monster Beverage (MNST) and AES (AES)

Outside the US, Shell (SHEL), TotalEnergies (TTE) and Volkswagen (VWAGY) report.

Ex-US highlights include a policy decision from the ECB, UK September net consumer credit and M4, Japan October consumer confidence index, Italy September unemployment rate, October consumer confidence index, economic sentiment and manufacturing confidence, Eurozone October economic confidence and Sweden Q3 GDP indicator.

From Christophe Barraud’s international Week Ahead rundown:

Conversation 0 Comments

One ongoing discussion across all days. Everyone can read; sign in to take part.

Your voice matters. Discussions are moderated for civility. Read our guidelines .

Log in to join the conversation

Loading comments...