Equities Remain Under Pressure As 10-Year Yield Hits 19-Year High
A bounce in AI names is helping offset pressure from a continued rise in bond yields and oil prices.
You've reached your free article limit
You've read 0 of 1 free Pro articles.
US equities opened Tuesday slightly lower after cutting back larger losses in the overnight session.
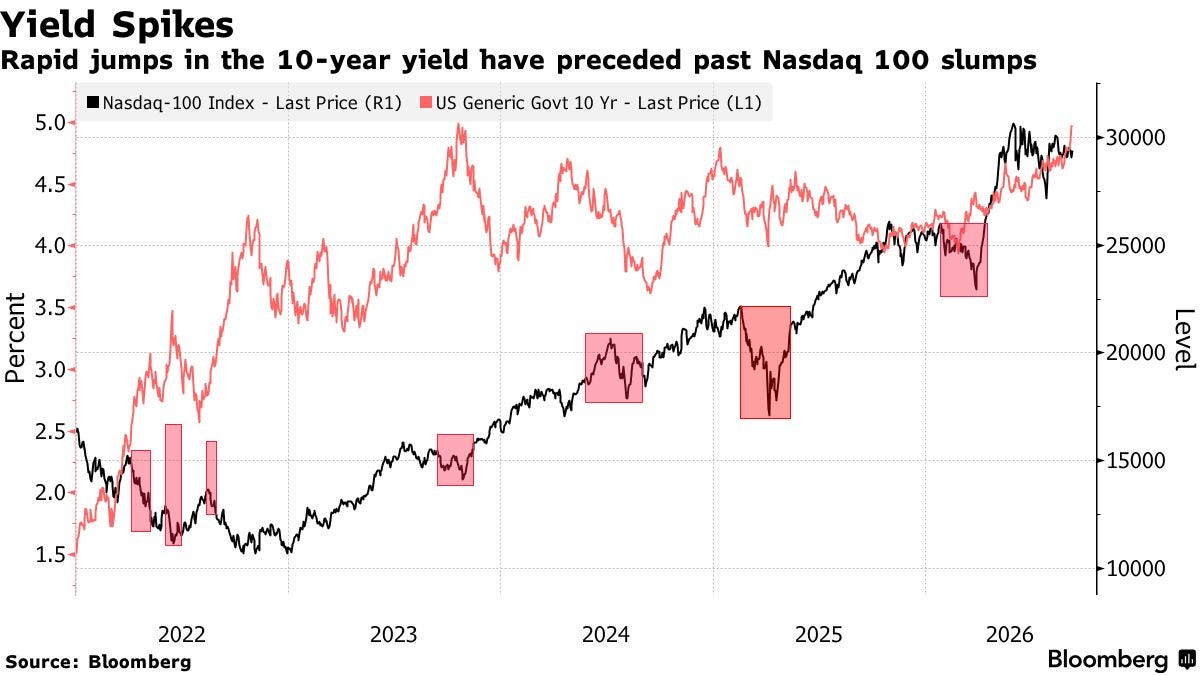
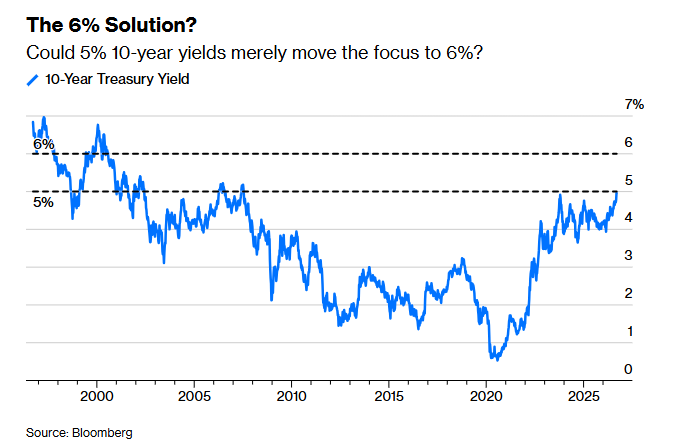
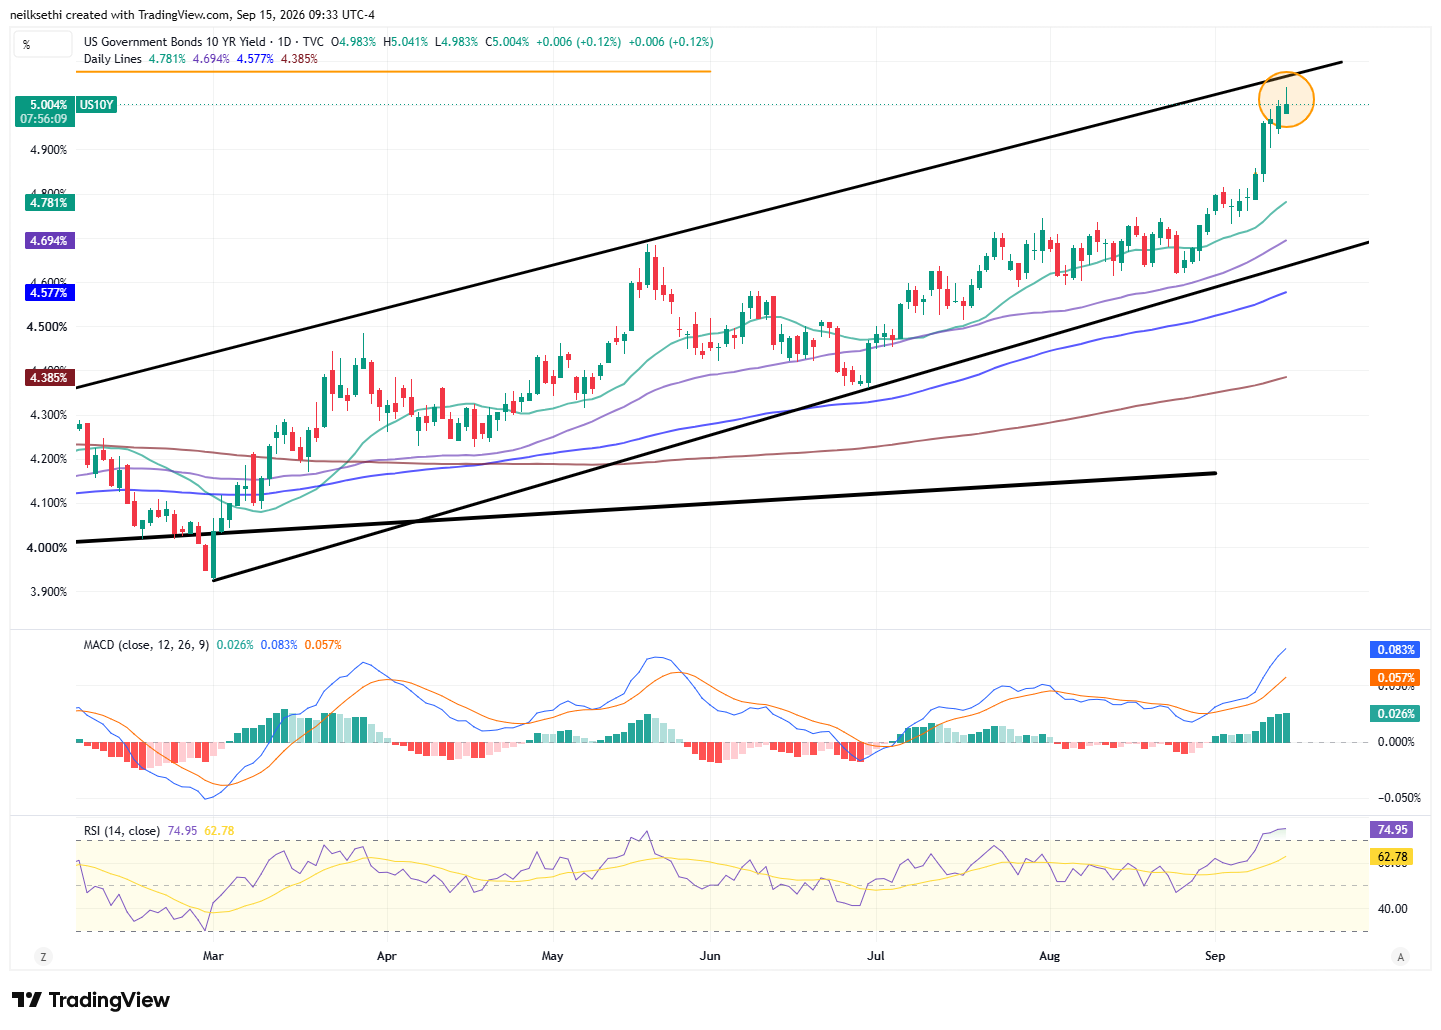
Equities hit their lows as the 10-year yield again traded over 5%, this time though hitting 5.04% and eclipsing the October 2023 high, meaning it was a level not seen since 2007.
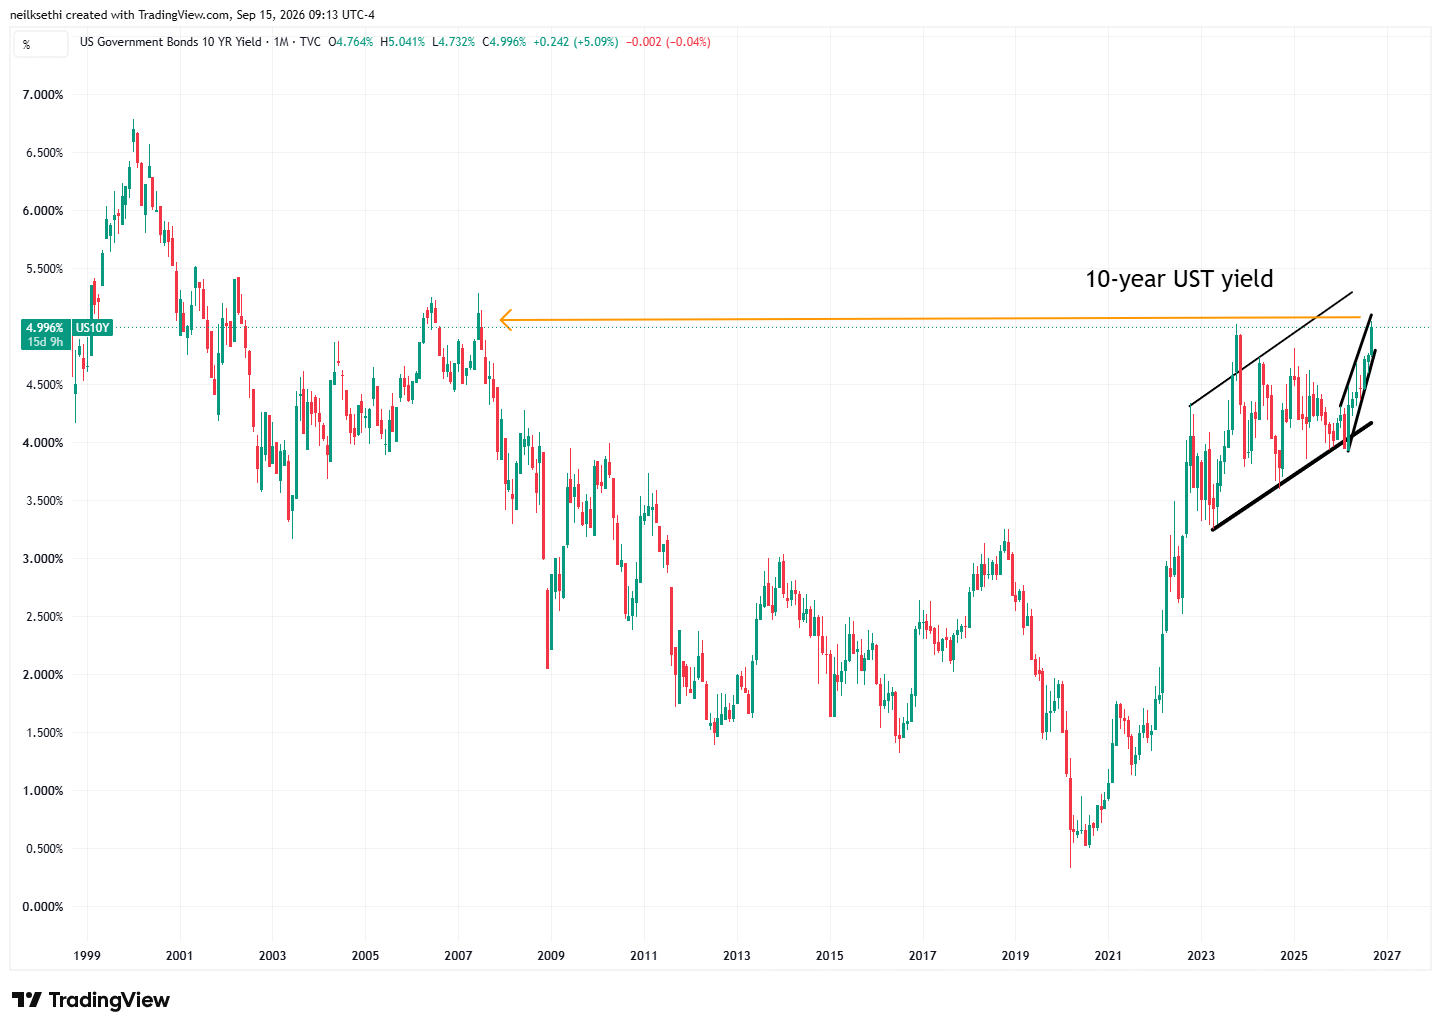
As you can imagine charts like those below filled my inbox.
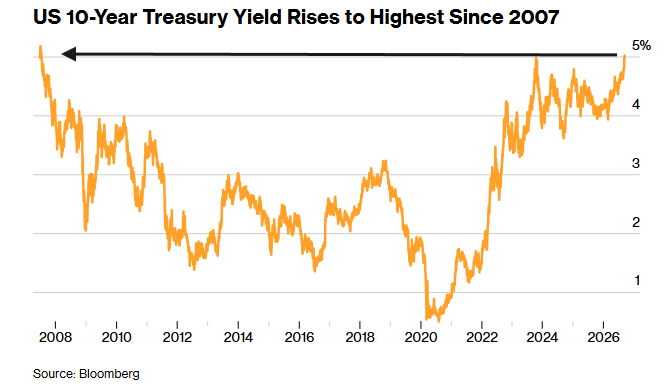
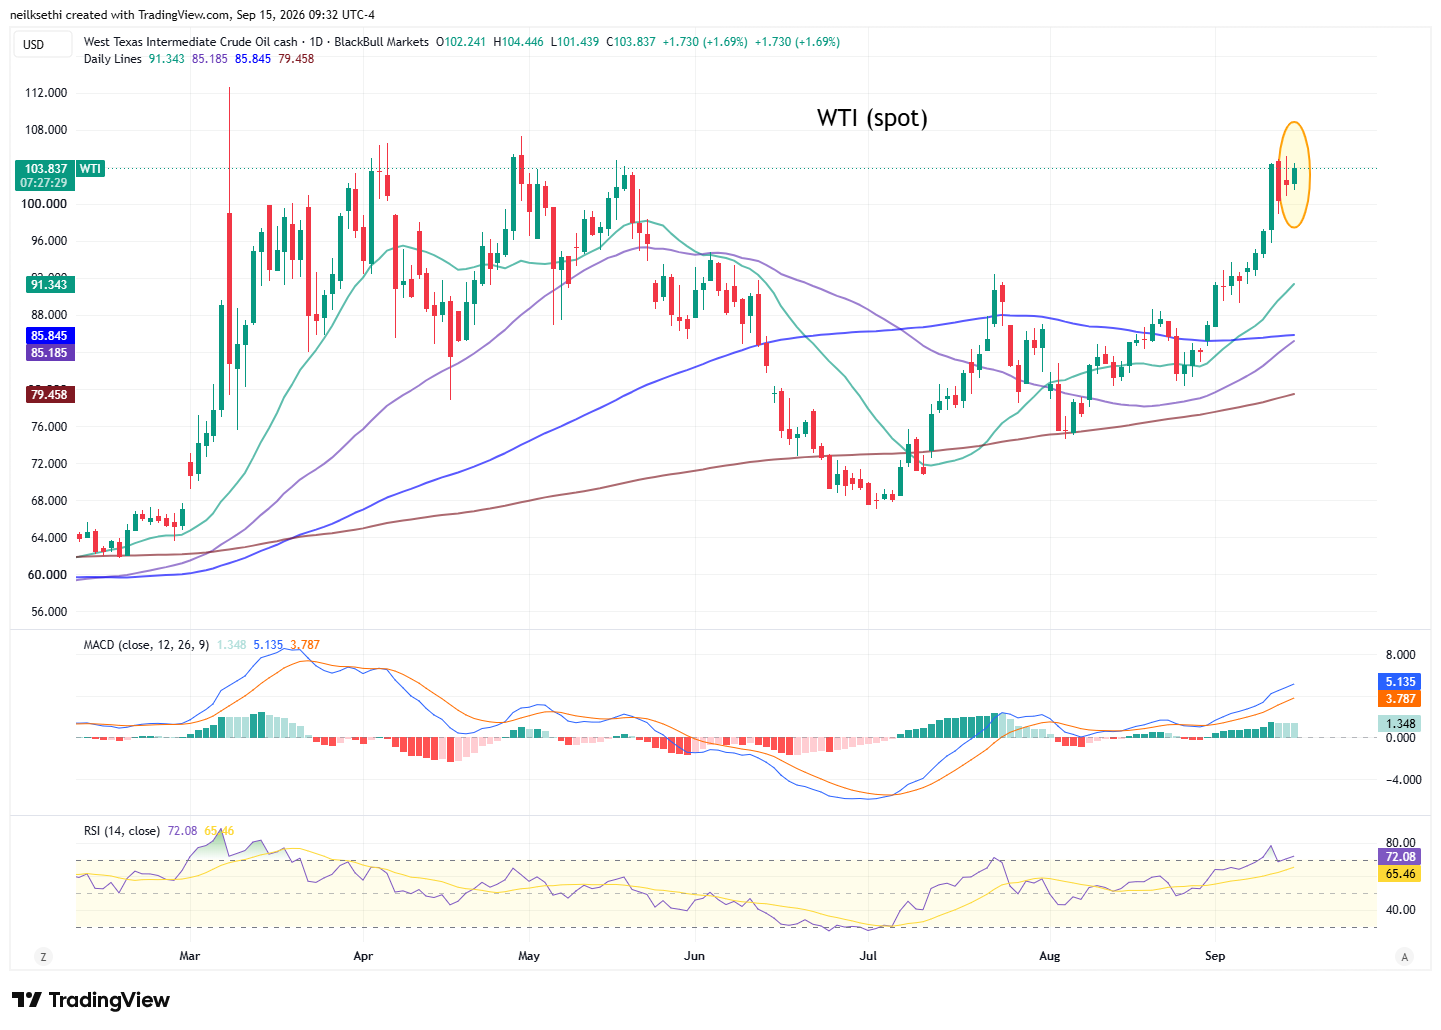
However, as we saw Monday, yields eased back which saw equities lift off those lows, even as Brent crude climbed toward $107 a barrel, extending gains for September to 18%.
Helping was a rebound in the AI trade. Nvidia (NVDA) rose nearly 1%, while Advanced Micro Devices (AMD), Intel (INTC) and Micron Technology (MU) all were up over that mark. The iShares PHLX Semiconductor ETF (SOXX) was up 0.8% in premarket trading, with 28 of its 30 equity components set to open higher. That follows a 5.6% drop on Monday, which was the biggest one-day decline since July 1st.
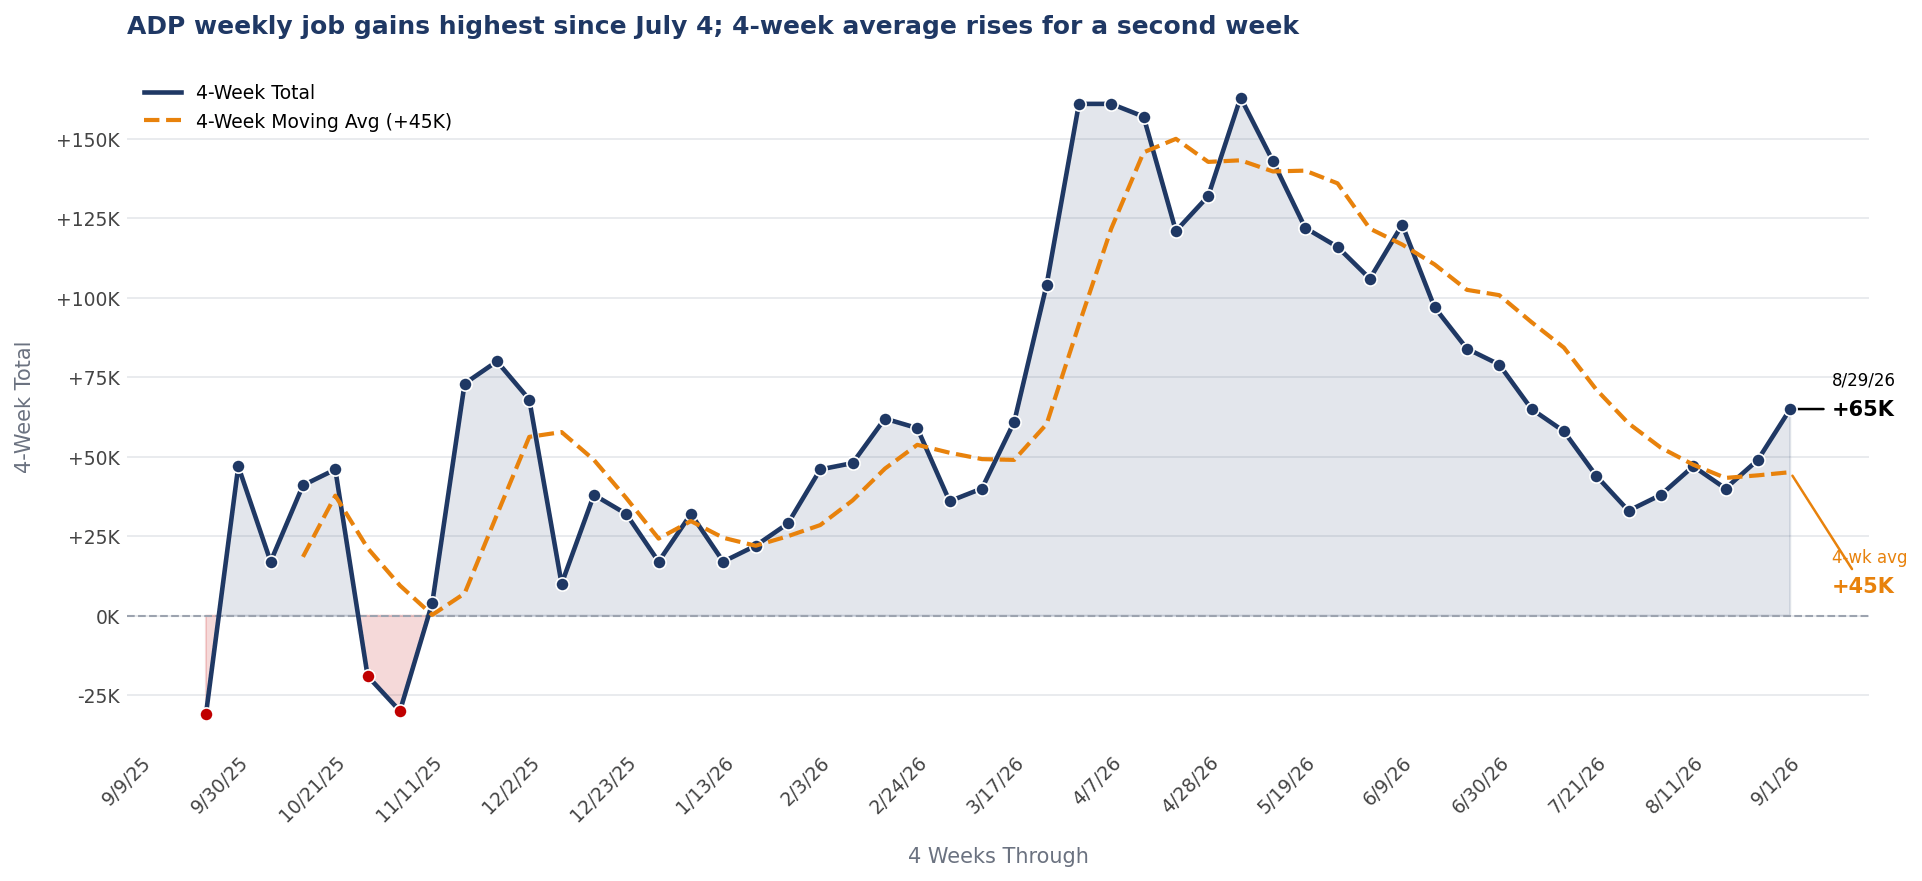
As noted in the Week Ahead, it’s a light start to the week and that continues Tuesday. Earlier this morning we did get the ADP weekly job growth estimate for the four weeks ending August 29th which rose for a third week to +65k (+16.25k/wk), the best since July 4th, and the 4-week moving average edged higher for a second week to +45k after having fallen the previous 13 weeks.
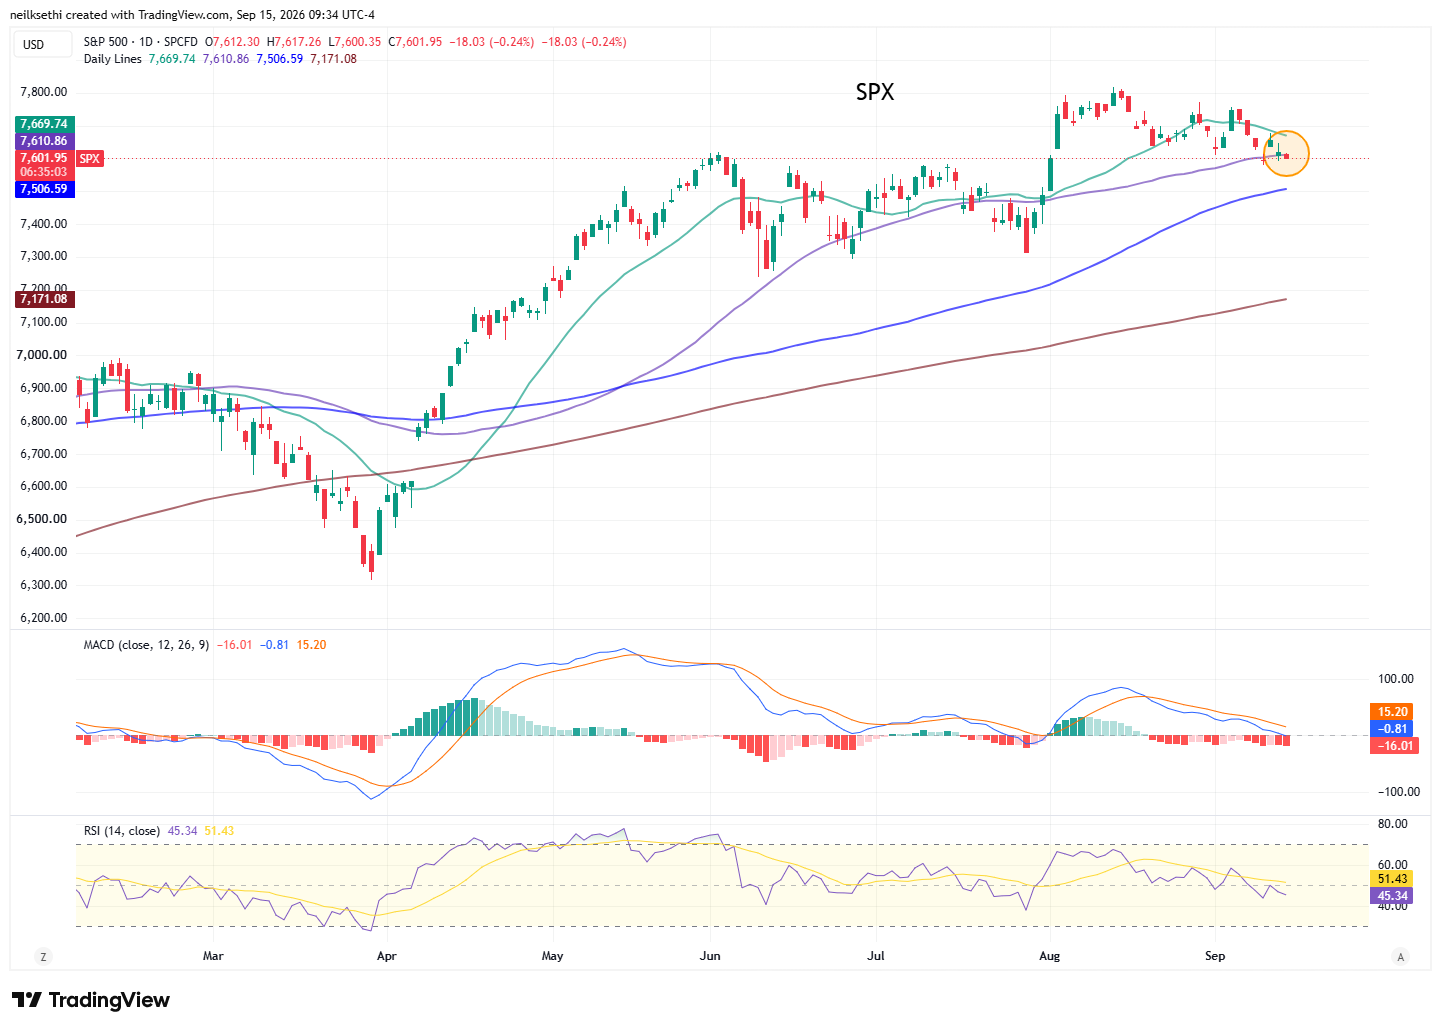
As of 9:35 am ET, the S&P 500 was -0.2% while the tech-heavy Nasdaq-100 index was -0.2%, and the small-cap Russell 2000 -0.3%.
[Note the International Update is below the US update]
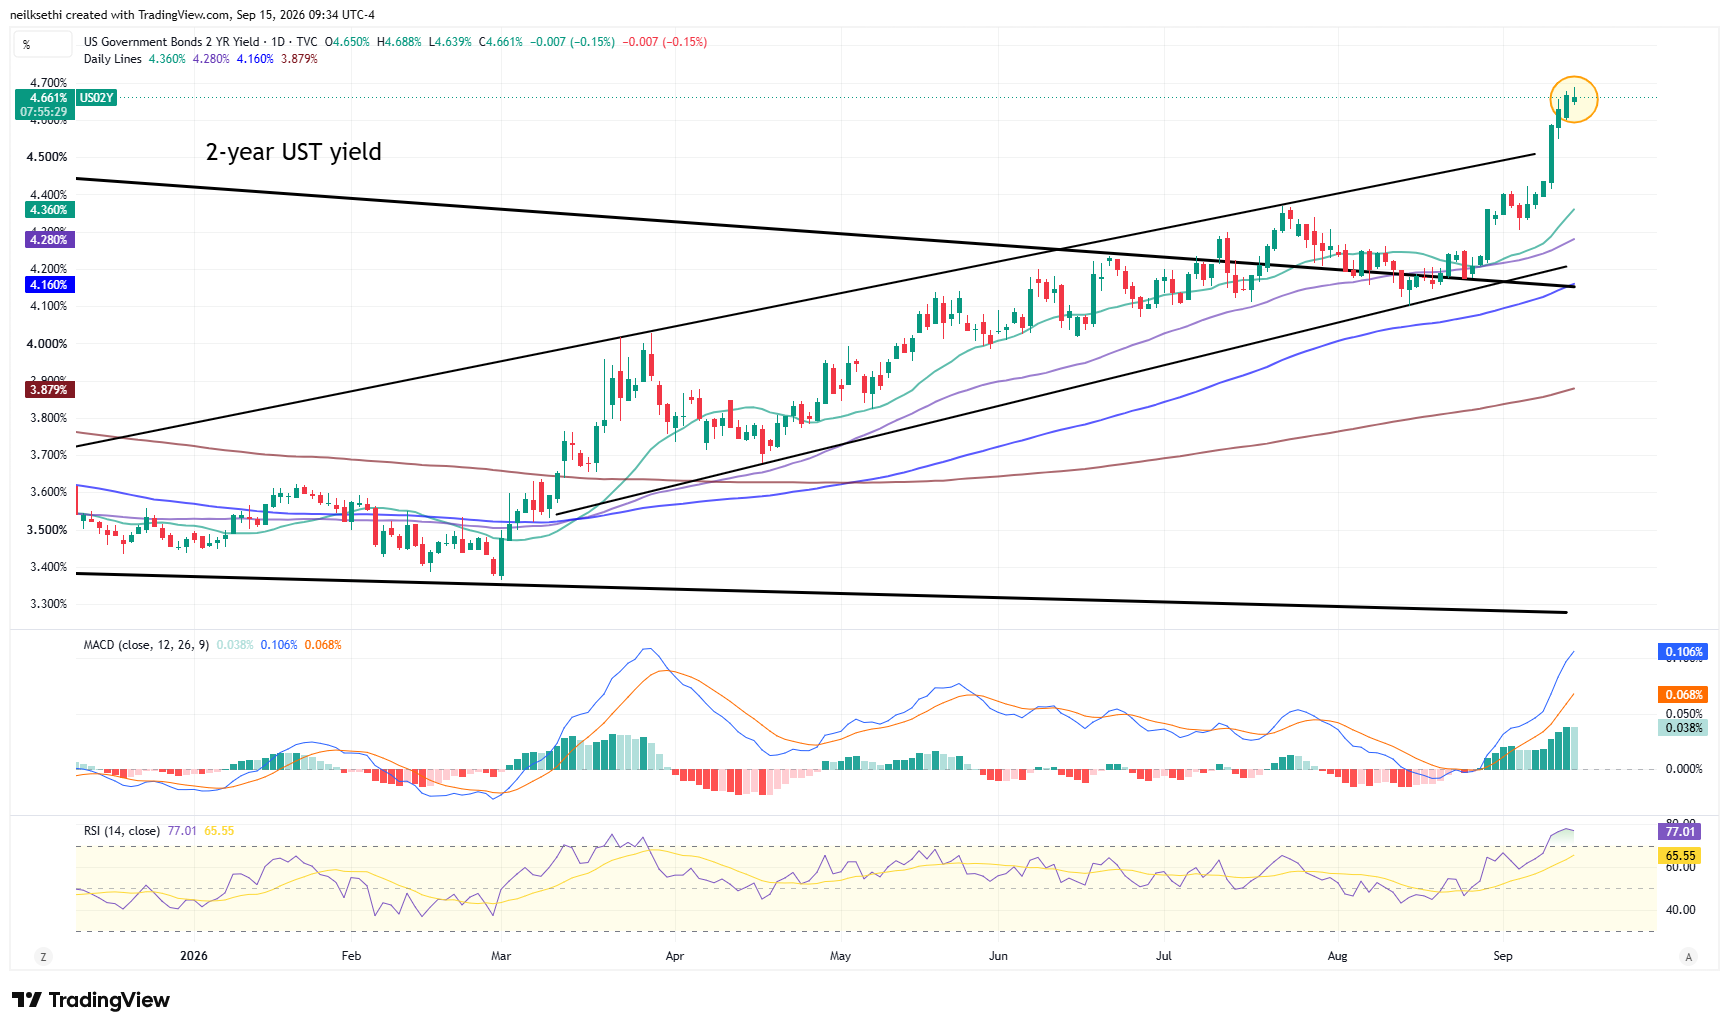
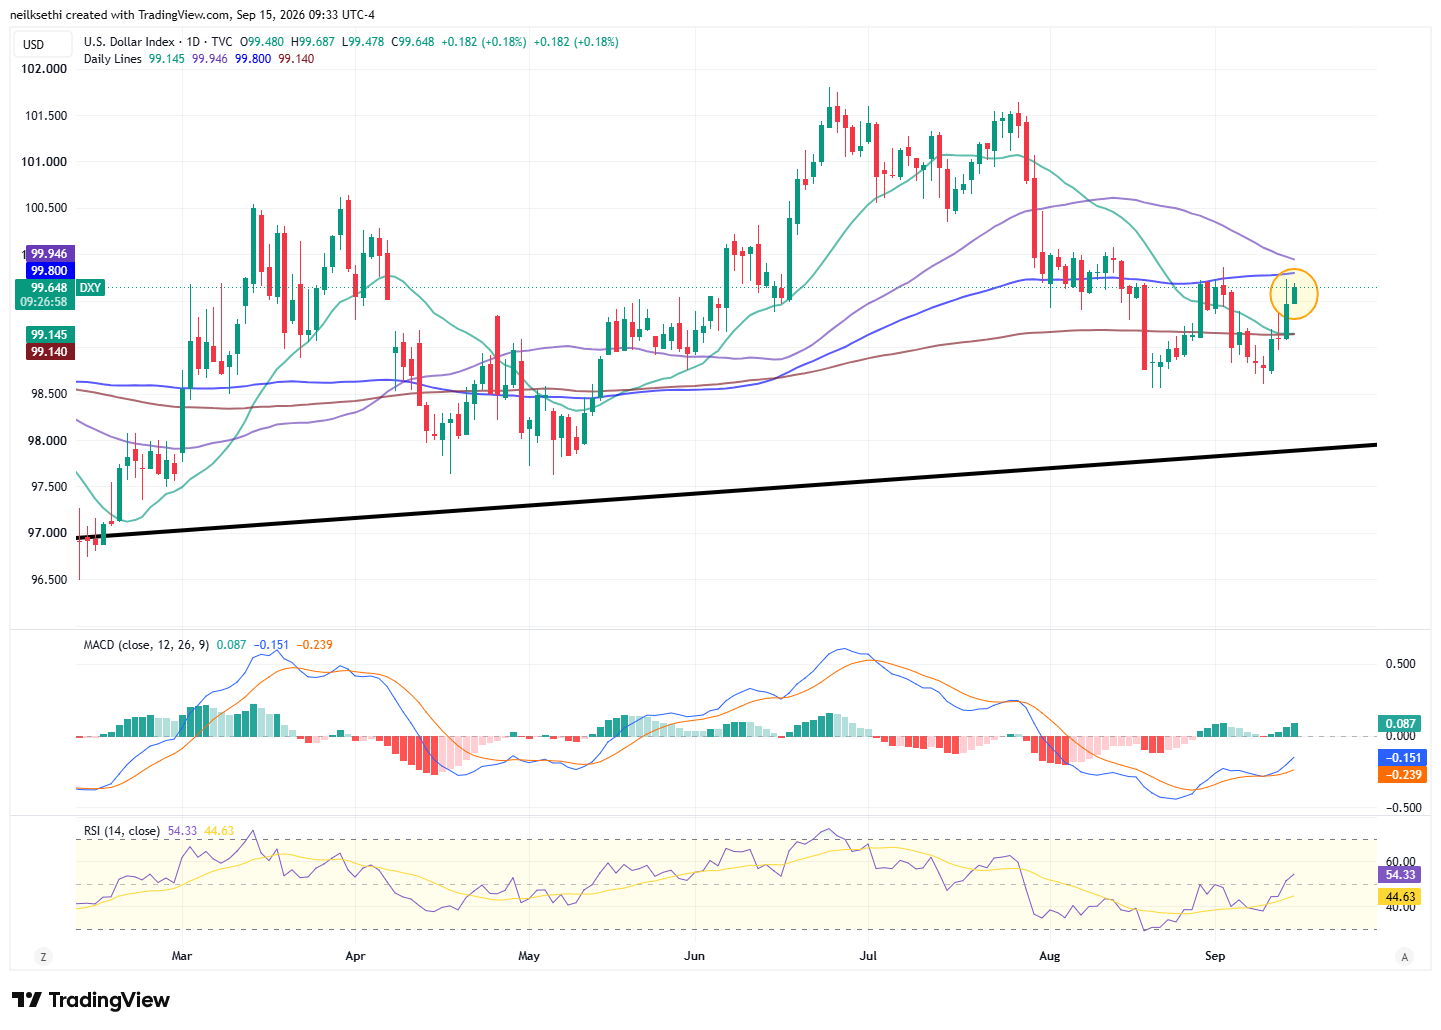
Note on all charts the colored lines are daily moving averages (the average price over the given number of days):
20 = green
50 = purple
100 = blue
200 = brownThe middle panel is MACD = Moving average convergence/divergence line, a measure of momentum that compares longer term and shorter term momentum to gauge if a move is strengthening or weakening. This is probably my favorite individual indicator (it’s also the favorite of Katie Stockton, a very fine technician).
The bottom panel is RSI = Relative Strength Index (basically what it sounds like) = measures the strength of the move comparing gains to losses over the given lookback window (I use the standard 14 periods).
SPX – remains near 5-week lows but hasn’t yet broken to a new low.
2-year yield – Just off the highest since July 2024.
10-year yield – While it has pulled back would still be a new post-November 2023 closing high.
DXY US dollar index – back into that strong zone of resistance.
US WTI crude – remaining near the highest close since 2022.
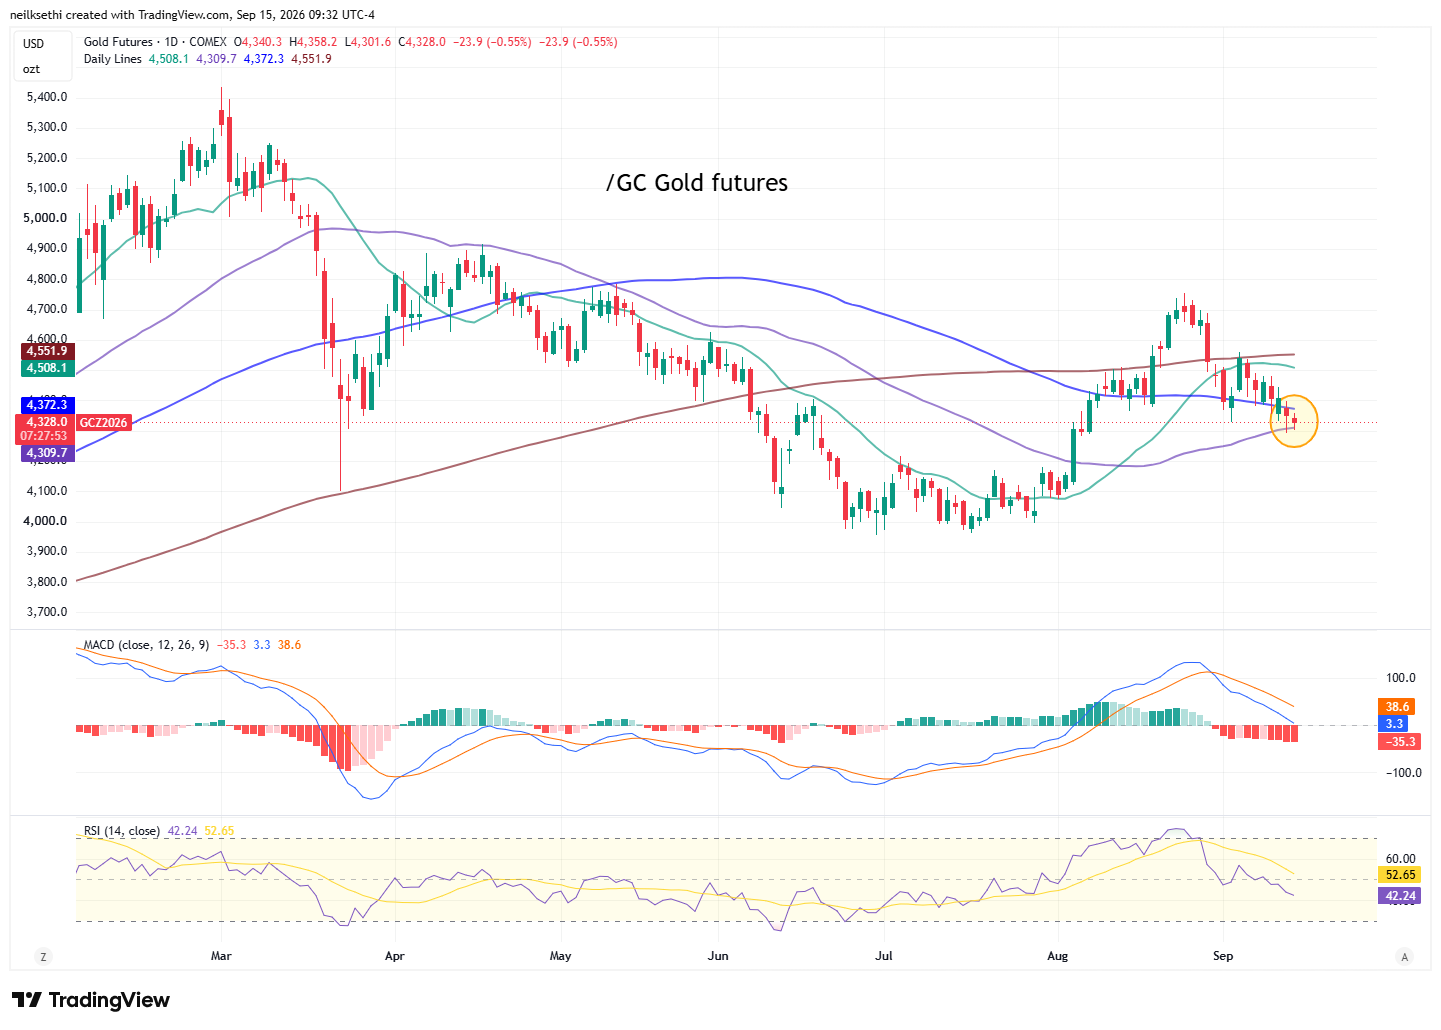
Gold futures (/GC) – Holding their 50-DMA.
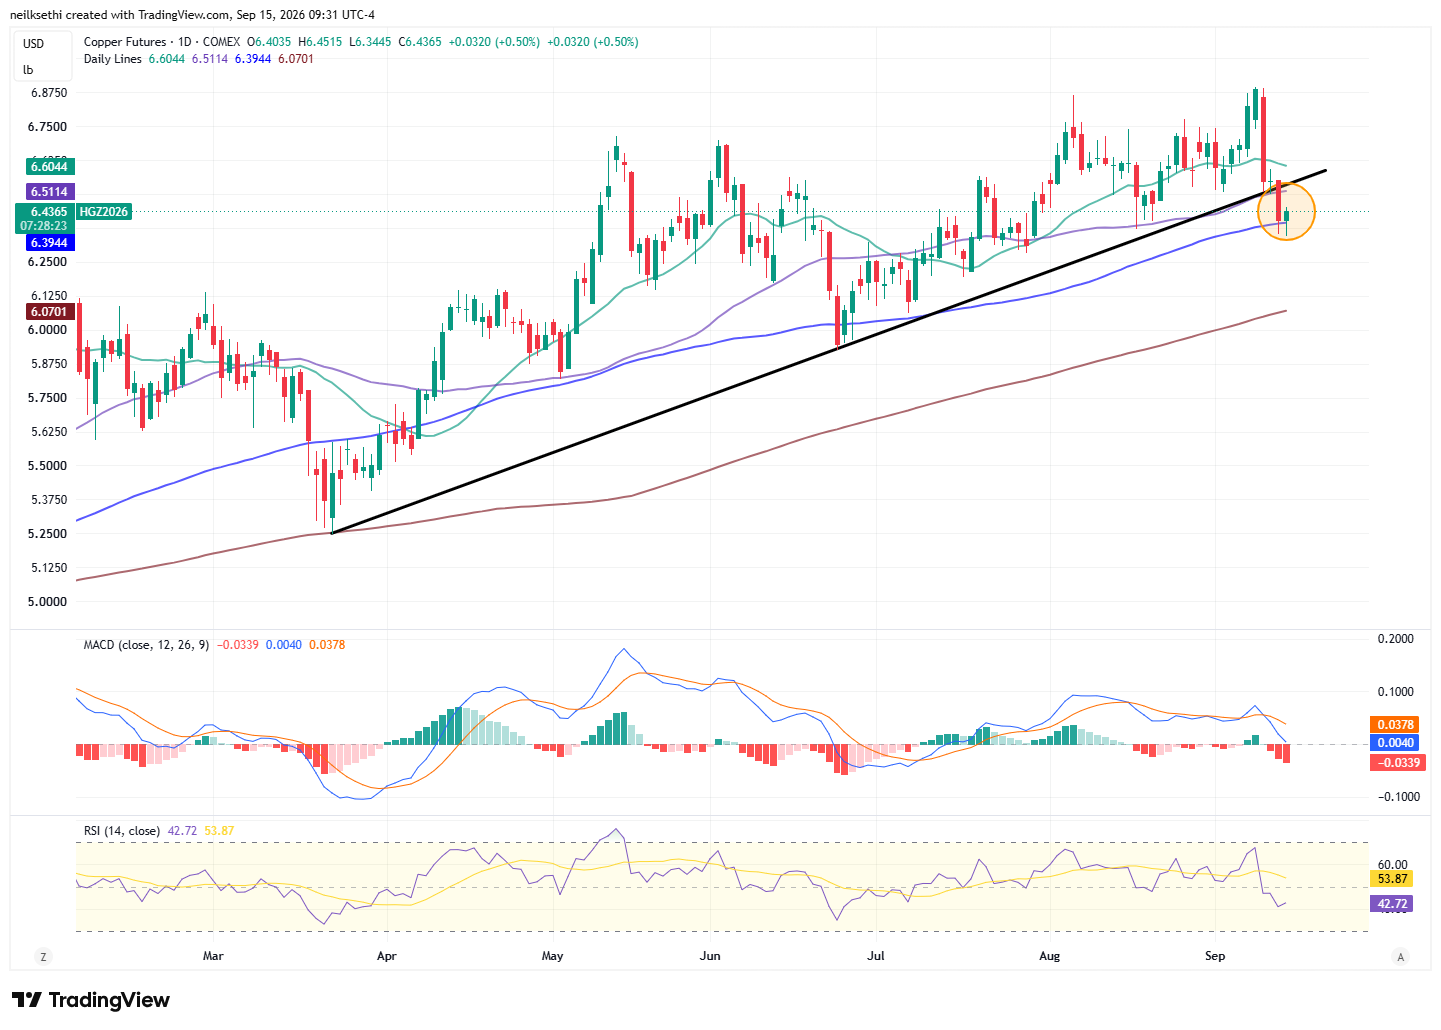
US copper futures (/HG) – rebounding along with the AI-trade finding some support at the 100-DMA.
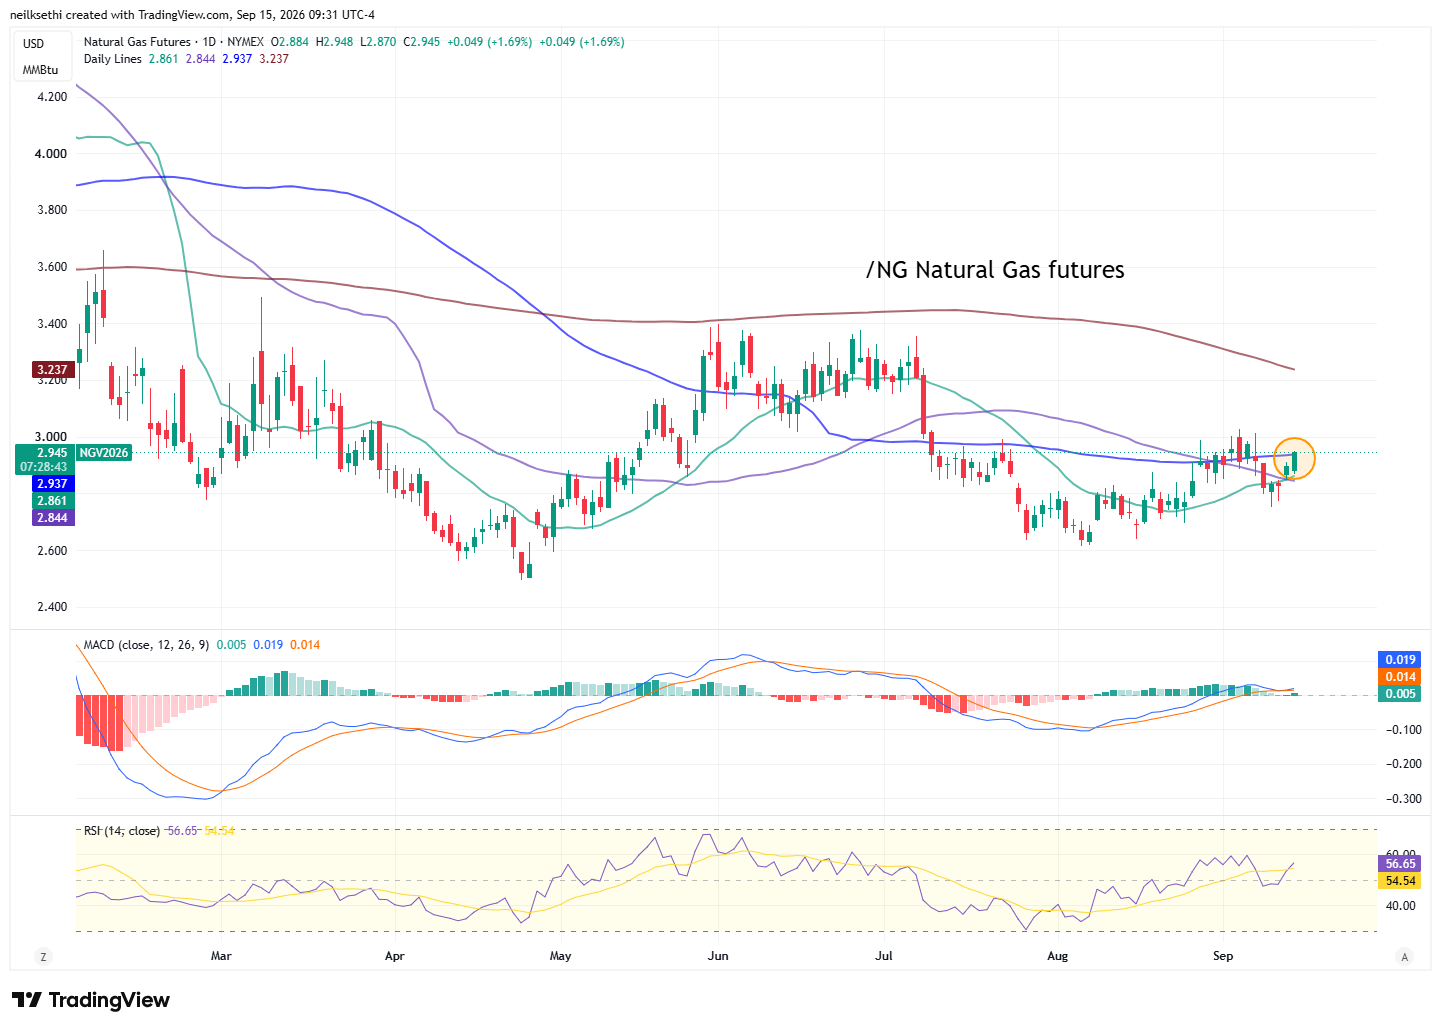
US natural gas futures (/NG) – remaining in range since early July.
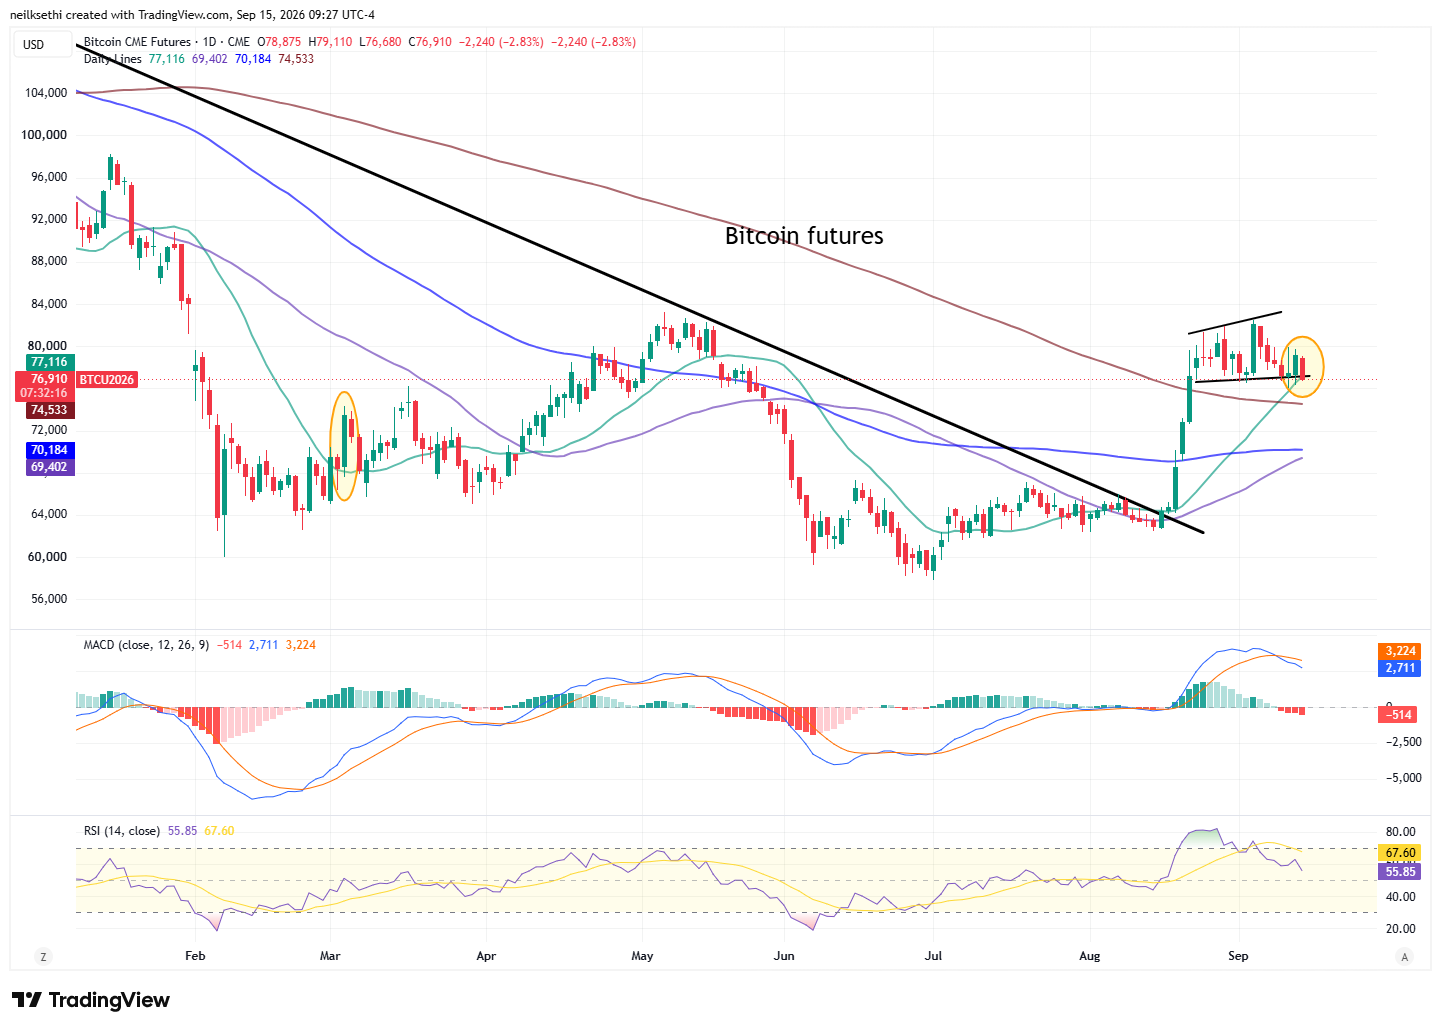
Bitcoin futures – again slipping under its “bull flag” pattern (and crypto stocks are lower (see below)) ahead of a make-or-break Senate cloture vote on the CLARITY Act.
Some pre-market company news:
- Anthropic PBC is pitching financial advisers on a version of Claude that blends the chatbot with financial analytics and risk management technology run by BlackRock Inc., Vanguard Group Inc. and other firms.
- Deutsche Bank AG slipped more than 2%, echoing declines among US peers after Bank of America Corp. warned that trading revenue for the current quarter will be flat.
- Dave & Buster’s Entertainment (PLAY): The arcade chain swung to a loss in the most recent quarter as it struggles to regain relevancy with customers. Shares tumbled nearly 14% premarket.
- Vera Therapeutics (VERA) +13% said atacicept met all final efficacy endpoints in the Phase 3 ORIGIN study in IgA nephropathy.
- Sysco (SYY), the wholesale distributor to restaurants, hospitals and schools slid nearly 2% after it announced a common stock offering of 12.3 million shares priced at $81 per share.
- Crypto linked stocks were lower ahead of a make-or-break Senate cloture vote on the CLARITY Act. Circle (CRCL) stock leads the drop, down more than 5%, while Strategy (MSTR), Coinbase (COIN), and Robinhood (HOOD) were 3-4% lower.
From around TheStreet Pro:
- Doug Kass – History Doesn’t Repeat, But Today’s Market Is Rhyming Loudly
- Helene Meisler – A Market Hanging by a Thread
- James “Rev Shark” DePorre – Extreme Uncertainty Ahead of the Fed Keeps Investors Off Balance
- Stephen Guilfoyle – Feeling the Weight of the Market
- Chris Versace – Bank of America Sends Interest Rate Warning: 8 Key Items Shaping the Stock Market Tuesday
Some other headline stories:
- MarketWatch: Saudi Arabia, a top oil exporter to the world, may be days away from not being able to export much crude.
- WSJ – A pullback by pension funds in Treasurys has created a void filled by hedge funds; the New York Fed is asking about the potential risks.
International Highlights:
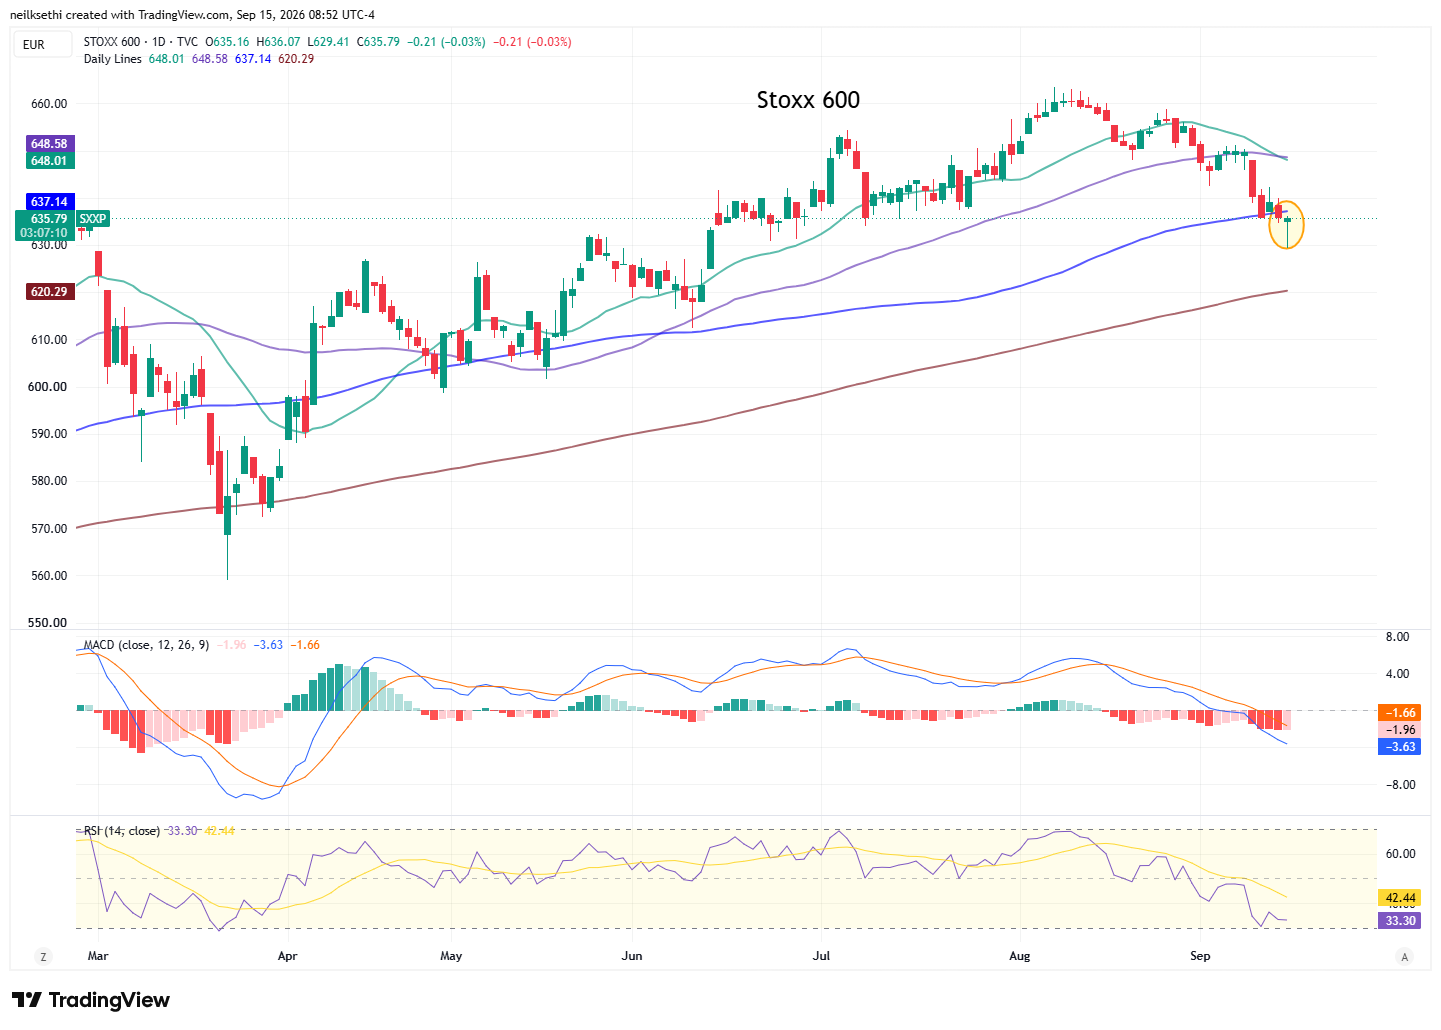
Europe’s benchmark STOXX 600 as of 8:50 am ET had battled back to just under unchanged levels almost erasing much deeper losses earlier in the session although still below its 100-DMA and at what would be the lowest close since June 23rd.
Germany’s DAX: UNCH, U.K.’s FTSE 100: -0.2%, France’s CAC 40: -0.2%, Italy’s FTSE MIB: UNCH, Spain’s IBEX 35: +0.1%.
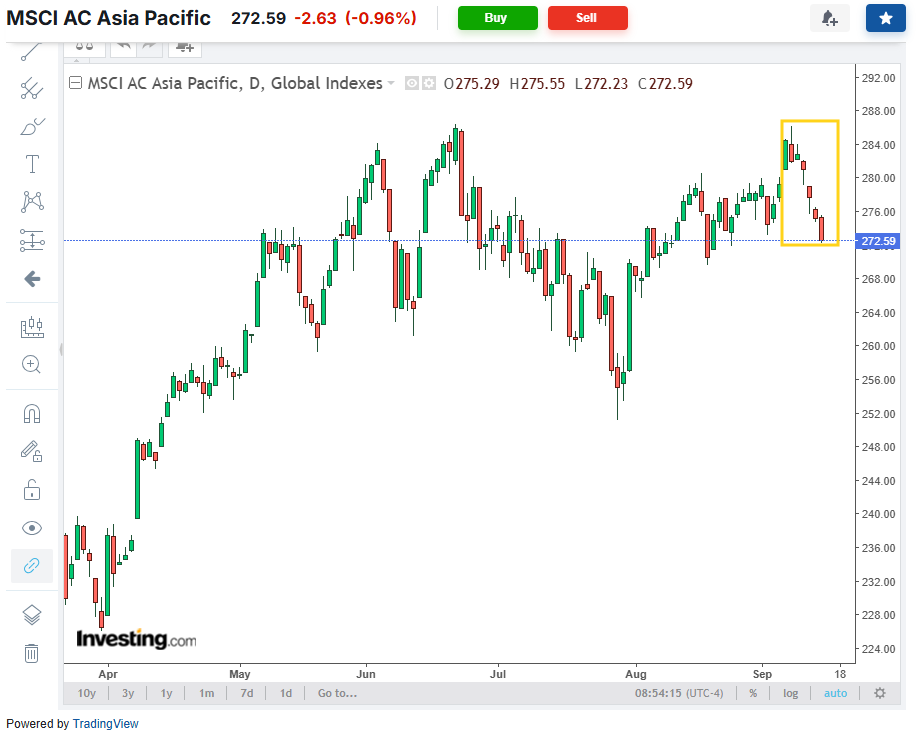
The broad MSCI AC Asia Pacific Index though ended lower for a fourth session -1.0% at what would be its lowest close since August 19th.
Japan’s Nikkei: UNCH, Hong Kong’s Hang Seng: -1.0%, China’s Shanghai Composite: -0.5%, India’s Sensex: -1.0%, South Korea’s Kospi: -0.9%, Australia’s ASX All Ordinaries: -0.8%.
Some ex-US highlights:
- BBG – The dramatic collapse of trade talks with the US in August helped clarify Canada’s negotiating “red lines,” said Prime Minister Mark Carney, who added he’s ready to get back to the table for the right deal.
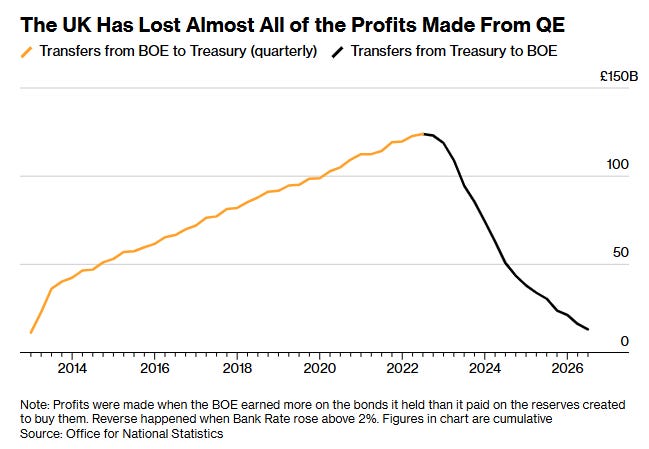
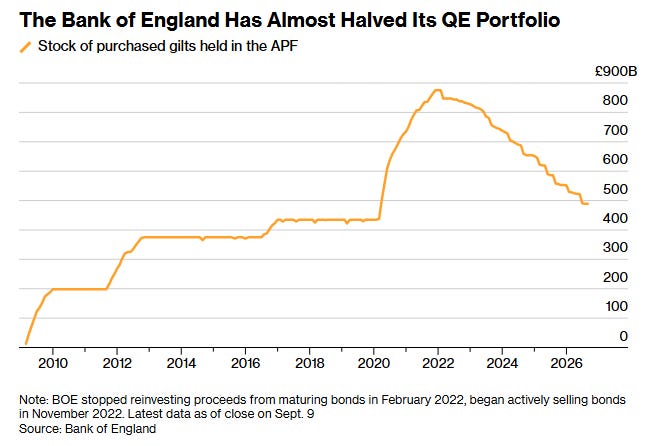
- BBG – The Bank of England could soon stop selling long-dated bonds that it amassed after the financial crisis and pandemic, according to a report by the Daily Telegraph, in a move that would be likely to save the Treasury billions of pounds.
- BBG – UK household energy bills are poised to jump by about 25% in January amid sharpened tensions in the Middle East, according to a Bloomberg Economics forecast that threatens to upend Prime Minister Andy Burnham’s drive to bear down on the cost of living.
- BBG – German Chancellor Friedrich Merz said his coalition will take action on “price gouging” amid mounting calls to alleviate the burden on consumers from surging fuel prices.
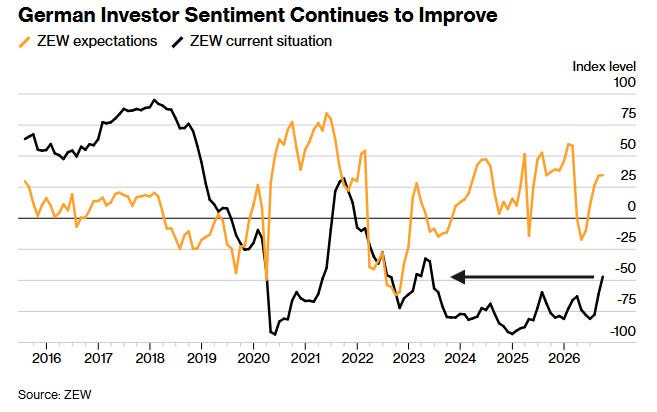
- BBG – German investor optimism inched higher in September, although below estimates, but a measure of current conditions improved more than anticipated to the best in three years.
- BBG – The UK said it will work with other countries on the safety of artificial intelligence, amid criticism that Andy Burnham’s government has been slow to respond to warnings that the technology could inflict catastrophic harm.
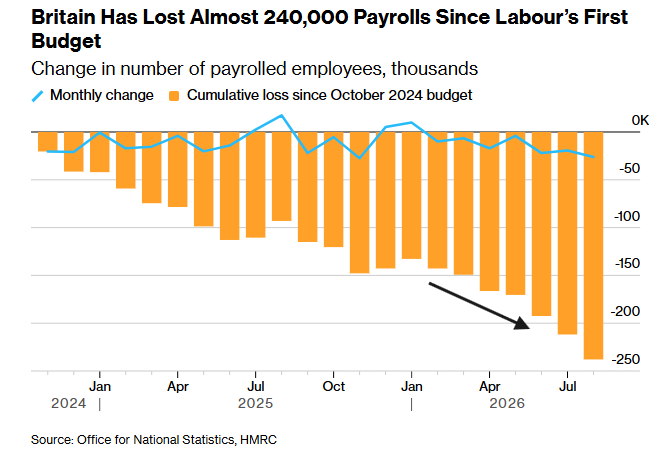
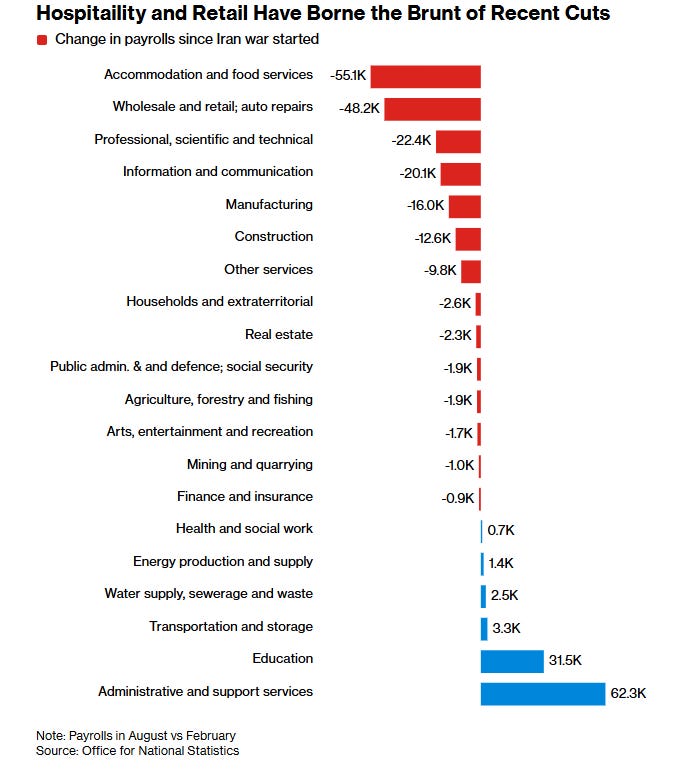
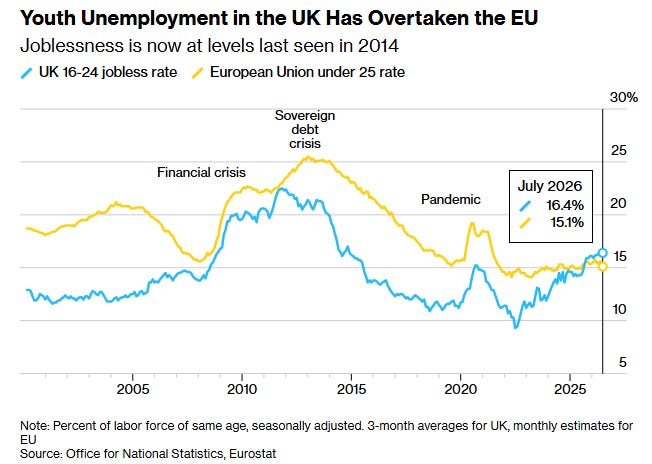
- BBG – Britain’s employers shed workers at the fastest rate in nine months, according to figures that emphasized the weak state of the jobs market ahead of the Bank of England’s latest interest rates decision on Thursday. Demand for workers remained tepid with job vacancies falling to a fresh five-year low.
- FT – China has implemented sweeping new controls on overseas travel for Chinese citizens as President Xi Jinping steps up efforts to secure state secrets, advanced technology and highly skilled workers.
- BBG – Japan is considering a new mid-term defense spending target of 3.5% of GDP in line with NATO and other US allies, a move that could send a shockwave through financial markets concerned about Prime Minister Sanae Takaichi’s spending plans.
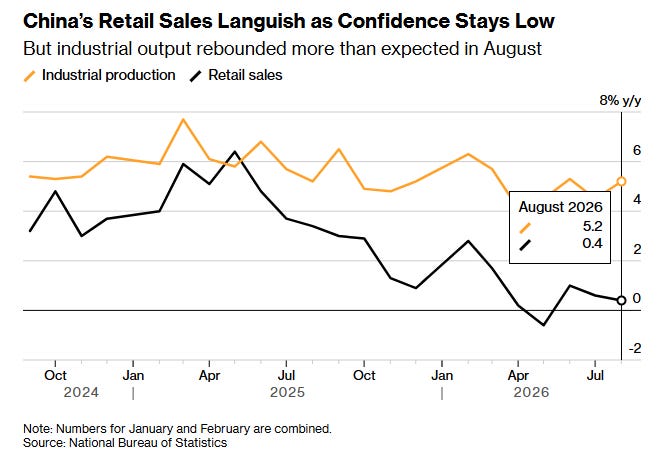
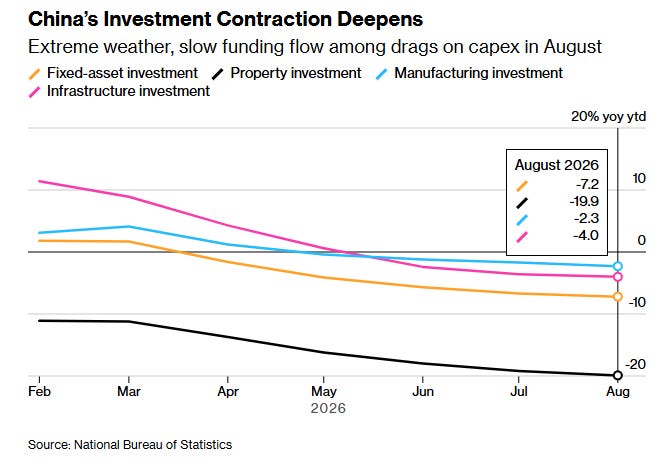
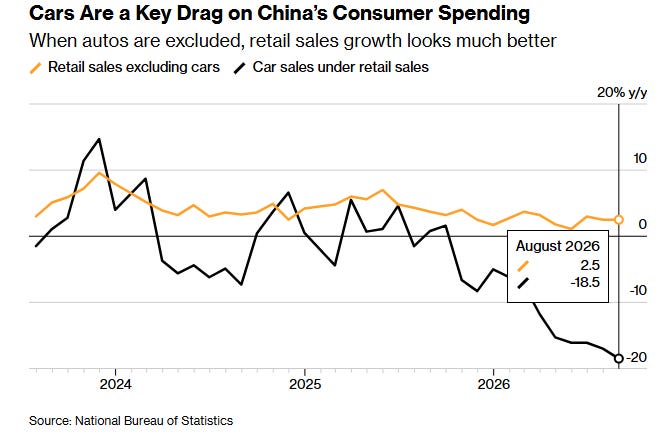
- BBG – China’s consumer spending and investment languished in August even as industrial output improved more than expected, widening a divide within the economy that complicates the decision facing policymakers over any additional stimulus. The widening divergence between domestic and external demand shows that the rapid expansion in China’s high-tech industries has yet to translate into better incomes and confidence among households.
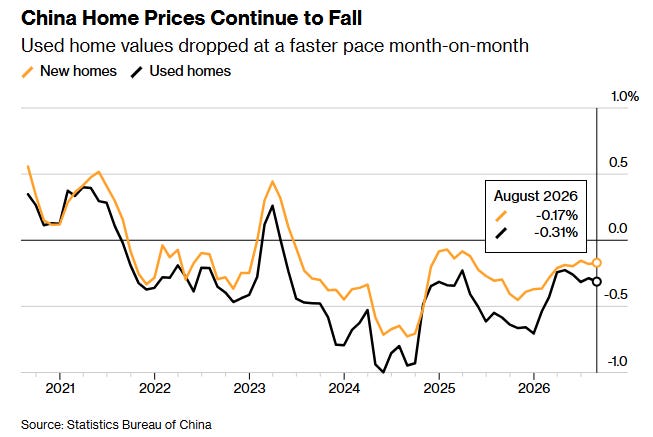
And China’s residential prices fell in August, with used-home values dropping at a faster pace, the latest sign of a slump that pushed policymakers to unveil fresh steps to support the market at the end of last month.
As a reminder, as I mentioned in the Week Ahead: “I want this piece, and to a larger extent the intra-week pieces (morning, evening, and economic updates), to evolve in whatever way is most meaningful for readers here. In that regard, I highly encourage an open and robust dialogue. Please post or email comments, questions, pushback, or suggestions on what I write, and especially what you would like to see more or less of. I read all the feedback, and I promise to be responsive as the newsletter settles into its new home. If you do put a comment in on a post please be sure to put @NeilSethi in front”