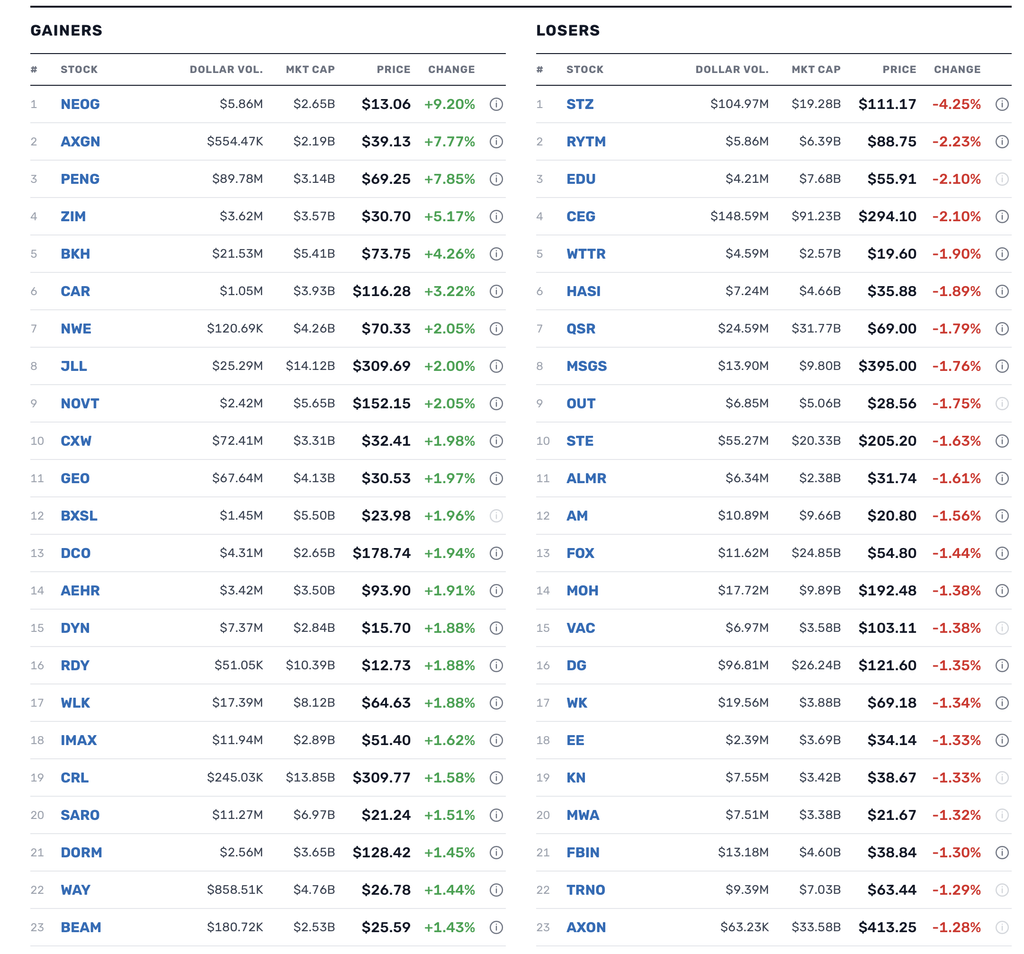
Tuesday’s After-Hours % Movers
Position: None
BY Doug Kass · Oct 6, 2026, 4:40 PM EDT
 Doug KassDoug Kass
Position: None
BY Doug Kass · Oct 6, 2026, 4:40 PM EDT
Closing Volume
– NYSE volume 5% below its one-month average
– NASDAQ volume 7% above its one-month average
– VIX index: down 3.29% to 15.01
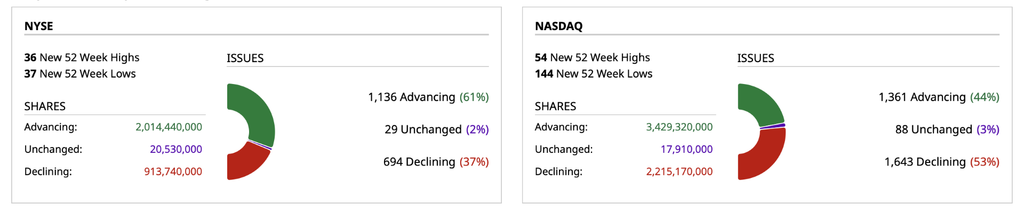
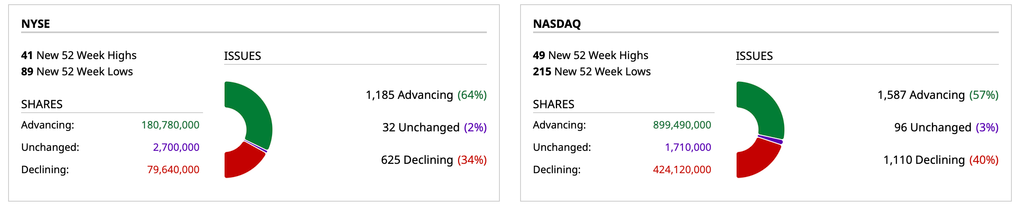
Breadth
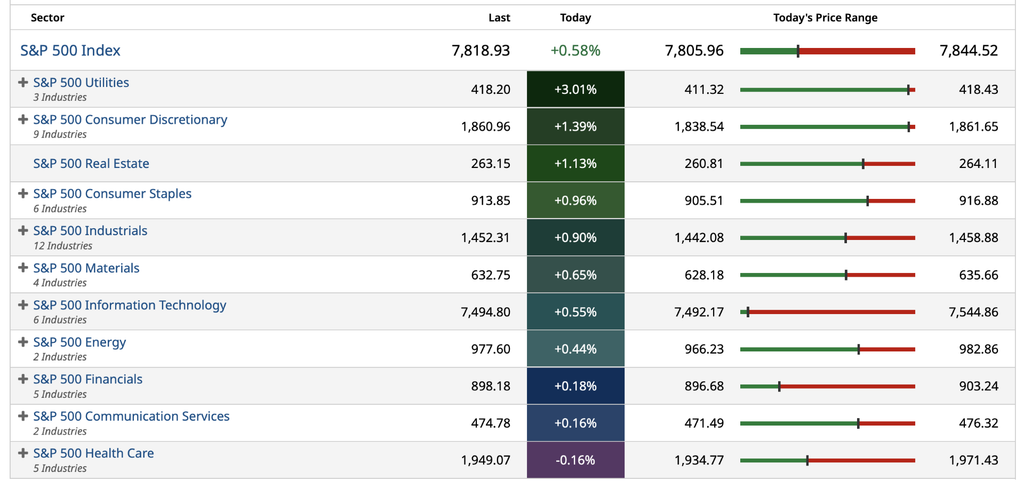
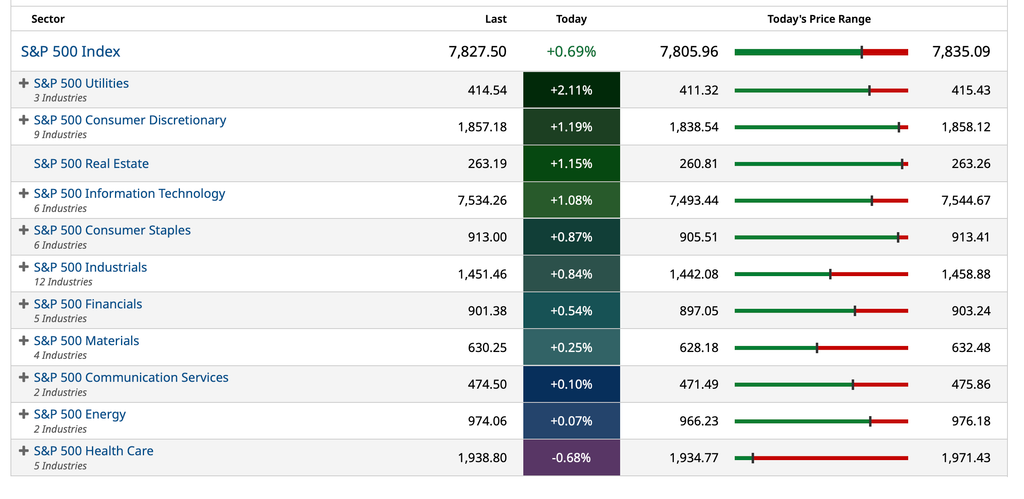
S&P 500 Sectors
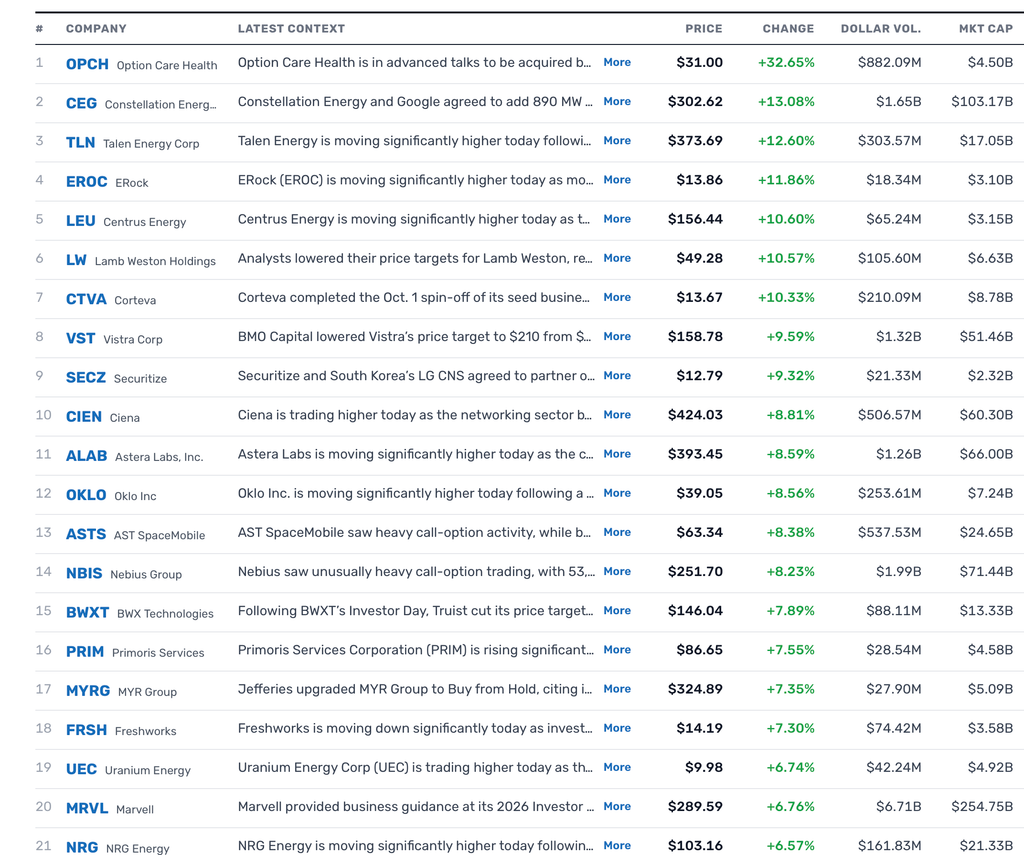
% Movers
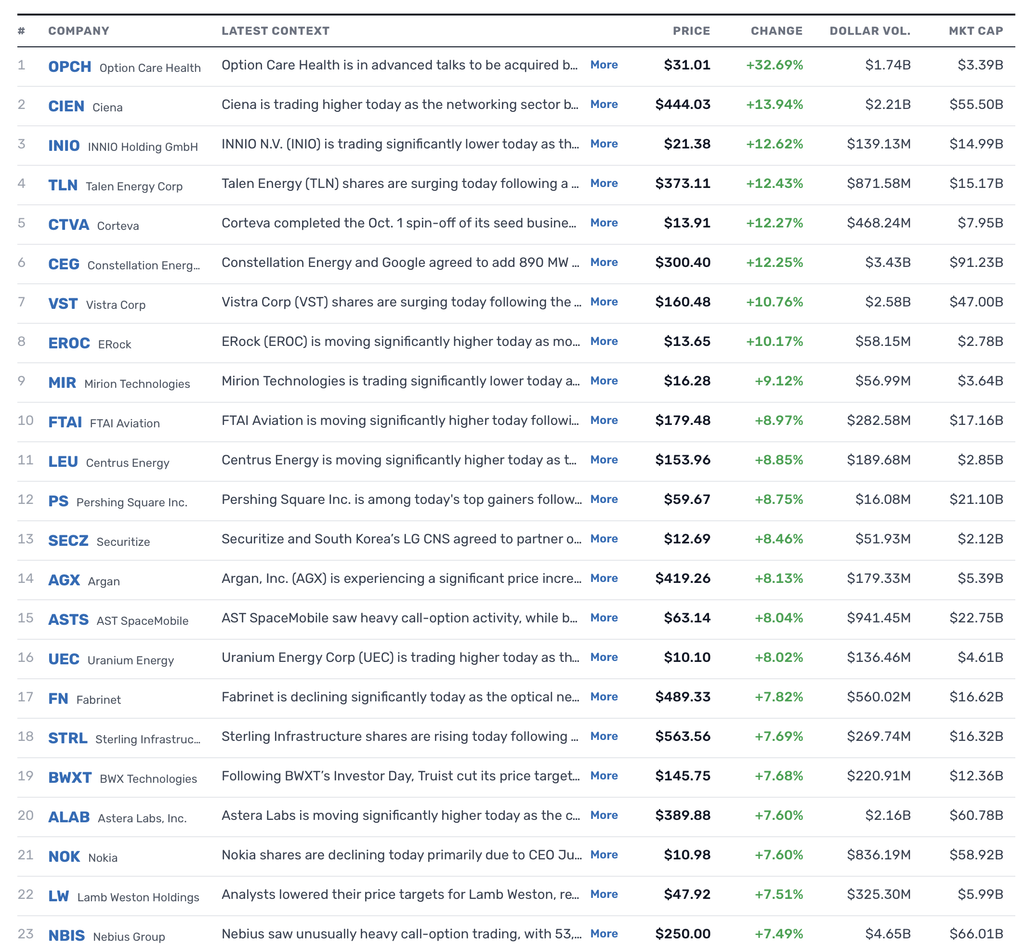
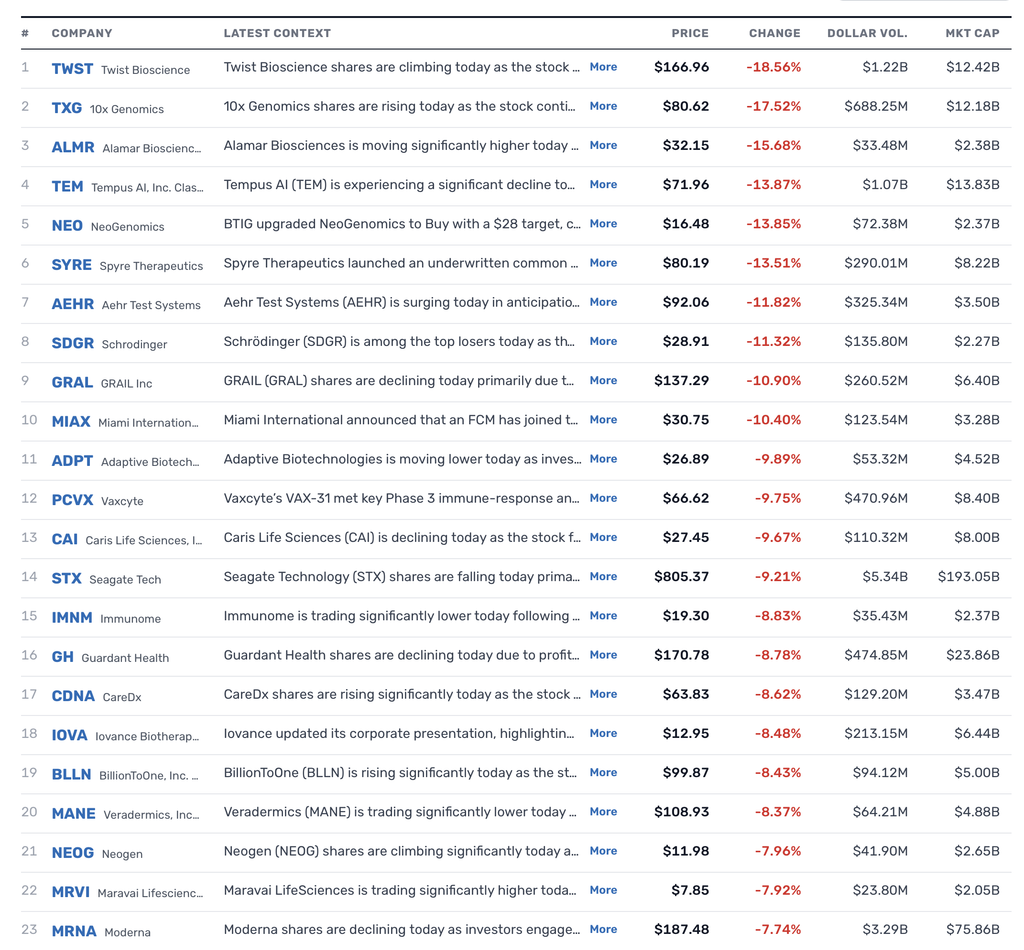
Heat Maps
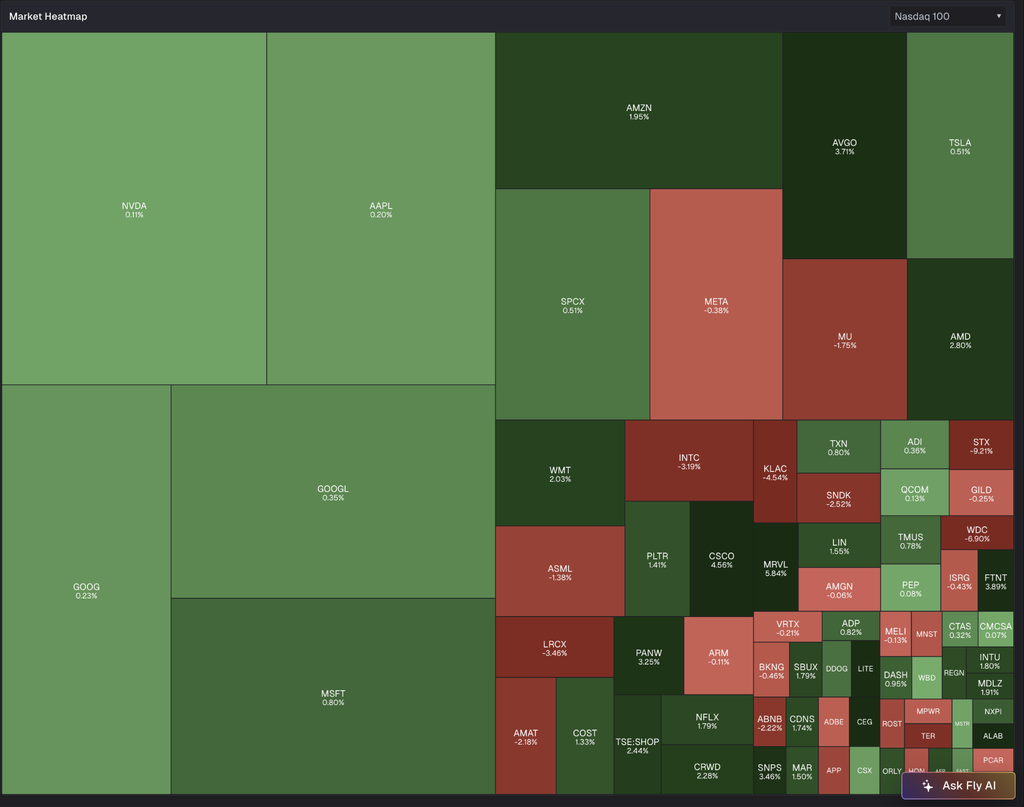
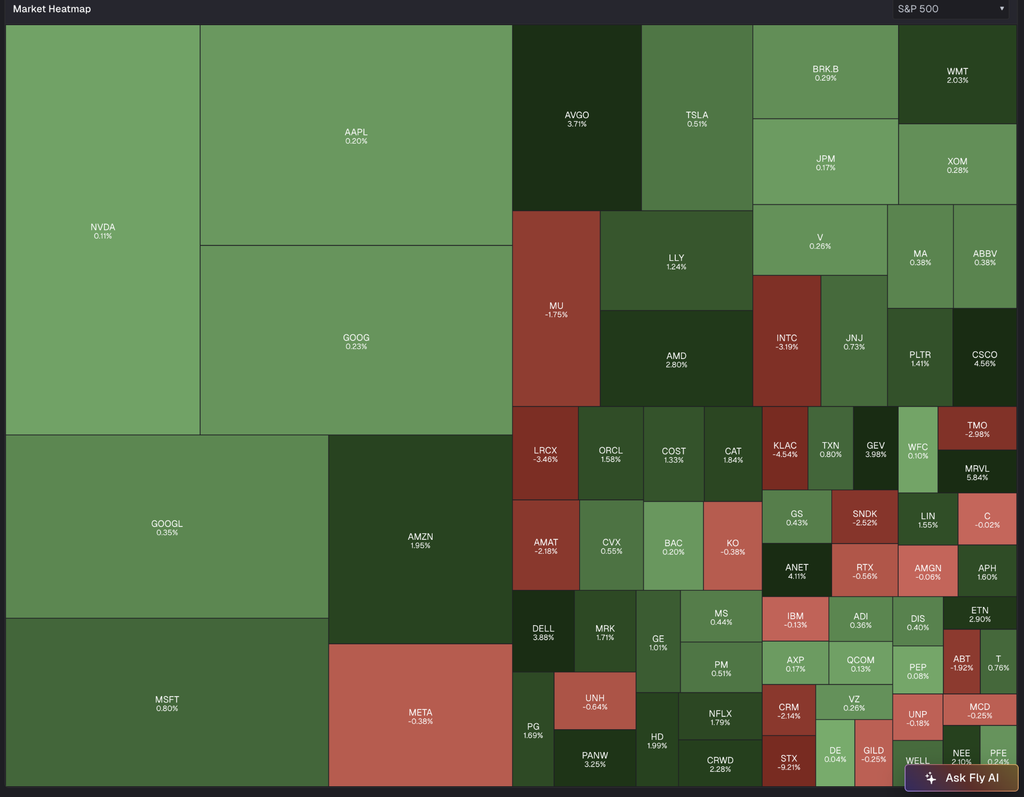
Position: None
BY Doug Kass · Oct 6, 2026, 4:29 PM EDT
BY Doug Kass · Oct 6, 2026, 3:45 PM EDT
A little known fact…
Micron (MU) and Nvidia (NVDA) alone will deliver more than 30% of the Q3 S&P EPS growth as the median stock barely grows.
Position: Short NVDA (VS), SPY (M)
BY Doug Kass · Oct 6, 2026, 3:39 PM EDT
henderson
Ed has a free newsletter today and it’s a cold look at the numbers. Glaringly, he talks about the AI labs’ coming debt raises is going to be tricky due to their lack of assets compared to the neoclouds that have valuable servers, racks and GPU’s even if they’re unable to finish the sites or fufill the massive power requirements (dark GPU’s anyone).
Position: None
BY Doug Kass · Oct 6, 2026, 3:30 PM EDT
Keith and Jim share my fears about market structure:
Position: None
BY Doug Kass · Oct 6, 2026, 3:16 PM EDT
* Yes that is all there is — as diversification is dying
I know what you must be saying to yourselves
“If that’s the way she feels about it, why doesn’t she just end it all?”
Oh, no, not me
I’m not ready for that final disappointment
‘Cause I know, just as well as I’m standing here talking to you
And when that final moment comes, and I’m breathing my last breath
I’ll be saying to myself
“Is that all there is?
Is that all there is?
If that’s all there is, my friends, then let’s keep dancing
Let’s break out the booze and have a ball
If that’s all there is”
– Peggy Lee, Is That All There Is? Peggy Lee — Is That All There Is? 1969
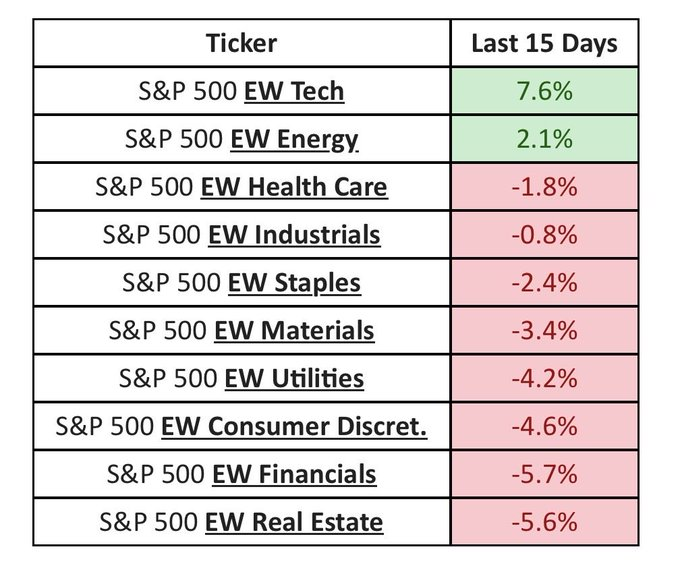
Why even mention any stock except hyperscalers, semis and memory companies?
Position: None
BY Doug Kass · Oct 6, 2026, 2:36 PM EDT
* And the market is not broadening…
The Russell Index is a dog with fleas.
Low of the day on the IWM.
Position: None
BY Doug Kass · Oct 6, 2026, 1:26 PM EDT
– NYSE volume 3% below its one-month average;
– Nasdaq volume 13% above its one-month average;
– VIX index: down 1.16% do 15.34
SOURCE: Barchart
SOURCE: Barchart
SOURCE: TheStreet Pro
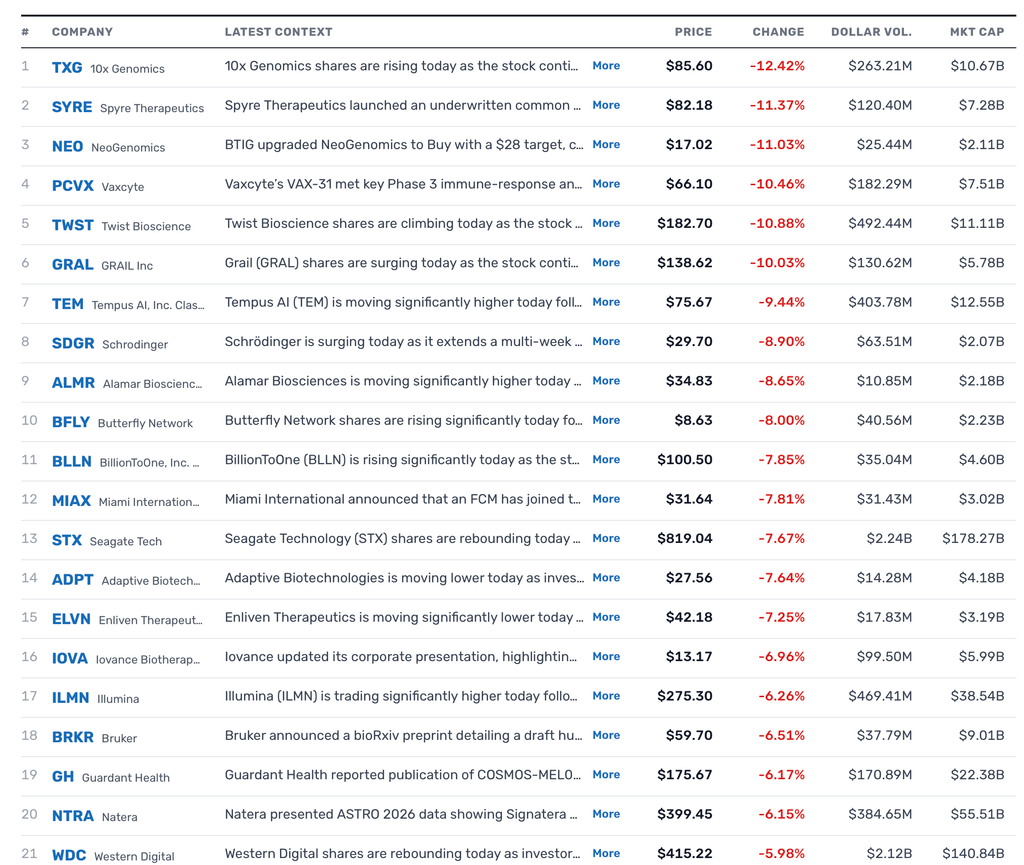
SOURCE TheFly
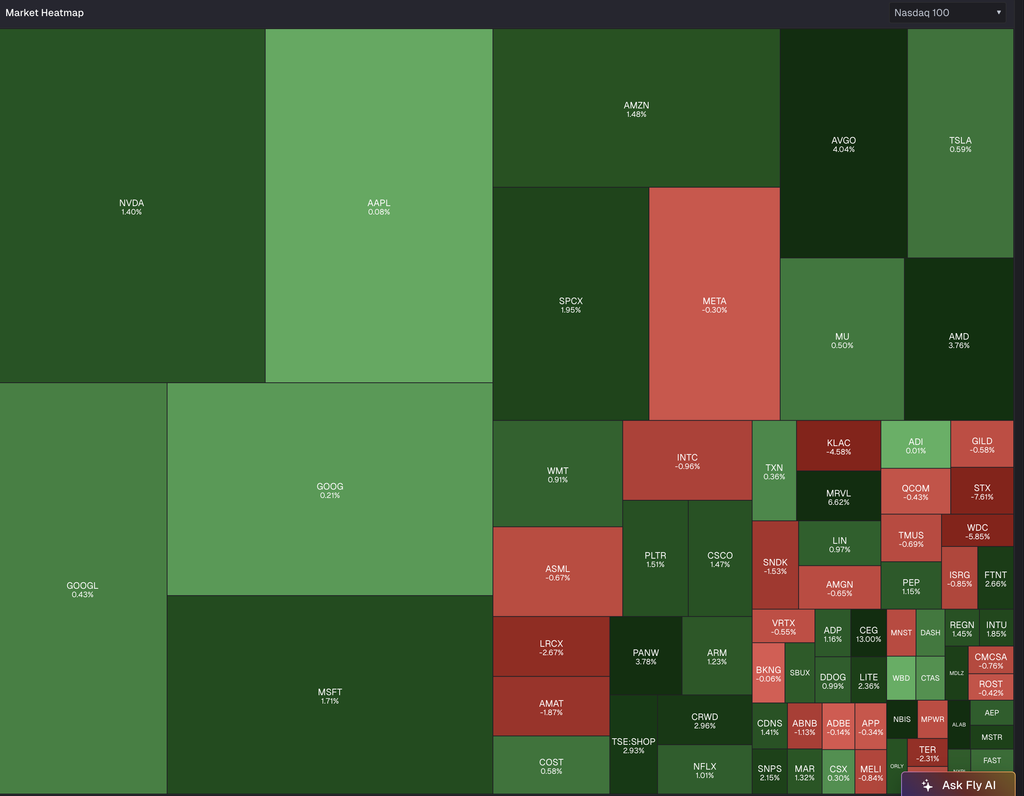
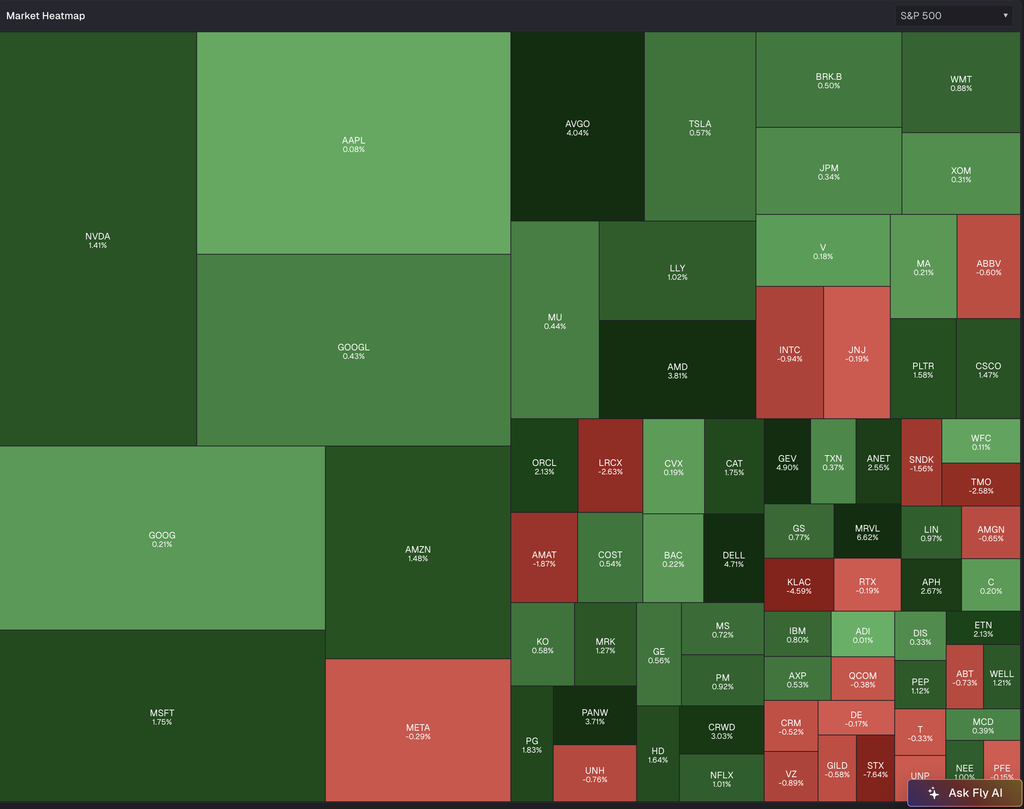
BY Doug Kass · Oct 6, 2026, 11:35 AM EDT
The following is from Peter Boockvar:
A main challenge that the bond markets of France, the US, the UK, Italy and German have is that foreigners are big participants and thus the pool of domestic savings in each country is not enough to absorb all the supply. For France in particular, about half the Oat market is owned by foreigners. For the US, UK German and Italian bond markets it’s about 1/3 of the tradeable market. And we are learning now the hard way that the kindness of foreign investors cannot be taken for granted. The Japanese JGB market in contrast, for those not familiar, is mostly owned by Japanese savers, Japanese institutions and the BoJ. And the trillion $/yen/euro/pound question is always when will Japanese institutions decide to bring more of their investing money home.
The WSJ has an article today titled “France’s appetite for ‘Magic Money’ has turned into a debt bomb…After years of overspending, the country has emerged as one of Europe’s weakest links. Investors are bracing for things to get worse.” That said by them, the contrarian in me tells me this likely marks a short-term top in French yields. I emphasize though, ‘short term.’
This was a quote in the piece from a portfolio advisor at a French asset manager, “France has been this free rider in Europe for years, if not decades. It has gotten away with fiscal murder. It worked as long as people were not noticing. Now people have started to notice.” A recent study from the French finance ministry estimates that “The cost of servicing France’s debt is expected to climb 59% by 2030.”
https://www.wsj.com/world/europe/france-debt-bonds-spending-c7981557?eafs_enabled=false
Another thing that France and others, including the US, got dependent on over the past few decades was getting bailed out by one’s central bank via QE (SOS, Morse code). This is what Marine Le Pen said today, “It’s essential to start a discussion with the ECB so that it intervenes and eases the burden of interest rates.” She not only said this, but stated her commitment to lower the country’s budget deficit to below 4% next year if elected.
Maybe the ECB does at some point and European bonds are rallying today, with French and Italian 10 yr yield each down about 10 bps. But we know that would only be addressing the symptoms, not the budgetary disease.
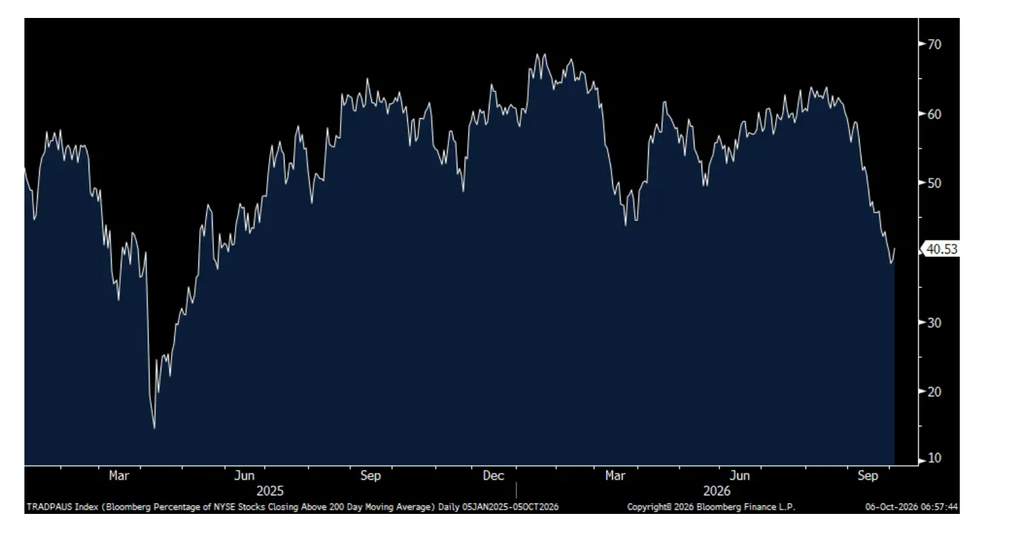
With respect to the rise in US yields and the AI trade continuing to power on notwithstanding, it seems we’ve entered into this game of chicken between bonds and AI stocks. Who will blink first. By the way, I’m only referring to AI stocks because everything else in the stock market has fallen sharply already. To quantify, just 41% of NYSE stocks closed above its 200 day moving average yesterday vs 64% about two months ago. That’s just off its lowest read since May 2025.
% of NYSE Closing Above its 200 day Moving Avg
For those utilizing the loan markets and where every basis point change in the cost of capital matters a lot (doesn’t matter now for the AI data center buildout), the move in rates is a really big deal, as it should be. Noting another WSJ article today, this one titled “The surge in rates is blowing up commercial real estate deals…Property buyers are demanding sellers renegotiate terms because of higher mortgage rates, signaling broader market distress” is worth the read.
It further said “Investors who agreed to a purchase price earlier this year when financing was cheaper are now demanding price cuts or other concessions before closing.”
https://www.wsj.com/real-estate/commercial-real-estate-interest-rates-22d04b1b?eafs_enabled=false
Moving on.
Similar to the very mixed Chinese economy, the September Hong Kong PMI remained under 50 at 49.2 vs 49.5 in the month before. S&P Global said, “Hong Kong SAR firms continued to face a challenging environment as the third quarter of the year drew to a close, although there were signs of demand stabilization amid success in securing new business overseas.”
BY Doug Kass · Oct 6, 2026, 10:50 AM EDT
cjsolus
just now
Positions: None.
BY Doug Kass · Oct 6, 2026, 10:34 AM EDT
With S&P cash +57 handles I have moved to medium sized short the indexes:
* SPY $780.29
* QQQ $761.35
Positions: Short SPY M QQQ M
BY Doug Kass · Oct 6, 2026, 10:25 AM EDT
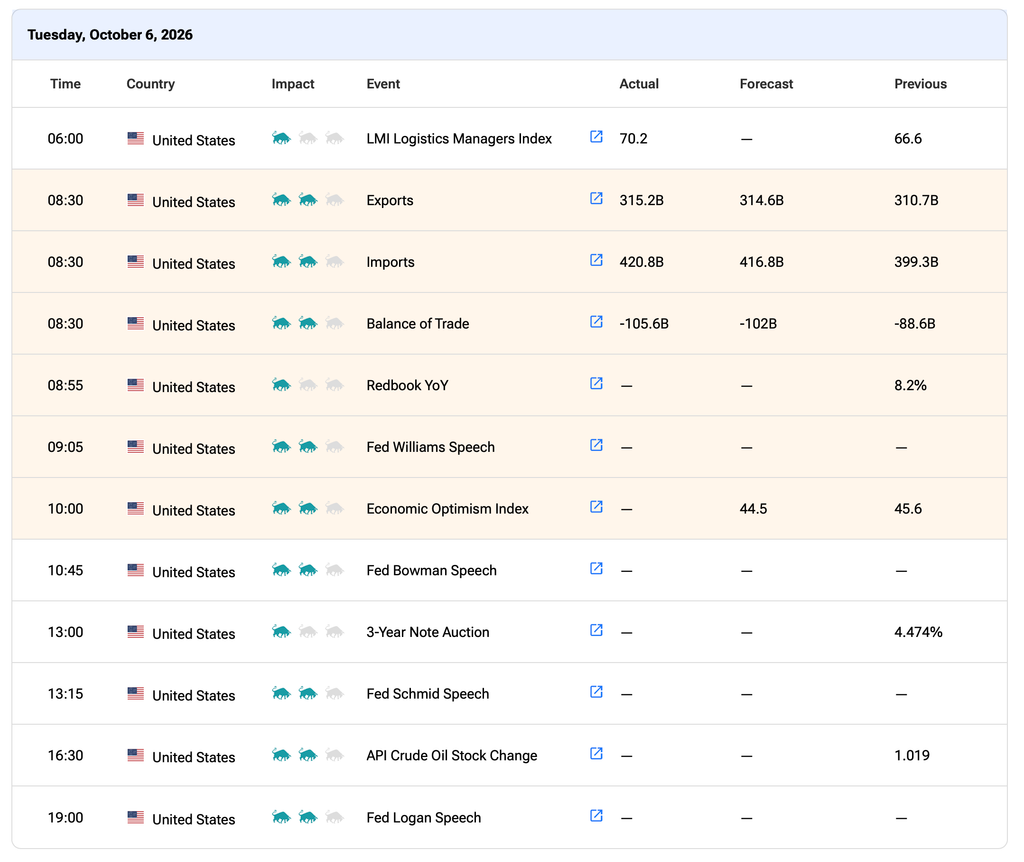
9:05 a.m.: Fed Bank of New York President Williams (Voter) moderates a discussion before the 2026 Governance & Culture Reform Conference organized by the Federal Reserve Bank of New York, NYC (No text);
10:45 a.m.: Fed Vice Chair for Supervision Bowman (Voter) speaks on “Modernizing Regulation and Supervision” before the 2026 Community Banking Research Conference at the Federal Reserve Bank of St. Louis, MO (Text available. Q&A from moderator. Livestream at https://www.communitybanking.org/);
1:15 p.m.: Fed Bank of Kansas City President Schmid (Non-Voter) speaks on “The Federal Reserve, Monetary Policy, and Rural and Agricultural Development” in fireside chat before the Enid Regional Development Alliance Luncheon, Enid OK (No text. Audience Q&A and livestream expected); 7:00PM: Fed Bank of Dallas President Logan (Voter) moderates a “Global Perspectives” question-and-answer session, Sanantonio, TX (No text. Livestream at dallasfed.org. Audience Q&A expected)
Source: TipRanks
Positions: None.
BY Doug Kass · Oct 6, 2026, 9:19 AM EDT
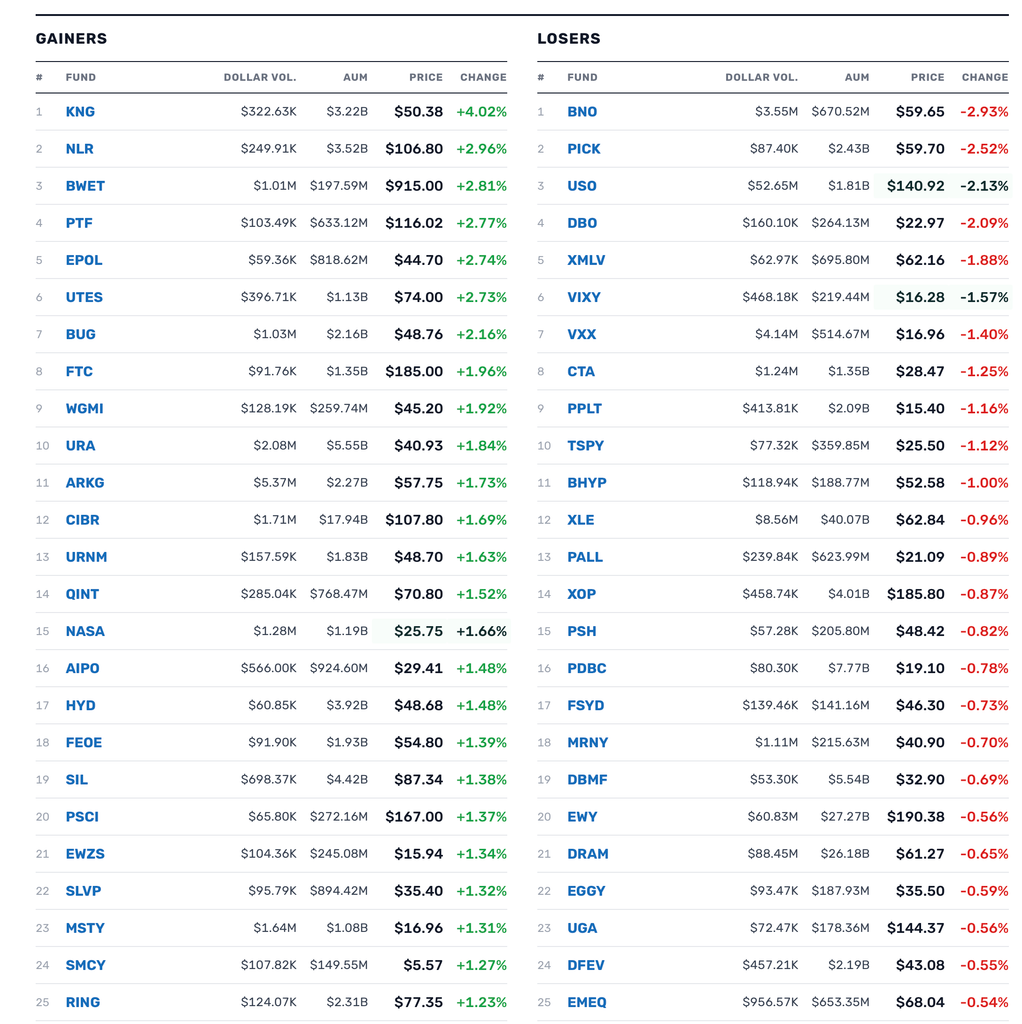
Source: TheStreet Pro
BY Doug Kass · Oct 6, 2026, 9:13 AM EDT
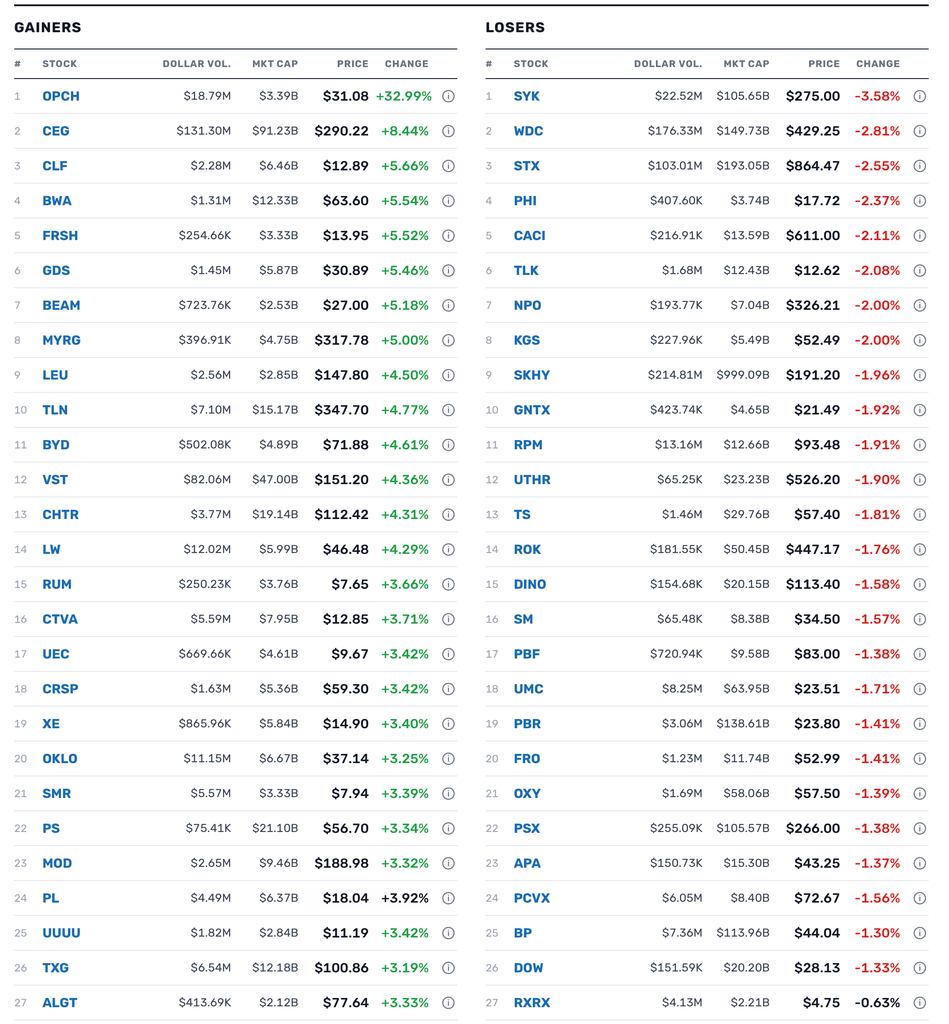
Source: TheStreet Pro
Chart from 8:44 a.m. ET
BY Doug Kass · Oct 6, 2026, 9:05 AM EDT
– JAGX +35% (announces a special stock dividend)
– OPCH +21% (reported takeover talks value the transaction at more than $5B including debt)
– APOG +20% (Q2 beat sharply and the FY adjusted EPS and sales outlooks were raised above expectations)
– CEG +9.3% (reports of a potential $1B-plus hyperscaler nuclear-power agreement)
– PENN +6.0%, BYD +2.7% (Deutsche Bank upgrades both to Buy, arguing recent regional-gaming weakness largely reflected calendar effects)
– FRSH +5.2% (set to join the S&P SmallCap 600 before the October 8 open)
– CLF +4.8% (Wells Fargo upgrades to Overweight on underappreciated 2027 earnings upside)
– VST +4.8% (nuclear and data-center power sympathy following reports of another major hyperscaler supply agreement)
– ZS +2.5% (reaffirms FY27 and Q1 revenue and adjusted EPS guidance)
– AMD +1.9% (Citi raises its price target to $800)
– SAIQ -15%, AMOD -15%, VEEA -13% (give back portions of Monday’s outsized speculative rallies)
– WDC -2.9%, STX -2.6% (storage leaders retreat after sharp recent gains; no clear fresh company-specific catalyst identified)
– PCVX -2.0% ($1B financing combines a $500M equity and pre-funded-warrant offering with $500M of convertible notes following the Phase 3 rally)
BY Doug Kass · Oct 6, 2026, 8:51 AM EDT
The U.S. stock market has become almost entirely AI-centric.
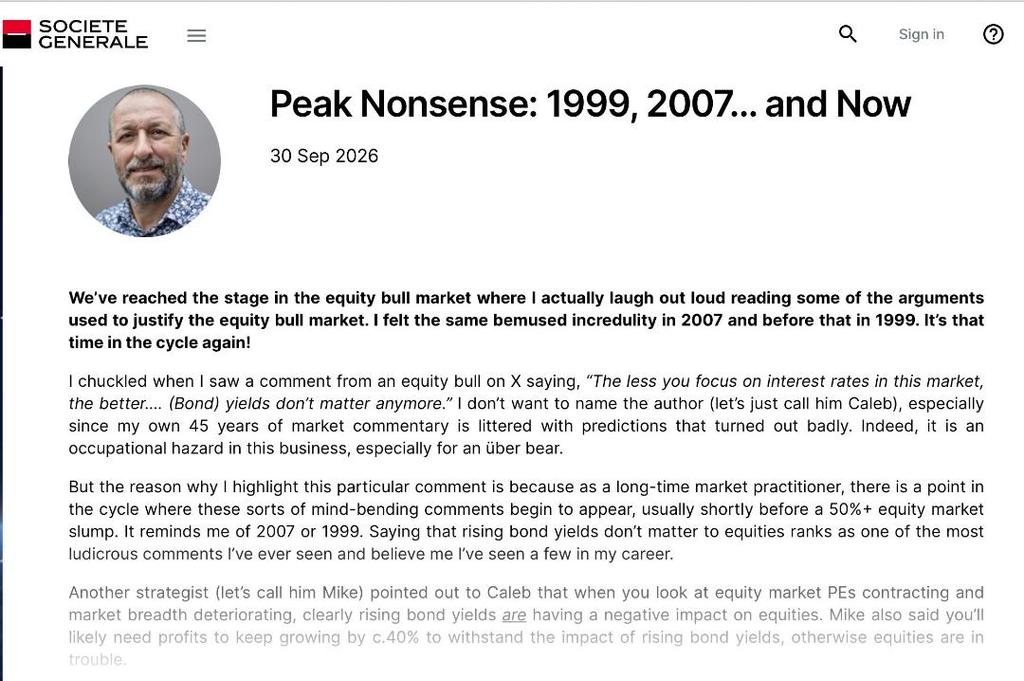
It has become so much so that traditional factors are being ignored by investors who operate in a casino-like setting of momentum-based trading/investing and speculation. These ignored factors include sticky inflation; interest rates “higher for longer;” foul and narrowing market breadth; inflated traditional valuation metrics (like CAPE Shiller, the Buffett Ratio and multiples to sales, and earnings before interest, taxes, depreciation, and amortization); a paper-thin equity risk premium; signs of a spent up (not pent up) consumer; and wayward foreign (improvisational), fiscal and monetary policies. Meanwhile momentum-based trading/investing and speculation (zero-days to expiration date options with a half life of less than 24 hours) account for nearly 70% of all options trading and a growing body of leveraged exchange-traded funds while worshiping at the alter of AI:
As noted in our “More Tales From Nvidia” series (now with over 250 issues!) we remain skeptical of AI’s circular financing, suspect of AI accounting and argue against the notion that an adequate return on capital will be realized from the swelling AI capital spending spree:
What follows are some of our more meaningful concerns:
But history has shown that market leadership, despite the conspicuous strength (yesterday, last month, last year and over the last five years) can be fleeting:
Importantly, stocks now have ample alternatives available in the fixed income market – in both absolute terms (5.3% 10 year Treasury yield) and relative to the meager and three decade low in the S&P dividend yield (of 1.07%):
The rise in interest rates is global and not restricted to our domestic market:
Meanwhile, real interest rates are moving higher:
And credit spreads are rising:
Real wages have been declining since the Spring and the savings rate is rapidly moving lower:
Were it not for the rapid growth in AI capital spending the U.S. economy would be barely growing and the expansion of corporate profits would be more subdued:
In ignoring an abundance of of fundamental and technical headwinds, the U.S. Stock Market, as Warren Buffett wrote in November, 1999, seems to be following “God’s Plan”:
“Once a bull market gets underway and once you reach the point where everybody has made money no matter what system he or she followed, a crowd is attracted into the game that is responding not to interest rates and profits but simply to the fact that it seems a mistake to be out of stocks. In effect, these people superimpose an I-can’t-miss-the-party factor on top of the fundamental factors that drive the market. like Pavlov’s dog, these “investors” learn that when the bell rings — in this case, the one that opens the New York Stock Exchange at 9:30 a.m. — they get fed. Through this daily reinforcement, they become convinced that there is a God and He wants them to get rich.”
As noted in the Societe Generale reference (in the beginning of this morning’s missive), this was also the condition in 1999 and in 2007… and its happening again.
As most are aware, the header of today’s opening missive is taken from a famous Yogi Berra quote.. Let’s try another Yogism:
“It gets late early out there.”
We may be facing something close to peak nonsense.
Positions; Short SPY S NVDA VS
BY Doug Kass · Oct 6, 2026, 7:34 AM EDT
* Not investment related…
Positions: None.
BY Doug Kass · Oct 6, 2026, 7:16 AM EDT
Wolf Street on CMBS delinquencies.
Position: None
BY Doug Kass · Oct 6, 2026, 6:20 AM EDT
Position: None
BY Doug Kass · Oct 6, 2026, 6:05 AM EDT
Here are Monday’s “things:”
* I reshorted the indices: SPY at $771.82 and QQQ at $752.71.
* I added to cannabis longs — MSOS at $4.41, GTBIF at $6.29 and GLAS at $5.28.
* I reshorted NVDA at $237.12. I took a small trading loss on much of this short at $237.49.
* I reshorted GRNY at $28.46.
Position: Long MSOS common (VL) and calls (S), GTBIF (S), and GLAS (S); Short GRNY (S), NVDA (VS)
BY Doug Kass · Oct 6, 2026, 5:55 AM EDT
The S&P Short Range Oscillator remains oversold at -4.56% vs. -4.26%.
In early trading (5:05 AM) I added to my index shorts:
* SPY $776.30
* QQQ $757.58
Position: Short SPY (S), QQQ (S)
BY Doug Kass · Oct 6, 2026, 5:45 AM EDT
Jim Bianco @biancoresearch says the rise of zero-day options "is outright gambling. And it's no longer investing." "Nobody wants to go public early in the process and have their stock gyrate around like a Kalshi betting market."
BREAKING 🚨: Europe Euro falls to its weakest level against the U.S. Dollar since May 2025 📉

Since we have my pal and Hall of Famer Baltimore Orioles pitcher @jim22palmer Jim Palmer on the @dougkass thread... This Tuesday will be October 6, an interesting highlight of JIm's career! Sixty years ago (oh my!) on that date in 1966 Jim beat my cousin Sandy Koufax in the Show more
Free newsletter: Outside of major hyperscaler backstops, I estimate that Anthropic and OpenAI would get a speculative B or CCC credit rating, which would be insufficient for the $50bn-$100bn a year they need, in an era of historically high interest rates. wheresyoured.at/credit-crunch/
In 1980, 6 out of the 10 largest companies in the US were Oil/Energy stocks. Today, that number is 0 and 9 out of the 10 largest companies are in Tech (and one could make an argument that it's 10 out of 10 if you believe Tesla is a Tech company). Video: youtube.com/watch?v=GFl2yD… Show more

Surging benchmark rates are starting to bite corporate credit more significantly. Spreads on high-yield bonds have widened 28bp in the past three days, the most since October 2025. While spreads are still relatively low, they've been widening at an accelerating clip.

Excellent stuff from Brian Garrett, Goldman's Derivatives guru, on collapsing correlations and poor breadth. But this chart caught my eye on concentration risk H/T @zerohedge zerohedge.com/markets/correl…

BREAKING 🚨: Japan Japan's 30-Year Yield hits highest level in history 🤯 👀

The weakness in the labor market is also reflected in the TREND of wage growth.

TREASURY YIELDS SURGE TO FRESH 24-YEAR HIGHS Treasuries sold off sharply, pushing the 10-year yield to 5.34% and the 30-year to 5.70%, their highest levels since 2002. Pressure comes from resilient growth, AI-driven investment and persistent inflation, with ISM Services Prices Show more

The Nasdaq closed at a record high. With almost 200 more issues at 52-week lows than 52-week highs. That's the 2nd-most ever at a record close, next to November 18, 2021.


Strong 2026 earnings growth has helped bring down the S&P 500’s forward P/E multiple. Consensus expects growth to cool in 2027 and 2028, but slower earnings growth alone is not a sell signal; a disappointment of those expectations is. h/t @ISABELNET_SA

Americans Tap Home Equity to Keep Spending For the past five months, prices have been rising faster than wages, a turnabout that might have pushed US consumers to cut back. Instead, they’ve kept spending. Consumption rose at the fastest pace in over a year in August, with Show more

Another "breadth chart" like we discussed yesterday, shows the percentage of stocks above their respective 50- and 200-DMAs. The decline explains the lackluster market performance of late, which has hidden more severe corrections in small, mid, and interest-rate-sensitive Show more

French 10-year bond yields are the highest relative to similarly-dated German bunds since the European debt crisis 14 years ago. France's borrowing costs have risen above those of Italy and Greece, with the nation facing one of the biggest fiscal deficits in the EU.

The financial pain is real: Wage growth fell to 3% (y/y) in September. That's the lowest in 5 years. Wage growth: 3% Inflation: ~3.4% Inflation has eaten up all wage gains for the average worker since April. Many people are having to make hard choices about what to buy and what Show more

Financing the AI buildout will total $10.3 trillion from 2025-2032, or an average of 3.63% of US GDP each year: study. That "would be larger relative to the economy than the major US canal, railroad, electrification, highway, & telecom investment booms" brookings.edu/articles/finan…
Speaking of Q3 earnings season, here is a good breakdown from $GS on EPS, Sales, and Margins by market sector.
While there seems to be a lot of people rooting for a crash in Technology stocks, not sure why, it is worth noting that Technology earnings have grown 380% more than Non-Tech, and have contributed 76% of the entire earnings growth of the S&P 500. h/t @thedailyshot
For the AI buildout to pay off, Americans will eventually have to spend about 9% of GDP a year on AI services. Sit with that number. That is roughly what the entire country spends on food. A Columbia paper presented at Brookings estimates AI revenue would need to hit $3.5Show more
To justify today's AI capex, we'll have to spend 9% of GDP on AI services, a study finds. Is it plausible we'll spend as much on AI as on food? Twice as much as on energy? The law of diminishing returns would like a word. My column: wsj.com/tech/ai/will-a…


